
- Home
- »
- Communications Infrastructure
- »
-
Command And Control Systems Market Size, Growth Report, 2026-2033GVR Report cover

Command And Control Systems Market (2026 - 2033)
Size, Share & Trends Analysis Report By Platform (Airborne, Maritime, Land, Space), By Solution (Hardware, Software, Services), By Application (Defense, Commercial), By Region, And Segment Forecasts
Market Size, 2025
$41.1BMarket Estimate, 2026
$43.6BMarket Forecast, 2033
$66.0BCAGR, 2026–2033
6.1%Command And Control Systems Market Summary
The global command and control systems market size was valued at USD 41.1 billion in 2025 and is projected to grow from USD 43.6 billion in 2026 to USD 66.0 billion in 2033, at a CAGR of 6.1% from 2026 to 2033. North America dominated the market, accounting for a largest revenue share in 2025. The market growth is attributed to the rising preference for integrated command and control (C2) solutions, which combine hardware, software, and advanced analytics to manage diverse data sources, from Internet of Things (IoT) sensors to satellite imagery, enable real-time monitoring, analysis, and decision-making; and enhance situational awareness and operational efficiency, which is crucial for rapid response and effective resource allocation.
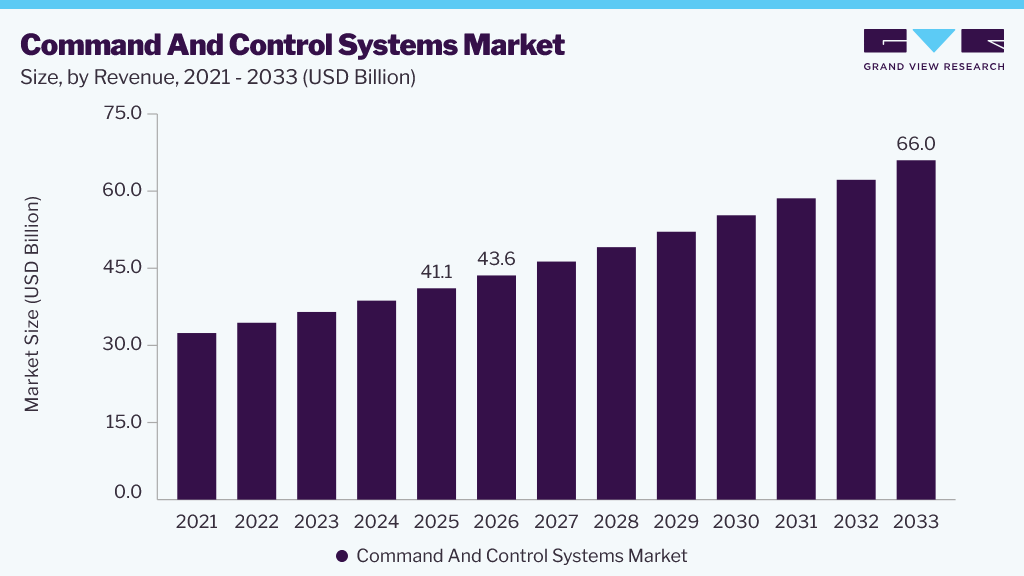 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By platform: The airborne segment held the largest market share of around 35.0% in 2025.
- By solution: The hardware segment held the largest market share in 2025.
- By application: The defense segment held the largest market share in 2025.
Regional Highlights
- Largest regional market: North America (Largest revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 41.1 Billion
- Estimated market size in 2026: USD 43.6 Billion
- Projected market size by 2033: USD 66.0 Billion
- CAGR (2026-2033): 6.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Moreover, rising geopolitical tensions and growing requirements associated with defense operations contribute to market growth. Increasing military modernization budgets and key advancements in technology applications across military and defense are fuel the demand for C2 systems. Advancements, such as integrating artificial intelligence (AI) technology in C2 systems for smarter decision-making, cloud adoption for scalability, 5G deployment for enhanced connectivity, and heightened cybersecurity measures to protect interconnected systems, further drive market growth. C2 systems are evolving with the continued digital transformation and the subsequent shift to cloud-based architecture and virtualized environments.
Cloud computing offers scalability, flexibility, and cost-efficiency, allowing organizations to access critical data and applications remotely while ensuring data security and adequate regulatory compliance. Advancements in cybersecurity measures to protect sensitive information and maintain operational integrity against evolving cyber threats are complementing this shift. In addition, the increasing adoption of C2 technologies in the commercial sector to effectively manage mission-critical operations is opening new growth avenues for the industry. Moreover, they are used in airports and manufacturing plants, power plants, oil & gas installation plants, and research labs, which, in turn, positively influence the overall market outlook.
Analyst Perspective
The global command and control systems market is projected to grow significantly over the forecast period. The growth of this market is primarily driven by rising geopolitical tensions, increasing investments in military modernization, a focus by multiple governments on improving defense capabilities, and a significant rise in utilization by commercial users, including aviation, maritime shipping, utility management, agro-tech, and others. The rapid pace of digitization, the increasing use of IoT-powered devices, and the growing demand for centralized access and control are expected to facilitate further growth. Some of the major challenges for this market include escalating cybersecurity threats, legacy systems, and high capital requirements associated with installation and post-deployment maintenance. Major companies in this market embrace strategies such as innovation, R&D investments, partnerships with other market participants, and more.
Platform Insights
The airborne segment accounted for the largest share of nearly 35.0% in 2025. The segment growth is attributed to airborne C2 systems' critical role in modern military operations, surveillance, and reconnaissance missions. Advanced airborne C2 systems facilitate real-time data collection, analysis, and communication, essential for maintaining air superiority, coordinating ground operations, and ensuring effective responses to security threats. The increasing integration of Unmanned Aerial Vehicles (UAVs) & drones in military and civilian applications necessitates versatile airborne command systems, further contributing to the segment's growth.
The maritime segment is expected to record its highest CAGR from 2026 to 2033. Modernization efforts are being pursued worldwide to enhance naval operations, maritime security, and coastal surveillance amidst the increasing geopolitical tensions and evolving maritime threats. At this juncture, advanced maritime C2 systems are being deployed aggressively to enable more efficient management of naval fleets by enhancing real-time tracking, communication, and coordination, which is critical for maritime defense and surveillance. The expansion of maritime trade and implementation of regulations to enhance safety and security at sea are creating lucrative growth avenues for the market.
Solution Insights
The hardware segment accounted for largest revenue share in 2025. The increasing demand for robust hardware that enhances the functionality and effectiveness of C2 systems is favoring segmental growth. Hardware, such as sensors, communication devices, displays, and control units, forms the backbone of a typical C2 system, enabling the collection, processing, and dissemination of critical data in real time. The introduction of modern hardware, including more powerful processors, enhanced sensors, and robust communication networks, further accelerates segmental growth.
The software segment is expected to record the highest CAGR from 2026 to 2033. The segment growth can be attributed to software's critical role in integrating, analyzing, and visualizing data to enhance decision-making and operational efficiency. Advanced software solutions facilitate real-time data processing, situational awareness, and coordination across various command and control operations. Advances in AI, ML, and big data analytics are facilitating the development of sophisticated software platforms capable of delivering predictive analysis, automation, and enhanced cybersecurity, enhancing the market outlook.
Application Insights
The defense segment accounted for largest revenue share in 2025. Several governments worldwide are aggressively pursuing defense modernization initiatives amid rising security concerns and growing armed conflicts in different parts of the world. Defense organizations are investing in advanced C2 systems to facilitate real-time monitoring, establish communication and coordination between troops, vehicles, and other assets, enhance situational awareness, and improve operational effectiveness across the overall military operations. The high prominence of C2 systems across the defense sector due to their advantages drives the segment growth.
The commercial segment is expected to register the highest CAGR from 2026 to 2033 owing to continued industrial automation, smart city initiatives, and rising emphasis on deploying efficient emergency response systems. As cities and industrial establishments transform digitally, the need for advanced C2 systems to enable real-time monitoring and predictive maintenance, streamline resource allocation, support urban development and industrial operations, and enhance safety protocols is growing. Moreover, the rising demand for C2 systems integrating diverse IoT sensors and communication networks further contributes to segment growth.
Regional Insights
The command and control systems market in North America is expected to record a significant growth rate from 2026 to 2033. This is attributed to the advancements in AI, ML, and cybersecurity, among other technologies, driving innovations in command and control systems in the region. The region’s commitment to modernizing its defense and homeland security devices, including the integration of cyber defense strategies with command and control systems, is creating substantial market opportunities.
U.S. Command And Control Systems Market Trends
The U.S. command and control systems market is anticipated to experience noteworthy growth, driven by increasing investments in the defense industry, growing use of command and control systems by the commercial aviation and utility management industries, and the presence of a strong IT & telecom industry in the country. The increasing adoption of modern technologies such as IoT, AI, and ML also contributes to the growth of this industry.
Europe Command And Control Systems Market Trends
The command and control systems market in Europe accounted for a significant revenue share in 2025 owing to the implementation of the North Atlantic Treaty Organization (NATO) standards in member states, which are raising interoperability and modernizing military assets, including command and control systems. Moreover, the European Union's investment in research and development for defense technology innovation, particularly in AI and cyber defense, is propelling the adoption of command and control systems, thereby contributing to market growth. In June 2026, Electro Optic Systems, manufacturer of advanced technology solutions, announced its latest investment of more than USD 11.4 million directed toward establishment of dedicated regional hub for AI-enabled counter-drone command and control (“C2”) systems in France, while anchoring its recently acquired defense technology specialist, MARSS. Such developments and increasing investments in enhancement of C2 system capabilities in the region are expected to support market growth in coming years.
Asia Pacific Command And Control Systems Market Trends
The command and control systems market in Asia Pacific is expected to record the highest CAGR from 2026 to 2033. The increasing geopolitical tensions and border disputes among regional countries have led to a considerable focus on national security, creating a significant demand for advanced command and control systems. In addition, rapid urbanization and smart city initiatives across the Asia Pacific are increasing the demand for robust command and control systems, thereby contributing to market growth.
Middle East and Africa (MEA) Command And Control Systems Market Trends
The MEA command and control systems market is anticipated to grow at a significant rate from 2026 to 2033. The market growth is being driven by the ongoing infrastructure projects in the region, particularly in the Gulf Cooperation Council (GCC) countries, which involve the development of smart cities. These projects require integrated command and control systems for efficient urban management, traffic control, and public safety, fueling market demand. These systems are integral to protecting critical infrastructure and ensuring secure communication channels, further contributing to the market's growth.
Key Command And Control Systems Company Insights
The command and control systems industry features a range of global, regional, and local players, making it a competitive market. The world’s leading companies are using partnerships, collaborations, acquisitions, mergers, and agreements as strategies to withstand the intense competition and increase their market share.
Some of the key players operating in the market include Lockheed Martin Corporation, BAE Systems plc, RTX Group, and Boeing, among others.
- Lockheed Martin Corporation is an aerospace and security company engaged in developing, manufacturing, and integrating advanced systems, products, and services. Its major business segments include aeronautics, missiles & fire control, rotary & mission systems, and space
- BAE Systems Plc manufactures military aircraft, submarines, surface ships, radar, communications, avionics, electronics, and guided weapon systems. Its major business segments include electronic systems, platforms & services, air, maritime, and cyber & intelligence
- RTX Corporation is an aerospace and defense company offering advanced systems and services for commercial, military, and government organizations. It caters to government and commercial customers in the original equipment and aftermarket parts and services segments of the aerospace industry
- Boeing manufactures and services defense products, commercial airplanes, and space systems across the globe. Its three main business segments include commercial airplanes, global services, and defense, space & security. Command and control systems come under the defense, space & security segment
Barco NV, Planar, and Christie Digital Systems USA, Inc., are some of the emerging market participants in the command and control systems market.
- Barco NV operates as a digital visualization solution provider, majorly in three business segments, including healthcare, entertainment, and enterprise. The company offers monitors, projectors, video walls, light-emitting diode displays, image processing, and visual display systems. The command and control systems are covered under the enterprise segment
- Christie Digital Systems USA, Inc. is a global audio and visual technologies company offering a wide range of projection solutions, including advanced RGB pure laser projection, video walls, LCD panels, and video wall processors, to SDVoE technology, content management, and image processing, among others
- Planar offers display solutions that are utilized in various control rooms and command centers, including those for military operations, space flight control, emergency management, network infrastructure management, real-time crime prevention, and traffic management. The company’s versatile, ultra-high resolution video walls and large format displays provide sharp visibility of data and the flexibility to display it effectively
Key Command And Control Systems Companies
The following key companies have been profiled for this study on the command and control systems market:
-
Lockheed Martin Corporation
-
BAE Systems
-
Collins Aerospace
-
Thales
-
Leonardo S.p.A.
-
Elbit Systems Ltd.
-
Boeing
-
Northrop Grumman
-
Saab AB
-
CACI International Inc.
-
Barco
-
Christie Digital Systems USA, Inc.
-
InFocus
-
Activu Corporation
-
Panasonic Corporation
-
Planar
-
Datapath Ltd.
-
Extron
-
Matrox Graphics Inc.
-
Hiperwall, Inc.
-
Green Hippo Ltd. (tvOne)
-
RTX
-
tvONE
-
RGB Spectrum
-
Userful Corporation
-
VuWall Technology Inc.
Recent Developments
-
In July 2026, demonstrating its key expertise and advanced technology capabilities in Command and Control (C2) and battle management, Integrated Air and Missile Defense (IAMD) and more, during field training exercise led by the U.S. Armed Forces in challenging operational environment, Indo-Pacific, Lockheed Martin Corporation showcased its ability to unify a wide range of sensors and C2 systems to facilitate faster and improved decision making.
-
In June 2026, Ondas Inc. announced plans to launch the Layered Autonomous Defense Operational C2 System (LADOS) at Eurosatory 2026 in France. The newly designed solutions by Ondas, with the capacity to unify multiple technologies and systems into one a singlerational backbone, are expected to improve its ability to assist in multi-domain operations and defense requirements.
-
In June 2026, Thales, one of the key defense technology and application industry participants, announced its latest collaboration with Bootech C2 and C4ISR products manufacturer for advance availability of interoperable solutions for multi-domain operations to Armenia and armed forces in various regions.
-
In April 2024, Lockheed Martin Corporation launched a new Power over Ethernet (POE) touchscreen panel called the Controlvu Touch Panel for command and control applications. This product allows operators to manage and monitor multiple video sources in real-time, directly from the touch screen panel.
-
In March 2024, Northrop Grumman signed a Memorandum of Understanding (MOU) with Diehl Defense GmbH & Co. KG to support Germany’s innovative layered air and missile defense capabilities. The former’s expertise in IAMD and control capabilities, such as the Integrated Battle Command System, complements Diehl’s ground-based air and missile defense systems.
-
In May 2024, VuWall Technology Inc. received an indefinite-delivery/indefinite-quantity contract with a maximum ceiling of USD 4.09 billion from the Missile Defense Agency. This initiative is aimed at accelerating the development of command and control, battle management, and communications systems.
-
In February 2024, BAE Systems Plc. announced plans to deliver advanced electromagnetic warfare mission systems for the U.S. Air Force’s fleet of EA-37B aircraft, which will become a part of the Compass Call mission that counters the command and control, computing, communications, combat systems, and intelligence, surveillance, reconnaissance, and targeting (C5ISRT) capabilities of the enemy.
Command And Control Systems Market Report Scope
Report Attribute
Details
Market size in 2025
USD 41.1 billion
Estimated market size in 2026
USD 43.6 billion
Projected market size by 2033
USD 66.0 billion
Growth rate
CAGR of 6.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Platform, solution, application, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; Australia; South Korea; Brazil; UAE; Saudi Arabia; South Africa
Key companies profiled
Lockheed Martin Corporation; BAE Systems; Collins Aerospace; Thales; Leonardo S.p.A.; Elbit Systems Ltd.; Boeing; Northrop Grumman; Saab AB; CACI International Inc.; Barco; Christie Digital Systems USA, Inc.; InFocus; Activu Corporation; Panasonic Corporation; Planar; Datapath Ltd.; Extron; Matrox Graphics Inc.; Hiperwall, Inc.; Green Hippo Ltd. (tvOne); RTX; tvONE; RGB Spectrum; Userful Corporation; VuWall Technology Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Command And Control Systems Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2026 to 2033. For this study, Grand View Research has segmented the global command and control systems market report based on platform, solutions, application, and region:
-
Platform Outlook (Revenue, USD Million, 2021 - 2033)
-
Land
-
Maritime
-
Space
-
Airborne
-
-
Solution Outlook (Revenue, USD Million, 2021 - 2033)
-
Hardware
-
Software
-
Services
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Defense
-
Commercial
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Frequently Asked Questions About This Report
The global command and control systems market is expected to grow at a CAGR of 6.1% from 2026 to 2033, reaching USD 66.0 billion
The global command and control systems market size was valued at USD 41.1 billion in 2025 and is estimated at USD 43.6 billion for 2026.
North America dominated with largest revenue share in 2025. This is attributed to the rapid technological developments and concentration of the major command and control system providers. Additionally, collaborative multinational military operations practiced by U.S. with the local governments in Middle East are contributing to the regional growth.
Key players in the market include Lockheed Martin Corporation; BAE Systems; Collins Aerospace; Thales; Leonardo S.p.A.; Elbit Systems Ltd.; Boeing; Northrop Grumman; Saab AB; CACI International Inc.; Barco; Christie Digital Systems USA, Inc.; InFocus; Activu Corporation; Panasonic Corporation; Planar; Datapath Ltd.; Extron; Matrox Graphics Inc.; Hiperwall, Inc.; Green Hippo Ltd. (tvOne); RTX; tvONE; RGB Spectrum; Userful Corporation; VuWall Technology Inc. and others.
The land command and control systems segment accounted for the largest revenue share of approximately 35.0% in 2025
About the Author(s)
Communications Infrastructure Research Team
Technology · Communications InfrastructureThis report was authored by the communications infrastructure research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the communications infrastructure segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


