
- Home
- »
- Animal Health
- »
-
Companion Animal Cardiac Drugs Market Report, 2026-2033GVR Report cover

Companion Animal Cardiac Drugs Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Pimobendan, Furosemide), By Animal Type (Dogs, Cats, Horses), By Indication, By End-use, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$2.0BMarket Estimate, 2026
$2.1BMarket Forecast, 2033
$3.9BCAGR, 2026–2033
9.1%Companion Animal Cardiac Drugs Market Summary
The global companion animal cardiac drugs market size was valued at USD 2.0 billion in 2025 and is projected to grow from USD 2.1 billion in 2026 to USD 3.9 billion by 2033, at a CAGR of 9.1% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 38.0% in 2025. The industry is driven by several key factors, including the rising prevalence of heart-related disorders in pets, increasing pet humanization and expenditure on pet healthcare, and continuous innovation in cardiology treatments.
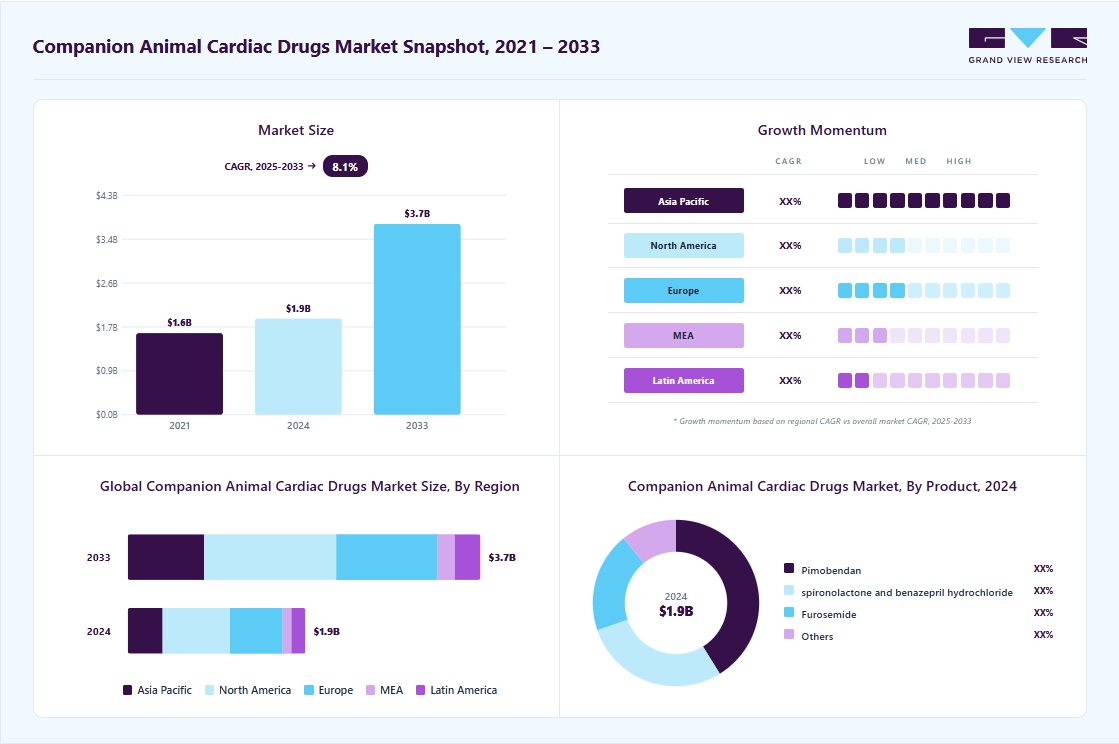 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By animal : Dogs segment led the market with the largest revenue share of 64.6% in 2025.
- By product: Pimobendan segment led the market with the largest revenue share of 41.1% in 2025
- By indication: Congestive heart failure (CHF) segment led the market with the largest revenue share of 38% in 2025.
- By end use: Veterinary hospitals and clinics segment led the market with the largest revenue share of 59.8% in 2025.
- By distribution channel: Hospital/clinic pharmacy segment led the market with the largest revenue share of 60.9% in 2025.
Regional Highlights
- Largest regional market: North America (38.0% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.0 Billion
- Estimated market size in 2026: USD 2.1 Billion
- Projected market size by 2033: USD 3.9 Billion
- CAGR (2026-2033): 9.1%
Prism AI by Grand View Research Free to tryAsk a question about the companion animal cardiac drugs marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Advancements in therapies and growing awareness about the importance of cardiac health in animals are encouraging pet owners to pursue specialized care. The rising penetration of pet insurance is playing a crucial role in driving the growth of the companion animal cardiac drugs market. Providers such as Frank and Trusted Insurance Services Ltd offer diverse insurance plans that cover a broad spectrum of illnesses, including heart disease, cancer, arthritis, diabetes, infections, and other chronic conditions. Such coverage eases the financial strain on pet owners, enabling them to opt for advanced treatments and commit to long-term therapies without hesitation. This increased affordability and access encourage earlier veterinary intervention and consistent use of prescribed medications, thereby expanding the treated patient pool and fueling sustained demand for cardiac drugs.
 To learn more about this report, Download Free Sample Report
Moreover, the market growth is accelerated by a combination of clinical, pharmaceutical, and awareness-driven initiatives. Collaborations between veterinary schools and private clinics in provinces such as Quebec and Alberta have facilitated the dissemination of updated cardiac care protocols, enabling veterinarians to diagnose and manage heart conditions more effectively. This has expanded the number of companion animals receiving timely treatment, directly increasing the demand for cardiac drugs. In parallel, pharmaceutical firms like Boehringer Ingelheim and Zoetis Canada have strengthened their provincial distribution networks, ensuring consistent availability of advanced medications. Reliable access encourages veterinarians to prescribe therapies with greater confidence, reducing treatment gaps and improving long-term management of chronic cardiac conditions.
At the same time, awareness campaigns led by organizations such as Humane Canada and the Canadian Veterinary Medical Association (CVMA) have played a crucial role in educating pet owners about early warning signs of heart disease, such as persistent coughing or reduced stamina. These initiatives prompt earlier veterinary consultations and timely initiation of treatment, further enlarging the treated patient pool. Collectively, improved clinical protocols, strong drug distribution infrastructure, and greater public awareness are fueling steady market growth, particularly in key drug categories like ACE inhibitors, diuretics, and beta-blockers.
Furthermore, regulatory approval is becoming increasingly important in the veterinary cardiology market as global demand for specialized animal care continues to grow. In the past, slow and restrictive approval processes limited the adoption of innovative treatments and medical devices, but regulatory agencies such as the U.S. FDA, the European Medicines Agency (EMA), and India’s CDSCO have started to adopt more facilitative approaches to ensure faster access to advanced veterinary solutions.
For instance, in May 2024, the FDA approved several animal drugs, including therapies for canine heart failure. Notably, UpCard-CA1, a torsemide oral solution, received conditional approval for treating pulmonary edema in dogs with congestive heart failure caused by myxomatous mitral valve disease (MMVD). Used in combination with established therapies such as pimobendan, spironolactone, and ACE inhibitors, this approval represents a significant advancement in veterinary cardiology by expanding treatment options and improving the management of cardiac conditions in dogs.
Market Dynamics
The industry is driven by several key factors, including the rising prevalence of heart-related disorders in pets, increasing pet humanization and expenditure on pet healthcare, and continuous innovation in cardiology treatments. Among these, increasing pet humanization and higher spending on companion animal healthcare continue to expand the adoption of specialized veterinary cardiology therapies. Pet owners are increasingly seeking early diagnosis and long-term management of chronic cardiac conditions such as myxomatous mitral valve disease (MMVD) and dilated cardiomyopathy (DCM), resulting in greater demand for prescription medications and regular cardiac monitoring.
Furthermore, improvements in veterinary diagnostic capabilities, wider availability of board-certified veterinary cardiologists, and increasing penetration of pet insurance have enhanced access to advanced treatment options. Regulatory approvals for novel formulations and generic alternatives are further improving product availability, while growing investments by pharmaceutical companies in veterinary cardiovascular therapeutics continue to strengthen the competitive landscape and support sustained market expansion.
The increasing emotional attachment between owners and companion animals has substantially influenced treatment decisions for chronic diseases, including cardiovascular disorders. Pet owners are increasingly willing to invest in advanced diagnostics, long-term pharmacological management, and routine follow-up consultations to improve quality of life and survival outcomes in affected animals. Higher disposable incomes across several developed and emerging economies, combined with expanding pet insurance coverage, have improved affordability of specialized cardiac therapies.
Veterinary hospitals are consequently witnessing higher demand for echocardiography, blood pressure monitoring, and long-term administration of medications such as pimobendan, ACE inhibitors, diuretics, and antiarrhythmic drugs. For instance, in July 2025, the U.S. FDA approved Boehringer Ingelheim's VETMEDIN-CA1 (pimobendan oral solution), the first treatment indicated to delay the onset of congestive heart failure in dogs with preclinical MMVD, expanding therapeutic options for early-stage disease management. Such product approvals continue to strengthen treatment adoption across companion animal cardiology.
Management of companion animal cardiac disorders frequently requires lifelong pharmacological therapy, periodic diagnostic imaging, laboratory testing, and repeated veterinary consultations, resulting in substantial treatment costs for pet owners. Chronic conditions such as MMVD and DCM often require combination therapy involving multiple prescription medications, increasing the overall financial burden throughout the treatment period. In several developing countries and rural regions, limited availability of veterinary cardiologists and advanced diagnostic equipment further delays diagnosis and treatment initiation.
In addition, smaller veterinary practices may lack access to echocardiography and specialized cardiovascular monitoring systems, restricting timely identification of cardiac abnormalities. Variations in reimbursement policies and relatively low penetration of pet insurance in several markets continue to limit access to advanced therapies. These factors reduce treatment compliance, delay disease management, and restrict wider adoption of premium companion animal cardiac drugs.
Growing clinical focus on identifying cardiac disease before the onset of congestive heart failure is creating significant opportunities for pharmaceutical manufacturers developing innovative veterinary cardiovascular therapies. Increasing use of routine cardiac screening, breed-specific health surveillance, and advanced imaging techniques is facilitating earlier diagnosis of degenerative heart diseases in companion animals, expanding the addressable treatment population. Pharmaceutical companies are investing in novel formulations, improved drug delivery systems, and lifecycle management strategies to enhance treatment adherence and clinical outcomes.
Furthermore, development of flavored oral formulations and generic alternatives is improving owner compliance while increasing product accessibility. For instance, in July 2025, Cronus Pharma introduced the first FDA-approved generic pimobendan chewable tablets for veterinary use, expanding treatment accessibility through a cost-competitive alternative. Moreover, continued research into disease-modifying therapies and preventive cardiovascular medicines is expected to create new commercial opportunities throughout the forecast period.
Market Concentration & Characteristics
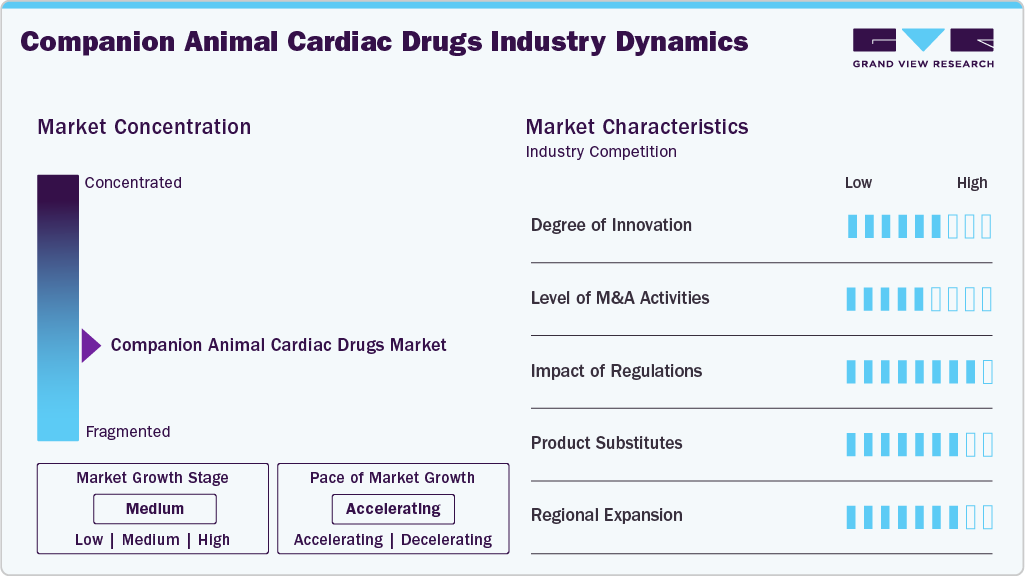
The industry is moderately concentrated, with growth momentum steadily accelerating. Leading global players, including Zoetis, Boehringer Ingelheim International GmbH, Merck & Co., Inc., Elanco, Ceva Santé Animale, and others, hold significant market shares. Their competitive edge is driven by robust R&D capabilities, extensive product portfolios, and well-established global distribution networks, enabling them to strengthen their presence and sustain market leadership.
The industry demonstrates moderate innovation. Beyond traditional drug classes, companies are investing in novel formulations, fixed-dose combinations, and improved delivery systems to enhance efficacy and compliance. A notable example is the development of Vetmedin (pimobendan), which has become a cornerstone therapy for managing congestive heart failure in dogs by improving both survival rates and quality of life. Innovation is further supported by ongoing clinical research, reformulations designed for ease of administration, and the integration of advanced monitoring practices.
 To learn more about this report, Download Free Sample Report
Mergers and acquisitions in the industry remain at a moderate level, primarily fueled by companies aiming to broaden their product offerings and extend their geographic presence. For instance, in December 2024, Siemens Healthineers acquired Advanced Accelerator Applications from Novartis. This acquisition expanded Siemens Healthineers' network of PET radio pharmacies, enhancing its capabilities in molecular imaging for various medical applications, including veterinary cardiology.
The industry is heavily influenced by regulatory oversight. Streamlined approval processes by agencies such as the U.S. FDA, European Medicines Agency (EMA), and India’s CDSCO have accelerated the introduction of new therapies, enabling faster availability of advanced treatments for conditions like congestive heart failure in pets. At the same time, strict safety, efficacy, and quality requirements ensure that only clinically validated and reliable drugs enter the market, strengthening veterinarian and pet owner confidence.
Product substitutes in the industry are relatively limited but can influence treatment approaches and demand. Alternatives such as nutraceuticals, dietary supplements, and specialized cardiac diets are sometimes used to support heart health in pets, either as complementary or partial substitutes for prescription drugs.
Companies leverage distributor networks, partnerships with veterinary hospitals & clinics, to establish local presence. For instance, in August 2024, Boehringer Ingelheim India partnered with Vvaan Lifesciences Pvt Ltd to enhance the availability of veterinary cardiology treatments in underserved regions, including Tier 2 cities and rural areas.
Animal Type Insights
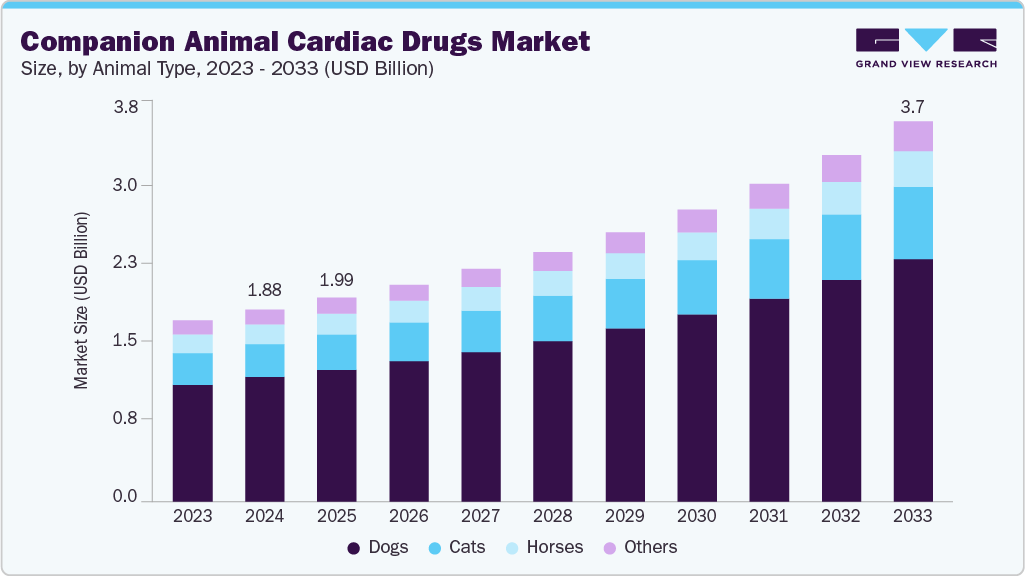
Based on animal, the dogs segment led the market with the largest revenue share of 64.6% in 2025. Dogs are regarded as one of the most common and preferred companion animals, surpassing cats and other pets in popularity, and their growing presence in households is closely tied to rising pet health expenditure. The increasing number of dog-owning families has significantly boosted demand for veterinary care, including specialized treatments such as cardiac treatments. In the U.S., for example, 86.9 million households own a pet, with dogs leading as the most popular choice (present in 65.1 million households), compared to 46.5 million households that own cats. This dominance highlights the central role of dogs in the pet population, driving higher spending on healthcare and supporting the growth of veterinary care services and cardiac drug adoption.
The cats segment is projected to witness the fastest growth in the global market, fueled by the rising prevalence of heart-related disorders, coupled with increasing obesity in cats. According to the Purina Institute, studies estimate that up to 63% of pet cats worldwide are overweight or obese. Excess weight places additional strain on the cardiovascular system, contributing to hypertension, reduced cardiac efficiency, and a higher risk of developing heart disease. The same source also highlights that around 15% of cats are affected by cardiac conditions, with the majority suffering from cardiomyopathies. This close link between obesity and cardiovascular disorders underscores the growing need for effective management strategies, including cardiac drugs, to improve long-term health outcomes in felines.
Product Insights
Based on product, the pimobendan segment led the market with the largest revenue share of 41.1% in 2025 and other products segment is expected to grow at the fastest CAGR over the forecast period, as it has become the standard of care for managing congestive heart failure, particularly in dogs suffering from conditions such as dilated cardiomyopathy (DCM) and myxomatous mitral valve disease (MMVD). Its dual mechanism, as both inodilators improving cardiac contractility while simultaneously reducing vascular resistance, offers superior therapeutic benefits compared to traditional treatments. Widely recommended in veterinary guidelines and backed by strong clinical evidence, pimobendan not only extends survival time but also enhances quality of life in affected pets.
The other segment is anticipated to grow at the fastest rate over the forecast period. Beyond the leading therapies, other cardiac drugs are playing a critical role in driving market growth by addressing diverse needs in managing companion animal heart disease. ACE inhibitors such as enalapril and benazepril are widely prescribed to reduce cardiac workload and slow disease progression, making them essential for long-term management. Beta-blockers, including atenolol, are increasingly used to control arrhythmias and improve heart rhythm stability, especially in cats with hypertrophic cardiomyopathy.
Indication Insights
Based on indication, the congestive heart failure (CHF) segment led the market with the largest revenue share of 38% in 2025. A study published by Himachal Journal of Agricultural Research in June 2025 highlights important demographic trends in the incidence of congestive heart failure (CHF) among dogs. The findings indicate that CHF occurs disproportionately in male dogs, accounting for nearly 75% of reported cases, suggesting potential sex-related physiological or hormonal predispositions. Furthermore, the condition is found to be more prevalent in dogs weighing over 15 kg, underscoring the role of body size and associated cardiovascular strain in disease development. These insights emphasize the need for targeted monitoring and early interventions in higher-risk groups, particularly larger male dogs, to improve clinical outcomes and strengthen preventive veterinary care strategies.
The other segment is anticipated to grow at the fastest CAGR over the forecast period, as these conditions, such as patent ductus arteriosus (PDA), ventricular septal defects, and pulmonic stenosis, are increasingly being diagnosed in dogs and cats due to advances in veterinary diagnostics and heightened pet owner awareness. With congenital defects often requiring lifelong management to improve survival rates and quality of life, veterinarians prescribe a range of cardiac drugs, including diuretics, ACE inhibitors, beta-blockers, and anti-arrhythmic agents.
End-use Insights
Based on end use, the veterinary hospitals and clinics segment led the market with the largest revenue share of 59.8% in 2025, as they act as the primary channel for prescribing and dispensing medications, ensuring proper treatment and management of heart conditions in pets. They are trusted by pet owners for professional guidance, continuous monitoring, and adjustments in drug regimens, which strengthens their role as the main distribution and care centers. Moreover, the growing number of veterinary practices and increasing pet visits for specialized care enhance their market share, making hospitals and clinics the key drivers of demand for cardiac drugs.
The other segment is anticipated to grow at the fastest CAGR over the forecast period. Academic and research institutes, along with specialty and emergency animal care centers, drive the companion animal cardiac drugs market by fostering advanced clinical research, developing innovative treatment protocols, and offering specialized care for complex cardiac conditions that general veterinary practices often cannot manage. These institutions play a dual role: they not only serve as referral hubs where pets with severe or rare heart disorders receive advanced diagnostics and therapies, but also contribute to continuous education and clinical trials that expand the availability and adoption of new cardiac drugs. Their influence enhances awareness among veterinarians and pet owners, increases the demand for evidence-based treatments, and accelerates the integration of novel pharmaceuticals into routine practice, thereby fuelling overall market growth.
Distribution Channel Insights
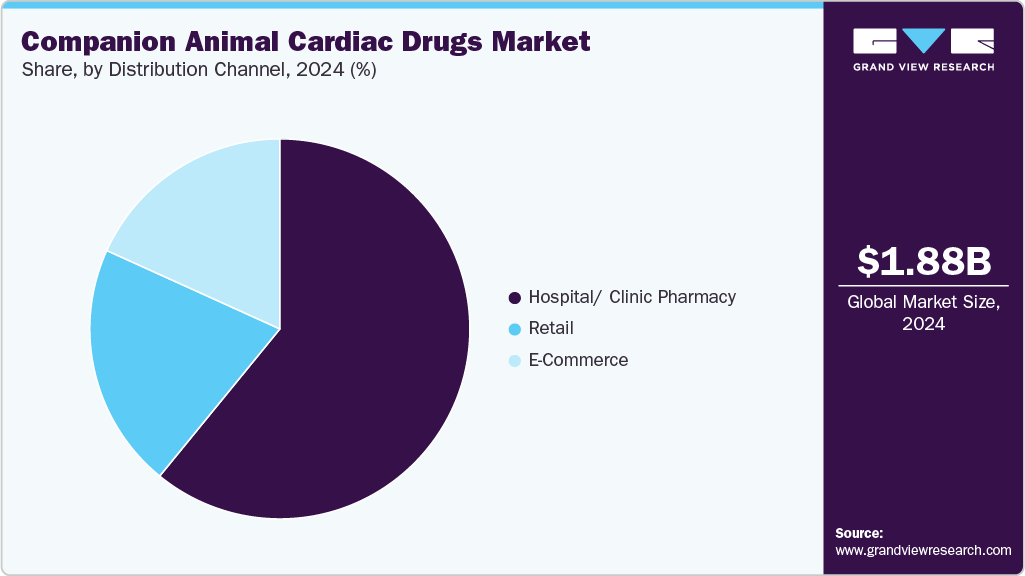
Based on distribution channel, the hospital/clinic pharmacy segment led the market with the largest revenue share of 60.9% in 2025 and e-commerce is expected to grow at the fastest growth rate over the forecast period, by serving as the primary point of access for prescribed medications, ensuring the timely and reliable availability of treatments for conditions such as heart failure, arrhythmias, and congenital defects. These pharmacies not only provide a controlled supply chain that guarantees the quality and authenticity of drugs but also enable veterinarians to closely monitor treatment compliance and adjust therapies as needed. With the increasing prevalence of cardiac disorders in pets and the growing preference for professional veterinary care, hospital and clinic pharmacies strengthen the distribution network and significantly contribute to market growth by fostering trust, accessibility, and continuity of care.
 To learn more about this report, Download Free Sample Report
The E-commerce segment is expected to grow at the fastest rate over the forecast period. Online veterinary pharmacies and platforms make it easier for owners to refill prescriptions, compare brands, and access specialized cardiac drugs that may not always be available at local clinics, ensuring consistent treatment adherence for pets with chronic heart conditions. Additionally, the growing trend of telemedicine integration with e-commerce platforms further enhances accessibility, enabling veterinarians to prescribe and directly link medications online, thereby fueling sales growth and expanding the overall reach of the market.
Regional Insights
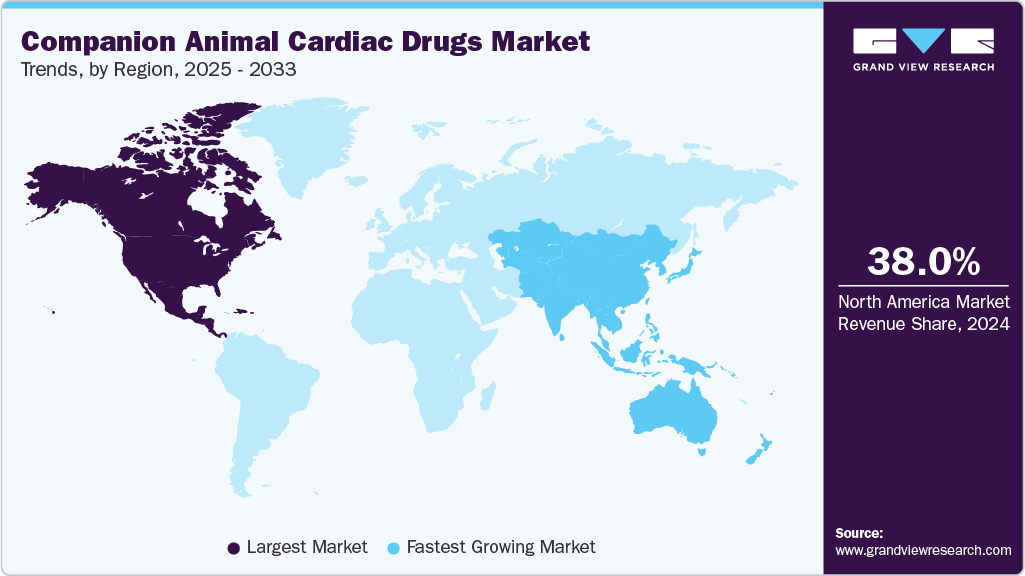
North America dominated the companion animal cardiac drugs market with a share of 38.0% in 2025, due to its high rate of pet ownership, advanced veterinary healthcare infrastructure, and strong spending capacity of pet owners on specialized treatments. For example, the American Pet Products Association (APPA) reports that U.S. pet care expenditure continues to rise annually, with a significant portion directed toward veterinary services and medications, reflecting the growing willingness of owners to invest in cardiac care for dogs and cats. The region also benefits from early adoption of advanced diagnostics, widespread availability of prescription drugs through veterinary clinics and e-commerce platforms, and the presence of leading pharmaceutical companies such as Zoetis and Elanco, which ensure a steady supply of innovative cardiac drugs, collectively making North America a key driver of market expansion.
 To learn more about this report, Download Free Sample Report
U.S. Companion Animal Cardiac Drugs Market Trends
The companion animal cardiac drugs market in the U.S. held the largest share in the North America region in 2025. The companion animal cardiac drugs market in the U.S. is fueled by a robust healthcare infrastructure and high pet care expenditure. Rising investments in veterinary services reflect a growing willingness among pet owners to pursue specialized treatments for chronic and complex conditions, including cardiac disorders. According to the American Pet Products Association (APPA), pet expenditures surpassed USD 151.9 billion in 2025, with an increasing share allocated to advanced veterinary care. This trend underscores the expanding prioritization of animal health, creating favorable conditions for the adoption of cardiac therapies and driving consistent growth in the market.
Europe Companion Animal Cardiac Drugs Market Trends
The companion animal cardiac drugs market in Europe is supported by rising pet ownership and continuous advancements in veterinary healthcare. Moreover, the region’s aging pet population is another key growth factor, as older animals are more susceptible to cardiovascular conditions, thereby increasing the need for advanced cardiac care. This trend is especially evident in countries such as Italy and Spain, where veterinary clinics are expanding services like blood pressure monitoring to address the needs of senior pets. Highlighting this shift, AniCura reported in February 2024 that senior pets represent a growing segment in Europe, with 31% of dogs and 33% of cats now classified as elderly, underscoring the rising demand for targeted cardiology services.
Germany companion animal cardiac drugs market is driven by a well-established pet healthcare system and a steady rise in pet ownership. Growing adoption, particularly among middle-income households, has increased demand for advanced veterinary services, including cardiology care. According to the International Trade Administration, in 2023, around 45% of German households owned a pet, with 14% owning two or more, totaling approximately 34.3 million pets nationwide. Cats and dogs continue to dominate pet preferences, with cats present in 25% of households, underscoring their enduring popularity and further supporting the demand for specialized veterinary services such as cardiac care.
Asia Pacific Companion Animal Cardiac Drugs Market Trends
The companion animal cardiac drugs market in Asia Pacific is anticipated to grow at the fastest CAGR over the forecast period, driven by increasing awareness of pet health and a rise in veterinary visits, particularly in urban centers. For instance, in countries such as China, rapid urbanization and shifting attitudes toward pet care have fueled demand for specialized cardiac services. Major cities like Shanghai and Beijing are witnessing a surge in cases requiring advanced cardiovascular management, supported by modern facilities such as the Shanghai Companion Animal Hospital, which provides dedicated cardiology care.
Japan companion animal cardiac drugs market is witnessing steady growth, primarily fueled by the rising pet population and the increasing prevalence of age-related heart conditions in companion animals. With many Japanese households treating pets as family members, there is a strong willingness to invest in advanced medical treatments, including long-term cardiac therapies. The aging pet population has particularly driven demand for medicines such as ACE inhibitors, diuretics, and inodilators, which are essential for managing chronic heart conditions like congestive heart failure.
Latin America Companion Animal Cardiac Drugs Market Trends
The companion animal cardiac drugs market in Latin America is fueled by the expansion of education and training programs within the region. For instance, in Brazil, several universities have introduced specialized veterinary cardiology courses, reflecting the increasing demand for skilled professionals capable of addressing complex cardiac conditions in pets. These academic initiatives are equipping new veterinarians with advanced knowledge of treatment protocols and the latest therapeutic approaches.
Argentinacompanion animal cardiac drugs market is driven by key developments centered in major urban areas. Major cities such as Buenos Aires, Córdoba, and Rosario are seeing significant growth in advanced veterinary practices that specialize in cardiology services. These clinics also work in close collaboration with academic institutions, promoting research in veterinary heart care and improving clinical outcomes for companion animals nationwide. The increasing adoption of modern treatment approaches and integration of global best practices are further elevating the standard of veterinary cardiology in Argentina. Together, these efforts are expanding access to specialized care and driving continuous market growth across the country.
Middle East & Africa Companion Animal Cardiac Drugs Market Trends
The companion animal cardiac drugs market in the Middle East is driven by the rising pet ownership and the growing need for specialized veterinary care. In the UAE, the increasing trend of pet adoption has driven demand for advanced treatments, including cardiac treatment. Similarly, in Saudi Arabia, premium veterinary clinics are now equipped to manage complex conditions such as heart failure and arrhythmias in companion animals. Economic growth in countries like Qatar and Kuwait is also enhancing affordability for high-end pet healthcare. Collectively, these factors are contributing to the expansion of veterinary cardiology facilities across the region, ensuring pets have access to high-quality and specialized care.
South Africacompanion animal cardiac drugs market is driven by the growth of the middle-class population, which has led to increased spending on pet wellness and preventive care. South African pet owners opt for regular check-ups and specialty consultations, contributing to a higher demand for cardiology evaluations. For instance, in January 2025, the Owner of a new pet in South Africa spent an average of USD 2,700 on vet fees in the first year. In addition, the veterinary pharmaceutical sector in the country is expanding, making advanced medications for cardiac conditions more accessible.
Key Companion Animal Cardiac Drugs Company Insights
Key players operating in the companion animal cardiac drugs market are undertaking various initiatives to strengthen their presence and increase the reach of their products and services. Strategies such as expansion activities and partnerships are key in propelling the market growth.
Key Companion Animal Cardiac Drugs Companies
The following key companies have been profiled for this study on the companion animal cardiac drugs market.
-
Boehringer Ingelheim International GmbH
-
Ceva
-
Elanco
-
Virbac
-
Zoetis
-
Dechra Pharmaceuticals PLC
-
Bimeda Corporate
-
Biogénesis Bagó
-
Merck & Co., Inc.
-
Vetoquinol SA
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Boehringer Ingelheim International GmbH, Zoetis, Elanco, Merck & Co., Inc., Ceva, Virbac, Vetoquinol SA, Dechra Pharmaceuticals PLC)
Established companies focus on expanding their companion animal cardiology portfolios through product innovation, lifecycle management, regulatory approvals, geographic expansion, strategic acquisitions, veterinary education programs, and strengthened distribution networks. Their strategies include development of novel formulations, expansion of label indications, investment in clinical studies, collaborations with veterinary hospitals and academic institutions, and increased commercialization of branded cardiovascular therapies across major companion animal markets.
These companies benefit from extensive global distribution networks, diversified companion animal pharmaceutical portfolios, established relationships with veterinarians, strong regulatory expertise, significant R&D investments, recognized brands, and broad manufacturing capabilities. Their financial strength enables continuous product development, rapid commercialization, wider market access, and sustained customer loyalty across developed and emerging markets.
High research and regulatory expenditures, lengthy product development timelines, increasing generic competition following patent expiry, pricing pressure in mature markets, and complex global regulatory requirements may affect commercial flexibility. Large organizational structures may also delay portfolio expansion and commercialization of newer cardiovascular therapies compared with smaller specialized pharmaceutical companies.
Emerging Players (AYURSUN PHARMA, Vetraise Remedies, Garuda Trade Kft., Animal Health Bioved, Curafyt, Euro Herbals)
Emerging companies compete by expanding regional pharmaceutical portfolios, introducing cost-effective generic products, strengthening partnerships with veterinary distributors, increasing manufacturing capabilities, and targeting underserved markets. Their commercial strategies include geographic expansion across developing countries, product registrations in new markets, collaborations with veterinary practices, and portfolio diversification within companion animal therapeutics.
These companies offer competitive pricing, greater operational flexibility, faster regional product commercialization, and strong relationships with local distributors and veterinary professionals. Their focused business models allow quicker response to regional demand, improved accessibility of veterinary medicines, and growing presence in price-sensitive markets.
Limited global commercial presence, comparatively smaller R&D budgets, narrower product portfolios, lower brand recognition, and restricted distribution capabilities may constrain expansion into highly competitive international markets. Dependence on regional sales and generic products may further limit competitive positioning against multinational animal health companies with diversified cardiovascular portfolios and established veterinary relationships.
Recent Developments
-
In February 2024, Boehringer Ingelheim partnered with Veeva Systems to enhance its clinical and regulatory operations in animal health. This collaboration aims to streamline clinical execution and accelerate the development of new veterinary medicines, including those targeting cardiovascular diseases in animals.
-
In November 2024,VETMEDIN Solution first FDA-approved oral solution for managing canine congestive heart failure due to myxomatous mitral valve disease (MMVD) or dilated cardiomyopathy (DCM).
-
In August 2023, Boehringer Ingelheim India partnered with Vvaan Lifesciences Pvt Ltd to enhance the availability of veterinary cardiology treatments in underserved regions, including Tier 2 cities and rural areas.
Companion Animal Cardiac Drugs Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.0 billion
Estimated market size in 2026
USD 2.1 billion
Projected market size by 2033
USD 3.9 billion
Growth rate
CAGR of 9.1% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Animal, product, indication, end use, and distribution channel
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Oman; Qatar.
Key companies profiled
Boehringer Ingelheim International GmbH; Ceva; Elanco; Virbac; Zoetis; Dechra Pharmaceuticals PLC; Bimeda Corporate; Biogénesis Bagó; Merck & Co., Inc.; Vetoquinol SA
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Companion Animal Cardiac Drugs Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global companion animal cardiac drugs market report based on animal type, product, indication, end-use, distribution channel, and region.
-
Animal Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Dogs
-
Cats
-
Horses
-
Others
-
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Pimobendan
-
Spironolactone and benazepril hydrochloride
-
Furosemide
-
Others
-
-
Indication Outlook (Revenue, USD Million, 2021 - 2033)
-
Congestive Heart Failure
-
Myocardial (Heart Muscle) Disease
-
Arrhythmias
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Veterinary Hospitals & Clinics
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital/ Clinic Pharmacy
-
Retail
-
E-Commerce
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
India
-
China
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
Qatar
-
Oman
-
-
Research Methodology
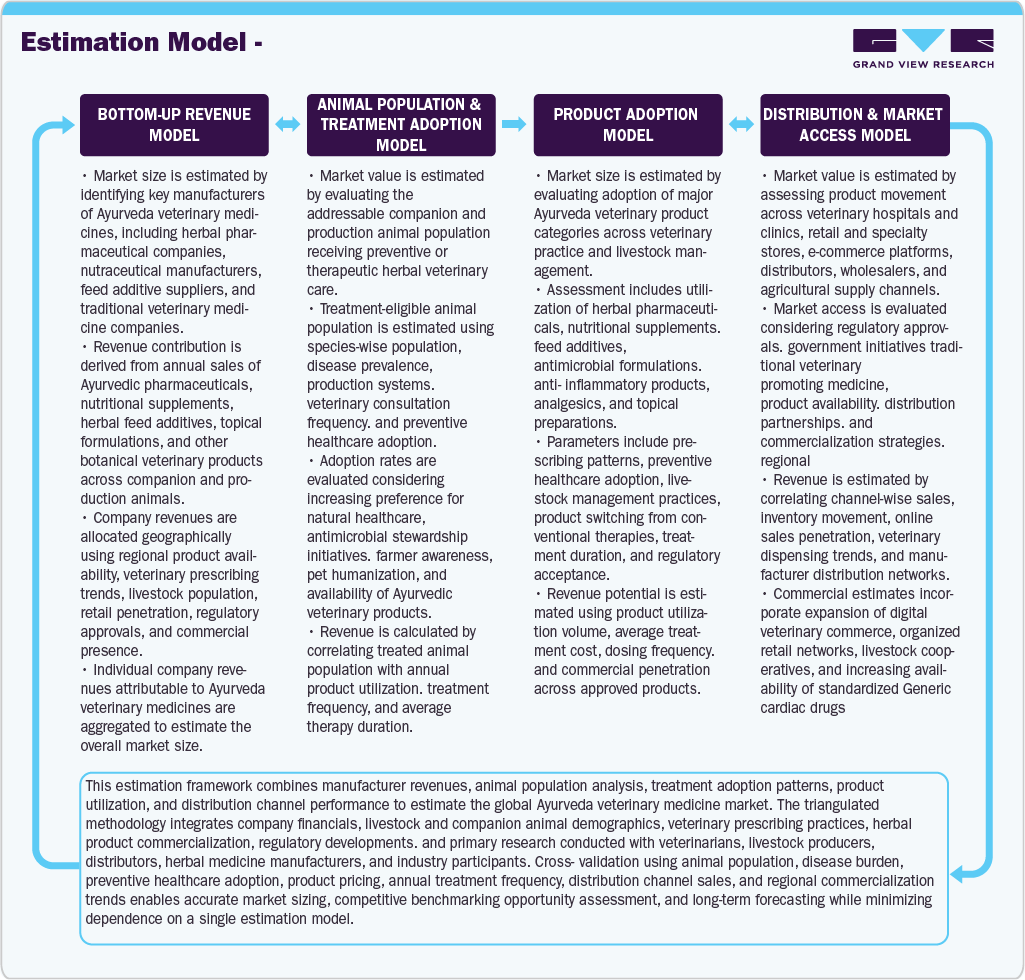
The companion animal cardiac drugs Market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each companion animal cardiac drugs Market segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Animal
Revenue Capture Definition
Dogs
Revenue generated from cardiac drugs administered to dogs for the management of cardiovascular disorders, including congestive heart failure, myxomatous mitral valve disease (MMVD), dilated cardiomyopathy, arrhythmias, and hypertension.
Cats
Revenue generated from cardiac drugs prescribed for cats to manage cardiovascular conditions such as hypertrophic cardiomyopathy, congestive heart failure, systemic hypertension, thromboembolic complications, and other cardiac disorders.
Horses
Revenue generated from cardiac drugs utilized in horses for the treatment and management of arrhythmias, valvular disorders, myocardial diseases, exercise-associated cardiac conditions, and other cardiovascular abnormalities.
Others
Revenue generated from cardiac drugs administered to other companion animals, including rabbits, ferrets, birds, and exotic pets requiring pharmacological management of cardiovascular disorders.
Segment - Product
Revenue Capture Definition
Pimobendan
Revenue generated from pimobendan formulations prescribed to improve cardiac contractility and manage congestive heart failure and preclinical myxomatous mitral valve disease, primarily in dogs.
Spironolactone and Benazepril Hydrochloride
Revenue generated from combination therapies containing spironolactone and benazepril hydrochloride used for long-term management of congestive heart failure, cardiac remodeling, and hypertension in companion animals.
Furosemide
Revenue generated from furosemide formulations prescribed for the treatment of pulmonary edema, fluid retention, and congestive heart failure associated with cardiovascular diseases in companion animals.
Others
Revenue generated from other companion animal cardiac drugs, including ACE inhibitors, beta-blockers, antiarrhythmic agents, calcium channel blockers, vasodilators, cardiac glycosides, and adjunct cardiovascular therapies.
Segment - Indication
Revenue Capture Definition
Congestive Heart Failure
Revenue generated from cardiac drugs utilized for the treatment and long-term management of congestive heart failure resulting from conditions such as myxomatous mitral valve disease, dilated cardiomyopathy, and other structural heart diseases.
Myocardial (Heart Muscle) Disease
Revenue generated from cardiac drugs prescribed for myocardial disorders affecting cardiac muscle function, including cardiomyopathies, myocarditis, and myocardial dysfunction in companion animals.
Arrhythmias
Revenue generated from antiarrhythmic and supportive cardiac therapies utilized to manage abnormal heart rhythms, conduction disorders, and associated cardiovascular complications in companion animals.
Others
Revenue generated from cardiac drugs prescribed for other cardiovascular indications, including systemic hypertension, valvular disorders, pulmonary hypertension, thromboembolic complications, and other cardiac conditions.
Segment - End Use
Revenue Capture Definition
Veterinary Hospitals & Clinics
Revenue generated from cardiac drugs prescribed, dispensed, and administered through veterinary hospitals, specialty cardiology centers, and general veterinary clinics for diagnosis and treatment of cardiovascular diseases in companion animals.
Others
Revenue generated from companion animal cardiac drugs supplied through other end users, including academic veterinary institutions, animal shelters, research organizations, and home-based veterinary care providers.
Segment - Distribution Channel
Revenue Capture Definition
Hospital/Clinic Pharmacy
Revenue generated from companion animal cardiac drugs dispensed directly through veterinary hospital and clinic pharmacies following clinical diagnosis and prescription.
Retail
Revenue generated from companion animal cardiac drugs sold through retail veterinary pharmacies, licensed pharmacy chains, and independent veterinary medicine retailers.
E-Commerce
Revenue generated from companion animal cardiac drugs distributed through online veterinary pharmacies, digital pharmacy platforms, and authorized e-commerce channels offering home delivery of veterinary cardiovascular medications.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Companion Animal Cardiac Disease Burden & Treatment Landscape Assessment
Evaluated disease prevalence across major companion animals, including myxomatous mitral valve disease (MMVD), dilated cardiomyopathy, congestive heart failure, arrhythmias, and other cardiovascular disorders. Assessed diagnosis rates, treated patient population, breed-specific disease incidence, clinical management pathways, and long-term pharmacological treatment patterns across key markets.
Enables stakeholders to identify high-growth therapeutic indications, quantify the addressable treatment population, prioritize regional commercialization strategies, and align product development with evolving clinical demand.
Competitive Portfolio & Regulatory Benchmarking
Assessed branded and generic cardiovascular drug portfolios, regulatory approvals, product lifecycle strategies, pipeline assets, label expansions, distribution partnerships, and commercialization activities of leading animal health companies. Evaluated competitive positioning across major cardiac drug classes and regional markets.
Supports identification of portfolio expansion opportunities, licensing prospects, generic entry potential, competitive differentiation strategies, and market gaps across the global companion animal cardiovascular therapeutics landscape.
Veterinary Prescribing Behavior & Commercial Opportunity Assessment
Evaluated prescribing trends across veterinary hospitals, specialty cardiology centers, and general veterinary practices. Assessed product adoption by drug class, treatment duration, patient compliance, pet insurance influence, generic substitution, distribution channel performance, and regional prescribing preferences.
Enables companies to optimize launch strategies, strengthen veterinary engagement, identify high-value distribution channels, improve market penetration, and prioritize investment opportunities across mature and emerging companion animal healthcare markets.
Frequently Asked Questions About This Report
Based on animal, the dogs segment led the market with the largest revenue share of 64.6% in 2025.
Based on product, the pimobendan segment led the market with the largest revenue share of 41.1% in 2025 and other products segment is expected to grow at the fastest CAGR over the forecast period.
Based on indication, the congestive heart failure (CHF) segment led the market with the largest revenue share of 38% in 2025.
Based on distribution channel, the hospital/clinic pharmacy segment led the market with the largest revenue share of 60.9% in 2025 and e-commerce is expected to grow at the fastest growth rate over the forecast period.
North America dominated the companion animal cardiac drugs market with a share of 38.0% in 2025. This is attributable to high rate of pet ownership, advanced veterinary healthcare infrastructure, and strong spending capacity of pet owners on specialized treatments.
The global companion animal cardiac drugs market size was estimated at USD 2.0 billion in 2025 and is expected to reach USD 2.1 billion in 2026.
The global companion animal cardiac drugs market is expected to grow at a compound annual growth rate of 9.1% from 2026 to 2033 to reach USD 3.9 billion by 2033.
Some key players operating in the companion animal cardiac drugs market include Boehringer Ingelheim International GmbH; Boehringer Ingelheim International GmbH, Ceva, Elanco, Virbac, Zoetis, Dechra Pharmaceuticals PLC, Bimeda Corporate, Biogénesis Bagó, Merck & Co., Inc., Vetoquinol SA
Key factors that are driving the market growth include the rising prevalence of heart-related disorders in pets, increasing pet humanization and expenditure on pet healthcare, and continuous innovation in cardiology treatments.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


