
- Home
- »
- Medical Devices
- »
-
Corneal Implants Market Size, Share & Trends Report, 2033GVR Report cover

Corneal Implants Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Human Tissue, Synthetic), By Surgery Method (Penetrating Keratoplasty, Endothelial Keratoplasty), By Application, By End use, By Region, And Segment Forecasts
Market Size, 2025
$518.5MMarket Estimate, 2026
$539.5MMarket Forecast, 2033
$711.8MCAGR, 2026–2033
4.0%Corneal Implants Market Summary
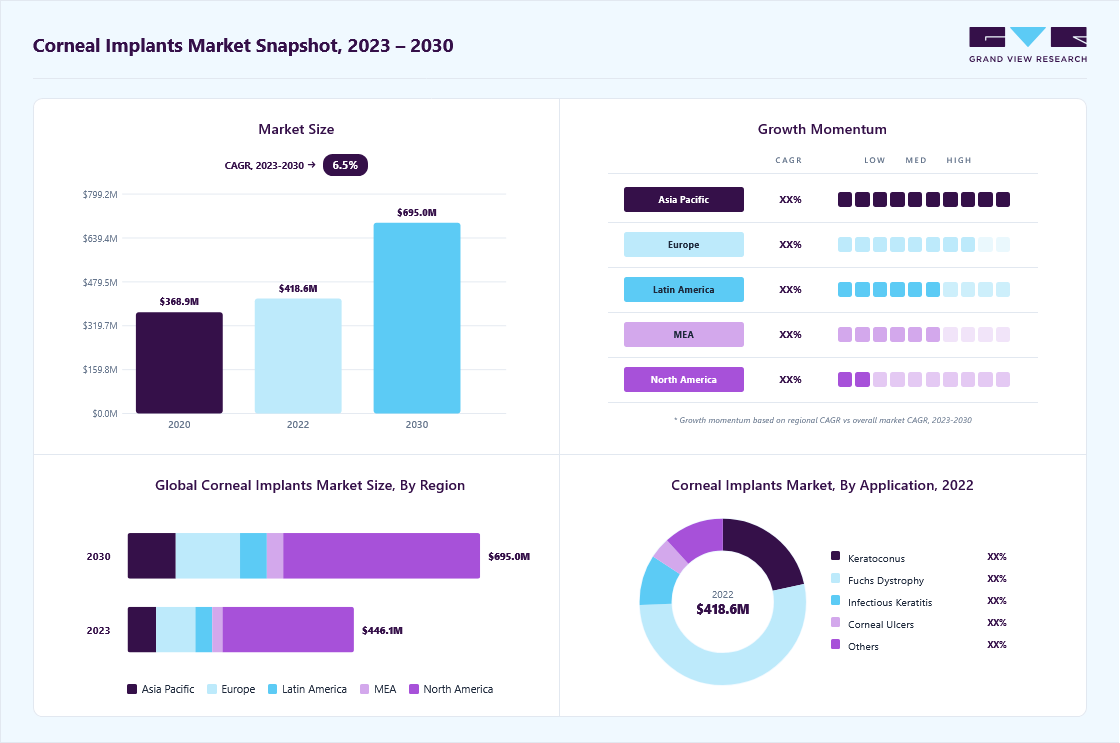
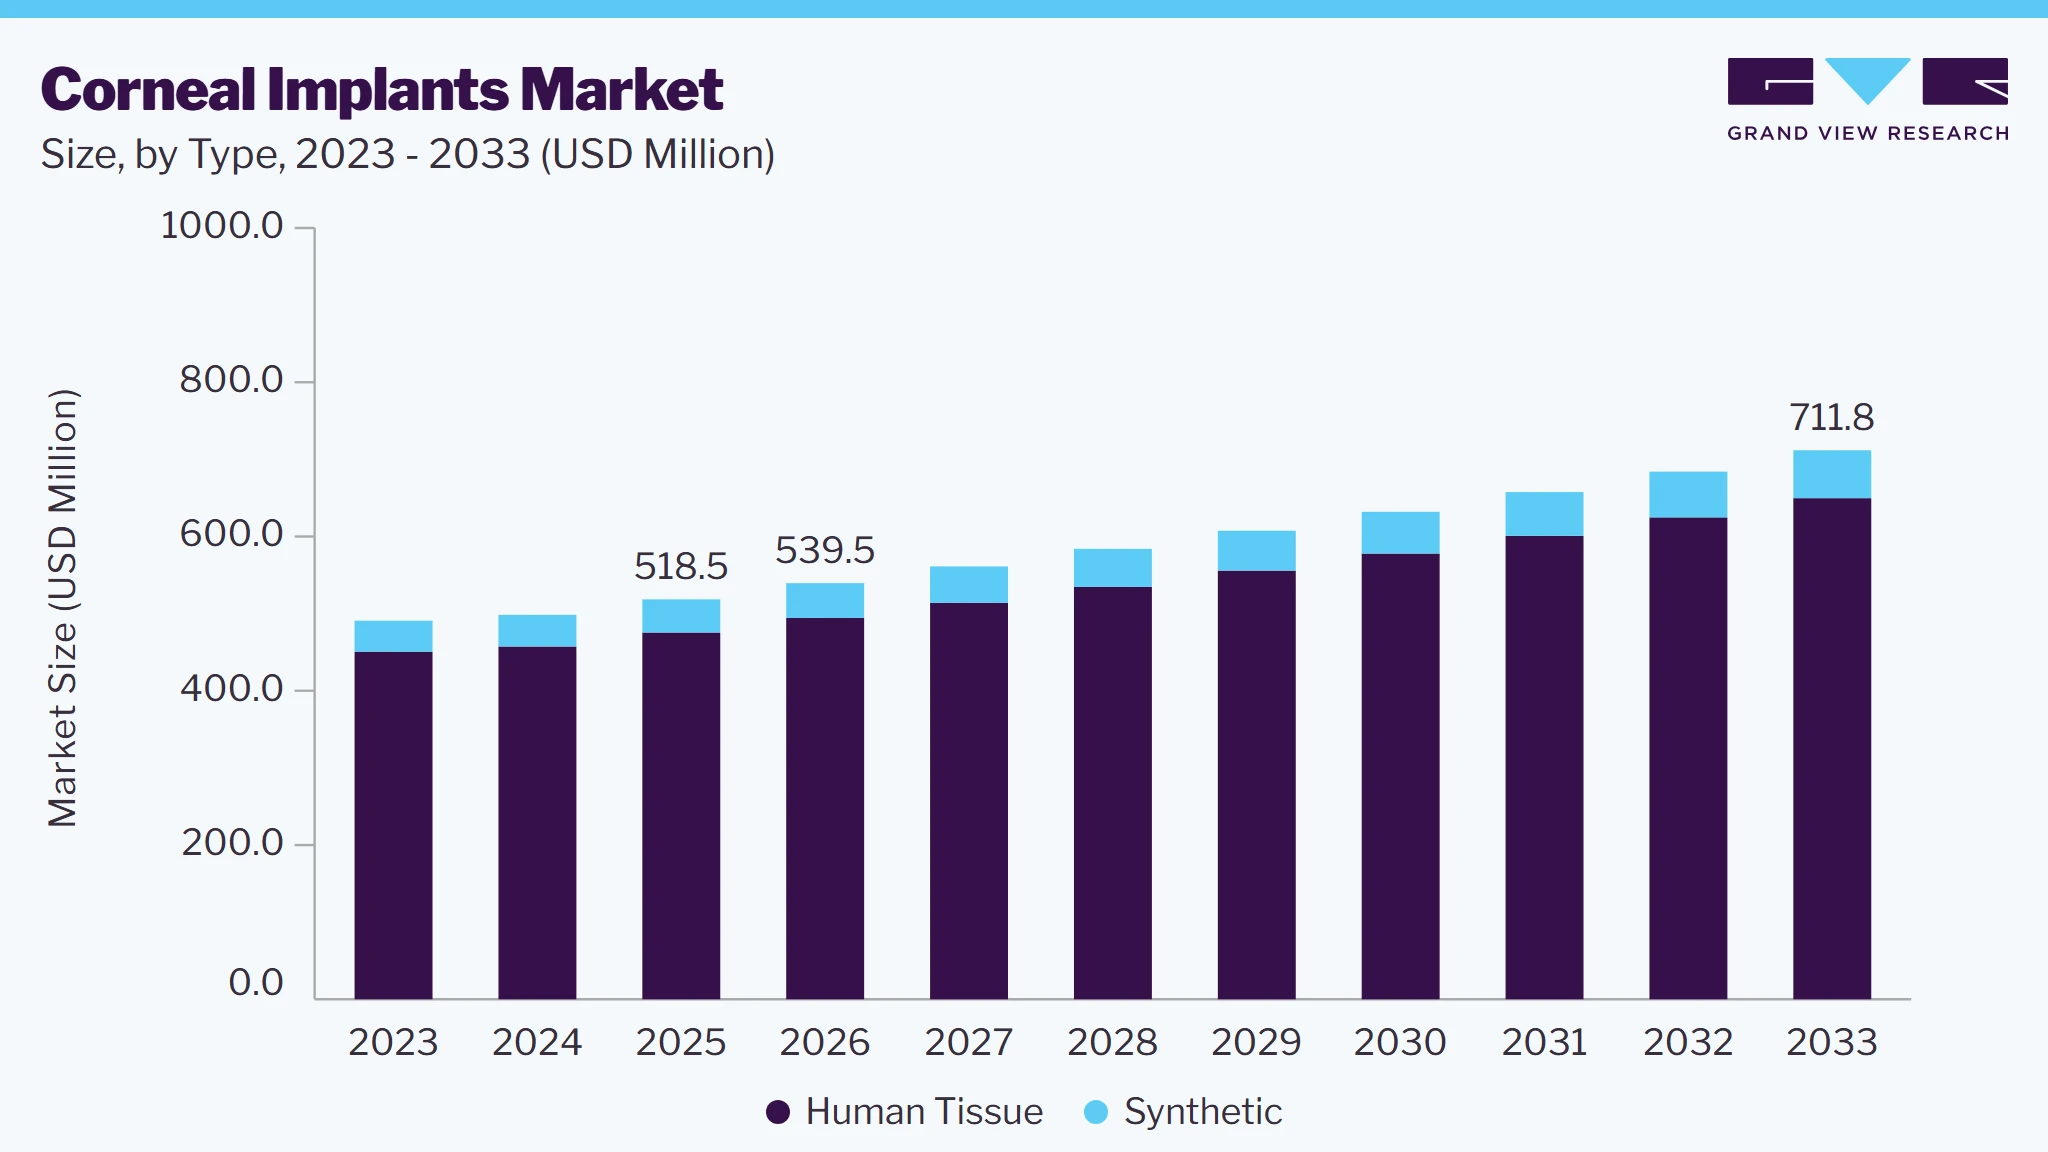
The global corneal implants market size was valued at USD 518.5 million in 2025 and is projected to grow from USD 539.5 million in 2026 to USD 711.8 million by 2033, at a CAGR of 4.0% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 57.4% of in 2025. The global corneal implants market is experiencing strong growth, driven by the rising prevalence of corneal disorders, increasing demand for corneal transplantation, and advancements in corneal tissue processing and synthetic implant technologies.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Human tissue segment held the highest market share of 91.7% in 2025.
- By surgery method: Penetrating keratoplasty segment held a leading market share in 2025.
- By application: Fuchs dystrophy segment held a leading market share in 2025.
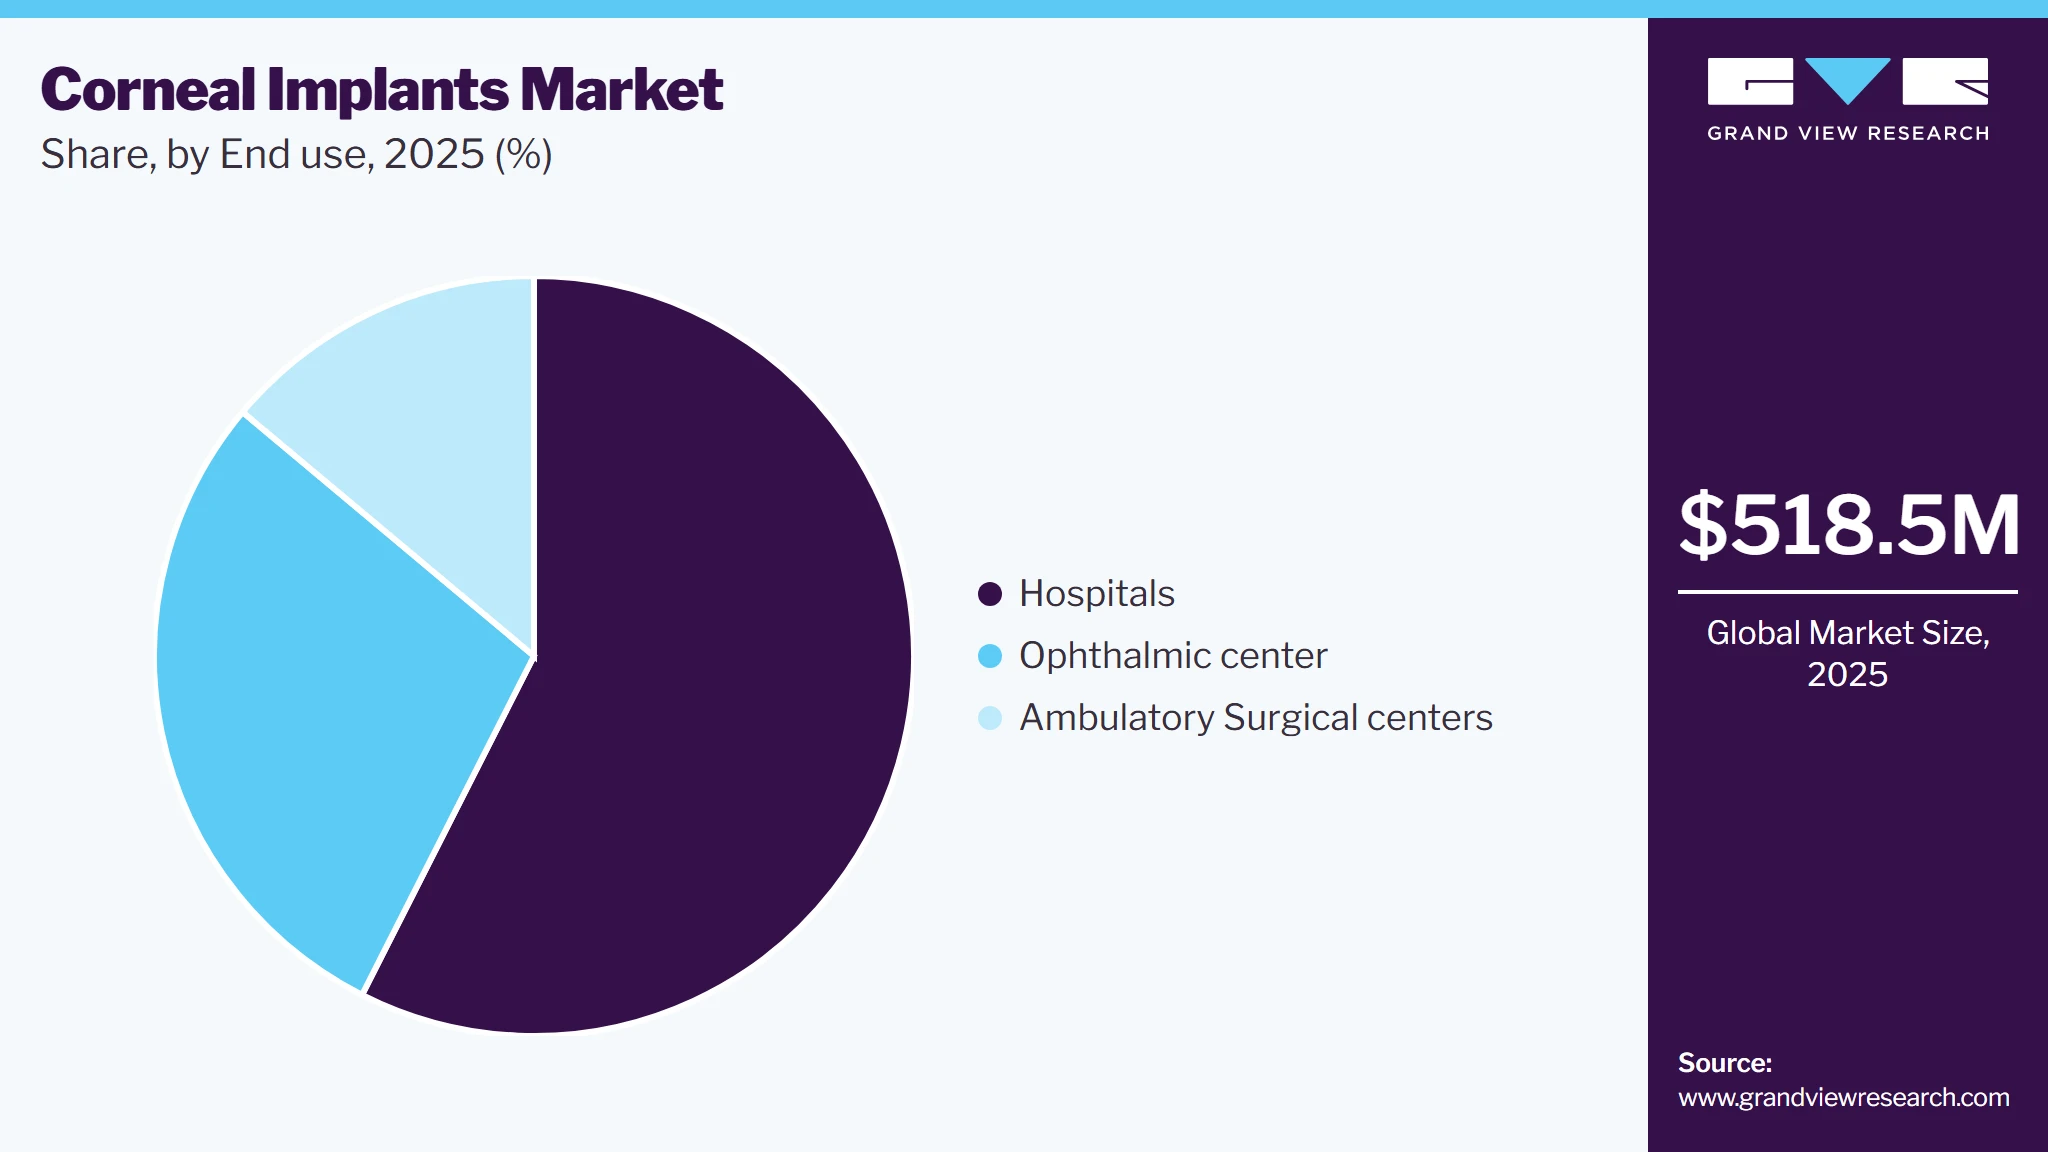
- By end use: Hospitals segment held a leading market share in 2025.
Regional Highlights
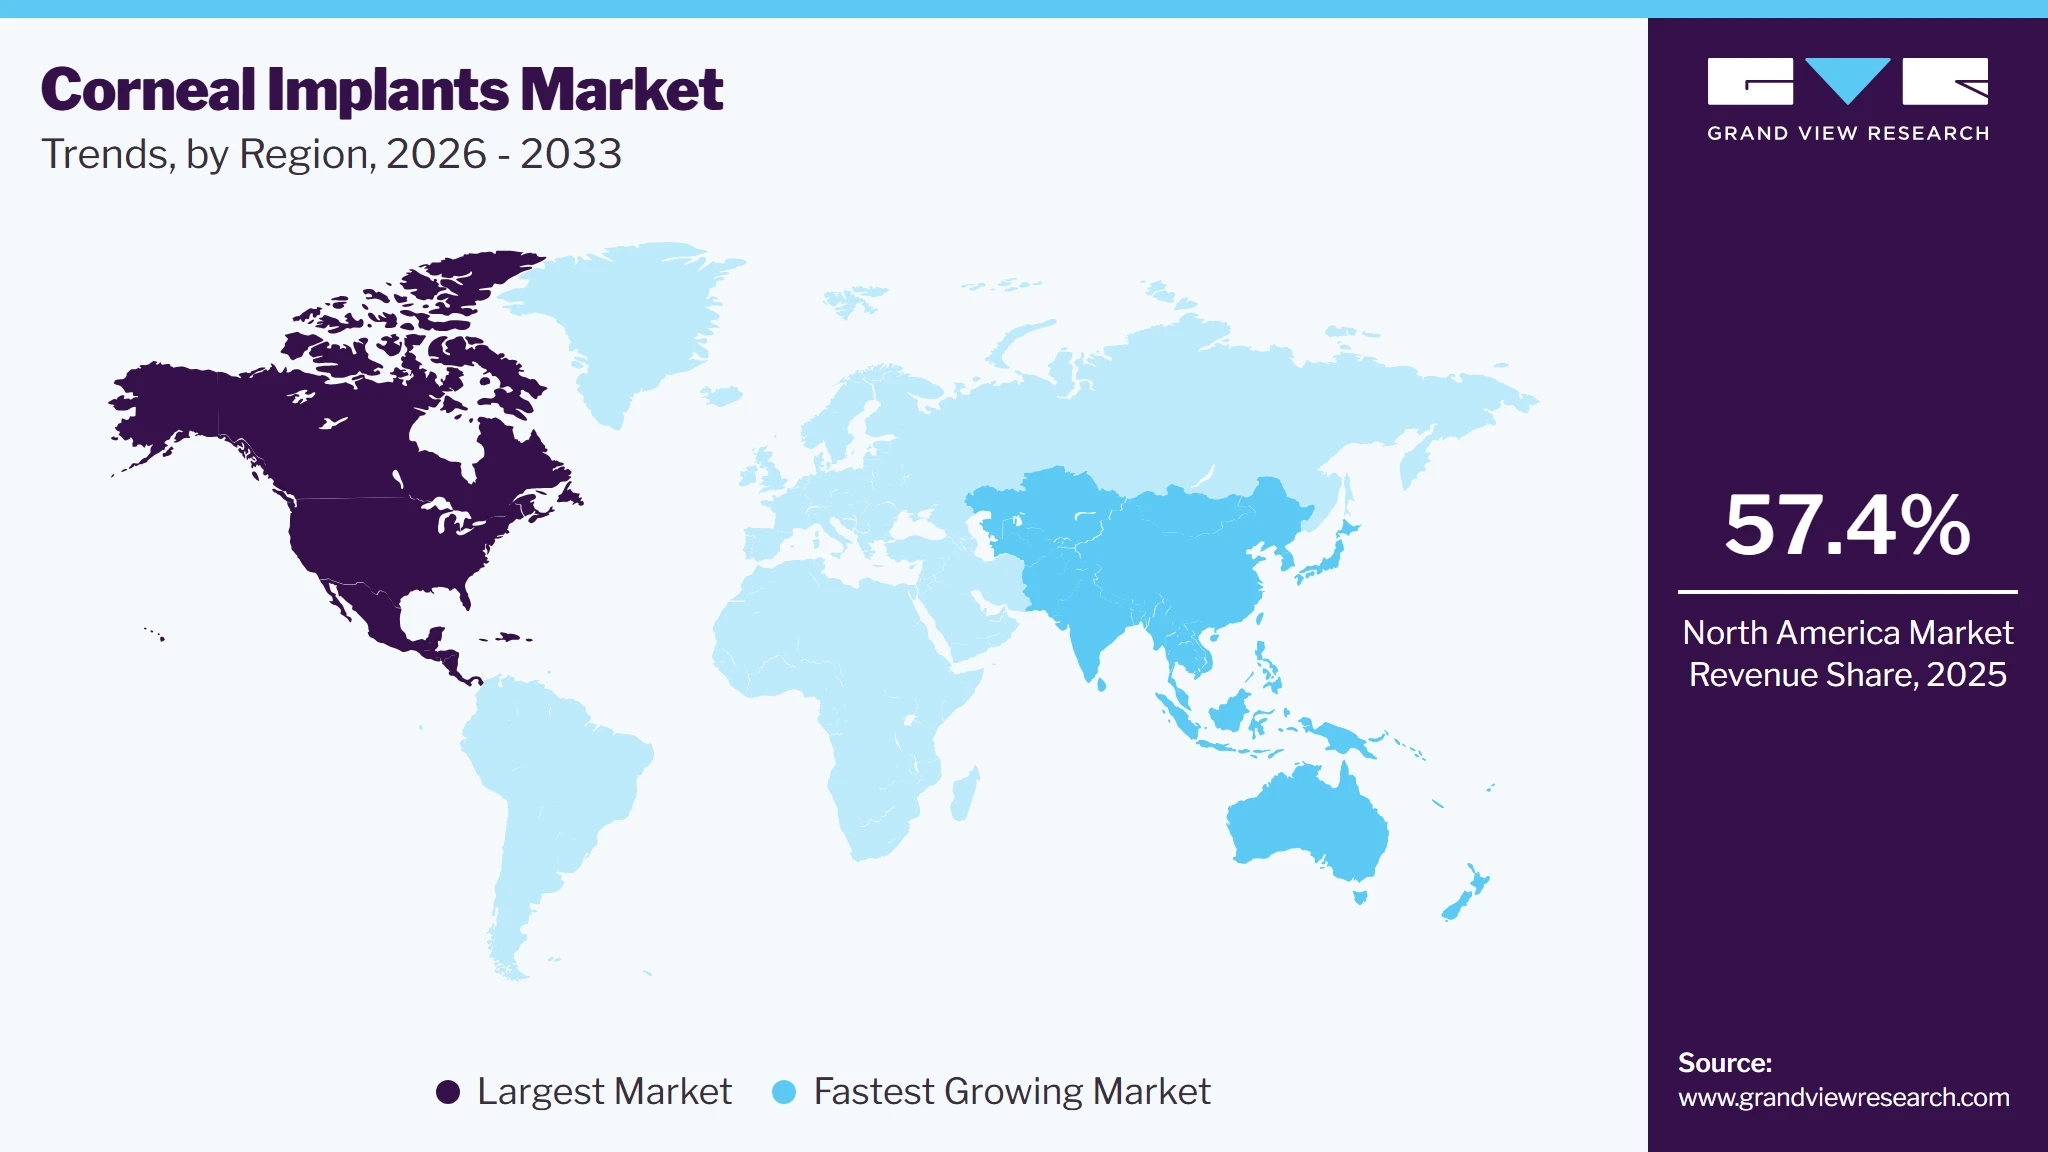
- Largest regional market: North America (57.4% revenue share in 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026 - 2033)
- By Country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market Size in 2025: USD 518.5 million
- Estimated Market Size in 2026: USD 539.5 million
- Projected Market Size by 2033: USD 711.8 million
- CAGR (2026-2033): 4.0%
GVR research-powered AIAsk Prism AI about the corneal implants marketGet cited answers from GVR research on market growth, segments, regulations and forecasts.Start with✓ Source-linked answers ✓ Market-specific context ✓ Traceable figuresExplore Prism AI ↗Growing incidence of keratoconus, Fuchs dystrophy, infectious keratitis, and corneal ulcers is expanding the need for advanced treatment options. In addition, improvements in endothelial keratoplasty techniques, customized donor-tissue solutions, and artificial corneal implants are supporting market development. Increasing awareness of vision-restoration procedures, expanding ophthalmic surgical infrastructure, and growing adoption of minimally invasive transplantation techniques are further contributing to market expansion. However, donor-tissue shortages, high procedure costs, and regulatory requirements remain key challenges.
 To learn more about this report, Download Free Sample Report
The underlying demand for corneal transplantation is connected to the broader global burden of vision impairment and eye disease. The World Health Organization (WHO) reported in February 2026 that at least 2.2 billion people globally have near or distance vision impairment, with at least 1 billion cases preventable or yet to be addressed. WHO also notes that the burden of eye disease is expected to increase alongside demographic and socioeconomic changes.
The market is supported by the continuing clinical need to treat corneal damage caused by diseases such as keratoconus, Fuchs' dystrophy, infectious keratitis, corneal ulcers, trauma, and other conditions that compromise corneal transparency. The National Eye Institute (NEI) states that severe corneal damage may require replacement of damaged tissue with healthy donor corneal tissue and identifies both full-thickness and partial-thickness transplantation approaches. It also recognizes artificial corneas, or keratoprostheses, as an alternative to conventional corneal transplantation.
Synthetic corneal implants represent a smaller but technologically important component of the market. These devices are intended to provide an alternative pathway when conventional donor transplantation is unsuitable or has failed. The FDA's keratoprosthesis guidance defines permanent keratoprostheses as devices implanted to allow light transmission through an opacified cornea, particularly in eyes where the patient is not a reasonable candidate for corneal transplantation. This positioning explains why synthetic implants should not automatically be modeled as a direct one-for-one substitute for donor corneas. Instead, they largely address a specialized population.
Synthetic technologies can potentially address:
-
repeated graft failure;
-
severe corneal opacity;
-
extensive ocular surface damage;
-
selected patients unsuitable for donor transplantation;
-
donor tissue shortages;
-
complex corneal reconstruction.
Instance: Artificial Cornea Used in the UK
A notable example of technological development occurred in the UK in 2024. Frimley Health NHS Foundation Trust reported the first commercial transplant using an artificial cornea in the UK. The procedure involved replacing the abnormal inner corneal lining with an artificial cornea rather than donated human tissue. This instance demonstrates how synthetic corneal technologies can move beyond experimental development into clinical implementation. It also illustrates a key market opportunity: artificial implants can potentially provide an alternative supply pathway where human donor tissue is limited.
However, a single clinical implementation should not be interpreted as evidence that artificial implants will replace donor transplantation across the broader market. Their adoption remains dependent on patient selection, clinical outcomes, regulatory status, cost, and surgeon acceptance.
Case Study: India - Expansion of District-Level Corneal Transplantation
India provides a useful case study for understanding how healthcare infrastructure can affect the corneal transplantation market.
In 2026, the Kerala Health Department reported that Thiruvananthapuram General Hospital successfully conducted a corneal transplant at the district-hospital level. The patient had developed corneal blindness following an eye injury during childhood, and the donor cornea was sourced from the EBAK Eye Bank. The government reported that the procedure, which could cost several lakhs of rupees in private hospitals, was provided free of charge.
The case is significant from a market-development perspective because decentralization can increase access to transplantation beyond major metropolitan ophthalmology centers. If similar infrastructure expansion occurs across additional districts, the addressable procedure base could increase. The case also highlights the relationship between eye banks, hospitals, trained surgeons, and government-supported healthcare systems. Market growth therefore depends not only on technology but also on the availability of trained personnel and appropriate tissue infrastructure.
Market Dynamics
The Corneal Implants Market is being supported by the rising burden of corneal disorders, increasing demand for corneal transplantation, expansion of eye-banking infrastructure, and advances in donor-tissue processing and artificial corneal technologies. Corneal transplantation remains an important treatment for severe corneal disease, while endothelial keratoplasty and synthetic/keratoprosthetic solutions are expanding treatment options for patients with specific clinical needs. Government initiatives to strengthen eye donation, cornea collection, transplantation infrastructure, and specialist training are also supporting market development.
One of the key drivers of the Corneal Implants Market is the growing requirement for corneal transplantation among patients with advanced corneal disorders, including keratoconus, Fuchs dystrophy, infectious keratitis, corneal ulcers, trauma, and corneal scarring. As the number of patients requiring vision-restoring interventions increases, demand for donor corneas and specialized transplantation procedures is also expanding.
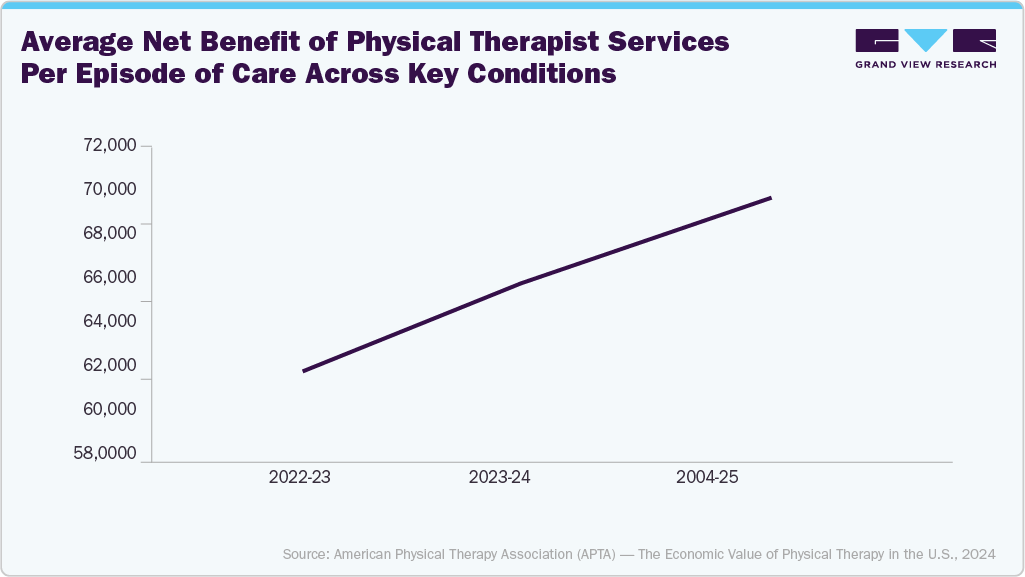
Government data from India demonstrates this underlying increase in corneal-service activity. According to the Ministry of Health & Family Welfare, cornea collections increased from 62,370 in 2022-23 to 66,434 in 2023-24 and 69,848 in 2024-25, representing approximately 12.0% growth over the two-year period. The government also reported 396 functional eye banks in the country in 2026, alongside continued support for eye-bank infrastructure, equipment, training, eye-donation promotion, and cornea-storage facilities.
Government-reported cornea collections under the National Programme for Control of Blindness and Visual Impairment (NPCBVI).
 To learn more about this report, Download Free Sample Report
Limited availability of suitable donor corneas remains an important restraint for the Corneal Implants Market. Although eye-bank networks and cornea-collection programs are expanding, the availability of suitable tissue can remain below clinical requirements in several markets. Tissue quality, retrieval timing, preservation, processing capacity, and geographic distribution can further influence the number of corneas available for transplantation.
The financial burden associated with corneal transplantation also limits access, particularly in markets where patients have substantial out-of-pocket expenses. Procedures require specialized ophthalmic surgeons, operating-room infrastructure, tissue-processing capabilities, and postoperative follow-up. For patients who are unsuitable for conventional transplantation, synthetic or keratoprosthetic implants may provide an alternative, but these solutions can involve additional clinical complexity and regulatory requirements. Consequently, donor-tissue shortages, specialized infrastructure requirements, and procedure-related costs remain key barriers to broader market penetration.
Market Concentration & Characteristics
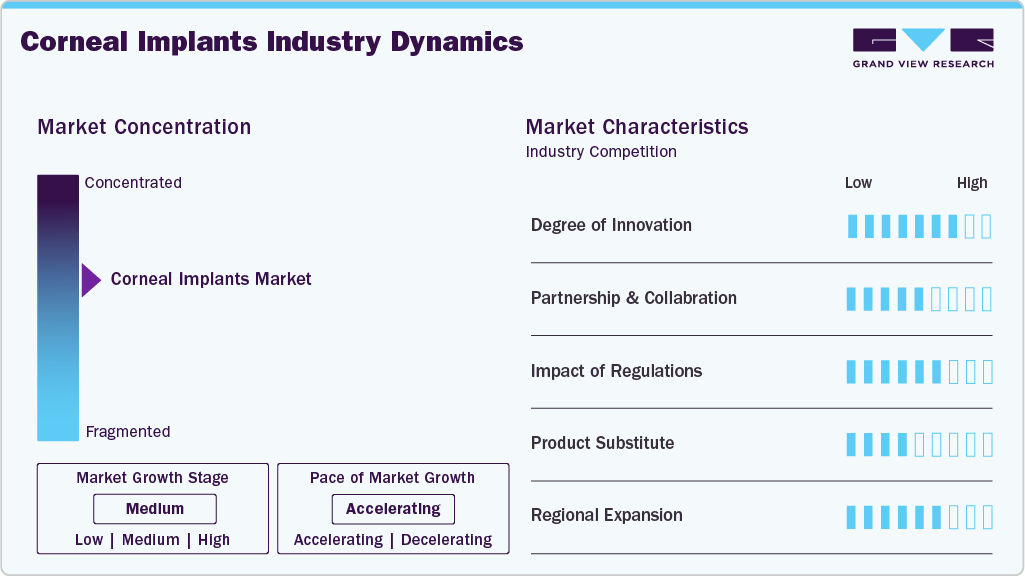
The Corneal Implants Market is relatively concentrated on the established donor-tissue and ophthalmic transplantation side, while the synthetic corneal segment remains more specialized. Companies and institutions such as Alcon, CorneaGen, Aurolab, and eye banks participate in the donor-tissue ecosystem, whereas companies developing artificial corneas and keratoprostheses address more specialized patient populations. The market operates across two major pathways: human-tissue transplantation, including penetrating and endothelial keratoplasty, and synthetic/artificial corneal implants, including keratoprostheses for patients who are unsuitable for conventional corneal transplantation. NHS Blood and Transplant reports that endothelial keratoplasty accounts for the majority of corneal grafts in the UK, reflecting the increasing importance of layer-specific transplantation techniques.
The market is characterized by continued innovation in corneal tissue processing, endothelial graft preparation, transplantation techniques, customized tissue solutions, and artificial corneal implants. Innovation is increasingly focused on improving graft quality, reducing surgical complexity, increasing tissue utilization, and oving from conventional full-thickness transplantation toward layer-specific and customized approaches. Endothelial keratoplasty replaces the diseased posterior layers of the cornea developing alternatives for patients who are poor candidates for conventional donor-tissue transplantation.
 To learn more about this report, Download Free Sample Report
Innovation is also m while preserving healthier anterior tissue, and it represents the majority of corneal grafts reported by NHS Blood and Transplant. At the synthetic end of the market, FDA guidance recognizes permanent keratoprostheses as devices designed to provide an optical pathway through an opacified cornea when a patient is not a reasonable candidate for a conventional corneal transplant.
Partnerships and collaborations are becoming important as the market depends on coordination among eye banks, hospitals, ophthalmic centers, transplant surgeons, research institutions, and technology developers. Collaboration supports donor-tissue procurement, tissue preservation, surgeon training, clinical research, and development of advanced transplantation technologies. A notable development occurred in March 2025, when Pantheon Vision partnered with EyeDeal Medical to develop a bioengineered artificial corneal implant designed to reduce dependence on human donor tissue. The collaboration focuses on developing a single-piece polymer artificial cornea aimed at addressing donor shortages and expanding access to corneal transplantation.
Regulation has a high impact on the Corneal Implants Market because both human donor tissue and synthetic corneal implants require compliance with transplantation, tissue-handling, medical-device, and clinical requirements. Regulatory frameworks influence tissue procurement, processing, storage, transplantation-center infrastructure, and the approval pathway for artificial corneal devices. India introduced an important regulatory change in November 2025 through amendments to the Transplantation of Human Organs and Tissues Rules. The amendment removed the mandatory requirement for clinical specular equipment at corneal transplantation centres, with the government stating that the change was intended to ease infrastructure and operational challenges, particularly for smaller rural and semi-urban eye centers.
For synthetic implants, the FDA classifies permanent keratoprostheses as Class II ophthalmic devices subject to the 510(k) pathway, while its guidance specifies requirements related to safety, effectiveness, biocompatibility, and clinical evaluation. Consequently, regulatory requirements remain an important factor influencing the commercialization and adoption of artificial corneal technologies.
The corneal implants market faces substitution from non-surgical and alternative ophthalmic treatments, depending on disease severity and clinical indication. In earlier-stage corneal conditions, corrective lenses, specialty contact lenses, corneal cross-linking, pharmacological treatment, or other disease-management approaches may delay or eliminate the need for transplantation. For patients requiring surgical intervention, however, substitution depends strongly on the underlying condition and affected corneal layer. Endothelial keratoplasty, anterior lamellar keratoplasty, penetrating keratoplasty, and keratoprosthesis can represent alternative approaches for different patient populations. NHS Blood and Transplant notes that the choice of transplantation technique depends on which layers of the cornea are affected.
Synthetic corneal implants provide an additional alternative for selected patients who are not reasonable candidates for conventional transplantation, including patients with severe corneal opacity or previous graft failure. Therefore, substitution within the market is primarily driven by disease severity, corneal-layer involvement, graft suitability, surgeon preference, and patient-specific clinical factors.
Regional expansion in the corneal implants market is being supported by increasing availability of corneal transplantation services, development of eye-bank infrastructure, improved surgical techniques, and growing investment in ophthalmic healthcare. Expansion is particularly relevant in countries where government programs are strengthening donor-tissue collection and transplantation capacity. Synthetic corneal technologies are also supporting regional expansion by addressing donor-tissue shortages. In September 2025, CorNeat Vision reported that its CorNeat KPro artificial cornea restored 20/20 vision in a patient with severe corneal scarring who was not a candidate for conventional transplantation. The RESEE clinical trial was being conducted across clinical centers in Canada, France, India, Israel, and the Netherlands, with planned expansion to U.S. centers in 2026. The device does not require donor tissue and is designed to integrate with the eye wall, highlighting its potential relevance in regions with limited corneal-donor availability.
"Restoring 20/20 vision to a blind eye with the CorNeat KPro is a powerful testament to how innovation and vision come together to change lives. At Beilinson's Ophthalmology Department, we are committed to leading with cutting-edge technologies, and this breakthrough reflects our mission to bring the future of eye care into the present."
- Head of Ophthalmology, Beilinson Hospital
"This is a landmark achievement, Delivering sight and aesthetics to an eye once beyond help highlights the sheer impact of our artificial cornea. This breakthrough not only restores vision for patients with untreatable corneal conditions but also delivers hope to millions of blind patients living in regions where donor tissue is scarce."
-CorNeat Vision's Co-Founder and Chief Medical Officer
Analyst Perspective
The Corneal Implants Market presents a steady growth outlook, supported by the increasing prevalence of corneal disorders, rising demand for corneal transplantation, and advancements in synthetic corneal implant technologies. From an analyst perspective, the market is evolving toward advanced donor-tissue solutions, customized grafts, and artificial corneal implants designed to address complex and treatment-resistant cases. Established players such as Alcon, CorneaGen, and Aurolab benefit from strong ophthalmic expertise and established surgical networks, while emerging companies are advancing synthetic and keratoprosthetic solutions. Growth is further supported by improvements in tissue processing, endothelial transplantation techniques, and specialized implants for conditions such as keratoconus and corneal dystrophies. However, limited donor-tissue availability, high procedure costs, regulatory requirements, and the need for specialized surgical expertise remain key constraints to broader market penetration.
Type Insights
The human tissue segment dominated the market in 2025, accounting for approximately 91.7% of overall market revenue. Its leading position is primarily attributed to the established clinical acceptance, proven safety profile, and extensive use of donor corneal tissue in transplantation procedures. Human corneal tissue remains the preferred option for patients with advanced corneal disorders, including keratoconus, corneal scarring, endothelial dysfunction, and other vision-impairing conditions. Growing awareness of corneal transplantation, improvements in tissue preservation and screening techniques, and the availability of well-established eye-bank networks further support segment growth. In addition, favorable clinical outcomes and long-term physician experience with human donor tissue continue to sustain its adoption across ophthalmic care settings.
The synthetic segment is expected to witness steady growth in the corneal implants market, supported by increasing development of biocompatible materials, growing donor tissue shortages, and advancements in artificial corneal technologies. Innovations in synthetic endothelial implants, keratoprostheses, and minimally invasive procedures are expanding treatment options for patients unsuitable for conventional transplantation. Rising clinical research and regulatory progress are further supporting adoption of synthetic corneal solutions.
Surgery Method Insights
The penetrating keratoplasty segment dominated the corneal implants market in 2025, supported by its established clinical use for treating advanced corneal disorders, including severe corneal scarring, keratoconus, and corneal opacity. Its widespread adoption is attributed to the availability of experienced ophthalmic surgeons, established surgical protocols, and favorable long-term clinical outcomes. In addition, the growing prevalence of corneal diseases and increasing demand for corneal transplantation procedures continue to support segment growth across major markets.
The endothelial keratoplasty segment is expected to witness steady growth in the corneal implants market. Growth is being reinforced by the increasing prevalence of endothelial disorders, including Fuchs’ endothelial corneal dystrophy, and the growing preference for minimally invasive transplantation techniques. Faster visual recovery, reduced surgical trauma, improved graft survival, and favorable clinical outcomes compared with conventional full-thickness procedures are further supporting adoption. Technological advancements in graft preparation and surgical instruments are also contributing to segment expansion.
Application Insights
The fuchs dystrophy segment dominated the corneal implants market in 2025, supported by the increasing prevalence of Fuchs endothelial corneal dystrophy, particularly among aging populations. The condition is a major indication for corneal transplantation and endothelial keratoplasty procedures, driving demand for corneal implants. Growing awareness, improved diagnostic capabilities, advancements in endothelial keratoplasty techniques, and increasing availability of specialized ophthalmic treatments are further supporting the adoption of corneal implants for managing progressive corneal endothelial dysfunction.
The infectiuos keratitis segment is expected to witness significant growth in the corneal implants market, supported by the rising incidence of bacterial, fungal, and viral corneal infections that can result in severe corneal damage and vision impairment. Increasing cases of treatment-resistant infections, delayed diagnosis, and corneal scarring are contributing to demand for transplantation procedures. Growing access to advanced ophthalmic care, improved diagnostic capabilities, and increasing adoption of surgical interventions for severe cases are further supporting segment growth.
End Use Insights
The hospitals segment held the largest revenue share of the corneal implants market in 2025, supported by the increasing number of corneal transplantation procedures performed in hospital settings and the availability of specialized ophthalmic infrastructure. Hospitals offer access to skilled corneal surgeons, advanced diagnostic and surgical equipment, and comprehensive postoperative care. Rising prevalence of corneal disorders, increasing patient volumes, and greater access to specialized eye-care services are further supporting the segment’s leading position.
 To learn more about this report, Download Free Sample Report
The ambulatory surgical centers segment is expected to witness fastest growth over the forecast period, driven by the increasing preference for minimally invasive and outpatient ophthalmic procedures. Growing adoption of same-day corneal surgeries, shorter hospital stays, lower procedural costs, and improved patient convenience are encouraging providers to shift suitable procedures to ambulatory settings. In addition, expanding availability of advanced ophthalmic surgical equipment, improved anesthesia techniques, and increasing investments in specialized ambulatory facilities are supporting segment expansion. Rising demand for efficient, cost-effective eye-care services and growing healthcare access are further contributing to the segment’s growth prospects.
Regional Insights
North America represents a mature market for corneal transplantation, supported by established eye-bank networks, advanced ophthalmic infrastructure, experienced corneal surgeons, and high adoption of advanced transplantation techniques. The U.S. has a well-developed donor-tissue ecosystem, although demand for corneal tissue and the development of alternatives to donor tissue remain important market considerations. The National Eye Institute identifies corneal transplantation and artificial corneas as established treatment options for advanced corneal disease.
 To learn more about this report, Download Free Sample Report
The U.S. corneal implants market is supported by a large installed base of ophthalmic services, established eye banks, and advanced surgical capabilities. Corneal transplantation is widely used for severe corneal damage, while artificial corneas provide an alternative for selected patients who are not suitable candidates for conventional transplantation. The U.S. market is also characterized by continued research into donor-tissue utilization, preservation, and advanced corneal replacement technologies.
Europe Corneal Implants Market Trends
The Europe corneal implants market is supported by established transplantation systems, eye-bank infrastructure, specialist ophthalmology centers, and increasing adoption of layer-specific transplantation techniques. Market development varies across countries according to donor availability, healthcare-system organization, transplantation capacity, and access to specialist ophthalmic services. The UK provides a particularly well-established framework through NHS Blood and Transplant, which maintains dedicated corneal activity, selection, allocation, and clinical governance systems.
The corneal implants market in UK is supported by an established national ocular-tissue transplantation infrastructure and specialized eye-bank services. Corneal transplantation is the most frequently performed transplant surgery in the UK, with endothelial keratoplasty accounting for the majority of corneal grafts. Fuchs' endothelial dystrophy, keratoconus, corneal edema, and failed previous grafts remain important indications, supporting continued demand for donor corneal tissue and specialized graft solutions.
The Germany corneal implants market is characterized by a developed healthcare system, established ophthalmic centers, and access to advanced corneal transplantation procedures. Demand is supported by treatment of endothelial disorders, keratoconus, corneal scarring, and other advanced corneal conditions. Increasing use of selective and layer-specific transplantation techniques is expected to support demand for specialized donor grafts, while artificial corneal technologies provide an emerging option for complex cases.
The corneal implants market in Spain is supported by established ophthalmic services and access to corneal transplantation for advanced corneal disease. Adoption is influenced by the availability of donor tissue, specialist surgical capacity, and regional healthcare infrastructure. Increasing use of endothelial and lamellar techniques, alongside developments in artificial corneal technologies, is creating opportunities for more specialized treatment pathways.
Asia Pacific Corneal Implants Market Trends
The Asia Pacific corneal implants market presents substantial expansion opportunities due to the region's large population, significant burden of corneal disease, improving ophthalmic infrastructure, and increasing development of eye-banking and transplantation services. Market development remains uneven across countries, with Japan and Australia having mature healthcare systems while China, India, and other Asian markets continue to strengthen access to specialist ophthalmic care. WHO initiatives in the Western Pacific region are also focused on expanding access to quality eye-care services.
China's corneal implants market is supported by a large population requiring ophthalmic care, expansion of specialist eye hospitals, and increasing investment in advanced vision-care infrastructure. Development of corneal transplantation capacity and eye-banking services provides opportunities for donor-tissue solutions, while synthetic and tissue-engineered corneal technologies represent emerging alternatives where donor availability is constrained.
The corneal implants market in Japan is supported by a highly developed healthcare system, advanced ophthalmic infrastructure, and an aging population with increasing requirements for treatment of corneal and endothelial disorders. The market emphasizes surgical precision, graft quality, and clinical outcomes. Continued adoption of endothelial keratoplasty and other selective transplantation techniques is expected to support demand for specialized corneal tissue and advanced surgical solutions.
Latin America Corneal Implants Market Trends
The Latin America Corneal Implants Market is developing alongside improvements in ophthalmic healthcare infrastructure, increasing awareness of corneal transplantation, and expansion of specialist eye-care services. Brazil and Mexico represent important markets because of their healthcare-system scale and established ophthalmic networks. However, disparities in access to specialist surgery, donor-tissue availability, healthcare expenditure, and transplantation infrastructure continue to influence regional adoption.
Brazil's Corneal Implants Market is supported by an established ophthalmology sector, increasing access to corneal transplantation, and development of eye-bank and tissue-donation networks. Demand is driven by advanced corneal conditions requiring transplantation, including keratoconus, endothelial disorders, corneal scarring, and infectious complications. Greater availability of specialized transplantation techniques and artificial corneal technologies could further expand treatment options for patients with complex disease.
Middle East & Africa Corneal Implants Market Trends
The Middle East & Africa (MEA) Corneal Implants Market presents an emerging opportunity supported by increasing healthcare investment, development of specialist ophthalmic centers, and growing adoption of advanced surgical technologies. Adoption remains concentrated in countries with stronger healthcare infrastructure and higher healthcare expenditure, while limited donor-tissue availability, specialist shortages, and uneven access to transplantation services remain important constraints. Artificial corneal technologies may provide additional opportunities in markets where donor tissue is scarce.
The Saudi Arabia Corneal Implants Market is supported by substantial healthcare investment, development of specialized hospitals and ophthalmic centers, and increasing adoption of advanced medical technologies. Expansion of specialist eye-care services can support demand for donor corneal tissue and advanced transplantation procedures. The market also provides an opportunity for synthetic corneal solutions as healthcare providers seek alternatives for complex cases and patients who are unsuitable for conventional donor-tissue transplantation.
Key Corneal Implants Company Insights
The corneal implants market is highly competitive, with major players such as CorNeat Vision, EyeYon Medical, KeraMed, Link Medical, CorneaGen, Glaukos Corporation, Bausch + Lomb, Carl Zeiss Meditec AG, Johnson & Johnson Vision, and Aurolab. Companies are focusing on product innovation, clinical development, regulatory approvals, and strategic collaborations to strengthen their market presence. Key areas of competition include the development of advanced synthetic and tissue-based corneal implants, improved biocompatibility, enhanced surgical outcomes, and minimally invasive implantation techniques. Leading players are also investing in clinical trials and partnerships with ophthalmic centers to expand indications and accelerate commercialization of next-generation corneal implant technologies.
Key Corneal Implants Companies
The following key companies have been profiled for this study on the corneal implnats market.
-
Alcon Inc.
-
CorneaGen
-
AJL Ophthalmic S.A.
-
KeraMed, Inc.
-
DIOPTEX
-
Aurolab
-
Florida Lions Eye Bank
-
San Diego Eye Bank
-
CorNeat Vision Ltd.
-
EyeYon Medical
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Alcon Inc., CorneaGen, Aurolab, Florida Lions Eye Bank, San Diego Eye Bank)
Established players focus on strengthening their positions across corneal transplantation through broad ophthalmic portfolios, donor-tissue procurement and processing, surgeon relationships, and expansion of advanced corneal graft solutions. Companies are increasingly emphasizing specialized tissue products, improved graft preparation, surgical workflow support, and partnerships with ophthalmic centers to expand access to corneal transplantation.
Strong clinical and surgeon relationships, established tissue-processing capabilities, broad ophthalmic portfolios, regulatory experience, extensive distribution networks, and established reputations in corneal surgery provide significant advantages. Their access to donor tissue and established transplantation infrastructure also supports recurring demand from hospitals and ophthalmic centers.
Dependence on donor tissue availability, tissue-processing requirements, regulatory constraints, and geographic variability in corneal donation can limit market expansion. Established players may also face challenges from shortages of suitable donor tissue, high surgical costs, and the need for specialized surgical expertise.
Emerging Players (AJL Ophthalmic S.A., KeraMed, Inc., DIOPTEX, CorNeat Vision Ltd., EyeYon Medical)
Emerging companies are primarily focused on developing synthetic and artificial corneal solutions designed to address donor-tissue shortages and patients who are unsuitable for conventional corneal transplantation. Their strategies include development of keratoprostheses, synthetic corneal implants, endothelial implants, and customized solutions for severe corneal disease, while pursuing regulatory approvals and clinical adoption through specialist ophthalmic centers.
Innovative implant technologies, reduced dependence on donor corneas, focus on difficult-to-treat patients, specialized product portfolios, and potential for addressing unmet needs in corneal blindness provide differentiation. Their smaller organizational structures can also support focused R&D and faster development of specialized implant technologies.
Limited commercial scale, smaller clinical evidence bases, regulatory and reimbursement uncertainties, dependence on specialist surgeons, and relatively low awareness compared with established ophthalmic companies can restrict adoption. Several products remain investigational or have limited market availability, while long-term clinical outcomes and broader surgeon acceptance continue to influence commercialization.
Recent Development
- In March 2026, researchers at Spain’s University of Granada developed a low-cost artificial cornea using fish scales. Laboratory and animal testing demonstrated favorable biocompatibility, transparency, and resistance. The technology could provide a donor-independent alternative for severe corneal disease, although human clinical trials are still required before potential clinical application.
"Although the standard transplant usually offers good results, it's necessary to develop new effective regeneration methods that do not depend on organ donation, which is subject to waiting lists.”
-Professor of histology at the southern Spanish university, who co-authored the research
- In December 2025, the FDA granted EyeYon Medical an Investigational Device Exemption for its EndoArt synthetic corneal endothelial implant, enabling a U.S. clinical study. Designed to treat chronic corneal edema, the minimally invasive device is already CE-marked in Europe, with over 800 implantations globally and additional clinical experience in China.
" The initiation of this U.S. clinical study marks an exciting moment for our field. EndoArt represents a truly novel approach to treating chronic corneal edema. I'm honored to lead this important investigation and to help evaluate a technology that may reshape the future of endothelial disease management.”
- MD, Director of Cornea and External Disease, Scripps Clinic Medical Group
Corneal Implants Market Report Scope
Report Attribute
Details
Market size in 2025
USD 518.5 million
Estimated market size in 2026
USD 539.5 million
Projected market size by 2033
USD 711.8 million
Growth rate
CAGR of 4.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, surgery method, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Australia; Thailand; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Alcon Inc.; CorneaGen; Aurolab; Florida Lions Eye Bank; San Diego Eye Bank; AJL Ophthalmic S.A.; KeraMed, Inc.; DIOPTEX; CorNeat Vision Ltd.; EyeYon Medical
Customization scope
Free report customization (equivalent up to 8 analyst’s working days) with purchase. Addition or alteration to country, regional, and segment scope
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Corneal Impants Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global corneal implants market report based on type, surgery method, application, end use and region:
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Human Tissue
-
Synthetic
-
-
Surgery Method Outlook (Revenue, USD Million, 2021 - 2033)
-
Penetrating Keratoplasty
-
Endothelial Keratoplasty
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Keratoconus
-
Fuchs Dystrophy
-
Infectiuos Keratitis
-
Coreneal ulcers
-
Other
-
-
End use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Ophthalmic Centers
-
Ambulatory Surgical Centers
-
-
Region Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
South Korea
-
India
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
MEA
-
Saudi Arabia
-
South Africa
-
UAE
-
Kuwait
-
-
Research Methodology
The corneal impants market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each corneal impants segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Human Tissue
Revenue generated from donor-derived human corneal tissue used in transplantation procedures, including penetrating and endothelial keratoplasty, with value captured through tissue procurement, processing, preservation, and distribution.
Synthetic
Revenue generated from artificial or synthetic corneal implants, including keratoprostheses and engineered corneal substitutes, used to restore vision in patients unsuitable for conventional donor-tissue transplantation or requiring specialized reconstruction.
Segment - Surgery Method
Revenue capture definition
Penetrating Keratoplasty
Revenue generated from full-thickness corneal transplantation procedures, involving replacement of the damaged cornea with donor tissue, including associated graft preparation, surgical products, and specialized transplantation services.
Endothelial Keratoplasty
Revenue generated from selective transplantation of the corneal endothelial layer, including DMEK and DSAEK procedures, with value captured through donor tissue, graft preparation, surgical products, and related services.
Segment - Application
Revenue capture definition
Keratoconus
Revenue generated from corneal implants and transplantation procedures used to manage advanced keratoconus, including donor grafts, synthetic implants, specialized tissue products, and associated surgical interventions.
Fuchs Dystrophy
Revenue generated from corneal transplantation and implant procedures used to treat advanced Fuchs dystrophy, including endothelial grafts, donor tissue, synthetic solutions, surgical products, and associated treatment services.
Infectious Keratitis
Revenue generated from corneal transplantation or implant procedures used for severe infectious keratitis, including therapeutic grafts, donor tissue, synthetic implants, surgical products, and related ophthalmic treatment services.
Corneal Ulcers
Revenue generated from corneal tissue and implant solutions used to treat severe or non-healing corneal ulcers, including therapeutic grafts, synthetic implants, tissue products, and associated surgical procedures.
Other
Revenue generated from corneal implant and transplantation procedures addressing additional indications, including corneal scarring, trauma, dystrophies, edema, perforations, burns, and other conditions requiring corneal reconstruction.
Segment - End use
Revenue capture definition
Hospitals
Revenue generated through corneal implant and transplantation procedures performed in hospital settings, including donor tissue, synthetic implants, surgical products, operating-room services, and associated ophthalmic treatment costs.
Ophthalmic Centers
Revenue generated through corneal implant and transplantation procedures performed at specialized ophthalmic centers, including tissue grafts, synthetic implants, surgical supplies, procedure fees, and associated patient-care services.
Ambulatory Surgical Centers
Revenue generated through corneal implant and transplantation procedures performed in outpatient ambulatory surgical centers, including implants, donor tissue, surgical supplies, procedure fees, and related perioperative services.
Estimation Model
Step
Guiding Question
Process Steps
Data Sources
Scope Definition
What exactly is included in the corneal implants market?
1. Define the market scope across corneal implants, transplantation tissues, synthetic corneal implants, and associated implant products. 2. Segment the market including human tissue and synthetic implants. 3. Define disease categories covered, including keratoconus, corneal edema, corneal dystrophy, and corneal scarring. 4. Establish geographic and temporal scope.
Ophthalmology clinical literature, AAO, WHO, CDC, national health statistics, regulatory databases
Build the Product Base
How many patients require corneal implantation, and what is the addressable procedure volume?
1. Estimate the patient pool with corneal disease requiring surgical intervention using prevalence/incidence data by country. 2. Determine the proportion of diagnosed patients clinically eligible for corneal implantation. 3. Estimate surgical treatment seeking based on diagnosis, treatment seeking behavior, and clinical eligibility. 4. Address the predicted corneal implant volume and traditional clinical implant procedure base.
Epidemiology studies, statistics, peer‑reviewed literature, primary procedure volumes
Estimate Penetration
How many eligible corneal patients receive implants, and what defines current utilization of each implant type?
1. Estimate treatment rates among eligible patients based on disease severity, physician recommendations, and availability of donor tissue and synthetic implants. 2. Determine transplant/implantation rates by geography, availability, and affordability. 3. Assess utilization of supporting surgical technologies, tissues, and consumables. 4. Evaluate shifts in treatment adoption driven by clinical advancements.
Peer‑reviewed ophthalmology literature, hospital databases, transplant/implantation center data
Revenue Conversion
How does corneal implant procedure volume translate into market revenue?
1. Collect average selling prices/reimbursement values for corneal implants by market, associated consumables, and surgical procedures. 2. Calculate the revenue per implant procedure to derive market significance. 3. Incorporate the revenue generated from surgical consumables and implant‑related hospital services. 4. Apply modality‑specific pricing and procedure volumes to obtain total market value.
Standard databases, national reimbursement schedules, hospital procurement data
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross Segmentation Analysis
Conducted a detailed cross-segmentation analysis of the global corneal implants market by evaluating the interrelationship between type, surgery method, application, and end use. The analysis assessed product adoption across human tissue and synthetic implants, penetrating keratoplasty and endothelial keratoplasty, and key applications including keratoconus, Fuchs dystrophy, infectious keratitis, corneal ulcers, and other corneal disorders. The analysis further examined differences across hospitals, ophthalmic centers, and ambulatory surgical centers to identify variations in product utilization and procedural demand.
Enables stakeholders to identify high-value segment combinations, understand how disease characteristics, surgical techniques, and end-use settings influence treatment selection, and assess where specific corneal implant solutions are gaining adoption.
Volume Analysis
Conducted a comprehensive procedure and volume analysis to assess the number of corneal transplantation and implant procedures performed across major markets and segment categories. The assessment considered procedure volumes by penetrating keratoplasty and endothelial keratoplasty, along with applications such as keratoconus, Fuchs dystrophy, infectious keratitis, and corneal ulcers. Regional evaluation incorporated donor cornea availability, eye-bank infrastructure, cornea collections, transplantation capacity, healthcare expenditure, and access to specialized ophthalmic services to estimate market potential and procedural penetration.
Provides stakeholders with a procedure-level view of market demand, enabling them to differentiate growth driven by transplantation volumes from growth driven by technology, pricing, or product mix. Volume insights support capacity planning, market forecasting, resource allocation, and market-entry decisions.
PESTEL Analysis
Conducted a market-specific PESTEL analysis covering the political, economic, social, technological, environmental, and legal factors influencing the global corneal implants market. Political factors included government-supported eye donation programs, eye-bank infrastructure, and transplantation initiatives; economic factors assessed healthcare expenditure, procedure costs, reimbursement, and affordability; social factors evaluated aging populations, corneal disease burden, awareness, and access to transplantation. Technological factors assessed advanced tissue processing, endothelial keratoplasty, synthetic corneas, and keratoprosthetic technologies, while legal and regulatory factors examined tissue regulations, donor eligibility, product approvals, clinical requirements, and transplantation standards.
Enables stakeholders to understand the external macroeconomic and industry forces that can influence corneal implant adoption across markets. The analysis supports evaluation of regulatory readiness, technological opportunities, healthcare infrastructure, pricing environment, donor-tissue availability, and market-entry risks.
Frequently Asked Questions About This Report
By application, the fuchs dystrophy segment held a leading market share in 2025.
By type, the human tissue segment held the highest market share of 91.7% in 2025. while synthetic segment is second fastest growing market
Asia Pacific is the fastest-growing region over the forecast period.
The global corneal implants market size was estimated at USD 518.5 million in 2025 and is expected to reach USD 539.5 million in 2026.
The global corneal implants market is expected to grow at a compound annual growth rate of 4.0% from 2026 to 2033 to reach USD 711.8 million by 2033.
North America dominated the global corneal implants market with a share of 57.4% in 2025. This is attributable to the well-established healthcare system and easy availability of products in the country along with the growing prevalence of eye disorders.
Some of the key player's global corneal implants market are Alcon Inc., CorneaGen, Aurolab, Florida Lions Eye Bank, San Diego Eye Bank, AJL Ophthalmic S.A., KeraMed, Inc., DIOPTEX, CorNeat Vision Ltd., EyeYon Medical
Increasing prevalence of eye disorders, Increasing awareness regarding the importance of eye donation and expected launch of new synthetic corneas is driving the growth of corneal implants market
Penetrating keratoplasty segment held a leading market share in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


