
- Home
- »
- Clinical Diagnostics
- »
-
D-dimer Testing Market Size & Share Report, 2026-2033GVR Report cover

D-dimer Testing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Analyzers, Reagents & Consumables), By Test, By Method, By Application, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$1.9BMarket Estimate, 2026
$2.1BMarket Forecast, 2033
$2.7BCAGR, 2026–2033
3.7%D-dimer Testing Market Summary
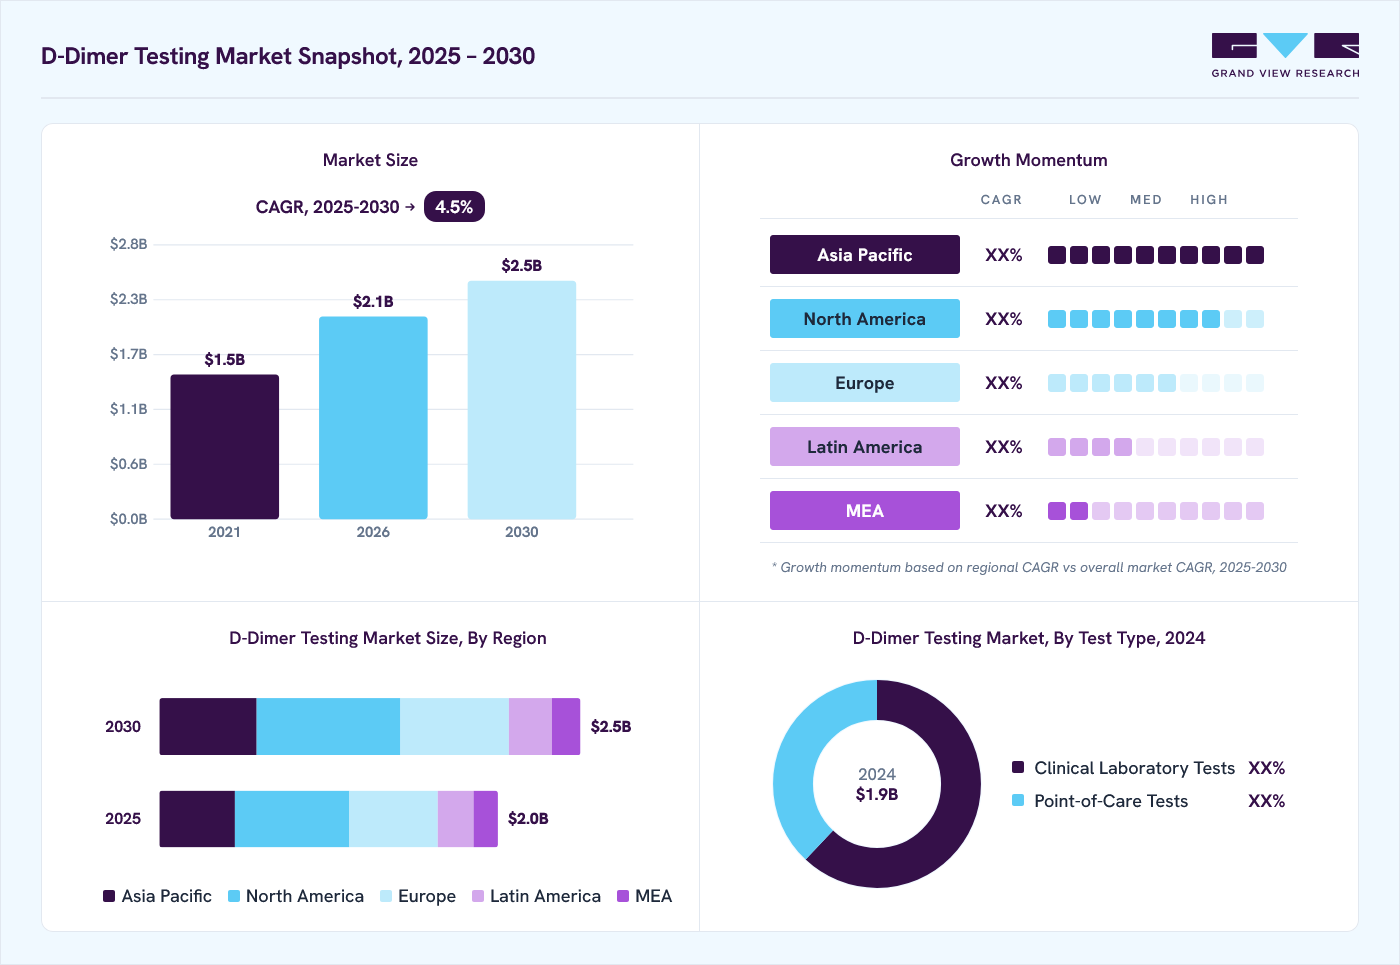
The global D-dimer testing market size was valued at USD 1.9 billion in 2025 and is projected to grow from USD 2.1 billion in 2026 to USD 2.7 billion by 2033, at a CAGR of 3.7% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 33.8% in 2025. Industry growth is primarily driven by the rising incidence of venous thromboembolism, increasing demand for rapid exclusion of thrombotic conditions, and wider adoption of automated and point-of-care D-dimer assays.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Reagents & consumables segment led the market with the largest revenue share of 65.0% in 2025.
- By test: Clinical laboratory tests segment led the market with the largest revenue share of 61.9% in 2025.
- By method: Enzyme-linked immunosorbent assay (ELISA) segment led the market with the largest revenue share of 41.5% in 2025.
- By application: Deep vein thrombosis (DVT) segment led the market with the largest revenue share of 37.2% in 2025.
- By end use: Hospitals segment led the market with the largest revenue share of 36.8% in 2025.
Regional Highlights
- Largest regional market: North America (33.8% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 1.9 Billion
- Estimated market size in 2026: USD 2.1 Billion
- Projected market size by 2033: USD 2.7 Billion
- CAGR (2026-2033): 3.7%
Prism AI by Grand View Research Free to tryAsk a question about the d-dimer testing marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →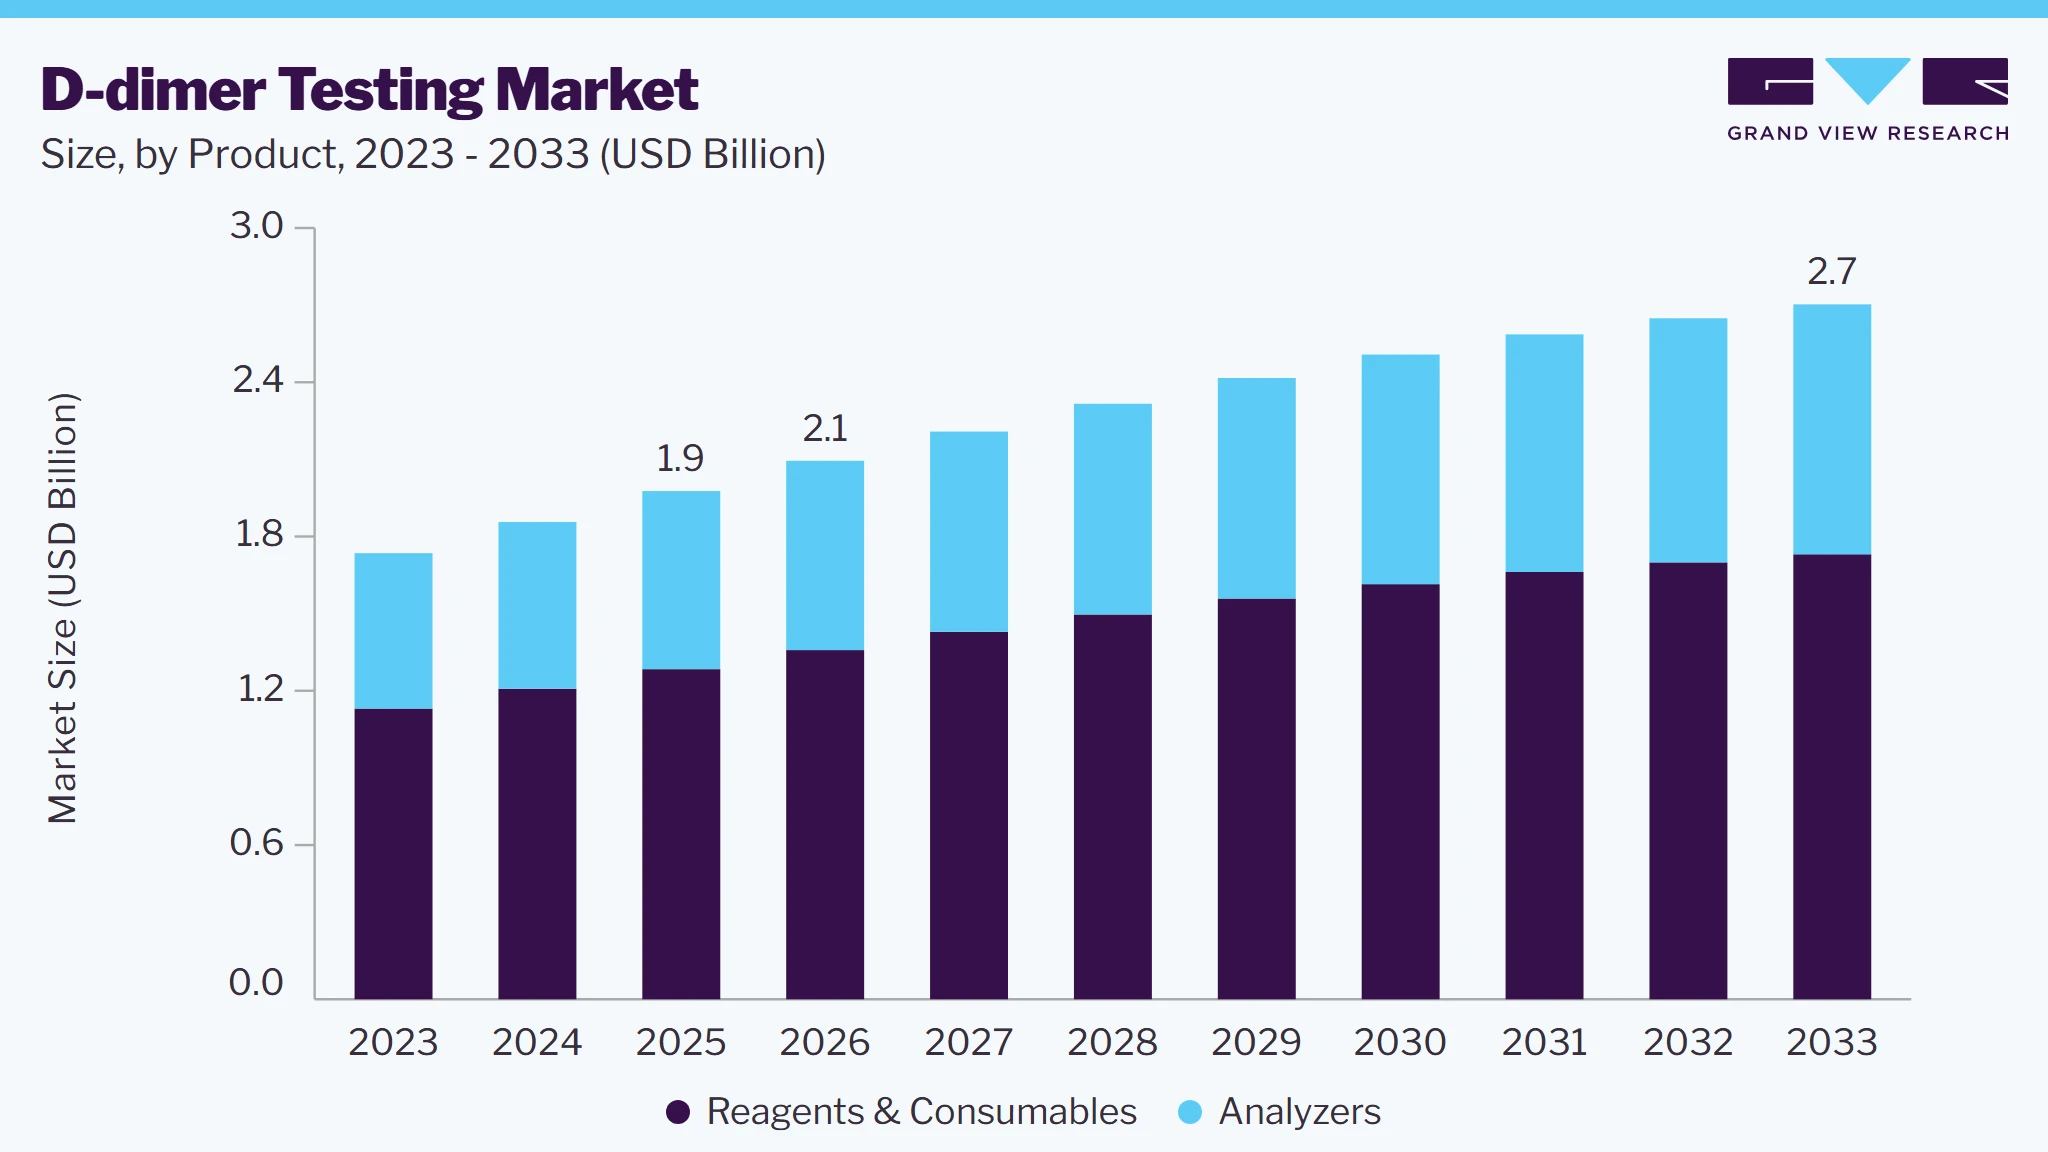 To learn more about this report, Download Free Sample Report
Market Dynamics
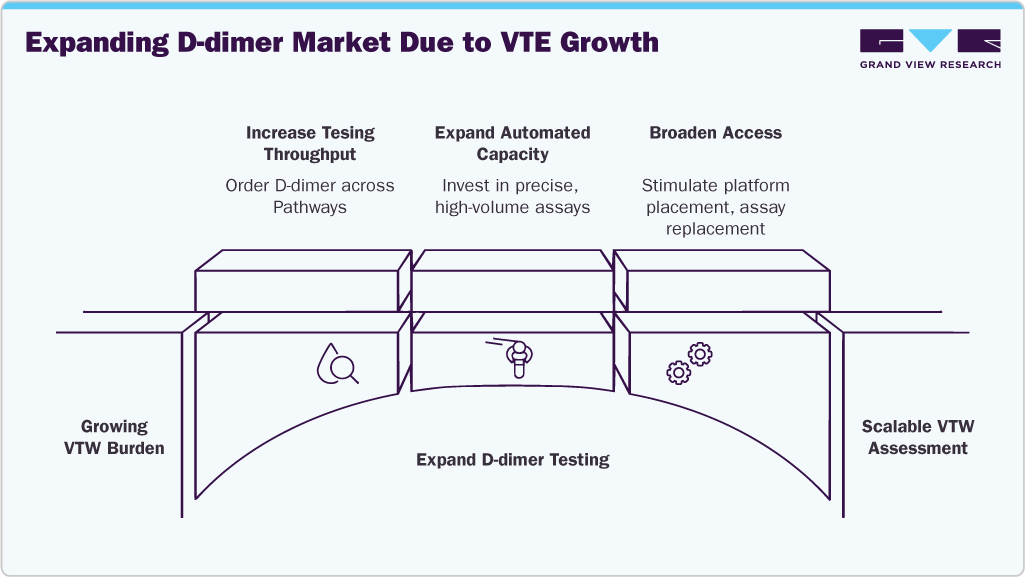
The expanding burden of venous thromboembolism (VTE), comprising deep vein thrombosis and pulmonary embolism, enlarges the population entering diagnostic pathways in which D-dimer serves as a first-line rule-out test for patients with non-high clinical probability. In October 2025, the International Society on Thrombosis and Haemostasis estimated that approximately 10 million hospital-associated blood-clot cases occur globally each year. This burden is directly relevant because hospitalization, surgery, cancer treatment, prolonged immobility, and pregnancy create recurring periods of elevated thrombotic risk. When these patients develop compatible symptoms, clinicians require rapid differentiation between VTE and other conditions before using ultrasound or computed tomography. Consequently, growth in the clinically suspected population, rather than only confirmed cases, expands demand for D-dimer assays, analyzers, reagents, and associated consumables.
The larger at-risk population generates substantial testing throughput across emergency, inpatient, and outpatient pathways whenever VTE is clinically suspected. A multicenter study published in 2024 evaluated 40,096 clinically requested D-dimer results and 11,372 computed tomography pulmonary angiography records from three Dutch teaching hospitals, demonstrating that individual institutions can generate several thousand assay orders annually. The study also reported real-world assay sensitivities of 97% and 99%, reinforcing the practical role of D-dimer testing in excluding pulmonary embolism before imaging. Separately, the CDC’s January 2025 update estimated up to 900,000 annual U.S. VTE cases, with more than one-third associated with recent hospitalization and one-fifth related to cancer. These high-risk cohorts support recurring demand for rapid assays, dependable analyzer capacity, and high-volume reagent supply.
 To learn more about this report, Download Free Sample Report
Over the longer term, sustained VTE-related testing demand will encourage laboratories to expand automated capacity and manufacturers to develop precise assays capable of consistently handling high clinical volumes. As VTE assessment expands across hospital networks and satellite laboratories, demand will increasingly favor scalable workflows, standardized interpretation, laboratory connectivity, and higher testing throughput without proportionate increases in staffing.
Limited standardization is a structural constraint because D-dimer comprises heterogeneous fibrin degradation products, while commercial assays use different antibodies, calibrators, analytical principles, reporting units, and decision thresholds. A 2024 international assessment examined External Quality Control for Assays and Tests data from 2017-2023, covering 578-690 laboratories annually and response rates of 88%-97%. In 2023, the three most-used assays accounted for 42%, 20%, and 10% of responses; however, the greatest interlaboratory variation occurred around 0.5 mg/L FEU, the commonly applied VTE exclusion threshold. This variability limits the interchangeability of results across hospitals and countries, complicates the transfer of clinical cutoffs between platforms, and makes multicenter protocols harder to standardize. Consequently, laboratories require method-specific validation and interpretation, lengthening procurement cycles and constraining seamless expansion across connected diagnostic networks.
CAP guidance described in August 2025 noted that FEU is approximately 1.74 times DDU, although a factor of two is commonly used. In one proficiency-testing summary, 32 laboratories reported a high-sensitivity reagent in DDU, while 657 used FEU. For another point-of-care reagent, 66 laboratories submitted a mean resembling FEU despite the manufacturer specifying DDU. After normalization to ng/mL FEU, CAP observed clusters approximately twice or half the dominant population, indicating probable unit errors. Preventive measures require unit verification, manufacturer-specific cutoffs, information-system configuration, staff training, clinician communication, and external quality assurance, increasing implementation costs and reducing flexibility to redistribute testing volumes across sites.
Long-term market development is further constrained by incomplete assay documentation and limited transferability of clinical evidence. A 2026 scoping review screened 9,670 records and included 58 VTE diagnostic-management studies involving 191-5,400 patients. Among 46 studies evaluating quantitative tests, only eight, or 17%, identified whether results used FEU or DDU, while only three of 58 studies, or 5.2%, reported assay detection limits. Researchers identified 19 quantitative assays across 19 threshold-and-unit combinations. Among 17 studies using multiple assays, only nine reported patient numbers by assay, and one provided assay-specific failure rates. These gaps complicate platform comparisons, multinational trials, and integration of new reagents into diagnostic pathways. Until commutable reference materials, common units, and minimum reporting standards achieve broad acceptance, new entrants will face higher validation costs and adoption barriers.
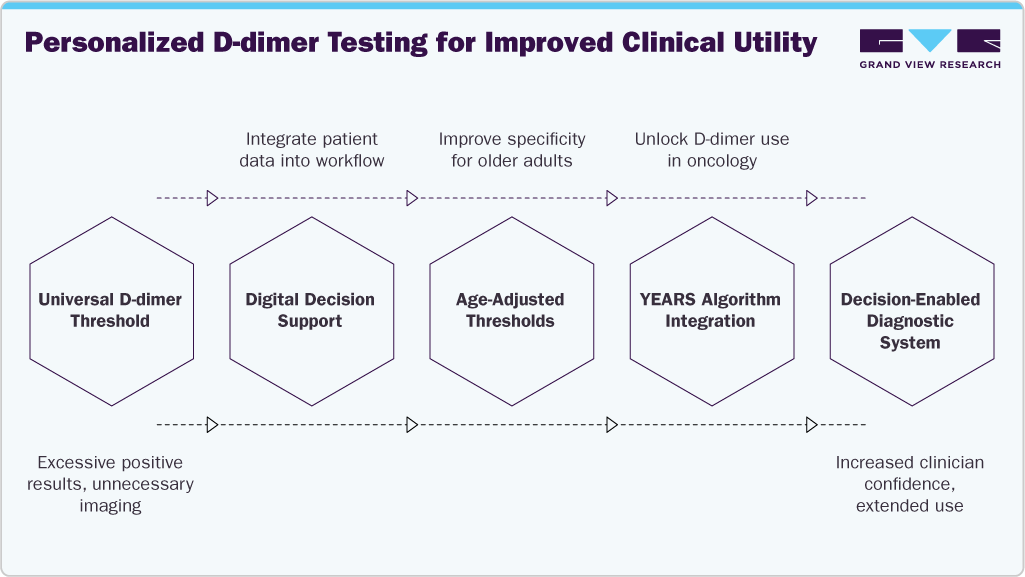
Personalized D-dimer cutoffs improve clinical utility in populations where the universal 500 µg/L threshold generates excessive positive results. The 2026 multinational ADJUST-DVT study evaluated 3,205 patients across 27 centers in Belgium, Canada, France, and Switzerland. Among 2,169 patients with non-high DVT probability, 531, or 25%, had levels below 500 µg/L, while another 161, or 7%, fell between conventional and age-adjusted thresholds; none of the latter developed VTE within three months. Among patients aged 75 years or older, the negative classification rate increased from 9% to 26% without false negatives, while the overall absolute improvement was 7.4%. These gains can expand D-dimer use among older adults and create demand for assays and software that automatically apply individualized cutoffs during testing.
Digital decision support can convert personalized thresholds into scalable demand by linking patient characteristics, clinical scores, and assay results within electronic workflows. A 2025 implementation study covered 38 U.S. emergency departments across three health systems and evaluated 270,247 encounters involving 211,658 patients over four months. Optional pretest-probability tools were documented in only 1%-3% of CTPA orders, whereas a mandatory workflow achieved 49%-53% documentation. At the mandatory site, 11% of initiated CTPA orders were canceled following assessment. However, manual calculation of Wells score components inflated the risk classification in 28% of CTPA cases, underscoring the need for automation. Vendors can integrate D-dimer results with Wells, PERC, YEARS, and age-adjusted logic, generating revenue from middleware, connectivity modules, implementation services, analyzer placements, and recurring assay consumption.
 To learn more about this report, Download Free Sample Report
Longer-term opportunities involve extending probability-adjusted thresholds to high-risk populations historically directed toward imaging. In July 2026, the randomized HYDRA trial enrolled 698 patients with active cancer and suspected pulmonary embolism across 21 hospitals in six countries. The YEARS algorithm applied a 1,000 ng/mL D-dimer threshold when no clinical criterion was present and 500 ng/mL when one or more criteria were applied. Its diagnostic failure rate was 1.8%, compared with 5.5% for a CTPA-only strategy, meeting noninferiority criteria while avoiding CTPA in 22% of patients. This evidence supports tailored D-dimer interpretation in oncology and creates opportunities for population-specific cutoff libraries, configurable software, and electronic-record integration. Vendors that combine assays, clinical rule engines, analytics, cybersecurity, and regulatory support can generate recurring software and service revenue alongside testing product sales.
Market Concentration & Characteristics
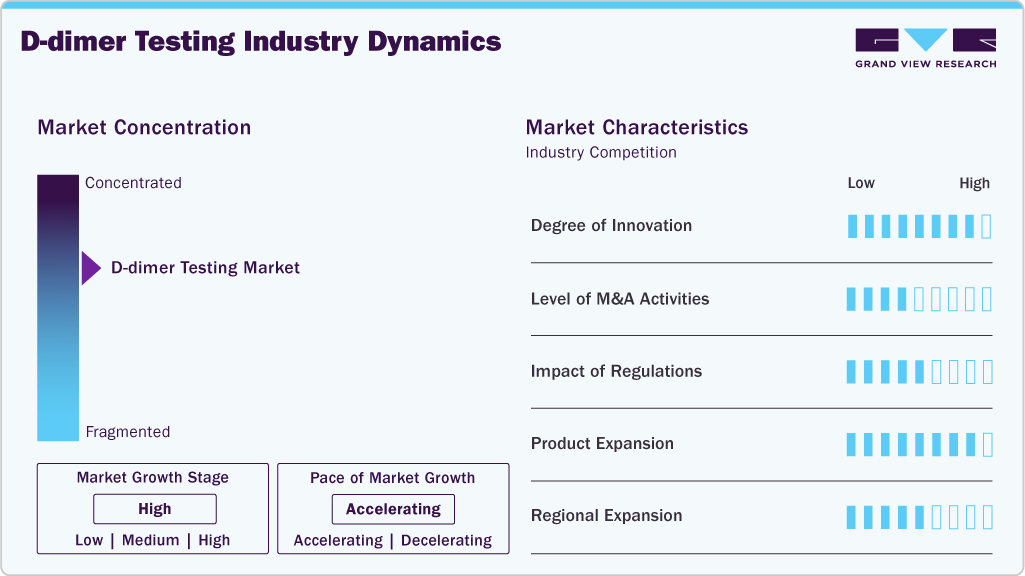
The D-dimer testing market demonstrates a moderate degree of innovation, reflecting its mature clinical foundation and incremental technological advancement. Innovation focuses on improving assay sensitivity, specificity, turnaround time, reagent stability, automation, and analyzer compatibility. Manufacturers are also expanding point-of-care platforms, integrated hemostasis menus, and digital connectivity to support faster clinical decisions and efficient laboratory workflows. The growing use of age-adjusted and probability-based cutoffs is encouraging integration with clinical decision-support systems. However, persistent differences in antibodies, calibrators, reporting units, and thresholds limit standardization. Therefore, innovation remains evolutionary, centered on workflow enhancement, decentralized testing, and improved clinical interpretation rather than disruption.
The global D-dimer testing industry exhibits a moderate level of merger and acquisition activity, as established diagnostic manufacturers typically prioritize internal product development, analyzer placements, and geographic expansion over frequent transactions. Nevertheless, targeted acquisitions remain strategically important for strengthening hemostasis portfolios, distribution networks, installed analyzer bases, and recurring reagent revenue. In April 2026, ARCHIMED and La Caisse completed the acquisition of Stago, a major specialist in coagulation analyzers and reagents, including D-dimer solutions. The transaction illustrates investor interest in scalable specialty diagnostics platforms. Future activity is expected to focus on portfolio consolidation, technological integration, and expansion into high-growth diagnostic markets.
 To learn more about this report, Download Free Sample Report
Regulations exert a high impact on the market because analyzers, reagents, calibrators, and controls must demonstrate analytical performance, clinical reliability, manufacturing quality, and appropriate labeling before commercialization. Requirements under the U.S. FDA and European IVDR increase development costs, evidence needs, and approval timelines, but they also strengthen confidence in test safety and accuracy. In August 2026, the FDA cleared INNOVANCE D-dimer 2.0, supported by evaluations involving approximately 2,500 patients across multiple systems, laboratories, and reagent lots. Such approvals expand access to updated assays, while stringent post-market, quality-system, and documentation obligations can slow entry for smaller manufacturers and competitors.
Product expansion is focused on broadening assay menus across automated coagulation, immunoassay, and point-of-care platforms. Manufacturers are introducing high-sensitivity, rapid-turnaround reagents, compact analyzers, extended calibration ranges, and software-supported interpretation to serve emergency departments, central laboratories, and decentralized care settings. Portfolio development increasingly emphasizes age-adjusted and clinical-probability-adjusted reporting, improved interference management, standardized units, and connectivity with laboratory information systems. Companies are also expanding geographic availability through regulatory registrations, distributor partnerships, and platform-specific assay additions. These initiatives increase instrument utilization, generate recurring reagent revenue, improve workflow efficiency, and strengthen supplier competitiveness across hospitals and diagnostic laboratories worldwide.
Regional expansion in the d-dimer testing market is driven by broader distribution networks, regulatory approvals, localized manufacturing, and installation of automated coagulation platforms across emerging healthcare systems. Manufacturers are strengthening their presence in the Asia Pacific, Latin America, and the Middle East and Africa through distributor agreements, laboratory partnerships, training programs, and technical support infrastructure. Rising hospital investment, expanding emergency diagnostics, and increasing awareness of venous thromboembolism support adoption beyond established markets in North America and Europe. Regional portfolio localization, including platform-compatible reagents, locally appropriate packaging, and flexible procurement models, improves affordability and availability while generating recurring revenue and expanding market penetration.
Analyst Perspective
The D-dimer testing market offers steady growth potential, supported by rising evaluation of suspected venous thromboembolism, expanding emergency-care volumes, and wider availability of automated coagulation testing. Reagent-based recurring revenue and installed analyzer bases provide manufacturers with defensible commercial positions. Growth will increasingly depend on assay specificity, harmonized reporting, rapid turnaround, and integration with clinical decision rules that reduce unnecessary imaging. Point-of-care adoption and expansion across emerging markets present additional opportunities. However, limited assay standardization, variable cutoffs, regulatory requirements, and reimbursement pressures remain important constraints. Companies combining clinical validation, workflow efficiency, and broad distribution are best positioned.
Product Insights
The reagents & consumables segment accounted for the largest share of 65.0% in the D-dimer testing market in 2025. Its strong position is driven by recurring purchases of assay reagents, kits, antibodies, calibrators, controls, cartridges, cuvettes, and other test-specific materials. Demand is directly linked to testing volumes across hospitals, diagnostic centers, and reference laboratories, particularly for suspected DVT, PE, and DIC. Ready-to-use formulations, extended onboard stability, improved sensitivity, and broad analyzer compatibility enhance laboratory efficiency and reduce wastage. In February 2025, Nordic Biomarker announced IVDR certification for its D-dimer reagents and associated calibrators, its first products certified under the European IVDR, strengthening compliant product availability and market adoption.
The analyzers segment is expected to grow at the fastest CAGR over the forecast period, supported by rising testing volumes, laboratory automation, and demand for rapid, standardized, and reproducible D-dimer results. Automated and semi-automated coagulation platforms improve throughput, reduce manual intervention, and boost D-dimer, along with APTT, PT, fibrinogen, and other hemostasis assays. Advanced systems incorporate random-access testing, barcode identification, automated sample handling, quality controls, and laboratory connectivity.
Test Insights
The clinical laboratory tests segment dominated the global market, accounting for 61.9% of revenue in 2025, led by high-volume testing across hospital laboratories, diagnostic centers, and reference laboratories. Quantitative assays performed on automated coagulation and immunoassay systems provide standardized, reproducible results for excluding DVT and PE and assessing DIC. Automation in sample identification, reagent handling, calibration, quality control, and information-system connectivity improves workflow efficiency. In April 2024, Siemens Healthineers released an updated application sheet for INNOVANCE D-dimer on CA-500/CA-600 series systems, providing validated assay parameters and supporting standardized laboratory use. Expanding laboratory capacity will sustain segment growth globally.
The point-of-care tests segment is expected to record the fastest growth, at a 4.0% CAGR, underpinned by demand for rapid D-dimer results in emergency departments, bedside settings, urgent-care facilities, and physician offices. Compact readers and dedicated cartridges reduce specimen transport and accelerate assessment of suspected venous thromboembolism. Simplified preparation, automated processing, barcode identification, and digital connectivity improve portability and usability. In July 2024, LumiraDx announced the completion of its acquisition by Roche, bringing its point-of-care diagnostic technology and platform capabilities into Roche’s portfolio. Healthcare decentralization, rising emergency-care volumes, and rapid rule-out pathways are expected to sustain analyzer and consumable demand.
Method Insights
The Enzyme-linked Immunosorbent Assay (ELISA) segment dominated the D-dimer testing market, accounting for 41.5% of revenue in 2025, fueled by its high analytical sensitivity, specificity, and quantitative capability. ELISA-based testing includes sandwich assays, pre-coated microplates, enzyme-labeled antibodies, calibrators, controls, substrates, and compatible readers used for D-dimer measurement. Technological improvements, including recombinant antibodies, optimized conjugates, and shorter incubation and washing steps, are improving throughput and reproducibility. In May 2024, Elabscience’s QuicKey Pro Human D2D (D-dimer) ELISA Kit was highlighted in the Korean market. Expanding coagulation research and biomarker testing should sustain recurring demand for ELISA kits and associated detection materials.
The fluorescence immunoassays segment is expected to demonstrate the fastest growth, at a 4.7% CAGR over the forecast period, supported by increasing demand for rapid, quantitative D-dimer testing in emergency, hospital, and near-patient settings. Fluorescent labels, compact readers, dry-reagent formats, barcode-based calibration, automated strip recognition, and simplified sample preparation improve sensitivity, portability, and workflow efficiency. In February 2025, WIZ Biotech announced that its fluorescence-immunochromatographic Diagnostic Kit for D-dimer received registration approval from Malaysia’s Medical Device Authority. The assay quantitatively measures D-dimer in plasma or whole blood for assessing venous thrombosis and DIC. Diagnostic decentralization and the expansion of multiparameter assay menus should sustain segment growth.
Application Insights
The Deep Vein Thrombosis (DVT) segment dominated the market, accounting for 37.2% of revenue in 2025, supported by frequent evaluation of patients presenting with lower-extremity pain or swelling. D-dimer testing, performed on laboratory analyzers, immunoassay systems, and point-of-care platforms, is combined with clinical pretest probability to exclude DVT in appropriate patients and reduce unnecessary imaging. Faster quantitative assays, improved standardization, and workflow integration strengthen clinical utility. The FDA recognizes CLSI H59-A guidance covering D-dimer use for excluding venous thromboembolic disease. Rising VTE awareness, expanding emergency services, and evidence-based imaging pathways should sustain recurring testing demand and revenue.
The Disseminated Intravascular Coagulation (DIC) segment is expected to demonstrate the fastest growth, supported by rising critical-care utilization, recurring monitoring requirements, and expanding automated coagulation testing. D-dimer reflects fibrin formation and breakdown and is interpreted alongside platelet count, fibrinogen, prothrombin time, and activated partial thromboplastin time. Automated platforms improve speed, standardization, and integration of multiparameter assessment. In June 2025, the International Society on Thrombosis and Haemostasis published an updated DIC definition and scoring system recommending D-dimer as the fibrin-related marker in the overt DIC score and specifying elevated thresholds. Growing ICU, oncology, obstetric, surgical, and emergency-care demand supports growth.
End Use Insights
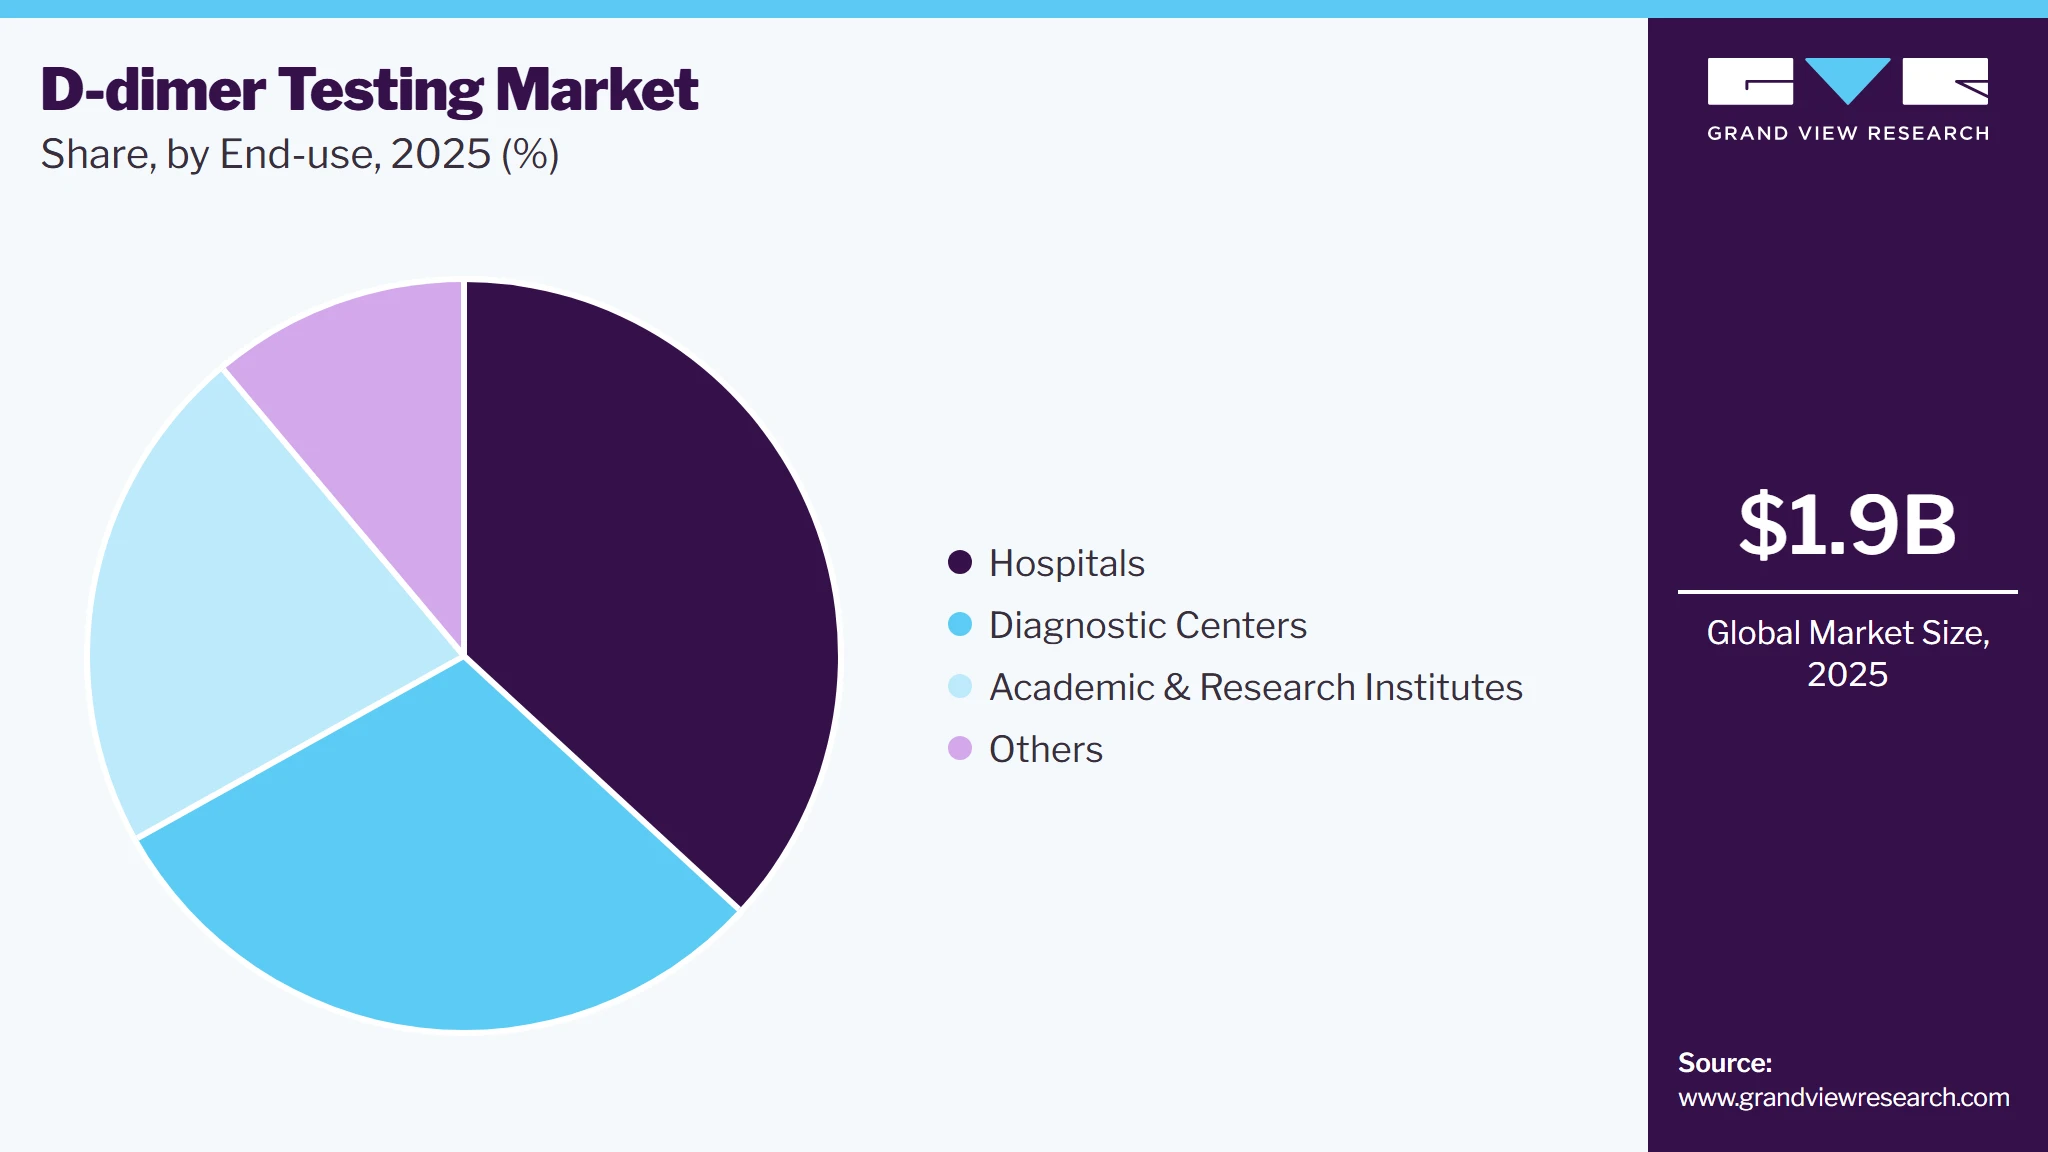
The hospitals segment accounted for the largest share of 36.8% in 2025, supported by high emergency, inpatient, outpatient, and laboratory testing volumes. Hospitals use D-dimer assays to support rapid exclusion of DVT and PE and assessment of DIC and other coagulation disorders. Revenue includes reagents, assay kits, analyzers, controls, calibrators, consumables, and testing services. In April 2024, Sysmex and Siemens Healthineers began independently selling their branded coagulation testing solutions in the U.S. and EU, broadening access to integrated instruments and reagents. Laboratory automation, rapid turnaround, hospital capacity expansion, and recurring reagent consumption should sustain growth.
 To learn more about this report, Download Free Sample Report
The diagnostic centers segment is expected to record the fastest growth, driven by expansion of private laboratory networks, outsourcing of specialized testing, and demand for accessible, rapid diagnostic services. Independent laboratories and standalone centers generate revenue from D-dimer reagents, assay kits, calibrators, controls, consumables, analyzers, and fee-based testing services. Compact automated platforms support D-dimer alongside PT, APTT, fibrinogen, and other hemostasis assays, improving throughput and instrument utilization. In April 2025, Lupin Diagnostics achieved 100% NABL accreditation across its greenfield laboratories, strengthening quality and supporting accredited diagnostic service expansion. Growing awareness, automation, quality assurance, and recurring reagent demand should support growth.
Regional Insights
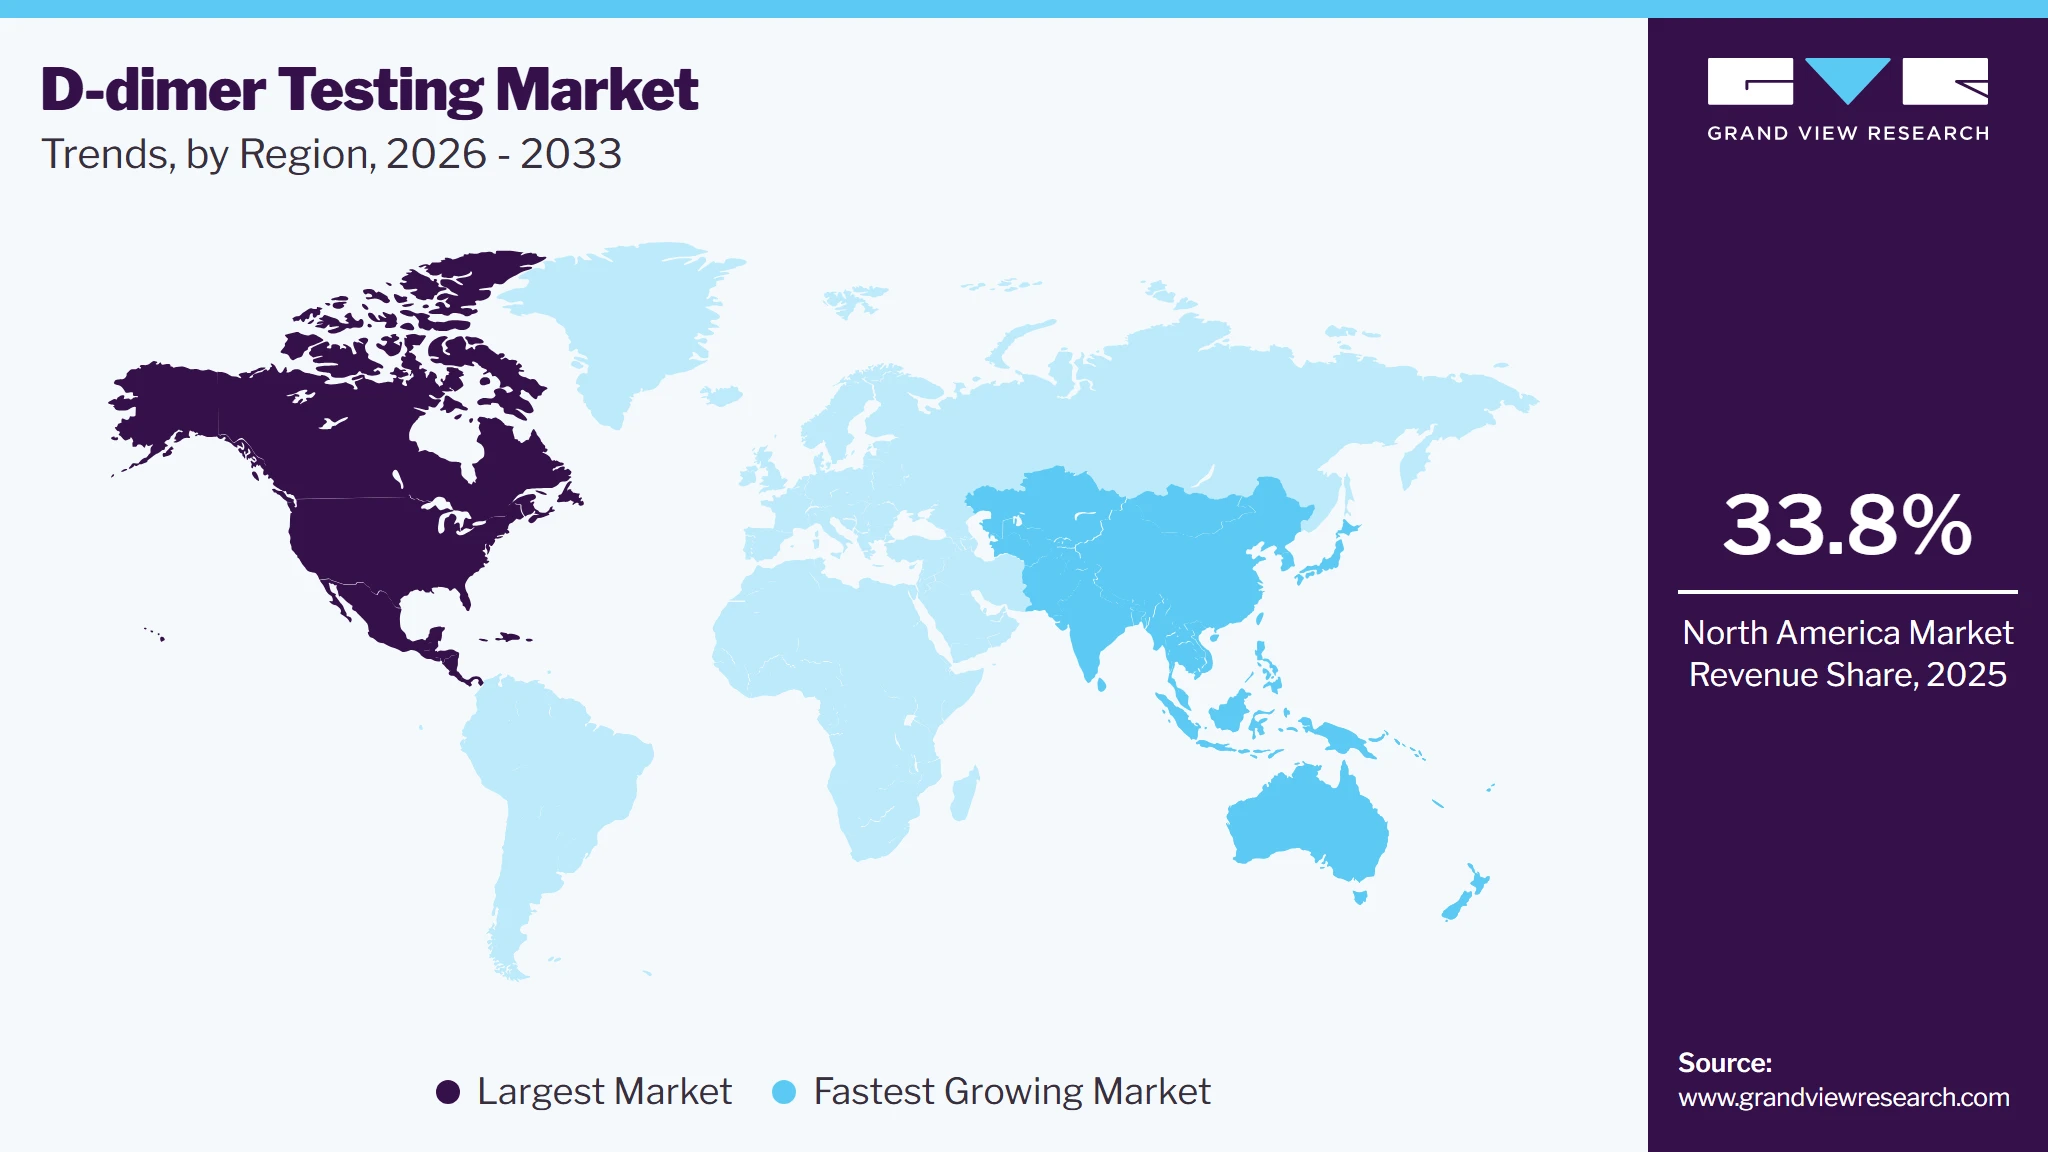
North America dominated the global D-dimer testing market, accounting for the largest revenue share of 33.8% in 2025, supported by advanced healthcare infrastructure, established laboratory networks, favorable reimbursement, and widespread coagulation testing. The region faces a substantial venous thromboembolism burden; the CDC estimates that up to 900,000 people in the U.S. are affected annually by VTE, including DVT and PE. Combining D-dimer assays with clinical pretest-probability assessment supports rapid exclusion and may reduce unnecessary imaging. Regulatory clearances, automated hemostasis platforms, strong hospital infrastructure, independent laboratories, and high diagnostic awareness are expected to sustain testing adoption and market leadership throughout the forecast period globally.
 To learn more about this report, Download Free Sample Report
U.S. D-Dimer Testing Market Trends
The D-dimer testing market in the U.S. accounted for the largest share of the North American industry, underscored by advanced laboratory infrastructure, high VTE testing volumes, favorable reimbursement, and strong adoption of automated coagulation systems. Competition includes Siemens Healthineers, Sysmex, Werfen, Roche, Beckman Coulter, bioMérieux, and Diazyme Laboratories, with vendors differentiating through accuracy, turnaround time, automation, assay menus, and workflow connectivity. In June 2025, Sysmex America received FDA clearance for the CN-6000 Automated Blood Coagulation Analyzer, covering INNOVANCE D-dimer alongside PT/INR, APTT, fibrinogen, and antithrombin testing. Integrated analyzer-reagent ecosystems, broad installed bases, recurring consumable demand, and technical support networks reinforce U.S. market leadership.
Europe D-Dimer Testing Market Trends
The D-dimer testing market in Europe is supported by a substantial VTE burden, developed emergency-care infrastructure, and evidence-based diagnostic pathways for DVT and PE. Clinical guidance supports the use of highly sensitive assays and age-adjusted thresholds for appropriately selected patients. National reimbursement systems, including Germany’s EBM and France’s quantitative D-dimer codes, support routine testing, while the EU IVDR strengthens clinical-evidence, conformity-assessment, and surveillance requirements. In June 2025, UpFront Diagnostics secured approximately USD 40,430 to support CE marking of its LVOne point-of-care stroke diagnostic, which measures D-dimer alongside GFAP from a finger-prick sample. Although stroke-focused, the initiative demonstrates regional investment in decentralized biomarker testing.
The UK D-dimer Testing Market is spurred by well-developed NHS diagnostic pathways, laboratory networks, external quality assurance, and demand for rapid evaluation of suspected DVT and PE. Competition includes Roche, Abbott, Siemens Healthineers, Werfen, Sysmex, Helena Biosciences, and point-of-care suppliers differentiating through sensitivity, turnaround time, automation, connectivity, and cost. In May 2026, UpFront Diagnostics commercially launched its UKCA-marked LVOne stroke triage test in the UK with London Ambulance Service deployment. The finger-prick assay measures D-dimer and GFAP within ten minutes. NHS procurement alignment, analyzer integration, assay breadth, and quality assurance drive competitiveness.
The D-dimer testing market in Germany is characterized by competition among multinational diagnostics and hemostasis specialists, including Siemens Healthineers, Roche Diagnostics, Sysmex, and Stago. Suppliers compete through analytical sensitivity, turnaround time, assay standardization, automation, connectivity, installed analyzer bases, and integration with broader coagulation menus. Siemens’ INNOVANCE D-dimer supports use across Siemens and Sysmex systems, while Roche offers centralized and near-patient solutions. German laboratories prioritize platforms combining D-dimer with PT, APTT, fibrinogen, anti-Xa, and other assays. Long-term competitiveness depends on IVDR readiness, validated cutoffs, quality assurance, technical service, reagent availability, digital interoperability, and efficient support for hospital laboratories and decentralized testing environments nationally.
Asia Pacific D-Dimer Testing Market Trends
The D-dimer testing market in the Asia Pacific is expected to depict the fastest CAGR over the forecast period, bolstered by increasing VTE awareness, rising cardiovascular and chronic disease burdens, and expanding hospital and diagnostic infrastructure across China, Japan, India, South Korea, and Australia. Adoption is strengthened by automated coagulation platforms and rapid testing for suspected DVT, PE, and DIC. Reimbursement remains country-specific; Australia includes D-dimer under Medicare pathology item 65120, providing a defined coverage pathway for eligible testing. Regulatory modernization, laboratory automation, digital healthcare investment, quality-control initiatives, and growing domestic diagnostics companies are improving access, standardization, and competitive intensity across both mature and emerging markets.
The China D-dimer testing market is competitive, with Mindray, Wondfo, Snibe, Maccura, and multinational suppliers competing across analyzers, reagents, controls, and laboratory automation. Domestic companies benefit from established distribution and localized manufacturing, while international vendors emphasize standardized assays, advanced automation, and integrated coagulation platforms. In July 2025, Wondfo Biotech reported that its wholly owned subsidiary obtained registration for a five-item thrombosis-testing panel, including D-dimer. The portfolio supports thrombotic disease assessment, DIC diagnosis, treatment monitoring, and recurrent thrombosis evaluation. Competition increasingly centers on broader assay menus, high throughput, reagent pricing, automated quality control, laboratory connectivity, instrument placement, and responsive technical support nationwide.
The Japan D-dimertesting market is supported by an aging population, rising chronic disease burden, preventive healthcare, and mature hospital laboratory infrastructure. Competition includes Sysmex, Werfen, other suppliers, and domestic manufacturers, with differentiation based on assay performance, automation, reagent consistency, workflow integration, turnaround time, and service support. In March 2025, Immunosense introduced GLEIA Check D-dimer in Japan, with PMDA records listing it as a newly registered product and Immunosense as the marketing authorization holder. Its compact reader and gold-linked electrochemical immunoassay technology expand options beyond central-laboratory platforms. Integrated analyzer-reagent-service portfolios, assay breadth, local support, and standardization drive competitiveness.
Latin America D-Dimer Testing Market Trends
The D-dimer testing market in Latin America is supported by increasing recognition of D-dimer as an accessible rule-out tool for DVT and PE within appropriate clinical pathways. Brazil and Argentina remain important markets, benefiting from expanding laboratory infrastructure and reimbursement frameworks. Brazil’s SUS uses SIGTAP to define diagnostic procedures and financing parameters, while Argentine national and provincial schedules support laboratory reimbursement. In January 2026, the implementation of Brazil’s Anvisa RDC 848/2024 reinforced essential safety and performance requirements for IVD devices, including risk management, analytical and clinical performance, quality systems, and clinical evaluation. Laboratory automation, accredited networks, and public-private collaboration are improving access.
Middle East and Africa D-Dimer Testing Market Trends
The D-dimer testing market in the Middle East & Africa is supported by rising demand for rapid thromboembolic assessment across emergency, inpatient, and diagnostic settings. Saudi Arabia and the UAE benefit from expanding hospitals and private healthcare networks, while South Africa has established a pathology infrastructure. Insurance coverage and standardized service pricing support eligible testing. The SFDA regulates IVD authorization, licensing, surveillance, quality, and performance, while SAHPRA oversees medical devices and IVDs. In February 2025, SAHPRA updated its Guideline for Classification of Medical Devices and IVDs to Version 5, clarifying classification requirements. Expanding capacity should sustain demand for analyzers, reagents, consumables, and tests.
Key D-Dimer Testing Company Insights
The global D-dimer testing market features competition among F. Hoffmann-La Roche Ltd., Siemens Healthineers AG, Werfen, Sysmex Corporation, and Abbott Laboratories. Market participants compete through product performance, assay reliability, turnaround time, analyzer throughput, workflow automation, digital connectivity, and customer support. Their portfolios include automated coagulation analyzers, immunoassay platforms, point-of-care systems, reagents, calibrators, and controls. Established companies leverage extensive distribution networks, regulatory capabilities, installed instrument bases, and long-standing relationships with hospitals and diagnostic laboratories. Key business strategies include expanding assay menus, securing regulatory approvals, entering new geographic markets, forming strategic partnerships, and undertaking targeted acquisitions to strengthen product portfolios and increase recurring revenue from consumables.
Key D-Dimer Testing Companies
The following key companies have been profiled for this study on the D-dimer testing market.
-
F. Hoffmann-La Roche Ltd.
-
Siemens Healthineers AG
-
Werfen
-
Sysmex Corporation
-
Abbott Laboratories
-
Diagnostica Stago S.A.S.
-
bioMérieux S.A.
-
Danaher Corporation
-
QuidelOrtho Corporation
-
Thermo Fisher Scientific Inc.
-
HORIBA, Ltd.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Player: F. Hoffmann-La Roche Ltd
- Leverage established hemostasis and diagnostic portfolios to provide standardized D-dimer testing across hospitals, emergency departments, diagnostic laboratories, and reference laboratories.
- Strengthen market positions through continuous D-dimer assay development, automated coagulation platforms, expanded assay menus, regulatory approvals, and laboratory workflow integration.
- Invest in high-throughput coagulation systems, automation, connectivity, quality control, and service infrastructure to improve laboratory efficiency and reinforce recurring reagent demand.
- Strong global brand recognition, extensive installed analyzer bases, established laboratory relationships, and broad geographic commercial networks.
- Comprehensive portfolios spanning D-dimer assays, automated coagulation analyzers, broader hemostasis testing, reagents, calibrators, quality-control materials, and laboratory connectivity.
- Significant regulatory, R&D, manufacturing, and technical-service capabilities supporting reliable product commercialization and long-term customer relationships.
- Large organizational structures may result in longer product-development, regulatory, and commercialization cycles compared with smaller specialized competitors.
- Premium system and reagent pricing may limit penetration in smaller laboratories and resource-constrained healthcare settings.
- Dependence on established centralized laboratory workflows may constrain exposure to rapidly developing decentralized and point-of-care testing opportunities.
Emerging Player: Werfen
- Leverage specialized diagnostic, laboratory, and analytical capabilities to expand participation in D-dimer and broader coagulation-testing workflows.
- Strengthen market presence through targeted assay and platform development, laboratory automation, regulatory expansion, and integration of D-dimer testing into broader diagnostic portfolios.
- Differentiate through specialized technologies, workflow efficiency, analytical performance, and solutions addressing laboratories seeking flexible and cost-effective testing capabilities.
- Established expertise in diagnostics, laboratory technologies, analytical instrumentation, and healthcare workflows provides a foundation for expanding D-dimer-related offerings.
- Ability to leverage existing customer relationships, distribution infrastructure, and complementary diagnostic portfolios to access laboratories without relying exclusively on standalone D-dimer products.
- Greater portfolio specialization in selected technology areas can support targeted innovation and faster adaptation.
- Smaller or less concentrated D-dimer-specific commercial exposure compared with leading dedicated hemostasis and IVD companies.
- More limited D-dimer-focused installed bases and recurring reagent ecosystems may restrict customer lock-in and economies of scale.
- Broader corporate portfolios may make D-dimer a relatively limited commercial priority, reducing dedicated investment compared with established hemostasis leaders.
Recent Developments
-
In August 2026, Siemens Healthineers got the FDA 510(k) clearance for its next-generation INNOVANCE D-dimer 2.0 assay, designed to provide improved precision, low interference, simplified handling, and consistent performance for DVT and PE exclusion.
-
In July 2025, Siemens Healthineers launched the CN-3000 and CN-6000 Hemostasis Systems in Canada following Health Canada licensing. The systems support Siemens' coagulation menu, including INNOVANCE D-dimer, expanding access to automated D-dimer testing in the Canadian laboratory market.
-
In March 2025, Werfen commercialized the ACL TOP Family 70 Series Hemostasis Testing Systems in North America following U.S. FDA 510(k) clearance and Health Canada licensure. The systems are compatible with Werfen's HemosIL reagent portfolio, including D-dimer assays, extending automated D-dimer testing across different laboratory volumes.
D-Dimer Testing Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.9 billion
Estimated market size in 2026
USD 2.1 billion
Projected market size by 2033
USD 2.7 billion
Growth rate
CAGR of 3.7% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, test, method , application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; Australia; Thailand; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
F. Hoffmann-La Roche Ltd.; Siemens Healthineers AG; Werfen; Sysmex Corporation; Abbott Laboratories; Diagnostica Stago S.A.S.; bioMérieux S.A.; Danaher Corporation; QuidelOrtho Corporation; Thermo Fisher Scientific Inc.; HORIBA, Ltd.
Customization scope
Free report customization (equivalent up to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global D-Dimer Testing Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global D-dimer testing market report by product, test, method, application, end use, and region.
-
Product Outlook (Revenue, USD billion, 2021 - 2033)
-
Analyzers
-
Reagents & Consumables
-
-
Test Outlook (Revenue, USD billion, 2021 - 2033)
-
Clinical Laboratory Tests
-
Point-of-Care Tests
-
-
Method Outlook (Revenue, USD billion, 2021 - 2033)
-
Enzyme-linked Immunosorbent Assay (ELISA)
-
Latex-enhanced Immunoturbidimetric Assays
-
Fluorescence Immunoassays
-
Others
-
-
Application Outlook (Revenue, USD billion, 2021 - 2033)
-
Deep Vein Thrombosis (DVT)
-
Pulmonary Embolism (PE)
-
Disseminated Intravascular Coagulation (DIC)
-
Others
-
-
End Use Outlook (Revenue, USD billion, 2021 - 2033)
-
Hospitals
-
Academic & Research Institutes
-
Diagnostic Centers
-
Others
-
-
Regional Outlook (Revenue, USD billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Norway
-
Denmark
-
Sweden
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The D-dimer testing market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each D-dimer testing segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Product
Revenue capture definition
Analyzers
Includes laboratory and point-of-care instruments used to perform D-dimer assays. Revenue flows from analyzer sales, leases, and placements with separately identifiable instrument charges, excluding reagents, consumables, and general laboratory equipment.
Reagents & Consumables
Includes D-dimer-specific reagent kits, cartridges, test cassettes, calibrators, controls, buffers, and assay-specific disposables. Market value is captured through recurring purchases required to perform, calibrate, and validate D-dimer tests.
Test
Revenue capture definition
Clinical Laboratory Tests
Covers D-dimer assays performed on centralized or laboratory-based analyzers by trained personnel. Revenue is primarily captured from high-throughput instruments, reagent kits, calibrators, controls, and associated assay consumables used within laboratories.
Point-of-Care Tests
Covers D-dimer assays performed near patients in emergency departments, wards, clinics, or ambulatory settings using compact devices. Commercial value derives from dedicated readers, single-use cartridges, cassettes, and testing consumables.
Method
Revenue capture definition
Enzyme-Linked Immunosorbent Assay (ELISA)
Includes plate-based enzyme immunoassays that detect D-dimer through antibody binding and enzyme-mediated signal development. Revenue is captured from ELISA kits, plates, conjugates, substrates, calibrators, controls, and compatible processing equipment.
Latex-Enhanced Immunoturbidimetric Assays
Includes assays measuring turbidity produced when antibody-coated latex particles bind D-dimer, primarily on automated coagulation or chemistry analyzers. Revenue flows mainly from reagent packs, latex suspensions, calibrators, controls, and disposables.
Fluorescence Immunoassays
Includes D-dimer immunoassays using fluorescent labels and optical detection, commonly in rapid or point-of-care platforms. Market proceeds arise from fluorescence readers, assay cartridges, test strips, reagents, calibration materials, and controls.
Others
Includes immunochromatographic, chemiluminescent, whole-blood agglutination, and other D-dimer methods not classified above. Commercial receipts come from method-specific analyzers, test kits, cartridges, strips, reagents, calibrators, controls, and consumables.
Application
Revenue capture definition
Deep Vein Thrombosis (DVT)
Covers D-dimer products used when the documented primary testing indication is suspected deep vein thrombosis, generally supporting exclusion before venous imaging. Market value reflects the corresponding proportion of instruments and consumables utilized..
Pulmonary Embolism (PE)
Covers D-dimer testing ordered primarily to evaluate suspected pulmonary embolism and support imaging decisions. Revenue allocation is based on PE-designated test volumes and the associated utilization of analyzers, reagents, cartridges, and controls.
Disseminated Intravascular Coagulation (DIC)
Includes D-dimer testing performed primarily to diagnose, assess, or monitor disseminated intravascular coagulation. Revenue is attributed from DIC-related test volumes and their proportional consumption of assay reagents, consumables, and analyzer capacity.
Others
Includes D-dimer testing for other documented indications, such as thrombotic-risk assessment and monitoring outside DVT, PE, or DIC pathways. Market income is allocated according to indication-specific test utilization and product consumption.
End Use
Revenue capture definition
Hospitals
Includes hospital laboratories, emergency departments, inpatient units, and hospital-affiliated testing facilities purchasing D-dimer products for clinical care. Revenue accrues through analyzer procurement, leasing, reagent contracts, cartridges, controls, and recurring consumable purchases.
Academic & Research Institutes
Includes universities and independent research institutions purchasing D-dimer products for non-routine research, method evaluation, and clinical studies. Funding flows into analyzers, research-use kits, reagents, controls, and study-specific consumables.
Diagnostic Centers
Includes independent diagnostic laboratories and laboratory networks performing D-dimer tests for referred or walk-in patients. Sales are captured through centralized analyzers, reagent supply agreements, calibrators, controls, and routine testing consumables
Others
Includes physician offices, ambulatory centers, specialty clinics, nursing facilities, and other purchasers not classified above. Market receipts arise predominantly from compact analyzers, point-of-care cartridges, rapid kits, controls, and related consumables.
Estimation Model
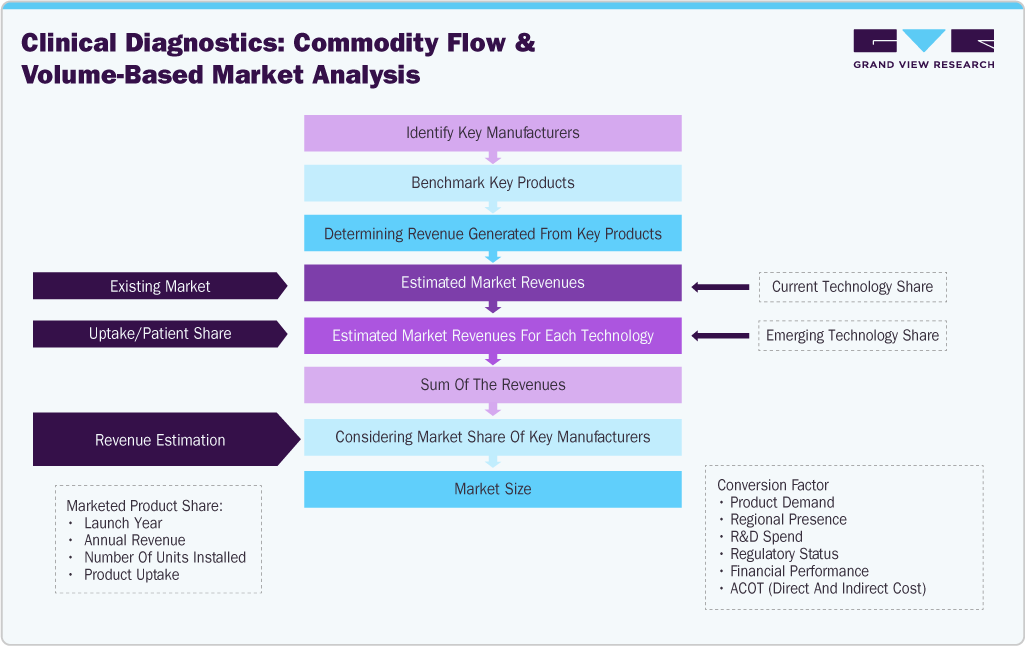
The D-dimer testing market was estimated using a bottom-up approach by identifying key manufacturers, benchmarking their analyzers and assay products, and assessing product-level revenues. Revenues were further allocated by testing method using market uptake and patient shares, aggregated, and validated against the estimated market shares of leading manufacturers to determine the overall market size.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
D-Dimer Testing Market Competitive Landscape & Technology Assessment
Assessed competition across automated coagulation analyzers, clinical laboratory immunoassays, and point-of-care D-dimer platforms. Evaluated manufacturers based on assay portfolios, analytical performance, turnaround time, throughput, reporting units, analyzer compatibility, regulatory approvals, connectivity, distribution networks, and geographic presence.
Enables the client to benchmark leading D-dimer testing companies, assess technological differentiation, identify competitive strengths and portfolio gaps, and evaluate positioning across hospital laboratories, diagnostic centers, emergency departments, and decentralized testing settings.
D-Dimer Test and Product Benchmarking Analysis
Conducted comparative benchmarking of D-dimer analyzers, reagents, consumables, and point-of-care tests. Assessed ELISA, latex-enhanced immunoturbidimetric, fluorescence immunoassay, and other methods based on sample type, sensitivity, cutoff, reporting unit, turnaround time, throughput, workflow requirements, and intended use.
Helps the client compare product performance and commercial positioning, identify unmet requirements, and prioritize opportunities across automated laboratory testing, rapid point-of-care testing, assay standardization, workflow integration, and personalized cutoff applications.
D-Dimer Testing Commercialization & Market-Entry Assessment
Assessed commercialization strategies, regulatory pathways, reimbursement conditions, distribution models, testing infrastructure, procurement requirements, and adoption barriers across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. Evaluated adoption across hospitals, diagnostic laboratories, research institutes, clinics, and ambulatory settings.
Supports market-entry and expansion planning by identifying high-potential regions and end users, evaluating regulatory and reimbursement requirements, assessing laboratory and point-of-care opportunities, and developing commercialization strategies for D-dimer analyzers, assays, reagents, and consumables.
Frequently Asked Questions About This Report
The global d-dimer testing market size was valued at USD 1.9 billion in 2025 and is estimated at USD 2.1 billion for 2026.
The global d-dimer testing market is expected to grow at a CAGR of 3.7% from 2026 to 2033, reaching USD 2.7 billion by 2033
Key factors that are driving the D-dimer testing market growth include a rise in the growing burden of venous thromboembolism and expansion of the high-risk population
Major market participants include F. Hoffmann-La Roche Ltd., Siemens Healthineers AG, Werfen, Sysmex Corporation, Abbott Laboratories, Diagnostica Stago S.A.S., bioMérieux S.A., Danaher Corporation, QuidelOrtho Corporation, Thermo Fisher Scientific Inc., HORIBA, Ltd., and among others. These companies compete through innovation, expansion, partnerships, and acquisitions.
Asia Pacific is projected to register the fastest CAGR of 4.42% during 2026-2033, owing to rising investments, expanding infrastructure, and increasing product adoption.
The Reagents & Consumables segment held the largest revenue share of 65.0% in 2025, supported by its broad commercial availability, recurring demand, and widespread end-user adoption.
Deep vein thrombosis (DVT) segment generated the highest revenue in 2025, driven by high product consumption, expanding use cases, and strong demand from key industries.
North America dominated with a 33.8% revenue share in 2025. This is attributable to a large number of publications related to the applications of D-dimer that expand the clinical utility of these coagulation tests in this region.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


