
- Home
- »
- Medical Devices
- »
-
Dental Insurance Market Size & Share Report, 2026-2033GVR Report cover

Dental Insurance Market (2026 - 2033)
Size, Share & Trends Analysis Report By Coverage (Dental Preferred Provider Organizations, Dental Health Maintenance Organizations), By Type (Major, Basic, Preventive), By Demographic, By Region, And Segment Forecasts
Market Size, 2025
$247.5BMarket Estimate, 2026
$259.1BMarket Forecast, 2033
$480.0BCAGR, 2026–2033
9.2%Dental Insurance Market Summary
The global dental insurance market size was valued at USD 247.5 billion in 2025 and is projected to grow from USD 259.1 billion in 2026 to USD 480.0 billion in 2033, at a CAGR of 9.2% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 41.0% in 2025. The global market is primarily driven by increasing awareness of oral health, the rising prevalence of dental disorders, the expansion of employer-sponsored dental benefit programs, and the escalating cost of dental treatments.
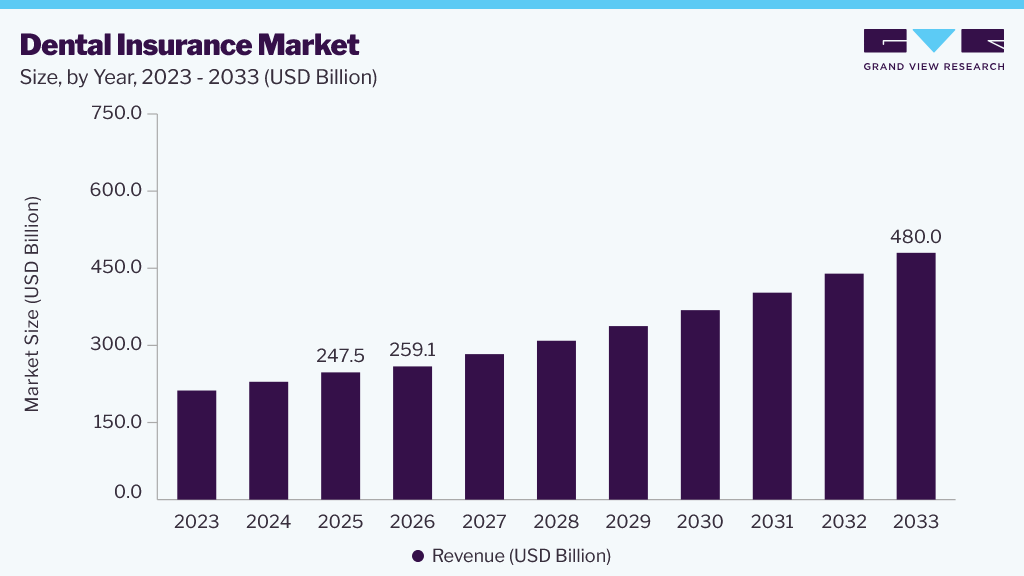 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By coverage: The DPPO segment held the largest revenue share of around 65.0% in 2025.
- By type: The preventive plan segment held the largest revenue share of over 40.0% in 2025.
- By demographic: The senior citizens segment held the largest share of over 60.0% in 2025.
Regional Highlights
- Largest regional market: North America (41.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 247.5 Billion
- Estimated market size in 2026: USD 259.1 Billion
- Projected market size by 2033: USD 480.0 Billion
- CAGR (2026-2033): 9.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
These factors are encouraging individuals and employers to adopt dental insurance plans to improve access to oral healthcare and mitigate the financial burden of dental procedures.Technological advancements are expected to create significant growth opportunities for the dental insurance market. The transition from traditional legacy systems to Software-as-a-Service (SaaS) and cloud-based platforms is transforming the operations of health and dental insurance providers by reducing reliance on on-premises infrastructure and improving data access. Cloud-based technologies enable greater scalability, seamless integration with healthcare and dental provider systems, simplified system upgrades, and improved user experiences. These capabilities can help insurers streamline claims processing, enhance customer engagement, improve operational efficiency, and develop more flexible and personalized dental insurance products, thereby supporting market expansion.
The large uninsured population also represents a significant opportunity for dental insurers to expand their customer base. According to a 2024 study published in the peer-reviewed journal Health Services Research, which cited data from the CareQuest Institute for Oral Health, nearly 68.5 million U.S. adults lacked dental coverage. The study also notes that adult dental benefits remain optional under the Affordable Care Act (ACA), creating a substantial coverage gap among adults. This large pool of uninsured individuals represents an untapped addressable population for dental insurers. As awareness of oral health increases and consumers seek greater financial protection against dental treatment costs, insurers have opportunities to increase enrollment through individual, employer-sponsored, and marketplace dental plans. The availability of adult dental plans across all U.S. states further supports the potential for insurers to convert the existing coverage gap into incremental demand for dental insurance products.
The increasing emphasis on preventive and value-based dental care is expected to create additional growth opportunities. Insurers are increasingly focusing on preventive services, including routine dental examinations, cleaning, and early diagnosis, to encourage regular utilization of dental services and potentially reduce the need for more costly treatments. Greater coverage and incentives for preventive care can encourage consumers to seek dental services earlier and more frequently, increasing utilization of covered services and strengthening the perceived value of dental insurance. This shift toward proactive oral healthcare is expected to support the adoption of insurance and encourage the development of more comprehensive dental plans.
Market Dynamics
The market is primarily driven by the increasing prevalence of dental disorders, growing awareness of oral health and preventive care, and rising dental treatment costs. The expansion of employer-sponsored dental benefit programs and increasing utilization of dental services, including preventive, restorative, and orthodontic procedures, further support market growth. However, limited coverage for certain advanced and cosmetic dental procedures, along with low insurance penetration in developing regions, may restrain market expansion. Nevertheless, the growing adoption of digital insurance platforms, increasing focus on preventive healthcare, and the large uninsured population continue to create significant growth opportunities for the market.
The rising prevalence of oral diseases and increasing expenditure on dental care are major drivers for the market. Dental insurance helps individuals manage the financial burden of preventive, restorative, and emergency dental care, making oral healthcare more accessible and affordable. The growing incidence of dental caries, periodontal diseases, tooth loss, and oral cancers is increasing demand for routine dental services, encouraging consumers to seek insurance coverage to protect against costs.
Growing awareness of oral health, expanding access to dental services, and increasing emphasis on preventive care are supporting demand for dental insurance. In addition, the rising cost of dental procedures, including implants, crowns, root canals, and orthodontic treatments, is prompting individuals and families to seek insurance coverage to reduce out-of-pocket healthcare costs. Favorable employer-sponsored dental benefit programs and government initiatives aimed at improving access to oral healthcare are further supporting market expansion. For instance, according to the Centers for Disease Control and Prevention (CDC) 2024 Oral Health Surveillance Report, nearly 21% of U.S. adults aged 20–64 years had at least one permanent tooth with untreated decay, based on nationally representative data from the NHANES. The continued prevalence of untreated dental conditions highlights the ongoing need for dental examinations, preventive services, and restorative treatments. This persistent demand for dental care, coupled with the financial burden associated with treatment, is expected to strengthen the value proposition of dental insurance and encourage greater adoption of coverage among individuals and families.
Limited coverage for certain dental procedures and high out-of-pocket expenses remain key restraints for the market. Many dental insurance plans impose annual coverage limits, waiting periods, deductibles, and exclusions for cosmetic treatments, orthodontics, and advanced restorative procedures. As a result, policyholders often continue to bear a significant portion of treatment costs, reducing the perceived value of insurance coverage.
In addition, reimbursement limitations and complex claims processes can discourage consumers from adopting insurance. In developing countries, low awareness of dental insurance and limited availability of comprehensive coverage further hinder market penetration. These challenges may hinder the adoption of dental insurance plans, particularly among low- and middle-income populations seeking affordable oral healthcare.
The rapid adoption of digital technologies and increasing focus on preventive oral healthcare are creating significant opportunities for the market. Insurance providers are increasingly implementing cloud-based platforms, artificial intelligence, digital claims management systems, and mobile applications to streamline policy administration, enhance customer experience, and improve operational efficiency. These advancements are enabling insurers to offer more personalized, accessible, and user-friendly services.
In addition, growing emphasis on preventive dentistry is encouraging insurers to expand coverage for routine checkups, cleanings, screenings, and early intervention services. Employers, healthcare organizations, and policymakers are increasingly recognizing the long-term cost benefits of preventive oral care, leading to broader insurance participation and coverage expansion. Furthermore, the large uninsured population and growing demand for affordable dental care present substantial opportunities for insurers to introduce innovative, flexible dental insurance products, thereby supporting market growth over the forecast period.
Analyst Perspective
The dental insurance market is increasingly shifting toward technology-enabled provider management and stronger healthcare access, rather than competing solely on premiums and coverage. Partnerships such as MetLife's collaboration with SKYGEN indicate that insurers are investing in digital provider credentialing and network management to reduce administrative friction and improve member access to in-network care. This trend is likely to intensify competition around provider-network breadth, digital service capabilities, claims efficiency, and overall member experience, enabling insurers to differentiate their offerings and strengthen customer retention.
Coverage Insights
The DPPO segment dominated the global market, accounting for around 65.0% of the market share in 2025. DPPOs often have a network of dentists who agree to provide services to plan members at a discounted rate. This can reduce consumers' out-of-pocket expenses compared to co-pays for services or medical bills. Many people choose plans that can help them save money on dental care. DPPO plans often include a billing schedule outlining the costs of specific procedures. This estimate is attractive to consumers because it helps them plan their dental expenses more effectively.
The dental health maintenance organizations segment is expected to register strong growth during the forecast period. DHMO plans often offer lower monthly premiums compared to other dental insurance options, such as dental indemnity plans. This affordability can make them an attractive choice for individuals and families seeking dental coverage while keeping costs manageable. DHMO plans emphasize preventive care services, including routine examinations, cleanings, and diagnostic procedures, helping improve oral health outcomes while reducing long-term treatment costs. This preventive-care focus, combined with lower premiums and predictable copayments, continues to support the adoption of DHMO plans among cost-conscious consumers.
Type Insights
By type, the market has been categorized into major, basic, and preventive segments. The preventive segment dominated the market in 2025 with over 40.0% of the global revenue. Dental prevention plans generally emphasize regular checkups, cleanings, and early intervention for dental problems. This approach encourages policyholders to maintain their oral health through regular visits to the dentist. In addition, premiums for preventive dental insurance plans are generally lower than those for comprehensive or primary dental insurance plans. This affordability makes them attractive to many individuals and families, thus increasing their market appeal.
The basic plan segment is expected to register strong growth during the forecast period. Basic plans are typically the most affordable options available to consumers. They offer essential products or services at lower prices, making them accessible to a broader range of customers, including those with limited budgets. Moreover, basic plans serve as entry-level options for customers new to a product or service category. The straightforward coverage structure and lower premium costs of basic plans make them particularly attractive to first-time policyholders and individuals seeking essential dental protection without comprehensive coverage.
Demographic Insights
By demographics, the market has been categorized into senior citizens, adults, and minors. The senior citizens segment dominated the market in 2025. Many countries, including the U.S., have aging populations due to increased life expectancy. This demographic trend contributes to the prominence of senior citizens in the dental insurance industry. Moreover, as individuals age, they are more likely to experience dental health issues, such as gum disease, tooth decay, and tooth loss. This leads to a greater demand for dental insurance to cover the costs of preventive care, restorative procedures, and dental treatments.
The adult segment is expected to register the fastest CAGR during the forecast period. Many countries have aging populations, with substantial numbers of adults aged 50 and older. As people age, they tend to require more dental care, including preventive, restorative, and potentially major dental procedures. This increased demand for dental services among older adults drives growth in the dental insurance sector.
Regional Insights
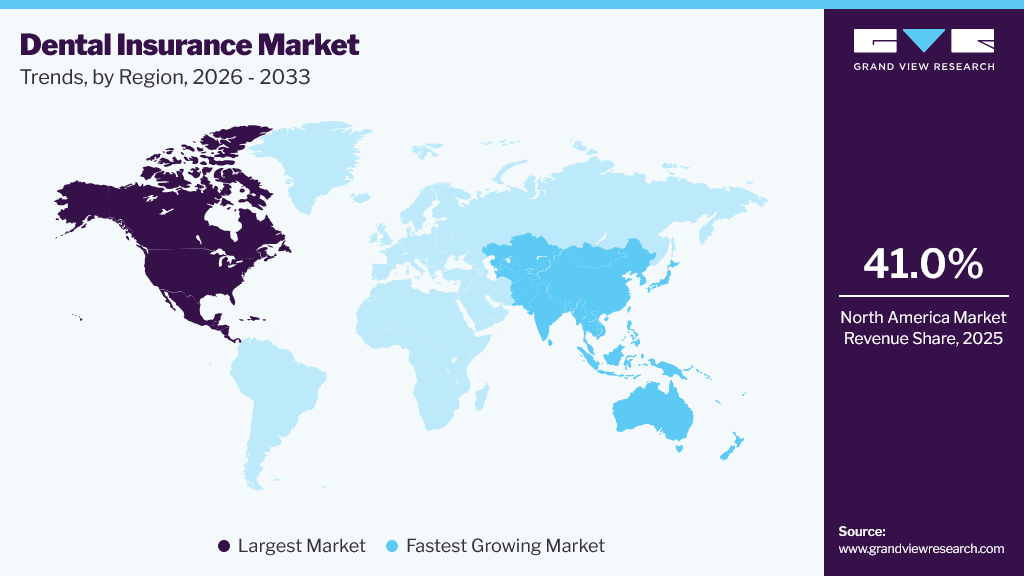
The dental insurance industry in North America dominated the global market, accounting for around 41.0% of revenue in 2025. North America is home to a large and relatively affluent population. The U.S. has a sizable middle-class population that can afford dental insurance premiums. This creates a substantial customer base for dental insurance providers. Moreover, in the U.S., many employers offer dental insurance as part of their employee benefits packages. This practice encourages a significant portion of the population to obtain dental insurance. In addition, high awareness of preventive oral healthcare and well-established dental care infrastructure further support the widespread adoption of dental insurance across the region.
 To learn more about this report, Download Free Sample Report
Asia Pacific Dental Insurance Market Trends
The dental insurance industry in Asia Pacific is expected to experience the fastest CAGR over the forecast period. There is a growing awareness regarding importance of dental health in the Asia-Pacific region. People are becoming more proactive about maintaining their oral health, which includes seeking regular dental check-ups and preventive care. This awareness drives the demand for dental insurance to cover these costs. In addition, improving healthcare infrastructure and expanding private health insurance penetration across emerging economies such as China, India, and Southeast Asian countries are supporting the adoption of dental insurance products.
Key Dental Insurance Company Insights
Key players in the dental insurance industry are adopting strategies such as partnerships, collaborations, acquisitions, product launches, digital platform enhancements, and provider network expansion to strengthen their market positions. Companies are also investing in digital tools and customer engagement capabilities to simplify enrollment, claims management, provider search, and access to dental benefits. Expansion of provider networks and investments in the broader oral healthcare ecosystem are further enabling insurers to improve service accessibility and strengthen customer retention.
Key Dental Insurance Companies:
The following are the leading companies in the dental insurance market:
-
Cigna Healthcare.
-
AXA
-
AFLAC INCORPORATED
-
Allianz
-
Aetna Inc.
-
Ameritas Mutual Holding Company
-
United HealthCare Services, Inc.
-
MetLife Services and Solutions, LLC
-
Delta Dental Plans Association.
-
HDFC ERGO General Insurance Company Limited.
-
United Concordia Companies, Inc.
Recent Developments
-
In June 2026, Delta Dental reported that its companies invested USD 131 million in oral healthcare initiatives during 2025, reaching more than 24 million people across all 50 states, Washington, D.C., and Puerto Rico. The investments included more than USD 66 million in direct oral care and nearly USD 23 million in dental workforce initiatives, with programs focused on expanding access to preventive and routine dental services. These initiatives strengthen Delta Dental's connection with underserved populations and support broader access to dental care, reinforcing its position as a leading provider in the U.S. dental insurance market.
-
In April 2025, MetLife partnered with SKYGEN to enhance the digital experience for dental providers and streamline provider credentialing. Through the collaboration, MetLife integrated SKYGEN's Dental Hub into its dental provider experience, enabling providers to manage credentialing and directory information through a centralized digital platform. The initiative is expected to reduce administrative burdens, improve provider network management, and expand access to quality dental care, thereby strengthening MetLife's service capabilities and competitive position in the dental insurance market
Dental Insurance Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 247.5 billion
Market size value in 2026
USD 259.1 billion
Revenue forecast in 2033
USD 480.0 billion
Growth rate
CAGR of 9.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Coverage, type, demographics, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; UK; Germany; France; Italy; Spain; Sweden; Norway; Denmark; India, Japan, China, Australia, South Korea, Thailand; Brazil; Mexico; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Cigna Healthcare; AXA; AFLAC INCORPORATED; Allianz; Aetna Inc.; Ameritas Mutual Holding Company; United HealthCare Services, Inc.; MetLife Services and Solutions, LLC; Delta Dental Plans Association.; HDFC ERGO General Insurance Company Limited.; United Concordia Companies, Inc.
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Dental Insurance Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest trends in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global dental insurance market report based on coverage, type, demographics, and region:
- Coverage Outlook (Revenue, USD Billion, 2021 - 2033)
- Dental Preferred Provider Organizations (DPPO)
- Dental Health Maintenance Organizations (DHMO)
- Dental Indemnity Plans
- Others
- Type Outlook (Revenue, USD Billion, 2021 - 2033)
- Major
- Basic
- Preventive
- Demographic Outlook (Revenue, USD Billion, 2021 - 2033)
- Senior Citizens
- Adults
- Minors
- Regional Outlook (Revenue, USD Billion, 2021 - 2033)
- North America
- U.S.
- Canada
- Europe
- UK
- Germany
- France
- Italy
- Spain
- Sweden
- Norway
- Denmark
- Asia Pacific
- Japan
- China
- India
- South Korea
- Australia
- Thailand
- Latin America
- Brazil
- Mexico
- Argentina
- Middle East & Africa
- South Africa
- Saudi Arabia
- UAE
- Kuwait
Frequently Asked Questions About This Report
The global dental insurance market size was valued at USD 247.5 billion in 2025 and is estimated at USD 259.1 billion for 2026.
The global dental insurance market is expected to grow at a CAGR of 9.2% from 2026 to 2033, reaching USD 480.0 billion by 2033.
North America dominated with approximately 41.0% revenue share in 2025.
Key players in the market include Cigna Healthcare, AXA, AFLAC INCORPORATED, Allianz, Aetna Inc., Ameritas Mutual Holding Company, United HealthCare Services, Inc., MetLife Services and Solutions, LLC, Delta Dental Plans Association, HDFC ERGO General Insurance Company Limited, United Concordia Companies, Inc, and others.
The DPPO segment led the market, holding the largest revenue share of around 65.0% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


