
- Home
- »
- Medical Devices
- »
-
Dental Obturation Materials Market Size, Share Report, 2035GVR Report cover

Dental Obturation Materials Market (2027 - 2035)
Size, Share & Trends Analysis Report By Product Type, By Obturation Technique, By Treatment Type, By Tooth Type, By End Use, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2026
$448.9MMarket Estimate, 2027
$470.1MMarket Forecast, 2035
$675.2MCAGR, 2027–2035
4.6%Dental Obturation Materials Market Summary
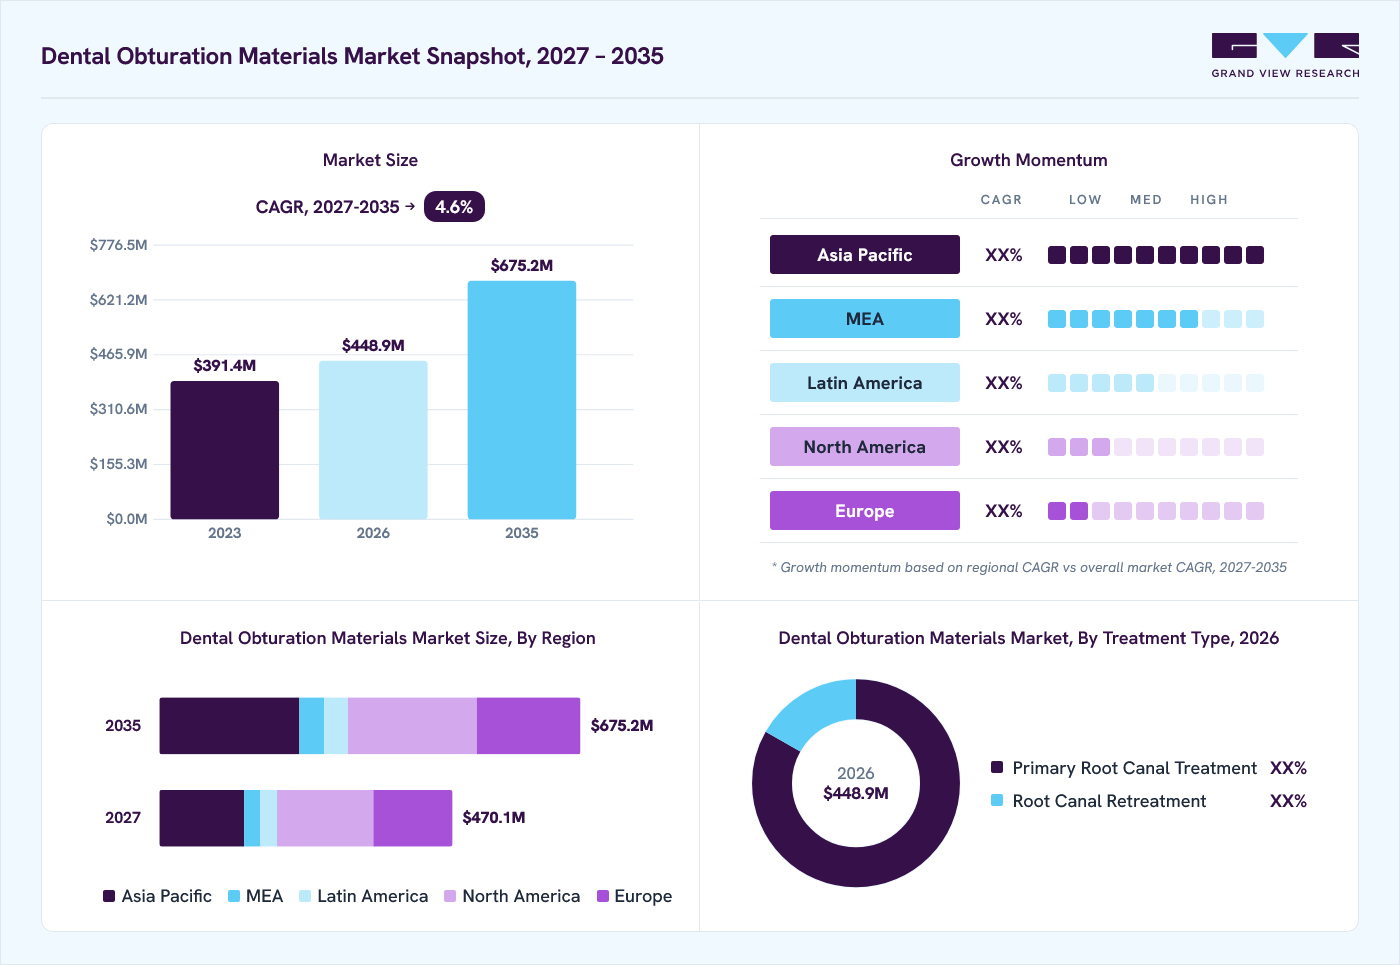
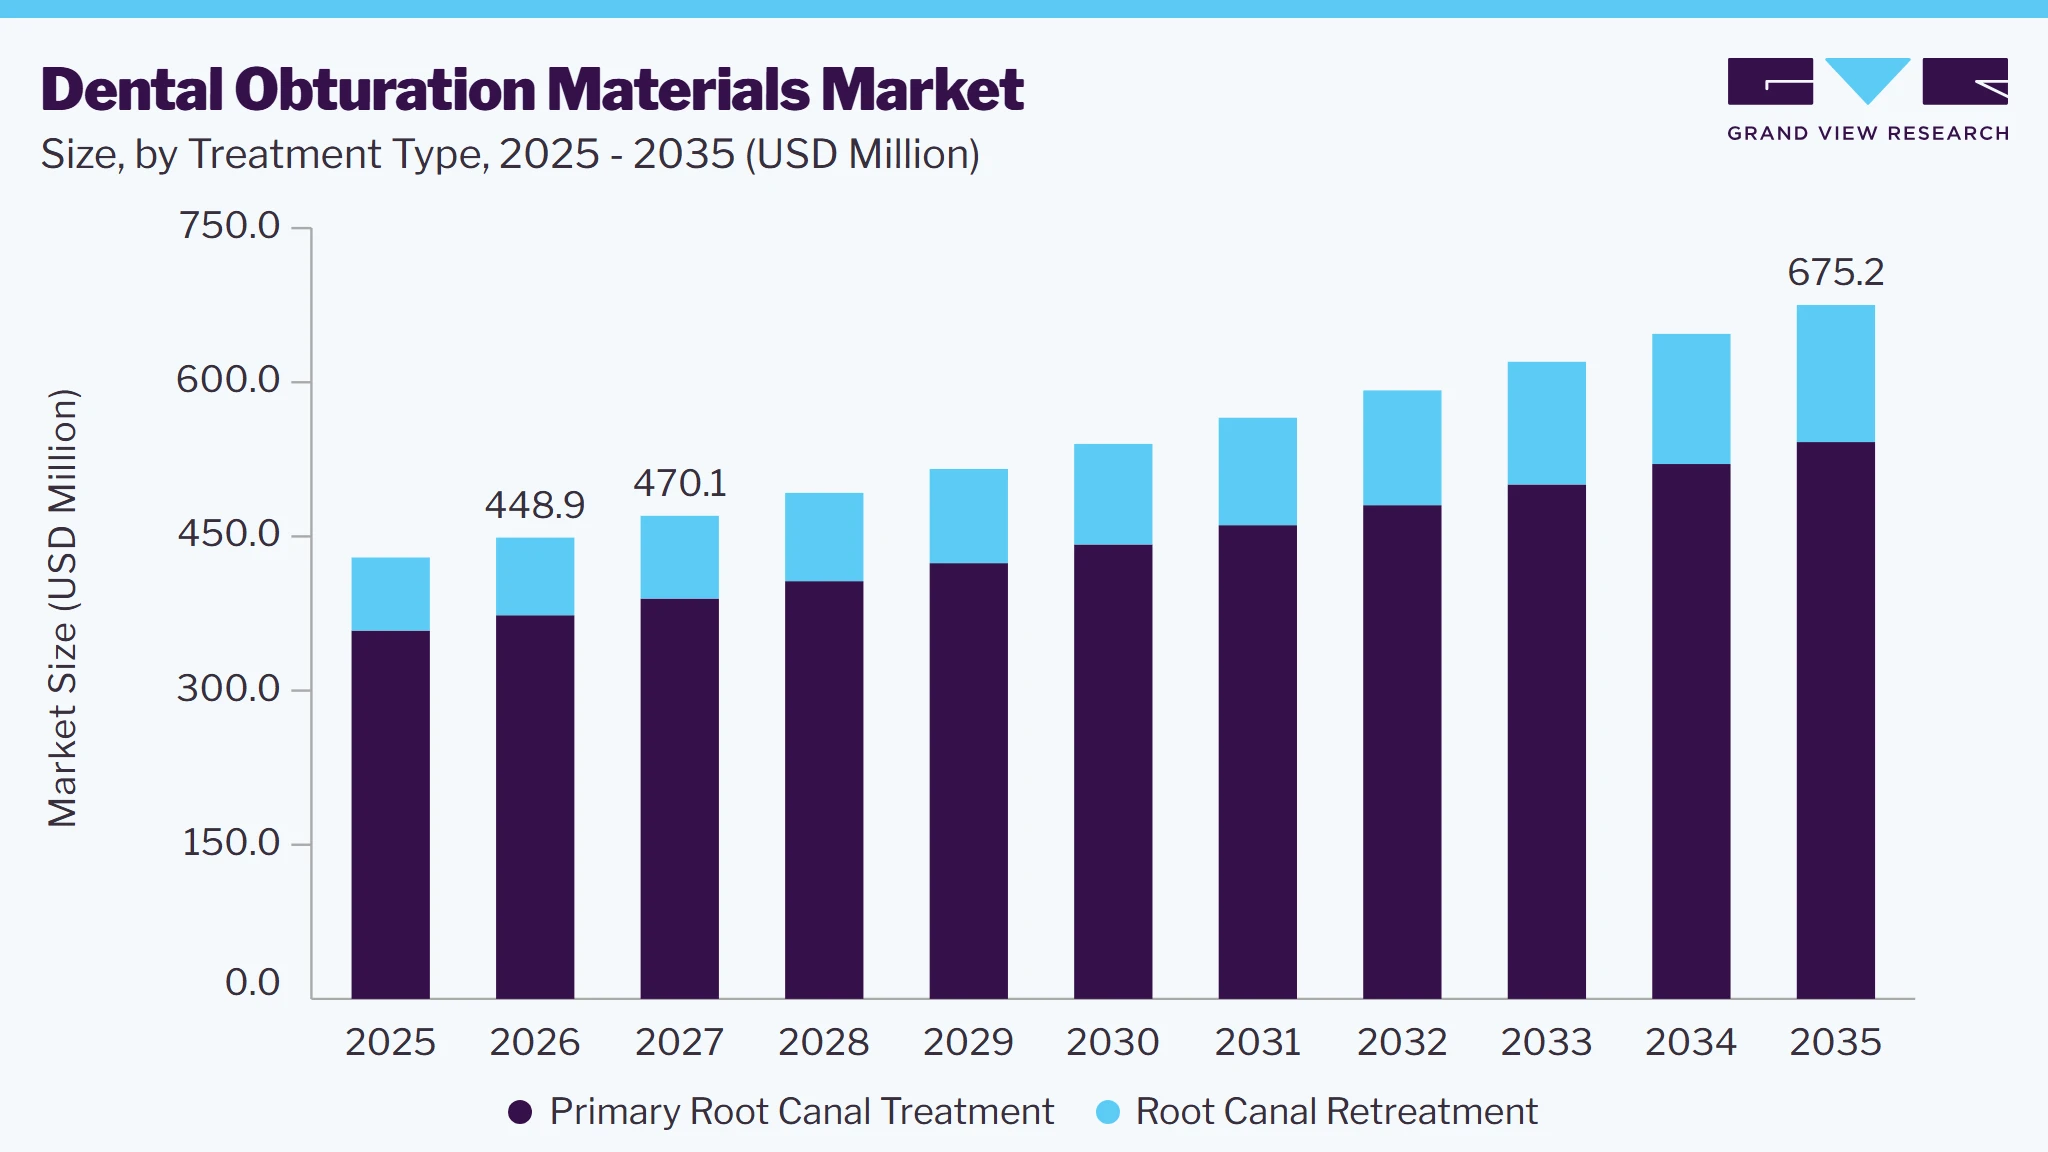
The global dental obturation materials market size was valued at USD 448.9 million in 2026 and is projected to grow from USD 470.1 million in 2027 to USD 675.2 million by 2035, at a CAGR of 4.6% from 2027 to 2035. North America dominated the market, accounting for a revenue share of 33.1% in 2026. The growth of the global dental obturation materials market is driven by the increasing global burden of untreated dental caries and pulpal diseases, rising demand for tooth-preserving endodontic treatments, and expanding access to specialized dental care.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product type: Root canal sealers segment led the market with the largest revenue share of 43.4% in 2026.
- By obturation technique: Carrier-based obturation segment led the market with the largest revenue share of 32.2% in 2026.
- By treatment type: Primary root canal treatment segment led the market with the largest revenue share of 83.2% in 2026.
- By tooth type: Molars segment led the market with the largest revenue share of 69.7% in 2026.
- By end use: Dental clinics segment led the market with the largest revenue share of 78.0% in 2026.
- By distribution channel: Dental distributor sales segment led the market with the largest revenue share of 77.5% in 2026.
Regional Highlights
- Largest regional market: North America (33.1% revenue share, 2026)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market Size in 2026: USD 448.9 million
- Estimated market size in 2027: USD 470.1 million
- Projected market size by 2035: USD 675.2 million
- CAGR (2027-2035): 4.6%
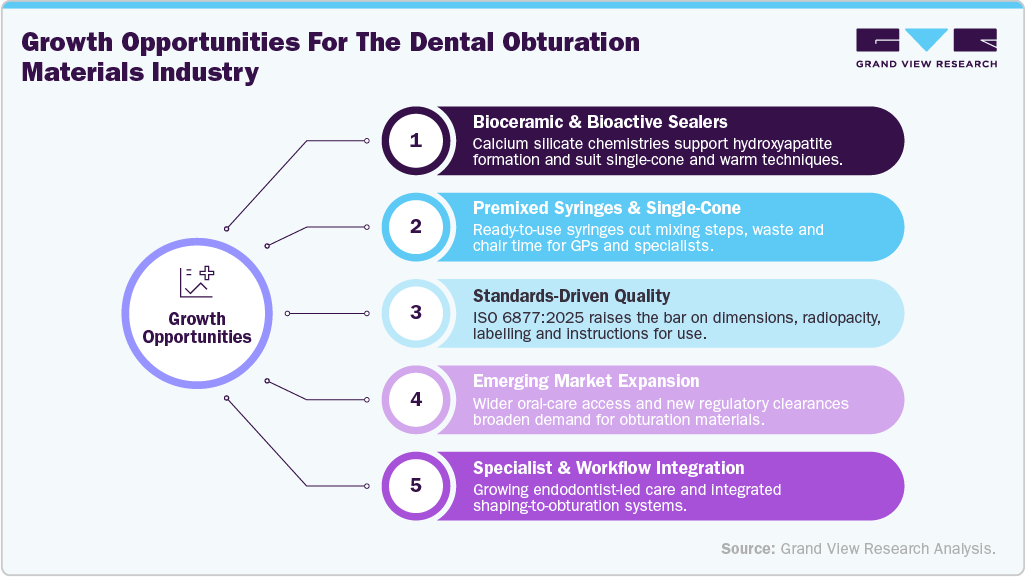
Prism AI by Grand View Research Free to tryAsk a question about the dental obturation materials marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Furthermore, continuous advancements in bioceramic and calcium silicate-based sealers, increasing adoption of bioactive obturation materials. In addition, the growth is supported by continuous product innovation that targets simpler workflows, lower material waste, and better healing biology. Manuf acturers are replacing mix-and-apply sealers with ready-to-use syringes and expanding bioceramic portfolios that work with single-cone, cold lateral, warm vertical, and carrier-based techniques. For instance, in September 2025, Dentsply Sirona announced two new obturation sealers for U.S. availability in October 2025: ProRoot Bio Sealer, a calcium silicate-based bioceramic sealer that contains no bismuth oxide (so it does not stain) and offers a flexible tip that reduces material waste per tip by up to 49%, and AH Plus Ribbon, a next-generation resin sealer built on the company’s 30-year resin technology with improved paste consistency and adhesion to gutta-percha.
 To learn more about this report, Download Free Sample Report
“Every dentist has an individual approach to endodontic treatment,” explains Arjan de Roy, Group Vice President Essential Dental Solutions at Dentsply Sirona. “With AH Plus Ribbon and ProRoot Bio Sealer, we offer a choice that matches the personal preferences of each user. Both endodontic sealers meet the highest standards and are based on clinically proven technologies. By providing the “Best of Both Worlds” with regards to both sealer technologies, we’re convinced that each sealer will give practitioners the confidence they need to successfully perform endodontic treatments.”
“ProRoot Bio Sealer has excellent viscosity allowing me to control placement. It flows into microanatomy and canal irregularities when present,” says David J. Landwehr, DDS, MS, Capital Endodontics, Madison, Wisconsin. “When a bioceramic sealer is the best alternative, ProRoot Bio Sealer will be my choice.”
Growing preference for specialist endodontic care and tooth preservation:
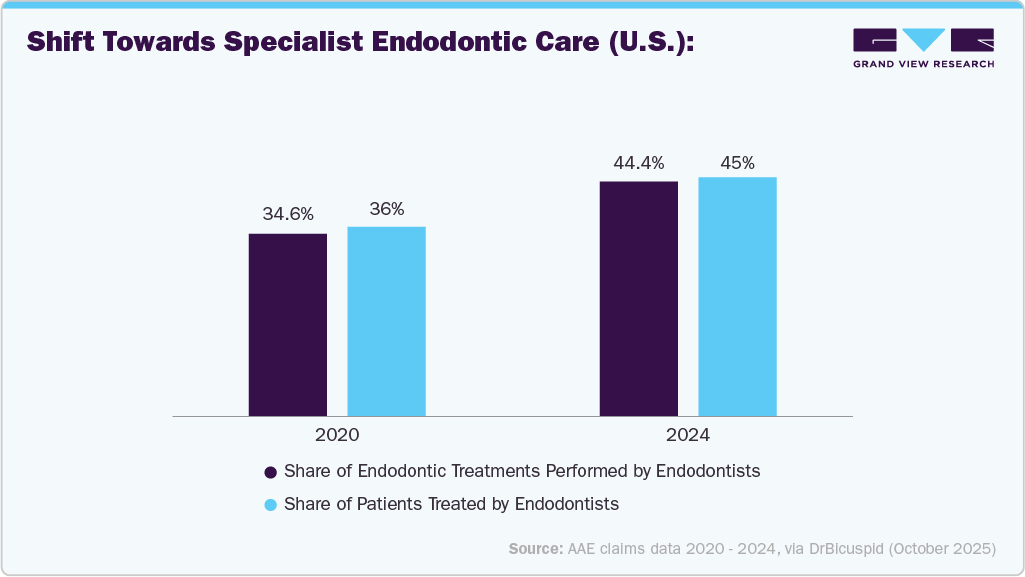
Patients are choosing to save natural teeth, and more root canal care is moving to specialists who use advanced obturation materials and techniques. Insurance claims data from 2020 to 2024, released by the American Association of Endodontists (AAE) in October 2025, show that endodontists’ share of endodontic treatments rose from 34.6% to 44.4%, and the share of patients treated by endodontists rose from 36% to 45%. The accompanying 2025 AAE survey of U.S. adults found that 94% value keeping their natural teeth as long as possible, 45% have had a root canal, and 71% of those patients are glad they chose it over extraction.
 To learn more about this report, Download Free Sample Report
 To learn more about this report, Download Free Sample Report
Market Dynamics
The dental obturation materials market is experiencing steady growth due to the increasing burden of dental caries, rising demand for endodontic treatments, and growing preference for tooth-preserving procedures. Dental obturation materials, including gutta-percha points and root canal sealers, play an essential role in filling and sealing the root canal system following cleaning, shaping, and disinfection. These materials help prevent bacterial reinfection, support periapical healing, and contribute to the long-term success of root canal treatment. The market is further supported by advancements in bioceramic and calcium silicate-based sealers, improved material properties, and the adoption of contemporary obturation techniques.
The increasing prevalence of untreated dental caries and associated pulpal complications is generating demand for endodontic procedures, thereby supporting the consumption of dental obturation materials. Advanced dental caries can cause irreversible pulpitis and periapical infections, requiring root canal treatment to preserve the affected tooth. According to the Global Burden of Disease Study 2023, published in August 2026, the global number of untreated permanent-tooth caries cases increased from 2.20 billion in 2019 to 2.26 billion in 2023. This growing disease burden is expected to increase the need for restorative and endodontic interventions, supporting demand for gutta-percha points, root canal sealers, and other obturation materials. The increasing requirement for effective management of pulpal and periapical conditions is expected to sustain market demand during the forecast period.
The high out-of-pocket expenditure associated with dental procedures and limited insurance coverage restrict access to endodontic treatment, particularly in low- and middle-income countries. Root canal procedures require diagnostic imaging, specialized instruments, clinical expertise, and multiple treatment materials, increasing the overall cost of care. In price-sensitive markets, patients may postpone treatment or opt for tooth extraction instead of undergoing restorative procedures, reducing the potential consumption of obturation materials. In March 2025, according to the World Health Organization, oral diseases affect nearly 3.7 billion people globally, while dental treatment remains expensive and is generally excluded from national universal health coverage benefit packages. These affordability constraints and disparities in dental healthcare access are expected to limit the adoption of endodontic procedures and associated obturation products in several regions.
The increasing research focus on bioactive and biocompatible dental materials is creating opportunities for manufacturers to develop advanced root canal sealers with improved biological properties and sealing performance. Calcium silicate-based and bioceramic formulations are gaining clinical attention due to their calcium-ion release, bioactivity, and favorable interaction with periapical tissues. Further research into bioactive glass, calcium phosphate-based materials, and regenerative endodontic formulations could support the development of next-generation products designed to improve mineralization, tissue compatibility, and periapical healing. Manufacturers can capitalize on this opportunity by developing formulations with improved flow characteristics, dimensional stability, adhesion, and compatibility with different obturation techniques. Continued clinical validation and product innovation in this category are expected to create opportunities for portfolio differentiation and premium product development during the forecast period.
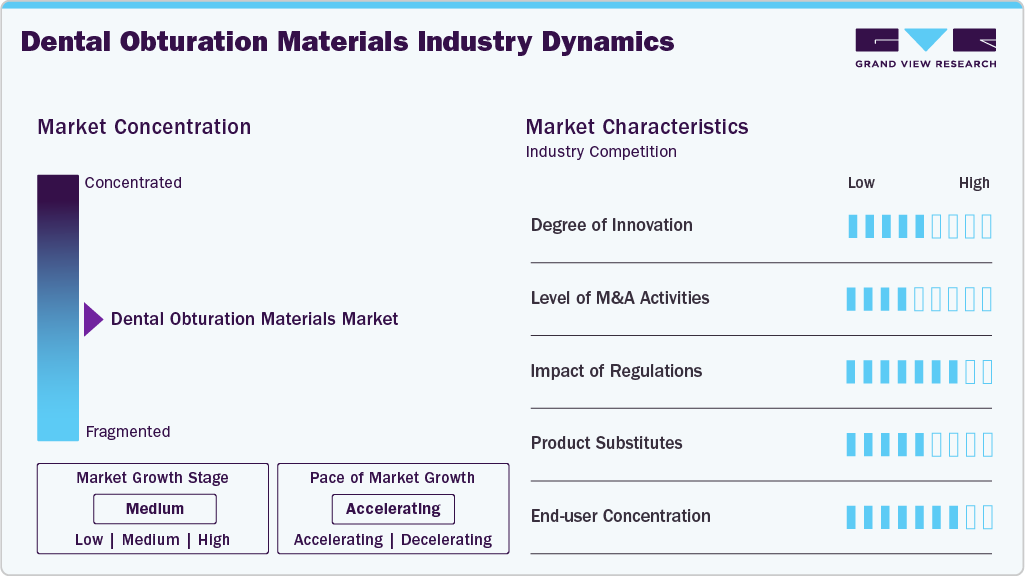
Market Concentration & Characteristics
The market is characterized by continuous innovation in material composition, biological properties, sealing performance, and compatibility with contemporary endodontic techniques. Manufacturers are developing advanced calcium silicate-based and bioceramic sealers with properties such as bioactivity, calcium-ion release, moisture tolerance, and favorable tissue interaction. Innovations also include premixed injectable sealers, improved flow characteristics, dimensional stability, and formulations designed for different obturation techniques, including single-cone and warm vertical compaction.
The market is characterized by strategic portfolio expansion and consolidation activities among dental product manufacturers seeking to strengthen their endodontic product offerings. Companies are pursuing acquisitions, partnerships, and distribution agreements to expand their presence in root canal sealers, gutta-percha products, endodontic instruments, and related consumables. These activities enable manufacturers to broaden their product portfolios, access established distribution networks, and strengthen their presence across general dentistry and specialized endodontic practices.
 To learn more about this report, Download Free Sample Report
Dental obturation materials are subject to regulatory requirements governing product quality, material characteristics, safety, labelling, and manufacturing consistency. In December 2025, in the U.S., the FDA recognized the fourth edition of ISO 6877:2025, Dentistry - Endodontic obturating materials, under Recognition Number 4-351. The standard specifies requirements related to dimensions, radiopacity, colour coding, melt mass-flow rate, marking, labelling, packaging, and instructions for use. The FDA identifies root canal filling resin under Class II and gutta-percha under Class I device classifications. Furthermore, the FDA will accept declarations of conformity to the previous ISO 6877:2021 edition until December 19, 2027, after which the earlier edition will no longer be accepted for premarket submissions. These regulatory requirements influence product development, quality assurance, testing, and commercialization strategies among manufacturers.
The market faces competition from alternative root canal filling materials and treatment approaches, including Resilon-based systems, alternative polymer-based filling materials, and different sealer formulations. Gutta-percha remains the established core-filling material in conventional root canal procedures, generally used in combination with root canal sealers. However, advancements in bioceramic sealers, calcium silicate-based formulations, and other bioactive materials are creating alternatives to conventional zinc oxide-eugenol and epoxy resin-based sealers.
Demand for dental obturation materials is primarily concentrated among dental clinics, endodontic specialty practices, multispecialty dental hospitals, and academic dental institutions. General dental clinics represent an important consumption base because root canal procedures are routinely performed to manage pulpal infections and preserve natural teeth. Endodontic specialty clinics also account for substantial product utilization due to their focus on primary root canal treatments, complex canal anatomy, and retreatment procedures.
Analyst Perspective
The market is positioned for sustained growth, driven by the rising prevalence of dental caries and pulpal diseases, increasing demand for tooth-preserving root canal treatments, and growing adoption of advanced endodontic procedures. Technological advancements in bioceramic and calcium silicate-based sealers, thermoplastic gutta-percha systems, and bioactive obturation formulations are creating opportunities for product innovation. In addition, expanding dental care infrastructure and the growing presence of specialty endodontic clinics are supporting market development, particularly in emerging economies. Companies offering biocompatible, clinically effective, and technique-compatible materials, supported by product innovation, regulatory compliance, strong distribution networks, and competitive pricing, are expected to strengthen their market positions.
Product Type Insights
The root canal sealers segment dominated the dental obturation materials market, accounting for 43.4% of the market in 2026. This dominance is supported by the widespread use of sealers in every obturation technique to fill the space between the filling material and the canal walls, the shift toward premixed bioceramic sealers with better sealing, bioactivity, and ease of delivery, and the need for hydraulic-setting materials that tolerate moisture. For instance, in June 2025, the U.S. FDA cleared Enpuno's Injectable Root Canal Bioceramic Sealer, a premixed, ready-to-use hydraulic cement paste made mainly of calcium silicates, zirconium dioxide, and calcium hydroxide, which is radiopaque, does not shrink while setting, and is supplied in preloaded syringes with disposable intracanal tips. Such clearances are expected to widen the choice of bioceramic sealers and sustain the leading position of this segment.
The integrated / hybrid obturation materials segment in the dental obturation materials market is expected to grow at the fastest rate during the forecast period due to the growing preference for ready-to-use materials that combine filling and sealing functions in a single bioactive material, which simplifies procedures and reduces voids in the obturation. For instance, in August 2025, the U.S. FDA cleared Mediclus's One-Fil Putty Injectable, a premixed, ready-to-use bioceramic root canal filling material delivered as a flowable paste in a syringe, which hardens through hydration in the presence of moisture and is used for permanent root canal filling and pulp capping. Such premixed bioceramic filling materials are expected to accelerate the adoption of integrated obturation solutions.
Obturation Technique Insights
The carrier-based obturation segment dominated the dental obturation materials market, accounting for 32.2% of the market in 2026. This dominance is supported by growing preference for warm, three-dimensional obturation that delivers predictable results with limited technique sensitivity, together with the availability of heat-compatible bioceramic sealers for use with carrier-based systems. For instance, in April 2026, Kerr introduced ZenSeal Pro, a calcium silicate-based bioceramic sealer in a 1.5 g syringe with flexible, trimmable ZenSave Tips, with heat-compatibility testing that supports use under warm vertical obturation and compatibility with carrier-based techniques. Such heat-compatible, all-in-one sealers are expected to support wider use of carrier-based obturation.
The cold single-cone technique in the dental obturation materials market is expected to grow at the fastest rate during the forecast period due to the widespread preference for simple, time-efficient obturation that uses a single master cone matched to the canal preparation together with a hydraulic bioceramic sealer, which reduces chair time and technique sensitivity. For instance, in April 2025, Henry Schein UK expanded its endodontic portfolio with the EdgeBioCeramic line, including the EdgeBioCeramic Sealer, which is mainly used for cold obturation, is made from a premix of calcium silicate and calcium phosphate bioceramics, and sets by reacting with the tooth's natural moisture. Such moisture-tolerant sealers are expected to keep the cold single-cone technique the preferred choice among clinicians.
Treatment Type Insights
The primary root canal treatment segment dominated the dental obturation materials market, accounting for 83.2% of the market in 2026. This dominance is supported by the large volume of first-time treatments for pulpal disease that is detected during routine visits, the rising awareness of tooth preservation, and the importance of regular check-ups in identifying disease early. For instance, according to the U.S. Centers for Disease Control and Prevention's National Center for Health Statistics, 66.7% of U.S. adults aged 18 years and older had a dental exam or cleaning in the past year, based on the 2025 National Health Interview Survey early release. Such regular dental contact is expected to keep identifying pulpal disease early and sustain primary root canal treatment volumes.
The root canal retreatment segment in the dental obturation materials market is expected to grow at the fastest rate during the forecast period due to growing number of previously treated teeth with persistent or recurrent disease, the need to remove existing fillings and bioceramic materials before re-obturation, and the referral of complex cases to specialists. The increasing adoption of advanced endodontic techniques, including ultrasonic instrumentation, rotary retreatment systems, and magnification-assisted procedures, is improving the effectiveness of existing filling material removal and canal re-preparation.
Tooth Type Insights
The molars segment dominated the dental obturation materials market, accounting for 69.7% of the market in 2026 and is expected to grow at the fastest rate during the forecast period. This dominance is supported by the complex anatomy of molars, with multiple canals, isthmuses, and curvatures, together with their high exposure to decay and large restorations and the need for three-dimensional visualization to achieve complete obturation. For instance, in September 2026, DEXIS announced DTX Studio Clinic v4.10, which adds an Endodontic Module for three-dimensional visualization of root canals when paired with CBCT. Such tools are expected to improve canal detection and fill quality in molars and support demand for obturation materials.
The premolars segment in the dental obturation materials market is expected to grow at a significant rate during the forecast period due to increasing retention of natural teeth in older adults, which keeps more premolars in function and raises the number of teeth that need endodontic treatment rather than extraction. For instance, in March 2025, the Institute of German Dentists (IDZ), together with the KZBV and BZÄK, presented the Sixth German Oral Health Study (DMS 6), which found that only 5% of people aged 65-74 are toothless, an 80% decline in this age group, with retained teeth increasing. Such tooth-preserving trends are expected to support steady demand for obturation materials in premolars.
End Use Insights
The dental clinics segment dominated the dental obturation materials market, accounting for 78.0% of the market in 2026. This dominance is supported by the high concentration of endodontic procedures in independent and group practices, and the growth of DSO-affiliated clinics that standardize material purchasing and treatment protocols. For instance, according to the American Dental Association Health Policy Institute's U.S. Dentist Workforce report published in September 2025, more than one in four dentists up to 10 years out of dental school were affiliated with a dental service organization in 2024. As newer dentists increasingly join group-managed clinics, dental clinics are expected to remain the main users of obturation materials.
The dental academic and teaching institutions segment in the dental obturation materials market is expected to grow at the fastest rate during the forecast period due to the increasing integration of endodontic training into dental education curricula, rising enrollment in dental programs, and growing emphasis on practical training in root canal procedures. Dental colleges and teaching institutions are expanding preclinical laboratory facilities and simulation-based training programs, increasing the consumption of gutta-percha points, sealers, and thermoplastic obturation materials for hands-on practice, clinical demonstrations, and research activities.
Distribution Channel Insights
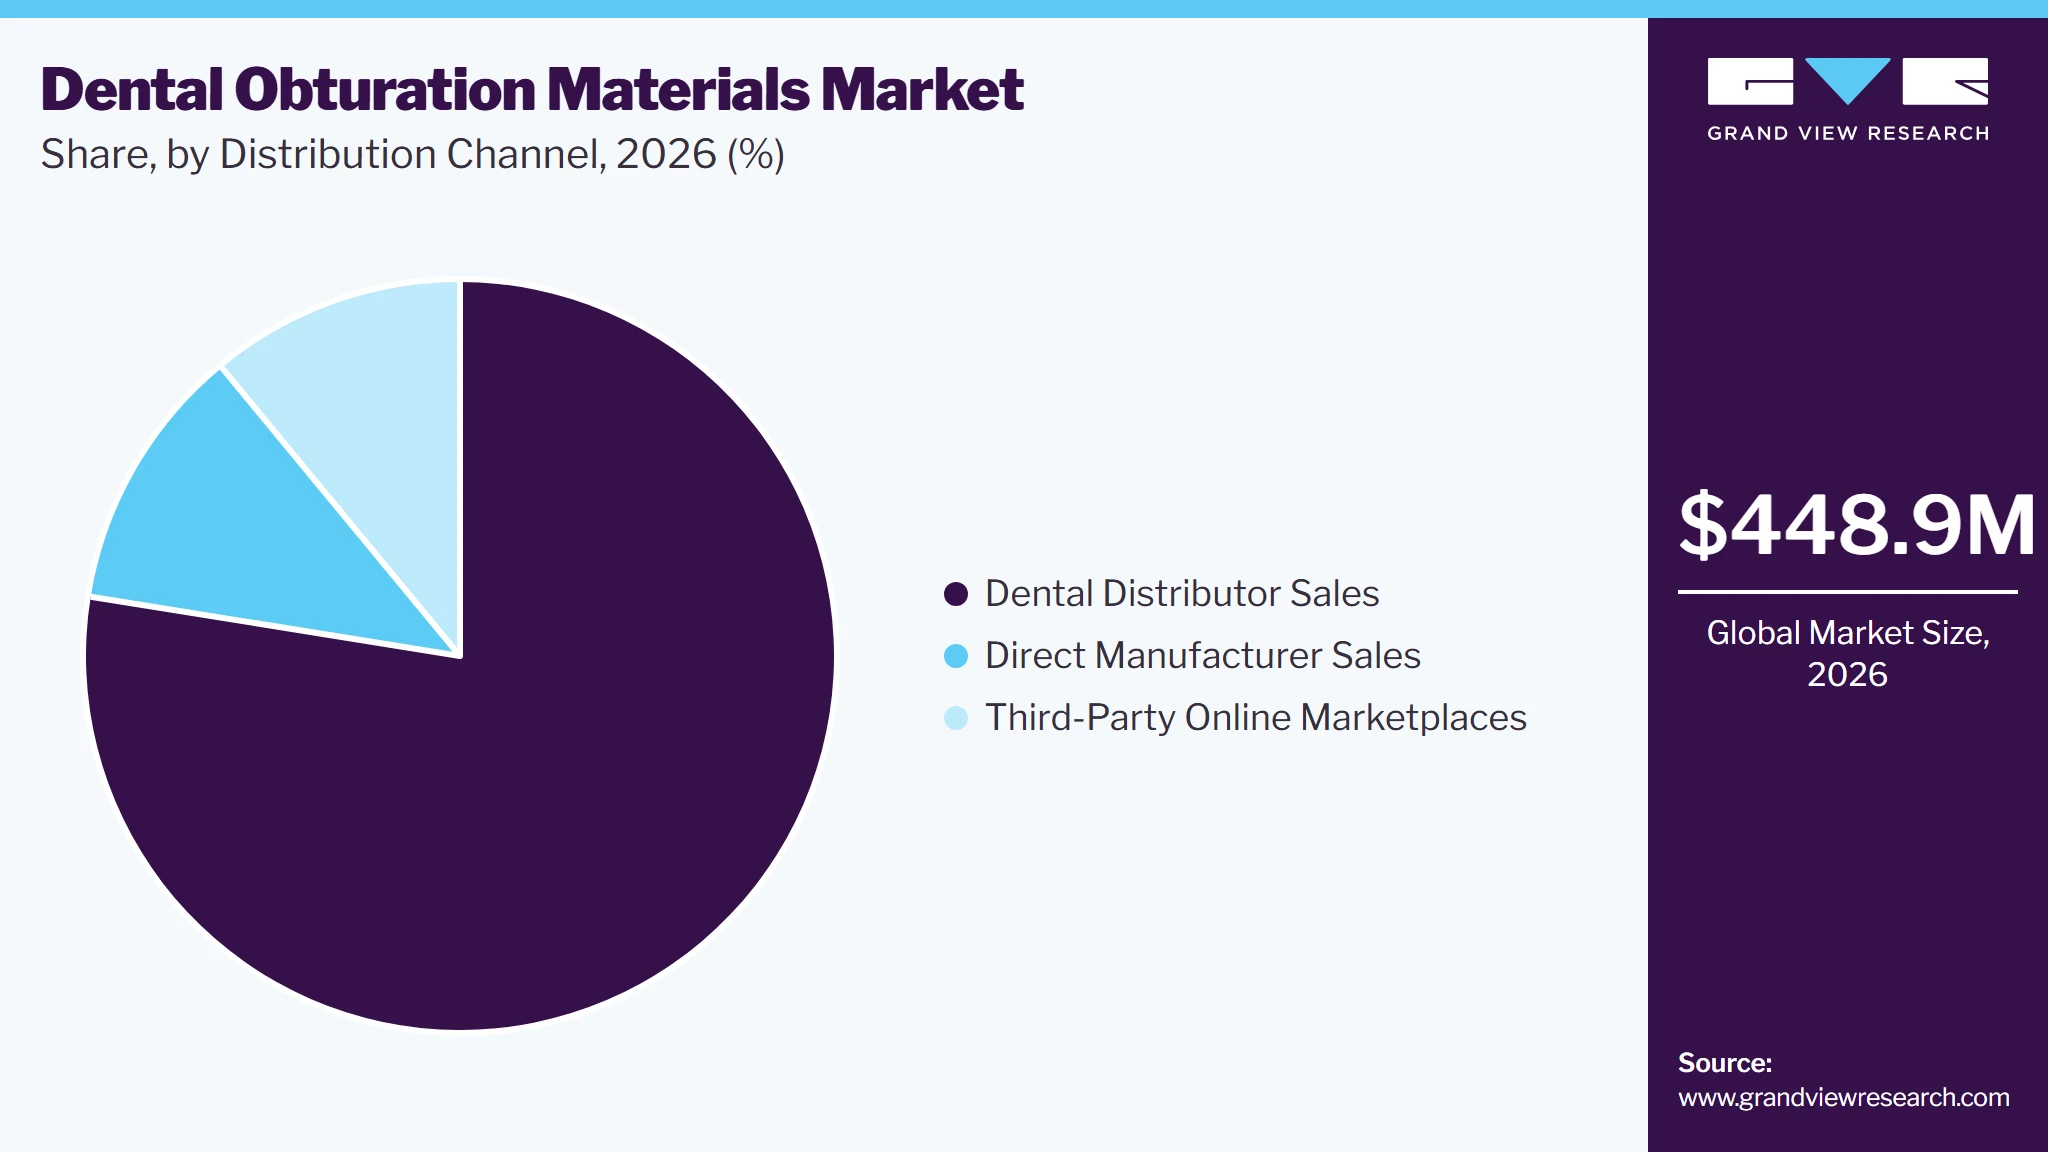
The dental distributor sales segment dominated the dental obturation materials market, accounting for 77.5% in 2026. This dominance is driven by the one-stop supply of endodontic materials alongside equipment and consumables, the technical support and product training that distributors provide for new bioceramic products, and long-standing relationships with dental practices. For instance, in April 2025, Patient Square Capital completed its acquisition of Patterson Companies, a leading supplier of products and services to the dental and animal health markets in North America and the U.K. Such investment in distribution scale is expected to keep distributors the primary route to market for obturation materials.
 To learn more about this report, Download Free Sample Report
The third-party online marketplaces segment of the dental obturation materials market is expected to grow at the fastest rate during the forecast period. Growth is driven by the convenience of online reordering, price transparency, a wider product selection, and the rising digitization of dental practice procurement. For instance, in the first quarter of 2026, Henry Schein reported that more than 80% of its U.S. dental e-commerce sales were running through its consolidated HenrySchein.com platform, which standardizes ordering for dental merchandise, equipment, and specialty products. The shift toward unified digital storefronts is expected to make online purchasing of endodontic consumables easier for dental practices.
Regional Insights
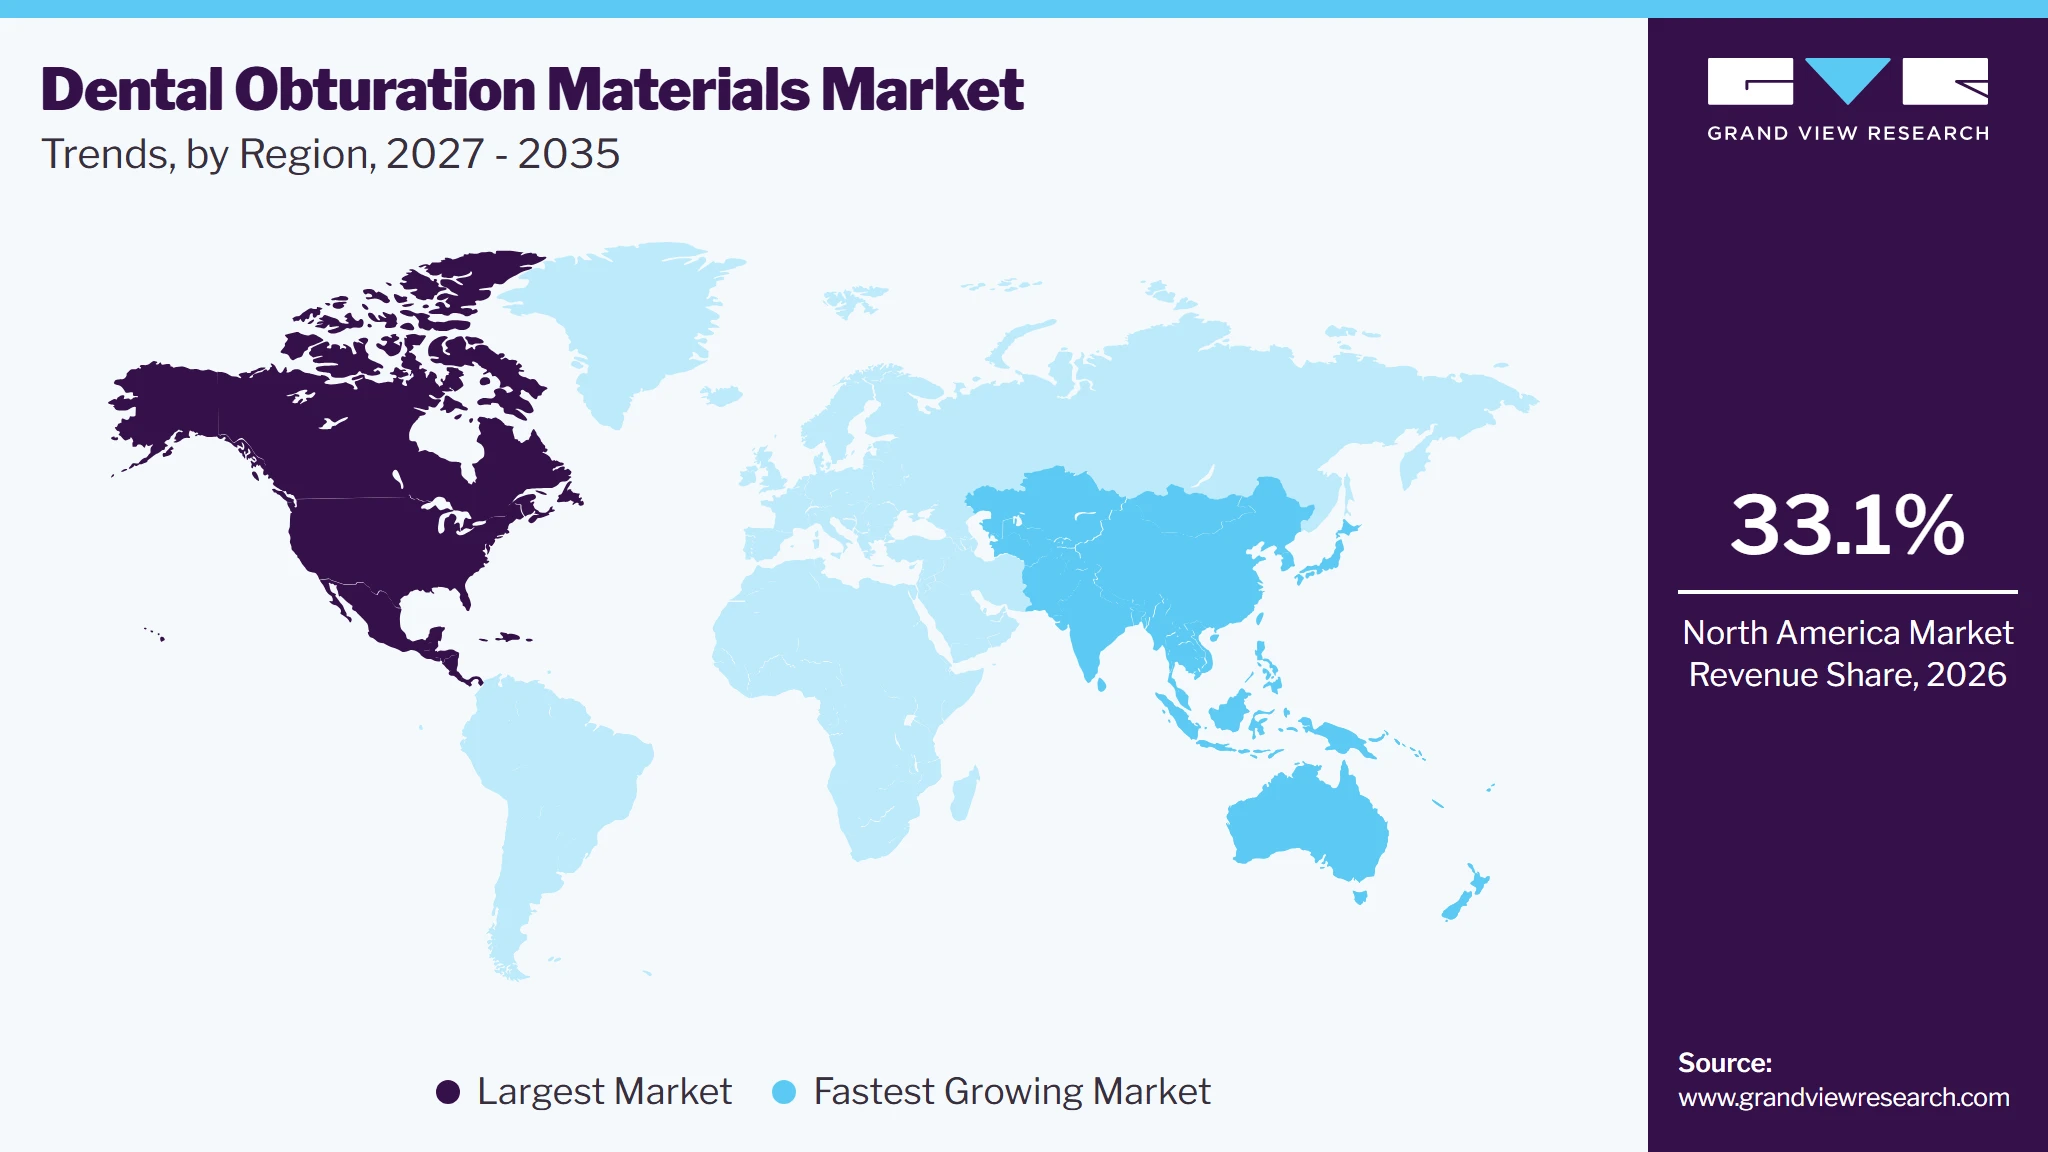
North America dominated the market, accounting for a revenue share of 33.1% in 2026. The North America dental obturation materials market is supported by the region's established dental healthcare infrastructure, widespread availability of endodontic specialists, increasing preference for natural tooth preservation, and access to advanced root canal treatment technologies. According to the American Association of Endodontists, the share of endodontic treatments performed by endodontists in the U.S. increased from 34.6% in 2020 to 44.4% in 2024, representing a 9.8% increase. Furthermore, Canada's Canadian Dental Care Plan (CDCP) included endodontic services, such as root canal treatments, within its covered benefits. During its first benefit period, approximately 3.6 million individuals enrolled, while more than 2 million members accessed oral healthcare services. These developments are supporting access to endodontic treatment and creating demand opportunities for dental obturation materials across North America.
 To learn more about this report, Download Free Sample Report
U.S. Dental Obturation Materials Market Trends
The U.S. dental obturation materials market is supported by the country's established dental healthcare infrastructure, increasing utilization of specialized endodontic services, and continued demand for natural tooth preservation. The availability of a large dental workforce, including general practitioners and endodontists, supports the delivery of root canal procedures across private dental practices, specialty clinics, and multispecialty dental groups. For instance, according to the American Dental Association (ADA) Health Policy Institute, the number of professionally active dentists in the U.S. reached 205,088 in 2025, compared with 202,485 in 2024. This established provider base support demand for gutta-percha points, root canal sealers, and advanced bioceramic obturation materials in the U.S. market
Europe Dental Obturation Materials Market Trends
The Europe dental obturation materials market is experiencing steady growth due to the region's established dental healthcare infrastructure, increasing availability of endodontic specialists, and rising demand for tooth-preserving restorative treatments across Germany, France, Italy, Spain, and the UK. The region benefits from a well-developed dental workforce, increasing access to specialized dental services, and the availability of advanced root canal treatment materials, including gutta-percha points and bioceramic-based sealers. According to Eurostat, the number of practising dentists increased between 2014 and 2024 in 23 out of 25 European countries with available data, indicating an expansion of the region's dental workforce. This established clinical workforce, combined with growing availability of endodontic services and continued advancements in root canal filling materials, is supporting demand for dental obturation products across Europe
UK Dental Obturation Materials Market Trends
The UK dental obturation materials market is witnessing steady growth due to the persistent burden of untreated dental caries, which leads to pulpal disease and the need for root canal treatment. For instance, in February 2025, the UK Government's oral health survey of 5-year-old schoolchildren in England reported that 22.4% had experience of obvious dentinal decay, down from 23.7% in 2022, and that 26.9% had experience of any visible decay, with disparities at regional and local authority levels. This continuing caries burden is expected to sustain demand for endodontic care and obturation materials in the country.
Asia Pacific Dental Obturation Materials Market Trends
The Asia Pacific dental obturation materials market is expected to witness strong growth due to expansion into emerging markets with high unmet dental treatment needs, including Tier 2 and Tier 3 cities where dental infrastructure is developing rapidly. For instance, in August 2026, Envista launched Kerr Consumables in India, covering restorative and endodontic dentistry, calling India a strategic growth market and planning to deepen its presence in Tier 2 and Tier 3 cities through clinician engagement and a multi-city roadshow with international experts. Such market-entry initiatives by global manufacturers are expected to improve access to modern obturation materials across the region.
China Dental Obturation Materials Market Trends
The China dental obturation materials market is witnessing strong growth, supported by the increasing awareness of oral health and preventive dental care, which raises early caries intervention and tooth-preservation treatments. For instance, in December 2025, China's National Health Commission and 12 other departments issued the Children and Adolescents' Five-Health Promotion Action Plan (2026-2030), which targets effective intervention in caries for 5-year-olds and 12-year-olds by 2030 through oral health education, fluoride application, pit-and-fissure sealing, and an annual oral check for students. Such programs are expected to increase early detection of dental disease and demand for endodontic treatment materials.
Latin America Dental Obturation Materials Market Trends
The Latin America dental obturation materials market is expected to witness strong growth, driven by the increasing volume of root canal treatments as public oral health programs widen access to dental care. For instance, in September 2025, Brazil's Ministry of Health reported that investment in the "Smiling Brazil" national oral health program rose from R$1.5 billion (~USD 273.3 Mn) to R$4.3 billion (~283.4 Mn)between 2022 and 2024, with about 33,000 oral health teams in operation and 800 new mobile dental units planned. Such public investment is expected to bring more patients into treatment and support demand for obturation materials across the region.
MEA Dental Obturation Materials Market Trends
The MEA dental obturation materials market is expected to witness strong growth due to the expansion of dental clinics and specialized endodontic treatment facilities, particularly across Gulf countries. For instance, in August 2026, Hamad Medical Corporation expanded dental services at Al Khor Hospital and Aisha Bint Hamad Al Attiyah Hospital in Qatar, bringing its dental treatment clinics to eight, with services including endodontics, and recruited eight specialist dentists across disciplines. Such expansion of specialist dental facilities is expected to increase the use of endodontic and obturation materials in the region.
Dr. Muneera Jassim Al Mohannadi, chief executive officer and medical director of Al Khor Hospital, said: “The expansion of dental services in the Northern Region reflects HMC’s commitment to providing integrated, high-quality specialised healthcare services across Qatar. It also demonstrates our continued focus on developing services in line with the evolving needs of the communities we serve, improving access to specialist care, and enhancing the overall patient experience.”
Key Dental Obturation Materials Company Insights
Some of the key companies in the dental obturation materials market include Dentsply Sirona, Peter Brasseler Holdings, LLC, Septodont Holding, COLTENE Group, Ultradent Products Inc. (Mitsui Chemicals, Inc.), Ivoclar, VERICOM, DiaDent, EdgeEndo, Kerr Corporation (Envista), and FKG Dentaire Sàrl. Organizations are focusing on increasing customer base to gain a competitive edge in the industry. Therefore, key players are taking several strategic initiatives, such as product launch, and partnerships with other major companies.
Key Dental Obturation Materials Companies:
The following key companies have been profiled for this study on the dental obturation materials market.
-
Dentsply Sirona
-
Peter Brasseler Holdings, LLC
-
Septodont Holding
-
COLTENE Group
-
Ultradent Products Inc. (Mitsui Chemicals, Inc.)
-
Ivoclar
-
VERICOM
-
DiaDent
-
EdgeEndo
-
Kerr Corporation (Envista)
-
FKG Dentaire Sàrl
-
Angelus SA
-
META BIOMED CO, LTD.
-
Sure Dent Corporation
-
PD Dental
-
Zarc4endo
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Dentsply Sirona, COLTENE Group, Kerr Corporation, Septodont Holding)
- Focus on developing advanced gutta-percha points, bioceramic sealers, thermoplastic obturation materials, and integrated obturation systems with improved sealing properties and biocompatibility.
- Expand global presence through strategic partnerships with dental distributors, endodontic specialists, dental hospitals, academic institutions, and dental clinics.
- Strong global brand recognition, extensive R&D capabilities, broad endodontic product portfolios, and established distribution networks.
- Strong presence across conventional gutta-percha, resin-based sealers, and advanced bioceramic obturation categories.
- Premium pricing of advanced bioceramic sealers and specialized obturation systems may restrict adoption among cost-sensitive dental practices.
- Competition from regional manufacturers offering lower-priced gutta-percha points and root canal sealers may create pricing pressure.
Emerging Players (VERICOM, DiaDent, EdgeEndo, FKG Dentaire, Angelus, META BIOMED)
- Strengthen international distribution through regional distributors, dental trade networks, and partnerships with endodontic clinics and dental institutions.
- Focus on competitive pricing, product specialization, international certifications, and compatibility with contemporary obturation techniques.
- Strong presence in selected regional markets, particularly Asia-Pacific and Europe, supported by established dental distribution relationships.
- Ability to address demand for cost-effective gutta-percha products and advanced calcium silicate-based sealers.
- Comparatively lower global brand recognition and smaller international distribution and service networks than established multinational competitors.
- Dependence on third-party distributors may limit direct access to international dental clinics and endodontic specialists.
Recent Developments
-
In September 2025, Kerr Dental launched SimpliCore, a carrier-based gutta-percha obturator designed to simplify root canal obturation and streamline clinical workflows. The device featured a solid gutta-percha core to facilitate retreatment and post-space preparation, along with radiopaque material for clear identification during dental imaging.
"SimpliCore further enhances our comprehensive obturation line-combining application simplicity with the advantages of warm gutta-percha," says Jindra Capek, General Manager of Kerr Dental.
-
In June 2025, Septodont and Micro-Mega announced a strategic distribution partnership to commercialize Micro-Mega's GenENDO range of endodontic files and motors across Europe, the UK, the Middle East, and Africa. The partnership expanded Septodont's endodontic portfolio by adding products designed for root canal shaping and preparation.
-
In April 2025, Brasseler USA introduced an Endodontist Specialty Sales Consultant Team at the American Association of Endodontists (AAE) Annual Meeting in Boston, alongside new endodontic products, including BC Sealer Ion+, EdgePRO Advanced Irrigation Laser, XP4D Anatomical NiTi System, and BC Sealer Solvent. These launches expanded its endodontic portfolio and strengthened its specialized product and clinical support for endodontists.
Dental Obturation Materials Market Report Scope
Report Attribute
Details
Market size in 2026
USD 448.9 million
Estimated market size in 2027
USD 470.1 million
Projected market size by 2035
USD 675.2 million
Growth rate
CAGR of 4.6% from 2027 to 2035
Base year for estimation
2026
Actual estimates/Historical data
2023 - 2025
Forecast period
2027 - 2035
Quantitative units
Revenue in USD Million and CAGR from 2027 to 2035
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product type, obturation technique, treatment type, tooth type, end use, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Thailand; Australia; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Dentsply Sirona, Peter Brasseler Holdings, LLC, Septodont Holding, COLTENE Group, Ultradent Products Inc. (Mitsui Chemicals, Inc.), Ivoclar, VERICOM, DiaDent, EdgeEndo, Kerr Corporation (Envista), FKG Dentaire Sàrl, Angelus SA, META BIOMED CO., LTD., Sure Dent Corporation, PD Dental, and Zarc4endo
Customization scope
Free report customization (equivalent up to 8 analyst’s working days) with purchase. Addition or alteration to country, regional & segment scope
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Dental Obturation Materials Market Report Segmentation
This report forecasts revenue growth at global, regional & country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2023 to 2035. For this study, Grand View Research has segmented the global dental obturation materials market report based on product type, obturation technique, treatment type, tooth type, end use, distribution channel, and region:
-
Product Type Outlook (Revenue, USD Million, 2023 - 2035)
-
Gutta-Percha Points
-
Conventional / Uncoated Gutta-Percha Points
-
Coated / Surface-Modified Gutta-Percha Points
-
-
Thermoplastic Gutta-Percha Materials
-
Injectable Gutta-Percha Cartridges
-
Gutta-Percha Pellets
-
Gutta-Percha Sticks / Bulk Materials
-
-
Carrier-Based Obturation Materials
-
Gutta-Percha-Coated Carrier Obturators
-
All-Gutta-Percha Carrier Obturators
-
-
Root Canal Sealers
-
Zinc Oxide-Eugenol-Based Sealers
-
Epoxy Resin-Based Sealers
-
Methacrylate Resin-Based Sealers
-
Calcium Silicate / Bioceramic-Based Sealers
-
Calcium Hydroxide-Based Sealers
-
Silicone-Based Sealers
-
Other Sealers
-
-
Integrated / Hybrid Obturation Materials
-
Gutta-Percha-Sealer Composite Materials
-
Bioactive / Bioceramic-Enhanced Composite Materials
-
-
-
Obturation Technique Outlook (Revenue, USD Million, 2023 - 2035)
-
Cold Single-Cone Technique
-
Cold Lateral Compaction
-
Warm Vertical Compaction
-
Continuous Wave Compaction
-
Thermoplastic Injection
-
Carrier-Based Obturation
-
-
Treatment Type Outlook (Revenue, USD Million, 2023 - 2035)
-
Primary Root Canal Treatment
-
Root Canal Retreatment
-
-
Tooth Type Outlook (Revenue, USD Million, 2023 - 2035)
-
Anterior Teeth
-
Premolars
-
Molars
-
-
End Use Outlook (Revenue, USD Million, 2023 - 2035)
-
Dental Clinics
-
Independent Clinics
-
DSO-Affiliated Clinics
-
-
Hospitals
-
Dental Academic & Teaching Institutions
-
-
Distribution Channel Outlook (Revenue, USD Million, 2023 - 2035)
-
Direct Manufacturer Sales
-
Dental Distributor Sales
-
Third-Party Online Marketplaces
-
-
Regional Outlook (Revenue, USD Million, 2023 - 2035)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Thailand
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The dental obturation materials market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each dental obturation materials segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Treatment Type
Revenue capture definition
Primary Root Canal Treatment
Revenue generated from obturation materials used in the initial root canal treatment of teeth, including gutta-percha points, root canal sealers, thermoplastic gutta-percha, and other filling materials used to seal prepared root canal systems.
Root Canal Retreatment
Revenue generated from obturation materials used during repeat endodontic procedures to refill root canals following the removal or correction of previous root canal filling materials, including gutta-percha points, root canal sealers, and thermoplastic obturation materials
Estimation Model
Approach Name
Description
Bottom-Up Estimation
The market is estimated by analyzing the annual volume of primary root canal treatments and retreatment procedures performed across dental clinics, hospitals, orthodontic specialty practices, and dental academic institutions at the country, regional, and global levels. The assessment incorporates the consumption of gutta-percha points, thermoplastic gutta-percha materials, carrier-based obturators, root canal sealers, and integrated or hybrid obturation materials.
Top-Down Approach
The market estimation begins with an assessment of the global dental consumables and endodontic products market, followed by evaluating the share contributed by dental obturation materials through secondary research and expert validation. The analysis considers key market indicators such as the prevalence of untreated dental caries and pulpal diseases, annual root canal treatment volumes, primary endodontic procedures, retreatment requirements, and access to specialized dental care.
Supply-Side Analysis
The analysis considers manufacturers’ production capacities, annual product shipments, sales revenues, product portfolio diversification across gutta-percha points, thermoplastic obturation materials, carrier-based obturators, and root canal sealers, manufacturing facilities, average selling prices, regulatory approvals, and regional distribution networks. In addition, factors such as product launches, advancements in bioceramic and calcium silicate-based sealers, and strategic partnerships with dental distributors are assessed.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Dental Obturation Materials Product Portfolio & Technique Analysis
Conducted a comprehensive assessment of the dental obturation materials portfolio, covering gutta-percha points, thermoplastic gutta-percha materials, carrier-based obturators, root canal sealers, and integrated or hybrid obturation materials. Evaluated product adoption across cold single-cone, cold lateral compaction, warm vertical compaction, continuous wave compaction, thermoplastic injection, and carrier-based obturation techniques.
Helps stakeholders identify high-growth product categories, understand technique-specific demand, assess material preferences among endodontic practitioners, and optimize product portfolios in line with evolving clinical practices and obturation requirements.
End-Use Adoption & Procurement Landscape Analysis
Analyzed the adoption of dental obturation materials across independent dental clinics, DSO-affiliated clinics, hospitals, and dental academic and teaching institutions. Assessed procurement practices, purchasing criteria, product pricing, material handling characteristics, clinical performance requirements, distributor relationships, and preferences for direct manufacturer sales, dental distributors, and third-party online marketplaces.
Enables manufacturers to identify high-demand end-user segments, understand procurement preferences, optimize distribution strategies, strengthen institutional and practitioner relationships, and expand market penetration across established and emerging dental care markets.
Product Positioning & Manufacturer Competitiveness Assessment
Evaluated leading dental obturation materials manufacturers based on product portfolio breadth, gutta-percha and sealer formulations, bioceramic and calcium silicate technologies, compatibility with contemporary obturation techniques, product quality, clinical evidence, regulatory compliance, pricing strategies, geographic presence, and distribution capabilities. The assessment also examined recent product launches, portfolio expansion initiatives, research and development activities, strategic partnerships, and competitive differentiation across conventional and advanced obturation materials.
Supports competitive benchmarking, identifies opportunities for material innovation and portfolio expansion, enables product differentiation, strengthens go-to-market strategies, and helps manufacturers improve competitive positioning through advanced formulations, clinical validation, distribution expansion, and market-specific product offerings.
Frequently Asked Questions About This Report
The global dental obturation materials market size was valued at USD 448.9 million in 2026 and is estimated at USD 470.1 million for 2027.
The global dental obturation materials market is expected to grow at a CAGR of 4.6% from 2027 to 2035, reaching USD 675.2 million by 2035
Key factors include the increasing global burden of untreated dental caries and pulpal diseases, rising demand for tooth-preserving endodontic treatments, and expanding access to specialized dental care. Furthermore, continuous advancements in bioceramic and calcium silicate-based sealers, increasing adoption of bioactive obturation materials.
North America dominated with a 33.1% revenue share in 2026.
The root canal sealers segment held the largest share of 43.4% in 2026, while integrated / hybrid obturation materials is the fastest-growing segment over the forecast period.
The carrier-based obturation held the largest share of 32.2% in 2026, while cold single-cone technique is the fastest-growing segment over the forecast period.
The dental distributor sales held the largest share of 77.5% in 2026, while third-party online marketplaces is the fastest-growing segment over the forecast period.
The dental clinics held the largest share of 78.0% in 2026 while dental academic and teaching institutions is the fastest-growing segment over the forecast period.
Key players include Dentsply Sirona, Peter Brasseler Holdings, LLC, Septodont Holding, COLTENE Group, Ultradent Products Inc. (Mitsui Chemicals, Inc.), Ivoclar, VERICOM, DiaDent, EdgeEndo, Kerr Corporation (Envista), FKG Dentaire Sàrl, Angelus SA, META BIOMED CO., LTD., Sure Dent Corporation, PD Dental, and Zarc4endo.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


