
- Home
- »
- Pharmaceuticals
- »
-
Dermatological Drugs Market Size And Share Report, 2033GVR Report cover

Dermatological Drugs Market (2026 - 2033)
Size, Share & Trends Analysis Report By Therapy (Acne, Psoriasis, Rosacea, Alopecia), By Type (Prescription, Over-the-counter), By Route Of Administration, By Drug Class, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$26.2BMarket Estimate, 2026
$28.6BMarket Forecast, 2033
$55.5BCAGR, 2026–2033
9.9%Dermatological Drugs Market Summary
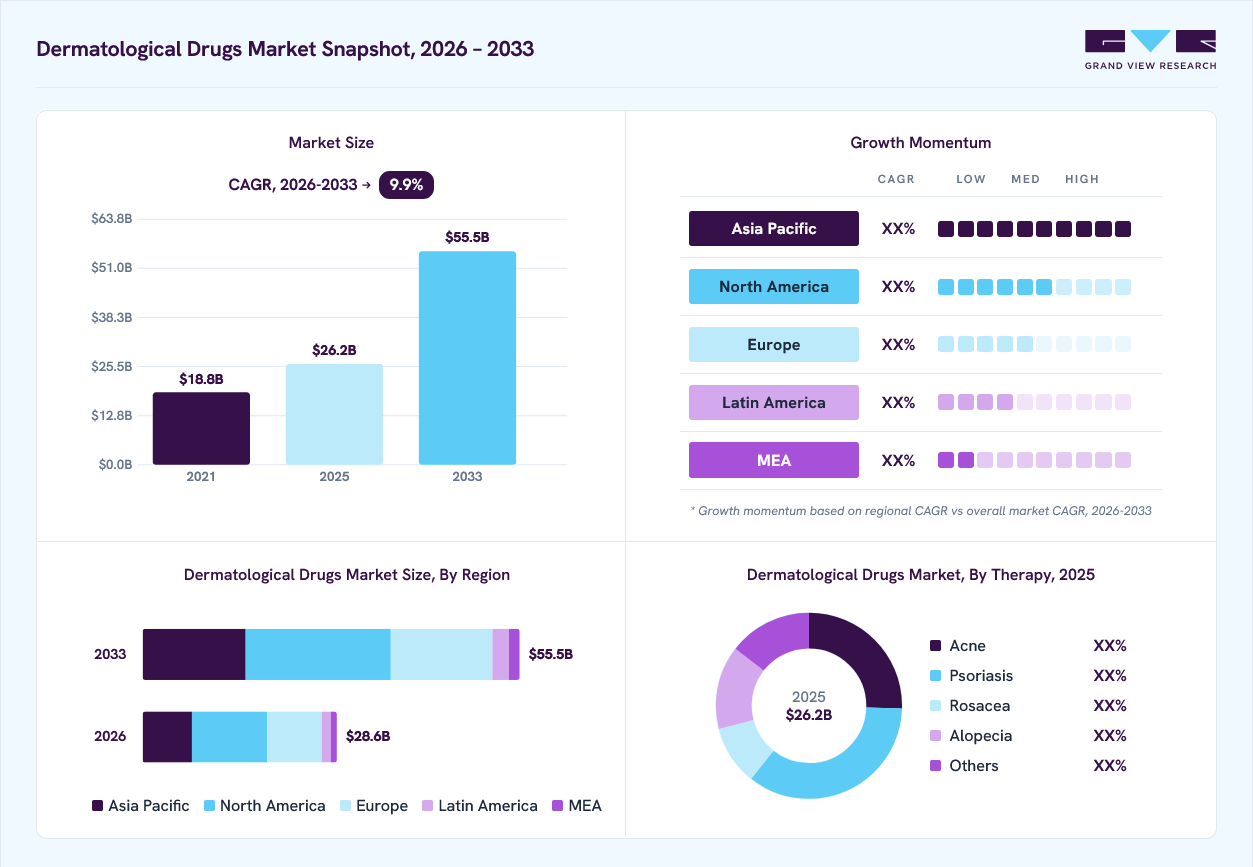
The global dermatological drugs market size was valued at USD 26.2 billion in 2025 and is projected to grow from USD 28.6 billion in 2026 to USD 55.5 billion by 2033, at a CAGR of 9.9% from 2026 to 2033. The market in North America dominated with a revenue share of 38.7% in 2025. Key factors driving the market include skin parasites, fungi, bacteria trapped in pores and hair follicles, fluid retention, dehydration prevention, and rising pollution levels.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By therapy: Psoriasis segment held the largest market share of 35.2% in 2025.
- By type: Prescription segment held the largest market share of 82.0% in 2025.
- By route of administration: Topical administration segment held the largest market share of 60.3% in 2025.
- By drug class: Corticosteroids segment held the largest market share of 30.2% in 2025.
- By distribution channel: Retail pharmacies segment held the largest market share of 50.9% in 2025.
Regional Highlights
- Largest regional market: North America (38.7% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 26.2 Billion
- Estimated market size in 2026: USD 28.6 Billion
- Projected market size by 2033: USD 55.5 Billion
- CAGR (2026-2033): 9.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Increasing awareness of skin diseases, the demand for rapid diagnosis, and innovative treatments are further growing in the market. Moreover, significant investments in research and development lead to new medications, and the availability of over-the-counter products makes treatments more accessible, contributing to overall growth.The increasing prevalence of skin conditions such as acne, psoriasis, and rosacea is increasing the demand for effective treatments such as topical retinoids, topical corticosteroids, and oral antibiotics. In addition, skin treatment includes laser therapy, topical & systemic medications, photodynamic therapy, radiotherapy, vitiligo surgery, and dermatological surgery. According to an article published by Healio in November 2024, Clindamycin is an effective treatment for acne vulgaris, available in topical and oral forms, as it helps reduce the risk of antibiotic resistance. The FDA has approved a new triple-combination gel with clindamycin, which has shown better results than other treatments.
 To learn more about this report, Download Free Sample Report
Advancements in technology such as nanotechnology, enhanced drug formulations, and targeted therapies are strengthening the market growth due to the effectiveness of treatments. For instance, an article published by Pharmaceutical Technology stated that Almirall partnered with Microsoft to improve drug discovery and is expected to introduce new dermatology treatments with AI technology in February 2024. Furthermore, this helps to accelerate the discovery of effective treatments for skin diseases, demonstrating growth in the pharmaceutical industry toward integrating technology into drug development.
Standard protocols such as the selection of guidelines, selection of medications, monitoring, and follow-up are prioritized for dermatological drugs. For instance, the FDA approved a new drug, EBGLYSS, developed by Eli Lilly in September 2024. The drug is designed to treat severe atopic dermatitis, known as eczema. Clinical trials stated that 38.0% of the patients experienced clear skin after 16 weeks of treatment. Therefore, the treatment is effective for patients struggling with eczema and is driving growth in the market.
Market Dynamics
The dermatological drugs market is supported by the rising prevalence of chronic skin disorders such as acne, psoriasis, atopic dermatitis, rosacea, fungal infections, and alopecia across both developed and emerging economies. Growing awareness of skin health, increasing access to dermatology specialists, and expanding use of prescription biologics and targeted therapies are contributing to market growth. Continued product innovation in topical formulations, oral therapies, and injectable treatments has improved disease management and patient outcomes. The market also benefits from higher healthcare spending and broader reimbursement for selected high value therapies in major countries. However, the high cost of biologics, limited reimbursement in many developing regions, and patent expirations for leading branded drugs continue to influence market competition and pricing. Generic drug availability is increasing treatment accessibility while creating pricing pressure for established manufacturers. In addition, ongoing research into immunology-based therapies, personalized medicine, and novel drug delivery technologies is expected to expand treatment options and support long term market development across multiple dermatological indications.
The dermatological drugs market is being driven by the increasing availability of targeted therapies for chronic inflammatory skin disorders such as psoriasis, atopic dermatitis, vitiligo, and alopecia. Advances in immunology have enabled the development of biologics, Janus kinase inhibitors, and other targeted therapies that offer improved efficacy and long term disease control compared with conventional treatments. Pharmaceutical companies are also expanding approved indications to pediatric and broader patient populations, increasing treatment adoption and improving patient access. In addition, growing clinical evidence supporting the safety and effectiveness of these therapies has strengthened physician confidence and encouraged reimbursement across major healthcare markets. Continuous investment in research and development and regulatory support for innovative therapies are expected to further strengthen the adoption of advanced dermatological drugs. For instance, in September 2025, Reuters reported that the U.S. Food and Drug Administration approved Incyte's Opzelura (ruxolitinib) cream for children aged 2 to 11 years with atopic dermatitis. The approval expanded the therapy beyond patients aged 12 years and older. Incyte stated that atopic dermatitis affects approximately 2 million to 3 million children aged 2 to 11 years and more than 21 million individuals aged 12 years and older in the United States. The company also projected Opzelura sales of approximately USD 650 million in 2025 and expected revenue to double over the following five years through expanded approvals in the United States and Europe.
The dermatological drugs market continues to face challenges associated with the high cost, lengthy timelines, and significant risks involved in developing innovative therapies. Late-stage clinical trials require extensive evaluation of efficacy and long term safety across diverse patient populations, increasing development expenses and delaying commercialization. Even when clinical studies achieve primary endpoints, inconsistent efficacy across dose groups or patient subgroups can reduce investor confidence and complicate regulatory and commercial strategies. In addition, pricing pressure from healthcare systems, competition from biosimilars and generic therapies, and growing reimbursement scrutiny create additional barriers for manufacturers seeking premium pricing. These factors increase financial risk and may delay investment decisions for promising dermatology products. For instance, in May 2026, Reuters reported that Apogee Therapeutics announced Phase II clinical trial results for zumilokibart involving 346 adults with moderate to severe atopic dermatitis. After 16 weeks of treatment, 65.9% of patients receiving the mid dose and 61.6% receiving the high dose achieved at least a 75% improvement in disease severity compared with 23.4% in the placebo group.
Strategic acquisitions and licensing agreements are creating significant opportunities for companies operating in the dermatological drugs market. Large pharmaceutical manufacturers are actively acquiring innovative biotechnology companies to strengthen their dermatology and immunology portfolios while reducing product development timelines. These transactions provide access to late stage clinical assets, commercial products, and specialized research capabilities, enabling companies to expand their presence in high growth therapeutic areas such as atopic dermatitis and psoriasis. Portfolio diversification also helps companies reduce dependence on mature products while supporting long term revenue growth. As demand for targeted dermatology therapies continues to increase, strategic acquisitions are expected to remain an important growth strategy across the global market. For instance, in June 2026, Reuters reported that AbbVie agreed to acquire Apogee Therapeutics for USD 10.9 billion in cash, offering USD 135.11 per share, representing a 49.49% premium over the previous closing price. The acquisition added the investigational atopic dermatitis therapy zumilokibart to AbbVie's immunology pipeline. AbbVie also reported that its immunology business generated more than USD 30 billion in revenue during 2025, representing a 14% increase from the previous year, supported by strong growth of Skyrizi and Rinvoq despite a 49% decline in Humira sales. The transaction was expected to close during the third quarter of 2026, demonstrating the increasing strategic value of dermatology assets within the global pharmaceutical industry.
Analyst Perspective
The dermatological drugs market is expected to witness steady growth, supported by the increasing prevalence of chronic skin disorders, expanding awareness of dermatological health, and continued innovation in targeted therapies. Biologics, Janus kinase inhibitors, and advanced topical formulations are reshaping treatment approaches for conditions such as psoriasis, atopic dermatitis, and alopecia. Established pharmaceutical companies continue to strengthen their portfolios through acquisitions, licensing agreements, and label expansions, while specialty dermatology companies focus on differentiated formulations and patient centric solutions. Increasing access to dermatology services in emerging markets and ongoing investment in research and development are expected to support long term market expansion despite pricing and reimbursement challenges.
Therapy Insights
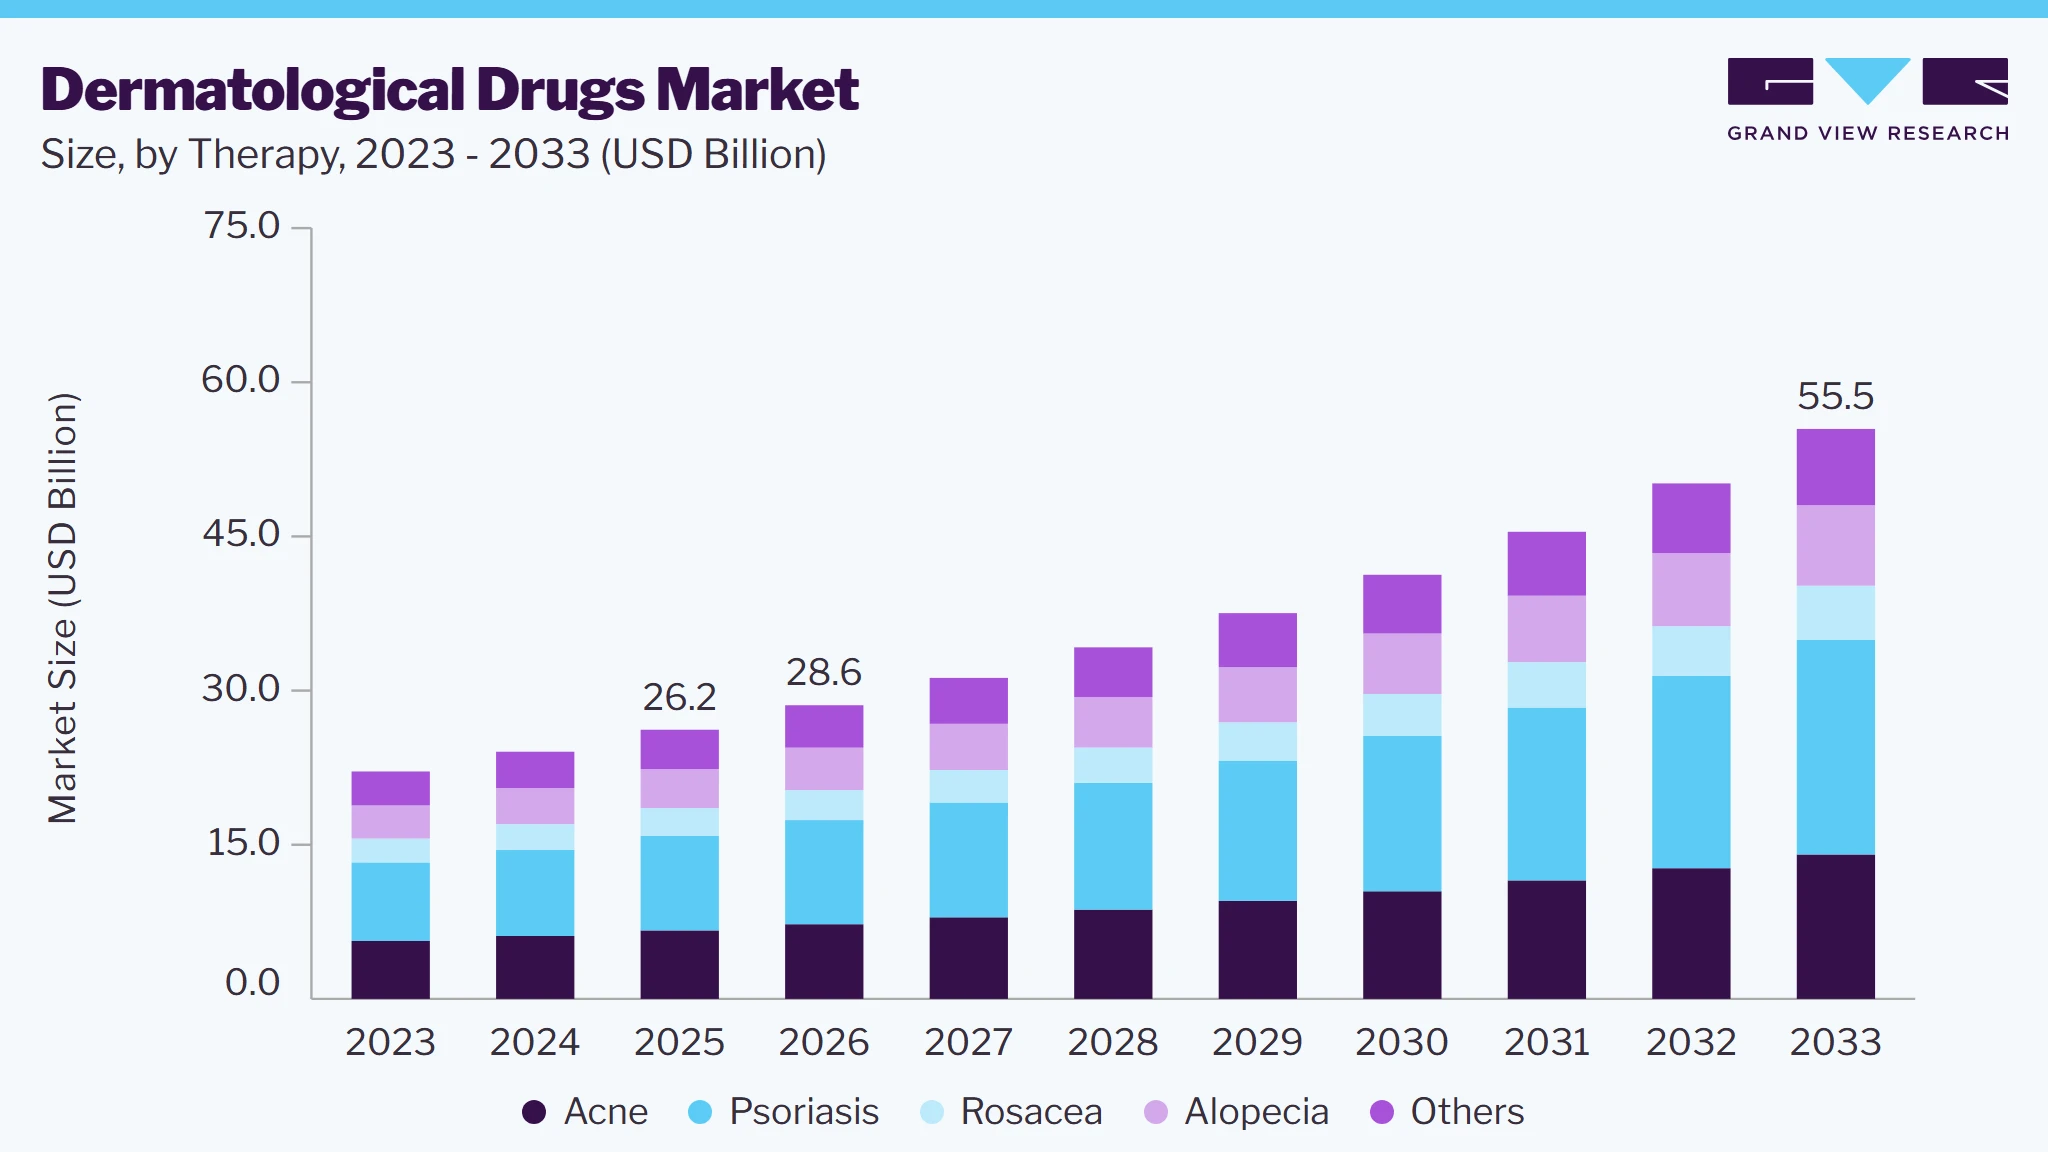
Based on therapy, the psoriasis segment led the market with the largest revenue share of 35.2% in 2025, which can be attributed to the awareness of the disease and the demand for effective treatments. The increased awareness of psoriasis has contributed to the demand for effective diagnoses and treatments. Approval of new drugs by regulatory agencies also increases the options available to patients, while many prefer oral medications over injections. According to an article published by Business Wire in September 2024, Organon acquired Dermavant Sciences. This includes VTAMA (tapinarof) cream, a non-steroidal treatment approved for severe plaque psoriasis in adults. The treatment is effective for patients struggling with skin conditions.
The acne segment is expected to grow with a significant CAGR of 9.9% over the forecast period, attributed to the increasing prevalence of acne, especially among teenagers and young adults. According to a study by the National Institutes of Health, patients are seeking effective treatments, with about 80.0% of adolescents experiencing the condition. In addition, advancements in treatment options, such as new drug formulations and combination therapies, have improved efficacy in managing acne. Furthermore, there is also a growing awareness of skincare and the importance of addressing acne, influenced by social media and consumer interest in health and wellness. The accessibility of over-the-counter (OTC) acne medications allows more individuals to find solutions for their skin concerns without needing prescriptions, further supporting market growth.
Type Insights
Based on type, the prescription segment led the market with the largest revenue share of 82.0% in 2025. The segment growth can be attributed to the rising prevalence of skin diseases, such as psoriasis and eczema, which leads to patients seeking medical help and requiring treatment. In addition, advancements in drug development are resulting in innovative therapies, such as biologics and targeted treatments, offer better results. Furthermore, improved healthcare access and the availability of medications have made it easier for patients to receive treatments, contributing to the growth of prescriptions in the market.
The over-the-counter segment is projected to grow at the fastest CAGR over the forecast period, due to the increasing awareness of skin conditions such as acne, eczema, and psoriasis, leading to higher demand for treatments. In addition, the convenience and affordability of OTC medications compared to prescription drugs make them a preferred choice for many consumers. The growth of e-commerce and online pharmacies also enhances accessibility, allowing patients to obtain these products easily. Therefore, the expansion of the over-the-counter segment is expected to grow in the market.
Route of Administration Insights
Based on route of administration, the topical administration segment led the market with the largest revenue share of 60.3% in 2025. This can be attributed to the growth of user-friendly delivery systems and effective treatments. Topical treatments allow for direct application to the affected area, enabling targeted therapies such as acne, psoriasis, and eczema, which enhances treatment effectiveness. In addition, the development of user-friendly systems, such as gels, creams, and patches, is also contributing to the growth in the market.
The parenteral administration is expected to grow with the fastest CAGR of 10.9% over the forecast period. This can be attributed to the growth for faster absorption of medications, which provides relief for patients with skin conditions; in addition, parenteral drugs bypass the digestive system, which avoids issues such as first-pass metabolism that can reduce the drug effectiveness when taken orally. Furthermore, this is also beneficial for patients who have difficulty swallowing pills, further driving the growth of parenteral routes in dermatological drugs.
Drug Class Insights
Based on drug class, the corticosteroids segment led the market with the largest revenue share of 30.2% in 2025. This can be attributed to rising skin infection cases and the growth of research and development. Skin conditions such as eczema, psoriasis, and dermatitis are increasing, leading to great demand for effective treatments. Furthermore, advancements in research and development have resulted in new formulations and delivery methods for corticosteroids, which improve effectiveness and safety. Therefore, the growing recognition of this segment as an essential treatment for inflammatory skin conditions has driven the market.
Calcineurin inhibitors are expected to grow at the fastest CAGR of 11.0% over the forecast period. Effective treatments such as topical calcineurin inhibitors, including tacrolimus and pimecrolimus, are commonly used to treat eczema. They are also primarily used to treat vitiligo, psoriasis, and seborrheic dermatitis. They are beneficial for sensitive skin areas and prevent skin thinning, making them suitable for long-term management. Furthermore, the effectiveness and safety of calcineurin inhibitors are positioned to further grow in the market.
Distribution Channel Insights
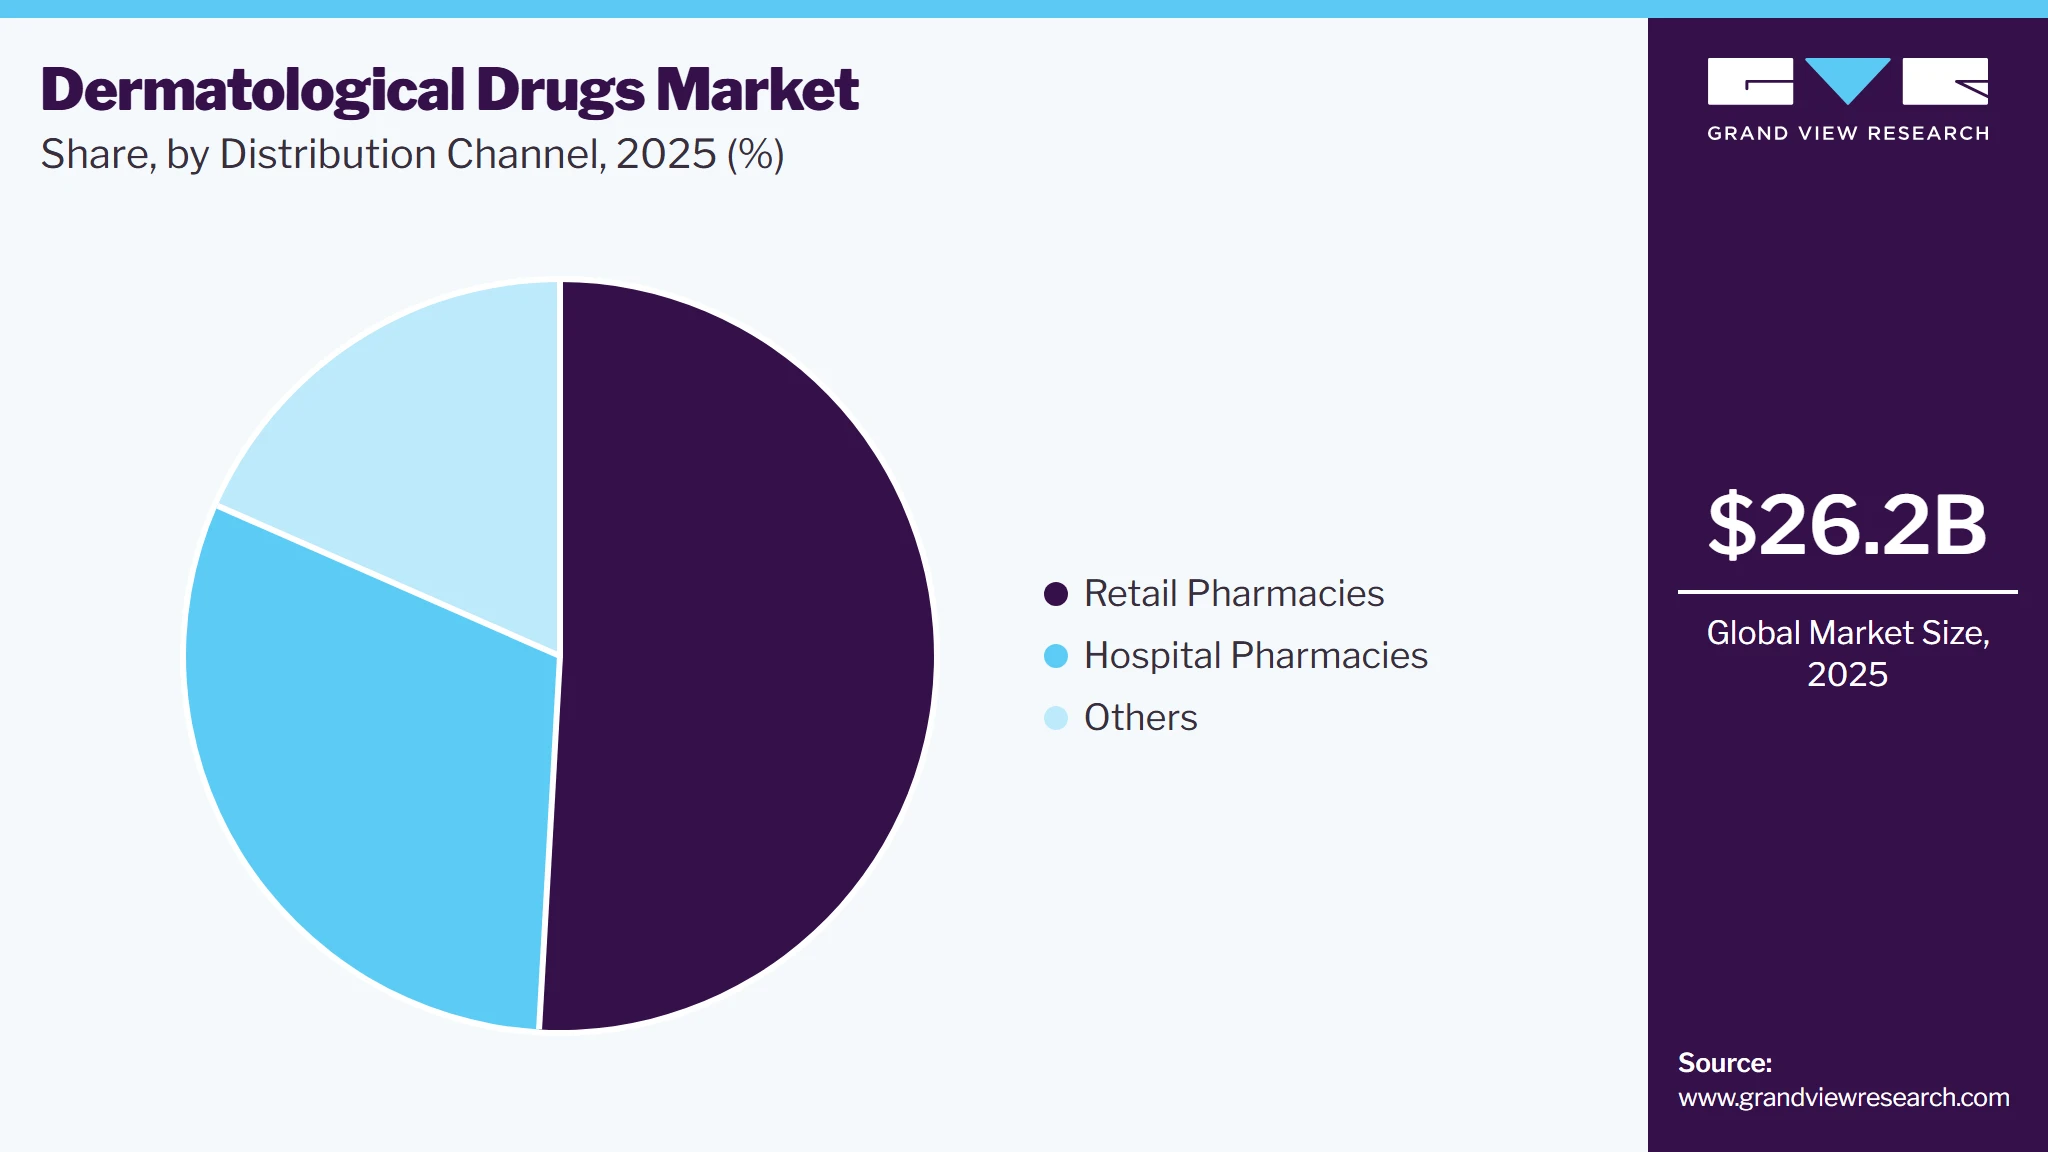
Based on distribution channel, the retail pharmacies segment led the market with the largest revenue share of 50.9% in 2025. This can be attributed to OTC dermatological product growth and awareness of skin conditions. Skin conditions, such as acne and eczema, are leading patients to seek treatment, resulting in higher sales of dermatological products at retail pharmacies. Furthermore, the growing availability of OTC dermatological products is making it easier for consumers to access treatments without needing a prescription, further increasing sales. The rise in consumer awareness about skin health and the importance of skincare encourages people to purchase dermatological products.
 To learn more about this report, Download Free Sample Report
Hospital pharmacies are expected to grow with a significant CAGR of 10.0% over the forecast period, attributed to a wide range of medications and demand for prescription-based dermatological treatments. The availability of a wide range of medications in hospital pharmacies allows healthcare professionals to recommend appropriate treatments, catering to patient needs. The presence of skilled healthcare providers in hospitals also enhances the likelihood of patients receiving the right prescriptions. Furthermore, the growing preference for purchasing medications from nearby pharmacies, combined with the availability of cost-effective OTC products, contributes to the expansion of this market.
Regional Insights
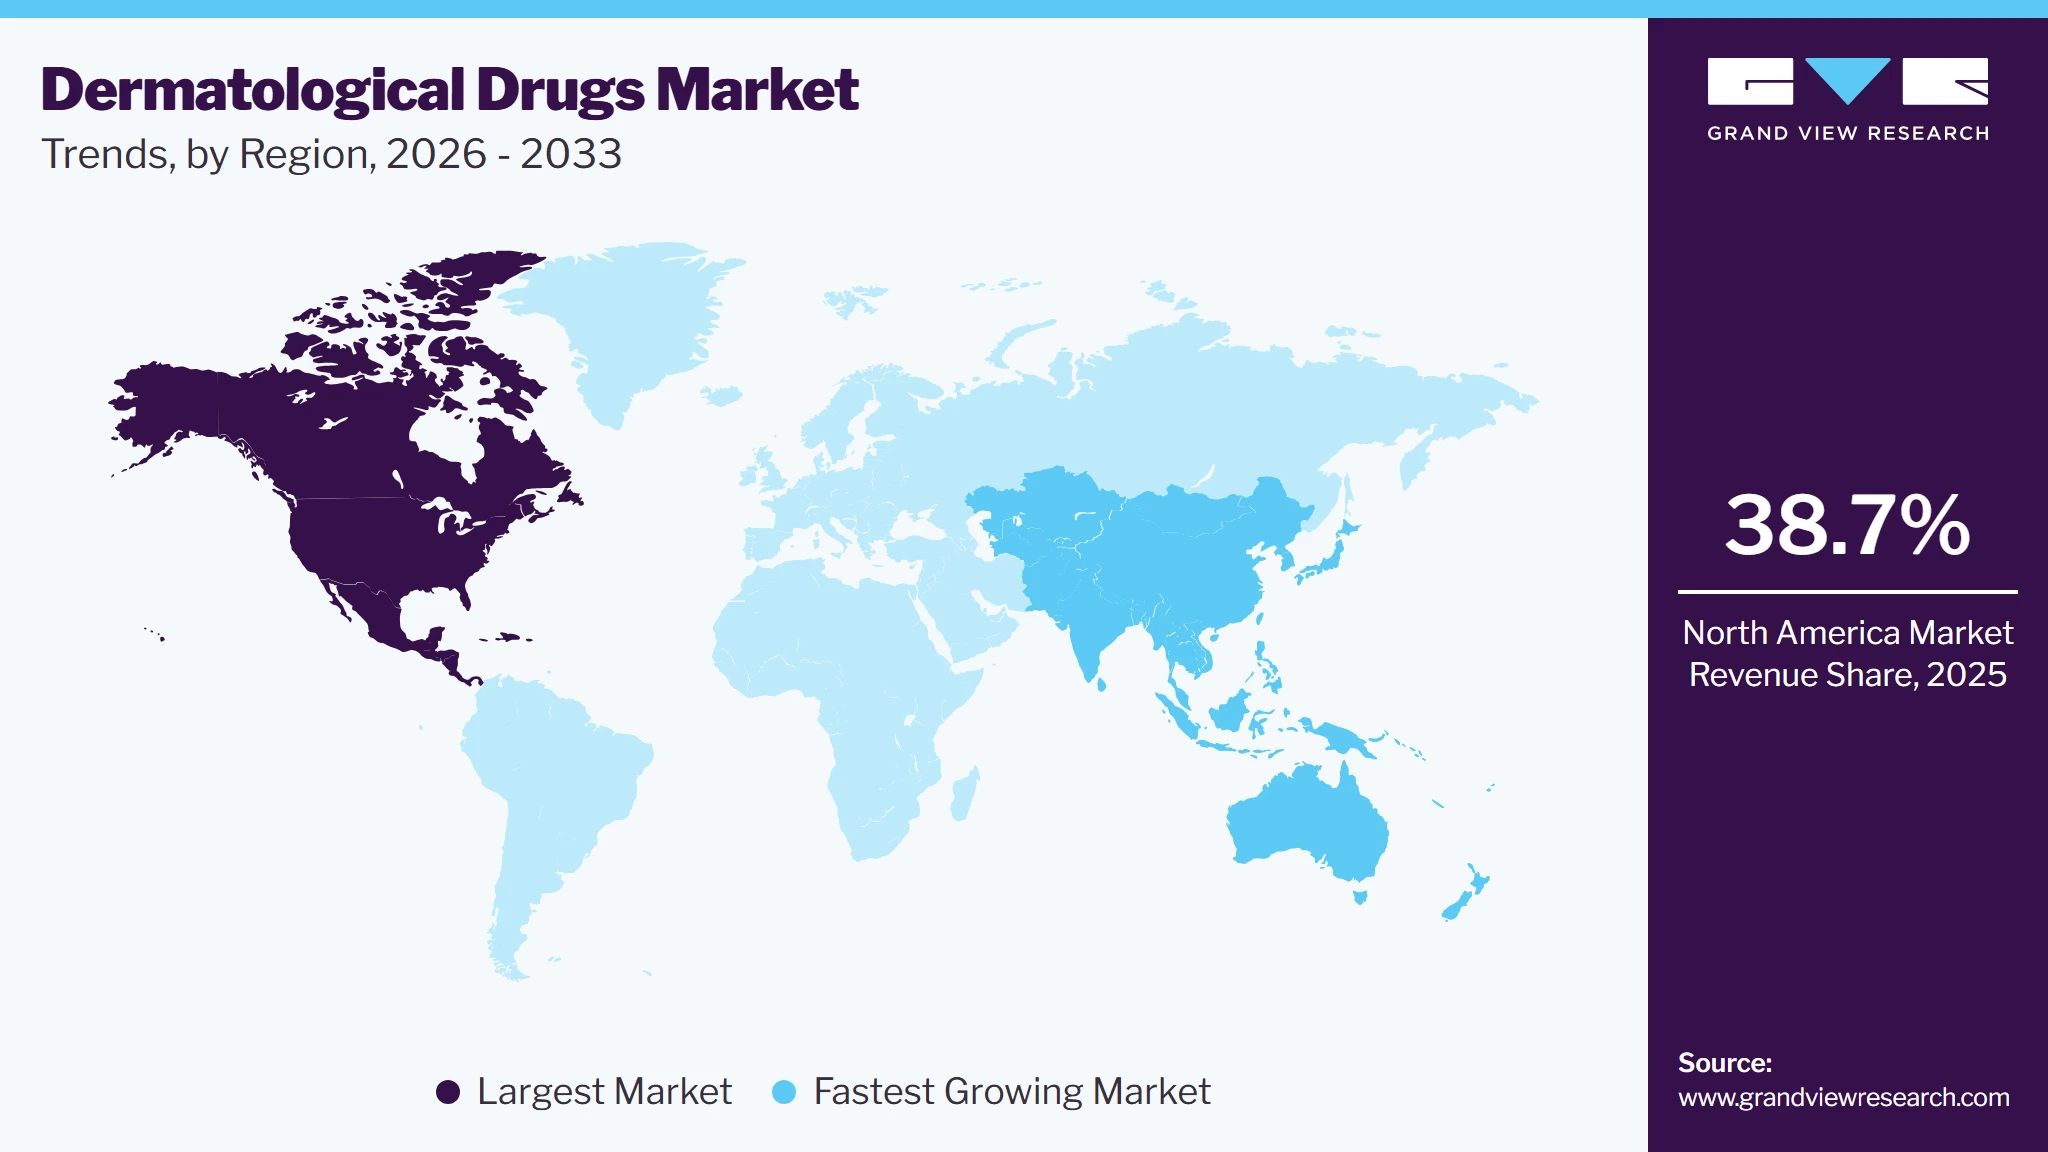
North America dominated the dermatological drugs market with the largest revenue share of 38.7% in 2025, which can be attributed to advancements in drug development and increasing awareness. The growing incidence of skin conditions such as acne, psoriasis, and eczema is increasing the demand for effective treatments. For instance, a survey updated by CeraVe in September 2024 stated that over 80% of adults in the U.S. experience skin concerns, and only half of them visit a dermatologist annually. The survey highlights barriers to dermatological care, such as long wait times and lack of insurance, which prevent many from seeking specialized treatment. Moreover, advancements in drug development, such as biologics and targeted therapies, are enhancing the treatment options available to patients. Furthermore, the rise in OTC products is contributing to the market growth in North America.
 To learn more about this report, Download Free Sample Report
U.S. Dermatological Drugs Market Trends
The dermatological drugs market in the U.S. held the largest share in the North America region in 2025, attributed to the rising cases of skin infections and the growing pipeline of clinical studies. Skin conditions, particularly acne, have intensified the need for effective treatments. Topical retinoids and antibiotics such as doxycycline and minocycline are gaining popularity for their effectiveness and favorable safety profiles. Furthermore, clinical studies aim to develop new dermatological treatments that indicate a robust research environment.
Asia Pacific Dermatological Drugs Market Trends
Asia Pacific is expected to grow at the fastest CAGR of 11.1% over the forecast period. This can be attributed to the increasing awareness of skin conditions and improved healthcare infrastructure. The awareness of skin health and available therapies are shifting the focus of patients to seeking medical care and treatments such as topical retinoids, corticosteroids, and isotretinoin. In addition, the healthcare infrastructure, including molecular diagnostics and imaging technologies, is improving the accuracy and early diagnosis of skin conditions, which supports the development and availability of new dermatological drugs.
China dermatological drugs market dominated Asia Pacific with the largest revenue share in 2025, which can be attributed to the increasing purchase of skincare products and improved accessibility across urban and rural areas. The rise in disposable income among consumers also contributes to the growth, as individuals are invested in purchasing skincare products and medications. According to an article published by BusinessWire in September 2024, LEO Pharma submitted a New Drug Application (NDA) for Enstilar, a treatment for adults with plaque psoriasis, to the National Medical Products Administration in China. Furthermore, the NDA submission is backed by positive results in which the treatment is considered effective, further increasing growth in dermatological drugs.
Europe Dermatological Drugs Market Trends
Europe dermatological drugs market is expected to grow significantly over the forecast period, driven by the rising cases of skin diseases and preference for non-invasive treatments. Skin conditions such as acne, psoriasis, and eczema are becoming common due to factors such as pollution and dietary changes. According to an article published by EurekAlert in May 2022, dermatologists in Germany identified a link between acne and low levels of omega-3 fatty acids at the European Academy of Dermatology and Venereology Spring Symposium. The study involves 100 patients with acne, and 94.0% were found to have omega-3 levels below the recommended range, implying diet is expected to influence acne severity. Moreover, the rising awareness of skin care health is prompting patients to seek non-invasive treatments, resulting in the usage of dermatological drugs.
Key Dermatological Drugs Company Insights
Some key players in the market are AbbVie Inc., Pfizer Inc., and GSK plc.; Sun Pharmaceutical Industries Ltd.; GALDERMA; Amgen Inc.; Johnson & Johnson Services, Inc.; Novartis AG; Eli Lilly and Company; Almirall, S.A; and Bausch Health Companies Inc. These companies employ various strategies to gain a competitive edge, such as launching new products to cater to diverse patient needs, focusing on personalized medicine to enhance treatment efficacy, and leveraging emerging markets to tap into increasing awareness about dermatological drugs. Furthermore, these businesses engage in collaborative research initiatives with healthcare organizations to drive innovation while integrating digital health solutions for enhanced patient access and adherence.
-
AbbVie Inc. is a biopharmaceutical company with a strong focus on dermatology, offering innovative treatments for various skin conditions. Its dermatological portfolio includes medications for chronic diseases such as psoriasis, atopic dermatitis, and hidradenitis suppurativa, with products such as RINVOQ demonstrating significant efficacy in clinical trials.
-
Pfizer Inc. offers a range of dermatological treatments to address various skin conditions. Its product, CIBINQO, is an oral medication approved for moderate to severe atopic dermatitis, providing an effective option for patients who have not found relief with other treatments. In addition, the company offers EUCRISA, a non-steroidal topical ointment approved for treating mild to moderate eczema for patients aged two and older.
Key Dermatological Drugs Companies
The following key companies have been profiled for this study on the dermatological drugs market.
-
AbbVie Inc.
-
Pfizer Inc.
-
GSK plc.
-
Sun Pharmaceutical Industries Ltd.
-
GALDERMA
-
Amgen Inc.
-
Johnson & Johnson Services, Inc.
-
Novartis AG
-
Eli Lilly and Company
-
Almirall, S.A
-
Bausch Health Companies Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (AbbVie Inc., Johnson & Johnson Services, Inc., Novartis AG, Eli Lilly and Company, Pfizer Inc., Amgen Inc., GSK plc.)
- Focus on expanding dermatology portfolios through biologics, targeted immunology therapies, and lifecycle management of established brands.
- Invest in clinical trials for label expansions across indications such as psoriasis, atopic dermatitis, alopecia areata, and other immune mediated skin disorders.
- Strengthen market presence through strategic acquisitions, licensing agreements, and collaborations with biotechnology companies while expanding access through reimbursement and patient support programs.
- Strong global brand recognition with diversified dermatology and immunology portfolios.
- Extensive research and development capabilities, robust regulatory expertise, and well-established commercialization infrastructure enable rapid global product launches.
- Broad relationships with hospitals, dermatologists, specialty pharmacies, and healthcare providers support sustained market leadership.
- High research and development expenditure and increasing pricing pressure from healthcare systems and payers.
- Loss of exclusivity for key products, growing biosimilar competition, and lengthy regulatory review timelines can impact revenue growth and delay commercialization of new therapies.
Emerging and Specialty Dermatology Players (GALDERMA, Sun Pharmaceutical Industries Ltd., Almirall, S.A., Bausch Health Companies Inc.)
- Focus on strengthening dermatology focused portfolios through innovative topical therapies, aesthetic dermatology products, prescription skin care solutions, and specialty treatments for acne, rosacea, psoriasis, and other chronic skin disorders.
- Expand geographic presence through strategic partnerships, licensing agreements, and regional product launches while investing in formulation improvements and patient centric drug delivery technologies.
- Strong specialization in dermatology enables focused product development and close engagement with dermatologists.
- Agile commercial strategies, expertise in topical formulations, and established presence in selected regional markets support faster response to changing treatment trends and patient needs.
- Limited product diversification compared with multinational pharmaceutical companies and relatively smaller research budgets for developing novel biologics.
- Dependence on selected therapeutic areas and regional markets may restrict long term growth, while competition from larger pharmaceutical companies and generic manufacturers continues to pressure market share and pricing.
Recent Developments
-
In August 2024, Sun Pharmaceutical Industries Ltd. launched STARIZO, an antibacterial treatment to combat Acute Bacterial Skin and Skin Structure Infections caused by drug-resistant bacteria such as MRSA in India. The medication offers the convenience of once-a-day dosing for six days, making it easier for patients than traditional treatments requiring more frequent dosing over longer periods.
-
In January 2024, Pfizer Inc. partnered with Glenmark Pharmaceuticals to introduce abrocitinib, also known as CIBINQO, an oral treatment for atopic dermatitis in India. This treatment provides rapid itch relief and sustained disease control for patients suffering from this chronic skin condition.
Dermatological Drugs Market Report Scope
Report Attribute
Details
Market size in 2025
USD 26.2 billion
Estimated market size in 2026
USD 28.6 billion
Projected market size by 2033
USD 55.5 billion
Growth rate
CAGR of 9.9% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Therapy, type, route of administration, drug class, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
AbbVie Inc.; Pfizer Inc.; GSK plc.; Sun Pharmaceutical Industries Ltd.; GALDERMA; Amgen Inc.; Johnson & Johnson Services, Inc.; Novartis AG; Eli Lilly and Company; Almirall, S.A; Bausch Health Companies Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Dermatological Drugs Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and analyzes the latest industry trends in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global dermatological drugs market report based on therapy, type, route of administration, drug class, distribution channel, and region.
-
Therapy Outlook (Revenue, USD Million, 2021 - 2033)
-
Acne
-
Psoriasis
-
Rosacea
-
Alopecia
-
Others
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Prescription
-
Over-the-counter (OTC)
-
-
Route of Administration Outlook (Revenue, USD Million, 2021 - 2033)
-
Topical Administration
-
Oral Administration
-
Parenteral Administration
-
-
Drug Class Outlook (Revenue, USD Million, 2021 - 2033)
-
Corticosteroids
-
Retinoids
-
Antibiotics
-
Antifungals
-
Calcineurin Inhibitors
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital Pharmacies
-
Retail Pharmacies
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The dermatological drugs market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each dermatological drugs segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Therapy
Revenue capture definition
Acne
Revenue generated from dermatological drugs indicated for the treatment of acne vulgaris and related acne conditions, including inflammatory and non-inflammatory acne. This includes prescription and OTC topical, oral, and injectable therapies specifically prescribed or purchased for acne management. Revenue from acne indications is captured exclusively within this segment.
Psoriasis
Revenue generated from dermatological drugs used for the treatment of psoriasis, including plaque psoriasis, guttate psoriasis, pustular psoriasis, erythrodermic psoriasis, and psoriatic skin manifestations. The segment includes topical therapies, systemic drugs, biologics, and targeted therapies indicated for psoriasis. Revenue associated with psoriasis treatment is classified solely within this segment.
Rosacea
Revenue generated from dermatological drugs prescribed for the treatment of rosacea, including erythematotelangiectatic, papulopustular, phymatous, and ocular rosacea. This segment includes topical and oral therapies approved or commonly prescribed for rosacea management. Revenue is captured exclusively from rosacea related indications.
Alopecia
Revenue generated from dermatological drugs indicated for the treatment of hair loss disorders, including androgenetic alopecia, alopecia areata, and other clinically diagnosed alopecia conditions. The segment includes topical, oral, injectable, and targeted therapies used to promote hair regrowth or reduce hair loss. Revenue is assigned exclusively to alopecia treatment.
Others
Revenue generated from dermatological drugs used for the treatment of skin disorders other than acne, psoriasis, rosacea, and alopecia. This includes atopic dermatitis, eczema, vitiligo, urticaria, fungal skin infections, bacterial skin infections, contact dermatitis, seborrheic dermatitis, hidradenitis suppurativa, and other dermatological conditions. Revenue from these indications is captured exclusively within this segment.
Segment - Type
Revenue capture definition
Prescription
Revenue generated from dermatological drugs that require a physician's prescription for dispensing. This includes branded and generic prescription medicines across topical, oral, and injectable formulations used for the treatment of dermatological conditions. Revenue is captured at the point of commercial sale.
Over-the-counter (OTC)
Revenue generated from dermatological drugs that are available without a prescription through retail pharmacies, supermarkets, online pharmacies, and other authorized outlets. This includes OTC creams, ointments, gels, shampoos, cleansers, antifungal preparations, acne treatments, and other consumer dermatology products. Revenue is classified exclusively within the OTC segment.
Segment - Route of Administration
Revenue capture definition
Topical Administration
Revenue generated from dermatological drugs administered directly to the skin, scalp, or nails. This includes creams, ointments, gels, lotions, foams, sprays, solutions, shampoos, and patches intended for localized treatment of dermatological disorders. Revenue is captured based on products formulated for topical administration.
Oral Administration
Revenue generated from dermatological drugs administered orally in the form of tablets, capsules, powders, oral solutions, or suspensions for the treatment of skin disorders. Revenue is assigned exclusively to products intended for systemic oral therapy.
Parenteral Administration
Revenue generated from dermatological drugs administered through injectable routes, including subcutaneous, intravenous, and intramuscular injections. This segment primarily includes biologics, monoclonal antibodies, and other injectable therapies indicated for moderate to severe dermatological conditions. Revenue is classified exclusively under parenteral administration.
Segment - Drug Class
Revenue capture definition
Corticosteroids
Revenue generated from dermatological corticosteroid drugs used to reduce inflammation, itching, and immune responses in skin disorders. This includes topical, oral, and injectable corticosteroid formulations indicated for dermatological conditions.
Retinoids
Revenue generated from retinoid based dermatological drugs used for the treatment of acne, psoriasis, photoaging, and other skin disorders. The segment includes topical and systemic retinoid formulations marketed for dermatological indications.
Antibiotics
Revenue generated from topical and systemic antibiotic drugs prescribed for bacterial skin infections and acne related conditions. Revenue from all dermatological antibiotic formulations is captured exclusively within this segment.
Antifungals
Revenue generated from dermatological antifungal drugs used to treat superficial and systemic fungal skin infections. The segment includes topical and oral antifungal formulations indicated for dermatological use.
Calcineurin Inhibitors
Revenue generated from topical and systemic calcineurin inhibitor drugs used primarily for inflammatory skin disorders such as atopic dermatitis and related immune mediated conditions. Revenue is classified exclusively within this segment.
Others
Revenue generated from dermatological drugs belonging to other pharmacological classes, including biologics, Janus kinase inhibitors, phosphodiesterase 4 inhibitors, antihistamines, immunosuppressants, antivirals, keratolytics, and other emerging dermatology therapies. Revenue from these products is captured exclusively within this segment.
Segment - Distribution Channel
Revenue capture definition
Hospital Pharmacies
Revenue generated from dermatological drugs dispensed through hospital pharmacies, including inpatient and outpatient hospital settings. This segment includes prescription therapies supplied through public and private hospitals.
Retail Pharmacies
Revenue generated from dermatological drugs sold through retail pharmacy chains, independent pharmacies, drug stores, and community pharmacies. The segment includes both prescription and OTC dermatological products purchased through retail outlets.
Others
Revenue generated from dermatological drugs distributed through online pharmacies, mail order pharmacies, specialty pharmacies, direct sales channels, government procurement programs, and other non traditional distribution channels. Revenue from these channels is classified exclusively within this segment.
Estimation Model
 To learn more about this report, Download Free Sample Report
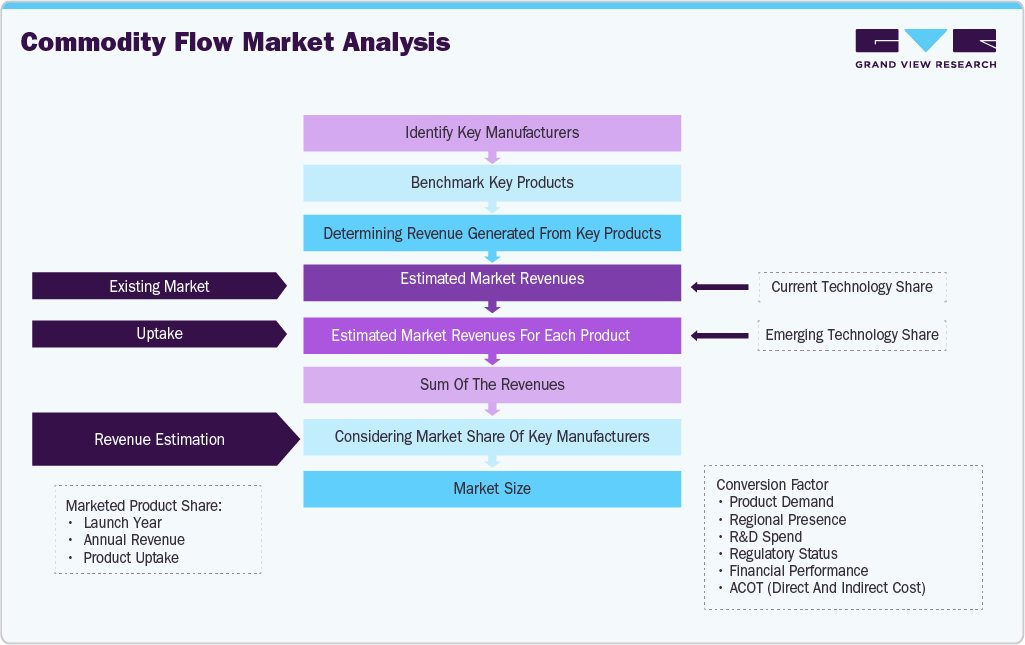
The dermatological drugs market was estimated using a structured bottom-up methodology supported by extensive secondary and primary research. The study began by identifying leading manufacturers and specialty pharmaceutical companies operating in the global dermatology therapeutics market, including companies with approved prescription and over the counter products. Key dermatology products were benchmarked based on approved indications, product type, route of administration, commercialization status, geographic presence, and target patient population. Annual sales of major dermatological drugs were collected from company annual reports, investor presentations, regulatory filings, financial disclosures, and other publicly available sources. Product level revenues were estimated for therapies where direct sales data were unavailable using prescription volume, treatment adoption, pricing trends, epidemiology, and regional utilization patterns. The revenues of individual products were aggregated to derive the overall market size, followed by validation through manufacturer market share analysis, distribution channel assessment, and expert interviews with dermatologists, pharmaceutical executives, and industry specialists. Final market estimates were triangulated using epidemiological data, regulatory approvals, competitive landscape analysis, healthcare expenditure, and demand trends across major regional markets to ensure consistency, accuracy, and alignment with current industry conditions.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Dermatological Drugs Competitive Landscape & Portfolio Assessment
Conducted a comprehensive assessment of the global dermatological drugs landscape by evaluating approved therapies, late-stage pipeline assets, treatment modalities, drug classes, and competitive positioning across major dermatological indications including psoriasis, atopic dermatitis, acne, rosacea, alopecia, and fungal skin infections. The study analyzed leading companies including AbbVie, Eli Lilly, Galderma, Pfizer, Novartis, Johnson & Johnson, Sun Pharmaceutical, Almirall, Bausch Health, Amgen, and GSK, while assessing innovation trends, regulatory approvals, and commercialization strategies.
Helped the client identify high growth therapeutic areas, benchmark competitor portfolios, evaluate pipeline differentiation, assess market entry opportunities, and prioritize strategic investments, licensing opportunities, and portfolio expansion within the evolving dermatology therapeutics market.
Dermatological Drug Benchmarking & Innovation Assessment
Delivered a detailed benchmarking study comparing dermatological drug classes, including corticosteroids, biologics, retinoids, antibiotics, antifungals, calcineurin inhibitors, and emerging targeted therapies. The assessment evaluated clinical performance, mechanism of action, route of administration, treatment positioning, safety profiles, patent landscape, lifecycle management strategies, and innovation trends across leading pharmaceutical companies.
Enabled the client to evaluate technology competitiveness, identify treatment gaps across dermatological indications, benchmark clinical differentiation, support product lifecycle planning, and prioritize research and development investments for next generation dermatology therapies.
Dermatological Drugs Manufacturing & Commercialization Assessment
Conducted a strategic assessment of the dermatological drug manufacturing and commercialization ecosystem by evaluating active pharmaceutical ingredient sourcing, formulation technologies, manufacturing capabilities, regulatory compliance, contract manufacturing partnerships, supply chain resilience, distribution networks, and regional commercialization strategies across topical, oral, and injectable dermatology products.
Supported strategic manufacturing and commercialization planning by identifying qualified manufacturing partners, optimizing supply chain strategies, evaluating regional market access opportunities, strengthening commercialization readiness, and improving long term scalability across global dermatology markets.
Frequently Asked Questions About This Report
The global dermatological drugs market size was valued at USD 26.2 billion in 2025 and is estimated at USD 28.6 billion for 2026.
The psoriasis segment led the market with the largest 35.2% revenue share in 2025.
The prescription segment accounted for the largest 82.0% revenue share in 2025, while topical administration led the route of administration segment with a 60.3% revenue share.
The corticosteroids segment held the largest 30.2% revenue share in 2025, while retail pharmacies dominated the distribution channel with a 50.9% revenue share.
Key players include AbbVie Inc., Pfizer Inc., GSK plc., Sun Pharmaceutical Industries Ltd., GALDERMA, Amgen Inc., Johnson & Johnson Services, Inc., Novartis AG, Eli Lilly and Company, Almirall, S.A., and Bausch Health Companies Inc.
Key factors include the rising prevalence of chronic skin disorders such as acne, psoriasis, atopic dermatitis, and rosacea, increasing adoption of biologics and targeted therapies, expanding regulatory approvals, growing healthcare expenditure, and continuous innovation in topical, oral, and injectable dermatology treatments.
North America dominated the dermatological drugs market with a 38.7% revenue share in 2025.
Asia Pacific is expected to be the fastest-growing regional market over the forecast period, driven by improving healthcare infrastructure, rising awareness of skin diseases, increasing healthcare spending, and growing access to advanced dermatological therapies.
The global dermatological drugs market is expected to grow at a CAGR of 9.9% from 2026 to 2033, reaching USD 55.5 billion by 2033.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


