
- Home
- »
- Petrochemicals
- »
-
Diesel Exhaust Fluid Market Size And Share Report, 2030GVR Report cover

Diesel Exhaust Fluid Market (2025 - 2030) Size, Share & Trends Analysis Report By Vehicle (LCV, HCV), By Component (Catalyst, Sensor), By Application (Construction Equipment, Agricultural Tractor), By Region, And Segment Forecasts
Market Size, 2024
$39,112.7MMarket Estimate, 2026
$41,764.5MMarket Forecast, 2030
$61,561.5MCAGR, 2025–2030
7.9%Diesel Exhaust Fluid Market Summary
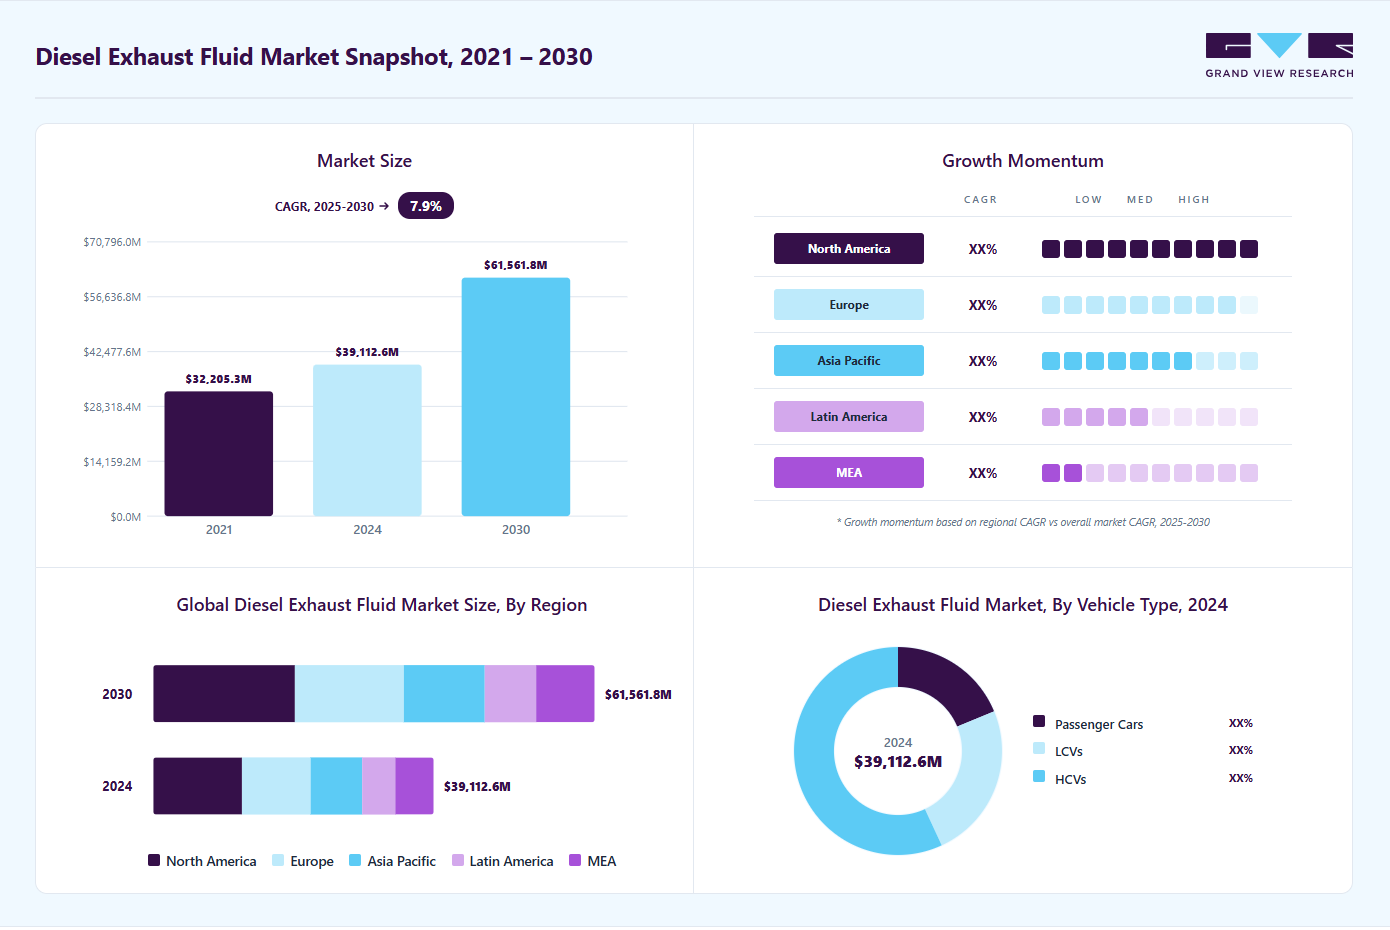
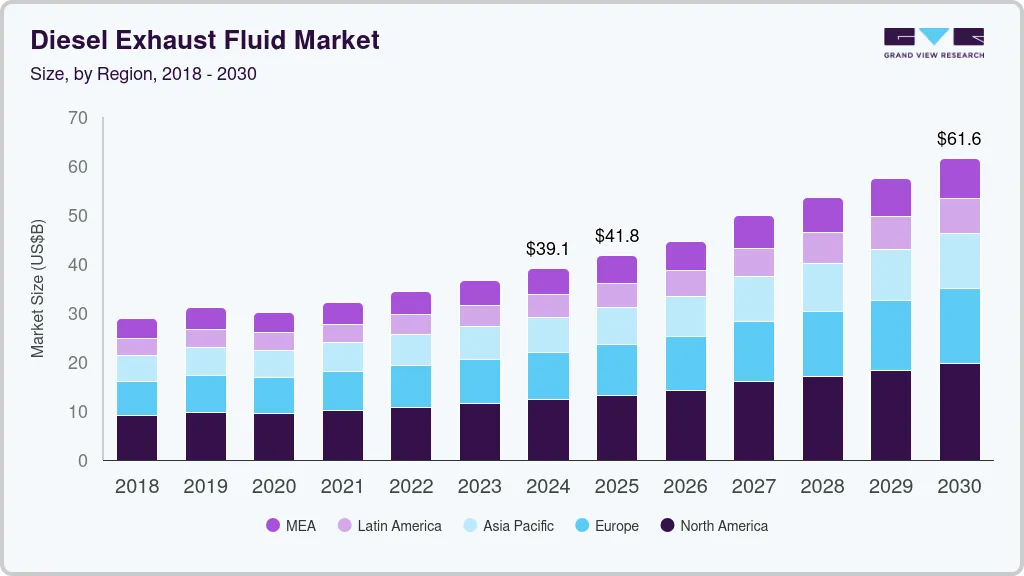
The global diesel exhaust fluid market size was estimated at USD 39,112.7 million in 2024 and is projected to reach USD 61,561.8 million by 2030, growing at a CAGR of 7.9% from 2025 to 2030. This growth is owing to its rising application in construction and agricultural equipment.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- North America diesel exhaust fluid market dominated the global market with a revenue share of 31.5% in 2023.
- The diesel exhaust fluid market in the U.S. is expanding at a significant rate.
- In terms of vehicle type, light commercial vehicles dominated the market with a revenue share of 24.3% in 2023.
- In terms of components, catalysts segment dominated the market with a revenue share of 39.7% in 2023.
- In terms of application, construction equipment segment dominated the market with a revenue share of 38.7% in 2023.
Market Size & Forecast
- 2024 Market Size: USD 39,112.7 Million
- 2030 Projected Market Size: USD 61,561.8 Million
- CAGR (2025-2030): 7.9%
- North America: Largest market in 2023
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2025–2030 annual, 2024 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The primary driver for the product market is the stringent emission regulations imposed to reduce air pollution and improve air quality. As governments worldwide enforce tighter standards for nitrogen oxide (NOx) emissions, diesel engines must incorporate Selective Catalytic Reduction (SCR) technology, which relies on DEF to function effectively. Moreover, the product helps convert NOx into harmless nitrogen and water vapor, enabling vehicles and machinery to meet regulatory requirements. Additionally, growing environmental awareness and sustainability goals across industries drive the adoption of DEF, while advancements in SCR technology and expanded distribution infrastructure further support its use.Diesel Exhaust Fluid (DEF) is mainly made up of two essential components: high-purity urea and deionized water. The quality of these ingredients is crucial for ensuring that the final product adheres to strict industry standards.
 To learn more about this report, Download Free Sample Report
Urea, which makes up 32.5% of the DEF solution, is the active component. It is usually produced from natural gas or coal through a catalytic process. For DEF production, the urea must be of very high purity, with a concentration of at least 67.5% and minimal biuret, a byproduct that can reduce DEF's effectiveness. The remaining 67.5% of DEF consists of deionized water, which has been purified to eliminate dissolved minerals and ions.
The major restraint for the product is its cost and logistical challenges associated with its storage and handling. DEF prices can fluctuate due to variations in raw material costs and transportation expenses, which can impact the overall operating costs for vehicle and equipment owners. Additionally, DEF requires proper storage conditions to prevent contamination and degradation, which adds complexity to its handling. In regions with limited infrastructure for DEF distribution or in industries with low margins, these factors can be a significant barrier.
Market Dynamics
Stringent vehicle emission regulations across major economies are one of the primary factors driving the growth of the diesel exhaust fluid market. Governments and environmental agencies worldwide have implemented increasingly rigorous standards to reduce nitrogen oxide (NOx) emissions from diesel-powered vehicles. Regulations such as Euro VI in Europe, EPA standards in the United States, Bharat Stage VI in India, and China VI standards have mandated the adoption of advanced emission control technologies in commercial vehicles, buses, agricultural equipment, and off-highway machinery. Diesel exhaust fluid plays a critical role in Selective Catalytic Reduction (SCR) systems, where it helps convert harmful nitrogen oxides into x`harmless nitrogen and water vapor, enabling vehicles to comply with these regulations.
Furthermore, continuous tightening of emission norms is encouraging fleet operators, transportation companies, and equipment manufacturers to invest in SCR-equipped diesel engines. As governments place greater emphasis on improving air quality and reducing environmental pollution, demand for diesel exhaust fluid is expected to increase alongside the growing installed base of SCR-enabled vehicles. The expansion of logistics, freight transportation, construction activities, and agricultural mechanization in emerging economies is further supporting adoption of emission-compliant diesel technologies, thereby driving sustained consumption of diesel exhaust fluid globally.
The growing adoption of electric vehicles (EVs) and alternative powertrain technologies represents a significant restraint for the diesel exhaust fluid market. Governments, automotive manufacturers, and consumers are increasingly shifting toward battery electric vehicles, hybrid vehicles, hydrogen fuel cell vehicles, and other low-emission transportation solutions to achieve decarbonization goals. Since diesel exhaust fluid is specifically required for diesel-powered engines equipped with SCR systems, the gradual replacement of diesel vehicles by alternative propulsion technologies could reduce long-term demand for DEF across several transportation segments.
In addition, many countries have announced ambitious electrification targets, incentives for EV adoption, and restrictions on internal combustion engine vehicles. Investments in charging infrastructure, advancements in battery technology, and declining EV ownership costs are accelerating this transition, particularly in passenger vehicles and urban transportation fleets. Although diesel engines are expected to remain important in heavy-duty transportation, agriculture, mining, and construction sectors for the foreseeable future, the long-term shift toward alternative powertrains may limit the growth potential of the diesel exhaust fluid market and create uncertainty regarding future demand trends.
Vehicle Type Insights
Light commercial vehicles dominated the market with a revenue share of 24.3% in 2023. The product is increasingly used in light commercial vehicles to meet stringent emissions regulations and enhance environmental performance.
In heavy commercial vehicles (HCVs), DEF serves a similar role but on a larger scale. HCVs, including trucks and buses, are subject to even stricter emissions regulations due to their higher levels of NOx emissions.
Component Insights
Catalysts dominated the market with a revenue share of 39.7% in 2023. The catalyst component of the product is crucial for the effective operation of Selective Catalytic Reduction (SCR) systems in diesel engines. DEF, primarily composed of urea and deionized water, acts as a reductant in the SCR process.
This catalytic reaction is crucial for reducing NOx emissions and meeting stringent environmental regulations. Effective emission control depends on the proper maintenance and management of the SCR catalyst to ensure optimal performance and compliance with standards.
Application Insights
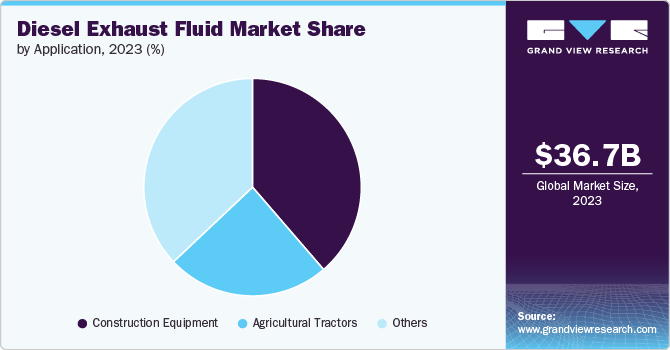
Construction equipment dominated the market with a revenue share of 38.7% in 2023 DEF. The product is essential for construction equipment to comply with modern emissions regulations, improve engine performance, and support environmental sustainability. Its application ensures that heavy machinery operates efficiently while meeting regulatory requirements, contributing to a cleaner and more sustainable construction industry.
 To learn more about this report, Download Free Sample Report
Diesel Exhaust Fluid (DEF) is critical for construction equipment as it enables compliance with stringent emissions regulations, particularly through Selective Catalytic Reduction (SCR) technology, which reduces nitrogen oxides (NOx) into harmless nitrogen and water vapor. Modern construction machines like excavators, bulldozers, and loaders use DEF to meet EPA's Tier 4 Final standards, enhancing engine efficiency and longevity while minimizing environmental impact.
DEF helps tractors meet the EPA’s Tier 4 Final emissions standards, ensuring significant reductions in air pollution. This application not only facilitates regulatory compliance but also enhances engine efficiency and longevity by optimizing combustion and reducing harmful emissions. Proper storage and regular refilling of DEF are crucial for maintaining tractor performance and sustainability in demanding agricultural operations.
Regional Insight
North America diesel exhaust fluid market dominated the global market with a revenue share of 31.5% in 2023 The construction industry in North America is expected to witness significant growth over the coming years owing to high demand for non-residential construction projects such as hospitals, commercial buildings, and colleges.
U.S. Diesel Exhaust Fluid Market Trends
The diesel exhaust fluid market in the U.S. is expanding at a significant rate owing to positive market fundamentals for commercial real estate and a strong economy, along with rising state and federal funding for institutional buildings and public works. For instance, in March 2023, the U.S. government announced an investment worth USD 2 trillion for the development of infrastructure including hospital buildings, roads, and other infrastructure. Thus the growing construction industry is further expected to increase the demand for construction equipments, further fueling the consumption for the product.
Asia Pacific Diesel Exhaust Fluid Market Trends
The diesel exhaust fluid market in Asia Pacific is growing due to the rising construction activities and growing demand from the construction sector in emerging countries, such as India, Japan, and South Korea.
As per the ITA, China was the largest construction market in the world in 2023. The 14th Five-year Plan of the country focuses on developing new infrastructures related to transportation, energy, water systems, etc. According to the same organization, an estimated USD 4.2 trillion investment is expected in new infrastructure developments in the country between 2021 and 2025. Thus, the ongoing urbanization and the increasing infrastructure development projects are expected to boost the demand for the product in the country in the coming years.
Europe Diesel Exhaust Fluid Market Trends
The diesel exhaust fluid market in Europe is expanding as the construction sector in various countries, including the UK, Germany, France, Italy, and Spain, is expected to fuel the demand for the product in Europe over the forecast period. Moreover, the construction sector in the region is expected to grow due to increased funding from the European Union (EU) , offered by governments of various countries of the region.
Key Diesel Exhaust Fluid Company Insights
Some of the key players operating in the market include Total Energies, Shell, BASF SE, Sinopec, Cummins Filtration, CF Industries Holdings, Inc., Dyno Nobel, Agrium Inc., Honeywell International Inc., and Faurecia SE. BASF SE, a leading chemical manufacturing company based in Germany, is a major player in the global chemicals industry. The company operates across six business segments: Chemicals, Surface Technologies, Materials, Nutrition & Care, Industrial Solutions, and Agricultural Solutions.
Key Diesel Exhaust Fluid Companies:
The following are the leading companies in the diesel exhaust fluid market. These companies collectively hold the largest market share and dictate industry trends.
- Total Energies
- Shell
- BASF SE
- Sinopec
- Cummins Filtration
- CF Industries Holdings, Inc.
- Dyno Nobel
- Agrium Inc.
- Honeywell International Inc.
- Faurecia SE
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weakness
Mature Players: TotalEnergies, Shell plc, BASF SE, SINOPEC, CF Industries Holdings, Inc., Honeywell International Inc.
- Focus was placed on expanding diesel exhaust fluid production capacities and strengthening supply chain integration through upstream ammonia and urea feedstock sourcing.
- Significant investments were made in emission control solutions, SCR technology support, and distribution infrastructure to meet growing DEF demand from commercial transportation and industrial sectors.
- Companies strengthened strategic partnerships with fuel retailers, fleet operators, OEMs, and industrial distributors to improve product availability and customer reach across global markets.
- Increased emphasis was placed on sustainability initiatives and regulatory compliance aligned with tightening vehicle emission standards
- Mature players benefited from extensive global manufacturing and distribution networks ensuring consistent DEF availability across key markets.
- Strong feedstock integration capabilities provided cost advantages and supply reliability during periods of urea market volatility.
- Robust financial resources and technical expertise supported investments in production expansion, logistics infrastructure, and product quality assurance.
- Established relationships with automotive OEMs, transportation fleets, and industrial customers strengthened long-term market positioning.
- High exposure to fluctuations in natural gas, ammonia, and urea prices affected overall profitability and pricing stability.
- Compliance with evolving environmental, transportation, and chemical handling regulations increased operational costs.
- Large organizational structures and global operations reduced flexibility in responding rapidly to regional market changes and niche customer requirements
Emerging Players: Cummins Filtration, Dyno Nobel, Agrium Inc., Faurecia SE
- Expansion efforts were focused on strengthening regional DEF distribution networks and developing application-specific solutions for commercial vehicles, off-highway equipment, and industrial applications.
- Companies emphasized strategic partnerships with fleet operators, service providers, and equipment manufacturers to increase market penetration.
- Investments were directed toward enhancing product accessibility, storage solutions, SCR system integration, and regional production capabilities.
- Focus remained on capturing growth opportunities in emerging transportation and industrial markets through cost-competitive offerings
- Emerging players benefited from stronger regional market presence and greater flexibility in serving localized customer requirements.
- Faster decision-making processes enabled quicker adaptation to changing emission regulations and customer needs.
- Specialized expertise in filtration systems, agricultural inputs, industrial chemicals, and vehicle technologies supported targeted market expansion strategies.
- Competitive pricing and customer-focused distribution models enhanced penetration within underserved markets
- Limited global manufacturing footprint compared to multinational market leaders restricted international expansion opportunities.
- Lower financial capability for large-scale capacity expansions and supply chain investments compared to integrated chemical and energy companies.
- Greater dependence on regional transportation and industrial activity exposed companies to localized economic and regulatory fluctuations.
- Relatively smaller brand recognition in the global DEF market limited competitiveness against established industry leaders
Recent Developments
-
In January 2022, The German Association of the Automotive Industry (VDA) awarded accreditation to CrossChem International's Hong Kong branch, authorizing it to start manufacturing AdBlue Diesel Exhaust Fluid. This certification confirms that the end product meets top-tier standards and will support the company's growth in the diesel exhaust fluid sector.
Diesel Exhaust Fluid Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 41,764.5 million
Revenue forecast in 2030
USD 61,561.5 million
Growth Rate
CAGR of 7.9% from 2025 to 2030
Actual data
2018 - 2024
Forecast period
2025 - 2030
Quantitative units
Volume in kilotons; revenue in USD million/billion and CAGR from 2025 to 2030
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, vehicle type, application, region
Regional scope
North America, Europe, Asia Pacific, Central & South America, Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; U.K.; Italy; France; Spain; China; India; Japan, South Korea; Brazil; Argentina; South Africa, Saudi Arabia
Key companies profiled
Total Energies, Shell, BASF SE, Sinopec, Cummins Filtration, CF Industries Holdings, Inc., Dyno Nobel, Agrium Inc., Honeywell International Inc., Faurecia SE
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Diesel Exhaust Fluid Market Report Segmentation
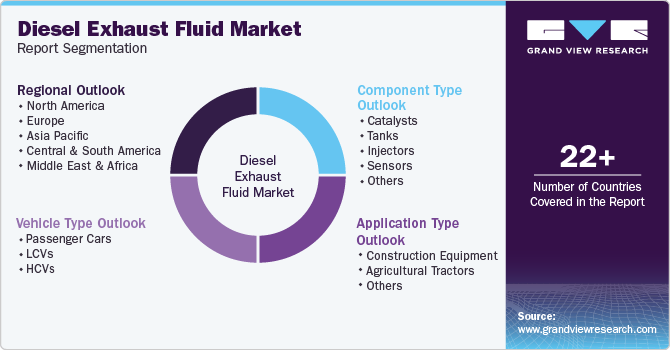
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2018 to 2030. For this study, Grand View Research has segmented the global diesel exhaust fluid market report based on vehicle type, component, application & region:
 To learn more about this report, Download Free Sample Report
-
Vehicle Type Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2030)
-
Passenger Cars
-
LCVs
-
HCVs
-
-
Component Type Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2030)
-
Catalysts
-
Tanks
-
Injectors
-
Sensors
-
Others
-
-
Application Type Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2030)
-
Construction Equipment
-
Agricultural Tractors
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2030)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Opportunity Assessment
A detailed opportunity analysis was performed focusing on growing demand from unsaturated polyester resins, polyurethane systems, plasticizers, solvents, personal care formulations, and industrial chemical applications. The study also assessed growth potential associated with infrastructure development, construction activities, automotive production, packaging materials, and specialty chemical manufacturing. Emerging opportunities related to downstream integration, developing economies, and evolving industrial demand patterns were also evaluated
Enabled identification of emerging application areas and future investment opportunities across the DEG value chain. Supported long-term growth strategy development, capacity planning, product diversification, and prioritization of high-growth regional and end-use markets
Cross-Segmentation
A detailed cross-segmentation analysis was conducted across DEG applications, end-use industries, and regional markets. The assessment evaluated demand patterns by application (UPR, plasticizers, solvents, lubricants, chemical intermediates) across construction, automotive, packaging, consumer goods, and industrial manufacturing sectors. Additional analysis highlighted region-specific growth trends, consumption patterns, and application-level market opportunities
Enabled deeper understanding of niche demand pockets, application-specific growth opportunities, and regional consumption dynamics. Supported targeted business development, investment prioritization, product positioning, and strategic decision-making across high-growth market segments.
Trade Assessment
A comprehensive trade assessment of the global DEG market was conducted, including import-export analysis by country and region, trade volume and value trends, major exporting and importing nations, tariff structures, customs regulations, and supply chain movement analysis. The study also evaluated regional production surpluses and deficits, international trade competitiveness, logistics infrastructure, and the impact of geopolitical developments on global DEG trade flows
Enabled identification of key trade corridors, sourcing dependencies, export opportunities, and regional supply-demand imbalances. Supported procurement planning, trade risk assessment, localization strategies, and distributor identification through enhanced visibility into global DEG trade dynamics
Frequently Asked Questions About This Report
The global diesel exhaust fluid market size was estimated at USD 36.66 billion in 2023 and is expected to reach USD 39.11 billion in 2024.
The global diesel exhaust fluid market is expected to grow at a compound annual growth rate of 7.9% from 2024 to 2030 to reach USD 61.56 billion by 2030.
North America dominated the diesel exhaust fluid market with a share of 31.52% in 2023. The construction industry in North America is expected to witness significant growth over the coming years owing to high demand for non-residential construction projects such as hospitals, commercial buildings, and colleges.
Some key players operating in the diesel exhaust fluid market include Total Energies, Shell, BASF SE, Sinopec, Cummins Filtration, CF Industries Holdings, Inc., Dyno Nobel, Agrium Inc., Honeywell International Inc., and Faurecia SE.
Key factors that are driving the market growth include rising application in construction and agricultural equipments.
About the Author(s)
Petrochemicals Research Team
Bulk Chemicals · PetrochemicalsThis report was authored by the petrochemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the petrochemicals segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


