
- Home
- »
- Distribution & Utilities
- »
-
Direct Air Capture Market Size And Share Report, 2026-2033GVR Report cover

Direct Air Capture Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (Solid-DAC (S-DAC), Liquid-DAC (L-DAC), Electrochemical-DAC (E-DAC)), By Application, By Region, And Segment Forecasts
Market Size, 2025
$147.0MMarket Estimate, 2026
$232.3MMarket Forecast, 2033
$3,336.4MCAGR, 2026–2033
46.3%Direct Air Capture Market Summary
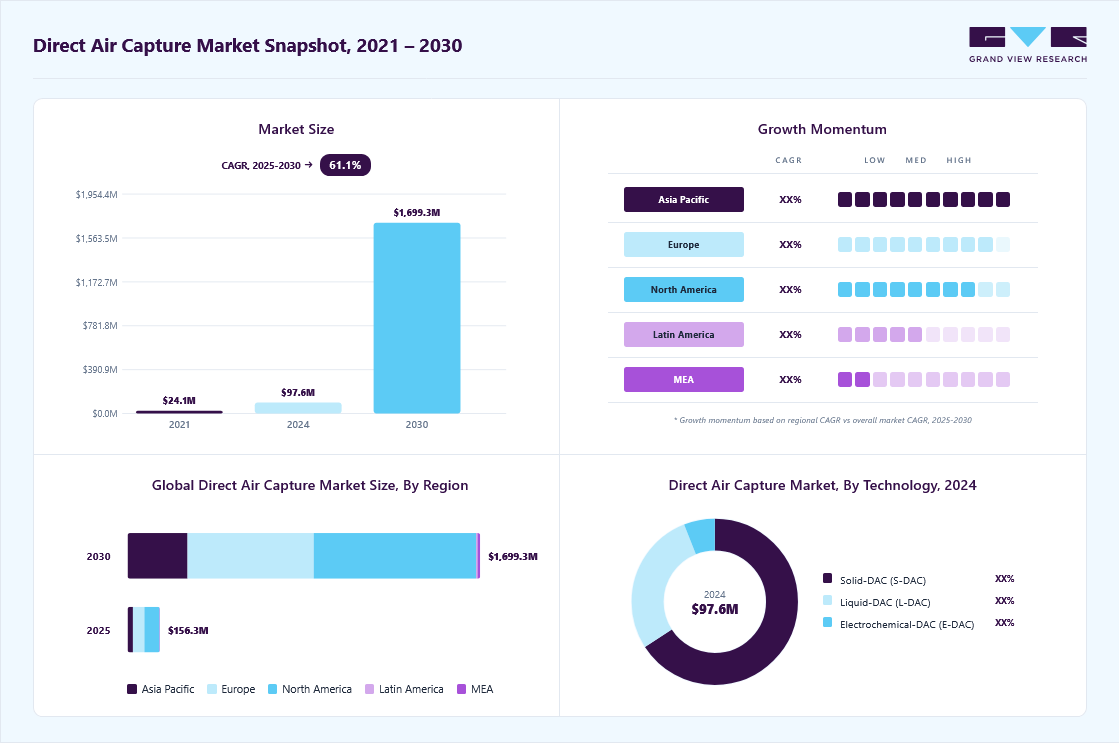
The global direct air capture market size was valued at USD 147.0 million in 2025 and is projected to grow from USD 232.3 million in 2026 to USD 3,336.4 million by 2033, at a CAGR of 46.3% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of 46.7% in 2025. The primary driver for the direct air capture (DAC) market is the increasing global awareness and urgency to mitigate climate change.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By technology: Solid-DAC segment held the largest market share of 66.6% in 2025.
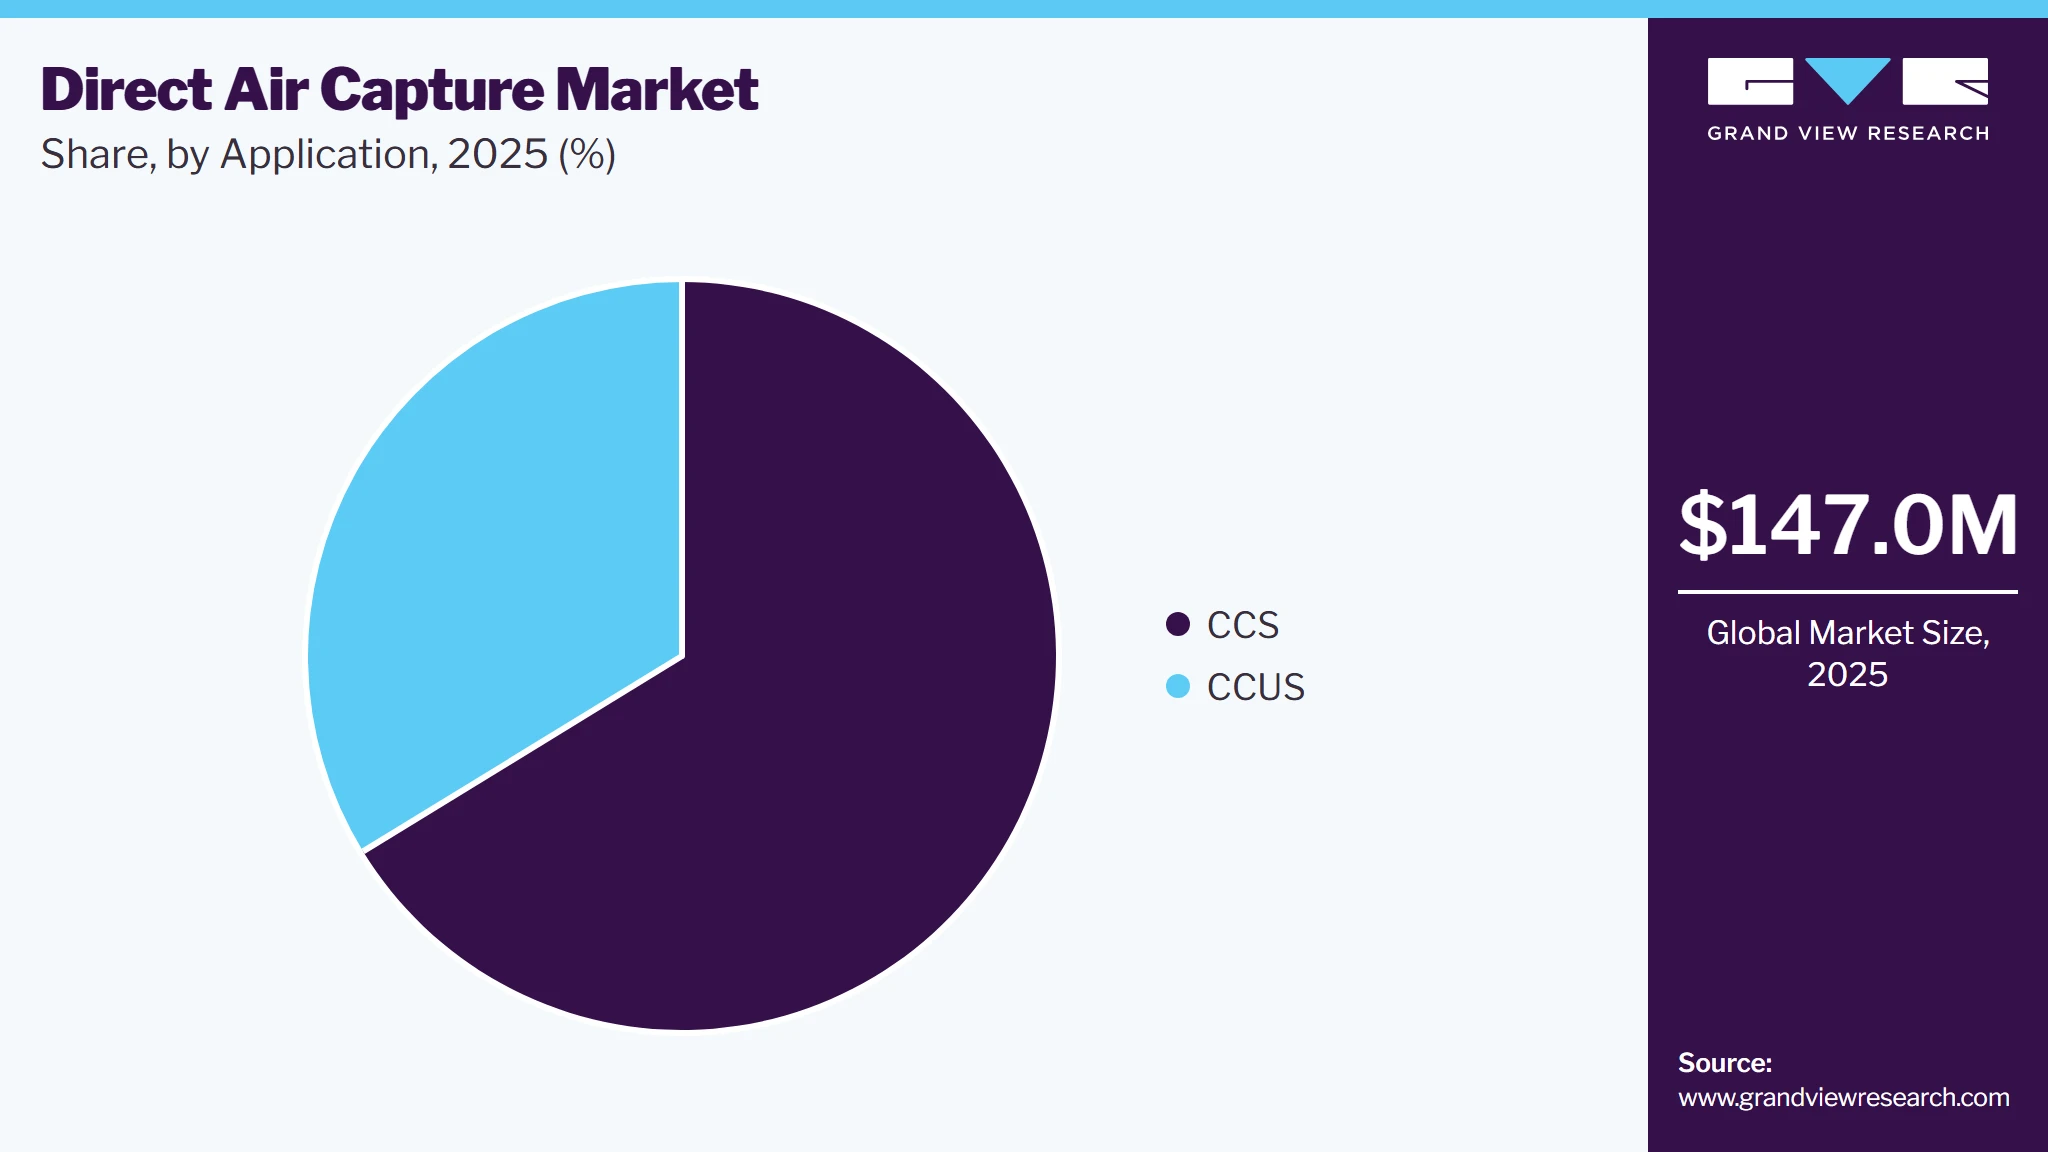
- By application: Carbon capture and storage segment led the market with the largest revenue share of 66.3% in 2025.
Regional Highlights
- Largest regional market: North America (46.7% revenue share, 2025)
- By country: The U.S. held the largest share of North America in 2025.
Market Size & Forecast
- Market Size in 2025: USD 147.0 Million
- Estimated Market Size in 2026: USD 232.3 Million
- Projected Market Size by 2033: USD 3,336.4 Million
- CAGR (2026-2033): 46.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Governments, industries, and organizations worldwide recognize the pressing need to reduce atmospheric CO₂ levels, one of the leading contributors to global warming. With the goals of the Paris Agreement aiming for net-zero emissions by mid-century, DAC technology offers a viable solution by capturing CO₂ directly from the air, which can then be stored or reused, significantly helping to offset carbon emissions. To learn more about this report, Download Free Sample Report
Governments around the world are implementing policies to support DAC technologies as part of broader decarbonization strategies. For example, carbon pricing mechanisms, such as carbon taxes and cap-and-trade programs, make DAC an attractive option for industries seeking to offset emissions. Additionally, subsidies and grants are being introduced to encourage research, development, and scaling of DAC technologies. In the United States, for instance, tax credits such as the 45Q incentive are encouraging companies to invest in DAC as part of their carbon management plans.
Market Dynamics
The direct air capture (DAC) market is growing as governments and industries seek additional solutions to reduce carbon emissions and achieve net-zero targets. DAC technology removes carbon dioxide directly from the atmosphere, making it particularly valuable for addressing hard-to-abate emissions that cannot be eliminated through conventional decarbonization measures. Growing policy support, carbon removal incentives, and corporate sustainability commitments are encouraging investments in large-scale DAC projects. However, the market continues to face challenges related to high technology costs, significant energy requirements, and the need for supporting carbon transport and storage infrastructure. Despite these barriers, ongoing technological advancements and increasing demand for verified carbon removal are expected to support the gradual expansion of the DAC market over the coming years.
Government incentives and policy support are playing a critical role in accelerating the growth of the market. Since DAC projects involve high capital costs, significant energy requirements, and long commercialization timelines, public funding programs, tax credits, grants, and carbon removal procurement initiatives help improve project economics and reduce financial risks. These incentives provide greater revenue visibility for project developers, encourage private-sector investment, and support the scale-up of commercial carbon removal infrastructure. As countries strengthen net-zero commitments and carbon management strategies, government-backed support mechanisms are becoming essential for transforming DAC from a pilot-stage technology into a commercially viable climate solution.
In April 2026, when the U.S. Department of Energy restored and retained USD 1.2 billion in federal funding for two major DAC projects, Project Cypress in Louisiana and the South Texas DAC Hub. Project Cypress is designed to capture 1 million metric tons of CO₂ annually, while the South Texas DAC Hub plans to remove 500,000 metric tons annually initially, with expansion beyond 1 million metric tons per year. The funding decision reinforced long-term government commitment to carbon removal infrastructure and improved investor confidence in large-scale DAC deployment, highlighting the significant impact of policy incentives on market growth.
The high cost and energy-intensive nature of DAC technology remain major barriers to widespread adoption. Unlike industrial carbon capture systems that collect concentrated CO₂ emissions from factories or power plants, DAC must extract carbon dioxide directly from ambient air, where CO₂ concentrations are extremely low. This requires large volumes of air to be processed using advanced sorbent materials, fans, and heat-intensive regeneration systems, resulting in significant energy consumption and operational expenses. Despite receiving continued DOE support, the South Texas DAC Hub and Project Cypress still require substantial public funding because current DAC costs remain significantly higher than most other carbon mitigation options, highlighting the technology's persistent cost and energy-intensity challenge.
The increasing adoption of net-zero commitments is creating strong demand for durable carbon removal credits that permanently remove CO₂ from the atmosphere. Unlike conventional carbon offsets, DAC-based credits offer long-term and verifiable carbon removal, making them attractive to corporations seeking high-integrity climate solutions. Large organizations are increasingly entering into multi-year carbon removal purchase agreements to meet voluntary and regulatory climate targets. This growing buyer confidence is improving project bankability, attracting investment, and creating significant commercial opportunities for DAC technology developers and project operators.
Analyst Perspective
The direct air capture (DAC) market is gaining significant traction as organizations increasingly seek permanent carbon removal solutions to achieve net-zero and broader climate commitments. Rising investments from governments, energy companies, and corporate carbon credit buyers, supported by favorable policy incentives, are accelerating the commercialization of DAC technologies. The market is witnessing a growing number of long-term carbon removal purchase agreements and large-scale project developments, reflecting stronger confidence in DAC as a viable decarbonization pathway. Although high capture costs and substantial energy requirements remain key challenges, ongoing technological advancements and scaling efforts are expected to improve cost efficiency, enhance commercial viability, and support long-term market growth.
Drivers, Opportunities & Restraints
One of the primary drivers of the Direct Air Capture (DAC) market is the global need to address climate change. DAC technology offers a method to capture carbon dioxide (CO₂) directly from the atmosphere, which is critical in reducing global greenhouse gas concentrations. Countries and industries worldwide are setting ambitious carbon reduction goals, such as achieving net-zero emissions by 2050, in line with international climate agreements. DAC is seen as an essential tool in achieving these targets, especially for sectors where reducing emissions is otherwise difficult.
Many corporations, particularly those in high-emission industries such as oil and gas, aviation, and manufacturing, are investing in DAC technologies as part of their sustainability and decarbonization strategies. With growing pressure from investors, regulators, and consumers, these companies are looking for ways to offset their carbon footprint. DAC offers a solution for capturing carbon that can be stored or utilized, helping companies meet their environmental goals while maintaining operational flexibility in hard-to-decarbonize areas.
One of the main restraints of the direct air capture (DAC) market is the high cost of operation, largely due to its energy-intensive processes. DAC systems require significant energy input to capture CO₂ from the atmosphere, particularly in comparison to point-source capture technologies like those used in industrial processes. This energy demand often results in higher operational costs, which can make DAC less economically attractive. Additionally, the cost of renewable energy or carbon-free electricity, necessary for making DAC truly sustainable, adds to the overall expenses.
The DAC market offers opportunities for transforming captured CO₂ into valuable products, creating new economic avenues. Captured carbon can be used in a variety of applications, such as the production of sustainable synthetic fuels, polymers, and construction materials like carbon-cured concrete. These carbon-to-value processes allow companies to not only reduce their carbon footprint but also generate new revenue streams from the captured CO₂. As demand grows for sustainable alternatives to traditional materials, DAC technology can be a key enabler of carbon utilization, driving its market appeal.
Technology Insights
Based on technology, the solid-DAC (S-DAC) segment led the market with the largest revenue share of 66.6% in 2025. Solid direct air capture (DAC) utilizes solid sorbents, such as porous materials or chemical agents, to selectively capture CO₂ from ambient air. These solid materials have high surface areas, enabling them to efficiently absorb carbon dioxide when air is passed over them. One of the key trends in the solid DAC market is the focus on developing and optimizing new materials that can enhance CO₂ capture capacity while reducing costs. Researchers are working on advanced solid sorbents that not only have higher adsorption rates but are also more durable, allowing for longer operational lifespans and reduced maintenance costs. Another emerging trend is the integration of renewable energy sources, such as solar and wind, into solid DAC systems to further reduce their carbon footprint. This alignment with clean energy trends makes solid DAC an increasingly attractive solution for sustainable carbon removal efforts.
The liquid DAC market is expected to see significant growth, driven by increasing demand for carbon removal solutions across industries such as energy, manufacturing, and aviation. As industries face mounting pressure to meet carbon reduction targets, liquid DAC presents a scalable and efficient solution for capturing atmospheric CO₂. The potential to reuse captured CO₂ in industrial processes or convert it into valuable products, such as synthetic fuels and chemicals, is another factor driving interest in the liquid DAC segment. The market outlook for liquid DAC is positive, with continued government support, corporate investments, and technological advancements positioning it as a critical component in the global carbon removal landscape.
Application Insights
Based on application, the carbon capture and storage (CCS) segment led the market with the largest revenue share of 66.3% in 2025. The increasing regulatory pressure to curb greenhouse gas emissions is a significant driver of the CCS segment. Governments are implementing stricter emissions targets, carbon pricing, and cap-and-trade programs, pushing industries to adopt carbon capture technologies to meet compliance. Furthermore, growing corporate sustainability commitments and the need to offset hard-to-abate emissions in sectors such as energy, cement, and steel are fueling demand for CCS solutions. Government incentives, such as the U.S. 45Q tax credit, which rewards companies for sequestering CO₂, also incentivize investment in CCS infrastructure and deployment.
 To learn more about this report, Download Free Sample Report
Technological innovations in carbon capture and storage processes are improving the efficiency and cost-effectiveness of CCUS systems. In the DAC market, advancements in material science, energy-efficient capture methods, and scalable deployment are reducing the overall cost of capturing CO₂ directly from the atmosphere. Additionally, trends show that captured CO₂ is increasingly being integrated into new products and markets. Carbon utilization is becoming a growing trend in industries like synthetic fuel production, concrete manufacturing, and agriculture, where captured carbon is used as a raw material. This integration of CCUS technologies into industrial supply chains is reshaping how businesses approach sustainability and carbon management.
Regional Insights
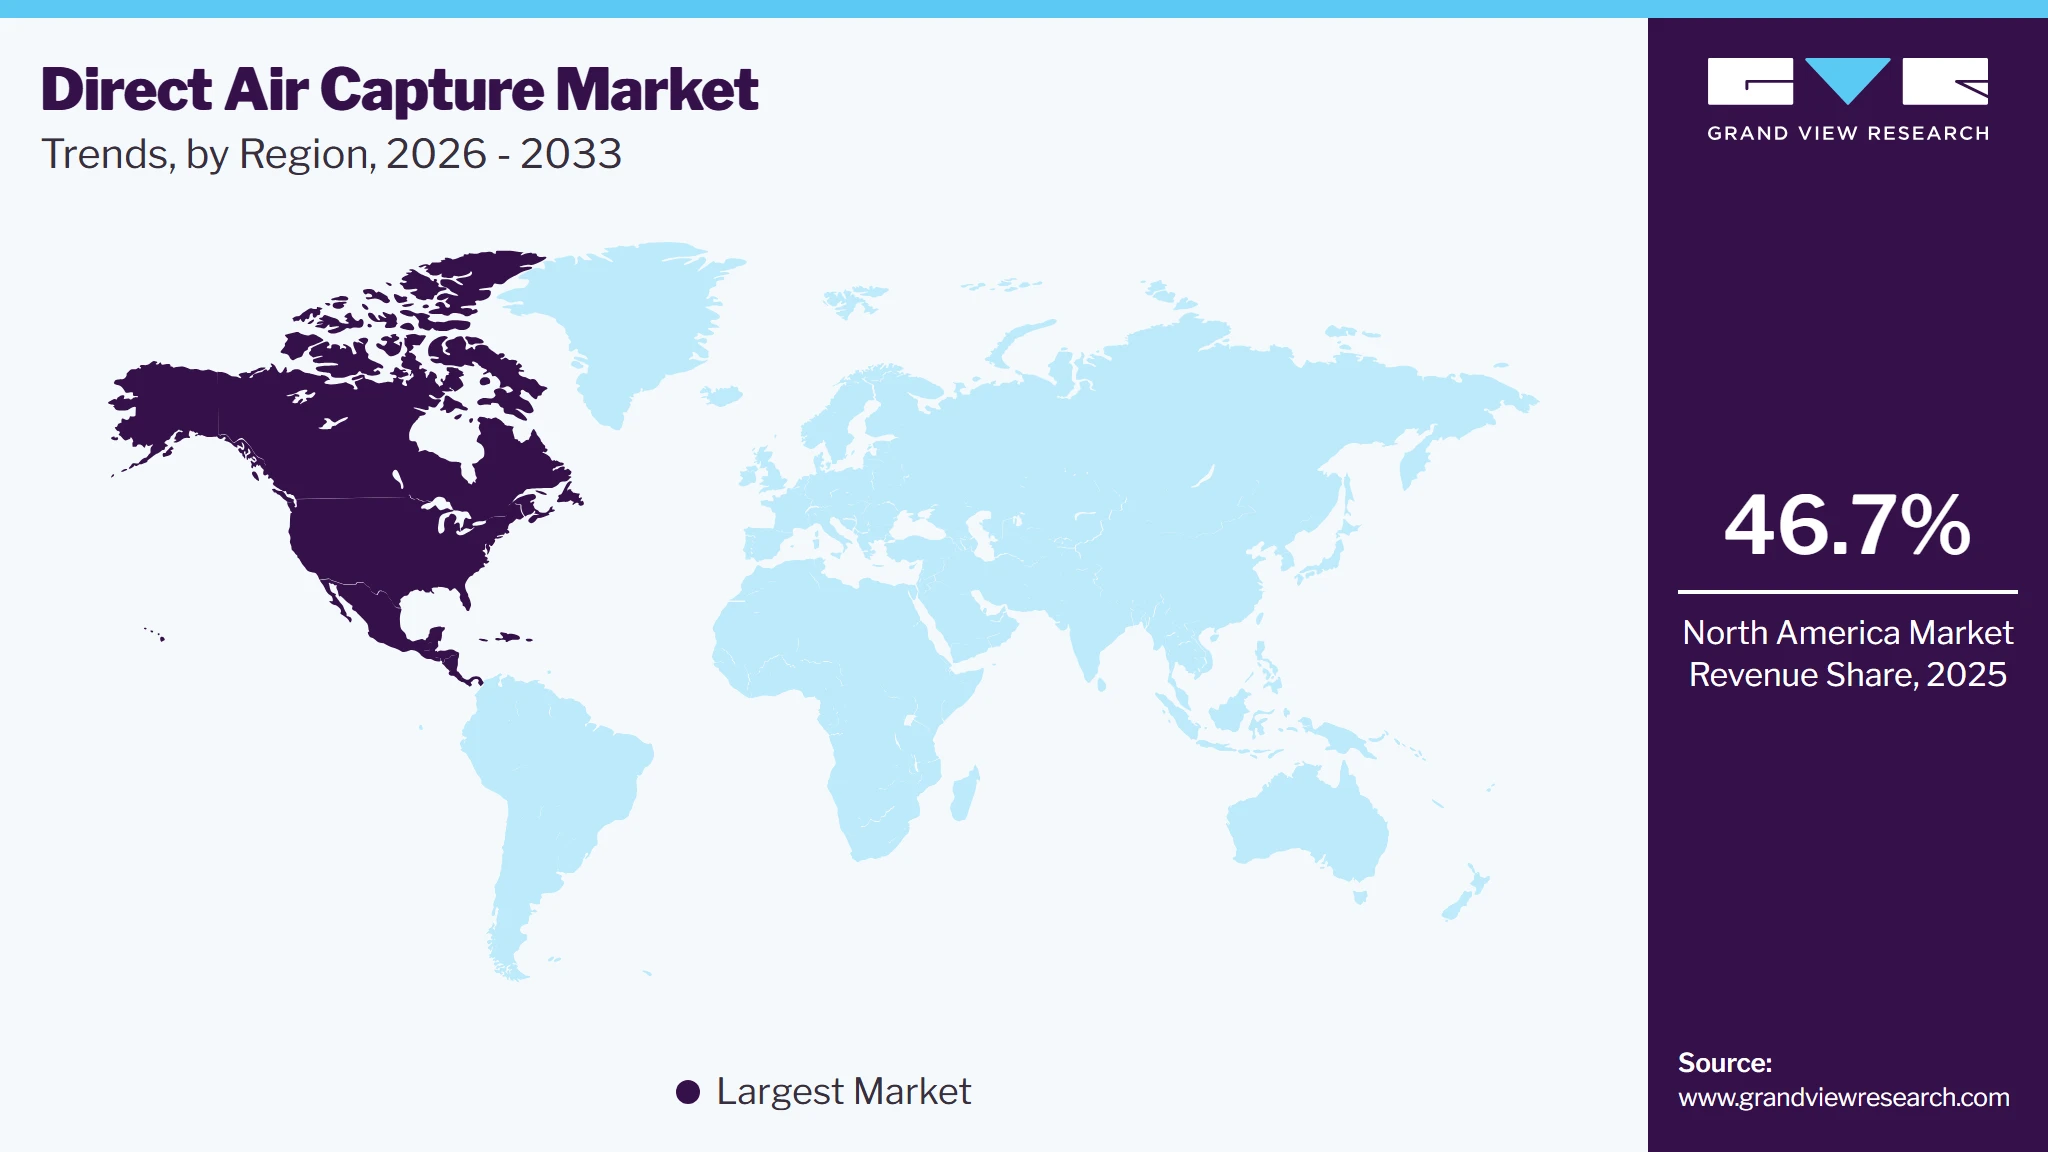
North America dominated the direct air capture market with the largest revenue share of 46.7% in 2025. The North America Direct Air Capture market is driven by a combination of technological advancements, substantial investments, and supportive policy frameworks. The region benefits from a robust infrastructure that facilitates the deployment and scaling of DAC technologies. Key drivers include substantial government funding and incentives aimed at reducing carbon emissions and meeting climate targets. The United States and Canada have introduced various initiatives, such as tax credits and grants, to encourage the development and commercialization of DAC solutions. Additionally, North American corporations are increasingly investing in DAC as part of their sustainability strategies to mitigate their carbon footprints. The presence of leading technology providers and research institutions in the region further accelerates innovation and adoption of DAC technologies. As climate policies tighten and the demand for carbon removal solutions grows, North America is well-positioned to maintain its leadership in the DAC market.
 To learn more about this report, Download Free Sample Report
The direct air capture (DAC) market in North America is experiencing robust growth driven by increasing environmental regulations, technological advancements, and rising investments in sustainable technologies. As concerns about climate change intensify, there is a growing demand for technologies that can effectively reduce atmospheric CO₂ levels. Government incentives and funding programs aimed at mitigating carbon emissions are fueling innovation and adoption of DAC technologies.
U.S. Direct Air Capture Market Trends
The direct air capture market in U.S. held the largest share in the North America region in 2025. The U.S. direct air capture (DAC) market is rapidly evolving, driven by a combination of technological advancements, regulatory support, and growing environmental awareness. DAC technology, which involves capturing carbon dioxide (CO2) directly from the atmosphere and either reusing it or storing it underground, is gaining traction as a crucial component in achieving net-zero emissions targets.
Europe Direct Air Capture Market Trends
The direct air capture market in Europe is experiencing rapid growth driven by a combination of regulatory support, technological advancements, and increasing climate commitments. Key drivers include stringent EU climate policies aimed at achieving carbon neutrality by 2050, which have spurred investments in DAC technologies as a crucial component of carbon removal strategies. The European Union's Green Deal and carbon pricing mechanisms are incentivizing both public and private sectors to fund DAC projects and research.
The direct air capture (DAC) market in Germany is gaining traction due to a combination of regulatory, economic, and technological drivers. As Germany strives to meet its ambitious climate targets, the country is investing heavily in DAC technology as a crucial component of its carbon removal strategy. Key drivers of this market include Germany’s stringent climate policies, which aim for carbon neutrality by 2045, and substantial government funding for research and development in climate technology. Additionally, the growing emphasis on reducing industrial emissions and offsetting unavoidable carbon footprints is propelling the adoption of DAC systems.
The UK direct air capture (DAC) market is rapidly evolving, driven by a combination of policy support, technological advancements, and growing awareness of climate change. The UK's commitment to achieving net-zero emissions by 2050 has significantly accelerated investments in DAC technologies, which are seen as crucial for offsetting residual emissions. Government policies, such as subsidies, tax incentives, and funding for research and development, play a pivotal role in stimulating market growth.
Asia Pacific Direct Air Capture Market Trends
The direct air capture (DAC) market in the Asia Pacific region is poised for significant growth, driven by a confluence of regulatory, economic, and technological factors. Governments across the region are increasingly prioritizing climate action, with policies and incentives aimed at reducing carbon emissions and achieving net-zero targets. This regulatory push is fostering an environment conducive to DAC technologies, which capture CO2 directly from the atmosphere and offer a viable solution for mitigating climate change.
China's direct air capture market is the largest in the Asia Pacific region, driven by robust growth driven by the country’s commitment to addressing climate change and advancing its technological capabilities. As one of the largest emitters of greenhouse gases globally, China’s focus on DAC reflects its strategic goal of achieving carbon neutrality by 2060.
The direct air capture market in Japan is driven by the country's commitment to decarbonize decarbonizing its industrial sectors and energy production, alongside substantial investments in research and development, is driving innovation and cost reduction in DAC technologies. The country's high energy consumption and reliance on fossil fuels accentuate the need for effective carbon removal solutions, further boosting the market.
Central & South America Direct Air Capture Market Trends
The direct air capture (DAC) market in Central and South America is evolving, driven by a confluence of regional and global factors that underscore the urgency of addressing climate change. DAC technology, which involves capturing carbon dioxide directly from the atmosphere, is gaining traction in these regions due to increasing environmental awareness, supportive governmental policies, and the growing need to meet international climate targets.
Middle East & Africa Direct Air Capture Market Trends
The direct air capture market in the Middle East and Africa is driven by regulatory commitments, industrial emissions, and energy transition goals, supported by technological advancements and investment opportunities. The region's focus on climate action and sustainable development is likely to further accelerate the adoption of DAC technologies in the coming years.
Key Direct Air Capture Company Insights
The direct air capture (DAC) market is characterized by a competitive and rapidly evolving landscape, driven by technological advancements, strategic investments, and increasing global emphasis on climate action. Key players in the DAC market, such as Climeworks, Carbon Engineering, and Carbon Clean Solutions, are at the forefront of technological innovation. These companies are pioneering advanced DAC technologies and large-scale facilities that capture CO2 directly from the atmosphere. Their leadership is defined by their ability to develop efficient, scalable solutions and secure significant investments for ongoing research and development
Key Direct Air Capture Companies
The following key companies have been profiled for this study on the direct air capture (DAC) market.
-
Climeworks
-
Carbon Engineering ULC.
-
Global thermostat
-
Heirloom Carbon Technologies
-
Soletair Power
-
CarbonCapture Inc
-
Avnos, Inc.
-
Noya PBC
-
Skytree
-
RepAir
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Climeworks, 1PointFive, Zero Carbon Systems, Deep Sky)
- Develop and operate large-scale commercial DAC facilities supported by long-term carbon removal agreements.
- Form partnerships with governments, energy companies, and industrial stakeholders to accelerate project deployment.
- Focus on scaling carbon removal capacity while reducing capture costs through process optimization and infrastructure expansion.
- Proven commercial deployments and operational experience in real-world DAC projects.
- Strong access to capital, strategic investors, and long-term offtake contracts.
- Greater credibility with corporate carbon removal buyers and policymakers.
- High capital requirements for project development and facility expansion.
- Longer deployment timelines due to permitting, infrastructure, and storage requirements.
- Significant dependence on policy support and carbon credit market development to achieve profitability.
Emerging Players (Heirloom Carbon Technologies, Soletair Power, CarbonCapture Inc., Avnos, Inc., Skytree, RepAir)
- Develop innovative capture technologies aimed at improving efficiency and lowering energy consumption.
- Focus on pilot projects, technology demonstrations, and strategic partnerships to validate commercial viability.
- Target niche applications and modular deployment models to accelerate market entry.
- Greater flexibility to introduce novel technologies and business models.
- Potential to achieve lower operating costs through next-generation capture processes.
- Faster innovation cycles compared to larger, more established competitors.
- Limited commercial track record and smaller operational scale.
- Dependence on external funding to support technology development and scale-up activities.
- Higher technology and commercialization risks compared to established market participants.
Recent Developments
-
In June 2024, RepAir along with EnEarth, the specialist Carbon Storage & Environmental Services subsidiary of Energean signed an agreement to use RepAir's DAC technology to capture CO2 and store it in the Prinos saline aquifer in Kavala, Greece. The project is expected to resume in early 2026 to store carbon dioxide.
-
In September 2024, 1PointFive announced an agreement with Microsoft to sell 500,000 metric tons of carbon dioxide removal (CDR) enabled by Direct Air Capture (DAC) technology.
Direct Air Capture Market Report Scope
Report Attribute
Details
Market Definition
The global Direct Air Capture (DAC) market represents the revenue generated from technologies used to capture carbon dioxide directly from the atmosphere and deliver it for storage or further utilization.
Market size in 2025
USD 147.0 million
Estimated Market size in 2026
USD 232.3 million
Projected Market size by 2033
USD 3,336.4 million
Growth rate
CAGR of 46.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Technology, Application, Region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; Spain; UK; France; Italy; Russia; China; India; Japan; Australia; Brazil; Argentina; Saudi Arabia; South Africa; UAE
Key companies profiled
Climeworks, 1PointFive, Zero Carbon Systems, Heirloom Carbon Technologies, Soletair Power, CarbonCapture Inc., Avnos, Inc., Skytree, RepAir, Deep Sky
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Direct Air Capture Market Report Segmentation
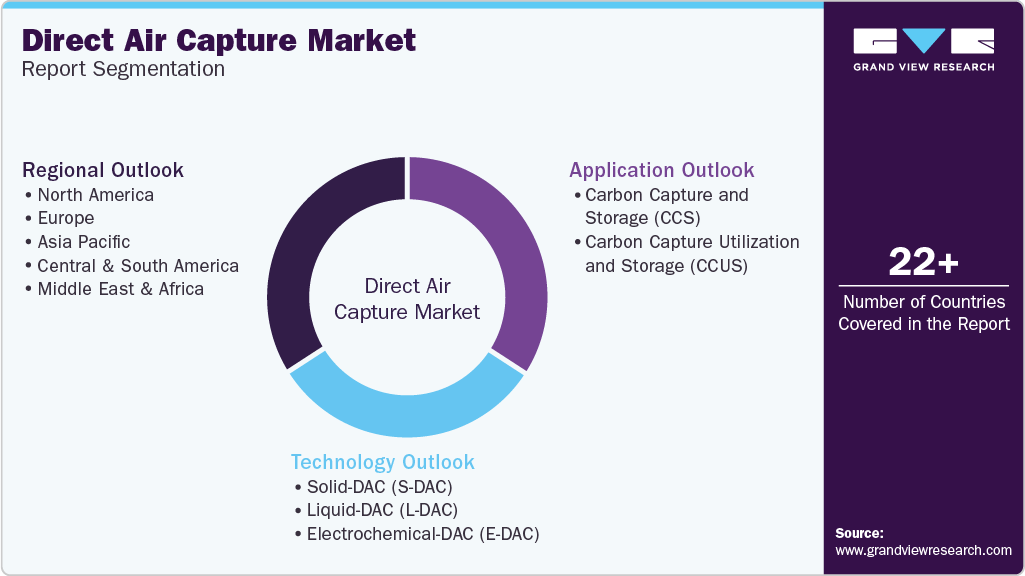
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global direct air capture market report on the basis of technology, application, and region:
 To learn more about this report, Download Free Sample Report
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Solid-DAC (S-DAC)
-
Liquid-DAC (L-DAC)
-
Electrochemical-DAC (E-DAC)
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Carbon Capture and Storage (CCS)
-
Carbon Capture Utilization and Storage (CCUS)
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Italy
-
Spain
-
France
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
-
Research Methodology
The direct air capture market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each direct air capture segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Technology
Revenue capture definition
Solid-DAC (S-DAC)
Solid-DAC technology uses solid sorbent materials to capture carbon dioxide directly from ambient air through adsorption and regeneration processes. Revenue is generated through the sale and operation of solid sorbent-based DAC systems, carbon removal services, and captured CO₂ supplied for storage or utilization applications.
Liquid-DAC (L-DAC)
Liquid-DAC technology captures carbon dioxide from the atmosphere using liquid chemical solvents that absorb CO₂ and release it during regeneration. Revenue is generated through the deployment and operation of solvent-based DAC facilities, carbon removal services, and the supply of captured CO₂ for storage or industrial use.
Electrochemical-DAC (E-DAC)
Electrochemical-DAC technology removes carbon dioxide from ambient air using electrochemical processes that separate and concentrate CO₂ with reduced thermal energy requirements. Revenue is generated through the operation of electrochemical DAC systems, carbon removal credits, and the sale of captured CO₂ for storage and utilization purposes.
Application
Revenue capture definition
Carbon Capture and Storage (CCS)
Directly captured carbon dioxide is permanently stored in geological formations to achieve long-term carbon removal and emissions mitigation. Revenue is generated through carbon removal services, storage contracts, carbon credit sales, and associated sequestration activities.
Carbon Capture Utilization and Storage (CCUS)
Directly captured carbon dioxide is utilized as a feedstock in industrial processes, fuels, chemicals, building materials, and other applications before or alongside permanent storage. Revenue is generated through the sale of captured CO₂, carbon utilization products, carbon removal services, and storage-related activities.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
DAC Capacity Development Layer
What forms the deployment base for direct air capture?
Identify existing and planned DAC facilities worldwide and assess installed and announced CO₂ capture capacities (tons/year). Evaluate government funding, carbon removal commitments, project pipelines, and investments supporting the deployment of DAC infrastructure.
02
Technology Adoption Layer
Which DAC technologies are being deployed?
Evaluate the adoption of Solid-DAC (S-DAC), Liquid-DAC (L-DAC), and Electrochemical-DAC (E-DAC) technologies across commercial and pilot-scale projects. Assess capture efficiency, energy requirements, scalability, and commercial readiness to determine the market share of each technology segment.
03
CO₂ Destination Layer
How is CO₂ allocated across storage and utilization applications?
Analyze the allocation of captured CO₂ across Carbon Capture and Storage (CCS) and Carbon Capture Utilization and Storage (CCUS) applications. Assess storage capacity, utilization pathways, carbon transport infrastructure, and end-user demand to determine application-level adoption and market penetration.
04
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the deployment and operation of technologies used to remove carbon dioxide directly from the atmosphere. The overall market value is determined by the adoption of different capture technologies, the volume of CO₂ removed, and the allocation of captured carbon across storage and utilization applications, which collectively drive revenue generation within the market.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Technology Benchmarking Assessment
Compared DAC technologies based on capture efficiency, energy requirements, scalability, technology maturity, and commercial deployment status. Assessed their relative strengths, limitations, and suitability for large-scale carbon removal projects.
Helped identify the most competitive technologies and evaluate long-term commercialization potential.
Competitive Landscape Assessment
Analyzed key market participants based on technology portfolio, project capacity, funding activities, partnerships, and expansion strategies. Evaluated competitive positioning across established and emerging DAC companies.
Enabled benchmarking of competitors and identification of strategic growth opportunities.
Regional Deployment & Policy Assessment
Assessed regional DAC deployment trends, project pipelines, carbon storage infrastructure, and policy support mechanisms. Evaluated the impact of incentives, regulations, and funding programs on market development.
Helped identify attractive investment regions and understand policy-driven growth opportunities.
Frequently Asked Questions About This Report
The global direct air capture market size was estimated at USD 147.0 million in 2025 and is expected to reach USD 232.3 million in 2026.
U.S. dominated the North America region market with a revenue share of 68.6% in 2025.
Asia Pacific is anticipated to register the fastest CAGR of 47.0% over the forecast period.
Based on technology, the Solid-DAC (S-DAC) segment accounted for largest revenue share of 66.6% in 2025.
Based on application, the Carbon Capture and Storage (CCS) segment accounted for largest revenue share of 66.3% in 2025.
The direct air capture market is expected to grow at a CAGR of 46.3% from 2026 to 2033 to reach USD 3.3 billion by 2033.
The North America region dominated the direct air capture market with a revenue share of 46.7% in 2025.
Some of the key players operating in the direct air capture market are Climeworks, 1PointFive, Zero Carbon Systems, Heirloom Carbon Technologies, Soletair Power, CarbonCapture Inc., Avnos, Inc., Skytree, RepAir, Deep Sky, and others.
The direct air capture market is primarily driven by increasing net-zero commitments from corporations and governments, along with rising demand for high-quality carbon removal solutions. Growing policy support, carbon credit markets, and investments in carbon management technologies are further accelerating market growth.
About the Author(s)
Distribution & Utilities Research Team
Energy & Power · Distribution & UtilitiesThis report was authored by the distribution & utilities research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the distribution & utilities segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


