
- Home
- »
- Advanced Interior Materials
- »
-
Direct To Shape Printer Market Size & Share Report, 2033GVR Report cover

Direct To Shape Printer Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (Inkjet, Laser), By Type (Single Pass, Multi Pass), By Ink Type (UV-based, Solvent-based, Aqueous-based), By End-use (Electronics, Toys & Sporting Goods), By Region, And Segment Forecasts
Market Size, 2025
$3.2BMarket Estimate, 2026
$3.6BMarket Forecast, 2033
$7.3BCAGR, 2026–2033
10.7%Direct To Shape Printer Market Summary
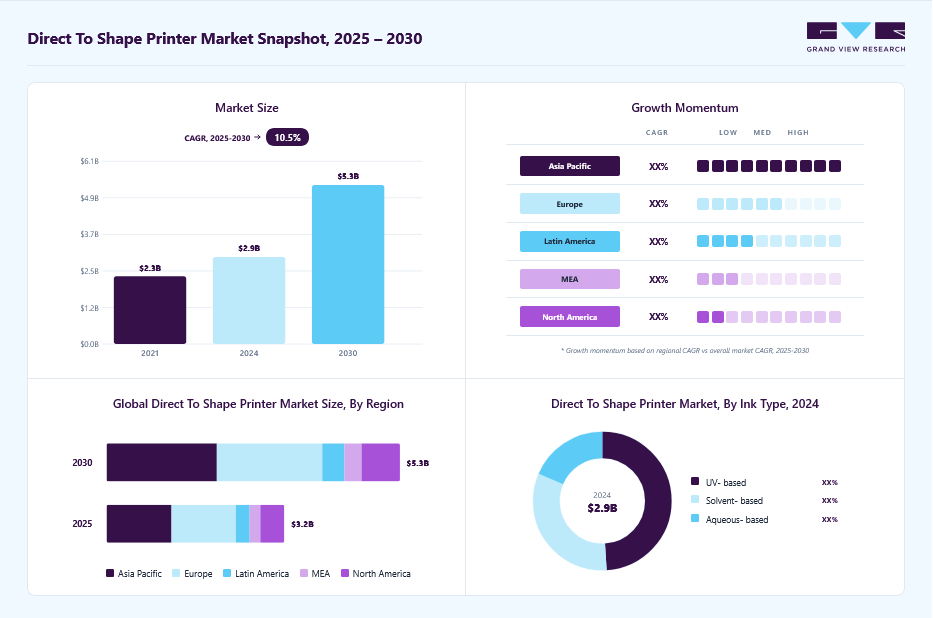
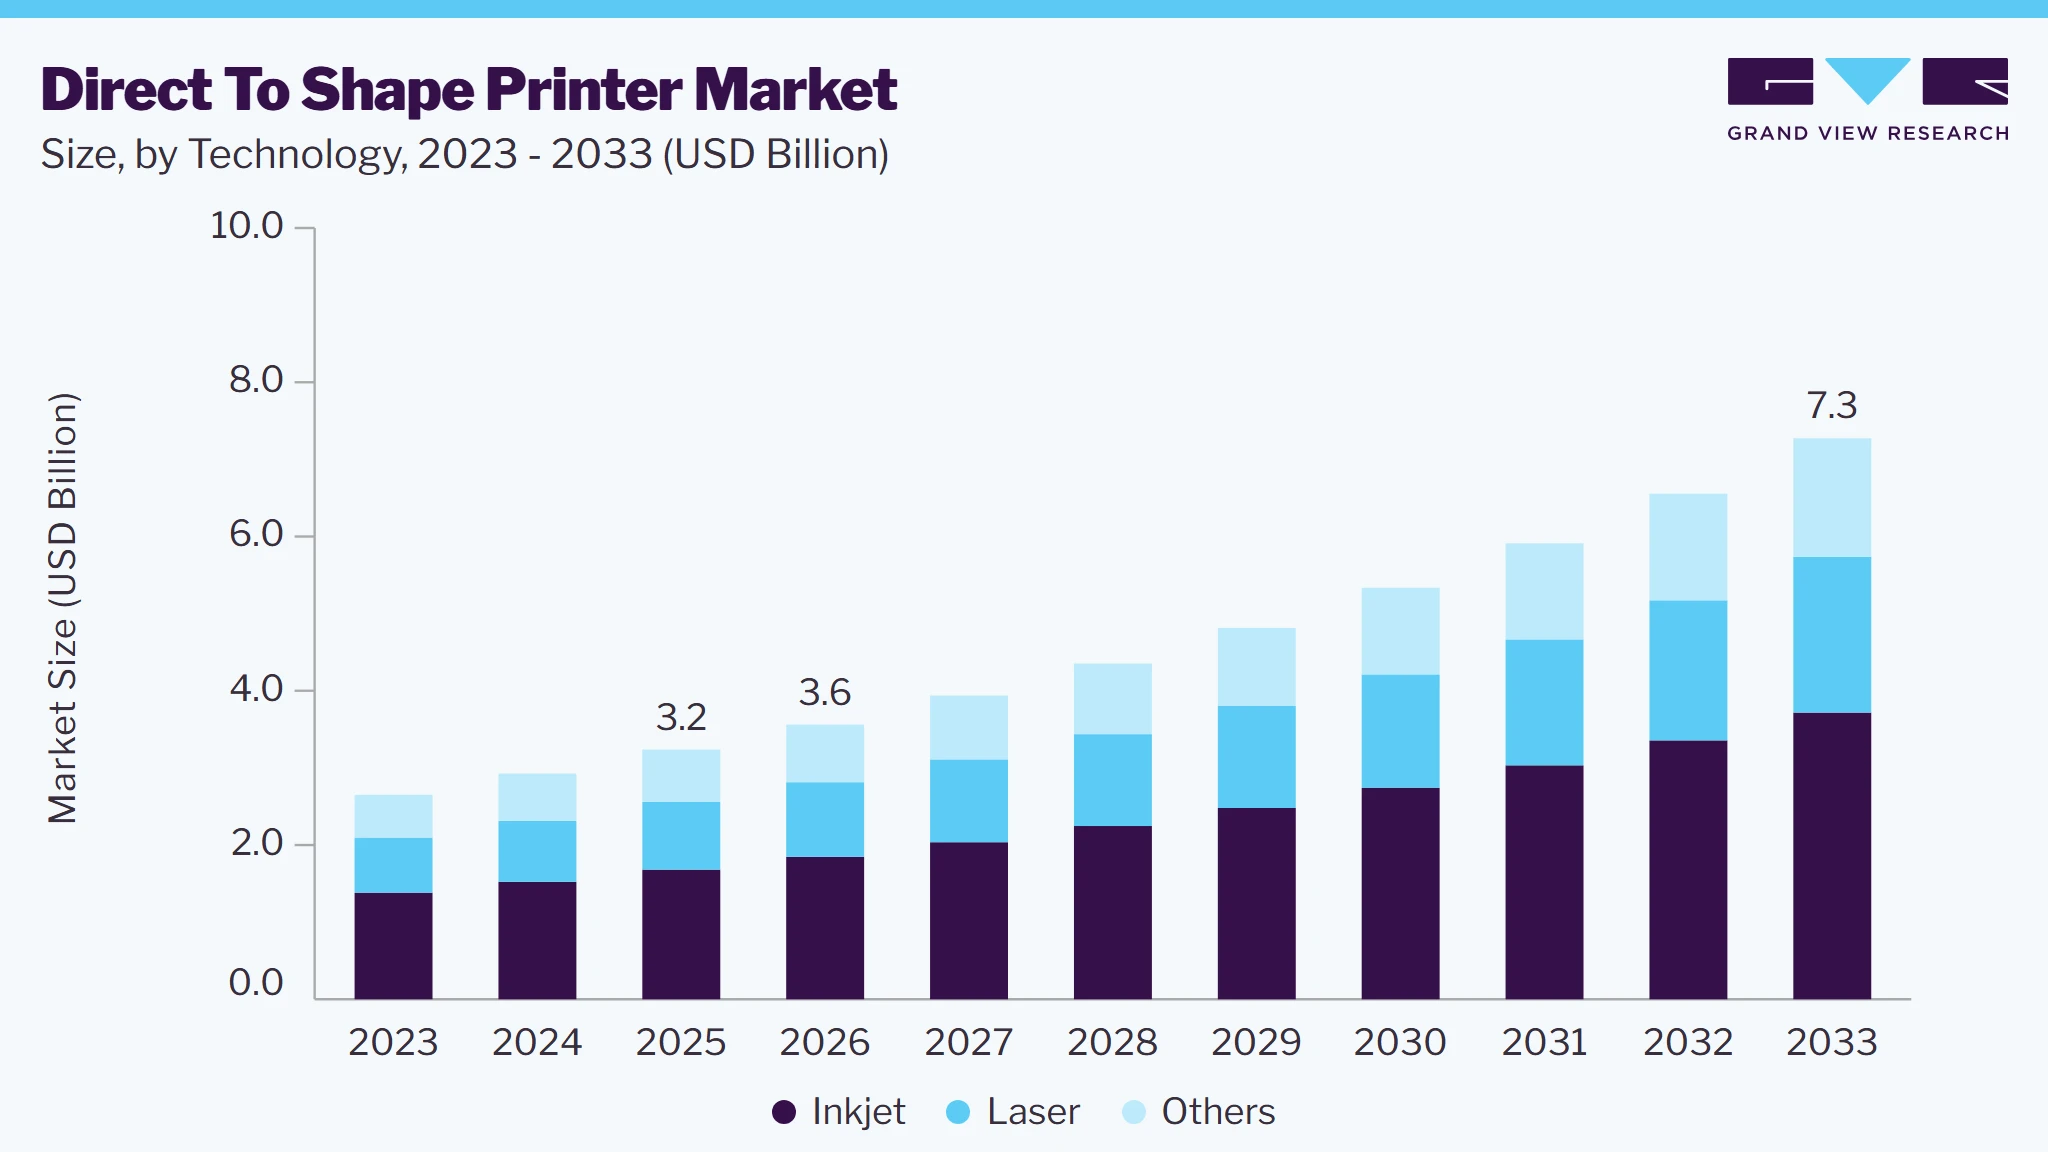
The global direct to shape printer market size was valued at USD 3.2 billion in 2025 and is projected to grow from USD 3.6 billion in 2026 to USD 7.3 billion by 2033, growing at a CAGR of 10.7% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest global share of 36.6% in 2025. A key driver fostering market growth is the increasing demand for customized products, which direct to shape printers can efficiently produce. Additionally, advancements in 3D printing technology have led to improved print quality and speed, making the process more appealing to various industries.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By technology: Inkjet segment led the market with the largest revenue share of 51.9% in 2025.
- By ink type: UV- based segment led the market with the largest revenue share of 49.0% in 2025.
- By type: Multi pass segment led the market with the largest revenue share of 75.4% in 2025.
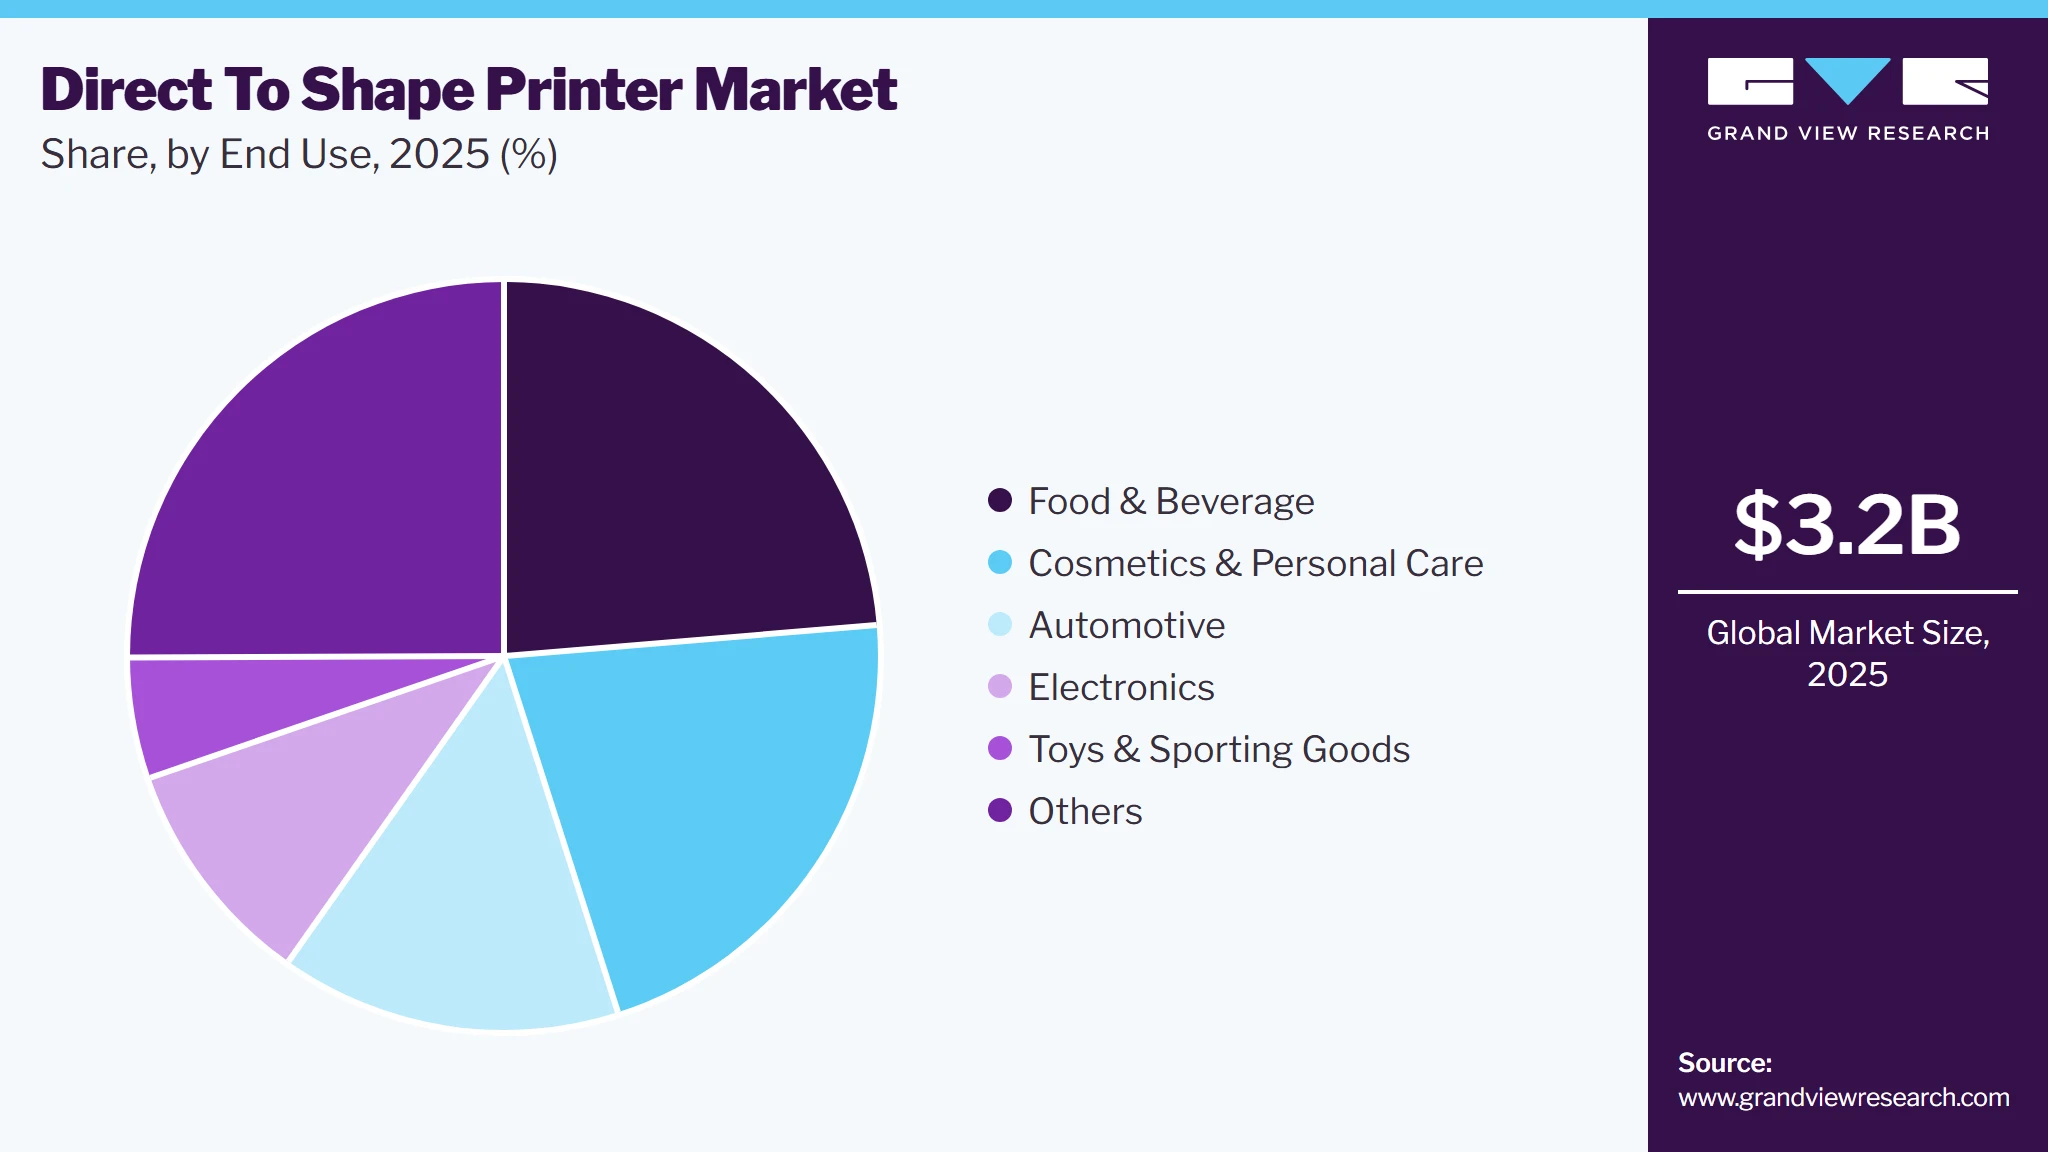
- By end-use: Food & beverage segment led the market with the largest share of 23.7% in 2025.
Regional Highlights
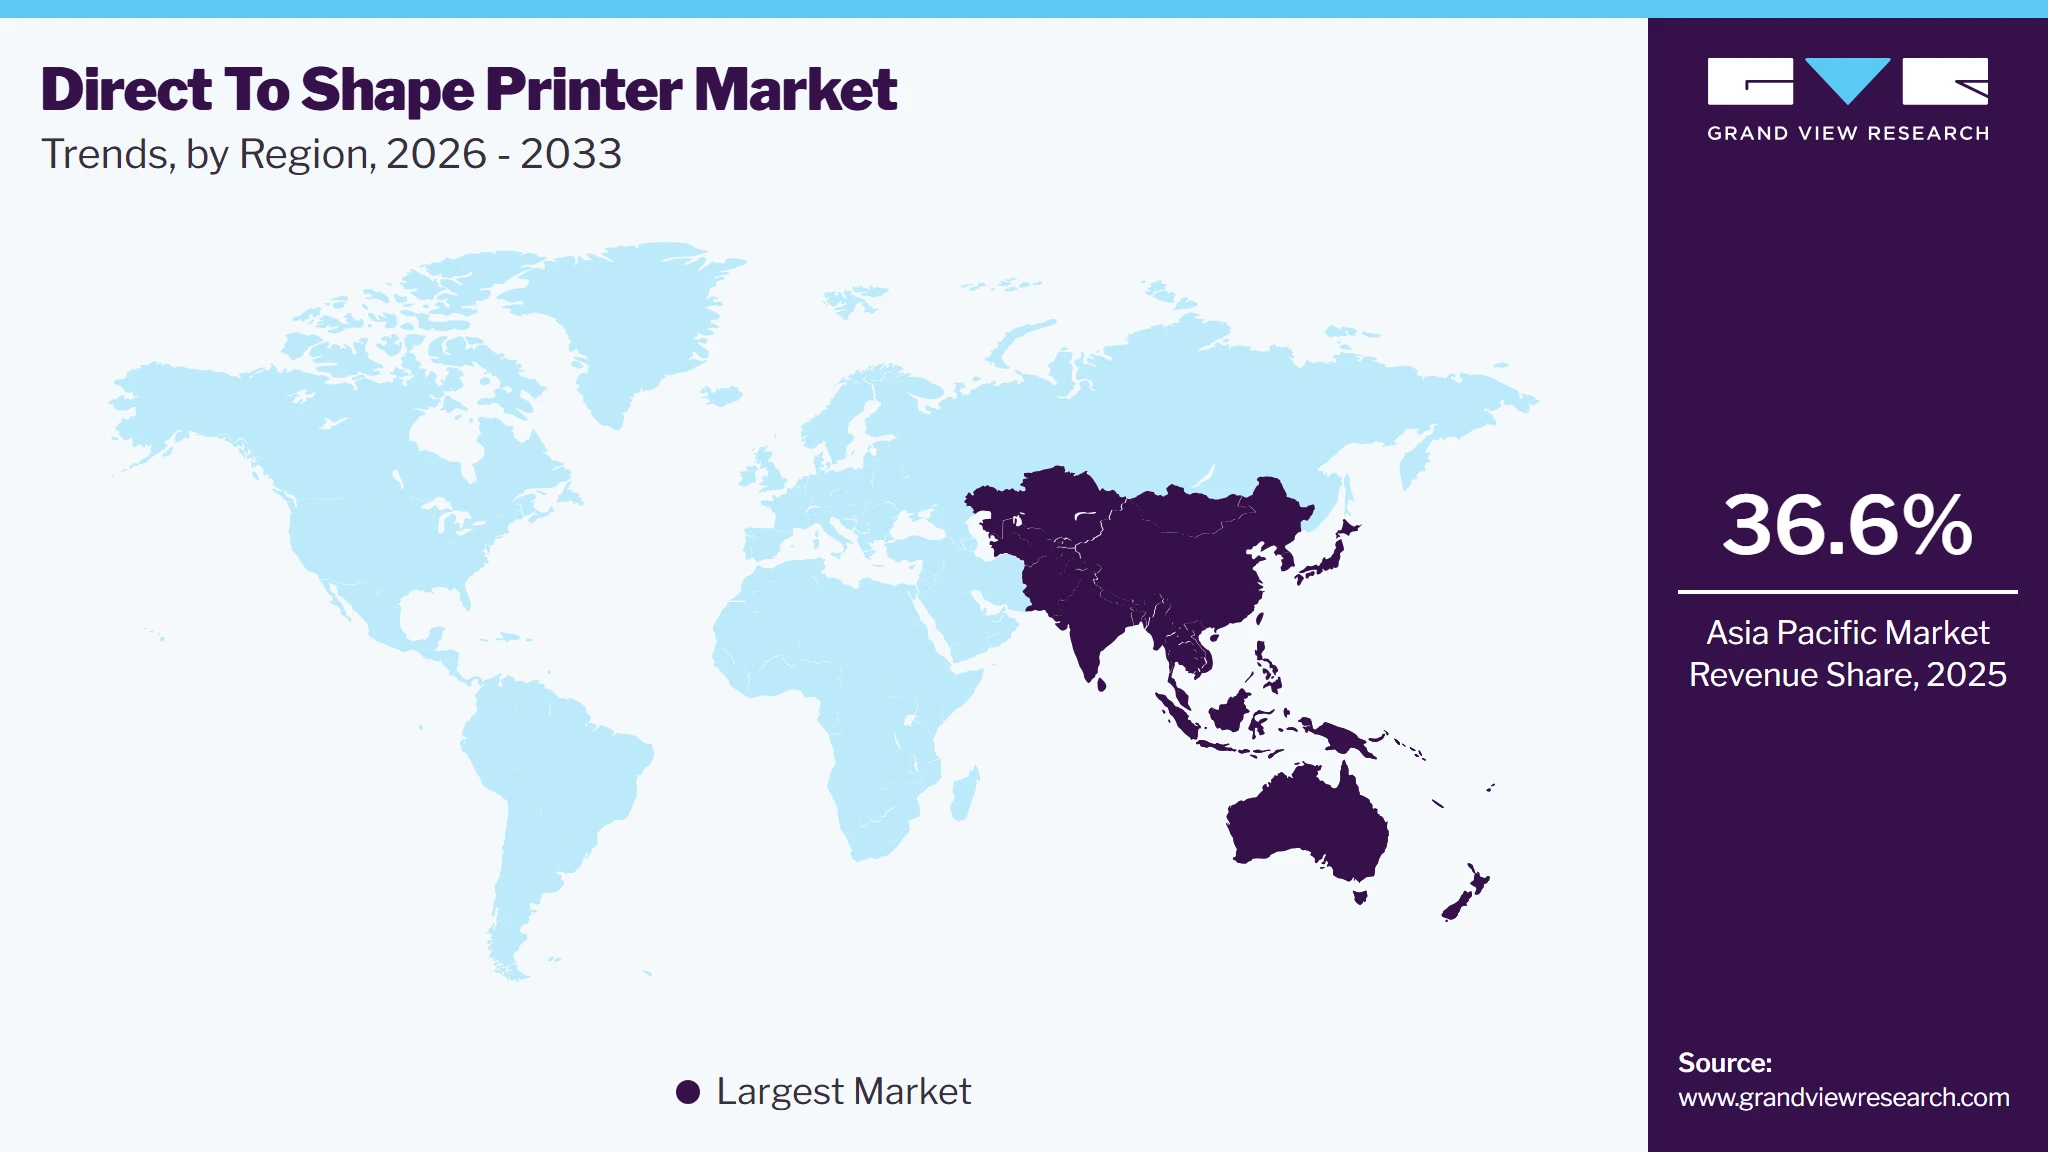
- Largest regional market: Asia Pacific (36.6% revenue share, 2025)
- By country: The China held the largest share of Asia Pacific in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.2 Billion
- Estimated market size in 2026: USD 3.6 Billion
- Projected market size by 2033: USD 7.3 Billion
- CAGR (2026-2033): 10.7%
GVR research-powered AIAsk Prism AI about the direct to shape printer marketGet cited answers from GVR research on market growth, segments, regulations and forecasts.Start with✓ Source-linked answers ✓ Market-specific context ✓ Traceable figuresExplore Prism AI ↗Cost-effectiveness and the ability to print on irregular surfaces have expanded the market’s Ink Types across sectors like automotive, packaging, and consumer goods. Furthermore, the growing trend of personalized and on-demand manufacturing is pushing businesses to adopt direct to shape, also referred to as direct to object printing solutions.
 To learn more about this report, Download Free Sample Report
Market Dynamics
The direct-to-shape (DTS) printer market is experiencing steady growth as manufacturers increasingly adopt digital printing technologies to improve production efficiency, reduce packaging waste, and enhance product aesthetics. Growing demand for customized packaging, shorter product life cycles, and premium branding across industries such as cosmetics, food & beverages, electronics, and automotive is driving investment in DTS printing solutions. The technology enables direct printing on curved and irregular surfaces without the need for labels or transfer films, helping manufacturers simplify production while supporting sustainability goals through reduced material consumption.
Brands are increasingly replacing conventional labels and shrink sleeves with direct-to-shape printing to reduce packaging waste and improve recyclability. By printing directly onto bottles, cans, jars, and containers, manufacturers eliminate additional packaging materials while achieving a cleaner, premium product appearance. This aligns with global sustainability initiatives and growing consumer preference for environmentally responsible packaging, encouraging greater adoption of DTS printers across consumer goods industries.
At the same time, premium packaging has become an important tool for product differentiation in competitive markets such as cosmetics, beverages, and personal care. Direct-to-shape printers produce high-resolution graphics, vibrant colors, and customized designs that enhance shelf appeal and support limited-edition products or personalized branding. The ability to switch designs quickly without changing printing plates also enables manufacturers to respond faster to changing consumer trends and marketing campaigns.
Despite their advantages, direct-to-shape printing systems require significant upfront investment in digital printers, UV curing systems, software, and automated handling equipment. Small and medium-sized manufacturers may find it difficult to justify these capital expenditures, particularly when existing labeling or conventional printing systems remain operational. Additionally, integrating DTS printers into production lines and training operators can increase implementation costs, slowing adoption among cost-sensitive businesses.
The expansion of Industry 4.0 and digitally connected manufacturing presents significant opportunities for the direct-to-shape printer market. Manufacturers are increasingly seeking production systems that support automation, real-time monitoring, and flexible manufacturing while enabling rapid design changes and variable data printing. DTS printers fit well within smart factory environments by reducing setup time and improving production efficiency.
Furthermore, increasing demand for personalized products, promotional packaging, and short production runs is creating new growth opportunities across cosmetics, beverages, pharmaceuticals, and consumer goods. As brands continue to focus on customer engagement through customized packaging and limited-edition products, the adoption of direct-to-shape printing is expected to accelerate, particularly among companies investing in agile and digitally enabled production capabilities.
Market Concentration & Characteristics
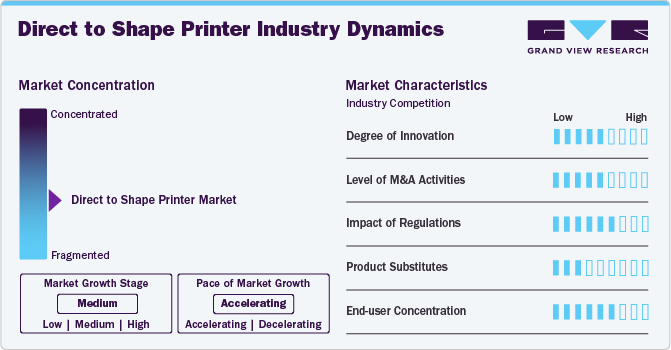
The global direct to shape printer industry is moderately fragmented, with a mix of large multinational corporations and smaller regional players competing for market share. Leading manufacturers focus on developing high-quality, versatile printers that can cater to a wide array of industries, including automotive, consumer goods, packaging, and healthcare. Innovation in this market is driven by the increasing demand for personalized products, reduced production costs, and the need for efficient, waste-reducing manufacturing processes. As businesses strive for higher levels of customization, direct to shape printers offer a solution that aligns with these growing demands.
Market dynamics are also shaped by the rise of sustainability concerns and eco-friendly manufacturing practices. As consumers and businesses increasingly prioritize environmentally responsible products, direct to shape printing technologies, which minimize waste and energy consumption, have become a significant point of focus for manufacturers. Regulations in various regions, especially around sustainability and waste reduction, push the industry toward the development of more energy-efficient and eco-friendly printing technologies. Companies that innovate with green solutions-such as printers using recyclable or biodegradable materials-are well-positioned to capture a share of the growing market driven by eco-conscious consumers and businesses.
 To learn more about this report, Download Free Sample Report
Despite the market’s growth, the direct to shape printer market faces competition from traditional manufacturing methods as well as other advanced printing technologies like 3D printing. To remain competitive, manufacturers must continually innovate and integrate new technologies, such as AI and IoT, to offer smarter, more efficient solutions. As industries seek more sustainable and customizable production options, the direct to shape printer market must adapt to changing consumer preferences, technological advancements, and regulatory pressures to maintain its momentum. Emphasizing flexibility, eco-friendliness, and cost-efficiency will be key to sustaining market leadership in this dynamic, evolving industry.
Analyst Perspective
The direct-to-shape (DTS) printer market is expected to witness steady growth over the forecast period, driven by the increasing adoption of digital printing technologies, demand for sustainable packaging, and the need for greater production flexibility across industries. Manufacturers are increasingly replacing conventional labeling processes with direct-to-shape printing to reduce material waste, improve operational efficiency, and enhance product aesthetics. Advancements in UV inkjet technology, automation, and high-speed single-pass printing are enabling higher productivity and superior print quality on complex surfaces. In addition, growing investments in smart manufacturing, product personalization, and premium packaging across cosmetics, food & beverage, electronics, and automotive industries are expected to create significant opportunities for market participants.
Drivers, Opportunities & Restraints
The most significant driving factors for the industry include the increasing demand for customization and personalization across various industries. As consumers increasingly seek unique, tailored products, businesses are turning to direct to shape printing for cost-effective, efficient solutions to meet this need.
The restraints affecting the industry include high initial setup costs, which can deter small and medium-sized businesses from adopting the technology. There are also limitations in material compatibility, as not all materials work well with direct to shape printers. Furthermore, the technology still faces challenges related to print durability and surface quality, which can affect product reliability and consumer satisfaction.
Opportunities for growth in the industry lie in the increasing adoption of Industry 4.0 principles, as businesses seek to optimize production efficiency and customize offerings. Furthermore, expansion into emerging markets also presents opportunities, as local manufacturers adopt advanced technologies to enhance their product offerings and meet demand for unique, custom items.
Technology Insights
Based on technology, the inkjet segment led the market with the largest revenue share of 51.9% in 2025, accounting for 52% of the revenue share due to its ability to offer high-resolution, vibrant, and detailed prints across a wide range of substrates. This flexibility makes it ideal for industries like packaging, cosmetics, and consumer goods, where customization and quality are key differentiators. As demand for personalized and on-demand printing increases, especially in sectors such as food and beverage, inkjet printing technology is gaining traction for its cost-effective, high-quality output.
Laser technology in direct to shape printers is becoming increasingly popular due to its precision, speed, and efficiency in printing high-quality, durable markings on various surfaces. Its growing adoption in industries like automotive, electronics, and packaging is driven by the need for high-definition prints that can withstand harsh conditions such as abrasion and temperature variations. Additionally, laser printing provides a cleaner, more sustainable alternative to traditional ink-based printing methods, contributing to its growing preference in industrial applications.
End-use Insights
Based on end-use, the food & beverage segment led the market with the largest revenue share of 23.7% in 2025 revenue share driven by the increasing need for packaging customization and high-quality branding. With an increasing emphasis on product differentiation and sustainability, manufacturers are turning to direct to shape printing to achieve unique packaging designs while maintaining the high print quality that meets food safety standards. Additionally, the need for efficient, on-demand printing solutions to accommodate shorter production runs and varying product batches is pushing growth in this sector.
 To learn more about this report, Download Free Sample Report
The toys and sporting goods industry is witnessing growing adoption of direct to shape printers driven by the need for customized branding and intricate designs on products. As consumer preferences shift toward personalized products, manufacturers are seeking cost-effective and efficient ways to produce high-quality prints on irregular shapes such as sports equipment and toy figurines. Direct-to-shape printing provides the flexibility, speed, and precision necessary to meet these demands while reducing lead times and costs.
Ink Type Insights
Based on ink type, the UV- based segment led the market with the largest revenue share of 49.0% in 2025. UV-based ink technology is expanding rapidly in the direct to shape printer market due to its ability to cure ink instantly using ultraviolet light, allowing for high-quality, durable prints on various surfaces. This technology is especially beneficial for industries that require fast production cycles and long-lasting prints, such as automotive and electronics. UV-based inks also offer the advantage of being more environmentally friendly than solvent-based inks, further driving their adoption in applications that require sustainability and efficiency.
Solvent-based inks are a popular choice in the direct to shape printer market due to their ability to produce durable, vibrant prints on a wide range of materials. These inks are particularly suited for applications that demand resistance to weathering, abrasion, and chemicals, making them ideal for industries such as packaging, automotive, and outdoor signage. As the demand for long-lasting, high-performance prints continues to rise, solvent-based inks remain a key driver of market growth, especially in industries with high durability requirements.
Type Insights
The Single Pass segment is growing at a significant CAGR over the forecast period, driven by their high-speed printing capabilities, allowing for faster production cycles and increased efficiency in industries like packaging, automotive, and consumer goods. This technology allows printing on a variety of shapes and sizes in a single pass, significantly reducing processing time and cost per unit. As manufacturers seek to improve productivity and meet the growing demand for customized products, single-pass technology is becoming a preferred choice for mass production and on-demand printing applications.
Based on type, the multi pass segment led the market with the largest revenue share of 75.4% in 2025, due to their ability to produce highly detailed and high-resolution prints, making them ideal for applications that require fine detailing, such as cosmetics and electronics. While slower than single-pass technology, multi-pass printers offer enhanced quality and precision, which is crucial for industries where intricate designs and color accuracy are essential. The growing trend for premium and customizable products across various sectors is driving the adoption of multi-pass printing technologies.
Regional Insights
North America direct to shape printer market is fueled by the presence of advanced manufacturing facilities, technological innovation, and a strong demand for personalized products. The automotive and consumer electronics industries are leading adopters of these printers. Additionally, the region's strong focus on sustainability and eco-friendly practices drives the demand for efficient and waste-reducing manufacturing methods like direct to shape printing.
U.S. Direct to Shape Printer Market Trends
The direct to shape printer market in the U.S. is projected to expand at a CAGR of 9.5% over the forecast period, driven by the increasing demand for customization in industries like food & beverage, automotive, and consumer goods. The presence of a well-established manufacturing base, combined with a focus on technological innovation and sustainability, fuels market growth. Additionally, the demand for eco-friendly printing solutions and quick turnaround times in the packaging industry are contributing to the expansion of the market.
Asia Pacific Direct to Shape Printer Market Trends
Asia Pacific dominated the direct to shape printer market with the largest revenue share of 36.6% in 2025. The region’s market is experiencing rapid market growth due to the strong manufacturing base in countries like China and India. The region has seen increased adoption of direct to shape printing technologies due to a rise in the demand for customized products across multiple sectors. Additionally, the growth of the e-commerce industry and demand for personalized packaging are further contributing to the rise in demand for direct to shape printers. Cost advantages and growing investments in research and development also bolster the market in this region.
 To learn more about this report, Download Free Sample Report
The direct to shape printer market in the China held the largest share in the Asia Pacific region in 2025. China’s direct to shape printer market is driven by its massive manufacturing sector, particularly in electronics, automotive, and packaging industries. The country's focus on increasing production efficiency and customization, along with government initiatives to reduce environmental impact, is accelerating the adoption of advanced printing technologies. The shift towards industrial automation and high-quality printing is also contributing to market growth.
The direct to shape printer market in India is expected to grow at a CAGR of 11.9% over the forecast period. In India, the growing demand for personalized products, particularly in consumer goods and packaging, is a major factor driving the market for direct to shape printers. The rapid growth of the manufacturing sector and the increasing focus on improving production efficiency are fueling the adoption of these technologies. Additionally, the push for more sustainable manufacturing processes in line with environmental regulations supports market expansion.
Europe Direct to Shape Printer Market Trends
The direct to shape printer market in Europe is driven by a combination of technological advancements and the region’s strong industrial base. Countries in Europe have a growing demand for custom packaging and personalized consumer goods, particularly in industries such as fashion, automotive, and food. European manufacturers are increasingly looking for cost-effective solutions to reduce waste and improve production efficiency, making direct to shape printing attractive.
Spain direct to shape printer market is projected to expand at a significant CAGR over the forecast period. In Spain, market growth is driven by the strong demand for personalized packaging, particularly in the food and beverage sector. The country’s focus on improving sustainability and reducing waste is also pushing the adoption of direct to shape printing technologies. The increasing popularity of eco-friendly inks and the shift toward on-demand production are key drivers in this market
The direct to shape printer market in Italy is projected to expand at a significant CAGR over the forecast period. Italy's direct to shape printer market is supported by the high demand for customized designs in industries like automotive, fashion, and food & beverage. The country's strong emphasis on craftsmanship and aesthetic appeal drives the need for high-quality, precision printing technologies. Additionally, the adoption of advanced printing methods that reduce material waste is helping propel market growth.
Latin America Direct to Shape Printer Market Trends
The direct to shape printer market in Latin America is expanding as more manufacturers adopt advanced production technologies to meet the demand for customized and personalized products. While the adoption rate is slower compared to other regions, growing demand in sectors like automotive, consumer goods, and packaging is expected to boost market growth. Additionally, increasing government support for technological advancements and infrastructure development is creating favorable conditions for market expansion.
Brazil direct to shape printer market is projected to grow at a significant CAGR over the forecast period driven by the demand for high-quality, customized prints in industries like food & beverage, automotive, and packaging. The increasing need for efficient, cost-effective production methods and the growing trend toward sustainable manufacturing practices are contributing to the rise of direct to shape printing technologies. The country’s expanding middle class also drives demand for unique and customized consumer products.
Middle East & Africa Direct to Shape Printer Market Trends
The direct to shape printer market in the Middle East and Africa is driven by rapid industrialization and technological adoption in the region, particularly in countries like the UAE and Saudi Arabia. The demand for personalized products and custom packaging is on the rise, and direct to shape printing solutions offer an efficient method of meeting these needs. Furthermore, investment in smart manufacturing and innovation in local industries is helping to drive market expansion.
Saudi Arabia direct to shape printer market is projected to expand at a significant CAGR over the forecast period. The country’s growing emphasis on diversifying the economy and investing in manufacturing industries, such as automotive, packaging, and consumer goods, is driving market growth. The country’s push for technological innovation, along with the need for high-quality, durable prints in extreme conditions, supports the adoption of direct to shape printers. Additionally, increasing demand for eco-friendly solutions and efficient production processes is further boosting market prospects.
Key Direct To Shape Printer Company Insights
Some of the key players operating in the market include HP Development Company, L.P. and Canon Inc. among others.
-
HP Development Company, L.P. is a global company specializing in personal computers, printers, and related supplies. The company operates in over 170 countries and is committed to advancing technology that drives positive change in society.The company invests significantly in research and development and has a diverse portfolio that includes laptops, desktops, printers, and accessories and serves a wide range of customers from individual consumers to large enterprises.
-
Canon Inc. is a global provider of imaging and optical products, renowned for its innovative digital imaging solutions. Its portfolio includes a wide range of products such as printers, multifunction devices, and medical imaging equipment. The company operates in various sectors, catering to both consumer and business markets.
Key Direct To Shape Printer Companies
The following key companies have been profiled for this study on the direct to shape printer market.
-
HP Development Company, L.P.
-
Canon Inc.
-
Xerox Corporation
-
Durst Group
-
EFI (Electronics For Imaging, Inc.)
-
Mimaki Engineering Co., Ltd.
-
Roland DG Corporation
-
Ricoh Company, Ltd.
-
Seiko Epson Corporation
-
Konica Minolta, Inc.
-
Agfa-Gevaert Group
-
Xaar plc
-
Inca Digital Printers Ltd.
-
Kornit Digital Ltd.
-
Stratasys Ltd.
-
3D Systems Corporation
-
Markforged, Inc.
-
Voxeljet AG
-
Brother Industries, Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Canon Inc., Ricoh Company, Ltd., Seiko Epson Corporation, HP Development Company, L.P., Brother Industries, Ltd., Konica Minolta, Inc.)
- Invest in advanced UV inkjet technology, automation, and high-speed direct-to-shape printing systems.
- Expand through global distribution networks, strategic partnerships, and strong after-sales support.
- Develop integrated digital printing solutions for packaging, industrial, and consumer goods applications.
- Strong financial resources and global brand recognition.
- Broad product portfolios supported by extensive R&D capabilities.
- Well-established customer base across multiple end-use industries.
- Higher equipment costs than specialized manufacturers.
- Slower product customization due to larger organizational structures.
- Direct-to-shape printing contributes only a small share of their overall business.
Emerging & Regional Players (e.g., Durst Group, EFI (Electronics For Imaging, Inc.), Mimaki Engineering Co., Ltd., Roland DG Corporation, Agfa-Gevaert Group, Xaar plc)
- Focus on specialized direct-to-shape and direct-to-object printing solutions for industrial applications.
- Continuously innovate in printhead technology, UV curing, and substrate compatibility.
- Strengthen market presence through OEM collaborations and expansion into high-growth packaging markets.
- Deep expertise in industrial inkjet and direct-to-shape printing technologies.
- Faster product innovation and greater flexibility in meeting customer-specific requirements.
- Strong reputation in premium, customized, and short-run digital printing applications.
- Smaller financial scale compared to multinational competitors.
- Limited global sales and service network in some regions.
- Greater dependence on industrial printing demand and niche application markets.
Recent Developments
-
In March 2024, FUJIFILM Europe GmbH introduced an inkjet ink technology named AQUAFUZE, which merges UV-curable and water-based ink properties for wide-format printing. THE UV-curable aqueous ink is designed for indoor applications like signage and wallpaper, offering advantages such as reduced printhead clogging, strong substrate adhesion without primers, a glossy finish, and lower odor for enhanced safety. The introduction of AQUAFUZE technology could significantly impact the direct to shape printing market by providing inks that meet the growing demand for durability and versatility in printing on complex surfaces. Its compatibility with various substrates and robust performance characteristics may broaden the application scope for direct to shape printers, facilitating advancements in customization and efficiency.
-
In April 2024, Velox Ltd., a company specializing in direct to shape digital decoration solutions, secured USD 38 million in funding led by Fortissimo Capital. This investment aims to accelerate Velox's global expansion and further innovation in high-speed digital printing for rigid packaging containers, particularly in the beverage can market. Fortissimo Capital plans to scale the company's production and capitalize on the growing demand for more sustainable and efficient printing technologies.
Direct To Shape Printer Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 3.2 billion
Market size value in 2026
USD 3.6 billion
Revenue forecast in 2033
USD 7.3 billion
Growth rate
CAGR of 10.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Technology, end-use, ink type, type, region.
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; South Korea; Australia; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
HP Development Company, L.P.; Canon Inc.; Xerox Corporation; Durst Group; EFI (Electronics For Imaging, Inc.); Mimaki Engineering Co., Ltd.; Roland DG Corporation; Ricoh Company, Ltd.; Seiko Epson Corporation; Konica Minolta, Inc.; Agfa-Gevaert Group; Xaar plc; Inca Digital Printers Ltd.; Kornit Digital Ltd.; Stratasys Ltd.; 3D Systems Corporation; Markforged, Inc.; Voxeljet AG; Brother Industries, Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Direct to Shape Printer Market Report SegmentationThis report forecasts revenue growth at global, regional & country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global direct to shape printer market report on the basis of technology, end-use, ink type, type, and region:
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Inkjet
-
Laser
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Cosmetics & Personal Care
-
Automotive
-
Electronics
-
Food & Beverage
-
Toys & Sporting Goods
-
Others
-
-
Ink Type Outlook (Revenue, USD Million, 2021 - 2033)
-
UV-based
-
Solvent-based
-
Aqueous-based
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Single Pass
-
Multi Pass
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
France
-
Germany
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The direct to shape printer market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each direct to shape printer segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Technology
Revenue Capture Definition
Inkjet
Revenue generated from the sale of inkjet-based direct-to-shape printers and integrated printing systems designed to print directly on three-dimensional objects using digital inkjet technology.
Laser
Revenue generated from the sale of laser-based direct-to-shape printing and marking systems used for permanent decoration, engraving, coding, and product identification.
Others
Revenue generated from the sale of other direct-to-shape printing technologies, including hybrid, pad printing, thermal, and specialty digital printing systems.
Ink Type
Revenue Capture Definition
UV- based
Revenue generated from the sale of direct-to-shape printers compatible with UV-curable ink systems for high-speed, durable printing applications.
Solvent- based
Revenue generated from the sale of direct-to-shape printers designed to operate with solvent-based inks for industrial and outdoor applications.
Aqueous- based
Revenue generated from the sale of direct-to-shape printers utilizing water-based ink systems for environmentally friendly printing applications.
Type
Revenue Capture Definition
Single Pass
Revenue generated from the sale of single-pass direct-to-shape printers designed for high-speed, continuous production environments.
Multi Pass
Revenue generated from the sale of multi-pass direct-to-shape printers intended for flexible, high-quality printing, customized production, and short-run manufacturing.
End Use
Revenue Capture Definition
Food & Beverage
Revenue generated from the sale of direct-to-shape printers used for decorating and coding bottles, cans, cups, containers, and other food and beverage packaging products.
Cosmetics & Personal Care
Revenue generated from the sale of direct-to-shape printers used for printing on cosmetic and personal care packaging, including bottles, jars, tubes, and containers.
Automotive
Revenue generated from the sale of direct-to-shape printers used for marking and decorating automotive components, plastic parts, trims, and fluid containers.
Electronics
Revenue generated from the sale of direct-to-shape printers used for printing on electronic device housings, accessories, appliances, and industrial electronic components.
Toys & Sporting Goods
Revenue generated from the sale of direct-to-shape printers used for decorating toys, sports equipment, reusable bottles, helmets, and recreational products.
Others
Revenue generated from the sale of direct-to-shape printers used across pharmaceutical, household, industrial, promotional, and other consumer product applications.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
End-use Industry Assessment
Which industries are generating demand for direct-to-shape printers?
Analyze adoption across cosmetics & personal care, food & beverage, automotive, electronics, toys & sporting goods, and other industrial sectors to estimate the addressable market.
02
Technology & Product Penetration
Which printer technologies and configurations are driving adoption?
Evaluate the penetration of inkjet, laser, and other technologies, along with single-pass and multi-pass systems, considering production volume, print quality, and application requirements.
03
Regional & Manufacturer Analysis
Which regions and manufacturers contribute the highest market demand?
Assess regional investments, manufacturing activity, packaging automation, and sales of leading direct-to-shape printer manufacturers to estimate regional market contribution.
04
Revenue Estimation
What is the total revenue generated from direct-to-shape printer sales?
Estimate market revenue by aggregating sales of direct-to-shape printing systems across technologies, ink types, end-use industries, and geographic regions, validated through company revenues and industry demand trends.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Delivered a comprehensive regional assessment covering North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. The report includes regional market size, growth forecasts, technology adoption trends, key end-use industries, country-level demand analysis, and the factors driving adoption of direct-to-shape printing across each region.
Enabled clients to identify high-growth regional markets, prioritize expansion strategies, understand region-specific demand drivers, and evaluate investment opportunities based on manufacturing activity, packaging trends, and digital printing adoption.
Competitive Benchmarking
Delivered an in-depth competitive analysis of leading market participants, including product portfolio comparison, technology capabilities, business strategies, recent developments, innovation focus, geographic presence, and competitive positioning across the direct-to-shape printer ecosystem.
Provided a clear understanding of competitor strengths, market positioning, technology differentiation, and strategic initiatives, supporting informed decisions related to partnerships, product development, competitive strategy, and market entry.
Opportunity Assessment
Delivered a detailed assessment of emerging growth opportunities across high-potential applications, advanced UV inkjet technologies, sustainable packaging solutions, smart manufacturing adoption, and expanding demand from cosmetics, food & beverage, electronics, and industrial sectors. The report also identified future investment hotspots and evolving customer requirements shaping market growth.
Helped clients identify untapped revenue opportunities, prioritize high-growth application areas, evaluate future technology investments, and develop long-term business strategies aligned with evolving industry trends and customer demand.
Frequently Asked Questions About This Report
The global direct to shape printer market size was valued at USD 3.2 billion in 2025 and is estimated at USD 3.6 billion in 2026.
The inkjet segment accounted for the largest revenue share of 51.9% in 2025, driven by its ability to deliver high-resolution printing, support variable data printing, and print efficiently on curved and irregular surfaces across multiple industries.
The UV-based ink segment held the largest revenue share of 49.0% in 2025 owing to its fast curing speed, excellent adhesion on diverse substrates, and superior durability against scratches, chemicals, and environmental exposure.
The food & beverage segment led the market with a 23.7% revenue share in 2025, supported by growing demand for sustainable packaging, premium product decoration, and direct printing on bottles, cans, and containers.
Asia Pacific is expected to register the fastest growth in the market during the forecast period. The region's growth is driven by expanding manufacturing activities, increasing investments in digital printing technologies, rising demand for sustainable packaging, and the rapid growth of the cosmetics, food & beverage, electronics, and consumer goods industries.
The direct-to-shape printer market is driven by the increasing demand for customized and high-quality prints across industries like packaging, automotive, and consumer goods. Technological advancements in printing technology, such as improved efficiency and eco-friendly solutions, further fuel market growth.
The global direct-to-shape printer market, in terms of revenue, is expected to grow at a compound annual growth rate of 10.7% from 2026 to 2033 to reach USD 7.3 billion by 2033.
Asia Pacific dominated the Direct-to-Shape Printer Market, accounting for the largest revenue share of 36.6% in 2025. The region's leadership is attributed to its strong manufacturing base, expanding packaging industry, rapid industrialization, and increasing adoption of digital printing technologies.
Some of the key players operating in the direct-to-shape printer market are HP Development Company, L.P.; Canon Inc.; Xerox Corporation; Durst Group; EFI (Electronics For Imaging, Inc.); Mimaki Engineering Co., Ltd.; Roland DG Corporation; Ricoh Company, Ltd.; Seiko Epson Corporation; Konica Minolta, Inc.; Agfa-Gevaert Group; Xaar plc; Inca Digital Printers Ltd.; Kornit Digital Ltd.; Stratasys Ltd.; 3D Systems Corporation; Markforged, Inc.; Voxeljet AG; Brother Industries, Ltd.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


