
- Home
- »
- Clinical Diagnostics
- »
-
Dried Blood Spot Collection Cards Market Report, 2026-2033GVR Report cover

Dried Blood Spot Collection Cards Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (Newborn Screening, Infectious Disease Testing, Forensics), By Card Type (Whatman 903, Ahlstrom 226), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$413.8MMarket Estimate, 2026
$430.5MMarket Forecast, 2033
$642.4MCAGR, 2026–2033
5.9%Dried Blood Spot Collection Cards Market Summary
The global dried blood spot collection cards market size was valued at USD 413.8 million in 2025 and is projected to grow from USD 430.5 million in 2026 to USD 642.4 million by 2033, at a CAGR of 5.9% from 2026 to 2033. The market in North America dominated with a revenue share of 35.3% in 2025. The use of dried blood collection cards is majorly observed in newborn screening programs and testing of infectious diseases, although it has been gaining significant traction in the field of forensics, toxicology, & therapeutic drug monitoring.
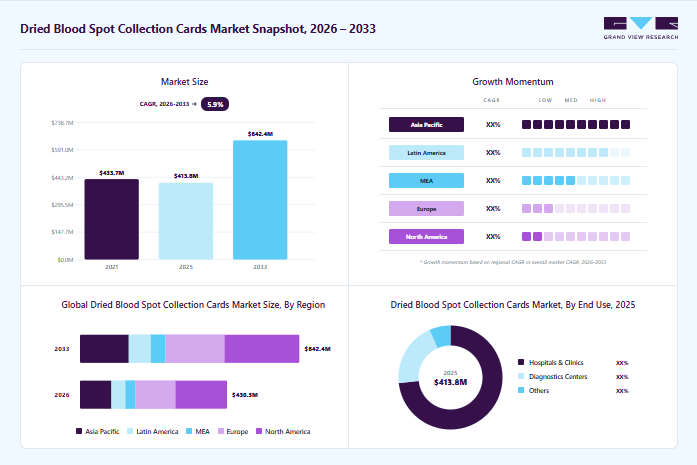 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By application: New born screening (NBS) segment led the market with the largest revenue share of 25.5% in 2025.
- By card type: Whatman 903 segment led the market with the largest revenue share of 40.3% in 2025.
- By end use: Hospitals & clinics segment led the market with the largest revenue share of 73.3% in 2025.
Regional Highlights
- Largest regional market: North America (35.3% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 413.8 Million
- Estimated market size in 2026: USD 430.5 Million
- Projected market size by 2033: USD 642.4 Million
- CAGR (2026-2033): 5.9%
Prism AI by Grand View Research Free to tryAsk a question about the dried blood spot collection cards marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Dried Blood Spot (DBS) is increasingly being used in HIV and hepatitis testing. Such factors are expected to offer favorable growth opportunities to the market. In addition, the growing population, along with a supportive framework from local governments for NBS, is a key factor fueling the growth of the market. DBS collection cards are widely utilized for serologic testing of viruses and provide an alternative method to collect blood when conventional labs and phlebotomy testing are inaccessible. COVID-19 serology is important for seroprevalence studies, identifying negative molecular results cases, and conducting diagnostic assessments. A study to determine the feasibility of a commercial COVID-19 assay to measure the level of antibodies from DBS cards was conducted by the Viral Hepatitis Care Network, the University of Toronto, the University Health Network, and other individual authors. The study found that plasma on DBS cards offered near-identical results to plasma samples, helping detect antibodies in 88% of people’s plasma.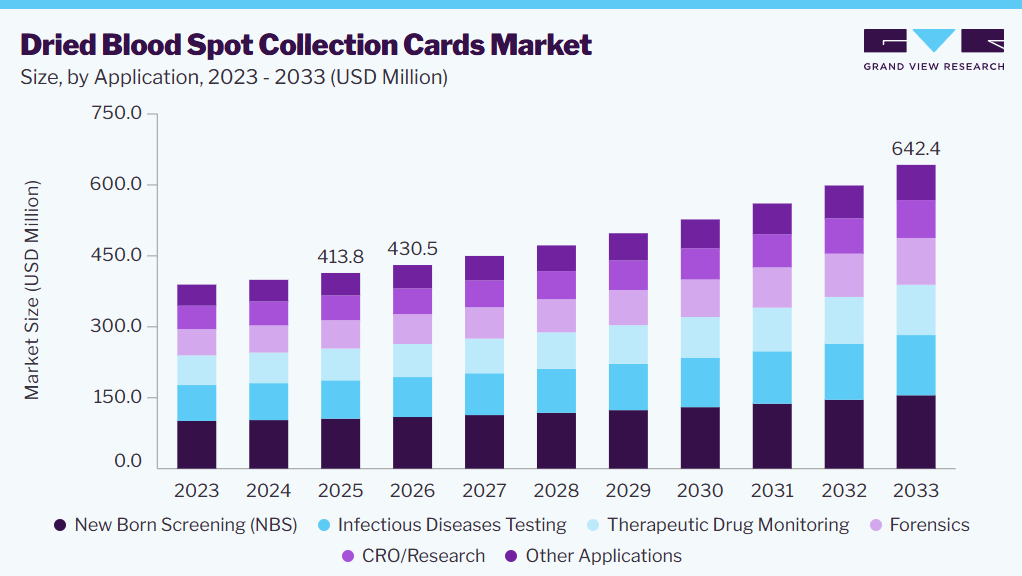 To learn more about this report, Download Free Sample Report
DBS cards have been used in a variety of toxicology applications, including toxicokinetics & epidemiological, environmental, and forensic toxicology. These cards may be employed as a sample preparation technique in forensic toxicology, and it has the ability to cost-effectively preserve evidence for closed cases. Screening processes and markers for follow-up of forensic or clinical interest are further applications in toxicology, where these cards may be progressively utilized. The employment of these cards also facilitates raised sample stability, enabling samples to be stored for a longer duration, thereby constructing a safer work environment for analysts and sample collectors, as only a minimal sample volume is required. In addition, the use of this technology enables first responders to obtain a simple finger-prick sample at a crime scene, such as a drug-facilitated or sexual assault case, without waiting for subsequent collection at the hospital post-admission of a victim, saving significant time as well as additional efforts.
NBS is also vital for the diagnosis of congenital diseases in infants. Over a span of time, the market has been witnessing an increase in the adoption of DBS in NBS for research purposes in various regions. For instance, a study published in BMC Med Ethics in November 2022 stated that parents in Hong Kong provide their consent to store and use residual DBS from NBS for biomedical research, with the understanding that parents’ autonomy and privacy will be protected. This increases the need for a transparent access policy and accountable governance to manage parents’ requirements and emerging opportunities in research by Residual Dried Blood Spots (rDBS).
Furthermore, DBS testing has primarily been employed to diagnose infectious diseases, specifically in resource-constrained regions, or to screen newborns for hereditary metabolic issues with a range of novel and innovative DBS products. Growing advantages and research studies for DBS testing for diagnostic purposes are expected to fuel market growth in the forecast period. In addition, the WHO recently recommended DBS for the diagnosis of hepatitis B & C and HIV due to the benefits of DBS in blood collection and transport. Rising initiatives by various government organizations and private-public partnerships or collaborations for enhancing usage as well as spreading awareness about diagnostic products, will boost the market demand in the coming years.
However, one of the major factors restraining the growth of the market is the contamination caused by DBS collection cards. It has been observed that the use of DBS collection cards causes issues such as cross-contamination and sample exposure for pathologists/clinicians handling specimens. A research study published by the NCBI states that the use of FTA cards for HIV detection yielded false-positive results when a high concentration of HIV was used. Similarly, it has been witnessed that DBS collection cards are vulnerable to cross-contamination or contamination by consumers, the environment, the equipment, and other collection cards during sample processing.
Market Dynamics
The dried blood spot collection cards market is witnessing steady growth driven by the increasing adoption of microsampling technologies across newborn screening, infectious disease diagnostics, therapeutic drug monitoring, and clinical research applications. The ability of dried blood spot collection cards to enable convenient sample collection, simplified transportation, and reduced storage requirements is supporting their wider utilization across healthcare systems. Market expansion is further supported by the growing emphasis on decentralized testing models and remote patient monitoring, which require reliable and patient friendly specimen collection solutions. Furthermore, ongoing advancements in volumetric microsampling technologies are improving sample consistency and analytical performance. For instance, in February 2025, Tasso launched its Tile T20 dried blood spot collection technology integrated with the Tasso Mini device, enhancing remote blood collection capabilities for clinical trials and diagnostic testing. Increasing demand for accessible diagnostic services and population screening programs is expected to support sustained market growth over the forecast period.
The growing shift toward decentralized healthcare delivery and remote diagnostic testing is driving demand in the Dried Blood Spot Collection Cards Market. Healthcare providers, diagnostic laboratories, and research organizations are increasingly adopting specimen collection methods that enable testing outside conventional clinical settings while maintaining sample quality and operational efficiency. Dried blood spot collection cards support this transition by facilitating simplified sample transport, reduced storage requirements, and broader access to diagnostic services in geographically dispersed populations. The increasing use of home-based testing programs, decentralized clinical trials, and population health screening initiatives is further contributing to market growth. In addition, pharmaceutical and biotechnology companies are incorporating microsampling approaches into clinical research workflows to reduce collection complexity and improve study reach. Industry participants are expanding their product portfolios to address the rising demand for remote sampling solutions. For instance, in June 2025, Sali metrics expanded its dried blood spot participant sampling kits to support decentralized research and remote biospecimen collection. Such developments are strengthening the adoption of DBS technologies across clinical and research settings, supporting continued market expansion.
Variability in sample quality and the absence of standardized analytical procedures continue to limit the broader adoption of dried blood spot collection cards across diagnostic and clinical testing applications. Differences in blood spot volume, hematocrit levels, sample collection techniques, and laboratory processing methods can affect test accuracy and result consistency, particularly in quantitative assays that require precise measurement. These challenges create concerns regarding data comparability across laboratories and healthcare institutions, which may slow the integration of DBS based testing into routine clinical practice. In addition, regulatory expectations related to assay validation and performance verification can increase the time and resources required for implementation. As healthcare providers and laboratories prioritize reliable and reproducible diagnostic outcomes, the need for standardized testing protocols remains a key industry challenge. Although ongoing technological advancements are improving sample collection and analytical performance, the lack of universal standardization continues to act as a constraint on wider commercial adoption of dried blood spot collection cards across global healthcare and research settings.
The increasing adoption of advanced microsampling technologies presents a significant growth opportunity for the Dried Blood Spot Collection Cards Market. Pharmaceutical companies, contract research organizations, diagnostic laboratories, and academic research institutions are increasingly utilizing microsampling approaches to support efficient sample collection, improve patient compliance, and streamline clinical study operations. The growing use of therapeutic drug monitoring, pharmacokinetic analysis, biomarker discovery, and population health screening is expanding the application scope of dried blood spot-based testing. In addition, the shift toward decentralized clinical trials and patient centric healthcare models is creating demand for specimen collection solutions that enable reliable testing outside traditional healthcare settings. Market participants are focusing on technologies that enhance sample quality, improve quantitative accuracy, and minimize variability associated with conventional dried blood spot collection methods. This trend is supporting broader adoption across clinical and research workflows. For instance, in February 2025, Neoteryx expanded its hematocrit independent microsampling solutions, enabling improved sample consistency and supporting the wider use of dried blood spot testing in clinical and bioanalytical applications. Such advancements are expected to create new commercial opportunities across diagnostic, pharmaceutical, and research settings.
Market Concentration & Characteristics
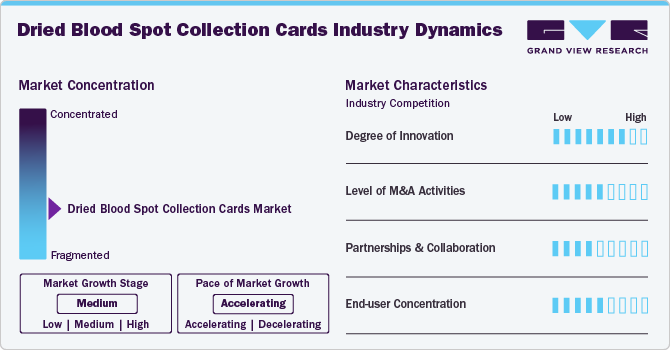
The degree of innovation is high in the market, particularly in the development of technologically advanced blood collection solutions. For instance, in September 2022, Capitainer, a Swedish startup, announced the highly positive results of its qDBS card. It is a volumetric DBS sampling device that showcases accurate outcomes for phenylketonuria. The new technology addresses the concern of the fluctuation in volume and hematocrit of blood in conventional cards.
Several players engage in mergers & acquisitions to strengthen their market position. This strategy enables companies to increase their capabilities, expand their product portfolios, and improve competency. For instance, in March 2021, Home Access Health was acquired by Everlywell, Inc., a healthcare and medical device company. This acquisition was expected to enhance the company’s at-home testing services for improving diagnostic care services.
 To learn more about this report, Download Free Sample Report
The stringent regulatory framework for dried blood spot collection cards is a major restraint on the industry, delaying innovation and increasing development costs. The regulatory framework for screening products is very stringent in countries where the industry has a high potential to grow due to the availability of a large patient pool.
The market shows a high end-user concentration, with a significant portion of revenue generated from a limited number of key customers, primarily in hospitals, clinics, and diagnostics centers. This concentration is driven by the dominance of a few major players.
Analyst Perspective
The Dried Blood Spot Collection Cards Market is experiencing steady growth driven by increasing adoption of microsampling technologies across newborn screening, infectious disease testing, therapeutic drug monitoring, and clinical research applications. The market is benefiting from the growing preference for decentralized healthcare models that require convenient and reliable specimen collection solutions. Advancements in volumetric and hematocrit independent sampling technologies are improving sample quality and expanding the applicability of DBS based testing. For instance, in 2025, Capitainer expanded its volumetric microsampling technologies to support enhanced sample accuracy and consistency. Continued expansion of remote diagnostics and population screening programs is expected to support long term market development.
Application Insights
Based on application, the new born screening (NBS) segment led the market with the largest revenue share of 25.5% in 2025. Advancements in research technologies to improve newborn screening are a major factor driving the market. Newborn screening is typically designed for the identification of pre-symptomatic conditions to plan an effective early intervention. Clinical laboratories are performing prospective pilot studies to ensure efficient workflow and analytical performance of screening tests. The study involves newborn screening for fragile X syndrome, a monogenic neurodevelopmental disorder. The study is conducted using customized analysis software and a high-throughput PCR system designed for the detection of fragile X mental retardation 1 gene repeat expansions from DBS samples. In the U.S., various agencies are supporting research studies on neonatal screening data. For instance, in May 2022, NHS England announced the launch of its updated guidelines for NBS screening which specifically focuses on the diagnosis of cystic fibrosis (CF) in the UK.
The forensic application segment is expected to register the fastest CAGR during the forecast period. An increase in government initiatives to enhance the adoption of DBS in drug abuse testing is a major factor expected to impact market growth. In October 2019, the World Anti-Doping Agency (WADA) signed a MoU with approximately seven Anti-Doping Organizations (ADOs) for the implementation and development of DBS testing. WADA collaborated with the ADOs to enhance the implementation and development of DBS in the field of sports. A meeting organized in March 2019 included WADA, the International Testing Agency (ITA), the International Olympic Committee (IOC), and various National Anti-Doping Organizations (NADOs); the meeting was conducted to oversee the progress of this project.
Card Type Insights
Based on card type, the whatman 903 segment led the market with the largest revenue share of 40.3% in 2025 and is anticipated to grow at the fastest growth rate over the forecast period. Whatman paper is a specific filter paper that is applied extensively in qualitative analysis. Among the various types of paper, Whatman 903 filter paper is FDA-approved as an in vitro Class II medical device, and it is utilized in the majority of newborn screening programs across the world. Although it is considered to be a relatively expensive ready-to-use card. The filter paper comprises cellulose fibers. It is developed from high-quality cotton linters. These filter papers are available in a wide range of grades. They are divided into grades according to their thickness, weight, and particle retention capabilities. In addition, these filter papers show high wet strength, thus segregating significant impurities.
The FTA cards segment is expected to register a considerable CAGR during the forecast period. The adoption of FTA cards is considered an attractive approach for fieldwork that involves molecular characterization and/or detection of viral pathogens, mostly when cheap and simple sample transport and collection systems are required. Also, the stability of the RNA genomic material of various viruses under different conditions additionally enhances the advantages of using FTA cards; this is also true in the case of metagenomics analysis. Therefore, an increase in the number of applications for FTA cards is the major factor expected to boost market growth over the forecast period.
End Use Insights
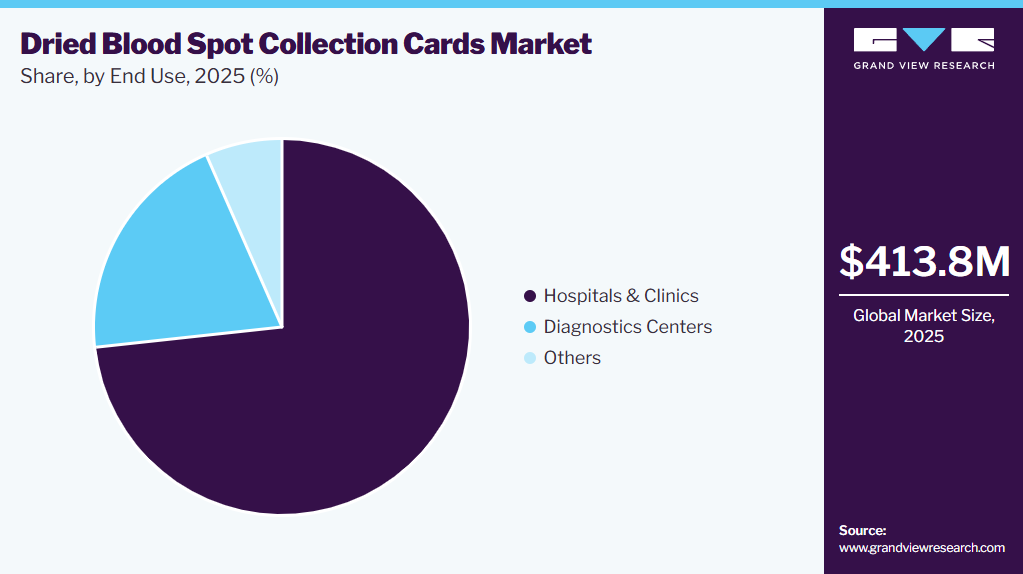
Based on end use, the hospitals & clinics segment led the market with the largest revenue share of 73.3% in 2025. Hospitals and clinics were key end users of DBS collection cards in 2024, owing to mandatory newborn screening in various regions. In the U.S., approximately 98% of women give birth in hospitals. An increase in the capacity of hospitals and clinics is anticipated to boost demand for DBS collection cards. For instance, the government of Australia announced a USD 70.12 billion (AUD 104.1 billion) budget for 2022-2023 on healthcare, which is 5.7% up from the last year. It allocated USD 26.27 million to support newborn screening programs in the region.
 To learn more about this report, Download Free Sample Report
Diagnostic centers are expected to register considerable CAGR during the forecast period. Diagnostics centers are also important users of DBS collection cards in the market. Hence, an increase in the number of diagnostics laboratories coupled with a rise in diagnostic testing of HIV and HCV is expected to boost DBS collection card market growth. As of August 2022, there were 24,802 diagnostic and medical labs in the U.S., with an average of 0.8% growth in the business of diagnostics and medical labs.
Regional Insights
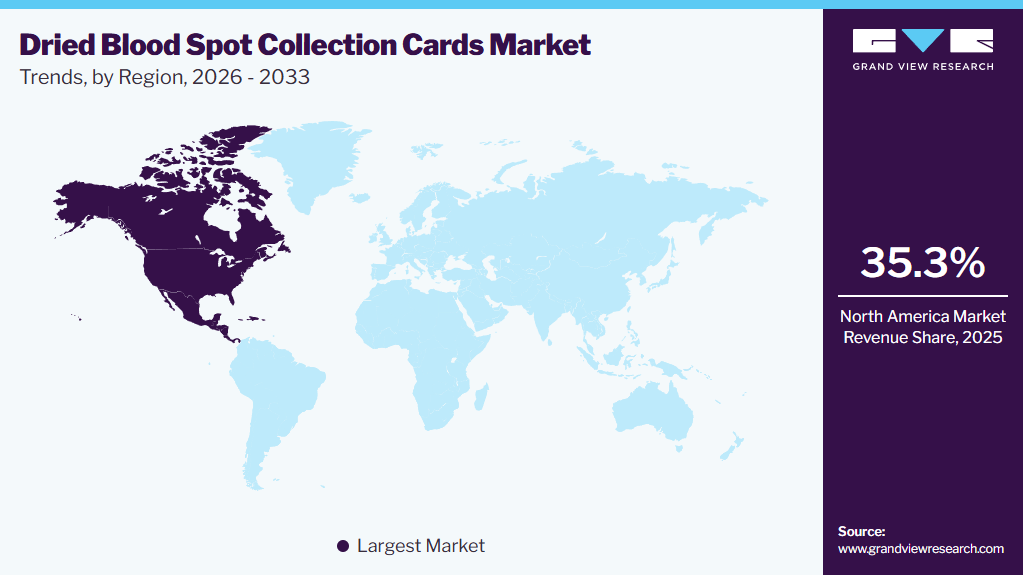
North America dominated the Dried Blood Spot Collection Cards Market with the largest revenue share of 35.3% in 2025. The dominant share can be attributed to the presence of a large number of manufacturers and well-established childcare facilities in the region. In addition, DBS procedure guidelines issued by public organizations ensure high-quality products, thus resulting in greater reliance on researchers & clinicians, thereby contributing to the overall demand for market across North America. Furthermore, the presence of well-established healthcare infrastructure and the availability of government funding for research are among the factors anticipated to augment market growth in this region.In July 2020, NIH invested USD 248.7 million in the development of new technologies to address challenges associated with testing for COVID-19.
 To learn more about this report, Download Free Sample Report
U.S. Dried Blood Spot Collection Cards Market Trends
The Dried Blood Spot Collection Cards Market in the U.S. held the largest share in the North America region in 2025. The dried blood spot collection cards market in the U.S. is expected to grow over the forecast period due to high adoption of advanced DBS collection cards, favorable reimbursement scenarios, and an increase in the prevalence of infectious diseases & newborn disorders.
Europe Dried Blood Spot Collection Cards Market Trends
The dried blood spot collection cards market in Europe was identified as a lucrative region in this industry. The growth of the market in the region can be attributed to the rise in the prevalence of chronic and infectious diseases and growing investments in the development of advanced diagnostics solutions
The UK dried blood spot collection cards market is growing primarily due to high demand for diagnostics, which can be attributed to an increase in the prevalence of infectious diseases.
The dried blood spot collection cards market in France is expected to grow over the forecast period due to the presence of strong healthcare systems, well-established healthcare insurance policies, continuous government support to manage healthcare, and increasing prevalence of infectious diseases, drug abuse, & preterm births.
Germany dried blood spot collection cards market in is expected to witness substantial growth owing to supportive healthcare policies in the country. According to the European Commission, Germany spends more per person on health as compared to other European countries, thus providing good access to care.
Asia Pacific Dried Blood Spot Collection Cards Market Trends
The dried blood spot collection cards market in Asia Pacific is expected to witness the fastest CAGR over the projected period. Asia Pacific is expected to be the fastest-growing market owing to the presence of a large target population in countries such as China and India. Moreover, increasing awareness regarding newborn screening is also expected to have a positive impact on the Asia Pacific dried blood spot collection cards market by 2030. In addition, the growing adoption of advanced laboratory procedures & techniques, such as DBS collection cards, for rapid diagnosis & investigations is one of the key factors driving market growth. Moreover, the introduction of innovative DBS collection cards is among the factors driving growth.
China dried blood spot collection cards market is expected to grow over the forecast period, owing to the presence of a large target population and continuous government initiatives to expand the diagnostics industry in the country.
The dried blood spot collection cards market in Japan is expected to grow over the forecast period presence of a well-established healthcare system and high adoption of advanced technology for early diagnosis & treatment of infectious & chronic diseases are expected to boost the market in the country.
Latin America Dried Blood Spot Collection Cards Market Trends
The dried blood spot collection cards market in Latin America was identified as a lucrative region in this industry. High incidence of life-threatening diseases, such as infectious diseases, including the COVID-19 outbreak, in key countries such as Brazil, Argentina, & Mexico is anticipated to drive market growth.
Brazil dried blood spot collection cards market is expected to grow over the forecast period owing to the presence of established healthcare infrastructure and favorable healthcare reimbursement scenarios as compared to other Latin American countries.
Middle East & Africa Dried Blood Spot Collection Cards Market Trends
The dried blood spot collection cards market in the Middle East & Africa was identified as a lucrative region in this industry. The market in this region is driven by ongoing government initiatives focused on improving early diagnosis and treatment of various life-threatening diseases in the MEA region.
Saudi Arabia dried blood spot collection cards market is expected to grow over the forecast period due to the increasing disposable income, and collaborative agreements with international organizations, such as WHO & UN, are expected to boost the market in the country by attracting key players.
Key Dried Blood Spot Collection Cards Company Insights
Some of the leading players operating in the dried blood spot collection cards market include F. Hoffmann-La Roche Ltd, QIAGEN, and Perkin Elmer. Key players are incorporating advanced medical technologies, with a high focus on delivering economic value to customers, further fulfilling unmet needs. Moreover, companies are focusing on undertaking various strategic initiatives with other major distributors and players to strengthen their market presence.
ArchimedLife and Eastern Business Forms are some of the emerging market participants in the dried blood spot collection cards market. These companies focus on improving health outcomes by receiving funding support from healthcare organizations and government bodies aided with novel product launches to capitalize on untapped avenues.
Key Dried Blood Spot Collection Cards Companies
The following key companies have been profiled for this study on the dried blood spot collection cards market.
-
QIAGEN
-
Perkinelmer
-
Roche
-
Shimadzu Corporation
-
Ahlstrom-Munksjö
-
Pall Corporation
-
Eastern Business Forms, Inc
-
Archimed Life Science Gmbh
-
Centogene N.V.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Well-Established Players (QIAGEN N.V., PerkinElmer, Inc., F. Hoffmann-La Roche Ltd, Shimadzu Corporation, Pall Corporation, Ahlstrom-Munksjö Oyj)
- Expand dried blood spot collection card portfolios through investments in microsampling technologies, molecular diagnostics, newborn screening solutions, and laboratory testing workflows.
- Focus on product innovation, strategic collaborations, geographic expansion, and integration of DBS technologies with diagnostic and research applications.
- Strengthen market presence through partnerships with healthcare providers, public health agencies, pharmaceutical companies, and research organizations.
- Strong brand recognition, extensive global distribution networks, established relationships with diagnostic laboratories and healthcare institutions, broad product portfolios, and advanced research capabilities.
- Ability to support large scale newborn screening, infectious disease testing, and clinical research programs across multiple regions.
- Large operational structures may limit agility in addressing specialized customer requirements.
- High regulatory compliance costs, extended product development timelines, and increasing competition from focused microsampling technology providers may impact growth flexibility in niche market segments.
Emerging Players (Archimed Life Science GmbH, Eastern Business Forms, Inc., CENTOGENE N.V.)
- Focus on developing specialized dried blood spot collection solutions for research, genetic testing, remote sample collection, and decentralized healthcare applications.
- Emphasize product differentiation, targeted collaborations, funding supported innovation, and expansion into underserved market segments.
- Invest in novel sampling technologies and customer specific collection solutions to increase market penetration.
- Specialized expertise in microsampling and specimen collection technologies, ability to address niche application requirements, focused product development strategies, and greater flexibility in responding to evolving customer needs.
- Strong positioning in emerging applications such as remote diagnostics, genomic testing, and decentralized clinical studies.
- More limited global reach, smaller distribution networks, and lower financial resources compared with established industry participants.
- Dependence on selected application areas and narrower product portfolios may constrain competitiveness in large scale public health screening and global diagnostic programs.
Recent Developments
-
In January 2024, Capitainer launched miQro Lab Solutions, a new U.S. laboratory in Warwick, Rhode Island. This initiative emphasizes the company’s goal to incorporate its innovative self-sampling technologies more swiftly into the U.S. healthcare framework. The establishment of miQro Lab Solutions is to expedite the adoption of Capitainer’s efficient and user-friendly solutions.
-
In September 2022, Neoteryx, a brand of Trajan Scientific, launched a program to support micro sampling pilot studies. Under this program, the company provided a free Mitra micro sampling device to scientists in healthcare and research organizations for a micro-sampling study. The program provided opportunities to determine the feasibility of remote sampling approaches in different environments.
-
In September 2022, Capitainer, a Swedish startup, announced the highly positive results of its qDBS card. It is a volumetric dried blood spot sampling device that showcases accurate outcomes for phenylketonuria. The new technology addresses the concern of fluctuation in volume and hematocrit of blood in conventional cards.
Dried Blood Spot Collection Cards Market Report Scope
Report Attribute
Details
Market size in 2025
USD 413.8 million
Estimated market size in 2026
USD 430.5 million
Projected market size by 2033
USD 642.4 million
Growth rate
CAGR of 5.9% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Application, Card type, End use Regional
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; and Kuwait
Key companies profiled
QIAGEN N.V., PerkinElmer, Inc., F. Hoffmann-La Roche Ltd, Shimadzu Corporation, Ahlstrom-Munksjö Oyj, Pall Corporation, Eastern Business Forms, Inc., Archimed Life Science GmbH, and CENTOGENE N.V.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Dried Blood Spot Collection Cards Market Report Segmentation
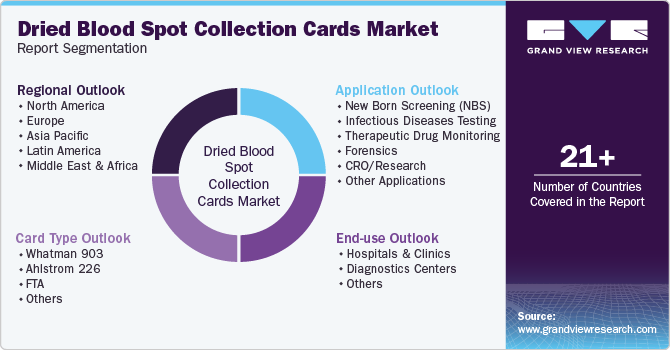
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global dried blood spot collection cards market report based on application, card type, end-use, and region.
 To learn more about this report, Download Free Sample Report
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
New Born Screening (NBS)
-
Infectious Diseases Testing
-
Therapeutic Drug Monitoring
-
Forensics
-
CRO/Research
-
Other Applications
-
-
Card Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Whatman 903
-
Ahlstrom 226
-
FTA
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals & Clinics
-
Diagnostics centers
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Singapore
-
Thailand
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The dried blood spot collection cards market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each dried blood spot collection cards segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Application
Revenue capture definition
New Born Screening (NBS)
Revenue is primarily captured through dried blood spot collection cards utilized in neonatal screening programs for detecting congenital, genetic, metabolic, and inherited disorders. Demand flows from hospitals, birthing centers, public health agencies, and newborn screening laboratories.
Infectious Diseases Testing
Revenue flows from dried blood spot collection cards used for infectious disease diagnosis, surveillance, and treatment monitoring. Demand is supported by HIV, hepatitis, tuberculosis, and other pathogen testing programs conducted by diagnostic laboratories and healthcare institutions.
Therapeutic Drug Monitoring
Revenue is derived from dried blood spot collection cards employed for measuring drug concentrations and monitoring therapeutic response. Demand accrues from pharmacokinetic assessments, chronic disease management programs, clinical laboratories, and personalized treatment monitoring applications.
Forensics
Revenue is captured through dried blood spot collection cards used in forensic toxicology, criminal investigations, postmortem analysis, and legal evidence collection. Demand originates from forensic laboratories, law enforcement agencies, judicial institutions, and medico legal examination centers.
CRO/Research
Revenue flows from dried blood spot collection cards utilized in clinical trials, biomarker research, bioanalytical studies, and pharmaceutical development activities. Demand is supported by contract research organizations, biotechnology companies, academic institutions, and translational research programs.
Other Applications
Revenue accrues from dried blood spot collection cards used in veterinary diagnostics, epidemiological studies, public health investigations, sports testing, and specialized healthcare applications. Demand originates from diverse institutional programs operating outside core diagnostic and research settings.
Segment - Card type
Revenue capture definition
Whatman 903
Revenue is primarily captured through standardized dried blood spot collection cards widely utilized in newborn screening, infectious disease testing, and clinical diagnostics. Demand flows from government screening programs, diagnostic laboratories, and healthcare institutions requiring validated sample collection media.
Ahlstrom 226
Revenue flows from dried blood spot collection cards designed for neonatal screening and laboratory testing applications. Demand is supported by public health screening initiatives, clinical laboratories, and healthcare providers requiring absorbent specimen collection substrates.
FTA
Revenue is derived from specialized collection cards incorporating nucleic acid stabilization technology for genetic, molecular, and infectious disease testing. Demand accrues from research organizations, molecular diagnostics laboratories, forensic institutions, and biobanking applications.
Others
Revenue is captured through proprietary and alternative dried blood spot collection cards used across diagnostic, research, pharmaceutical, veterinary, and public health applications. Demand originates from specialized testing requirements and emerging microsampling technologies.
Segment - End use
Revenue capture definition
Hospitals & Clinics
Revenue is primarily captured through dried blood spot collection cards utilized for newborn screening, infectious disease testing, therapeutic drug monitoring, and routine clinical diagnostics. Demand flows from inpatient care settings, outpatient clinics, and hospital affiliated laboratory networks.
Diagnostic Centers
Revenue flows from dried blood spot collection cards used by independent diagnostic laboratories and specialized testing centers for specimen collection and analysis. Demand is supported by high testing volumes associated with screening programs, disease monitoring, and laboratory services.
Others
Revenue is derived from dried blood spot collection cards utilized by contract research organizations, academic institutions, public health agencies, pharmaceutical companies, forensic laboratories, and veterinary testing facilities. Demand accrues from research, surveillance, and specialized testing applications.
Estimation Model
The dried blood spot collection cards market was estimated using a bottom-up methodology that involved identifying leading manufacturers and evaluating their product portfolios across key card types, applications, and end use settings. Revenue contributions were assessed through an analysis of product adoption patterns, utilization rates, company disclosures, and industry specific demand across newborn screening, infectious disease testing, therapeutic drug monitoring, forensic testing, and research applications. Market estimates were further refined by evaluating application wise adoption trends, testing volumes, and end user demand across major geographic regions. The resulting market values were consolidated and validated through manufacturer market share assessments, competitive benchmarking, and secondary research analysis to derive the overall market size and forecast projections.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Dried Blood Spot Collection Cards Competitive Landscape & Microsampling Technology Assessment
Assessed the global dried blood spot collection cards market landscape, covering card technologies, microsampling platforms, newborn screening applications, infectious disease testing, therapeutic drug monitoring, and research use. Analyzed key market participants, product portfolios, strategic initiatives, technology advancements, and adoption trends across healthcare and research settings.
Helped the client identify growth opportunities across microsampling technologies, evaluate competitive positioning, benchmark product capabilities, and prioritize strategic investments, partnerships, and market expansion opportunities within the dried blood spot collection cards industry.
Dried Blood Spot Collection Cards Technology & Product Benchmarking Study
Delivered a comprehensive benchmarking of dried blood spot collection card technologies across Whatman 903, Ahlstrom 226, FTA cards, and emerging microsampling solutions. Evaluated sample collection performance, storage stability, analytical compatibility, workflow efficiency, application suitability, and product differentiation among leading manufacturers.
Enabled the client to assess technology competitiveness, identify innovation gaps, benchmark product development strategies, and prioritize investments in advanced microsampling technologies, decentralized testing solutions, and next-generation specimen collection platforms.
Dried Blood Spot Collection Cards End User Infrastructure & Commercialization Feasibility Assessment
Assessed laboratory infrastructure, newborn screening networks, diagnostic centers, research institutions, public health programs, and regulatory frameworks supporting DBS collection card adoption. Evaluated testing volumes, application trends, commercialization pathways, reimbursement considerations, and end user requirements across major markets.
Supported commercialization planning by identifying market access opportunities, evaluating distribution partnerships and service models, assessing regulatory and reimbursement considerations, mitigating operational risks, and strengthening long-term scalability and adoption potential across global healthcare and research markets.
Frequently Asked Questions About This Report
North America dominated the Dried Blood Spot Collection Cards Market with the largest revenue share of 35.3% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Based on card type, the whatman 903 segment led the market with the largest revenue share of 40.3% in 2025.
Based on end use, the hospitals & clinics segment led the market with the largest revenue share of 73.3% in 2025.
Newborn screening held the largest dried blood spot collection cards market share of 25.5% in 2025 owing to various attributes such as its low cost, short diagnosis period, minimally invasive procedure, high precision, reproducibility, simple transportation, easy collection & storage, reduced biohazard risks, among other blood collection techniques.
The global dried blood spot collection cards market size was valued at USD 413.8 million in 2025 and is expected to reach USD 430.5 million in 2026.
The global dried blood spot collection cards market is expected to grow at a compound annual growth rate of 5.9% from 2026 to 2033 to reach USD 642.4 million by 2033.
Some major players catering to the dried blood spot collection cards market growth include Hemaxis, Danaher Corporation, Shimadzu, PerkinElmer, Inc., QIAGEN, Eastern Business Forms, Inc., Ahlstrom, ARCHIMED Life Science GmbH, CENTOGENE N.V. among others.
Use of DBS cards for applications such as newborn screening (NBS), therapeutic drug monitoring, HIV surveillance, clinical chemistry application, biomarker validation, biomarker development, drug discovery & development, systems biology, and forensic science among others driving the dried blood spot collection cards market growth.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


