
- Home
- »
- Medical Imaging
- »
-
Dual And Multi Energy Computed Tomography Market Report 2033GVR Report cover

Dual And Multi Energy Computed Tomography Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Prospective, Retrospective), By Application (Oncology, Neurology, Cardiology, Vascular Musculoskeletal), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$1.0BMarket Estimate, 2026
$1.1BMarket Forecast, 2033
$1.8BCAGR, 2026–2033
7.0%Dual And Multi Energy Computed Tomography Market Summary
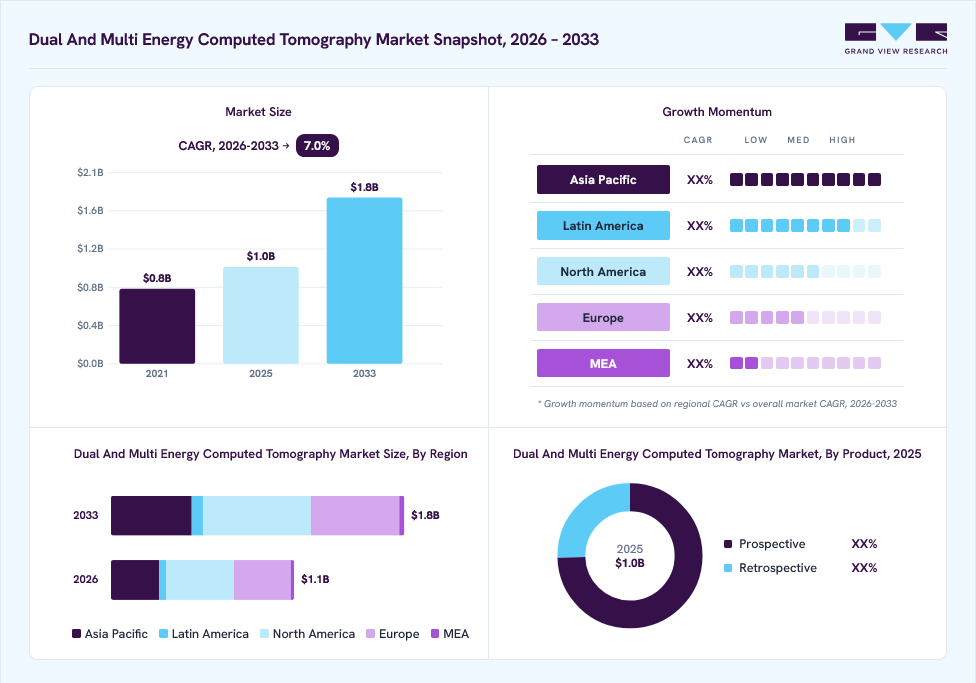
The global dual and multi energy computed tomography market size was valued at USD 1.0 billion in 2025 and is projected to grow from USD 1.1 billion in 2026 to USD 1.8 billion by 2033, at a CAGR of 7.0% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 37.1% in 2025. As older adults often present with complex medical conditions, the need for enhanced imaging technologies became increasingly critical in clinical practice.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Prospective segment dominated the market, with a revenue share of 74.5% in 2025.
- By application: Oncology segment held the largest market share of 27.3% in 2025.
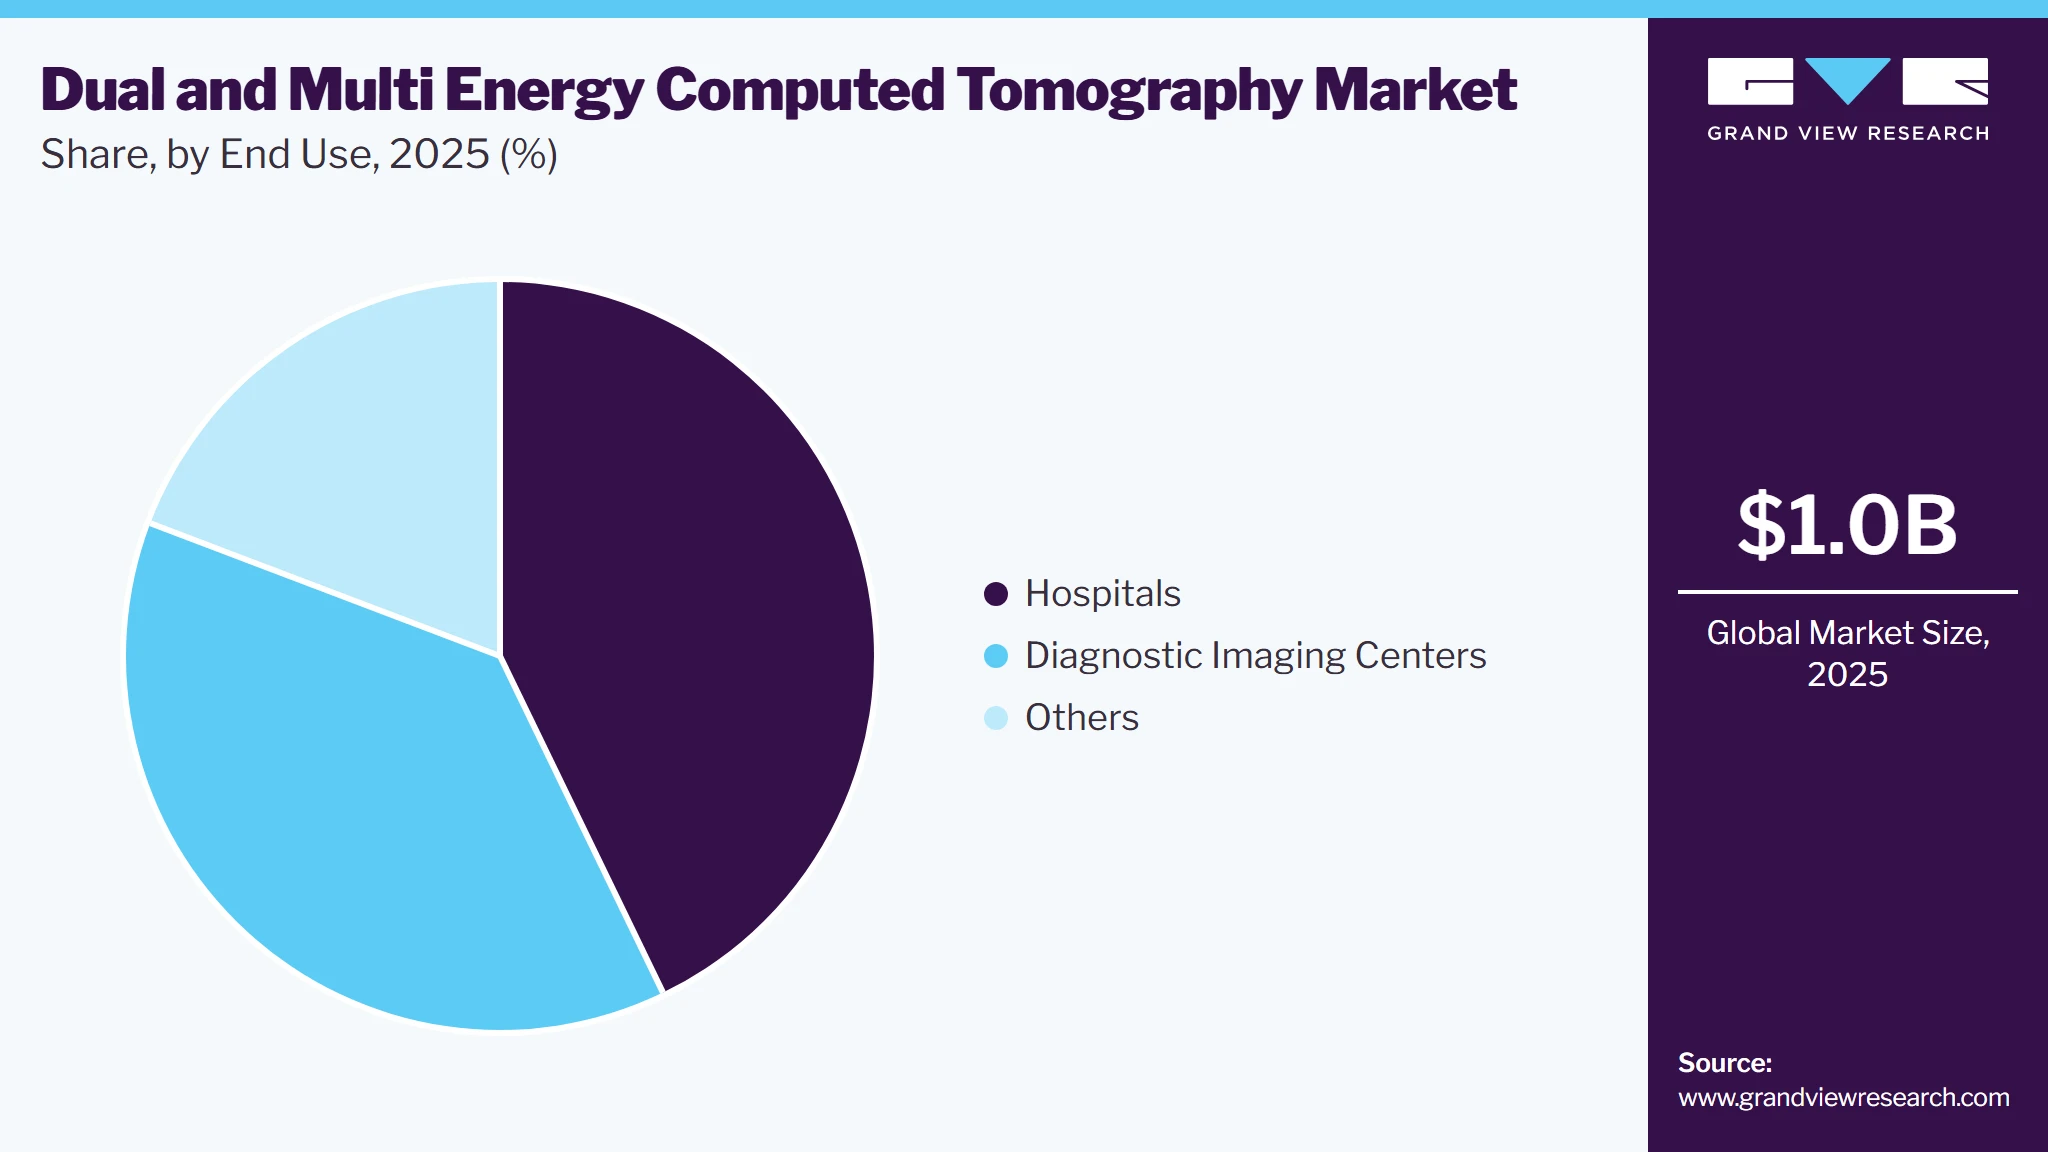
- By end use: Hospitals segment accounted for the largest revenue share of 42.8% in 2025.
Regional Highlights
- Largest regional market: North America (37.1% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.0 Billion
- Estimated market size in 2026: USD 1.1 Billion
- Projected market size by 2033: USD 1.8 Billion
- CAGR (2026-2033): 7.0%
Prism AI by Grand View Research Free to tryAsk a question about the dual and multi energy computed tomography marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Technological advancements in CT imaging techniques have further propelled the adoption of dual and multi-energy modalities. Continuous innovations improved diagnostic capabilities, enabling healthcare providers to deliver superior patient outcomes. This trend was evidenced by the increased integration of advanced imaging technologies within clinical settings. For example, the integration of dual-energy techniques enhances the characterization of tumors and optimizes the differentiation between various tissue types. Consequently, healthcare providers were compelled to invest in advanced imaging solutions to meet rising expectations for quality care, particularly among older patients.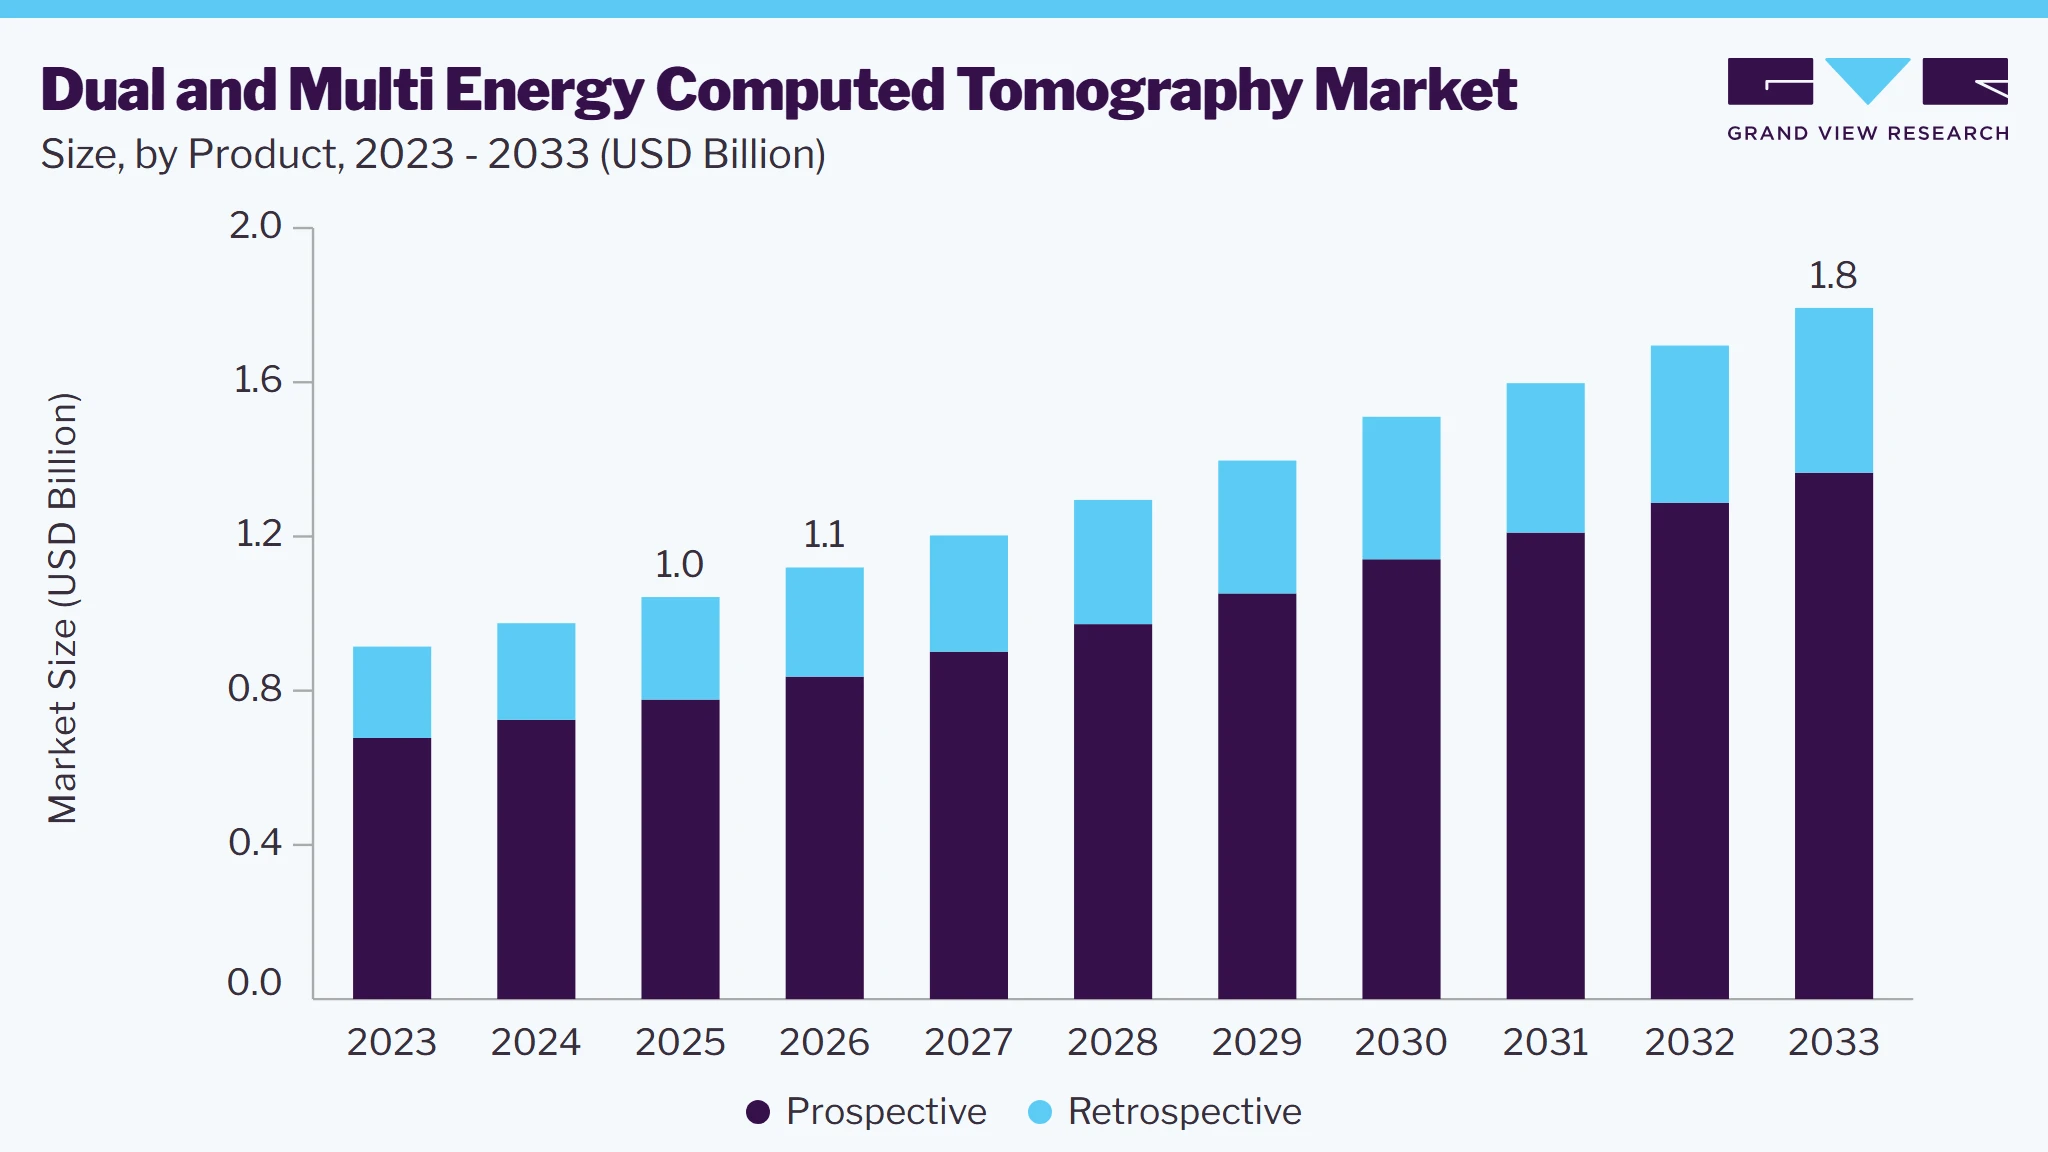 To learn more about this report, Download Free Sample Report
According to the American Heart Association, in North America, approximately 48% of adults aged over 65 were affected by cardiovascular diseases in both 2023 and 2024. In the UK, about one-third of the elderly population reported chronic conditions during the same period. This surge in chronic diseases increased the requirement for effective imaging solutions, further elevating the significance of dual and multi-energy CT technologies in diagnosing and managing complex medical issues.
Furthermore, according to the Indian Union Budget 2024-2025, the government allocated approximately USD 11 billion to healthcare for FY 2024-25, marking a 12.9% increase from the previous fiscal year’s budget. Increased funding specifically for advanced diagnostic techniques and minimally invasive procedures highlights a growing commitment to enhancing medical imaging capabilities, reflecting a broader trend toward improving healthcare delivery systems on a global scale.
Market Dynamics
The market for dual and multi-energy computed tomography is growing at a very fast rate as healthcare organizations invest in advanced imaging technologies for improved diagnostic accuracy and clinical decision-making across various applications. Dual and multi-energy computed tomography (CT) devices use several energy levels of X-rays in order to provide better tissue differentiation, lesion characterization, material quantitation and imaging artifact reduction compared to standard CT. The market for dual and multi-energy CT imaging technologies is characterized by widespread use of these systems in oncology, cardiology, neurology, musculoskeletal diagnosis, pulmonary imaging, emergency room diagnostics, and abdominal diagnosis. Increased burden of chronic diseases such as cancer, cardiovascular diseases, and metabolic disorders is driving the need for highly accurate diagnostic tools that would help in early disease diagnosis and therapy planning. Also, developments in imaging technology such as detector development, photon-counting CT, spectral imaging algorithms, AI-based image reconstruction, and dose reduction strategies are improving imaging outcomes and decreasing radiation exposure. Additionally, increased adoption of precision medicine approaches, growing demand for non-invasive diagnostic methods, and growing use of CT imaging in tertiary care hospitals, academic medical centers, and specialized diagnostic centers are fueling the market growth.
One of the primary factors that are driving the growth of the dual and multi-energy computed tomography market is the increased requirement for accurate and early disease diagnosis. In some cases, conventional CT scanners are faced with certain difficulties in distinguishing between tissues with comparable levels of attenuation, especially when dealing with challenging cases associated with oncological, cardiovascular, neurological, and musculoskeletal diseases. With the help of dual and multi-energy CT technologies, such problems can be effectively addressed due to their ability to make use of multiple energy spectra of X-rays to perform material decomposition, virtual monoenergetic imaging, iodine quantification, and better tissue characterization. The increased burden of chronic diseases, the growing requirement for precision medicine, and the increased preference for non-invasive diagnostics have become an additional incentive for healthcare providers to purchase such sophisticated medical imaging systems.
However, despite their numerous clinical benefits, the deployment of such advanced systems as dual and multi-energy CT scanners is limited due to the expensive nature of the technology. These advanced systems necessitate the use of highly developed hardware and software components that increase the capital costs of acquiring such CT systems significantly in comparison with regular CT systems. Besides that, the costs of installation and maintenance services, software updates, personnel training, and service agreements can also impose an additional burden on the healthcare facility. Small hospitals, community healthcare centers, and facilities from developing countries face serious limitations associated with their financial capabilities and other healthcare needs that prevent them from purchasing advanced imaging devices. Additionally, there are some inconsistencies in the reimbursement practices for advanced spectral imaging in several regions that can diminish the financial motivation of healthcare organizations to use these technologies.
Analyst Perspective
The dual and multi energy computed tomography market finds itself at the crossroads of several revolutionary forces shaping the diagnostic imaging industry, including increased need for accurate diagnostics, use of innovative imaging modalities, and high incidence of various chronic diseases around the globe. The rise in incidence of cancer, cardiovascular disease, neurologic disorders, musculoskeletal diseases, and vascular disease has resulted in a surge in the demand for high-end imaging technology to facilitate early detection, treatment, and monitoring of these conditions. Dual and multi energy CT systems have significant advantages compared to their standard counterparts, as they provide better tissue differentiation, material decomposition, and artifact reduction, as well as offer advanced quantitative imaging capabilities. The market is benefiting from the modernization of health infrastructure, increased adoption of premium CT systems in tertiary care facilities, and increased awareness among radiologists about the benefits of spectral imaging. In addition, investment into imaging software ecosystem and workflow solutions presents a new revenue source for the industry. With continued emphasis on diagnostic precision, efficiency, and better patient management within health care organizations, it is anticipated that the use of dual- and multi-energy CTs will become increasingly common within hospitals, imaging centers, and specialized health care facilities globally.
Product Insights
Based on product, the prospective segment led the market with the largest revenue share of 74.5% in 2025. Technological advancements in dual and multi-energy CT systems have markedly improved diagnostic capabilities and imaging quality. Driven by the rising prevalence of chronic diseases and increasing patient expectations, these innovations support early diagnosis and treatment planning, further accelerated by enhanced healthcare infrastructure and ongoing investment in research and development.
The demand for retrospective techniques is expected to grow lucratively over the forecast period. Retrospective techniques facilitate the analysis of multi-energy scan data, enabling precise tissue differentiation essential for identifying pathologies, especially in oncology and cardiovascular imaging. Ongoing hardware and software advancements enhance the reliability of these analyses, while increased research, development, and regulatory approvals drive adoption among healthcare professionals seeking evidence-based imaging solutions.
Application Insights
Based on application, the oncology segment led the market with the largest revenue share of 27.3% in 2025, owing to its advanced diagnostic capabilities, enabling detailed tissue characterization and early tumor detection. This technology enhances treatment planning and monitoring, addressing the growing cancer prevalence and the need for precise medical imaging solutions, ultimately improving patient outcomes.
Vascular applications are expected to register significant growth over the forecast period, fueled by the technology’s superior image quality through enhanced tissue differentiation, improved contrast for detecting vascular structures, reduced artifacts from high-energy virtual monoenergetic images, and the ability to generate virtual non-contrast images, minimizing radiation exposure. Moreover, technological advancements, the rising prevalence of chronic diseases, and increasing patient expectations further propel market growth, highlighting the significance of advanced imaging solutions.
End-use Insights
Based on end use, the hospitals segment led the market with the largest revenue share of 42.8% in 2025, as hospitals are witnessing increasing patient caseloads due to chronic diseases, significant technological advancements enhancing diagnostic accuracy, and non-invasive diagnostic capabilities that reduce surgical risks. Moreover, growing patient expectations for high-quality care, economic investments in advanced imaging technologies, and diverse clinical applications further elevate the demand for these systems.
 To learn more about this report, Download Free Sample Report
Diagnostic imaging centers are projected to grow at the fastest CAGR of 8.0% over the forecast period. Key factors driving demand for dual and multi-energy CT systems in diagnostic imaging centers include technological advancements offering superior imaging capabilities, an increase in patient referrals due to chronic diseases, and a focus on early disease detection. Moreover, these systems provide cost-effectiveness through improved diagnostic precision, meet rising patient expectations for quality care, and support research and development initiatives.
Regional Insights
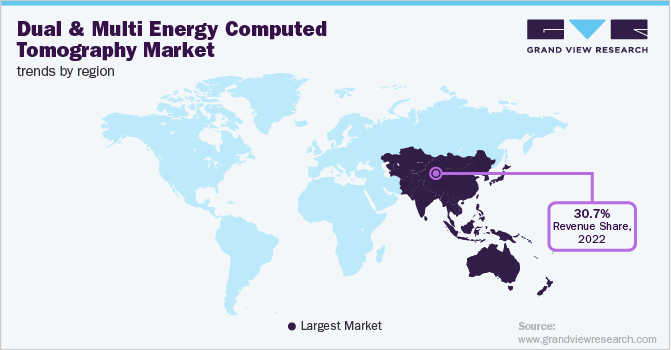
North America dominated the dual and multi-energy computed tomography market with the largest revenue share of 37.1% in 2025. Market growth in the region is driven by several factors, including an advanced healthcare infrastructure, high healthcare expenditure, and a rising prevalence of chronic diseases. Significant government support for medical technologies and research further amplifies this growth. The region’s commitment to innovative diagnostic solutions and increasing demand for accurate imaging techniques is propelling the adoption of dual and multi-energy CT systems.
 To learn more about this report, Download Free Sample Report
U.S. Dual And Multi Energy Computed Tomography Market Trends
The dual and multi-energy computed tomography market in the U.S. held the largest share in the North America region in 2025, driven by substantial investments in healthcare technology, a high prevalence of chronic diseases such as cancer, and an aging population. The presence of key industry players promotes innovation and competition within the sector. Moreover, increased government funding for healthcare initiatives enhances access to advanced imaging technologies.
Europe Dual And Multi Energy Computed Tomography Market Trends
Europe dual and multi energy computed tomography market held substantial market share in 2024, fueled by rising healthcare expenditures, ongoing technological advancements, and an increasing prevalence of chronic diseases. The growing aging population plays a significant role in increasing demand for advanced imaging solutions. Moreover, supportive regulatory frameworks for innovative medical technologies encourage the widespread adoption of dual-energy CT systems across diverse healthcare settings.
The dual and multi energy computed tomography market in UK is expected to grow lucratively in the forecast period. Japan’s aging population, with over 1 in 10 citizens aged 80 or older, drives a heightened demand for diagnostic imaging services. As the country consistently ranks as the world’s oldest population, this demographic shift fuels market growth. Enhanced investments in healthcare technology and growing awareness of early disease detection further accelerate adoption of advanced imaging solutions.
Asia Pacific Dual And Multi Energy Computed Tomography Market Trends
Asia Pacific dual and multi energy computed tomography market is expected to register the fastest CAGR over the forecast period. The region is experiencing a surge in chronic disease incidences, rapid urbanization, and increasing demand for advanced medical imaging technologies. The expansion of healthcare infrastructure and rising disposable incomes facilitate market growth as more patients seek quality diagnostic services. These trends underscore the growing importance of dual and multi-energy CT systems in improving healthcare outcomes across the region.
The dual and multi energy computed tomography market in Japan is projected to grow at the fastest CAGR of 8.9% over the forecast period, supported by an aging population. This demographic trend intensifies the demand for advanced diagnostic imaging solutions. Japan’s strong commitment to healthcare innovation and investment in cutting-edge medical technologies also aid market growth in the country.
Key Dual And Multi Energy Computed Tomography Company Insights
Some key companies operating in the market include Koninklijke Philips N.V.; GE HealthCare; Siemens Healthcare Limited; CANON MEDICAL SYSTEMS CORPORATION; among others. These companies are investing in product launches and conducting clinical trials to determine the clinical efficacy of these systems.
-
GE HealthCare specializes in advanced dual and multi-energy computed tomography systems that enhance diagnostic capabilities. Their Revolution Ascend platform employs Gemstone Spectral Imaging and rapid kV switching to optimize image quality and support early disease detection.
-
Shimadzu Corporation provides dual-energy CT systems designed to enhance diagnostic accuracy and patient safety. Their advanced imaging technologies improve material differentiation within the body, facilitating tumor and cardiovascular disease detection while reducing radiation exposure during procedures.
Key Dual And Multi Energy Computed Tomography Companies
The following key companies have been profiled for this study on the dual and multi energy computed tomography market.
-
Koninklijke Philips N.V.
-
GE HealthCare
-
Siemens Healthcare Limited
-
CANON MEDICAL SYSTEMS CORPORATION
-
FUJIFILM Corporation
-
Shimadzu Corporation
-
Koning Health
-
Neusoft Medical Systems Co., Ltd.
-
Carestream Health
-
PLANMECA OY
-
Hitachi High-Tech Corporation
-
Stryker
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Koninklijke Philips N.V.; GE HealthCare; Siemens Healthcare Limited; FUJIFILM Corporation; Shimadzu Corporation; Hitachi High-Tech Corporation; Stryker)
Mature companies focus on expanding comprehensive medical imaging devices portfolios comprising CT, MRI, nuclear imaging, X-rays and others. They emphasize global manufacturing capabilities, hospital contracting, supply chain optimization, and continuous product innovation to maintain market leadership.
Extensive distribution networks and strong relationships with hospitals, ambulatory surgical centers, and group purchasing organizations (GPOs). Broad product portfolios enable bundled procurement agreements and recurring revenue generation from high-volume surgical procedures. Significant financial resources support R&D investments, regulatory compliance, and large-scale manufacturing operations.
Dependence on large-scale manufacturing and global supply chains may increase exposure to raw material shortages and logistical disruptions. Pricing pressures from healthcare cost-containment initiatives and competitive bidding processes can impact margins. Large organizational structures may reduce agility in responding to niche market demands and emerging technologies.
Emerging Players (CANON MEDICAL SYSTEMS CORPORATION; Koning Health; Neusoft Medical Systems Co., Ltd.; Carestream Health; PLANMECA OY)
Emerging companies prioritize cost-effective medical imaging solutions, specialty-focused product development, ergonomic instrument designs, and differentiated medical imaging technologies. Many focus on expanding regional presence, targeting underserved healthcare facilities, and offering alternatives to premium-priced products from established manufacturers.
Agile product development processes enable faster innovation and adaptation to evolving surgeon preferences. Competitive pricing strategies, specialty-focused portfolios, and flexibility in addressing niche clinical requirements provide opportunities to gain market share. Ability to target emerging markets and outpatient surgical settings supports growth.
Limited global distribution infrastructure and lower brand recognition compared with multinational competitors. Smaller R&D budgets and manufacturing scale may constrain product development and market expansion. Dependence on distributor partnerships and challenges associated with regulatory approvals may slow penetration into highly regulated markets.
Recent Developments
-
In January 2025, Philips launched its AI-enabled CT 5300 in India, featuring advanced diagnostic capabilities and streamlined workflows, at the Asian Oceanian Congress of Radiology.
-
In December 2024, Siemens Healthineers expanded its photon-counting CT portfolio in the USA, introducing new scanners with high image quality at low radiation doses.
-
In December 2024, GE HealthCare showcased over 40 innovations, including AI-enabled technologies, at RSNA in Chicago, aiming to enhance precision care and improve operational efficiencies in the USA.
-
In December 2024, Neusoft Medical Systems showcased its AI-powered medical imaging solutions at the RSNA Annual Meeting in Chicago, aiming to enhance diagnostic precision and improve global access to quality care.
-
In May 2024, Siemens Healthineers hosted a clinical symposium in Quang Ninh, Vietnam, focusing on Dual Energy CT’s impact on cardiovascular imaging, marking their first collaboration in the region.
Dual And Multi Energy Computed Tomography Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.0 billion
Estimated market size in 2026
USD 1.1 billion
Projected market size by 2033
USD 1.8 billion
Growth rate
CAGR of 7.0% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; South Korea; Thailand; Australia; Brazil; Argentina; South Africa; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Koninklijke Philips N.V.; GE HealthCare; Siemens Healthcare Limited; CANON MEDICAL SYSTEMS CORPORATION; FUJIFILM Corporation; Shimadzu Corporation; Koning Health; Neusoft Medical Systems Co., Ltd.; Carestream Health; PLANMECA OY; Hitachi High-Tech Corporation; Stryker
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Dual And Multi Energy Computed Tomography Market Report Segmentation
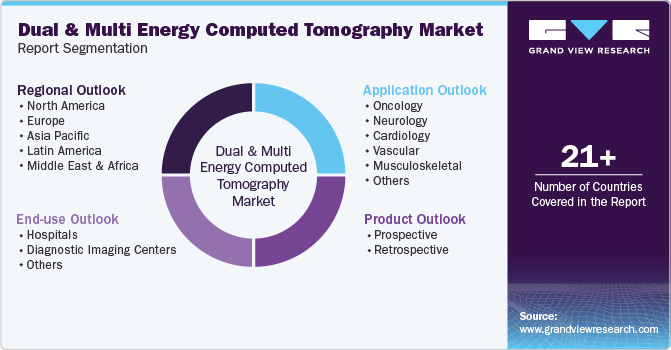
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global dual and multi energy computed tomography market report based on product, application, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Prospective
-
Retrospective
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Oncology
-
Neurology
-
Cardiology
-
Vascular
-
Musculoskeletal
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Diagnostic Imaging Centers
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The dual and multi energy computed tomography market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each dual and multi energy computed tomography segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Product
Revenue capture definition
Prospective
Revenue is generated through dual and multi-energy CT examinations performed using prospectively acquired spectral imaging data, where multiple energy datasets are captured simultaneously during the initial scan. Healthcare providers capture value through enhanced diagnostic information, reduced need for follow-up imaging, lower radiation exposure, and improved workflow efficiency across oncology, cardiovascular, neurological, and abdominal imaging applications.
Retrospective
Revenue is derived from dual and multi-energy CT studies utilizing retrospectively reconstructed spectral datasets from acquired imaging scans. Imaging centers and hospitals generate value by leveraging advanced post-processing capabilities, material decomposition, virtual monoenergetic imaging, and tissue characterization tools that enhance diagnostic confidence without requiring additional patient scanning, thereby improving utilization of installed CT infrastructure.
Application
Revenue capture definition
Oncology
Revenue is captured through the use of dual and multi-energy CT systems for tumor detection, lesion characterization, treatment planning, therapy monitoring, and disease staging across various cancer types. Healthcare providers benefit from enhanced tissue differentiation, iodine quantification, and improved visualization of malignant lesions that support precision oncology initiatives.
Neurology
Revenue is generated through spectral CT imaging utilized for the diagnosis and assessment of stroke, intracranial hemorrhage, brain tumors, neurovascular disorders, and other neurological conditions. Market participants capture value through advanced tissue characterization, artifact reduction, and improved differentiation between hemorrhagic and ischemic abnormalities.
Vascular
Revenue flows from the utilization of dual and multi-energy CT systems in peripheral vascular imaging, aortic disease assessment, pulmonary embolism detection, and vascular intervention planning. The segment benefits from enhanced vessel visualization, plaque characterization, contrast optimization, and improved diagnostic accuracy in complex vascular conditions.
Cardiology
Revenue is derived from advanced cardiac imaging applications including coronary artery disease assessment, myocardial perfusion evaluation, structural heart analysis, and cardiac intervention planning. Healthcare providers capture value through superior visualization of coronary anatomy, reduction of blooming artifacts, and improved characterization of calcified and non-calcified plaques.
Musculoskeletal
Revenue is generated through the application of dual and multi-energy CT imaging for bone, joint, trauma, and orthopedic evaluations. Market participants benefit from capabilities such as bone marrow edema detection, implant artifact reduction, gout assessment, and enhanced differentiation of musculoskeletal tissues that support accurate diagnosis and treatment planning.
Other Applications
Revenue is captured through the use of dual and multi-energy CT systems across abdominal imaging, pulmonary imaging, emergency medicine, urology, hepatology, and other specialty diagnostic areas. The segment benefits from broad utilization of spectral imaging capabilities for improved tissue characterization, material differentiation, and clinical decision support across diverse medical conditions.
End use
Revenue capture definition
Hospitals
Revenue is generated through the procurement and utilization of dual and multi-energy CT systems by public and private hospitals for routine diagnostics, emergency imaging, surgical planning, oncology management, and advanced clinical applications. Manufacturers benefit from large-scale capital equipment purchases, service contracts, software upgrades, and recurring imaging procedure volumes.
Diagnostic Imaging Centers
Revenue is captured through the deployment of dual and multi-energy CT systems in independent imaging centers and outpatient diagnostic facilities. Market participants benefit from increasing demand for advanced non-invasive imaging services, high patient throughput, and referrals for specialized spectral CT examinations across multiple disease areas.
Others
Revenue is derived from the adoption of dual and multi-energy CT technologies by academic medical centers, research institutions, specialty clinics, government healthcare facilities, and ambulatory care settings. Value is generated through clinical research activities, advanced diagnostic programs, and specialized imaging applications that require enhanced spectral imaging capabilities.
Estimation Model
Step No.
Step Title
Key Question
Process Steps
Data Sources
01
Scope Definition
What is being sized?
Define Dual and Multi-Energy Computed Tomography Categories
Scope Type, Application, and Use Case
Establish Geographic Coverage (Global/Regional)
Align to base year & forecast horizon (2020–2030)
ACRS, ESR, WHO, FDA, CE Mark
02
Build the Product Base
How large is total addressable market?
Collect Annual CT Device Volumes Installed
Identify Dual Energy and Multi-Energy CT-Capable Systems
Assess Replacement Cycles
Develop Installed Forecasts
Company annual reports, Hospital procurement data, Radiology statistics
03
Estimate Utilization & Procedure Volumes
What portion of procedures use disposable devices?
Estimate Annual CT Procedures per Installed System
Determine Share of Exams Utilizing Dual/Multi-Energy Imaging
Map Procedure Volumes Across Oncology, Cardiology, Neurology, Vascular, and Musculoskeletal Applications
Validate Utilization Rates through Radiologist and Hospital Interviews
Radiology surveys, Hospital imaging statistics, Trade surveys
04
Revenue Conversion
How does volume become revenue?
Determine System ASPs by Technology Type and Region
Estimate Revenue from Equipment Sales
Apply Regional Pricing Variations
Cross-check with Company Revenues and Public Filings
Distributor pricing sheets, Procurement data, Import/export databases, Expert interviews
Delivered Customization
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Landscape Analysis
Conducted a comprehensive competitive landscape assessment for the global dual and multi-energy CT market, covering leading manufacturers of spectral CT, dual-source CT, rapid kVp switching CT, dual-layer detector CT, and photon-counting CT systems. The study evaluated product portfolios, installed base presence, technological differentiation, detector architectures, AI-enabled imaging capabilities, service offerings, pricing strategies, distribution networks, regulatory approvals, strategic partnerships, and regional expansion initiatives across hospitals, diagnostic imaging centers, and academic medical institutions. It also assessed innovation trends related to spectral imaging, material decomposition, low-dose imaging workflow automation, and next-generation photon-counting technologies adopted by both established imaging OEMs and emerging technology developers.
Enables stakeholders to understand competitive positioning, technology leadership, commercialization strategies, and market share dynamics shaping the global dual and multi-energy CT market. Supports informed decision-making related to vendor selection, capital equipment investments, procurement planning, technology benchmarking, partnership opportunities, and regional market expansion. Helps manufacturers identify innovation gaps, strengthen business strategies, and enhance competitive go-to-market approaches within diagnostic imaging segments.
Segment by Application Analysis
Conducted a detailed segment-level assessment of the dual and multi-energy CT market across key clinical applications including Oncology, Neurology, Vascular, Cardiology, Pulmonology, and Other Applications. The study analyzed procedure volume, product imaging utilization trends, disease burden trends, clinical workflow efficiency, contrast utilization rates, and adoption trends across different hospital and diagnostic imaging center tiers, correlating utilization and disease incidence rates.
Enables stakeholders to gain granular insights into high-growth clinical applications, evolving imaging utilization trends, and specialty-specific diagnostic requirements. Supports strategic alignment between product development priorities and clinical workflow optimization, helping manufacturers identify potential areas of emerging clinical demand and technology adoption.
Macroeconomic Analysis
Conducted an in-depth driver and macroeconomic analysis focused on healthcare expenditure growth, global imaging budgets, and diagnostic imaging procedure volumes across developed and emerging economies. The study analyzed healthcare spending trends, radiology budgets, hospital capital budgets, imaging reimbursement models, and private healthcare investments, including hospital capital equipment technology replacement cycles and diagnostic imaging upgrade programs. Additionally, it assessed regulatory developments, procurement policies, inflationary pressures, supply chain dynamics, semiconductor availability, and international trade factors affecting CT system manufacturing and deployment.
Enables stakeholders to understand macroeconomic factors influencing CT system demand, procurement cycles, and technology replacement trends. Supports long-term strategic planning by providing insights on investment distribution, capacity planning, and budget optimization strategies. Helps manufacturers anticipate changing healthcare spending patterns and increasing demand for advanced diagnostic imaging solutions.
Frequently Asked Questions About This Report
Oncology segment led the market with the largest revenue share of 27.3% in 2025, while vascular applications is the fastest-growing area.
Hospitals segment led the market with the largest revenue share of 42.8% in 2025, while diagnostic imaging centers is the fastest-growing segment.
North America dominated with a 37.1% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The prospective technique accounted for the largest share of 74.5%. In 2025. The technique that occurs before the patient needs to be scanned is the prospective technique. The prospective technique further includes dual source, single source consecutive, single source twin-beam, single source sequential, and rapid kVPswitch.
The global dual and multi energy computed tomography market size was estimated at USD 1.0 billion in 2025 and is expected to reach USD 1.1 billion in 2026.
The global dual and multi energy computed tomography market is expected to grow at a compound annual growth rate of 7.0% from 2026 to 2033 to reach USD 1.8 billion by 2033.
Some key players operating in the dual and multi energy computed tomography market include Koninklijke Philips N.V., GE Healthcare, Siemens Healthineers, Canon Medical Systems, Fujifilm Holdings Corporation, Shimadzu Corporation, Koning Corporation, Neusoft Medical Systems Co. Ltd, CareStream Health, Planmeca Group, Hitachi Healthcare Systems, Stryker Corporation
Key factors that are driving the dual and multi energy computed tomography market growth include the growing prevalence of various lifestyle-associated chronic diseases such as cancer and cardiovascular conditions and increasing demand for advanced imaging solutions.
About the Author(s)
Medical Imaging Research Team
Healthcare · Medical ImagingThis report was authored by the medical imaging research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical imaging segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


