
- Home
- »
- Healthcare IT
- »
-
E-prescribing Market Size, Share & Trends Report, 2033GVR Report cover

E-prescribing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Solutions, Services), By Delivery Mode (Web/Cloud-Based, On Premise), By End-use (Hospital, Pharmacy), By Usage Methods, By Substances, By Specialties, By Region, And Segment Forecasts
Market Size, 2025
$5.9BMarket Estimate, 2026
$7.3BMarket Forecast, 2033
$27.6BCAGR, 2026–2033
21.0%E-prescribing Market Summary
The global e-prescribing market size was valued at USD 5.9 billion in 2025 and is projected to grow from USD 7.3 billion in 2026 to USD 27.6 billion by 2033, at a CAGR of 21.0% from 2026 to 2033. North America dominated the market, accounting for the revenue share of 43.2% in 2025. This growth is attributed to government initiatives and regulatory mandates supporting electronic prescribing, the growing adoption of electronic health records (EHRs) and healthcare IT systems, and the expansion of telehealth and remote healthcare services, which are key drivers of the market growth.
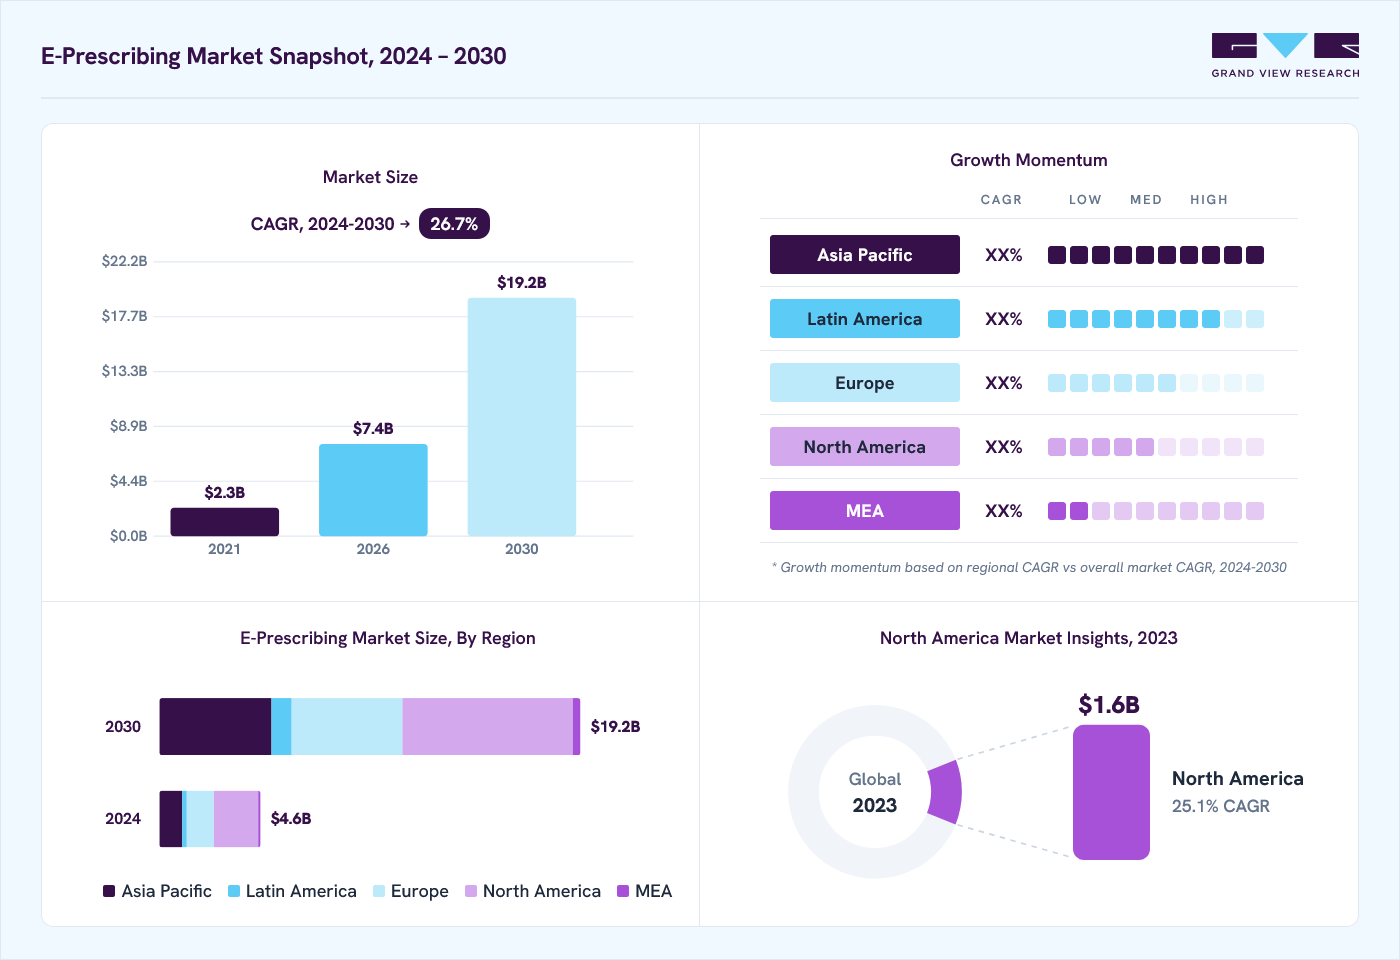 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Solutions segment held the largest market share of 56.9% in 2025.
- By delivery mode: Web/cloud based segment dominated the market with a revenue share of 62.9% in 2025.
- By end-use: Hospitals segment led the market with the largest revenue share of 37.8% in 2025.
- By specialties: Sports medicine segment dominated the market with a revenue share of 23.3% in 2025.
- By usage methods: Handheld segment accounted for the largest market revenue share in 2025.
Regional Highlights
- Largest regional market: North America (43.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 5.9 Billion
- Estimated market size in 2026: USD 7.3 Billion
- Projected market size by 2033: USD 27.6 Billion
- CAGR (2026-2033): 21.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
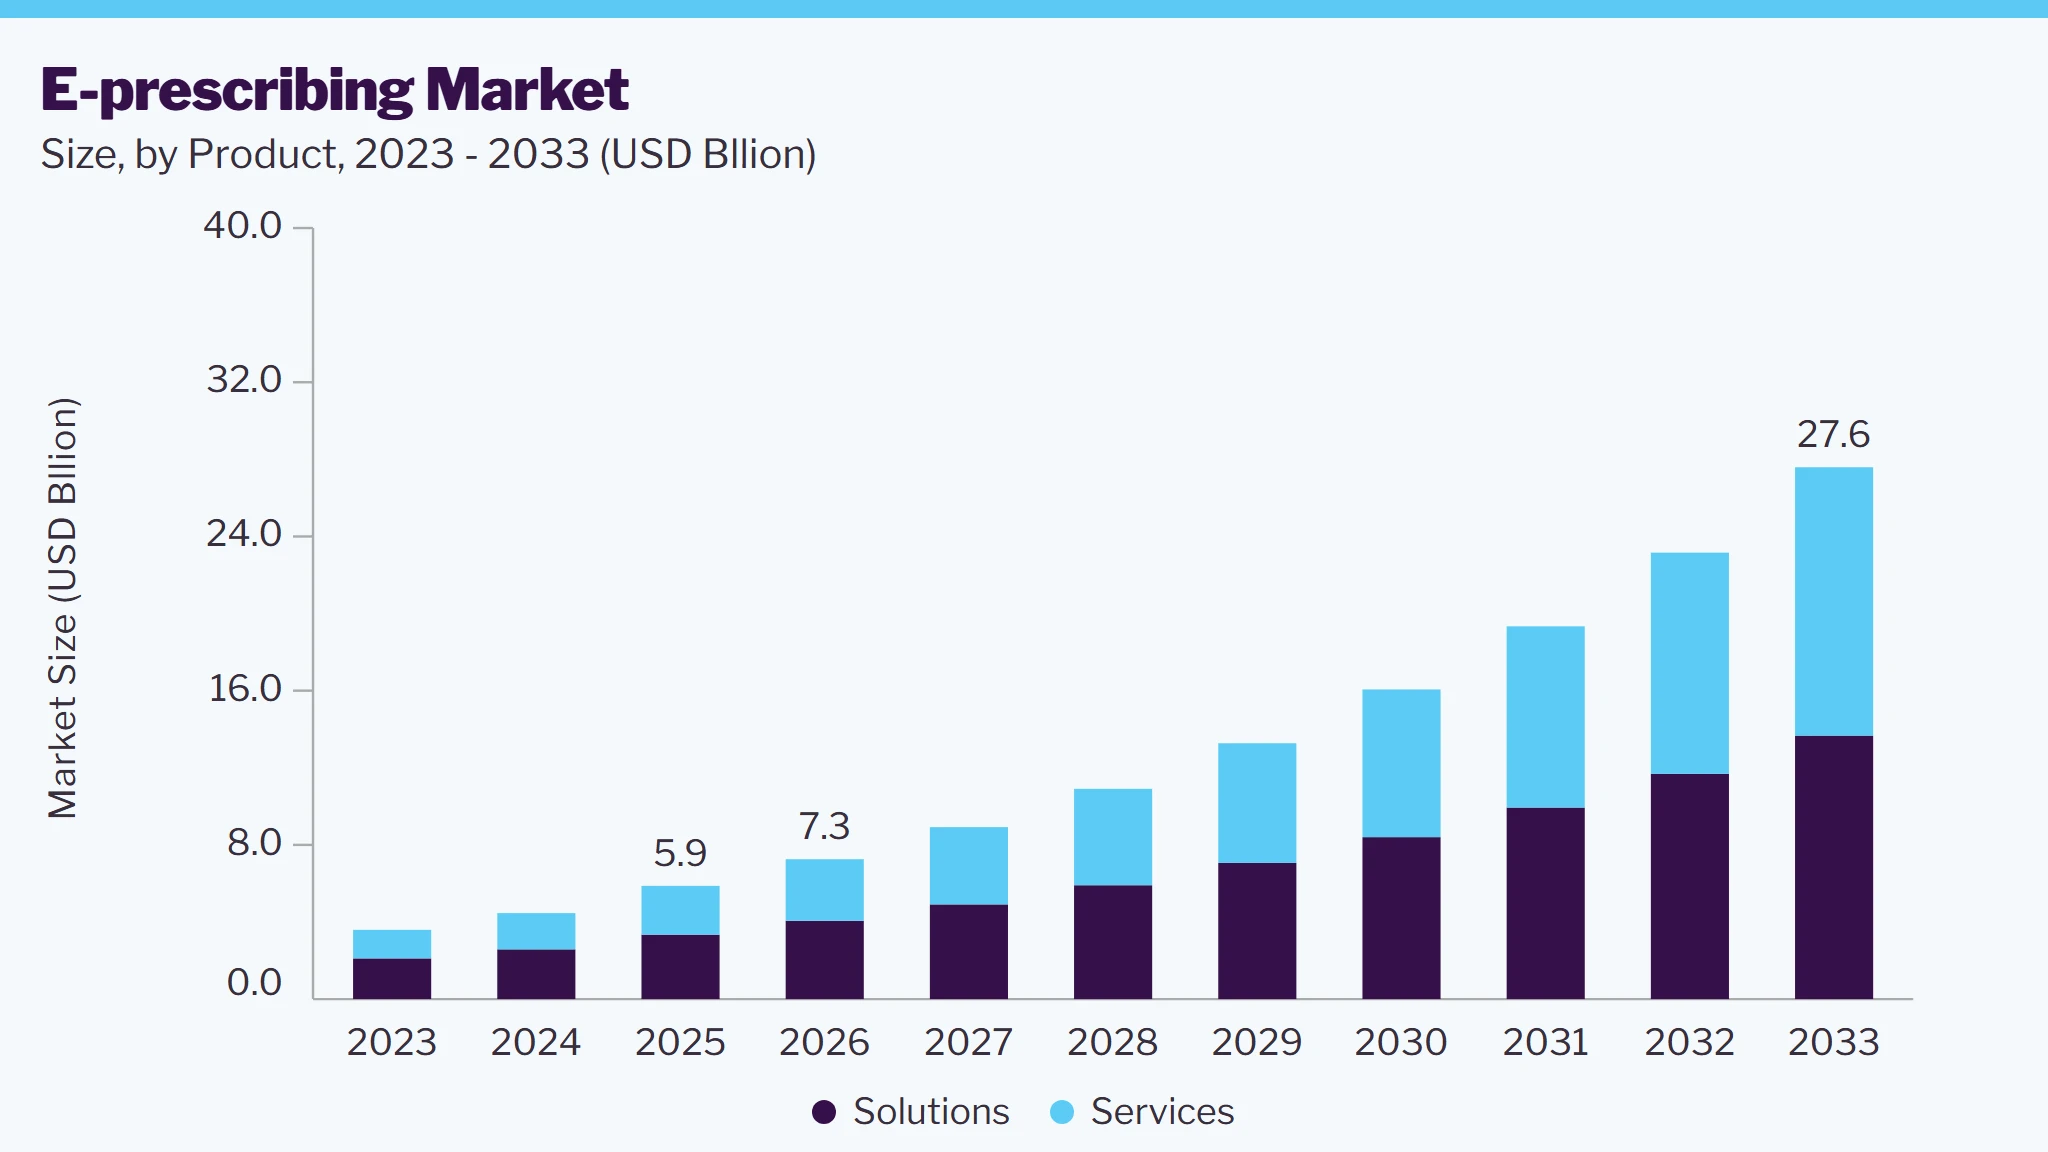 To learn more about this report, Download Free Sample Report
Market Dynamics
The e-prescribing industry is driven by government initiatives and regulatory mandates supporting electronic prescribing, the growing adoption of electronic health records (EHRs) and healthcare IT systems, and the expansion of telehealth and remote healthcare services. Healthcare providers are increasingly adopting e-prescribing solutions to improve prescribing accuracy, enhance workflow efficiency, reduce medication errors, and ensure regulatory compliance.
In addition, advancements in digital health technologies, including cloud-based platforms, clinical decision support, and interoperability with EHRs, pharmacy systems, and health information exchanges, are improving prescription management and care coordination. The increasing focus on patient safety, healthcare cost reduction, and streamlined clinical workflows is further supporting the adoption of e-prescribing across healthcare settings.
The increasing adoption of electronic health records and healthcare IT systems is a major driver of market growth, as e-prescribing is typically integrated into EHR platforms. Healthcare providers are implementing digital clinical workflows to improve care coordination, streamline prescription management, maintain comprehensive patient medication histories, and comply with regulatory requirements. The integration of e-prescribing with EHR systems also enables real-time clinical decision support, drug interaction checks, allergy alerts, and formulary verification, helping reduce medication errors while improving prescribing efficiency and patient safety. As hospitals, physician practices, and ambulatory care centers continue investing in digital healthcare infrastructure, demand for integrated e-prescribing solutions is expected to increase.
Market players are continually developing innovations in e-prescription and EHR platforms. For instance, in August 2025, Oracle Health launched its next-generation, AI-powered, cloud-based EHR for ambulatory providers, embedding AI into clinical workflows and integrating e-prescribing capabilities to enhance care delivery and reduce administrative burden. Similarly, in November 2025, Oracle Health's new EHR received ONC Health IT certification and met U.S. DEA Electronic Prescriptions for Controlled Substances (EPCS) requirements, enabling healthcare organizations to securely manage electronic prescriptions and support interoperability and regulatory compliance.
Data security and patient privacy concerns remain significant constraints on the global market because electronic prescriptions involve transmitting and storing sensitive patient health information across interconnected healthcare systems. Cyberattacks, ransomware incidents, unauthorized access, and data breaches can compromise confidential medical and prescription records, resulting in financial losses and reputational damage for healthcare organizations.
Compliance with regulations such as HIPAA in the U.S. and the GDPR in Europe requires healthcare providers and solution vendors to implement robust cybersecurity measures, including encryption, authentication, and access controls. These requirements increase implementation complexity and operational costs, particularly for smaller healthcare providers with limited IT resources. As a result, concerns about data protection and cybersecurity continue to slow the adoption of e-prescribing solutions in some healthcare settings.
The integration of artificial intelligence (AI) into e-prescribing platforms is creating significant growth opportunities by improving prescribing accuracy, streamlining clinical workflows, and supporting better medication management. AI-powered solutions can analyze patient records, medication history, allergies, laboratory results, and potential drug interactions to provide real-time clinical decision support and personalized prescribing recommendations. These capabilities help reduce medication errors, improve patient safety, lower physician workload, and enhance the overall efficiency of the prescribing process. As healthcare providers increasingly adopt AI-enabled digital health solutions, demand for intelligent e-prescribing platforms is expected to grow.
Market players are actively incorporating AI into their e-prescribing and EHR solutions to strengthen medication management capabilities. For instance, in March 2025, Elsevier enhanced its ClinicalKey AI platform by integrating it with Epic's electronic health record (EHR) system and DrFirst's iPrescribe platform. The integration enables clinicians to access AI-powered, evidence-based clinical decision support directly within their prescribing workflow, improving medication selection, streamlining clinical decision-making, and reducing the time required to access critical patient care information.
"Making this world-class, evidence-based research tool available within the iPrescribe by DrFirst app gives healthcare providers across all practice sizes and specialties instant access to AI-powered conversational searches of clinical literature, helping them make informed prescribing decisions from anywhere."
Colin Banas, M.D., M.H.A., Chief Medical Officer, DrFirst.
Market Characteristics & Concentration
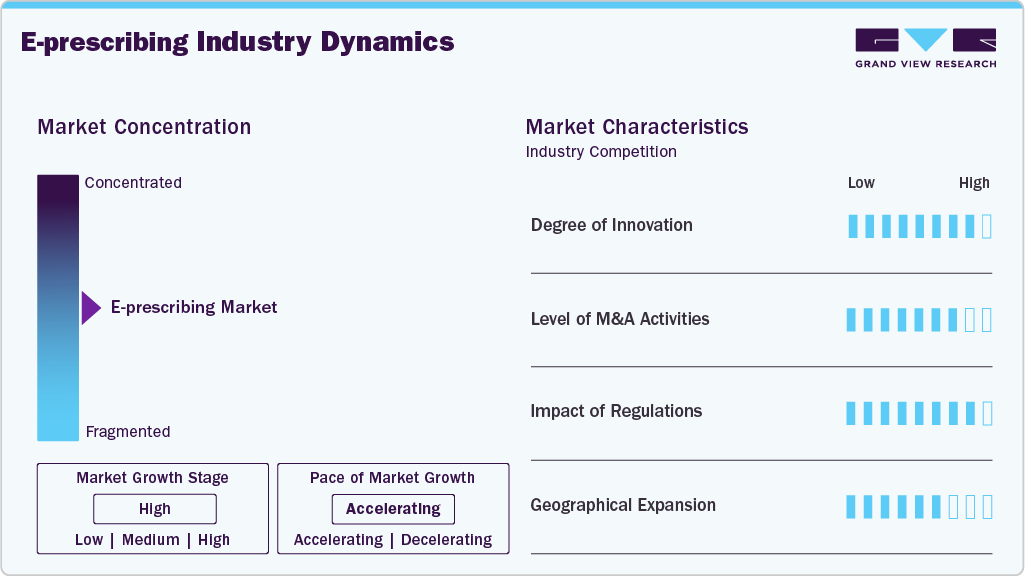
The degree of innovation in the e-prescribing industry is high, driven by advancements in AI, cloud-based healthcare platforms, clinical decision support, and interoperability technologies. For instance, in February 2025, Surescripts launched its Prior Authorization Automation solution, a first-of-its-kind technology that automates prior authorization workflows between healthcare providers and payers. The solution reduces manual administrative tasks, accelerates access to medication, and improves prescribing efficiency by integrating directly into existing clinical workflows.
 To learn more about this report, Download Free Sample Report
"Our focus is to make generative AI practical within clinicians' everyday workflows so they can spend more time caring for patients and less time navigating technology."
Seth Howard, Executive Vice President of R&D, Epic Systems Corporation.
The level of partnerships and collaboration activities in the e-prescribing industry is high. For instance, in July 2025, Hackensack Meridian Health partnered with DrFirst to integrate AI-powered medication management tools into its Epic EHR system. The collaboration enables clinicians to access medication history, prescription price transparency, electronic prior authorization, and e-prescribing capabilities within a unified workflow, improving prescribing efficiency and patient care.
"This isn't about using technology for technology's sake. It's about giving our clinicians better tools to help patients receive the right medications quickly, safely, and with less administrative burden."
-Robert C. Garrett, FACHE, Chief Executive Officer, Hackensack Meridian Health.
Regulations significantly affect the e-prescribing industry as governments continue to strengthen policies promoting secure electronic prescribing, interoperability, and patient data protection. Regulations related to Electronic Prescribing of Controlled Substances, HIPAA, GDPR, and national digital health initiatives require solution providers to implement robust security, authentication, and data privacy measures. These regulatory frameworks encourage the adoption of standardized, secure e-prescribing solutions, improving prescription accuracy, reducing fraud, and supporting healthcare interoperability.
The market is expanding as companies strengthen their presence through cloud-based healthcare platforms, strategic acquisitions, and the expansion of digital health infrastructure across developed and emerging markets. Vendors are increasing investments in localized healthcare IT solutions, interoperable EHR platforms, and pharmacy connectivity to improve access to electronic prescribing services.
Analyst Perspective
The e-prescribing market is evolving beyond basic electronic prescription generation toward integrated, workflow-oriented solutions that connect prescribing with patient records, scheduling, payments, clinical documentation, and other healthcare functions. The launch of Boulevard’s ePrescribe functionality reflects this broader shift, particularly in med spas and clinical wellness practices, where providers increasingly seek unified platforms to streamline clinical and administrative workflows. Integration of prescribing capabilities within broader healthcare software ecosystems can reduce system switching, minimize duplicate data entry, and improve workflow efficiency. Going forward, continued integration with electronic health records, clinical decision-support tools, pharmacy networks, and patient-management platforms is expected to strengthen the role of e-prescribing as a core component of connected healthcare delivery.
Product Insights
The solutions segment dominated the market with the largest revenue share of 56.9% in 2025. Increasing adoption of integrated e-prescribing platforms, growing digitalization of healthcare, and the high value of software licensing and subscription models. The segment is further divided into integrated solutions and standalone solutions. Integrated solutions seamlessly connect with electronic health records, electronic medical records, and practice management systems, while standalone solutions are designed to support specific prescribing functions, making them suitable for smaller healthcare providers and independent practices.
The services segment is anticipated to grow at the fastest CAGR of 23.4% over the forecast period. Rising demand for implementation, technical support, training, consulting, and network connectivity services is driving growth in the segment. As healthcare organizations continue adopting cloud-based e-prescribing platforms and interoperable healthcare IT systems, the need for ongoing support and integration services is expected to increase. Among service offerings, support services are projected to account for the largest share due to their role in ensuring uninterrupted system performance and regulatory compliance.
Delivery Mode Insights
The web/cloud-based segment accounted for the largest market revenue share of 62.9% in 2025, owing to its lower implementation costs, scalability, ease of deployment, and remote accessibility. Cloud-based platforms are particularly attractive to physician offices, ambulatory care centers, and small- to medium-sized healthcare organizations seeking cost-effective digital prescribing solutions. Leading healthcare IT companies such as Oracle Health, athenahealth, Veradigm, and eClinicalWorks continue to expand their cloud-based offerings.
The on-premises segment is expected to grow at the fastest CAGR from 2026 to 2033. Large hospitals and integrated healthcare systems continue to prefer on-premise deployments due to enhanced control over sensitive patient data, stronger internal security policies, and customization capabilities. Growing investments in cybersecurity and healthcare IT infrastructure are further supporting demand for on-premise solutions.
End-use Insights
The hospitals segment led the market with the largest revenue share of 37.8% in 2025. This is due to the widespread implementation of enterprise EHR systems, increasing patient volumes, and growing adoption of integrated digital prescribing workflows. Hospitals also benefit from centralized IT infrastructure and regulatory compliance programs, which support the large-scale deployment of e-prescribing systems.
The pharmacy segment is anticipated to grow at the fastest CAGR during the forecast period. Increasing adoption of electronic prescription processing, prescription refill automation, and real-time prescription benefit verification is improving operational efficiency and medication adherence. Integration with e-prescribing networks is further streamlining pharmacy workflows and enhancing patient convenience.
Usage Methods Insights
The handheld segment accounted for the largest market revenue share in 2025, driven by the growing use of smartphones and tablets among healthcare professionals. Mobile e-prescribing applications enable clinicians to securely access medication history, formularies, clinical decision support, and patient information from virtually any location, improving workflow flexibility.
The computer-based devices segment is expected to grow at the fastest CAGR during the forecast period. Desktop and laptop-based e-prescribing systems remain widely used across hospitals and physician practices due to their integration with EHR platforms, advanced clinical workflows, and secure connectivity with pharmacies and healthcare networks.
Substances Insights
The controlled substances segment accounted for the largest market revenue share in 2025, due to increasing adoption of Electronic Prescribing of Controlled Substances and growing regulatory requirements aimed at preventing prescription fraud, medication misuse, and opioid abuse. Secure authentication, identity verification, and audit capabilities are further driving adoption in this segment.
The non-controlled substances segment is anticipated to grow at the fastest CAGR of 28.6% from 2026 to 2033. Rising prescription volumes for chronic diseases such as diabetes, hypertension, cardiovascular disorders, and infectious diseases, along with increasing digitalization of prescribing workflows across primary care and specialty practices, are expected to support continued growth in this segment.
Specialties Insights
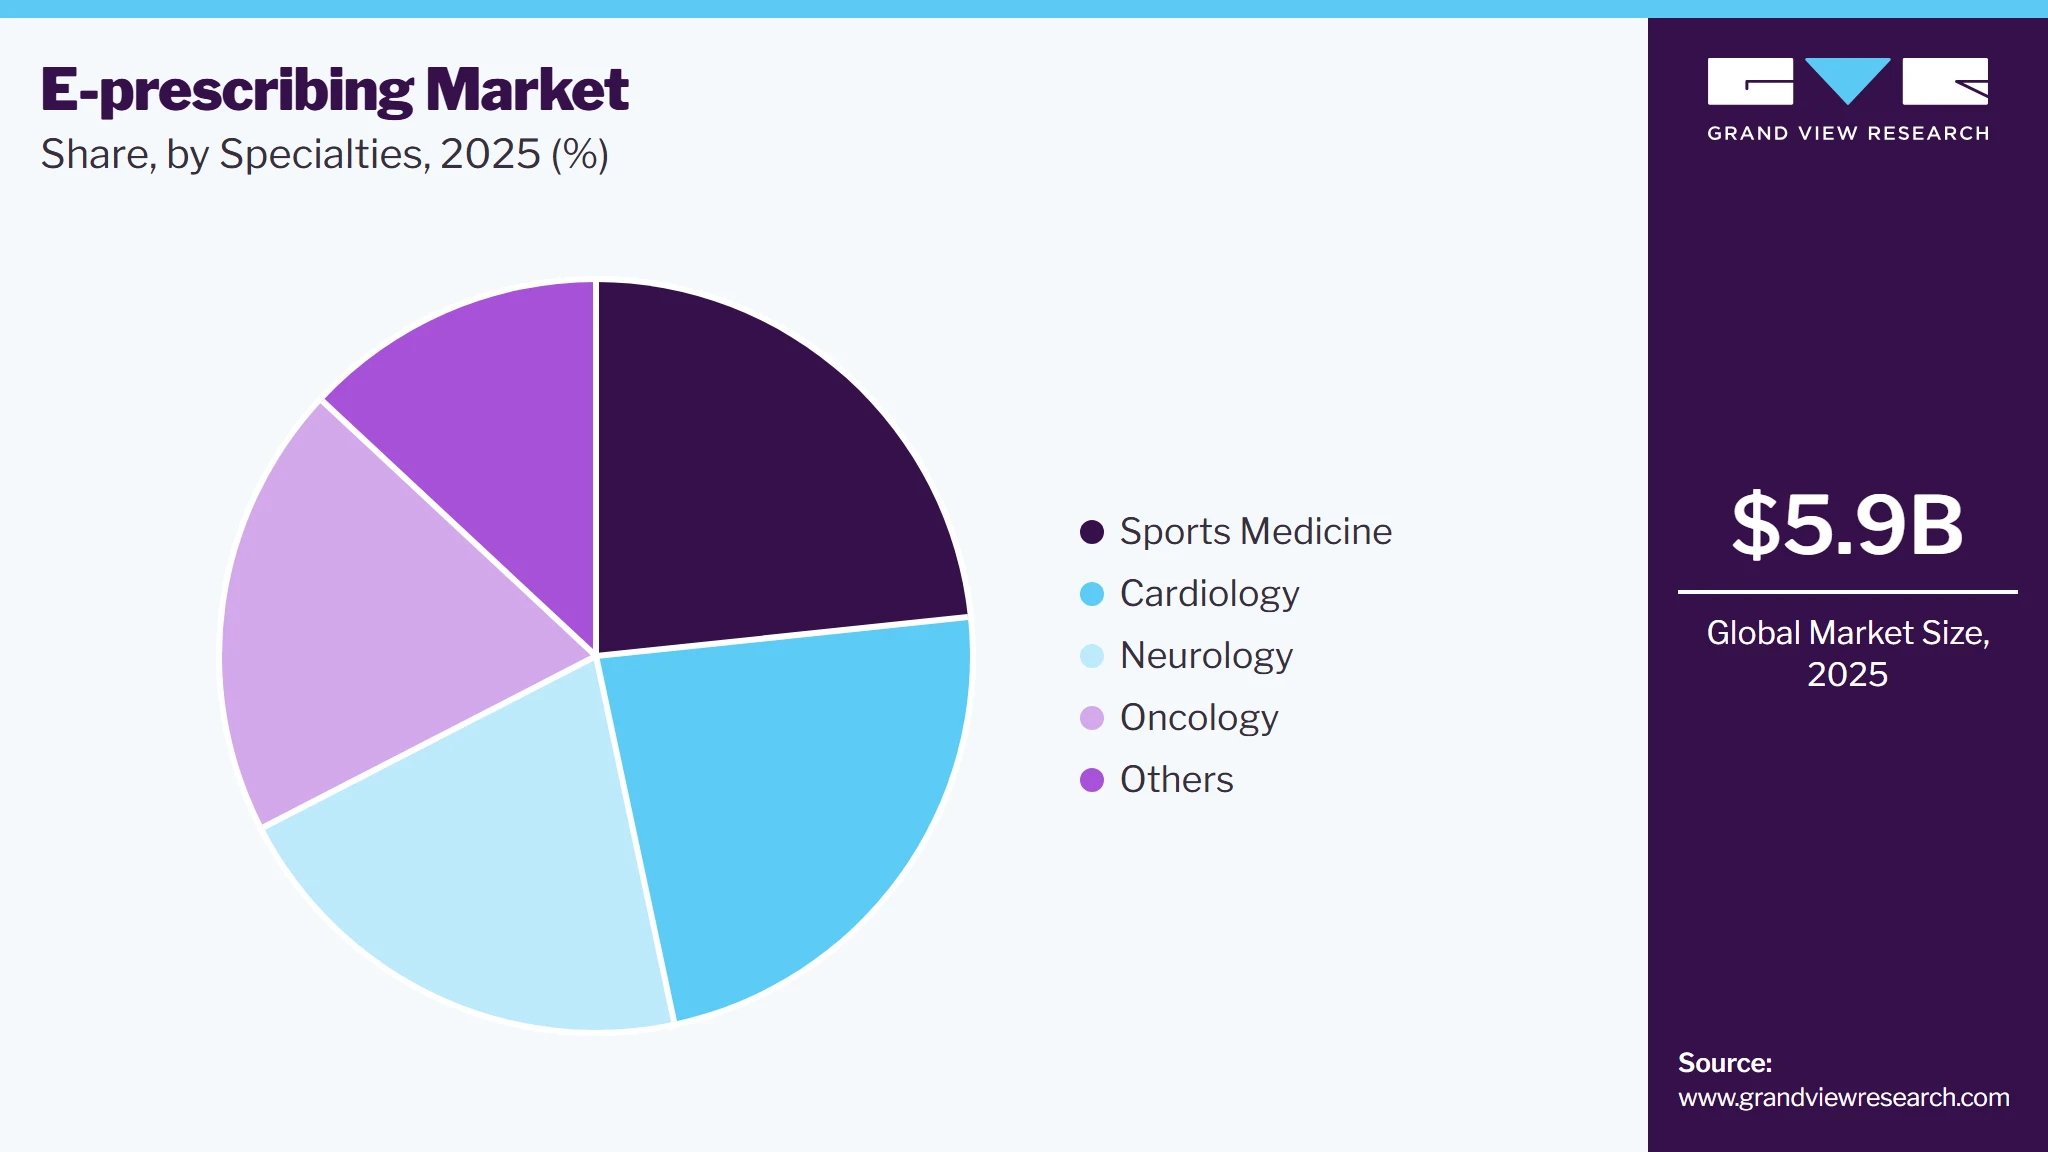
The sports medicine segment led the market with the largest revenue share of 23.3% in 2025. This dominance is attributed to the increasing adoption of e-prescribing solutions in outpatient sports medicine clinics and orthopedic practices to streamline medication management, improve prescribing accuracy, and enhance clinical workflow efficiency. The growing volume of sports-related injuries and musculoskeletal disorders has further contributed to the widespread use of electronic prescribing in this specialty.
 To learn more about this report, Download Free Sample Report
The cardiology segment is anticipated to grow at the fastest CAGR during the forecast period from 2026 to 2033. The increasing prevalence of cardiovascular diseases, rising demand for long-term medication management, and growing adoption of digital healthcare technologies are driving segment growth. E-prescribing solutions enable cardiologists to improve prescription accuracy, monitor medication histories, support clinical decision-making, and enhance patient adherence, making them an essential component of cardiovascular care.
Regional Insights
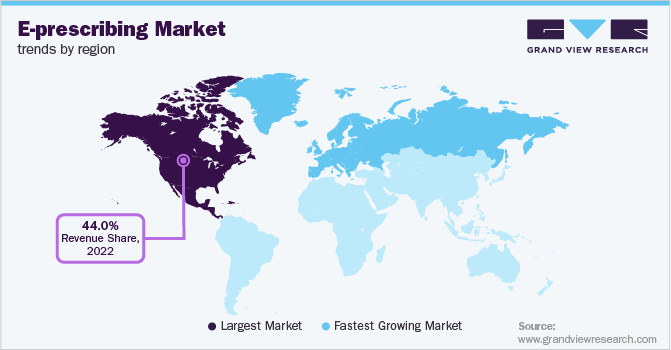
The North America e-prescribing market held the largest revenue share of 43.2% in 2025. This dominance is due to advanced healthcare infrastructure, high adoption of digital health technologies, and supportive government regulations. Widespread integration of electronic health records, robust IT systems, and the presence of major solution providers facilitate seamless implementation of e-prescribing solutions. In addition, initiatives such as the U.S. Centers for Medicare & Medicaid Services (CMS) promoting electronic prescribing of controlled substances, rising focus on reducing medication errors, and growing demand for efficient healthcare workflows further drive the region’s dominance in the market.
 To learn more about this report, Download Free Sample Report
U.S. E-prescribing Market Trends
The e-prescribing market in the U.S. accounted for the largest market revenue share in North America in 2025, due to the high adoption of EHR systems, favorable federal regulations supporting EPCS, and the increasing use of digital health technologies across hospitals, physician practices, and pharmacies. Growing investments in AI-enabled clinical decision support, interoperability, and cloud-based healthcare platforms are further accelerating the adoption of e-prescribing solutions.
Europe E-Prescribing Market Trends
The e-prescribing market in Europe is driven by increasing healthcare digitalization, expanding adoption of electronic health records, and government initiatives promoting cross-border interoperability and digital prescriptions. Growing investments in healthcare IT infrastructure and rising demand for efficient medication management are supporting market growth across the region.
The UK e-prescribing market is driven by NHS initiatives promoting electronic prescribing and digital healthcare transformation. Increasing adoption of integrated care systems, electronic patient records, and telehealth services is supporting the widespread implementation of e-prescribing across primary and secondary care settings.
The e-prescribing market in Germany is expanding due to increasing implementation of electronic prescriptions (eRezept), growing adoption of healthcare IT solutions, and government initiatives supporting healthcare digitalization. Rising investments in interoperable healthcare systems are further driving market growth.
Asia Pacific E-prescribing Market Trends
The e-prescribing market in the Asia Pacific is expected to grow at the fastest CAGR of 30.3% during the forecast period from 2026 to 2033. Market growth is driven by expanding healthcare digitalization, increasing adoption of EHR systems, improving healthcare infrastructure, and government initiatives promoting digital health services. Growing investments in healthcare IT and telemedicine are further supporting the adoption of e-prescribing solutions.
The Japan e-prescribing market is experiencing significant growth, driven by increasing healthcare digitalization, rapid adoption of electronic medical records, and government initiatives promoting digital healthcare services. The country's aging population and focus on improving medication safety are encouraging greater adoption of e-prescribing solutions.
The e-prescribing market in China is expanding rapidly due to increasing investments in digital healthcare infrastructure, growing adoption of hospital information systems, and the rapid digital transformation of the healthcare sector. The expansion of internet hospitals, electronic health records, and telemedicine services is further accelerating the adoption of e-prescribing solutions across the country.
Latin America E-prescribing Market Trends
The e-prescribing market in Latin America is driven by increasing healthcare digitalization, expanding adoption of electronic medical records, and government efforts to modernize healthcare systems. Rising investments in healthcare IT infrastructure are supporting the implementation of e-prescribing solutions across the region.
Middle East & Africa E-prescribing Market Trends
The e-prescribing market in the Middle East & Africa is witnessing steady growth due to increasing healthcare modernization initiatives, expanding digital health infrastructure, and growing adoption of electronic medical records. Government investments in healthcare digital transformation and improving access to healthcare services are creating new opportunitiesfor the adoption of e-prescribing solutions.
Key E-prescribing Company Insights
Key industry players are continuously innovating and introducing AI-enabled e-prescribing solutions, cloud-based platforms, and interoperable healthcare IT technologies to strengthen their market position. Companies are focusing on integrating e-prescribing with EHRs, pharmacy systems, and clinical decision support tools to improve prescribing efficiency and patient safety. Strategic initiatives such as product launches, partnerships, acquisitions, and geographic expansion are further enhancing their market presence.
Key E-prescribing Companies:
The following key companies have been profiled for this study on the global e-prescribing market:
-
Oracle
-
Veradigm LLC
-
Epic Systems Corporation
-
athenahealth
-
NextGen Healthcare
-
Surescripts
-
DrFirst
-
eClinicalWorks
-
Greenway Health
-
Practice Fusion
-
RXNT
-
MEDITECH
-
CompuGroup Medical (CGM)
-
AdvancedMD
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Oracle Health, Epic Systems Corporation, athenahealth, Veradigm LLC, Surescripts)
Expand cloud-based e-prescribing platforms, strengthen EHR interoperability, integrate AI-powered clinical decision support, enhance Electronic Prescribing of Controlled Substances (EPCS) capabilities, and expand partnerships.
Strong brand recognition, extensive healthcare provider networks, established EHR ecosystems, comprehensive e-prescribing capabilities, and strong regulatory compliance.
High implementation and maintenance costs, complex system integration, lengthy deployment cycles, and dependence on large healthcare organizations.
Emerging Players (DrFirst, RXNT, Practice Fusion, Greenway Health, eClinicalWorks)
Develop cloud-native e-prescribing solutions, enhance AI-driven medication management, expand telehealth integration, and improve interoperability with pharmacies and healthcare IT systems.
Agile product development, cost-effective cloud solutions, strong user experience, flexible deployment models, and rapid innovation.
Smaller customer base, limited global presence, lower brand recognition than established vendors, and fewer enterprise-scale deployments.
Recent Developments:
-
In July 2026, LENZ Therapeutics launched a new telehealth prescribing platform for VIZZ (aceclidine ophthalmic solution) 1.44%, enabling eligible patients to receive online evaluations from independent licensed eye care providers, electronic prescription fulfillment through an e-pharmacy partner, and home delivery. The initiative is designed to improve patient access, streamline the e-prescribing process, and accelerate the adoption of VIZZ for the treatment of presbyopia.
"At this stage of our launch, our goal is to make accessing VIZZ as seamless as possible. With the launch of this platform, we are removing a key hurdle to product access by providing consumers with a safe and convenient way to be evaluated online by an independent, licensed eye care professional who can determine whether VIZZ may be appropriate for them. We believe the combination of introducing telehealth and our national television advertising campaign will help accelerate consumer awareness, access, and adoption of VIZZ."
Eef Schimmelpennink, President and Chief Executive Officer, LENZ Therapeutics.
-
In April 2026, Boulevard announced the launch of ePrescribe, a new functionality that enables secure electronic prescribing directly within patient profiles. By integrating prescribing into the existing workflow, ePrescribe is designed to reduce the need to switch between systems, minimize duplicate data entry, and reduce the potential for prescription-related errors. The feature allows med spas and other clinical wellness practices to manage prescriptions alongside payments, scheduling, charting, and other patient-related workflows within the Boulevard platform.
E-prescribing Market Report Scope
Report Attribute
Details
Market size in 2025
USD 5.9 billion
Estimated market size in 2026
USD 7.3 billion
Projected market size by 2033
USD 27.6 billion
Growth rate
CAGR of 21.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, delivery mode, end-use, usage methods, substances, specialties, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; and Kuwait
Key companies profiled
Oracle Health; Veradigm LLC; Epic Systems Corporation; athenahealth; NextGen Healthcare; Surescripts; DrFirst; eClinicalWorks; Greenway Health; Practice Fusion, Inc.; Networking Technology, Inc. (dba RXNT); MEDITECH; CompuGroup Medical SE & Co. KGaA (CGM); AdvancedMD, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global E-prescribing Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends across each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global e-prescribingmarket report based on the product, delivery mode, end-use, usage method, substance, specialties, and region:
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Solutions
-
Integrated Solutions
-
Standalone Solutions
-
-
Services
-
Support
-
Implementation
-
Training
-
Network
-
-
-
Delivery Mode Outlook (Revenue, USD Billion, 2021 - 2033)
-
Web/Cloud-Based
-
On Premise
-
-
End-use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospital
-
Office-based Physicians
-
Pharmacy
-
-
Usage Methods Outlook (Revenue, USD Billion, 2021 - 2033)
-
Handheld
-
Computer-Based Devices
-
-
Substances Outlook (Revenue, USD Billion, 2021 - 2033)
-
Controlled Substances
-
Non-controlled Substances
-
-
Specialties Outlook (Revenue, USD Billion, 2021 - 2033)
-
Oncology
-
Sports Medicine
-
Neurology
-
Cardiology
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The e-prescribing marketfigures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing—reconciling supply-side and demand-side estimates—and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each e-prescribing segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment- Product
Revenue Capture Definition
Solutions (Integrated Solutions, Standalone Solutions)
Revenue generated from the licensing, subscription, implementation, and maintenance of integrated and standalone e-prescribing software solutions used to create, transmit, and manage electronic prescriptions across healthcare settings.
Services (Support, Implementation, Training, Network)
Revenue generated from professional services associated with e-prescribing platforms, including implementation, technical support, user training, consulting, system integration, and prescription network connectivity services.
Segment- Delivery Mode
Revenue Capture Definition
Web/Cloud-Based
Revenue generated from cloud-hosted or web-based e-prescribing platforms delivered through Software-as-a-Service (SaaS) or other cloud deployment models.
On-Premise
Revenue generated from e-prescribing software deployed and managed on healthcare organizations' local servers and IT infrastructure.
Segment- End-use
Revenue Capture Definition
Hospital
Revenue generated from e-prescribing solutions implemented in hospitals, health systems, and integrated delivery networks for inpatient and outpatient prescribing.
Office-based Physicians
Revenue generated from e-prescribing solutions used by physician offices, clinics, and ambulatory care practices for electronic prescription management.
Pharmacy
Revenue generated from e-prescribing platforms and network services used by retail, specialty, mail-order, and hospital pharmacies for receiving, processing, and managing electronic prescriptions.
Segment- Usage Methods
Revenue Capture Definition
Handheld
Revenue generated from e-prescribing solutions accessed through smartphones, tablets, and other handheld mobile devices used by healthcare professionals.
Computer-Based Devices
Revenue generated from e-prescribing solutions accessed through desktop computers, laptops, and workstation-based clinical systems.
Segment- Substances
Revenue Capture Definition
Controlled Substances
Revenue generated from electronic prescribing solutions supporting Electronic Prescribing of Controlled Substances (EPCS), including DEA-compliant authentication and secure transmission capabilities.
Non-controlled Substances
Revenue generated from the electronic prescribing of prescription medications that are not classified as controlled substances.
Segment- Specialties
Revenue Capture Definition
Oncology
Revenue generated from e-prescribing solutions used in oncology practices for prescribing cancer therapies and supportive medications.
Sports Medicine
Revenue generated from e-prescribing solutions used in sports medicine settings for prescribing medications related to musculoskeletal injuries, rehabilitation, and pain management.
Neurology
Revenue generated from e-prescribing solutions used by neurologists for prescribing medications for neurological disorders and related conditions.
Cardiology
Revenue generated from e-prescribing solutions used in cardiology practices for prescribing cardiovascular medications and chronic disease therapies.
Others
Revenue generated from e-prescribing solutions used across other medical specialties, including dermatology, endocrinology, gastroenterology, pediatrics, psychiatry, and primary care.
Estimation Model
Section
Heading
Content
Top-Down
Commodity Flow Analysis
Market size was estimated by analyzing revenues generated by leading e-prescribing solution providers, EHR vendors, and healthcare IT companies. Company annual reports, investor presentations, regulatory filings, industry databases, and primary interviews were used to estimate revenue contributions and derive the overall market size.
Segmentation
Country-Level Segment Share Modeling
Market shares for deployment mode, delivery mode, end use, and regional segments were estimated based on country-specific EHR adoption, healthcare IT maturity, e-prescribing penetration, the regulatory landscape, and healthcare infrastructure. Weighted average analysis was applied to derive regional and global segment shares.
Validation
Data Triangulation & Validation Model
Market estimates were validated through triangulation of secondary research, primary interviews, company revenue analysis, healthcare provider adoption trends, and demand-side assessments to ensure consistency and accuracy across all market segments and geographies.
Forecasting
Forecasting & CAGR Modeling
Market forecasts were developed based on historical adoption trends, expansion of EHR systems, government regulations supporting electronic prescribing and EPCS, telehealth growth, AI integration, healthcare IT investments, and technology innovation. Regression analysis and trend modeling were applied to project future market growth.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Pricing Benchmarks and ACV Analysis
Analysis of average selling prices (ASP), pricing benchmarks, and pricing variations across e-prescribing solutions by deployment mode, delivery model, and end-use segment.
Helps evaluate pricing strategies, benchmark solutions across competitors, optimize product positioning, and identify revenue growth opportunities across different customer segments.
Competitive Positioning Analysis & Market Share Analysis
Comprehensive assessment of Company market share, product portfolio benchmarking, platform capabilities, strategic initiatives, partnerships, mergers & acquisitions, and competitive positioning.
Enables benchmarking of market leaders and emerging players, identifies competitive gaps, and supports strategic planning, partnership decisions, and market expansion strategies.
Regional Opportunity Analysis
Detailed assessment of regional growth opportunities based on healthcare IT adoption, EHR implementation, regulatory initiatives, telehealth expansion, digital health infrastructure, and investment trends across key countries and regions.
Helps identify high-growth regional markets, prioritize expansion strategies, optimize resource allocation, and capitalize on emerging opportunities across developed and emerging healthcare markets.
Frequently Asked Questions About This Report
The solutions segment held the largest market share of 56.9% in 2025.
The web/cloud based segment dominated the market with a revenue share of 62.9% in 2025.
The sports medicine segment dominated the market with a revenue share of 23.3% in 2025.
Some key players operating in the e-prescribing market include Oracle Health, Veradigm LLC, Epic Systems Corporation, athenahealth, NextGen Healthcare, Surescripts, DrFirst, eClinicalWorks, Greenway Health, Practice Fusion, Inc., Networking Technology, Inc. (dba RXNT), MEDITECH, CompuGroup Medical SE & Co. KGaA (CGM), AdvancedMD, Inc.
Key factors that are driving the e-prescribing market growth include government initiatives and regulatory mandates supporting electronic prescribing, the growing adoption of electronic health records (EHRs) and healthcare IT systems, and the expansion of telehealth and remote healthcare services.
The global E-Prescribing market size was valued at USD 5.9 billion in 2025 and is estimated at USD 7.3 billion for 2026.
The global E-Prescribing market is expected to grow at a CAGR of 21.0% from 2026 to 2033, reaching USD 27.6 billion by 2033.
North America dominated the market, accounting for the revenue share of 43.2% in 2025.
The hospitals segment dominated the market with a revenue share of 37.8% in 2025.
About the Author(s)
Healthcare IT Research Team
Healthcare · Healthcare ITThis report was authored by the healthcare it research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the healthcare it segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


