
- Home
- »
- Automotive & Transportation
- »
-
Electric Vehicle Battery Thermal Management Systems Market Report 2033GVR Report cover

Electric Vehicle Battery Thermal Management Systems Market (2026 - 2033)
Size, Share & Trends Analysis Report By System (Active, Passive), By Application (Passenger Vehicles, Commercial Vehicles), By Region (North America, Europe, Asia Pacific, Latin America, MEA), And Segment Forecasts
Market Size, 2025
$7.0BMarket Estimate, 2026
$9.2BMarket Forecast, 2033
$75.1BCAGR, 2026–2033
35.0%Electric Vehicle Battery Thermal Management Systems Market Summary
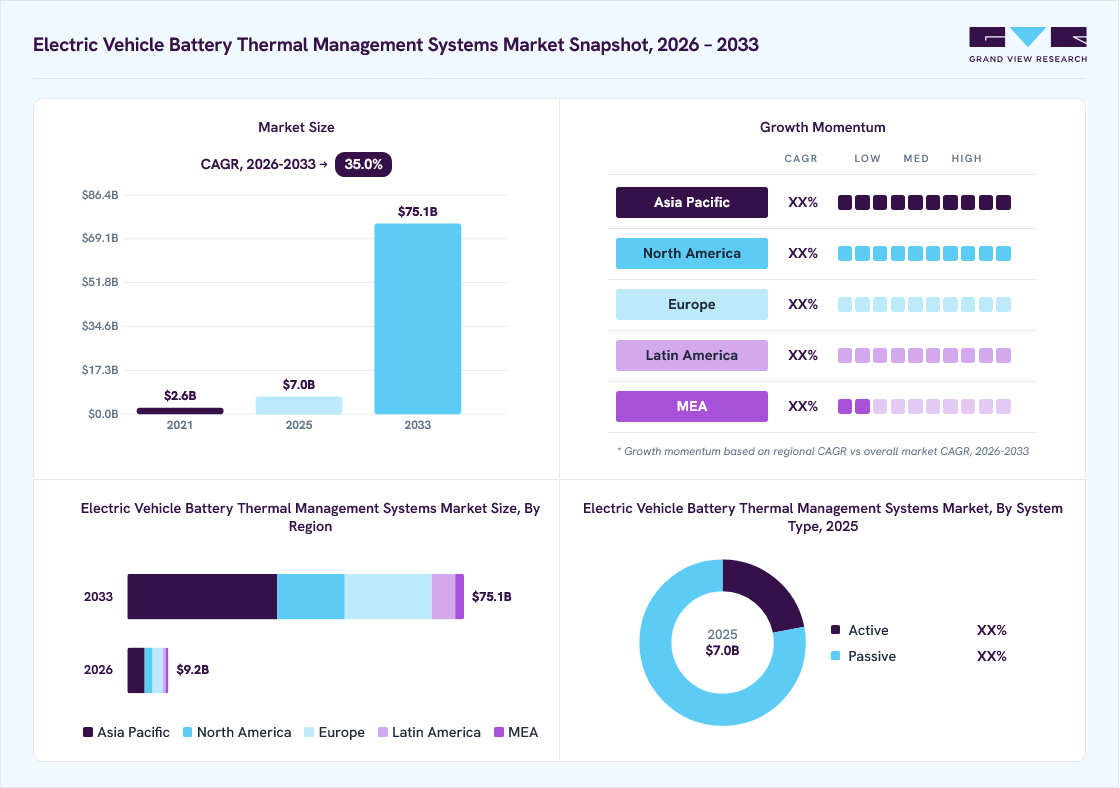
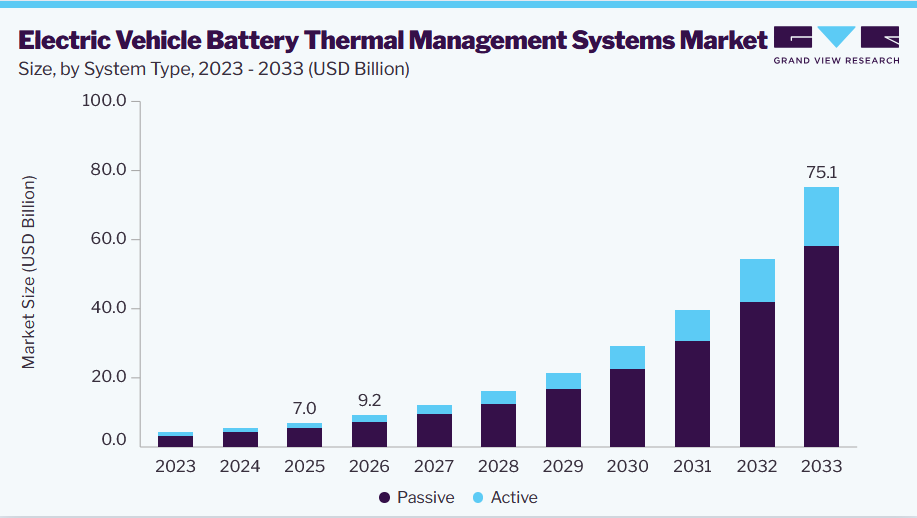
The global electric vehicle battery thermal management systems market size was valued at USD 7.0 billion in 2025 and is projected to grow from USD 9.2 billion in 2026 to USD 75.1 billion by 2033, at a CAGR of 35.0% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest revenue share of 41.8% in 2025. The substantial growth in popularity and adoption of electric vehicles (EVs) globally has driven the demand for thermal management solutions that can enhance the performance, safety, and lifespan of their batteries.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By system type: Passive segment dominated the market, with a revenue share of 78.1% in 2025.
- By application: Passenger Vehicle segment held the largest market share of 88.9% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (41.8% revenue share, 2025)
- By country: The China is the fastest growing country in 2025.
Market Size & Forecast
- Market size in 2025: USD 7.0 Billion
- Estimated market size in 2026: USD 9.2 Billion
- Projected market size by 2033: USD 75.1 Billion
- CAGR (2026-2033): 35.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
An increase in awareness regarding the environmental benefits of EVs has boosted their production, particularly in emerging economies such as India and China, leading to a corresponding growth in manufacturing advanced battery systems. This has led to significant progress in the EV battery thermal management systems industry.Electric vehicle batteries, especially lithium-ion batteries, perform optimally within a specific temperature range, which is generally around 68-86°F. A battery thermal management system (BTMS) ensures that the battery temperature stays within this range by cooling or heating the battery as required. This helps maintain consistent energy output levels and charging/discharging efficiency, positively impacting the vehicle's driving range and performance. With increasing sales of EVs, the need for efficient and reliable battery thermal management systems has risen significantly to ensure that these vehicles perform optimally in all conditions. According to BloombergNEF (BNEF), electric vehicle sales are expected to reach 16.7 million units in 2024, growing from 13.9 million in 2023. Automakers are moving toward increasing the driving range of EVs, resulting in the development of larger and higher-capacity batteries. Such batteries generate more heat during charging and discharging, creating greater thermal management challenges. This has resulted in a strong demand for active and passive BTM systems.
 To learn more about this report, Download Free Sample Report
The growing popularity and implementation of fast-charging networks, which can charge EV batteries rapidly, leads to excessive heat generation in these components. Efficient BTMS solutions are crucial to handle such thermal loads, ensuring safe and quick charging without damaging the battery. Governments across developed economies are implementing fast-charging networks for consumer convenience. According to the Global EV Outlook 2024 report by the International Energy Agency (IEA), there was an increase of over 40% in the public charging stock worldwide in 2023, with the expansion rate of fast chargers outpacing that of slow chargers. Fast chargers accounted for more than 35% of the public charging stock in 2023 and are expected to maintain a positive growth trend in the coming years. However, their high power delivery generates substantial heat due to internal resistance and electrochemical reactions, which can lead to thermal runaway, reduced battery efficiency, and shortened battery lifespan in vehicles. Manufacturers in the electric vehicle battery thermal management systems industry are thus focused on developing solutions that can address this issue conveniently.
Market Dynamics
Advancements in battery technologies, high-energy-density battery packs, liquid cooling architectures, phase change materials, refrigerant-based cooling systems, artificial intelligence-enabled battery management systems (BMS), and IoT-integrated thermal monitoring solutions are significantly enhancing the efficiency, safety, performance, and lifespan of electric vehicle battery thermal management systems across passenger vehicles, commercial vehicles, electric buses, and high-performance electric mobility applications. The integration of real-time temperature monitoring, predictive diagnostics, smart control algorithms, and energy optimization technologies further improves battery charging efficiency, driving range, fast-charging capability, and overall vehicle reliability. However, high development and integration costs, complex thermal system designs, stringent safety and regulatory requirements, and dependence on specialized materials and components increase manufacturing expenses and create challenges for cost-sensitive vehicle segments. Meanwhile, the rapid adoption of electric vehicles, growing deployment of fast-charging infrastructure, increasing demand for extended battery life and enhanced vehicle safety, supportive government electrification initiatives, and continuous investments in next-generation battery technologies are creating opportunities for manufacturers to develop intelligent, lightweight, energy-efficient, and scalable battery thermal management solutions tailored to evolving electric mobility requirements.
The increasing adoption of electric vehicles (EVs) and expansion of fast-charging infrastructure are significantly driving demand for advanced electric vehicle battery thermal management systems across passenger cars, commercial vehicles, electric buses, and high-performance mobility applications. Modern battery thermal management systems equipped with liquid cooling technologies, refrigerant-based cooling circuits, phase change materials, and intelligent control algorithms enable precise temperature regulation, improved battery efficiency, enhanced safety, and extended battery lifespan. These next-generation solutions support high-power charging, maintain battery performance under varying operating conditions, and minimize the risk of thermal runaway, making them critical components of modern electric mobility platforms.
The market is also witnessing growing integration of artificial intelligence, advanced battery management systems (BMS), and IoT-enabled thermal monitoring technologies. AI-driven control systems facilitate real-time temperature monitoring, predictive diagnostics, adaptive cooling strategies, and energy optimization, helping vehicle manufacturers improve charging efficiency, maximize driving range, and reduce battery degradation. Additionally, the increasing deployment of ultra-fast charging networks and the development of high-energy-density battery chemistries are accelerating the adoption of intelligent, energy-efficient, and scalable battery thermal management solutions capable of supporting next-generation electric vehicle architectures.
The deployment of advanced electric vehicle battery thermal management systems requires substantial investment in cooling and heating components, thermal interface materials, sensors, control units, refrigerant circuits, pumps, heat exchangers, and battery management systems (BMS). The high upfront costs associated with system design, testing, validation, and integration often limit adoption in cost-sensitive vehicle segments, particularly entry-level passenger EVs and emerging electric mobility markets. Additionally, automotive manufacturers must invest in specialized engineering capabilities, safety certifications, and vehicle platform modifications to accommodate sophisticated thermal management architectures, further increasing overall development and ownership costs.
The market also faces challenges related to complex system integration and implementation processes. Battery thermal management systems must operate seamlessly with battery packs, BMS, power electronics, HVAC systems, charging infrastructure, and vehicle control units to maintain optimal battery temperatures under diverse operating and charging conditions. Ensuring compatibility across multiple vehicle platforms, battery chemistries, and component suppliers often requires extensive engineering expertise, lengthy validation cycles, and significant integration expenses. Any deficiencies in thermal management performance can adversely affect battery safety, charging efficiency, driving range, and battery lifespan, creating additional challenges for manufacturers seeking to optimize electric vehicle performance and reliability.
The rapid expansion of electric vehicle charging networks, particularly high-power DC fast-charging stations, is creating significant opportunities for electric vehicle battery thermal management systems manufacturers worldwide. Increasing consumer demand for reduced charging times, extended driving range, and enhanced battery durability is driving investments in advanced thermal management technologies capable of maintaining optimal battery temperatures during high-rate charging and discharging cycles. Battery thermal management systems play a critical role in improving charging efficiency, mitigating thermal degradation, and ensuring safe operation, making them an essential component of next-generation electric mobility platforms.
The market is also benefiting from the growing adoption of high-performance electric vehicles, electric buses, commercial fleets, and heavy-duty electric trucks, which require sophisticated cooling and heating solutions to support larger battery packs and higher energy densities. As battery technologies continue to evolve and vehicle manufacturers pursue longer-range and ultra-fast-charging capabilities, demand is increasing for intelligent thermal management systems incorporating liquid cooling, refrigerant-based architectures, phase change materials, and AI-enabled control strategies. This trend is generating substantial opportunities for manufacturers to develop lightweight, energy-efficient, and scalable battery thermal management solutions tailored to the performance, safety, and operational requirements of future electric vehicle applications.
Analyst Perspective
The electric vehicle battery thermal management systems market is witnessing strong growth driven by rising EV adoption, fast-charging infrastructure, and advancements in high-energy-density batteries. Automakers are adopting advanced liquid cooling, refrigerant-based systems, intelligent BMS, AI, and IoT-enabled thermal monitoring to improve battery safety, lifespan, charging efficiency, and vehicle range. Despite challenges such as high integration costs, complex designs, and stringent safety requirements, continued investments in electrification, ultra-fast charging, and next-generation battery technologies are expected to support steady market growth.
System Insights
Based on system type, the passive segment led the market with the largest revenue share of 78.1% in 2025. Passive systems witness a healthy demand in the automotive sector, as they are cost-effective and simple to install. With the rising popularity of budget-friendly EV models and two-wheelers, particularly in emerging economies where affordability is a priority, manufacturing passive solutions is expected to remain strong in the coming years. These systems rely on heat sinks, phase-change materials (PCM), and natural convection, which require minimal maintenance compared to active system components. Such simplicity appeals to manufacturers looking for low-maintenance solutions in smaller or lower-power EVs. PCMs, particularly those having a solid-liquid phase change, have been studied extensively in recent years for their application in this market.
The active segment is expected to grow at the highest CAGR during the forecast period due to the growing popularity of high-performance EVs that necessitate optimal battery performance and longevity. These vehicles, which include sports cars, SUVs, and trucks, are increasingly equipped with high-capacity batteries to improve their driving range. High energy density generates more heat during operation and charging processes, making active thermal management critical for maintaining temperature within safe limits. Moreover, active systems offer precise temperature control, ensuring consistent battery performance in varying climatic conditions. This is essential for improving energy efficiency and extending battery life, which is critical for reducing the total cost of ownership and increasing customer satisfaction. Innovations such as integrated liquid cooling, refrigerant-based systems, and phase-change materials are becoming more cost-effective and scalable, aiding segment expansion.
Application Insights
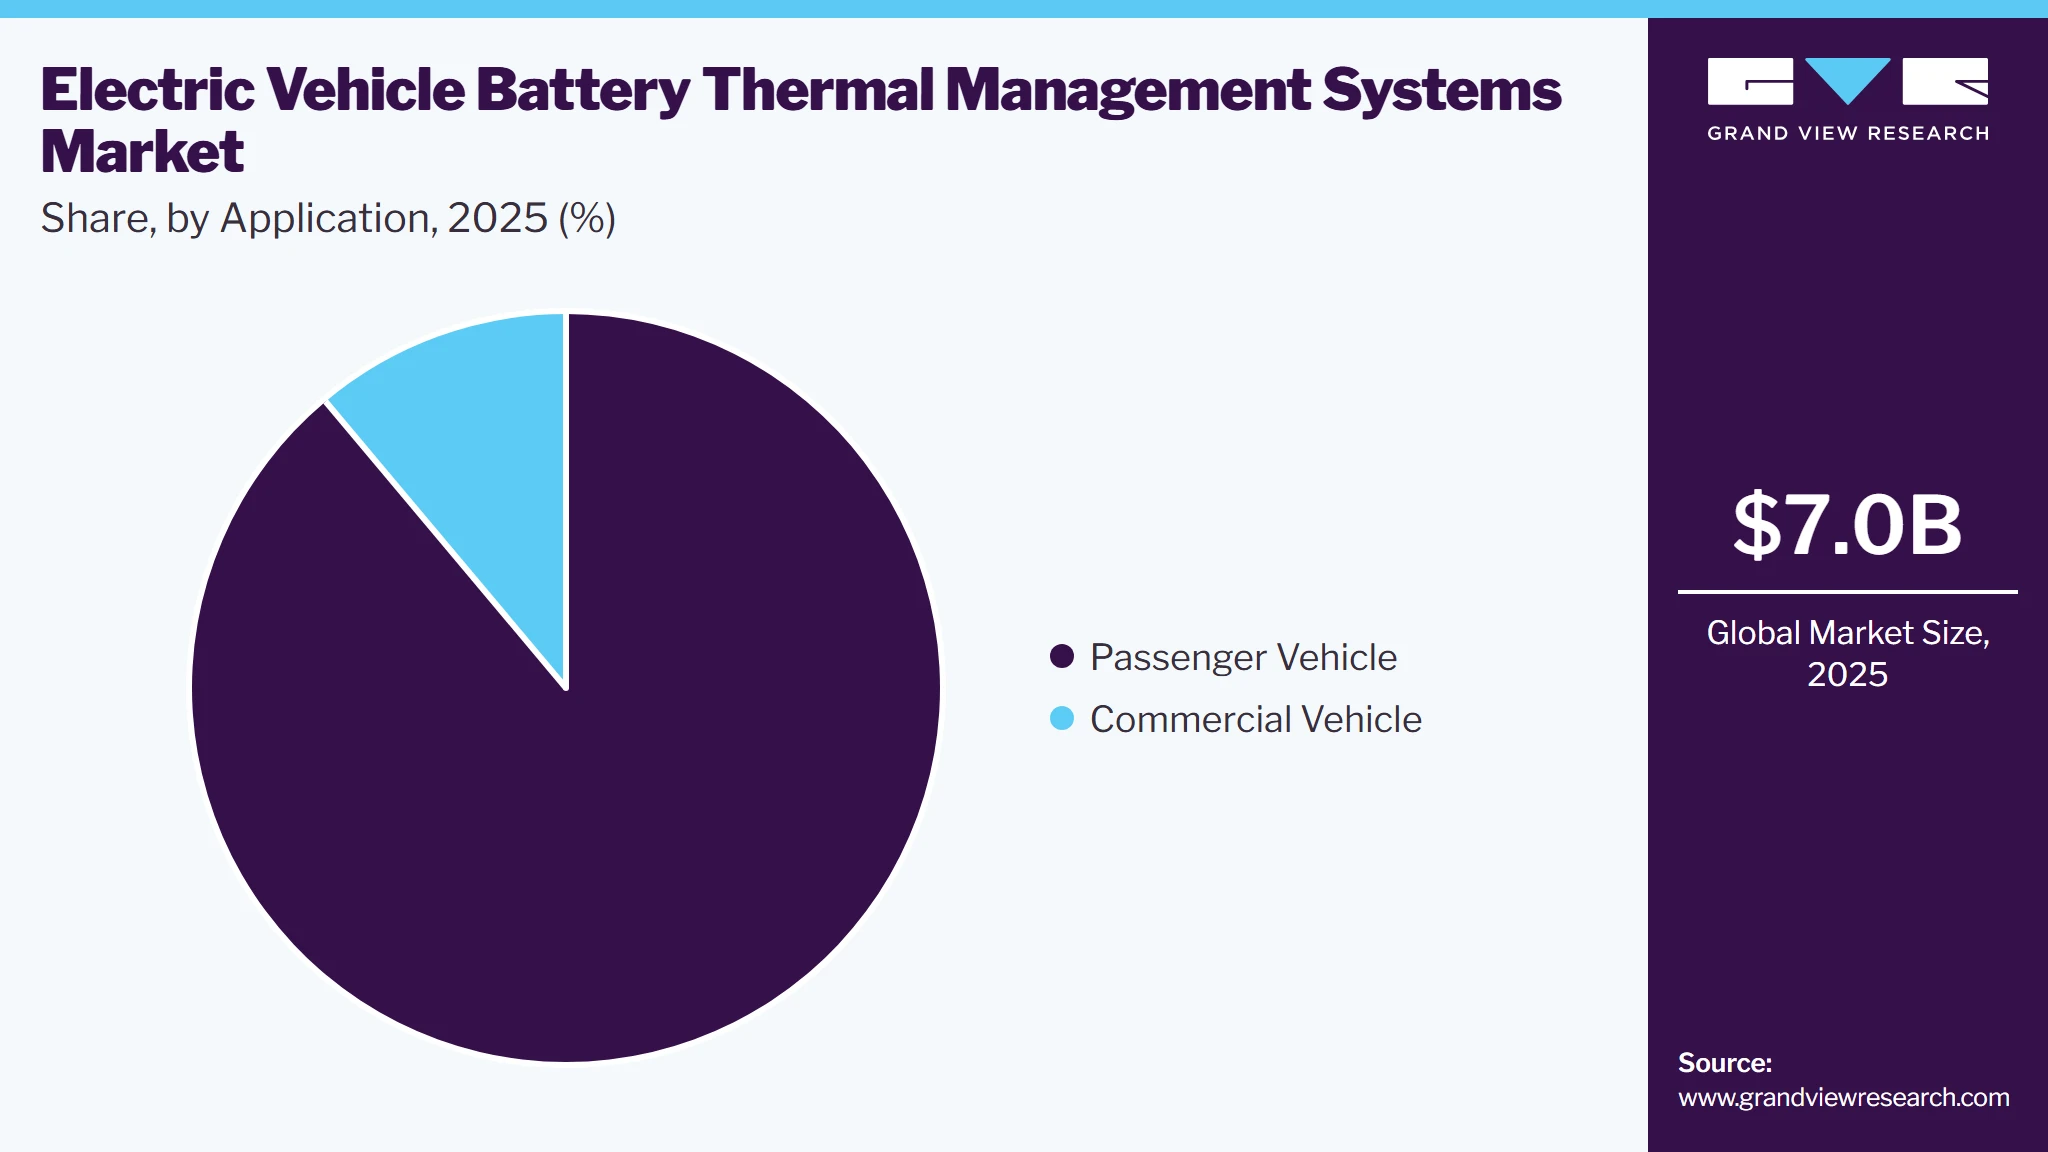
Based on application, the passenger vehicle segment led the market with the largest revenue share of 88.9% in 2025. The widespread availability of passenger electric vehicles globally and the increasing pace of government initiatives to boost consumer product awareness have aided market growth. The global shift toward sustainable transportation is driving the demand for these vehicles, which rely heavily on efficient BTMS to ensure battery performance, safety, and longevity. Consumers expect passenger EVs to deliver longer ranges, faster charging, and improved safety. These demands necessitate a robust thermal management system to address the excessive heat generated during high power output and rapid charging cycles. Furthermore, governments and international organizations have introduced regulations mandating thermal safety, battery efficiency, and environmental compliance. These standards compel automakers to invest in advanced BTMS for passenger EVs.
 To learn more about this report, Download Free Sample Report
The commercial vehicles segment is anticipated to grow at a substantial CAGR from 2026 to 2033 in the electric vehicle battery thermal management systems industry. The demand for these solutions in commercial electric fleets has witnessed healthy growth, driven by the electrification of transportation, the need for operational efficiency, enhanced safety, and regulatory compliance. As commercial fleets continue to expand and diversify, the role of BTMS has become increasingly critical in ensuring electric vehicles' performance, reliability, and sustainability. Commercial fleets benefit from fast-charging capabilities to minimize downtime, where thermal management is essential to manage the increased heat generated during rapid charging, ensuring battery health and safety. Urban fleets, such as delivery vans and buses, require BTMS that can handle frequent stops and starts, while long-haul electric trucks need systems that manage sustained high loads over extended periods.
Regional Insights
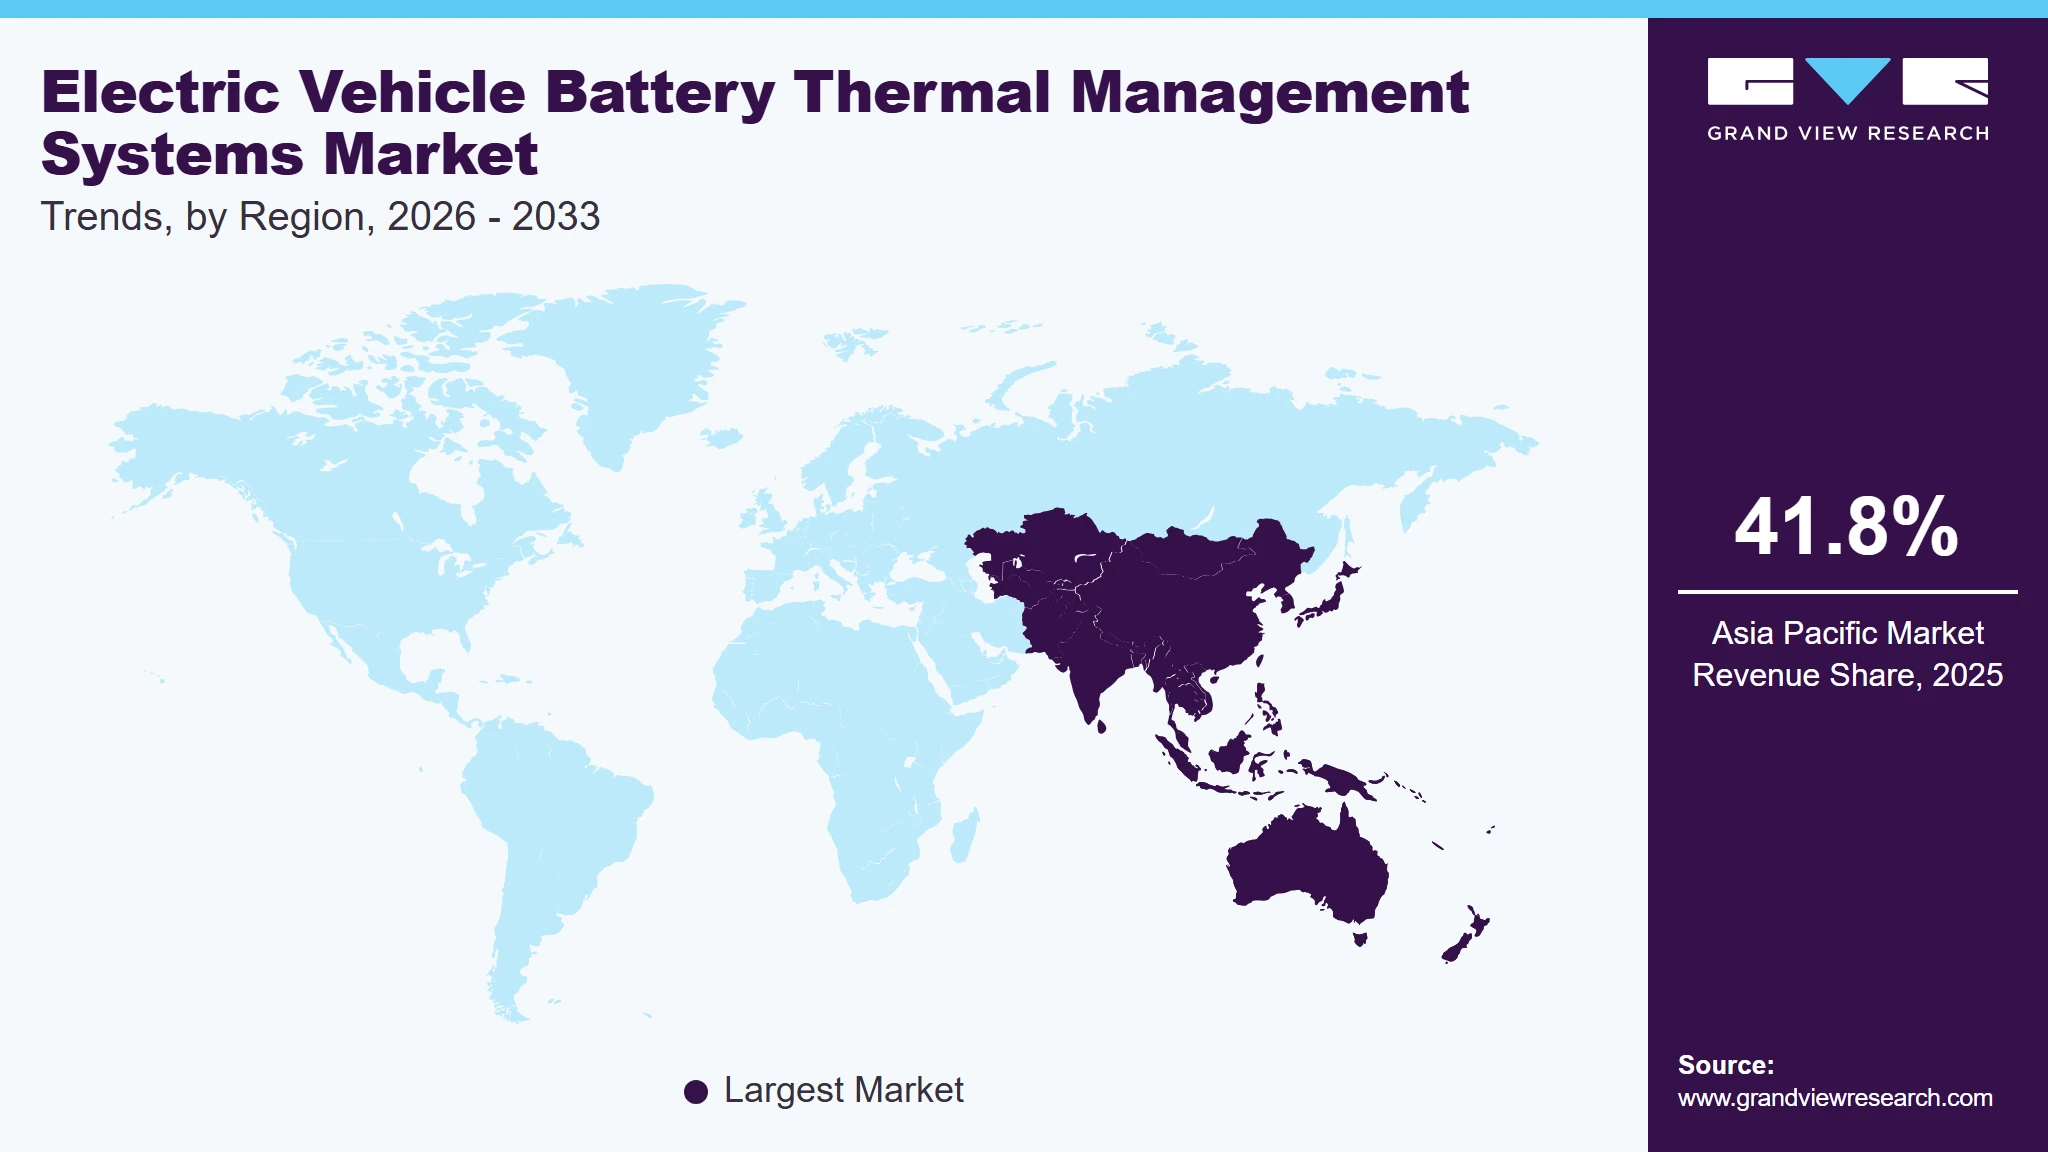
Asia Pacific dominated the global electric vehicle battery thermal management systems market with the largest revenue share of 41.8% in 2025, owing to the extensive adoption of passenger and commercial electric vehicles among regional consumers. Additionally, economies such as China, Japan, and India have become major manufacturing hubs in the electric mobility space, enabling the large-scale production of efficient thermal management systems for EV batteries. Leading EV manufacturers and battery producers in these countries drive the need for advanced BTMS to ensure performance, safety, and compliance. The deployment of fast-charging stations due to rapid urbanization and the increasing use of EVs for ride-hailing and delivery services further fuel the adoption of fast-charging-compatible BTMS in Asia Pacific.
 To learn more about this report, Download Free Sample Report
China Electric Vehicle Battery Thermal Management Systems Market Trends
China is the fastest growing country in the Aisa Pacific electric vehicle battery thermal management systems market, aided by favorable government initiatives, the exponential growth of the automotive and EV sectors, and several major global battery manufacturers. The country is the leading adopter of electric vehicles, with consumers becoming more aware of their role in environmental protection. According to a report by the IEA, China contributed to around 80% of the global sales growth of EVs during the first half of 2024. As a result, the demand for efficient battery thermal management solutions can also be expected to witness a noticeable boost during the forecast period.
Europe Electric Vehicle Battery Thermal Management Systems Market Trends
Europe accounted for a substantial revenue share in the global market in 2025, as the region is well-known for the large-scale adoption of electric mobility solutions, both in the personal vehicle and commercial fleet segments. The demand for EVs spans passenger cars, electric buses, logistics vans, and long-haul electric trucks, each requiring efficient BTMS customized per operational requirements. Furthermore, establishing seamless charging networks across regional economies boosts the demand for thermal management systems to ensure consistent battery performance under diverse conditions. Leading automotive manufacturers and regional authorities are constantly looking for ways to boost EV performance to increase customer satisfaction while ensuring adherence to environmental norms. In June 2024, the 2nd European EV Thermal Management Summit 2024 event was held in Frankfurt, Germany. The summit discussed emerging trends and cutting-edge technologies in integrated and efficient thermal management systems that fall under the region’s net zero and sustainability objectives. Such initiatives are expected to bring positive advancements in the European market.
North America Electric Vehicle Battery Thermal Management Systems Market Trends
North America electric vehicle battery thermal management systems market is expected to advance at a significant CAGR in the market from 2026 to 2033. The presence of a strong electric mobility economy in the U.S. and Canada and the region’s reputation as a technological hub are expected to bring major developments in this industry in the coming years. Companies such as Tesla, Rivian, Lucid Motors, and legacy automakers such as GM and Ford are constantly expanding their EV portfolios, driving BTMS integration. Moreover, the adoption of electric vehicles has steadily grown in the region, owing to initiatives such as the U.S. EV tax credit under the Inflation Reduction Act (IRA) and Canada’s subsidies for EV purchases. Increased funding for charging infrastructure expansion, including fast-charging networks, has further driven the need for effective BTMS to manage heat generated during high-speed charging.
U.S. Electric Vehicle Battery Thermal Management Systems Market Trends
The U.S. electric vehicle battery thermal management systems market dominant revenue share in the North American market in 2025. The presence of large-scale manufacturing facilities for batteries and the growing presence of commercial electric fleets on roads have led to continued developments in this market. A report published by S&P Global Mobility in August 2024 stated that between January and June, the number of passenger vehicles and light trucks in the country grew by around 1.8 million units, of which 1.6 million (89%) came from EVs and hybrid EVs. The strengthening of road transportation and the e-commerce industry in the U.S. has further resulted in the extensive electrification of commercial fleets, such as buses and delivery vehicles. These vehicles operate intensively, necessitating the deployment of robust thermal management systems to manage high thermal loads and prolonged operational cycles.
Key Electric Vehicle Battery Thermal Management Systems Company Insights
Some of the major companies involved in the global electric vehicle battery thermal management systems industry include GENTHERM, Robert Bosch, and Dana Limited, among others.
-
GENTHERM specializes in thermal management technologies by developing heating and cooling solutions within the automotive and medical sectors. In the automotive segment, the company develops climate and comfort solutions, fluid systems, ClimateSense, WellSense, and battery performance solutions. GENTHERM also develops battery heating and battery air cooling systems, as well as thermoelectric heating and cooling for hybrid EVs. The company has further collaborated with the Israeli developer Carrar to launch the direct evaporation liquid technology that addresses safety and reliability concerns in battery systems.
-
Robert Bosch offers advanced technological solutions and services to customers, operating through four major segments - Mobility Solutions, Industrial Technology, Consumer Goods, and Energy & Building Technology. Under the Mobility division, the company is involved in researching and producing different thermal management system components. These include the electric refrigerant compressor, the electric coolant pump PCE 2.0, the electric coolant pump PDE, the GBB air conditioning blower motor and module, and EC motors for electric cooling fans.
Key Electric Vehicle Battery Thermal Management Systems Companies
The following key companies have been profiled for this study on the electric vehicle battery thermal management systems market.
-
Robert Bosch GmbH
-
GENTHERM
-
Valeo
-
Dana Limited
-
MAHLE GmbH
-
Hanon Systems
-
VOSS Automotive, Inc
-
3M
-
Grayson Automotive Services Limited
-
Polymer Science, Inc.
-
PARKER HANNIFIN CORP
-
NeoGraf
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Robert Bosch GmbH, GENTHERM, Valeo, Dana Limited, MAHLE GmbH, Hanon Systems, Parker Hannifin Corp.)
- Focus on developing advanced battery thermal management solutions, including liquid cooling systems, refrigerant-based architectures, heat exchangers, thermal valves, pumps, and intelligent thermal control modules.
- Continuous investments in next-generation cooling technologies, AI-enabled battery management systems (BMS), thermal simulation capabilities, and integrated e-mobility platforms.
- Strong global manufacturing footprint, extensive automotive OEM relationships, broad product portfolios, and significant R&D capabilities.
- Proven expertise in thermal management, HVAC systems, and electrification technologies, supported by established supply chains and comprehensive validation capabilities.
- Ability to provide integrated thermal management solutions tailored to multiple EV platforms and battery chemistries.
- High research, development, and validation costs associated with advanced thermal technologies.
- Longer product development and qualification cycles due to stringent automotive safety, reliability, and regulatory requirements.
- Exposure to pricing pressures from OEMs seeking cost reductions for mass-market electric vehicles.
Emerging Players (VOSS Automotive, Inc., 3M, Grayson Automotive Services Limited, Polymer Science, Inc., NeoGraf)
- Focus on specialized thermal management components, including thermal interface materials, graphite-based heat spreaders, coolant distribution systems, phase change materials, and lightweight thermal solutions.
- Emphasis on customized engineering, material innovation, and application-specific thermal solutions designed to improve battery safety, charging performance, and energy efficiency.
- Greater agility in developing innovative materials and customer-specific thermal solutions.
- Faster commercialization of emerging technologies and strong expertise in niche thermal management applications.
- Limited global manufacturing scale and comparatively lower financial resources than established automotive suppliers.
- Dependence on OEM partnerships and battery manufacturers for market penetration.
Recent Developments
-
In October 2024, at the Paris Motor Show, Valeo and TotalEnergies announced an extension of their partnership, initiated in 2022 by creating a novel cooling solution for electric vehicle batteries. The companies have been conducting field trials for this immersive cooling system (liquid dielectric) that helps maintain the battery's optimal temperature, lowers its carbon footprint, improves its autonomy, and offers protection against fire hazards. The partnership further aims to develop a fluid system that can optimize and enhance the performance of next-gen EVs.
-
In October 2024, Hanon Systems, which develops and supplies thermal management solutions for electric mobility, unveiled a new manufacturing facility in Ontario, Canada. This would be the company’s first plant in North America to manufacture electric scroll compressors, which form a vital component for optimal thermal management in battery and hybrid EVs. Production at this location is expected to begin in 2025, with the facility offering a capacity of 900,000 electric compressors. The company has four facilities similar to those in Korea (Pyeongtaek), China (Changchun and Dalian), and Portugal.
-
In January 2024, Grayson Thermal Systems announced that it had received substantial funding from HSBC UK. This investment would enable the company to build three production lines at its Tyseley facility in Birmingham, England, which includes a battery thermal management system line and two heat pump lines. Moreover, the funding would be utilized to modernize Grayson’s fabrication facility to increase production output and boost efficiency.
Electric Vehicle Battery Thermal Management Systems Market Report Scope
Report Attribute
Details
Market size in 2025
USD 7.0 billion
Estimated Market size in 2026
USD 9.2 billion
Projected Market size by 2033
USD 75.1 billion
Growth rate
CAGR of 35.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
System, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; U.K.; Germany; France; China; Japan; India; Australia; South Korea; Australia; Brazil; Kingdom of Kingdom of Saudi Arabia (KSA); UAE; South Africa
Key companies profiled
Robert Bosch GmbH; GENTHERM; Valeo; Dana Limited; MAHLE GmbH; Hanon Systems; VOSS Automotive, Inc; 3M; Grayson Automotive Services Limited; Polymer Science, Inc.; PARKER HANNIFIN CORP; NeoGraf
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Electric Vehicle Battery Thermal Management Systems Market Report Segmentation
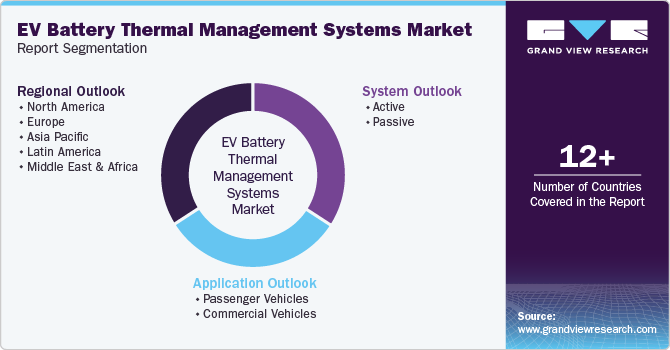
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global electric vehicle battery thermal management systems market report based on system, application, and region:
 To learn more about this report, Download Free Sample Report
-
System Outlook (Revenue, USD Million, 2021 - 2033)
-
Active
-
Passive
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Passenger Vehicles
-
Commercial Vehicles
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
U.K.
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
MEA
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The electric vehicle battery thermal management systems market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each electric vehicle battery thermal management systems segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment- System Type
Revenue Capture Definition
Active
This segment captures revenue generated from active battery thermal management systems that utilize powered cooling and heating mechanisms, including liquid cooling, air cooling, refrigerant-based cooling, electric heaters, pumps, compressors, and heat exchangers, to maintain battery cells within optimal operating temperatures. These systems are widely deployed in passenger cars, commercial vehicles, electric buses, and high-performance electric vehicles requiring precise thermal control, enhanced fast-charging capabilities, improved safety, and extended battery life.
Passive
This segment includes revenue derived from passive battery thermal management systems designed to regulate battery temperatures through natural heat dissipation methods, such as phase change materials (PCMs), thermal insulation, heat spreaders, and conductive materials, without relying on active energy-consuming components. These systems are commonly utilized in cost-sensitive electric vehicles and applications with relatively lower thermal loads, where simplicity, lightweight design, and reduced energy consumption are prioritized.
Segment- Application
Revenue Capture Definition
Passenger Vehicle
This segment captures revenue generated from battery thermal management systems integrated into electric passenger vehicles, including hatchbacks, sedans, SUVs, luxury EVs, and sports electric vehicles. These systems support optimal battery performance, fast-charging capability, driving range enhancement, and battery longevity while ensuring safe operation under varying climatic and driving conditions. Growing consumer adoption of electric passenger vehicles and increasing demand for high-energy-density batteries are key contributors to revenue generation within this segment.
Commercial Vehicle
This segment includes revenue derived from battery thermal management systems deployed in electric commercial vehicles, including buses, trucks, vans, delivery fleets, and heavy-duty electric vehicles. These systems are engineered to manage the higher thermal loads associated with larger battery packs, intensive duty cycles, and frequent fast-charging operations. Advanced thermal management solutions help improve operational reliability, maximize battery lifespan, enhance vehicle uptime, and support the electrification of commercial transportation and logistics fleets.
Estimation Model
Layer Name
Key Question
Description
Electric Vehicle Parc and Battery Deployment Layer
Where are battery thermal management systems used and what drives demand?
Establish the total potential demand base by identifying battery thermal management system deployment across battery electric vehicles (BEVs), plug-in hybrid electric vehicles (PHEVs), electric buses, electric trucks, light commercial vehicles, and other electrified mobility applications requiring effective battery temperature regulation to ensure safety, performance, and longevity.
Addressable EV Production Market Layer
Which vehicle platforms can realistically adopt advanced battery thermal management solutions?
Refine the total electric vehicle base into the realistically serviceable market by considering factors such as battery capacity, vehicle segment, charging requirements, thermal load characteristics, battery chemistry compatibility, vehicle architecture, cost considerations, and regional electric vehicle adoption trends.
Battery Thermal Management Systems Procurement Layer
Who is actively integrating, upgrading, or sourcing battery thermal management systems?
Estimate annual demand generation by analyzing electric vehicle production volumes, new EV model launches, battery manufacturing expansions, investments in fast-charging infrastructure, adoption of high-energy-density batteries, replacement and upgrade cycles, and increasing electrification initiatives across passenger and commercial vehicle segments.
Revenue Layer
How is revenue generated from battery thermal management system sales?
Revenue is generated through the sale of battery thermal management systems across various system types (active and passive) and vehicle applications (passenger and commercial vehicles). Market revenue is calculated by considering vehicle production volumes, battery pack capacities, thermal management architectures, component configurations, software and control system integration, engineering and validation services, regional pricing variations, and value chain margins across component suppliers, system manufacturers, and automotive OEMs.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Electric Vehicle Battery Thermal Management Systems Market Assessment
Structured evaluation of market dynamics including key drivers, restraints, opportunities, and industry trends across the battery thermal management systems value chain.
Assessment of technology evolution across liquid cooling systems, refrigerant-based architectures, phase change materials, intelligent battery management systems (BMS), and AI-enabled thermal control solutions.
Clear visibility into market growth drivers and adoption barriers.
Strategic input for market entry, expansion planning, and investment decisions.
End-Use and Application Insights
Analysis of demand distribution across passenger vehicles and commercial vehicles.
Evaluation of evolving industry requirements related to fast-charging capability, battery safety, thermal efficiency, driving range optimization, high-energy-density battery adoption, and vehicle electrification initiatives.
Identification of high-growth and high-value application segments.
Support for targeted product development and go-to-market strategies.
Technology and Competitive Landscape Review
Benchmarking of key battery thermal management technologies including active and passive systems, liquid cooling solutions, air cooling technologies, phase change materials, and advanced thermal interface materials.
Analysis of major players' innovation strategies, product differentiation, thermal management capabilities, OEM partnerships, and regional market presence.
Competitive intelligence for technology positioning and portfolio optimization.
Guidance for R&D prioritization, partnership evaluation, and long-term growth planning.
Frequently Asked Questions About This Report
The global electric vehicle battery thermal management systems market size was valued at USD 7.0 billion in 2025 and is estimated at USD 9.2 billion for 2026.
The global electric vehicle battery thermal management systems market is expected to grow at a CAGR of 35.0% from 2026 to 2033, reaching USD 75.1 billion by 2033.
Some key players operating in the electric vehicle battery thermal management system market include Robert Bosch GmbH, Gentherm Incorporated, Valeo, Hanon Systems, Mahle GmbH, Dana Limited, Voss Automotive GmbH, Grayson, 3M, Polymer Science, Inc., and Lord Corporation.
The passive segment led with a 78.1% revenue share in 2025, while active is the fastest-growing segment.
Key factors that are driving the market growth include the increasing adoption rate of the electric vehicle across the globe and the growing need to develop fast-charging batteries that generate more heat.
Asia Pacific dominated the market, accounting for the largest revenue share of 41.8% in 2025.
The passenger vehicle segment held the highest market share of 88.9% in 2025.
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


