
- Home
- »
- Medical Devices
- »
-
Epilepsy Drugs Market Size & Share Report, 2026-2033GVR Report cover

Epilepsy Drugs Market (2026 - 2033)
Size, Share & Trends Analysis Report By Treatment (First Generation Anti-epileptics, Second Generation Anti-epileptics), By Distribution Channel (Hospital Pharmacies, Retail Pharmacies), By Region, And Segment Forecasts
Market Size, 2025
$11.7BMarket Estimate, 2026
$12.3BMarket Forecast, 2033
$17.5BCAGR, 2026–2033
5.2%Epilepsy Drugs Market Summary
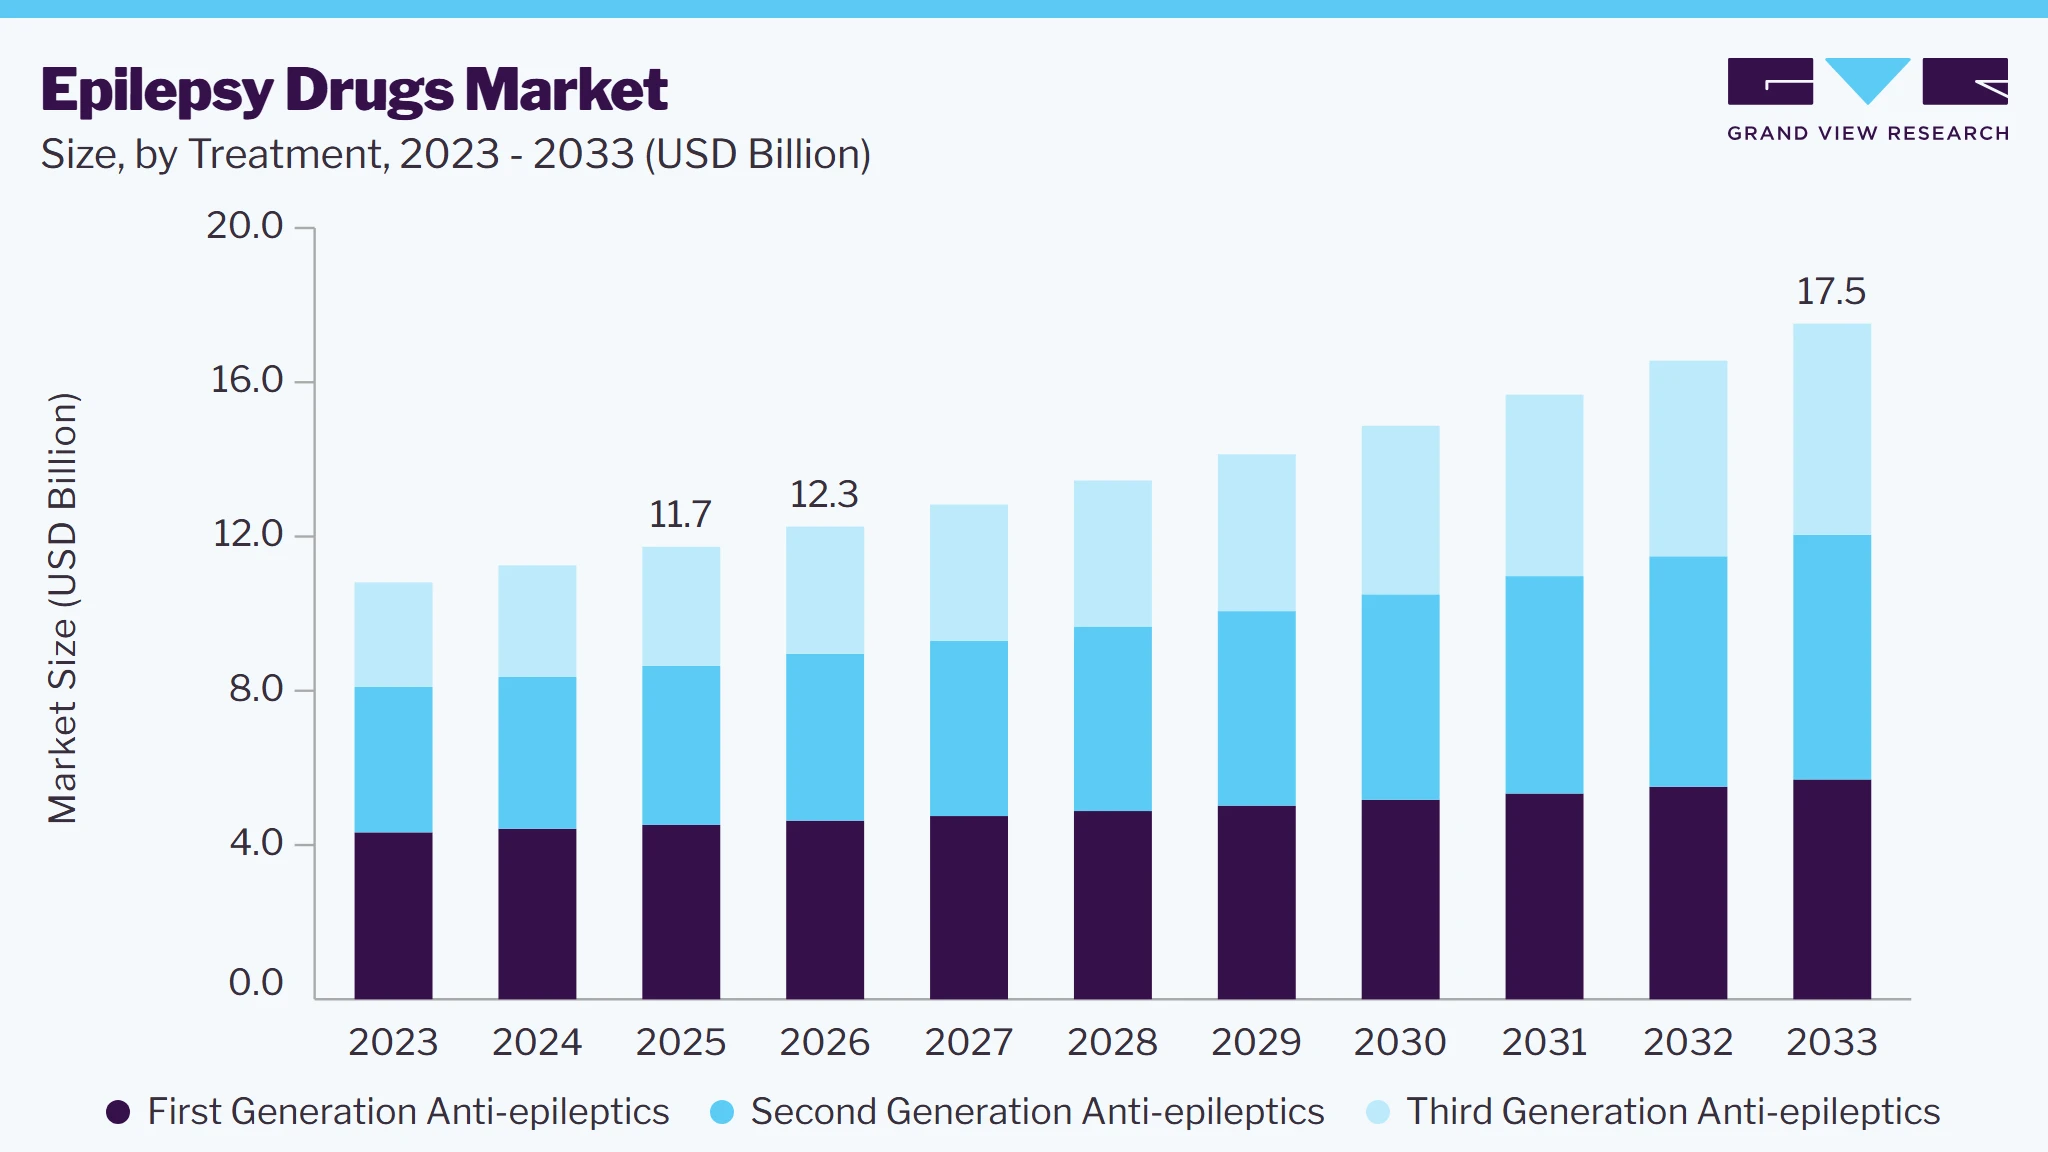
The global epilepsy drugs market size was valued at USD 11.7 billion in 2025 and is projected to grow from USD 12.3 billion in 2026 to USD 17.5 billion by 2033, at a CAGR of 5.2% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 41.2% in 2025. As the global incidence of epilepsy rises, there is a greater demand for effective treatments, fueling innovation in drug therapies.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By treatment: First generation anti-epileptics segment led the market with the largest revenue share of 38.5% in 2025.
- By distribution channel: Hospital pharmacies segment led the market with the
- largest revenue share of 49.3% in 2025.
Regional Highlights
- Largest regional market: North America (41.2% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 11.7 Billion
- Estimated market size in 2026: USD 12.3 Billion
- Projected market size by 2033: USD 17.5 Billion
- CAGR (2026-2033): 5.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Newer anti-epileptic drugs (AEDs) are being developed with improved efficacy, fewer side effects, and better patient outcomes. These advancements are expanding treatment options and improving the quality of life for patients, further contributing to the market expansion.
 To learn more about this report, Download Free Sample Report
Technological advancements in drug delivery systems, such as nano-based formulations and targeted therapies, are enhancing the efficacy and precision of epilepsy treatments. These innovations enable better control over drug release, improving patient compliance and reducing side effects. Furthermore, the rising focus on pediatric epilepsy, driven by increasing awareness and the need for specialized care, is expanding the market for epilepsy drugs. As the demand for more effective, child-friendly treatments grows, these factors are set to significantly accelerate the growth of the epilepsy drugs market in the near future.
Market Dynamics
The epilepsy drugs market is driven by the increasing prevalence of epilepsy, growing awareness regarding neurological disorders, and the rising demand for effective seizure management. Healthcare providers are focusing on improving long term seizure control and reducing the burden of uncontrolled epilepsy, which continues to support the adoption of anti-seizure medications across different patient populations. Ongoing research and development activities are contributing to the introduction of new therapies and expanded treatment options for patients with drug resistant epilepsy. A notable industry development highlights this trend. For instance, in April 2025, Neurelis received FDA approval for VALTOCO (diazepam nasal spray) for the treatment of seizure clusters in children aged 2 to 5 years. The product is used as a short-term treatment for episodes of frequent seizures in epilepsy patients. The market is also benefiting from increasing access to neurological care and continued efforts to improve treatment outcomes through targeted therapies. However, generic competition and the high cost of newer branded therapies continue to create challenges for market participants. Despite these factors, ongoing innovation in epilepsy treatment and the growing focus on addressing unmet clinical needs are expected to support continued market growth.
The growth of the epilepsy drugs market is being driven by the increasing focus on patients with drug resistant epilepsy, a condition that affects a significant portion of the global epilepsy population. Despite the availability of multiple anti-seizure medications, many patients continue to experience uncontrolled seizures, creating a need for newer therapies with improved clinical outcomes. Healthcare providers are increasingly adopting advanced anti-seizure drugs that help reduce seizure frequency and improve quality of life in patients who do not respond adequately to conventional treatment. In addition, growing awareness of epilepsy management, improving diagnosis rates, and greater access to neurological care are supporting the uptake of these therapies across developed and emerging markets. Pharmaceutical companies are also investing in clinical research to demonstrate the effectiveness of newer medications in difficult to treat patient groups. A notable industry development highlights this trend. For instance, in September 2025, Angelini Pharma presented new clinical data on cenobamate showing sustained seizure control in adults with uncontrolled epilepsy. The findings reinforced the growing clinical interest in newer anti-seizure therapies for patients with persistent seizures. As healthcare systems continue to focus on improving long term treatment outcomes, demand for effective therapies for drug resistant epilepsy is expected to remain a key market growth driver.
The high cost of third generation anti-seizure medications remains a key restraint in the epilepsy drugs market. These therapies are developed to provide improved seizure control, better tolerability, and additional treatment options for patients who do not respond adequately to conventional anti-seizure drugs. However, their higher acquisition cost compared with earlier generation medications limits their use in routine clinical practice. As epilepsy requires long term and often lifelong treatment, the cumulative cost of newer therapies can become substantial for both patients and healthcare providers. This cost difference is particularly evident when compared with first and second generation anti-seizure drugs that have been available for many years. In many healthcare settings, treatment is initiated with lower cost alternatives before considering newer medications. As a result, third generation therapies are often used in selected patient groups rather than across the broader epilepsy population. This limits prescription volumes and slows the transition from conventional therapies to newer products. Consequently, the higher cost of third generation anti-seizure medications continues to act as a barrier to their wider adoption, restricting the overall growth potential of this segment within the epilepsy drugs market.
The continued development and commercialization of new anti-seizure medications present a significant opportunity for the epilepsy drugs market. Many patients continue to experience breakthrough seizures despite available treatment options, creating demand for therapies with different mechanisms of action and improved efficacy. Advances in neuroscience research, precision medicine, and genetic understanding of epilepsy are encouraging pharmaceutical companies to develop targeted therapies for specific seizure disorders and patient populations. The market is also benefiting from growing interest in therapies for rare epileptic syndromes and drug-resistant epilepsy, where unmet medical needs remain substantial. Regulatory agencies are increasingly supporting the development of treatments for neurological disorders through expedited review pathways and orphan drug programs. A notable industry development highlights this opportunity. For instance, in August 2025, MSN Laboratories received approval to proceed with a Phase III clinical trial for cenobamate tablets, supporting the development of additional treatment options for epilepsy patients. Such developments indicate continued investment in expanding the epilepsy treatment pipeline and increasing the availability of new therapies. As research activities progress and more products move through clinical development, opportunities for market expansion are expected to increase.
Analyst Perspective
The epilepsy drugs market is expected to witness steady growth driven by the increasing prevalence of epilepsy, growing diagnosis rates, and continued demand for therapies that address drug resistant seizures. Market competition is gradually shifting toward newer generation anti-seizure medications that offer improved clinical outcomes for patients with difficult to control epilepsy. While established pharmaceutical companies continue to leverage broad commercial networks and strong neurology portfolios, specialized players are gaining attention through targeted therapies and innovative formulations. However, generic competition and the high cost of newer treatments remain key challenges. Continued investment in rare epilepsy disorders and precision therapies is expected to shape future market expansion.
Treatment Insights
Based on treatment, the first generation anti-epileptics segment led the market with the largest revenue share of 38.5% in 2025, propelled by their superior efficacy, safety profile, and reduced side effects compared to earlier generations. These drugs, such as levetiracetam and lacosamide, offer broader-spectrum action, making them effective for various types of epilepsy, specifically treatment-resistant cases. Their favorable pharmacokinetic properties, including fewer drug interactions and once-daily dosing, enhance patient compliance. As a result, third-generation AEDs are increasingly preferred by healthcare providers and patients, driving their dominant market position.
The second generation anti-epileptics segment is anticipated to emerge as the fastest-growing segment in the market and is projected to grow at a CAGR of 7.7% over the forecast period, owing to their enhanced efficacy and safety profile compared to first-generation drugs. These newer medications are designed to minimize side effects, offer better seizure control, and improve patient compliance. With advancements in research and growing awareness, the demand for second-generation AEDs is rapidly escalating, particularly as they target specific types of seizures and neurological disorders. This trend positions the second-generation AEDs segment for notable market growth in the coming years.
Distribution Channel Insights
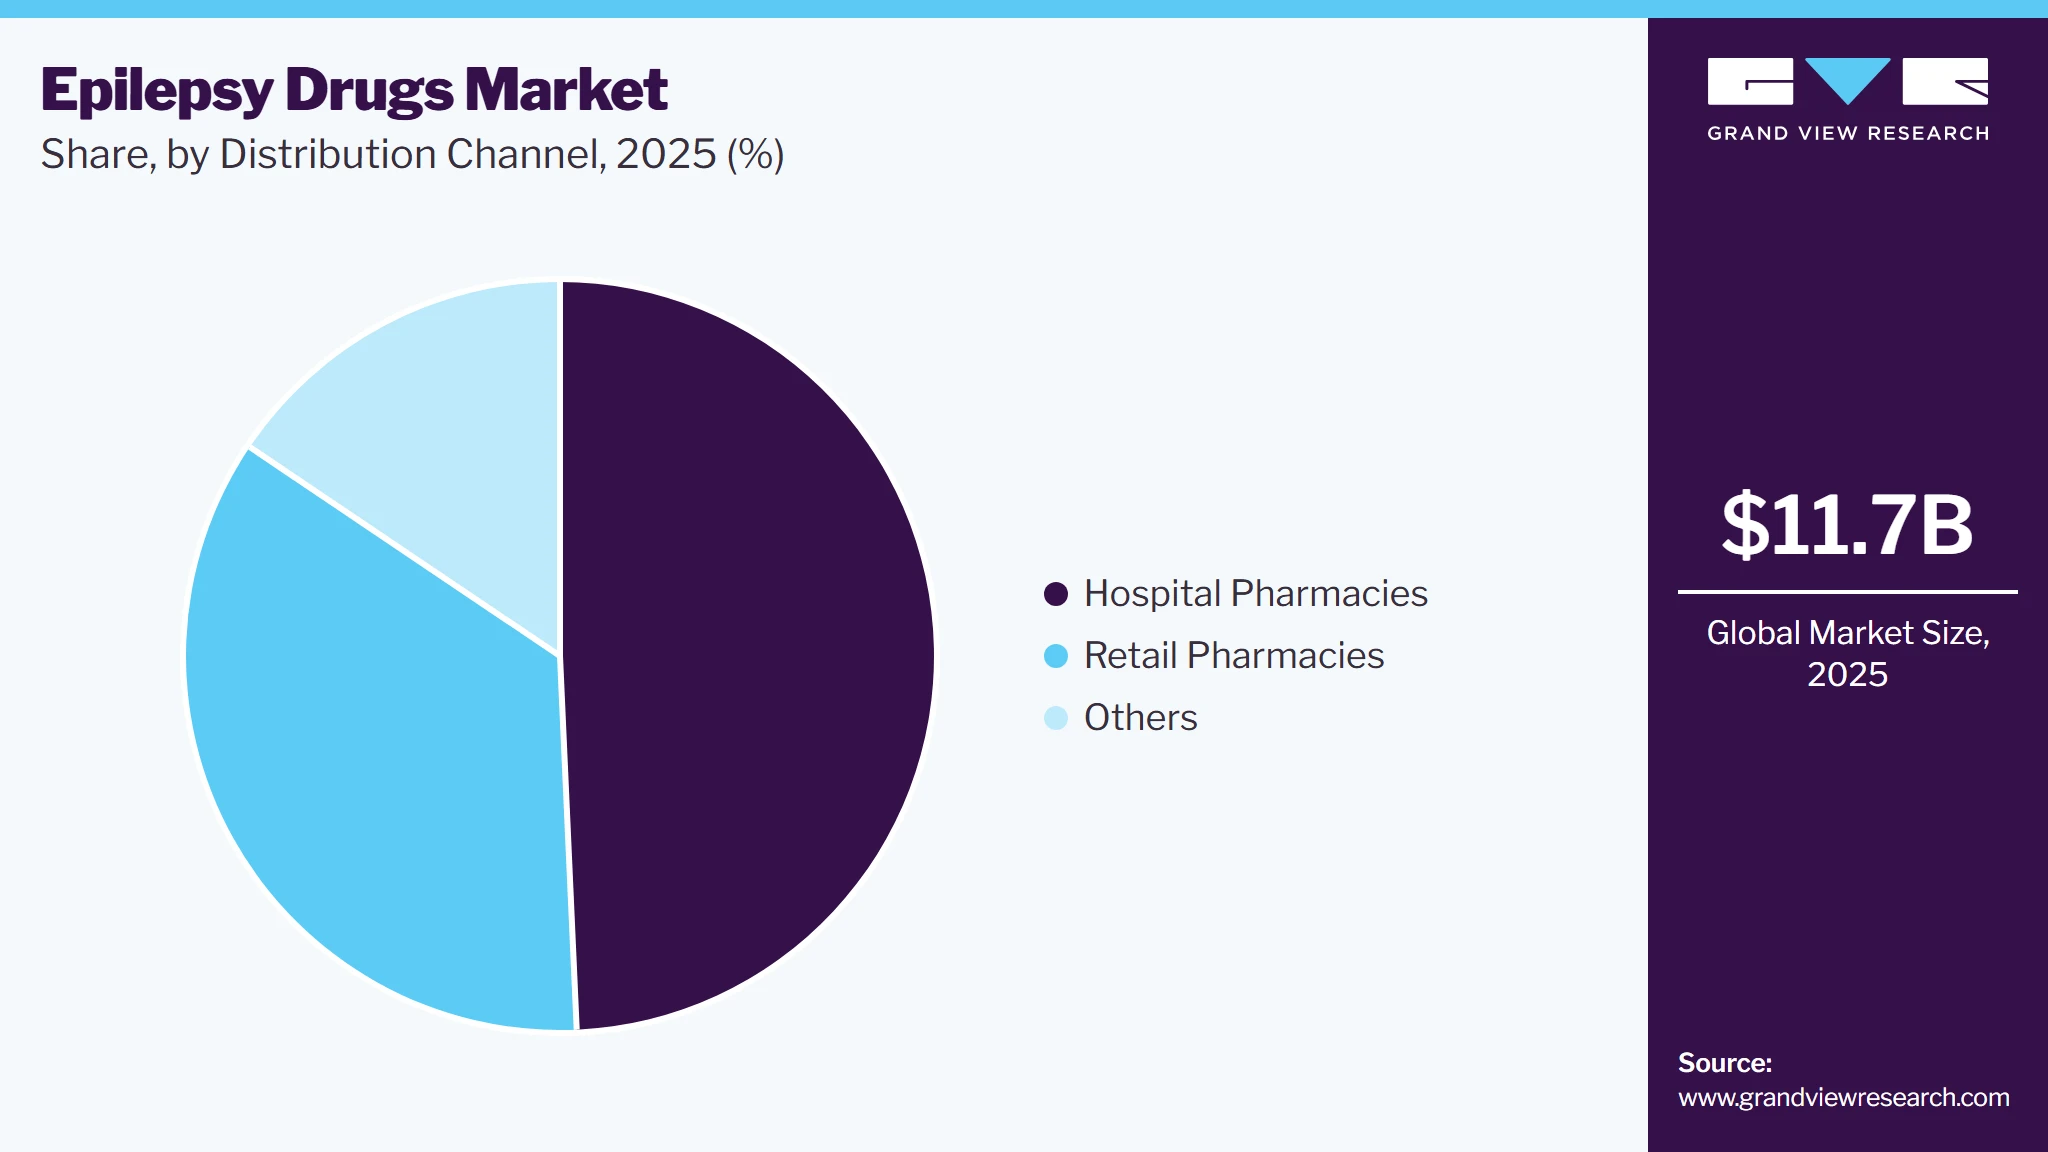
Based on distribution channel, the hospital pharmacies segment led the market with the largest revenue share of 49.3% in 2025 due to their widespread accessibility and convenience. With a large number of patients seeking treatment for epilepsy, retail pharmacies serve as a primary point of access for prescription medications. The availability of both branded and generic antiepileptic drugs (AEDs) in these pharmacies, coupled with the rise in self-medication and over-the-counter options, has further boosted their dominance. Moreover, retail pharmacies often offer competitive pricing and patient-friendly services, making them the go-to source for epilepsy drug procurement.
 To learn more about this report, Download Free Sample Report
The hospital pharmacies segment is expected to stand out as the fastest growing segment and capture a CAGR of 4.4% during the forecast period, fueled by the surging demand for specialized care and treatment. Hospitals are pivotal in managing complex epilepsy cases, offering access to advanced diagnostic tools, expert physicians, and a wide range of anti-epileptic drugs (AEDs). With a surge in patients requiring continuous and personalized treatment, hospital pharmacies are becoming key players in drug distribution. This trend is further supported by ongoing drug formulations and treatment regimen advancements, boosting the segment growth prospects.
Regional Insights
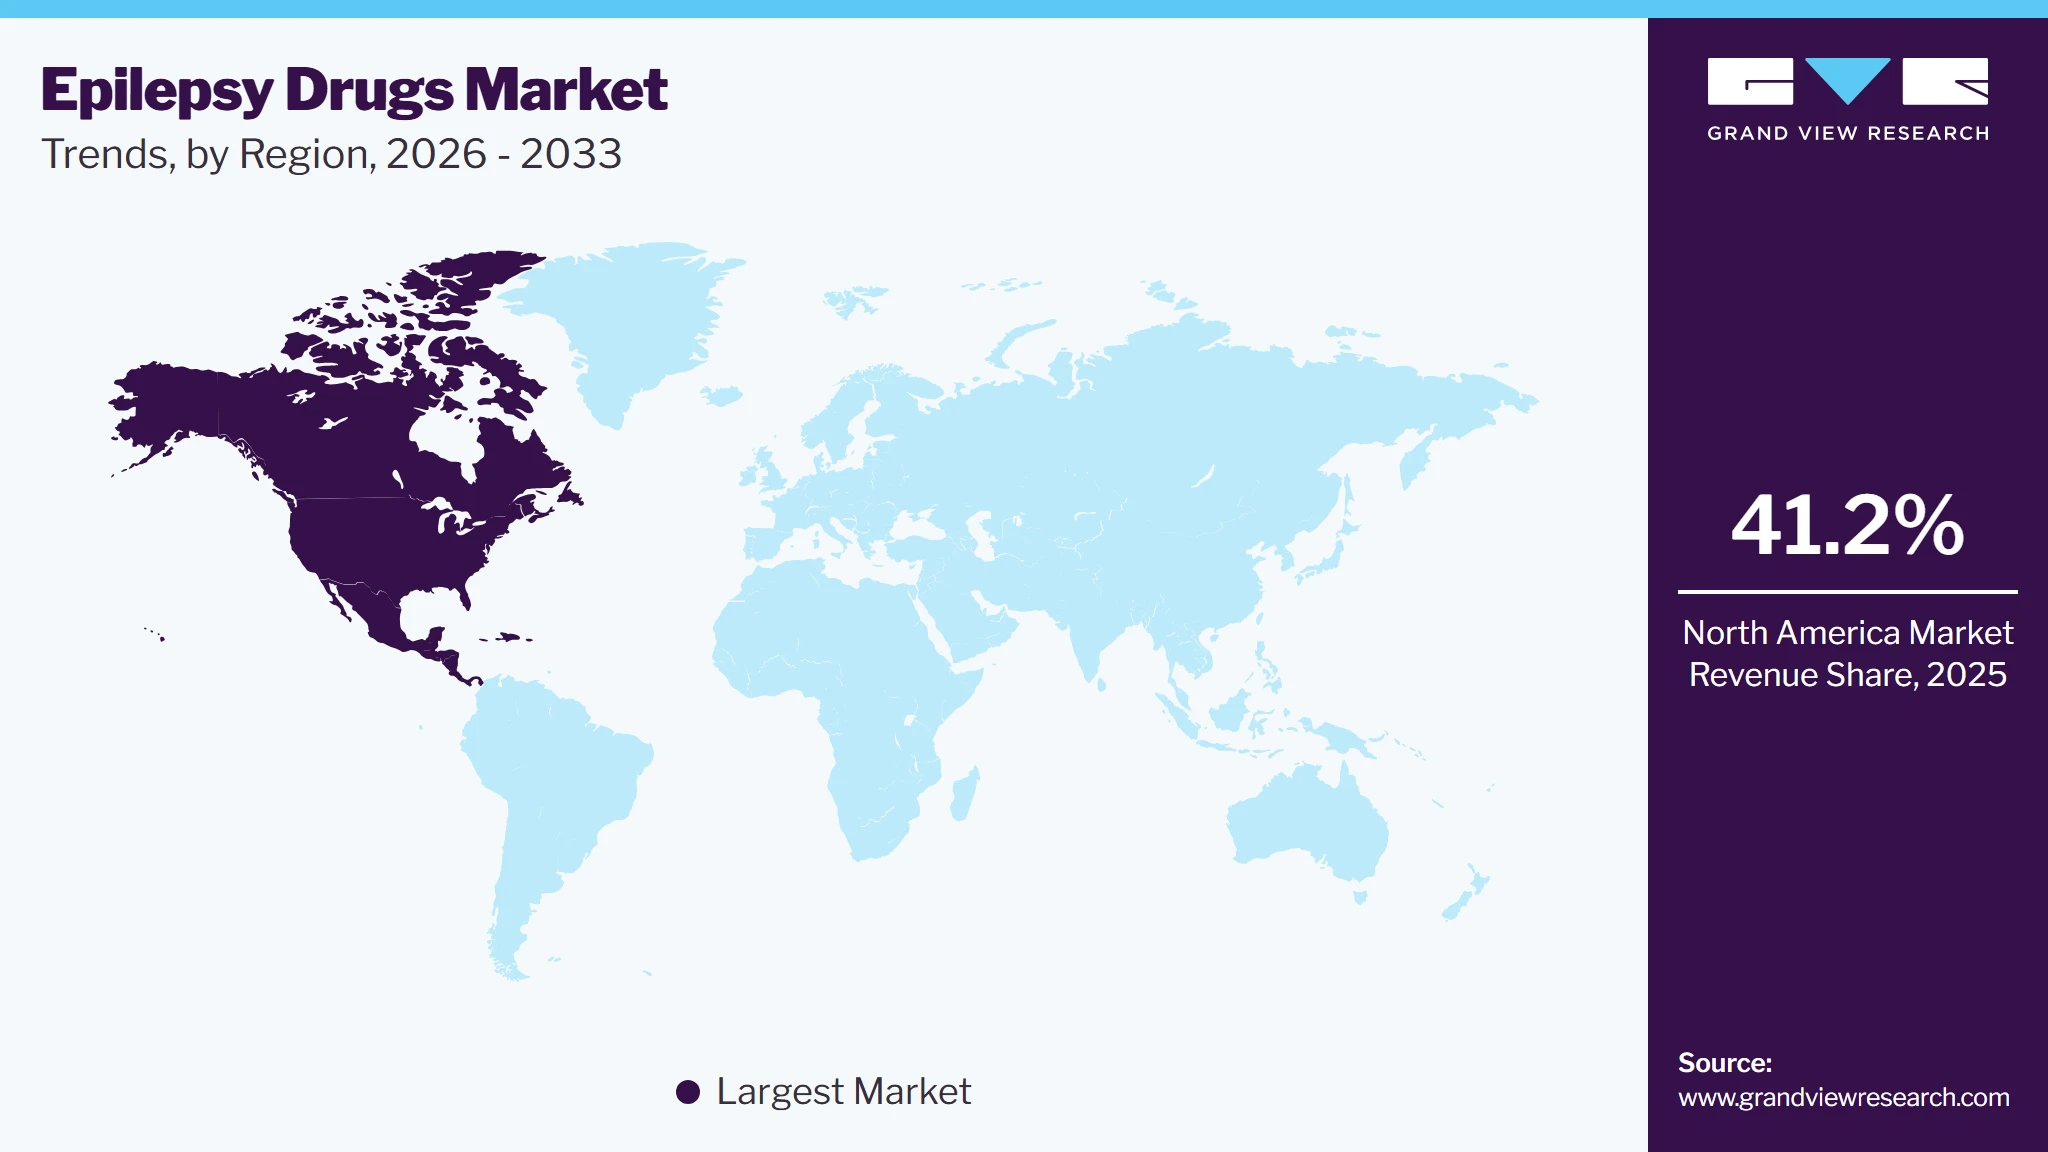
North America dominated the epilepsy drugs market with the largest revenue share of 41.2% in 2025, attributed to advanced healthcare infrastructure, high awareness levels, and robust regional research and development. The U.S. leads in drug innovation, with numerous pharmaceutical companies developing new anti-epileptic drugs (AEDs) and expanding treatment options. In addition, favorable reimbursement policies and widespread access to health care contribute to increased drug adoption. The growing number of diagnosed epilepsy cases, along with the aging population across the region, further boosts the demand for effective epilepsy treatments, thereby strengthening the dominant market position of North America.
 To learn more about this report, Download Free Sample Report
U.S. Epilepsy Drugs Market Trends
The epilepsy drugs market in the U.S. held the largest share in the North America region in 2025 due to its high prevalence of epilepsy, ample healthcare investments, and advanced medical infrastructure. The well-established healthcare system of the country, coupled with sizable research and development efforts, has led to the availability of innovative anti-epileptic drugs (AEDs). In addition, a growing focus on personalized medicine and better patient awareness is propelling demand for effective treatment options. With an aging population and higher diagnosis rates, the U.S. market is expected to grow in the coming years.
Canada is anticipated to achieve a significant CAGR over the forecast period, owing to growing healthcare infrastructure and increasing awareness about epilepsy. With a rising number of diagnosed cases, particularly among the aging population, there is a higher demand for effective treatment options. The focus of Canada on medical research and innovation, along with government support for healthcare initiatives, fuels the development of advanced antiepileptic drugs. Besides, a strong healthcare system across the country ensures widespread access to medications, further accelerating the growth of the epilepsy drugs market in the region.
Europe Epilepsy Drugs Market Trends
Europe is set to expand at the fastest growing CAGR of 4.8% from 2025 to 2033, propelled by the high prevalence of epilepsy, advanced healthcare infrastructure, and a well-established regulatory environment. With an emphasis on innovative drug development and increasing patient awareness, demand for effective epilepsy treatments is surging. Moreover, the presence of key pharmaceutical companies and ongoing research initiatives in Europe is fueling market growth. As healthcare systems continue to improve and access to novel therapies expands, Europe is projected to experience remarkable growth.
Europe is anticipated to achieve a noteworthy revenue share during the forecast period, spurred by its high disease burden and advanced healthcare systems. With an aging population and increasing awareness about epilepsy, there is a rising demand for effective treatments. The region's robust pharmaceutical industry, coupled with ongoing research and development efforts, is fueling the creation of innovative antiepileptic drugs. Moreover, government support for healthcare initiatives and the availability of treatment options are projected to fuel further the expansion of the epilepsy drugs market in Europe.
The U.K. is expected to establish a considerable foothold by 2033, fueled by escalating epilepsy cases and advancements in medical treatments. With a strong healthcare system, high levels of patient awareness, and continuous research into novel therapies, demand for effective epilepsy medications is surging. The U.K. also benefits from a robust regulatory environment and support for drug development, making it a hub for pharmaceutical innovation. As new antiepileptic drugs (AEDs) become available, the U.K. is set to witness significant growth in its epilepsy drug market.
Germany is projected to accumulate sizable gains by 2033, driven by its thriving healthcare system, growing elderly population, and increasing awareness of neurological disorders. The emphasis on research and development in the country fosters innovation in anti-epileptic drugs (AEDs), driving the availability of advanced treatment options. Furthermore, the strong healthcare policies of Germany, which provide broad access to medications, are expected to boost market growth. With a surge in number of epilepsy diagnoses and a well-established pharmaceutical sector, Germany is anticipated to experience substantial expansion in the epilepsy drugs market.
Asia Pacific Epilepsy Drugs Market Trends
Asia Pacific epilepsy drugs market is expected to register at a notable CAGR over the forecast period, attributed to the large and diverse population of the region, surging prevalence of epilepsy, and improving healthcare infrastructure. As awareness of epilepsy increases, demand for effective treatment options is growing across countries in the region. Besides, rapid urbanization, increasing healthcare access, and government initiatives to improve medical care contribute to market growth. The expanding pharmaceutical industry in the region and ample investments in research and development of antiepileptic drugs further support its potential for remarkable growth in the epilepsy drugs market.
Japanis projected to grow at a commendable CAGR over the forecast period due to its aging population, which leads to a higher incidence of epilepsy and advancements in healthcare. The country's strong pharmaceutical industry and commitment to innovation in medical research are fueling the development of novel antiepileptic drugs (AEDs). Furthermore, the well-established healthcare system and regulatory support of Japan provide a favorable environment for drug adoption and market growth. As new and more effective treatments become available, Japan is set to see significant expansion in the years ahead.
China captured a noteworthy share in 2024, spurred by its large population and increasing awareness of neurological disorders. As healthcare access improves and healthcare infrastructure develops in the country, more individuals are being diagnosed and treated for epilepsy. In addition, the escalating investment in medical research and drug development in China is propelling innovation in anti-epileptic drugs (AEDs). The rising incidence of epilepsy and government initiatives to expand healthcare coverage are further accelerating the demand for epilepsy medications, positioning China for substantial market growth.
Key Epilepsy Drugs Company Insights
Some of the key companies in the epilepsy drugs market include UCB S.A.; Sanofi; Pfizer, Inc.; Otsuka America Pharmaceutical, Inc.; Eisai Co., Ltd.; Abbott Laboratories, Inc.; Novartis AG; GlaxoSmithKline plc; Sunovion Pharmaceuticals, Inc.; Jazz Pharmaceuticals plc; Neurelis, Inc.
-
Abbott Laboratories, Inc. offers various healthcare products, including diagnostics, medical devices, nutrition, and branded generic medicines. It aims to improve health outcomes and enhance quality of life globally.
-
Novartis AG provides innovative healthcare solutions, particularly prescription medications, vaccines, and gene therapies. It emphasizes oncology, ophthalmology, neuroscience, and cardiovascular diseases to improve global health.
Key Epilepsy Drugs Companies
The following key companies have been profiled for this study on the epilepsy drugs market.
-
UCB S.A.
-
Sanofi
-
Pfizer, Inc.
-
Otsuka America Pharmaceutical, Inc.
-
Eisai Co., Ltd.
-
Abbott Laboratories, Inc.
-
Novartis AG
-
GlaxoSmithKline plc
-
Sunovion Pharmaceuticals, Inc.
-
Jazz Pharmaceuticals plc
-
Neurelis, Inc.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Established Players (UCB S.A., Sanofi, Pfizer, Inc., Eisai Co., Ltd., Novartis AG, GlaxoSmithKline plc, Abbott Laboratories, Inc.)
- Focus on expanding epilepsy treatment portfolios through lifecycle management, label expansions, and development of therapies targeting drug resistant epilepsy and rare seizure disorders.
- Invest in clinical research, regulatory approvals, and strategic collaborations to strengthen market presence across major healthcare markets.
- Maintain strong engagement with neurologists, epilepsy centers, hospitals, and patient advocacy organizations through medical education and disease awareness initiatives.
- Strong commercial presence supported by established brands, broad product portfolios, and extensive experience in neurology and central nervous system disorders.
- Global distribution capabilities, established regulatory expertise, and long standing relationships with healthcare providers support market penetration and product adoption.
- Exposure to patent expirations and increasing generic competition for established epilepsy therapies.
- Large organizational structures may result in longer development timelines and slower adaptation to emerging treatment approaches compared with smaller specialized companies.
Emerging and Specialized Players (Otsuka America Pharmaceutical, Inc., Sunovion Pharmaceuticals, Inc., Jazz Pharmaceuticals plc, Neurelis, Inc.)
- Focus on specialized epilepsy segments through the development and commercialization of therapies for seizure clusters, refractory epilepsy, and rare neurological disorders.
- Emphasize product differentiation through novel formulations, targeted indications, and patient focused treatment approaches.
- Pursue strategic partnerships, clinical development programs, and geographic expansion to increase market reach.
- Ability to address specific unmet clinical needs through focused neurology portfolios and specialized treatment offerings.
- Greater operational flexibility enables faster decision making and quicker response to evolving clinical and regulatory requirements.
- Limited product diversification compared with larger pharmaceutical companies.
- Dependence on a smaller number of products and narrower commercial infrastructure may constrain market reach and increase vulnerability to competitive pressures and regulatory risks.
Recent Developments
-
In November 2024, Neurelis, Inc. shared insights on the study design from their enrollment process for the Stellina study. This study investigated VALTOCO® (diazepam nasal spray) for treating seizure clusters in epilepsy patients aged 2 to 5.
-
In October 2023, Sanofi sold its epilepsy medication Frisium (clobazam) and ten other CNS medicine brands to Pharmanovia. Frisium is used as an adjunctive treatment with other epilepsy medications.
Epilepsy Drugs Market Report Scope
Report Attribute
Details
Market size in 2025
USD 11.7 billion
Estimated market size in 2026
USD 12.3 billion
Projected market size by 2033
USD 17.5 billion
Growth rate
CAGR of 5.2% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Treatment, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
UCB S.A., Sanofi, Pfizer, Inc., Otsuka America Pharmaceutical, Inc., Eisai Co., Ltd., Abbott Laboratories, Inc., Novartis AG, GlaxoSmithKline plc, Sunovion Pharmaceuticals, Inc., Jazz Pharmaceuticals plc, Neurelis, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Epilepsy Drugs Market Report Segmentation
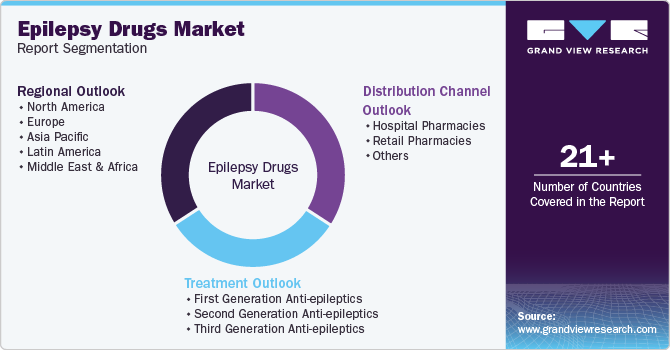
This report forecasts revenue and volume growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global epilepsy drugs market report on the basis of treatment, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Treatment Outlook (Revenue, USD Million, 2021 - 2033)
-
First Generation Anti-epileptics
-
Second Generation Anti-epileptics
-
Third Generation Anti-epileptics
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital Pharmacies
-
Retail Pharmacies
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
U.K.
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Norway
-
Sweden
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The epilepsy drugs market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each epilepsy drugs segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Treatment
Revenue capture definition
First Generation Anti-epileptics
Includes anti-epileptic drugs introduced during the early phases of epilepsy pharmacotherapy and widely used for the treatment of focal and generalized seizures. This segment comprises products such as phenytoin, carbamazepine, valproic acid, phenobarbital, ethosuximide, and their branded and generic formulations. Revenue is generated from the sale of first generation anti-epileptic drugs only and excludes second generation and third generation anti-epileptic therapies.
Second Generation Anti-epileptics
Includes anti-epileptic drugs developed as newer alternatives to first generation therapies with improved pharmacokinetic profiles, safety characteristics, or reduced drug interaction potential. This segment comprises products such as lamotrigine, levetiracetam, topiramate, oxcarbazepine, gabapentin, pregabalin, tiagabine, vigabatrin, and zonisamide. Revenue is generated from the sale of second generation anti-epileptic drugs only and excludes first generation and third generation anti-epileptic therapies.
Third Generation Anti-epileptics
Includes recently developed anti-epileptic drugs designed to provide additional treatment options for patients with difficult to control seizures or specific epilepsy syndromes. This segment comprises products such as brivaracetam, cenobamate, perampanel, eslicarbazepine acetate, lacosamide, rufinamide, and cannabidiol based therapies. Revenue is generated from the sale of third generation anti-epileptic drugs only and excludes first generation and second generation anti-epileptic therapies.
Segment – Distribution Channel
Revenue capture definition
Hospital Pharmacies
Includes revenue generated from epilepsy drugs dispensed through hospital based pharmacies and institutional healthcare facilities. This segment covers anti-epileptic medications supplied to inpatients, emergency care patients, and patients receiving treatment through hospital affiliated outpatient services. Revenue is attributed to sales occurring through hospital pharmacy channels only and excludes sales through retail pharmacies, online pharmacies, mail order pharmacies, and specialty pharmacy networks.
Retail Pharmacies
Includes revenue generated from epilepsy drugs dispensed through community pharmacies, chain pharmacies, independent pharmacies, and other retail drug outlets. This segment covers prescription anti-epileptic medications supplied directly to patients for ongoing epilepsy management. Revenue is attributed to sales through retail pharmacy channels only and excludes hospital pharmacy, specialty pharmacy, online pharmacy, and mail order pharmacy sales.
Others
Includes revenue generated from epilepsy drugs distributed through channels outside hospital and retail pharmacies. This segment comprises online pharmacies, mail order pharmacies, specialty pharmacies, long term care pharmacy providers, and other non-traditional pharmaceutical distribution channels. Revenue is attributed exclusively to these alternative channels and excludes sales captured under hospital pharmacies and retail pharmacies.
Estimation Model
Based on the methodology illustrated in the image, the Epilepsy Drugs Market was estimated using a patient pool and treatment uptake model. The analysis began by identifying the total population across key countries and regions, followed by assessing the incidence and prevalence of epilepsy to determine the overall epilepsy patient pool. The patient pool was further refined by evaluating the proportion of diagnosed patients through epidemiological studies, healthcare databases, and national health statistics. This diagnosed population served as the foundation for estimating the addressable market for epilepsy therapeutics.
The next step involved calculating the treated patient pool by analyzing treatment-seeking behavior, healthcare access, reimbursement coverage, and physician prescribing patterns. The treated population was then segmented according to therapy type, including first-generation antiepileptic drugs, second-generation antiepileptic drugs, and novel epilepsy treatments. Market share and patient uptake for each therapy category were assessed using prescription data, company reports, and expert interviews. Finally, the number of patients receiving each therapy was multiplied by the average annual cost of treatment to estimate revenue generated by individual drug segments. The aggregation of revenues across all therapies and regions resulted in the overall Epilepsy Drugs Market size, with forecasts developed based on disease prevalence trends, treatment adoption rates, product launches, and evolving healthcare expenditure.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Epilepsy Drugs Competitive Landscape & Pipeline Assessment
Conducted a targeted assessment of the global epilepsy drugs market, evaluating marketed products, late-stage pipeline candidates, therapeutic positioning, and competitive strategies of key participants including UCB, Eisai, Jazz Pharmaceuticals, Neurelis, Pfizer, Sanofi, and Novartis. The study analyzed product portfolios across focal seizures, generalized seizures, seizure clusters, drug resistant epilepsy, and rare epileptic syndromes, while assessing clinical development activities, regulatory milestones, and commercialization strategies.
Helped the client identify high growth therapeutic segments, evaluate competitive intensity, benchmark product positioning, and prioritize licensing, partnership, acquisition, and portfolio expansion opportunities within the epilepsy treatment market.
Epilepsy Drugs Product Benchmarking & Clinical Differentiation Study
Delivered a comprehensive benchmarking analysis of epilepsy therapies, comparing first generation, second generation, and third generation anti seizure medications. The assessment evaluated efficacy, safety profiles, seizure reduction outcomes, mechanism of action, treatment adherence, regulatory status, and clinical adoption trends across leading branded and generic products. The study also assessed emerging therapies targeting drug resistant epilepsy and rare epilepsy disorders.
Enabled the client to assess product competitiveness, identify unmet clinical needs, benchmark development strategies, and prioritize investments in innovative anti seizure therapies and next generation epilepsy treatment approaches.
Epilepsy Treatment Market Access & Commercialization Feasibility Assessment
Conducted a strategic assessment of the epilepsy treatment ecosystem, evaluating prescribing patterns, treatment pathways, reimbursement environments, distribution channels, regulatory requirements, and commercialization readiness across major markets. The study analyzed hospital utilization, retail pharmacy trends, patient access challenges, physician adoption patterns, and regional opportunities influencing the uptake of epilepsy therapies.
Supported commercialization planning by identifying market access opportunities, evaluating distribution and reimbursement challenges, mitigating adoption barriers, and strengthening long term growth strategies across developed and emerging epilepsy treatment markets.
Frequently Asked Questions About This Report
By treatment segment the first generation anti-epileptics segment led the market with a 38.5% revenue share in 2025, while the second generation anti-epileptics segment is expected to be the fastest growing.
North America dominated the epilepsy drugs market with a 41.2% revenue share in 2025.
Europe is the fastest-growing regional market and is projected to expand at the highest CAGR over the forecast period.
The hospital pharmacies segment held the largest revenue share of 49.3% in 2025 and is also expected to be the fastest-growing distribution channel during the forecast period.
Major opportunities include the development of novel anti-seizure therapies, expansion of treatments for drug-resistant epilepsy and rare epilepsy syndromes, advancements in targeted drug delivery systems, increasing focus on pediatric epilepsy, and broader adoption of precision medicine approaches.
Key players include UCB S.A., Sanofi, Pfizer Inc., Otsuka America Pharmaceutical, Inc., Eisai Co., Ltd., Abbott Laboratories, Novartis AG, GlaxoSmithKline plc, Sunovion Pharmaceuticals, Inc., Jazz Pharmaceuticals plc, and Neurelis, Inc.
Key factors include the rising prevalence of epilepsy, increasing focus on drug-resistant epilepsy treatment, growing diagnosis rates, continuous development of next-generation anti-seizure medications, expanding access to neurological care, and increasing investments in epilepsy-focused research and development.
The global epilepsy drugs market size was valued at USD 11.7 billion in 2025 and is estimated at USD 12.3 billion for 2026.
The global epilepsy drugs market is expected to grow at a CAGR of 5.2% from 2026 to 2033, reaching USD 17.5 billion by 2033.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


