
- Home
- »
- Petrochemicals
- »
-
Ethylene Glycols Market Size, Growth Report, 2026-2033GVR Report cover

Ethylene Glycols Market (2026 - 2033)
Size, Share & Trends Analysis Report By Derivative (MEG, DEG, TEG), By Application (Polyester Fibers, PET, Antifreeze & Coolants), By End Use (Automotive, Textile), By Region, And Segment Forecasts
Market Size, 2025
$19.5BMarket Estimate, 2026
$20.5BMarket Forecast, 2033
$29.4BCAGR, 2026–2033
5.3%Ethylene Glycols Market Summary
The global ethylene glycols market size was valued at USD 19.5 billion in 2025 and is projected to grow from USD 20.5 billion in 2026 to USD 29.4 billion by 2033, growing at a CAGR of 5.3% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 40.0% in 2025. Market growth worldwide can be attributed to rising demand from the textile and automotive industries, increased PET resin production, technological advancements, renewable energy initiatives, and utilization effects. Furthermore, innovation has improved market productivity and product quality, fostering connections with end-user industries where ethylene glycol is a key feedstock, thereby driving market growth.
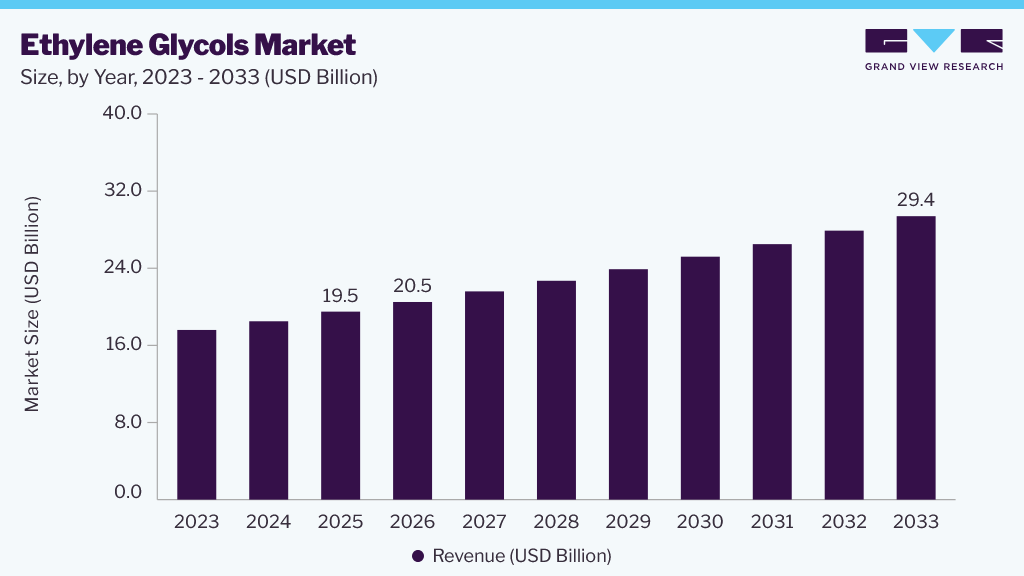 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By derivative type: The triethylene glycol (TEG) derivative segment dominated the market with a revenue share of 41.0% in 2025
- By application: The PET segment held the largest revenue share of over 44.0% in 2025.
- By end use: The packaging segment dominated the market, with a revenue share of about 35.0% in 2025.
Regional Highlights
- Largest regional market: North America (40.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (Highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 19.5 Billion
- Estimated market size in 2026: USD 20.5 Billion
- Projected market size by 2033: USD 29.4 Billion
- CAGR (2026-2033): 5.3%
GVR research-powered AIAsk Prism AI about the ethylene glycols marketGet cited answers from GVR research on market growth, segments, regulations and forecasts.Start with✓ Source-linked answers ✓ Market-specific context ✓ Traceable figuresExplore Prism AI ↗Industry growth is primarily driven by rising demand for polyethylene terephthalate (PET) packaging, owing to its superior clarity, strength, and recyclability. The increasing consumption of bottled beverages, packaged food, and consumer goods continues to drive PET resin demand, thereby positively impacting ethylene glycol consumption.
The growing demand for polyester fibers in textile and industrial applications is another major growth driver. Ethylene glycol serves as a key raw material in polyester fiber production, which is widely used in apparel, home furnishings, and industrial textiles. Strong textile manufacturing activity, particularly in the Asia Pacific, continues to support market expansion.
Increasing vehicle production and sales, especially in emerging economies, are further contributing to market growth. Ethylene glycol is widely used in automotive coolants and antifreeze formulations for thermal management applications. Rising demand for HVAC systems in commercial and industrial infrastructure is also supporting consumption. In addition, the growing use of ethylene glycol as a heat-transfer fluid in renewable energy systems, such as solar panels and wind turbines, is creating additional growth opportunities.
Technological advancements in ethylene glycol production processes are improving manufacturing efficiency and reducing operating costs. Growing focus on sustainability has also accelerated the adoption of bio-based ethylene glycol. Ongoing investments in process optimization, advanced catalysts, and sustainable production technologies are expected to further support market growth.
Analyst Perspective
The market is expected to witness steady growth over the forecast period, supported by strong demand from PET packaging, polyester fiber production, and automotive coolant applications. Asia Pacific remains the key demand center due to its large textile manufacturing base and expanding packaging industry, particularly in China and India. The market is also benefiting from the growing adoption of bio-based ethylene glycol and advances in production technologies that enhance efficiency and sustainability. However, volatility in crude oil and ethylene prices, along with environmental regulations governing petrochemical production, may pose challenges for market participants. Capacity expansions, downstream integration, and increasing investments in sustainable production technologies are expected to shape the competitive landscape over the coming years.
Derivative Type Insights
The Triethylene Glycol (TEG) derivative segment dominated the market, accounting for approximately 41.0% of revenue in 2025. TEG has emerged as a key derivative in industries such as plastics, chemicals, and natural gas processing. Its low volatility, high boiling point, and moisturizing and regulating properties make it an ideal choice for specific applications such as natural gas dehydration and hygroscopic processes. Rising investments in natural gas infrastructure and LNG processing facilities, particularly in the U.S., Qatar, and China, are further driving demand for TEG due to its high efficiency in moisture removal during gas dehydration. Growing demand for high-performance plasticizers, unsaturated polyester resins, and specialty chemical formulations is also supporting segment growth, as TEG is widely used as an intermediate in the production of industrial chemicals and performance materials.
The Monoethylene Glycol (MEG) derivative segment is expected to register the fastest CAGR during the forecast period. MEG is a versatile and highly sought-after chemical with a wide range of applications. Its use spans industries such as polyester fibers, antifreeze, and packaging materials. MEG is valued for its chemical stability, low freezing point, and efficient heat transfer properties, making it highly suitable for polyester production, packaging, and coolant applications. The segment is primarily driven by rising demand from polyester fiber manufacturing, supported by increasing consumption in apparel, home textiles, and industrial applications, particularly across China and India. In addition, the growing demand for PET resin in packaging applications is further accelerating segment growth. According to the PET Resin Association, PET remains one of the most widely used packaging materials for beverage bottles and food containers due to its lightweight, durability, and recyclability, directly supporting MEG consumption as a key raw material in PET production.
Application Insights
The PET application segment dominated the market, accounting for 44.0% of revenue in 2025. Polyethylene Terephthalate (PET) is a highly sought-after material in various industries, including packaging, textiles, and automotive. Its popularity stems from its durability, excellent moisture resistance, and high chemical resistance. PET-based polyester fibers are widely used in the textile industry for apparel, home furnishings, and industrial fabrics, driving demand for ethylene glycol. Its versatility and benefits make it an attractive choice for companies seeking reliable and high-quality materials. The segment is further driven by rising demand for packaged food and beverages, as PET remains a preferred material for bottles and food containers due to its lightweight, transparent, and recyclable nature. Growing consumption of bottled water, carbonated drinks, and ready-to-eat food products continues to support PET demand globally. In addition, the growing emphasis on sustainable and recyclable packaging solutions is accelerating PET adoption across packaging applications, as manufacturers focus on reducing packaging weight and advancing circular economy initiatives.
Polyester Fibers are expected to register the fastest CAGR in the forecast period. Polyester fibers, derived from PET, boast numerous desirable characteristics, including high strength, durability, and resistance to stretching and shrinkage. These benefits make them an attractive choice for various applications. In addition, polyester fibers are generally cheaper than natural fibers, such as cotton or wool, which enhances their value proposition. This affordability and accessibility make them a popular choice among textile manufacturers. The segment is further driven by rising demand from the apparel and home furnishings industries, where polyester fibers are widely used in sportswear, fashion apparel, upholstery, carpets, and bedding products for their durability and cost-effectiveness. Increasing urbanization and changing consumer lifestyles are further supporting demand for polyester-based textile products. In addition, growing adoption of polyester fibers in industrial applications, including automotive fabrics, conveyor belts, tire cords, and filtration materials, is contributing to segment growth due to their superior mechanical strength and chemical resistance.
End Use Insights
The packaging segment dominated the market, accounting for approximately 35.0% of revenue in 2025. The consumer goods industry has experienced significant growth, driven by changes in consumer lifestyles. As a result, there is a growing demand for PET packaging solutions. Ethylene glycol is a key component in the production of PET resins, which are used in packaging applications such as bottles, containers, and films. Its flexibility and suitability for packaging purposes make it an attractive choice. Furthermore, the trend towards eco-friendly packaging solutions is driving consistent demand for ethylene glycol.
The automotive segment is expected to register steady growth over the forecast period. Market growth is driven primarily by increased demand for antifreeze in the automotive sector, supported by global automobile sales and regular consumption across both aftermarket and OEM channels. Ethylene glycol is a key component in the production of high-quality antifreeze, which prevents engine coolants from freezing in cold climates and helps maintain optimal engine temperature. The segment is further supported by rising vehicle production, particularly across emerging economies such as China and India, where increasing passenger vehicle ownership and expanding automotive manufacturing are driving demand for engine coolants and thermal management fluids. In addition, growing adoption of electric vehicles is contributing to segment growth, as advanced thermal management systems in EV batteries and power electronics increasingly require efficient coolant solutions, further supporting ethylene glycol consumption in automotive applications.
Regional Insights
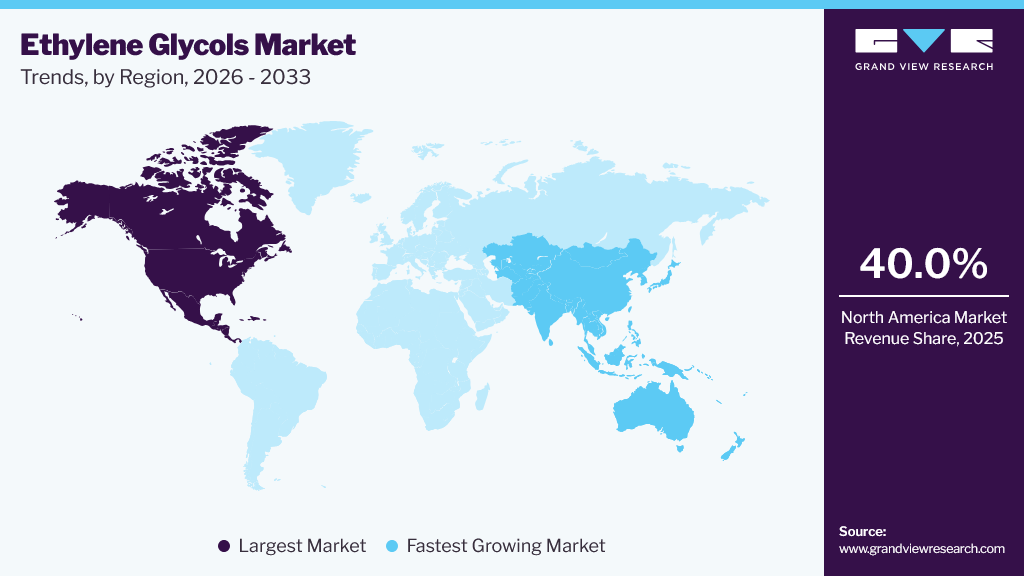
North America dominated the market, accounting for a revenue share of 40.0% in 2025. The regional market is supported by major industry participants such as Dow Inc., Exxon Mobil Corporation, and LyondellBasell Industries, which maintain strong production capabilities and established distribution networks. Growing demand for polyester fibers, PET packaging, automotive coolants, and industrial chemicals continues to support market growth across the region. In addition, abundant shale gas-based feedstocks and well-established integrated petrochemical infrastructure provide a strong competitive advantage for ethylene glycol production in North America. The region is expected to witness steady growth over the forecast period, supported by cost-competitive raw materials, ongoing investments in downstream petrochemicals, and sustained demand from automotive, packaging, and industrial end-use industries.
 To learn more about this report, Download Free Sample Report
U.S. Ethylene Glycols Market Trends
The ethylene glycols market in the U.S. dominated North America with a revenue share of approximately 41.0% in 2025. The manufacturing and use of ethylene glycol have seen significant advancements in production technology, especially in the U.S. The country has embraced a culture of learning and innovation through research, leading to the development of modern technologies that advance production and product quality. Moreover, the country’s large industrial infrastructure, especially in plastics, textiles, and the automobile industries, drives the use of ethylene glycol.
Europe Ethylene Glycols Market Trends
The ethylene glycols market in Europe was identified as a lucrative region in the global market in 2025. European companies, strategically located near international markets, have established a broader export footprint, leveraging strong trade connections with key regions. The region’s well-developed automotive, textile, and chemical industries drive demand for ethylene glycol products, allowing European companies to capture a significant market share.
Germany ethylene glycols market held a substantial market share in 2025. Germany’s thriving automobile industry, renowned for its high-quality products and sophisticated engineering, drives demand for ethylene glycol in applications such as coolants and heat transfer fluids. This focus on automotive excellence contributes to Germany’s market growth. Moreover, according to the World Bank, the country imports ethylene glycol from Belgium, the Netherlands, China, and the UK, further solidifying its position in the market.
Asia Pacific Ethylene Glycols Market Trends
The ethylene glycols market in the Asia Pacific is expected to register the fastest CAGR over the forecast period. The region is characterized by rapid industrialization and urbanization, which are driving demand for ethylene glycol across packaging, textiles, automotive, and industrial applications. Strong growth in polyester fiber and PET resin production, coupled with rising disposable incomes and expanding manufacturing activities, continues to support regional market growth. Increasing demand for apparel, packaged food and beverages, automotive products, and antifreeze solutions across emerging economies such as China and India is further accelerating market expansion. For instance, in January 2024, SABIC approved a USD 6.4 billion investment for the SABIC Fujian Petrochemical Complex in China. The project includes a mixed-feed steam cracker with an annual ethylene capacity of up to 1.8 million tons, along with downstream production facilities for ethylene glycols, polyethylene, polypropylene, and polycarbonate. This investment is expected to strengthen regional ethylene glycol production capacity and support growing demand from the polyester and packaging industries across Asia-Pacific.
China ethylene glycols market is expected to grow rapidly in the coming years. China is a major manufacturing hub, particularly in textiles and automobiles. Its industrial production requires a large amount of ethylene glycol for manufacturing polyester fibers and PET resins. The market is further supported by strong demand from the packaging industry, driven by rising consumption of bottled beverages, packaged food products, and consumer goods. In addition, ongoing industrial expansion, rapid urbanization, and rising investments in petrochemical production capacity are expected to further support ethylene glycol demand nationwide.
Key Ethylene Glycols Company Insights
Some key companies in the market include Exxon Mobil Corporation, Dow Inc., SABIC, China Petrochemical Corporation, Shell Chemicals, and Reliance Industries Limited, among others. Market leaders are driving growth through strategic initiatives, including joint ventures, mergers, capacity expansions, collaborations, new product launches, and alliances, to enhance their market presence and competitiveness.
- Exxon Mobil Corporation is a multinational oil and gas company engaged in the exploration, production, refining, and distribution of petroleum and natural gas products. The company produces ethylene glycol through its global chemical manufacturing network. Exxon Mobil’s advanced production technologies and strong operational capabilities enable efficient and sustainable ethylene glycol production for diverse industrial applications.
- Dow Inc. is a leading global chemical company with a strong focus on producing high-quality ethylene glycols for various industrial applications. The company emphasizes sustainability, innovation, and research & development to deliver advanced product solutions while minimizing environmental impact.
Key Ethylene Glycols Companies
The following key companies have been profiled for this study on the ethylene glycols market:
-
Exxon Mobil Corporation.
-
Dow
-
SABIC
-
China Petrochemical Corporation (Sinopec)
-
Shell
-
Reliance Industries Limited
-
NIPPON SHOKUBAI CO., LTD.
-
LOTTE Chemical Corporation.
-
LyondellBasell Industries Holdings B.V.
-
Indorama Ventures Public Company Limited
Recent Developments
- In May 2024, LyondellBasell completed the divestiture of its Ethylene Oxide & Derivatives (EO&D) business to INEOS Oxide. The transaction included the Bayport, Texas production facility, which manufactures high-purity ethylene oxide and downstream derivatives, including ethylene glycols.
Ethylene Glycols Market Report Scope
Report Attribute
Details
Market size in 2025
USD 19.5 billion
Estimated market size in 2026
USD 20.5 billion
Projected market size by 2033
USD 29.4 billion
Growth rate
CAGR of 5.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Volume and revenue forecast, company ranking, competitive landscape, growth factors, and trends
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Derivative type, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; Japan; India; South Korea; Brazil; Argentina; South Africa; Saudi Arabia
Key companies profiled
Exxon Mobil Corporation; Dow; SABIC; China Petrochemical Corporation (Sinopec); Shell; Reliance Industries Limited; NIPPON SHOKUBAI CO., LTD.; LOTTE Chemical Corporation.; LyondellBasell Industries Holdings B.V.; Indorama Ventures Public Company Limited.
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Ethylene Glycols Market Segmentation
This report forecasts revenue growth at regional and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global ethylene glycols market based on derivative type, application, end use, and region.
-
Derivative Type Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Monoethylene Glycol (MEG)
-
Diethylene Glycol (DEG)
-
Triethylene Glycol (TEG)
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Polyester Fibers
-
PET
-
Antifreeze and Coolants
-
Films
-
Others
-
-
End Use Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Textile
-
Automotive
-
Packaging
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
-
Frequently Asked Questions About This Report
The global ethylene glycols market size was valued at USD 19.5 billion in 2025 and is estimated at USD 20.5 billion for 2026
The global ethylene glycols market is expected to grow at a CAGR of 5.3% from 2026 to 2033, reaching USD 29.4 billion.
North America dominated with an approximately 40.0% revenue share in 2025.
⮚ Key players in the market include Exxon Mobil Corporation, Dow, SABIC, China Petrochemical Corporation (Sinopec), Shell, Reliance Industries Limited, NIPPON SHOKUBAI CO., LTD., LOTTE Chemical Corporation, LyondellBasell Industries Holdings B.V., Indorama Ventures Public Company Limited, and others.
The Triethylene Glycol (TEG) derivative segment accounted for the largest revenue share of approximately 41.0% in 2025
About the Author(s)
Petrochemicals Research Team
Bulk Chemicals · PetrochemicalsThis report was authored by the petrochemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the petrochemicals segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


