
- Home
- »
- Pharmaceuticals
- »
-
Europe Medical Foods Market Size And Share Report, 2033GVR Report cover

Europe Medical Foods Market (2026 - 2033)
Size, Share & Trends Analysis Report By Route Of Administration (Oral, Enteral), By Product (Pills, Liquid), By Application, By Modules, By Sales Channel, By Country, And Segment Forecasts
Market Size, 2025
$6.3BMarket Estimate, 2026
$6.5BMarket Forecast, 2033
$7.9BCAGR, 2026–2033
2.8%Europe Medical Foods Market Summary
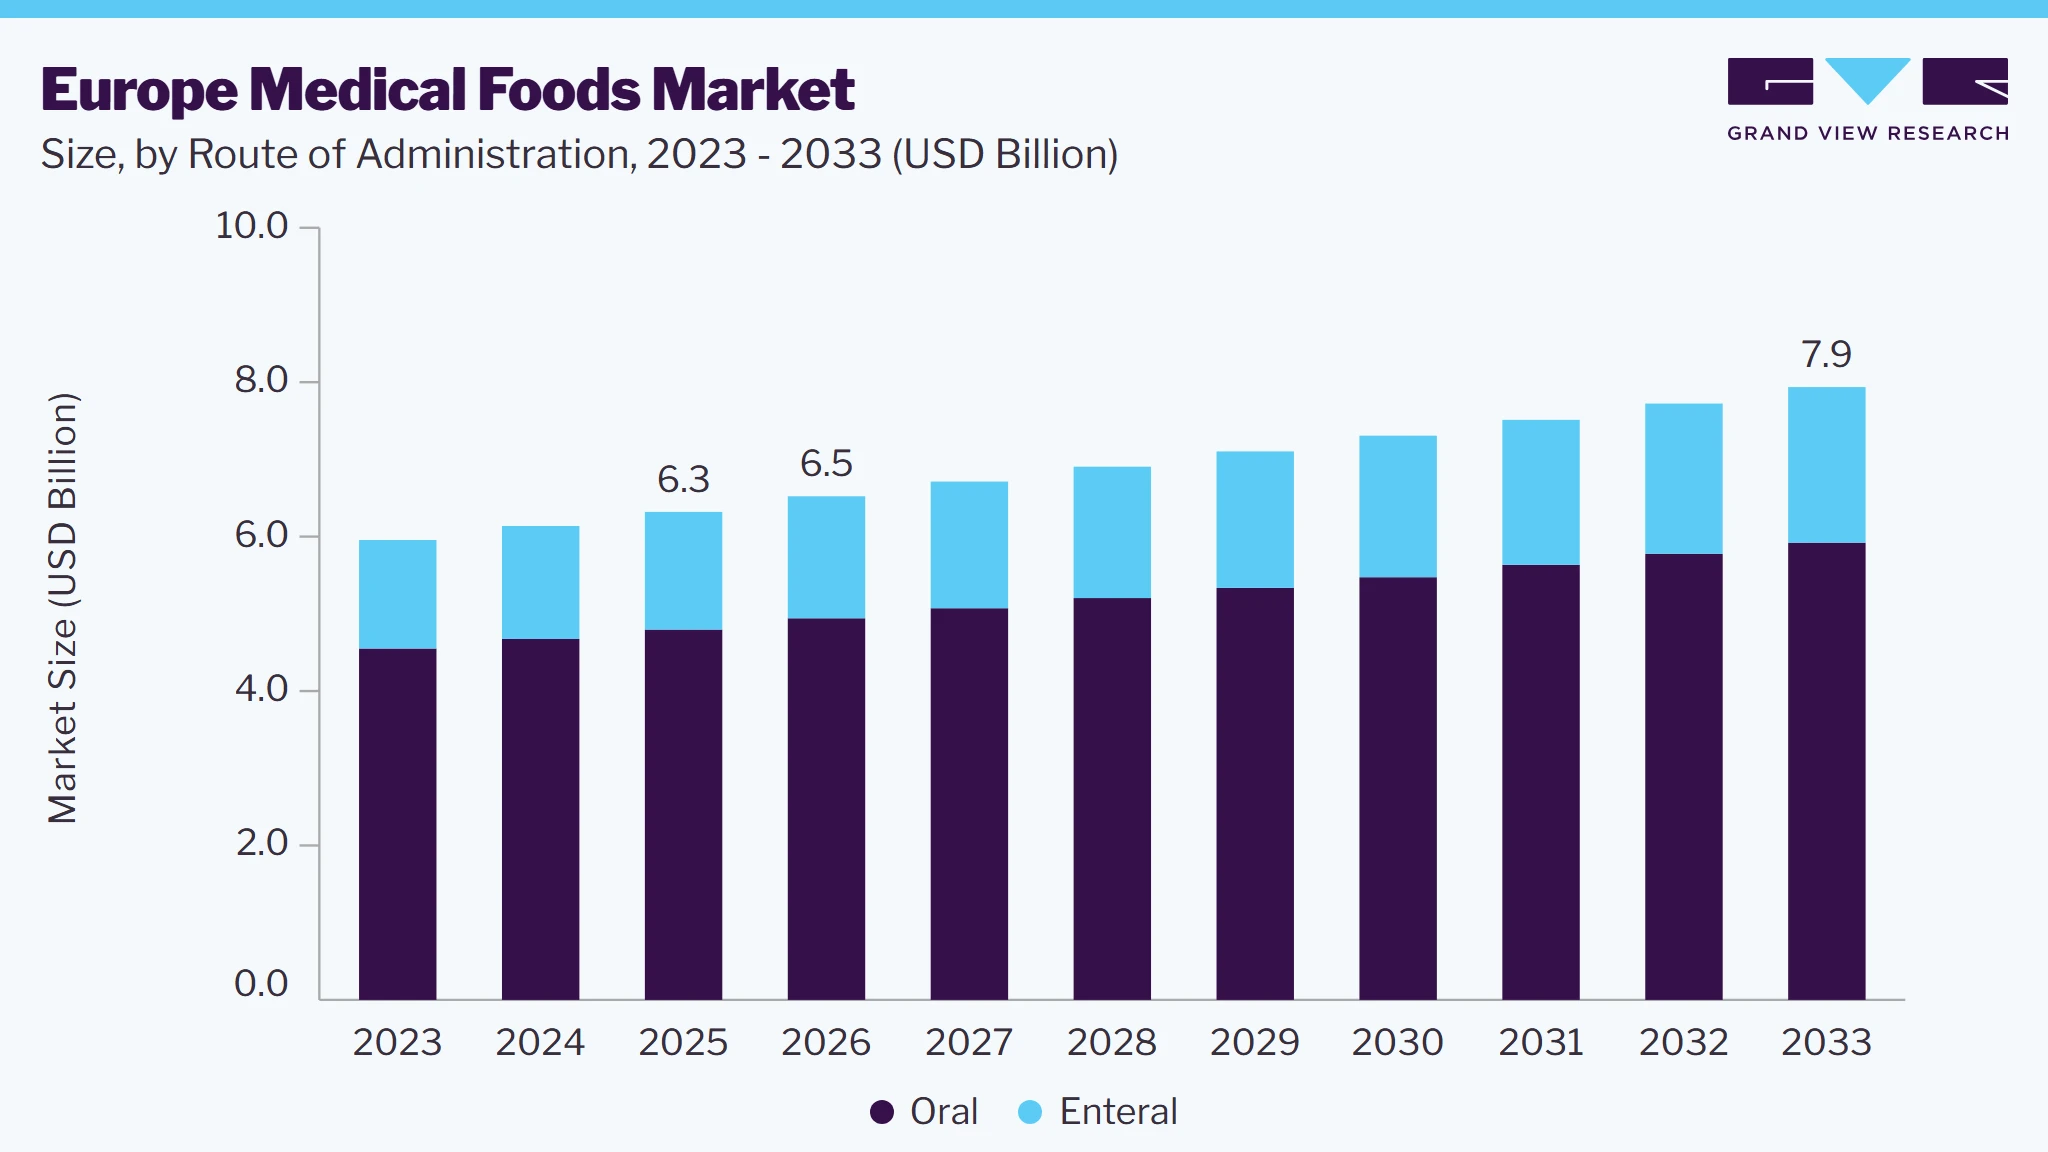
The Europe medical foods market size was valued at USD 6.3 billion in 2025 and is projected to grow from USD 6.5 billion in 2026 to USD 7.9 billion by 2033, growing at a CAGR of 2.8% from 2026 to 2033. The growth is attributed to Europe’s large and aging population, which is increasingly susceptible to chronic and age-related conditions, including cardiovascular and respiratory diseases, thereby driving demand for specialized nutritional solutions and medical foods to support disease management and improve overall health outcomes.
Key Market Trends & Insights
- By route of administration: Oral segment held the largest market share of 75.9% in 2025.
- By product: Powder segment accounted for the largest market revenue share of 35.3% in 2025.
- By application: Cancer segment dominated the market with the largest share of 12.0% in 2025.
Market Size & Forecast
- Market size in 2025: USD 6.3 Billion
- Estimated market size in 2026: USD 6.5 Billion
- Projected market size by 2033: USD 7.9 Billion
- CAGR (2026-2033): 2.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Market Dynamics
The market is expected to witness gradual growth, driven by the increasing prevalence of chronic and age-related diseases, rising demand for specialized nutritional products, and growing awareness of disease-specific nutrition. Improvements in healthcare infrastructure, the expansion of long-term care services, and advancements in medical food formulations are further supporting market development. In addition, the growing focus on nutritional management and supportive care is expected to drive market expansion over the forecast period.
The rising incidence of chronic diseases, including cardiovascular, respiratory, metabolic, and gastrointestinal disorders, is a key driver of demand for medical foods in Europe. These conditions are frequently associated with nutritional deficiencies, impaired nutrient absorption, increased metabolic requirements, or disease-specific dietary restrictions, creating a growing need for specialized nutritional interventions. However, the increasing adoption of medical foods to support disease management, maintain nutritional status, facilitate recovery, and improve patient outcomes is driving market growth across hospitals, long-term care facilities, and home care settings.
Moreover, the increasing focus of European healthcare systems on chronic disease prevention, early diagnosis, and long-term disease management is creating favorable opportunities for medical food manufacturers. For instance, in December 2025, the European Commission introduced the Safe Hearts Plan, the EU’s first comprehensive initiative focused on cardiovascular disease prevention and management, emphasizing prevention, early detection, treatment, and personalized care. Such initiatives are expected to strengthen the integration of nutritional support into broader chronic disease management strategies, thereby supporting demand for specialized medical foods across Europe.
The general lack of awareness and understanding of medical foods within the medical community is limiting their adoption. Medical foods require a prescription and supervision by medical professionals. Although these products are gaining acceptance, they remain poorly understood by patients, physicians, and pharmacists. This factor prevents doctors from adopting or prescribing medical foods, which may restrain market growth. Furthermore, not all medical experts are convinced that medical foods assist in chronic disease management. Thus, the lack of awareness among medical professionals and patients is expected to impede market growth.
As the prevalence of chronic and metabolic diseases continues to increase, demand is growing for medical foods formulated to address specific nutritional requirements associated with conditions such as neurological disorders, gastrointestinal diseases, and inherited metabolic disorders. These products provide targeted nutritional formulations designed to support the dietary management of patients whose nutritional requirements cannot be adequately met through a conventional diet. For instance, Abbott Nutrition offers KetoCal, a ketogenic medical food formulated for individuals following a ketogenic diet for the dietary management of drug-resistant epilepsy. Similarly, the availability of specialized medical foods for conditions such as phenylketonuria (PKU), Crohn’s disease, and other gastrointestinal and metabolic disorders is expanding, creating opportunities for manufacturers to develop condition-specific nutritional solutions.
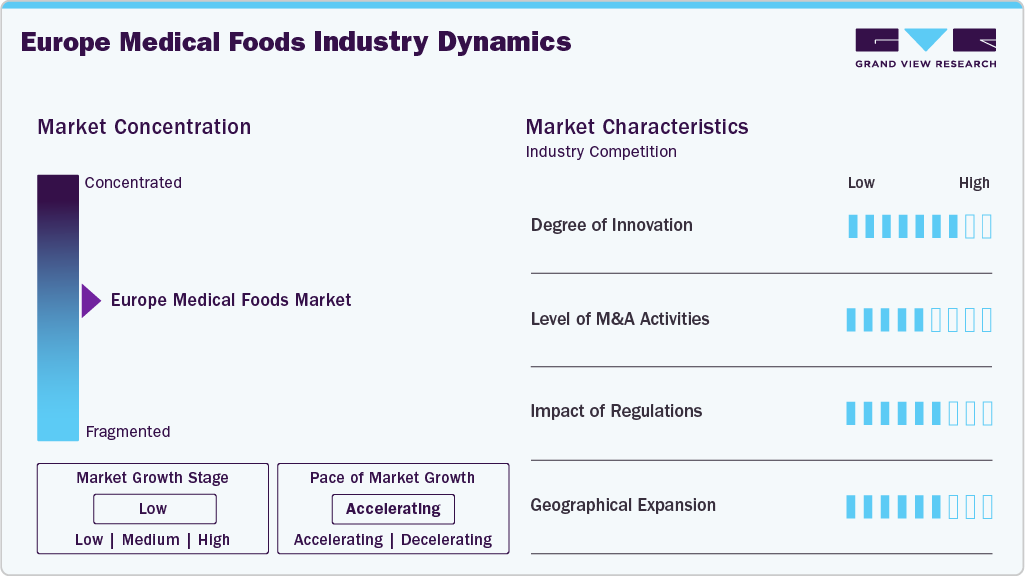
Market Characteristics
The degree of innovation in the Europe medical foods industry is high. Leading manufacturers are focusing on expanding the product's application scope and targeting different population cohorts to gain large market shares. For instance, in March 2023, RELIEF THERAPEUTICS Holding SA launched its latest PKU GOLIKE BARs across Europe. These bars, designed for the dietary management of phenylketonuria (PKU), are part of the PKU GOLIKE product line, which utilizes the company's proprietary Physiomimic Technology. This technology enables a prolonged-release formulation of amino acids, providing next-generation medical foods to improve PKU management by offering sustained nutritional support.
M&A activities, including acquisitions, mergers, and strategic partnerships, enable companies to strengthen their medical nutrition portfolios, expand market presence, and enhance product capabilities. For instance, in March 2026, Nestlé introduced Complete Pediatric Oral Blends in select European markets, expanding its specialized medical nutrition portfolio with an oral nutritional solution designed for children with special medical nutrition needs. The launch strengthened Nestlé Health Science's presence in pediatric medical nutrition and supported its strategy of expanding medical nutrition offerings across Europe.
 To learn more about this report, Download Free Sample Report
The Europe medical foods industry is influenced by stringent regulatory requirements governing the composition, safety, labeling, and commercialization of Food for Special Medical Purposes (FSMP). Regulation (EU) No. 609/2013 and Commission Delegated Regulation (EU) 2016/128 establish specific requirements for FSMP, ensuring product quality and consumer safety while increasing compliance requirements for manufacturers.
Geographic expansion drives the Europe medical foods industry by enabling access to diverse resources, increasing market penetration and revenue, and fostering regulatory compliance and standardization. For instance, in September 2023, Danone announced a USD 51.22 million (EUR 50 million) investment to expand its existing plant in Opole, Poland, to produce medical nutrition products. This facility would cater to individuals with special dietary needs. The expansion follows Danone's acquisition of the Polish medical nutrition company Promedica earlier in the year, marking a strategic move to strengthen its position in the medical nutrition sector.
Analyst Perspective
The market is expected to witness gradual growth, driven by the rising prevalence of chronic and metabolic disorders, an aging population, and increasing awareness of specialized nutritional interventions. Growing demand for disease-specific nutrition, particularly for malnutrition, diabetes, gastrointestinal disorders, and neurological conditions, is supporting market expansion across the region. In addition, favorable healthcare infrastructure, increasing adoption of clinical nutrition, and advancements in product formulations are expected to create new growth opportunities. Market participants are focusing on product innovation, clinical validation, and strategic partnerships to strengthen their presence and address evolving nutritional needs.
Route of Administration Insights
The oral segment led the market, accounting for 75.9% of total revenue in 2025. Increased preference for oral products, commercial viability, and supportive initiatives are key factors driving demand for orally administered medical foods. Moreover, the growing manufacturing of oral products in the form of prethickened products, powders, and pills is anticipated to fuel the segment. For instance, in January 2023, Nutricia launched its Fortimel Plant-Based Energy, a plant-based oral nutritional supplement designed to meet the nutritional needs of individuals with malnutrition or at risk due to illness. This addition to the Fortimel portfolio leverages Nutricia's parent company, Danone's proficiency in plant nutrition. It further expands the range of Fortimel products, which are clinically proven medical nutrition solutions designed to meet patients' daily needs.
The enteral route of administration segment is expected to witness the fastest growth over the forecast period. The demand for enteral feeding formulas is increasing due to the rising prevalence of chronic diseases, such as cancer and cardiovascular diseases, which may lead to metabolic complications and difficulty in consuming food during treatment. In critically ill patients, enteral nutrition plays an important role in preventing undernutrition and loss of lean body mass, particularly during catabolic states associated with systemic inflammation. The growing adoption of enteral nutrition in critical care settings and increasing awareness of its clinical benefits are expected to support market segment growth.
Product Insights
The powder segment accounted for the largest market revenue share of 35.3% in 2025. Medical foods are mostly available in powder form and can be administered orally or enterally by mixing with milk or water, as advised by the physician. Medical foods in powdered form are suitable for patients of all ages, especially for oral administration. Owing to a strong preference for powdered formulations for their ease of consumption, manufacturers are developing product categories aligned with consumer preferences.
Liquid is anticipated to grow at the fastest rate during the forecast period, owing to the rising adoption of liquid formulations in the pediatric and geriatric populations, where intake of solid formulations is limited or impossible, and in cases of clinically diagnosed dysphagia or when oral physiology is limited. Moreover, liquid-formulated food helps maintain sufficient hydration and electrolyte balance, favoring segment growth. For instance, in October 2023, Nutricia launched its medical nutrition beverage, Fortini + Mix Multi Fibre. The product features a well-balanced combination of fruit and vegetable ingredients, specifically designed to address the dietary needs of pediatric patients dealing with disease-related malnutrition and stunted growth.
Application Insights
The cancer segment dominated the market with the largest share of 12.0% in 2025, driven by the rising prevalence of cancer and the high risk of disease-related malnutrition among patients undergoing cancer treatment. The increasing adoption of specialized nutritional products to support nutritional status, manage treatment-related side effects, and improve patient recovery has further contributed to segment growth.
The Parkinson's Disease (PD) segment is expected to grow at the fastest CAGR during the forecast period, driven by the rising prevalence of neurodegenerative disorders and increasing demand for specialized nutritional support. Medical foods containing omega-3 fatty acids, coenzyme Q, and vitamins D and B, along with ketogenic diets and probiotics, are increasingly being explored to support nutritional management and complement pharmacological treatment, thereby driving segment growth.
Modules Insights
The protein module segment dominated the market with the largest revenue share of 12.8% in 2025. Protein modules are used in severe infections, trauma, burns, malnutrition, post-surgery recovery, and critically ill patients. The increasing prevalence of chronic diseases, such as cancer, chronic kidney disease, and malnutrition, which require specialized nutritional interventions, likely drives the segment growth. Patients undergoing treatments like chemotherapy or dialysis often suffer from muscle wasting and protein deficiencies, boosting demand for protein-enriched medical foods. In addition, the aging population, particularly in developed countries, further contributes to the need for protein modules to combat age-related muscle loss (sarcopenia).
The hypoallergenic modules segment is anticipated to grow at the fastest CAGR during the forecast period. The growth is driven by the increasing prevalence of food allergies and intolerances, especially among infants and individuals with chronic health conditions. Hypoallergenic medical foods cater to patients with specific dietary needs, such as those unable to tolerate proteins found in common foods like cow's milk or soy. These products are formulated to minimize allergic responses and are crucial for managing conditions such as severe food allergies, eosinophilic esophagitis, and gastrointestinal disorders. The rising awareness of food-related health issues and advancements in hypoallergenic formulations, such as amino acid-based or extensively hydrolyzed proteins, are expected to further support segment expansion over the forecast period.
Sales Channel Insights
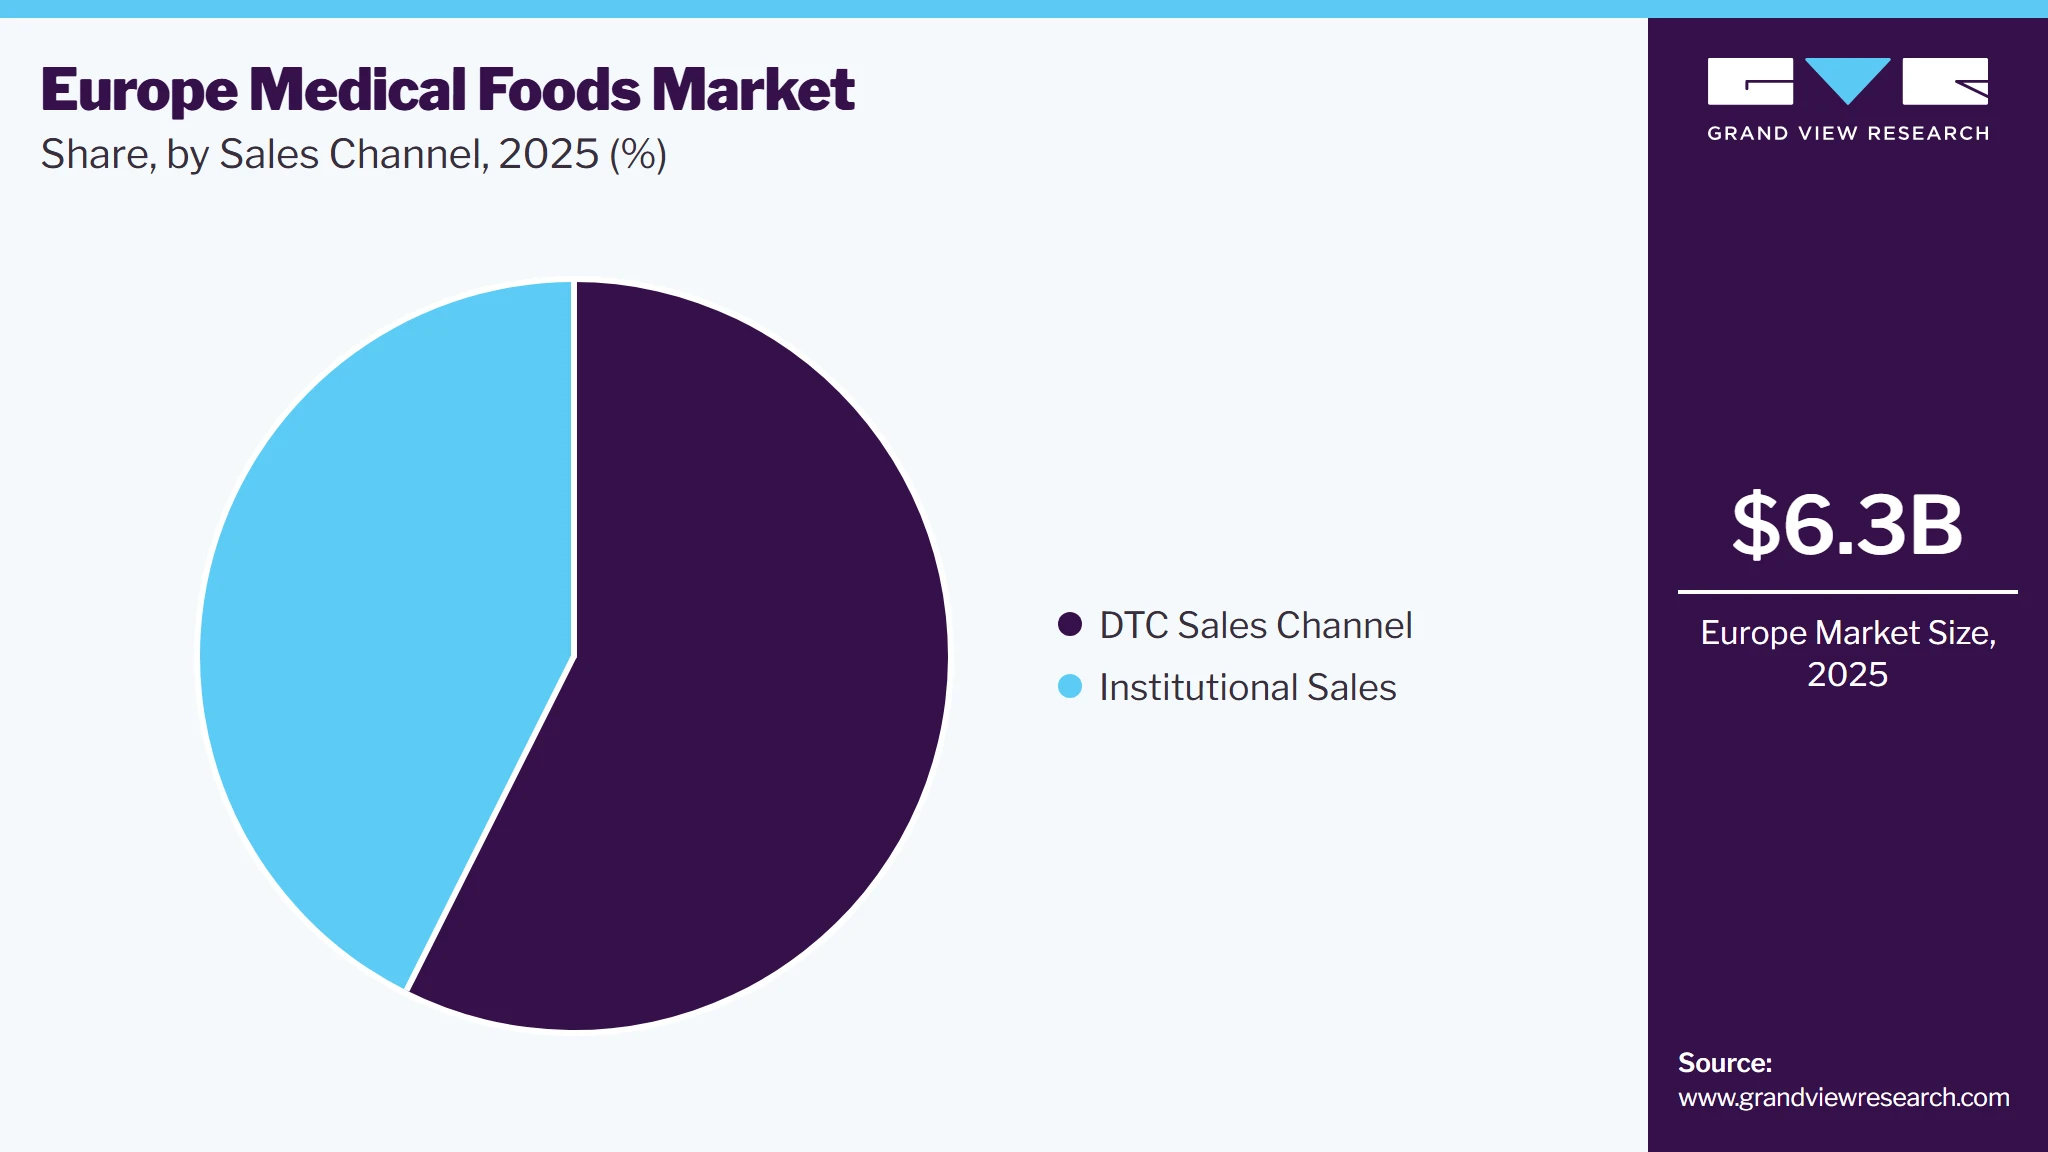
Direct-to-consumer (DTC) sales channel held the largest market share of 57.4% in 2025 and is expected to grow at the fastest CAGR during the forecast period. DTC sales have emerged as a significant channel in the market, providing manufacturers with opportunities to engage directly with consumers and tailor their offerings to specific health needs. DTC sales in the medical foods sector enable companies to bypass traditional retail channels and establish direct relationships with end users. This model has gained traction for its ability to deliver personalized customer experiences and strengthen brand loyalty. By leveraging online platforms, companies can offer detailed product information, educational resources, and tailored recommendations based on individual health conditions.
 To learn more about this report, Download Free Sample Report
Institutional sales is anticipated to grow significantly over the forecast period. The segment's growth is driven by increasing recommendations from doctors to use medical foods. Institutions that purchase medical foods include hospitals, long-term care centers, hospices, clinics, and disability facilities. Since consumption of medical foods is recommended under medical supervision, revenue from institutional sales is highest. In addition, training programs for healthcare professionals on the benefits of medical foods further enhance their adoption within institutions. As awareness among clinicians grows of the efficacy of these products in improving patient outcomes, institutional sales are expected to grow significantly.
Country Insights
UK Medical Foods Market Trends
The medical foods market in UK held a substantial share in 2025, driven by the growing geriatric population and rising risk of malnutrition among elderly individuals. For instance, in July 2025, the UK Government introduced the Good Food Cycle, emphasizing improved nutrition and healthier food systems, which is expected to support greater awareness of nutritional interventions and contribute to demand for medical foods in the UK.
Germany Medical Foods Market Trends
The medical foods market in Germany is positively influenced by the rising cancer burden and the growing need for radiotherapy and supportive nutritional care. According to the ESTRO-HERO analysis article, the number of radiotherapy treatment courses across Europe was projected to increase by approximately 16% between 2012 and 2025, with considerable variation across countries. The anticipated rise in cancer treatment requirements is expected to increase the demand for specialized nutritional support among patients undergoing intensive cancer therapies, thereby supporting the adoption of medical foods in Germany.
France Medical Foods Market Trends
The medical foods market in France is supported by the country's aging population and increasing burden of chronic diseases, which are contributing to greater demand for specialized nutritional support. According to an article published by Le Monde in March 2023, around 26% of France's population was aged over 60, representing approximately one in four inhabitants. This demographic trend, coupled with the growing nutritional needs of older adults and patients with chronic conditions, is expected to support the adoption of medical foods in France.
Key Europe Medical Foods Company Insights
Some of the key players operating in the market include Danone, Nestlé, Abbott, Fresenius Kabi AG, Targeted Medical Pharma, Inc. (Physician Therapeutics, LLC, is a division of the company), Primus Pharmaceuticals, Inc., and Mead Johnson & Company, LLC. Key players are focusing on product launches, portfolio expansion, and strategic initiatives to strengthen their market presence. Companies such as Danone, Nestlé, Abbott, and Fresenius Kabi offer specialized medical nutrition products that address diverse nutritional needs associated with chronic diseases, malnutrition, aging, and pediatric conditions, while other players focus on targeted nutritional solutions to meet specific medical requirements across European markets.
Key Europe Medical Foods Companies
-
Danone
-
Nestlé
-
Abbott
-
Targeted Medical Pharma, Inc. (Physician Therapeutics, LLC, is a division of the company)
-
Primus Pharmaceuticals, Inc.
-
Fresenius Kabi AG
-
Mead Johnson & Company, LLC
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Danone, Nestlé, Abbott, Fresenius Kabi AG, etc.)
Focus on expanding specialized medical nutrition portfolios across disease-specific, pediatric, and clinical nutrition applications, supported by strong healthcare professional engagement.
Strong brand recognition, extensive product portfolios, and established distribution networks across European markets.
High competition and stringent European regulatory requirements for medical food formulations and health claims.
Emerging Players (Targeted Medical Pharma, Inc. and Primus Pharmaceuticals, Inc.
Focus on specialized, condition-specific medical nutrition products targeting underserved patient populations and niche therapeutic applications.
Greater flexibility in product development and targeted market positioning compared with larger diversified nutrition companies.
Higher dependence on specialized product segments and healthcare professional adoption is limiting broader market penetration.
Recent Developments:
-
In March 2026, Nestlé launched Complete Pediatric Oral Blends in select European markets, providing specialized oral nutritional support for children with medical nutrition needs and expanding its pediatric medical nutrition portfolio.
-
In November 2025, Danone announced a €70 million investment in its Steenvoorde, France, production facility, including a dedicated medical nutrition line. The expansion strengthened the company’s European manufacturing capabilities and increased production capacity for specialized medical nutrition products to meet growing regional demand.
-
In November 2023, Danone launched its first medical nutrition product, Fortimel, for adults in China, which is categorized as a food for special medical purposes. This launch is a crucial component of Danone's strategy in China, aimed at leveraging its scientific expertise across all life stages and driving growth in the adult medical nutrition segment.
-
In September 2023, Danone announced a EUR 50 million (USD 53.78 million) expansion of its production facility in Opole, Poland, to meet increasing demand for medical nutrition worldwide. This move aims to enhance its position in the adult medical nutrition market, with the growing rate of chronic diseases and an aging population. The expansion is anticipated to enable Danone to serve patients across the globe, as many people are expected to require medical nutrition at some point in their lives due to diseases such as cancer and stroke, which can result in malnutrition.
-
In April 2023, Danone acquired ProMedica, a Poland-based company specializing in home care services. This acquisition is part of Danone's strategy to expand in the lucrative specialized nutrition market and strengthen its presence in Poland.
-
In February 2023, Neslte and EraCal Therapeutics entered into a research collaboration to control food intake.
Europe Medical Foods Market Report Scope Table
Report Attribute
Details
Market size in 2025
USD 6.3 billion
Market size value in 2026
USD 6.5 billion
Revenue forecast in 2033
USD 7.9 billion
Growth rate
CAGR of 2.8% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Route of administration, product, application, modules, sales channel, country
Country scope
UK; Germany; Spain; France; Italy; Denmark; Sweden; Norway; Poland; Netherlands; Portugal; Slovakia; Finland; Czech Republic; Hungary; Belgium
Key companies profiled
Danone; Nestlé; Abbott; Targeted Medical Pharma, Inc. (Physician Therapeutics, LLC, is a division of the company); Primus Pharmaceuticals, Inc.; Fresenius Kabi AG; Mead Johnson & Company, LLC
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Europe Medical Foods Market Report Segmentation
This report forecasts revenue growth at country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the Europe medical foods market report based on route of administration, product, application, modules, sales channel, and region.
-
Route of Administration Outlook (Revenue, USD Billion, 2021 - 2033)
-
Oral
-
Enteral
-
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Pills
-
Powder
-
Liquid
-
Others (semisolid, semiliquid)
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Chronic Kidney Disease
-
Minimal Hepatic Encephalopathy
-
Chemotherapy Induced Diarrhoea
-
Pathogen Related Infections
-
Diabetic Neuropathy
-
ADHD
-
Depression
-
Alzheimer's Disease
-
Nutritional Deficiency
-
Orphan Diseases
-
Tyrosinemia
-
Eosinophilic Esophagitis
-
Food Protein Module-induced enterocolitis syndrome (FPIES)
-
Phenylketonuria (PKU)
-
Maple syrup urine disease (MSUD)
-
Homocystinuria
-
Others (Urea Cycle Disorder (UCD), Glycogen Storage Disease (GSD), etc.)
-
-
Wound Healing
-
Chronic Diarrhea
-
Constipation Relief
-
Protein Booster
-
Dysphagia
-
Pain Management
-
Parkinson's Disease
-
Epilepsy
-
Other Cancer related treatments
-
Severe Protein Allergy
-
Cancer
-
Cachexia
-
Other (debilitating conditions, COPD, etc.)
-
-
Modules Outlook (Revenue, USD Billion, 2021 - 2033)
-
Amino Acid Module
-
Protein Module
-
Vitamin & Mineral Modules
-
Fatty Acid based Modules
-
Carbohydrate Modules
-
Fiber Modules
-
Ketogenic Modules
-
Peptide based Modules
-
Hypoallergic Modules
-
Others (Electrolyte Module, etc.)
-
-
Sales Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
DTC Sales Channel
-
Online Sales
-
Retail Sales
-
-
Institutional Sales
-
Hospitals
-
Others (Long-term Care Facilities, etc.)
-
-
-
Country Outlook (Revenue, USD Billion, 2021 - 2033)
-
UK
-
Germany
-
Spain
-
France
-
Italy
-
Denmark
-
Sweden
-
Norway
-
Poland
-
Netherlands
-
Portugal
-
Slovakia
-
Finland
-
Czech Republic
-
Hungary
-
Belgium
-
Research Methodology
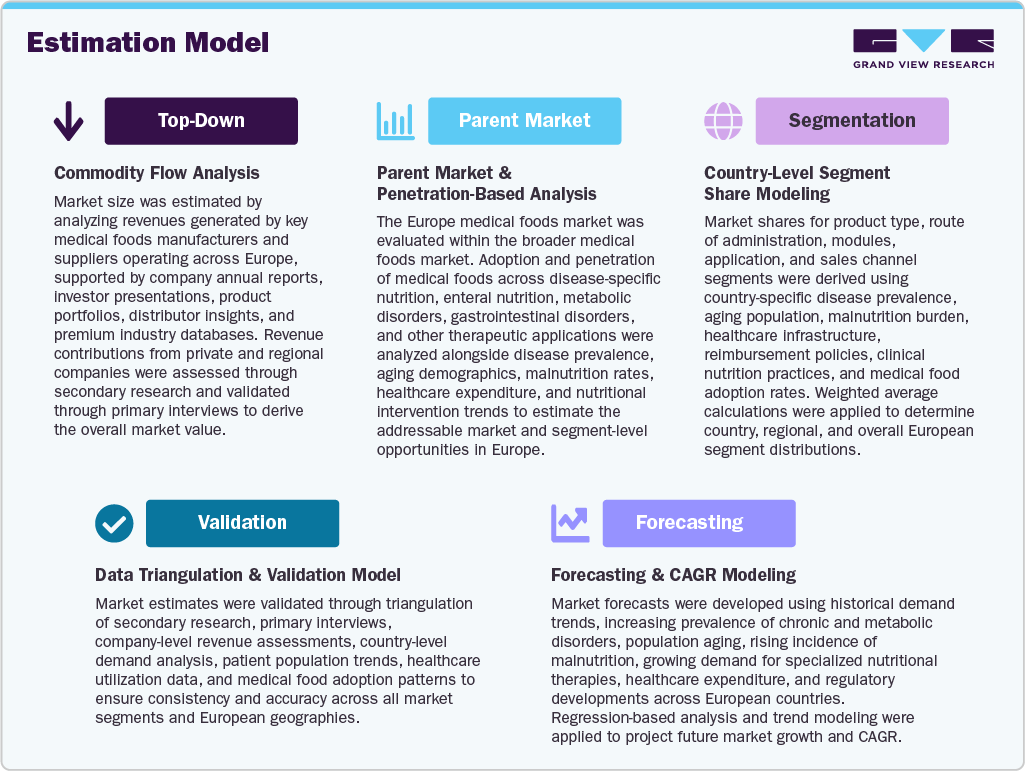
The medical foods market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing—reconciling supply-side and demand-side estimates—and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each medical foods segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment-Route of Administration
Revenue Capture Definition
Oral
Revenue generated from medical food products administered orally and consumed directly by patients to provide specialized nutritional support for managing disease-specific dietary requirements. This route includes formulations delivered in various product forms, such as pills, powders, liquids, and other oral formats, for individuals capable of consuming medical nutrition by mouth.
Enteral
This segment captures income from medical foods delivered through enteral feeding methods to patients who are unable to meet their nutritional requirements through regular oral intake. Products are administered through feeding tubes and support individuals with severe dysphagia, neurological disorders, chronic diseases, and other conditions requiring specialized nutritional intervention.
Segment- Product
Revenue Capture Definition
Pills
Revenue derived from medical food products formulated in pill-based formats to provide concentrated nutrients and disease-specific nutritional components. These products offer convenient administration and are utilized for managing specialized nutritional requirements associated with various medical conditions.
Powder
This segment represents income from powdered medical food formulations that are typically mixed with water, beverages, or other suitable foods before consumption or administration. These products enable flexible dosing and customized nutritional supplementation across clinical and home-care settings.
Liquid
Market value in this category stems from ready-to-use or concentrated liquid medical foods designed to provide complete or supplemental nutrition. These formulations are particularly suitable for patients experiencing swallowing difficulties or requiring easily consumable nutritional support.
Others (semisolid, semiliquid)
Includes revenue from alternative medical food formats, including semisolid and semiliquid formulations, developed to facilitate nutritional intake among patients with specific dietary, swallowing, or disease-related requirements.
Segment- Application
Revenue Capture Definition
Chronic Kidney Disease
Revenue generated from medical foods formulated to address the specialized nutritional requirements of individuals with chronic kidney disease. These products help manage nutrient intake and support dietary interventions involving proteins, electrolytes, minerals, and other nutrients under medical supervision.
Minimal Hepatic Encephalopathy
This segment captures income from disease-specific medical foods designed to provide nutritional support for patients with minimal hepatic encephalopathy by addressing altered nutritional requirements associated with impaired liver function.
Chemotherapy Induced Diarrhoea
Market value arises from medical food products intended to provide nutritional support and help manage dietary requirements among cancer patients experiencing diarrhea associated with chemotherapy treatment.
Pathogen Related Infections
Revenue originates from specialized medical foods used to support nutritional requirements during pathogen-related infections, helping maintain nutritional status and support recovery in affected patients.
Diabetic Neuropathy
This segment reflects earnings from medical foods designed to provide specialized nutritional support for individuals experiencing diabetic neuropathy, with formulations intended to complement dietary management and address specific nutritional needs.
ADHD
Revenue generated from medical food products formulated to support the nutritional requirements of individuals with attention-deficit/hyperactivity disorder (ADHD), particularly where specific dietary interventions are recommended as part of clinical management.
Depression
This category captures income from specialized medical foods intended to address nutritional requirements associated with depression and support dietary management under healthcare professional supervision.
Alzheimer's Disease
Market value in this segment stems from medical foods formulated to provide nutritional support for individuals with Alzheimer's disease, including products designed to address disease-associated nutritional challenges and maintain adequate nutrient intake.
Nutritional Deficiency
Revenue derived from medical foods developed to address specific nutrient deficiencies arising from inadequate intake, impaired absorption, metabolic disorders, or increased nutritional requirements.
Orphan Diseases
Revenue generated from specialized medical foods developed to address the unique nutritional requirements associated with rare and orphan diseases. These products provide disease-specific nutritional support for patients with inherited metabolic disorders and other rare conditions requiring specialized dietary management, including disorders involving amino acid, protein, and metabolic pathways.
Wound Healing
This segment encompasses income from specialized medical foods containing nutrients that support tissue repair, collagen formation, immune function, and recovery in patients with wounds or compromised healing capacity.
Chronic Diarrhea
Revenue generated from medical food products designed to provide nutritional support for individuals experiencing persistent diarrhea, helping address nutrient losses and support dietary management.
Constipation Relief
This category reflects earnings from medical foods formulated to support bowel regularity and dietary management in individuals experiencing constipation through specialized nutritional components.
Protein Booster
Market value stems from protein-enriched medical foods intended to supplement dietary protein intake among individuals with increased protein requirements or inadequate protein consumption due to disease or nutritional challenges.
Dysphagia
Revenue originates from medical foods developed for individuals with swallowing difficulties, providing appropriately formulated nutritional support through products that facilitate safer and more manageable intake.
Pain Management
This segment captures income from specialized medical foods used as part of nutritional management strategies for individuals experiencing chronic or disease-associated pain.
Parkinson's Disease
Revenue generated from medical foods formulated to support nutritional management among individuals with Parkinson's disease, addressing specific dietary requirements that may arise from disease progression and treatment.
Epilepsy
This category includes income from medical foods designed to support specialized dietary interventions for epilepsy, including nutritional formulations associated with ketogenic and other medically supervised dietary approaches.
Other Cancer Related Treatments
This segment reflects revenue from medical foods used alongside cancer-related treatments to address nutritional challenges, support dietary requirements, and help maintain nutritional status during treatment and recovery.
Severe Protein Allergy
Market value arises from specialized medical foods formulated for individuals with severe protein allergies, providing nutritionally adequate alternatives while limiting exposure to specific allergenic proteins.
Cancer
Revenue derived from medical foods developed to address the nutritional needs of cancer patients, including products intended to support nutritional status, manage disease-related malnutrition, and complement clinical care.
Cachexia
This segment captures income from medical foods designed to provide nutritional intervention for patients experiencing cachexia, supporting energy and nutrient intake in conditions associated with severe weight and muscle loss.
Other (debilitating conditions, COPD, etc.)
Includes revenue from medical foods used for additional debilitating conditions and chronic disorders, including chronic obstructive pulmonary disease (COPD) and other medical conditions requiring specialized nutritional management.
Segment- Modules
Revenue Capture Definition
Amino Acid Module
Revenue generated from medical food formulations containing specific amino acids or amino acid combinations designed to meet disease-specific nutritional requirements and support metabolic management in patients with specialized dietary needs.
Protein Module
This segment captures income from protein-based medical food formulations developed to provide supplemental or complete protein nutrition for individuals with disease-related malnutrition, increased nutritional requirements, or impaired dietary intake.
Vitamin & Mineral Modules
Market value in this category stems from medical foods containing essential vitamins and minerals formulated to address nutritional deficiencies and support physiological functions in patients requiring specialized dietary intervention.
Fatty Acid Based Modules
Revenue originates from medical food formulations enriched with specific fatty acids, including essential and specialized lipid components, to support energy provision and disease-specific nutritional requirements.
Carbohydrate Modules
This segment reflects earnings from medical foods containing tailored carbohydrate sources designed to provide energy while addressing specific metabolic or dietary requirements associated with medical conditions.
Fiber Modules
Revenue derived from fiber-based medical food formulations intended to support digestive health, bowel regularity, and nutritional management in patients with specific gastrointestinal and metabolic requirements.
Ketogenic Modules
This category captures income from medical foods formulated around high-fat, low-carbohydrate nutritional profiles used primarily in medically supervised dietary interventions, particularly for epilepsy and selected metabolic conditions.
Peptide Based Modules
Market value stems from medical food products incorporating specialized peptides designed to provide easily utilized nutritional components and support targeted nutritional requirements in patients with specific medical conditions.
Hypoallergic Modules
Revenue generated from medical food formulations designed to minimize allergic reactions by utilizing extensively hydrolyzed, amino acid-based, or otherwise modified nutritional components for individuals with food allergies or intolerances.
Others (Electrolyte Module, etc.)
Includes revenue from medical food modules incorporating other specialized nutritional components, such as electrolytes and other disease-specific nutrients, developed to address specialized dietary requirements.
Segment- Sales Channel
Revenue Capture Definition
DTC Sales Channel
Revenue generated through direct-to-consumer channels that enable patients and caregivers to purchase medical food products without relying exclusively on institutional procurement pathways. This segment includes online sales platforms and retail sales outlets that provide access to specialized nutritional products for home-based use and ongoing dietary management.
Institutional Sales
This segment captures income from medical foods supplied through institutional healthcare channels, primarily hospitals and other care facilities such as long-term care institutions. Products distributed through these channels are used to support patients requiring medically supervised nutritional intervention and specialized dietary management.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Product-Level Pricing & Price Benchmarking
Detailed pricing analysis of individual medical food products across key European markets, covering manufacturer, product, application, formulation, pack size, dosage/form, and price per unit or serving.
Enables clients to benchmark competitive pricing, identify premium-priced products, assess country-level price variations, and identify pricing opportunities.
Medical Food Innovation & Emerging Trends Analysis
Assessment of emerging trends and innovations across Europe, including personalized medical nutrition, microbiome-focused nutrition, ketogenic medical foods, specialized formulations for aging and dysphagia, novel protein sources, precision nutrition, and innovative delivery formats.
Helps clients identify high-potential innovation areas, unmet nutritional needs, emerging product concepts, and future growth opportunities for product development and investment.
European Medical Food Conference & Industry Event Intelligence
Coverage of major European and international medical food, clinical nutrition, metabolic disease, oncology nutrition, gastrointestinal nutrition, and healthy aging conferences and exhibitions, including key themes, participating companies, product launches, presentations, and emerging technologies.
Provides visibility into industry direction, competitor activities, emerging technologies, product launches, and potential partnership and networking opportunities across the European medical food ecosystem.
Frequently Asked Questions About This Report
The powder segment accounted for the largest market revenue share of 35.3% in 2025.
The cancer segment dominated the market with the largest share of 12.0% in 2025.
The Europe medical foods market size was valued at USD 6.3 billion in 2025 and is estimated at USD 6.5 billion in 2026.
The Europe medical foods market is expected to grow at a compound annual growth rate of 2.8% from 2026 to 2033, to reach USD 7.9 billion by 2033.
Oral segment accounted for the largest market share of 75.9% of the total revenue in 2025. Increased preference for orally administered products, commercial viability, and supportive initiatives are key factors driving the demand for oral administered medical foods.
Some key players operating in the Europe medical foods market include Danone, Nestlé, Abbott, Targeted Medical Pharma Inc. (Physician Therapeutics LLC, a division of the company), Primus Pharmaceuticals Inc., Fresenius Kabi AG, Mead Johnson & Company, LLC
Key factors that are driving the Europe medical foods market growth include rise in the prevalence of chronic diseases, the rapidly growing geriatric population, and governmental authorities focusing on reducing malnutrition.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


