
- Home
- »
- Advanced Interior Materials
- »
-
Farm Tire Market Size, Share And Trends Report, 2033GVR Report cover

Farm Tire Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Bias, Radial), By Application (Tractors, Harvesters, Forestry, Irrigation, Implements, Sprayers), By Distribution (OEM, Aftermarket), By Region, And Segment Forecasts
Market Size, 2025
$8.9BMarket Estimate, 2026
$9.4BMarket Forecast, 2033
$14.4BCAGR, 2026–2033
6.4%Farm Tire Market Size & Trends
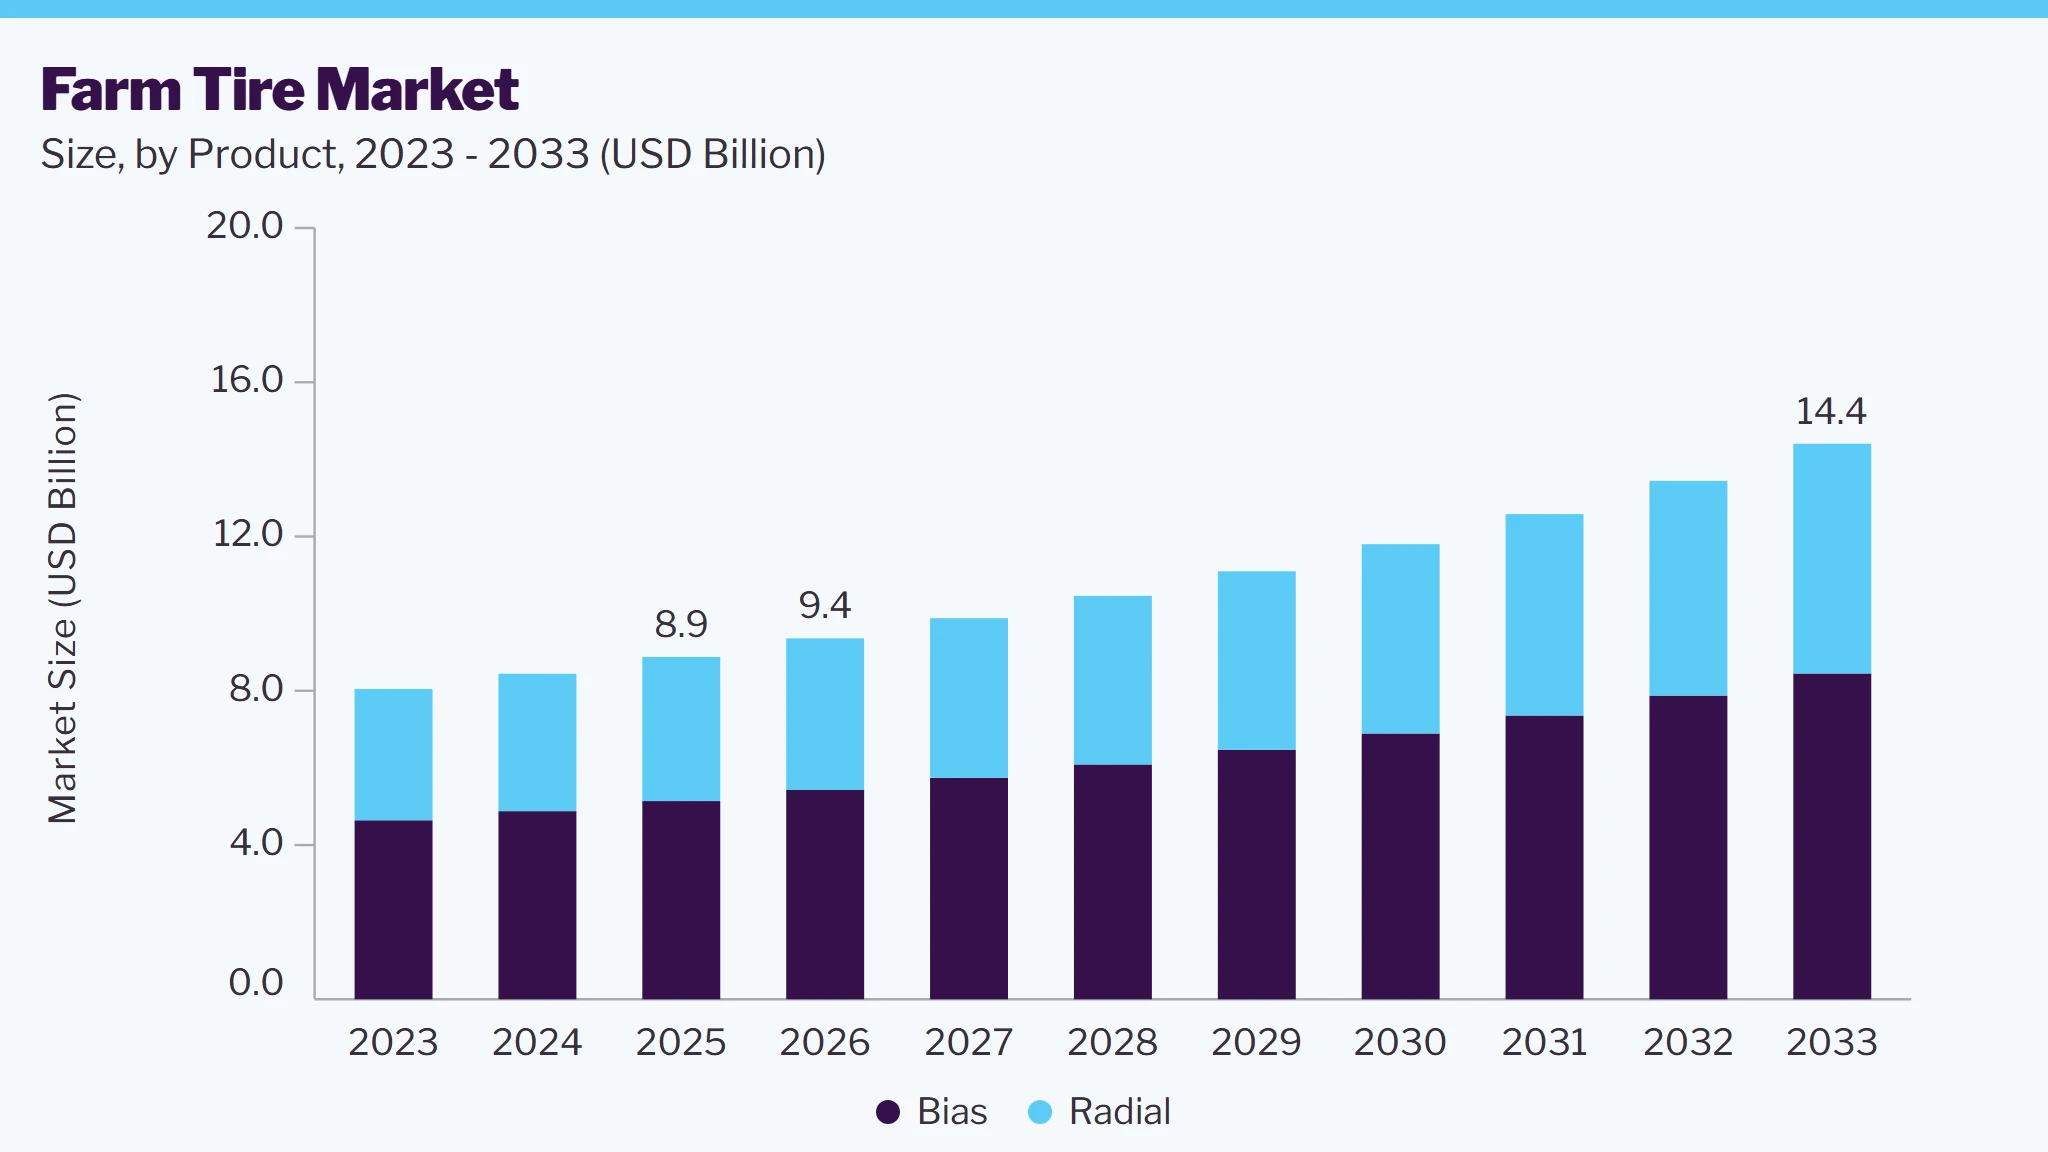
The global farm tire market size was value at USD 8.9 billion in 2025 and is projected to grow from USD 9.4 billion in 2026 to USD 14.4 billion by 2033, at a CAGR of 6.4% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 44.3% in 2025. The growing demand for farm tires in agricultural vehicles, coupled with the expansion of the agriculture sector, is projected to boost the market growth over the forecast period.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Bias segment led the market with the largest revenue share of 57.9% in 2025.
- By application: Tractors segment led the market with the largest revenue share of 44.6% in 2025.
- By distribution: Aftermarket segment led the market with the largest revenue share of 70.1% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (44.3% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 8.9 Billion
- Estimated market size in 2026: USD 9.4 Billion
- Projected market size by 2033: USD 14.4 Billion
- CAGR (2026-2033): 6.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Adoption of advanced technologies by farmers to increase the agricultural yield and meet the rising food demand is projected to be the key factor benefiting the farm tire market growth. In addition, the sales of tractors have witnessed substantial growth in the historic years on account of the rising demand for technological up-gradation, thereby having a positive impact on the farm tire market growthThe market in the U.S. is expected to witness high growth in the years to come on account of the presence of a number of manufacturing facilities. In addition, improvements in farming technologies and favorable policies are expected to aid the growth of the agriculture industry, thereby driving the demand for related products, including tires.
 To learn more about this report, Download Free Sample Report
Rapid urbanization, coupled with the increasing standards of living, has imposed high pressure on food production and productivity across the globe. The expansion of the agricultural sector in order to meet the rising demand for food products is anticipated to benefit the demand for agricultural vehicles, thereby fueling the demand for farm tire over the forecast period.
Increasing demand for products with superior properties, such as high puncture and wear and tear resistance, is likely to propel the production of quality products. In addition, the high production of farm tires, coupled with the rising consumption across the globe, is likely to propel the growth of the farm tire market.
Local players mostly focus on their specific strengths and retain their customers by providing custom services to tractor and harvester manufacturers. Companies in the industry also focus on increasing their production capacity as the demand for farm tires is growing in the agricultural industry on account of the increasing demand for agricultural produce.
Market Dynamics
The farm tire market is witnessing steady growth due to the increasing mechanization of agriculture, rising adoption of high-horsepower tractors and harvesting equipment, and growing demand for precision farming technologies. Farmers are investing in advanced tires that provide better traction, reduced soil compaction, improved fuel efficiency, and longer operational life. The expansion of commercial farming, government support for agricultural modernization, and replacement demand for worn-out tires are further supporting market growth. In addition, innovations in radial tire technology, IF/VF tires, and sustainable materials are enhancing the performance and durability of farm tires across diverse agricultural applications.
The increasing mechanization of farming activities is a major factor driving the farm tire market. Growing labor shortages, the need for higher productivity, and expanding commercial agriculture have encouraged farmers to adopt tractors, harvesters, sprayers, and other modern agricultural machinery. This has significantly increased the demand for durable farm tires capable of operating under heavy loads and varying field conditions. Radial farm tires, in particular, are gaining popularity due to their superior traction, fuel efficiency, and reduced soil disturbance.
Additionally, precision agriculture practices are creating demand for technologically advanced farm tires that enhance equipment stability and minimize crop damage. Manufacturers are introducing IF (Increased Flexion) and VF (Very High Flexion) tires that allow heavy machinery to operate with lower inflation pressures, improving field performance while protecting soil health. Growing investments in agricultural infrastructure and farm modernization programs across both developed and emerging economies continue to support long-term market expansion.
The high initial cost of advanced farm tires remains a key challenge for the market, particularly among small and medium-sized farmers with limited purchasing capacity. Premium radial and IF/VF tires require higher investments than conventional bias tires, which can delay replacement cycles or encourage the continued use of lower-cost alternatives. Furthermore, fluctuations in the prices of natural rubber, synthetic rubber, carbon black, steel, and other raw materials increase manufacturing costs and impact profit margins for tire manufacturers. These pricing uncertainties can also lead to higher product costs for end users, limiting market growth in price-sensitive agricultural regions.
The increasing focus on sustainable farming and digital agriculture presents significant opportunities for the farm tire market. Manufacturers are investing in eco-friendly tire materials, recyclable components, and energy-efficient production processes to meet evolving environmental regulations and customer expectations. At the same time, the integration of tire pressure monitoring systems, telematics, and sensor-based technologies is enabling predictive maintenance and improving operational efficiency for agricultural machinery. As precision farming expands globally, demand for intelligent, long-lasting, and soil-friendly farm tires is expected to create substantial growth opportunities for industry participants.
Market Concentration & Characteristics
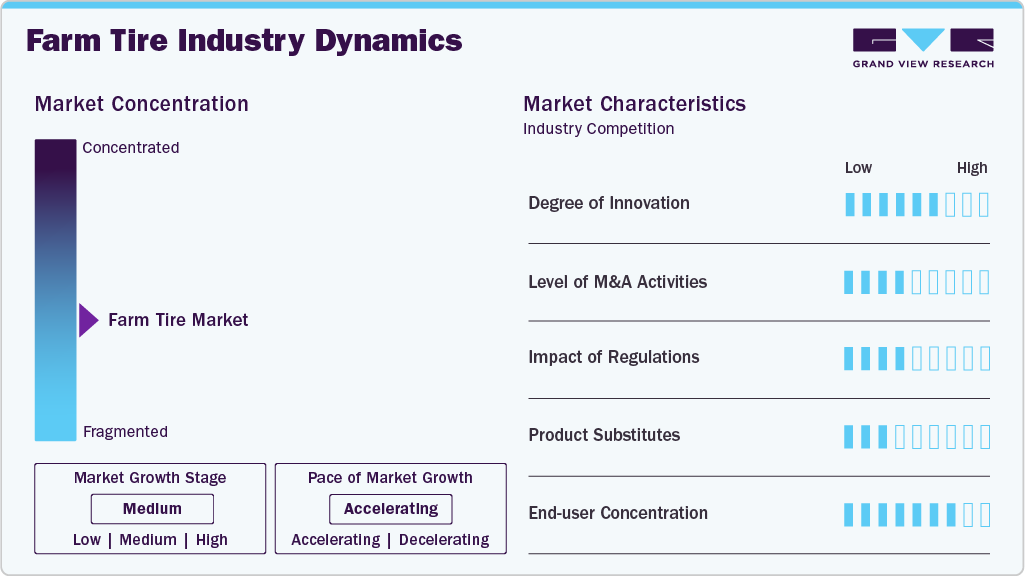
The farm tire market is experiencing a moderate to high degree of innovation, driven by the evolving needs of modern agriculture and environmental sustainability. Manufacturers are investing in advanced materials like low-rolling resistance rubber compounds, self-cleaning treads, and airless tire technologies to enhance performance, durability, and fuel efficiency. Precision farming and autonomous machinery demand tires that are compatible with GPS and sensor-based systems, encouraging continuous R&D. Furthermore, the shift toward sustainable and regenerative agriculture has led to innovation in tire designs that minimize soil compaction and improve traction on diverse terrains. Collaborations between tire manufacturers and agri-tech firms also play a key role in pushing innovation boundaries.
 To learn more about this report, Download Free Sample Report
The threat of substitutes in the farm tire market is relatively low, as there are limited alternatives that can fully replace the functionality, durability, and terrain-specific performance of specialized agricultural tires. While technologies like rubber tracks are gaining traction for specific applications such as minimizing soil compaction in large-scale farms, they are generally more expensive and less versatile compared to pneumatic tires. Moreover, traditional methods like animal-powered plowing or manual farming tools are no longer viable substitutes in commercial farming due to low efficiency. Therefore, despite emerging innovations, farm tires remain the most cost-effective and adaptable solution for modern agricultural machinery.
Analyst Perspective
he farm tire market is evolving from a replacement-driven industry to a technology-oriented market focused on improving farm productivity, operational efficiency, and soil health. Demand is increasingly shifting toward high-performance radial, IF (Increased Flexion), and VF (Very High Flexion) tires that enable higher load-carrying capacity, minimize soil compaction, and support precision farming practices. Manufacturers are strengthening their competitive position through investments in advanced tread designs, durable rubber compounds, digital tire monitoring technologies, and sustainable manufacturing processes to meet the changing requirements of modern agriculture. In addition, rising agricultural mechanization, increasing adoption of high-horsepower equipment, expanding replacement demand, and growing investments in precision farming across emerging economies are expected to support long-term market growth and create opportunities for product innovation and portfolio expansion.
Product Insights
Based on product, the bias segment led the market with the largest revenue share of 57.9% in 2025 and is expected to grow at a CAGR of 6.5% over the forecast period. The use of bias tires is high in India and China as these tires are manufactured using natural rubber, which is produced mainly in the two countries. In addition, the crosshatch construction of the bias tire, coupled with its availability at low cost, is likely to fuel its demand.
The cost of raw materials is low, which, in turn, decreases the manufacturing cost of the product. However, the decreasing supply of natural rubber is likely to restrain the segment’s growth. In addition, natural rubber increases the rigidity of the tire, which loses uniformity after use, compromising the round shape of the farm tire and decreasing its shelf life.
Radial tires are manufactured with steel ply, which increases durability, along with bead-to-bead construction at an angle of 90 degrees to the circumferential centerline, which increases the flexibility of tires and reduces the rolling resistance, resulting in improved performance. This is likely to drive the demand for radial farm tires in agricultural vehicles over the forecast period.
The cost of radial tires is high on account of the use of synthetic rubber and modern manufacturing technology requiring high-cost machinery. As a result, the penetration of the product in the major agricultural markets and the developing economies, such as India and China, is low. The aforementioned factors are likely to limit the farm tire market expansion.
Distribution Insights
Based on distribution, the aftermarket segment led the market with the largest revenue share of 70.1% in 2025 and is expected to grow at a CAGR of 6.7% over the forecast period. The rising demand for the replacement of tires by farmers on account of the expansion of agricultural activities across the globe is anticipated to benefit the segment growth over the forecast period.
The use of bias tires is reducing as they are being replaced with radial tires having high-performance characteristics. In addition, the growth of new vehicle sales is lower, indicating that the demand for tires is lower through OEM distribution compared to replacement. These factors are projected to drive the demand for farm tires through aftermarket sales.
The demand for new farm tires through aftermarket channels is increasing owing to the presence of different types of platforms, such as online, authorized dealers, and third-party dealers. However, the popularity of tire retreading in developing economies, such as India and China, is likely to restrain the demand for farm tires through the aftermarket.
The demand for farm tires through the OEM channel is expected to witness growth owing to the increasing demand for new agricultural vehicles, such as tractors and harvesters. The demand for these vehicles is high in developed economies as farmers are able to afford the newly introduced, expensive farm equipment that aids in executing farming activities on large patches of land.
Application Insights
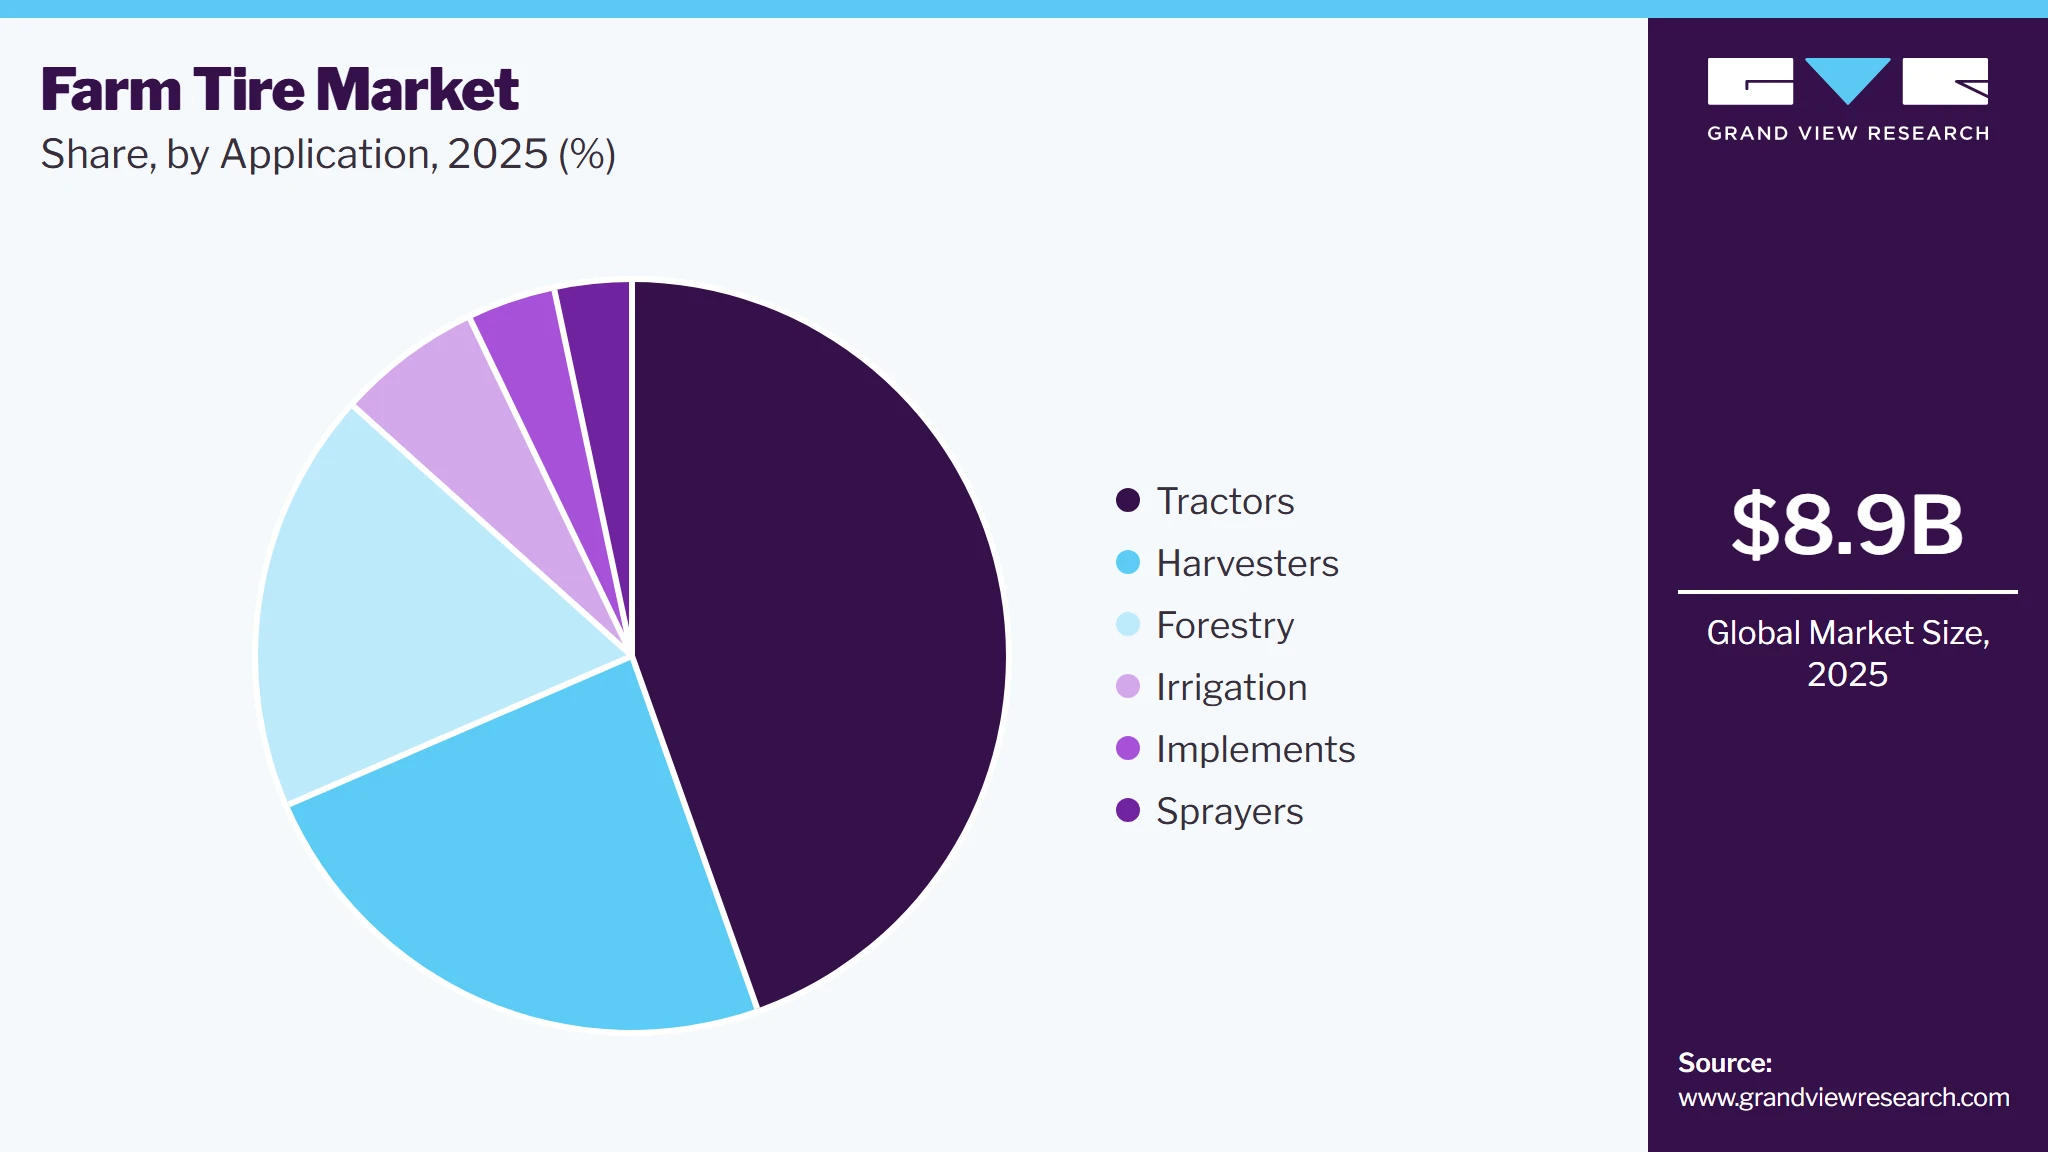
Based on application, the tractors segment led the market with the largest revenue share of 44.6% in 2025 and is expected to grow at a CAGR of 6.7% over the forecast period. As a result, the demand for tires is also witnessing growth with the increasing popularity and use of tractors in the industry.
The demand for farm tires in the harvesters segment is expected to witness growth owing to the introduction of several types of harvesters to suit the farming needs. For instance, John Deere has introduced crop-specific harvesters to meet the requirements of farmers, resulting in the ease of harvesting crops, such as sugarcane and corn. This has led to an increased demand for harvesters for long patches of farm.
 To learn more about this report, Download Free Sample Report
The growing demand for technologically advanced machinery for forestry operations is expected to drive the demand for tires. In addition, high penetration of forestry equipment in mature markets, including North America and Europe, results in rising aftermarket sales for the tires, which is likely to propel the market growth of farm tires over the forecast period.
The growth in the mechanization of irrigation processes on account of increased efficiency and superior crop yield, supported by mechanized irrigation, is expected to drive the market for irrigation equipment. This is further likely to drive the demand for irrigation equipment, including farm tires, thereby propelling the farm tire market growth.
Regional Insights
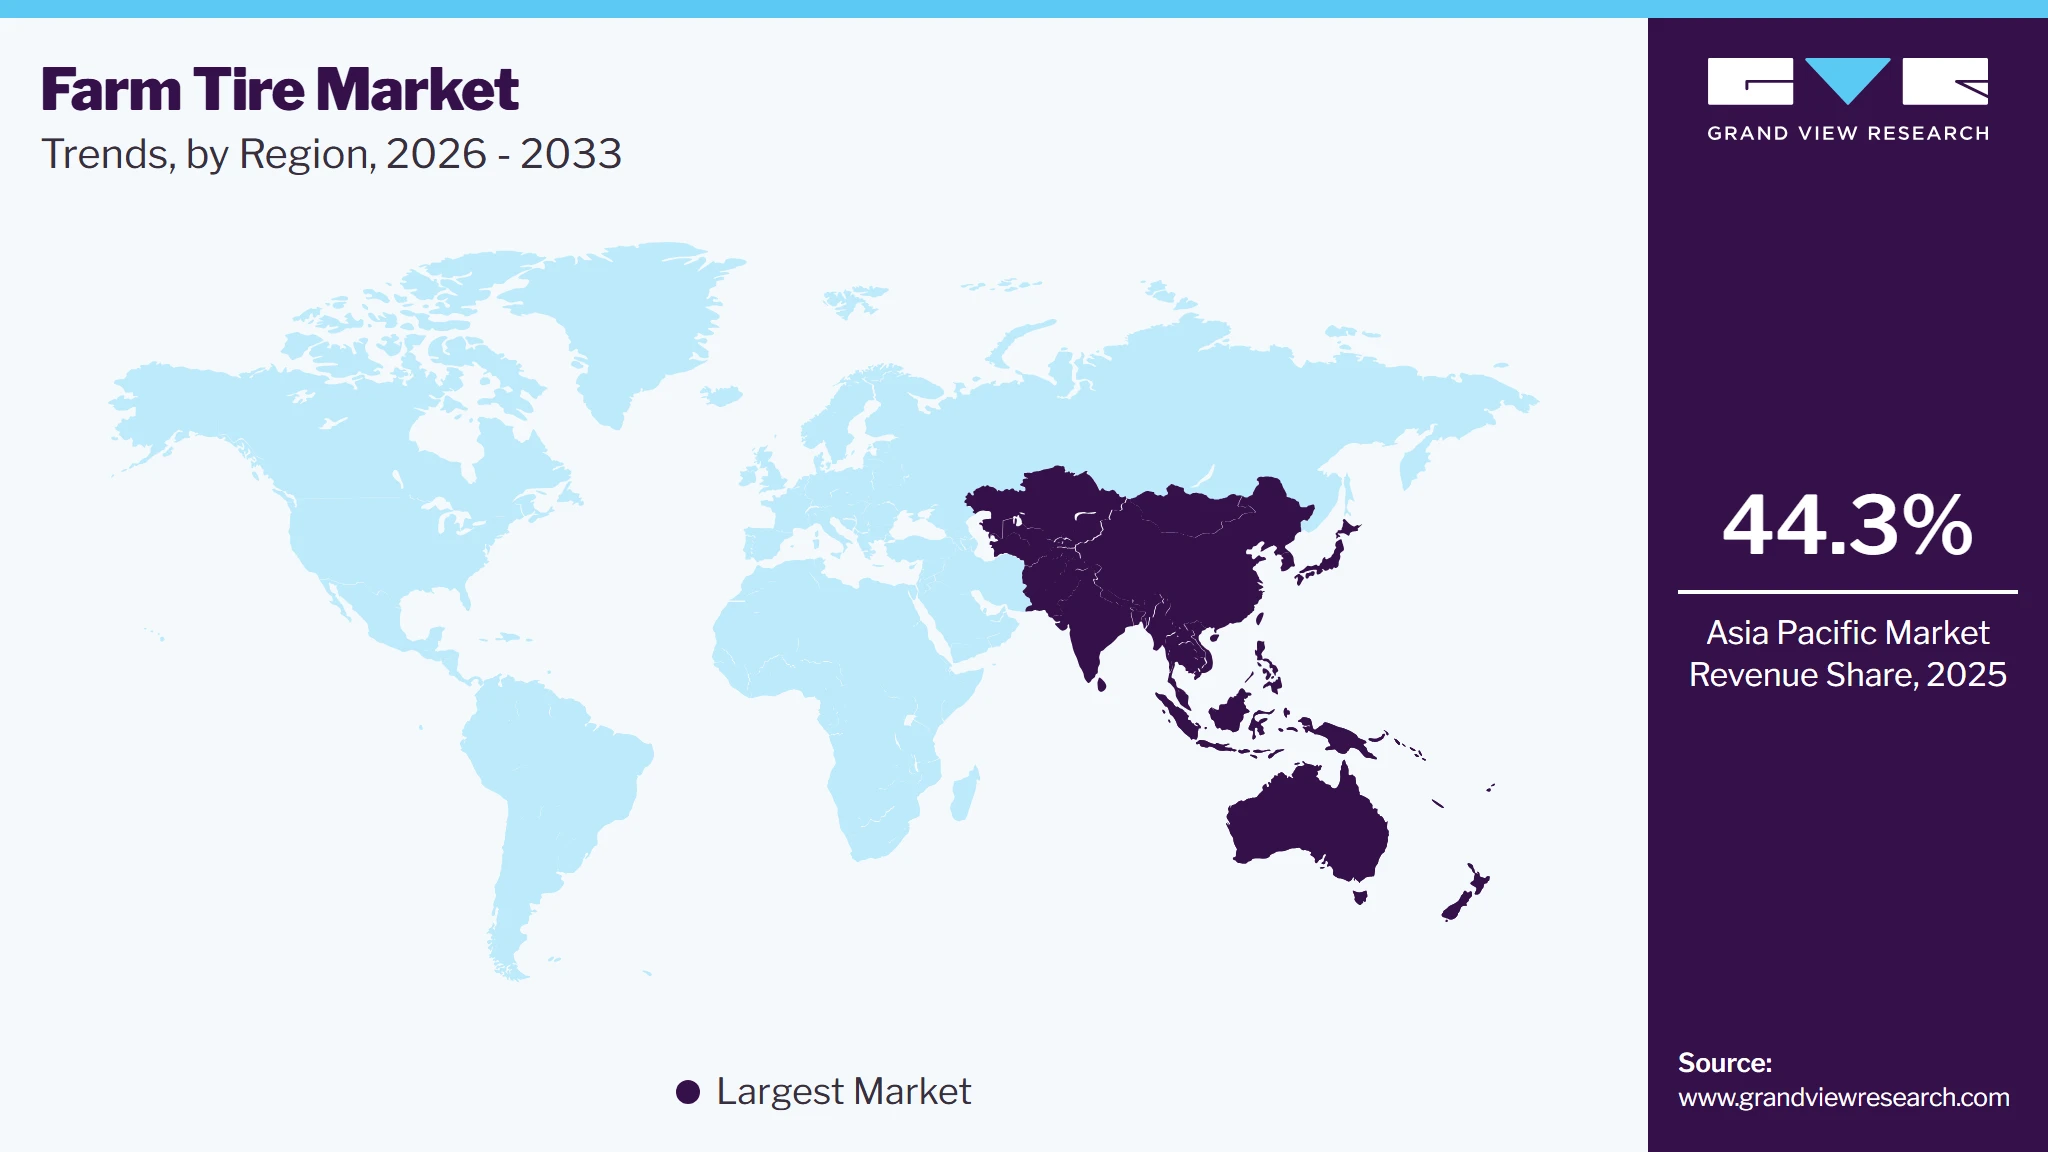
Asia Pacific dominated the farm tire market with the largest revenue share of 44.3% in 2025. This is attributed to factors such as increasing population, rising disposable income of the middle-class population, and rapid industrialization and urbanization. In addition, the presence of small and large-scale manufacturers in the region is likely to benefit the farm tire market growth.
 To learn more about this report, Download Free Sample Report
China Farm Tire Market Trends
The farm tire market in China held the largest share in the Asia Pacific region in 2025. China farm tires market demand is rising due to increased agricultural mechanization and government support for modernizing farming practices. As the country shifts from labor-intensive to machinery-driven farming to address rural labor shortages and boost productivity, there’s a surge in demand for high-performance and durable farm tires. Additionally, China’s expanding agri-tech sector and its focus on food security are further fueling investments in advanced farming equipment, including tractors and harvesters, which directly drives tire demand.
Europe Farm Tire Market Trends
Europe farm tires market is witnessing steady growth in farm tire demand owing to precision agriculture practices, strong regulatory frameworks supporting sustainable farming, and the presence of well-established OEMs. Farmers are increasingly adopting high-tech machinery to improve yield efficiency, requiring tires that support better traction, reduced soil compaction, and fuel efficiency. Moreover, the push for eco-friendly agricultural methods has led to a preference for radial tires that offer better performance and environmental benefits.
As a key agricultural hub within Europe, farm tire market in Germany is growing due to advancements in agri-tech and a strong focus on automation. The German government’s support for smart farming initiatives, combined with the country's robust machinery manufacturing base, contributes to rising demand for specialized and high-load capacity farm tires. The growth of organic and sustainable farming practices also necessitates tires that minimize ground pressure and enhance field performance.
North America Farm Tire Market Trends
North America's farm tire demand is increasing as a result of the region's vast agricultural landscape, widespread use of mechanized farming, and adoption of cutting-edge farming technologies. Climate variability and the need for higher productivity have encouraged farmers to upgrade to more durable and efficient tires. The presence of major agricultural equipment manufacturers and a well-established aftermarket service ecosystem also bolsters tire sales across the U.S. and Canada.
The demand in the U.S. farm tires market is primarily driven by large-scale commercial farming, high equipment penetration, and continued investment in precision agriculture. Farmers are replacing old machinery with advanced tractors and harvesters that require high-quality tires capable of handling heavier loads and varied terrains. Additionally, rising grain prices and government subsidies for agricultural upgrades are further motivating farmers to invest in better equipment, including premium tires.
Latin America Farm Tire Market Trends
The Latin America farm tire market, especially countries like Brazil and Argentina, is experiencing growth in demand due to the expansion of commercial farming and export-oriented agriculture. The region's increasing soybean, maize, and sugarcane cultivation necessitates large-scale farming equipment, which in turn drives the need for robust and reliable tires. Improved rural infrastructure, foreign investments in agriculture, and growing awareness about the benefits of radial tires are also supporting market growth.
Middle East & Africa Farm Tire Market Trends
In the Middle East & Africa, farm tire demand is growing due to ongoing agricultural development projects, government-led food security initiatives, and the modernization of traditional farming methods. As more arid and semi-arid regions adopt irrigation-based farming, the need for equipment capable of operating in challenging conditions rises, increasing demand for durable, high-traction tires. Additionally, increasing imports of farm machinery and supportive policies are helping drive the farm tire market forward.
Key Farm Tire Company Insights
Some key players operating in the market include Bridgestone Corporation and Continental AG
-
Bridgestone is a global leader in tire manufacturing, offering a wide range of premium agricultural tires known for durability and performance. Its Firestone brand is especially dominant in the North American farm tire market, catering to tractors, harvesters, and sprayers.
-
Continental AG is a top-tier player recognized for its innovative agricultural tire solutions that enhance fuel efficiency and reduce soil compaction. The company focuses heavily on precision farming compatibility and sustainable tire technology.
Hankook Tire & MRF Limited are some emerging market participants in the farm tire market.
-
Hankook is steadily entering the agricultural segment with its growing portfolio of farm tires designed for high load-bearing and improved traction. The company is leveraging its R&D capabilities to compete with established players in emerging markets.
-
MRF is an Indian tire manufacturer expanding its presence in the farm tire sector with cost-effective, robust solutions tailored for local and regional farming needs. It is gaining traction in developing markets by focusing on affordability and reliability.
Key Farm Tire Companies
The following key companies have been profiled for this study on the farm tire market.
-
Balkrishna Industries Limited (BKT)
-
Bridgestone Corporation
-
Continental AG
-
Compagnie Générale des Établissements Michelin (CGEM)
-
Sumitomo Rubber Industries, Ltd.
-
Titan International, Inc.
-
Mitas
-
TBC Corporation
-
Apollo Tyres Ltd.
-
Hankook Tire
-
MRF Limited
-
JK Tyre & Industries Ltd.
-
CEAT
-
The Carlstar Group, LLC
-
Specialty Tires of America, Inc.
-
Alliance Tire Group (ATG)
-
Trelleborg AB
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Balkrishna Industries Limited (BKT); Bridgestone Corporation; Continental AG; Compagnie Générale des Établissements Michelin (CGEM); Sumitomo Rubber Industries, Ltd.; Titan International, Inc.; Mitas; TBC Corporation; Apollo Tyres Ltd.; Hankook Tire; MRF Limited; JK Tyre & Industries Ltd.; CEAT; Trelleborg AB)
- Invest in advanced radial, IF, and VF farm tire technologies to improve traction, durability, and reduce soil compaction.
- Expand global manufacturing capacity and strengthen OEM partnerships with leading agricultural machinery manufacturers while enhancing aftermarket distribution networks.
- Focus on sustainable tire manufacturing through recyclable materials, fuel-efficient designs, and digital tire monitoring technologies.
- Strong global manufacturing footprint with extensive dealer and distribution networks across agricultural markets.
- Broad product portfolios covering tractors, harvesters, sprayers, implements, and forestry equipment with advanced R&D capabilities.
- Long-standing relationships with OEMs and strong brand recognition supported by continuous product innovation.
- High dependence on volatile natural rubber, synthetic rubber, steel, and carbon black prices affecting production costs.
- Significant capital investment required for advanced tire manufacturing facilities and continuous technology development.
- Increasing regulatory pressure related to sustainability, emissions, and end-of-life tire recycling requirements.
Emerging Players (The Carlstar Group, LLC; Specialty Tires of America, Inc.; Alliance Tire Group (ATG))
- Focus on specialized agricultural tires for niche farming applications, including compact tractors, forestry equipment, and implement tires.
- Expand regional distribution networks and strengthen partnerships with dealers and aftermarket service providers.
- Differentiate through cost-effective solutions, customized tire designs, and application-specific product offerings.
- Strong expertise in niche agricultural and specialty tire segments with flexible product development capabilities.
- Faster response to regional customer requirements and growing presence in replacement tire markets.
- Competitive pricing strategies and customized solutions for diverse agricultural applications.
- Smaller manufacturing scale and lower global market presence compared to multinational tire manufacturers.
- Limited financial resources for large-scale R&D investments and global expansion initiatives.
- Higher dependence on regional agricultural demand and aftermarket sales, making revenues more susceptible to seasonal market fluctuations.
Recent Developments
-
In October 2023, Continental AG expanded its agricultural range by launching new sizes in TractorMaster and CompactMaster AG/EM series to support larger and more powerful machinery.
-
In May 2023, Bridgestone expanded its VX-R TRACTOR tire range, introducing 23 new sizes in the 65, 70, and 85 series, ranging from 24 to 38-inch rims. These tires, developed with enliten technology, aim to enhance sustainability without compromising performance.
Farm Tire Market Report Scope
Report Attribute
Details
Market size in 2025
USD 8.9 billion
Estimated market size in 2026
USD 9.4 billion
Projected market size by 2033
USD 14.4 billion
Growth rate
CAGR of 6.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in thousand units, Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, distribution, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Turkey; China; India; Japan; Australia; Brazil; Argentina; South Africa
Key companies profiled
Balkrishna Industries Limited (BKT); Bridgestone Corporation; Continental AG; Compagnie Générale des Établissements Michelin (CGEM); Sumitomo Rubber Industries, Ltd.; Titan International, Inc.; Mitas; TBC Corporation; Apollo Tyres Ltd.; Hankook Tire; MRF Limited; JK Tyre & Industries Ltd.; CEAT; The Carlstar Group, LLC; Specialty Tires of America, Inc.; Alliance Tire Group (ATG); Trelleborg AB
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Farm Tire Market Report Segmentation
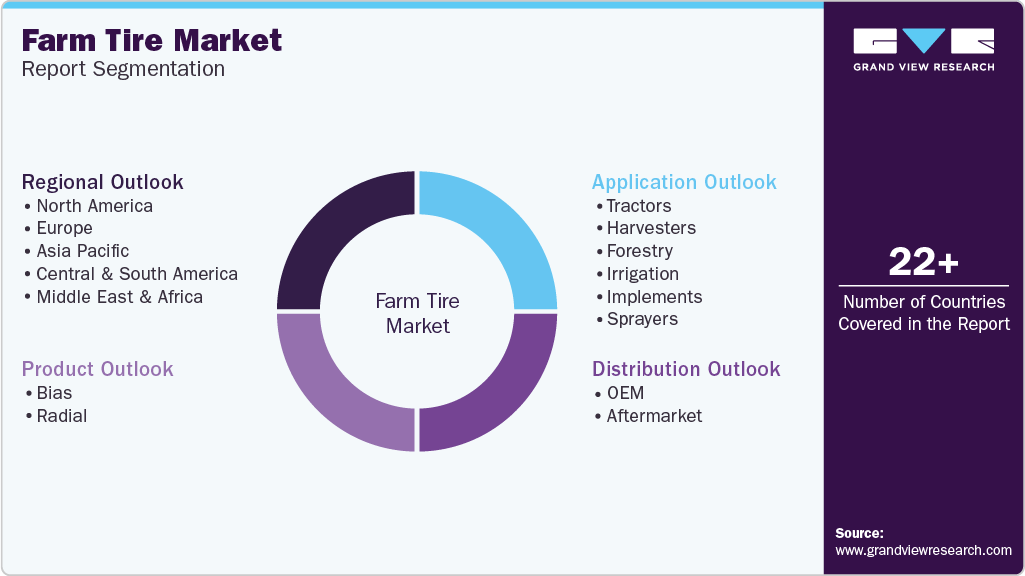
This report forecasts revenue growth at global, regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global farm tire market report based on the product, application, distribution, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Thousand Units; Revenue, USD Million, 2021 - 2033)
-
Bias
-
Radial
-
-
Application Outlook (Volume, Thousand Units; Revenue, USD Million, 2021 - 2033)
-
Tractors
-
Harvesters
-
Forestry
-
Irrigation
-
Implements
-
Sprayers
-
-
Distribution Outlook (Volume, Thousand Units; Revenue, USD Million, 2021 - 2033)
-
OEM
-
Aftermarket
-
-
Regional Outlook (Volume, Thousand Units; Revenue; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Turkey
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
-
Research Methodology
The farm tire market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each farm tire segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Bias
Revenue generated from the sale of bias-ply farm tires designed for tractors, trailers, and other agricultural equipment requiring high sidewall strength, durability, and resistance to impacts and cuts while operating in rugged field conditions and uneven terrain.
Radial
Revenue generated from the sale of radial farm tires engineered to provide superior traction, reduced soil compaction, improved fuel efficiency, enhanced ride comfort, and longer service life for modern tractors, harvesters, and advanced agricultural machinery.
Segment - Distribution
Revenue capture definition
OEM
Revenue generated from the sale of farm tires supplied directly to original equipment manufacturers for installation on new tractors, harvesters, sprayers, implements, and other agricultural machinery during the manufacturing and assembly process.
Aftermarket
Revenue generated from the sale of replacement farm tires through distributors, dealers, retailers, and service providers for existing agricultural vehicles and equipment requiring maintenance, performance upgrades, or tire replacement due to wear and tear.
Segment Application
Revenue capture definition
Tractors
Revenue generated from the sale of farm tires used on agricultural tractors for land preparation, plowing, planting, cultivation, hauling, and other field operations requiring high traction, stability, and load-carrying capacity.
Harvesters
Revenue generated from the sale of farm tires designed for combine harvesters and harvesting equipment requiring high load-bearing capacity, excellent flotation, reduced soil compaction, and stable performance during harvesting operations.
Forestry
Revenue generated from the sale of farm and forestry tires used on logging tractors, skidders, forwarders, and forestry equipment operating in rugged terrains, offering enhanced traction, puncture resistance, and durability in harsh working environments.
Irrigation
Revenue generated from the sale of farm tires installed on irrigation equipment and agricultural machinery used for water distribution and field irrigation, ensuring reliable mobility, stability, and efficient operation across different soil conditions.
Implements
Revenue generated from the sale of farm tires used on agricultural implements such as trailers, seeders, balers, cultivators, spreaders, and other towed equipment, providing reliable load support, stability, and smooth field transportation.
Sprayers
Revenue generated from the sale of farm tires designed for self-propelled and trailed agricultural sprayers, enabling stable movement, reduced crop damage, precise field navigation, and efficient pesticide, herbicide, and fertilizer application across agricultural lands.
Estimation Model
Layer Name
Key Question
Description
Raw Material & Tire Manufacturing
What is the production capacity and supply of farm tires by product type?
Estimates the supply of farm tires by evaluating the availability of natural rubber, synthetic rubber, carbon black, steel cords, and other raw materials, along with tire manufacturing capacity, production technologies, and output of bias and radial tires across key regions.
OEM & Aftermarket Distribution
How many farm tires are supplied through OEM and aftermarket channels?
Evaluates the distribution of farm tires through original equipment manufacturers and replacement markets by analyzing agricultural machinery production, replacement cycles, dealer networks, fleet maintenance trends, and demand across OEM and aftermarket sales channels.
End-Use Application Demand
Which applications generate the highest demand for farm tires?
Measures demand across tractors, harvesters, forestry equipment, irrigation systems, implements, and sprayers by assessing agricultural mechanization, equipment utilization, replacement frequency, farm size, and seasonal farming activities across different regions.
Regional Revenue Validation
What is the final market value by region and segment?
Validates market estimates through regional agricultural machinery sales, farm tire pricing trends, manufacturer revenues, dealer and distributor sales, import-export analysis, replacement demand, and adoption of advanced tire technologies to derive the final market size by product, distribution channel, application, and region.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Market Analysis
Detailed assessment of the farm tire market across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, highlighting regional demand drivers, agricultural mechanization trends, and growth opportunities.
Enables clients to identify high-growth regional markets and develop region-specific expansion and investment strategies.
Competitive Benchmarking
Comprehensive profiling and benchmarking of leading farm tire manufacturers based on product portfolio, strategic initiatives, technological capabilities, geographic presence, and competitive positioning.
Helps clients evaluate competitor strengths, identify market gaps, and formulate effective competitive strategies.
Distribution Channel & Technology Analysis
In-depth analysis of OEM and aftermarket sales channels, dealer networks, replacement demand, and emerging tire technologies such as radial, IF, VF, and smart tire solutions.
Provides insights into revenue opportunities, channel optimization, and technology adoption trends to support strategic business decisions.
Frequently Asked Questions About This Report
Asia Pacific held the highest revenue market share of 44.3% in 2025, driven by extensive agricultural activities, rapid farm mechanization, a large tractor fleet, and strong demand for replacement tires in countries such as China and India.
Aftermarket segment led the market with the largest revenue share of 70.1% in 2025.
Increasing agricultural mechanization, rising adoption of high-performance farming equipment, and growing demand for durable, fuel-efficient tires are the key factors driving the farm tire market.
Some of the key players operating in the farm tire market include Balkrishna Industries Limited (BKT), Bridgestone Corporation, Continental AG, Compagnie Générale des Etablissements Michelin, Sumitomo Rubber Industries, Ltd., Titan International, Inc., Mitas, TBC Corporation, Apollo Tyres Ltd., Hankook Tire, MRF Limited, JK Tyre & Industries Ltd., CEAT, The Carlstar Group, LLC, Specialty Tires of America, Inc., Alliance Tire Group (ATG), Trelleborg AB
The farm tire market size was estimated at USD 8.9 billion in 2025 and is expected to reach USD 9.4 billion in 2026.
Bias segment led the market with the largest revenue share of 57.9% in 2025.
Tractors segment led the market with the largest revenue share of 44.6% in 2025.
The farm tire market is expected to grow at a compound annual growth rate of 6.4% from 2026 to 2033 to reach USD 14.4 billion by 2033.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


