
- Home
- »
- IT Services & Applications
- »
-
Farming As A Service Market Size, Share Report, 2026-2033GVR Report cover

Farming As A Service Market (2026 - 2033)
Size, Share & Trends Analysis Report By Service Type (Farm Management Solutions, Production Assistance, Access To Market), By Delivery Model, By End-use (Farmers, Government, Corporate), By Region, And Segment Forecasts
Market Size, 2025
$5.7BMarket Estimate, 2026
$6.4BMarket Forecast, 2033
$16.7BCAGR, 2026–2033
14.5%Farming-as-a-Service Market Summary
The global farming as a service market size was valued at USD 5.7 billion in 2025 and is projected to grow from USD 6.4 billion in 2026 to USD 16.7 billion by 2033, at a CAGR of 14.5% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 44.9% in 2025. This growth is driven by increasing mechanization and automation of agricultural activities.
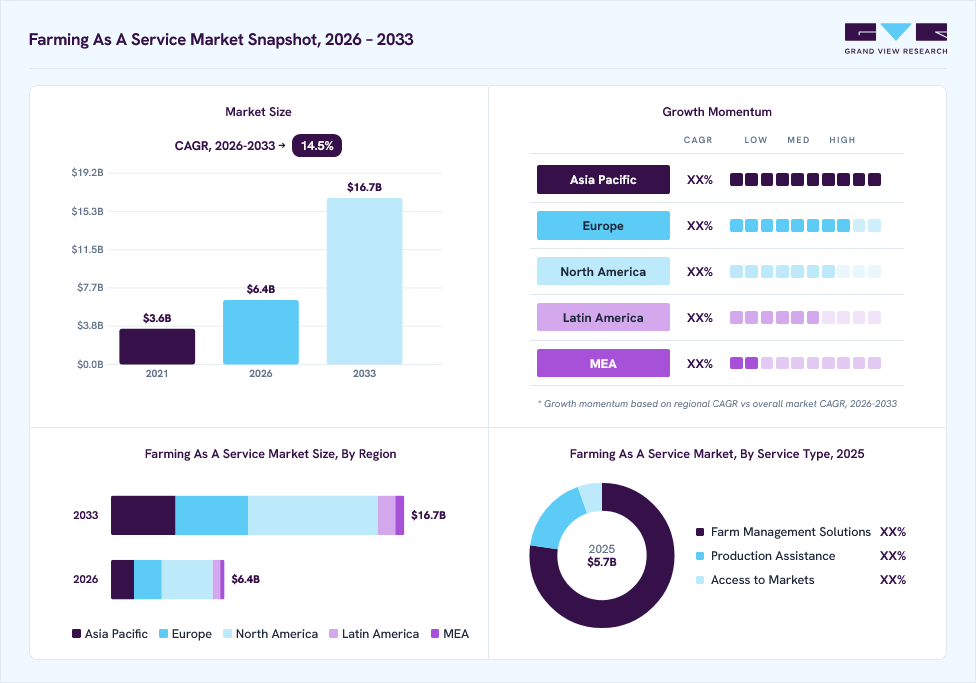 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By service type: Farm management solutions segment dominated the market, with a revenue share of 77.1% in 2025.
- By delivery model: Subscription segment held the largest market share of 58.7% in 2025.
- By end use: Farmers segment held the largest market share of 32.0% in 2025.
Regional Highlights
- Largest regional market: North America (44.9% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 5.7 Billion
- Estimated market size in 2026: USD 6.4 Billion
- Projected market size by 2033: USD 16.7 Billion
- CAGR (2026–2033): 14.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The rapid advancement and adoption of digital technologies in agriculture are drivng the farming-as-a-service market growth. Precision farming tools, satellite imaging, drones, and IoT-based sensors are transforming how farms are managed. FaaS providers integrate these technologies to deliver services such as real-time crop monitoring, variable rate application of inputs, and predictive analytics for better decision-making. These solutions increase operational efficiency and contribute to resource conservation by reducing the overuse of water, fertilizers, and pesticides. The digital ecosystem created by FaaS enhances transparency, traceability, and accountability across the value chain, making it attractive to both farmers and agribusiness stakeholders.The increasing adoption of digital technologies in agriculture drives the farming-as-a-service market growth. With the rise of precision farming tools, data analytics, GPS-enabled equipment, and remote sensing, farmers are now more equipped than ever to make data-driven decisions. However, many small and marginal farmers, especially in emerging economies, lack the capital or technical expertise to adopt these technologies independently. FaaS addresses this gap by offering access to advanced machinery, services, and digital tools on a subscription or pay-per-use model, making precision agriculture financially viable and operationally accessible to a wider base of farmers.
 To learn more about this report, Download Free Sample Report
Government support and favorable policy frameworks are also propelling the FaaS market forward. Many countries are recognizing the role of technology in ensuring food security. They are introducing subsidies, grants, and public-private partnerships to promote precision farming and rural mechanization through FaaS platforms. In addition, climate change and the associated unpredictability of weather patterns have increased the demand for adaptive farming solutions. FaaS helps mitigate risks associated with erratic climatic conditions by offering tailored agronomic insights and insurance-related services, thus enhancing farmers’ resilience.
The rising popularity of outcome-based farming models is driving the adoption of the farming-as-a-service market. Unlike conventional models that rely heavily on ownership of assets and inputs, FaaS promotes a shift towards result-oriented services where productivity, efficiency, and sustainability are prioritized over input volume. This change aligns with broader global trends in smart agriculture and the circular economy, positioning FaaS as a crucial enabler of future-ready farming systems. As farmers increasingly look for innovative, scalable, and economically viable solutions, the relevance and adoption of farming-as-a-service will continue to grow across both developed and developing agricultural landscapes.
Market Dynamics
The farming as a service (FaaS) market is gaining momentum as farmers increasingly seek access to modern agricultural technologies and professional farming services without making substantial capital investments. Service providers are offering solutions such as farm equipment leasing, drone-based crop monitoring, precision farming advisory, soil testing, irrigation management, and digital farm management platforms on a subscription or pay-per-use basis. This model is particularly attractive to small and medium-sized farmers who face financial constraints but require advanced technologies to improve productivity and operational efficiency. The growing digitalization of agriculture, rising awareness of precision farming practices, and increasing demand for cost-effective farming solutions are driving market growth.
The increasing adoption of drones, sensors, and smart farming equipment is driving the farming as a service (FaaS) market, as these technologies are fundamentally transforming how agricultural operations are monitored and managed. Modern farming increasingly relies on data-driven decision-making, and technologies such as drones and field sensors generate valuable real-time information about crop health, soil conditions, irrigation needs, and pest infestations. However, purchasing, operating, and maintaining these advanced technologies often requires significant investment and technical expertise that many farmers cannot easily afford. Farming as a service providers bridge this gap by offering access to these technologies on a service basis, allowing farmers to benefit from precision agriculture without bearing the full cost of ownership. This model makes advanced farming tools more accessible to small and medium-sized agricultural producers. As awareness of precision farming benefits grows, demand for technology-enabled FaaS solutions continues to increase.
High operational costs associated with advanced farming technologies represent a significant restraint on the FaaS market, as they directly affect the profitability and scalability of service providers. While the FaaS model is designed to reduce the capital burden on farmers, service providers must invest heavily in sophisticated equipment, including drones, GPS-guided machinery, precision sprayers, autonomous tractors, IoT sensor networks, and advanced analytics platforms. Beyond the initial investment, these technologies require continuous maintenance, calibration, software upgrades, and technical support to ensure optimal performance. The cost of maintaining technologically advanced equipment can be substantial, particularly when services are delivered across geographically dispersed agricultural regions. These ongoing expenditures increase operational overhead and can limit the ability of providers to offer affordable pricing to farmers. Consequently, high operating costs may slow the expansion of Farming as a service offerings, especially in price-sensitive agricultural markets.
The growing adoption of digital platforms and mobile applications is creating additional opportunities for machinery-sharing services within the farming as a service ecosystem. Digital platforms enable farmers to locate, reserve, schedule, and pay for equipment through user-friendly interfaces, simplifying the entire rental process. Real-time availability tracking, automated scheduling, and digital payment systems improve operational efficiency and customer convenience. FaaS providers can integrate these capabilities with broader farm management services to create comprehensive agricultural support platforms. Such digital ecosystems improve equipment accessibility and strengthen customer engagement and service retention. As rural connectivity and smartphone adoption continue to improve, the potential for digitally enabled machinery-sharing models is expected to increase significantly.
Analyst Perspective
The farming as a service market is fundamentally transforming agricultural technology adoption by shifting the industry from an ownership-based model to a service-based consumption model. Unlike traditional agricultural equipment markets, success in this sector depends less on hardware sales and more on the ability to deliver measurable agronomic outcomes, operational support, and recurring value to farmers. Providers that can establish strong local service networks, integrate multiple farming services into a single offering, and demonstrate clear productivity improvements are likely to achieve higher customer retention and market penetration. As farm economics become increasingly focused on efficiency and risk management, the FaaS model is expected to play a crucial role in democratizing access to advanced agricultural technologies across both developed and emerging farming regions.
Service Type Insights
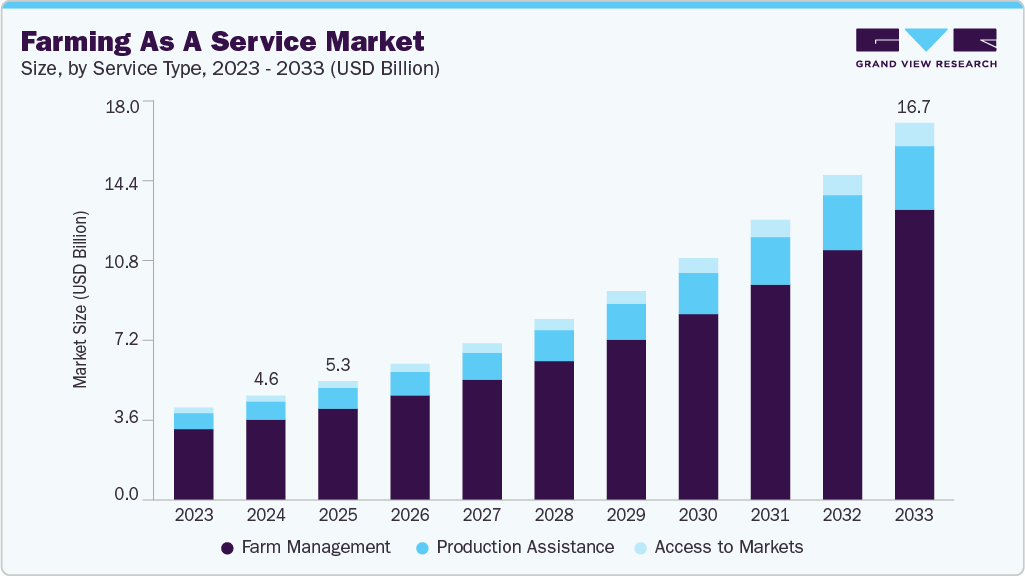
Based on service type, the farm management solutions segment led the market with the largest revenue share of 77.1% in 2025. Farm management solutions include solutions such as providing insights to government, farmers, corporates, and other final advisory firms. Farm management services also include precision farming services, which have shown tremendous growth in recent years owing to the growing acceptance of precision farming to meet the rising global demand for high-quality food products. Tools such as hyperspectral imaging technology, sensors (to gather data on weather conditions and soil health), auto-guidance equipment, precision irrigation systems, etc., to improve agricultural results. Further boosting demand for precision farming and quickening market expansion is the worsening water issue and the growing need to conserve natural resources.
The access to markets segment is projected to be the fastest-growing segment from 2025 to 2033. The increasing penetration of digital platforms and mobile technologies in rural areas drives the FaaS market growth. With smartphones becoming more accessible and mobile internet coverage expanding, it has become easier to deliver services such as remote sensing, satellite imagery-based advisory, and market intelligence to farmers. These platforms allow service providers to reach remote locations and deliver customized, real-time recommendations, thereby enhancing farm productivity. Moreover, data analytics integrated with these platforms helps farmers make informed decisions regarding crop planning, irrigation, pest control, and harvesting schedules.
Delivery Model Insights
Based on delivery model, the subscription segment led the market with the largest revenue share of 58.7% in 2025. The popularity of the recurring service model is growing due to its affordability and convenience for resource-constrained farmers. Rather than making high-capital purchases for machinery or analytics tools, farmers can subscribe to services on a monthly, seasonal, or per-hectare basis. This model democratizes access to advanced technologies such as drones, automated irrigation systems, and yield forecasting software. It also ensures regular updates, maintenance, and customer support, which are essential for farmers who may not have the technical expertise to operate or troubleshoot complex equipment. Furthermore, subscription models often allow for scalability and customization, letting farmers choose specific service bundles based on their crop type, land size, or regional challenges. This flexibility enhances service adoption and fosters long-term engagement, which, in turn, supports the sustainability of FaaS platforms.
The pay per use segment is projected to growing at a CAGR of 15.3% from 2025 to 2033. The growing need among smallholder farmers for better price realization and improved market connectivity is drivng the segment growth. Traditionally, many farmers have faced exploitation from middlemen and limited access to competitive marketplaces, resulting in inconsistent income and low profitability. FaaS platforms are now bridging this gap by directly connecting farmers to end-buyers, including agribusinesses, food processors, and retailers, often through digital marketplaces. This ensures transparency in pricing, reduces transaction layers, and opens up broader demand channels for their produce. Moreover, the availability of market intelligence and price forecasting through FaaS tools enables farmers to plan their harvest and sales strategies more efficiently. These services are particularly valuable in remote or underserved regions where access to market information has historically been minimal.
End-use Insights
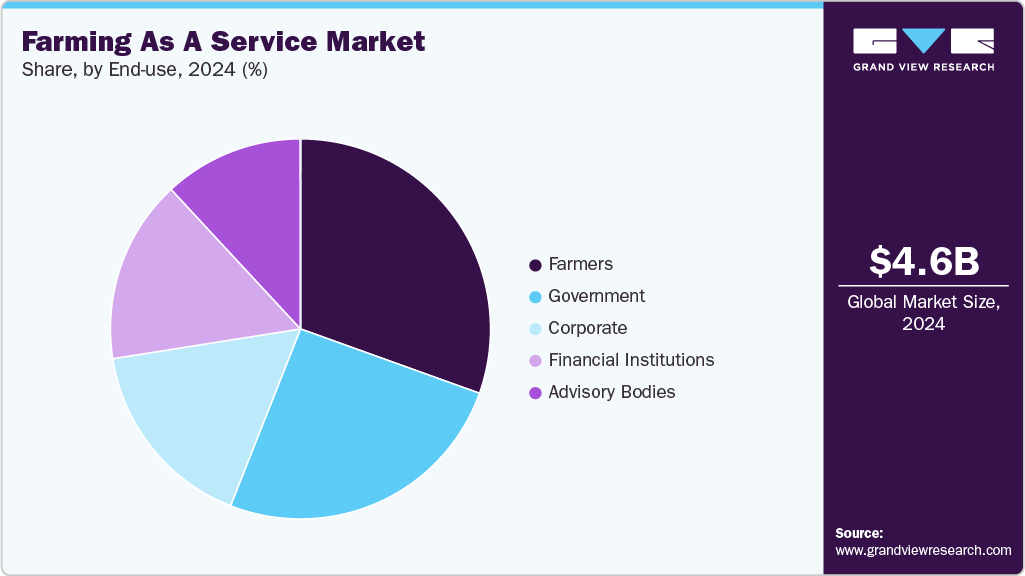
Based on end use, the farmers segment led the market with the largest revenue share of 32.0% in 2025. The seasonal and cyclical nature of farming activities makes on-demand access to equipment and skilled labor particularly appealing. Many farmers, especially those with small landholdings, cannot afford to purchase expensive machinery such as harvesters, seeders, or sprayers for limited seasonal use. FaaS offerings, such as equipment rental marketplaces and mechanization-as-a-service models, address this gap by enabling shared access to machinery, which enhances operational efficiency without adding capital expenditure burdens. This democratization of technology through service-based models significantly strengthens the value proposition for farmers, thereby propelling market growth.
 To learn more about this report, Download Free Sample Report
The government segment is projected to grow at a CAGR of 15.8% from 2025 to 2033. Subsidy programs and policy frameworks are propelling the growth of FaaS under the government segment. Governments are increasingly allocating funds and grants for precision agriculture, farm mechanization, and agri-tech startups offering service-based models. These initiatives often include incentives for drone-based surveillance, satellite mapping, and real-time weather and crop advisory systems, all delivered through FaaS platforms. Moreover, several public-private partnerships (PPPs) are being launched to create scalable and efficient models for technology-driven farming, further integrating government efforts into the ecosystem.
Regional Insights
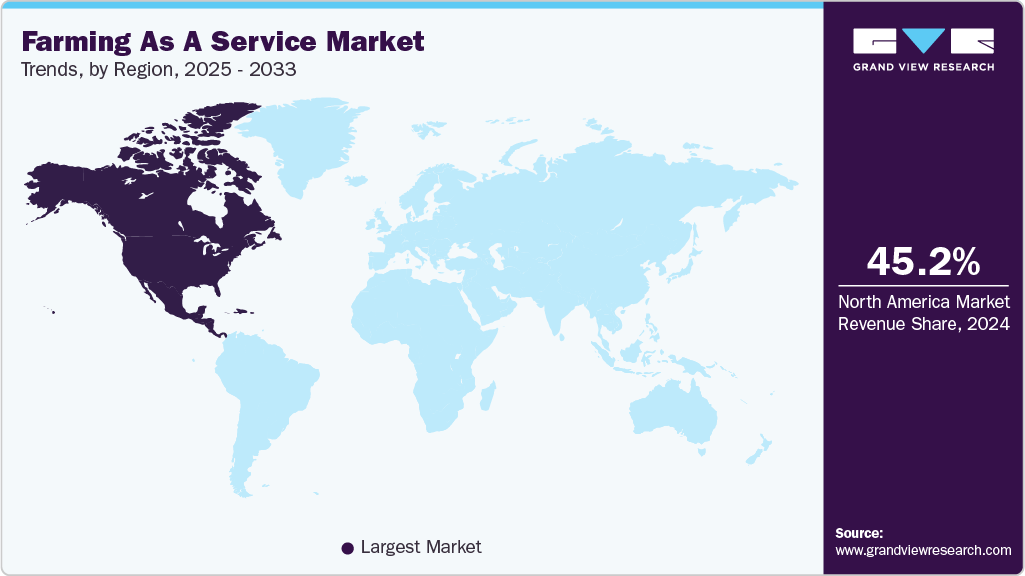
North America dominated the global farming as a service market with the largest revenue share of 44.9% in 2025. The rise in demand for organic and sustainably grown food is influencing farmers to modernize their practices, and FaaS is helping them transition smoothly. By outsourcing critical functions such as crop advisory, monitoring, and analytics, farmers can implement best practices without needing deep in-house expertise. This trend is particularly relevant in North America, where consumers are increasingly conscious of food origin and agricultural transparency. As a result, FaaS is not just a cost-saving measure but also a strategic tool for farms aiming to meet evolving market expectations.
 To learn more about this report, Download Free Sample Report
U.S. Farming As A Service Market Trends
The farming as a service market in the U.S. held the largest share in the North America region in 2025. The growth of digital infrastructure across North America is accelerating the growth of the Farming-as-a-Service (FaaS) market. High-speed internet connectivity, increasing mobile device penetration, and the expansion of cloud-based platforms have enabled seamless deployment of smart farming solutions. These digital tools allow real-time data collection and remote management of farm activities, which is especially valuable in vast agricultural regions where on-ground supervision is difficult. FaaS providers are leveraging this digital transformation to offer services such as satellite-based crop monitoring, predictive weather alerts, and cloud-integrated farm management systems. This connectivity also allows farmers to access these services through user-friendly mobile apps, simplifying decision-making and operational planning.
Europe Farming As A Service Market Trends
The farming-as-a-service industry in Europe is expected to grow during the forecast period. The widespread adoption of digital farming technologies is also accelerating the FaaS market in Europe. With strong telecommunications infrastructure and rising awareness of agri-tech solutions, European farmers are increasingly turning to cloud-based farm management systems, remote sensing, and AI-driven decision support tools. These technologies are typically bundled into service models by FaaS providers, enabling real-time monitoring of crop conditions, predictive analysis for yield forecasting, and timely advisory services. Such data-driven approaches help farmers make more precise and sustainable decisions, improve operational transparency, and optimize the use of inputs like water, seeds, and fertilizers.
The farming-as-a-service industry in the UK is grow during the forecast period. The UK government’s growing emphasis on agri-environmental payments and results-based farming schemes is driving the farming-as-a-service market growth. These new schemes often require farmers to submit detailed records of their land management practices, environmental impacts, and biodiversity outcomes. Managing and reporting such complex data can be time-consuming and technically difficult without specialist tools. FaaS platforms increasingly offer these record-keeping and compliance-reporting capabilities as part of their packages, which not only simplifies administration but also helps farmers qualify for higher levels of government funding. This built-in alignment between FaaS services and policy frameworks provides an added incentive for farmers to adopt such models.
Asia Pacific Farming As A Service Market Trends
The Asia Pacific farming-as-a-service industry is expected to be the fastest-growing segment, with a CAGR of 16.8% over the forecast period. The need to modernize agriculture across a diverse and predominantly agrarian landscape is driving the farming-as-a-service market growth. Many countries in the region, such as India, China, Vietnam, Indonesia, and the Philippines, rely heavily on agriculture for employment and rural livelihoods yet face serious challenges related to productivity, land fragmentation, labor shortages, and climate vulnerability. In this context, FaaS has emerged as a viable solution to bridge the technological and operational gaps that hinder farm efficiency. By offering on-demand services ranging from equipment rental to precision farming and advisory support, FaaS helps small and marginal farmers access modern tools without needing to invest in expensive capital assets.
The farming-as-a-service industry in China is projected to grow during the forecast period. The rise of agritech startups and corporate participation is further propelling the FaaS market in China. Numerous technology companies, including giants like Alibaba and Tencent, are investing in agriculture platforms that integrate AI, IoT, big data, and cloud computing into farming operations. These companies are collaborating with cooperatives, local governments, and agricultural service firms to offer end-to-end farming solutions under the FaaS model.
Key Farming As A Service Company Insights
Some of the key companies operating in the market Mahindra & Mahindra Ltd, and Deere & Company, among others are some of the leading participants in the farming-as-a-service market.
-
Mahindra & Mahindra Ltd. manufactures farm equipment and automotive vehicles. The company also offers information technology, hospitality, and financial services. The company’s subsidiaries include Mahindra Engineering and Chemical Products Limited, Mahindra Overseas Investment Company (Mauritius) Ltd., Mahindra Vehicle Manufacturers Limited, Mahindra Two Wheelers Europe Holdings S.a.r.l., Mahindra USA, Inc., Mahindra Consulting Engineers Limited, Mahindra Holdings Limited, and Mahindra Airways Limited.
-
Deere & Company is engaged in the manufacturing & construction of agricultural and forestry machinery, drivetrains, and diesel engines for heavy equipment and lawn care machinery. Additionally, the company also manufactures and provides other heavy manufacturing equipment. The company serves diverse industries such as agriculture, forestry, construction, landscaping & grounds care, engines & drivetrain, government and military, and sports turf.
Agrostar, and Bighaat are some of the emerging market participants in the farming-as-a-service market.
-
Agrostar is an agriculture product and service provider. The company, through its platform, provides farmers with expert advice, agricultural information, agronomy information, and weather forecasts.
-
Bighaat is an agritech startup that provides farmers with a platform to exchange information and learn about all aspects of farming. The company also offers products and services, including healthcare and crop support services.
Key Farming As A Service Companies
The following key companies have been profiled for this study on the farming as a service market.
-
Accenture
-
AGRIVI
-
Apollo Agriculture
-
BigHaat
-
Conservis
-
Deere & Company
-
EM3 Agriservices
-
GeoPard Agriculture
-
IBM Corporation
-
ITC Limited
-
Mahindra&Mahindra Ltd.
-
Syngenta
-
Taranis
-
Trimble Inc.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Established Players (John Deere; Trimble Inc.; AGCO Corporation; CNH Industrial; Bayer AG)
- Mature players in the farming as a service market focus on providing integrated farming solutions rather than standalone products. They combine equipment leasing, precision agriculture tools, agronomic consulting, and digital farm management services.
- Their strategy aims to help farmers improve productivity without large upfront capital investments. They also leverage extensive dealer and service networks to expand service delivery across farming regions.
- Mature players benefit from long-standing relationships with farmers and agricultural cooperatives. Their broad portfolios allow them to offer end-to-end farming support from planting to harvesting.
- Strong financial resources enable investment in digital platforms, service infrastructure, and advanced machinery. Their established service ecosystems create trust and encourage long-term customer engagement.
- Managing service operations across diverse agricultural regions can be resource-intensive. Service quality may vary depending on local dealer capabilities and infrastructure.
- Large organizations can face challenges in tailoring solutions to specific farm sizes and crop types. Dependence on seasonal farming activities can also affect service utilization rates.
Emerging Players (EM3 AgriServices; Trringo; Hello Tractor; Apollo Agriculture; DeHaat)
- Emerging players focus on asset-light service models that improve access to farming resources. They offer equipment rental, advisory services, input delivery, and digital farming support through mobile platforms.
- Their strategy targets small- and medium-sized farmers who cannot afford to own expensive machinery. Many also use data analytics to deliver customized recommendations and service packages.
- Emerging players provide affordable access to modern farming technologies and equipment. Their digital-first approach improves convenience and access to services for farmers.
- Flexible pay-per-use models reduce financial barriers for farm mechanization. They are also well-positioned to address underserved rural and fragmented agricultural markets.
- Emerging players often depend on regional operations and limited service coverage. Scaling service delivery across multiple geographies can be operationally challenging.
- Customer retention may be affected by seasonal demand patterns and price sensitivity. Limited financial resources can also constrain fleet expansion and technology investments.
Recent Developments
-
In June 2025, Pivot Bio partnered with Taranis to help farmers adopt more sustainable nutrient management practices through the Taranis Conservation program. Through this partnership, Pivot Bio’s dealer network will be able to offer Taranis Conservation services, which assist growers in securing NRCS funding for regenerative practices such as soil testing, nitrogen stabilizers, and variable rate technology.
-
In October 2024, Syngenta signed a multi-year partnership with Taranis to drive AI-powered advancements in agronomic productivity and conservation-focused innovation for agricultural retailers across the U.S. As part of this collaboration, a significant investment will support ag retailers in adopting Taranis’ AI-based agronomic platforms. The initiative is designed to modernize ag retail workflows, improve on-farm decision-making, promote the adoption of conservation practices, and ultimately enhance farm profitability.
-
In September 2024, AGRIVI partnered with the Barbados Agricultural Development and Marketing Corporation (BADMC) to launch an innovative AI-powered advisory platform aimed at boosting the productivity and sustainability of agriculture across Barbados. This initiative features the AI Agronomic Advisor, a virtual agronomy expert accessible to all Barbadian farmers via WhatsApp, 24/7. Acting as a direct link between BADMC and the farming community, the platform provides continuous access to expert consultations, agricultural knowledge, and active support on critical farming issues.
Farming As A Service Market Report Scope
Report Attribute
Details
Market size in 2025
USD 5.7 billion
Estimated market size in 2026
USD 6.4 billion
Projected market size by 2033
USD 16.7 billion
Growth rate
CAGR of 14.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share analysis, competitive landscape, growth factors, and trends
Segments covered
Service type, delivery model, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; China; India; Japan; Australia; South Korea; Brazil; UAE; Saudi Arabia; South Africa
Key companies profiled
Mahindra & Mahindra Ltd.; Deere & Company; ITC Limited; Trimble Inc.; EM3 Agriservices; Apollo Agriculture; Accenture; Taranis; IBM Corporation; BigHaat; Conservis; AGRIVI; Syngenta; GeoPard Agriculture
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Farming As A Service Market Report Segmentation
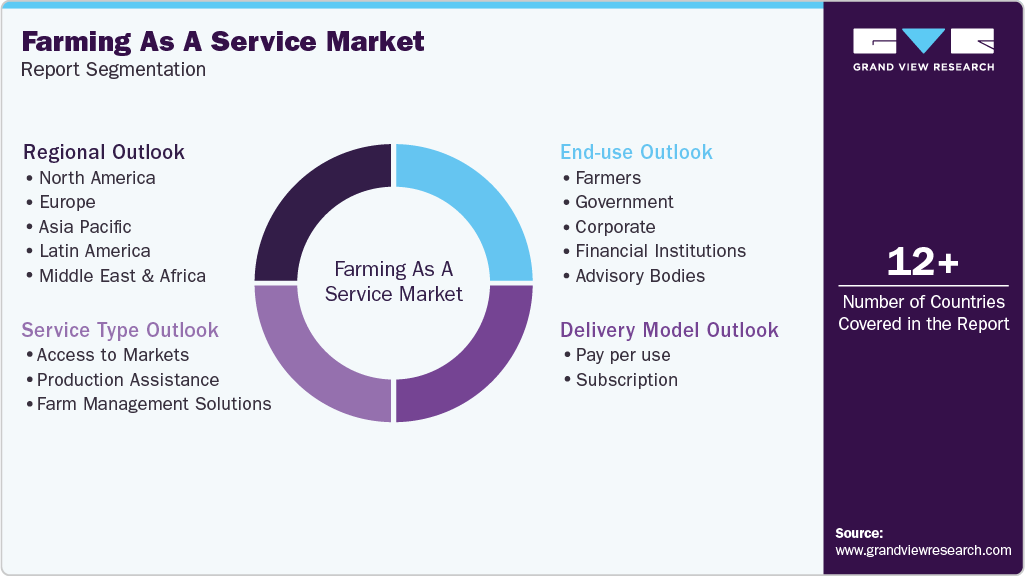
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global farming-as-a-service market report based on service type, delivery model, end-user, and region.
 To learn more about this report, Download Free Sample Report
-
Service Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Farm Management Solutions
-
Precision Farming Tools
-
Analytics
-
Information Sharing
-
-
Production Assistance
-
Equipment Rentals
-
Labor Services
-
Utility Services
-
-
Access to Markets
-
Supplier to Farmers
-
Farmers to End Market
-
-
-
Delivery Model Outlook (Revenue, USD Billion, 2021 - 2033)
-
Pay per use
-
Subscription
-
-
End-use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Farmers
-
Government
-
Corporate
-
Financial Institutions
-
Advisory Bodies
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Southeast Asia
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The farming as a service market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each farming as a service segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Service Type
Revenue capture definition
Farm Management Solutions
Value is captured through digital platforms that support crop planning, precision agriculture, field monitoring, input optimization, weather intelligence, and farm analytics. Providers generate recurring income by delivering data-driven insights that help improve productivity, reduce resource wastage, and enhance operational decision-making.
Production Assistance
Economic activity is centered on providing access to farm machinery, drone services, soil testing, irrigation support, harvesting equipment, and skilled labor on demand. Service providers benefit from increasing mechanization needs among farmers who prefer asset-light operating models rather than purchasing expensive equipment outright.
Access to Markets
Revenue opportunities arise from platforms connecting farmers with buyers, processors, exporters, retailers, and agribusinesses. Operators monetize through transaction fees, commission structures, trade facilitation services, logistics coordination, and value-added supply chain solutions.
Segment – Delivery Model
Revenue capture definition
Pay per use
Income is earned each time a farmer utilizes a specific service such as drone spraying, equipment rental, soil analysis, crop advisory, or harvesting support. This model appeals to small and marginal farmers seeking flexibility without long-term financial commitments.
Subscription
Providers secure predictable recurring cash flows by offering bundled services through monthly, seasonal, or annual plans. Subscribers typically gain continuous access to advisory support, monitoring tools, farm analytics, and productivity-enhancing technologies throughout the cultivation cycle.
Segment – Growing Mechanism
Revenue capture definition
Farmers
The largest demand segment, where spending is directed toward improving yields, reducing production costs, and gaining access to modern agricultural technologies. Adoption is particularly strong among growers seeking professional farm services without making significant capital investments.
Government
Public-sector engagement is driven by agricultural modernization programs, digital farming initiatives, rural development schemes, and food security objectives. Service providers often participate through large-scale implementation projects, technology deployment contracts, and farmer outreach programs.
Corporate
Agribusinesses, food processors, exporters, and input suppliers utilize FaaS platforms to strengthen supply chain visibility, improve sourcing quality, and support contract farming operations. Commercial partnerships often involve integrated service ecosystems spanning production, monitoring, and procurement activities.
Financial Institutions
Banks, insurers, and agricultural lenders leverage FaaS platforms to improve risk assessment, credit underwriting, crop monitoring, and portfolio management. Access to real-time farm data enhances lending decisions and supports the development of agriculture-focused financial products.
Advisory Bodies
Agricultural consultancies, research institutions, cooperatives, NGOs, and extension agencies engage with FaaS providers to deliver technical guidance, sustainability programs, and farmer education initiatives. Their involvement supports knowledge dissemination and promotes wider adoption of modern farming practices.
Estimation Model
Layer Name
Key Question
Description
Service Demand Layer
What agricultural challenges create demand for Farming as a service?
Analyze the operational challenges faced by farmers, including labor shortages, rising equipment costs, limited access to advanced technologies, fragmented land holdings, and the need for higher productivity. This layer identifies where outsourced agricultural services can help growers improve efficiency, reduce capital expenditure, and gain access to modern farming capabilities without owning expensive assets.
Service Delivery Ecosystem Layer
Who provides Farming as a service solutions?
Evaluate the ecosystem of service providers including agricultural machinery operators, drone service companies, digital agriculture platforms, agronomy consultants, input suppliers, and farm management technology providers. The effectiveness of the market depends on the availability of service networks, technological expertise, geographic coverage, and the ability to deliver specialized farming operations on demand.
Farm Engagement Layer
How are farming services incorporated into agricultural operations?
Assess the adoption of services such as precision planting, soil analysis, crop monitoring, drone-based spraying, irrigation management, harvesting support, equipment rental, and data-driven farm advisory solutions. This layer measures the extent to which farmers integrate external service providers into their production cycles to improve yields, optimize resource utilization, and enhance decision-making.
Outcome & Revenue Layer
How is value generated within the Farming as a service ecosystem?
Examine revenue generation through subscription-based farm management platforms, pay-per-use machinery services, acreage-based service contracts, drone operations, agronomic consulting, and data analytics offerings. Value is created by lowering upfront investment requirements for farmers while enabling service providers to generate recurring income through continuous engagement across multiple stages of the agricultural production cycle.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Farm Service Outsourcing & Operational Efficiency Trends
Conducted a focused analysis of outsourcing models for land preparation, planting, spraying, harvesting, equipment rental, and agronomic advisory services across commercial farms and smallholder agriculture.
Helps stakeholders identify high-demand service categories, evaluate outsourcing adoption trends, and assess revenue opportunities in service-based agriculture models.
Shared Machinery Access & On-Demand Farming Service Adoption Trends
Evaluated adoption trends for pay-per-use farm equipment, digital booking platforms, contractor networks, drone services, and mechanization-as-a-service offerings aimed at improving equipment accessibility and utilization.
Provides insights into farmer preferences for asset-light operations, emerging platform-based business models, and commercially attractive service offerings that reduce capital expenditure.
Digital Agriculture Platforms & Rural Service Ecosystem Opportunity Assessment
Assessed demand for integrated Farming as a service platforms combining farm management, crop advisory, input procurement, financial services, remote monitoring, and yield optimization tools, along with challenges related to service scalability, rural connectivity, and farmer awareness.
Supports investment and expansion strategies by identifying underserved farming communities, evaluating ecosystem readiness, and strengthening long-term growth opportunities in technology-enabled agricultural service delivery.
Frequently Asked Questions About This Report
The farm management solutions segment led with a 77.1% revenue share in 2025, while production assistance segment is the fastest-growing segment.
The subscription segment led with a 58.7% revenue share in 2025 and it is also the fastest-growing segment.
The farmers segment held the largest share (over 32%) in 2025, while advisory bodies segment is the fastest-growing segment.
Key players operating in the farming-as-a-service market include Mahindra & Mahindra Ltd.; Deere & Company; ITC Limited; Trimble Inc.; EM3 Agriservices; Apollo Agriculture; Accenture; Taranis; IBM Corporation; BigHaat; Conservis; AGRIVI; Syngenta; GeoPard Agriculture.
The global farming-as-a-service market size was estimated at USD 5.7 billion in 2025 and is expected to reach USD 6.4 billion in 2026.
The global farming-as-a-service market is expected to grow at a compound annual growth rate of 14.5% from 2026 to 2033 to reach USD 16.7 billion by 2033.
Key factors include increasing mechanization and automation of agricultural activities, increasing adoption of drones, sensors, and smart farming equipment, and growing adoption of digital platforms and mobile applications.
North America dominated with 44.9% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
About the Author(s)
IT Services & Applications Research Team
Technology · IT Services & ApplicationsThis report was authored by the it services & applications research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the it services & applications segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


