
- Home
- »
- Animal Health
- »
-
Flea, Tick And Heartworm Products Market Size Report 2033GVR Report cover

Flea, Tick And Heartworm Products Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product, By Type (Prescription, OTC), By Animal, By Mode Of Delivery, By Parasite (External Parasite, Internal Parasite), By Care, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$8.4BMarket Estimate, 2026
$9.1BMarket Forecast, 2033
$15.2BCAGR, 2026–2033
7.6%Flea, Tick And Heartworm Products Market Summary
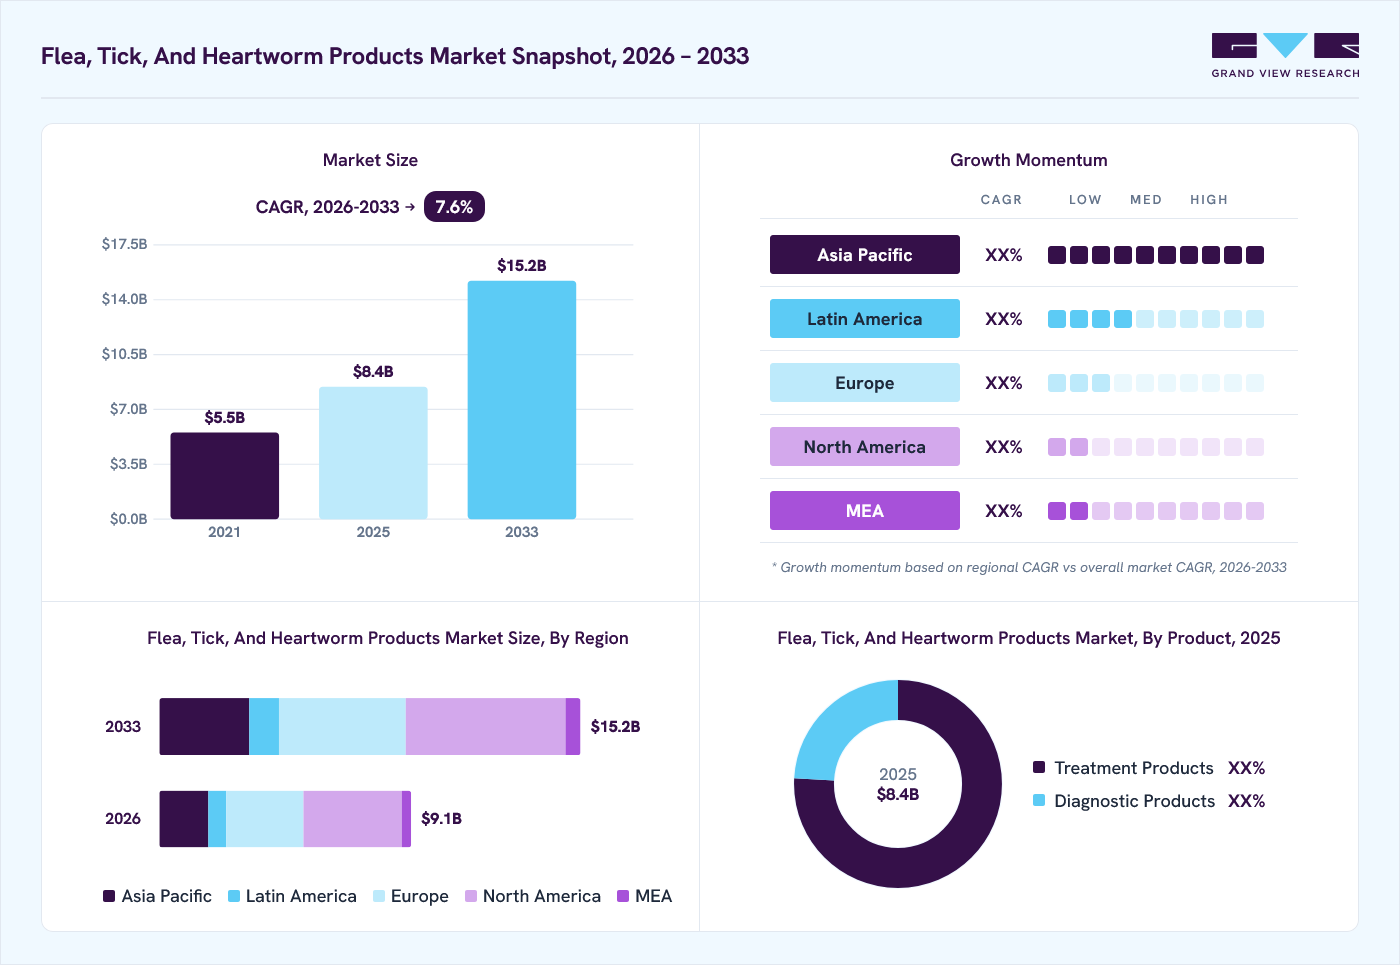
The global flea, tick, and heartworm products market size was valued at USD 8.4 billion in 2025 and is projected to grow from USD 9.1 billion in 2026 to USD 15.2 billion by 2033, at a CAGR of 7.6% from 2026 to 2033. North America market dominated, with a revenue share of 39.3% in 2025. The market is experiencing growth driven by the increasing prevalence of vector-borne diseases, the growing importance of preventive care, and the emergence of novel FTH products.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Treatment products segment led the market with the largest revenue share of 75.8% in 2025.
- By type: Prescription segment led the market with the largest revenue share of 60.6% in 2025.
- By animal type: Canine segment led the market with the largest revenue share of 48.8% in 2025.
- By mode of delivery: Topical segment led the market with the largest revenue share of 47.2% in 2025.
- By parasite: External parasite segment led the market with the largest revenue share of 75.3% in 2025.
Regional Highlights
- Largest regional market: North America (39.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecasts
- Market size in 2025: USD 8.4 Billion
- Estimated market size in 2026: USD 9.1 Billion
- Projected market size by 2033: USD 15.2 Billion
- CAGR (2026-2033): 7.6%
Prism AI by Grand View Research Free to tryAsk a question about the Flea, tick and heartworm products marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
A rise in the spread of heartworm disease and cases of parasitic infestations among animals is also expected to fuel the growth of the flea, tick and heartworm products industry. The expansion of flea-, tick-, and mosquito-borne diseases like Lyme disease, ehrlichiosis, and heartworm is creating greater awareness among pet owners and veterinarians about preventive care. In recent years, their spread has been on the rise globally. According to 2023 data published by the American Veterinary Medical Association (AVMA) and the American Heartworm Society (AHS), estimated that in 2022, many veterinary clinics in the U.S. handled over 100+ cases of heartworm disease in animals per clinic. Of the total veterinarians who responded to this survey, 29% reported that heartworm disease cases have steadily risen over the last year. The prevalence of heartworm diseases was reported to be about 20% for dogs and 33% for cats in the U.S., according to a March 2024 study published in the Parasites & Vectors journal.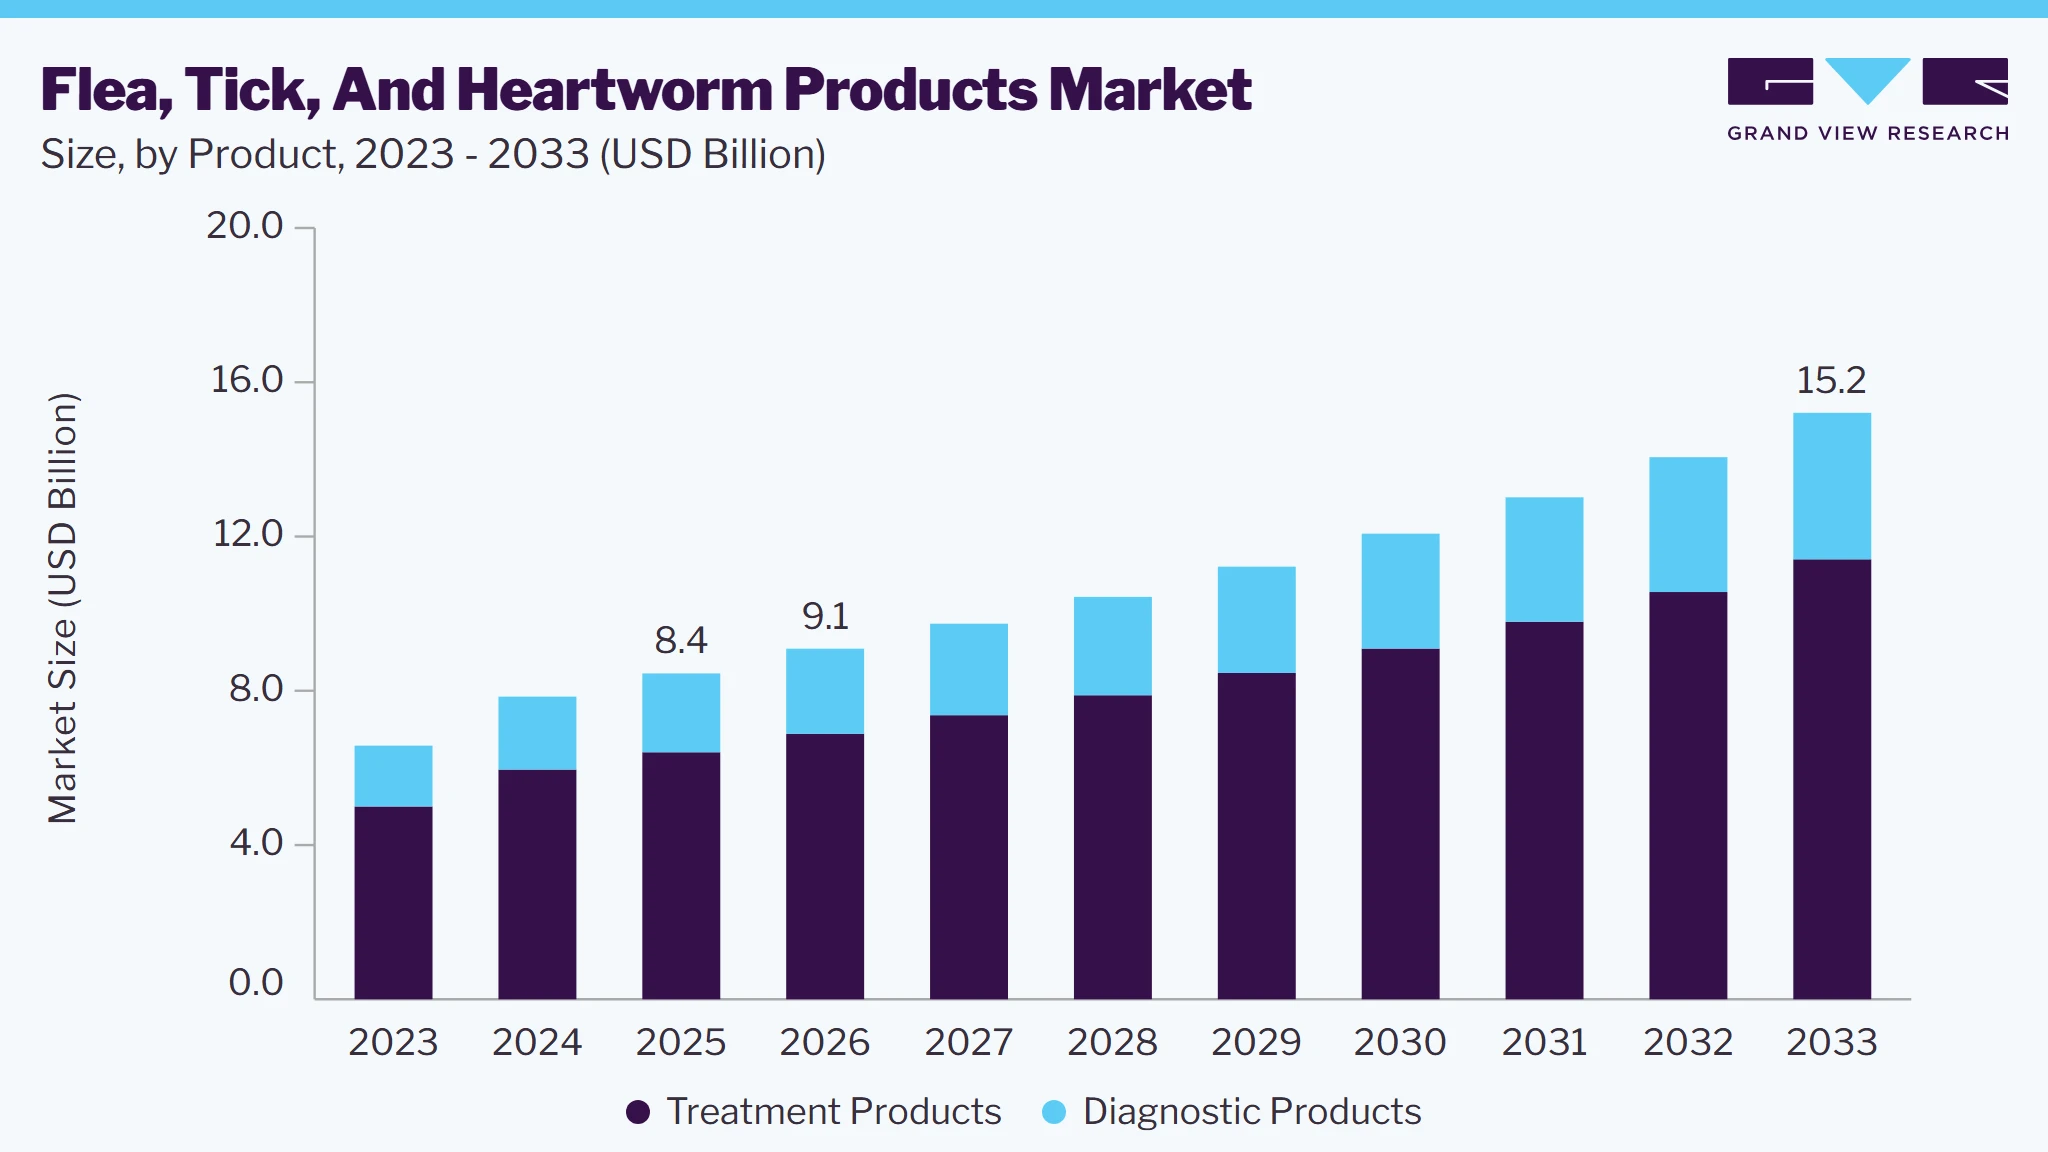 To learn more about this report, Download Free Sample Report
In addition, a March 2024 release by the British Small Animal Veterinary Association (BSAVA) reported that even though the disease is not endemic in the UK, heartworm disease diagnosis has been steadily increasing, with most cases found in dogs. Additionally, a study was conducted in Australia to understand the prevalence of heartworm infection in dogs. This February 2023 study inferred that the prevalence was estimated to be as high as 32.1%, varying slightly in different areas of the country.
The market is set to experience high growth prospects in the forecast period. One of the crucial drivers in this market is the increasing emphasis put by veterinary professionals on the importance of preventive care in animals for managing parasitic infections like flea, tick, and heartworm. Preventive care focuses on administering FTH medication to animals like cats & dogs since their early years of development, irrespective of infestation. Product manufacturers are also actively innovating and seeking regulatory approvals to increase their product portfolio and assist in effectively managing these conditions.
Furthermore, a Merck Animal Health survey of August 2025 revealed a significant gap between pet owners’ intentions and their actual compliance with flea and tick prevention. Most owners recognize the importance of treatment, struggle with timely administration, seasonal misconceptions, and lack of awareness about vector-borne diseases like ehrlichiosis. This highlights an urgent need for education and long-duration solutions. These compliance challenges are driving demand for innovative, long-lasting, and veterinarian-prescribed flea and tick preventives. As awareness grows, companies offering annual or extended-duration treatments are likely to see strong adoption and revenue growth.
Recent Product Launches in the Flea, Tick and Heartworm Products Market
Company
Month & Year of Launch / Approval
Description
Elanco
Oct-24
Credelio Quattro approved by the U.S. FDA: a chewable tablet covering fleas, ticks, heartworm, and several intestinal worms. Reuters
Boehringer Ingelheim
Apr-24
Launched NexGard SPECTRA in India: a monthly chewable combining afoxolaner + milbemycin oxime for both internal & external parasite control. Devdiscourse
Merck Animal Health
Jul-25
Bravecto Quantum (fluralaner injectable) approved in the U.S.: single injection provides 8-12 months of flea & tick protection. Industry Intelligence Inc.
Virbac
Aug-22
Introduced Iverhart Max: a chewable tablet combining ivermectin, pyrantel pamoate, and praziquantel; broad internal parasite plus heartworm coverage
Market Dynamics
The flea, tick, and heartworm products market is experiencing sustained growth, driven by the increasing shift toward comprehensive parasite management and preventive veterinary healthcare. The market is witnessing a transition from single-parasite treatments to broad-spectrum products capable of protecting against multiple internal and external parasites through a single formulation. Manufacturers are actively investing in product innovation, including long-acting injectables, combination chewable tablets, and improved topical formulations that enhance efficacy, simplify administration, and improve treatment compliance. At the same time, growing pet healthcare expenditure, expanding companion animal ownership, and increasing awareness of zoonotic and vector-borne diseases are encouraging pet owners to adopt year-round parasite prevention strategies rather than seasonal treatment approaches.
In addition, the rapid expansion of online veterinary pharmacies, digital pet healthcare platforms, and tele-veterinary services is improving product accessibility and supporting recurring purchases through subscription-based models. However, challenges including evolving parasite resistance to existing active ingredients, stringent regulatory requirements for product approval, and pricing pressure from generic alternatives continue to influence competitive strategies. Despite these challenges, ongoing innovation, portfolio expansion, and increasing investments in preventive companion animal healthcare are expected to sustain long-term market growth.
The increasing prevalence of canine heartworm disease is a major driver for the flea, tick, and heartworm products market. According to the American Heartworm Society (AHS) 2025 Heartworm Incidence Map, an estimated 1.1 million dogs in the U.S. are infected with heartworm, with no state remaining heartworm-free. Texas reported the highest canine heartworm incidence for the first time, recording a 3.78% positivity rate in 2025, up from 2.97% in 2022, while moderate infection rates have expanded into previously low-risk regions such as southern California, southwest Colorado, central Washington, northern Idaho, and southern Maine. The emergence of heartworm in cooler and drier climates is being driven by factors including climate variability, the movement of infected wildlife reservoirs, and increased relocation of dogs through rescue and adoption programs. As veterinary organizations continue to emphasize year-round parasite prevention, pet owners are increasingly adopting broad-spectrum flea, tick, and heartworm preventive products to reduce infection risk. This expanding disease burden, coupled with growing awareness of preventive veterinary care, is expected to accelerate demand for combination parasiticides and support sustained growth of the global flea, tick, and heartworm products market.
Low adherence to parasite prevention protocols remains a significant restraint for the flea, tick, and heartworm products market. Despite veterinary recommendations advocating continuous protection, many pet owners administer preventive treatments inconsistently or discontinue them after seasonal parasite activity declines. Missed doses, irregular treatment schedules, and misconceptions that indoor pets or pets living in colder regions are at lower risk reduce the effectiveness of preventive programs. In addition, limited awareness regarding the long-term consequences of flea, tick, and heartworm infestations contributes to lower compliance rates. These factors reduce repeat product purchases, hinder preventive healthcare adoption, and ultimately restrain the overall growth of the global flea, tick, and heartworm products market.
The development and regulatory approval of long-acting parasiticides present a significant growth opportunity for the flea, tick, and heartworm products market. For instance, in July 2025, the introduction of innovative products such as BRAVECTO QUANTUM, the first FDA-approved injectable parasiticide providing up to 12 months of flea and tick protection with a single dose, highlights the industry's shift toward extended-duration preventive therapies. Long-acting formulations improve treatment compliance by reducing the need for frequent monthly dosing, while offering greater convenience for both veterinarians and pet owners. In addition, continued investments in novel drug delivery technologies, sustained-release formulations, and broad-spectrum parasite protection are expanding the range of preventive solutions available in the market. As veterinary professionals increasingly recommend year-round parasite prevention and pet owners seek more convenient, long-lasting products, the adoption of extended-duration parasiticides is expected to accelerate, creating substantial opportunities for manufacturers to strengthen their product portfolios and expand their market presence.
Market Concentration & Characteristics
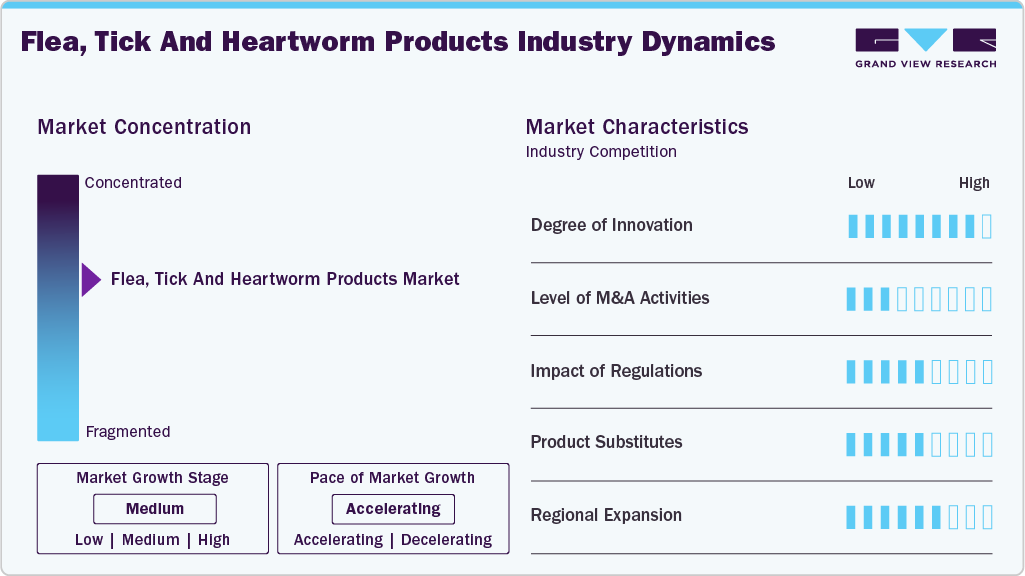
The flea, tick, and heartworm products market exhibits moderate concentration. The pace of its growth is accelerating, dominated by leading players such as Zoetis, Boehringer Ingelheim, Elanco, Merck Animal Health, and Ceva. These companies hold strong brand portfolios, global distribution networks, and invest heavily in R&D, creating competitive barriers for smaller players, transforming innovation and market expansion.
The degree of innovation in the flea, tick and heartworm products industry is estimated to be high. The industry manufacturers are actively launching innovative products using novel techniques to address market problems. For example, in September 2025, Elanco’s Credelio Quattro achieved blockbuster status for delivering broad-spectrum parasite protection covering fleas, ticks, heartworm disease, and positioning the company for global expansion beginning in 2026.
 To learn more about this report, Download Free Sample Report
The market has a low level of mergers and acquisitions. Industry participants are trying to consolidate the distribution channels for FTH products by acquiring other platforms. For instance, in January 2023, PetMeds acquired PetCareRx. The acquisition was completed to capitalize on the latter's vast pet FTH, vitamins, treats, etc., portfolio to increase the former's product portfolio and market reach.
The regulations are estimated to impact the market greatly. On the one hand, the market is constantly experiencing an influx of FTH product approvals by the regulatory authorities. On the other hand, the market is also experiencing a turbulent phase amidst regulatory action about the safety issues of some of the major products.
A few leading players, including Boehringer Ingelheim, Zoetis, and Merck & Co. Inc., currently dominate the market with blockbuster products such as Simparica Trio, NexGard, Frontline, Heartgard, and Bravecto. These globally recognized brands generate significant revenue and maintain strong market control. As a result, despite the presence of substitutes, the market remains relatively concentrated due to their established brand strength.
The market is witnessing moderate regional expansion as industry leaders strengthen their presence through partnerships with animal shelters and welfare organizations. For instance, in January 2025, Zoetis expands its portfolio with FDA approvals, enhancing Simparica Trio and Revolution Plus coverage, addressing emerging ticks and tapeworms, strengthening market leadership, veterinarian confidence, and adoption in canine and feline preventives.
Product Insights
Based on product, the treatment products segment led the market with the largest revenue share of 75.8% in 2025, owing to strong demand for effective parasite management in pets. Pet owners increasingly seek solutions to treat existing infestations, rather than solely relying on preventive measures, boosting sales of prescription and over-the-counter treatments. Popular products such as Simparica Trio, NexGard, Frontline, and Heartgard dominate this segment due to their broad-spectrum efficacy against multiple parasites. High awareness of vector-borne diseases, rising pet ownership, and veterinary recommendations further fuel adoption.
The diagnostic products segment is expected to register the fastest CAGR during the forecast period. Comprising test kits and consumables for detecting parasites such as heartworms, its growth is driven by increasing demand for antigen testing in pets. The global rise in heartworm cases has amplified the need for accurate and timely diagnosis, prompting manufacturers to develop specialized test kits. These innovations enhance detection reliability and speed, meeting veterinary and pet-owner needs.
Type Insights
Based on type, the prescription segment led the market with the largest revenue share of 60.6% in 2025. Veterinarians primarily prescribe oral chewables or topical treatments for effective parasite control, particularly as resistance to some over-the-counter preventives rises in certain regions. Prescription products often use different chemical classes to ensure safety and efficacy, requiring veterinary oversight. For instance, in July FDA approved Bravecto Quantum (fluralaner extended-release injectable), the first long-acting treatment providing 8-12 months of flea and tick protection. Its administration requires professional guidance, reinforcing the importance of prescription options in the market.
OTC is the fastest-growing market segment, with its growth fueled by the increasing pet ownership and consumer preference for convenient, accessible solutions. Pet owners are seeking easy-to-administer treatments without requiring veterinary visits, boosting demand for topical, oral, and spray products. Rising awareness of year-round parasite risks, combined with growing retail availability in pharmacies, pet stores, and online platforms, further accelerates adoption. Manufacturers are responding with innovative formulations, user-friendly packaging, and broad-spectrum efficacy.
Animal Insights
Based on animal type, the canine segment led the market with the largest revenue share of 48.8% in 2025, driven by the high prevalence of parasitic infestations in dogs and strong pet ownership rates. Dog owners increasingly invest in preventive treatments to protect their pets from fleas, ticks, and heartworm, supported by veterinary recommendations and growing awareness of animal health. Popular products such as oral chewables, spot-on treatments, and collars specifically designed for dogs reinforce the dominance of this segment in the market.
The other segment, including ferrets, horses, and similar species, is expected to be the fastest-growing over the forecast period. This market growth is expected due to rising awareness of parasite risks in non-canine and non-feline pets, along with increasing ownership of exotic and farm animals, which is driving demand for specialized preventive and treatment products. Veterinary recommendations and tailored formulations for these species ensure safe and effective parasite control, boosting adoption.
Mode of Delivery Insights
Based on mode of delivery, the topical segment led the market with the largest revenue share of 47.2% in 2025, owing to its advantages over oral medications. Many topical treatments are not systemically absorbed, meaning they do not enter the pet’s bloodstream or penetrate the skin barrier. This makes them particularly suitable for animals with a history of adverse drug reactions or those that have not responded well to oral treatments, offering a safer and effective alternative for parasite control.
The injectable segment is projected to register the fastest CAGR over the forecast period, driven by its higher bioavailability for treating internal infections like heartworm disease. With the rising incidence of heartworm among dogs, cats, and other animals, along with a growing number of new injectable product launches, demand for this delivery method is expected to increase significantly, positioning injectables as a rapidly expanding segment in the flea, tick, and heartworm products market.
Parasite Insights
Based on parasite, the external parasite segment led the market with the largest revenue share of 75.3% in 2025. The growing recognition of the health hazards associated with external parasites, such as allergic reactions, skin infections, and the spread of vector-borne diseases, fuels the need for efficient control measures. Pet owners are progressively looking for preventive and therapeutic options like topical spot-on treatments, oral chewables, collars, and sprays to safeguard their pets throughout the year. Veterinary endorsements, along with novel formulations that provide extensive protection and convenient administration.
The internal parasite segment is projected to grow at the fastest CAGR over the forecast period, driven primarily by the prevalence of heartworm infections in dogs and cats. According to 2023 reports from AVMA, BSAVA, and AHS, heartworm has become one of the fastest-spreading parasitic infections in companion animals. Its potential to cause severe and sometimes fatal cardiac complications underscores the critical need for effective internal parasite prevention and treatment.
Care Insights
Based on care, the preventive care segment led the market with the largest revenue share of 88.3% in 2025, and is projected to register the fastest CAGR over the forecast period. This growth is driven by veterinarians and animal welfare organizations emphasizing proactive measures against flea, tick, and heartworm (FTH) complications. Pet owners are increasingly advised to administer preventive medications regularly, regardless of current infection status, to avoid parasitic infestations. In instances where infestations are detected, structured treatment protocols complement preventive care. The focus on early intervention and routine prophylaxis is fueling widespread adoption.
The therapeutic care segment is the second fastest growing, driven by the rising cases of parasitic infections and the need for targeted treatment. This segment includes medications and protocols designed to treat active infestations, including fleas, ticks, and heartworms, as well as related complications. Increased awareness among pet owners and veterinarians about the health risks associated with untreated infestations, such as allergic reactions, anemia, and cardiac issues, is fueling demand.
Distribution Channel Insights
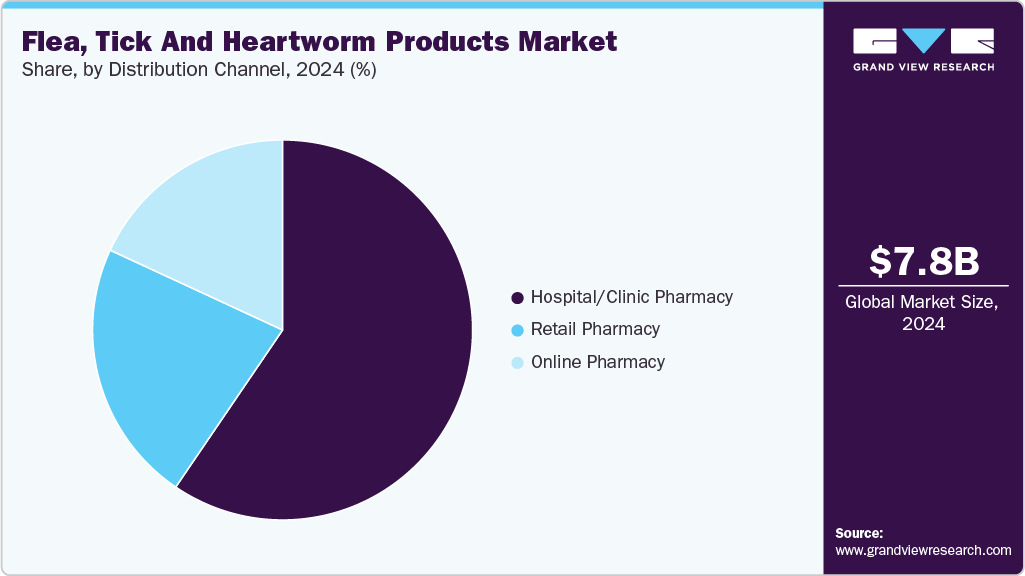
Based on distribution channel, the hospital/clinic pharmacy segment led the market with the largest revenue share of 59.5% in 2025. This dominance is driven by the prescription requirement for most FTH products, necessitating veterinary oversight before purchase. Growing pet owner willingness to invest in pet health, coupled with increasing FTH-related complications, further fuels demand. In addition, rising patient volumes at veterinary clinics, where drugs often require professional monitoring, support consistent product sales.
 To learn more about this report, Download Free Sample Report
The online segment is projected to register the fastest growth over the forecast period, driven by increasing online pharmacy penetration in developing regions, a wider variety of OTC products, and the convenience of digital purchasing. Online platforms allow pet owners to access a broad range of veterinary products from non-medical supplies to OTC and prescription drugs directly from their devices, at any time. Competitive offerings, discounts, and promotions further enhance adoption. The ease of procurement, combined with expanding product availability and user-friendly interfaces, is accelerating market growth, positioning the online channel as a key driver in the flea, tick, and heartworm products market.
Regional Insights
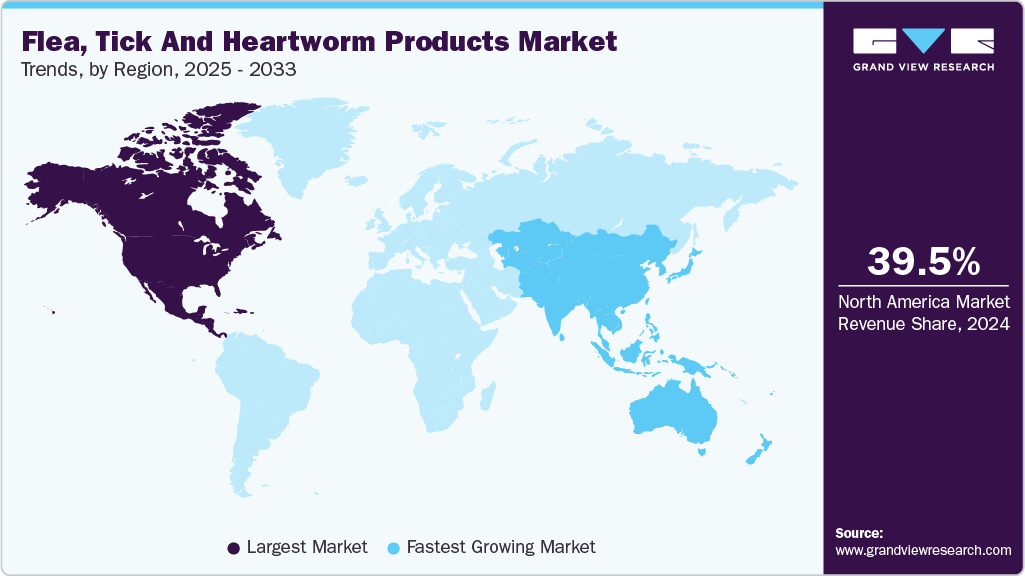
North America dominated the flea, tick, and heartworm products market with the largest revenue share of 39.3% in 2025, holding the largest revenue share of 39.48%. The growing number of pet owners in North America is boosting demand for flea, tick, and heartworm (FTH) products. Rising incidences of FTH-related illnesses in pets further drive the need for preventive and treatment solutions. Supported by a well-established veterinary industry with widespread clinics and increasing pet healthcare expenditures, the region is witnessing significant market growth, fueled by pet owners’ willingness to invest in comprehensive animal care.
 To learn more about this report, Download Free Sample Report
U.S. Flea, Tick and Heartworm Products Market Trends
The flea, tick, and heartworm products market in the U.S. held the largest share in the North America region in 2025. The flea, tick and heartworm products industry in the U.S. accounted for the highest market share in the North America market, owing to significant product approvals by the U.S. FDA and strict regulatory screening of FTH products and their effects in practical applications in recent years.
The Canada flea, tick and heartworm products market is expected to grow at a significant CAGR during the forecast period. The market is developing due to growing awareness of preventive healthcare and demand for convenient treatment options. Recent advancements focus on broad-spectrum efficacy, improved safety profiles, and the development of natural or eco-friendly formulations, catering to consumer preferences for safer and environmentally conscious pet care solutions.
Europe Flea, Tick And Heartworm Products Market Trends
The Europe flea, tick and heartworm products industry is projected to experience growth driven by rising demand for flea, tick, and heartworm products, fueled by increasing risks of parasite transmission from pets to humans. According to 2024 data from Animal Health Europe, over 700 new parasitic infections emerged between 2009 and 2016 due to dog-to-human transmission. Additionally, approximately 128,888 Lyme disease cases were reported between 2005 and 2020, originating from tick infestations in pets, highlighting the critical need for effective preventive and treatment measures across the region.
The flea, tick and heartworm products market in Germany is expected to grow significantly over the forecast period. The market is expanding due to heightened awareness of preventive care and advancements in treatment options. For instance, in January 2025, Boehringer Ingelheim launched Frontpro, a chewable tablet for dogs that protects against fleas and ticks. Frontpro is the first over-the-counter FTH product available in Germany, offering a convenient solution for pet owners.
The UK flea, tick and heartworm products market is expected to grow significantly over the forecast period. An increasing prevalence of tick and flea infestations influences the country’s growth. According to Animal Health Europe 2024, approximately one in four cats and one in seven dogs in the UK are affected by fleas. This rising incidence is fueling demand for FTH products, including shampoos, spot-on treatments, and powders, as pet owners seek effective solutions to protect their animals from these parasites.
Asia Pacific Flea, Tick and Heartworm Products Market Trends
The Asia Pacific flea, tick and heartworm products industry is expected to grow at the fastest CAGR over the forecast period.The market is witnessing rapid growth, driven by urbanization and rising disposable incomes in countries like China and India, contributing to greater demand for pet healthcare products. In addition, advancements such as the introduction of combination treatments, such as Elanco's Credelio Quattro, a chewable tablet that protects dogs against multiple parasites, including fleas, ticks, and heartworms. These innovations, along with expanding veterinary infrastructure and rising disposable incomes, are propelling the market's expansion across the region.
The flea, tick and heartworm products market in China is witnessing new growth opportunities due to growing R&D infrastructure and increasing disposable incomes. Advancements such as combination treatments, including Elanco's Credelio Quattro chewable tablet that protects dogs against multiple parasites, are enhancing preventive care. Along with expanding veterinary infrastructure and growing consumer spending on pet health, these innovations are fueling the market’s expansion across the country.
The market for flea, tick and heartworm products in India is poised for strong growth, driven by rising pet adoption and increasing demand for preventive healthcare. According to 2024 data from Dogster, over 11% of Indian households own at least four pets. Recognizing this potential, global companies are expanding their presence through product launches and regional operations. For example, in April 2024, Boehringer Ingelheim introduced NexGard Spectra, a chewable tablet targeting internal and external parasites, following CDSCO approval.
Latin America Flea, Tick And Heartworm Products Market Trends
The growth of the flea, tick and heartworm products industry is fueled by the increasing pet ownership, which is driving higher demand for veterinary medications. Countries such as Brazil and Argentina rank among the highest globally in pet ownership per capita. For instance, 2024 data from Dogster estimates that approximately 80% of Argentina’s population has owned a pet at some point, highlighting strong market potential.
Brazil flea, tick and heartworm products market is gaining momentum, supported by increasing pet ownership, higher disposable incomes, and evolving consumer attitudes toward pet healthcare. Growing public awareness of the importance of preventing flea, tick, and heartworm infections, along with supportive government initiatives, is further expected to drive demand and expand the market in the country.
Middle East & Africa Flea, Tick and Heartworm Products Market Trends
The Middle East & Africa (MEA) flea, tick, and heartworm products market, comprising countries like South Africa, Saudi Arabia, Kuwait, and the UAE, is primarily driven by the surge in pet ownership across the region. For instance, approximately 45% of adults in South Africa own pets, reflecting the nation’s strong affinity for animals. Of these pet owners, 78% have dogs, whereas 36% keep cats. This increase is boosting pet owners’ spending on healthcare, particularly for preventive and therapeutic treatments against parasitic infections and infestations.
The South Africa flea, tick and heartworm products market held the largest revenue share of the MEA market, largely fueled by the country’s high dog ownership. According to a 2024 Dogster article, approximately 78% of pet owners in South Africa own dogs, which are the primary hosts for fleas, ticks, and heartworms. As most FTH products target these conditions in dogs, the strong dog adoption rate is expected to drive demand, creating significant market growth opportunities.
The flea, tick and heartworm products market in the UAE is experiencing growth with the rising awareness for pet health and advancements in veterinary care. Innovations such as combination treatments, including Elanco's Credelio Quattro chewable tablet, protecting dogs against multiple parasites, are enhancing preventive care. Expanding veterinary infrastructure and rising consumer spending on pet health are further fueling the regional market growth.
Key Flea, Tick and Heartworm Products Company Insights
The market is competitive due to the presence of domestic players in each country, fragmenting the market. Thus, creating an intense competition to maintain in the market. Moreover, companies and organizations are engaging heavily in activities such as research & development, product launch, and expansion of portfolio, as well as geographical presence. For instance, in April 2025, The FDA approved a label extension for Zoetis' Simparica Trio, making it the only canine combination parasiticide preventing flea tapeworms, ticks, heartworm, and intestinal worms, enhancing comprehensive parasite protection for dogs.
Key Flea, Tick and Heartworm Products Companies
The following key companies have been profiled for this study on the flea, tick, and heartworm products market.
-
Zoetis
-
Boehringer Ingelheim
-
Merck & Co. Inc.
-
Virbac
-
Elanco
-
Ceva
-
Promika, LLC
-
Sergeant's Pet Care Products, Inc.
-
ADAMS (Central Garden & Pet)
-
BioNote Inc.
-
Secure Diagnostics Ltd.
-
iNtRON Biotechnology
-
Biopanda Reagents Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Zoetis; Boehringer Ingelheim; Merck & Co., Inc.; Virbac; Elanco; Ceva; Sergeant's Pet Care Products; ADAMS (Central Garden & Pet))
- Established companies focus on expanding broad-spectrum parasite prevention portfolios by offering oral chewables, topical formulations, collars, sprays, shampoos, and combination products for flea, tick, and heartworm prevention. They invest heavily in research and development, product lifecycle management, veterinary education, direct-to-client marketing, and global regulatory approvals. Strategic acquisitions, digital pet health platforms, and partnerships with veterinary clinics further strengthen their market position.
- Market leaders benefit from trusted veterinary brands, strong clinical evidence, patented formulations, global regulatory approvals, extensive sales networks, and long-standing relationships with veterinarians. Their broad product portfolios, continuous innovation, and integrated animal health solutions enable premium pricing and high customer retention across both prescription and OTC channels.
- Established vendors face increasing competition from generic alternatives, parasite resistance concerns, regulatory scrutiny regarding product safety, rising R&D costs, and pricing pressure in mature markets. Patent expirations and evolving consumer preferences toward natural or alternative parasite control products may also limit long-term growth.
Emerging Players (Promika, LLC; BioNote Inc.; Seegene Diagnostics Ltd.; iNTRON Biotechnology; Biopanda Reagents Ltd.)
- Emerging companies focus on innovative parasite diagnostics, novel active ingredients, natural formulations, rapid diagnostic solutions, and targeted regional product launches. Many leverage contract manufacturing, distributor partnerships, online sales channels, and veterinary collaborations to increase market penetration while emphasizing affordability and differentiated product offerings.
- Emerging companies compete through faster innovation cycles, niche product development, flexible pricing strategies, specialized diagnostic capabilities, and the ability to respond quickly to changing veterinary needs. Their focus on emerging technologies and regional market requirements enables differentiation in specialized market segments.
- Emerging vendors generally have limited commercial reach, lower brand awareness, smaller sales teams, and fewer regulatory approvals than multinational competitors. Scaling manufacturing, generating clinical evidence, expanding international distribution, and competing against established veterinary brands remain key challenges.
Recent Developments
-
In September 2025, Elanco’s Credelio Quattro achieved blockbuster status, offering the broadest isoxazoline parasite protection against fleas, ticks, heartworm, and intestinal worms, marking a major advancement in comprehensive canine parasite control.
-
In July 2025, Intervet, Inc. received FDA approval for Bravecto Quantum, the first long-acting injectable for dogs, protecting against fleas and ticks for 8-12 months.
-
In January 2025, FDA expanded Zoetis’s Simparica Trio and Simparica Chewables’ labels to include Asian longhorned tick control, broadening their coverage and reinforcing their status as leading combination parasiticides for dogs. In addition, the FDA also approved a new label indication for Revolution Plus, used for the treatment of Dipylidium caninum (tapeworm) infections.
Flea, Tick and Heartworm Products Market Report Scope
Report Attribute
Details
Market size in 2025
USD 8.4 billion
Estimated market size in 2026
USD 9.1 billion
Projected market size by 2033
USD 15.2 billion
Growth rate
CAGR of 7.6% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, type, animal type, mode of delivery, parasite, care, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Oman; Qatar.
Key companies profiled
Zoetis; Boehringer Ingelheim; Merck & Co. Inc.; Virbac; Elanco; Ceva; Promika, LLC; Sergeant's Pet Care Products, Inc.; ADAMS (Central Garden & Pet); BioNote Inc.; Secure Diagnostics Ltd.; iNtRON Biotechnology; Biopanda Reagents Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Flea, Tick and Heartworm Products Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global flea, tick and heartworm products market report based on product, type, animal, mode of delivery, parasite, care, distribution channel, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Diagnostic Products
-
Test Kits
-
Consumables
-
-
Treatment Products
-
Spot on
-
Oral pills/Chewable
-
Spray
-
Liquid Solution
-
Shampoo
-
Others
-
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Prescription
-
OTC
-
-
Animal Outlook (Revenue, USD Million, 2021 - 2033)
-
Canine
-
Feline
-
Others
-
-
Mode of Delivery Outlook (Revenue, USD Million, 2021 - 2033)
-
Topical
-
Oral
-
Injectable
-
-
Parasite Outlook (Revenue, USD Million, 2021 - 2033)
-
External Parasite
-
Internal Parasite
-
-
Care Outlook (Revenue, USD Million, 2021 - 2033)
-
Preventive Care
-
Therapeutic Care
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital/Clinic Pharmacy
-
Retail Pharmacy
-
Online Pharmacy
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
UAE
-
Saudi Arabia
-
Kuwait
-
Qatar
-
Oman
-
-
Research Methodology
The flea, tick and heartworm products market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each flea, tick and heartworm products segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue Capture Definition
Diagnostic Products
Represents the revenue generated from products used to detect flea-, tick-, and heartworm-related infections and infestations in companion animals. This segment includes diagnostic tools that support early disease identification and treatment planning.
Treatment Products
Covers the market value derived from therapeutic products developed to prevent, control, or eliminate flea, tick, and heartworm infestations in animals. Demand is driven by the increasing prevalence of parasitic diseases and preventive veterinary care.
Test Kits
Includes revenue generated from rapid diagnostic kits and laboratory-based testing products used for detecting parasitic infections. These products enable timely diagnosis in veterinary clinics, hospitals, and diagnostic laboratories.
Consumables
Represents the sales generated from consumable items used during parasite diagnosis and treatment, including reagents, cartridges, sample collection materials, and laboratory accessories. Continuous testing volumes contribute to recurring demand in this segment.
Spot on
Reflects the revenue generated from topical spot-on formulations applied directly to the animal's skin for parasite prevention and treatment. These products are widely adopted due to their ease of application and broad-spectrum protection.
Oral pills/Chewable
Accounts for the market value of oral tablets and chewable formulations designed to protect against fleas, ticks, and heartworms. The segment benefits from increasing preference for convenient and palatable treatment options.
Spray
Represents the revenue earned from spray-based parasite control products applied directly to animals for immediate protection against external parasites. These products are commonly used for localized infestations and supplementary parasite management.
Liquid Solution
Covers income generated from liquid formulations administered either topically or orally to prevent or treat parasitic infestations. Product demand is supported by dosing flexibility across different animal sizes.
Shampoo
Includes the revenue generated from medicated and anti-parasitic shampoos formulated to remove and control fleas, ticks, and other external parasites. This segment also supports routine grooming and skin hygiene.
Others
Comprises revenue from other flea, tick, and heartworm management products, including collars, powders, injectable formulations, wipes, and emerging delivery systems. Product innovation continues to expand this category.
Segment - Type
Revenue Capture Definition
Prescription
Represents the market revenue generated from veterinarian-prescribed flea, tick, and heartworm products that require professional diagnosis and clinical supervision. Growth is supported by increasing veterinary visits and preventive healthcare adoption.
OTC
Covers sales generated from over-the-counter products that can be purchased without a veterinary prescription. This segment benefits from easy accessibility through retail and online channels.
Segment - Animal Type
Revenue Capture Definition
Canine
Accounts for the revenue generated from flea, tick, and heartworm products specifically intended for dogs. The segment represents a major share of the market due to the high prevalence of parasitic diseases in canine populations.
Feline
Represents the value generated from parasite prevention and treatment products developed for cats. Growing feline ownership and increasing awareness of parasite prevention continue to support market expansion.
Others
Includes revenue generated from products intended for other companion animals, such as rabbits, ferrets, and small mammals requiring parasite control. This segment addresses niche veterinary care needs.
Segment - Mode of Delivery
Revenue Capture Definition
Topical
Reflects the revenue generated from products applied externally to the skin or coat for parasite prevention and treatment. Topical formulations remain widely used because of their convenience and effectiveness against external parasites.
Oral
Covers the market value of orally administered tablets, capsules, chewables, and liquid formulations for systemic parasite protection. Increasing acceptance of long-acting oral products is supporting segment growth.
Injectable
Represents the sales generated from injectable formulations administered by veterinary professionals to provide long-duration parasite prevention or treatment. Product innovation in extended-release injectables is driving market opportunities.
Segment - Parasite
Revenue Capture Definition
External Parasite
Includes the revenue generated from products targeting external parasites such as fleas, ticks, mites, and lice. Increasing awareness of vector-borne diseases continues to support demand within this segment.
Internal Parasite
Represents the market value of products intended to prevent or treat internal parasitic infections, including heartworms and gastrointestinal worms. Growing emphasis on routine deworming and heartworm prevention contributes to market growth.
Segment - Care
Revenue Capture Definition
Preventive Care
Accounts for the revenue generated from products used to prevent flea, tick, and heartworm infestations before infection occurs. The segment is supported by increasing veterinary recommendations for year-round parasite prevention.
Therapeutic Care
Represents the sales generated from products administered for the treatment and management of existing parasitic infestations or infections. Demand is driven by rising disease incidence and improved diagnosis rates.
Segment - Distribution Channel
Revenue Capture Definition
Hospital/Clinic Pharmacy
Reflects the revenue generated through veterinary hospitals and clinic pharmacies supplying prescription and professional-use parasite control products. Veterinary recommendations significantly influence purchasing decisions in this channel.
Retail Pharmacy
Covers sales generated through retail pharmacies and pet supply stores offering both prescription and OTC parasite control products. Wide product availability and consumer accessibility support market growth.
Online Pharmacy
Represents the market value generated through online pharmacies and digital pet healthcare platforms selling flea, tick, and heartworm products. Growth is fueled by increasing e-commerce adoption, home delivery services, and subscription-based purchasing models.
Estimation Model
Bottom-Up Revenue Model
Pet Population & Parasite Incidence Model
Veterinary Prescription & Distribution Channel Model
Preventive Healthcare & Regulatory Landscape Model
- Market size is estimated by identifying leading animal health companies, veterinary pharmaceutical manufacturers, and companion animal parasite control product suppliers across major regions.
- Revenue attributable to oral medications, topical treatments, collars, injectables, sprays, shampoos, and combination parasiticides is collected from company financial reports, investor presentations, regulatory filings, and paid industry databases.
- Individual company revenues are aggregated and validated using product portfolio analysis, regional sales, pricing trends, prescription patterns, and estimated contribution of parasite control products.
- Market value is estimated by assessing companion animal population, pet ownership rates, flea, tick, and heartworm prevalence, climatic conditions, and disease burden across major countries.
- Adoption rates are evaluated using veterinary preventive care recommendations, consumer awareness, parasite seasonality, pet travel frequency, and compliance with preventive treatment schedules.
- Revenue is calculated by applying annual treatment frequency, preventive coverage rates, average treatment duration, and product utilization across different animal types.
- Market size is estimated by evaluating sales through veterinary hospitals, veterinary clinics, retail pharmacies, pet specialty stores, online pharmacies, and e-commerce platforms.
- Parameters including prescription rates, OTC availability, online pharmacy penetration, retail expansion, product accessibility, and purchasing behavior are assessed across major regions.
- Revenue potential is estimated using average selling prices, prescription compliance, repeat purchase rates, and channel-wise sales contribution.
- Market value is estimated by assessing preventive veterinary healthcare expenditure, parasite surveillance programs, regulatory approvals, product innovation, and companion animal healthcare spending.
- Product utilization is evaluated using long-acting formulations, combination therapies, resistance management strategies, veterinary guidelines, and consumer preference for broad-spectrum protection.
- Revenue is calculated by applying preventive treatment adoption rates, premium product penetration, veterinary compliance, and regulatory acceptance across major markets.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Companion Animal Parasite Prevention Landscape Assessment
Conducted a comprehensive evaluation of the companion animal parasite prevention ecosystem covering manufacturers of flea, tick, and heartworm products, veterinary clinics, pet retailers, online pharmacies, diagnostic providers, and regulatory agencies. Assessed preventive care trends, parasite prevalence, product innovation, prescription practices, and treatment adoption across major countries.
Provides a holistic view of the parasite prevention market, enabling stakeholders to identify emerging demand, regulatory developments, innovation opportunities, and future investment areas.
Preventive Product Positioning & Competitive Assessment
Evaluated leading market participants based on product portfolio diversity, active ingredient innovation, formulation technologies, prescription versus OTC presence, veterinary engagement, distribution partnerships, marketing strategies, geographic footprint, and lifecycle management initiatives. Included competitive comparison across multinational and regional companies.
Supports product positioning, competitive differentiation, acquisition screening, pricing optimization, and portfolio expansion by identifying strengths, weaknesses, and whitespace opportunities.
Veterinary Prescription & Consumer Adoption Analysis
Assessed preventive treatment adoption by evaluating veterinary prescription behavior, consumer compliance, seasonal parasite incidence, purchasing frequency, online pharmacy penetration, retail channel performance, and regional disease burden. Identified priority markets with strong preventive healthcare adoption and commercial potential.
Helps companies optimize commercialization strategies, improve market penetration, strengthen channel partnerships, and maximize revenue opportunities through targeted customer engagement.
Frequently Asked Questions About This Report
The global flea, tick and heartworm products market size was valued at USD 8.4 billion in 2025 and is estimated at USD 9.1 billion for 2026.
The global flea, tick and heartworm products market is expected to grow at a CAGR of 7.6% from 2026 to 2033, reaching USD 15.2 billion by 2033.
North America market dominated, with a revenue share of 39.3% in 2025.
Some key players operating in the flea tick and heartworm products market include Zoetis, Boehringer Ingelheim, Merck & Co. Inc, Virbac, Elanco, Ceva, Promika, LLC, Sergeant's Pet Care Products, Inc., Adams, BioNote Inc., Secure Diagnostics Ltd., iNtRON Biotechnology, and Biopanda Reagents Ltd.
Key factors that are driving the flea tick and heartworm products market growth the include growing importance of preventive care, emergence of novel FTH products, rise in spread of heartworm disease among animals, rise in awareness campaigns and increasing cases of parasitic infestations.
Asia Pacific is also the fastest-growing region over the forecast period.
The prescription segment led with a 60.6% revenue share in 2025, while the OTC is the fastest-growing segment.
The topical segment led with a 47.2% revenue share in 2025, while the injectables is the fastest-growing segment.
The treatment product segment led with a 75.8% revenue share in 2025, while the diagnostic products is the fastest-growing segment.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


