
- Home
- »
- Petrochemicals
- »
-
Food Grade Lubricants Market Size, Share Report 2026-2033GVR Report cover

Food Grade Lubricants Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product Mineral, Synthetic, Bio-Based), By Application (Food, Beverages, Pharmaceuticals, Cosmetics), By Region (North America, Europe, Asia Pacific), And Segment Forecasts
Market Size, 2025
$485.7MMarket Estimate, 2026
$485.7MMarket Forecast, 2033
$577.0MCAGR, 2026–2033
10.2%Food Grade Lubricants Market Summary
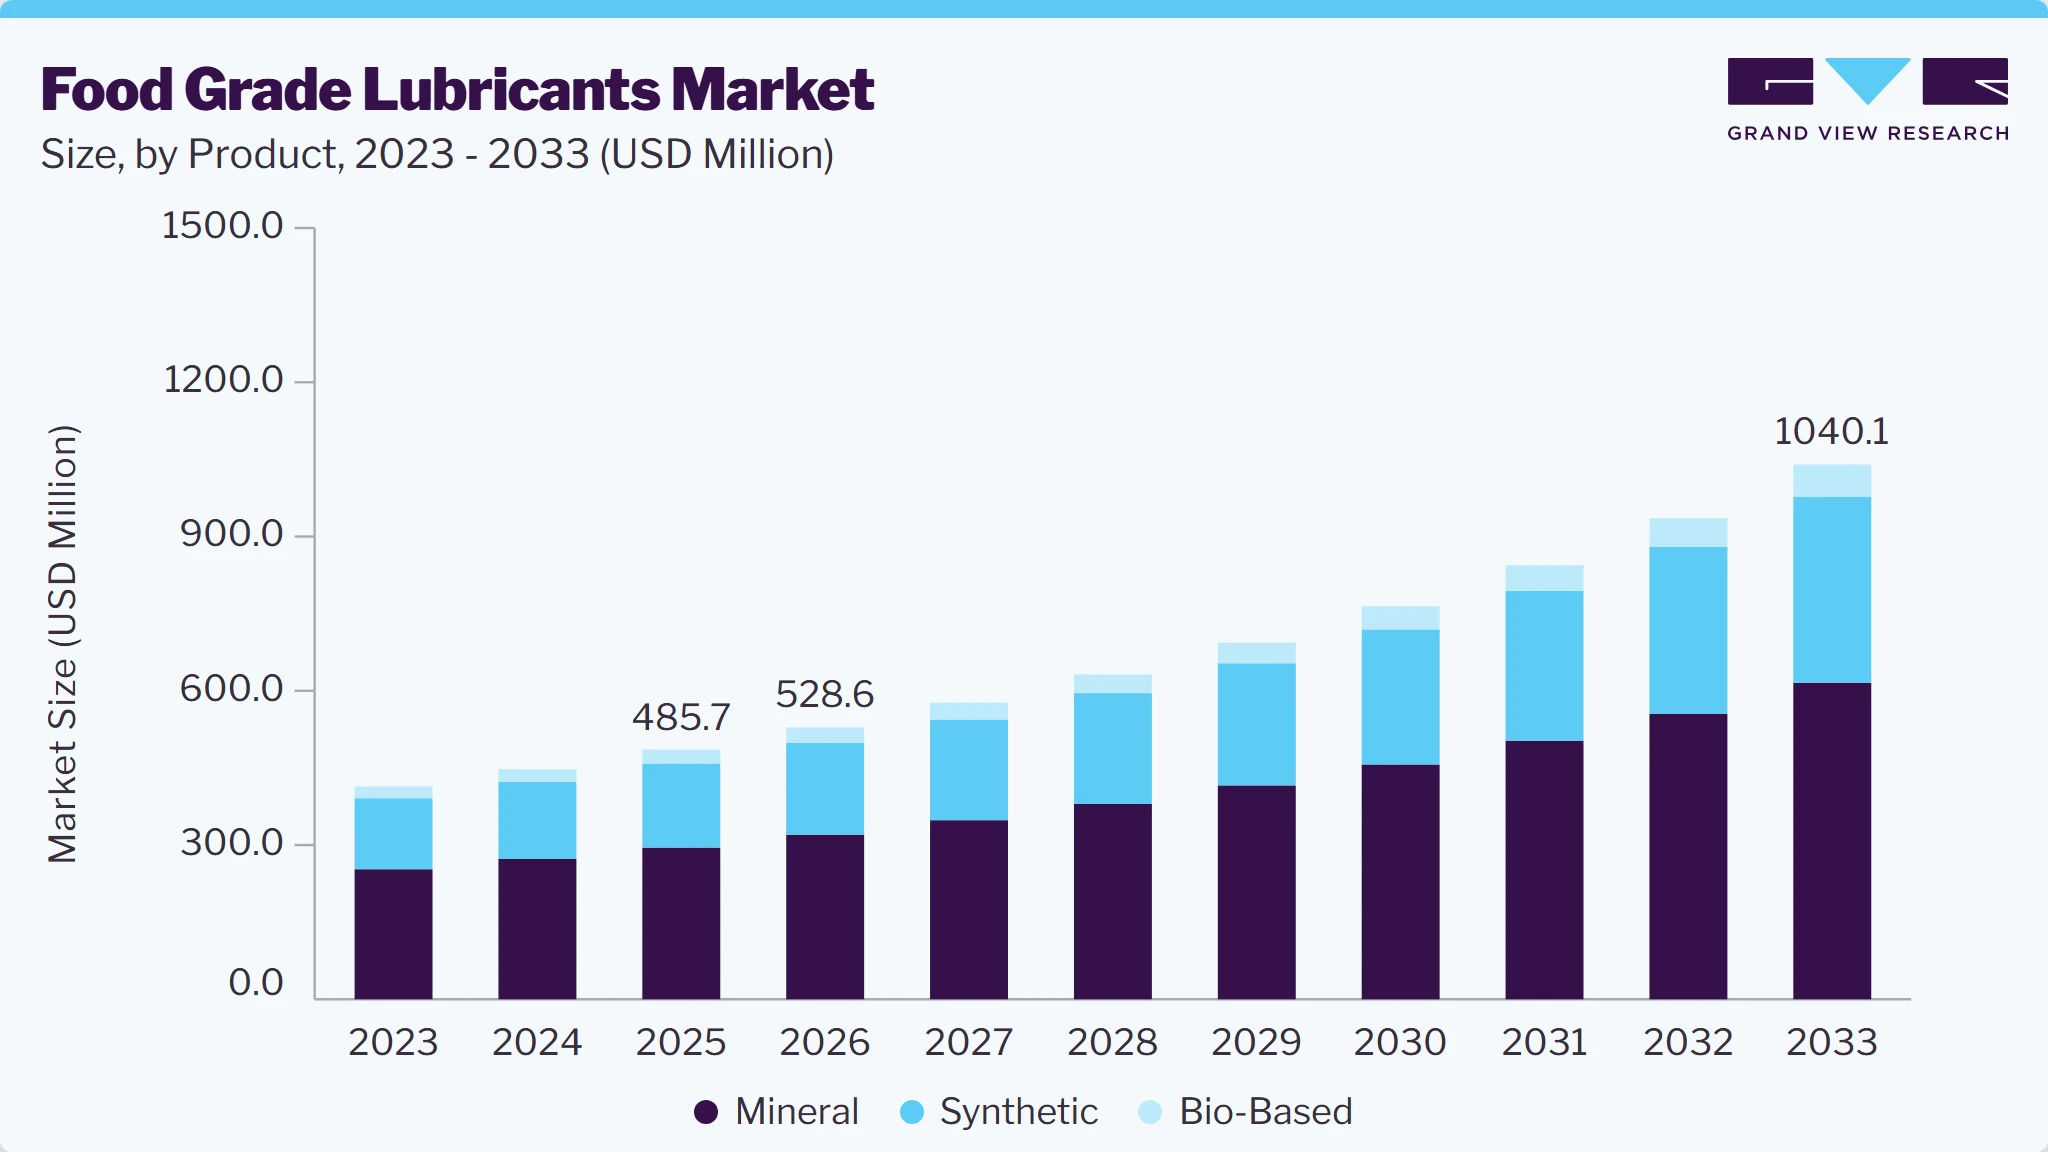
The global food grade lubricants market size was valued at USD 485.7 million in 2025 and is projected to grow from USD 528.6 million in 2026 to USD 1,040.1 million by 2033, growing at a CAGR of 10.2% from 2026 to 2033. Europe dominated the market, accounting for a revenue share of 39.8% in 2025. The global expansion of the food and beverage industry drives the market, which increases the need for lubricants that enhance equipment efficiency while adhering to safety standards. The rising consumption of processed foods further fuels demand.
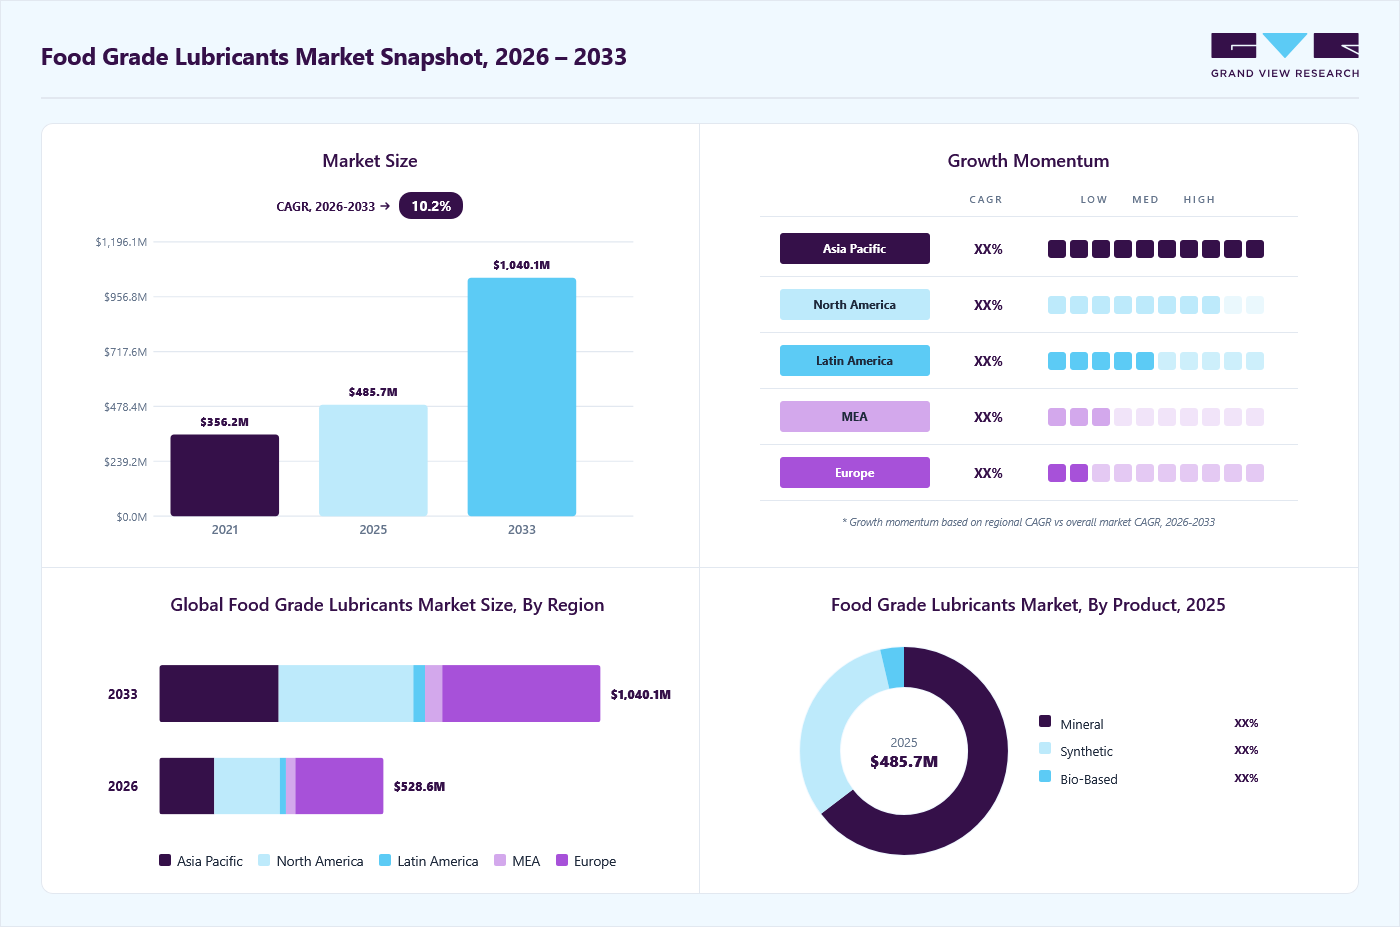 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Mineral segment accounted for the highest market share, representing 60.8% of total revenue in 2025.
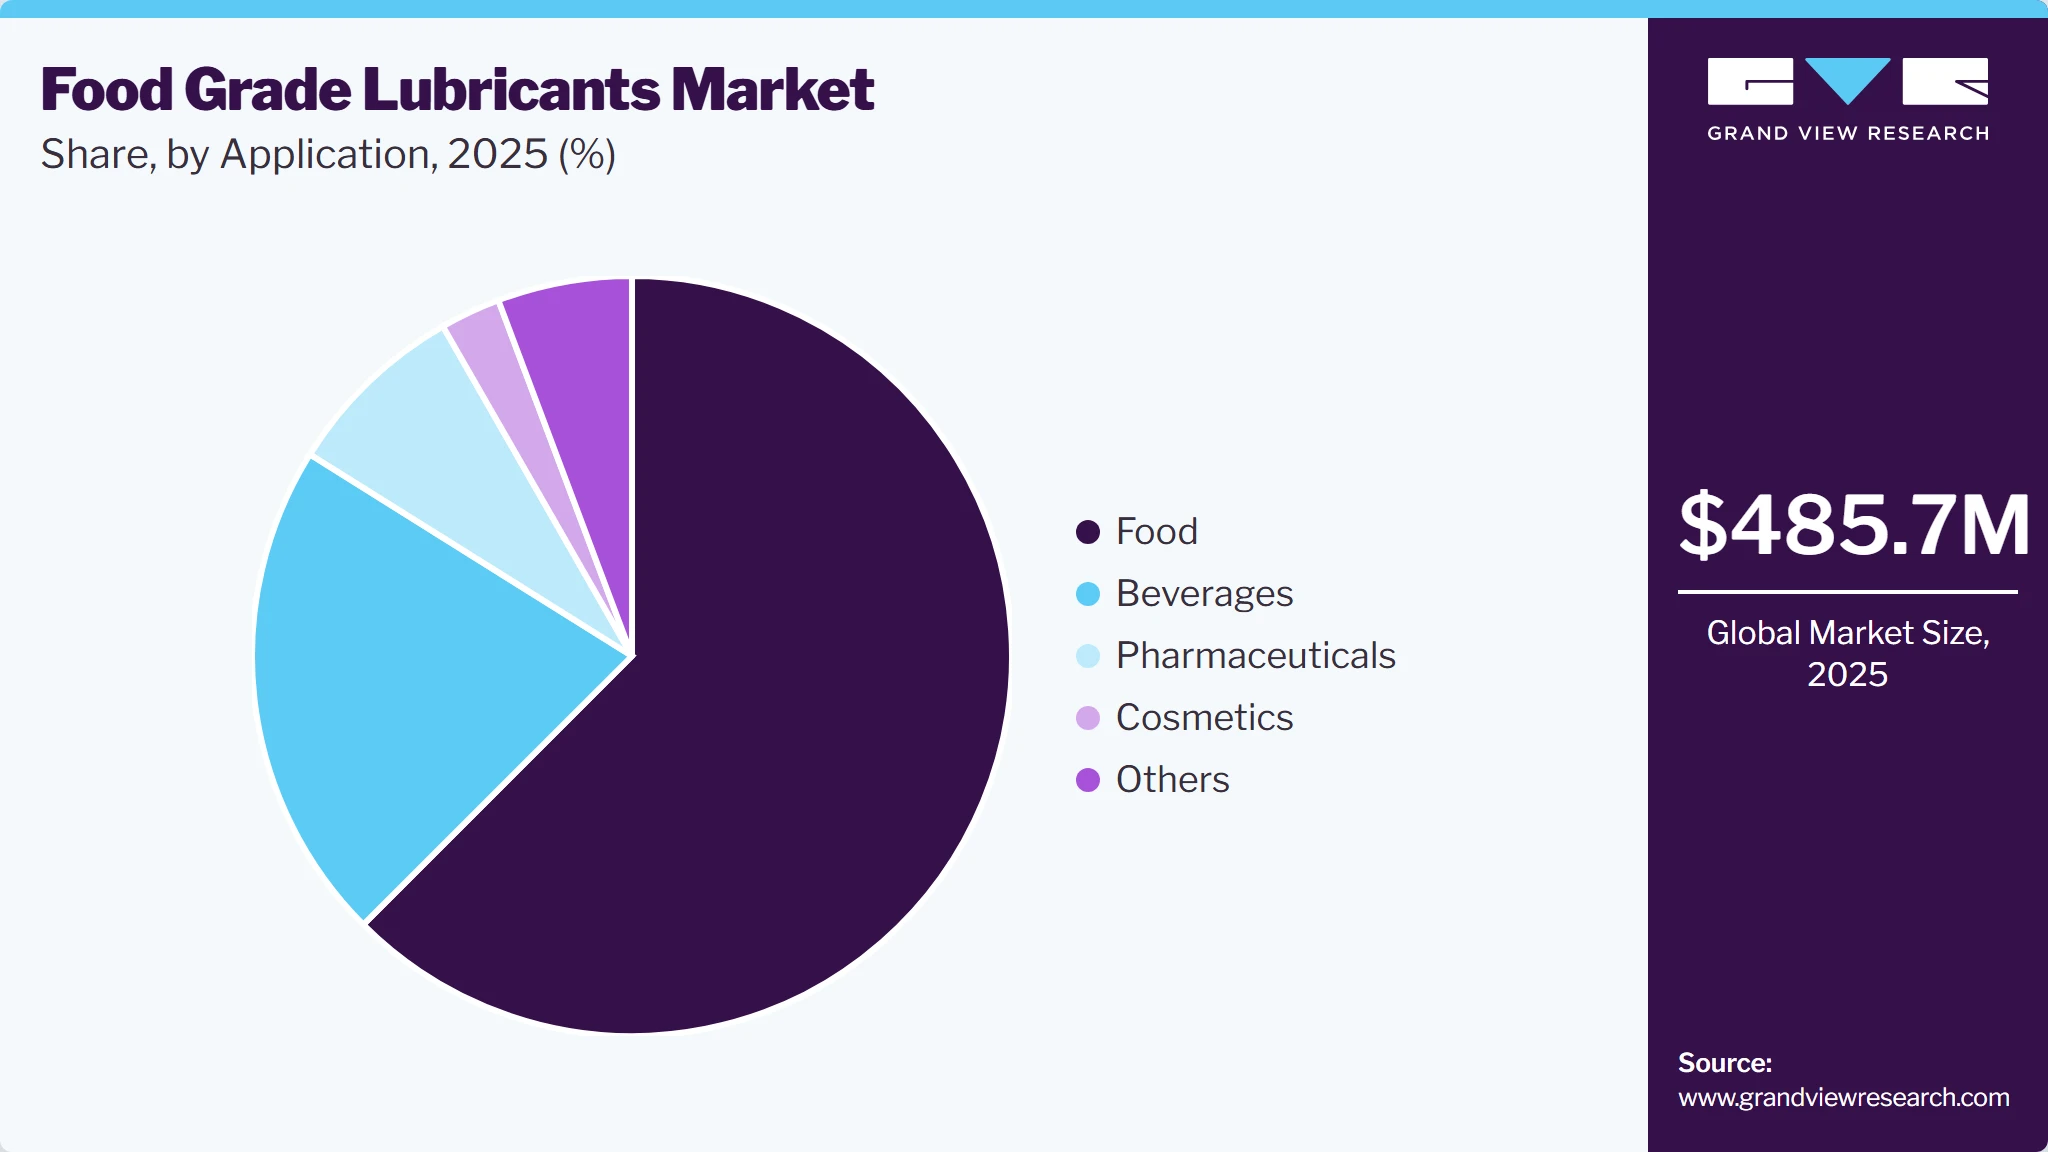
- By application: Food segment held the largest market share of 62.5% in 2025.
Regional Highlights
- Largest regional market: Europe (39.8% revenue share, 2025)
- By country: Germany held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 485.7 Million
- Estimated market size in 2026: USD 528.6 Million
- Projected market size by 2033: USD 1,040.1 Million
- CAGR (2026-2033): 10.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Technological advancements, including synthetic and biodegradable lubricants, support adoption in extreme conditions. In addition, industries such as dairy and meat processing prioritize high-quality lubricants to ensure safety and product quality.The global growth of the food and beverage industry necessitates lubricants that enhance equipment efficiency while complying with strict safety regulations. Rising demand for processed and packaged foods further boosts adoption. Technological advancements, such as synthetic and biodegradable lubricants, cater to extreme operational conditions. In addition, industries such as dairy and meat processing prioritize high-quality lubricants to ensure product safety and quality. For instance, the UK food and beverage industry contributed USD 48.4 billion in GVA and a turnover of USD 182.0 billion in 2023, with domestic sales amounting to USD 159.1 billion.
 To learn more about this report, Download Free Sample Report
The increasing consumption of processed foods drives demand for food-grade lubricants, essential for maintaining hygiene and safety in food processing machinery. These lubricants help prevent contamination and ensure compliance with food safety standards. This trend reflects the growing need for efficient and reliable machinery in the expanding food production sector. For instance, in June 2022, Northeastern University revealed that 73% of the U.S. food supply is ultra-processed.
Technological advancements, such as the development of synthetic and biodegradable lubricants, enhance the functionality of food-grade lubricants in extreme conditions. These innovations improve performance, safety, and compliance, supporting their growing adoption in the food processing industry. For instance, the CASSIDA product line from FUCHS offers high-performance lubricants tailored for the food and beverage industries. The range includes fully synthetic, semi-synthetic, and white-oil-based lubricants optimized for specific applications. Key products include CASSIDA Fluids and Greases (fully synthetic) and CASSIDA FM Lubricants (semi-synthetic and white-oil-based), designed for reliability and safety in food processing environments.
Market Dynamics
The food grade lubricants market is experiencing steady growth, driven by increasing regulatory emphasis on food safety, hygiene compliance, and operational efficiency across food processing, beverage manufacturing, pharmaceutical production, and cosmetic manufacturing facilities. As production lines become more automated and manufacturers strive to minimize contamination risks, the demand for lubricants specifically formulated for incidental food contact has increased significantly. Stringent standards established by food safety authorities and industry organizations are encouraging end users to adopt high-performance food-grade lubricants that ensure equipment reliability while meeting compliance requirements.
The growing emphasis on food safety and contamination prevention is a primary driver of the food-grade lubricants market. Food and beverage manufacturers are operating under increasingly stringent regulatory frameworks that require the use of lubricants suitable for incidental food contact in processing and packaging equipment. Compliance with food safety standards has become a critical operational requirement, prompting manufacturers to replace conventional industrial lubricants with certified food-grade alternatives. This shift is particularly evident in highly regulated industries such as dairy, meat processing, beverages, and pharmaceuticals, where maintaining product integrity is essential for protecting brand reputation and consumer trust.
The rising consumer awareness regarding food quality and safety is encouraging manufacturers to strengthen quality assurance measures throughout their production processes. Food-grade lubricants help minimize contamination risks while supporting consistent equipment performance and operational reliability. As companies continue to prioritize compliance, traceability, and risk management, the adoption of specialized lubricants is expected to increase across both established and emerging food manufacturing markets.
One of the key restraints affecting the food-grade lubricants market is the relatively higher cost associated with specialized formulations and certification requirements. Food-grade lubricants are developed using carefully selected base oils and additives that comply with stringent safety regulations, resulting in higher production costs than conventional industrial lubricants. For small and medium-sized manufacturers operating under budget constraints, the premium pricing of these products can limit adoption, particularly in cost-sensitive markets. Fluctuations in raw material prices, particularly for synthetic base oils and specialty additives, can further impact product pricing and profit margins. In some developing regions, limited awareness regarding the long-term benefits of food grade lubricants and the availability of lower-cost conventional alternatives may also slow market penetration.
Emerging economies present substantial growth opportunities for food-grade lubricant manufacturers due to the rapid expansion of food processing, beverage production, pharmaceutical manufacturing, and personal care industries. Rising disposable incomes, population growth, and evolving consumer preferences are encouraging investments in modern production facilities equipped with advanced machinery and automation technologies. These developments are increasing the need for specialized lubricants that support operational efficiency while meeting food safety and quality standards. As industrialization and infrastructure development continue to progress across the Asia Pacific, Latin America, and parts of the Middle East and Africa, suppliers are expected to benefit from expanding customer bases and increasing product penetration in these high-growth markets.
Analyst Perspective
The food grade lubricants market is driven by increasing regulatory scrutiny surrounding food safety, contamination prevention, and equipment reliability across food and beverage processing industries. Rising automation in manufacturing facilities is accelerating demand for high-performance lubrication solutions that enhance operational efficiency and reduce maintenance downtime. Synthetic and bio-based lubricants are gaining traction as end users prioritize sustainability, longer service intervals, and improved equipment performance. Emerging economies present significant growth opportunities due to expanding food processing and pharmaceutical manufacturing sectors. While higher product costs remain a challenge, ongoing investments in food safety compliance and advanced processing technologies are expected to support long-term market expansion.
Product Insights
Based on product, the mineral segment accounted for the highest market share, representing 60.8% of total revenue in 2025. The growing demand for high-purity, food-grade lubricants to meet stringent safety standards is a key driving factor for the mineral food-grade lubricants market. In addition, expanding production facilities in key regions, such as Asia, supports the increasing market need for reliable and high-quality lubricants in the food and beverage industry. For instance, in February 2024, CLG (Chevron Lummus Global) launched a new white oil processing facility in China designed to produce high-purity white oils. With a capacity of 200,000 metric tons per year, this facility was expected to cater to the food-grade lubricant market, providing products that meet stringent safety standards for the food and beverage industry.
The bio-based segment is expected to grow at the fastest CAGR of 10.4% over the forecast period, which can be attributed to the growing demand for sustainable, non-toxic, and eco-friendly lubricants that ensure food safety while offering high performance and biodegradability in food and beverage processing machinery. For instance, Bio-Food Grade Gear Oils are bio-based, odorless, and tasteless, making them safe for incidental food contact in food and beverage machinery. These oils are made from renewable agricultural resources and offer excellent performance, biodegradability, and sustainability.
Application Insights
By application, food segment held a dominant position, contributing 62.5% of total revenue in 2025. It comprises bakery, confectionery, dairy, meat, poultry & seafood, sauces & dressings, and others. The segment growth can be attributed to the growing demand for high-performance, food-safe lubricants that enhance equipment efficiency, reduce maintenance, and ensure compliance with food safety standards in food processing environments. For instance, in February 2024, Metalube launched its next-generation Metachain Food Grade chain oils, NSF registered for food-safe applications. The product range includes ester-based oils with varying viscosities (FG-30, FG-35, FG-40, FG-45) designed for equipment such as bakery ovens and conveyors. These oils enhance thermal stability, reduce deposits, and offer optimized performance. The oils are suitable for both food-contact and non-food-contact areas, meeting high standards for food safety in food processing environments.
 To learn more about this report, Download Free Sample Report
The beverages segment is expected to register the fastest CAGR of 10.1% during the forecast period. The segment consists of carbonated soft drinks, fruit beverages, sports drinks, alcoholic beverages, and others. The driving factors for the segment include the need for efficient lubrication solutions that ensure the smooth operation of beverage processing equipment while maintaining strict food safety standards. The demand for high-performance lubricants that reduce wear extend equipment life, and minimize contamination risks in food and beverage production lines contributes to market growth.
Regional Insights
North America food grade lubricants market held a significant market share in 2025, which can be attributed to the increasing demand for high performance, extended fluid life, and regulatory compliance for safe use in food processing applications where incidental food contact may occur. For instance, in January 2022, Petro-Canada (Suncor Energy Inc.) expanded its food-grade lubricant line by introducing the PURITY FG Synthetic Compressor Fluid, designed for food processing applications. This synthetic PAO-based product offers superior performance with enhanced thermal stability, extended fluid life, and resistance to wear and oxidation. It is NSF H1 registered and compliant with FDA regulations, ensuring safe use in environments where incidental food contact may occur. The product suits various applications, including compressors and gearboxes in food processing plants.
Europe Food Grade Lubricants Market Trends
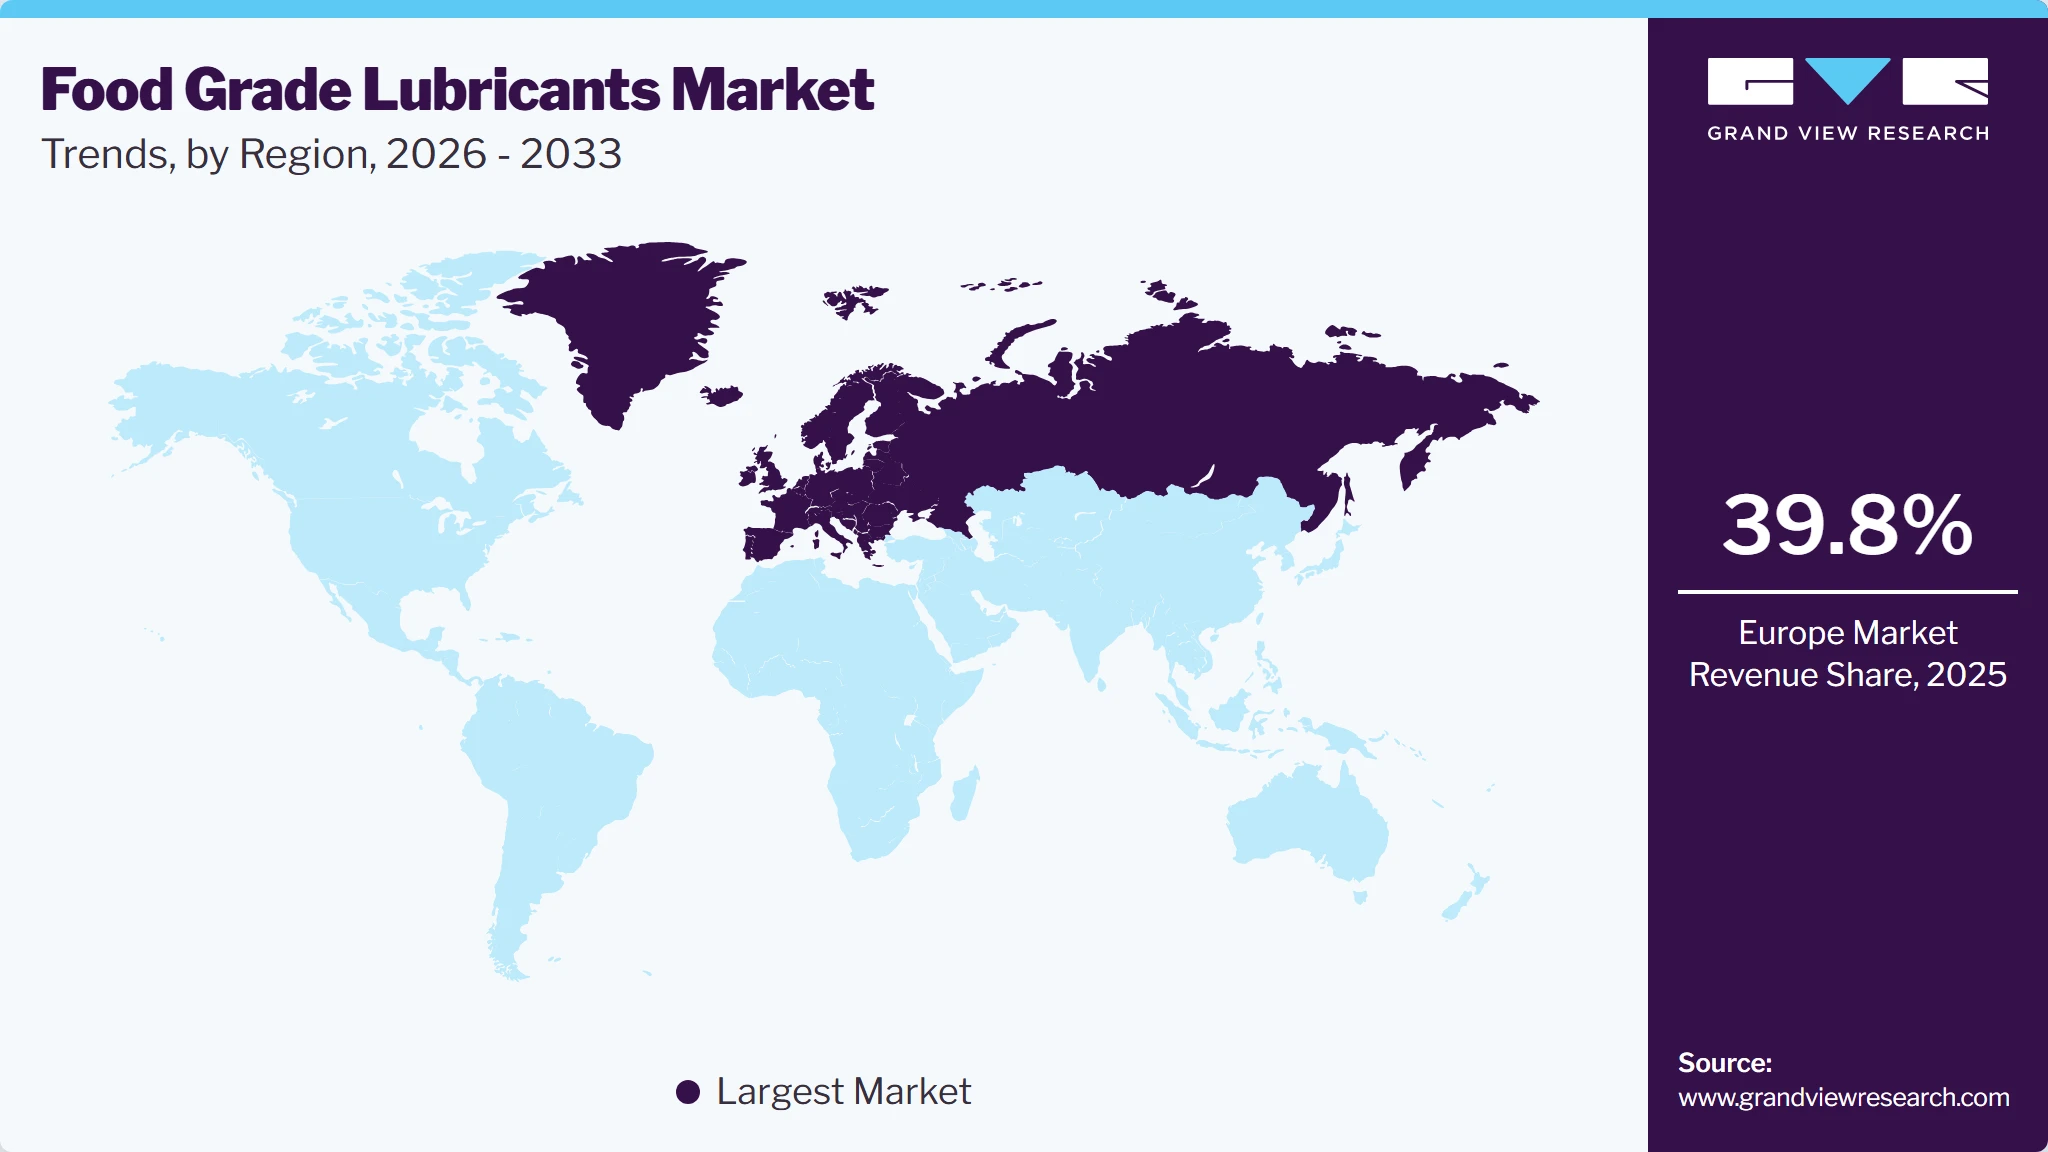
Europe dominated the food grade lubricants market with the highest revenue share of 39.8% in 2025, which can be attributed to the significant size and growth of the food and drink industry. This industry employs millions and generates substantial turnover, leading to the increased demand for high-performance lubricants that ensure safety and efficiency in manufacturing processes. For instance, in 2022, the EU food and drink industry generated a turnover of USD 1.2 trillion and added USD 242.9 billion in value, establishing itself as one of the largest manufacturing sectors in the region.
 To learn more about this report, Download Free Sample Report
Germany accounted for 25.2% of the European food grade lubricants market in 2025 and is expected to grow at the fastest CAGR over the forecast period owing to the increasing investment in manufacturing high-performance lubricants. In May 2024, Klüber Lubrication (Freudenberg SE) announced an investment of USD 16.8 million to expand its production facility in Mysore, India. The investment was expected to enhance the company's capacity to manufacture high-performance lubricants, including food-grade variants.
Asia Pacific Food Grade Lubricants Market Trends
The Asia Pacific food grade lubricants market is anticipated to grow at a CAGR of 11.1% over the forecast period, which can be attributed to the growing focus on sustainability and energy efficiency in manufacturing processes, which aligns with the increasing demand for environmentally conscious lubricants in the food industry. For instance, in May 2024, ENEOS Corporation, an energy and lubricants company, established a pilot plant to produce refined base oils in Japan. The company aims to produce a significant volume of refined oil that adheres to industry standards, contributing to energy efficiency and environmental conservation efforts within the lubricants market.
The Japan food grade lubricants market is expected to grow rapidly in the coming years due to strict regulatory standards, such as NSF H1 certification, ensuring high-quality lubricants for safe food processing. In addition, the growing focus on sustainability and energy-efficient manufacturing processes, exemplified by companies such as ENEOS, boosts demand for eco-friendly lubricants.
The China food grade lubricants market held a substantial market share in 2025 owing to the growth of the food processing industry, where increasing demand for safe and efficient lubricants is essential for improving productivity and meeting hygiene standards. Rising health and hygiene awareness among consumers has also prompted manufacturers to invest in high-quality, contamination-free lubricants.
Key Food Grade Lubricants Company Insights
Some of the key companies operating in the food grade lubricants market include Exxon Mobil Corporation, CITGO Petroleum Corporation, FUCHS, TotalEnergies, and others. Organizations are focusing on increasing their customer base to gain a competitive edge in the industry. Therefore, key players are taking several strategic initiatives, such as mergers and acquisitions and partnerships with other major companies.
-
Exxon Mobil Corporation is a major integrated oil and gas company that produces, explores, and discovers crude oil, natural gas, and liquids. It also refines crude oil, manufactures lubricants, and produces various petrochemicals, including plastics and specialty products. The company operates a vast network of manufacturing plants, transportation systems, and distribution centers globally.
-
FUCHS is an independent lubricant manufacturer that develops, produces, and markets a wide range of lubricants and specialty products globally. Its portfolio includes automotive and industrial lubricants, metalworking fluids, and solutions for niche applications, catering to automotive, aerospace, construction, food, and agriculture industries.
Key Food Grade Lubricants Companies:
The following key companies have been profiled for this study on the food grade lubricants market.
-
Exxon Mobil Corporation
-
CITGO Petroleum Corporation
-
FUCHS
-
TotalEnergies
-
Petro-Canada (Suncor Energy Inc.)
-
Klüber Lubrication (Freudenberg SE)
-
SKF
-
LANXESS
-
JAX Incorporated
-
Calumet, Inc.
-
Shell plc
-
Chevron Corporation
-
Clearco Products Co, Inc.
-
CONDAT
-
Dow
-
ELBA LUBRICAITON INC USA
-
Engen Petroleum LTD
-
Matrix Specialty Lubricants
-
The Chemours Company
-
The Lubrizol Corporation
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Exxon Mobil Corporation, CITGO Petroleum Corporation, FUCHS, TotalEnergies, Petro-Canada (Suncor Energy Inc.), Klüber Lubrication (Freudenberg SE), SKF, LANXESS, Shell plc, Chevron Corporation, Dow, The Chemours Company, The Lubrizol Corporation, Calumet, Inc., JAX Incorporated)
- Focus on continuous product innovation and development of high-performance synthetic and food-safe lubricant formulations.
- Leverage global manufacturing footprints and integrated supply chains to ensure consistent product availability.
- Maintain compliance with international food safety certifications and regulatory standards to strengthen customer trust.
- Expand market presence through strategic partnerships, distributor networks, and technical service support for large food and beverage manufacturers.
- Strong brand recognition and long-standing relationships with multinational food, beverage, and pharmaceutical companies.
- Extensive R&D capabilities enabling the development of specialized lubricants for diverse processing environments.
- Broad product portfolios covering mineral, synthetic, and bio-based food grade lubricant solutions.
- Global distribution networks and technical expertise facilitate rapid customer support and market penetration.
- Large organizational structures can reduce flexibility and slow response times to niche customer requirements.
- Higher operational and compliance costs compared to smaller regional competitors.
- Dependence on mature markets may limit growth potential in certain regions.
- Premium pricing strategies may reduce competitiveness in highly price-sensitive markets.
Emerging Players (Clearco Products Co., Inc., CONDAT, ELBA Lubrication Inc. USA, Engen Petroleum Ltd, Matrix Specialty Lubricants)
- Focus on niche applications and customized lubrication solutions tailored to specific customer requirements.
- Target regional markets and underserved customer segments to establish market presence.
- Compete through flexible manufacturing and faster product development cycles.
- Invest in specialty formulations and sustainable lubricant technologies to differentiate offerings.
- Greater agility in responding to evolving customer demands and regulatory changes.
- Ability to provide customized products and personalized technical support.
- Strong focus on specialized applications where larger competitors may have limited attention.
- Competitive pricing strategies that appeal to small and medium-sized manufacturers
- Limited geographic presence and distribution capabilities compared to established multinational companies.
- Lower brand recognition and customer trust in highly regulated industries.
- Restricted financial resources for large-scale R&D, acquisitions, and capacity expansions.
- Greater vulnerability to raw material price fluctuations and supply chain disruptions due to smaller procurement volumes.
Recent Developments
-
In September 2024, Petro-Canada's PURITY FG SEAMER-E Fluid was recognized by PneumaticScaleAngelus, an OEM for can seamer machines, for several high-speed lubrication seaming units. This food-grade lubricant complies with strict safety standards such as NSF H1 certification and FDA regulations and fits into HACCP and GMP plans, ensuring suitability for incidental food contact. The fluid offers benefits such as extended stability, excellent load capacity, and corrosion resistance, making it a reliable choice for food processing maintenance protocols.
-
In October 2023, The Lubrizol Corporation announced the launch of Carbopol Polymers for Nutraceuticals, which was approved for EU food-grade applications. These polymers allow manufacturers to innovate by producing smaller, easier-to-digest tablets while offering multifunctional benefits such as sustained release and stable suspension of active ingredients.
Food Grade Lubricants Market Report Scope
Report Attribute
Details
Market size in 2025
USD 485.7 million
Estimated market size in 2026
USD 528.6 million
Projected market size by 2033
USD 1,040.1 million
Growth rate
CAGR of 10.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/million, Volume in Kilotons and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Russia; China; Japan; India; South Korea; Southeast Asia; Brazil; Argentina; Colombia; Peru; Saudi Arabia; South Africa
Key companies profiled
Exxon Mobil Corporation; CITGO Petroleum Corporation; FUCHS; TotalEnergies; Petro-Canada (Suncor Energy Inc.); Klüber Lubrication (Freudenberg SE); SKF; LANXESS; JAX Incorporated; Calumet, Inc.; Shell plc; Chevron Corporation; Clearco Products Co, Inc.; CONDAT; Dow; ELBA LUBRICAITON INC USA; Engen Petroleum LTD; Matrix Specialty Lubricants; The Chemours Company; The Lubrizol Corporation
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Food Grade Lubricants Market Report Segmentation
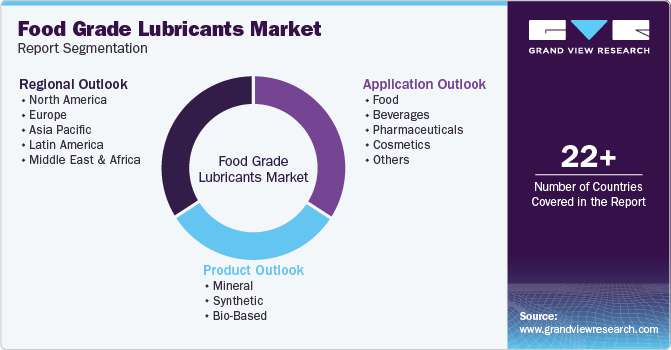
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global food grade lubricants market report based on product, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Mineral
-
Synthetic
-
Bio-Based
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Food
-
Bakery
-
Confectionery
-
Dairy
-
Meat, Poultry, & Seafood
-
Sauces & Dressings
-
Others
-
-
Beverages
-
Carbonated Soft Drinks
-
Fruit Beverages
-
Sports Drinks
-
Alcoholic Beverages
-
Others
-
-
Pharmaceuticals
-
Cosmetics
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Russia
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Southeast Asia
-
-
Latin America
-
Brazil
-
Argentina
-
Colombia
-
Peru
-
-
Middle East and Africa (MEA)
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The food grade lubricants market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each food grade lubricants segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Mineral
Revenue is generated through the sale of mineral oil-based food grade lubricants used in food processing, packaging, and handling equipment. Their cost-effectiveness, broad compatibility with industrial machinery, and compliance with food safety standards support widespread adoption across food and beverage manufacturing facilities.
Synthetic
Revenue is derived from synthetic food grade lubricants utilized in high-performance applications requiring superior thermal stability, oxidation resistance, and extended service intervals. Demand is driven by increasing automation in food processing plants and the need to improve equipment efficiency while minimizing maintenance downtime.
Bio-Based
Revenue is generated through the commercialization of bio-based food grade lubricants formulated from renewable raw materials. Growing emphasis on sustainability, environmental compliance, and the adoption of eco-friendly manufacturing practices is supporting demand across food, beverage, pharmaceutical, and cosmetic production facilities.
Segment - Application
Revenue capture definition
Food
Revenue capture is supported by the use of food grade lubricants in food processing equipment, conveyors, mixers, ovens, and packaging machinery. Demand is driven by stringent food safety regulations, contamination prevention requirements, and increasing production of processed and packaged food products.
Beverages
Revenue is generated from the application of food grade lubricants in beverage manufacturing and bottling operations, including filling lines, conveyors, pumps, and packaging equipment. Rising consumption of soft drinks, alcoholic beverages, functional beverages, and packaged drinks supports market growth.
Pharmaceuticals
Revenue is derived from the use of food grade lubricants in pharmaceutical manufacturing equipment where high purity, contamination control, and regulatory compliance are critical. Growth is supported by expanding pharmaceutical production and increasing investments in advanced manufacturing facilities.
Cosmetics
Revenue is generated through the utilization of food grade lubricants in cosmetic production machinery and processing systems requiring safe and non-contaminating lubrication solutions. Growing demand for personal care and beauty products, coupled with stringent quality standards, supports segment expansion.
Other Applications
Revenue is supported by the adoption of food grade lubricants in animal feed processing, nutraceutical manufacturing, packaging operations, and other industrial applications requiring incidental food-contact compliance. Expanding awareness of equipment reliability and workplace safety contributes to segment growth.
Estimation Model
Layer Name
Key Question
Description
Raw Material & Production Layer
What forms the supply base?
Identify the global production of food grade lubricants manufactured from mineral oils, synthetic base oils, and bio-based feedstocks used in food-safe lubrication applications. Evaluate the availability of key raw materials including white mineral oils, polyalphaolefins (PAOs), synthetic esters, vegetable oils, performance additives, and thickening agents required for food grade lubricant production. Assess refining processes, formulation technologies, certification requirements, production capacities, supply chain dynamics, and major manufacturing hubs that support the supply of food grade lubricants for food processing, beverage production, pharmaceutical manufacturing, cosmetic production, and other industrial applications requiring incidental food-contact compliance.
Application Adoption Layer
Where are food grade lubricants consumed?
Assess the allocation of food grade lubricants across major end-use sectors including food processing, beverages, pharmaceuticals, cosmetics, and other industrial applications. Demand patterns are influenced by stringent food safety regulations, increasing automation in processing facilities, contamination prevention requirements, growing packaged food and beverage consumption, expansion of pharmaceutical manufacturing, and rising emphasis on equipment reliability and operational efficiency
Consumption Intensity Layer
How much food grade lubricants are utilized?
Analyze food grade lubricant consumption volumes across end-use industries by evaluating lubrication requirements, equipment density, maintenance schedules, production capacities, and operating conditions. This includes applications in conveyors, mixers, filling equipment, packaging machinery, pumps, compressors, ovens, refrigeration systems, pharmaceutical processing equipment, and cosmetic manufacturing systems. The layer determines annual demand intensity across application categories, lubricant types, facility sizes, and regional markets.
Revenue Layer
How is market revenue generated?
Market revenue is generated through the production and sale of mineral, synthetic, and bio-based food grade lubricants formulated for food-safe industrial applications. Revenue growth is influenced by product performance, regulatory compliance, certification standards, equipment maintenance requirements, technological advancements in lubricant formulations, increasing adoption of synthetic and sustainable lubricants, and growing demand from food processing, beverage manufacturing, pharmaceutical production, cosmetic manufacturing, and other industries requiring high-purity lubrication solutions.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
The study delivers detailed country-level analysis across major food grade lubricants production and consumption markets including the U.S., Canada, Germany, France, the U.K., Italy, China, India, Japan, South Korea, Brazil, Mexico, Australia, and other key regions. The assessment covers lubricant manufacturing capacities, raw material availability (mineral oils, synthetic base oils, bio-based feedstocks), trade dynamics, regulatory frameworks, food safety compliance requirements, and demand outlook across food processing, beverages, pharmaceuticals, cosmetics, and other industrial applications.
Enables stakeholders to identify high-growth regional markets, evaluate supply-demand dynamics, understand regulatory requirements, assess raw material sourcing opportunities, and prioritize investments in countries experiencing growth in food processing, beverage manufacturing, pharmaceutical production, and industrial automation.
Trade Assessment
The report delivers comprehensive historical trade analysis covering food grade lubricant imports, exports, major producing and consuming countries, trade flows, supply chain networks, pricing trends, and evolving market developments influencing product availability and competitiveness. The assessment further evaluates regional production concentration, feedstock sourcing patterns, certification requirements, and cross-border supply dependencies affecting lubricant distribution.
Provides valuable insights into sourcing strategies, export opportunities, procurement risks, and international trade patterns, enabling companies to optimize supply chains, strengthen market positioning, diversify supplier networks, and mitigate disruptions associated with raw material volatility, regulatory changes, and logistics constraints.
Opportunity Assessment
The study delivers detailed assessment of growth opportunities across food processing, beverage manufacturing, pharmaceuticals, cosmetics, packaging operations, and other industrial applications utilizing food grade lubricants. The analysis further evaluates opportunities arising from increasing food safety regulations, rising automation in manufacturing facilities, growing demand for synthetic and bio-based lubricants, sustainability initiatives, and expansion of food and pharmaceutical production capacities in emerging economies.
Helps companies identify high-potential investment areas, assess long-term demand prospects, align product innovation and expansion strategies with evolving regulatory and operational requirements, and capitalize on emerging opportunities across food-safe lubrication, sustainable manufacturing, and advanced industrial processing applications.
Frequently Asked Questions About This Report
Europe dominated with a share of 39.8% in 2025.
Key Players in the food grade lubricants market are Exxon Mobil Corporation; CITGO Petroleum Corporation; FUCHS; TotalEnergies; Petro-Canada (Suncor Energy Inc.); Klüber Lubrication (Freudenberg SE); SKF; LANXESS; JAX Incorporated; Calumet, Inc.; Shell plc and others.
Mineral segment accounted for the highest market share, representing 60.8% of total revenue in 2025 while bio-based segment is expected to be the fastest-growing market.
The global food grade lubricants market is expected to grow at a CAGR of 10.2% from 2026 to 2033, reaching USD 1,040.1 million by 2033.
The food grade lubricants market is primarily driven by stringent food safety regulations, increasing automation in food and beverage processing facilities, and the growing need to prevent product contamination during manufacturing.
The global food grade lubricants market size was valued at USD 485.7 million in 2025 and is estimated at USD 528.6 million in 2026.
Food held a dominant position, contributing 62.5% of total revenue in 2025 and beverages segment is second fastest growing market
About the Author(s)
Petrochemicals Research Team
Bulk Chemicals · PetrochemicalsThis report was authored by the petrochemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the petrochemicals segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


