
- Home
- »
- Medical Imaging
- »
-
Forensic Imaging Market Size And Share Report, 2026-2033GVR Report cover
![Forensic Imaging Market (2026 - 2033)Report]()
Forensic Imaging Market (2026 - 2033)
Size, Share & Trends Analysis Report By Modality (X-ray, CT), By Application (Death Investigations, Clinical studies), By End-use (Forensic Institutes, Hospitals), By Region, And Segment Forecasts
Market Size, 2025
$102.9MMarket Estimate, 2026
$113.5MMarket Forecast, 2033
$228.5MCAGR, 2026–2033
10.5%Forensic Imaging Market Summary
The forensic imaging market size was valued at USD 102.9 million in 2025 and is projected to grow from USD 113.5 million in 2026 to USD 228.5 million by 2033, at a CAGR of 10.5% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 36.6% in 2025. Increasing preference for virtopsy or virtual autopsy over traditional autopsy methods is one of the major drivers for market growth.

Key Market Trends & Insights
- By modality: CT segment led the market with the largest revenue share of 48.0% in 2025.
- By application: Death investigations segment led the market with the largest revenue share of 75.7% in 2025.
- By end use: Forensic institutes segment led the market with the largest revenue share of 62.9% in 2025.
Regional Highlights
- Largest regional market: North America (36.6% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 102.9 Million
- Estimated market size in 2026: USD 113.5 Million
- Projected market size by 2033: USD 228.5 Million
- CAGR (2026-2033): 10.5%
In addition, increasing awareness regarding the value of virtual autopsy as an alternative or supplement to the traditional “body opening” autopsy has boosted the market growth. Furthermore, integration with artificial intelligence and expanding applications of the imaging modalities in the identification of the deceased and matching of severed body parts is expected to open new avenues of market growth. Forensic imaging is the process of producing an exact, copy of digital storage media, such as hard drives or flash drives, to preserve its contents for analysis in criminal investigations. This technique ensures that all data, including deleted files and unallocated space, is captured without altering the original evidence. Forensic imaging is critical in maintaining data integrity, allowing investigators to analyze the copied information while safeguarding the original device from potential changes or damage.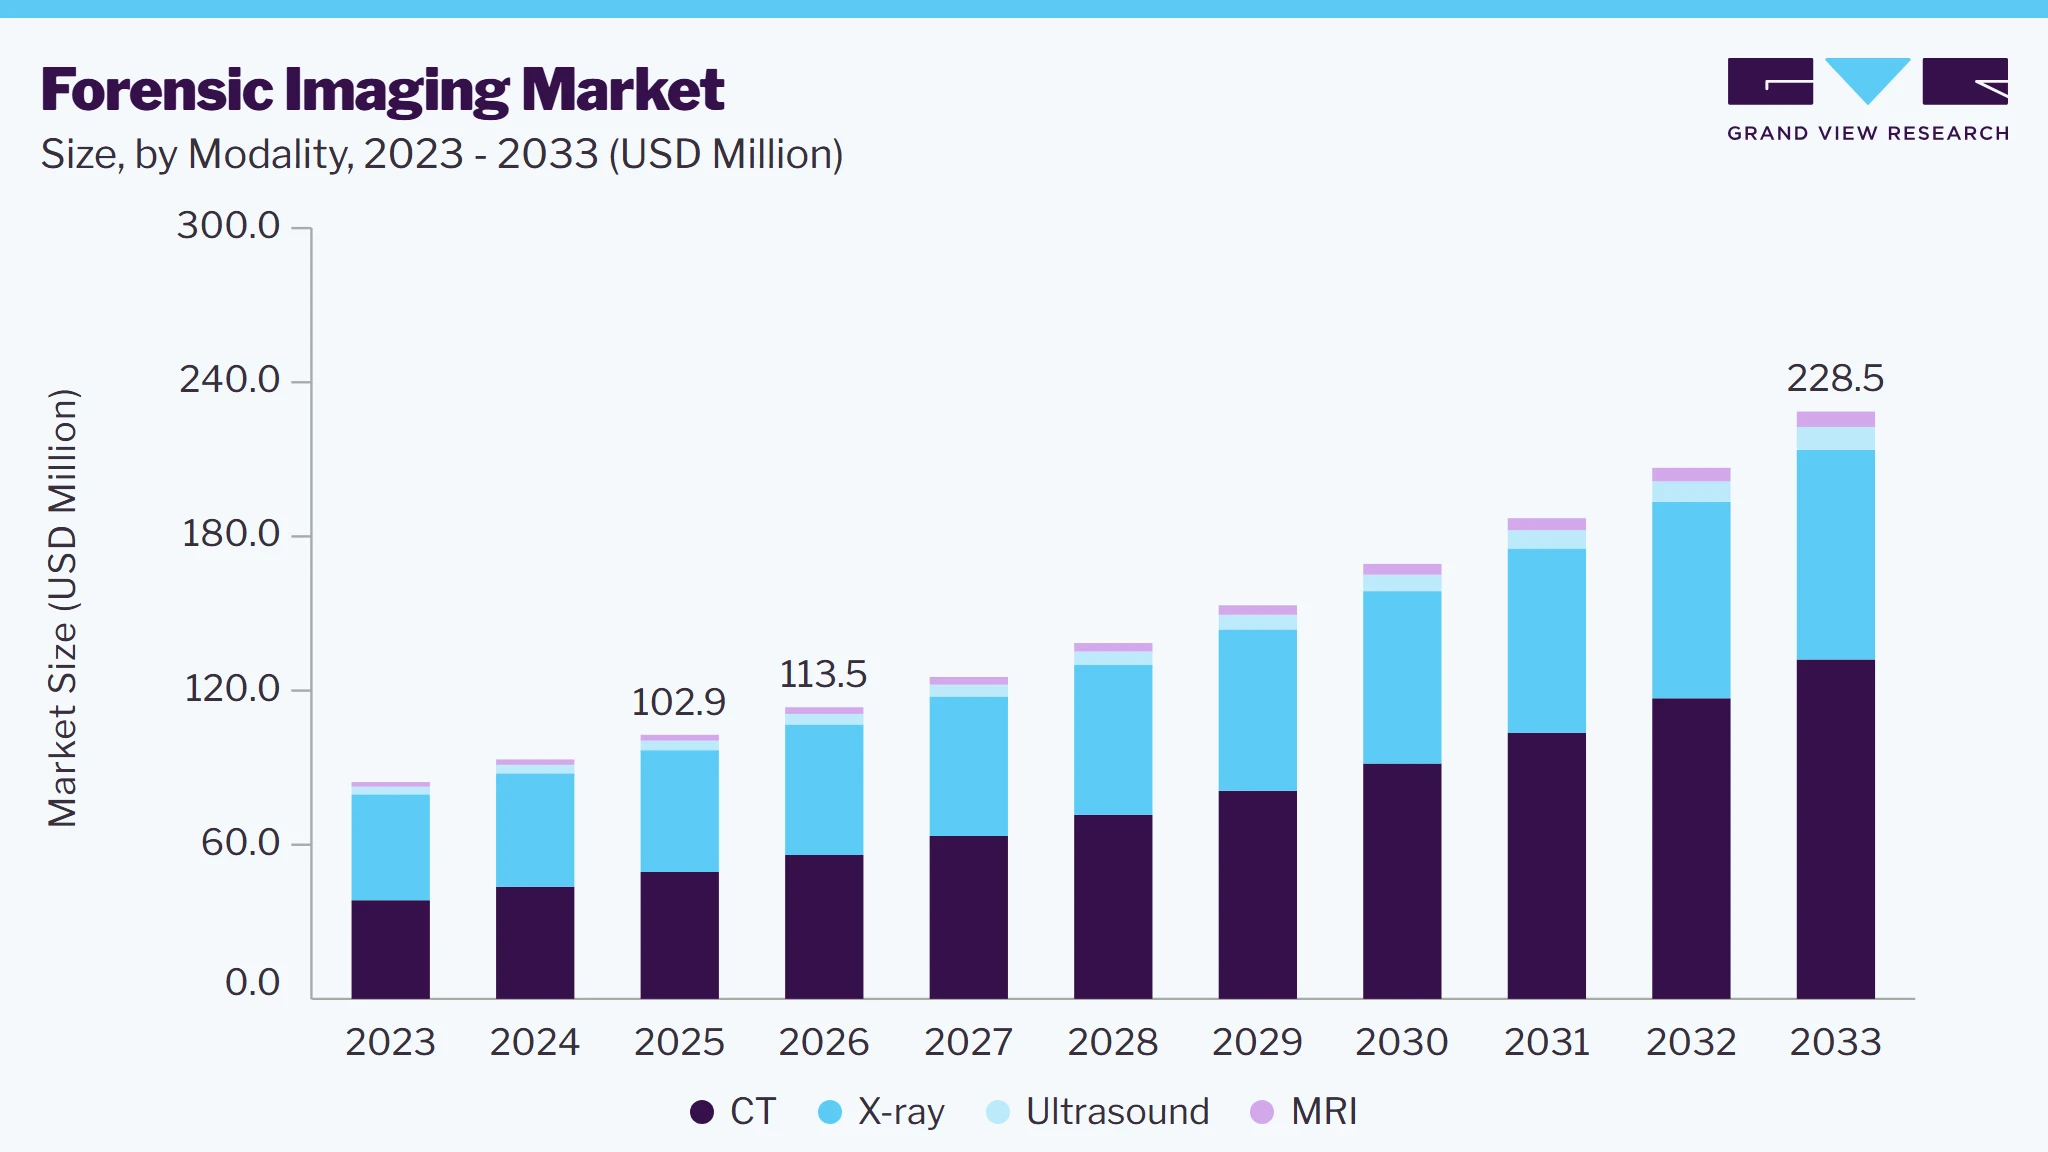
Minimally invasive nature of virtual autopsies is attracting large number of professionals towards choosing it over conventional method. The procedure involves use of advanced radiological assistance such as computed tomography (CT) and magnetic resonance imaging (MRI) to scan the body of deceased. It is believed to deliver better insights than conventional autopsies that are specific, sensitive, and accurate. In addition, when the risk of infections or contaminations is identified as high, professionals opt of virtual autopsy process. Easy access and availability of imaging technology is developed economies, enhanced healthcare infrastructures, and increasing number of pathological postmortems are expected to drive growth for this market in coming years.
The increasing preference for virtual autopsy in judiciary systems is anticipated to expand the use of the forensic imaging modalities. At times, the photo evidence developed from a traditional autopsy procedure is very disturbing and gruesome for lay viewers, thus impeding its acceptability in court proceedings. In such cases, 3D reconstructed images with necessary markings developed through the usage of modern imaging technologies are more palatable and appreciated by judges. Moreover, the digitalization of the evidence enables data storage and prevents its vulnerability towards tampering. The increasing global crime rate, lack of human resources in medical examiner offices, and the advent of advanced technology are the factors expected to drive the growth of the market.
Market Dynamics
The forensic imaging market is experiencing significant growth as law enforcement agencies, forensic laboratories, medical examiner offices, government investigative bodies, and judicial institutions increasingly adopt advanced imaging technologies to support criminal investigations, evidence documentation, and forensic analysis. Forensic imaging encompasses a wide range of technologies and solutions, including digital photography systems, 3D forensic scanners, post-mortem computed tomography (PMCT), forensic radiography systems, multispectral and hyperspectral imaging platforms, facial reconstruction software, crime scene mapping solutions, and digital evidence enhancement tools. These technologies are utilized across diverse forensic applications, including crime scene investigation, post-mortem examinations, forensic pathology, ballistic analysis, document authentication, fingerprint and trace evidence examination, disaster victim identification, and accident reconstruction. The growing need for accurate, non-destructive, and scientifically validated methods of evidence collection and analysis is driving the adoption of advanced forensic imaging solutions worldwide. Furthermore, advancements in artificial intelligence, 3D visualization, image enhancement algorithms, cloud-based evidence management, and high-resolution imaging technologies are enabling investigators to improve evidence interpretation, streamline case workflows, and enhance courtroom presentation of forensic findings. The increasing complexity of criminal investigations, rising emphasis on digital evidence preservation, growing investments in forensic infrastructure, and expanding use of imaging technologies for both criminal and civil investigations continue to support demand for sophisticated forensic imaging solutions across public safety, healthcare, and judicial sectors.
The growing need for accurate, reliable, and non-destructive methods of forensic investigation is a major factor driving the growth of the forensic imaging market. Increasing crime rates, complex criminal cases, mass casualty incidents, and the rising volume of digital and physical evidence have intensified the demand for advanced imaging technologies that can support detailed documentation and analysis without compromising evidence integrity. Forensic imaging solutions such as post-mortem computed tomography (PMCT), 3D crime scene scanning, multispectral imaging, and digital evidence enhancement systems enable investigators to capture, preserve, and examine critical evidence with high precision. These technologies improve the accuracy of forensic examinations, facilitate case reconstruction, and enhance the presentation of findings in legal proceedings. Additionally, growing adoption of digital forensic workflows by law enforcement agencies, forensic laboratories, and medical examiner offices is further accelerating market growth. As judicial systems increasingly rely on scientifically validated evidence, the demand for advanced forensic imaging technologies continues to expand across both criminal and civil investigations.
The high cost associated with acquiring, implementing, and maintaining advanced forensic imaging systems remains a significant restraint for the forensic imaging market. Technologies such as post-mortem CT scanners, 3D laser scanning systems, hyperspectral imaging platforms, and specialized forensic software require substantial capital investment, making adoption challenging for smaller forensic laboratories, regional law enforcement agencies, and resource-constrained institutions. In addition to equipment costs, organizations must invest in software licensing, system upgrades, data storage infrastructure, and specialized personnel training to effectively utilize these technologies. Ongoing maintenance and calibration requirements further increase operational expenditures. Budget limitations within public-sector forensic departments can delay procurement decisions and restrict access to advanced imaging capabilities, particularly in developing regions. Furthermore, the lack of standardized forensic imaging infrastructure across jurisdictions may hinder widespread implementation. These financial and operational challenges can limit technology adoption despite the growing demand for enhanced forensic investigation and evidence analysis capabilities.
Analyst Perspective
The forensic imaging market sits at the intersection of forensic science, medical imaging, and criminal justice modernization. Growing adoption of non-invasive techniques and demand for validated forensic evidence are driving advanced imaging use. Rising crime complexity and medico-legal investigations boost demand for CT, X-ray, MRI, and ultrasound. Institutes and hospitals employ these modalities for post-mortem exams, trauma assessments, disaster victim identification, and virtual autopsy. Advancements in high-resolution imaging, 3D reconstruction, AI-assisted analysis, and digital evidence platforms enhance efficiency and courtroom presentation. Expanding adoption of virtual autopsy programs and investments in forensic infrastructure and forensic radiology further support growth. Law enforcement and judicial systems prioritize objective, reproducible, technology-driven approaches, accelerating adoption across death investigations, clinical forensic studies, and specialized applications.
Modality Insights
Based on modality, the CT segment led the market with the largest revenue share of 48.0% in 2025. A postmortem CT examination can more precisely locate lesions and fractures in complex regions such as the spine, neck, face, and pelvis of the corpse, compared to traditional autopsy. In addition, the practice of CT examination prior autopsy to narrow down the autopsy scope is getting wider acceptance owing to the cost and time benefits. For instance, if a CT scan signifies that a car accident victim died due to head trauma and has a normal pelvis and abdomen, then the autopsy would be limited to the head region.
MRI is expected to grow at a CAGR of 12.5% over the forecast period. An MRI is often recommended as an adjunct to CT scans due to its ability to deliver excellent soft tissue contrast images of the neurological tissue such as the brain and spine. Moreover, limitations such as single body part scan at a time and requirement of specific body conditions have kept the utilization rate of MRI in forensic imaging low.
End-use Insights
Based on end-use, the forensic institutes segment led the market with the largest revenue share of 62.9% in 2025. Multiple forensic institutes across the world are increasingly engaged in research activities related to the use of forensic imaging in numerous applications. This has resulted in a growing number of installations of forensic imaging systems. The Victoria Institute of Pathology Sydney and Institute of Forensic Medicine Denmark have already installed CT scanners for forensic imaging purposes.
The hospital segment is expected to grow at a CAGR of 11.0% from 2026 to 2033. Hospitals are equipped with all specific requirements such as floor space, technical staff, capital, pathologist, and radiologist for performing a virtual autopsy under one roof. In addition, problems such as cost, risk, and time associated with the transfer of corpse to forensic institutes for the investigation will lead to an increase in the adoption of forensic imaging tools in hospitals over the forecast years.
Application Insights
Based on application, the death investigations segment led the market with the largest revenue share of 75.7% in 2025. This growth can be attributed to the increasing number of unnatural deaths such as suicide, murders, and accidental trauma. In addition, strong evidence requirement by the court, underlying the exact cause of death in cases lacking proper eyewitness, has fueled the utilization of virtual autopsy. Furthermore, rising crime rates and the demand for advanced imaging technologies enhance the need for accurate and reliable forensic evidence, fostering greater investment in this field.
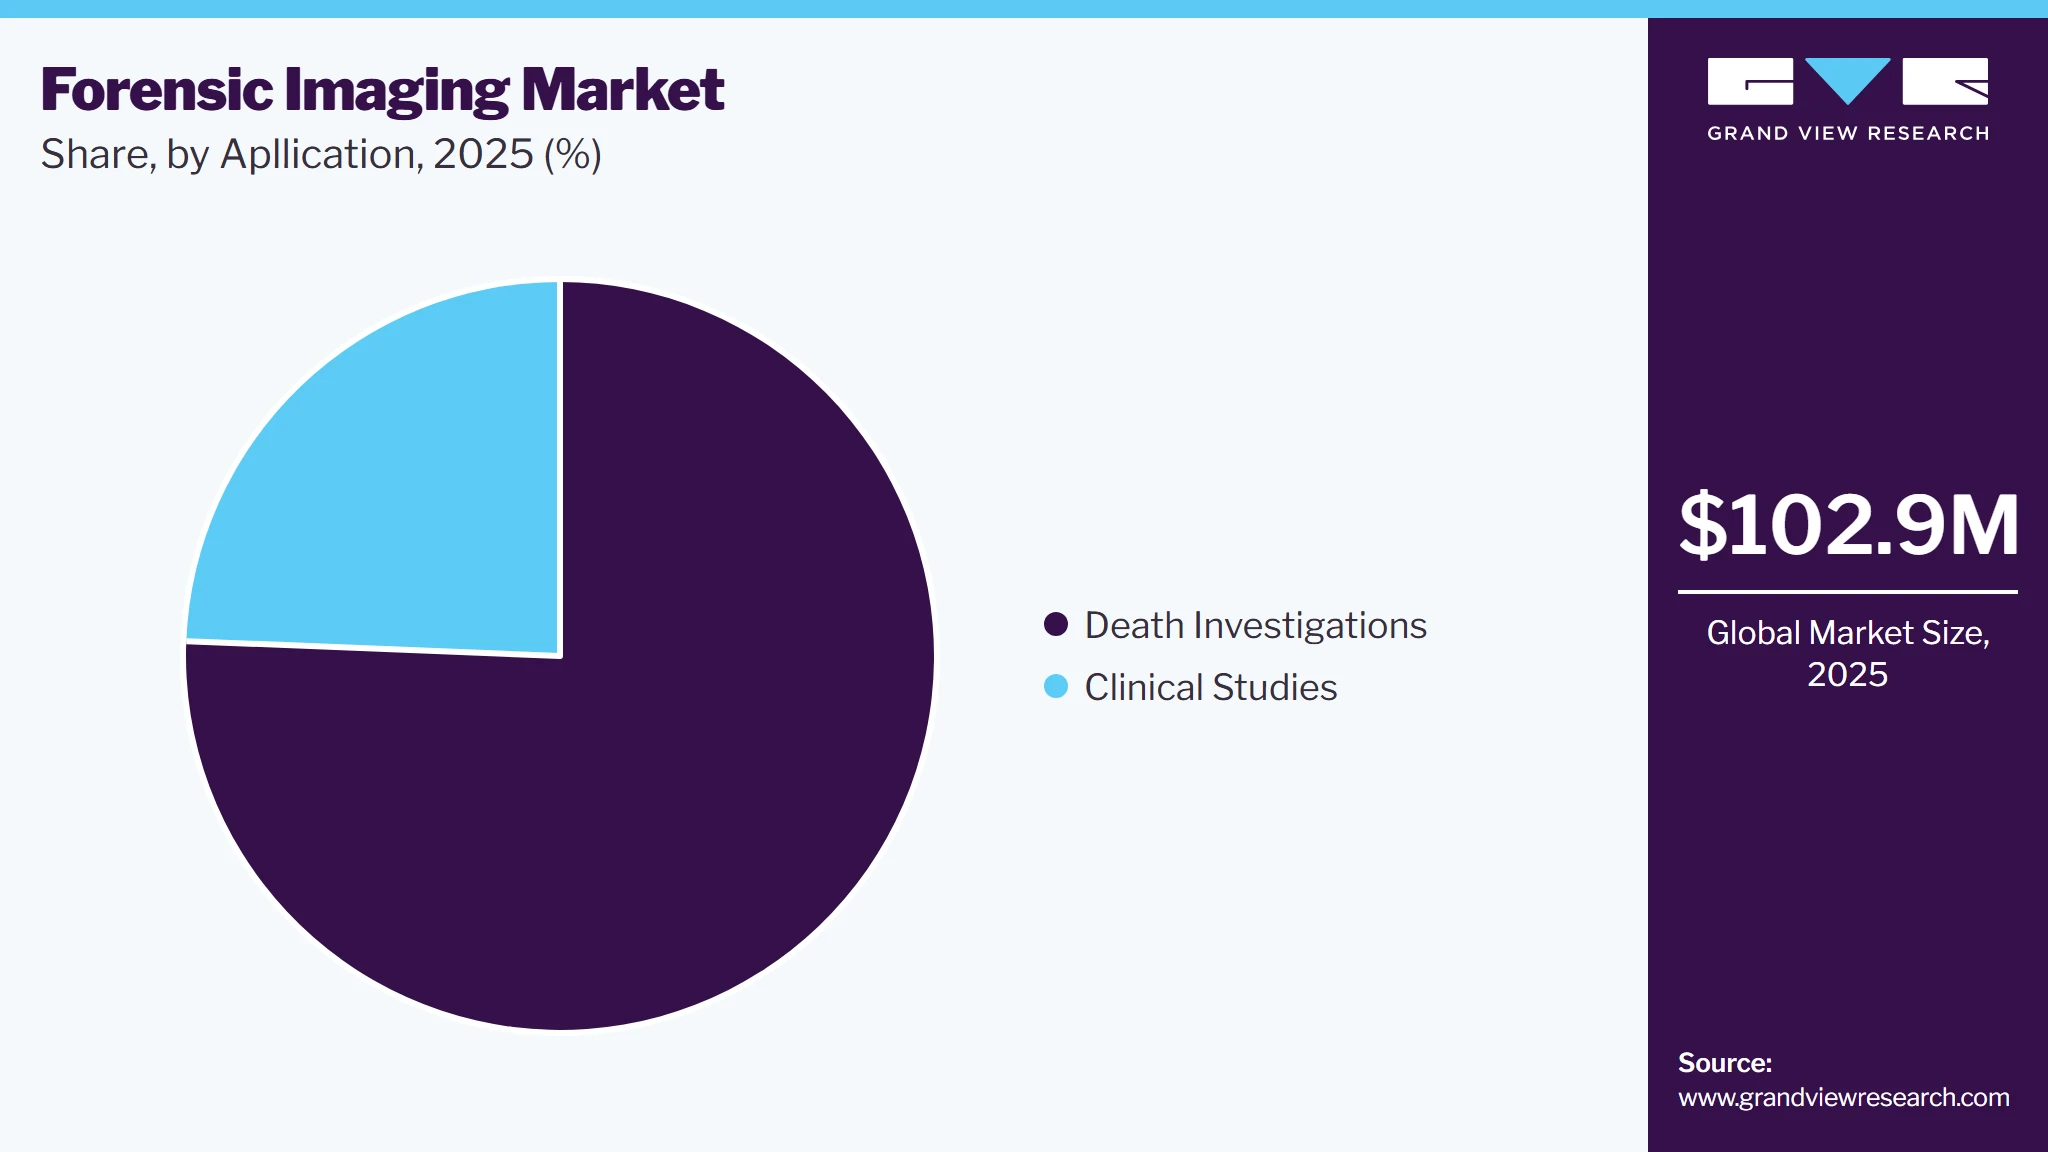
The clinical studies segment is expected to grow at a significant CAGR of 11.3% over the forecast period. This segment is primarily driven by using forensic imaging technology in research centers, organ donor’s examinations, criminal investigations for academic purposes, and more. In addition, significant discoveries related to newly identified diseases and infections are expected to develop lucrative opportunities for the segment. Furthermore, government initiatives aimed at enhancing forensic research capabilities are boosting interest in clinical applications, facilitating better outcomes in medical investigations.
Regional Insights
Europe forensic imaging market dominated the global market and accounted for the largest revenue share of 34.2% in 2025. This growth can be attributed to the early adoption of advanced imaging technologies in forensic investigations. In addition, countries such as the UK, Germany, and France are leading this trend by investing in digital forensic capabilities and enhancing their infrastructure. Furthermore, strong regulatory support and collaboration among European nations for crime investigations further drive market expansion. Moreover, the increasing demand for high-quality forensic processes, coupled with government initiatives to improve forensic science training, is also contributing to this growth.
UK Forensic Imaging Market Trends
The forensic imaging market in the U.S. held the largest share in the North America region in 2025, primarily driven by a significant focus on improving investigative techniques and outcomes. The country has been at the forefront of integrating advanced imaging technologies into law enforcement practices. In addition, increased funding for forensic research and development, along with a growing emphasis on non-invasive methods such as virtual autopsies, is enhancing the effectiveness of death investigations. Furthermore, ongoing training programs for forensic professionals are ensuring that they are equipped with the latest skills and knowledge in imaging technology.
Asia Pacific Forensic Imaging Market Trends
The Asia Pacific forensic imaging market is expected to grow at a CAGR of 11.6% over the forecast period, owing to increasing inclination towards virtual autopsies over conventional autopsies, availability of advanced imaging equipment in the region, less distressing procedural steps and enhancement in healthcare infrastructure. In addition, government initiatives aimed at upgrading forensic infrastructure and technology are critical drivers of this growth. Furthermore, increasing public awareness regarding the importance of forensic science in criminal investigations is prompting greater adoption of advanced imaging solutions across the region.
The forensic imaging market in Japan dominated the Asia Pacific market and accounted for the largest revenue share in 2024, driven by a strong emphasis on technological innovation within law enforcement agencies. In addition, as public safety concerns rise, there is a growing demand for precise and reliable forensic tools. Furthermore, collaborations between academic institutions and law enforcement agencies are fostering research and development efforts that enhance forensic imaging capabilities in the country.
North America Forensic Imaging Market Trends
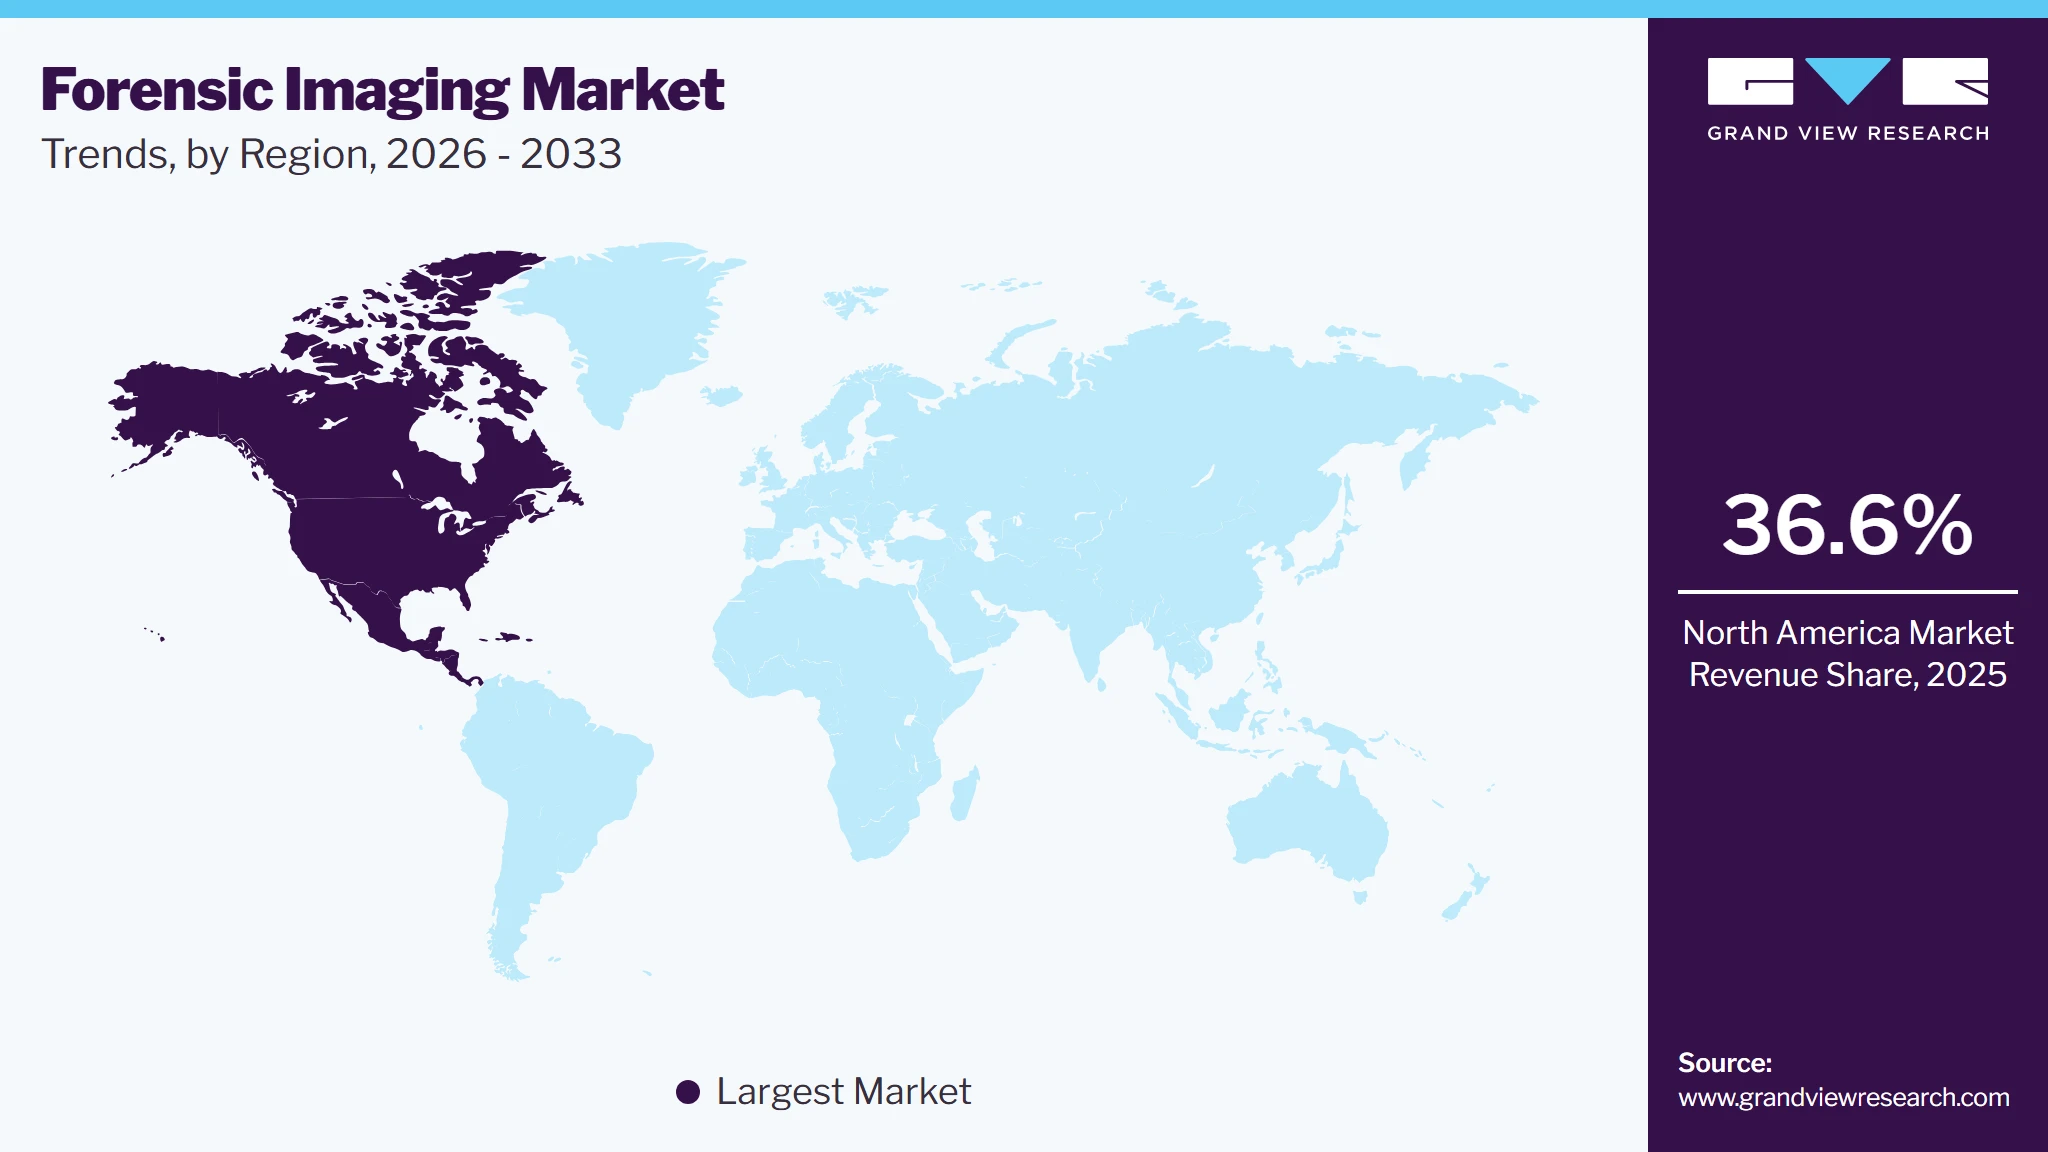
North America dominated the forensic imaging market with the largest revenue share of 36.6% in 2025. North America forensic imaging market is expected to grow significantly over the forecast period driven by rising rate of criminal activities, rapidly growing number of traumatic deaths, and increasing inclusion of forensic imaging in virtual autopsies. In addition, the U.S. leads this segment due to its well-established legal framework and robust healthcare infrastructure that supports forensic investigations. Furthermore, the ongoing transition from coroner systems to medical examiner systems is increasing the demand for sophisticated imaging solutions to handle complex cases efficiently. Moreover, strong participation from key industry players ensures continuous innovation within the market.
The forensic imaging market in the U.S. held the largest share in the North America region in 2025. The U.S. is expected to show huge demand for additional pathologists at autopsy examiner centers in the coming years to cope with the heavy workload. This is anticipated to increase the adoption of advanced imaging technologies in autopsy centers, which, in turn, will help them to lower the number of unnecessary autopsies performed.
Key Forensic Imaging Company Insights
Key players in the global forensic imaging industry include Neusoft Corporation, FUJIFILM, Hitachi, Ltd., and others. These companies are adopting various strategies to enhance their competitive edge. These include investing in research and development to innovate advanced imaging technologies, forming strategic partnerships to expand market reach, and focusing on mergers and acquisitions to consolidate their positions. In addition, companies are prioritizing product launches that address specific forensic needs, while also enhancing customer engagement through targeted marketing initiatives.
-
Neusoft Corporation provides a range of products that support forensic imaging applications. Their offerings include intelligent PACS (Picture Archiving and Communication System), RIS (Radiology Information System), and various imaging systems such as CT, MRI, and ultrasound. Neusoft operates in segments such as healthcare IT, medical imaging, and diagnostic solutions, focusing on integrating cutting-edge technologies such as AI and big data to enhance diagnostic accuracy and workflow efficiency in forensic investigations.
-
Shimadzu Corporation manufacturer of precision instruments and equipment, including advanced imaging systems utilized in forensic applications. The company produces a variety of products such as X-ray systems, CT scanners, and analytical instruments that play a crucial role in crime scene investigations and medical examinations. The company operates in segments including medical systems, industrial equipment, and analytical instruments, emphasizing innovation and quality to meet the evolving needs of forensic imaging professionals and enhance investigative outcomes.
Key Forensic Imaging Companies:
The following key companies have been profiled for this study on the forensic imaging market.
-
Canon Medical Systems Corporation
-
Bruker
-
Neusoft Corporation
-
Shimadzu Corporation
-
FUJIFILM
-
Hitachi, Ltd.
-
Toshiba Medical Systems, Inc.
-
GE Healthcare
-
Siemens Healthineers
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (GE HealthCare, Siemens Healthineers, Canon Medical Systems, FUJIFILM Healthcare, Konica Minolta, Philips)
- Established companies focus on leveraging existing diagnostic imaging portfolios to address forensic applications through CT, X-ray, MRI, and ultrasound platforms. Their strategies emphasize advanced imaging capabilities, AI-enabled image reconstruction, enterprise imaging software, post-processing solutions, long-term service agreements, and partnerships with forensic institutes, hospitals, and academic centers. Many also support virtual autopsy (virtopsy) initiatives and forensic radiology research programs to expand adoption.
- Extensive global installation bases, strong brand recognition, and established relationships with hospitals, radiology departments, and government institutions provide significant advantages. Broad product portfolios enable integrated hardware-software offerings, while substantial R&D investments support continuous innovation in imaging quality, workflow automation, and visualization technologies. Global service networks and regulatory expertise further strengthen market positioning.
- High dependence on capital equipment sales can expose companies to fluctuations in public-sector budgets and procurement cycles. Premium pricing may limit adoption among smaller forensic institutions and developing regions. Large organizational structures may slow customization of solutions specifically designed for forensic workflows and niche investigative requirements.
Emerging Players (Esaote, Planmed, Ziehm Imaging, 3D Systems, FARO Technologies)
- Emerging companies focus on specialized forensic imaging applications, portable imaging systems, 3D reconstruction technologies, forensic visualization software, digital evidence documentation platforms, and cost-effective imaging solutions. Many prioritize innovation in post-mortem imaging workflows, crime scene digitization, cloud-based image management, and advanced analytical tools tailored to forensic investigations.
- Agile development capabilities enable rapid adaptation to evolving forensic requirements and technological advancements. Specialized expertise in niche applications such as 3D forensic reconstruction, virtual autopsy software, and crime scene imaging allows differentiation from larger imaging vendors. Competitive pricing and flexible deployment models can facilitate adoption among smaller forensic laboratories and research institutions.
- Limited global distribution networks and smaller installed bases compared with multinational imaging manufacturers. Lower financial resources may restrict large-scale R&D investments, global expansion efforts, and long-term service support capabilities. Dependence on partnerships with forensic institutions and distributors can create challenges in achieving broad market penetration and competing for large government procurement contracts.
Recent Developments
-
In December 2024, Canon Medical Systems USA introduced an expanded suite of AI-powered solutions designed to automate end-to-end workflows, enhancing its CT portfolio. These solutions include remote scan support, protocol management, and automated processing for CT neuro and chest studies. The AI-driven workflow aims to improve operational efficiency across healthcare systems by streamlining clinical workflows from protocol setup to image processing, reducing manual tasks, and enabling care teams to focus more on patient care.
-
In March 2024, General Atomics Electromagnetic Systems (GA-EMS) launched the Full Spectrum Imaging System Crime Scene Examiner (FSIS-CSE), a portable forensic imaging tool designed for crime scene evidence capture. This compact system features a high-resolution camera mounted on a tablet, enabling faster scans and sharper image capture of latent biological, chemical, and trace evidence in confined spaces. The FSIS-CSE integrates all necessary LEDs and filters, enhancing efficiency and providing a significant advantage in field operations for law enforcement and forensic laboratories, ensuring compatibility with AFIS systems.
Forensic Imaging Market Report Scope
Report Attribute
Details
Market size in 2025
USD 102.9 million
Estimated market size in 2026
USD 113.5 million
Projected market size by 2033
USD 228.5 million
Growth rate
CAGR of 10.5% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Modality, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Australia; Norway; Sweden; Denmark
Key companies profiled
Canon Medical Systems Corporation; Bruker; Neusoft Corporation; Shimadzu Corporation; FUJIFILM; Hitachi, Ltd.; Toshiba Medical Systems, Inc.; GE Healthcare; Siemens Healthineers.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Forensic Imaging Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global forensic imaging market report based on modality, end-use, application, and region:

-
Modality Outlook (Revenue, USD Million, 2021 - 2033)
-
X-ray
-
CT
-
Ultrasound
-
MRI
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Forensic Institutes
-
Hospitals
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Death Investigations
-
Clinical studies
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Sweden
-
Norway
-
Denmark
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Thailand
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The forensic imaging market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each forensic imaging segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Modality
Revenue capture definition
X-Ray
Revenue is generated through the sale of forensic radiography systems, digital X-ray detectors, portable X-ray units, image acquisition software, and associated service contracts utilized for skeletal examinations, trauma assessment, foreign object detection, and evidence documentation. Manufacturers and solution providers benefit from recurring revenue through software upgrades, maintenance services, detector replacements, and expanding adoption of digital forensic radiography across forensic laboratories and medico-legal institutions.
CT
Revenue is derived from the commercialization of forensic computed tomography (CT) systems, post-mortem CT imaging solutions, advanced visualization software, and image reconstruction platforms used for non-invasive autopsy procedures, injury assessment, ballistic investigations, and disaster victim identification. Market participants capture value through high-value equipment sales, software licensing agreements, workflow integration services, and ongoing technical support contracts.
Ultrasound
Revenue flows from the sale of ultrasound imaging systems, portable ultrasound devices, specialized probes, and forensic imaging software used for soft tissue evaluation, guided examinations, and supplementary post-mortem investigations. Manufacturers generate recurring revenue through consumables, probe replacements, service agreements, and increasing utilization of portable imaging solutions in forensic and medico-legal settings.
MRI
Revenue is generated through the deployment of forensic magnetic resonance imaging (MRI) systems, advanced imaging software, and post-processing solutions utilized for detailed soft tissue visualization, neurological assessments, and specialized forensic investigations. Market participants benefit from premium pricing associated with high-resolution imaging capabilities, software subscriptions, maintenance contracts, and demand from advanced forensic research and academic institutions.
Segment - Application
Revenue capture definition
Death Investigations
Revenue is captured through the utilization of forensic imaging technologies including CT, X-ray, MRI, ultrasound, 3D reconstruction software, and image management platforms used for post-mortem examinations, cause-of-death determination, trauma analysis, and disaster victim identification. Manufacturers and service providers benefit from recurring demand for imaging procedures, software licenses, data storage solutions, and forensic reporting tools required for medico-legal investigations.
Clinical Studies
Revenue is generated through the use of forensic imaging systems in research activities, validation studies, academic investigations, injury biomechanics research, and the development of new forensic methodologies. Market participants capture value through equipment procurement, research collaborations, imaging services, software subscriptions, and specialized analytical tools utilized by universities, hospitals, and forensic research organizations.
Segment - End-use
Revenue capture definition
Forensic Institutes
Revenue is derived from the procurement and utilization of forensic imaging systems, image analysis software, evidence documentation platforms, and digital archiving solutions by government forensic laboratories, medical examiner offices, and forensic science institutes. Market participants benefit from long-term public-sector contracts, system upgrades, maintenance agreements, and ongoing investments in forensic infrastructure modernization.
Hospitals
Revenue is generated through the use of forensic imaging technologies within hospitals and medico-legal centers for post-mortem imaging, trauma assessment, forensic consultations, and clinical forensic investigations. Manufacturers capture value through equipment sales, software licensing, imaging service contracts, and integration with existing radiology infrastructure.
Others
Revenue flows from imaging solutions utilized by academic institutions, law enforcement agencies, military organizations, disaster response teams, private forensic service providers, and research centers. Market participants benefit from specialized project-based deployments, training programs, consulting services, software subscriptions, and customized forensic imaging solutions designed for unique investigative requirements.
Estimation Model
Step
Guiding Question
Process Steps
Data Sources
Scope Definition
What is being studied?
1. Define Forensic Imaging Modalities (X-ray, CT, Ultrasound, MRI). 2. Scope Application Segments (Forensic Investigation, Clinical Studies). 3. Define End-use Categories (Forensic Institutions, Hospitals, Others). 4. Define Utilization for Forensic Institution and Hospital.
Forensic agencies, forensic pathology departments, radiology societies
Build the Product Base
How large is the total addressable market?
1. Collect Annual Death Investigation and Autopsy-based Case Utilization. 2. Assess Installed Base of Forensic Imaging Systems (CT, X-ray, MRI, Ultrasound). 3. Map Imaging Utilization Across Forensic Institutions and Hospitals. 4. Compute Case Volumes and Installed Base Utilization.
Forensic agencies, forensic institutions, forensic radiology departments, hospital databases
Estimate Penetration
What proportion of investigations utilize forensic imaging?
1. Assess Imaging Utilization Rate by Investigation Type. 2. Evaluate Adoption of Virtual Autopsy Techniques and Post-mortem Imaging. 3. Analyze Utilization by Application (Death Investigation vs. Clinical Research). 4. Validate Adoption Rates through Expert Interviews and Published Studies.
Forensic agencies, forensic radiology departments, government databases
Revenue Conversion
How does utilization become revenue?
1. Estimate ASPs for Imaging Systems and Software Platforms. 2. Calculate Annual Imaging System Volumes and Segment Utilization. 3. Apply Regional Pricing for Instrument and Service Revenues. 4. Estimate Revenues from Infrastructure Investment, Government Records, and Public Databases.
Forensic agencies, government data, equipment databases, expert interviews
Delivered Customizations
This report has been delivered with the following In-depth customizations
Competitive Landscape Analysis
Conducted a comprehensive competitive landscape assessment for the global forensic imaging market, covering leading providers of forensic CT, X-ray, MRI, ultrasound, 3D reconstruction platforms, forensic visualization software, and virtual autopsy solutions. The study evaluated product portfolio breadth, imaging capabilities, software integration, forensic workflow support, regulatory compliance, geographic presence, research collaborations, and strategic initiatives across forensic institutes, hospitals, academic centers, and law enforcement agencies. It also assessed emerging trends in artificial intelligence-assisted image analysis, post-mortem imaging, cloud-based evidence management, and digital forensic investigation technologies adopted by both established imaging companies and specialized forensic solution providers.
Enables stakeholders to understand the competitive dynamics, technology positioning, and commercialization strategies shaping the global forensic imaging market. The study supports informed decision-making related to vendor selection, technology investments, partnership opportunities, and product differentiation strategies. It also helps organizations identify innovation gaps, evaluate emerging forensic imaging technologies, and strengthen market entry and expansion strategies across forensic science and medico-legal investigation environments.
Segment by Application Analysis
Conducted a detailed segment-level assessment of the forensic imaging market across key application areas including Death Investigations and Clinical Studies. The study analyzed forensic case volumes, imaging utilization rates, modality adoption patterns, virtual autopsy implementation, workflow requirements, and application-specific demand for CT, X-ray, MRI, and ultrasound technologies. It further evaluated historical and forecast demand trends, technological adoption rates, institutional investments, and evolving forensic investigation practices influencing imaging utilization across different application settings.
Enables stakeholders to gain granular insights into high-growth application segments, evolving forensic investigation trends, and modality-specific utilization patterns. The study supports product portfolio optimization, targeted commercialization strategies, resource allocation, and identification of emerging opportunities associated with increasing adoption of virtual autopsy programs, forensic radiology, and advanced medico-legal imaging practices.
Macroeconomic Analysis
Conducted an in-depth driver and macroeconomic assessment focused on government spending on public safety and forensic infrastructure, healthcare expenditure trends, technological advancements in medical imaging, and investments in forensic science modernization programs influencing forensic imaging demand. The study evaluated critical factors including national forensic budgets, crime investigation expenditures, judicial system modernization initiatives, imaging equipment procurement trends, skilled workforce availability, and regulatory frameworks affecting forensic imaging adoption. Additionally, it assessed the growing emphasis on non-invasive investigative techniques, digital evidence preservation, and the increasing use of imaging technologies in death investigations and medico-legal examinations.
Enables stakeholders to understand the key macroeconomic, regulatory, institutional, and technological factors influencing demand within the global forensic imaging market. The study supports long-term strategic planning, investment prioritization, product development initiatives, market expansion decisions, and risk assessment by providing insights into evolving government funding patterns, forensic infrastructure development, and technology adoption trends across forensic and healthcare ecosystems.
Frequently Asked Questions About This Report
The global forensic imaging market is expected to grow at a CAGR of 10.5% from 2026 to 2033, reaching USD 228.5 million by 2033.
North America dominated with a revenue share of 36.6% in 2025.
Some key players operating in the forensic imaging market include Canon Medical Systems Corporation; Bruker; Neusoft Corporation; Shimadzu Corporation; FUJIFILM; Hitachi, Ltd.; Toshiba Medical Systems, Inc.; GE Healthcare; Siemens Healthineers.
Key factors that are driving the forensic imaging market growth include increasing global crime rates, rising preference for virtual autopsy, and the improving affordability for imaging modalities.
The global forensic imaging market size was valued at USD 102.9 million in 2025 and is estimated at USD 113.5 million in 2026.
CT segment led the market with the largest revenue share of 48.0% in 2025.
Death investigations segment led the market with the largest revenue share of 75.7% in 2025.
Forensic institutes segment led the market with the largest revenue share of 62.9% in 2025.
About the Author(s)
Medical Imaging Research Team
Healthcare · Medical ImagingThis report was authored by the medical imaging research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical imaging segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs — add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


