
- Home
- »
- Next Generation Technologies
- »
-
Free Ad-supported Streaming TV Market Size Report, 2033GVR Report cover

Free Ad-supported Streaming TV Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Linear Channel, Video-on Demand), By Device Type (Smart TVs, Mobile Devices), By Content Type (Movies, Music & Entertainment, News, Sports), By Region, And Segment Forecasts
Market Size, 2025
$11.5BMarket Estimate, 2026
$13.6BMarket Forecast, 2033
$40.2BCAGR, 2026–2033
16.8%Free Ad-supported Streaming TV Market Summary
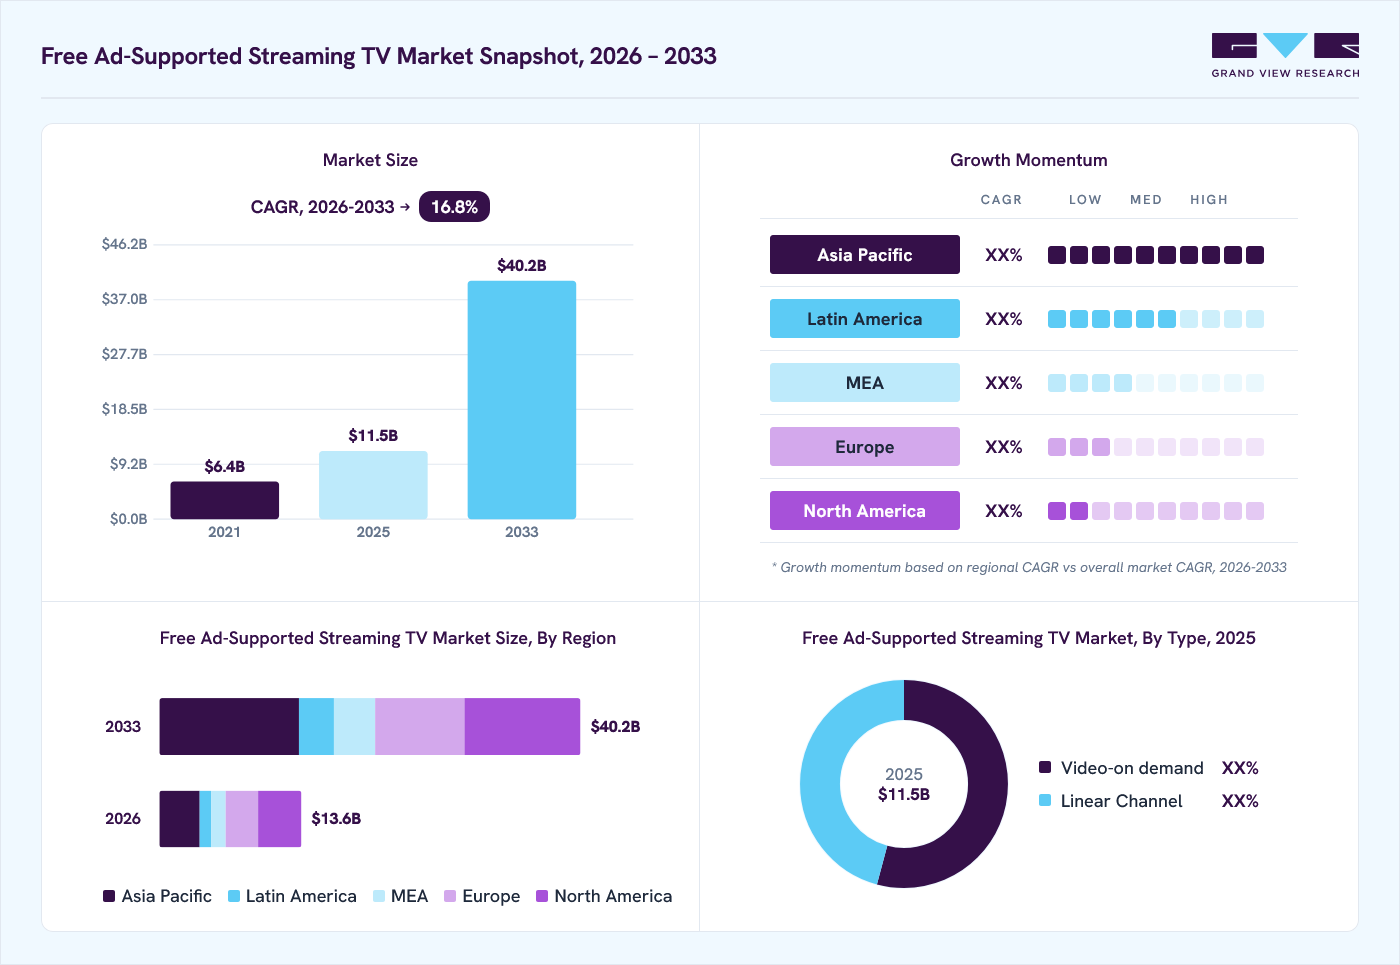
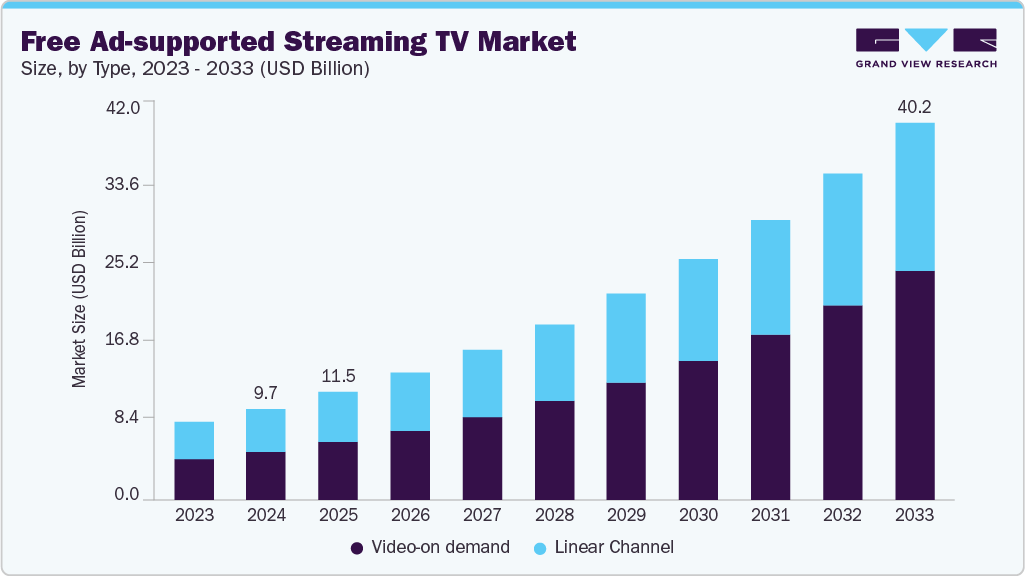
The global free ad-supported streaming TV market size was valued at USD 11.5 billion in 2025 and is projected to grow from USD 13.6 billion in 2026 to USD 40.2 billion by 2033, at a CAGR of 16.8% from 2026 to 2033. The market in North America dominated with a revenue share of 30.9% in 2025. The market is driven by the media companies, which are launching genre-specific FAST channels and expanding exclusive content partnerships to increase audience reach and advertising revenue.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Video-on demand segment held the largest market share of 53.9% in 2025.
- By device type: Smart TVs segment held the largest market share of 49.4% in 2025.
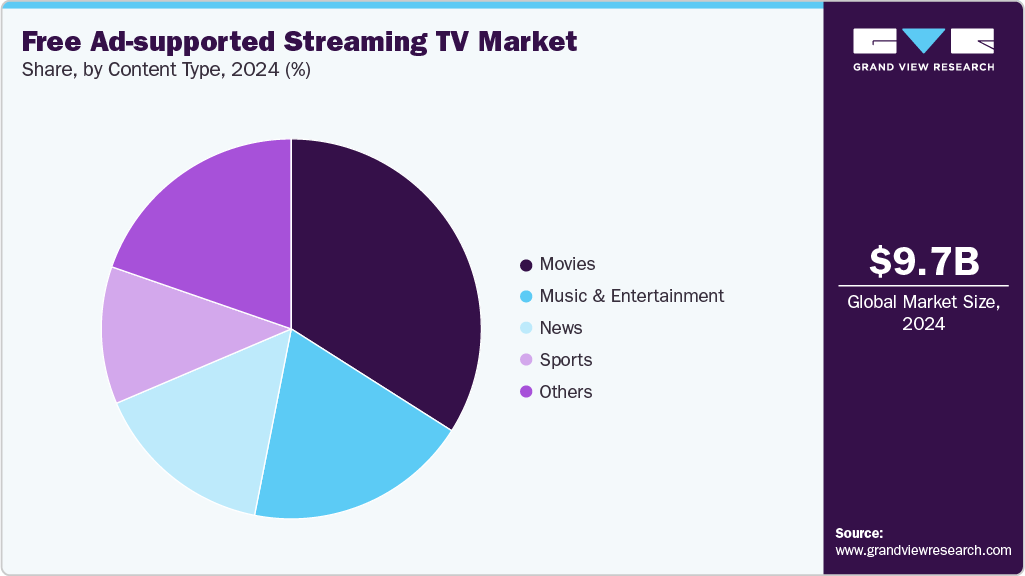
- By content type: Movies segment held the largest market share of 33.7% in 2025.
Regional Highlights
- Largest regional market: North America (30.9% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 11.5 Billion
- Estimated market size in 2026: USD 13.6 Billion
- Projected market size by 2033: USD 40.2 Billion
- CAGR (2026-2033): 16.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Consumers are increasingly seeking affordable alternatives to traditional cable and subscription-based streaming services. Rising living costs and economic uncertainty are accelerating the adoption of free, ad-supported platforms. These services offer access to a wide range of content without monthly fees, making them particularly appealing to price-sensitive audiences. Advertisers benefit from larger, engaged viewership as consumers shift to free streaming channels. This trend positions FAST platforms as a sustainable growth segment in the digital entertainment ecosystem.FAST platforms are increasingly investing in a broad range of content, including live TV, movies, series, and niche programming. Curated channels and genre-specific offerings attract targeted demographics, enhancing viewer retention. Partnerships with independent studios and international content providers enrich the content library, appealing to multicultural audiences. Data-driven insights allow platforms to optimize programming based on engagement metrics. Diversification of content ensures both higher viewer engagement and better monetization opportunities for advertisers.
 To learn more about this report, Download Free Sample Report
The demand for advertisers is rapidly shifting toward digital video and streaming platforms, driven by the need for measurable ROI and precise audience targeting capabilities. Free ad-supported streaming TV (FAST) services offer premium ad inventory at a lower cost than traditional television, appealing to both major brands and small to medium-sized enterprises. The integration of programmatic advertising enables real-time bidding and personalized ad placements, enhancing overall monetization opportunities. Rising advertising investments are also stimulating innovation in content creation and platform functionality. As a result, FAST platforms are emerging as strategic and influential channels within the modern advertising landscape.
Market Dynamics
The free ad-supported streaming TV (FAST) market is expanding as consumers increasingly shift away from paid subscription services in favor of free, ad-supported streaming content that reduces entertainment costs. Growing smart TV adoption, connected TV (CTV) usage, and high-speed internet availability are making FAST channels more accessible across households. Meanwhile, the advertisers are increasing investments in CTV advertising to reach targeted audiences through measurable and data-driven campaigns, creating a sustainable revenue model for platform operators.
The rapid adoption of connected TVs (CTVs) and smart TVs is significantly expanding the audience base for free ad-supported streaming TV (FAST) platforms by enabling seamless access to streaming services without additional hardware. As smart TVs become more affordable and internet connectivity improves, consumers are increasingly choosing internet-based television experiences over traditional cable and satellite services. This shift has created a larger installed base of devices capable of supporting FAST channels, increasing both viewership and engagement.
The integration of FAST services directly into smart TV operating systems and home screens has further improved content discoverability and user convenience, encouraging higher viewing time. In addition, growing partnerships between television manufacturers, streaming platforms, and content providers are expanding the availability of localized and premium ad-supported content, supporting sustained growth in the FAST market.
The free ad-supported streaming TV (FAST) market faces strong competition from subscription-based and hybrid streaming platforms that offer ad-free viewing, exclusive original content, and early access to premium releases. Many consumers continue to subscribe to these services because of their extensive content libraries, higher streaming quality, and personalized viewing experience, limiting the time spent on FAST platforms. This competition makes it challenging for FAST providers to attract and retain long-term viewers, particularly in regions with high subscription streaming adoption.
In addition, several major streaming companies are introducing lower-priced ad-supported subscription tiers, reducing the distinction between paid and free streaming services. As viewers gain access to premium content with fewer advertisements at affordable prices, FAST platforms face increasing pressure to strengthen their content offerings, improve user engagement, and differentiate their services to maintain audience growth.
Artificial intelligence is creating significant opportunities in the free ad-supported streaming TV (FAST) market by enabling platforms to deliver highly personalized content recommendations based on individual viewing behavior and preferences. This improves content discovery, increases watch time, and encourages viewers to spend more time on FAST platforms, leading to higher audience retention and stronger platform engagement. Interactive advertising formats, such as shoppable ads, QR code-enabled campaigns, and personalized promotional content, further enhance the viewing experience while providing measurable outcomes for advertisers.
As advertisers increasingly prioritize data-driven campaigns, AI-powered audience segmentation and real-time ad optimization are helping maximize advertising efficiency and return on investment. The combination of personalized content delivery and interactive advertising enables FAST providers to increase advertising revenue while maintaining a free viewing experience for consumers. This convergence of AI, advanced analytics, and connected TV technologies is expected to support long-term platform differentiation and create new monetization opportunities across the FAST ecosystem.
Market Concentration & Characteristics
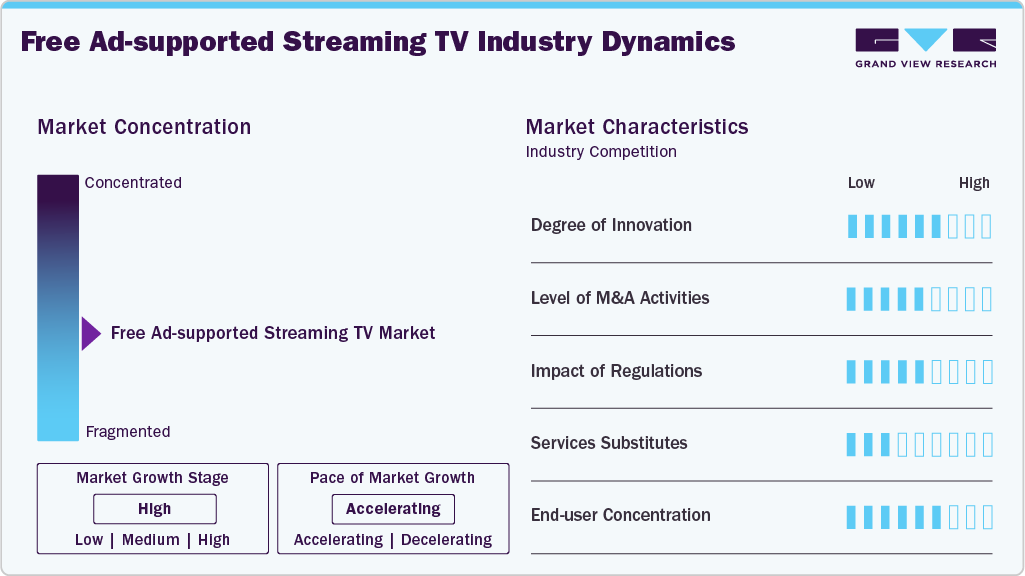
The free ad-supported streaming TV market is experiencing a moderate level of mergers and acquisitions, as media companies acquire content libraries, advertising technology providers, and streaming platforms to strengthen their competitive positions. Strategic partnerships and acquisitions are helping companies expand content portfolios, improve monetization capabilities, and accelerate entry into new regional markets. This trend is supporting long-term market expansion and operational efficiencies.
 To learn more about this report, Download Free Sample Report
The threat of service substitutes is moderate, as FAST platforms compete with subscription video-on-demand (SVOD), advertising-supported video-on-demand (AVOD), traditional television, and social media video platforms. However, the availability of free premium content supported by advertising offers a distinct value proposition for cost-conscious consumers. Increasing demand for free entertainment continues to strengthen the competitive position of FAST services despite the presence of multiple alternatives.
Analyst Perspective
The free ad-supported streaming TV (FAST) market is entering a growth phase as rising subscription fatigue, increasing connected TV penetration, and advertiser migration toward measurable digital television reshape the global video ecosystem. These platforms combine free premium content with data-driven advertising, creating a scalable monetization model that benefits both viewers and advertisers. The defining competitive advantage, however, is expected to belong to platforms that combine extensive content libraries, AI-powered content discovery, and advanced advertising capabilities within a unified streaming ecosystem. Providers that effectively integrate personalized recommendations, programmatic advertising, and localized content offerings are positioned to achieve higher viewer retention, stronger advertising yields, and sustainable long-term revenue growth.
Type Insights
Based on type, the video-on demand segment led the market with the largest revenue share of 53.9% in 2025 and is expected to grow at the fastest CAGR over the forecast period. The segment growth is propelled by the success of platforms such as Tubi, Pluto TV, and The Roku Channel, which provide extensive movies, series, and original programming at no cost to viewers. As consumers experience subscription fatigue, the attractiveness of free, ad-supported content continues to rise. Tubi, for example, has effectively combined linear streaming with on-demand viewing, enabling users to switch seamlessly between continuous programming and specific content selections. Furthermore, the VOD segment within FAST platforms is gaining momentum through advancements in targeted advertising, significantly enhancing revenue opportunities for content providers. By leveraging audience data and behavioral insights, advertisers can deliver more relevant and personalized ads, driving higher engagement and improved monetization outcomes.
The linear channel segment is expected to grow at a significant CAGR during the forecast period, driven by growing consumer preference for a traditional, lean-back viewing experience within digital streaming environments. The format’s curated, scheduled programming reduces content selection fatigue and encourages longer viewing sessions, resulting in higher engagement levels. This structured model also offers advertisers consistent ad inventory and predictable placement opportunities, maximizing visibility and return on investment. Major FAST providers, such as Pluto TV, Samsung TV Plus, and Xumo, have expanded their channel portfolios across various genres, including news, sports, and entertainment, to attract a broader audience. As a result, the linear channel segment continues to serve as a key driver of user retention and advertising revenue within the evolving FAST market.
Device Type Insights
Based on device type, the smart TVs segment led the market with the largest revenue share of 49.4% in 2025, driven by the seamless integration of streaming capabilities directly into television hardware. The widespread adoption of smart TVs has eliminated the need for external devices, making it easier for consumers to access FAST channels and on-demand content. Manufacturers such as Samsung, LG, and Vizio are enhancing user interfaces and partnering with FAST service providers to deliver pre-installed apps and personalized content recommendations. This integration has improved accessibility, increased viewership, and expanded advertising reach. As a result, the smart TVs segment continues to be a major growth driver, fueling audience expansion and strengthening monetization opportunities across the FAST ecosystem.
The mobile devices segment is expected to grow at a significant CAGR during the forecast period, driven by the increasing consumption of on-the-go entertainment and the widespread availability of high-speed mobile internet. Smartphones and tablets have become primary access points for streaming, particularly among younger demographics who seek flexibility and convenience. FAST platforms are optimizing their mobile applications with adaptive streaming, personalized recommendations, and interactive ad formats to enhance the viewing experience. The rise in 5G connectivity further supports high-quality, low-latency video delivery, encouraging longer watch times and higher engagement. Consequently, the mobile devices segment is emerging as a key growth driver, expanding audience reach and creating new monetization avenues for advertisers and content providers within the FAST ecosystem.
Content Type Insights
Based on content type, the movies segment led the market with the largest revenue share of 33.7% in 2025 and is expected to grow at a significant CAGR over the forecast period. Platforms are leveraging data analytics to curate personalized movie recommendations, enhancing viewer engagement and retention. High-quality, genre-diverse content attracts both mass and niche audiences, making the segment a key magnet for advertising revenue. As a result, the movies segment remains a primary growth driver, expanding monetization opportunities and solidifying the strategic value of FAST platforms in the digital entertainment ecosystem.
 To learn more about this report, Download Free Sample Report
The sports segment is expected to grow at the highest CAGR over the forecast period, owing to increasing consumer demand for live and on-demand sports content across digital platforms. The rise in FAST services, which offer exclusive sports channels and event coverage, is attracting highly engaged audiences. Advertisers are capitalizing on this trend by placing targeted campaigns during high-viewership events, enhancing monetization potential. Moreover, partnerships between streaming platforms and sports leagues are expanding content availability, making the sports segment a key driver of audience growth and revenue in the FAST market.
Regional Insights
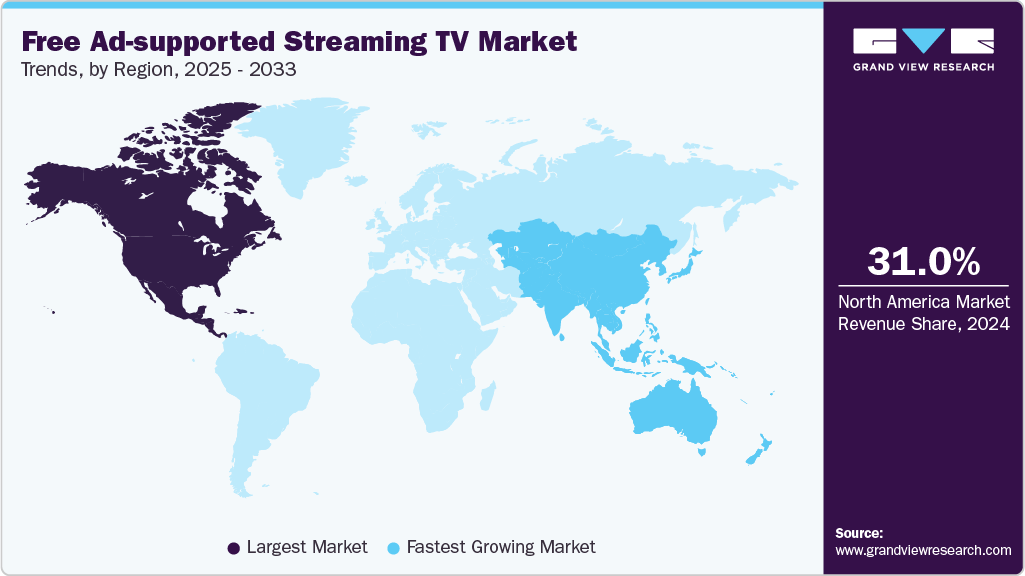
North America dominated the free ad-supported streaming TV market with the largest revenue share of 30.9% in 2025, driven by high digital adoption and the presence of major industry players such as Pluto TV, Tubi, and The Roku Channel. The region’s mature advertising ecosystem and widespread smart TV penetration continue to support audience expansion. Consumers are increasingly shifting from paid subscriptions to free, ad-supported options, enhancing advertiser reach and platform monetization. As a result, North America remains the dominant and most established market for FAST services worldwide.
 To learn more about this report, Download Free Sample Report
U.S. Free Ad-supported Streaming TV Market Trends
The free ad-supported streaming TV market in the U.S. held the largest share in the North America region in 2025, fueled by increasing demand for cost-effective entertainment amid subscription fatigue. Major media companies and tech platforms are launching dedicated FAST channels to capitalize on growing viewership. Advancements in targeted and programmatic advertising are further strengthening monetization potential for both advertisers and content owners. Consequently, the U.S. continues to lead the global FAST landscape in terms of innovation, ad revenue generation, and content diversity.
Europe Free Ad-supported Streaming TV Market Trends
The free Ad-supported streaming TV market in Europe is expected to grow significantly over the forecast period, supported by rising adoption of connected TVs and increasing availability of localized FAST channels. Broadcasters and media companies are forming partnerships with streaming platforms to extend content distribution and ad-based monetization. Markets such as the UK, Germany, and France are at the forefront, benefiting from established digital advertising ecosystems. This regional expansion is driving stronger audience engagement and providing new revenue opportunities for advertisers targeting European consumers.
Asia Pacific Free Ad-supported Streaming TV Market Trends
The free Ad-supported streaming TV market in the Asia Pacific is anticipated to register the highest CAGR of over 19.0% during the forecast period, driven by rapid internet penetration, growing smartphone usage, and increasing preference for free digital content. Regional players are expanding localized FAST offerings to cater to diverse linguistic and cultural audiences. The rise of 5G networks and affordable smart devices is further enhancing streaming accessibility across emerging economies such as India, Indonesia, and the Philippines. With strong audience growth potential, the Asia Pacific is poised to become the fastest-growing region in the global FAST market.
Key Free Ad-supported Streaming TV Company Insights
Some key companies in the Free Ad-supported Streaming TV industry are Pluto TV, Tubi TV, The Roku Channel, Peacock TV, and Sling TV.
-
Pluto TV, owned by Paramount Global, is one of the leading Free Ad-Supported Streaming TV (FAST) platforms, offering a wide selection of live and on-demand channels across various genres, including news, sports, entertainment, and lifestyle. The service provides curated linear channels and a growing library of movies and series, available without subscription fees. Its monetization model is primarily ad-driven, leveraging advanced targeting tools to enhance advertiser returns. Pluto TV’s strong global expansion strategy and partnerships with major content providers have solidified its position as a pioneer in the FAST market.
-
The Roku Channel, operated by Roku, Inc., is a leading FAST platform integrated into Roku’s streaming devices and smart TV ecosystem. It offers a mix of live linear channels, on-demand movies, and exclusive Roku Originals, all supported by advertising revenue. Roku’s platform advantage allows seamless integration of content, distribution, and ad inventory across millions of connected devices. With strong advertiser relationships and user analytics, The Roku Channel remains a key driver of engagement and ad monetization in the FAST market.
Key Free Ad-supported Streaming TV Companies
The following key companies have been profiled for this study on the free Ad-supported streaming TV market.
-
Amazon.com, Inc.
-
Crackle
-
Peacock TV LLC
-
Plex
-
Pluto TV
-
Roku, Inc.
-
Sling TV
-
Tubi TV
-
Vudu
-
Xumo, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Amazon.com, Inc.; Peacock TV LLC; Pluto TV; Roku, Inc.; Tubi TV)
- Focus on expanding premium content libraries through licensing agreements and original programming.
- Strengthen advertising capabilities using first-party audience data, AI-driven targeting, and strategic partnerships.
- Large active viewer base supported by broad device compatibility and established brand recognition.
- Strong advertising ecosystems and diversified content portfolios generate consistent platform engagement.
- High content acquisition and platform operating costs impact profitability.
- Intense competition limits user growth and increases dependence on advertising revenue.
Emerging Players (Crackle; Plex; Sling TV; Vudu; Xumo, Inc.)
- Expand niche and genre-specific FAST channels to serve targeted audience segments.
- Form content distribution partnerships and improve platform accessibility across connected devices.
- Greater flexibility to introduce specialized content and differentiated viewing experiences.
- Lean operating models enable faster adaptation to changing viewer preferences.
- Limited brand awareness and smaller content libraries reduce audience reach.
- Lower advertising scale and regional presence constrain revenue growth compared with larger competitors.
Recent Developments
-
In August 2025, Hisense launched Hisense Channels, a Free Ad-Supported Streaming TV (FAST) service featuring over 200 premium channels, powered by Xumo Enterprise. The service is now available on Hisense Google TVs and will expand to additional smart TVs soon. Xumo Enterprise, the B2B arm of Xumo, provides the infrastructure and monetization capabilities for the platform. Hisense Channels offers content from leading publishers, including Scripps, Radial Entertainment, and Stingray, aiming to enhance the streaming experience for viewers.
-
In July 2025, Zee5 announced a strategic partnership with Amagi Media Labs to launch its Free Ad-Supported Streaming Television (FAST) service in India. Scheduled for an August debut, the service aims to offer a traditional TV-like viewing experience with a variety of content genres, including comedy, drama, and horror, available for free with advertisements. This move is designed to strengthen Zee5's presence in the rapidly growing connected TV market, which is projected to expand at an annual rate of 12.67% from 2025 to 2030. By entering the FAST sector, Zee5 aims to diversify its revenue streams and enhance its competitiveness against established players such as The Roku Channel and Plex.
-
In February 2025, Samsung TV Plus India expanded its Free Ad-Supported Streaming TV (FAST) offerings by launching five exclusive channels in collaboration with Warner Bros. Television. These channels, House of Crime, Foodie Hub, Wild Flix, Wheel World, and XXtreme Jobs, are designed to engage both regional and urban audiences, with a strong focus on Hindi-language programming. The partnership addresses the growing demand for high-quality, free entertainment accessible via Samsung Smart TVs and mobile devices. This strategic initiative reinforces Samsung TV Plus’s commitment to enhancing viewer choice and delivering value to advertisers within the competitive FAST market.
Free Ad-supported Streaming TV Market Report Scope
Report Attribute
Details
Market size in 2025
USD 11.5 billion
Estimated market size in 2026
USD 13.6 billion
Projected market size by 2033
USD 40.2 billion
Growth rate
CAGR of 16.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, device type, content type, region
Regional scope
North America, Asia Pacific; Europe; MEA; Latin America
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; South Africa; UAE
Key companies profiled
Amazon.com,Inc.; Crackle; Peacock TV LLC; Plex; Pluto TV; Roku, Inc.; Sling TV; Tubi TV; Vudu; Xumo, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Free Ad-supported Streaming TV Market Report Segmentation
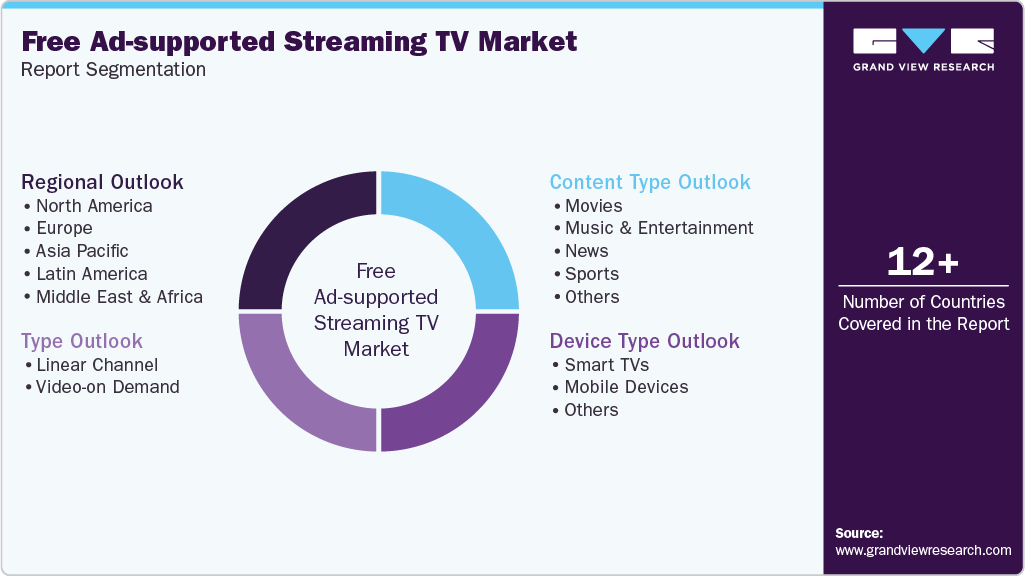
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global free Ad-supported streaming TV market report based on type, device type, content type, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Linear Channel
-
Video-on Demand
-
-
Device Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Smart TVs
-
Mobile Devices
-
Others
-
-
Content Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Movies
-
Music & Entertainment
-
News
-
Sports
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
MEA
-
UAE
-
South Africa
-
KSA
-
-
Research Methodology
The free ad-supported streaming TV market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each free ad-supported streaming TV segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Linear Channel
Revenue for the linear channel segment includes advertising income generated from scheduled, always-on streaming channels that deliver curated content such as news, sports, movies, and entertainment. It captures ad impressions, sponsorships, and brand placements across continuously programmed FAST channels.
Video-on demand
Revenue for the video-on-demand segment covers advertising generated from on-demand content selected by viewers, including movies, TV shows, and exclusive programming. It includes income from targeted ad placements delivered before, during, or after streamed content based on viewer preferences.
Segment - Device Type
Revenue capture definition
Smart TVs
Revenue from this segment is generated through FAST content streamed directly on connected television platforms with integrated applications. Higher viewing duration, premium screen experience, and increased advertising inventory contribute to this segment's revenue share.
Mobile Devices
The mobile devices segment captures revenue from FAST services accessed through smartphones and tablets across dedicated applications and mobile browsers. Growing mobile video consumption and personalized advertising support monetization across diverse user groups.
Others
The others segment includes streaming devices, desktop and laptop computers, gaming consoles, and other internet-enabled screens used to access FAST content. Revenue is supported by cross-device viewing and broader accessibility across multiple digital ecosystems.
Segment - Content Type
Revenue capture definition
Movies
Movie content generates revenue by offering licensed films across multiple genres without requiring a subscription. Revenue is generated through extended viewing sessions that increase advertising inventory and campaign reach.
Music & Entertainment
Music videos, celebrity programming, reality shows, and entertainment channels maintain consistent audience engagement across different age groups. These categories support recurring advertising demand through frequent viewer visits and broad consumer appeal.
News
News channels generate revenue by delivering continuous live and on-demand coverage that encourages regular daily viewership. High viewing frequency provides advertisers with consistent exposure during time-sensitive programming.
Sports
Sports content generates revenue through live events, highlights, analysis, and sports-themed channels, which drive strong audience engagement. Major tournaments and seasonal competitions increase viewership, supporting premium advertising opportunities.
Others
This segment includes lifestyle, kids, documentaries, travel, cooking, education, and niche interest channels that serve specialized audience groups. Diverse content offerings expand viewer coverage and create additional advertising opportunities across multiple consumer segments.
Estimation Model
Layer Name
Key Questions
Description
Connected Device Layer
Who can access FAST services?
Identify the installed base of internet-connected devices such as smart TVs, streaming media players, smartphones, tablets, and PCs capable of accessing FAST platforms. This establishes the addressable audience for free ad-supported streaming services.
Viewer Engagement Layer
How many users watch FAST content?
Apply viewer adoption and active usage rates to estimate the number of monthly active FAST viewers across supported devices. This converts the addressable audience into the active viewer base, generating streaming activity.
Content Consumption Layer
Where is viewing time distributed?
Measure viewing hours across content categories such as movies, news, sports, music & entertainment, and other channels, along with platform-level engagement. This reflects content consumption patterns that determine available advertising inventory.
Advertising Monetization Layer
How much revenue is generated?
Apply advertising metrics including ad impressions, fill rates, CPMs, and advertiser spending across FAST platforms to estimate total market revenue. This represents the monetization of viewer engagement through ad-supported streaming services.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Market Entry & Expansion Assessment
Regional demand sizing and forecasting
Customer segmentation and buying behavior analysis
Competitive landscape benchmarking
Regulatory and distribution channel assessment
Identified high-growth market opportunities
Supported go-to-market strategy development
Highlighted investment priorities and risks
Enabled data-driven expansion planning
Technology & Innovation Assessment
Emerging technology trend analysis
Innovation pipeline
Technology adoption readiness assessment
Ecosystem and partnership mapping
Identified future growth areas
Supported roadmap planning innovation
Evaluated commercialization potential
Strengthened strategic partnership decisions
Customer & End-User Insights Study
Consumer awareness and adoption analysis
Purchase decision journey mapping
Satisfaction and loyalty assessment
Usage pattern and pain-point evaluation
Revealed key adoption drivers and barriers
Supported customer-centric product development
Improved targeting and engagement strategy
Identified opportunities for retention and upselling
Frequently Asked Questions About This Report
The market is driven by the media companies, which are launching genre-specific FAST channels and expanding exclusive content partnerships to increase audience reach and advertising revenue.
Asia Pacific is the fastest-growing region over the forecast period.
The Video-on demand segment led with a 53.9% revenue share in 2025, while Linear Channel is the prominent growing segment.
The smart TVs segment led with a 49.4% revenue share in 2025.
Movies held the largest revenue share in 2025, while Sports is the fastest growing segment.
The global free ad-supported streaming TV market size was valued at USD 11.5 billion in 2025 and is estimated at USD 13.6 billion for 2026.
Some key players operating in the free ad-supported streaming TV (FAST) market include: Amazon.com,Inc.; Crackle; Peacock TV LLC; Plex; Pluto TV; Roku, Inc.; Sling TV; Tubi TV; Vudu; Xumo, Inc.
The global free ad-supported streaming TV market is expected to grow at a CAGR of 16.8% from 2026 to 2033, reaching USD 40.2 billion by 2033.
North America dominated the FAST market, accounting for 30.9% in 2025. This is attributable to the fact that consumers are increasingly seeking free entertainment options due to rising living costs and subscription fatigue, making FAST services an attractive alternative to traditional cable and paid streaming platforms in this region.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


