
- Home
- »
- Medical Devices
- »
-
Fundus Cameras Market Size & Share Report, 2026-2033GVR Report cover

Fundus Cameras Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product, By End Use (Hospitals, Ophthalmology Clinics, Ophthalmic & Optometrist Offices), By Region (North America, Europe, Latin America, MEA), And Segment Forecasts
Market Size, 2025
$392.5MMarket Estimate, 2026
$416.2MMarket Forecast, 2033
$657.6MCAGR, 2026–2033
6.8%Fundus Cameras Market Summary
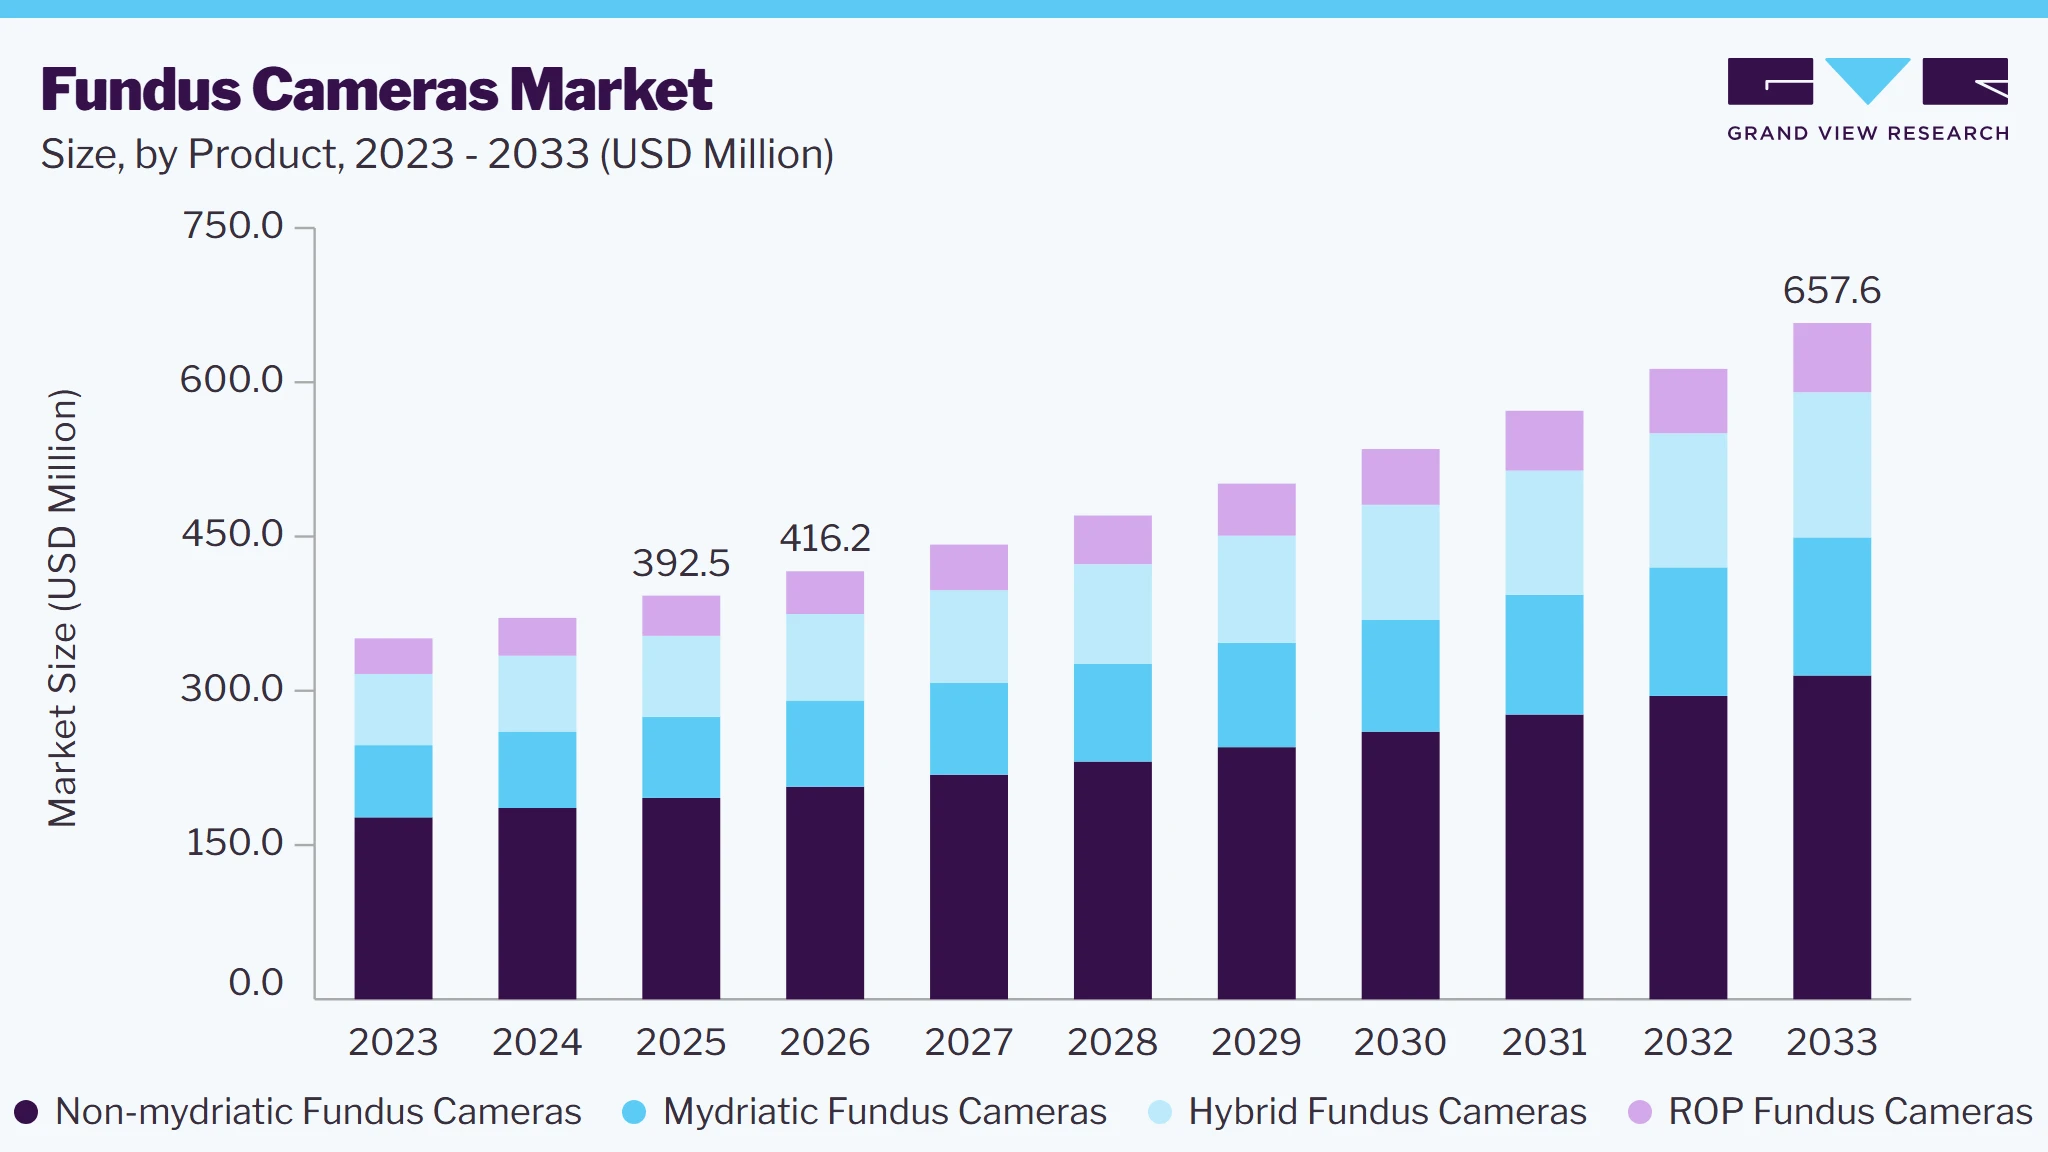
The global fundus cameras market size was valued at USD 392.5 million in 2025 and is projected to grow from USD 416.2 million in 2026 to USD 657.6 million by 2033, at a CAGR of 6.8% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 37.4% in 2025. The increasing geriatric population and chronic disorders, such as diabetes and hypertension, are responsible for the growth in the incidence of retinal disorders.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Non-mydriatic fundus cameras segment led the market with the largest revenue share of 49.9% in 2025.
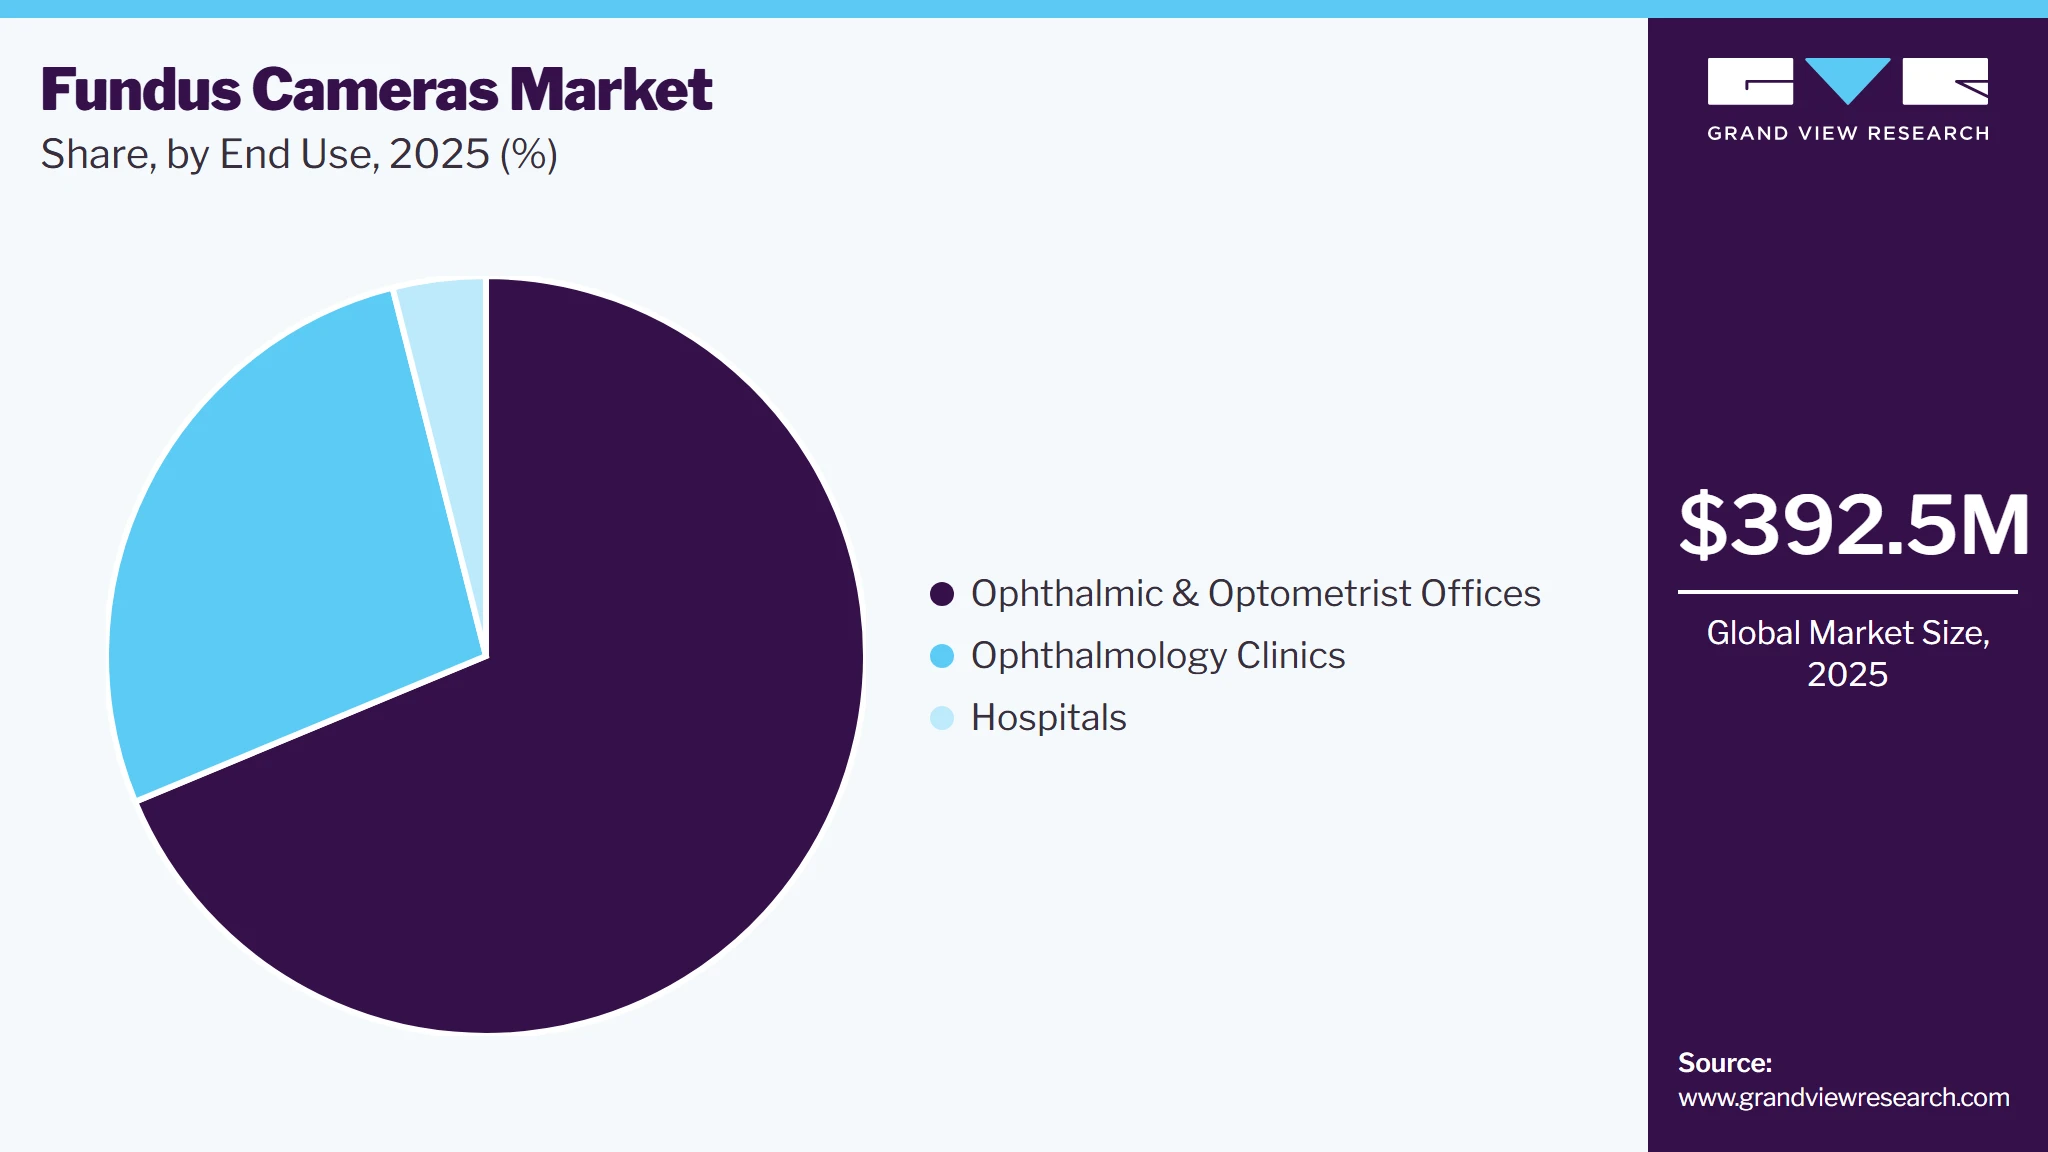
- By end-use: Ophthalmic & optometrist offices segment led the market with the largest revenue share of 68.7% in 2025.
Regional Highlights
- Largest regional market: North America (37.4% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 392.5 Million
- Estimated market size in 2026: USD 416.2 Million
- Projected market size by 2033: USD 657.6 Million
- CAGR (2026-2033): 6.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Key retinal disorders include Diabetic Retinopathy (DR), Age-related Macular Degeneration (AMD), and Retinopathy of Prematurity (ROP). Furthermore, increasing awareness about eye disorders and commercializing several technologically advanced products are likely to propel the market during the forecast period.Due to the rising incidence of chronic diseases like hypertension, diabetes, and geriatrics, retinal abnormalities are on the rise. Diabetic eye diseases consist of several eye conditions, including DR, diabetic macular edema, glaucoma, and cataracts. According to the National Eye Institute (NEI), in the U.S., diabetic retinopathy patients in America are expected to double from 7.7 million in 2010 to 14.6 million in 2050. In addition, advancements in the field are expected to drive the market during the forecast period.
 To learn more about this report, Download Free Sample Report
The use of portable fundus photography cameras in hospital settings, as highlighted by the University of Colorado's ophthalmology department in February 2024, is transforming patient care and resident training. These compact, smartphone-sized devices enhance the ability of on-call residents to conduct comprehensive and efficient evaluations, crucial in fast-paced environments. The cameras, equipped with long lenses, enable real-time imaging and allow supervising physicians to view the images remotely, improving diagnosis and treatment plans. This innovation saves time, facilitates follow-up care, and reduces consultation delays.
As the fundus camera market grows, its potential to enhance clinical efficiency and patient outcomes is evident, especially in emergency and on-call situations. The trend suggests a broader adoption of such devices in both clinical and home settings, aligning with the increasing demand for more accessible, cost-effective, and mobile ophthalmic imaging solutions. This development is pivotal for the future of retina diagnostics and training.
The market is anticipated to expand due to rising awareness of eye problems and the launch of numerous cutting-edge products. The development of digital cameras, red-free fundus cameras, film-based fundus cameras, and other tools for clear and detailed fundus imaging are likely to lead to market growth throughout the projected period. Artificial intelligence, machine learning, and big data have enormous potential for improving healthcare. Diagnosing illnesses such as DR has proven to be quite accurate with the inclusion of AI in fundus cameras. It has been demonstrated that machine learning algorithms may detect eyes at risk for postoperative myopic regression following refractive surgery by using preoperative fundus photography in conjunction with other preoperative parameters, including anterior chamber depth, central corneal depth, age, and intended ablation thickness.
In addition, supportive government policies are anticipated to promote corporate expansion. According to the rules and regulations of medical device agencies in the U.S. and Japan, fundus imaging cameras must be updated every four years. By ensuring the quality of the equipment, this regulation improves diagnosis and treatment. The law is likely to maintain and increase the country's need for electronics.
Market Dynamics
The fundus cameras market is growing steadily because of the rising importance of early diagnosis and screening of retinal diseases, along with the evolution of advanced technology in digital ophthalmic imaging systems. The fundus camera allows for the imaging of the retina, optic disc, macula, and retinal blood vessels. Through this instrument, the retinal problems can be detected, documented, and monitored. The fundus camera industry includes mydriatic, non-mydriatic, hybrid, and retinopathy of prematurity (ROP) fundus cameras. The growing prevalence of diabetic retinopathy, age-related macular degeneration (AMD), glaucoma, and other retinal diseases, as well as the increasing number of diabetes cases and aging population, is contributing to the growth of the industry. Besides, technological innovations like ultra-widefield imaging, artificial intelligence-assisted retinal image interpretation, cloud-based image storage, teleophthalmology integration, and hand-held fundus camera solutions are further enhancing the growth potential of the industry.
Increasing prevalence of retinal diseases around the world and growing emphasis on preventive ophthalmological care are some of the key drivers of the fundus camera market. The increasing adoption of digital fundus photography devices is helping physicians in detecting diabetes-induced retinopathy, glaucoma, age-related macular degeneration, retinopathy caused by hypertension, and various other eye ailments at an early stage. Implementation of diabetes eye screening programs, high levels of awareness regarding avoidable blindness, and growing need for regular retinal checks are boosting the deployment of these devices in hospitals as well as ophthalmology clinics. Moreover, rising use of artificial intelligence-based retinal screening solutions and teleophthalmology services is increasing access to eye care.
Despite significant technological advancements, widespread adoption of advanced fundus camera systems remains constrained by high acquisition costs and uneven availability of specialized ophthalmic infrastructure. Premium imaging systems equipped with ultra-widefield capabilities, OCT integration, artificial intelligence software, and cloud connectivity require substantial capital investment, making procurement challenging for smaller healthcare facilities and independent ophthalmic practices. Furthermore, limited reimbursement for routine retinal screening in certain regions, shortage of trained ophthalmic personnel, and infrastructure limitations in low- and middle-income countries may restrict broader market penetration and delay technology adoption.
Market Concentration & Characteristics
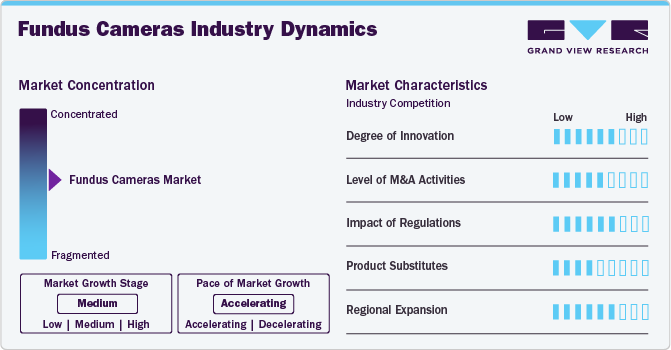
The fundus camera industry is concentrated around a few key players, with companies like Canon, ZEISS, and Optovue dominating the industry. These companies focus on high-quality, advanced imaging technologies for retinal screening, including non-mydriatic and portable models. The industry is characterized by continuous innovation in AI integration for disease detection, portability, and telemedicine compatibility. Growing demand for early detection of ocular diseases like diabetic retinopathy and glaucoma is driving expansion in the industry. In addition, there is a shift towards more compact, user-friendly devices, enabling broader accessibility in both clinical and home care settings, improving patient outcomes.
The industry is experiencing a high degree of innovation, driven by advancements like the collaboration between Avant Technologies Inc. and Ainnova Tech Inc. In November 2024, their integration of Ainnova’s low-cost retinal camera with Vision AI software marks a major leap. This technology enables seamless retinal image capture and AI-powered analysis for early detection of ocular and systemic diseases. By combining affordable imaging with artificial intelligence, this innovation improves accessibility, enhances diagnostic accuracy, and supports proactive disease management. The integration of AI in retinal imaging promises to revolutionize routine healthcare screenings and expand detection capabilities worldwide.
 To learn more about this report, Download Free Sample Report
Mergers and acquisitions (M&A) activity in the industry has increased. In March 2018, Optomed Oy acquired Commit Oy, a healthcare software solutions company, marking a significant M&A activity in the fundus camera industry. The merger combined Optomed’s hand-held fundus cameras with Commit’s screening software, creating a robust international provider of comprehensive disease screening solutions. This acquisition enhances customer service, drives innovation, and strengthens international growth. Optomed plans to leverage Commit’s expertise in diabetic retinopathy and other disease screenings, particularly with Finland's successful screening programs, for global expansion. The merger underscores the growing trend of integrating software and imaging technologies in the fundus camera market.
Regulations significantly influence the industry by ensuring product safety, efficacy, and quality. A prime example is Optomed USA’s launch of the Optomed Aurora AEYE in May 2024, the first FDA-cleared handheld AI fundus camera for detecting diabetic retinopathy beyond the mild stage. The approval highlights the critical role of regulatory standards in advancing medical technology. With FDA clearance, this device offers immediate, on-the-spot retinal screenings in primary care settings, enhancing early disease detection. Its clinical success, with diagnostic sensitivity of 92%-93%, illustrates how regulations ensure both safety and effectiveness, driving innovation in retinal health management.
In the industry, product substitutes include various imaging technologies like optical coherence tomography (OCT) and slit-lamp biomicroscopy. OCT provides detailed cross-sectional images of the retina, offering high-resolution views for detecting conditions like macular degeneration and glaucoma. Slit-lamp biomicroscopy, combined with a retinal lens, allows ophthalmologists to examine the fundus without a specialized camera. Additionally, smartphone-based retinal imaging systems are emerging as affordable, portable substitutes, providing basic retinal screenings. While these alternatives may not match the accuracy and comprehensive functionality of traditional fundus cameras, they offer convenient options for initial screenings and remote healthcare applications.
Regional expansion in the industry is driven by increasing healthcare access, rising awareness of eye health, and a growing demand for advanced eye care solutions. Topcon Healthcare’s launch of the NW500 robotic fundus camera in the U.S. in January 2023 highlights this trend. The NW500, with its innovative slit scan technology and high-quality imaging, allows for quicker, non-dilated retinal screenings, enhancing both workflow efficiency and patient experience. These advancements make it easier to incorporate advanced eye care into diverse healthcare settings, expanding Topcon's presence in global markets while meeting the rising demand for reliable, accessible retinal diagnostics.
Analyst Perspective
Market trends within the fundus cameras industry continue to progress along with the developments in the field of digital ophthalmology, artificial intelligence, and telemedicine. Increased focus from the medical community on the early detection of diabetes retinopathy, glaucoma, age-related macular degeneration, and pediatric retinal disease leads to higher interest in the use of the latest retinal imaging technology in hospitals as well as ambulatory environments. Companies are more likely to concentrate on development of ultra-wide field imaging technology, handheld systems, cloud-based imaging management, and AI diagnostics algorithms that provide enhanced accuracy and ease of use of ophthalmic technology. With ongoing development of preventive eye screenings and remote retinal evaluation services, the need for high-tech fundus cameras will become even more obvious.
Product Insights
Based on product, the non-mydriatic fundus cameras segment led the market with the largest revenue share of 49.9% in 2025. It improves the ability of a practitioner to view and observe detailed retinal anatomy, thereby improving the diagnosis and management of eye diseases. Furthermore, non-mydriatic cameras use fundus photography, eliminating the need for dilating drops and bright lights; hence, fundus photography is more patient friendly. This property also helps glaucoma patients for whom dilation is contraindicated. Advancements in non-mydriatic cameras, such as fluorescein imaging, portability, and live-action systems, are anticipated to drive the market during the forecast period.
The hybrid fundus cameras segment is estimated to register the fastest CAGR from 2025 to 2030. These cameras combine traditional fundus imaging with advanced technologies like optical coherence tomography (OCT) and fluorescein angiography, offering enhanced diagnostic capabilities. The growing demand for more comprehensive and accurate retinal imaging, coupled with the increasing prevalence of eye diseases such as diabetic retinopathy and glaucoma, is driving the growth of hybrid fundus cameras. Their ability to provide detailed, multi-modal imaging in a single device makes them increasingly popular in clinical settings.
End Use Insights
Based on end-use, the ophthalmic & optometrist offices segment led the market with the largest revenue share of 68.7% in 2025. Hospitals include secondary care, tertiary care, and advanced care. Hospitals are mostly preferred for paediatric eye care services and complicated procedures where one or more ophthalmologists and diagnostic and surgical support services are available. However, preference for specialty eye clinics, such as ophthalmologist and optometrist offices, may restrain the market's growth.
 To learn more about this report, Download Free Sample Report
The ophthalmic & optometrist offices segment is estimated to register the fastest CAGR from 2025 to 2030 due to increasing optometrist practitioners, preference for primary eye care, and low-cost services by ophthalmic and optometrist offices compared to ophthalmologists. Furthermore, a stagnated supply of ophthalmologists allows optometric offices to dominate the market. For instance, the lack of ophthalmologists in low-income countries in the Asia Pacific, Latin America, and Africa increases the demand for optometrists in emerging regions.
Regional Insights
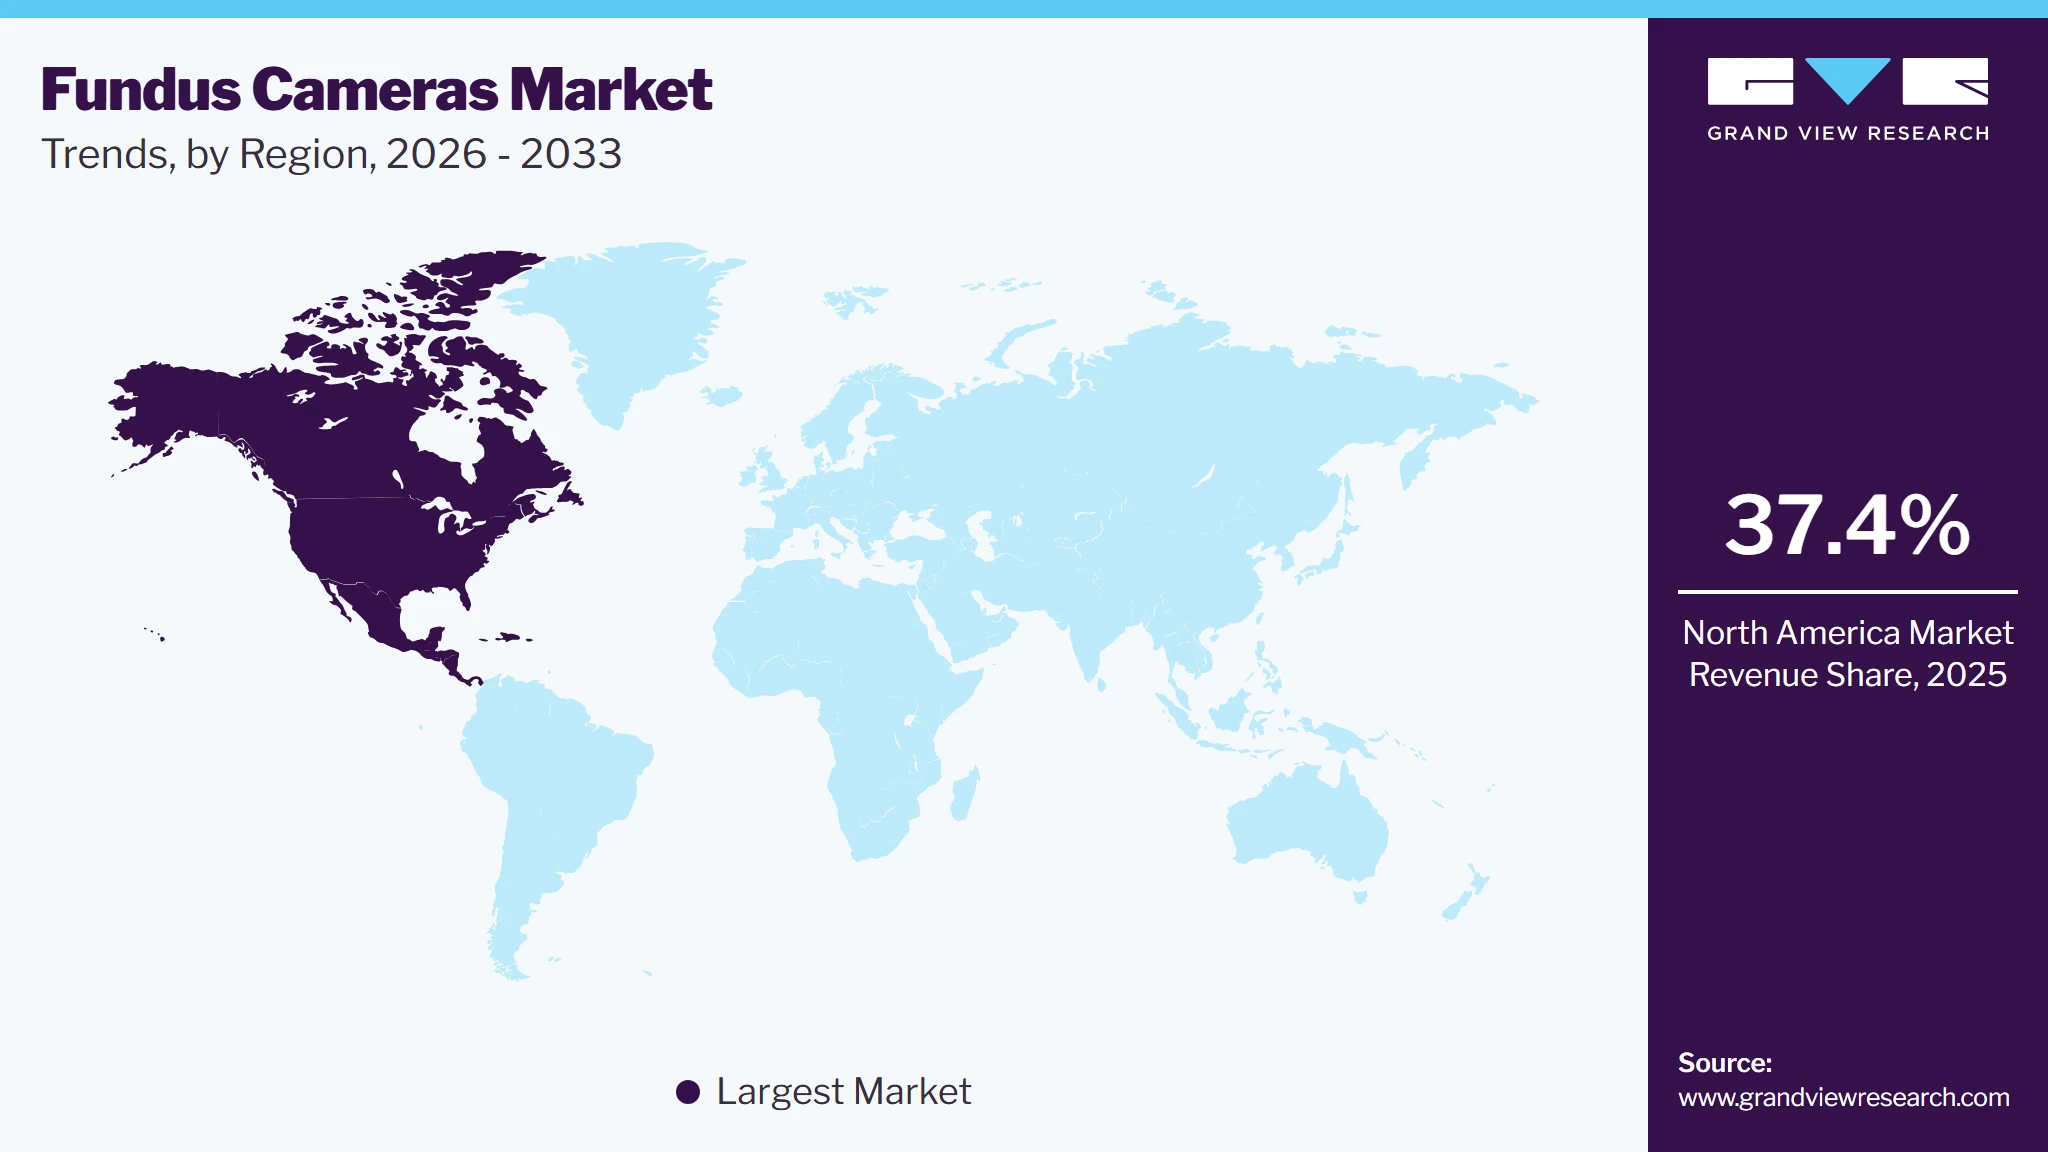
North America dominated the fundus cameras market with the largest revenue share of 37.4% in 2025. Major factors contributing to the growth of this region include the increasing geriatric population and technical advances in the field. Furthermore, the approval and launch of fundus cameras in the U.S. and Canada and the high adoption of new technologies will likely boost the market share. The widening application of fundus cameras for early detection and screening for eye diseases and lifestyle-associated diseases is anticipated to propel the market during the forecast period.
 To learn more about this report, Download Free Sample Report
U.S. Fundus Cameras Market Trends
The fundus cameras market in the U.S. held the largest share in the North America region in 2025, highlighting its major influence on the region's overall landscape. According to the CDC data released in May 2024, around 12 million Americans aged 40 and older experience some form of vision impairment, including 1 million who are blind. Additionally, approximately 6.8% of children under 18 in the U.S. have a diagnosed eye or vision condition, with nearly 3% suffering from blindness or significant vision impairment, which persists even with corrective lenses.
Europe Fundus Cameras Market Trends
The European fundus cameras market is likely to witness a CAGR of 6.5% over the forecast period due to the local presence of major market players, technological developments in fundus cameras, such as easy-to-use, portability, and development of hybrid cameras, and adoption of newer products. For instance, key players such as Carl Zeiss Meditec Group, Optomed Oy (Ltd.), and CenterVue SpA are headquartered in Europe. In November 2022, Optomed announced the release of Aurora IQ, a handheld fundus camera with built-in artificial intelligence for quicker eye inspection. Furthermore, a rising number of diabetic retinopathy patients and the geriatric population is expected to boost the overall market during the forecast period.
The fundus cameras market in the UK is growing steadily, driven by an increasing demand for early detection of retinal diseases like diabetic retinopathy and age-related macular degeneration. In 2023, the market expanded by 6%, with a notable shift towards non-mydriatic and portable fundus cameras. The National Health Service (NHS) reported that over 2.5 million diabetic patients were screened for retinal conditions, boosting the adoption of fundus cameras in both clinical and remote settings.
France fundus cameras market is experiencing steady growth due to increasing awareness of eye health and advancements in diagnostic technology. The market is driven by the rising prevalence of diabetic retinopathy, macular degeneration, and other retinal diseases. In 2023, the French healthcare system saw a 5% increase in the adoption of fundus cameras, with non-mydriatic and portable models gaining traction in clinical and mobile healthcare settings. Additionally, the introduction of AI-driven fundus cameras is expected to boost market growth by 7% annually through 2025, enhancing early detection and enabling more efficient screenings across the country.
The fundus cameras market in Germany is expected to expand in the foreseeable future as people become more aware of potential issues linked to eye care, like infections or discomfort. This growing awareness has resulted in a stronger focus on ensuring the quality and dependability of vision correction products.
Asia Pacific Fundus Cameras Market Trends
The Asia Pacific fundus cameras market is expected to grow fastest from 2025 to 2030, driven by the rising prevalence of eye diseases like cataracts, glaucoma, and refractive errors, along with an aging population and workforce. Technological innovations and government efforts to enhance healthcare infrastructure also drive market expansion.
Countries like India and China, with large populations and increasing cataract surgery rates, are critical contributors to this growth. For instance, Samsung's initiative, announced on October 13, 2022, through its Galaxy Upcycling program, highlights the growing role of technology in expanding access to eye care. By repurposing old Galaxy devices into affordable EYELIKE Fundus Cameras, Samsung addresses the need for cost-effective retinal screening in underserved areas, particularly in low- and middle-income countries. This initiative significantly contributes to the fundus camera market by making retinal imaging accessible to both medical and non-medical professionals. It also showcases how innovative, sustainable solutions can increase screening capacities, helping to combat vision loss globally and improve early detection of conditions leading to blindness.
The fundus cameras market in China is steadily growing, with significant advancements in AI technology. In November 2018, Baidu launched an AI-powered tool to detect ocular fundus conditions that could cause blindness. The AI Fundus Camera screens for three eye diseases and generates reports from photos taken without a physician's assistance. Developed in collaboration with Chinese eye hospitals, the system focuses on diabetic retinopathy, macular degeneration, and glaucoma. Trained on labeled fundus images, the AI achieved 94% sensitivity and specificity in detecting these conditions, enhancing the efficiency and accessibility of eye disease screenings.
Japan fundus cameras market is primarily driven by the high volume of cataract surgeries, which commonly require ophthalmic sutures. Japan has one of the highest rates of cataract surgeries globally, contributing significantly to the demand for these products. Additionally, Japan invests heavily in healthcare, with the government allocating substantial funds toward advanced eye care services. In 2023, Japan’s healthcare expenditure reached over USD 400 billion, further supporting the growth of the fundus cameras market.
Latin America Fundus Cameras Market Trends
The fundus cameras market in Latin America is experiencing steady growth. Improving healthcare infrastructure, along with greater access to advanced surgical technologies, is fueling the demand for fundus cameras in the region. In addition, rising awareness of eye care and government initiatives to reduce vision impairment are contributing to market expansion. The growing number of ophthalmic surgeries and investments in medical devices further support the market’s positive trajectory.
Middle East & Africa Fundus Cameras Market Trends
The Middle East and Africa fundus cameras marketis anticipated to witness robust growth over the forecast period, is driven by the increasing prevalence of eye diseases, especially in the aging population, and the government's focus on healthcare improvements. Moreover, the rise in disposable income and lifestyle changes, including increased screen time, contribute to heightened demand for vision care services and products.
Key Fundus Cameras Company Insights
The competitive scenario in the fundus cameras industry is highly competitive, with key players such as Carl Zeiss Meditec, Inc., NIDEK Co., Ltd. and others. The major companies are undertaking various organic and inorganic strategies such as new product development, collaborations, acquisitions, mergers, and regional expansion to serve the unmet needs of their customers.
Key Fundus Cameras Companies
The following key companies have been profiled for this study on the fundus cameras market.
-
Carl Zeiss Meditec, Inc.
-
Kowa Company Ltd.
-
Optomed Oy (Ltd.)
-
Optovue, Incorporated
-
CenterVue SpA
-
NIDEK Co., Ltd.
-
Topcon Medical Systems, Inc.
-
Clarity Medical Systems, Inc.
-
Canon, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Carl Zeiss Meditec, Inc.; Kowa Company Ltd.; NIDEK Co., Ltd.; Topcon Medical Systems, Inc.; Canon, Inc.)
- Established manufacturers focus on comprehensive ophthalmic imaging portfolios by integrating fundus cameras with OCT, fluorescein angiography, ultra-widefield imaging, AI-assisted diagnostic software, and cloud-based workflow management solutions. They emphasize continuous product innovation, regulatory approvals, strategic partnerships with hospitals and eye care networks, and expansion of global distribution capabilities.
- Strong global brand recognition, extensive installed customer base, diversified ophthalmic imaging portfolios, established clinical validation, broad service infrastructure, and long-standing relationships with ophthalmology practices provide sustainable competitive advantage.
- Dependence on capital equipment purchasing cycles, premium product pricing, lengthy procurement processes, and increasing competition from emerging portable imaging providers may limit growth in price-sensitive markets.
Emerging Players (Eigen, MedCom, Focal Healthcare, UC-Care Medical Systems Ltd., GeoScan Medical)
- Emerging companies prioritize portable fundus imaging solutions, AI-enabled retinal diagnostics, cloud-based teleophthalmology platforms, compact imaging systems, and cost-effective screening technologies targeting outpatient clinics and community-based screening programs. They focus on product differentiation through mobility, ease of use, and digital connectivity while expanding strategic collaborations with healthcare providers and distributors.
- Innovative portable imaging technologies, flexible product development, artificial intelligence integration, competitive pricing strategies, and strong focus on telemedicine applications enable rapid adoption across decentralized healthcare settings and screening programs.
- Limited global commercial reach, smaller installed customer base, comparatively lower brand recognition, dependence on strategic distribution partnerships, and regulatory expansion challenges may restrict international market penetration compared with larger multinational competitors.
Recent Developments
-
In October 2024, Visionix unveiled the VX 610, a nonmydriatic automated fundus camera, at Vision Expo West. It features auto alignment, focus, and capture, with a compact design and no need for pupil dilation thanks to cross-polarized light. The device is tablet-driven, telehealth-ready, and ideal for retinal screening, including diabetic retinopathy.
-
In May 2024, Remidio Inc. is set to deploy its 1000th FOP-NM handheld fundus camera in the U.S. this quarter. Since 2019, these portable, non-mydriatic devices have transformed diabetic retinopathy screening by eliminating dilation and offering high-quality images. Their ease of use has gained widespread acceptance, enhancing access to retinal care.
-
In March 2024, the University of Colorado Ophthalmology residents began using portable fundus photography cameras to enhance on-call evaluations. These smartphone-sized cameras allow for efficient, comprehensive imaging, improving patient assessments and follow-up care. The technology facilitates real-time supervision by physicians, ensuring accurate diagnoses and treatment plans in hospital settings.
-
In November 2023, Tohoku University has developed a new fundus camera using oblique illumination, which improves imaging of the retina and optic nerve. This technology enhances image contrast and allows for quasi-3D views, potentially enabling patients to capture their own retinal images at home. The approach is cost-effective, simple, and real-time.
Fundus Cameras Market Report Scope
Report Attribute
Details
Market size in 2025
USD 392.5 million
Estimated market size in 2026
USD 416.2 million
Projected market size by 2033
USD 657.6 million
Growth rate
CAGR of 6.8% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; South Korea; Thailand; Australia; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Carl Zeiss Meditec, Inc.; Kowa Company Ltd.; Optomed Oy (Ltd.); Optovue, Incorporated; CenterVue SpA; NIDEK Co.Ltd.; Topcon Medical Systems, Inc.; Clarity Medical Systems, Inc.; Canon, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Fundus Cameras Market Report Segmentation
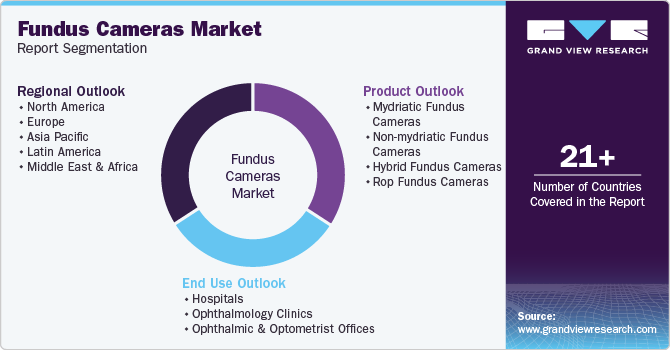
This report forecasts revenue growth at global, regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global fundus cameras market report based on product, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, 2021 - 2033)
-
Mydriatic fundus cameras
-
Tabletop
-
Handheld
-
-
Non- mydriatic fundus cameras
-
Tabletop
-
Handheld
-
-
Hybrid fundus cameras
-
ROP fundus cameras
-
-
End Use Outlook (Revenue, 2021 - 2033)
-
Hospitals
-
Ophthalmology Clinics
-
Ophthalmic & Optometrist Offices
-
-
Regional Outlook (Revenue, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
India
-
China
-
Japan
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The Fundus Cameras market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Fundus Cameras segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Mydriatic Fundus Cameras
Revenue is generated through the sale and utilization of fundus imaging systems designed for retinal examinations following pharmacological pupil dilation. Manufacturers capture revenue through capital equipment sales, high-resolution imaging software, image management platforms, service contracts, software upgrades, and accessories. These systems continue to be preferred in comprehensive ophthalmology practices requiring superior image quality for detailed retinal evaluation.
Non-mydriatic Fundus Cameras
Revenue is derived from digital fundus cameras capable of capturing retinal images without pharmacological dilation, supporting routine screening and outpatient eye examinations. Manufacturers generate revenue through equipment sales, AI-enabled image analysis software, cloud-based image storage, maintenance services, and workflow integration solutions. Growing adoption in diabetic retinopathy screening and primary eye care continues to support demand for this segment.
Hybrid Fundus Cameras
Revenue is generated through multifunctional imaging systems capable of operating in both mydriatic and non-mydriatic modes while integrating advanced imaging capabilities such as fluorescein angiography, ultra-widefield imaging, and multimodal retinal diagnostics. Manufacturers benefit from premium equipment pricing, software licensing, imaging upgrades, and recurring service agreements. Increasing demand for versatile ophthalmic imaging platforms continues to drive growth within this segment.
ROP Fundus Cameras
Revenue is derived from specialized retinal imaging systems designed for neonatal retinal examinations and retinopathy of prematurity screening. Manufacturers generate revenue through dedicated neonatal imaging devices, portable handheld systems, imaging software, accessories, maintenance contracts, and telemedicine-enabled image sharing solutions. Increasing neonatal screening initiatives and expansion of pediatric ophthalmology services continue to support adoption.
Segment - End-use
Revenue capture definition
Hospitals
Revenue is generated through procurement and utilization of advanced fundus imaging systems by tertiary hospitals, multispecialty hospitals, academic medical centers, and government healthcare institutions providing comprehensive ophthalmic diagnostics. Manufacturers benefit from capital equipment sales, enterprise imaging integration, software licensing, maintenance contracts, and long-term service agreements.
Ophthalmology Clinics
Revenue is derived from specialized ophthalmology clinics utilizing fundus cameras for routine retinal imaging, disease diagnosis, treatment planning, and longitudinal patient monitoring. Increasing patient volumes, expansion of retinal specialty practices, and adoption of AI-assisted diagnostic workflows continue to support equipment utilization, software upgrades, and recurring service revenues.
Ophthalmic & Optometrist Offices
Revenue is generated through adoption of compact and non-mydriatic fundus cameras by optometrists and independent ophthalmic offices performing routine eye examinations, diabetic retinopathy screening, glaucoma assessment, and preventive vision care. Growing emphasis on early disease detection and expansion of primary eye care services continue to support market growth within this segment.
Estimation Model
01. Scope Definition
02. Build Installed Base
03. Estimate Procedure Volume
04. Revenue Conversion
What is being sized?
How large is total addressable market?
What portion of retinal examinations utilize fundus cameras?
How does volume become revenue?
PROCESS STEPS
PROCESS STEPS
PROCESS STEPS
PROCESS STEPS
Define Fundus Cameras Market Scope
Estimate Annual Installed Base of Fundus Camera Systems
Assess Annual Retinal Imaging Procedures Across Healthcare Settings
Determine ASPs of Systems By Product
Scope Product, and End Use Segments
Segment Installed Systems by Product
Evaluate Utilization Rates By Fundus Cameras Type
Estimate Revenue from Sales of Equipment
Establish Geographic Coverage (Global/Regional)
Assess Annual Replacement Cycles of Equipment
Analyze Patient Throughput, And Screening Frequency
Apply Regional Pricing Variations
Align on base year & forecast horizon (2026-2033)
Forecast Installed Base Growth Across Regions
Validate Through Industry Interviews
Cross-validate with Company Revenues and Public Findings
DATA SOURCES: FDACE MDR, PMDA, NMPA
DATA SOURCES: Hospital Procurement Databases, Company Annual Reports, Academic Research Infrastructure Records
DATA SOURCES: Primary interviews, clinical surveys, Industry experts
DATA SOURCES: Company Annual Reports, Distributor pricing sheets, procurement data, expert interviews
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Landscape Analysis
Conducted a comprehensive assessment of leading fundus camera manufacturers by evaluating digital retinal imaging technologies, mydriatic and non-mydriatic imaging systems, hybrid imaging platforms, ROP fundus cameras, artificial intelligence-enabled diagnostic capabilities, teleophthalmology integration, regulatory approvals, product portfolios, pricing strategies, commercialization approaches, geographic presence, strategic partnerships, mergers and acquisitions, and investment initiatives. The assessment included detailed benchmarking of established and emerging participants to understand technology positioning and competitive differentiation across global ophthalmic imaging markets.
Enables stakeholders to benchmark technology leadership, identify product innovation trends, evaluate competitive positioning, understand commercialization strategies, compare product portfolios, assess partnership opportunities, and formulate investment and market expansion strategies within the retinal imaging ecosystem.
Segment by Application Analysis
Conducted a detailed assessment of fundus camera adoption across mydriatic, non-mydriatic, hybrid, and ROP fundus camera segments by evaluating utilization across hospitals, ophthalmology clinics, and ophthalmic & optometrist offices. The study assessed imaging procedure volumes, equipment procurement trends, workflow integration, technology adoption rates, patient throughput, screening program expansion, purchasing behavior, and diagnostic utilization patterns to estimate demand across each product and end-user segment.
Enables stakeholders to identify high-growth product segments, optimize commercialization strategies, prioritize product development, understand procurement trends, evaluate customer adoption patterns, forecast equipment demand, and support strategic business planning across diverse ophthalmic care settings.
Macroeconomic Analysis
Conducted an in-depth assessment of global retinal disease prevalence, diabetic population growth, aging demographics, blindness prevention initiatives, healthcare expenditure, reimbursement policies, ophthalmic infrastructure development, regulatory landscape, and adoption of digital ophthalmology technologies influencing demand for fundus cameras. The study also evaluated government-led diabetic retinopathy screening programs, expansion of teleophthalmology services, artificial intelligence adoption, and investment trends impacting market growth across developed and emerging healthcare systems.
Enables stakeholders to understand demographic, epidemiological, economic, regulatory, and healthcare system factors influencing demand within the fundus cameras market. The study supports long-term forecasting, manufacturing capacity planning, pricing strategy development, regional market expansion decisions, investment prioritization, and evaluation of future growth opportunities driven by evolving ophthalmic screening practices.
Frequently Asked Questions About This Report
North America dominated the fundus cameras market with a share of 37.4% in 2024. This is attributable to the high awareness of eye disorders, increasing chronic disorders, and technical advances in digital and handheld devices.
Some key players operating in the fundus cameras market include Carl Zeiss Meditec, Inc.; Kowa Company Ltd.; Optomed Oy (Ltd.); Optovue Incorporated; CenterVue SpA; NIDEK Co., Ltd.; Topcon Medical Systems, Inc.; Clarity Medical Systems, Inc.; and Canon, Inc.
Key factors that are driving the fundus cameras market growth include increasing eye disorders and supportive government regulations.
The non-mydriatic cameras accounted for the largest industry share of 49.4% in 2024, and the segment is further expected to witness substantial growth over the forecast period.
The global fundus cameras market size was valued at USD 370.6 million in 2024 and is estimated at USD 416.2 million for 2026.
The global fundus cameras market is expected to grow at a CAGR of 6.4% from 2025 to 2030, reaching USD 535.0 million by 2030.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


