
- Home
- »
- Paints, Coatings & Printing Inks
- »
-
Fusion Bonded Epoxy Coatings Market Report, 2026-2033GVR Report cover

Fusion Bonded Epoxy Coatings Market (2026 - 2033)
Size, Share & Trends Analysis Report By End Use (Oil & Gas, Water & Wastewater, Construction & Infrastructure), By Application (Rebar, Pipelines, Valves & Fittings, Structural Steel), By Region, And Segment Forecasts
Market Size, 2025
$7.3BMarket Estimate, 2026
$7.5BMarket Forecast, 2033
$11.3BCAGR, 2026–2033
6.1%Fusion Bonded Epoxy Coatings Market Summary
The global fusion bonded epoxy coatings market size was valued at USD 7.3 billion in 2025 and is projected to grow from USD 7.5 billion in 2026 to USD 11.3 billion by 2033, at a CAGR of 6.1% from 2026 to 2033. The Asia Pacific held the largest share of 42.6% of the global market in 2025. The market is primarily driven by sustained investments in oil & gas pipeline infrastructure and expanding water & wastewater transmission networks, particularly across Asia Pacific and the Middle East.
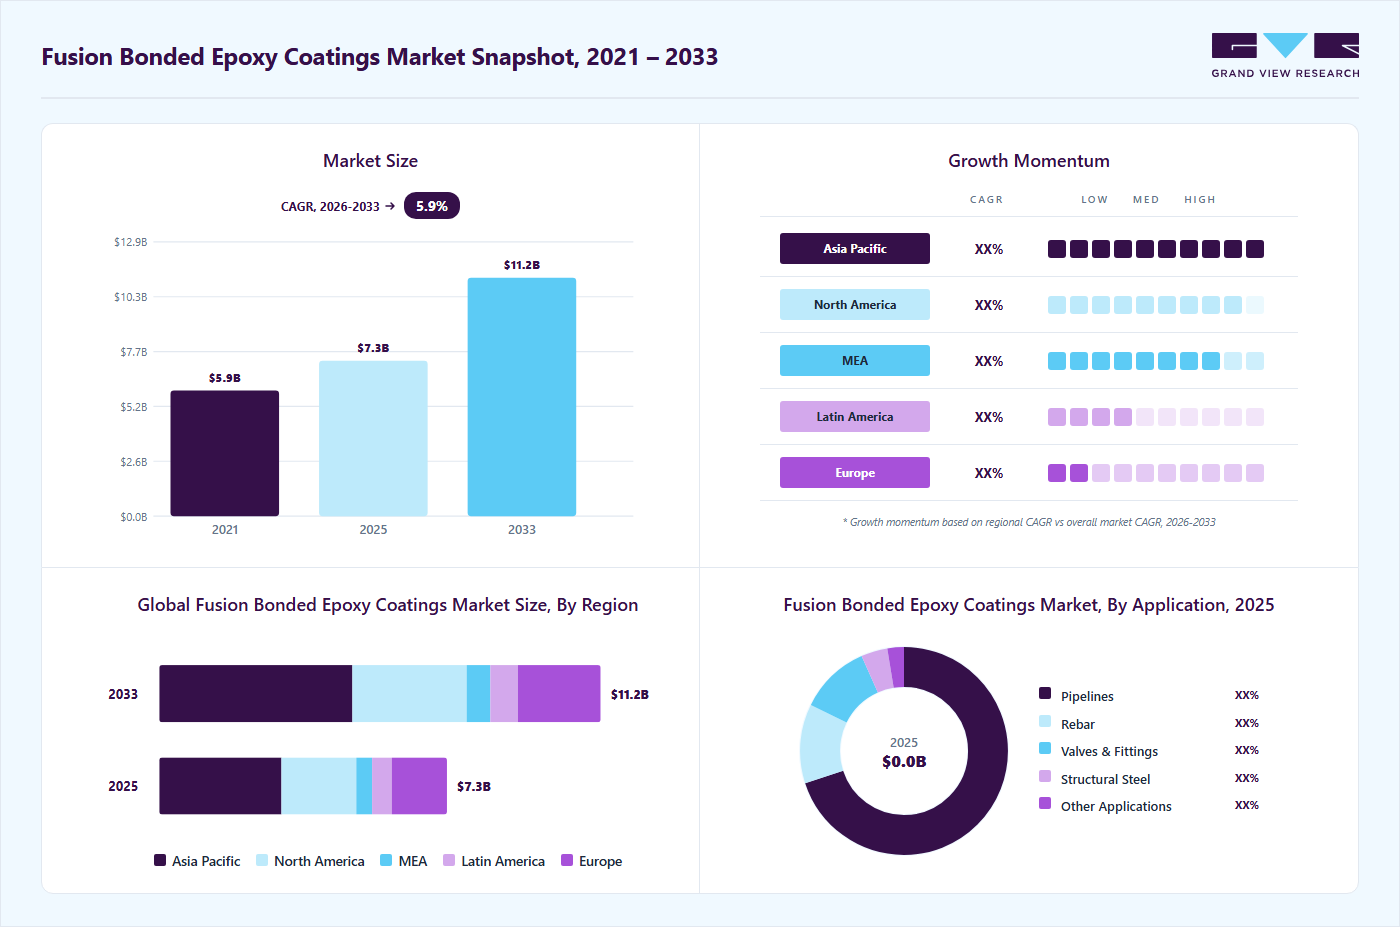 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By application: Pipelines segment held the largest revenue share of 70.4% in 2025.
- By application: Rebar segment is expected to grow at a CAGR of 6.3% over the forecast period.
- By end-use: Oil & gas segment held the largest revenue share of 57.4% in 2025.
Regional Highlights- Largest regional market: Asia Pacific (42.6% revenue share, 2025)
- By country: The China led the Asia Pacific market in 2025.
Market Size & Forecast
- Market size in 2025: USD 7.3 Billion
- Estimated market size in 2026: USD 7.5 Billion
- Projected market size by 2033: USD 11.3 Billion
- CAGR (2026-2033): 6.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Increasing regulatory emphasis on corrosion prevention, asset longevity, and lifecycle cost optimization is accelerating the adoption of FBE coatings across pipelines, valves & fittings, and reinforcing steel applications. The growing need to rehabilitate aging pipeline infrastructure in North America and Europe, coupled with rising urbanization and industrialization in emerging economies, continues to reinforce demand for high-performance protective coatings.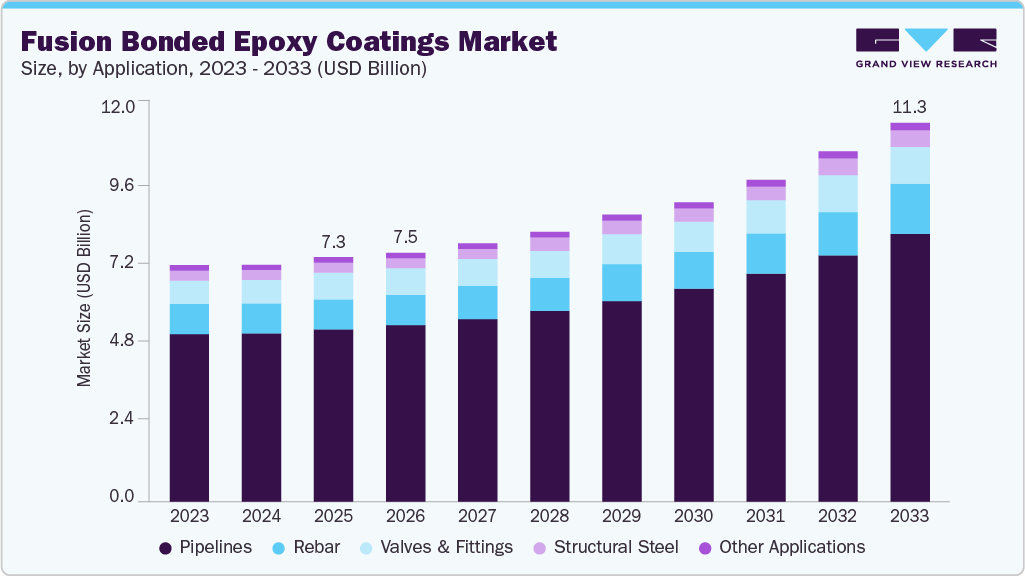 To learn more about this report, Download Free Sample Report
Significant growth opportunities are emerging from the rapid expansion of municipal water infrastructure, including desalination, irrigation, and potable water distribution projects, where FBE-coated pipes and rebar offer superior durability and compliance with safety standards. Furthermore, the ongoing transition toward hydrogen and CO₂ transport pipelines, along with increasing investments in offshore and subsea infrastructure, is expected to create new application avenues for advanced FBE formulations. Technological advancements by key players such as PPG Industries, Arkema, and BASF in high-temperature, abrasion-resistant, and multi-layer coating systems are further unlocking value-added opportunities across harsh operating environments.
Despite favorable demand fundamentals, the market faces challenges from the increasing adoption of alternative coating systems, such as three-layer polyethylene (3LPE) and polypropylene (3LPP), particularly in high-performance pipeline applications. Volatility in epoxy resin raw material prices, driven by fluctuations in petrochemical feedstocks, continues to exert pressure on manufacturer margins. The capital-intensive and cyclical nature of oil & gas investments, along with stringent environmental and application standards, can lead to project delays and uneven demand patterns, thereby impacting the growth trajectory of FBE coatings across key end use industries.
Market Concentration & Characteristics
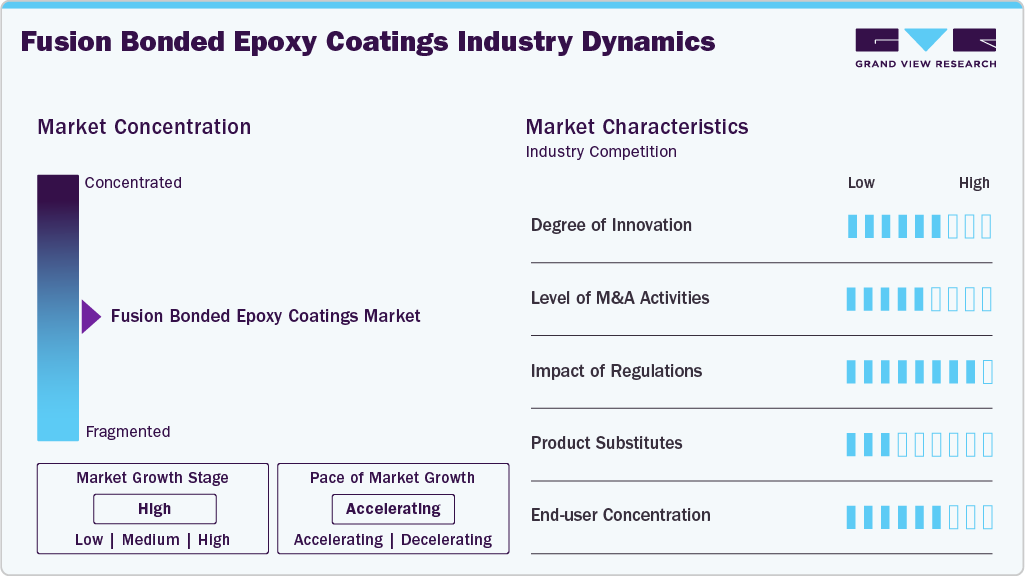
The global fusion bonded epoxy coatings industry is characterized by a moderately consolidated competitive landscape, with a mix of large multinational coatings manufacturers and specialized epoxy powder producers competing on technology, performance, and geographic reach. Key players such as PPG Industries, Sherwin-Williams, BASF, and Arkema leverage strong R&D capabilities, integrated supply chains, and global distribution networks to maintain their market positions. At the same time, niche and application-focused players such as Jotun, SolEpoxy, and VITRACOAT compete by offering specialized formulations tailored for pipelines, rebar, and harsh environmental conditions, particularly in regional markets.
 To learn more about this report, Download Free Sample Report
Competition is primarily driven by product performance (corrosion resistance, temperature tolerance), compliance with international standards (e.g., ISO, AWWA), and cost efficiency, especially in large-scale pipeline projects. Companies are increasingly focusing on strategic collaborations with EPC contractors, pipeline operators, and government infrastructure bodies to secure long-term supply contracts. The investments in advanced multi-layer coating systems, environmentally compliant formulations, and localized manufacturing capabilities are emerging as key differentiators. While global players dominate high-value projects, regional manufacturers continue to gain traction through competitive pricing and proximity to end-use markets, resulting in a dynamic and evolving competitive environment.
Application Insights
The pipelines segment held the largest revenue share of 70.4% in 2025, driven by the extensive application of fusion bonded epoxy coatings in oil & gas transmission and water distribution networks, where long-term corrosion protection and mechanical integrity are critical. FBE coatings are widely preferred for pipeline applications due to their excellent adhesion, chemical resistance, and durability under high-pressure and harsh environmental conditions, making them a standard solution across upstream, midstream, and downstream infrastructure. The ongoing investments in cross-country pipeline expansion projects in Asia Pacific and the Middle East, along with the rehabilitation of aging pipeline infrastructure in North America and Europe, have further reinforced the dominance of this segment.
The rebar segment represents the second-largest application, supported by increasing adoption of epoxy-coated reinforcing steel in bridges, highways, and coastal infrastructure to enhance durability and reduce maintenance costs. The valves & fittings segment, closely linked to pipeline infrastructure, continues to witness steady demand as these components require high-performance coatings to ensure corrosion resistance and operational reliability. The structural steel segment exhibits moderate growth due to competition from alternative coating technologies, although it remains relevant in select industrial and marine environments. Other applications, including storage tanks, offshore components, and specialty industrial equipment, contribute a smaller share but provide niche growth opportunities, particularly in environments requiring enhanced protection against corrosion and chemical exposure.
End Use Insights
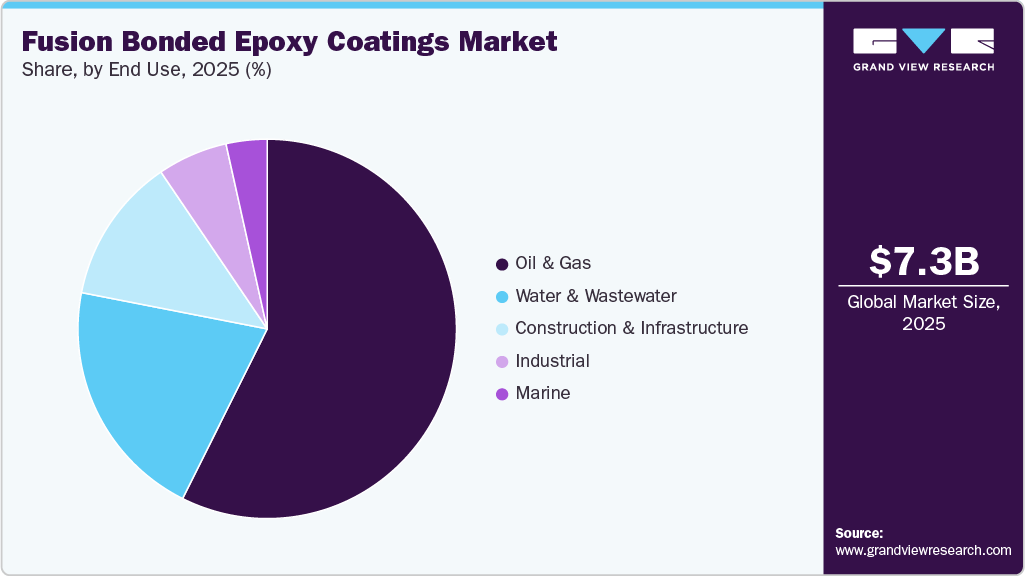
The oil & gas segment dominated the market with the largest revenue share of 57.4% in 2025, primarily due to the extensive deployment of FBE coatings in long-distance transmission pipelines for crude oil, natural gas, and refined products. The segment’s leadership is underpinned by the critical need for high-performance corrosion protection, mechanical durability, and long service life in harsh operating environments, including offshore and high-pressure applications. The continuous investments in pipeline expansion projects across Asia Pacific and the Middle East, coupled with the rehabilitation of aging pipeline infrastructure in North America and Europe, have significantly driven demand for FBE coatings in this segment.
 To learn more about this report, Download Free Sample Report
The water & wastewater segment represents the second largest and fastest-growing end use, supported by rising investments in municipal water distribution, desalination, and sewage treatment infrastructure, where FBE coatings are widely used for internal and external pipe protection. The construction & infrastructure segment, driven by increasing adoption of epoxy-coated rebar in bridges, highways, and urban development projects, continues to witness steady growth. The industrial segment benefits from applications in chemical processing, power generation, and manufacturing facilities, where corrosion resistance is critical for operational efficiency. The marine segment, although relatively smaller, finds application in offshore platforms and subsea pipelines, but its growth remains comparatively moderate due to competition from alternative coating technologies such as multilayer polyolefin systems.
Regional Insights
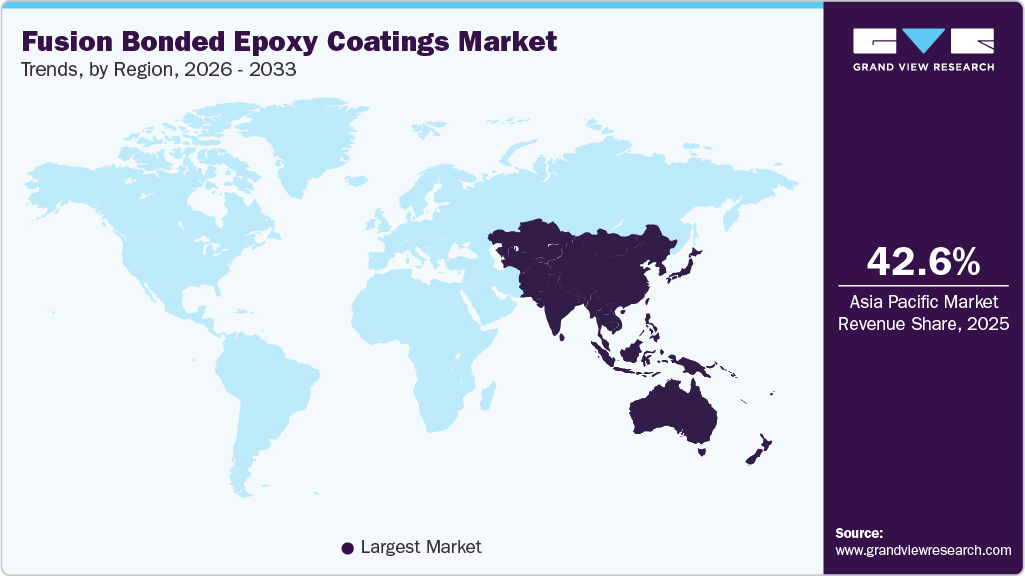
Asia Pacific fusion bonded epoxy coatings industry dominated the global market due to the rapid expansion of oil & gas pipeline networks, water infrastructure, and urban construction activities, particularly across emerging economies. Strong government investments in energy security, cross-country pipelines, and desalination projects, coupled with increasing industrialization, have significantly driven demand for high-performance corrosion protection coatings. The presence of large-scale manufacturing hubs and cost-competitive production ecosystems further supports regional market leadership.
 To learn more about this report, Download Free Sample Report
China fusion bonded epoxy coatings industry represented the largest contributor within the Asia Pacific region, driven by extensive investments in pipeline infrastructure, municipal water systems, and large-scale construction projects under national development initiatives. The country’s focus on infrastructure modernization, industrial expansion, and environmental protection standards has accelerated the adoption of advanced coating solutions, particularly in rebar and pipeline applications. Domestic manufacturing capabilities and strong supply chain integration further reinforce market growth.
North America Fusion Bonded Epoxy Coatings Market Trends
North America fusion bonded epoxy coatings industry held the second largest global revenue share, supported by aging pipeline infrastructure refurbishment, shale oil & gas expansion, and stringent regulatory frameworks governing corrosion protection. The region demonstrates high adoption of advanced coating technologies due to strict environmental and safety standards, particularly in the US and Canada. The increasing investments in water and wastewater infrastructure upgrades are contributing to steady market demand.
U.S. Fusion Bonded Epoxy Coatings Market Trends
The U.S. fusion bonded epoxy coatings industry led the North American market, driven by ongoing investments in pipeline replacement programs, offshore exploration activities, and infrastructure resilience initiatives. Regulatory mandates emphasizing asset integrity management and environmental compliance have accelerated the adoption of high-performance coatings. The presence of key market players and continuous technological advancements support sustained market growth.
Europe Fusion Bonded Epoxy Coatings Market Trends
Europe’s fusion bonded epoxy coatings industry is characterized by stringent environmental regulations, strong focus on sustainability, and rehabilitation of aging infrastructure, particularly in Western Europe. Demand is driven by offshore energy projects, district heating pipelines, and water infrastructure modernization, alongside increasing preference for eco-friendly coating solutions. The region’s mature industrial base ensures stable but relatively moderate growth.
Germany fusion bonded epoxy coatings industry is a key market within Europe, supported by its advanced industrial sector, strong engineering capabilities, and emphasis on infrastructure durability. The country’s investments in energy transition projects, including hydrogen pipelines and renewable integration, are creating new demand avenues for high-performance coatings. The strict regulatory compliance and quality standards drive the adoption of premium coating technologies.
Middle East & Africa Fusion Bonded Epoxy Coatings Market Trends
Middle East & Africa fusion bonded epoxy coatings industry is witnessing robust growth, primarily driven by large-scale oil & gas pipeline projects, offshore developments, and desalination infrastructure investments. Countries in the Gulf Cooperation Council (GCC) are investing heavily in energy infrastructure expansion and diversification, which is fueling demand for corrosion-resistant coatings. In Africa, gradual development of water and industrial infrastructure supports emerging opportunities.
Latin America Fusion Bonded Epoxy Coatings Market Trends
Latin America fusion bonded epoxy coatings industry demonstrated moderate growth potential, supported by investments in oil & gas exploration, pipeline expansion, and mining infrastructure, particularly in Brazil and Mexico. The region is also experiencing increasing demand for water infrastructure development and urban construction, although economic volatility and regulatory challenges may constrain growth to some extent. Nonetheless, rising focus on infrastructure modernization is expected to sustain market demand over the forecast period.
Key Fusion Bonded Epoxy Coatings Company Insights
Key players, such as 3M, Sherwin-Williams , Jotun, SolEpoxy, PPG Industries , and BASF SE are dominating the market.
3M
3M is a diversified technology company with a strong presence in advanced materials and industrial solutions, playing a strategic role in the global fusion bonded epoxy (FBE) coatings market through its high-performance protective coatings and material science expertise. The company leverages its core competencies in adhesives, sealants, and surface protection technologies to deliver durable, corrosion-resistant solutions tailored for critical applications such as pipelines, infrastructure, and industrial assets. Backed by robust R&D capabilities and a global manufacturing footprint, 3M focuses on innovation-driven product development, sustainability, and regulatory compliance, enabling it to maintain a competitive edge and strong customer relationships across key end-use industries including oil & gas, construction, and transportation.
Key Fusion Bonded Epoxy Coatings Companies:
The following key companies have been profiled for this study on the fusion bonded epoxy coatings market.
- 3M
- Sherwin-Williams
- Jotun
- SolEpoxy
- PPG Industries
- BASF SE
- Arkema
- Specialty Polymer Coatings
- VITRACOAT
- Tecosy
Fusion Bonded Epoxy Coatings Market Report Scope
Report Attribute
Details
Market size in 2025
USD 7.3 billion
Estimated market size in 2026
USD 7.5 billion
Projected market size by 2033
USD 11.3 billion
Growth rate
CAGR of 6.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, Volume in Kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
End use, application, region
Regional scope
North America; Europe; Asia Pacific; Middle East & Africa; Latin America
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; India; Japan; South Korea; Brazil; Argentina; South Africa; Saudi Arabia
Key companies profiled
3M; Sherwin-Williams; Jotun; SolEpoxy; PPG Industries; BASF SE; Arkema; Specialty Polymer Coatings; VITRACOAT; Tecosy
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Fusion Bonded Epoxy Coatings Market Report Segmentation
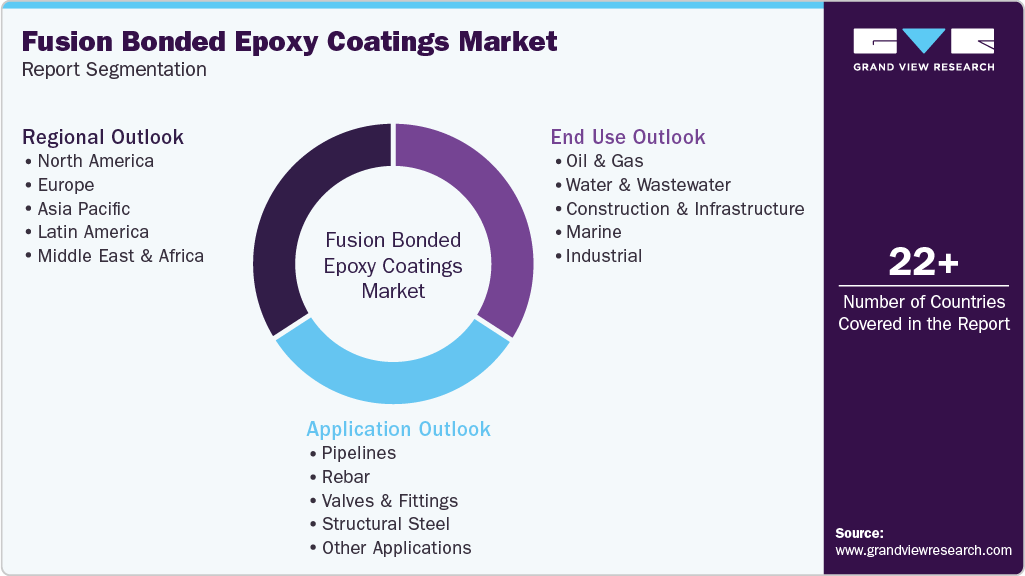
This report forecasts revenue & volume growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global fusion bonded epoxy coatings market report based on application, end use, and region.
 To learn more about this report, Download Free Sample Report
-
End Use Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Oil & Gas
-
Water & Wastewater
-
Construction & Infrastructure
-
Marine
-
Industrial
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Pipelines
-
Rebar
-
Valves & Fittings
-
Structural Steel
-
Other Applications
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Latin America
-
Brazil
-
Argentina
-
-
Frequently Asked Questions About This Report
Asia Pacific dominated with a 42.6% revenue share in 2025.
Pipelines segment dominated the market and accounted for the largest revenue share (over 70.0%) in 2025.
The oil & gas segment led with a 57.4% revenue share in 2025, while water & wastewater is the fastest-growing segment.
The global fusion bonded epoxy coatings market size was valued at USD 7.3 billion in 2025 and is estimated at USD 7.5 billion for 2026.
The global fusion bonded epoxy coatings market is expected to grow at a CAGR of 6.1% from 2026 to 2033, reaching USD 11.3 billion by 2033.
The pipelines segment dominated the market with a 70.4% revenue share in 2025 due to the critical need for high-performance corrosion protection in long-distance oil & gas and water transmission networks, where asset integrity and lifecycle cost optimization are paramount. The sustained investments in pipeline expansion, rehabilitation of aging infrastructure, and stringent regulatory standards have reinforced the large-scale adoption of advanced coating solutions in this segment.
Key players include 3M; Sherwin-Williams; Jotun; SolEpoxy; PPG Industries; BASF SE; Arkema; Specialty Polymer Coatings; VITRACOAT; Tecosy.
Market growth is primarily driven by rising investments in oil & gas pipeline infrastructure, water & wastewater networks, and large-scale construction projects, which necessitate advanced corrosion protection solutions to ensure asset longevity and operational efficiency. The stringent environmental and safety regulations, coupled with increasing focus on lifecycle cost optimization, are accelerating the adoption of high-performance coatings across key end-use industries.
About the Author(s)
Paints, Coatings & Printing Inks Research Team
Bulk Chemicals · Paints, Coatings & Printing InksThis report was authored by the paints, coatings & printing inks research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the paints, coatings & printing inks segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


