
- Home
- »
- Advanced Interior Materials
- »
-
Steel Market Size, Share And Growth Report, 2026-2033GVR Report cover

Steel Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Stainless Steel, Carbon Steel, Alloy Steel, Tool Steel), By Product (Flats, Longs), By End Use (Automotive, Building & Construction, Energy & Utilities), By Region, And Segment Forecasts
Market Size, 2025
$1,494.0BMarket Estimate, 2026
$1,525.8BMarket Forecast, 2033
$2,283.0BCAGR, 2026–2033
5.9%Steel Market Summary
The global steel market size was valued at USD 1,494.0 billion in 2025 and is projected to grow from USD 1,525.8 billion in 2026 to USD 2,283.0 billion by 2033, at a CAGR of 5.9% from 2026 to 2033. Asia Pacific dominated the market, accounting for 64.6% of revenue in 2025. The expansion of the building and construction sector, rising automotive demand, development of electrical and utilities infrastructure, and growth of industrial manufacturing are key factors driving demand for steel.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Carbon steel segment held the largest market share of 63.5% in 2025.
- By product: Flats segment held the largest market share of 51.5% in 2025.
- By end use: Building & construction segment held the largest market share of 79.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (64.6% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1,494.0 Billion
- Estimated market size in 2026: USD 1,525.8 Billion
- Projected market size by 2033: USD 2,283.0 Billion
- CAGR (2026-2033): 5.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Additionally, reprocessing and reusing steel further adds value to the overall steel market. The building and construction sector is one of the largest consumers of steel, with the material widely used in structural frameworks, reinforcement, bridges, transportation infrastructure, and commercial and residential buildings. Steel's high strength, durability, versatility, and recyclability make it well-suited for applications requiring long service life and structural reliability. According to the World Urban Forum, UNEP, and the Global Alliance for Buildings and Construction (GlobalABC) report for the year 2025-2026, the building and construction sector is growing between 11-13%. Increasing infrastructure investment, urban development, and construction activity across emerging economies are therefore expected to sustain demand for steel. To learn more about this report, Download Free Sample Report
The global steel market is also undergoing a significant transformation driven by sustainability and technological advancement. At present, the iron and steel industry consumes approximately 7% of the global energy supply and contributes approximately 7 to 9% of the global greenhouse gases. Steel manufacturers are increasingly investing in low-carbon production technologies, electric arc furnaces, renewable energy, and energy-efficient processes to reduce emissions and comply with increasingly stringent environmental requirements. At the same time, digitalization through artificial intelligence, the Internet of Things, automation, and data analytics is enabling manufacturers to improve production efficiency, optimize resource utilization, enhance quality control, and reduce operating costs.
Demand is further supported by the expansion of electric mobility and energy-efficient infrastructure. Global electric-car sales exceeded 20 million units in 2025, accounting for approximately one-quarter of new-car sales, thereby strengthening demand for steel used in vehicle bodies, chassis, motors, and charging infrastructure. Meanwhile, continued urbanization is supporting long-term construction and infrastructure requirements. The latest UN assessment indicates that around two-thirds of the global population is expected to live in urban areas by 2050, creating sustained demand for buildings, transportation networks, utilities, and other infrastructure.
 To learn more about this report, Download Free Sample Report
The industry is also witnessing strategic partnerships, technological collaborations, capacity expansion, and consolidation as steel producers seek to strengthen competitiveness and accelerate the transition toward sustainable production. Collectively, infrastructure investment, urbanization, automotive electrification, industrial expansion, and decarbonization initiatives are expected to remain key factors shaping the global steel market over the coming years.
Market Dynamics
The global steel market is driven by increasing infrastructure development, urbanization, industrial expansion, and growing demand from the automotive and energy sectors. Rising investments in residential and commercial construction, transportation networks, renewable energy infrastructure, and manufacturing facilities are supporting steel consumption across major economies. The growing adoption of electric vehicles is also creating demand for advanced, lightweight, and high-strength steel products. Additionally, the industry is undergoing a significant transformation toward sustainable and low-carbon steel production, with manufacturers investing in electric arc furnaces, renewable energy, energy-efficient technologies, and recycling capabilities.
However, supply chain disruptions, volatile raw material prices, high energy costs, and geopolitical uncertainties remain key challenges for steel producers. Transportation disruptions and fluctuations in iron ore, coking coal, and scrap prices can increase production costs and affect profitability. Nevertheless, the expansion of renewable energy, infrastructure modernization, and increasing demand for green steel are expected to create significant growth opportunities, while technological advancements and strategic partnerships continue to reshape the competitive landscape.
The expansion of building and infrastructure development is a major driver of global steel demand, as steel is extensively used in structural frameworks, reinforcement, bridges, railways, roads, airports, power infrastructure, and commercial and residential buildings. Increasing government spending on transportation, energy, utilities, and urban infrastructure is creating sustained demand for both structural and fabricated steel products. According to the World Steel Association, global steel demand in volume is expected to increase by 1.3% in 2026 to approximately 1.77 billion metric tons, with continued strength in public infrastructure investment supporting the recovery.
The growth of infrastructure-intensive emerging economies is particularly important for steel consumption. According to the CBRE's 2026 Asia Pacific Real Estate Market Outlook Mid-Year Review, commercial real estate in Asia Pacific grew by 27% in the first half of 2026. Steel demand in volume across ASEAN economies is also projected to increase by 3.5% in 2026, driven by infrastructure investment and manufacturing expansion. Urbanization is providing an additional long-term catalyst for demand. The latest UN World Urbanization Prospects 2025 reports that cities currently accommodate 45% of the global population, while two-thirds of global population growth through 2050 is expected to occur in cities. The number of megacities is projected to increase from 33 in 2025 to 37 by 2050, requiring substantial investment in housing, transportation, utilities, and public infrastructure. Consequently, continued infrastructure modernization, urban expansion, and construction activity are expected to sustain steel consumption and create opportunities for steel producers, particularly in rapidly developing economies across Asia and other emerging markets.
The increasing frequency of supply chain disruptions is constraining the growth of the global steel market by raising transportation costs, lengthening delivery times, and creating uncertainty about the availability of raw materials and finished steel products. Ongoing geopolitical tensions, including the Russia-Ukraine war and conflicts affecting the Red Sea and the Middle East, have disrupted established trade routes and increased risks for international shipments. The UN Trade and Development (UNCTAD) reported that by mid-2024, tonnage transiting the Suez Canal had declined by 70%, while arrivals around the Cape of Good Hope increased by 89% as vessels were rerouted away from the Red Sea. These longer routes have increased fuel consumption, insurance, chartering, and crew costs, and have also created port congestion and longer delivery schedules.
The disruption of the Black Sea shipping network following the Russia-Ukraine conflict has further altered established trade flows and affected the transportation of commodities and industrial materials. More recently, heightened geopolitical tensions in the Middle East have created additional risks for maritime transportation and energy supplies, potentially increasing fuel and logistics costs. Consequently, steel manufacturers and distributors face higher input and logistics costs, inventory-management challenges, production delays, and greater exposure to price volatility. Prolonged disruptions could compel producers to diversify their supplier base, maintain higher inventories, or shift toward regional sourcing, thereby increasing overall operating costs and potentially limiting market growth.
The rapid expansion of renewable energy and energy infrastructure presents a significant growth opportunity for the global steel market. The transition toward cleaner energy systems is driving large-scale investments in solar power, wind energy, electricity grids, energy storage, and hydrogen infrastructure, all of which require substantial quantities of steel. Steel is widely used in wind turbine towers, solar mounting structures, transmission infrastructure, substations, pipelines, storage facilities, and supporting construction, creating opportunities for steel producers across multiple applications.
Global investment in clean energy is expected to remain strong. According to the International Energy Agency (IEA), global energy investment is projected to reach USD 3.3 trillion in 2025, with approximately USD 2.2 trillion directed toward clean energy technologies, including renewables, grids, storage, and electrification. This represents roughly twice the investment expected in fossil fuels and highlights the accelerating shift toward energy-transition infrastructure. (iea.org)
The expansion of electricity networks is particularly important because increasing renewable generation requires significant investment in transmission and distribution infrastructure. The IEA estimates that global investment in electricity grids needs to increase to approximately USD 600 billion annually by 2030, creating additional demand for steel-intensive infrastructure. Furthermore, the growing emphasis on decarbonization is encouraging steel manufacturers to develop low-carbon and green steel, creating opportunities to capture premium demand from renewable energy, automotive, construction, and other sustainability-focused industries. Consequently, the convergence of energy transition, grid modernization, and industrial decarbonization is expected to create significant long-term opportunities for steel manufacturers.
Analyst Perspective
The global steel market is positioned for steady growth, supported by infrastructure development, urbanization, industrial expansion, and rising demand from construction, automotive, and energy sectors. The increasing adoption of electric vehicles and renewable energy infrastructure is creating additional demand for high-strength, lightweight, and specialized steel products. Furthermore, the industry is undergoing a structural shift toward low-carbon and sustainable steel production, encouraging investments in electric arc furnaces, recycling, renewable energy, and advanced manufacturing technologies. However, raw material price volatility, energy costs, geopolitical uncertainties, and supply chain disruptions remain key challenges for market participants. Overall, companies that strengthen production efficiency, supply-chain resilience, technological capabilities, and low-carbon offerings are better positioned to capitalize on emerging opportunities and maintain competitiveness.
Type Insights
The carbon steel segment dominated the steel market, accounting for 63.5% of revenue in 2025. Carbon steel is widely used in heavy-duty applications due to its high strength, durability, affordability, and versatility. Its properties can be adjusted by varying carbon content, enabling manufacturers to select grades with appropriate levels of hardness, toughness, weldability, and machinability for specific applications. Carbon steel also offers good structural integrity and load-bearing capability, making it particularly suitable for demanding construction and industrial applications. Growing investments in infrastructure, construction, automotive manufacturing, energy, and industrial development are driving global demand for carbon steel. In construction, it is extensively used in structural beams, columns, reinforcement bars, pipelines, and roofing systems due to its strength and cost-effectiveness. Furthermore, its applications in oil and gas pipelines, machinery, pressure vessels, bridges, railways, and heavy equipment are supporting consumption. The material's recyclability and established manufacturing infrastructure further enhance its appeal, while continued urbanization and industrialization are expected to sustain demand for carbon steel.
The stainless-steel segment is expected to grow at the fastest CAGR of 7.8% during the forecast period. Stainless steel is valued for its exceptional corrosion resistance, strength, durability, and aesthetic appeal, making it suitable for applications exposed to moisture, chemicals, heat, and demanding operating conditions. It is highly recyclable, easy to maintain, and available in a wide range of grades and finishes, supporting its use across diverse industries. Growing investments in construction, automotive, food processing, healthcare, energy, and industrial manufacturing are driving demand for stainless steel worldwide. In construction, it is used for façades, roofing, structural components, railings, and architectural applications because of its durability and appearance. The automotive industry uses stainless steel in exhaust systems, structural components, and other applications requiring corrosion and heat resistance. Furthermore, its extensive use in medical equipment, kitchen appliances, food-processing machinery, chemical-processing equipment, pipelines, and power-generation facilities is supporting market growth. The increasing emphasis on sustainable, long-lasting materials is expected to further strengthen demand for stainless steel.
Product Insights
The steel flats segment accounted for the largest market share, at 51.5%, in 2025, supported by strong demand from key end-use industries, particularly automotive and construction. The growing adoption of electric vehicles is increasing demand for high-strength and lightweight steel flat products, which help manufacturers improve vehicle efficiency and performance. In the construction sector, increasing emphasis on durable and sustainable building materials is further supporting demand for steel flat products. In addition, advancements in steel manufacturing technologies are improving product quality, production efficiency, and material performance, enhancing the segment's attractiveness. Strategic collaborations between steel producers and technology companies are also supporting innovation, process optimization, and market expansion.
The long steel segment is expected to grow at a CAGR of 6.6% during the forecast period, driven primarily by increasing construction and infrastructure development worldwide. Rapid urbanization and population growth are generating demand for reinforcing bars, structural sections, and other long steel products used extensively in residential, commercial, and infrastructure projects. Furthermore, investments in roads, bridges, railways, utilities, and other large-scale infrastructure projects are creating sustained demand for long steel. Rising industrialization across emerging economies is also supporting consumption as governments and private developers expand manufacturing facilities, industrial infrastructure, and urban development projects.
End Use Insights
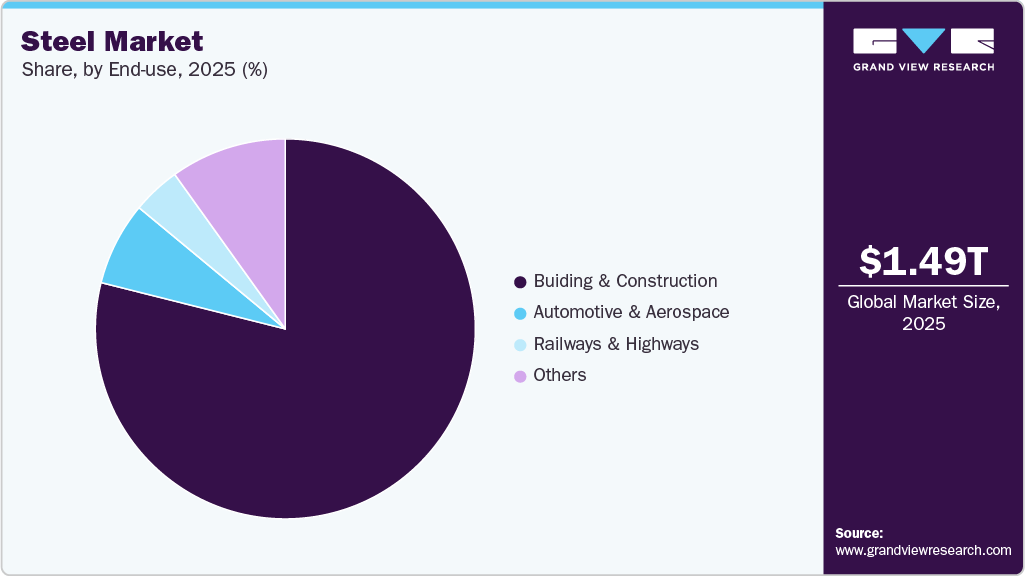
The building & construction segment accounted for the largest market share, at 79.0%, in 2025, driven by rapid urbanization, infrastructure development, and rising construction activity worldwide. Rising populations and expanding urban centers are increasing demand for residential, commercial, and infrastructure projects, thereby driving substantial steel consumption for structural applications. In addition, the growing emphasis on sustainable construction practices is strengthening steel demand, as its durability, strength, and recyclability make it a preferred material for long-term and resource-efficient construction.
 To learn more about this report, Download Free Sample Report
The automotive segment is projected to grow at the fastest rate, at 6.3%, during the forecast period. In the automotive industry, increasing electric vehicle production is driving demand for lightweight, high-strength steel that improves vehicle safety, durability, and energy efficiency. Additionally, growth in the aerospace sector, supported by rising air travel and aircraft production, is increasing demand for specialized steel alloys used in critical, high-stress components. Continued technological innovation across both mobility sectors is therefore expected to sustain demand for advanced steel products and reinforce steel's role as a high-performance material.
Regional Insights
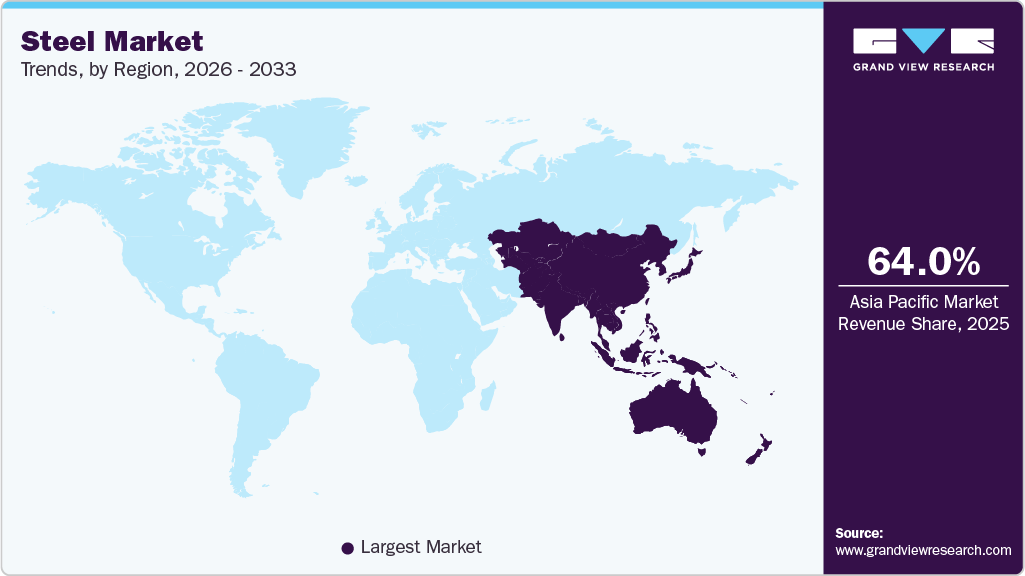
The Asia Pacific region accounted for the largest revenue share, at 64.6%, of the global steel market in 2025, and its dominance is expected to continue throughout the forecast period. Strong infrastructure development and rapid urbanization across countries such as China and India are driving substantial investments in highways, bridges, commercial buildings, residential construction, and other large-scale projects, thereby supporting steel consumption. In addition, the region's expanding automotive industry is generating significant demand for steel used in vehicle manufacturing. The diverse manufacturing base, coupled with increasing investments in renewable energy and power infrastructure, is further strengthening regional steel demand.
 To learn more about this report, Download Free Sample Report
China Steel Market Trends
China remains the world's largest steel producer and consumer, supported by its extensive construction, automotive, manufacturing, and energy & utilities sectors. Chinese steel exports reached approximately 119.02 million tons in 2025, representing a 7.5% increase and underscoring the country's significant role in the global steel industry. Continued urbanization and industrial expansion, along with government initiatives to strengthen economic growth and infrastructure development, are expected to sustain steel demand in the country. Furthermore, ongoing investments in construction, manufacturing capacity, transportation infrastructure, and clean energy are expected to reinforce China's position as a key contributor to the growth of the Asia-Pacific steel market.
North America Steel Market Trends
The North American steel market is expected to grow at a rate of over 5.5% over the forecast period, supported by substantial investments in infrastructure modernization and construction projects. Government initiatives, particularly in the U.S., aimed at upgrading aging infrastructure are generating sustained demand for steel across transportation, utilities, construction, and other infrastructure applications. In parallel, the resurgence of domestic manufacturing and reshoring activities is increasing demand for locally produced steel products. The growing focus on sustainability is also encouraging the use of recycled and low-carbon steel, further supporting market development across the region. The U.S. steel market accounted for the largest revenue share of more than 70.0% in the North American market in 2025, driven by robust construction activity and significant federal infrastructure investments. The expansion of key manufacturing industries, including automotive and aerospace, is further increasing demand for high-quality and specialized steel products. In addition, the growing adoption of green building practices and sustainable construction standards is strengthening demand for recycled and environmentally responsible steel solutions. These trends, combined with continued infrastructure spending and industrial investment, are expected to reinforce the U.S.'s position as the leading steel market in North America.
Key Steel Company Insights
The competitive landscape of the global steel industry is highly competitive and characterized by capacity expansion, strategic partnerships, acquisitions, vertical integration, and investments in low-carbon steel production. Leading producers such as China Baowu, ArcelorMittal, Nippon Steel, POSCO, Tata Steel, JSW Steel, and Nucor are pursuing strategies to strengthen their market positions and secure critical raw materials. For instance, Nippon Steel acquired a 30% stake in Canada's Kami iron ore project in 2025, strengthening its access to high-grade iron ore required for lower-carbon steelmaking. ArcelorMittal and Nippon Steel's AM/NS India joint venture is also expanding capacity through an 8.2 million-ton-per-year integrated steel plant in Andhra Pradesh, supporting long-term growth in India. In addition, ArcelorMittal announced 1 GW of new renewable energy projects in India to supply its AM/NS India operations. Such developments demonstrate the industry's increasing focus on capacity expansion, supply chain security, the energy transition, and technological advancement.
Some of the key players operating in the market include Nippon Steel Corporation, ArcelorMittal, and China Baowu Steel Group.
-
Nippon Steel Corporation is Japan’s largest steelmaker. It operates through business segments, namely Steelmaking & Steel Fabrication, Engineering, Chemicals, New Materials, and System Solutions. Its core segments are Steelmaking and Steel Fabrication, which include Engineering & Construction, Chemicals & Materials, and System Solutions. It delivers diverse products and caters to all key end-user industries of steel.
-
China Baowu Steel Group, an integrated steel producer founded by the Shanghai Baosteel Group Corporation, produces a range of steel products, including HR steel, CR sheets, heavy plates, pipes & tubes, bars & wire rods, and rail & section steel. It has a total manufacturing capacity of 50.95 Mtpa across 4 plants in China.
Key Steel Companies
The following are the leading companies in the steel market. These companies collectively hold the largest market share and dictate industry trends.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: ArcelorMittal, Nippon Steel Corporation, POSCO, China Baowu Steel Group, Tata Steel, JFE Steel Corporation
- Focus on large-scale integrated steel production, capacity expansion, and global supply chain optimization.
- Invest heavily in green steel technologies, electric arc furnaces (EAF), hydrogen-based steelmaking, and digital manufacturing systems.
- Strong financial capabilities, advanced R&D infrastructure, and established relationships with OEMs and industrial customers.
- Extensive global manufacturing footprint with diversified steel product offerings across flat, long, and specialty steel segments.
- Significant capital expenditure requirements for decarbonization and modernization initiatives.
- Increasing pressure from carbon emission regulations, trade tariffs, and global oversupply conditions, particularly from Asian markets.
Emerging Players: Stegra, Hongye Steel (Shandong) Co., Ltd., Meranti Steel
- Increase investments in green steel initiatives, process automation, and export-oriented operations to strengthen regional and international market presence.
- Target growing demand from infrastructure, construction, industrial manufacturing, and renewable energy sectors through strategic expansion and product diversification.
- Modern production infrastructure with increasing focus on operational efficiency and sustainable steelmaking practices.
- Competitive pricing strategies are supported by regional manufacturing advantages and flexible production capabilities.
- Limited global distribution networks and high capital requirements for scaling low-carbon steel production technologies.
- Comparatively smaller production scale and lower brand recognition than established global steel manufacturers.
Recent Developments
-
In June 2026, ArcelorMittal announced a strategic collaboration with Amazon Web Services (AWS) to accelerate industrial automation, artificial intelligence, and lower-carbon construction. The collaboration is intended to support digital transformation across ArcelorMittal's operations and enhance productivity and sustainability.
-
In January 2026, Nippon Steel announced a new 2030 Medium- to Long-term Management Plan, outlining a large-scale growth strategy to strengthen its global steel business and expand its competitive position.
-
In January 2025, JFE Steel Corporation announced the sale of its JGreeX green steel to JFE Shoji Pipe & Fitting Corporation (JKK). This marks a significant milestone as it is the first instance of a Japanese steel distributor offering JGreeX in the steel pipe sector. The collaboration with JKK will facilitate a sales system designed for small-lot shipments and rapid deliveries, allowing JFE Steel to effectively market and supply its green steel to a diverse customer base.
Steel Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1,494.0 billion
Estimated Market size value in 2026
USD 1,525.8 billion
Revenue forecast in 2033
USD 2,283.0 billion
Growth Rate
CAGR of 5.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in kilotons, revenue in USD trillion/billion/million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market position analysis, competitive landscape, growth factors, and trends
Segments covered
Type, product, end use, region
Regional Scope
North America, Europe, Asia Pacific, Latin America, Middle East & Africa
Country Scope
U.S.; Canada; Mexico; Germany; France; Italy; Russia; China; Japan; India; Brazil; Saudi Arabia; UAE
Key companies profiled
ArcelorMittal; China Baowu Steel Group; EMSTEEL; JFE Steel Corporation; Nippon Steel Corporation; Nucor Corporation; Outokumpu; POSCO; Tata Steel; Thyssenkrupp
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Steel Market Report Segmentation
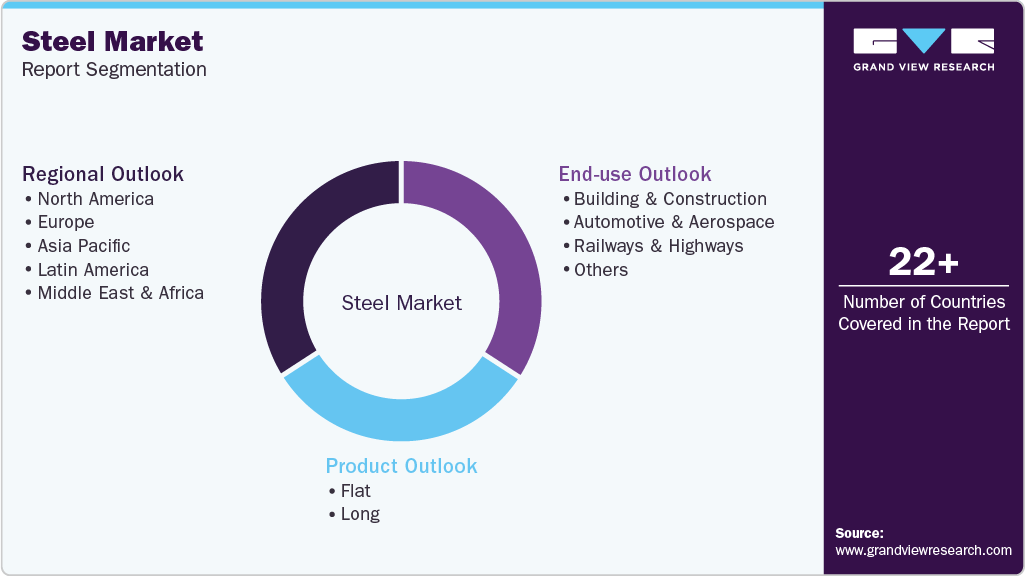
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global steel market report based on type, product, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Stainless Steel
-
Carbon Steel
-
Alloy Steel
-
Tool Steel
-
Others
-
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Flats
-
Coil
-
Sheet
-
Plates
-
Others
-
-
Longs
-
Bars & Rods
-
Pipes & Tubes
-
Others
-
-
-
End Use Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Automotive
-
Building & Construction
-
Energy & Utilities
-
Industrial Manufacturing
-
Aerospace & Defense
-
Electrical Equipment
-
Consumer Goods
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
Italy
-
Russia
-
-
Asia Pacific
-
China
-
Japan
-
India
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
-
Delivered Customizations
Client Request
Customization Delivered
Value Adds
Green Steel Market Assessment
Delivered a dedicated study on the global green steel market covering low-carbon steel production technologies, hydrogen-based steelmaking, electric arc furnace adoption, regulatory landscape, sustainability trends, and competitive benchmarking of key green steel producers. The study also included market sizing, demand outlook, investment analysis, and decarbonization strategies across major steel-producing regions.
Provided strategic insights into emerging opportunities in sustainable steel production, evolving decarbonization trends, technology adoption, and investment potential within the rapidly growing green steel industry.
Country-Level European Steel Market Assessment
Delivered a customized country-wise steel market analysis covering Germany, Belgium, France, and the Netherlands, with historical and forecast market sizing data for total steel consumption.
Country-specific steel demand trends, compare regional market dynamics, and support strategic planning and expansion decisions within key European steel markets.
Steel Trade Statistics
A trade intelligence study covering import price (CIF), customs duty, VAT amount, total landed cost, import selling price, demand-supply gap, and import volume analysis for key steel product categories, including rebars, structural steel sections, billets, steel pipes & tubes, and scraps. The study included a detailed country-level assessment of Armenia, Morocco, Georgia, Azerbaijan, and Uzbekistan.
Helped the client evaluate regional steel trade competitiveness, understand import cost structures, identify supply-demand gaps, and support strategic pricing, sourcing, and market entry decisions across multiple steel product categories and geographies.
Frequently Asked Questions About This Report
Steel is an extensively used material in various forms in construction, automotive, railways, aerospace, consumer electronics, and other such industries. Its large-scale production base and penetration across numerous applications aids to its market growth.
The global steel market size was estimated at USD 1,494.0 billion in 2025 and is expected to reach USD 1,525.8 billion in 2026.
The global steel market is expected to grow at a compound annual growth rate of 5.9% from 2026 to 2033 to reach USD 2,283.0 billion by 2033.
Based on end use segment, building & construction held the largest revenue share of more than 79.0% in 2025 owing to growth of construction activities in various economies.
Some of the key vendors of the global steel market are Tata Steel, Nippon Steel Corporation, POSCO, ArcelorMittal, JFE Steel, Baosteel Group, among others.
Asia Pacific dominated with a 64.6% revenue share in 2025.
The steel flats segment accounted for the largest market share of 51.5% in 2025.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


