
- Home
- »
- Pharmaceuticals
- »
-
Gastroesophageal Reflux Disease Therapeutics Market Report, 2026-2033GVR Report cover

Gastroesophageal Reflux Disease Therapeutics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Drug Type (Antacids, H2 Receptor Blockers, Proton Pump Inhibitors, Pro-kinetic Agents), By Region (North America, Asia Pacific), And Segment Forecasts
Market Size, 2025
$5.2BMarket Estimate, 2026
$5.3BMarket Forecast, 2033
$6.1BCAGR, 2026–2033
2.0%Gastroesophageal Reflux Disease Therapeutics Market Summary
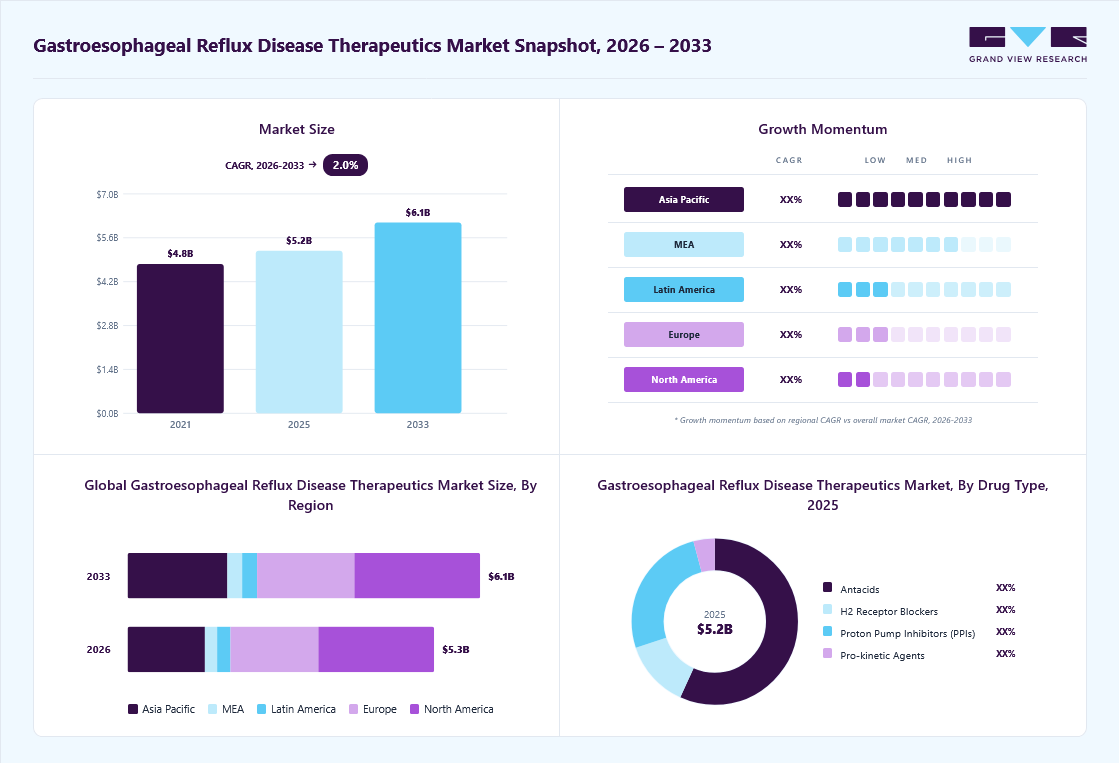
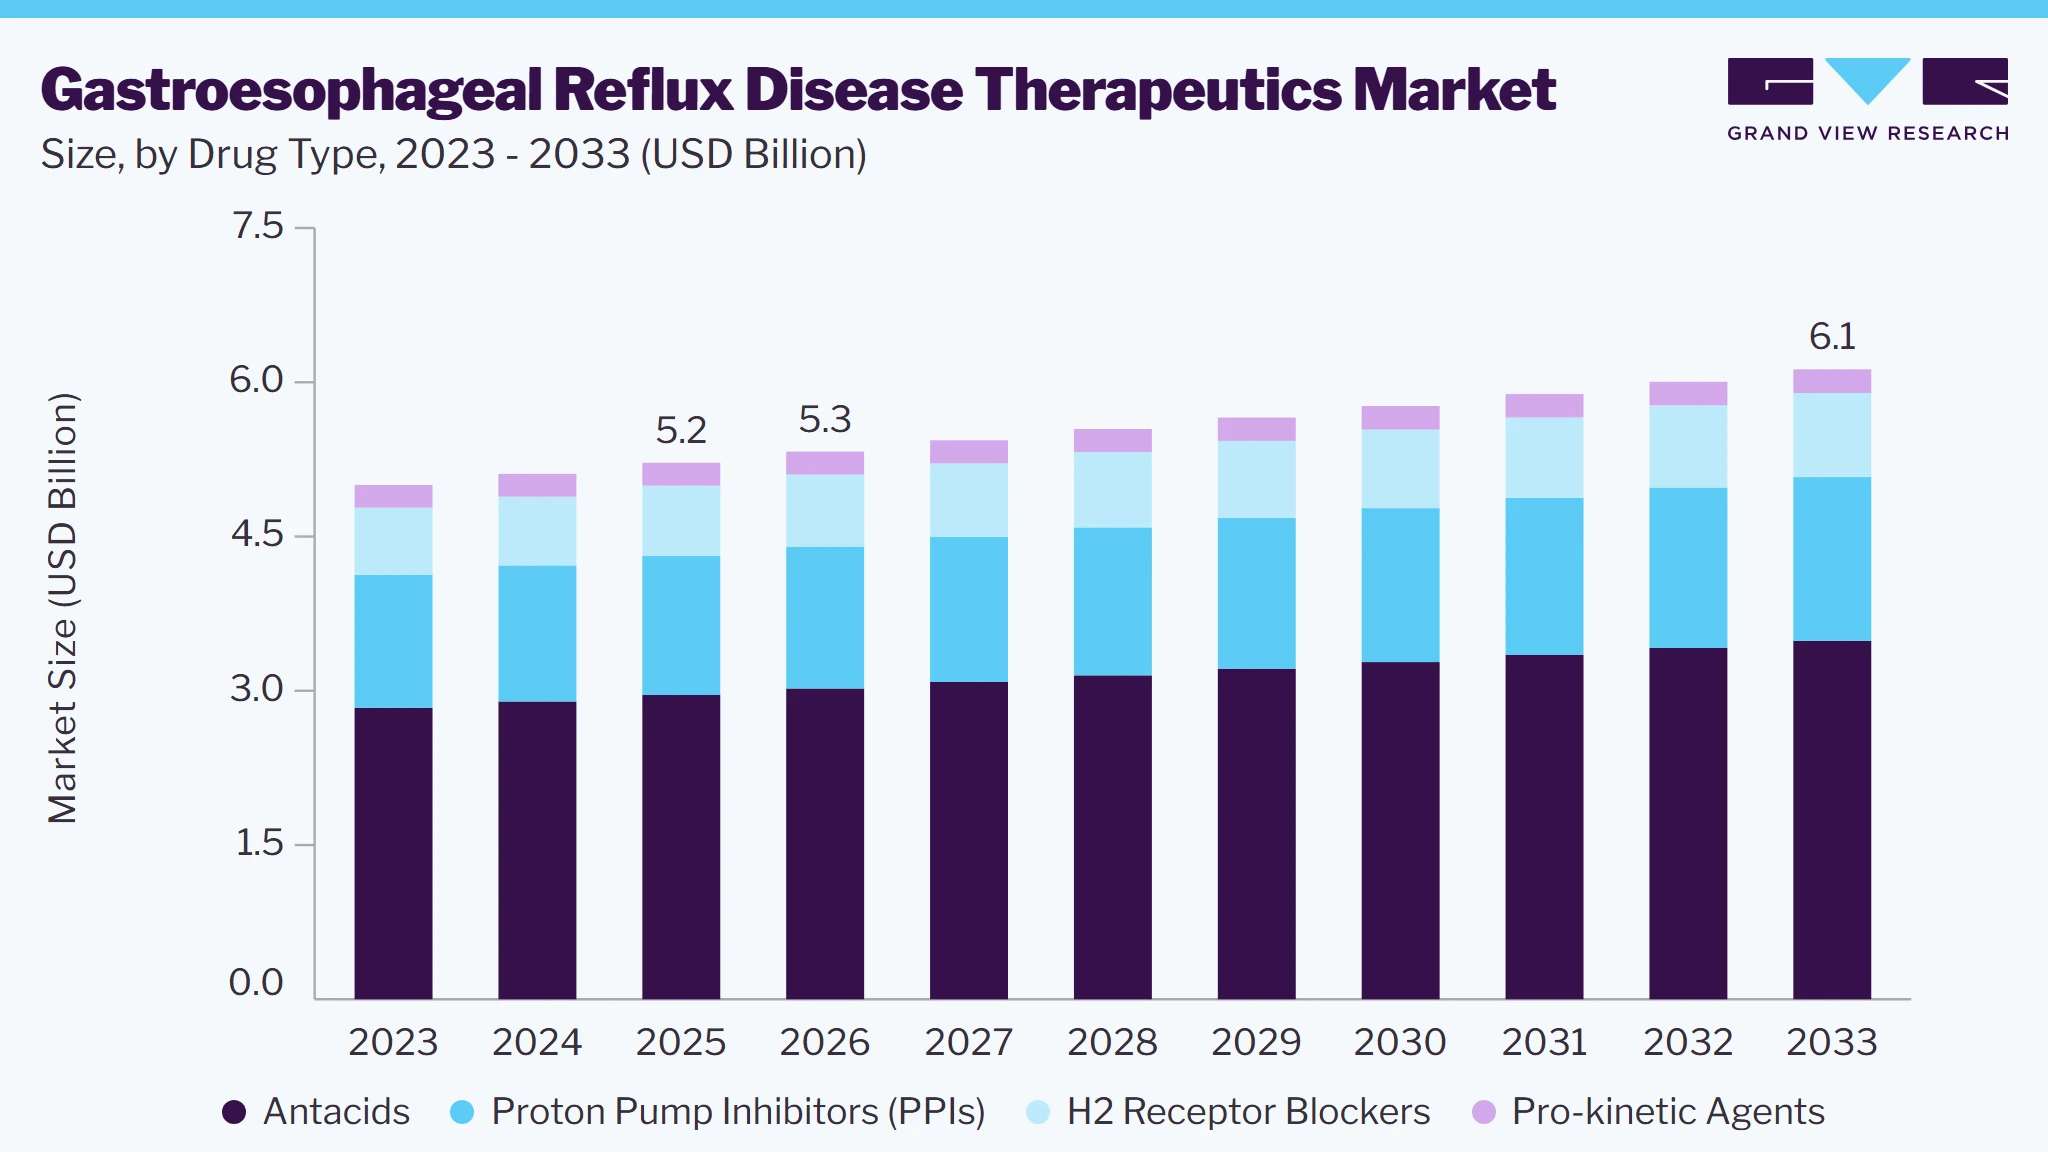
The global gastroesophageal reflux disease therapeutics market size was valued at USD 5.2 billion in 2025 and is projected to grow from USD 5.3 billion in 2026 to USD 6.1 billion by 2033, growing at a CAGR of 2.0% from 2026 to 2033. North America dominated the market with the largest revenue share of 38.1% in 2025. Lifestyle changes, including urbanization and dietary habits, further contribute to the rising prevalence of GERD.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By drug type: Antacids segment led the market with the largest revenue share of 56.7% in 2025.
Regional Highlights
- Largest regional market: North America (38.1% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 5.2 Billion
- Estimated market size in 2026: USD 5.3 Billion
- Projected market size by 2033: USD 6.1 Billion
- CAGR (2026-2033): 2.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
A 2024 BMC study conducted in Iran reported a 10.99% prevalence rate, pointing to lifestyle factors such as high sugar intake and low physical activity as significant triggers. Moreover, 45.3% of participants engaged in insufficient physical activity, underscoring the correlation between sedentary lifestyles, processed food consumption, and increased GERD symptoms. These trends necessitate effective therapeutic interventions to manage the growing patient population. The rising prevalence of gastroesophageal reflux disease (GERD) significantly drives the therapeutics market, with approximately 13.98% of the adult population globally affected by this condition. Notably, regional variations influence demand, with prevalence rates soaring to 22.40% in Turkey and as low as 4.16% in China. This growing incidence correlates with an aging population in the U.S., where it is projected that around 20% of citizens will be aged 65 and older by 2024. This demographic is more susceptible to GERD due to higher rates of obesity, diabetes, and other chronic conditions, necessitating tailored therapeutic solutions to effectively address their specific needs.Increasing public awareness surrounding GERD has also fueled demand for over-the-counter medications. A 2023 population-based survey revealed that 40% of U.S. citizens reported experiencing GERD symptoms at some point, with 33% experiencing symptoms in the past week. This heightened awareness has spurred consumers to seek immediate relief through antacids and proton pump inhibitors, a trend expected to persist into 2024 due to ongoing awareness campaigns. As more individuals recognize the available treatment options, the market for GERD therapeutics is poised for significant growth.
 To learn more about this report, Download Free Sample Report
Government initiatives also play a critical role in promoting the GERD therapeutics market. In 2023, the World Health Organization launched a global initiative aimed at reducing gastrointestinal diseases through increased research funding and public health campaigns. Various national health departments are now implementing educational programs to raise awareness of GERD risk factors and encourage healthier lifestyles. It is anticipated that several countries will enhance their healthcare policies to support early diagnosis and treatment of GERD, further facilitating market growth in response to increasing healthcare expenditures and awareness efforts.
Market Dynamics
The gastroesophageal reflux disease therapeutics market is driven by the increasing prevalence of reflux related disorders, growing awareness regarding gastrointestinal health, and rising demand for effective treatment options across both prescription and over the counter segments. Healthcare providers are placing greater emphasis on early diagnosis and appropriate disease management to reduce symptom burden and prevent complications associated with chronic reflux conditions. Continued utilization of proton pump inhibitors, histamine receptor antagonists, and emerging potassium competitive acid blockers is supporting market growth. A notable industry development highlights this trend. For instance, in May 2025, Phathom Pharmaceuticals advanced the commercialization of VOQUEZNA (vonoprazan), an FDA approved potassium competitive acid blocker for the treatment of erosive and non-erosive gastroesophageal reflux disease, supporting broader treatment options and strengthening competition within the GERD therapeutics market. At the same time, increasing focus on personalized treatment strategies and long term disease management is encouraging broader adoption of therapeutic interventions. However, generic competition, concerns regarding prolonged use of certain acid suppressing therapies, and reimbursement related challenges continue to influence market dynamics. Despite these factors, ongoing investment in therapeutic innovation and expanding access to gastroenterology care are expected to support sustained market development.
The gastroesophageal reflux disease therapeutics market is primarily driven by the growing prevalence of GERD across both developed and developing regions. Factors such as changing dietary habits, increasing consumption of processed foods, rising obesity rates, sedentary lifestyles, and an aging population have contributed to a larger patient pool requiring long term disease management. Healthcare providers are increasingly focusing on early diagnosis and treatment to reduce the risk of complications including erosive esophagitis, Barrett's esophagus, and esophageal strictures. This has supported sustained demand for pharmacological therapies such as proton pump inhibitors, histamine receptor antagonists, and emerging potassium competitive acid blockers. Growing patient awareness regarding chronic digestive disorders and improved access to gastroenterology services are further strengthening treatment adoption. In addition, ongoing research and development activities are supporting the introduction of innovative therapeutic options for GERD management. A notable industry development reflects this trend. For instance, in August 2025, Braintree Laboratories reported positive Phase III TRIUMpH study results for tegoprazan, a novel potassium competitive acid blocker for gastroesophageal reflux disease, highlighting continued innovation in GERD therapeutics and pipeline development. Such developments highlight ongoing efforts to expand treatment options and address unmet clinical needs within the GERD patient population. As the burden of reflux related disorders continues to increase globally, demand for effective and durable therapeutic solutions is expected to remain a key market growth driver.
Long term safety concerns associated with acid suppressing therapies and the growing availability of generic products continue to restrain the gastroesophageal reflux disease therapeutics market. Proton pump inhibitors remain widely used for the treatment of GERD, but concerns regarding extended use have led healthcare providers to monitor treatment duration and patient outcomes more closely. Issues related to nutrient deficiencies, kidney health, bone related conditions, and potential drug interactions may affect prescribing patterns and encourage periodic treatment review. In addition, the widespread availability of generic proton pump inhibitors has increased pricing pressure across the market, limiting growth opportunities for newer branded therapies. This challenge is particularly evident in regions where lower cost treatment options are widely prescribed. Patient concerns regarding long term medication use may also affect treatment adherence and influence therapy selection. Furthermore, the availability of lower cost generic proton pump inhibitors may reduce the uptake of newly introduced GERD therapies, as healthcare providers often continue prescribing established treatment options with well documented clinical outcomes. As a result, safety concerns, pricing pressure, and generic competition continue to influence treatment uptake and overall market growth within the gastroesophageal reflux disease therapeutics market.
The increasing development and adoption of novel acid suppression therapies present a significant opportunity for the gastroesophageal reflux disease therapeutics market. While proton pump inhibitors remain the standard treatment option for GERD, a considerable number of patients continue to experience persistent symptoms or incomplete symptom relief, creating demand for alternative therapeutic approaches. Emerging drug classes, particularly potassium competitive acid blockers, are gaining attention due to their ability to provide rapid and sustained acid suppression. These therapies have the potential to address unmet treatment needs and improve disease management across different patient populations. Growing research and development activities are further supporting the advancement of innovative therapies aimed at enhancing treatment outcomes and patient adherence. In addition, increasing awareness of gastrointestinal health and improving access to specialist care are contributing to the adoption of newer treatment options. Ongoing clinical development programs and continued investment in gastrointestinal drug research are supporting the development of new therapeutic options for patients with persistent or difficult to manage GERD symptoms. As healthcare providers continue to seek treatment options that offer improved symptom control and long-term disease management, the adoption of next generation GERD therapies is expected to create growth opportunities for market participants during the forecast period.
Analyst Perspective
The gastroesophageal reflux disease therapeutics market continues to be supported by the widespread use of proton pump inhibitors, which remain the primary treatment option across most patient populations. However, a considerable number of patients continue to experience persistent symptoms despite treatment, creating demand for additional therapeutic options. This has increased attention toward newer therapies, including potassium competitive acid blockers, which are expanding available treatment choices within the market. At the same time, the widespread availability of generic therapies continues to influence prescribing patterns and treatment adoption across many regions. Ongoing clinical development activities, increasing disease awareness, and improving access to gastroenterology services are further contributing to market development. As treatment options continue to expand, competition is expected to increase across both established and emerging therapeutic classes, supporting continued evolution of the gastroesophageal reflux disease therapeutics market.
Drug Type Insights
Based on drug type, the antacids segment led the market with the largest revenue share of 56.7% in 2025, fueled by the effectiveness of antacids in delivering rapid relief from heartburn and acid indigestion. As over-the-counter (OTC) medications, they are easily accessible, cost-effective, and favored for self-medication. Their rising popularity is fueled by increased GERD prevalence and lifestyle factors contributing to acid-related disorders.
H2 receptor blockers are projected to grow at the fastest CAGR of 2.2% over the forecast period due to the efficacy of these medications in reducing stomach acid production, offering longer-lasting relief compared to antacids. Their widespread availability as over-the-counter options enhances accessibility for consumers seeking treatment for mild to moderate GERD symptoms, further contributing to their increasing popularity.
Regional Insights
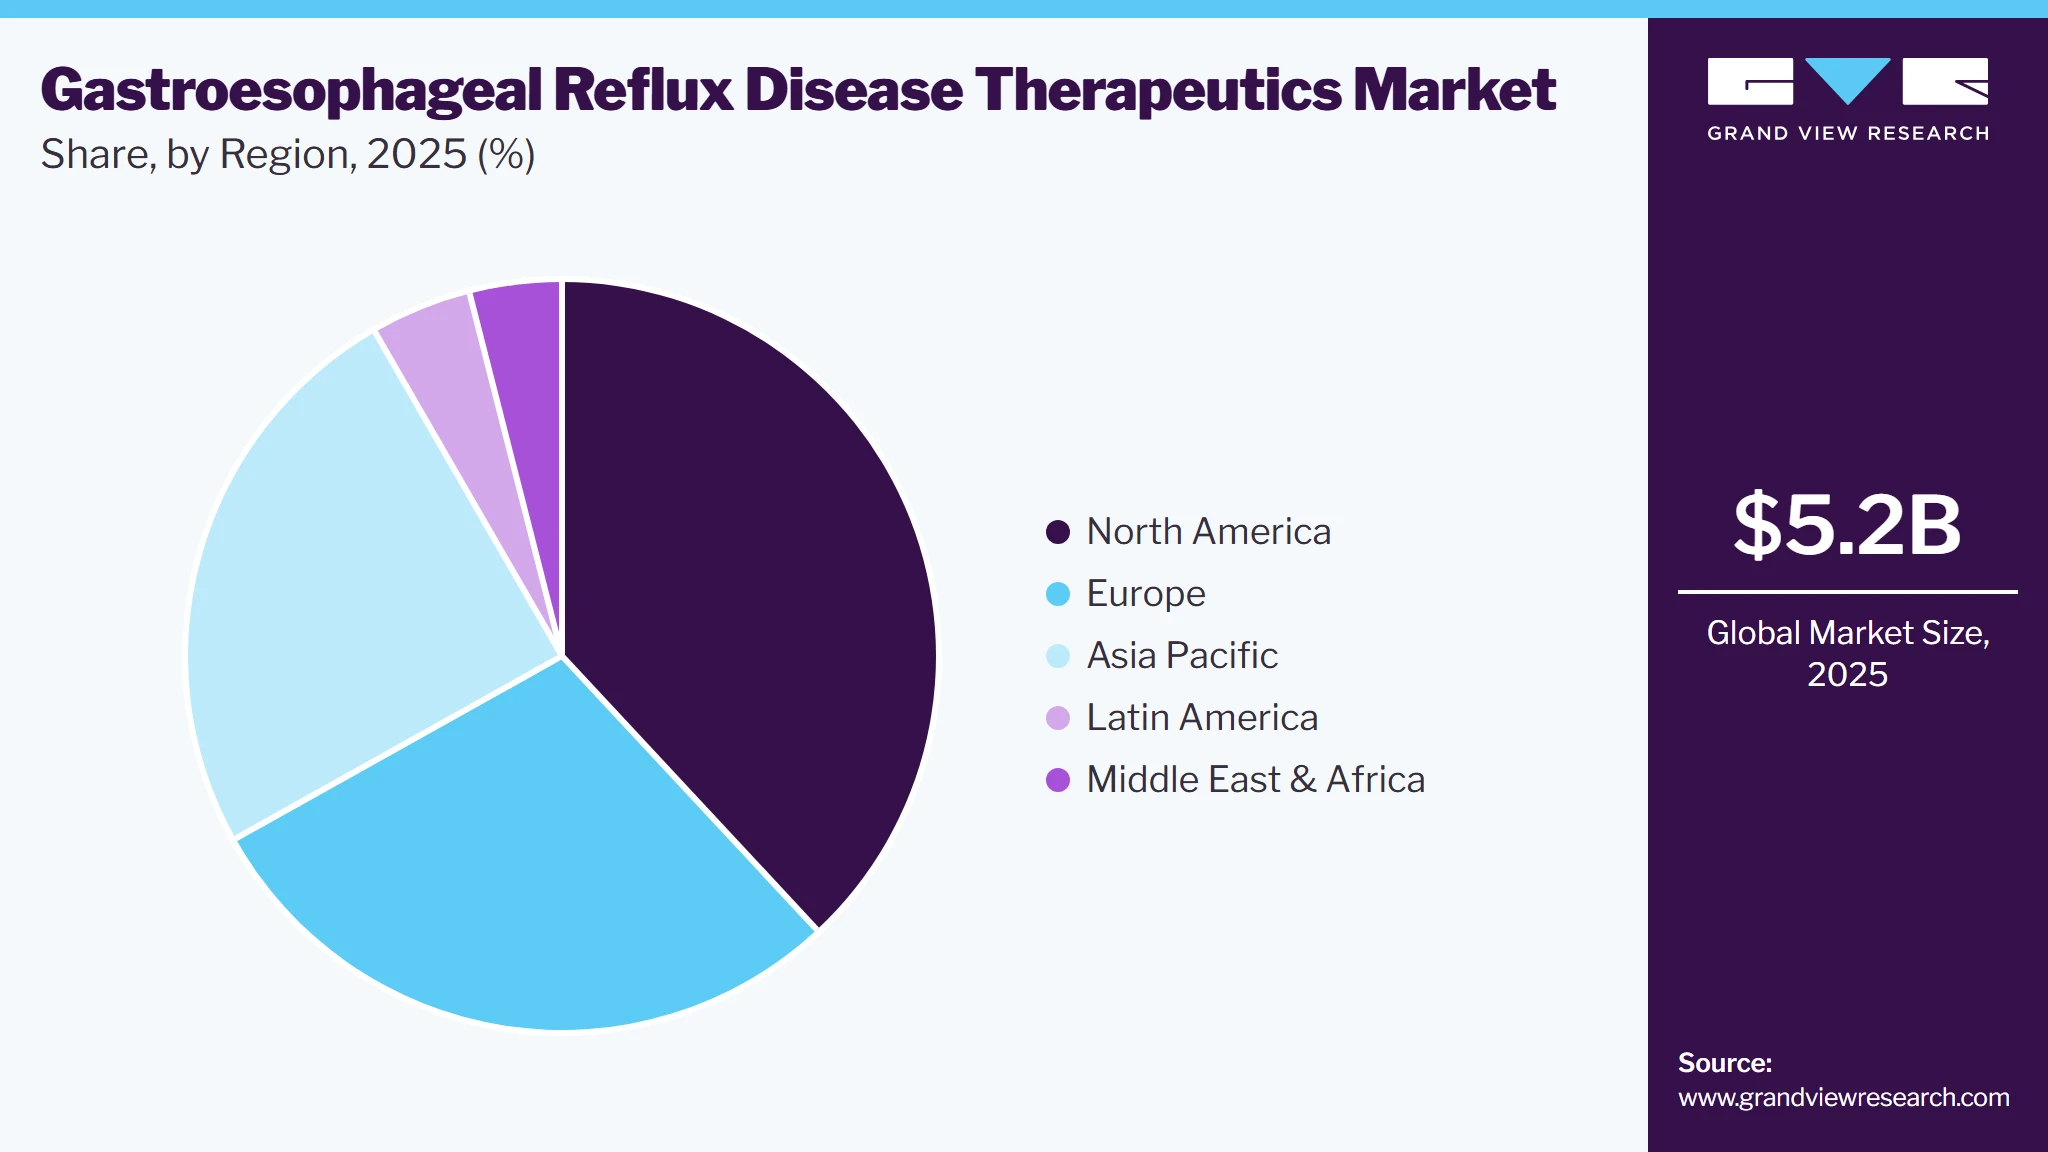
North America dominated the gastroesophageal reflux disease therapeutics market with the largest revenue share of 38.1% in 2025. Market growth in the region is propelled by lifestyle factors, including obesity and dietary habits. The robust healthcare infrastructure, substantial investments in research and development, and increased awareness of GERD symptoms collectively enhance the demand for effective therapeutic options in this sector.
 To learn more about this report, Download Free Sample Report
U.S. Gastroesophageal Reflux Disease Therapeutics Market Trends
The gastroesophageal reflux disease therapeutics market in the U.S. held the largest share in the North America region in 2025. The demand for GERD therapeutics in the U.S. is further stimulated by enhanced public awareness campaigns, a rising trend toward self-medication, and the accessibility of advanced treatment options. These factors collectively contribute to the growing market for effective GERD management solutions.
Europe Gastroesophageal Reflux Disease Therapeutics Market Trends
Europe gastroesophageal reflux disease therapeutics market held substantial market share in 2025, owing to a marked increase in GERD prevalence attributed to lifestyle changes and dietary habits. Enhanced healthcare spending, continuous research initiatives, and public health campaigns aimed at elevating GERD awareness are driving demand for effective therapeutic interventions across European nations.
The gastroesophageal reflux disease therapeutics market in Germany is expected to grow rapidly over the forecast period, driven by a strong healthcare infrastructure and a high prevalence of GERD within its population. The nation benefits from advanced pharmaceutical research and development, coupled with rising public awareness of available treatment options, which collectively fuel demand for tailored, effective therapeutic solutions that meet patient needs.
Asia Pacific Gastroesophageal Reflux Disease Therapeutics Market Trends
Asia Pacific gastroesophageal reflux disease therapeutics market is expected to register the fastest CAGR of 5.1% over the forecast period. The region is witnessing swift urbanization, shifting dietary habits, and increasing obesity rates. Enhanced healthcare investments and growing awareness of GERD symptoms and treatment options are propelling market expansion, establishing it as a significant growth area within the global therapeutics landscape.
The gastroesophageal reflux disease therapeutics market in China dominated the Asia Pacific gastroesophageal reflux disease therapeutics market in 2024. There has been a substantial rise in GERD cases linked to lifestyle changes and dietary modifications among the population. The government’s emphasis on enhancing healthcare infrastructure and promoting awareness of GERD treatment options further accelerates market growth in this sector.
Key Gastroesophageal Reflux Disease Therapeutics Company Insights
Some key companies operating in the market include AstraZeneca; Eisai Co., Ltd.; GSK plc.; Takeda Pharmaceutical Company Limited; and Ironwood; among others. Key players are prioritizing innovative drug development and strategic partnerships. Companies are investing in research and development to improve therapeutic options, while awareness campaigns are driving consumer demand.
-
Eisai Co., Ltd., with its proton pump inhibitor, Pariet (rabeprazole), target reflux esophagitis and non-erosive GERD. They are also developing Lemborexant, currently in Phase II trials, to improve treatment options.
-
GSK plc provides a variety of medications for gastroesophageal reflux disease, including proton pump inhibitors and H2 receptor antagonists. The company emphasizes research and development to create innovative therapies that effectively alleviate GERD symptoms and enhance overall gastrointestinal health for patients.
Key Gastroesophageal Reflux Disease Therapeutics Companies:
The following key companies have been profiled for this study on the gastroesophageal reflux disease therapeutics market.
-
AstraZeneca
-
Eisai Co., Ltd.
-
GSK plc
-
Takeda Pharmaceutical Company Limited
-
Ironwood
-
Johnson & Johnson Services, Inc.
-
SFJ Pharmaceuticals
-
Sebela Pharmaceuticals
-
Phathom Pharmaceuticals, Inc.
-
Camber Pharmaceuticals, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (AstraZeneca, Eisai Co., Ltd., GSK plc, Takeda Pharmaceutical Company Limited, Johnson & Johnson Services, Inc.)
- Maintain market presence through established gastrointestinal portfolios, broad commercial networks, and continued expansion across prescription and over the counter GERD therapies. Focus on lifecycle management, geographic expansion, regulatory compliance, and strategic collaborations to strengthen product positioning. Leverage existing healthcare provider relationships and distribution channels to support long term product adoption across global markets.
- Strong brand recognition and established relationships with healthcare providers, hospitals, pharmacies, and distributors. Extensive commercial infrastructure, regulatory expertise, and financial resources that support product commercialization and geographic expansion. Broad experience in gastrointestinal and acid related disorder markets with established product portfolios and global market access capabilities.
- Exposure to generic competition limits growth potential for mature therapies. Dependence on established therapeutic classes with limited product differentiation. Challenges associated with maintaining revenue growth in markets characterized by pricing pressure, patent expirations, and increasing availability of lower cost alternatives.
Emerging and Specialty Players (Ironwood Pharmaceuticals, SFJ Pharmaceuticals, Sebela Pharmaceuticals, Phathom Pharmaceuticals, Inc., Camber Pharmaceuticals, Inc.)
- Focus on the development, commercialization, and expansion of specialized GERD therapies and gastrointestinal treatment portfolios. Advance clinical development programs targeting unmet treatment needs and support product growth through licensing agreements, strategic partnerships, regulatory activities, and targeted commercialization initiatives. Emphasize differentiated therapeutic approaches, niche market opportunities, and expansion within gastrointestinal disease management.
- Strong focus on innovation, specialized gastrointestinal expertise, and the ability to address specific patient populations with differentiated therapies. Greater operational flexibility and focus on emerging treatment opportunities compared with larger pharmaceutical companies. Ability to rapidly advance targeted development and commercialization strategies within the gastrointestinal therapeutics space.
- Limited commercial scale and geographic reach compared with larger pharmaceutical companies. Dependence on successful clinical development, regulatory approvals, strategic partnerships, and product adoption for sustained growth. Challenges related to expanding market presence, scaling commercial operations, and competing against established companies with broader product portfolios and stronger distribution networks.
Recent Developments
-
In October 2024, Camber announced the successful launch of eight new generic products in Q3, enhancing its portfolio with high-quality, cost-effective alternatives to brand-name medications.
-
In July 2024, Phathom Pharmaceuticals announced FDA approval for VOQUEZNA® (vonoprazan) 10 mg tablets, offering a new treatment for heartburn associated with Non-Erosive GERD, benefiting millions of affected adults.
-
In July 2024, AstraZeneca announced an approximately USD 30 million investment to expand its Global Innovation and Technology Centre in Chennai, creating approximately 1,300 skilled positions by 2025.
-
In June 2024, Takeda expanded its partnership with Partners In Health to enhance health equity in Massachusetts, aiming to dismantle systemic barriers and strengthen local health workforce capacity.
Gastroesophageal Reflux Disease Therapeutics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 5.2 billion
Estimated market size in 2026
USD 5.3 billion
Projected market size by 2033
USD 6.1 billion
Growth rate
CAGR of 2.0% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Drug type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; Russia; Iceland; Finland; China; Japan; India; South Korea; Australia; Thailand; Singapore; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Israel
Key companies profiled
AstraZeneca, Eisai Co., Ltd., GSK plc, Takeda Pharmaceutical Company Limited, Ironwood, Johnson & Johnson Services, Inc., SFJ Pharmaceuticals, Sebela Pharmaceuticals, Phathom Pharmaceuticals, Inc., Camber Pharmaceuticals, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Gastroesophageal Reflux Disease Therapeutics Market Report Segmentation
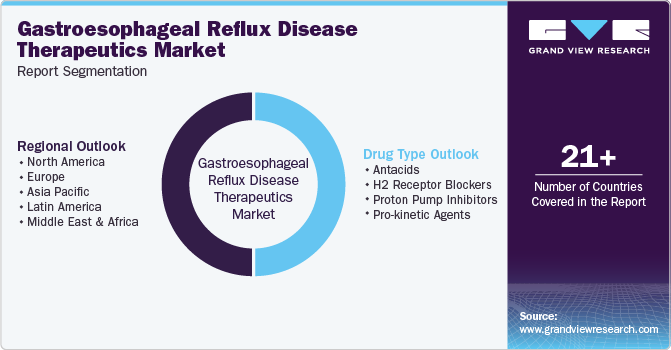
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global gastroesophageal reflux disease therapeutics market report based on drug type and region:
 To learn more about this report, Download Free Sample Report
-
Drug Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Antacids
-
H2 Receptor Blockers
-
Proton Pump Inhibitors (PPIs)
-
Pro-kinetic Agents
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The gastroesophageal reflux disease therapeutics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each gastroesophageal reflux disease therapeutics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Drug Type
Revenue capture definition
Antacids
Includes calcium carbonate, magnesium hydroxide, aluminum hydroxide, sodium bicarbonate, and combination antacid formulations used to neutralize gastric acid and provide symptomatic relief from gastroesophageal reflux disease. Revenue is generated from the sale of branded and generic antacid therapies across prescription and over the counter channels. This segment excludes H2 receptor blockers, proton pump inhibitors, pro kinetic agents, potassium competitive acid blockers, alginate based therapies, and procedural treatments.
H2 Receptor Blockers
Includes famotidine, cimetidine, nizatidine, and other therapies that reduce gastric acid secretion through histamine H2 receptor inhibition for the management of gastroesophageal reflux disease. Revenue is generated from the sale of branded and generic H2 receptor blocker therapies. This segment excludes antacids, proton pump inhibitors, pro kinetic agents, potassium competitive acid blockers, alginate based therapies, and procedural treatments.
Proton Pump Inhibitors (PPIs)
Includes omeprazole, esomeprazole, pantoprazole, lansoprazole, rabeprazole, dexlansoprazole, and other proton pump inhibitor therapies used for the treatment and maintenance management of gastroesophageal reflux disease. Revenue is generated from the sale of branded and generic proton pump inhibitor therapies. This segment excludes antacids, H2 receptor blockers, pro kinetic agents, potassium competitive acid blockers, alginate based therapies, and procedural treatments.
Pro kinetic Agents
Includes metoclopramide, domperidone, mosapride, itopride, acotiamide, and other therapies that improve gastrointestinal motility and gastric emptying for the management of gastroesophageal reflux disease. Revenue is generated from the sale of branded and generic pro kinetic therapies. This segment excludes antacids, H2 receptor blockers, proton pump inhibitors, potassium competitive acid blockers, alginate based therapies, and procedural treatments.
Estimation Model
The market size of the Gastroesophageal Reflux Disease (GERD) Therapeutics Market is estimated through a combination of secondary research, primary research, and data triangulation techniques. The study begins with extensive secondary research, including the analysis of annual reports, investor presentations, company financial statements, regulatory publications, clinical trial databases, healthcare journals, and data from organizations such as the World Health Organization (WHO), National Institutes of Health (NIH), Centers for Disease Control and Prevention (CDC), and gastroenterology associations. This research helps identify the prevalence of GERD, treatment adoption patterns, therapeutic advancements, pricing trends, and key market participants.
A bottom-up approach is employed by assessing revenues generated from GERD therapeutics, including proton pump inhibitors (PPIs), H2 receptor antagonists, antacids, potassium-competitive acid blockers (P-CABs), and other emerging therapies across major manufacturers and geographic regions. Simultaneously, a top-down approach is conducted by evaluating overall gastrointestinal drug expenditures and determining the proportion attributable to GERD treatment based on disease prevalence, prescription volumes, and treatment rates.
Primary research is carried out through interviews with gastroenterologists, hospital pharmacists, pharmaceutical executives, distributors, healthcare providers, and industry experts to validate market estimates, treatment trends, and future demand outlook. Market segmentation is analyzed by drug class, route of administration, distribution channel, and region. Finally, data triangulation and forecast modeling are applied to reconcile findings from multiple sources and generate accurate market size estimates and growth projections for the GERD Therapeutics Market.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
GERD Treatment Adoption Analysis
Assessment of prescribing and utilization trends across proton pump inhibitors, H2 receptor blockers, pro kinetic agents, and emerging acid suppression therapies, including treatment preferences across different patient populations and healthcare settings.
Helps identify treatment utilization patterns, adoption trends, and areas of market expansion across established and emerging therapies.
Refractory GERD and Unmet Needs Assessment
Analysis of treatment patterns, disease burden, and therapeutic gaps among patients with persistent symptoms, non erosive reflux disease, and treatment resistant GERD.
Supports identification of unmet clinical needs and opportunities for differentiated therapies targeting inadequately managed patient populations.
Novel Acid Suppression Therapy Assessment
Evaluation of potassium competitive acid blockers and other emerging therapies, including clinical development progress, treatment positioning, and potential impact on existing therapeutic classes.
Provides insights into future treatment trends, competitive dynamics, and potential areas of market growth.
Patient Segmentation and Disease Management Analysis
Assessment of treatment approaches across erosive GERD, non erosive reflux disease, refractory GERD, and maintenance therapy populations, including treatment switching and long- term disease management patterns.
Helps identify high value patient segments and supports product positioning and commercialization strategies.
Competitive Benchmarking and Product Portfolio Analysis
Comparative assessment of approved products, pipeline candidates, clinical evidence, commercialization activities, and strategic initiatives of leading GERD therapeutics market participants.
Supports competitive intelligence, portfolio evaluation, partnership assessment, and market positioning decisions.
Frequently Asked Questions About This Report
Some key players operating in the gastroesophageal reflux disease therapeutics market include AstraZeneca, Eisai Co., Ltd., GSK plc., Takeda Pharmaceutical Company Limited., Ironwood Pharmaceuticals, Inc., Johnson & Johnson Services, Inc., SFJ Pharmaceuticals, Sebela Pharmaceuticals, Phathom Pharmaceuticals, Inc., Camber Pharmaceuticals, Inc.
Key factors that are depriving the market growth include factors such as the low success rates associated with the GERD management devices, rising prevalence of GERD and other gastrointestinal disorders, and a rising trend of self-medication aided with presence of strong product pipeline.
North America dominated the market with the largest revenue share of 38.1% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The global gastroesophageal reflux disease therapeutics market size was valued at USD 5.2 billion in 2025 and is projected to grow from USD 5.3 billion in 2026
The global gastroesophageal reflux disease therapeutics market is expected to grow at a compound annual growth rate of 2.0% from 2026 to 2033 to reach USD 6.1 billion by 2033.
Based on drug type, the antacids segment led the market with the largest revenue share of 56.7% in 2025.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


