
- Home
- »
- Medical Devices
- »
-
Gastroretentive Drug Delivery Systems Market Report, 2025-2030GVR Report cover

Gastroretentive Drug Delivery Systems Market (2025 - 2030)
Size, Share & Trends Analysis Report By Type (Floating, Expandable), By Dosage (Tablets, Capsule, Gel, Liquid), By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2024
$15.6BMarket Estimate, 2026
$17.6BMarket Forecast, 2030
$22.7BCAGR, 2025–2030
6.4%Market Size & Trends
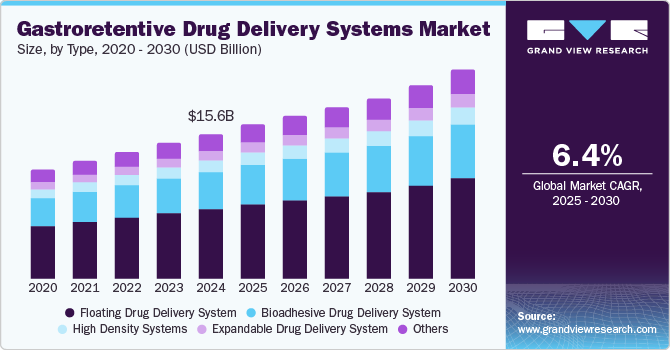
The global gastroretentive drug delivery systems market size was valued at USD 15.6 billion in 2024 and is projected to grow from USD 17.6 billion in 2026 to USD 22.7 billion by 2030, at a CAGR of 6.4% from 2025 to 2030. North America dominated the market, accounting for a revenue share of 41.3% in 2024. Market growth is driven by an increasing global prevalence of gastric disorders, including peptic ulcer disease and H. pylori infections. Approximately 4 million individuals worldwide are affected by peptic ulcer disease annually, with a lifetime prevalence ranging from 5% to 10% in the general population. This rising incidence intensifies the demand for effective treatment options, creating substantial market opportunities for gastroretentive drug delivery systems (GRDDS) as pharmaceutical companies strive to address these pressing healthcare needs.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Research indicates that individuals over the age of 70 exhibit longer gastric retention times compared to younger demographics. This characteristic suggests that gastroretentive systems may offer enhanced therapeutic benefits for older adults, who are often more susceptible to gastric disorders. As the population ages, the development of tailored gastroretentive solutions adaptable to this demographic becomes critical.
Furthermore, studies show that females generally experience slower gastric emptying compared to males, influencing the effectiveness of GRDDS. Pharmaceutical companies are increasingly recognizing these variances, motivating them to invest in research and development focused on creating specialized GRDDS that cater to these diverse patient populations. This personalized approach to drug delivery enhances treatment efficacy, appealing to healthcare providers and patients alike.
Advances in controlled-release methods and improvements in bioavailability have rendered gastroretentive systems more efficient and attractive to pharmaceutical entities. By reducing dosing frequency and improving therapeutic outcomes, GRDDS enhance patient adherence, which is especially vital in chronic disease management. As firms continue to allocate substantial resources toward developing advanced gastroretentive systems, the market is poised for continued expansion, driven by evolving healthcare demands and technological advancements. For instance, in September 2024, Lonza inaugurated the Innovaform Accelerator in Colmar, enhancing co-innovation for pharmaceutical applications with advanced formulation and encapsulation technology, streamlining the delivery of challenging active pharmaceutical ingredients.
Type Insights
Floating drug delivery systems (FDDS) dominated the market and accounted for a share of 47.0% in 2024. By maintaining buoyancy in the stomach, these systems extend gastric retention time, facilitating controlled drug release and improved plasma concentration. This is advantageous for narrow absorption-window drugs, reducing therapeutic fluctuations and enhancing patient compliance through decreased dosing frequency, thus promoting FDDS adoption.
Bioadhesive drug delivery systems are expected to grow at the fastest CAGR of 7.1% over the forecast period, aided by their capability to enhance drug absorption by adhering to the gastric mucosa. This extended residence time improves bioavailability, facilitates targeted delivery, reduces dosing frequency, and ultimately enhances patient compliance and therapeutic outcomes.
Dosage Insights
Tablets held the largest revenue share of 37.4% in 2024 as they improve drug bioavailability, particularly for those absorbed in the stomach, by extending gastric retention time and minimizing dosing frequency, thereby enhancing patient compliance and therapeutic efficacy. Furthermore, advancements in formulation technologies enable the creation of gastroretentive tablets tailored to specific gastric conditions, favored by manufacturers and healthcare providers.
Liquid drug delivery systems are projected to grow at the fastest CAGR of 7.8% over the forecast period. Liquid formulations facilitate rapid absorption, making them ideal for drugs with narrow absorption windows. They enable precise dosing, enhancing patient compliance, particularly among the elderly and pediatric populations. Incorporating gastroretentive technologies allows for sustained release and prolonged gastric retention, maximizing therapeutic efficacy and minimizing side effects in modern pharmaceuticals.
Distribution Channel Insights
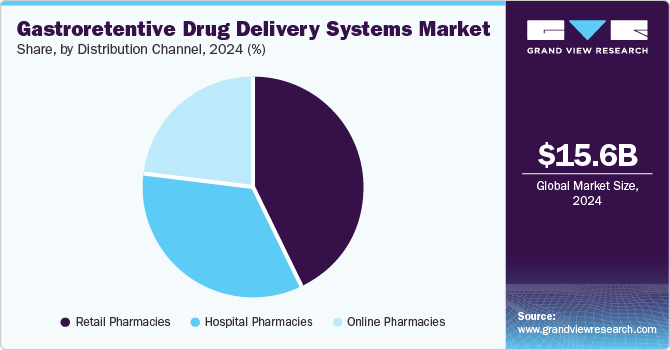
Retail pharmacies led the market with a revenue share of 43.3% in 2024. GRDDS improve drug bioavailability and reduce dosing frequency, enabling retail pharmacies to serve a growing patient base seeking effective gastric disorder treatments. The accessibility of gastroretentive formulations enhances adherence to prescribed therapies, driving market growth amid rising gastrointestinal disease prevalence and expanding product offerings in retail environments.
 To learn more about this report, Download Free Sample Report
Online pharmacies are expected to witness the fastest growth of 7.3% over the forecast period. The growth of e-commerce has enabled patients to easily access gastroretentive formulations that may require specific handling. Online platforms offer comprehensive product information and customer reviews, facilitating informed purchasing. Increased gastrointestinal disorder prevalence drives demand, allowing online pharmacies to provide a diverse range of gastroretentive products and enhance patient satisfaction.
Regional Insights
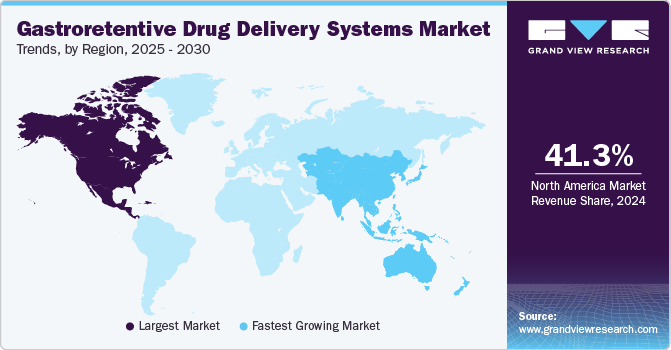
North America gastroretentive drug delivery systems market dominated the global market with a revenue share of 41.3% in 2024. Market growth in the region is driven by the high prevalence of gastrointestinal disorders such as gastric ulcers and GERD. Enhanced research and development investments by pharmaceutical companies, coupled with an advanced healthcare infrastructure, foster innovation in drug delivery technologies and promote improved patient compliance in treatment.
 To learn more about this report, Download Free Sample Report
U.S. Gastroretentive Drug Delivery Systems Market Trends
The gastroretentive drug delivery systems market in U.S. dominated the North America market with a revenue share of 81.7% in 2024. Increased investments in R&D by pharmaceutical companies are advancing innovation in drug delivery technologies in the U.S. Enhanced healthcare infrastructure and rising patient awareness are additionally driving demand for gastroretentive formulations, thereby improving patient compliance and overall therapeutic outcomes for healthcare providers.
Europe Gastroretentive Drug Delivery Systems Market Trends
Europe gastroretentive drug delivery systems market held substantial market share in 2024. The European market benefits from improved healthcare infrastructure and increased research activities. Economic advancements in countries such as Germany and France are driving healthcare spending, while the entry of international pharmaceutical manufacturers fosters the development of innovative gastroretentive formulations to meet growing demand in the region.
The gastroretentive drug delivery systems market in Germany is expected to grow in the forecast period. Economic growth in Germany has resulted in heightened healthcare expenditure, paving the way for the entry of international drug manufacturers. Furthermore, the increasing prevalence of gastrointestinal disorders is driving demand for innovative drug delivery solutions in Germany.
Asia Pacific Gastroretentive Drug Delivery Systems Market Trends
Asia Pacific gastroretentive drug delivery systems market is expected to register the fastest CAGR of 6.8% in the forecast period. Increasing investments in healthcare and heightened awareness of innovative drug delivery technologies are driving demand in countries such as Japan and India. The growing prevalence of gastrointestinal disorders, alongside intensified research and development activities, along with expanding pharmaceutical markets and improved regulatory frameworks, contribute to rapid sector growth in the region.
The gastroretentive drug delivery systems market in China dominated the Asia Pacific market in 2024. The Chinese government’s emphasis on enhancing healthcare access and quality has increased demand for advanced drug delivery technologies. Moreover, heightened awareness of innovative treatments among both patients and healthcare providers is facilitating the adoption of gastroretentive systems in the country.
Key Gastroretentive Drug Delivery Systems Company Insights
Some key companies operating in the market include Catalent, Inc; Lonza; Evonik Industries AG; Colorcon; Quotient Sciences; among others. Key players are prioritizing product innovation and strategic partnerships, investing in R&D while expanding market presence.
-
Lonza offers specialized excipients and formulation solutions, leveraging its polymer technology expertise to develop gastroretentive formulations that improve drug bioavailability and meet the demand for effective oral therapies.
-
Evonik Industries AG specializes in innovative excipients for GRDDS via its EUDRAGIT line, enhancing therapeutic efficacy and patient compliance through improved gastric retention and controlled release.
Key Gastroretentive Drug Delivery Systems Companies:
The following are the leading companies in the gastroretentive drug delivery systems market. These companies collectively hold the largest market share and dictate industry trends.
- Catalent, Inc
- Lonza
- Evonik Industries AG
- Colorcon
- Quotient Sciences
- AptarGroup, Inc.
- Aenova Holding GmbH
- Evotec SE
- Vectura Group Ltd
- Ashland
Prism AI by Grand View Research Free to tryAsk a question about the gastroretentive drug delivery systems marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Recent Developments
-
In September 2024, Evonik launched EUDRACAP colon capsules for targeted ileo-colonic drug delivery, enhancing oral therapies for sensitive ingredients such as live biotherapeutics while expanding their innovative EUDRACAP portfolio.
-
In June 2024, Lonza launched the Capsugel Enprotect size 9 capsule, facilitating pre-clinical testing of acid-sensitive APIs in rodents, streamlining drug development and enhancing first-in-human timelines.
Gastroretentive Drug Delivery Systems Market Report Scope
Report Attribute
Details
Market size in 2024
USD 15.6 billion
Estimated market size in 2026
USD 17.6 billion
Projected market size by 2030
USD 22.7 billion
Growth rate
CAGR of 6.4% from 2025 to 2030
Base year for estimation
2024
Historical data
2018 - 2023
Forecast period
2025 - 2030
Report updated
October 2024
Quantitative units
Revenue in USD million/billion and CAGR from 2025 to 2030
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Type, dosage, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Denmark, Sweden, Norway, China, Japan, India, Australia, South Korea, Thailand, Brazil, Argentina, South Africa, Saudi Arabia, UAE, Kuwait
Key companies profiled
Catalent, Inc; Lonza; Evonik Industries AG; Colorcon; Quotient Sciences; AptarGroup, Inc.; Aenova Holding GmbH; Evotec SE; Vectura Group Ltd; Ashland
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Gastroretentive Drug Delivery Systems Market Report Segmentation
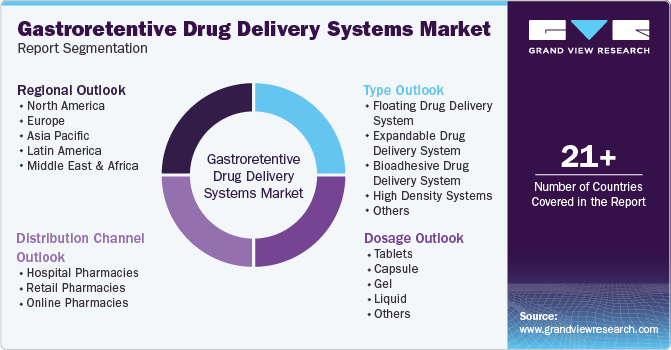
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2018 to 2030. For this study, Grand View Research has segmented the global gastroretentive drug delivery systems market report based on type, dosage, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2018 - 2030)
-
Floating Drug Delivery System
-
Expandable Drug Delivery System
-
Bioadhesive Drug Delivery System
-
High Density Systems
-
Others
-
-
Dosage Outlook (Revenue, USD Million, 2018 - 2030)
-
Tablets
-
Capsule
-
Gel
-
Liquid
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million, 2018 - 2030)
-
Hospital Pharmacies
-
Retail Pharmacies
-
Online Pharmacies
-
-
Regional Outlook (Revenue, USD Billion, 2018 - 2030)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global gastroretentive drug delivery systems market size was valued at USD 15.6 billion in 2024 and is estimated at USD 17.6 billion for 2026.
The global gastroretentive drug delivery systems market is expected to grow at a CAGR of 6.4% from 2025 to 2030, reaching USD 22.7 billion by 2030.
Key factors that are driving the market growth include rising disease burden throughout the world and the proven efficacy of GRDDS in addressing several gastric-related disorders such as gastric ulcers, peptic ulcers, and others.
North America dominated with a revenue share of 41.3% in 2024.
Some key players operating in the GRDDS market include Ranbaxy, F. Hoffmann La Roche, Pharmacia, GlaxoSmithKline, Lupin, Pfizer, Depomed, Galanix, Sun Pharma, and Alcon, Inc.
The floating drug delivery systems segment accounted for the largest revenue share of 47.0% in 2024 in the GRDDS market. This system is one of the important methods to attain gastric retention to gain adequate drug bioavailability.
The retail pharmacies distribution channel segment dominated the market for GRDDS and captured the largest revenue share of 43.3% in 2024.
The tablets segment dominated the GRDDS market and accounted for the largest revenue share of 37.4% in 2024.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst -

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


