
- Home
- »
- Pharmaceuticals
- »
-
Gaucher Disease Drugs Market Size Report, 2026-2033GVR Report cover

Gaucher Disease Drugs Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Type 1, Type 2, Type 3, Others), By Therapy (Enzyme Replacement Therapy, Substrate Replacement Therapy, Others), By Region, And Segment Forecasts
Market Size, 2025
$1.8BMarket Estimate, 2026
$1.9BMarket Forecast, 2033
$2.2BCAGR, 2026–2033
2.3%Gaucher Disease Drugs Market Trends
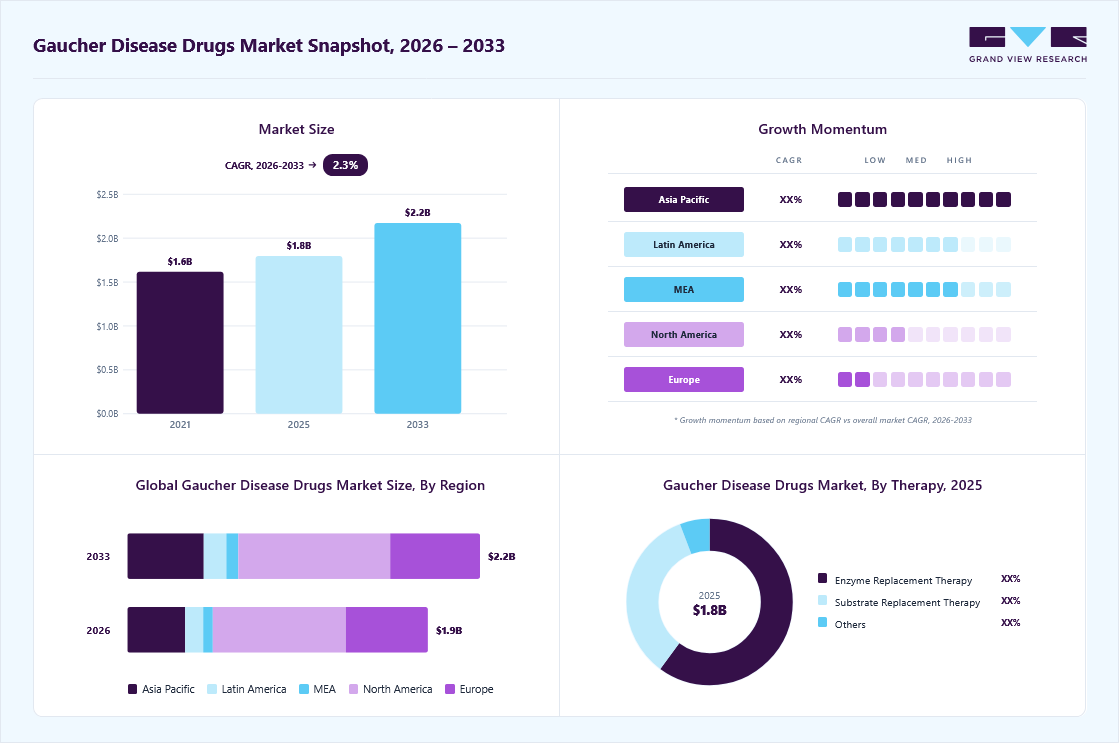
The global gaucher disease drugs market size was valued at USD 1.8 billion in 2025 and is projected to grow from USD 1.9 billion in 2026 to USD 2.2 billion by 2033, growing at a CAGR of 2.3% from 2026 to 2033. North America dominated the gaucher disease drugs market with the largest revenue share of 44.5% in 2025. An increase in the number of patients with rare diseases, increasing investment in the healthcare sector, and growing awareness about GD are expected to drive the market during the forecast period.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By drugs type: Type 1 segment led the market with the largest revenue share of 72.7% in 2025.
- By therapy: Enzyme replacement therapy segment led the market with the largest revenue share of 60.0% in 2025.
Regional Highlights
- Largest regional market: North America (44.5% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.8 Billion
- Estimated market size in 2026: USD 1.9 Billion
- Projected market size by 2033: USD 2.2 Billion
- CAGR (2026-2033): 2.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Gaucher disease is an autosomal recessive metabolic disorder and the most common lysosomal storage disorder. According to the National Gaucher Foundation (NGF) of the U.S., Gaucher disease affects almost 1 in every 40,000 live births in the general population. Genetic conditions are caused by mutations in the GBA gene, leading to reduced production of glucocerebrosidase and a consequent accumulation of glucocerebroside. This excess lipid accumulates in the brain, bone marrow, lungs, kidney, liver, and spleen, which obstructs normal body functions. The market is likely to exhibit modest growth during the forecast period. The rising incidence of lysosomal storage disease and increasing efforts to identify more GD patients are among the primary growth stimulants for the market.Several government and global organizations' awareness programs and initiatives are being carried out worldwide to spread awareness about rare diseases. For instance, in July 2023, the Australian government announced USD 3.3 Million to support around 2 million citizens suffering from rare diseases. That will provide them with support to create new educational programs and spread awareness.
 To learn more about this report, Download Free Sample Report
The global economies are now more concentrated on the healthcare sector and the welfare of their people. Thus, there is a surge in investments to support patients with rare diseases to improve people's standard of living. For instance, in March 2023, the Government of Canada announced support of around USD 1.5 Billion for three years to provide affordability and effective as well as authentic drugs for patients of rare diseases.
The lack of drugs in the late-stage pipeline and the rising treatment cost limit the market from realizing its utmost potential. There remains a high unmet need to develop improved treatments that combat neuronopathic complications at reduced costs and convenient administration schedules. Nevertheless, increasing investments in research and development activities related to rare diseases are projected to shape the future of the market.
Market Dynamics
The Gaucher Disease Drugs Market is influenced by the growing recognition of rare genetic disorders, increasing diagnosis rates, and continued improvements in disease management strategies. The market benefits from the widespread adoption of enzyme replacement therapies, which remain the primary treatment option due to their proven efficacy in managing systemic manifestations of the disease. Substrate reduction therapies are also gaining acceptance, particularly among patients seeking oral treatment alternatives. Supportive regulatory frameworks for orphan drugs and favorable reimbursement policies in several developed countries continue to encourage market growth. Advances in genetic screening and diagnostic technologies are enabling earlier identification of patients, supporting timely treatment initiation and improved clinical outcomes. At the same time, ongoing research activities focused on novel therapeutic approaches, including gene based treatments, are expanding the future treatment landscape. However, factors such as high therapy costs, limited patient populations, and disparities in access to specialized healthcare services across regions remain key challenges affecting market expansion and treatment accessibility.
The Gaucher Disease Drugs Market is being driven by continuous advancements in therapeutic development aimed at improving long term disease management and reducing treatment burden. While enzyme replacement therapies remain the standard treatment approach, pharmaceutical companies are increasingly investing in innovative modalities such as gene therapies that have the potential to deliver sustained clinical benefits with fewer interventions. Growing research activity, supportive orphan drug regulations, and increasing awareness of rare genetic disorders are encouraging the development of next generation treatment options. These advancements are expected to improve patient outcomes, enhance treatment accessibility, and strengthen the overall commercial landscape for Gaucher disease therapies. Furthermore, increasing collaboration between biotechnology companies, regulatory agencies, and patient advocacy groups is accelerating clinical development efforts and supporting market expansion. For instance, in October 2024, NeurologyLive reported positive Phase 1/2 GALILEO-1 trial results for Spur Therapeutics' FLT201 gene therapy in Gaucher disease. The study demonstrated reductions in lyso-Gb1 levels ranging from 42% to 96% among treated patients, and the company stated plans to initiate a Phase 3 clinical trial in 2025. This progress highlighted the growing momentum behind advanced therapeutic approaches that could transform long term treatment strategies for Gaucher disease patients.
A major restraint in the Gaucher Disease Drugs Market is the limited patient population affected by the disease, which creates challenges for clinical trial recruitment, product commercialization, and return on investment for drug developers. As a rare lysosomal storage disorder, Gaucher disease affects a relatively small number of patients worldwide, making it difficult to conduct large scale clinical studies and generate extensive real world evidence. The rarity of the condition also contributes to delayed diagnosis in several regions, limiting treatment penetration and reducing the addressable market. In addition, manufacturers often face high research, development, and production costs that must be recovered across a small patient base. These factors can contribute to elevated therapy prices and reimbursement challenges in certain healthcare systems. For instance, in October 2025, CGTLive reported updated GALILEO-1 data for FLT201, where 4 patients discontinued their prior standard of care therapy within 4 to 11 weeks after receiving treatment, with follow up durations ranging from 19 to 23 months. The report underscored the reality that clinical studies in Gaucher disease frequently involve very small patient populations, reflecting a key structural challenge within the market.
A significant opportunity for the Gaucher Disease Drugs Market lies in the development of therapies targeting neurological manifestations associated with neuronopathic forms of the disease. Existing enzyme replacement therapies have demonstrated strong efficacy in treating systemic symptoms but have limited ability to address central nervous system complications. This has created a substantial unmet medical need, particularly for patients with Type 3 Gaucher disease. Companies developing therapies capable of targeting neurological disease progression have the potential to access an underserved segment with limited treatment options. Advances in substrate reduction therapies, gene therapies, and other novel approaches are expanding the possibilities for addressing these unmet needs. Regulatory incentives for orphan drug development further enhance the attractiveness of this opportunity. For instance, in May 2026, Sanofi announced that the U.S. FDA had accepted the New Drug Application for venglustat under Priority Review for Type 3 Gaucher disease and assigned a target action date of November 25, 2026. If approved, the therapy would become the first treatment in the United States specifically designed to address the progressive neurological manifestations of Type 3 Gaucher disease, creating a meaningful opportunity for innovation and market expansion.
Type Insights
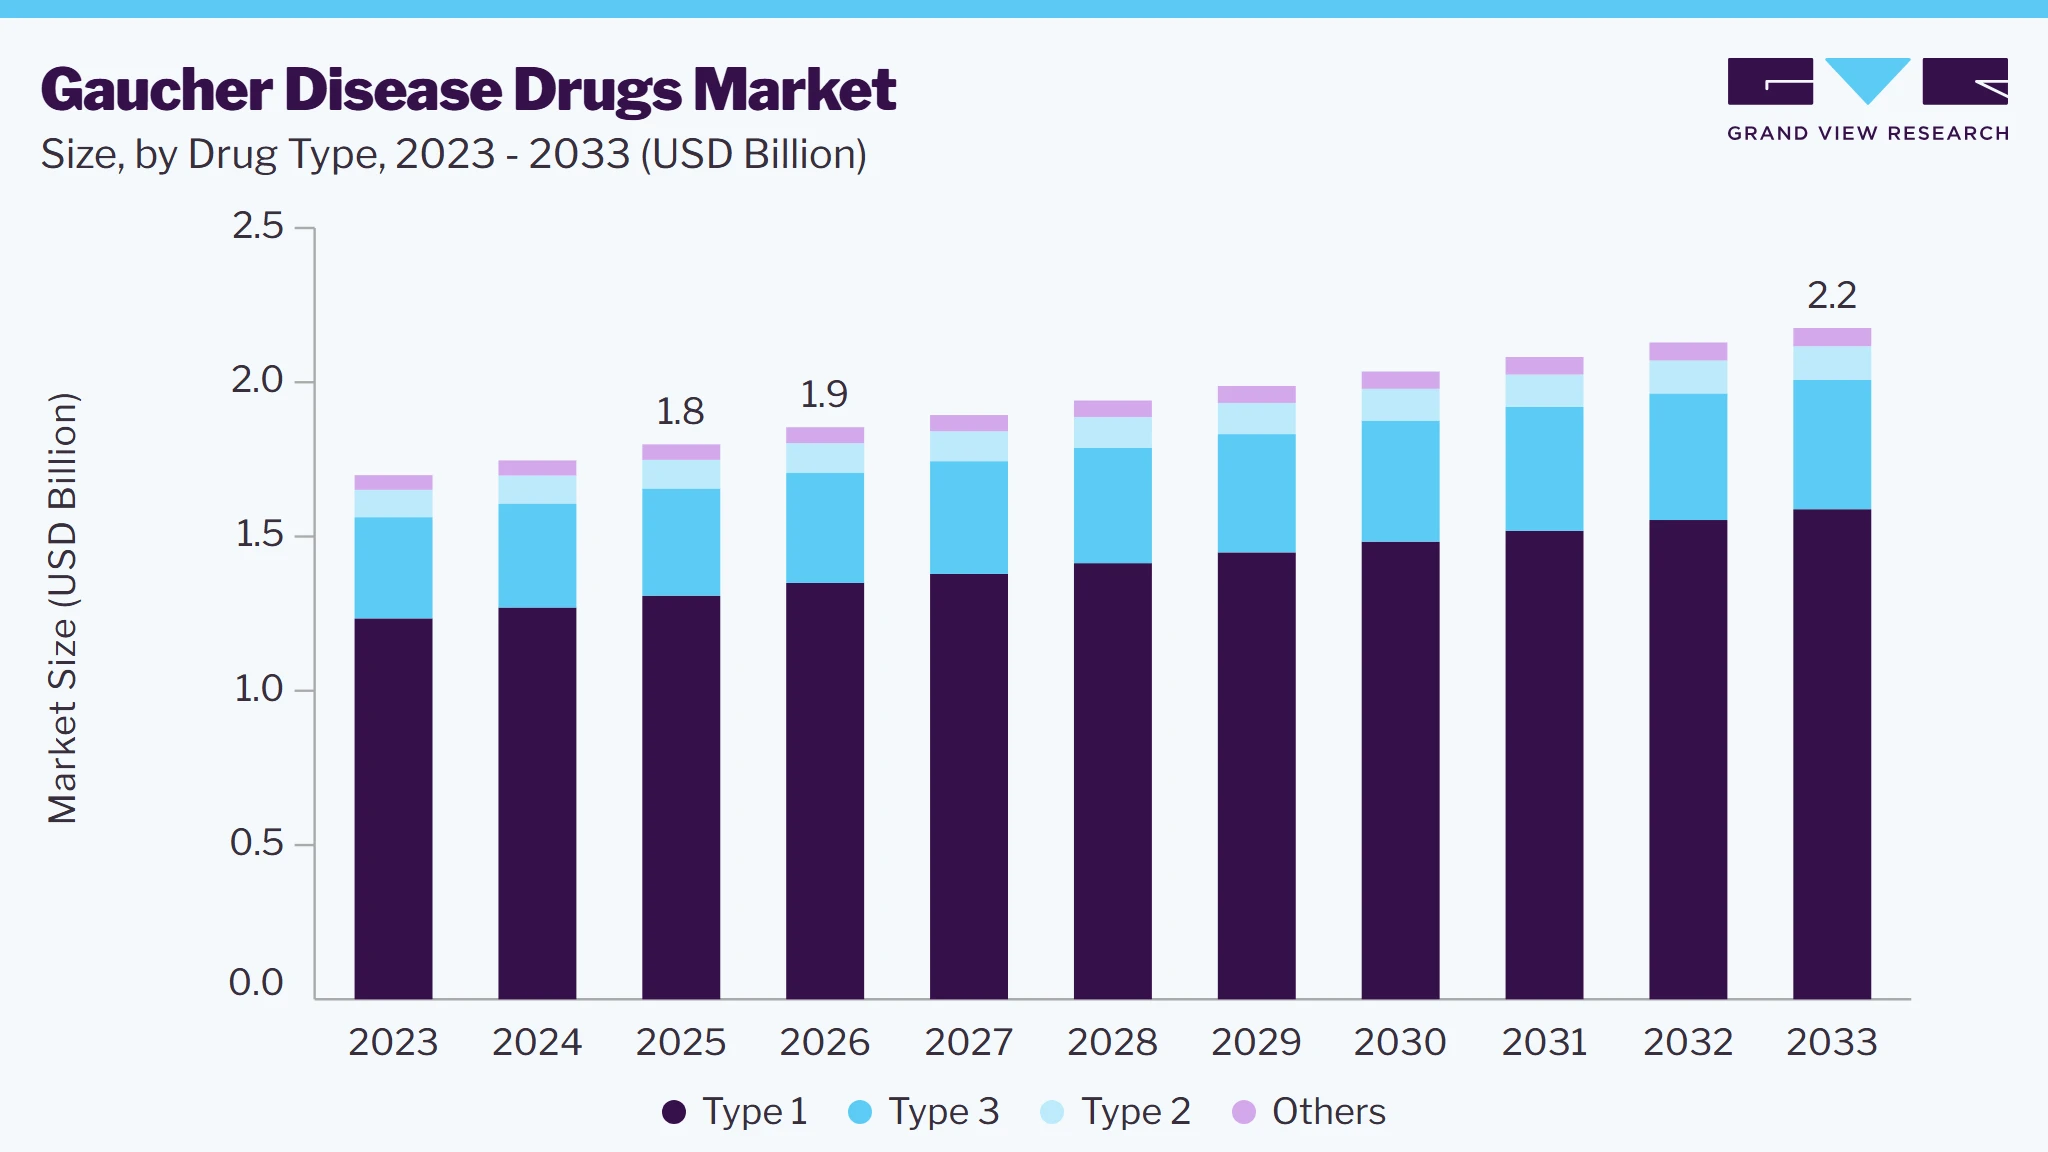
Based on drugs type, the type 1 segment led the market with the largest revenue share of 72.7% in 2025, owing to its rising prevalence in patients. Type 1 disease is the most common disease among all three types. According to National Organization for Rare Disorders (NORD) in March 2020, type 1 alone accounts for more than 90% of cases of GD. The condition does not affect the central nervous system (CNS), making it non-neuronopathic. This disorder can develop anytime between childhood and adulthood; the average life expectancy is 70 years. The segment is estimated to retain its position until 2030 owing to the increasing adoption of treatment for this type.
Type 2 and 3 are neuronopathic diseases, causing CNS complications during the disease course. Infants with type 2 GD rarely survive beyond two years due to lack of treatment and severity of disease progression. The type 3 segment is expected to grow at the fastest CAGR of 2.75% over the forecast period. This growth can be attributed to its gigantic presence in the eastern part of the world. According to NGF, type - 3 is more common than type - 1 in the Middle East, India, China, and Pacific Rim.
Other rare forms of the disease include the perinatal lethal form and the cardiovascular form. The perinatal lethal form is the most severe disease, causing life-threatening complications in infants or fetuses. Cardiovascular form affects the heart, primarily causing calcification of heart valves.
Therapy Insights
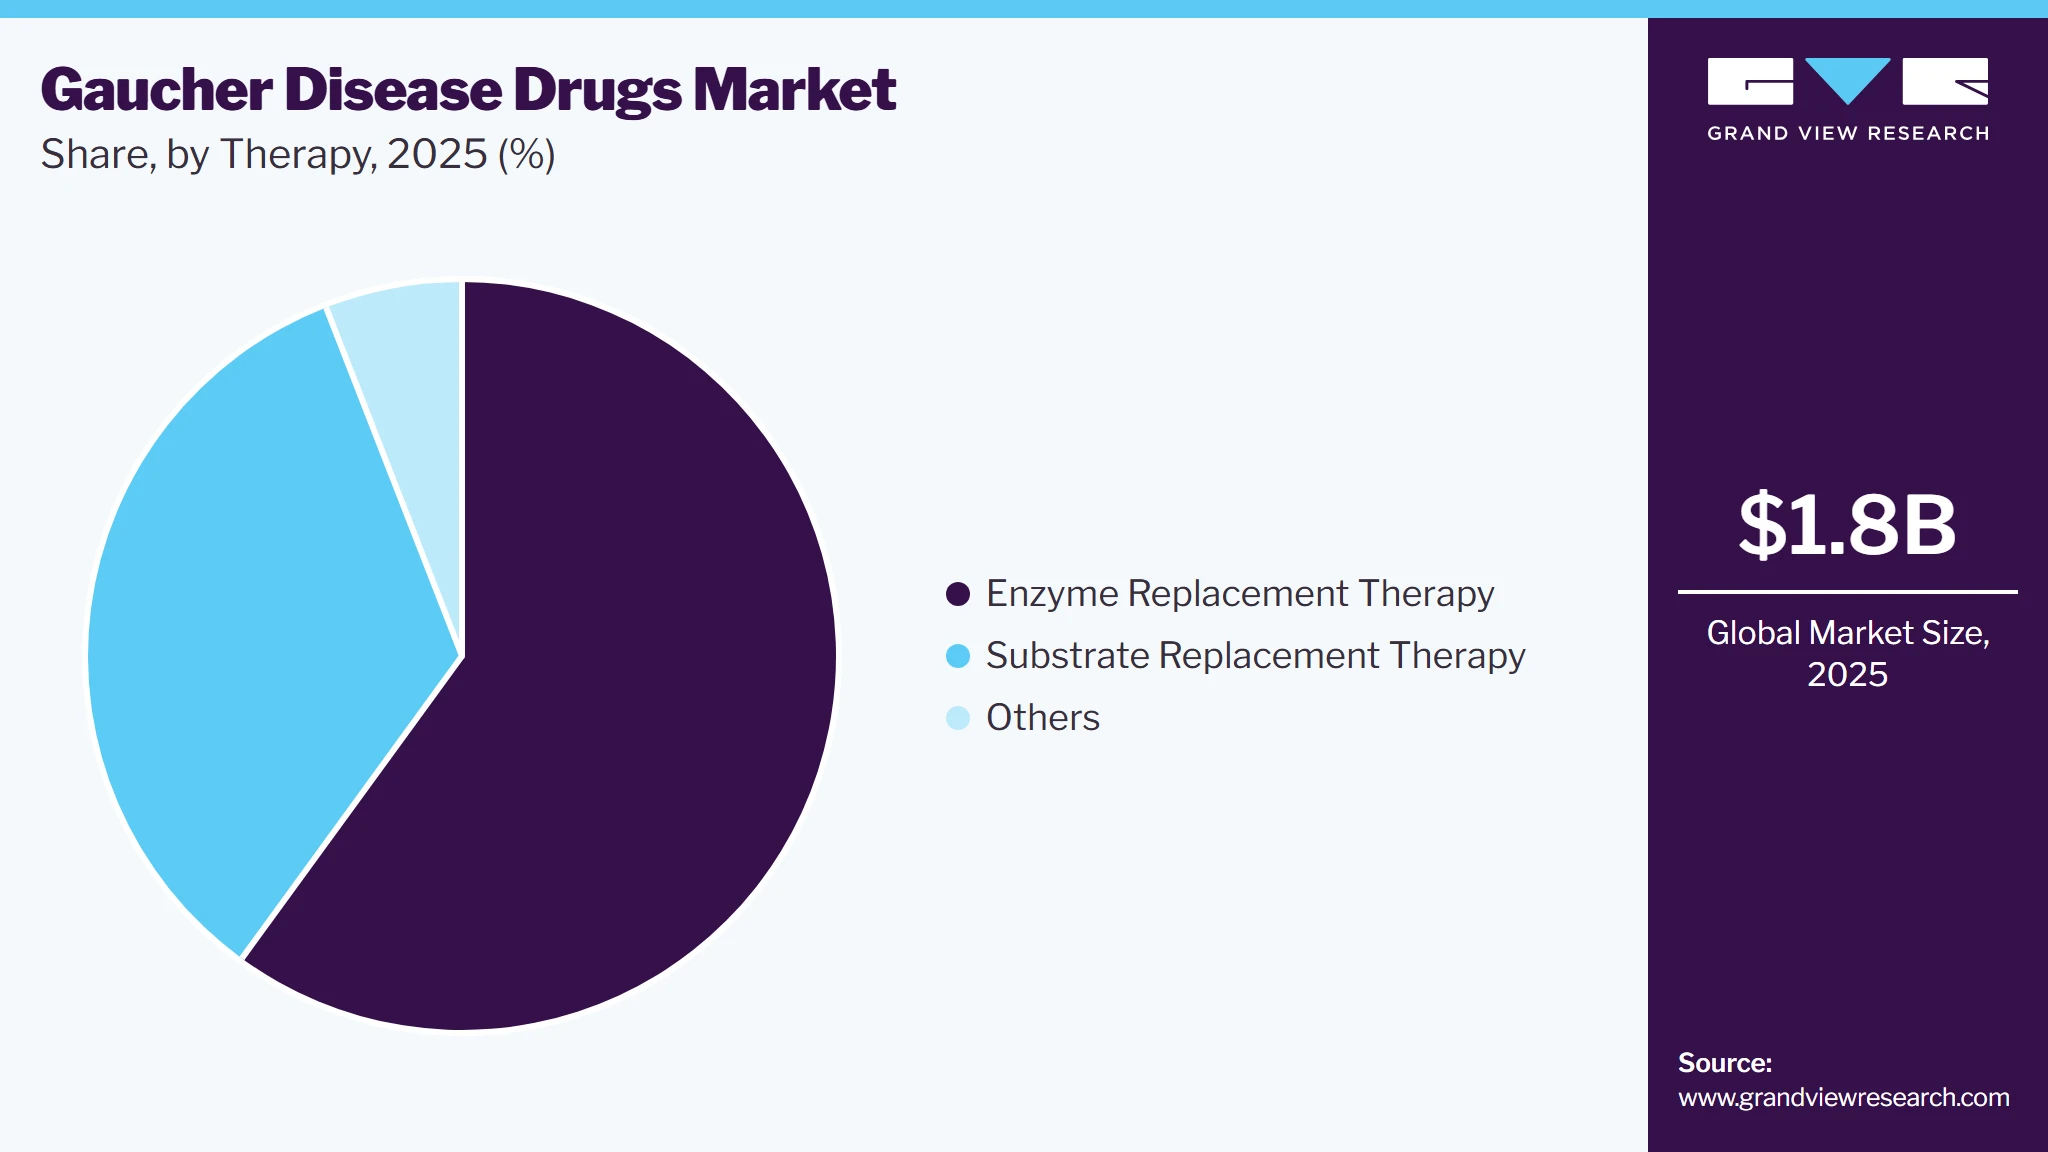
Based on drugs therapy, the enzyme replacement therapy segment led the market with the largest revenue share of 60.0% in 2025. However, the market is expected to grow slowly in the forecast period owing to the upcoming substitutes of ERT and higher treatment costs. According to NGF, the cost of ERT can go up to USD 2,00,000 or more each year.
 To learn more about this report, Download Free Sample Report
SRT is expected to grow at the fastest CAGR of 9.3% owing to the ease of treatment, as SRT is an oral medication. Moreover, SRT is cost saving as compared to other ways of treatment. The U.S. Food and Administration (FDA) approved the first SRT in 2003 for Gaucher disease. As of now, the U.S. FDA has approved two oral SRT drugs, namely: Cerdelga and Zavesca, for patients of GD.
Regional Insights
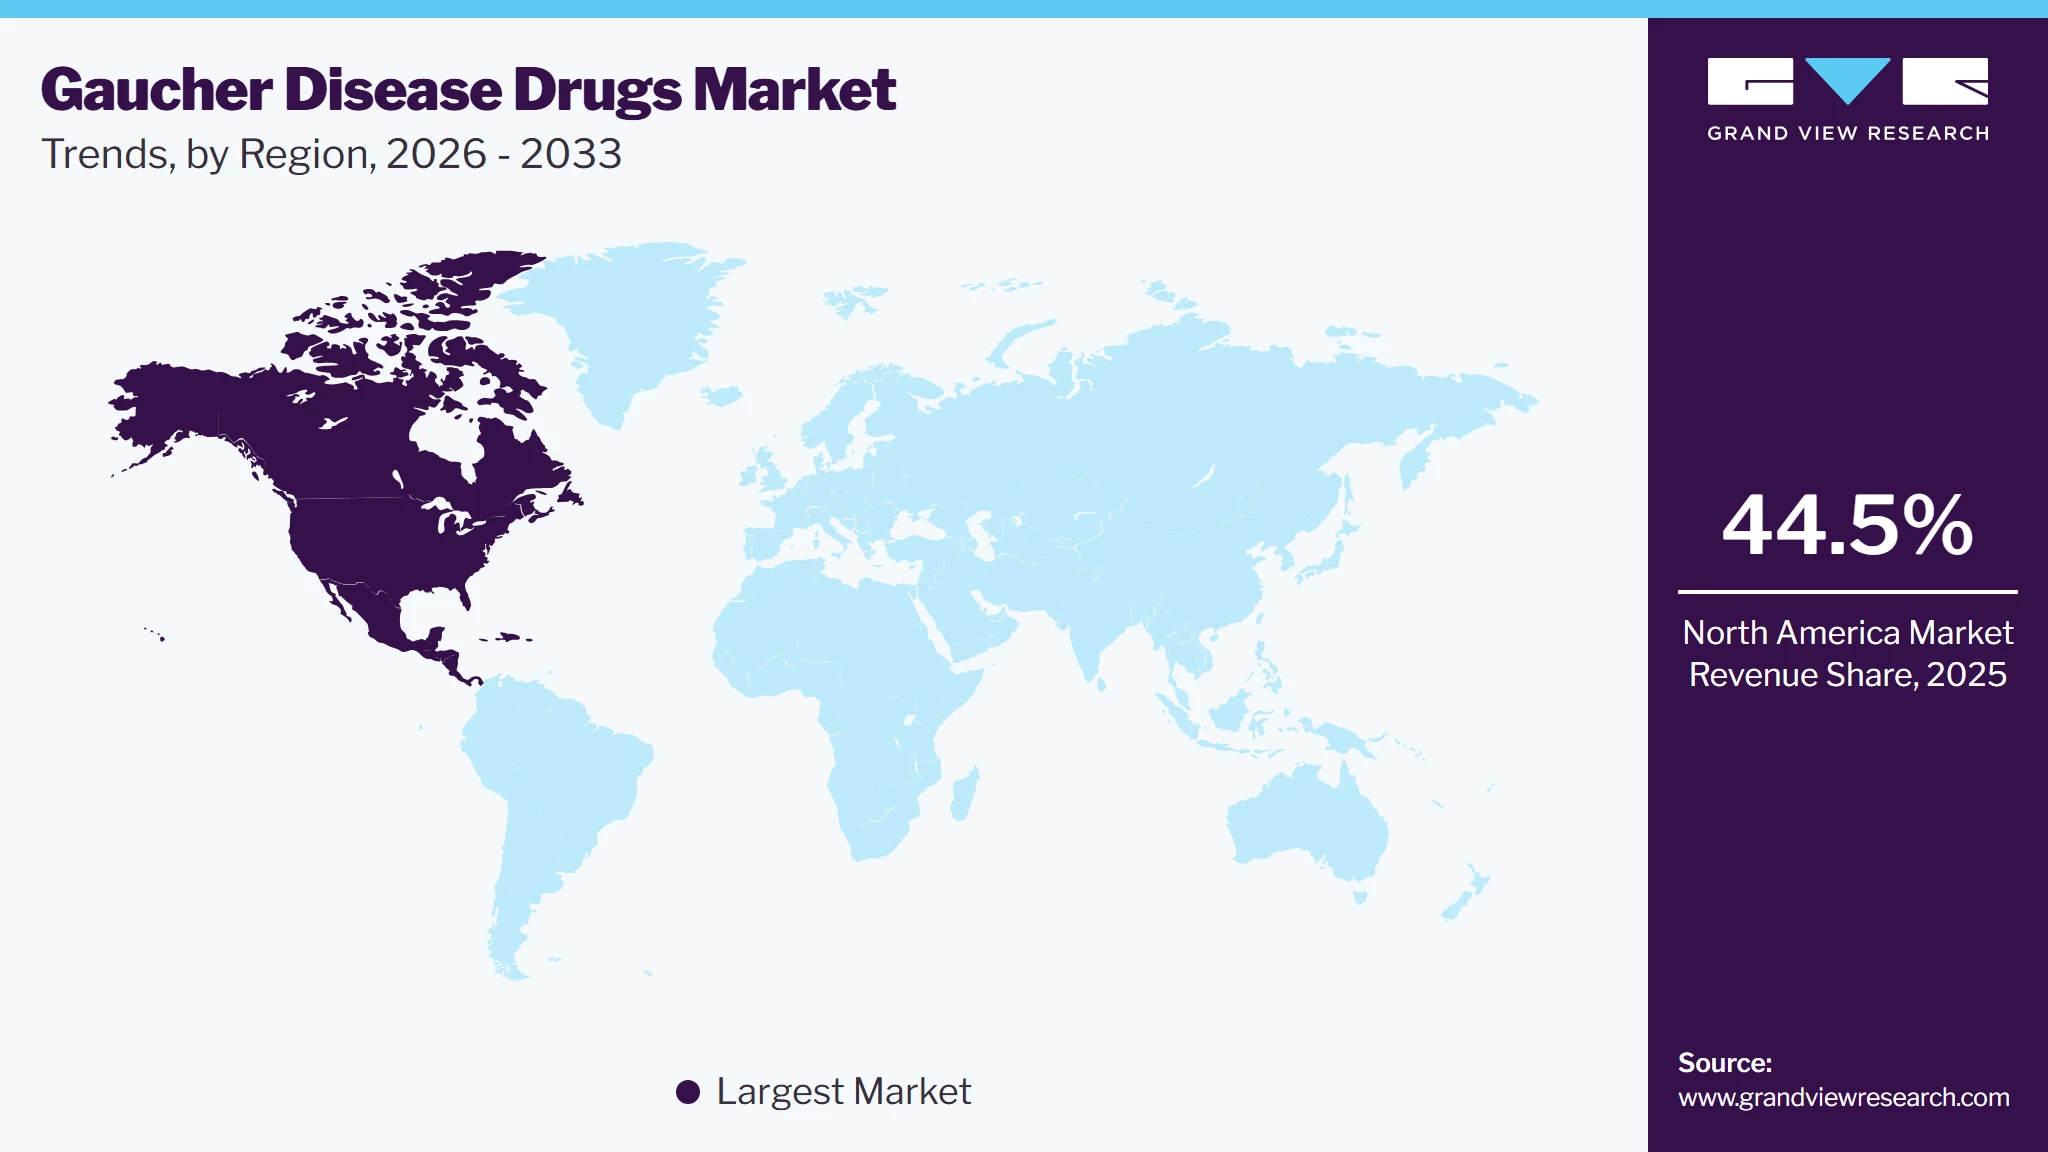
North America dominated the gaucher disease drugs market with the largest revenue share of 44.5% in 2025 owing to rising awareness about Gaucher disease, advanced healthcare infrastructure, and access to treatment. The gaucher disease drugs market in the U.S. held the largest share in the North America region in 2025. According to a report published by NORD in March 2020, the U.S. alone has approximately 6000 people living with GD. Organizations such as the National Gaucher Foundation of the U.S. and the National Gaucher Foundation of Canada are spreading awareness among people about GD. North America was followed by Europe in the revenue share owing to the presence of an Ashkenazi Jewish population and better infrastructure facilities to treat GD and other rare diseases.
 To learn more about this report, Download Free Sample Report
Asia Pacific is expected to grow at the fastest CAGR of 3.4% in the forecast period. This growth can be backed by the rising healthcare infrastructure facilities and government initiatives to spread awareness about rare and life-threatening diseases. For instance, the Australian government is running a Life Saving Drug Program (LSDP) program to pay for medicines for patients with life-threatening and ultra-rare diseases. Medicines for GD are also listed in the LSDP.
Key Companies & Market Share Insights
Collaborations for the development and commercialization of therapeutics drive the market. Companies focus on launching authentic treatment therapies and substitutes for existing therapies. For instance, in January 2022, Freeline announced FDA clearance of its International New Drug (IND) application for its gene therapy FLT201. This therapy has been approved as an investigational gene therapy and is expected to be a transformative treatment for Gaucher disease patients. In December 2020, Lilly announced the acquisition of Prevail Therapeutics, which will help Lilly to establish a gene therapy program to develop treatments for patients with Gaucher disease. In August 2020, Centogene N.V. and Evotec SE announced extending their Gaucher disease-related drug discovery partnership. This extended partnership is expected to accelerate drug and medical solution discovery for Gaucher disease.
In April 2018, Amerigen Pharmaceuticals Limited and Dipharma S.A. announced the approval of their Miglustat 100 mg capsules by the U.S. FDA. It is anticipated work as monotherapy for patients with type 1 Gaucher disease. The market players are also doing mergers and acquisitions to get a competitive advantage. For instance, in January 2017, Janssen acquired Actelion, a type-1 Gaucher disease treatment-approved company, to add complementary therapeutics and promising late-stage pipeline candidates to its portfolio.
Key Gaucher Disease Drugs Companies:
The following key companies have been profiled for this study on the gaucher disease drugs market.
-
Sanofi
-
Takeda Pharmaceutical Company Limited
-
Pfizer Inc
-
Johnson & Johnson Services, Inc.
-
ERAD Therapeutic
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Sanofi, Takeda Pharmaceutical Company Limited, Pfizer Inc., Johnson & Johnson Services, Inc., Chiesi Global Rare Diseases)
- Focus on strengthening rare disease portfolios through lifecycle management of approved Gaucher disease therapies and expansion into additional geographic markets. Invest in clinical research, patient support programs, physician education initiatives, and strategic collaborations to improve diagnosis and treatment access. Continue to advance next generation therapies and pursue regulatory approvals for label expansions and new indications.
- Strong commercial presence supported by established rare disease expertise, extensive regulatory experience, and global distribution capabilities. Robust financial resources enable sustained investment in research and development, clinical trials, and market access initiatives. Long standing relationships with healthcare providers, treatment centers, and patient advocacy organizations support market leadership.
- High dependence on a limited rare disease patient population can constrain revenue growth. Significant research, development, manufacturing, and compliance costs associated with orphan drugs may affect profitability. Complex global regulatory requirements can lengthen product development and approval timelines.
Emerging Players (ERAD Therapeutic, Spur Therapeutics, ISU ABXIS Co., Ltd., Azafaros B.V., Gain Therapeutics, Inc.)
- Focus on developing innovative therapies including gene therapies, pharmacological chaperones, substrate reduction approaches, and next generation enzyme replacement technologies. Target unmet clinical needs such as neuronopathic Gaucher disease and long term disease modification. Pursue strategic partnerships, licensing agreements, and clinical development programs to accelerate commercialization and market entry.
- Ability to introduce differentiated therapeutic platforms addressing limitations of existing treatments. Agile organizational structures enable faster decision making and greater focus on innovation. Strong emphasis on novel mechanisms of action creates opportunities to address underserved patient segments and gain orphan drug advantages.
- Limited commercial infrastructure and smaller financial resources compared with established pharmaceutical companies. Dependence on successful clinical trial outcomes and regulatory approvals increases business risk. Restricted global distribution capabilities and lower market visibility may slow adoption following product launch.
Gaucher Disease Drugs Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.8 billion
Estimated market size in 2026
USD 1.9 billion
Projected market size by 2033
USD 2.2 billion
Growth rate
CAGR of 2.3% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, therapy, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; Russia; Iceland; Finland; China; Japan; India; South Korea; Australia; Thailand; Singapore; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Israel
Key companies profiled
Sanofi, Takeda Pharmaceutical Company Limited, Pfizer Inc., Johnson & Johnson Services, Inc., ERAD Therapeutic, Chiesi Global Rare Diseases, Spur Therapeutics (formerly Freeline Therapeutics), ISU ABXIS Co., Ltd., Azafaros B.V., Gain Therapeutics, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Gaucher Disease Drugs Market Report Segmentation
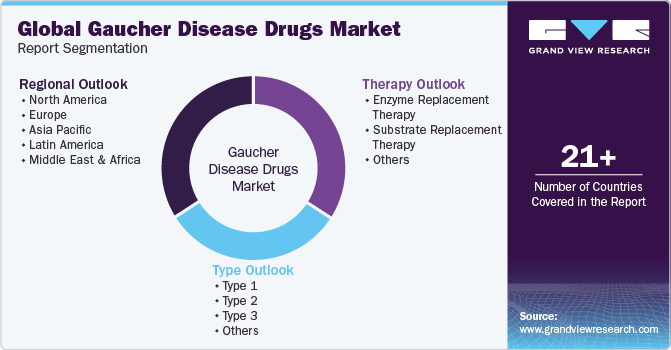
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global Gaucher disease drugs market report on the basis of type, therapy, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Type 1
-
Type 2
-
Type 3
-
Others
-
-
Therapy Outlook (Revenue, USD Million, 2021 - 2033)
-
Enzyme Replacement Therapy
-
Substrate Replacement Therapy
-
Others
-
-
Regional Outlook (Revenue in USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
U.K.
-
Germany
-
France
-
Italy
-
Spain
-
Sweden
-
Norway
-
Denmark
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
Kuwait
-
-
Research Methodology
The gaucher disease drugs market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each gaucher disease drugs segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Drugs Type
Revenue capture definition
Type 1
Revenue generated from drugs prescribed for the treatment of Type 1 Gaucher disease, the non neuronopathic and most prevalent form of the disorder. This segment includes revenue from enzyme replacement therapies, substrate reduction therapies, and other approved or investigational treatments administered to patients diagnosed with Type 1 Gaucher disease. All revenue associated with Type 1 indications is classified exclusively within this segment irrespective of therapy type, treatment setting, or geographic market.
Type 2
Revenue generated from drugs used in the treatment of Type 2 Gaucher disease, the acute neuronopathic form characterized by severe neurological involvement and rapid disease progression. This segment includes revenue from approved therapies, supportive pharmacological treatments, and investigational products specifically prescribed for Type 2 Gaucher disease. Revenue attributable to Type 2 indications is reported exclusively within this category.
Type 3
Revenue generated from drugs prescribed for Type 3 Gaucher disease, the chronic neuronopathic form associated with both systemic and neurological manifestations. This segment includes sales of enzyme replacement therapies, substrate reduction therapies, and emerging treatments intended to manage disease progression and neurological complications. All revenue related to Type 3 Gaucher disease is assigned solely to this segment.
Others
Revenue generated from drugs used in Gaucher disease indications not specifically categorized under Type 1, Type 2, or Type 3. This includes atypical presentations, mixed phenotypes, unclassified Gaucher disease cases, and future disease classifications recognized during the forecast period. Revenue is allocated to this segment only when it cannot be attributed to the predefined disease type categories.
Segment - Drugs Therapy
Revenue capture definition
Enzyme Replacement Therapy
Revenue generated from enzyme replacement therapies used for the treatment of Gaucher disease. These therapies supplement deficient glucocerebrosidase enzyme activity and include products such as imiglucerase, velaglucerase alfa, taliglucerase alfa, and other approved or future enzyme replacement products. Revenue from all Gaucher disease treatments based on enzyme replacement mechanisms is attributed exclusively to this segment.
Substrate Reduction Therapy
Revenue generated from substrate reduction therapies that reduce the production and accumulation of glucocerebroside in Gaucher disease patients. This segment includes oral therapies such as eliglustat, miglustat, and future substrate reduction products approved for Gaucher disease management. All revenue associated with substrate reduction treatment approaches is classified solely within this category.
Others
Revenue generated from Gaucher disease therapies not categorized as enzyme replacement therapy or substrate reduction therapy. This includes gene therapies, pharmacological chaperones, stem cell based therapies, supportive treatments, investigational products, and emerging therapeutic modalities under commercialization. Revenue is assigned to this segment only when the therapy mechanism does not fall within the predefined treatment categories above.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Gaucher Disease Competitive Landscape & Pipeline Assessment
Conducted a targeted assessment of the global Gaucher disease therapeutics landscape, evaluating approved enzyme replacement therapies, substrate reduction therapies, and emerging pipeline candidates including gene therapies and pharmacological chaperones. The study analyzed key market participants such as Sanofi, Takeda Pharmaceutical Company Limited, Chiesi Global Rare Diseases, Spur Therapeutics, and Gain Therapeutics, along with ongoing clinical development activities, regulatory milestones, and innovation trends across Type 1, Type 2, and Type 3 Gaucher disease segments.
Helped the client identify high potential therapeutic opportunities, assess competitive positioning, benchmark pipeline maturity, and evaluate licensing, acquisition, and partnership opportunities within the evolving Gaucher disease treatment market.
Gaucher Disease Therapy & Innovation Benchmarking Study
Delivered a comprehensive benchmarking analysis of Gaucher disease treatment technologies, focusing on enzyme replacement therapies, substrate reduction therapies, gene therapy platforms, and novel disease modifying approaches. The assessment compared clinical efficacy, safety profiles, treatment accessibility, pipeline progress, intellectual property positioning, and commercialization strategies across leading developers and emerging biotechnology companies.
Enabled the client to assess technology competitiveness, identify innovation gaps, evaluate emerging therapeutic modalities, and prioritize investments in next generation Gaucher disease treatment platforms and rare disease research initiatives.
Gaucher Disease Manufacturing & Commercialization Feasibility Assessment
Conducted a strategic assessment of the Gaucher disease drug manufacturing ecosystem, evaluating biologics production capabilities, enzyme manufacturing infrastructure, supply chain requirements, regulatory compliance frameworks, orphan drug commercialization pathways, and global distribution networks. The study also examined manufacturing scalability, market access challenges, reimbursement environments, and regional treatment availability supporting commercial expansion.
Supported strategic planning by identifying qualified manufacturing partners, assessing supply chain resilience, evaluating commercialization readiness, strengthening market access strategies, and improving long term scalability for Gaucher disease therapeutics across global markets.
Frequently Asked Questions About This Report
The global gaucher disease drugs market size was valued at USD 1.8 billion in 2025 and is expected to reach USD 1.9 billion by 2026.
The global Gaucher disease drugs market is expected to grow at a CAGR of 2.3% from 2026 to 2033, reaching USD 2.2 billion by 2033.
Enzyme replacement therapy segment led the market with the largest revenue share of 60.0% in 2025.
Some of the key players operating in the Gaucher disease drugs market are Sanofi Genzyme, Shire, Pfizer, and Johnson & Johnson. Sanofi Genzyme dominated the market with a nearly 65.0% share in 2022.
Rising incidence of the disease and increasing efforts for the identification of more GD patients are among the primary growth factors for the market.
North America dominated the market with the largest revenue share of 44.5% in 2025.
Type 1 segment led the market with the largest revenue share of 72.7% in 2025.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


