
- Home
- »
- Biotechnology
- »
-
Gene Silencing Market Size And Share Report, 2026-2033GVR Report cover

Gene Silencing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (Drug Discovery & Development, Therapeutics Manufacturing), By Product & Service, By End Use(Pharmaceutical & Biotechnology Companies, Academic & Research Institutes), By Region, And Segment Forecasts
Market Size, 2025
$11.2BMarket Estimate, 2026
$12.6BMarket Forecast, 2033
$28.7BCAGR, 2026–2033
12.5%Gene Silencing Market Summary
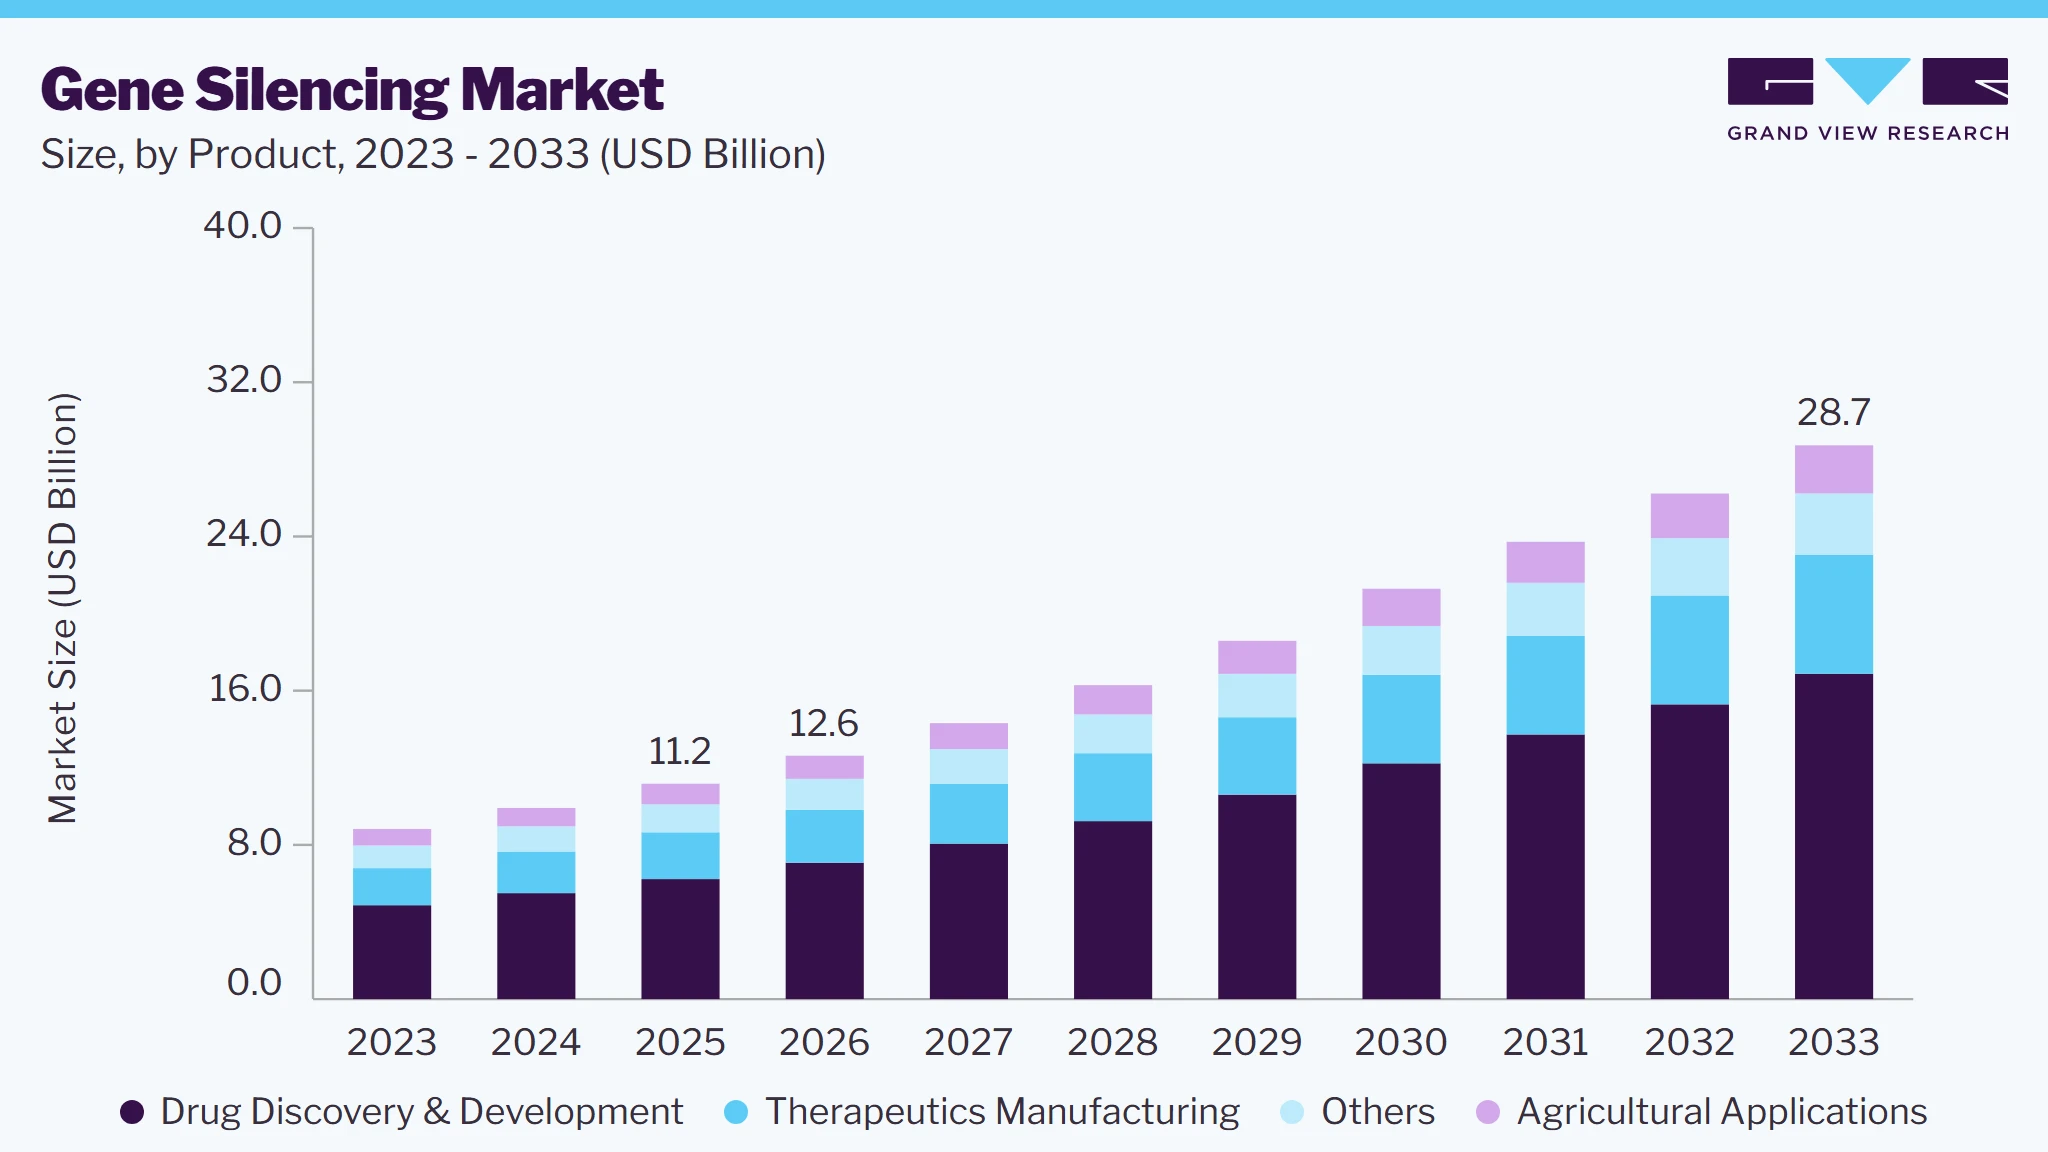
The global gene silencing market size was valued at USD 11.2 billion in 2025 and is projected to grow from USD 12.6 billion in 2026 to USD 28.7 billion by 2033, at a CAGR of 12.5% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 48.6% in 2025. The gene silencing industry is driven by the rising prevalence of genetic disorders and chronic diseases, prompting demand for targeted therapies such as RNA interference (RNAi) and antisense oligonucleotides (ASOs).
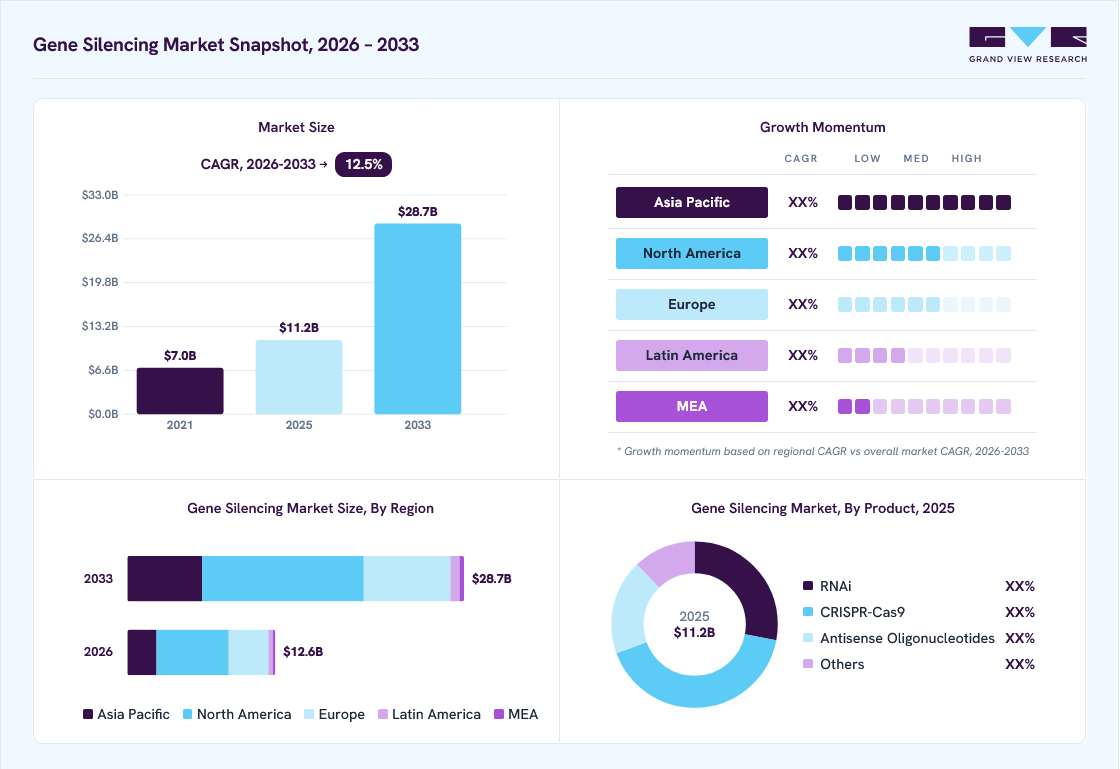 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product & service: Products segment held the largest revenue share of over 71.0% in 2025.
- By application: Drug discovery & development segment held the largest revenue share of over 55.7% in 2025
- By end use: Pharmaceutical & biotechnology companies segment held the largest revenue share of over 41.8% in 2025.
Regional Highlights
- Largest regional market: North America (48.6% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 11.2 Billion
- Estimated market size in 2026: USD 12.6 Billion
- Projected market size by 2033: USD 28.7 Billion
- CAGR (2026-2033): 12.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Advancements in delivery systems, like lipid nanoparticles, have improved the stability and precision of these treatments, expanding their potential to address conditions like neurological and cardiovascular diseases.One primary driver is the increasing prevalence of genetic disorders and chronic diseases, which has heightened the demand for innovative therapeutic approaches. Gene silencing technologies, such as RNA interference (RNAi) and antisense oligonucleotides (ASOs), offer targeted treatments by specifically inhibiting the expression of disease-causing genes. This precision has made them attractive candidates for addressing conditions that were previously difficult to treat.
 To learn more about this report, Download Free Sample Report
Technological advancements have also played a pivotal role in driving the market forward. Innovations in delivery mechanisms, such as lipid nanoparticles and conjugate-based systems, have enhanced the stability and specificity of gene silencing agents, improving their efficacy and safety profiles. These developments have expanded the potential applications of gene silencing beyond hepatic diseases to include neurological and cardiovascular disorders. Collaborations between biotech companies, pharmaceutical firms, and academic institutions have further accelerated the development and commercialization of RNAi therapeutics, addressing regulatory and technical challenges.
Recent corporate activities underscore the dynamic market nature. For example, Arrowhead Pharmaceuticals entered into a substantial licensing agreement with Sarepta Therapeutics, valued at up to $11.38 billion over the next five years. This deal includes an upfront payment of $825 million and reflects a significant commitment to advancing gene silencing therapies for neuromuscular diseases. In addition, Avidity Biosciences has made notable strides in developing RNA-targeting therapies for muscular dystrophies. Their innovative approach aims to silence problematic genes associated with these conditions, offering hope for effective treatments. These developments highlight the growing investment and confidence in gene silencing technologies as transformative therapeutic modalities.
The market is experiencing significant growth, driven by advancements in gene silencing technology and the increasing demand for targeted therapies. Market research indicates a growing interest in gene silencing techniques, such as RNA interference (RNAi) and CRISPR-based technologies, which pave the way for innovative treatments in various therapeutic areas, including genetic disorders and cancer. As the gene silencing industry size continues to expand, key technology trends, such as improved delivery systems and enhanced precision targeting, are facilitating more effective and personalized treatments. These innovations are attracting investment and driving the market forward, with a focus on overcoming delivery challenges and maximizing therapeutic potential.
Rising Incidence of Genetic Disorders
The prevalence of genetic and congenital diseases significantly impacts prenatal and neonatal mortality rates across various regions. Genetic factors are key contributors to many multifactorial conditions, adding to their complexity and severity. These disorders often involve multiple bodily systems, making effective treatment challenging due to their genetic origins.
Data from the Department of Health and the Government of Western Australia highlight the extensive reach of genetic disorders, affecting a notable portion of the population. The high incidence of genetic conditions and birth abnormalities among newborns underscores the urgent need for targeted interventions. While gene silencing techniques offer promising treatment options for certain genetic disorders, many current therapies fail to address the root genetic causes.
Genetic mutations, environmental factors like chemical exposure, and radiation further contribute to developing these conditions, emphasizing the demand for improved therapeutic strategies. The rising prevalence of genetic disorders across different demographics and regions drives market growth as innovative treatments become essential to managing these complex conditions.
Gene Therapy Clinical Trial Pipeline
Gene Therapies
Company
Phase
Indication
RP-L102
Rocket Pharmaceuticals
Preregistration
Fanconi's anaemia
DTX401
Ultragenyx Pharmaceutical Inc
III
Glycogen storage disease type I
ADVM-022
Adverum Biotechnologies
II
Diabetic retinopathy; Wet age-related macular degeneration
KYV-101
Kyverna Therapeutics
II
Multiple sclerosis; Myasthenia gravis; Stiff-person syndrome
RP A501
Rocket Pharmaceuticals
II
Glycogen storage disease type II
ALLO 605
Allogene Therapeutics/Cellectis
I/II
Multiple myeloma
CD19-NEX-T
Juno Therapeutics
I
Multiple sclerosis; Non-Hodgkin's lymphoma; Systemic lupus erythematosus
NW 301V
Neowise Biotechnology
I
Solid tumors
WZTL 002
Wellington Zhaotai Therapies
I
Non-Hodgkin's lymphoma
High Cost of Gene Silencing Treatments
The high cost of gene silencing treatments is primarily driven by the complexity of the technologies involved, including the development of specialized delivery systems, rigorous clinical trial processes, and the need for precise genetic targeting. Advanced techniques like RNA interference (RNAi) and CRISPR-based therapies require significant research and development investment and sophisticated manufacturing capabilities to ensure safety and efficacy. Moreover, the regulatory hurdles for approval and the need for personalized treatment regimens further contribute to the high expenses. These factors make gene silencing therapies expensive, limiting their accessibility despite their potential to treat rare and complex genetic disorders.
Technique
Mechanism
Applications
Advantages
Limitations
Cost
RNA Interference (RNAi)
Utilizes small interfering RNAs (siRNAs) to degrade target mRNA, preventing translation.
Functional genomics, therapeutic gene silencing.
High specificity, reversible effects.
Delivery challenges, potential off-target effects.
Moderate
CRISPR-Cas9
Employs a guide RNA to direct the Cas9 nuclease to specific DNA sequences, enabling targeted gene editing.
Gene knockout, functional genomics, potential therapeutic applications.
Permanent gene disruption, versatile applications.
Ethical concerns, risk of off-target effects.
High (due to research and development expenses)
RISPR Interference (CRISPRi)
A catalytically dead Cas9 (dCas9) is guided to gene promoters to inhibit transcription without inducing DNA breaks.
Reversible gene silencing, regulation of gene expression.
Does not rely on double-stranded DNA breaks or tunable expression.
Requires careful design to avoid off-target effects.
High (due to development and optimization efforts)
Market Dynamics
The gene silencing market is witnessing robust growth, driven by the increasing adoption of RNA interference (RNAi) and antisense technologies in therapeutics and functional genomics research. Rising investments in precision medicine, expanding applications in oncology and rare disease treatment, and growing demand for targeted gene therapies are further supporting market expansion. In addition, ongoing advancements in delivery technologies and increasing life sciences research activities are expected to propel market growth over the forecast period.
Technological advancements in siRNA and miRNA platforms are driving growth in the gene silencing market by enhancing the specificity, stability, and therapeutic efficacy of these approaches. Innovations such as chemically modified oligonucleotides, lipid nanoparticle-based delivery systems, and GalNAc conjugates have improved targeted delivery while reducing off-target effects. These advancements have broadened the application of gene silencing technologies across oncology, rare diseases, and other therapeutic areas, supporting increased adoption in both research and clinical settings.
For instance, in February 2025, Wave Life Sciences initiated a Phase 1 clinical trial of WVE-007, a long-acting GalNAc-conjugated siRNA candidate targeting obesity, highlighting the ongoing advancement of next-generation siRNA platforms with improved durability and tissue-targeting capabilities. In addition, in November 2024, Codexis presented advancements in its Enzyme Catalyzed Oligonucleotide (ECO) Synthesis platform, demonstrating novel enzymatic manufacturing approaches designed to enhance the scalability and efficiency of RNAi therapeutic production. Such advancements are expected to strengthen the commercial landscape for gene silencing technologies over the forecast period.
Stringent regulatory requirements for RNA-based therapeutics pose a significant challenge to the growth of the gene silencing market. Gene silencing products, including siRNA and antisense therapies, must undergo extensive preclinical and clinical evaluations to demonstrate their safety, efficacy, and long-term effects. Regulatory agencies require comprehensive data on off-target effects, immunogenicity, biodistribution, and delivery mechanisms, resulting in prolonged development timelines and increased development costs for market participants.
In addition, the evolving regulatory landscape for advanced genetic medicines creates uncertainties for developers, particularly for novel RNA platforms and delivery technologies. Differences in regulatory frameworks across regions further complicate global commercialization strategies, requiring companies to meet varying approval standards and compliance requirements. These factors can delay product approvals and market entry, thereby restraining the overall growth of the gene silencing market.
Market Concentration & Characteristics
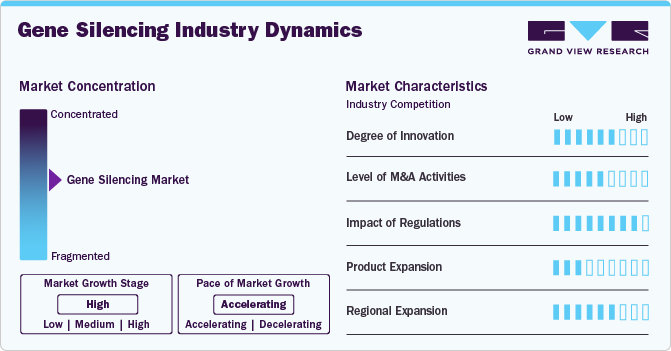
Innovation in the gene silencing industry is robust, with continuous advancements in RNA interference (RNAi) technologies, antisense oligonucleotides (ASOs), and improved delivery systems like lipid nanoparticles. Companies are actively developing novel therapeutic approaches to target previously untreatable genetic conditions, enhancing treatment precision and efficacy.
The industry has seen substantial merger and acquisition (M&A) activity as larger pharmaceutical firms acquire biotech innovators to strengthen their gene silencing portfolios. Notable deals include Novartis' acquisition of The Medicines Company for its RNAi technology, showcasing the strategic importance of these therapies in expanding treatment pipelines.
 To learn more about this report, Download Free Sample Report
Regulatory frameworks play a crucial role in shaping the gene silencing industry, with stringent guidelines set by authorities like the FDA and EMA. These regulations ensure safety, efficacy, and ethical considerations in gene-editing applications, influencing the pace of product approvals and commercialization.
The gene silencing industry is witnessing rapid product expansion, with therapies targeting conditions such as hereditary transthyretin amyloidosis (hATTR), hypercholesterolemia, and certain cancers. Companies are actively exploring new indications to broaden the clinical application of gene silencing therapies.
North America leads the gene silencing industry due to strong research infrastructure and high investment in biotech innovations. However, Asia-Pacific is emerging as a key growth region, driven by increasing healthcare investments, rising genetic disorder prevalence, and expanding clinical research initiatives.
Analyst Perspective
The gene silencing market is expected to witness significant growth, driven by the increasing adoption of RNA interference (RNAi), antisense technologies, and CRISPR-based approaches in therapeutic development and functional genomics research. Rising investments in precision medicine, expanding applications in oncology and rare disease treatment, and growing demand for targeted therapies are fueling market expansion. Continuous advancements in gene editing and nucleic acid delivery technologies are improving the efficacy and specificity of gene silencing platforms, while increasing research activities in genomics and drug discovery are expected to support long-term market growth. Market participants are focusing on technological innovation and strategic collaborations to strengthen their competitive position in this rapidly evolving field.
Product & Service Insights
In 2024, the products segment accounted for the largest revenue share. The market is driven by continuous advancements in RNA interference (RNAi), antisense oligonucleotides (ASOs), and CRISPR-Cas technologies. Innovations in delivery systems such as lipid nanoparticles, GalNAc conjugates, and viral vectors have enhanced these therapies' stability, specificity, and efficacy. Furthermore, the increasing demand for targeted treatment options addressing rare genetic disorders, cancer, and neurodegenerative diseases has spurred product development. Companies are actively investing in expanding their product pipelines, with several gene silencing drugs gaining regulatory approvals or advancing through clinical trials, further driving gene silencing industry growth.
Services is expected to register the fastest CAGR during the forecast period. As pharmaceutical and biotech companies focus on developing RNAi, antisense oligonucleotides (ASOs), and CRISPR-based therapies, they increasingly rely on external service providers for assay development, gene sequence validation, vector design, and delivery optimization.
Application Insights
Based on application, the drug discovery & development segment held the largest revenue share of over 55.7% in 2025, and it is expected to grow with the fastest CAGR over the forecast period. Researchers are leveraging RNA interference (RNAi), antisense oligonucleotides (ASOs), and CRISPR-Cas technologies to identify and silence disease-causing genes, accelerating the development of novel therapeutics. In addition, collaborations between biotech firms, academic institutions, and pharmaceutical companies foster innovation in gene silencing-based drug discovery, enabling faster progression from preclinical research to clinical trials and driving gene silencing industry growth.
The therapeutics manufacturing segment is expected to register a significant CAGR during the forecast period. Increasing demand for RNAi, antisense oligonucleotide (ASO), and CRISPR-based therapies has prompted manufacturers to invest in automated systems, single-use bioreactors, and improved purification techniques to enhance production efficiency and product stability. Moreover, partnerships between biotech firms and contract manufacturing organizations (CMOs) are accelerating the large-scale production of gene silencing therapies. Regulatory advancements ensuring quality control and streamlined approval processes further support the expansion of gene silencing therapeutics manufacturing.
End Use Insights
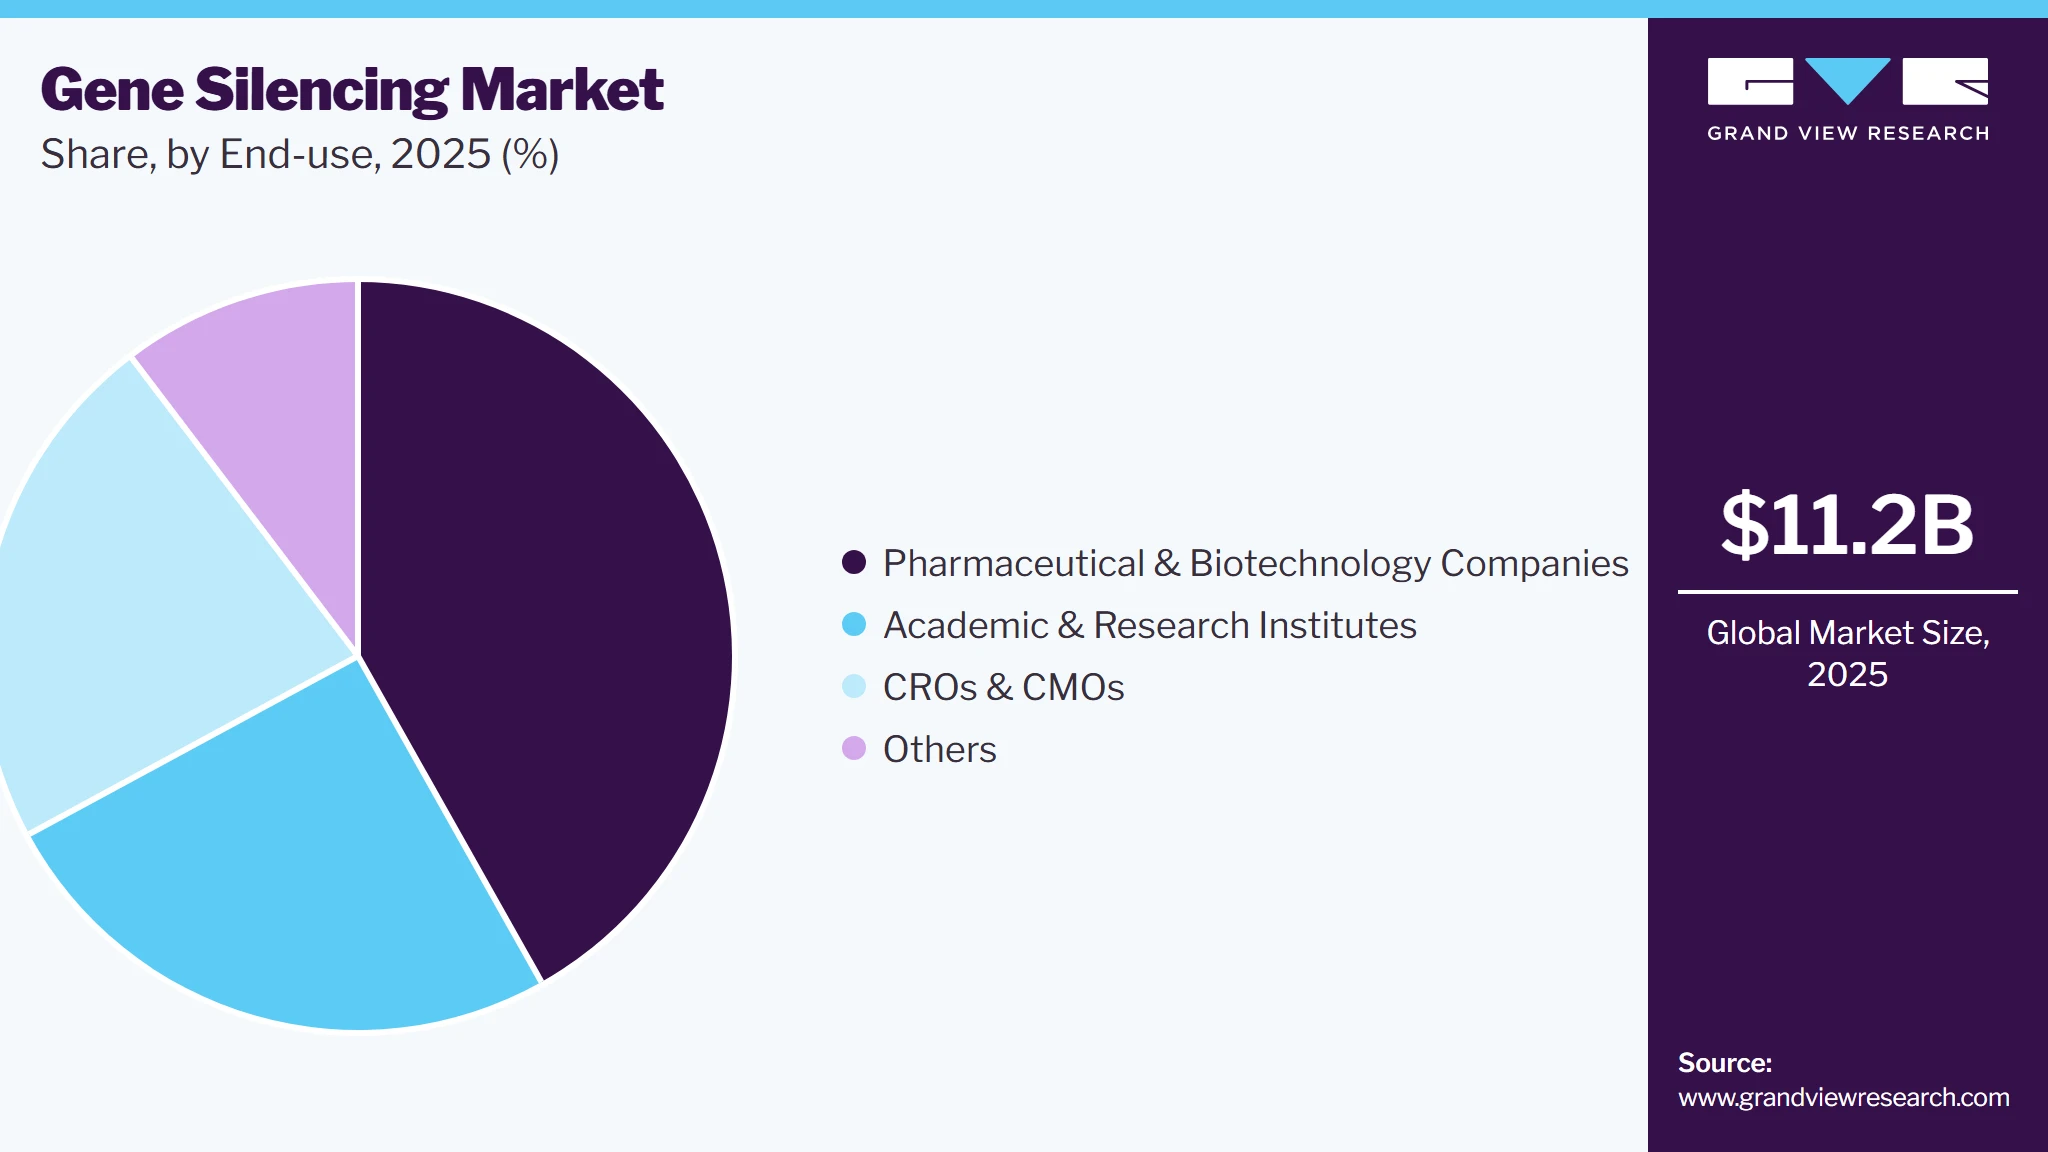
Based on end use, the pharmaceutical & biotechnology companies segment held the largest revenue share of over 41.8% in 2025. Companies are actively expanding their R&D pipelines, leveraging gene silencing to address unmet medical needs. Strategic collaborations, licensing agreements, and acquisitions further accelerate innovation and product development. Furthermore, regulatory incentives such as orphan drug designations and fast-track approvals encourage biotech and pharma firms to pursue gene silencing therapies, driving industry growth.
 To learn more about this report, Download Free Sample Report
CROs & CMOs segment.is expected to register the highest CAGR during the forecast period. The market is driven by the rising demand for specialized expertise and scalable production solutions in gene silencing therapeutics. Pharmaceutical and biotech companies increasingly outsource preclinical research, clinical trials, and manufacturing processes to CROs and CMOs to reduce costs, enhance efficiency, and accelerate time-to-market. CROs provide advanced services such as target validation, assay development, and bioinformatics support, while CMOs invest in cutting-edge bioprocessing technologies to meet the growing demand for RNAi, antisense oligonucleotides (ASOs), and CRISPR-based therapies. This outsourcing trend is boosting growth in the CRO and CMO segments within the market.
Competitive Analysis
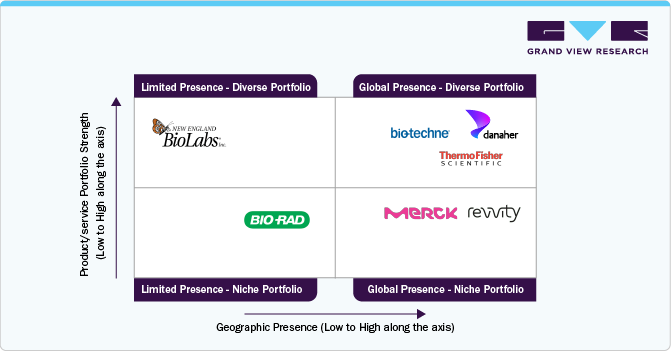 To learn more about this report, Download Free Sample Report
Source: Investor Presentations, Company Websites, Primary Research, Grand View Research
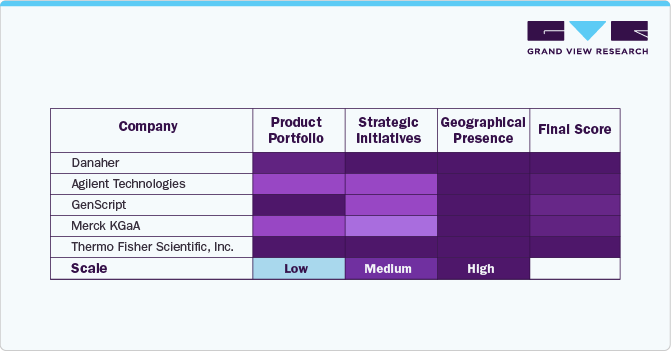 To learn more about this report, Download Free Sample Report
Source: Investor Presentations, Company Websites, Primary Research, Grand View Research
The table evaluates key players in the market based on parameters such as product portfolio, strategic initiatives, and geographic presence. Danaher, Agilent Technologies, GenScript, Merck KGaA, and Thermo Fisher Scientific, Inc. exhibit high scores across all parameters, indicating a strong product portfolio, strategic initiatives, and global presence. These companies are well-positioned in the market due to their broad offerings and international reach. Revvity, Inc. and others show medium rankings in strategic initiatives while maintaining high scores in other areas. This suggests that while they have strong market penetration, they may need to enhance their strategic initiatives to remain competitive. Bio-Techne and Bio-Rad Laboratories have room for growth in expanding collaborations, partnerships, and innovation strategies.
Regional Insights
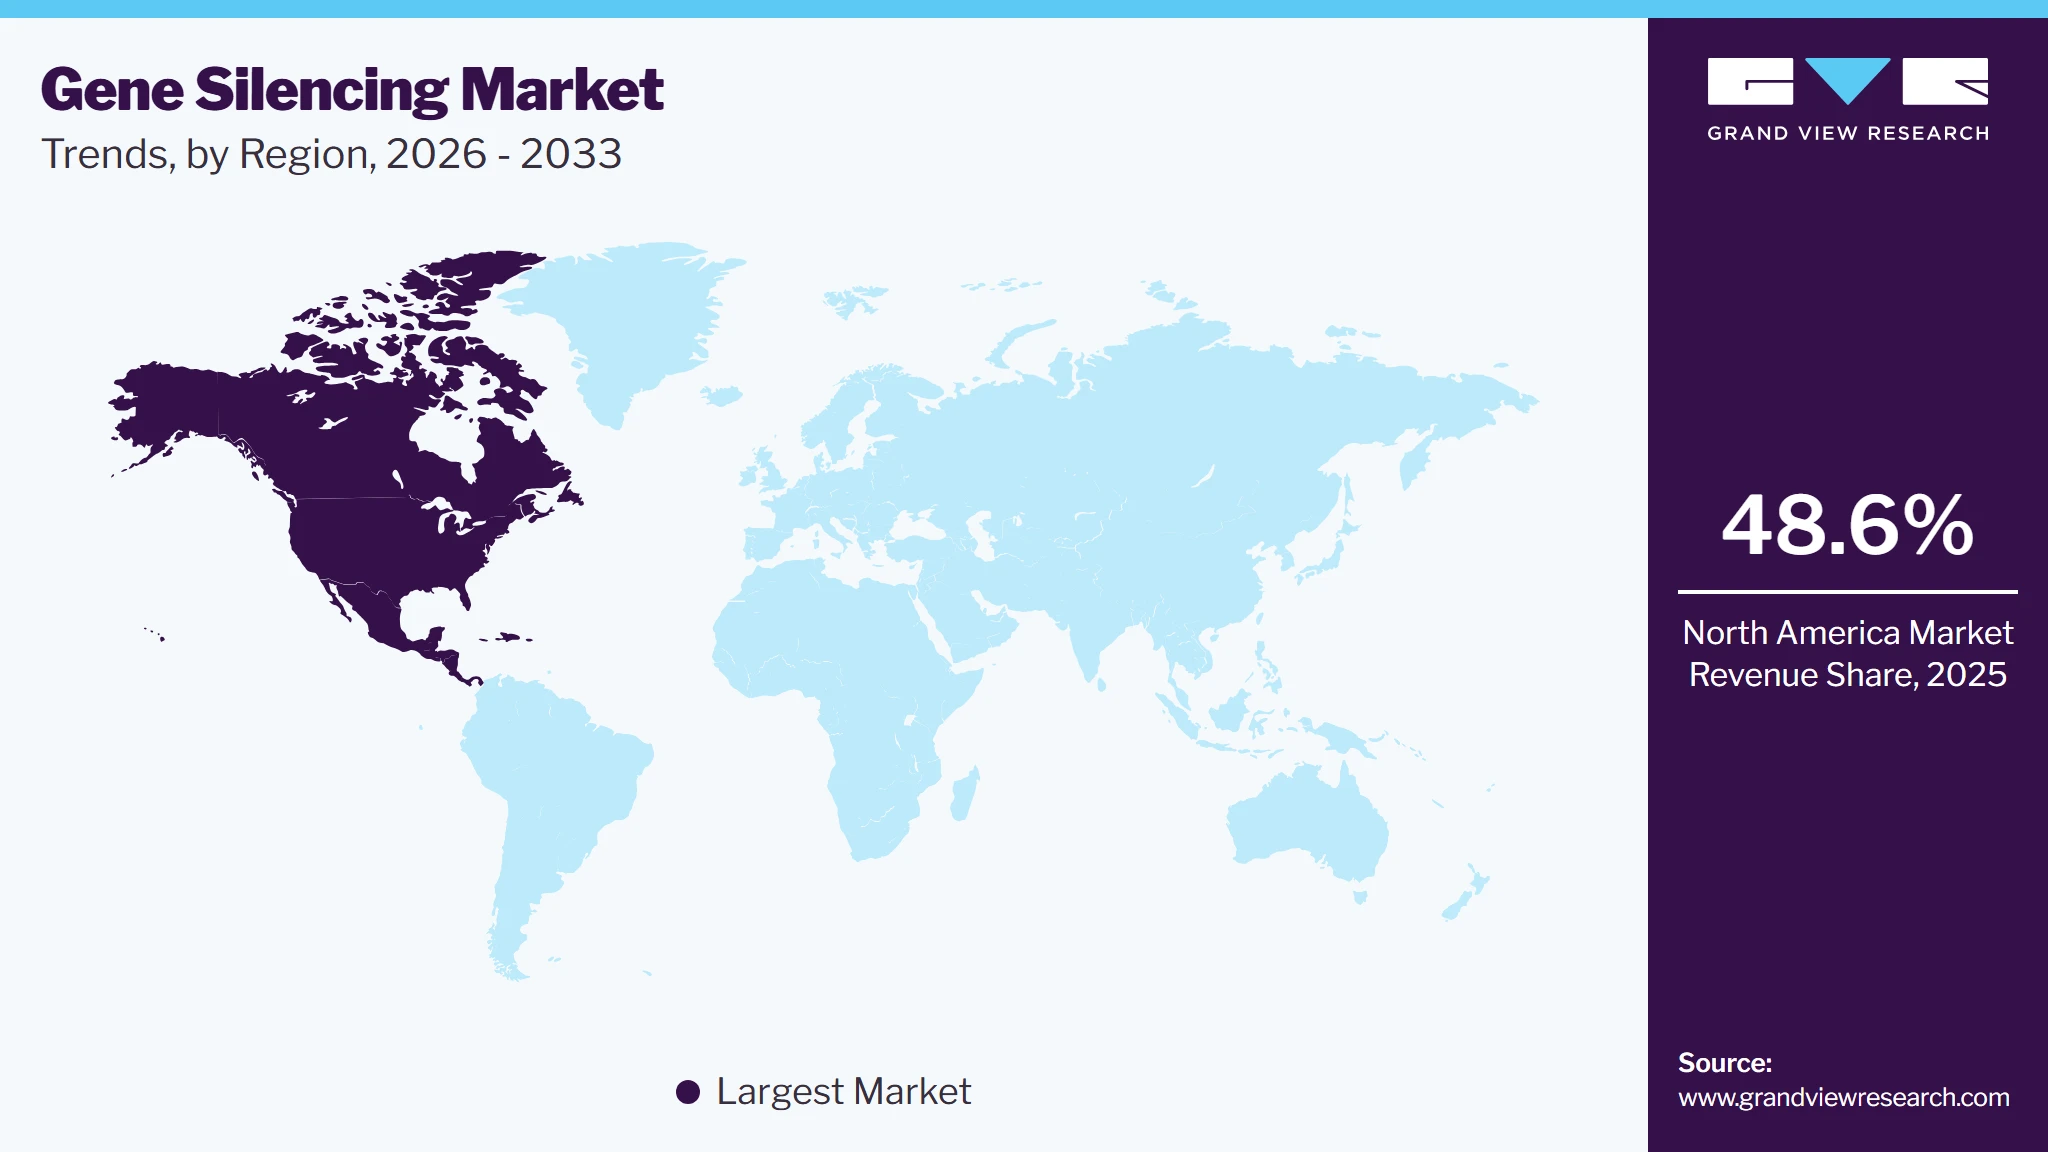
North America dominated the gene silencing market with the largest revenue share of 48.6% in 2025. The North American market size is driven by strong investment in biotechnology, a well-established healthcare infrastructure, and ongoing research in RNA interference (RNAi) and antisense oligonucleotide (ASO) technologies. Leading pharmaceutical firms actively collaborate with research institutions to develop innovative therapies, boosting market growth. Furthermore, a population with high susceptibility to rare diseases, increased market penetration rates, and technologically advanced healthcare infrastructure support regional growth.
 To learn more about this report, Download Free Sample Report
U.S. Gene Silencing Market Trends
The gene silencing market in the U.S. held the largest share in the North America region in 2025. The gene silencing market in the U.S. benefits from extensive government funding for genetic research, coupled with the presence of major biotech players like Alnylam Pharmaceuticals and Ionis Pharmaceuticals. Increasing clinical trials for gene-silencing therapies and FDA approvals for RNA-based drugs further accelerate growth.
Europe Gene Silencing Market Trends
The gene silencing market in Europe is growing due to the rising incidences of genetic disorders. Supportive regulatory frameworks from the European Medicines Agency (EMA) drive demand for gene silencing therapies. Strategic collaborations between biotech firms and academic institutions foster innovation across the region.
The UK gene silencing market is propelled by strong government support for genomic research, advanced healthcare facilities, and initiatives like Genomics England. This fosters the development of gene-silencing therapies targeting rare and complex genetic disorders.
The gene silencing market in Germany is witnessing significant growth due to its robust biotechnology sector. This sector, combined with increased funding for genetic research and partnerships between pharma giants and universities, has accelerated the development of gene silencing technologies. Regulatory support for advanced therapies further strengthens the market.
Asia Pacific Gene Silencing Market Trends
The gene silencing market in Asia Pacific is expanding rapidly due to increasing investments in healthcare innovation, rising awareness of genetic conditions, and growing partnerships between regional biotech firms and global pharmaceutical leaders.
China gene silencing market is driven by government initiatives promoting genetic research, rising healthcare investments, and an expanding biotechnology industry. The country’s emphasis on developing precision medicine further fuels demand.
The gene silencing market in Japan is supported by a strong focus on genetic medicine research, government-backed genomic initiatives, and collaborations between Japanese pharma companies and global biotech firms.
MEA Gene Silencing Market Trends
The gene silencing market in the Middle East is gaining momentum due to increasing investments in healthcare infrastructure and growing awareness of advanced cancer diagnostics. The region’s rising cancer burden and efforts to improve early detection and personalized medicine are moderately driving demand for innovative technologies like CTC analysis. Partnerships between healthcare institutions and global biotech firms are further accelerating the adoption of liquid biopsy solutions.
The gene silencing market in Saudi Arabia isexpected to grow significantly over the forecast period. In Saudi Arabia, the CTC market is supported by the government's healthcare reforms under Vision 2030, which emphasize advanced diagnostic technologies and improved cancer care. Rising investments in precision medicine and initiatives to enhance oncology research capabilities are fostering demand for CTC-based testing for early detection and monitoring of metastatic cancers.
Kuwait gene slicing market is growing due to the rise in the prevalence of cancer, and increasing investments in diagnostic innovations drive the adoption of CTC technologies. The country's healthcare sector is expanding its focus on precision oncology, with medical institutions exploring non-invasive methods like CTC analysis to improve cancer diagnosis, prognosis assessment, and treatment monitoring.
Key Gene Silencing Company Insights
Key players mostly adopted partnerships, acquisitions, and expansion strategies. Companies such as Bio-Techne have acquired smaller companies with advanced technologies to expand their market reach globally.
Key Gene Silencing Companies:
The following key companies have been profiled for this study on the gene silencing market.
- Revvity, Inc.
- Danaher
- Agilent Technologies
- GenScript
- Merck KGaA
- Thermo Fisher Scientific, Inc.
- Illumina
- Bio-Rad Laboratories
- Bio-Techne
- New England Biolabs, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Revvity, Danaher, Merck KGaA, Thermo Fisher Scientific, etc.)
- Focus on expanding gene silencing portfolios through RNAi reagents, CRISPR technologies, nucleic acid synthesis, and integrated genomic workflow solutions.
- Broad product portfolios, strong global distribution networks, and extensive customer bases across pharmaceutical, biotechnology, and academic research sectors.
- Exposure to evolving regulatory requirements and rapid technological advancements may shorten product lifecycles.
Emerging Players (GenScript, Bio-Rad Laboratories, Bio-Techne, New England Biolabs)
- Focus on specialized gene silencing reagents, custom nucleic acid synthesis, and application-specific research tools for functional genomics studies.
- Strong technical expertise in niche molecular biology applications and customized solutions.
- Limited global scale and narrower product portfolios compared to diversified market leaders.
Recent Developments
-
In January 2024, the completion of the gene therapy collaboration between Biogen and Ginkgo Bioworks is anticipated to drive the demand for gene therapies in the future.
-
In December 2023, The Swiss Agency for Therapeutic Products approved Libmeldy to treat early-onset metachromatic leukodystrophy. This regulatory approval highlights gene therapy's increasing recognition and acceptance as a viable treatment for genetic disorders.
-
In May 2023, Novartis acquired a gene therapy candidate from Avrobio, a company experiencing financial difficulties. Novartis provided an exceptional advance payment of $87.5 million for the clinical-phase asset without any conditions for future payments. The agreement included AVR-RD-04, a hematopoietic stem cell gene therapy program currently being investigated for treating the rare genetic disorder cystinosis.
Gene Silencing Market Report Scope
Report Attribute
Details
Market size in 2025
USD 11.2 billion
Estimated market size in 2026
USD 12.6 billion
Projected market size by 2033
USD 28.7 billion
Growth rate
CAGR of 12.5% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product & service, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Norway, Denmark, Sweden, China, Japan, India, South Korea, Australia, Thailand, Brazil, Argentina, Saudi Arabia, South Africa, UAE, Kuwait
Key companies profiled
Revvity, Inc.; Danaher; Agilent Technologies; GenScript; Merck KGaA; Thermo Fisher Scientific, Inc.; Illumina; Bio-Rad Laboratories; Bio-Techne; New England Biolabs, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Gene Slicing Market Report Segmentation
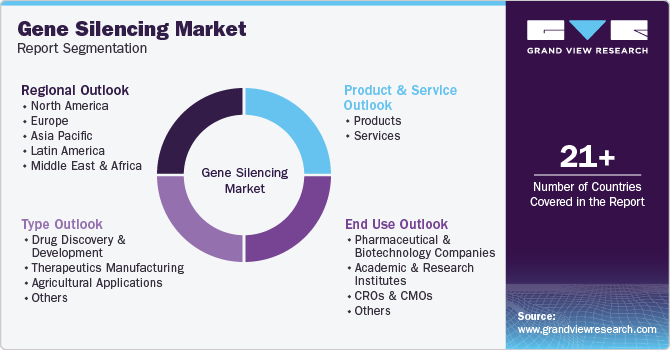
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global gene silencing market report based on product & service, application, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product & Service Outlook (Revenue, USD Billion, 2021 - 2033)
-
Products
-
RNAi
-
miRNA
-
siRNA
-
Others
-
-
CRISPR-Cas9
-
CRISPR Kits & Reagents
-
CRISPR Libraries
-
Others
-
-
Antisense Oligonucleotides
-
Others
-
-
Services
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Drug Discovery & Development
-
Neurology
-
Oncology
-
Infectious Diseases
-
Metabolic Diseases
-
Others
-
-
Therapeutics Manufacturing
-
Agricultural Applications
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Pharmaceutical & Biotechnology Companies
-
Academic & Research Institutes
-
CROs & CMOs
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Sweden
-
Denmark
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
UAE
-
Saudi Arabia
-
Kuwait
-
-
Research Methodology
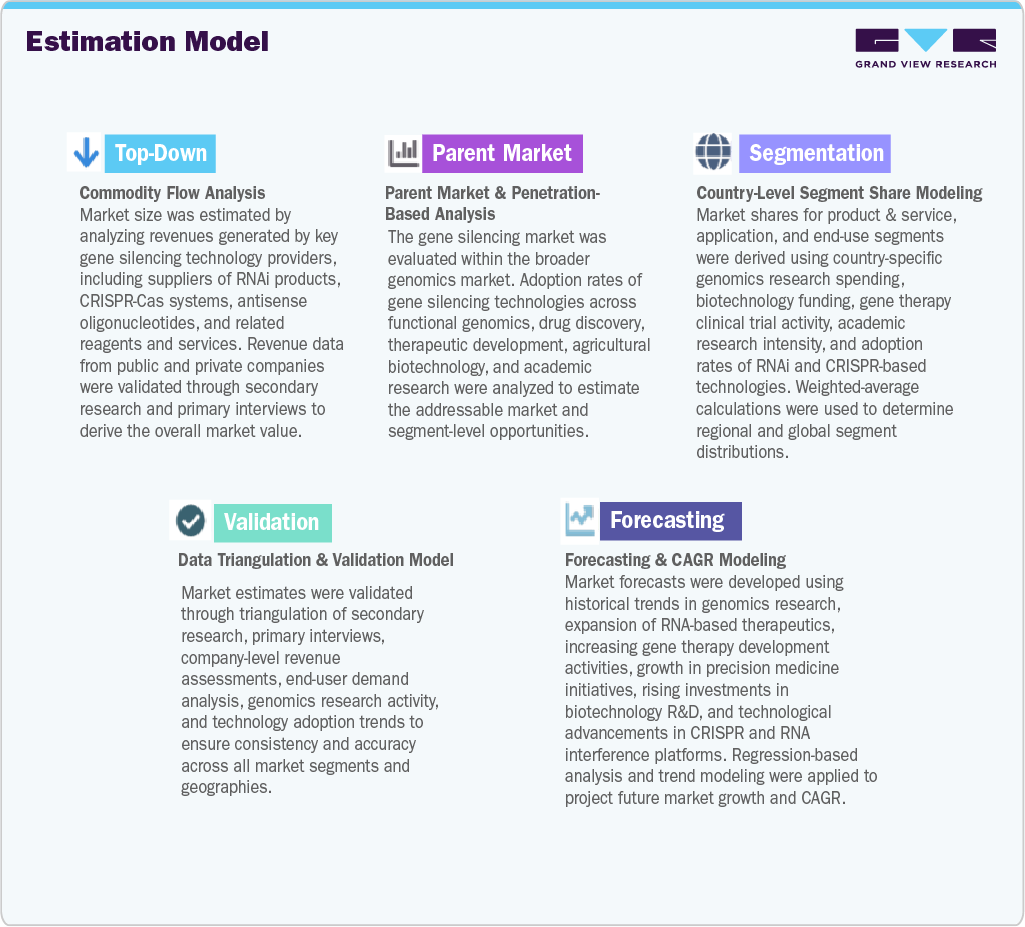
The gene silencing market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each gene silencing segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product & Service
Revenue Capture Definition
Products
Revenue generated from products used to suppress, regulate, or inhibit gene expression at the transcriptional or post-transcriptional level for research, therapeutic, and drug development applications. This segment encompasses RNA interference (RNAi)-based products, including miRNA, siRNA, and other RNA silencing molecules; CRISPR-Cas9 products such as CRISPR kits, reagents, libraries, and related genome-editing tools; antisense oligonucleotides designed to selectively modulate gene expression; and other gene silencing technologies utilized across functional genomics, disease modeling, and therapeutic development workflows.
Services
This segment captures income from outsourced gene silencing services provided to academic institutions, pharmaceutical companies, and biotechnology firms. Service offerings include custom RNAi and CRISPR design, gene knockdown studies, target validation, functional genomics analysis, assay development, screening services, and other contract research activities supporting drug discovery and biomedical research.
Segment - Application
Revenue Capture Definition
Drug Discovery & Development
Revenue originates from the use of gene silencing technologies for target identification, target validation, biomarker discovery, functional genomics, and preclinical drug development. The segment includes applications across multiple therapeutic areas, including neurology, oncology, infectious diseases, metabolic diseases, and other disease indications where modulation of gene expression is used to understand disease mechanisms and identify novel therapeutic targets.
Therapeutics Manufacturing
This segment reflects earnings derived from the use of gene silencing technologies in the development and manufacturing of RNA-based therapeutics, gene therapies, and other advanced therapeutic modalities. These technologies support process optimization, quality assessment, and large-scale production of gene-modulating therapies intended for clinical and commercial use.
Agricultural Applications
Market value in this category stems from the application of gene silencing technologies in crop improvement, pest and disease resistance, trait enhancement, and agricultural biotechnology research. Gene silencing approaches are increasingly employed to develop crops with improved yield, stress tolerance, and nutritional characteristics.
Others
Includes revenue generated from additional applications of gene silencing technologies in areas such as diagnostics, environmental biotechnology, industrial biotechnology, toxicology studies, and other emerging research fields not covered under the primary application categories.
Segment - End Use
Revenue Capture Definition
Pharmaceutical & Biotechnology Companies
Revenue generated from gene silencing products and services utilized by pharmaceutical and biotechnology companies for drug discovery, target validation, therapeutic development, biomarker identification, and clinical research activities.
Academic & Research Institutes
This segment captures income from the adoption of gene silencing technologies by universities, government laboratories, and research organizations conducting basic, translational, and applied research in genomics, molecular biology, and disease biology.
CROs & CMOs
Market revenue arises from the use of gene silencing technologies by contract research organizations (CROs) and contract manufacturing organizations (CMOs) providing outsourced research, assay development, screening, preclinical studies, and manufacturing services to pharmaceutical and biotechnology clients.
Others
Includes revenue derived from hospitals, diagnostic laboratories, agricultural research centers, non-profit organizations, and other institutions employing gene silencing technologies for specialized research and clinical applications.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Gene Silencing Technology Cross-Segmentation Analysis
Detailed cross-segmentation analysis across gene silencing technologies including RNAi (siRNA, miRNA), CRISPR-Cas9, antisense oligonucleotides (ASOs), and services by application areas such as drug discovery & development, therapeutics manufacturing, and agricultural applications. Further assessment by end use across pharmaceutical & biotechnology companies, academic institutes, and CROs/CMOs.
Enables clients to identify high-growth technology-application combinations, evaluate commercialization opportunities across therapeutic areas, prioritize R&D investments, and uncover emerging demand pockets within the gene silencing ecosystem.
Competitive Benchmarking & Pipeline Assessment for Gene Silencing Companies
Comprehensive benchmarking of leading gene silencing companies based on product portfolio, therapeutic pipeline strength, technology platforms, clinical-stage assets, partnerships, licensing agreements, manufacturing capabilities, geographic presence, and strategic initiatives. Analysis also includes evaluation of RNAi, CRISPR, and ASO-based development pipelines.
Helps clients assess competitive positioning, identify partnership or acquisition opportunities, benchmark innovation strategies, and refine market entry and portfolio expansion decisions within the gene silencing space.
Regional Opportunity Assessment for Gene Silencing Therapeutics & Research Tools
Customized regional and country-level assessment covering North America, Europe, Asia Pacific, Latin America, and MEA, with analysis of genomic research funding, regulatory landscape, clinical trial activity, biotechnology infrastructure, adoption of precision medicine, and demand for gene silencing products and services across key countries.
Supports identification of high-growth regional markets, evaluation of country-specific commercialization potential, optimization of expansion strategies, and alignment of investment priorities with evolving regulatory and research ecosystems.
Frequently Asked Questions About This Report
The global gene silencing market size was valued at USD 11.2 billion in 2025 and is estimated at USD 12.6 billion for 2026.
The global gene silencing market is expected to grow at a CAGR of 12.5% from 2026 to 2033, reaching USD 28.7 billion by 2033.
North America dominated the gene silencing market with a share of 48.6% in 2025. This is attributable to rising demand for advanced drug development technologies and increasing opportunities in the RNAi therapy space.
Some key players operating in the gene silencing market include Revvity, Inc., Danaher, Agilent Technologies, GenScript, Merck KGaA, Thermo Fisher Scientific, Inc., Illumina, Bio-Rad Laboratories, Bio-Techne, New England Biolabs, Inc.
Key factors that are driving the market growth include advancements in gene-editing technologies, increased research in targeted therapies, and growing demand for personalized medicine.
The pharmaceutical & biotechnology companies segment held the largest revenue share of over 41.8% in 2025.
The products segment held the largest revenue share of over 71.0% in 2025.
The drug discovery & development segment held the largest revenue share of over 55.7% in 2025, and it is expected to grow with the fastest CAGR over the forecast period.
About the Author(s)
Biotechnology Research Team
Healthcare · BiotechnologyThis report was authored by the biotechnology research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the biotechnology segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


