
- Home
- »
- Healthcare IT
- »
-
Germany Digital Health Market Size And Share Report, 2033GVR Report cover

Germany Digital Health Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (Tele-healthcare, mHealth, Healthcare Analytics, Digital Health Systems), By Component, By Application, By End Use (Patients, Providers, Payers), And Segment Forecasts
Market Size, 2025
$10.1BMarket Estimate, 2026
$11.9BMarket Forecast, 2033
$34.8BCAGR, 2026–2033
16.6%Germany Digital Health Market Summary
The Germany digital healthmarket size was valued at USD 10.1 billion in 2025 and is projected to grow from USD 11.9 billion in 2026 to USD 34.8 billion by 2033, at a CAGR of 16.6% from 2026 to 2033. The market growth is driven by the rising adoption of telemedicine, remote patient monitoring, and electronic health records (EHRs), supported by the increasing burden of chronic disease, an aging population, and healthcare workforce shortages.
Key Market Trends & Insights
- By technology: Tele-healthcare segment held the largest market share of 44.7% in 2025.
- By application: Diabetes segment dominated the market with the largest market share of 29.7% in 2025.
- By end use: Patients’ segment held the largest market share of 33.8% in 2025.
- By component, Software segment held the largest market share of 45.7% in 2025.
Market Size & Forecast
- Market size in 2025: USD 10.1 Billion
- Estimated market size in 2026: USD 11.9 Billion
- Projected market size by 2033: USD 34.8 Billion
- CAGR (2026-2033): 16.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
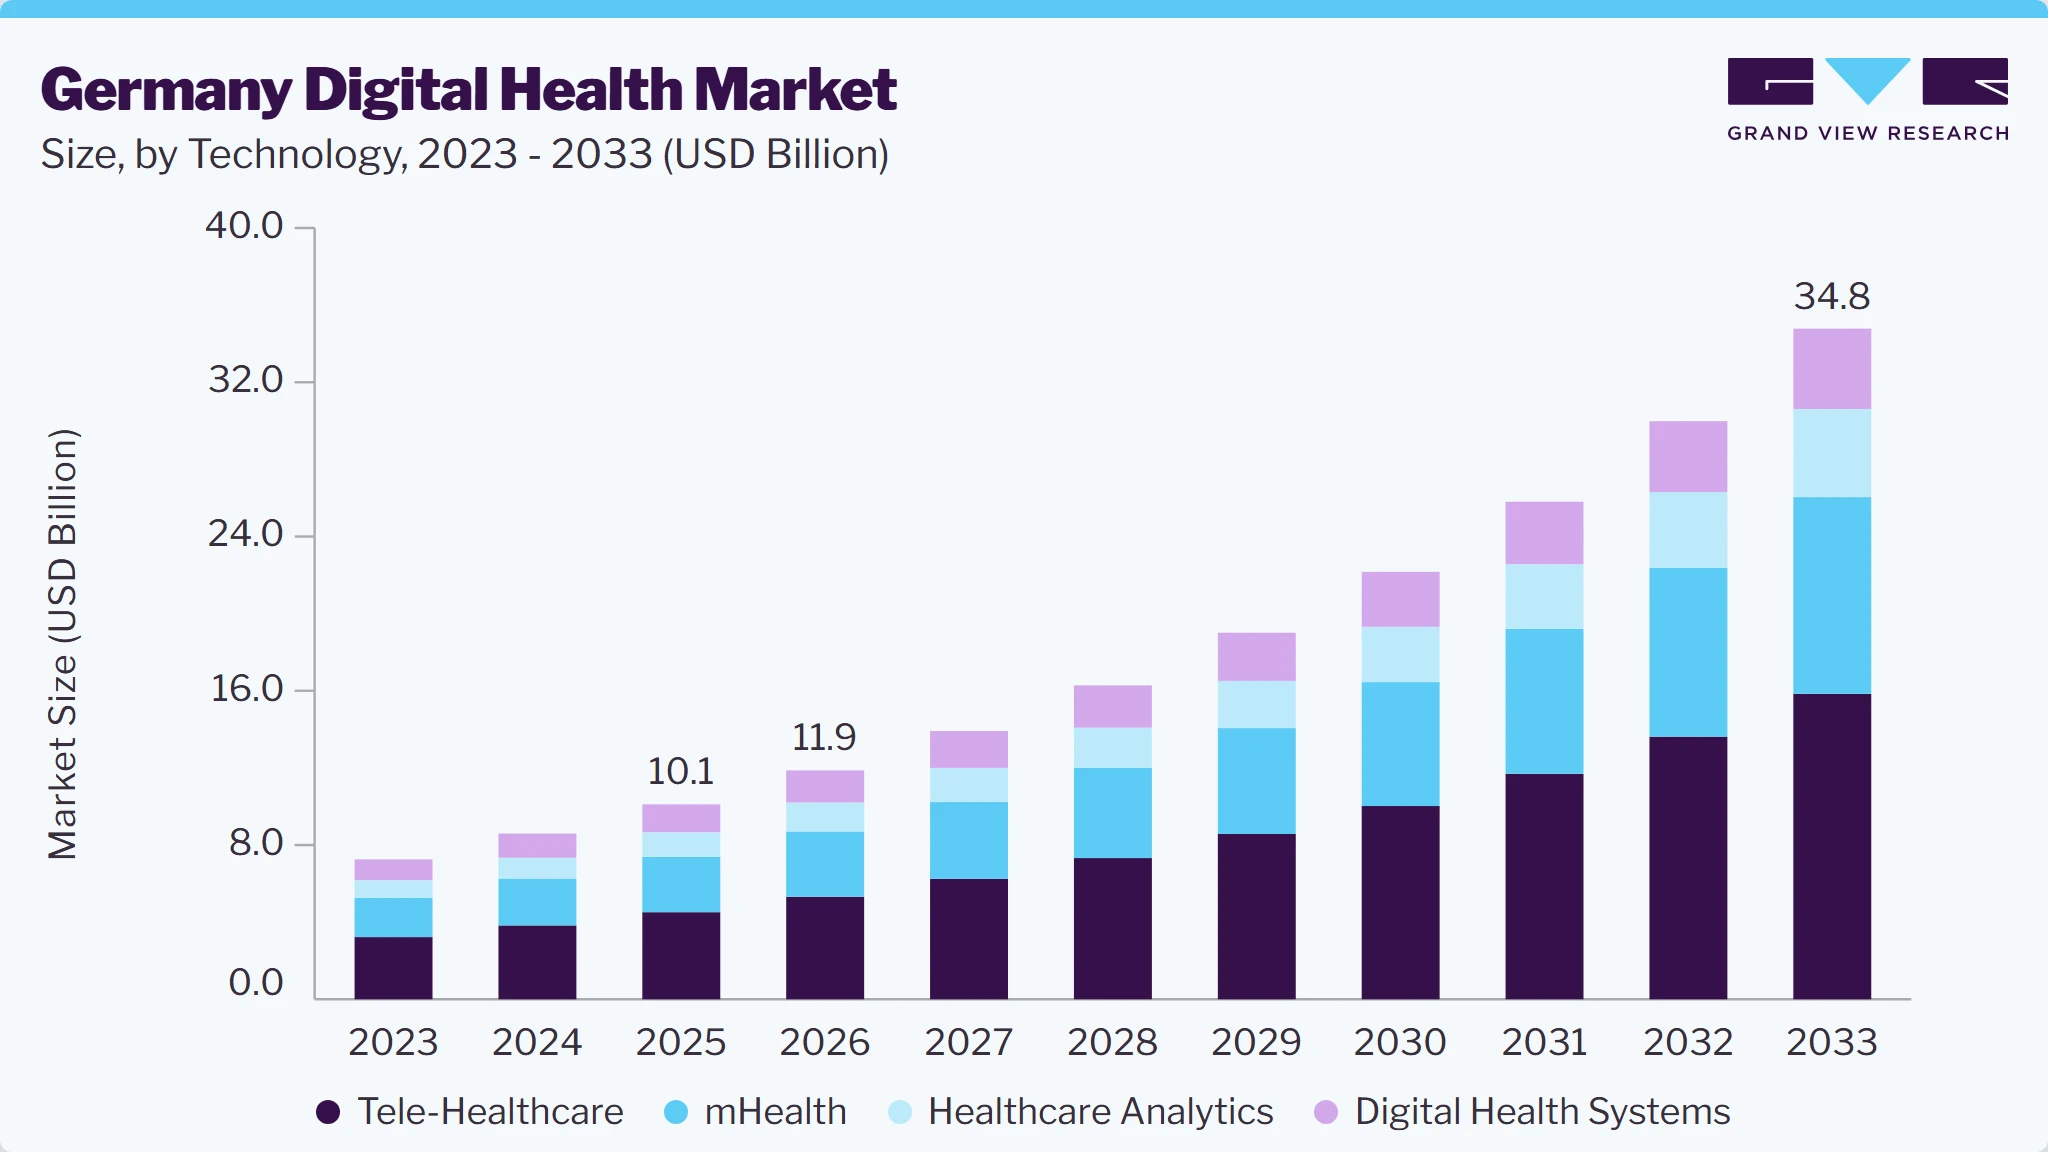 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The increasing adoption of EHR and connected healthcare infrastructure is further supporting market growth. For instance, in April 2025, Versicherungsbüro Weiss reported that Germany initiated the nationwide rollout of electronic patient records (ePA), enabling the secure exchange of patient health information and improving healthcare interoperability.
Market Dynamics
The German digital health industry is experiencing steady growth, driven by the increasing adoption of digital healthcare technologies, rising government initiatives supporting healthcare digitalization, and rising demand for efficient, patient-centric care. The widespread implementation of electronic health records (EHRs), ePrescriptions, telemedicine, digital therapeutics, and remote patient monitoring enhances healthcare accessibility, operational efficiency, and clinical outcomes. Furthermore, advancements in artificial intelligence (AI), cloud-based healthcare platforms, wearable technologies, and health data analytics are enabling personalized care, improving clinical decision-making, and strengthening care coordination. However, concerns related to data privacy and cybersecurity, interoperability limitations across healthcare systems, and the high costs associated with digital infrastructure implementation continue to pose challenges to market growth. Despite these constraints, ongoing technological innovation, supportive regulatory initiatives, and increasing investments in digital health are strengthening competition and accelerating the adoption of secure, integrated, and value-based healthcare solutions across Germany.
The DiGA (digital health applications) reimbursement program is a major driver of Germany’s digital health industry. Under this program, physicians can prescribe approved digital health apps, and statutory health insurance (GKV) reimburses their cost. This mechanism directly incentivizes patient adoption of digital therapies and provides a clear regulatory pathway for developers, encouraging the creation of clinically validated apps for conditions such as diabetes, mental health disorders, and cardiovascular diseases.
Since its launch, the program has led to measurable uptake of digital therapies, with prescription-based DiGAs increasingly integrated into routine care. By linking reimbursement to clinical evidence, DiGA ensures quality and efficacy, while simultaneously expanding access to innovative digital solutions across urban and rural populations. This structured integration into Germany’s healthcare system strengthens the digital health ecosystem and positions the country as a global leader in reimbursed digital health innovation. In April 2025, the National Association of Statutory Health Insurance Funds (GKV-Spitzenverband) released a report on DiGA usage in Germany covering September 2020 to December 2024, reporting a total of 861,000 uses. The report found that out of 68 listed DiGAs, only 12 showed confirmed benefits at the time of inclusion, while nine were subsequently removed for failing to demonstrate a positive healthcare impact.
Strict data protection regulations under the European Union’s General Data Protection Regulation (GDPR) and Germany’s Federal Data Protection Act (BDSG) act as a key restraint on the market. These regulations impose stringent requirements for the collection, processing, storage, and sharing of sensitive patient health data, requiring healthcare providers and digital health companies to implement robust cybersecurity, consent management, and compliance frameworks. In addition, the European Health Data Space (EHDS) Regulation, adopted by the European Union in 2025, introduces new governance and interoperability requirements for electronic health data, further increasing compliance obligations for healthcare organizations. While these regulations strengthen patient privacy and data security, they also increase implementation costs, lengthen deployment timelines, and can slow the adoption of cloud-based healthcare platforms, AI-enabled applications, and cross-border digital health solutions.The expansion of artificial intelligence (AI)-enabled healthcare solutions presents a significant opportunity for the Germany digital health industry. AI technologies are increasingly integrated into medical imaging, clinical decision support, workflow automation, and hospital operations to improve diagnostic accuracy, optimize clinical workflows, and enhance patient care. Growing investments in healthcare digitalization and the rising demand for efficient healthcare delivery are expected to accelerate the adoption of AI-powered digital health solutions across Germany.
For instance, in November 2025, Siemens Healthineers launched new AI-enabled radiology services and AI-powered simulation solutions designed to streamline imaging workflows, automate clinical tasks, and improve hospital operational efficiency. These solutions help healthcare providers enhance productivity, reduce reporting time, and optimize resource utilization. Such innovations are accelerating AI adoption across Germany's healthcare sector, creating new growth opportunities for digital health solution providers and supporting the long-term expansion of the Germany digital health industry.
Market Concentration & Characteristics
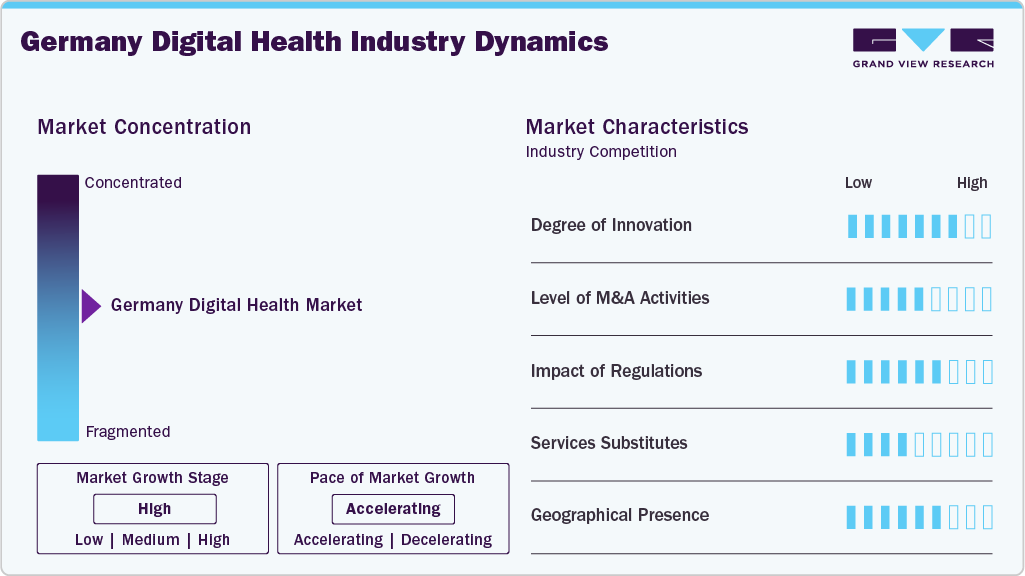
Germany’s digital health industry demonstrates a high degree of innovation, driven by continuous advancements in artificial intelligence, digital therapeutics, telemedicine, electronic health records, and connected healthcare platforms. Companies are increasingly launching AI-enabled applications and digital treatment solutions to enhance patient outcomes, clinical efficiency, and personalized care. For instance, in November 2024, HelloBetter, a German digital therapeutics company, secured EUR 3 million to advance MindFIT, an AI-powered mental health solution that delivers personalized treatment and improves patient engagement. These developments strengthen Germany’s digital health ecosystem, accelerate AI adoption, and support long-term market growth.
 To learn more about this report, Download Free Sample Report
The German digital health industry is experiencing a moderate level of mergers and acquisitions as companies aim to strengthen digital healthcare capabilities, expand software portfolios, and improve integrated care solutions. These acquisitions focus on enhancing healthcare IT infrastructure, digital patient engagement, and clinical workflow management to meet the rising demand for connected healthcare services. For instance, in June 2024, CompuGroup Medical SE & Co. KGaA acquired AmbulApps GmbH, a German provider of digital patient intake and clinical documentation solutions. This acquisition expanded CompuGroup Medical's digital health portfolio and improved its ability to deliver integrated healthcare software, supporting innovation and growth in Germany's digital health sector.
The Germany digital health industry is significantly influenced by supportive regulatory initiatives that promote the adoption of digital healthcare while ensuring data security, interoperability, and patient privacy. Government policies such as the Digital Act (DigiG) and the nationwide implementation of the electronic patient record (ePA) are accelerating healthcare digitalization and encouraging healthcare providers to adopt interoperable digital health solutions. For instance, in January 2025, Germany introduced the opt-out electronic patient record (ePA) model, under which electronic patient records are automatically created for individuals covered by statutory health insurance unless they actively opt out. This regulatory reform is expected to significantly increase the adoption of electronic health records, improve information sharing among healthcare providers, and strengthen the long-term growth of the market.
The threat of service substitutes in the German digital health industry remains moderate, as traditional in-person consultations and paper-based processes still coexist with digital services. However, the growing use of telemedicine, digital patient management, secure clinical communication, and electronic health records is steadily reducing reliance on conventional models. For instance, in February 2024, Doctolib fully integrated Siilo Messenger into its software as Doctolib Siilo, allowing healthcare professionals to securely communicate, share patient information, and coordinate care on a single digital platform. This integration improves care coordination, decreases dependence on traditional communication, and supports Germany’s ongoing shift toward digital healthcare.
The German digital health industry has a moderate to high geographic presence, supported by nationwide healthcare digitalization initiatives and broad adoption of digital health solutions in hospitals, clinics, pharmacies, and home care. Well-established healthcare IT providers, robust digital infrastructure, and strong public-private collaboration have accelerated the nationwide rollout of interoperable digital health services. For instance, in July 2024, gesund.de expanded its CardLink solution nationwide, allowing patients to redeem electronic prescriptions through its mobile app at participating pharmacies. This service has improved access to prescription medications, enhanced patient-pharmacy connectivity, and further advanced digital healthcare adoption across Germany.
Analyst Perspective
The Germany digital health industry is experiencing significant growth, driven by the increasing adoption of digital healthcare technologies, supportive government initiatives, and rising demand for efficient, patient-centric healthcare delivery. The widespread implementation of electronic patient records (ePA), ePrescriptions (eRezept), telemedicine platforms, and reimbursable Digital Health Applications (DiGA) is accelerating the digital transformation of the country's healthcare ecosystem. Technological advancements in artificial intelligence (AI), cloud computing, remote patient monitoring, healthcare analytics, and connected medical devices are enhancing clinical decision-making, streamlining healthcare workflows, and improving patient outcomes.
Technology Insights
The tele-healthcare segment dominated the Germany market with a 44.7% revenue share in 2025. The segment's dominance is driven by the increasing adoption of virtual consultations, remote patient monitoring, and digital care platforms, which enhance healthcare accessibility and ease pressure on hospitals and physician practices. Rising government support for telemedicine, expanding digital healthcare infrastructure, and growing patient preference for convenient, connected care continue to drive the adoption of tele-healthcare solutions. For instance, in November 2025, Doctolib introduced an AI-enabled practice management platform in Germany that combines appointment scheduling, clinical documentation, billing, and three AI assistants to automate administrative tasks. This platform is expected to save medical practices up to 10 hours per week, increasing workflow efficiency and supporting broader digital healthcare adoption.
The healthcare analytics segment is expected to register the fastest CAGR during the forecast period. The growth is driven by the increasing use of artificial intelligence, predictive analytics, and cloud-based platforms to support clinical decision-making, population health management, and operational efficiency. Growing volumes of electronic health data, the rising demand for data-driven healthcare and precision medicine are expected to accelerate the adoption of healthcare analytics solutions, supporting the long-term growth of the market.
Application Insights
The diabetes segment dominated the Germany market with a 29.7% revenue share in 2025 and is expected to register the fastest CAGR over the forecast period. The segment's growth is driven by the increasing prevalence of diabetes, rising adoption of continuous glucose monitoring (CGM), connected insulin delivery systems, and mobile health applications for disease management.
Growing government support for digital healthcare and increasing use of remote patient monitoring and AI-enabled diabetes management platforms, is further accelerating the adoption of digital solutions. For instance, in January 2024, Abbott expanded the digital capabilities of its FreeStyle Libre ecosystem by integrating the FreeStyle Libre 3 sensor with CamDiab's CamAPS FX automated insulin delivery application in Germany. The integration enables real-time glucose monitoring and automated insulin dosing, improving diabetes management and supporting the adoption of connected digital health solutions. Such advancements are enhancing personalized diabetes care, improving patient outcomes, and driving the continued growth of the diabetes segment in Germany's digital health industry.
The cardiovascular segment is expected to witness significant CAGR over the forecast period, driven by the increasing prevalence of cardiovascular diseases (CVDs), rapid advancements in healthcare technologies, rising healthcare expenditure, and growing demand for remote patient monitoring solutions. Furthermore, the expansion of healthcare IT infrastructure, improved internet connectivity, and increasing accessibility to virtual care platforms are accelerating the adoption of digital health technologies for cardiovascular disease prevention, diagnosis, treatment, and long-term disease management. The integration of connected medical devices, wearable technologies, artificial intelligence (AI), and data analytics is further enhancing clinical outcomes and supporting the continued growth of this segment.
End Use Insights
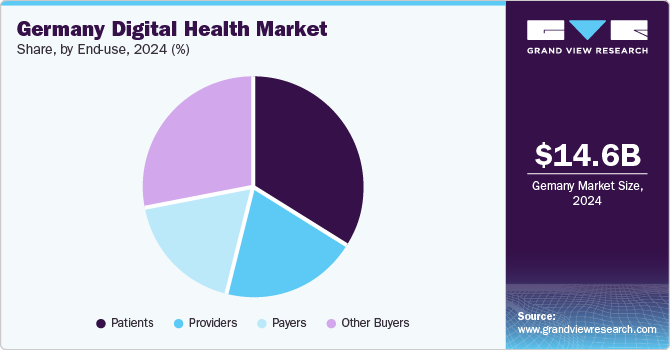
The patients’ segment dominated the market with a 33.8% revenue share in 2025 and is expected to register the fastest CAGR over the forecast period. The segment's growth is driven by increasing adoption of telemedicine, mobile health applications, remote patient monitoring, and digital therapeutics for chronic disease management. Growing patient awareness, wider availability of electronic patient records (ePA), and expanding access to digital healthcare services are further supporting market growth. For instance, in June 2024, DAK-Gesundheit launched a new digital care application developed with Germany-based Nui Care to support the country's approximately 4.8 million informal caregivers. The app provides personalized care guidance, digital checklists, benefit calculators, and application support, improving access to healthcare information and empowering patients and caregivers through a digital platform. Such patient-centric digital solutions are expected to accelerate the adoption of digital healthcare services and support the continued growth of the patient segment in Germany.
The provider segment accounted for the second-largest revenue share, driven by the increasing adoption of advanced digital health technologies, including digital therapeutics, telemedicine, and remote patient management solutions. Healthcare providers are increasingly leveraging these technologies to deliver evidence-based therapies, personalized treatment plans, and virtual consultations beyond traditional care settings. The integration of digital health platforms into clinical workflows enhances care coordination, improves patient engagement, and enables continuous monitoring, resulting in better clinical outcomes and greater healthcare accessibility. Furthermore, ongoing investments in healthcare IT infrastructure and the growing emphasis on value-based care are expected to further support the growth of the provider segment over the forecast period.
Component Insights
The software segment dominated the Germany market with a revenue share of 45.7% in 2025 and is expected to register the fastest CAGR over the forecast period. The segment's growth is driven by the increasing adoption of electronic health records (EHRs), telemedicine platforms, AI-enabled clinical decision support systems, digital therapeutics, and practice management software across healthcare settings. Growing government initiatives promoting healthcare digitalization, rising implementation of interoperable healthcare IT systems, and increasing demand for workflow automation are further accelerating software adoption. For instance, in September 2024, jameda launched its AI Assistant for healthcare providers in Germany following successful testing in more than 100 medical practices and over 2,000 patient consultations. The AI-powered solution automates clinical documentation and reduces physicians' administrative workload by saving up to 11 minutes per consultation. Such innovations are enhancing healthcare efficiency, encouraging the adoption of advanced healthcare software solutions, and supporting the long-term growth of the software segment in Germany's digital health industry.
 To learn more about this report, Download Free Sample Report
The services segment held a significant market share in 2025, owing to the rising demand for tele-healthcare component maintenance, staffing, training, resource allocation, and optimization services. It is projected that the market players can concentrate more on offering these services to maintain their dominant positions, which can fuel the segment growth. The market share of this category is also anticipated to grow as electronic health platforms develop and customer expectations for improved services rise. The major players' extensive range of pre-and post-installation services is expected to contribute to the segment growth.
Key Germany Digital Health Company Insights
Market participants are actively focusing on strategic initiatives such as product innovation, partnerships, mergers and acquisitions, collaborations with healthcare providers, and the expansion of digital health portfolios to strengthen their market position in Germany. Companies are also investing in artificial intelligence (AI), cloud-based healthcare platforms, telemedicine, remote patient monitoring, and interoperable digital health solutions to address the growing demand for digital healthcare services. These strategic initiatives are expected to intensify market competition and create significant growth opportunities over the forecast period.
Key Germany Digital Health Companies:
-
Cerner Corporation
-
GE Healthcare
-
Abbott
-
Olympus Corporation
-
Resideo Technologies
-
Cisco
-
Telefonica SA.
-
Softserve
-
Computer Programs and Systems, Inc.
-
Vocera Communications
-
CISCO Systems, Inc.
-
Apple Inc.
-
McKesson Corporation
-
Epic Systems Corporation
-
Vodafone Group
-
Airstrip Technologies
-
Google, Inc.
-
Samsung Electronics Co. Ltd.
-
Orange
-
Qualcomm Technologies, Inc.
-
CompuGroup Medical
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., CompuGroup Medical SE & Co. KGaA, GE HealthCare, Oracle Health (Cerner), Epic Systems Corporation)
- Focus on expanding integrated digital healthcare ecosystems through electronic health records (EHRs), telehealth platforms, AI-enabled clinical decision support, cloud-based healthcare solutions, connected medical devices, and strategic partnerships with hospitals and government healthcare programs. Companies also invest in interoperability, cybersecurity, and artificial intelligence to strengthen digital healthcare infrastructure across Germany.
- Broad digital health portfolios, established relationships with healthcare providers, strong financial resources, advanced AI and cloud capabilities, extensive implementation experience, and robust research and development enable these companies to maintain a strong competitive position in Germany’s digital health market.
- High implementation and maintenance costs, lengthy procurement cycles, integration challenges with legacy healthcare systems, and strict compliance with Germany’s data privacy and interoperability regulations can slow market expansion and product deployment.
Emerging & Specialized Players (e.g., SoftServe, Resideo Technologies, Vocera Communications)
- Focus on developing specialized digital health solutions such as remote patient monitoring, AI-powered healthcare applications, digital communication platforms, connected care solutions, IoT-enabled healthcare devices, and virtual care technologies. These companies primarily compete through technological innovation, strategic collaborations, and customized solutions targeting specific healthcare needs.
- Strong expertise in niche digital health technologies, faster product development cycles, flexible deployment models, and innovative AI- and IoT-based solutions enable these companies to respond quickly to evolving healthcare demands and digital transformation initiatives.
- Limited healthcare software portfolios, lower brand recognition among hospitals, smaller customer bases, and comparatively fewer financial resources may restrict nationwide expansion and competition with established healthcare IT providers.
Recent Developments
- In April 2025, the German Federal Ministry of Health launched the nationwide rollout of the electronic patient record (ePA) for all statutory health insurance members following successful pilot testing. The initiative enables patients and healthcare providers to securely access and exchange medical records, prescriptions, laboratory reports, and treatment information through a standardized digital platform. The rollout is expected to strengthen interoperability and accelerate digital healthcare adoption across Germany.
"The electronic patient record (ePA) for all is a central building block for the digitalization of healthcare and will improve medical care through better availability of health information."
- German Federal Ministry of Health (BMG)- In November 2025, Doctolib launched an AI-powered practice management software in Germany, integrating appointment scheduling, patient management, billing, and AI-assisted clinical documentation into a single platform. The solution is designed to reduce administrative burden, save physicians up to 10 hours per week, and improve operational efficiency in medical practices, supporting the digital transformation of outpatient healthcare.
"The AI assistants automate repetitive administrative tasks, allowing healthcare professionals to spend more time caring for patients."
- Doctolib- In November 2025, Siemens Healthineers introduced new AI-enabled Radiology Services and AI-powered simulation solutions to help healthcare providers automate imaging workflows, optimize operational planning, and improve diagnostic efficiency. The launch expands the company's digital imaging portfolio and reinforces its leadership in AI-driven healthcare innovation.
"Our AI-enabled radiology services help healthcare providers improve efficiency while supporting high-quality patient care."
- Siemens Healthineers- In September 2025, Smartpatient and Novo Nordisk launched a digital support program for obesity care in Germany, integrating treatment support, lifestyle coaching, and personalized education. The platform uses gamification and privacy-preserving analytics to improve patient adherence and health outcomes.
Germany Digital Health Market Report Scope
Report Attribute
Details
Market size in 2025
USD 10.1 billion
Estimated market size in 2026
USD 11.9 billion
Projected market size by 2033
USD 34.8 billion
Growth rate
CAGR of 16.6% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Technology, component, application, end use
Key companies profiled
Cerner Corporation; GE HealthCare; Abbott; Olympus Corporation; Resideo Technologies; Cisco Systems, Inc.; Telefónica S.A.; SoftServe; Computer Programs and Systems, Inc. (CPSI); Vocera Communications; Apple Inc.; McKesson Corporation; Epic Systems Corporation; Vodafone Group Plc; AirStrip Technologies; Google LLC; Samsung Electronics Co., Ltd.; Orange S.A.; Qualcomm Technologies, Inc.; CompuGroup Medical SE & Co. KGaA.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Germany Digital Health Market Report Segmentation
This report forecasts revenue growth at country levels, and provides an analysis of the industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the Germany digital health market on the basis of technology, component, application, and end use.
-
Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
Tele-Healthcare
-
Tele-care
-
Activity Monitoring
-
Remote Medication Management
-
-
Tele-health
-
LTC Monitoring
-
Video Consultation
-
-
-
mHealth
-
Wearables & Connected Medical Devices
-
Vital Sign Monitoring Devices
-
Heart Rate Monitors
-
Activity Monitors
-
Electrocardiographs
-
Pulse Oximeters
-
Spirometers
-
Blood Pressure Monitors
-
Others
-
-
Sleep Monitoring Devices
-
Electrocardiographs Fetal and Obstetric Devices
-
Neuromonitoring Devices
-
Electroencephalographs
-
Electromyographs
-
Others
-
-
-
mHealth Apps
-
Medical Apps
-
Women Apps
-
Fitness and Nutrition
-
Menstrual Health
-
Pregnancy Tracking & Postpartum Care
-
Menopause
-
Disease Management
-
Others
-
-
Chronic Disease Management Apps
-
Diabetes Management Apps
-
Blood Pressure and ECG Monitoring Apps
-
Mental Health Management Apps
-
Cancer Management Apps
-
Obesity Management Apps
-
Other Chronic Disease Management Apps
-
-
Personal Health Record Apps
-
Medication Management Apps
-
Diagnostic Apps
-
Remote Monitoring Apps
-
Others
-
-
Fitness Apps
-
-
mHealth Services
-
Monitoring ServicesDiagnosis Services
- Independent Aging Solutions
- Chronic Disease Management & Post-Acute Care Services
-
Healthcare System Strengthening Services
-
Others
-
-
-
Digital Health Systems
-
Electronic Health Records (EHR)
-
E-prescribing Systems
-
Healthcare Analytics
-
-
-
Component Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hardware
-
Software
-
Services
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Obesity
-
Diabetes
-
Cardiovascular
-
Respiratory Diseases
-
Others (Medication Adherence, Fitness and Wellness, Post-operative Care, Smoking Cessation, CNS Disease, Pregnancy and Parenting Management, and Personal Goal and Habit Platforms)
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Patients
-
Providers
-
Payers
-
Other Buyers (Wellness Centers, Fitness Centers, and Gyms)
-
Research Methodology
The Germany digital health market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing—reconciling supply-side and demand-side estimates—and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Germany digital health segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Technology
Revenue capture definition
Tele-Healthcare
Includes digital platforms that enable remote healthcare delivery through video consultations, virtual follow-ups, telemonitoring, and online clinical support. Revenue is generated from teleconsultation software, virtual care platforms, remote monitoring services, and subscription-based digital healthcare solutions used by hospitals, physician practices, and patients across Germany.
mHealth
Covers mobile-based healthcare applications and connected digital tools that support disease management, wellness, medication adherence, and patient engagement. The segment generates revenue through smartphone applications, wearable device connectivity, digital coaching platforms, and mobile health subscriptions adopted by German consumers and healthcare providers.
Healthcare Analytics
Comprises software solutions that analyze healthcare data to improve clinical outcomes, operational efficiency, and population health management. Revenue is derived from AI-powered analytics platforms, predictive analytics, clinical decision support systems, and healthcare data management solutions implemented by hospitals, insurers, and research organizations in Germany.
Digital Health Systems
Includes integrated healthcare IT infrastructure such as electronic patient records (ePA), hospital information systems, ePrescription platforms, and practice management software. Revenue is generated through software licensing, cloud deployment, system integration, and maintenance services supporting Germany’s digital healthcare ecosystem.
Segment - Component
Revenue capture definition
Hardware
Physical devices used for digital health monitoring and care, including wearables, remote monitoring sensors, smart medical devices, and connected diagnostic tools.
Software
Applications and platforms that collect, process, and analyze health data from patients or devices, enabling tracking, alerts, and insights for both patients and healthcare providers.
Services
Digital health services supporting care delivery and management, including telemedicine consultations, remote patient monitoring, chronic disease management programs, and digital health coaching.
Segment - Application
Revenue capture definition
Obesity
Includes digital health solutions designed to support weight management through nutrition guidance, physical activity tracking, behavioral coaching, and remote lifestyle monitoring. Revenue is generated from mobile applications, connected devices, and digital wellness platforms used by individuals and healthcare providers.
Diabetes
Includes technologies and services for diabetes management, such as continuous glucose monitors, insulin tracking apps, telemedicine consultations, and digital platforms for monitoring and managing blood sugar levels.
Cardiovascular
Includes digital solutions for monitoring and managing cardiovascular conditions through connected ECG devices, blood pressure monitoring, cardiac rehabilitation platforms, and remote patient management systems. Revenue is generated from digital cardiac monitoring technologies and associated healthcare software.
Respiratory Diseases
Covers digital platforms and connected devices used to manage asthma, COPD, sleep apnea, and other respiratory disorders through remote monitoring and treatment adherence. Revenue is generated from smart inhalers, respiratory monitoring devices, telehealth services, and disease management applications.
Others
Includes digital health applications supporting medication adherence, mental wellness, smoking cessation, pregnancy care, post-operative recovery, neurological disorders, fitness, and preventive healthcare. Revenue is generated from disease-specific digital applications, wellness platforms, and personalized health management solutions.
Segment - End use
Revenue capture definition
Patients
Individual users of digital health solutions, including mobile health apps, wearable devices, remote monitoring tools, and telehealth services, aimed at self-care, disease management, fitness tracking, and preventive health.
Providers
Hospitals, clinics, physician practices, and other healthcare facilities adopting digital health technologies for patient management, clinical decision support, telemedicine, EHR systems, and workflow optimization.
Payers
Health insurance companies, government programs, and third-party administrators that fund or reimburse digital health services and solutions, including telehealth consultations, remote monitoring, and chronic disease management tools.
Other Buyers
Organizations outside traditional patient, provider, or payer categories, such as employers, corporate wellness programs, pharmacies, and digital health platforms purchasing solutions for population health management, employee health monitoring, or service integration.
Estimation Model
Methodology
Approach
Top-Down
Healthcare Digitalization-Based Market Estimation: The Germany digital health market was estimated using a top-down approach by evaluating the country's overall healthcare expenditure, healthcare IT investments, and digital transformation initiatives. Market size was derived by assessing the penetration of digital health technologies, including telehealth, mHealth, digital therapeutics (DiGA), healthcare analytics, electronic patient records (ePA), ePrescriptions (eRezept), remote patient monitoring, and connected healthcare solutions across healthcare settings.
Parent Market
Healthcare IT & Digital Transformation Assessment: The market was benchmarked against Germany's broader healthcare IT and digital transformation industry. The analysis considered digital health adoption across hospitals, ambulatory care centers, home healthcare, payers, and patients while evaluating government-led digitalization programs, healthcare infrastructure modernization, reimbursement policies, and regulatory initiatives supporting digital healthcare implementation.
Segmentation
Segment Share Modeling: Market shares across technology, component, application, and end-use segments were estimated using adoption rates of telehealth, mHealth, healthcare analytics, healthcare software, digital therapeutics, and connected healthcare platforms. Company product portfolios, reimbursement frameworks, healthcare utilization patterns, hospital digitalization levels, patient adoption trends, and government digital health programs were analyzed to estimate segment-level revenue across Germany.
Validation
Data Triangulation & Industry Validation: Market estimates were validated through a combination of secondary research, primary interviews, and company revenue analysis. Primary interviews included executives from digital health companies, hospital IT managers, healthcare providers, health insurers, digital therapeutics developers, and healthcare technology consultants. Additional validation was performed using company financial reports, product launches, regulatory approvals, reimbursement decisions for Digital Health Applications (DiGA), government digital health statistics, and healthcare IT adoption data to ensure consistency across all market segments.
Forecasting
Adoption-Driven Forecasting Model: Market forecasts were developed using historical adoption trends, technology penetration, healthcare expenditure growth, regulatory developments, reimbursement expansion, and digital healthcare investment patterns. The forecasting model incorporated key growth drivers, including increasing adoption of electronic patient records (ePA), telemedicine, Digital Health Applications (DiGA), artificial intelligence, cloud-based healthcare platforms, remote patient monitoring, and government initiatives promoting healthcare digitalization. Revenue projections through 2033 were developed using regression analysis, demand modeling, and market penetration assessments.
Delivered Customizations
This report has been delivered with the following In-depth customizations.
Client Request
Customization Delivered
Value Adds
Digital Health Adoption & Healthcare Provider Analysis
Detailed assessment of digital health adoption across hospitals, physician practices, pharmacies, and home healthcare settings in Germany. The analysis includes telemedicine utilization, electronic patient record (ePA) implementation, ePrescription adoption, Digital Health Applications (DiGA), healthcare IT investments, provider digital maturity, and key adoption barriers.
Helps technology vendors identify high-growth healthcare segments, prioritize customer groups, optimize commercialization strategies, and support market expansion through targeted digital health solutions.
AI & Healthcare Technology Innovation Assessment
Comprehensive evaluation of artificial intelligence adoption across medical imaging, clinical decision support, healthcare analytics, remote patient monitoring, and workflow automation. The analysis includes technology benchmarking, innovation pipeline assessment, product launches, strategic collaborations, regulatory developments, and future technology outlook within Germany’s digital health ecosystem.
Supports innovation strategy, identifies emerging technology opportunities, evaluates competitive positioning, and provides actionable insights for product development and long-term investment decisions.
Digital Health Policy, Reimbursement & DiGA Market Analysis
In-depth analysis of Germany’s digital health regulatory landscape, including Digital Health Applications (DiGA), electronic patient records (ePA), ePrescriptions (eRezept), reimbursement pathways, data privacy regulations, interoperability standards, and healthcare digitalization initiatives. The study also evaluates market access requirements and reimbursement trends influencing digital health adoption.
Enables companies to optimize market entry strategies, navigate regulatory requirements, strengthen reimbursement planning, reduce commercialization risks, and identify long-term growth opportunities in Germany’s digital health market.
Frequently Asked Questions About This Report
Software segment held the largest share (over 45.0%) in 2025, and is the fastest-growing component.
The patients segment dominated the Germany digital health market with a 33.8% revenue share in 2025 and is expected to register the fastest growth over the forecast period.
The Germany digital health market is expected to grow at a CAGR of 16.6% from 2026 to 2033, reaching USD 34.8 billion by 2033.
The tele-healthcare segment dominated the Germany digital health market with a 44.7% revenue share in 2025. The segment's dominance is driven by the increasing adoption of virtual consultations, remote patient monitoring, and digital care platforms, which enhance healthcare accessibility and ease pressure on hospitals and physician practices.
Some of the key players operating in the Germany digital health market include Cerner Corporation, GE HealthCare, Abbott, Olympus Corporation, Resideo Technologies, Cisco Systems, Inc., Telefónica S.A., SoftServe, Computer Programs and Systems, Inc. (CPSI), Vocera Communications, Apple Inc., McKesson Corporation, Epic Systems Corporation, Vodafone Group Plc, AirStrip Technologies, Google LLC, Samsung Electronics Co., Ltd., Orange S.A., Qualcomm Technologies, Inc., and CompuGroup Medical SE & Co. KGaA.
The market growth is driven by the rising adoption of telemedicine, remote patient monitoring, and electronic health records (EHRs), supported by the increasing burden of chronic disease, an aging population, and healthcare workforce shortages. The increasing adoption of EHR and connected healthcare infrastructure is further supporting market growth. For instance, in April 2025, Versicherungsbüro Weiss reported that Germany initiated the nationwide rollout of electronic patient records (ePA), enabling the secure exchange of patient health information and improving healthcare interoperability.
The diabetes segment dominated the Germany digital health market with a 29.7% revenue share in 2025 and is expected to register the fastest CAGR over the forecast period.
The Germany digital health market size was valued at USD 10.1 billion in 2025 and is estimated at USD 11.9 billion for 2026.
About the Author(s)
Healthcare IT Research Team
Healthcare · Healthcare ITThis report was authored by the healthcare it research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the healthcare it segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


