
- Home
- »
- Advanced Interior Materials
- »
-
Green Steel Market Size, Share & Growth Report, 2026-2033GVR Report cover

Green Steel Market (2026 - 2033)
Size, Share & Trends Analysis Report By Production Technology (EAF, Hydrogen-based DR), By End-use (Construction, Automotive), By Region (North America, Europe, Asia Pacific, Central & South America, Middle East & Africa), And Segment Forecasts
Market Size, 2025
$573.0BMarket Estimate, 2026
$604.3BMarket Forecast, 2033
$1,312.0BCAGR, 2026–2033
11.7%Green Steel Market Summary
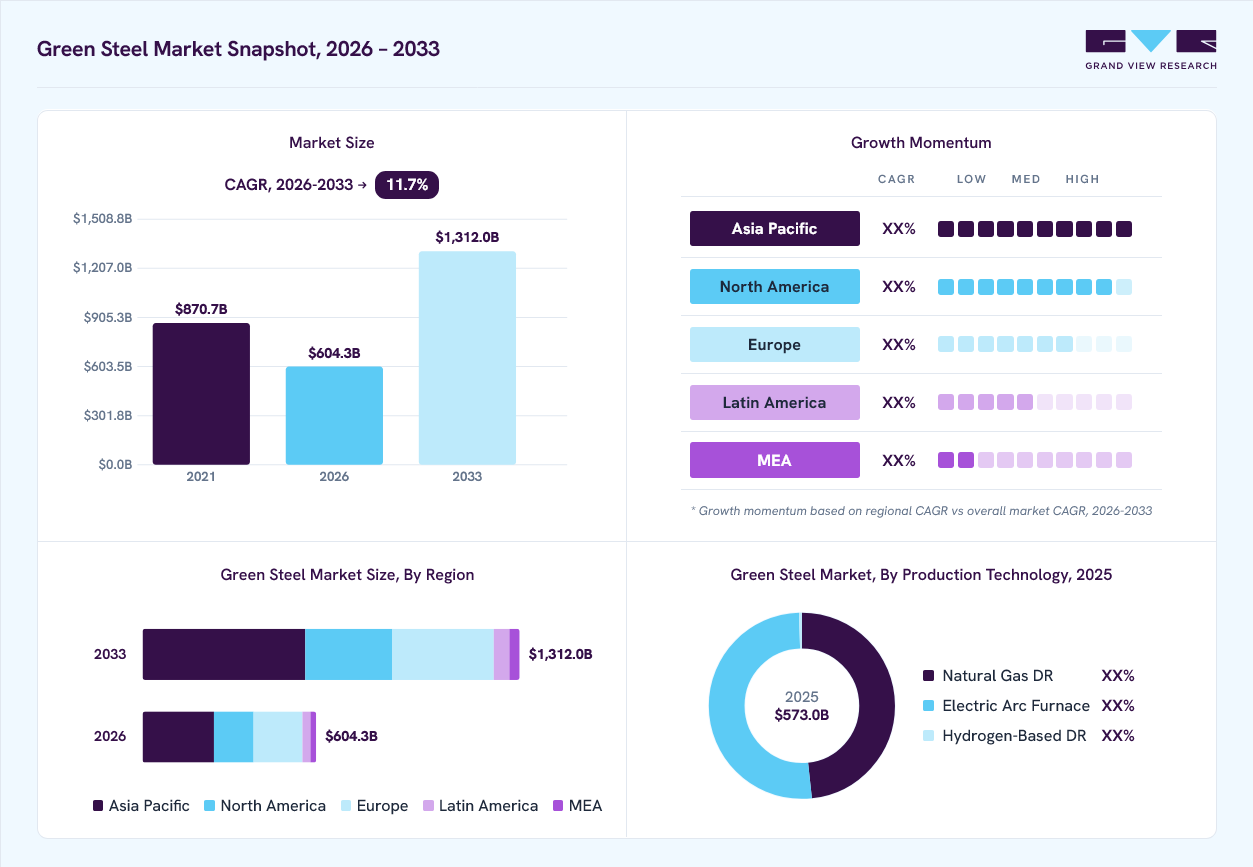
The global green steel market size was valued at USD 573.0 billion in 2025 and is projected to grow from USD 604.3 billion in 2026 to USD 1,312.0 billion by 2033, at a CAGR of 11.7% from 2026 to 2033. Asia Pacific dominated the green steel market with the largest revenue share of 40.9% in 2025. This growth is significantly driven by the increasing demand for sustainable manufacturing practices and the reduction of carbon footprints in the steel industry.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By production technology: Electric arc furnace segment held the largest market share of 51.2% in 2025.
- By end-use: Automotive & transportation segment held the largest market share of 47.6% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (40.9% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 573.0 Billion
- Estimated market size in 2026: USD 604.3 Billion
- Projected market size by 2033: USD 1,312.0 Billion
- CAGR (2026-2033): 11.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
 To learn more about this report, Download Free Sample Report
Price Trends of Green Steel
The green steel market has seen notable price fluctuations, largely influenced by the availability and cost of raw materials and the adoption rate of new technologies. In 2022, prices surged due to heightened demand from environmentally conscious manufacturers and supply chain disruptions caused by geopolitical tensions.
 To learn more about this report, Download Free Sample Report
However, in 2023, prices began to stabilize as technological advancements improved production efficiency and new policies incentivized the use of green steel. By 2024, the market observed a price decline, reflecting broader stabilization in the commodities market and increased production capacity.
Market Dynamics
The green steel market is growing as industries look for cleaner ways to produce steel and meet carbon reduction goals. Demand is increasing from the automotive, construction, and manufacturing sectors that are seeking low-emission materials. Investments in hydrogen-based steelmaking and renewable energy are supporting market growth, while government policies are encouraging adoption. However, high production costs and limited green hydrogen availability remain key challenges. As technology improves and production scales up, green steel is expected to become more commercially viable and widely adopted.
Stringent climate regulations and carbon reduction targets are accelerating the adoption of green steel worldwide. Governments are introducing carbon pricing mechanisms, emissions trading systems, and low-carbon procurement policies that increase the cost of conventional steel production while encouraging investment in cleaner technologies such as hydrogen-based DRI and renewable-powered electric arc furnaces. As steel producers face growing pressure to decarbonize their operations and maintain market access, demand for green steel is expected to strengthen across major industrial sectors.
The European Union's Carbon Border Adjustment Mechanism (CBAM) entered its definitive phase in 2026, requiring importers of steel and other carbon-intensive products to account for the embedded emissions associated with their imports. This regulation effectively raises the cost of high-carbon steel entering the EU market and is encouraging steel producers globally to invest in low-carbon and green steel production technologies to maintain market access and competitiveness.
The green steel market faces a significant challenge from the limited availability and high cost of green hydrogen, which is a critical input for low-carbon steel production. Hydrogen-based steelmaking becomes economically viable only when green hydrogen can be produced at competitive costs, often targeted below USD 2 per kilogram. However, high electrolyzer investment costs, insufficient renewable energy capacity, and underdeveloped hydrogen transportation and storage infrastructure continue to restrict large-scale adoption. These bottlenecks increase production costs and slow the transition from conventional steelmaking processes to green steel technologies. In September 2025, Germany-based steel producer Salzgitter AG announced a delay of approximately three years for the expansion phases of its SALCOS green steel project. The company cited the slow development of the hydrogen market, high energy costs, and the need for stronger government support to accelerate hydrogen infrastructure and supply.
The implementation of the European Union’s Carbon Border Adjustment Mechanism (CBAM) is creating significant growth opportunities for green steel producers, particularly in Asia. As importers of steel into the EU become subject to carbon-related costs, demand for low-carbon and near-zero-emission steel is expected to increase. Manufacturers that invest in green steel technologies can strengthen their competitiveness in international markets, secure access to premium customers, and benefit from growing demand for sustainable materials across Europe. In 2025, India-based JSW Steel announced plans to develop green steel production capabilities and expand low-carbon steel offerings to align with evolving international sustainability requirements, including CBAM-related demand from Europe. The company has been investing in renewable energy integration, green hydrogen initiatives, and decarbonization strategies to enhance its position in export markets. Such investments reflect how Asian steel producers are preparing to capitalize on growing European demand for low-carbon steel products.
Analyst Perspective
The green steel market is growing as steel manufacturers invest in cleaner production methods to reduce carbon emissions. Demand is increasing from industries such as automotive, construction, and manufacturing that are looking to meet their sustainability goals. Companies are expanding production capacity through technologies such as electric arc furnaces and hydrogen-based steelmaking, although high costs and limited hydrogen availability remain challenges. Many producers are introducing green steel gradually while continuing to operate conventional facilities. As government support increases and production costs improve, green steel is expected to become a larger part of the global steel industry.
Production Technology Insights
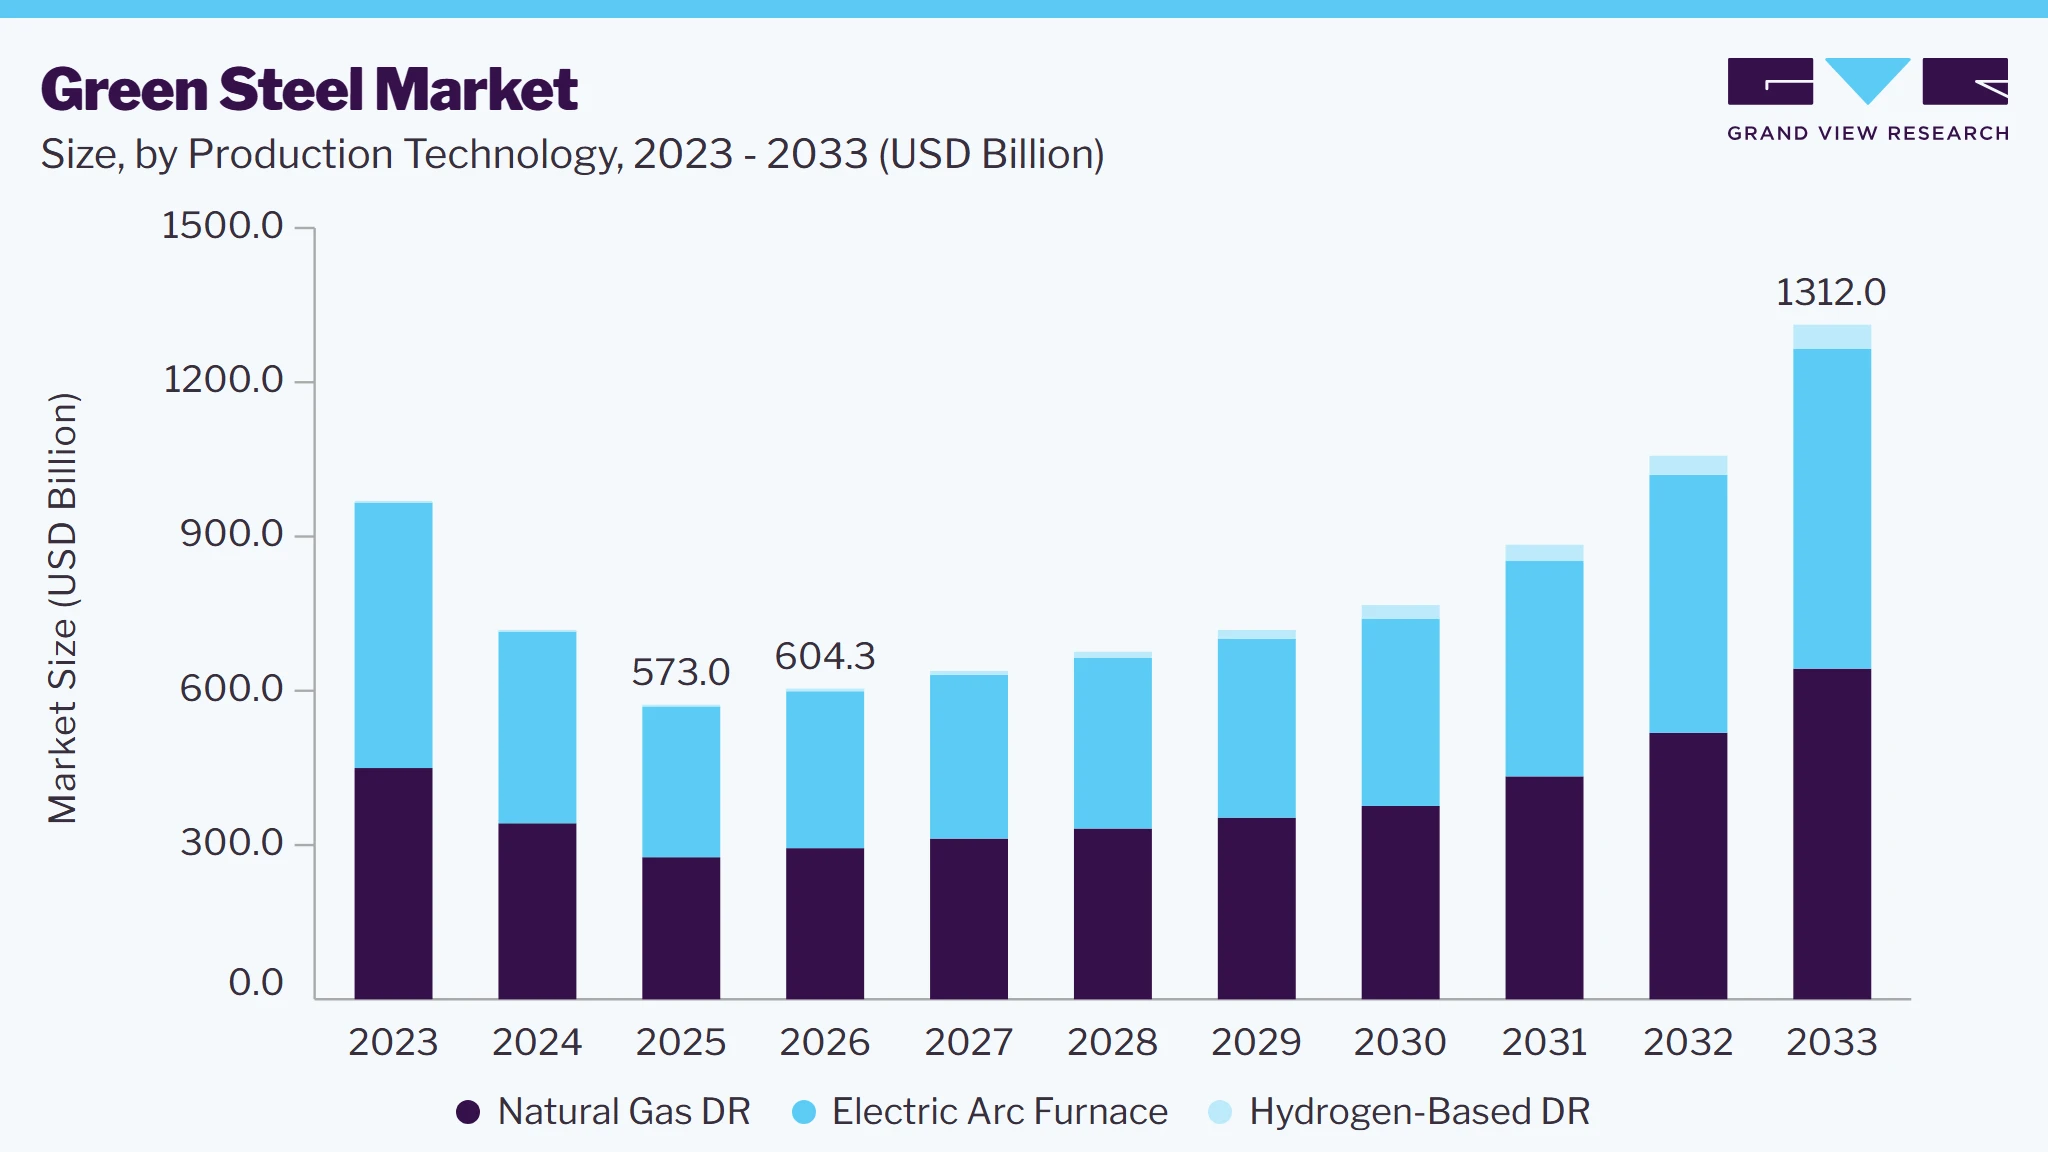
Based on production technology, the electric arc furnace segment led the market with the largest revenue share of 51.2% in 2025. EAF technology dominates the market due to its efficiency and lower carbon emissions compared to traditional blast furnaces. EAF is widely adopted in the building and construction industry, with a strong push for sustainable materials. The use of scrap in EAF further enhances its environmental benefits, making it a preferred choice for manufacturers aiming to meet stringent sustainability standards.
 To learn more about this report, Download Free Sample Report
Hydrogen-based direct reduction is a cutting-edge technology in green steel production that uses hydrogen as a reducing agent instead of traditional carbon sources. This method produces water vapor as a byproduct instead of CO2, significantly reducing carbon emissions. Leading companies like SSAB, ArcelorMittal, and HYBRIT are investing heavily in hydrogen-based technologies, aligning global decarbonization targets. With ongoing advancements and pilot projects, hydrogen DRI is poised to play a crucial role in revolutionizing the industry’s carbon reduction efforts.
End-use Insights
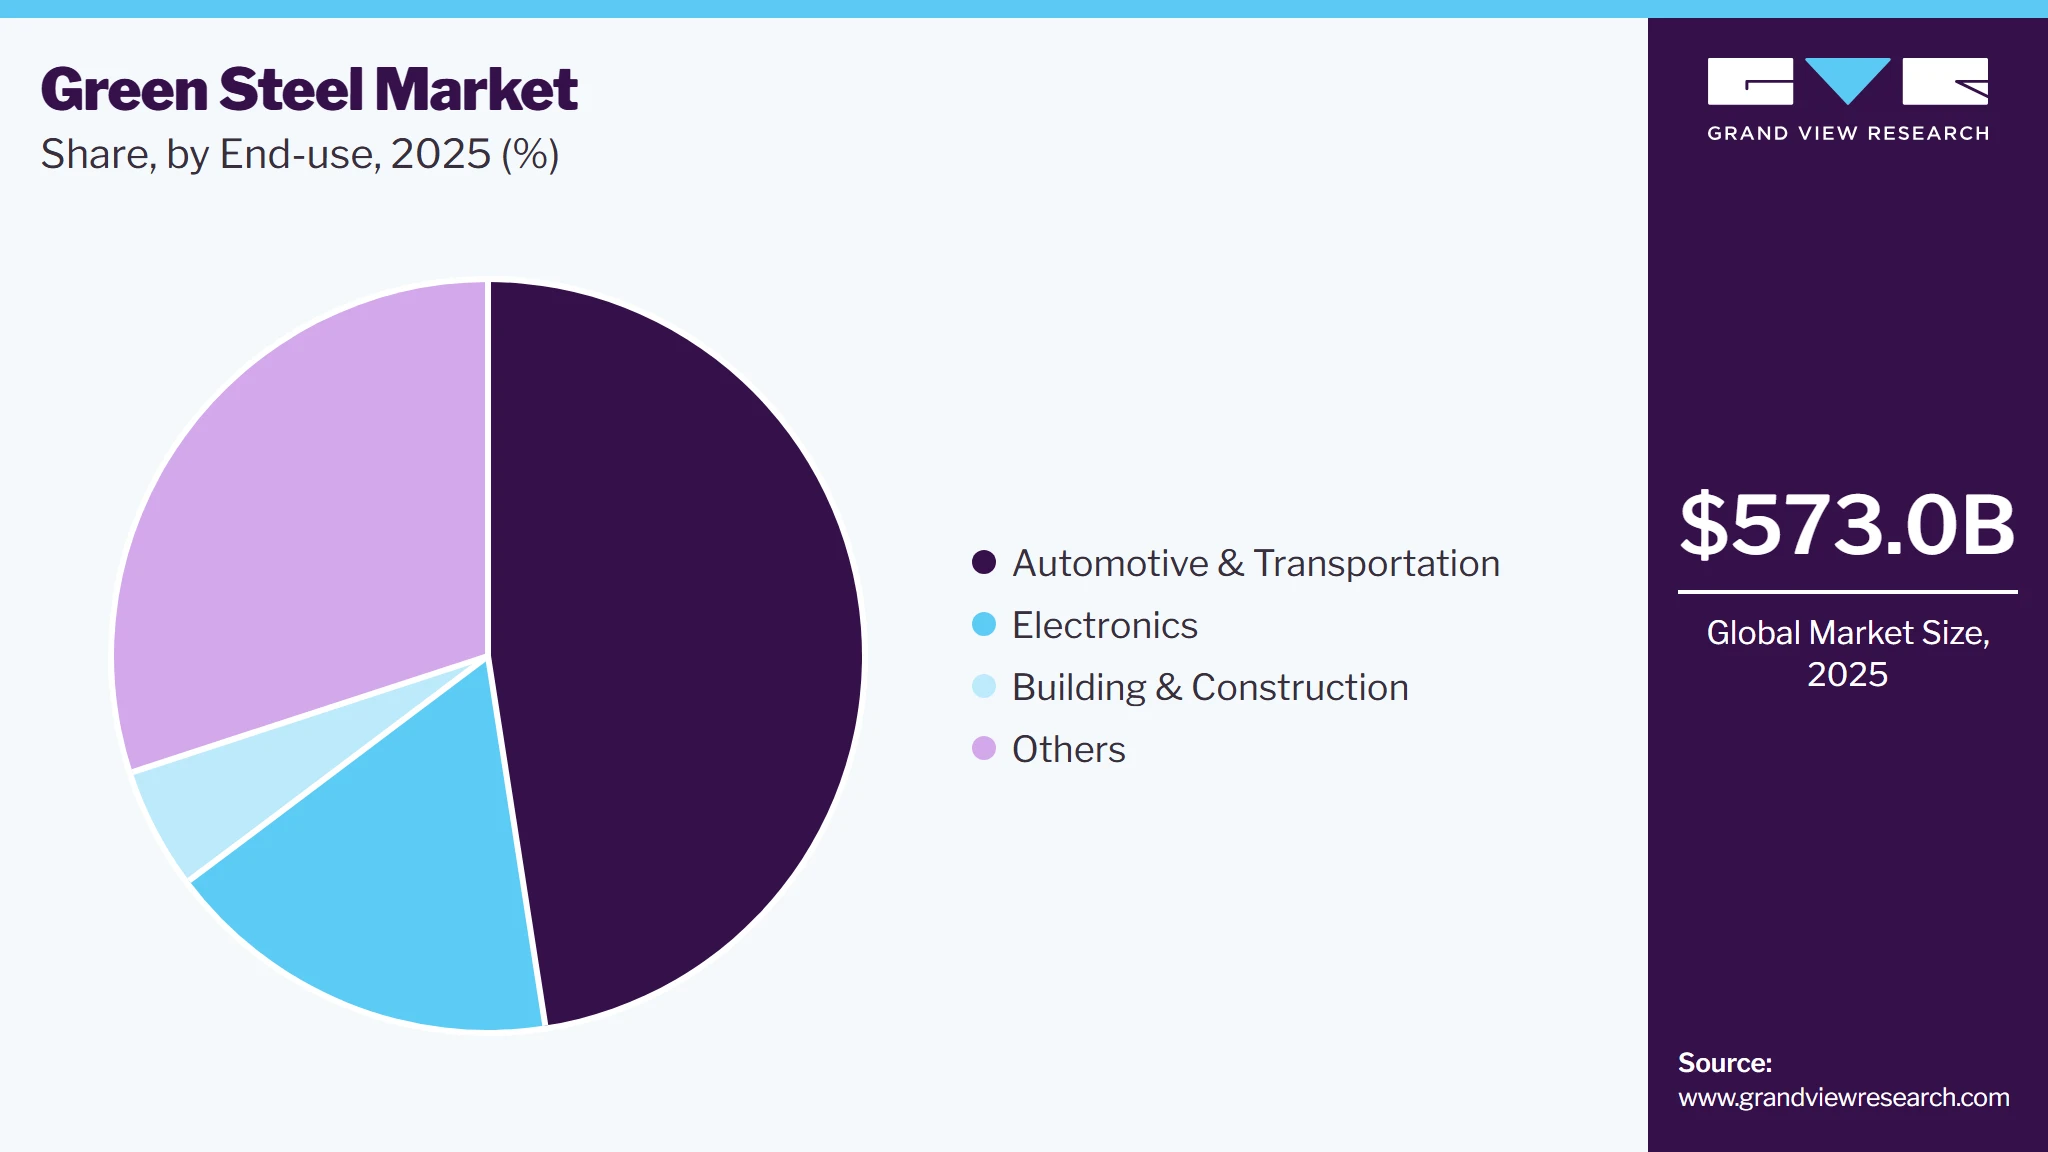
Based on end-use, the automotive & transportation segment led the market with the largest revenue share of 47.6% in 2025. The automotive and transportation sector leads the green steel market as it adopts eco-friendly materials to meet emission reduction targets and cater to environmentally conscious consumers. In 2023, major automakers, including AB Volvo and BMW AG, collaborated with green steel manufacturers to incorporate eco-friendly materials into vehicle bodies and chassis.
The building and construction segment is emerging as an important end-use sector for green steel, which is projected to see substantial growth due to the increasing shift towards sustainable materials in urban infrastructure projects. As global cities aim to lower their carbon footprints, green steel is becoming integral in building frameworks, bridges, and high-rise structures.
Regional Insights
The North America green steel market is characterized by increasing investments in sustainable technologies and a strong focus on reducing industrial emissions. The construction and automotive sectors are pivotal consumers, with green steel being integral to infrastructure projects and EV manufacturing. Government incentives and corporate sustainability commitments further propel market growth in the region.
U.S. Green Steel Market Trends
The U.S. green steel market is essential for industries such as construction and automotive, driven by stringent environmental regulations and the growing demand for sustainable materials. The push for green infrastructure and the automotive sector's transition to EVs are significant growth drivers. Technological innovations and investments in renewable energy sources enhance the market's outlook.
Asia Pacific Green Steel Market Trends
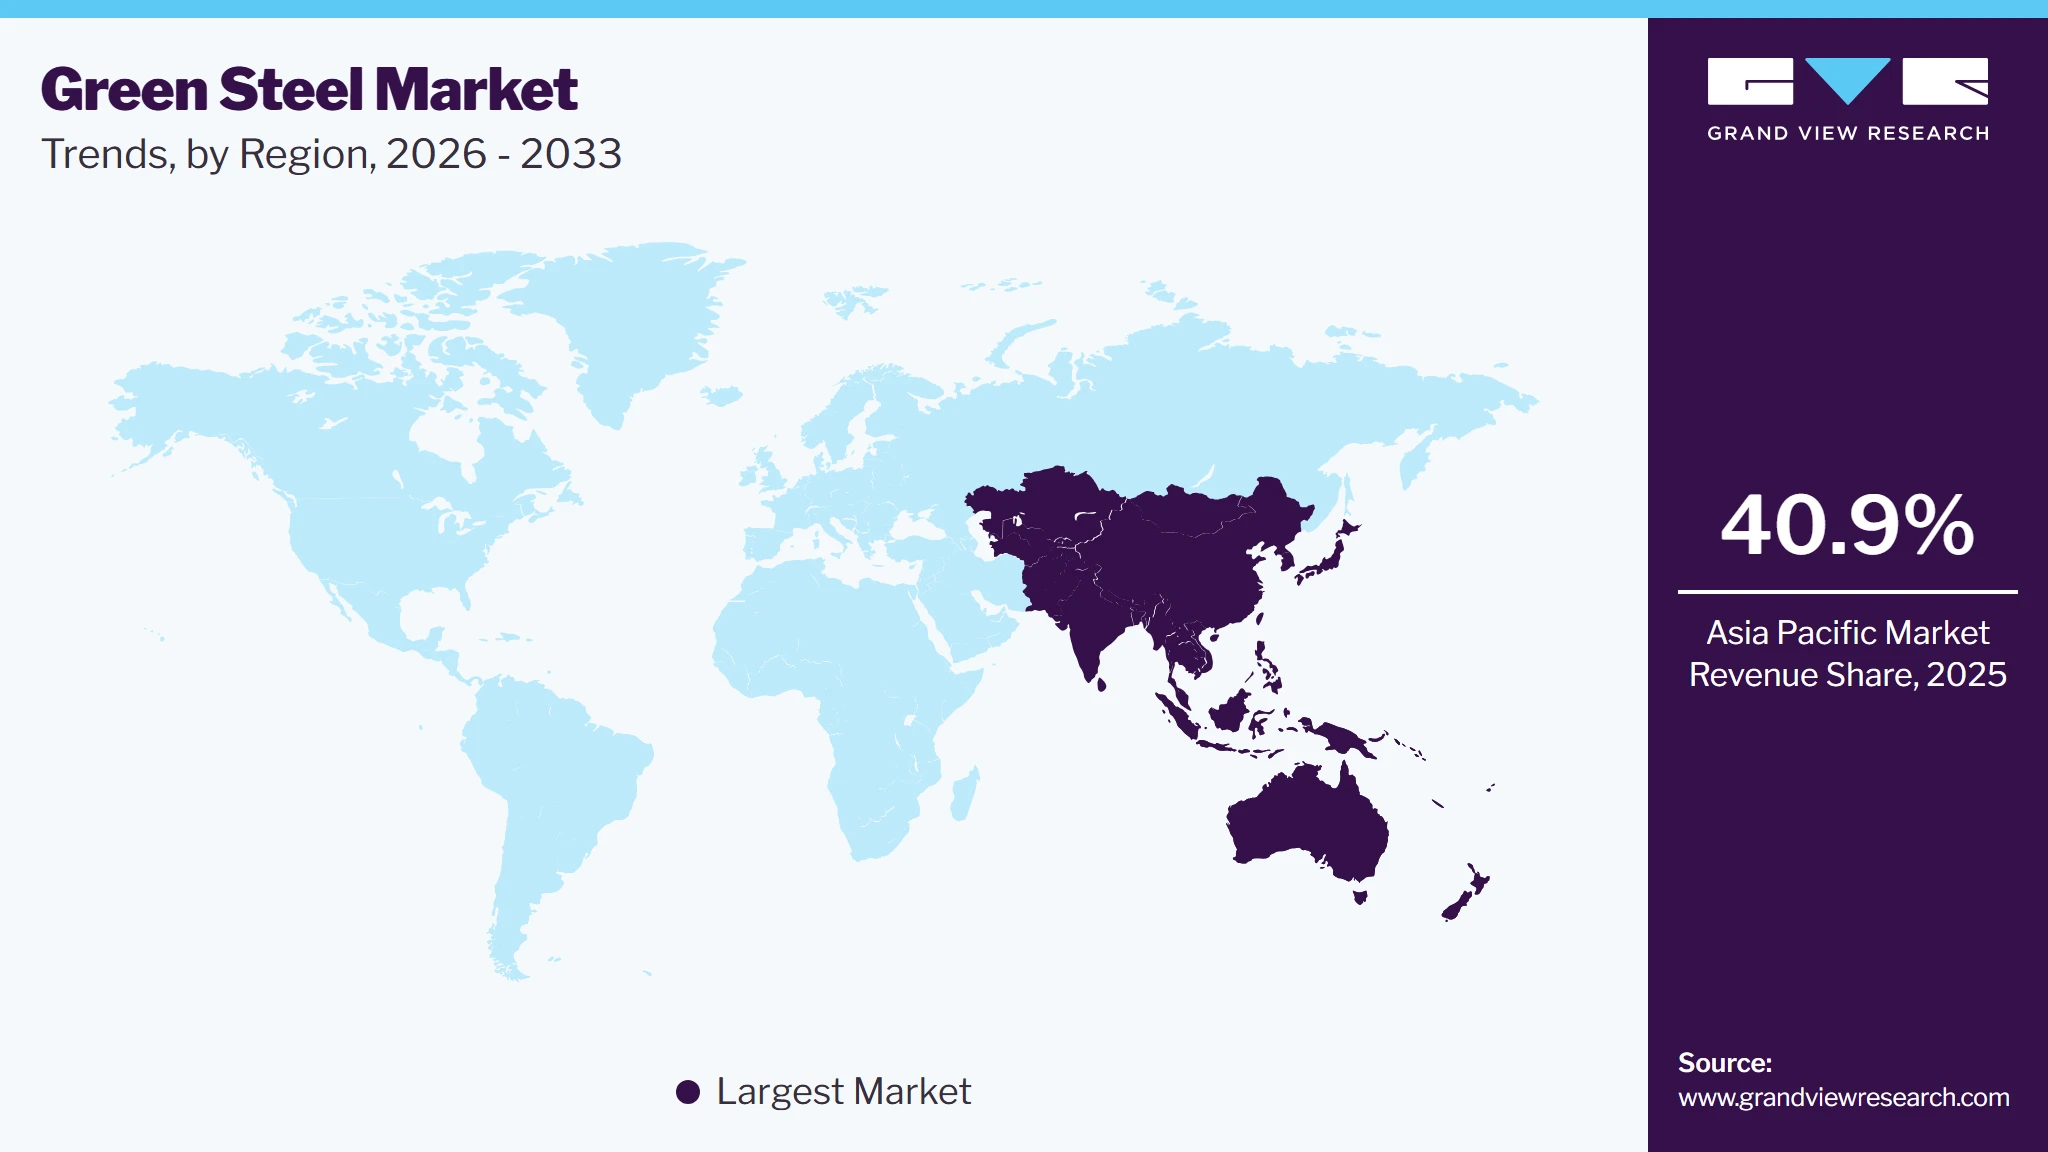
Asia Pacific dominated the green steel market with the largest revenue share of 40.9% in 2025. Asia Pacific green steel market is growing rapidly, driven by investments in sustainable manufacturing and heightened environmental awareness. The green steel market in China held the largest share in the Asia Pacific region in 2025. China, Japan, and South Korea are leaders in production, with demand rising in automotive, construction, and electronics sectors. Government policies promoting carbon neutrality and the adoption of advanced production technologies such as EAF and hydrogen-based steelmaking are key drivers, further fueling market expansion.
 To learn more about this report, Download Free Sample Report
Europe Green Steel Market Trends
Europe is a major market for green steel, with significant contributions from countries like Germany and Sweden. The region's growth is underscored by robust regulatory frameworks promoting sustainable manufacturing and substantial investments in green steel production technologies. The European Union's Green Deal and other environmental initiatives are key drivers of market growth, fostering an ecosystem conducive to green steel adoption.
Key Green Steel Company Insights
Some of the key players operating in the market include ArcelorMittal, SSAB, and ThyssenKrupp AG.
-
ArcelorMittal, based in Luxembourg, leads green steel production with initiatives like the ‘XCarb’ program, which aims to reduce carbon emissions. The company is expanding its market presence through strategic partnerships and investments.
-
SSAB, located in Sweden, produces fossil-free steel through its HYBRIT initiative, using hydrogen instead of coal to transform the steel industry.
-
ThyssenKrupp AG, based in Germany, focuses on green steel via its ‘Steel for the Future’ program, emphasizing sustainable practices and technological advancements.
Key Green Steel Companies:
The following key companies have been profiled for this study on the green steel market.
-
ArcelorMittal
-
China BaoWu Steel Group Corporation Limited
-
Emirates Steel Arkan
-
Nippon Steel Corporation
-
Nucor Corporation
-
Outokumpu
-
Salzgitter AG
-
SSAB
-
Tata Steel
-
thyssenkrupp AG
-
voestalpine AG
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (ArcelorMittal, thyssenkrupp AG, Nucor Corporation, Nippon Steel Corporation, China Baowu Steel Group, Tata Steel, voestalpine AG
• Invest in large-scale decarbonization projects, including EAF expansion, hydrogen-based DRI, and carbon capture technologies.
• Leverage existing steelmaking infrastructure to gradually transition toward low-carbon production.
• Form partnerships with renewable energy and hydrogen suppliers to secure long-term feedstock availability.
• Large production capacities and strong financial resources.
• Established customer relationships and global distribution networks.
• Ability to fund large-scale technology upgrades and pilot projects.• High capital expenditure requirements for decarbonization.
• Significant dependence on legacy blast furnace assets.
• Exposure to energy price volatility and regulatory compliance costs.Emerging Players (SSAB, Outokumpu, Emirates Steel Arkan, Salzgitter AG)
• Focus on green steel production as a core growth strategy rather than retrofitting extensive legacy assets.
• Accelerate deployment of hydrogen-based steelmaking and low-carbon production routes.
• Target premium markets seeking certified low-emission steel products.• Early-mover advantage in commercial green steel production.
• Lower carbon footprint and stronger sustainability positioning.
• Greater operational flexibility in adopting new technologies.• Smaller production scale and lower market reach compared to global steel giants.
• Heavy dependence on policy support, subsidies, and hydrogen infrastructure development.
• Higher production costs due to limited economies of scale.Recent Developments
-
In February 2024, Salzgitter Flachstahl GmbH (Salzgitter), a subsidiary of Salzgitter AG and Octopus Energy’s generation arm, signed a long-term Power Purchase Agreement (PPA) to enable the future production of green steel.
-
In January 2024, ArcelorMittal launched the XCarb Program, which focuses on achieving carbon-neutral steel production by leveraging innovative technologies and increasing the use of renewable energy sources. The initiative includes investments in hydrogen-based steelmaking and partnerships with key industry stakeholders to advance sustainable steel production.
-
In October 2023, Nippon Steel announced its Green Transformation Initiative, which aims to reduce carbon dioxide emissions by 30% by 2030 and achieve carbon neutrality by 2050. The strategy involves adopting new technologies, increasing the use of renewable energy, and enhancing energy efficiency across its production processes.
-
In March 2023, the HYBRIT Initiative by SSAB, LKAB, and Vattenfall is a partnership that aims to revolutionize steel production by using hydrogen instead of coal, significantly reducing carbon emissions. The initiative represents a major step towards fossil-free steel production and highlights the potential for large-scale industrial decarbonization.
-
In March 2023,Midrex Technologies, Inc., a subsidiary of Kobe Steel, is set to provide and erect the MIDREX Flex reduction facility for ThyssenKrupp Steel Europe AG at their Duisburg location in Germany. This installation is expected to boast an annual production capability of 2.5 million tons.
Green Steel Market Report Scope
Report Attribute
Details
Market Definition
The green steel market comprises steel produced using low-carbon technologies such as electric arc furnaces (EAFs), hydrogen-based reduction, and emission-reduced blast furnace processes utilizing natural gas to lower greenhouse gas emissions compared to conventional steelmaking.
Market size in 2025
USD 573.0 billion
Estimated market size in 2026
USD 604.3 billion
Projected market size by 2033
USD 1,312.0 billion
Growth rate
CAGR of 11.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Million, Volume in Kilotons and CAGR from 2026 to 2033
Report coverage
Revenue forecast, volume forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Production technology, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S., Canada, Mexico, Germany, UK, Spain, Russia, Sweden, China, India, Japan, South Korea, Thailand, Brazil, Argentina, Saudi Arabia, UAE, South Africa
Key companies profiled
SSAB, ArcelorMittal, thyssenkrupp AG, Nucor Corporation, Outokumpu, voestalpine AG, Emirates Steel Arkan, Nippon Steel Corporation, China BaoWu Steel Group Corporation Limited, Salzgitter AG, Tata Steel
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Green Steel Market Report Segmentation
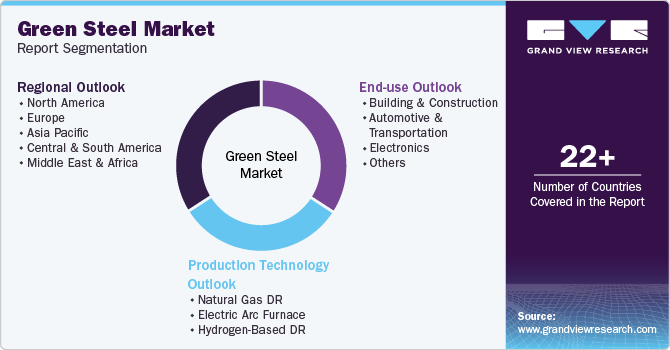
This report forecasts revenue and volume growth at global, country, and regional levels and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global green steel market report based on production technology, end-use, and region.
 To learn more about this report, Download Free Sample Report
-
Production Technology Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Natural Gas DR
-
Electric Arc Furnace
-
Hydrogen-Based DR
-
-
End-use Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
Building & Construction
-
Automotive & Transportation
-
Electronics
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Spain
-
Russia
-
Sweden
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Thailand
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The green steel market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each green steel segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Production Technology
Revenue capture definition
Natural Gas DR
This approach replaces some of the coal used in a blast furnace with natural gas, which has a lower carbon footprint. By partially substituting coal with natural gas, this method reduces the overall emissions of traditional steel production. However, it does not eliminate carbon emissions, as natural gas still produces CO₂, making it an emission reduction approach rather than zero-carbon.
Electric Arc Furnace
An Electric Arc Furnace uses electricity to melt recycled scrap steel or direct reduced iron (DRI) to produce steel. The emissions from this process can be minimized if the electricity used is from renewable sources, making it a low-carbon or even zero-carbon process. EAFs are especially efficient for recycling steel, significantly reducing the need for raw materials and energy compared to traditional blast furnaces.
Hydrogen-Based DR
This method uses hydrogen gas, rather than carbon-based fuels, to reduce iron ore into pure iron. The hydrogen acts as a reducing agent, bonding with oxygen in the ore to form water (H₂O) rather than carbon dioxide (CO₂). When powered by green hydrogen (produced using renewable energy), this approach can achieve near-zero carbon emissions, making it a promising path for achieving fully green steel.
Segment – End-Use
Revenue capture definition
Building & Construction
In the building and construction industry, green steel is used as a low-carbon alternative to traditional steel in structural frameworks, reinforcing bars, and other construction materials.
Automotive & Transportation
Green steel is employed in the production of vehicles, trains, and other transportation equipment to lower the carbon footprint of manufacturing processes. By incorporating green steel in body frames, chassis, and other components, the automotive and transportation industries aim to create lighter and more environmentally friendly vehicles, aligning with the sector's shift towards reducing emissions and promoting sustainability.
Electronics
For the electronics sector, green steel is used in the manufacturing of durable enclosures, internal frames, and other structural elements in devices like computers, smartphones, and household appliances.
Others
In sectors like aerospace, energy, and heavy machinery, green steel is applied to create high-strength, durable components with a lower environmental footprint.
Estimation Model
Layer Name
Key Question
Description
Green Steel Production Base Layer
What forms the production base?
Identify global steel production volumes generated through low-carbon steelmaking routes, including natural gas-based direct reduction, EAFs, and hydrogen-based direct reduction technologies. Assess installed capacity, operating utilization rates, planned capacity additions, and regional production trends to establish the addressable market size for green steel.
Raw Material & Manufacturing Layer
How is green steel produced?
Estimate the availability and utilization of key production inputs including iron ore, scrap steel, natural gas, green hydrogen, renewable electricity, and supporting infrastructure. Analyze production facilities, technology deployment, supply chain readiness, and manufacturing capabilities across major green steel-producing regions to assess supply dynamics.
Technology Commercialization & Offtake Layer
How extensively is green steel adopted by end users?
Analyze the commercialization and market uptake of green steel produced through Natural Gas DR, EAF, and Hydrogen-Based DR routes. Evaluate procurement commitments, decarbonization targets, carbon regulations, sustainability initiatives, and demand from building & construction, automotive & transportation, electronics, and other industrial sectors that influence green steel production expansion.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of green steel produced using Natural Gas DR, EAF, and Hydrogen-Based DR technologies. Production volumes, technology-specific steel output, average selling prices, green steel premiums, and end-use industry demand collectively determine the overall market value.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
End-Use Industry Opportunity Assessment
Identified growth opportunities associated with building & construction, automotive & transportation, electronics, and other industrial applications. The study assessed green steel adoption trends, sustainability commitments, procurement initiatives, carbon reduction targets, investment activity, and emerging application areas driving future demand for low-carbon steel products.
Enabled prioritization of high-growth end-use segments, supported market expansion strategies, and provided insights for resource allocation, business development, and long-term investment planning.
Green Steel Competitive Landscape Assessment
Detailed competitive landscape analysis covering producers of green steel through electric arc furnace, hydrogen-based DR, and natural gas-based DR technologies. The study profiled key market participants based on geographic presence, organizational structure, technology adoption, product portfolio, customer base, strategic partnerships, decarbonization initiatives, and expansion projects across major regions.
Enabled evaluation of competitive positioning, technology leadership, production capabilities, customer engagement strategies, and market participation across the green steel value chain.
Regional Green Steel Production & Trade Assessment
Conducted a detailed assessment of regional green steel production capacities, planned capacity additions, import-export dynamics, trade flows, policy frameworks, and carbon border regulations across North America, Europe, Asia Pacific, Latin America, and the Middle East.
Enabled identification of regional growth opportunities, supply-demand imbalances, export potential, and market entry strategies across key geographies.
Frequently Asked Questions About This Report
The green steel market size was estimated at USD 573.0 billion in 2025 and is expected to reach USD 604.3 billion in 2026.
The green steel market is expected to grow at a CAGR of 11.7% from 2026 to 2033 to reach USD 1,312.0 billion by 2033.
The Asia Pacific region dominated the green steel market with a revenue share of 40.9% in 2025.
The key players operating in the green steel market are SSAB, ArcelorMittal, thyssenkrupp AG, Nucor Corporation, Outokumpu, voestalpine AG, Emirates Steel Arkan, Nippon Steel Corporation, China BaoWu Steel Group Corporation Limited, Salzgitter AG, Tata Steel; and others.
The green steel market is driven by stringent carbon emission regulations, growing demand for low-carbon materials from end-use industries, increasing investments in hydrogen-based steelmaking, and the expansion of renewable energy infrastructure.
China dominated the Asia Pacific region market with a revenue share of 74.0% in 2025.
Asia Pacific is anticipated to register the fastest CAGR of 12.5% over the forecast period.
Based on production technology, the electric arc furnace segment accounted for largest revenue share of 51.2% in 2025.
Based on end-use, the automotive & transportation segment accounted for largest revenue share of 47.6% in 2025.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


