
- Home
- »
- Advanced Interior Materials
- »
-
Gypsum Plaster Market Size & Share Report, 2026-2033GVR Report cover

Gypsum Plaster Market (2026 - 2033)
Size, Share & Trends Analysis Report By Plaster System (Manually-applied, Machine-applied, Finishes), By Raw Material (Natural, Synthetic), By End-use (Residential, Commercial, Industrial), By Region, And Segment Forecasts
Market Size, 2025
$3.6BMarket Estimate, 2026
$3.8BMarket Forecast, 2033
$5.8BCAGR, 2026–2033
6.0%Gypsum Plaster Market Summary
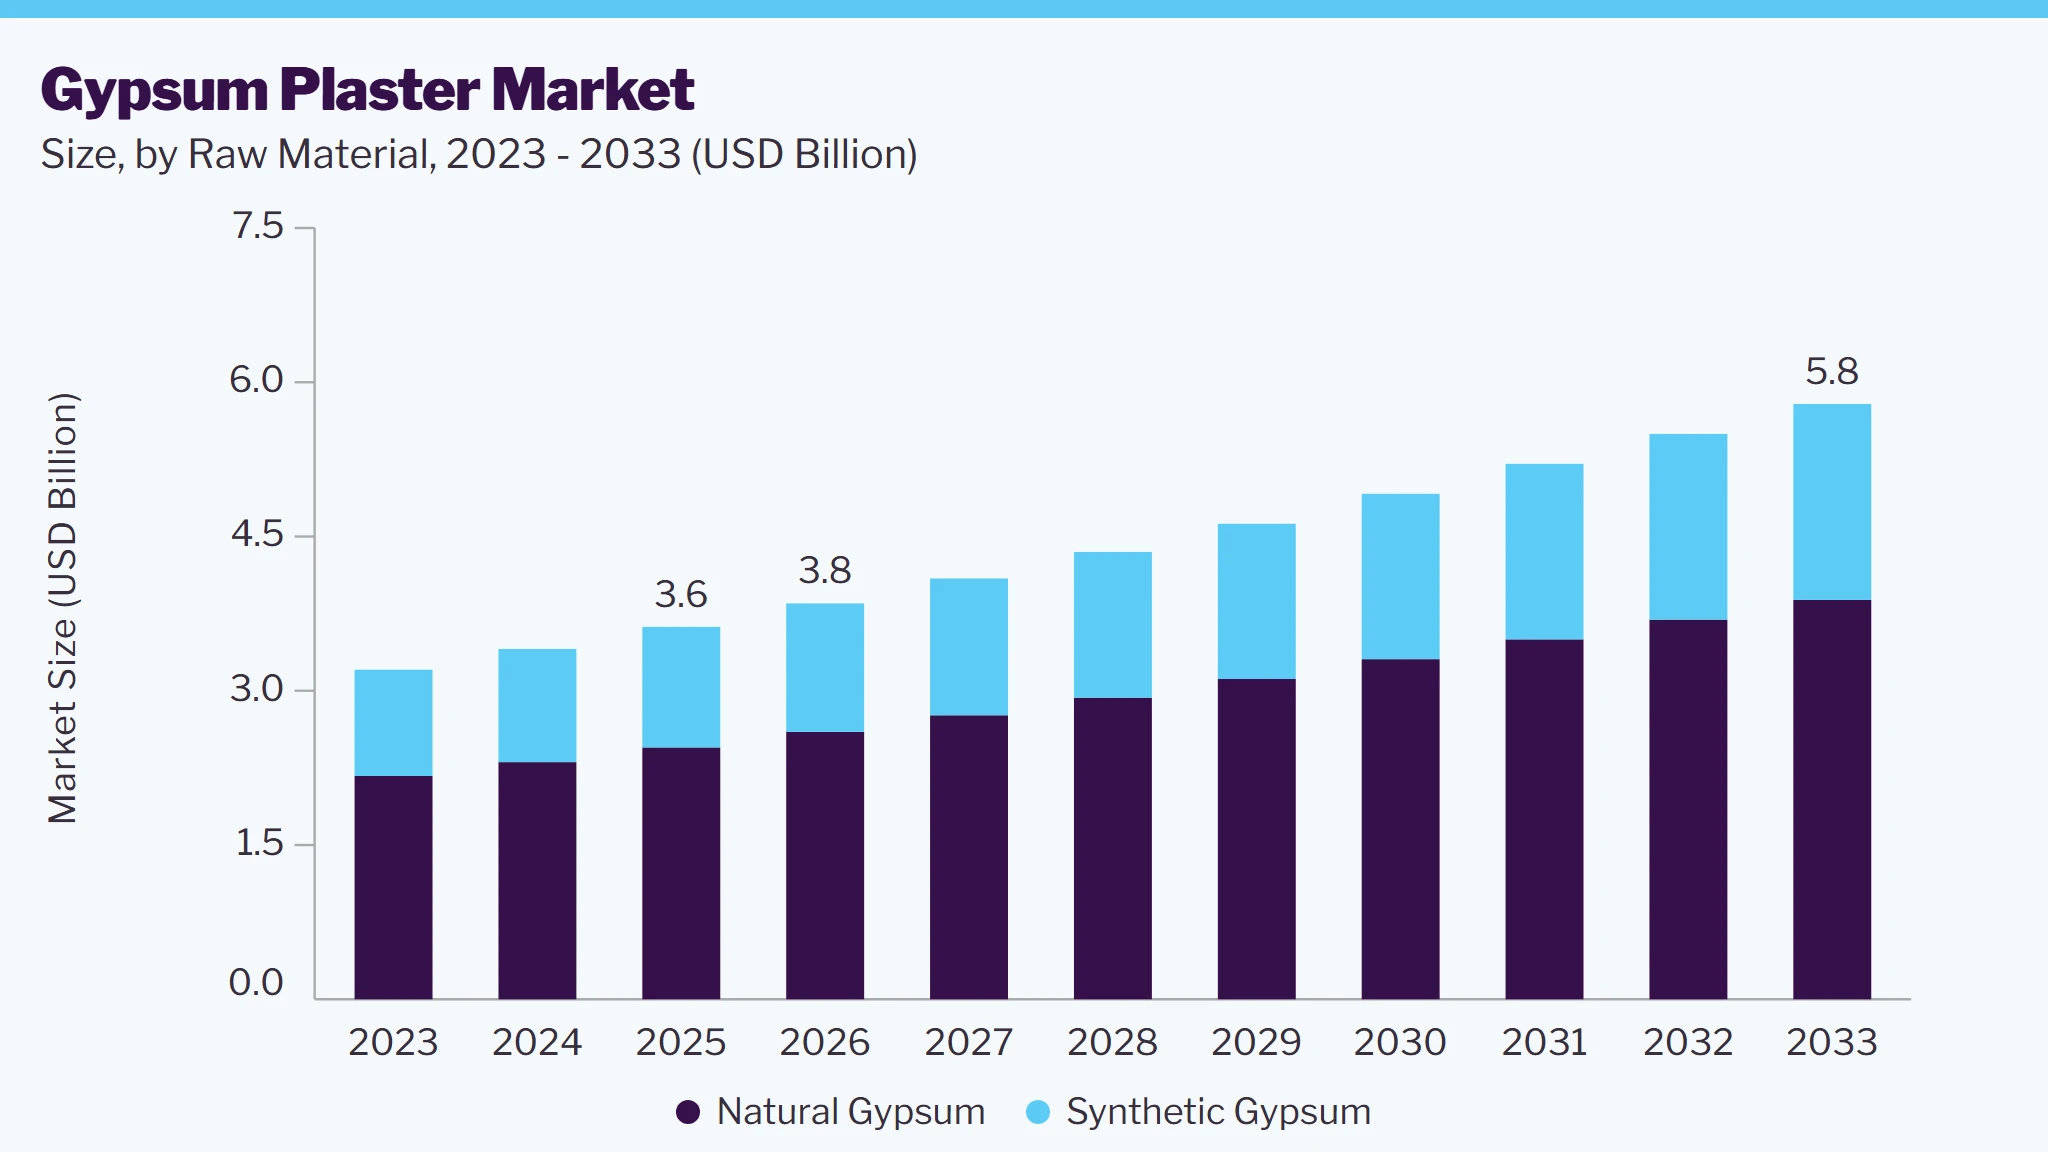
The global gypsum plaster market size was valued at USD 3.6 billion in 2025 and is projected to grow from USD 3.8 billion in 2026 to USD 5.8 billion by 2033, at a CAGR of 6.0% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 46.9%in 2025. One of the primary factors propelling market expansion is the growing adoption of gypsum-based materials in residential, commercial, and industrial construction.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By raw material: Natural gypsum segment led the market with the largest revenue share of 67.6% in 2025.
- By plaster system: Manually-applied plaster segment led the market with the largest revenue share of 43.2% in 2025.
- By end use: Residential segment led the market with the largest revenue share of 44.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (46.9% revenue share, 2025)
- Fastest-growing regional market: MEA (highest CAGR, 2026-2033)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 3.6 Billion
- Estimated market size in 2026: USD 3.8 Billion
- Projected market size by 2033: USD 5.8 Billion
- CAGR (2026-2033): 6.0%
Prism AI by Grand View Research Free to tryAsk a question about the gypsum plaster marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Gypsum plaster is widely preferred due to its superior fire resistance, acoustic insulation properties, and ease of application compared to traditional cement plaster. In addition, the rapid pace of urbanization and infrastructure development in emerging economies is further driving the demand for gypsum plaster in large-scale construction projects.
 To learn more about this report, Download Free Sample Report
Technological advancements in gypsum production and processing techniques are also crucial to market growth. The development of lightweight and enhanced-strength gypsum plasters has improved their application in modern construction, making them suitable for a wider range of structural and decorative uses. Furthermore, the availability of pre-mixed and ready-to-use gypsum plaster products simplifies construction, reduces labor costs, and accelerates project timelines, increasing market adoption.
In addition, the expanding renovation and remodeling sector, particularly in developed regions such as North America and Europe, is boosting the demand for gypsum plaster. Homeowners and commercial property owners are increasingly opting for gypsum-based solutions for interior finishes, owing to their smooth texture, aesthetic appeal, and durability. The growing focus on modular and prefabricated construction techniques is another factor driving the market, as gypsum plaster offers fast-setting and easy-to-handle properties, making it an ideal choice for prefabricated building components.
Market Dynamics
The gypsum plaster market is experiencing steady growth, driven by rapid urbanization, increasing residential and commercial construction activities, and the growing preference for high-performance building materials. Gypsum plaster is widely used for interior wall finishing, ceilings, partitions, and decorative applications due to its smooth finish, faster application, excellent fire resistance, and lower shrinkage compared to conventional cement plaster. Rising investments in infrastructure development, affordable housing projects, and renovation activities, particularly across emerging economies, are further accelerating market demand. In addition, continuous advancements in lightweight gypsum formulations, improved moisture-resistant products, and sustainable manufacturing processes are enhancing product performance and expanding the adoption of gypsum plaster across modern construction projects.
The expansion of residential, commercial, and infrastructure construction is a key driver of the Gypsum Plaster market. Governments worldwide are investing heavily in urban infrastructure, smart city projects, and affordable housing developments, creating significant demand for advanced construction materials. Gypsum plaster is increasingly preferred over traditional cement plaster because it offers faster application, reduced drying time, excellent surface finish, and lower labor requirements, helping contractors improve project efficiency and reduce overall construction timelines.
In addition to growing construction investments, increasing awareness of sustainable and energy-efficient building practices is supporting market growth. Gypsum plaster contributes to improved indoor comfort through its fire-resistant and thermal insulation properties while reducing water consumption during application. Continuous innovations in lightweight formulations, enhanced durability, and moisture-resistant gypsum products are further encouraging adoption across residential, commercial, healthcare, hospitality, and institutional buildings.
One of the major restraints affecting the gypsum plaster market is its limited suitability for prolonged exposure to moisture and exterior environments. Unlike cement-based materials, conventional gypsum plaster can lose strength when exposed to excessive humidity or water, restricting its application primarily to interior construction. Additionally, fluctuations in gypsum raw material availability, transportation costs, and energy prices can increase production expenses, creating pricing challenges for manufacturers operating in highly competitive markets.
The increasing adoption of green building practices and prefabricated construction systems presents significant growth opportunities for the gypsum plaster market. Developers and contractors are increasingly selecting gypsum plaster due to its lower environmental impact, reduced construction waste, and compatibility with sustainable building certifications. Furthermore, the rapid growth of modular and prefabricated construction is driving demand for lightweight, easy-to-install interior finishing materials. Ongoing product innovations, including moisture-resistant, crack-resistant, and high-strength gypsum plaster formulations, are expected to expand applications and create substantial long-term growth opportunities across both developed and emerging construction markets.
Market Concentration & Characteristics
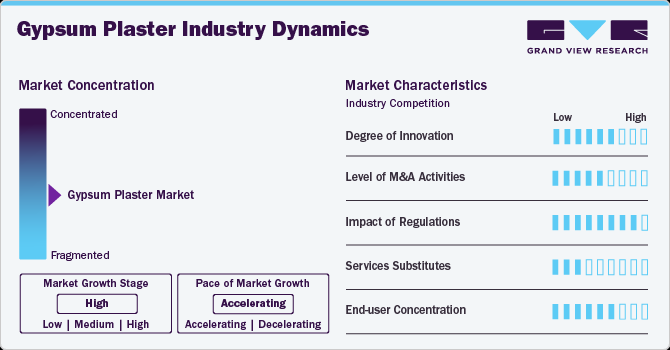
The global gypsum plaster industry exhibits a moderate to high market concentration, with key players dominating the industry through advanced manufacturing processes, product diversification, and strategic partnerships. The degree of innovation in the market is notable, driven by the development of lightweight, high-strength, and environmentally sustainable gypsum plaster variants. Companies are investing in enhanced formulations, such as quick-setting and moisture-resistant gypsum plasters, to meet the evolving demands of modern construction. Furthermore, innovations in automated application techniques and ready-mix gypsum plasters have improved efficiency and reduced labor dependency, further strengthening the market’s competitive landscape. The presence of both multinational corporations and regional manufacturers ensures a balance between large-scale production capabilities and localized supply chains, contributing to steady market growth.
 To learn more about this report, Download Free Sample Report
Regulations play a critical role in shaping the gypsum plaster industry, as governments worldwide emphasize sustainable construction practices, fire safety standards, and low-carbon building materials. Regulatory bodies such as LEED (Leadership in Energy and Environmental Design) and BREEAM (Building Research Establishment Environmental Assessment Method) promote using gypsum plaster for its recyclability, energy efficiency, and reduced environmental impact. However, the market faces competition from service substitutes like cement plaster, lime plaster, and synthetic wall coatings, which are preferred in certain applications due to regional preferences and cost considerations. The end-use concentration is high in the construction sector, with demand driven by residential, commercial, and industrial infrastructure projects. However, the growing trend of prefabricated and modular construction has increased the utilization of gypsum plaster, reinforcing its position as a key material in contemporary building practices.
Analyst Perspective
The gypsum plaster market has evolved from being a conventional interior finishing material to becoming an essential component of modern construction, driven by rapid urbanization, increasing infrastructure investments, and the growing preference for faster, high-quality building solutions. The shift toward lightweight construction materials, improved fire resistance, and efficient application methods has significantly expanded its adoption across residential, commercial, and industrial projects. Looking ahead, the market is expected to witness steady growth, supported by rising demand for sustainable building materials, expanding renovation activities, increasing adoption of machine-applied plaster systems, and continuous innovations in moisture-resistant and high-performance gypsum formulations, positioning gypsum plaster as a key material in the future of modern construction.
Plaster System Insights
Based on plaster system, the manually-applied plaster segment led the market with the largest revenue share of 43.2% in 2025, driven by its widespread use in residential, commercial, and industrial construction projects. Traditional hand-applied plastering remains preferred among builders and contractors due to its cost-effectiveness, ease of application, and flexibility in achieving smooth and customized finishes. Skilled laborers favor manually applied gypsum plaster for its better workability, improved adhesion to various surfaces, and suitability for intricate architectural detailing. In addition, the rising demand for high-quality interior finishes in both new construction and renovation projects is contributing to the expansion of this segment.
Machine-applied plaster is expected to grow at the fastest CAGR of 7.4% over the forecast period, driven by the increasing demand for efficient and labor-saving construction solutions. The adoption of mechanized plastering techniques is rising as the construction industry seeks to enhance productivity, reduce manual labor dependency, and improve the uniformity of plaster applications. Machine-applied plaster offers significant time savings and cost efficiency, making it an attractive choice for large-scale residential, commercial, and industrial projects. Furthermore, the growing shortage of skilled labor in many regions has prompted contractors and developers to invest in automated plastering technologies to ensure consistent quality and faster project completion.
Raw Material Insights
Based on raw material, the natural gypsum segment led the market with the largest revenue share of 67.6% in 2025. Natural gypsum, a mineral primarily composed of calcium sulfate dihydrate, is extensively mined and processed to produce high-quality gypsum plaster. The increasing preference for natural gypsum-based plaster is attributed to its consistent chemical composition, minimal processing requirements, and lower environmental impact, making it a preferred choice for construction applications. Moreover, the abundant global reserves of natural gypsum, particularly in regions such as North America, the Middle East, and Asia-Pacific, ensure a steady and reliable supply for the growing construction industry.
Synthetic gypsum is expected to grow at the fastest CAGR of 6.5% over the forecast period. Synthetic gypsum, a byproduct of industrial processes such as flue gas desulfurization (FGD) in coal-fired power plants, is increasingly being utilized as a sustainable alternative to natural gypsum. The rising focus on reducing industrial waste and promoting circular economy initiatives has led to a surge in demand for synthetic gypsum, as it helps divert waste from landfills and minimize resource depletion. In addition, government regulations and environmental policies encouraging industries to adopt sustainable practices have further propelled the utilization of synthetic gypsum in plaster production.
End-use Insights
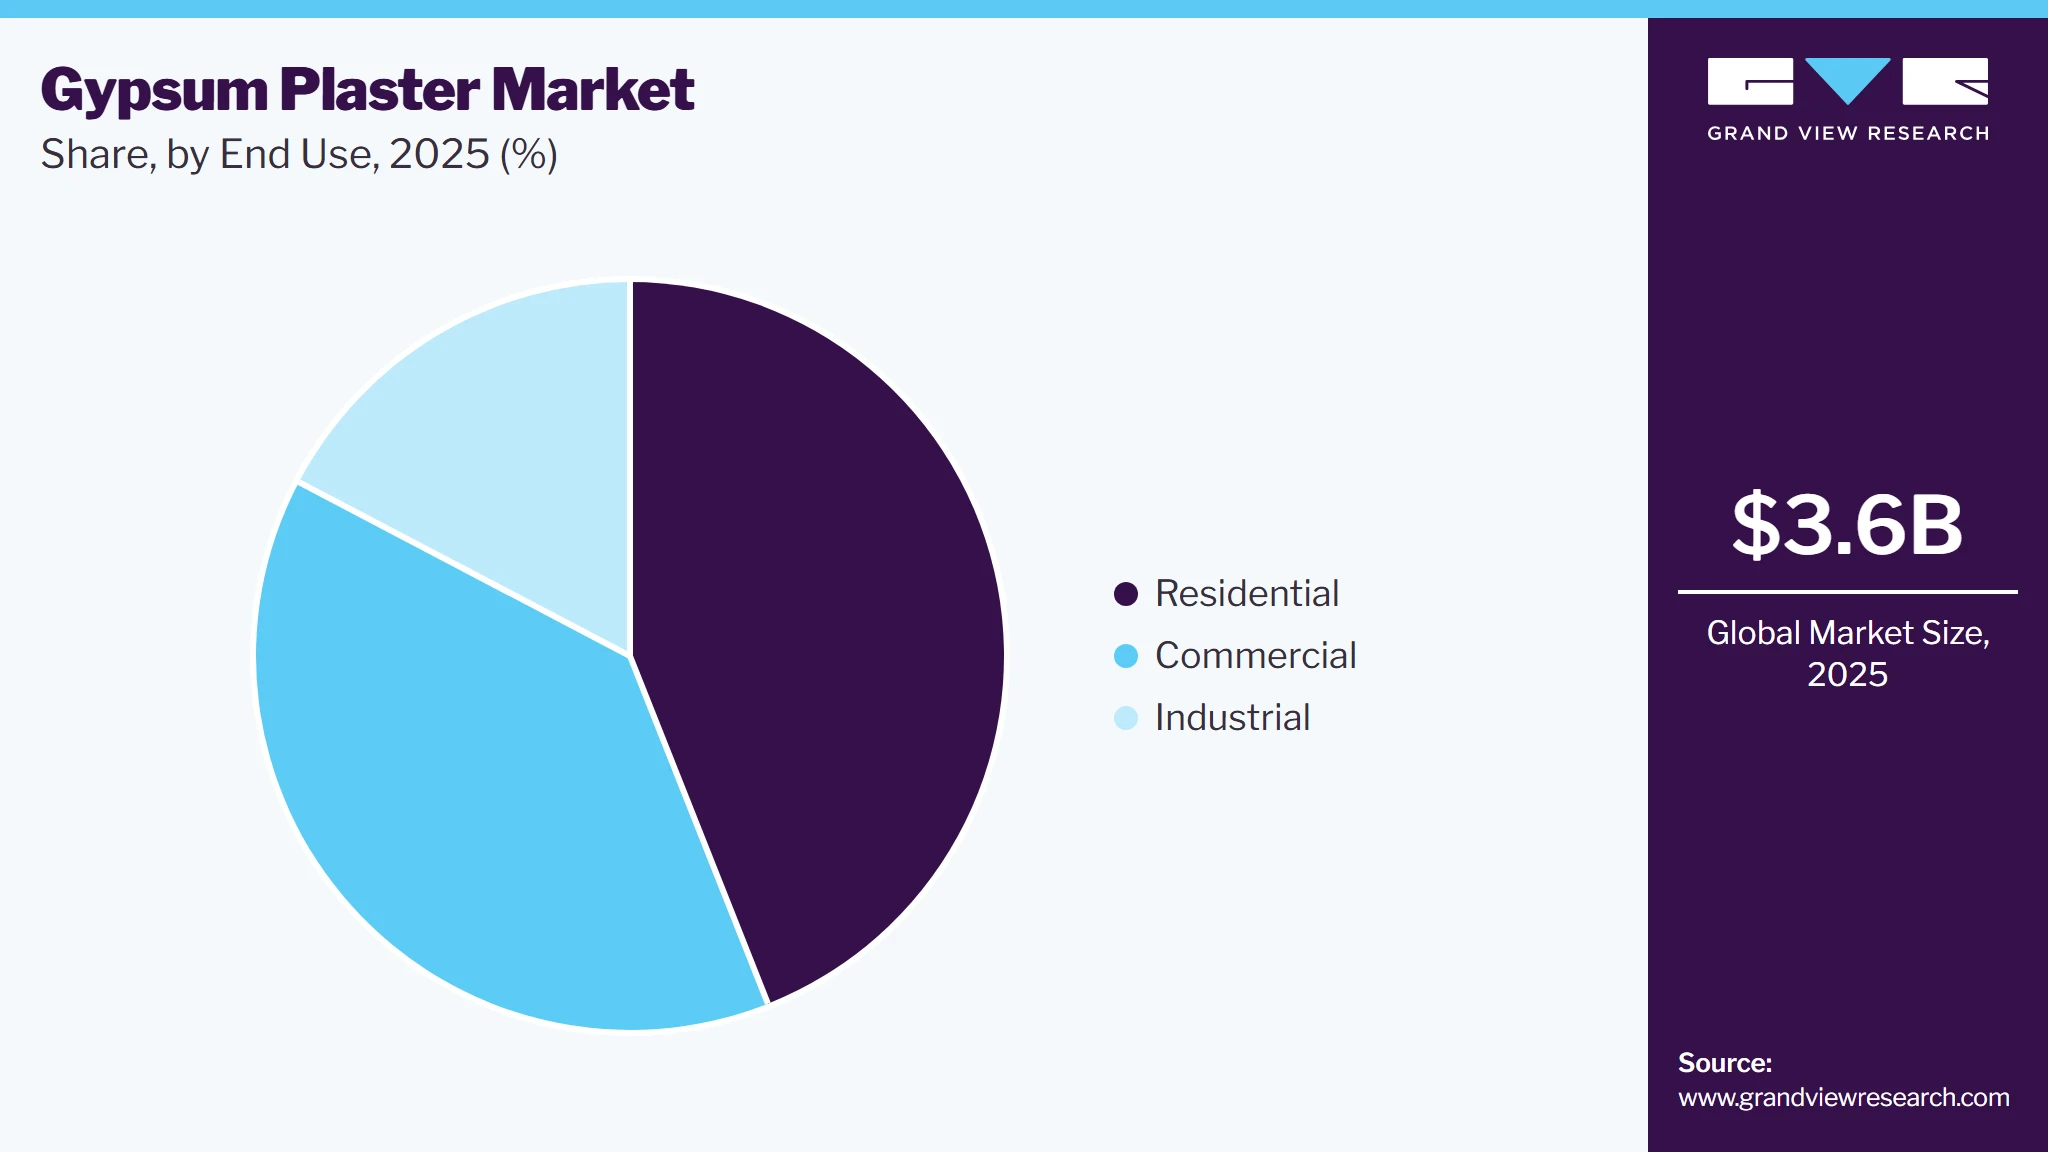
Based on end use, residential segment led the market with the largest revenue share of 44.0% in 2025. The rising emphasis on sustainable and energy-efficient housing solutions contributes to expanding gypsum plaster usage in the residential sector. With stringent environmental regulations and green building certifications, homebuilders and developers are shifting towards low-carbon, recyclable materials that align with energy conservation goals. Gypsum plaster offers low thermal conductivity, improving insulation and reducing energy consumption in residential spaces. This aligns with homeowners' and developers' increasing preference for eco-friendly and cost-effective construction materials.
 To learn more about this report, Download Free Sample Report
Commercial is expected to grow at the fastest CAGR of 7.4% over the forecast period, driven by the increasing demand for high-quality interior finishes in modern commercial buildings. Gypsum plaster is widely used in office spaces, hotels, shopping malls, hospitals, and educational institutions due to its smooth finish, fire resistance, and durability. The rising aesthetic and functional interior design trend in commercial establishments further fuels demand, as gypsum plaster allows for intricate architectural detailing while maintaining structural integrity. Furthermore, the need for faster construction timelines in commercial projects has led to adopting pre-mixed and quick-setting gypsum plaster solutions, which help reduce labor costs and project completion time.
Regional Insights
The gypsum plaster market in North America is expected to grow at a significant CAGR over the forecast period. The growing construction industry in North America, driven by both residential and commercial building projects, is a significant factor driving the market. With urbanization and population growth, there is a constant need for new housing and commercial spaces, further driving the demand for gypsum-based products. Furthermore, technological advancements and manufacturing processes have led to the development of high-performance gypsum plaster products that offer improved durability, faster setting times, and enhanced finish quality, making them more attractive to builders and contractors.
U.S. Gypsum Plaster Market Trends
The U.S. gypsum plaster market is driven by the growing demand for eco-friendly and sustainable building materials. As environmental concerns continue to rise, construction companies are turning to materials with lower carbon footprints and greater resource efficiency. Gypsum plaster stands out as an environmentally friendly option because it is often made from natural gypsum, an abundant mineral that can be easily recycled. Nevertheless, the production process of gypsum plaster consumes less energy than that of traditional cement production, further reducing its environmental impact.
Asia Pacific Gypsum Plaster Market Trends
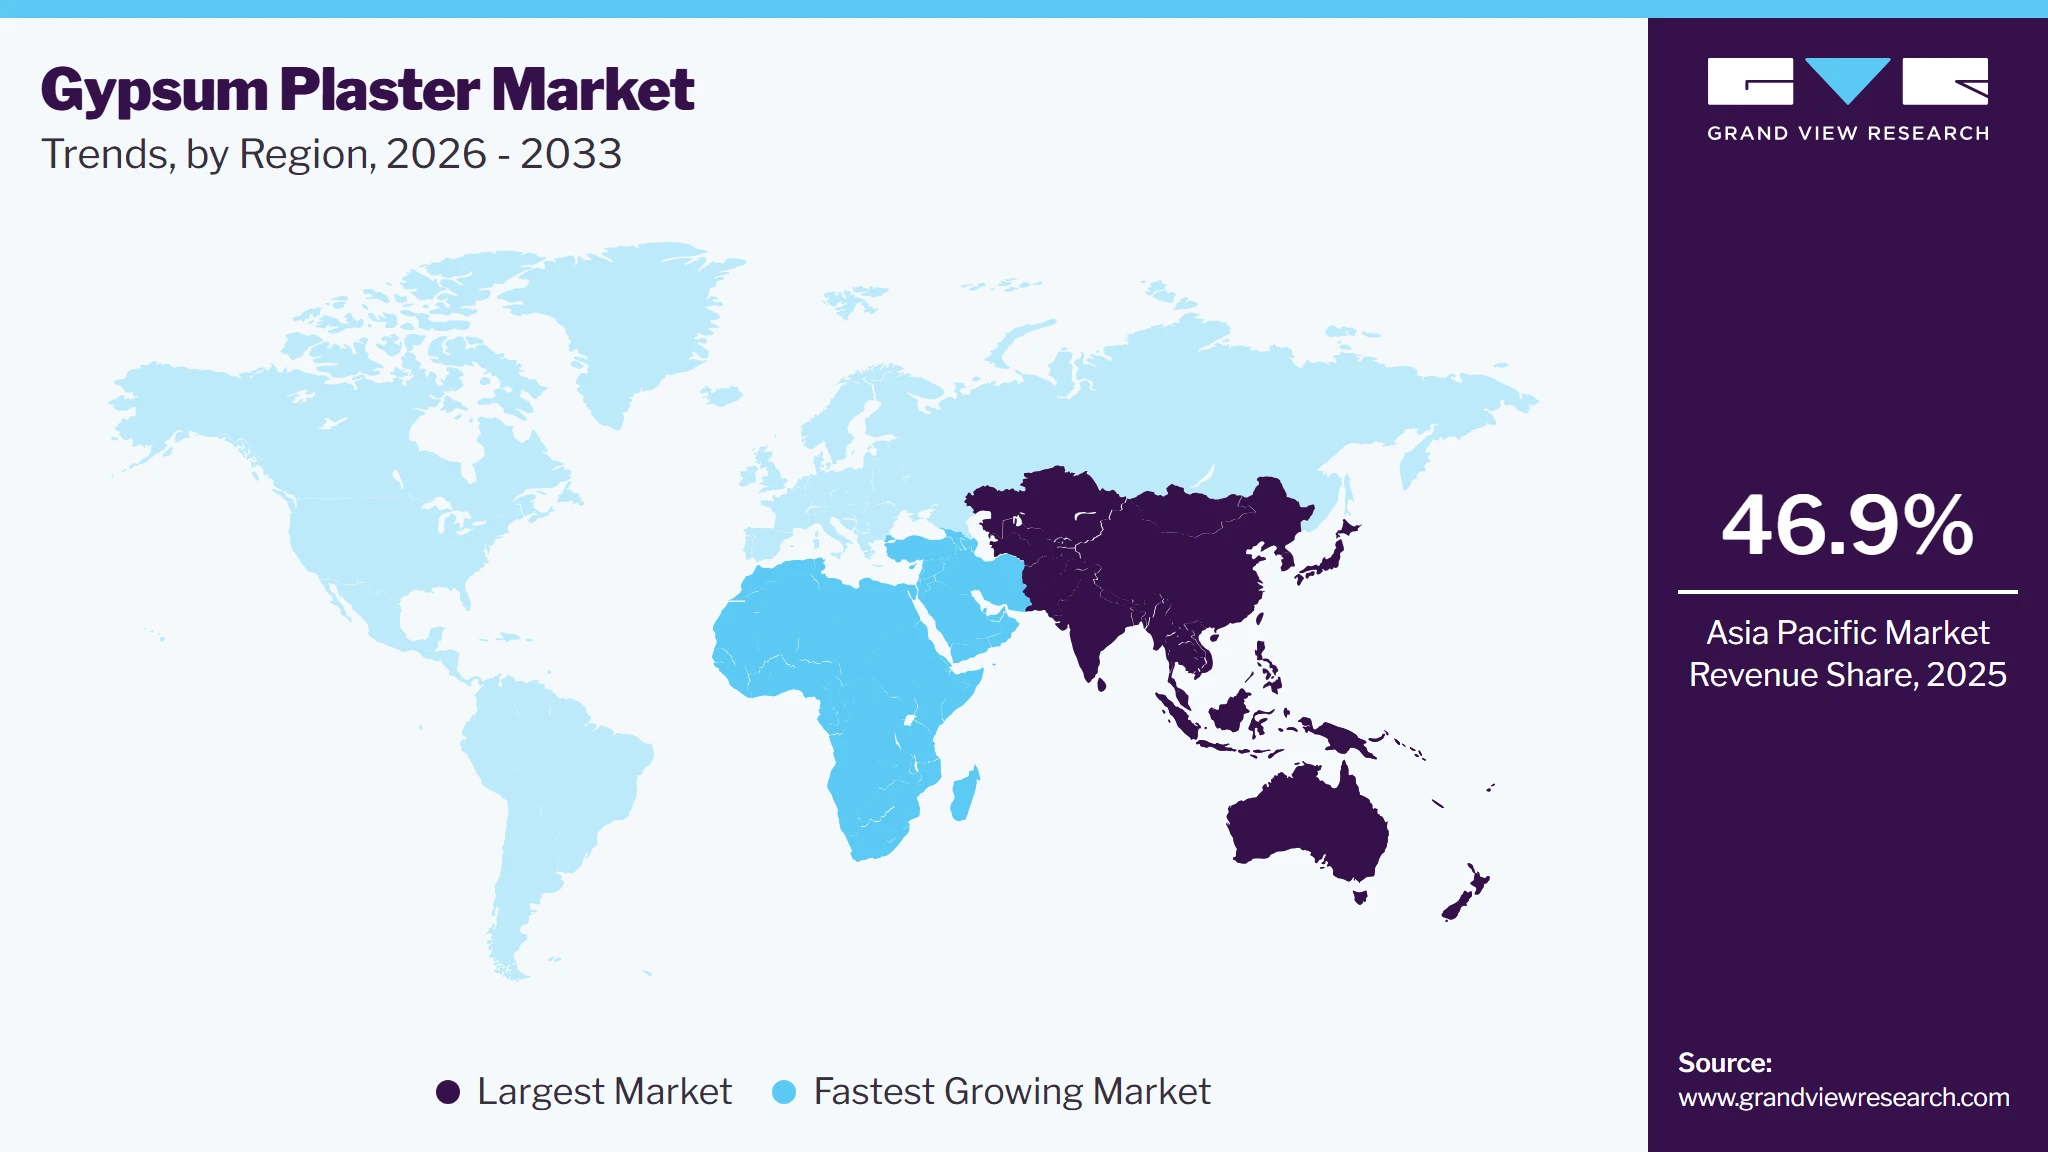
Asia- Pacific dominated the Gypsum Plaster market with the largest revenue share of 46.9% in 2025, driven by rapid urbanization and infrastructure development across key economies such as China, India, Japan, and Southeast Asia. The rising demand for affordable and high-quality construction materials in residential, commercial, and industrial projects is a major factor propelling market expansion. Governments in the region are investing heavily in smart city initiatives, housing projects, and commercial infrastructure, increasing the need for efficient and sustainable building materials like gypsum plaster. Moreover, the growing middle-class population and rising disposable incomes have contributed to increased demand for modern housing and high-end interior finishes, further supporting market growth.
 To learn more about this report, Download Free Sample Report
The Gypsum Plaster market in China held the largest share in the Asia Pacific region in 2025. Technological advancements in gypsum extraction, processing, and manufacturing also contribute to market growth. Developing enhanced-strength, lightweight, and ready-to-use gypsum plaster formulations improves construction efficiency and reduces labor costs. In addition, the expansion of gypsum mining and production facilities within China, coupled with advancements in automated production technologies, is ensuring a steady supply of high-quality gypsum plaster products at competitive prices.
Europe Gypsum Plaster Market Trends
The gypsum plaster market in Europe is driven by the rising trend of renovation and refurbishment activities. Many European countries, particularly those with older building stocks, such as the UK, Germany, and France, focus on updating and upgrading their existing infrastructure. Gypsum plaster plays a significant role in these renovations due to its ease of application, smooth finish, and versatility in both aesthetic and functional aspects. The growing popularity of interior design trends that emphasize clean, modern, and minimalist spaces has further fueled the use of gypsum plaster in renovations. Furthermore, gypsum plaster's ability to provide a smooth surface ideal for paint and wallpapering has made it the go-to material for interior wall finishing, contributing to its dominance in the European market.
Germany gypsum plaster market dominated the European market in 2024. Germany's competitive advantage in the global market for innovation and technology impacts the gypsum plaster industry. The growing integration of advanced technologies, such as automation and 3D printing in construction, has increased the efficiency and scalability of applying gypsum plaster. Applying gypsum plaster quickly and efficiently reduces labor costs and time, particularly in large-scale projects. This technological advancement, coupled with continuous product innovations—such as improved moisture resistance and enhanced durability has further driven the material's adoption in a variety of projects.
Latin America Gypsum Plaster Market Trends
The gypsum plaster market in Latin America is expected to show significant growth over the forecast period. The growing demand for fire-resistant building materials in Latin America has significantly driven the market. Gypsum plaster possesses excellent fire-resistant properties, which make it an essential material in ensuring the safety and compliance of buildings with stringent fire safety regulations. This is particularly important in Latin American countries that are prone to natural disasters, such as earthquakes and wildfires, where construction standards are becoming more stringent. As the need for fire-resistant materials rises, gypsum plaster's safety features make it an attractive option for developers looking to meet these evolving regulations, thereby driving its use in a wide variety of construction applications.
Middle East & Africa Gypsum Plaster Market Trends
The gypsum plaster market in MEA is witnessing considerable growth, owing to the increasing adoption of green building construction across Middle East & Africa. Many MEA countries have started to adopt stricter environmental regulations, such as energy efficiency standards and certifications for sustainable construction practices. This growing awareness and adoption of green building practices contributes to the heightened preference for materials like gypsum plaster, which is energy-efficient, recyclable, and does not contribute significantly to pollution. The ability of gypsum plaster to help regulate interior temperature and humidity, along with its ability to act as an effective sound barrier, makes it a key element in achieving sustainability goals in modern construction projects. As environmental regulations tighten and builders seek more energy-efficient alternatives to traditional materials, gypsum plaster is positioned as a vital component in meeting these demands.
Key Gypsum Plaster Company Insights
Some key players operating in the market include Saint-Gobain, Global Gypsum Company Co. Ltd.
-
Saint-Gobain is a global player in producing and distributing building materials, including gypsum-based products. The company’s extensive range of plaster and drywall solutions are well-regarded for their quality, performance, and sustainability. Saint-Gobain focuses on providing innovative, energy-efficient solutions that meet the demands of modern construction, especially in regions with stringent environmental regulations. Their gypsum products are widely used in residential, commercial, and industrial applications.
-
Global Gypsum Company is a major manufacturer and supplier of gypsum plaster products with a strong presence in various international markets. Known for producing high-quality gypsum plaster, its products are used in a wide range of applications, including wall coatings, ceilings, and decorative finishes. The company focuses on delivering superior products and services to meet the needs of residential and commercial construction projects while prioritizing eco-friendly manufacturing processes.
Escayescos, SL, and USG Corporation are some of the emerging market participants.
-
Escayescos, SL is a Spanish company specializing in manufacturing gypsum plaster and related products for the construction industry. The company offers a wide range of plaster solutions for interior and exterior applications, particularly emphasizing high-quality finishes and decorative plaster. Escayescos’ innovative approach to gypsum production makes it a significant player in the regional market, and its focus on both residential and commercial sectors has enabled it to expand its presence in the European and global markets.
-
USG Corporation is a leading building materials manufacturer, including gypsum-based products, in the United States. Known for its high-performance drywall systems, joint compounds, and plaster products. Their products are widely used in residential and commercial construction due to their durability, ease of installation, and superior finish. USG’s commitment to innovation and sustainability is reflected in its eco-friendly product offerings, including low-VOC and energy-efficient solutions.
Key Gypsum Plaster Companies
The following key companies have been profiled for this study on the gypsum plaster market.
-
Saint-Gobain
-
Knauf Gips KG
-
Global Gypsum Company Co. LTD
-
Escayescos, SL
-
USG Corporation
-
James Hardie Industries plc
-
Georgia-Pacific Gypsum II LLC
-
YOSHINO GYPSUM CO., LTD
-
Vg-orth GmbH & Co. KG
-
LA MARUXIÑA
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Saint-Gobain; Knauf Gips KG; USG Corporation; James Hardie Industries plc; Georgia-Pacific Gypsum II LLC; YOSHINO GYPSUM CO., LTD)
- Focus on expanding comprehensive gypsum plaster portfolios, including manually-applied plaster, machine-applied plaster, finishing plaster, and specialty gypsum products for residential, commercial, and industrial construction. Invest in advanced manufacturing technologies, sustainable production processes, product innovation, and high-performance plaster formulations while strengthening global distribution networks and partnerships with contractors, developers, and building material distributors.
- Strong global manufacturing footprint, diversified product portfolios, extensive distribution networks, and established relationships with construction companies and infrastructure developers support consistent revenue generation. Continuous investments in R&D, automation, sustainable manufacturing, and premium product development strengthen their competitive position across international construction markets.
- High capital investment requirements for manufacturing facilities, energy-intensive production processes, and compliance with environmental regulations increase operational costs. Fluctuations in raw material availability, energy prices, and construction industry cycles may impact profitability and production efficiency.
Emerging Players (Global Gypsum Company Co. LTD; Escayescos, SL; Vg-orth GmbH & Co. KG; LA MARUXIÑA)
- Focus on strengthening regional market presence through cost-effective gypsum plaster solutions, customized product offerings, and specialized plaster formulations for residential renovation, commercial construction, and niche architectural applications. Expand customer base by improving production efficiency, developing sustainable gypsum products, and establishing partnerships with regional distributors and contractors while gradually investing in manufacturing modernization and product quality enhancement.
- Greater operational flexibility enables faster product customization, competitive pricing, and quicker response to regional market requirements. Strong local market knowledge, specialized product offerings, and close customer relationships help these companies compete effectively in regional construction markets.
- Limited production capacity, smaller international presence, and lower financial resources restrict expansion into large-scale global construction projects. Lower brand recognition and comparatively limited investment in advanced manufacturing technologies, automation, and research & development may reduce competitiveness against established multinational gypsum plaster manufacturers.
Recent Developments
-
In December 2024, BUA Group unveiled its new gypsum plaster plant, marking a significant milestone in the West African construction industry. The state-of-the-art facility, designed to produce high-quality gypsum plaster, aims to meet the growing demand for construction materials in the region. With this move, BUA Group seeks to enhance local production capabilities, reduce reliance on imports, and contribute to developing the Nigerian and broader West African construction markets. The plant’s launch is expected to strengthen the gypsum plaster supply chain, drive economic growth, and support the construction of infrastructure projects across the region.
Gypsum Plaster Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.6 billion
Estimated market size in 2026
USD 3.8 billion
Projected market size by 2033
USD 5.8 billion
Growth rate
CAGR of 6.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Raw material, plaster system, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; Spain; China; India; Japan; South Korea; Australia; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
Saint-Gobain, Knauf Gips KG, Global Gypsum Company Co. LTD, Escayescos, SL, USG Corporation, James Hardie Industries plc, Georgia-Pacific Gypsum II LLC, YOSHINO GYPSUM CO., LTD, Vg-orth GmbH & Co. KG, LA MARUXIÑA
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Gypsum Plaster Market Report Segmentation
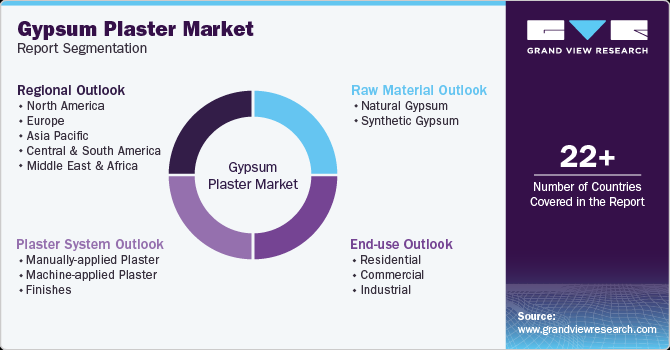
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global gypsum plaster market report based on plaster system, raw material, end-use and region.
 To learn more about this report, Download Free Sample Report
-
Plaster System Outlook (Revenue, USD Million, 2021 - 2033)
-
Manually-applied Plaster
-
Machine-applied Plaster
-
Finishes
-
-
Raw Material Outlook (Revenue, USD Million, 2021 - 2033)
-
Natural Gypsum
-
Synthetic Gypsum
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Residential
-
Commercial
-
Industrial
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Central & South America
-
Middle East & Africa
-
Research Methodology
The gypsum plaster market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each gypsum plaster segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Raw Material
Revenue capture definition
Natural Gypsum
Revenue generated from gypsum plaster manufactured using naturally mined gypsum. Includes standard gypsum plaster, finishing plaster, casting plaster, and construction-grade plaster used for wall finishing, ceilings, partitions, decorative moldings, and other residential, commercial, and industrial building applications.
Synthetic Gypsum
Revenue generated from gypsum plaster manufactured using synthetic gypsum, primarily obtained as a byproduct of flue gas desulfurization (FGD) processes and other industrial operations. Includes eco-friendly gypsum plaster products used for interior wall finishing, ceilings, prefabricated construction, and decorative applications, offering a sustainable alternative to natural gypsum while meeting performance and quality standards.
Segment – Plaster System
Revenue capture definition
Manually-applied Plaster
Revenue generated from gypsum plaster products designed for manual application using traditional hand tools. Includes base coat plaster, finishing plaster, and repair plaster used for interior walls, ceilings, partitions, and renovation projects across residential, commercial, and institutional buildings.
Machine-applied Plaster
Revenue generated from gypsum plaster products formulated for mechanized spray application using plastering machines. Includes high-performance gypsum plasters used in large-scale residential, commercial, industrial, and infrastructure projects where faster application, consistent surface quality, and improved labor efficiency are required.
Finishes
Revenue generated from gypsum finishing plaster products applied as the final surface layer to achieve smooth, decorative, and paint-ready wall and ceiling finishes. Includes skim coats, finishing compounds, and specialty finish plasters used in new construction, remodeling, and interior decoration applications.
Segment – End Use
Revenue capture definition
Residential
Revenue generated from gypsum plaster products used in residential construction and renovation. Includes plaster for interior walls, ceilings, partitions, decorative finishes, and repair applications in single-family homes, apartments, condominiums, and residential housing projects.
Commercial
Revenue generated from gypsum plaster products used in commercial buildings. Includes plaster solutions for offices, shopping malls, hotels, hospitals, educational institutions, airports, retail spaces, and other commercial facilities requiring smooth interior finishes, fire resistance, and efficient construction.
Industrial
Revenue generated from gypsum plaster products used in industrial construction and infrastructure. Includes plaster applications for factories, warehouses, manufacturing facilities, processing plants, utility buildings, and other industrial structures where durable, high-quality interior finishing and fire-resistant building materials are required.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Construction Demand Base Layer
What forms the demand base?
Identify the global demand generated by residential, commercial, and industrial construction activities requiring interior wall and ceiling finishing materials. This layer establishes the total addressable market based on new construction projects, renovation and remodeling activities, urbanization, infrastructure investments, housing developments, and the growing adoption of modern construction materials across developed and emerging economies.
02
Gypsum Plaster Adoption Layer
Where is gypsum plaster utilized?
Estimate the adoption of gypsum plaster across major end-use sectors, including residential, commercial, and industrial construction. Assess the penetration of manually-applied plaster, machine-applied plaster, and finishing plasters based on construction methods, project scale, labor availability, building specifications, fire safety requirements, and demand for faster and high-quality interior finishing solutions.
03
Plaster Consumption Intensity Layer
How much gypsum plaster is utilized?
Analyze the volume of gypsum plaster consumed based on building floor area, construction frequency, renovation cycles, application thickness, project type, and interior finishing requirements. Plaster consumption is influenced by building design, construction techniques, labor efficiency, adoption of mechanized plastering systems, and increasing demand for lightweight, crack-resistant, and moisture-resistant gypsum plaster products.
04
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of gypsum plaster products manufactured from natural gypsum and synthetic gypsum, including manually-applied plaster, machine-applied plaster, and finishing plaster systems. Revenue is generated from demand across residential, commercial, and industrial construction projects, renovation activities, infrastructure developments, and sales through building material distributors, contractors, developers, and construction companies seeking efficient, high-quality, and durable interior finishing solutions.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Detailed regional analysis of the Gypsum Plaster Market across North America, Europe, Asia Pacific, Central & South America, and the Middle East & Africa. Includes market size, revenue forecasts, construction activity trends, raw material availability, demand drivers, regulatory landscape, and growth opportunities by country and region.
Enables identification of high-growth regional markets, supports geographic expansion strategies, optimizes resource allocation, and assists in prioritizing investments based on regional demand and construction activity.
Competitive Benchmarking
Comprehensive benchmarking of leading gypsum plaster manufacturers based on product portfolio, production capacity, raw material sourcing, geographic presence, manufacturing capabilities, sustainability initiatives, strategic partnerships, mergers & acquisitions, distribution network, and innovation pipeline.
Helps evaluate competitive positioning, identify market gaps and best practices, support strategic planning, and benchmark organizational capabilities against leading industry participants.
Pricing Analysis
In-depth pricing analysis of gypsum plaster products across raw materials (natural gypsum and synthetic gypsum), plaster systems (manually-applied plaster, machine-applied plaster, and finishes), and major regional markets. Includes raw material cost trends, manufacturing cost structure, regional price variations, and competitive price comparisons.
Supports pricing optimization, procurement planning, supplier evaluation, cost competitiveness analysis, and informed decision-making for product positioning, contract negotiations, and long-term sourcing strategies.
Frequently Asked Questions About This Report
Asia Pacific dominated the gypsum plaster market with a revenue share of 46.9% in 2025.
Middle East & Africa is the fastest-growing region in the gypsum plaster market, registering a CAGR of 7.8% over the forecast period.
The manually-applied Plaster segment led the gypsum plaster market with a revenue share of 43.2% in 2025, supported by its extensive adoption in residential construction, renovation projects, and regions with high availability of skilled manual labor.
Key players in the gypsum plaster market include Saint-Gobain, Knauf Gips KG, Global Gypsum Company Co. LTD, Escayescos, SL, USG Corporation, James Hardie Industries plc, Georgia-Pacific Gypsum II LLC, YOSHINO GYPSUM CO., LTD, Vg-orth GmbH & Co. KG, and LA MARUXIÑA.
The gypsum plaster market is primarily driven by rapid urbanization, increasing residential and commercial construction activities, growing demand for lightweight and fire-resistant building materials, rising adoption of machine-applied plaster systems, and expanding investments in infrastructure development and sustainable construction practices.
The global gypsum plaster market was valued at USD 3.6 billion in 2025 and is estimated to reach USD 3.8 billion in 2026.
The global gypsum plaster market is expected to grow at a CAGR of 6.0% from 2026 to 2033, reaching USD 5.8 billion by 2033.
The natural gypsum segment led the gypsum plaster market with a revenue share of 67.6% in 2025, driven by its abundant availability, established supply chain, and widespread use in residential and commercial construction projects.
The synthetic gypsum segment is expected to be the fastest-growing raw material segment in the gypsum plaster market, owing to increasing adoption of sustainable construction materials, improved product consistency, and greater utilization of industrial byproducts in gypsum production.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


