
- Home
- »
- Beauty & Personal Care
- »
-
Hair And Scalp Care Market Size & Share Report, 2026-2033GVR Report cover

Hair And Scalp Care Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Shampoo, Conditioner, Hair Oils, Hair Serums, Masks & Treatments), By Concern, By Hair Type, By Price Tier, By End Use, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$88.2BMarket Estimate, 2026
$93.6BMarket Forecast, 2033
$150.5BCAGR, 2026–2033
7.0%Hair And Scalp Care Market Summary
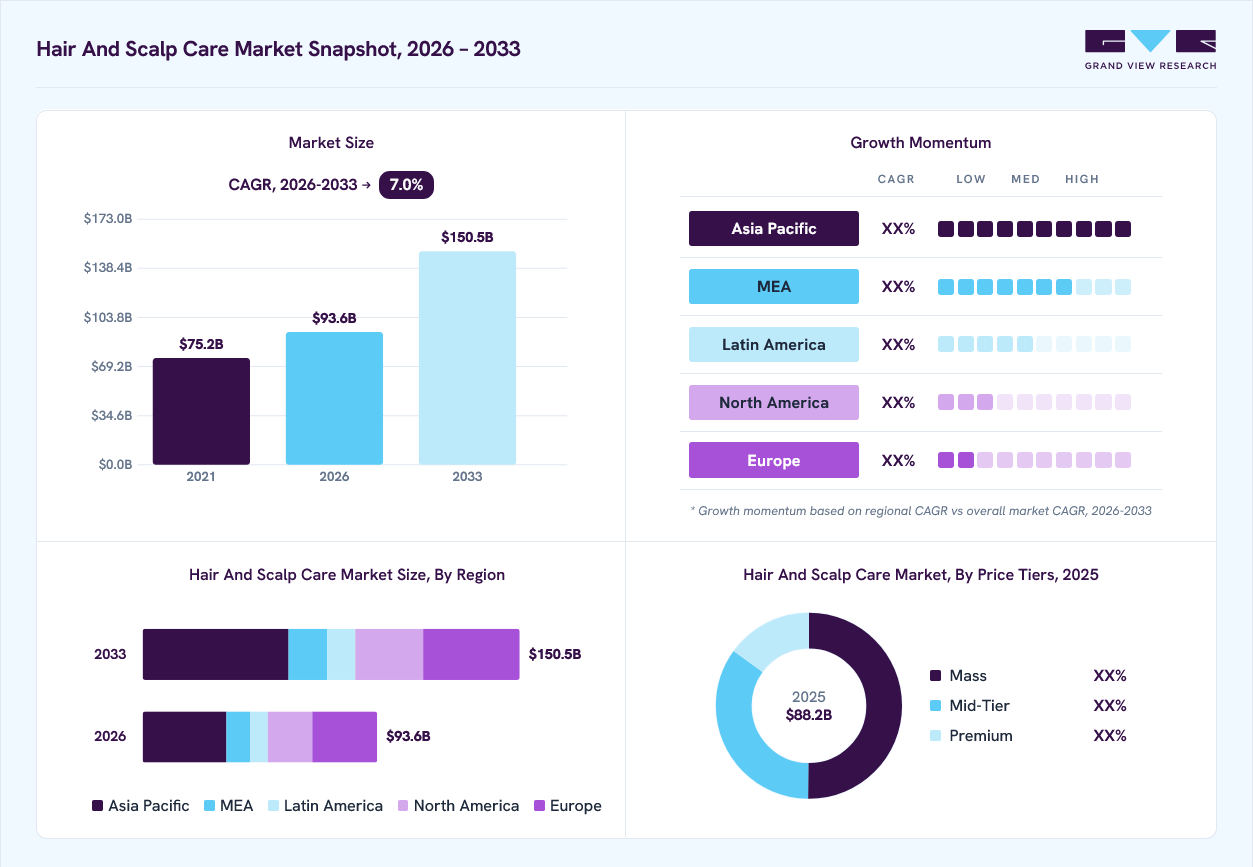
The global hair and scalp care market size was valued at USD 88.2 billion in 2025 and is projected to grow from USD 93.6 billion in 2026 to USD 150.5 billion by 2033, growing at a CAGR of 7.0% from 2026 to 2033. The Asia Pacific market held the largest share of 35.3% of the global market in 2025. The increasing prevalence of hair and scalp issues, such as dandruff, hair loss, and dryness, has driven demand for specialized care products.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The shampoo segment led the market with the largest revenue share of 39.80% in 2025.
- By concern: The oily and greasy scalp segment led the market with the largest revenue share of 29.43% in 2025
Regional Highlights
- Largest regional market: Asia Pacific (35.3% revenue share, 2025)
- By country: China accounted for dominating revenue share of the Asia Pacific sodium sulfate market in 2025.
Market Size & Forecast
- Market size in 2025: USD 88.2 Billion
- Estimated market size in 2026: USD 93.6 Billion
- Projected market size by 2033: USD 150.5 Billion
- CAGR (2026-2033): 7.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The rising concerns, such as hair fall, dandruff, scalp sensitivity, premature greying, and thinning hair across all age groups, increasingly drive the global hair and scalp care industry’s growth. Urban lifestyles, rising stress levels, exposure to pollution, hard water use, and changing dietary patterns have intensified scalp-related problems, prompting consumers to seek targeted treatment-oriented products rather than basic cleansing solutions. This shift has supported demand for anti-dandruff shampoos, scalp serums, hair growth solutions, and dermatologically tested formulations. Manufacturers are responding by expanding problem-solution portfolios, including sulfate-free, pH-balanced, and ingredient-focused products designed to address specific scalp conditions, thereby strengthening repeat purchase behavior and long-term brand loyalty.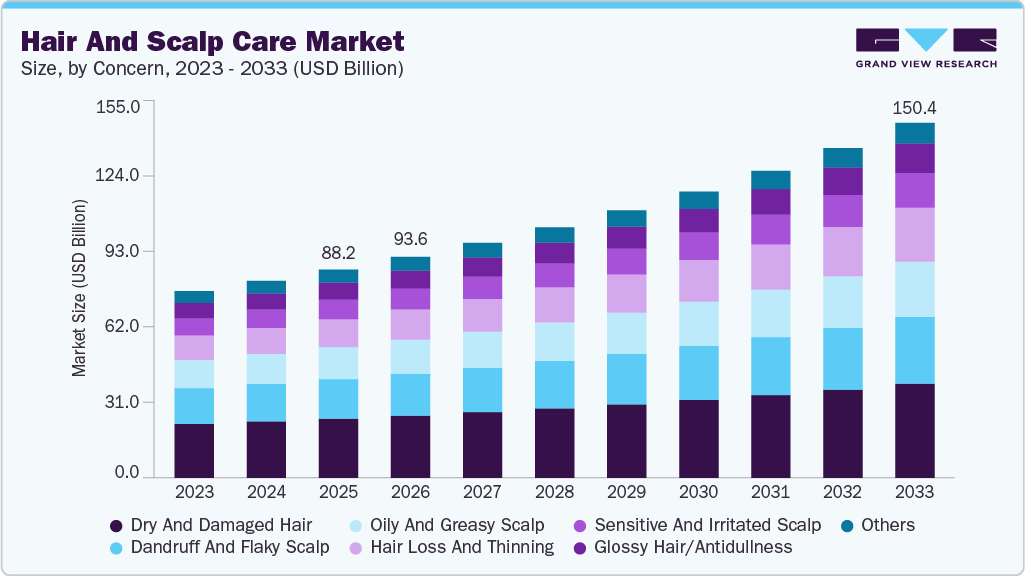 To learn more about this report, Download Free Sample Report
For instance, in February 2025, Head & Shoulders upgraded shampoo and conditioner collections designed to address different scalp and hair needs rather than relying on a single universal formula. The new ranges combine the brand’s core anti-dandruff performance with enhanced conditioning, improved sensory appeal, and targeted benefits tailored to specific hair types. This update reflects a broader shift toward more personalized hair care solutions that balance scalp health with everyday hair concerns.
Social media platforms and digital beauty content have become powerful demand drivers in the global hair and scalp care market, significantly shaping consumer awareness and purchase decisions. Tutorials, product reviews, influencer-led routines, and before-and-after transformations on platforms such as Instagram, YouTube, and TikTok have normalized scalp care as an extension of skincare. Consumers are increasingly educated about ingredients, formulations, and scalp health benefits, accelerating interest in exfoliating scrubs, scalp masks, pre-wash oils, and treatment serums. Celebrity endorsements and influencer collaborations further amplify product visibility, enabling brands to rapidly scale new launches, test niche formulations, and align offerings with evolving beauty trends across millennial and Gen Z consumers.
The rapid expansion of e-commerce has significantly enhanced accessibility and market penetration for hair and scalp care products globally. Online platforms enable consumers to compare formulations, read verified reviews, and access a wider range of premium, professional, and niche brands that may not be available through traditional retail channels. Subscription models, personalized product recommendations, and direct-to-consumer strategies have further supported market growth by improving convenience and repeat engagement.
Market Dynamics
The hair & scalp care market is witnessing strong expansion driven by increasing consumer awareness of scalp health as a foundation for overall hair quality. The category has evolved beyond traditional shampoos and conditioners to include targeted solutions such as scalp serums, exfoliating treatments, anti-dandruff formulations, hair growth stimulants, and microbiome-balancing products. Rising concerns related to pollution exposure, stress-induced hair loss, hormonal imbalance, and lifestyle-related scalp disorders are reshaping consumer preferences toward preventive and treatment-oriented hair care routines. Additionally, premiumization trends, ingredient transparency, and the influence of dermatology-backed formulations are significantly strengthening market adoption across both mass and premium segments.
The increasing incidence of hair thinning, dandruff, seborrheic dermatitis, and premature hair loss is a major driver of the hair & scalp care market. Factors such as urban pollution, water quality deterioration, high stress levels, irregular sleep patterns, nutritional deficiencies, and excessive use of chemical-based styling products are contributing to deteriorating scalp health globally. In particular, androgenic alopecia and stress-related telogen effluvium are becoming more common across younger populations, expanding the consumer base beyond traditionally older demographics.
Additionally, hormonal fluctuations, post-pregnancy hair fall, and age-related follicle weakening are further accelerating demand for targeted scalp treatments. According to dermatological observations, hair loss-related concerns affect a significant portion of the adult population worldwide, with increasing cases reported in both men and women under the age of 35. This rising burden is prompting consumers to adopt preventive scalp care routines and invest in specialized products that focus on follicle strengthening, scalp microbiome balance, and long-term hair density improvement.
Despite strong demand, the hair & scalp care market faces challenges related to inconsistent product efficacy and high market fragmentation. A large number of products make exaggerated claims regarding hair regrowth, dandruff elimination, or scalp detoxification, leading to consumer skepticism and reduced brand trust. Many over-the-counter formulations provide temporary cosmetic improvement rather than clinically validated long-term results, creating dissatisfaction among users.
In addition, the market is highly saturated with both global and local brands offering similar formulations, making differentiation difficult. This intense competition often results in pricing pressure and heavy reliance on marketing-driven positioning rather than product innovation. Consumers are also becoming increasingly cautious about ingredient safety, particularly concerning sulfates, parabens, silicones, and synthetic fragrances, which may limit adoption of conventional formulations and slow repeat purchases in certain segments.
The increasing shift toward science-backed and personalized hair care solutions presents a major growth opportunity in the market. Consumers are increasingly seeking dermatologist-developed, clinically tested, and ingredient-transparent products that address specific concerns such as hair thinning, scalp inflammation, and microbiome imbalance. This has accelerated demand for active ingredient-based formulations such as peptides, niacinamide, salicylic acid, and botanical extracts designed for targeted scalp repair and follicle stimulation.
Technological advancements in digital diagnostics, AI-driven hair analysis, and at-home scalp assessment tools are enabling brands to offer personalized treatment regimens tailored to individual hair conditions. Additionally, the rising popularity of clean beauty, vegan formulations, and sustainable packaging is encouraging innovation in eco-friendly product development. The expansion of e-commerce and direct-to-consumer channels is further improving accessibility, allowing niche and specialized brands to scale rapidly while addressing evolving consumer expectations for customized, results-driven scalp care solutions.
Analyst Perspective
The Hair & Scalp Care market is increasingly being driven by a “scalp-first” shift, where scalp health is treated as the primary driver of hair outcomes rather than just cosmetic repair. Demand is rising for dermo-cosmetic formulations targeting microbiome balance, dandruff recurrence, and follicle strengthening, especially in urban Asia-Pacific markets. Anti-hairfall and regrowth segments are expanding faster than traditional conditioning, fueled by stress-related alopecia and pollution exposure. Premiumization is evident through salon-grade serums and probiotic scalp treatments. Brands are also integrating AI-based scalp diagnostics and personalized regimens via D2C channels, reducing reliance on one-size-fits-all shampoo-centric routines. Consumer loyalty is increasingly efficacy-led.
Brand Market Share Insights
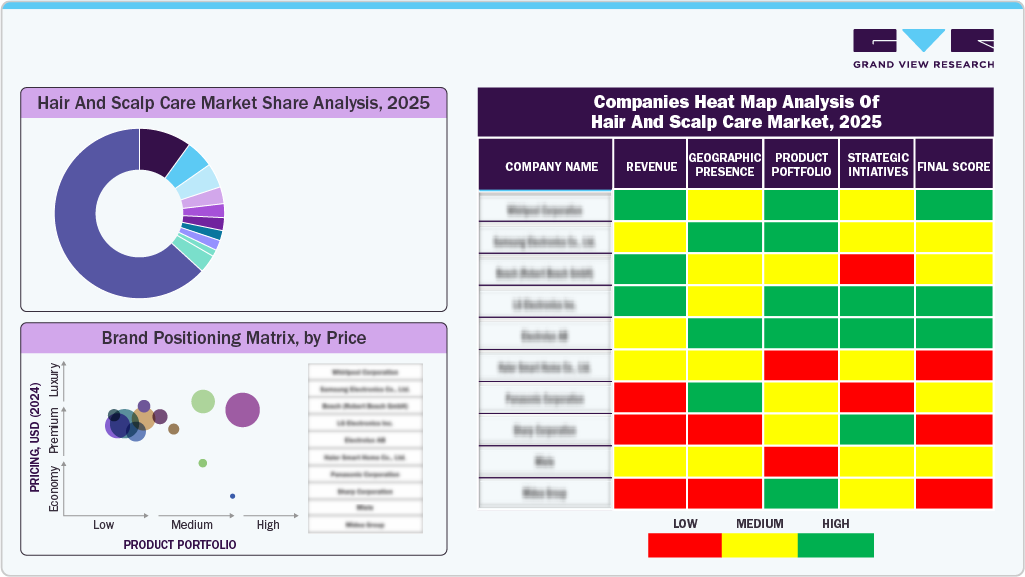
The global hair and scalp care market is shaped by a mix of large multinational beauty companies and a rapidly expanding set of niche, premium, and digital-first brands, all competing to meet rising consumer expectations around efficacy, ingredient quality, personalization, and brand credibility. Market participants are increasingly prioritizing advanced formulation development, with greater emphasis on ingredient transparency, clean-label positioning, sustainably sourced actives, and science-backed scalp solutions. Alongside this, brands are broadening their portfolios to include targeted treatments, dermatological-grade products, multifunctional formats, and trial or travel-sized offerings to improve consumer adoption and repeat usage. Omnichannel strategies, including direct-to-consumer platforms and robust e-commerce integration, are being leveraged to expand reach, enhance consumer engagement, and capture real-time feedback.
 To learn more about this report, Download Free Sample Report
Consumer Insights
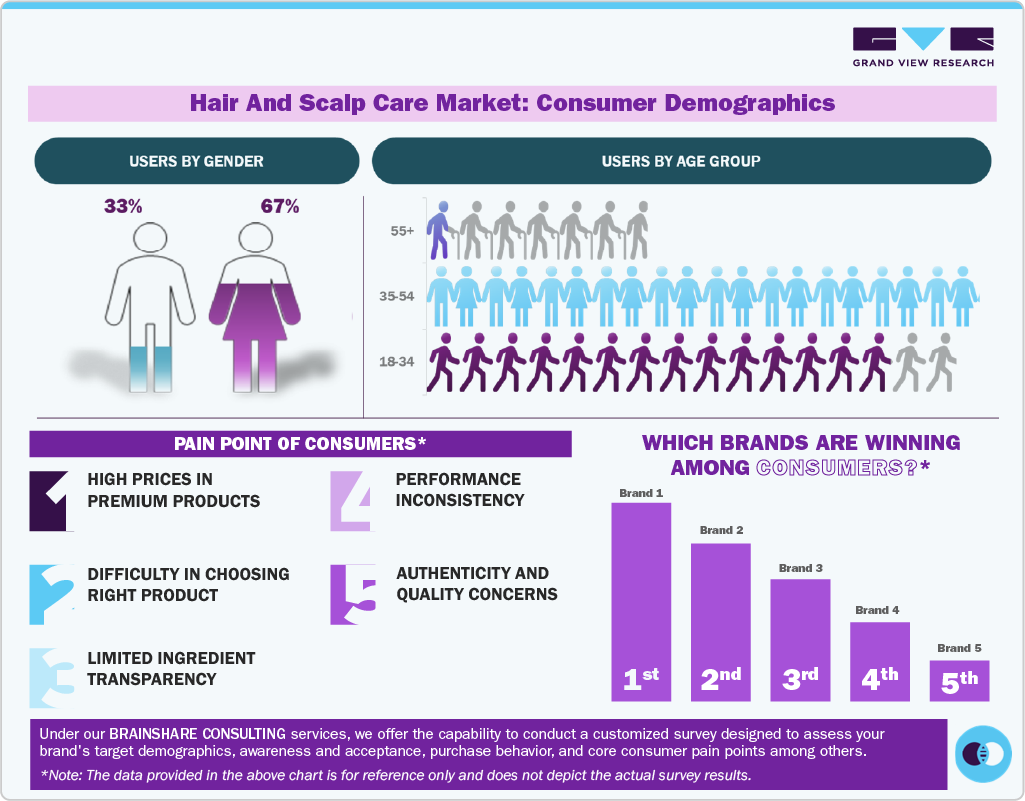
According to a YouGov survey conducted in August 2025, hair and scalp care engagement varies significantly across age groups, highlighting noticeable behavioural differences among global consumers. Among adults aged 18-34, nearly 9 in 10 regularly use shampoo or conditioner, with about 23% using hair oil and 25% using serums or masks, indicating a stronger inclination toward experimentation and multi-product routines. In contrast, older demographics tend to have simpler routines. Adults aged 55 and above report using only 11% of serums/masks, suggesting that younger consumers are more open to trying targeted treatments and diversified product formats to address specific concerns and lifestyle aspirations. This pattern reflects a broader global trend of younger cohorts increasingly willing to explore specialized hair and scalp solutions beyond basic cleansing.
 To learn more about this report, Download Free Sample Report
Consumer motivations in hair care are also shaped by emotional and experiential associations, rather than functional need alone. The same YouGov survey reveals that 66% of Americans cite hygiene and upkeep as key reasons for hair care, but women are notably more likely than men to link hair routines to confidence and appearance goals (72% vs. 42%). Furthermore, the average consumer stays within modest spending brackets: 42 % report a monthly hair care spend of USD 1-50, and only 5 % are willing to spend USD 100 or more, indicating cautious investment even among engaged users. These data highlight how consumers balance routine demands with personal values such as confidence enhancement, wellness, and sensory experience, which, in turn, shape global brand engagement and purchase behaviour.
Broader consumer sentiment data from Revuze’s analysis of over 1.2 million haircare product reviews underscores the growing importance of product attributes tied to experience and performance; fragrance and scent were among the top drivers of satisfaction, while demand for hydration-focused products and natural, chemical-free ingredients also showed significant year-over-year growth. This points to an evolving market where consumers, particularly digital-savvy younger cohorts, seek products that deliver both sensory appeal and tangible benefits, increasingly informed by peer reviews, online discovery, and social influence rather than traditional advertising alone.
Product Insights
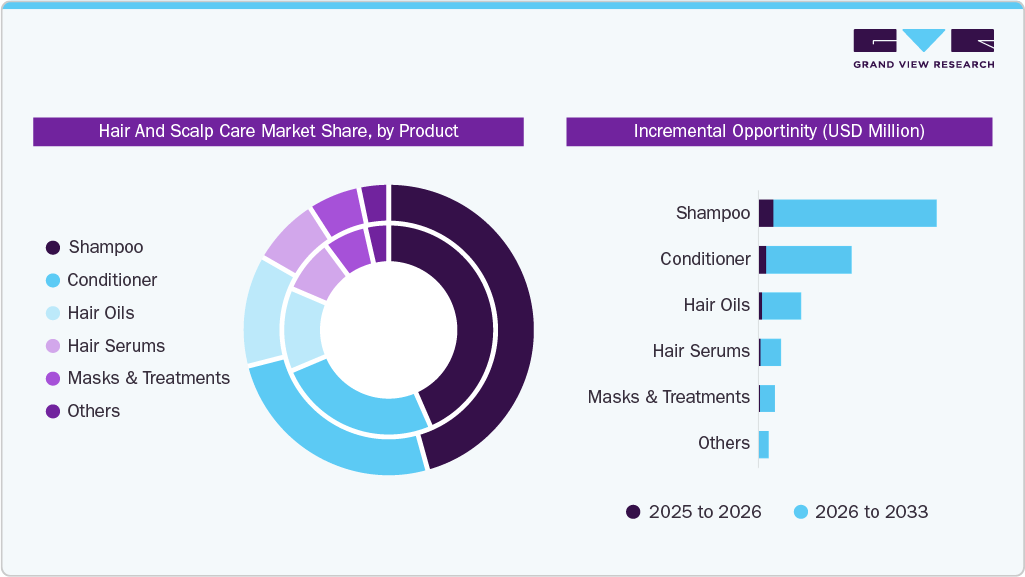
Based on product, the shampoo segment led the market with the largest revenue share of 39.80% in 2025 and is expected to grow at the fastest CAGR over the forecast period, driven by its essential role in daily hair hygiene and scalp maintenance. Consumers increasingly view shampoos as targeted treatment solutions rather than basic cleansing products, driving demand for formulations addressing concerns such as dandruff, hair fall, scalp sensitivity, dryness, and excess oil production. The growing popularity of specialized, sulfate-free, medicated, natural, and dermatologist-recommended shampoos has further expanded the segment’s consumer base. In addition, rising awareness of scalp health, increasing product innovation, and the introduction of premium and personalized hair care solutions continue to support strong market penetration. The segment is also benefiting from widespread retail availability and recurring purchase behavior, reinforcing its dominant position and expected high growth rate during the forecast period.
 To learn more about this report, Download Free Sample Report
The demand for hair conditioner is expected to grow at a CAGR of 7.1% from 2026 to 2033. Demand is expanding beyond basic moisturizing conditioners toward products offering richer textures, longer-lasting fragrances, and targeted benefits such as smoothening, strengthening, and scalp comfort. While conditioners were traditionally positioned in the premium segment due to higher concentrations of conditioning agents and oils, manufacturers are increasingly broadening their appeal through affordable formulations, simplified fragrance profiles, and smaller pack sizes.
Concern Insights
Based on concern, the oily and greasy scalp segment led the market with the largest revenue share of 29.43% in 2025, due to the high prevalence of excess sebum production across diverse age groups and climatic regions. Factors such as hormonal fluctuations, environmental pollution, humid weather conditions, stress, and lifestyle changes have contributed to an increasing number of consumers experiencing oily scalp-related issues. Excess oil often leads to concerns including dandruff, scalp irritation, itchiness, and hair thinning, prompting consumers to seek specialized treatment products. As a result, demand for oil-control shampoos, scalp exfoliators, clarifying treatments, and balancing scalp serums has increased significantly. Growing consumer awareness regarding the link between scalp health and overall hair quality continues to drive product adoption, supporting the segment’s leading market position.
Hair and scalp care products used for hair loss and thinning are expected to grow at a CAGR of 8.6% from 2026 to 2033, driven by the increasing incidence of stress-related hair fall, hormonal imbalance, nutritional deficiencies, and lifestyle changes across both men and women. Consumers are increasingly seeking targeted, treatment-led solutions rather than cosmetic coverage, supporting demand for anti-hair fall shampoos, scalp serums, growth tonics, and leave-in treatments formulated with actives such as caffeine, biotin, niacinamide, peptides, plant stem cells, and clinically tested botanical extracts.
Hair Type Insights
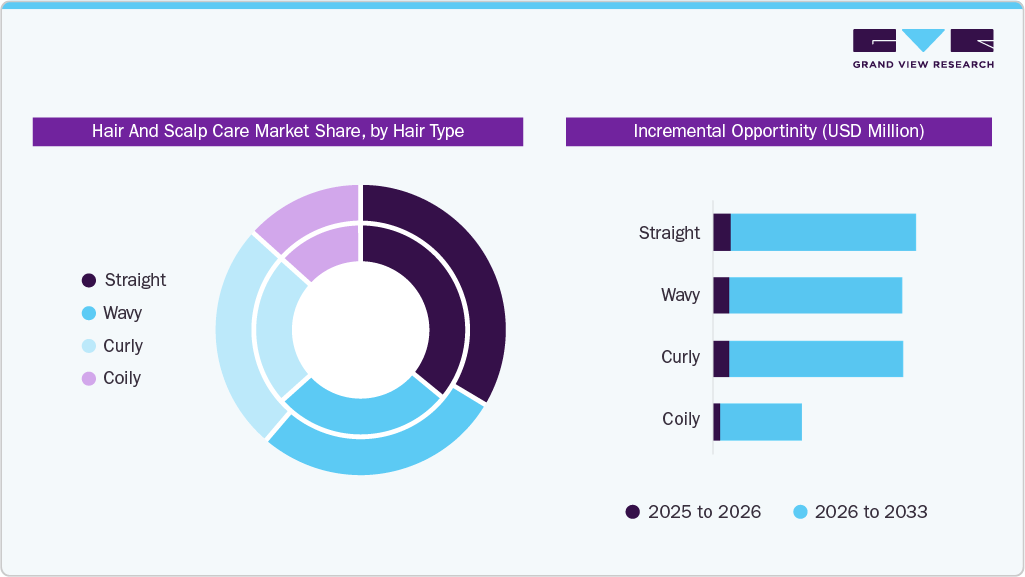
Hair and scalp care products for straight hair led the industry, accounting for the largest revenue share of 35.99% in 2025. Consumers increasingly favor straight-hair-specific formulations over general-purpose products, supporting demand for shampoos, conditioners, masks, oils, and leave-in treatments designed to preserve smoothness, enhance shine, and control frizz without adding excess weight. The growth is strongly supported by premium offerings that emphasize advanced smoothing and protection technologies, long-term hair health, and refined fragrances combined with sensorial textures.
 To learn more about this report, Download Free Sample Report
Hair and scalp care products used for curly hair are expected to grow at a CAGR of 8.1% from 2026 to 2033. Curly hair requires higher levels of hydration and structural support due to its coiled pattern, driving demand for specialized shampoos, co-washes, conditioners, curl creams, gels, and leave-in treatments that enhance definition while minimizing frizz and breakage. Consumers increasingly prefer formulations enriched with humectants, natural butters, lightweight oils, and protein-balancing complexes that support curl elasticity without stiffness or buildup.
End Use Insights
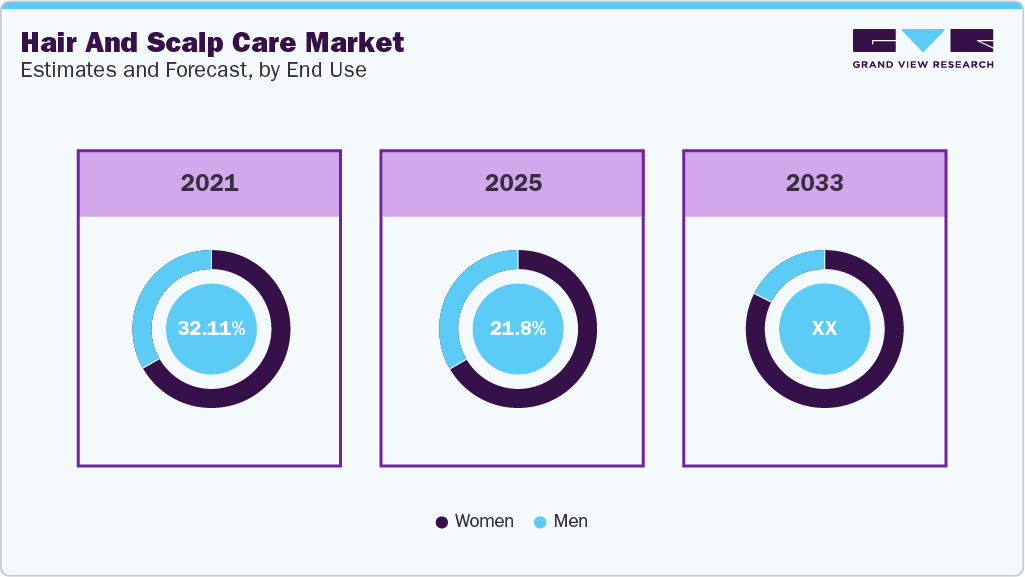
The women's end-use segment led the hair and scalp care market, accounting for the largest revenue share of 66.89% in 2025. Women tend to adopt preventive and corrective hair care practices earlier and more frequently, driving sustained demand for cleansing, conditioning, repair, and scalp-focused products. Purchasing decisions in this segment are strongly influenced by product efficacy, sensory attributes such as fragrance and texture, and alignment with individual hair needs and lifestyle preferences. In addition, increased awareness of hair health, greater access to premium and dermatologist-backed products, and growing acceptance of tailored solutions continue to support higher spending.
 To learn more about this report, Download Free Sample Report
The men’s end-use segment is expected to grow at a CAGR of 7.8% from 2026 to 2033. Men are progressively shifting from basic shampoo usage toward targeted solutions addressing concerns such as hair fall, dandruff, scalp irritation, and premature thinning. Growing interest in premium grooming, evolving lifestyle patterns, and greater exposure to digital content have encouraged experimentation with different formulations, fragrances, and treatment-led products. In addition, strong visibility of male grooming through celebrity endorsements, sports personalities, and social media influencers continues to normalize the use of advanced hair and scalp care products.
Price Tier Insights
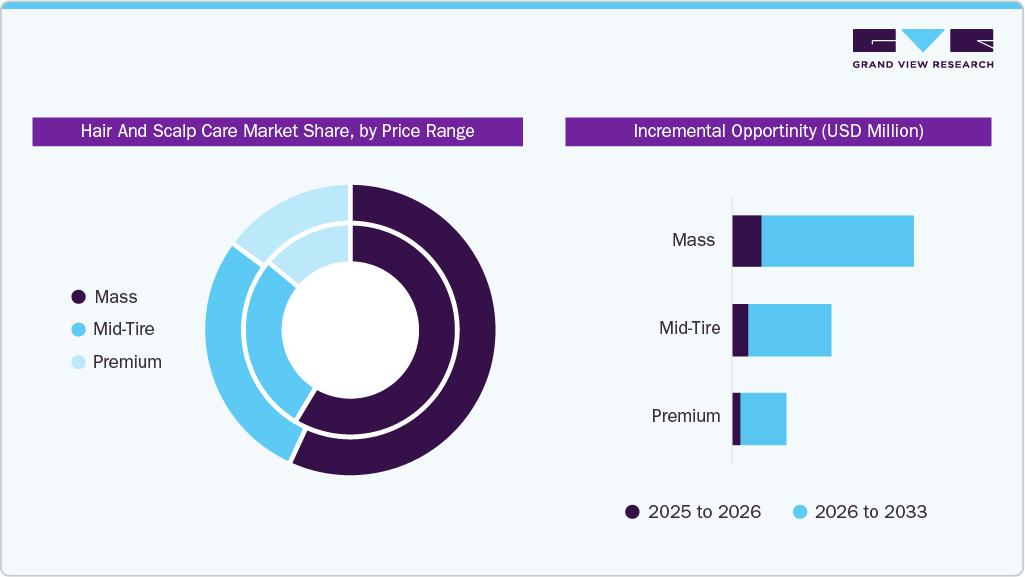
Mass hair and scalp care products accounted for the largest share of 58.63% in 2025. Consumers favor mass hair and scalp care products for their practicality, versatility, and ease of incorporation into regular routines, supported by familiar formulations, mild fragrances, and multiple usage formats. High availability across retail and e-commerce channels, along with frequent product replenishment cycles, continues to drive repeat purchases and reinforces the dominant revenue contribution of the mass segment within the global hair and scalp care market.
 To learn more about this report, Download Free Sample Report
Premium hair and scalp care products are expected to grow at a CAGR of 7.9% from 2026 to 2033, driven by rising consumer preference for high-quality formulations that balance performance, sensory appeal, and brand value without entering ultra-luxury price tiers. This segment attracts brand-conscious, quality-driven consumers who seek noticeable improvements in hair and scalp health alongside refined fragrances and elevated usage experiences. Premium products are increasingly favored for personal upgrades, gifting, and occasion-led purchases, supported by a strong emphasis on packaging design and ingredient sophistication.
Distribution Channel Insights
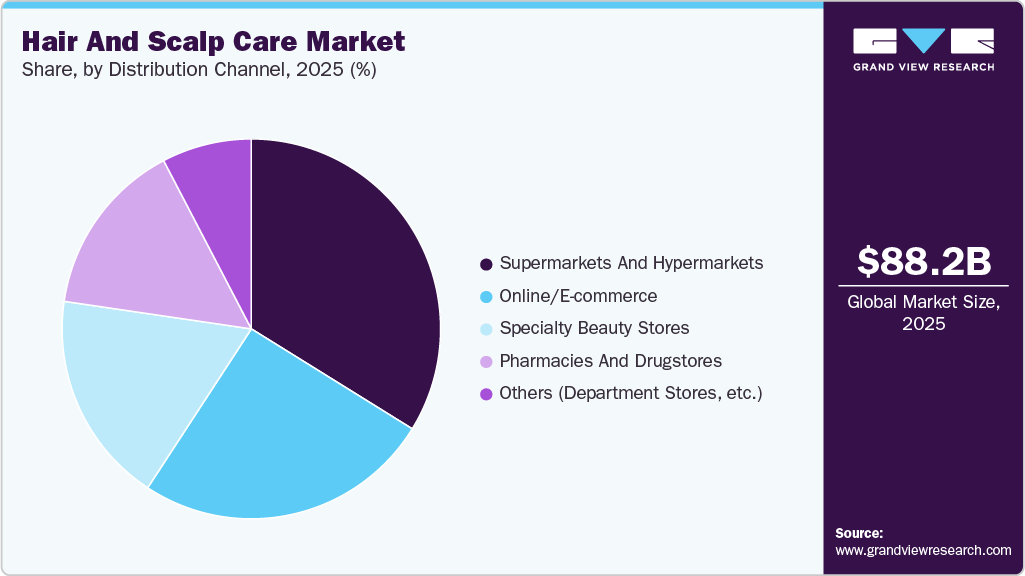
Sales of hair and scalp care products through supermarkets and hypermarkets accounted for the largest share of 33.82% in 2025, supported by their extensive reach, convenience-driven shopping behavior, and strong dominance in everyday personal care purchasing. These outlets serve as primary touchpoints for routine replenishment, enabling consumers to easily access a wide range of mass and mid-priced hair and scalp care products under one roof. High shelf visibility, frequent price promotions, and multi-pack or value-based offerings encourage brand switching and repeat purchases.
Sale of hair and scalp care products through online/e-commerce is expected to grow at a CAGR of 8.2% from 2026 to 2033. Consumers are using online platforms to access a wider variety of hair and scalp care products, including dermatologist-recommended, premium, and niche formulations that are often unavailable in physical retail. Detailed ingredient disclosures, user reviews, tutorial content, and algorithm-based recommendations are helping shoppers make informed purchase decisions despite the lack of physical product testing. In addition, the rise of mobile commerce, subscription-based replenishment models, and direct-to-consumer brand websites is strengthening repeat purchases. Rapid growth in internet penetration and digital payment adoption across emerging economies continues to accelerate online sales.
Regional Insights
The North America hair and scalp care industry accounted for the largest share of 25.63% in 2025. Consumers in the region actively invest in solutions addressing concerns such as hair fall, scalp sensitivity, color protection, and damage repair, supporting demand for shampoos, conditioners, masks, serums, and scalp treatments with clinically backed, clean-label positioning. The market benefits from a well-developed distribution infrastructure, with specialty beauty retailers, salons, and e-commerce platforms enabling access to a wide range of mass, premium, and professional brands.
 To learn more about this report, Download Free Sample Report
U.S. Hair and Scalp Care Market Trends
The hair and scalp care industry in the U.S. is supported by high consumer awareness of hair health, strong discretionary spending, and a well-established culture of routine and treatment-led grooming. U.S. consumers actively invest in products targeting concerns such as hair fall, scalp sensitivity, color protection, and damage from frequent heat styling and chemical treatments. Demand is particularly strong for shampoos, conditioners, and scalp treatments positioned around clean ingredients, dermatologist-backed claims, and sensorial appeal, including refined fragrances and lightweight textures.
Europe Hair and Scalp Care Market Trends
The Europe hair and scalp care industry accounted for the largest revenue share of 22.57% in 2025. European consumers demonstrate high awareness of hair health and ingredient sourcing, driving demand for clean-label, dermatologically tested, and sustainably formulated shampoos, conditioners, and scalp treatments. The market shows pronounced premium and niche penetration, with consumers valuing sensorial attributes such as refined fragrances, texture, and packaging alongside functional benefits.
The growth of the hair and scalp care market in the UK is driven by strong consumer focus on personal grooming, wellness, and product quality, supported by high awareness of hair health and ingredient safety. Demand is increasingly shaped by interest in premium and wellness-oriented formulations that combine functional benefits with refined sensory experiences, including mild fragrances and nourishing textures.
The France hair and scalp care market held the largest share of Europe in 2025, characterized by strong consumer emphasis on formulation quality, sensorial performance, and premium positioning, reflecting the country’s deep-rooted beauty and fragrance culture. French consumers show high awareness of ingredient provenance, safety standards, and product craftsmanship, driving demand for clean-label, dermatologically tested, and sustainably formulated hair and scalp solutions.
Asia Pacific Hair and Scalp Care Market Trends
Asia Pacific dominated the hair and scalp care market with the largest revenue share of 35.3% in 2025. It remains the largest market for hair and scalp care products due to its large population base, increasing beauty and personal care expenditure, and strong cultural emphasis on hair health. Consumers across countries such as China, India, Japan, and South Korea are increasingly adopting specialized products targeting concerns such as hair loss, dandruff, scalp sensitivity, premature greying, and pollution-induced hair damage. The region has also witnessed growing demand for herbal, natural, and ingredient-focused formulations containing botanicals, oils, peptides, and scalp-nourishing actives. Furthermore, rapid urbanization, rising disposable incomes, expanding e-commerce penetration, and the growing influence of social media beauty trends have accelerated product awareness and accessibility. The increasing popularity of scalp-focused treatments and preventive hair care routines is expected to continue supporting market growth across the region.
China Hair and Scalp Care Market Trends
The hair and scalp care market in the China held the largest share of about 25.7% in the Asia Pacific region in 2025, due to its sizable consumer base, increasing spending on premium personal care products, and growing awareness of scalp wellness as an integral part of overall beauty routines. Rising concerns related to hair thinning, stress-induced hair loss, environmental pollution, and aging have significantly increased demand for specialized scalp treatments, anti-hair loss shampoos, serums, and functional hair care products. Chinese consumers are increasingly favoring premium and efficacy-driven formulations that combine traditional botanical ingredients with advanced dermatological technologies. Furthermore, the rapid growth of digital commerce platforms, livestream shopping, and social commerce has enabled brands to reach a broader audience and accelerate product penetration. The market is also benefiting from the growing popularity of personalized beauty solutions and professional scalp-care services offered through salons and specialized hair clinics.
The India hair and scalp care market is expected to witness growth, driven by rising consumer demand for luxury and premium fragrances. Increasing disposable incomes and growing awareness of global fragrance trends are contributing to the product demand. Al Abbadi Fragrances launched its exclusive luxury collection in New Delhi in September 2025, offering artisan-crafted, limited-edition perfumes with 18-24 hours of longevity.
Central & South America Hair and Scalp Care Market Trends
The Central & South America hair and scalp care industry is expected to grow at a CAGR of 7.2% from 2026 to 2033. The market growth is driven by high daily use of hair care products, favorable climate conditions, strong appearance-conscious grooming habits, and frequent washing routines. Consumers in the region actively seek solutions for concerns such as dryness, frizz, hair fall, and damage caused by humidity, sun exposure, and chemical treatments, supporting demand for nourishing shampoos, conditioners, oils, and leave-in products.
Middle East & Africa Hair and Scalp Care Market Trends
The Middle East & Africa hair and scalp care industry is expected to grow at a CAGR of 5.4% from 2026 to 2033. High temperatures, low humidity, and frequent sun exposure increase the need for intensive nourishment, scalp hydration, and damage-repair solutions, driving demand for oils, masks, serums, and conditioning treatments. Consumers in the region place strong value on product richness, longevity, and sensorial experience, supporting higher adoption of premium and concentrated formulations.
Key Hair And Scalp Care Companies:
The following key companies have been profiled for this study on the hair and scalp care market.
-
L’Oréal S.A.
-
Johnson & Johnson Services, Inc.
-
Beiersdorf
-
Procter & Gamble
-
Unilever
-
AMOREPACIFIC US, INC.
-
The Estée Lauder Companies Inc.
-
Kanebo Cosmetics Inc.
-
Himalaya Global Holdings Ltd
-
Shiseido Company, Limited
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (L’Oréal S.A.; Procter & Gamble; Unilever; Kao Corporation; Amorepacific Corporation; Kenvue)
- Expand scalp-focused product portfolios across anti-dandruff, hair loss, scalp hydration, sensitive scalp, and damage repair categories through continuous R&D and dermatological research.
- Strengthen omnichannel distribution through mass retail, salons, pharmacies, e-commerce, and professional haircare networks while investing in premiumization, personalized haircare, and scalp diagnostic technologies.
- Strong brand equity, extensive global distribution, and diversified portfolios spanning mass-market, premium, professional, and dermatological haircare segments.
- Significant R&D capabilities, consumer insights, and marketing resources enable rapid commercialization of innovative scalp-care and hair wellness solutions.
- High operational and marketing costs associated with maintaining global brand portfolios and distribution networks.
- Slower decision-making and reduced agility compared to emerging specialist brands targeting rapidly evolving consumer trends and niche scalp concerns.
Emerging & Specialized Players (Shiseido Company, Limited; Beiersdorf; The Estée Lauder Companies Inc.; LVMH)
- Focus on premium scalp wellness, dermatology-driven formulations, ingredient-led innovation, and prestige beauty positioning to capture high-value consumer segments.
- Leverage strong skincare expertise, luxury branding, and targeted product launches addressing scalp health, hair thinning, sensitivity, and healthy-aging hair concerns.
- Strong consumer trust in skin health, beauty science, and premium personal care categories, enabling expansion into scalp-care adjacencies.
- Ability to capitalize on the growing "skinification of haircare" trend through clinically backed ingredients, premium formulations, and differentiated brand positioning.
- Relatively narrower haircare portfolios and lower scale in hair-specific categories compared with global haircare leaders.
- Dependence on premium consumer spending and limited presence in mass-market haircare channels can constrain volume growth in price-sensitive markets.
Recent Developments
-
In February 2026, Mielle introduced a new scalp-focused collection created to support natural hair textures and protective styling routines. The range emphasizes scalp comfort and moisture balance, helping address dryness and irritation that can occur with long-term styling. The launch reinforces Mielle’s focus on targeted scalp care as an essential part of maintaining healthy hair rather than treating scalp needs as an afterthought.
-
In July 2025, Root Botanié launched India’s first haircare brand focused on gender-specific scalp microbiome solutions tailored for urban lifestyles. The brand centers on scalp health as the foundation for stronger hair, with separate formulations designed to address the differing concerns of men and women. By combining botanical ingredients with modern scientific approaches, the range targets issues linked to pollution, stress, and daily urban exposure, positioning itself as a personalized hair wellness offering rather than a conventional cosmetic care product.
Hair and Scalp Care Market Report Scope
Report Attribute
Details
Market size in 2025
USD 88.2 billion
Estimated market size in 2026
USD 93.6 billion
Projected market size by 2033
USD 150.5 billion
Growth rate
CAGR of 7.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, concern, hair type, end use, price tier, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Rest of Europe; China; Japan; India; Australia & New Zealand; South Korea; Rest of APAC; Brazil; Rest of CSA; South Africa; Rest of MEA
Key companies profiled
L’Oréal S.A.; Kenvue; Beiersdorf; Procter & Gamble; Unilever; Amorepacific Corporation; The Estée Lauder Companies Inc.; Kao Corporation; Shiseido Company, Limited; LMVH
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Hair and Scalp Care Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global hair and scalp care market report based on product, concern, hair type, end use, price tier, distribution channel, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Shampoo
-
Conditioner
-
Hair Oils
-
Hair Serums
-
Masks and Treatments
-
Others
-
-
Concern Outlook (Revenue, USD Million, 2021 - 2033)
-
Dry and Damaged Hair
-
Dandruff and Flaky Scalp
-
Oily and Greasy Scalp
-
Sensitive and Irritated Scalp
-
Hair Loss and Thinning
-
Glossy Hair/Antidullness
-
Others
-
-
Hair Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Straight
-
Wavy
-
Curly
-
Coily
-
-
Price Tier Outlook (Revenue, USD Million, 2021 - 2033)
-
Mass
-
Mid-Tire
-
Premium
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Women
-
Men
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Supermarkets and Hypermarkets
-
Specialty Beauty Stores
-
Pharmacies and Drugstores
-
Online/E-commerce
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia & New Zealand
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa
-
South Africa
-
-
Research Methodology
The hair and scalp care market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each hair and scalp care segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Shampoo
Covers formulation types including medicated, anti-dandruff, sulfate-free, and clarifying shampoos across mass and premium tiers. Includes product variants targeting daily cleansing, scalp purification, and hair texture enhancement. Assesses packaging formats, ingredient innovations, and distribution through retail, salons, e-commerce, and professional haircare channels across global markets and regions.
Conditioner
Includes rinse-out, leave-in, deep conditioners, and co-wash formats designed for hydration, detangling, and cuticle smoothing. Covers silicone-based and natural formulations, salon-grade treatments, and at-home usage. Evaluates product positioning across damage repair, moisture retention, frizz control, and nourishment-focused offerings distributed through professional and consumer retail ecosystems.
Hair Oils
Encompasses traditional, ayurvedic, herbal, and modern lightweight oil formulations targeting scalp nourishment, strengthening, and pre-wash treatment routines. Includes blends with essential oils, growth-stimulating actives, and anti-hair fall ingredients. Covers usage across mass household applications, premium wellness offerings, and regional haircare traditions influencing global product demand patterns.
Hair Serums
Includes leave-in formulations focused on frizz control, shine enhancement, heat protection, and scalp-specific treatment serums. Covers silicone-based and clean-label alternatives, anti-breakage solutions, and lightweight formulations. Assesses usage across styling routines, post-wash applications, and professional salon treatments targeting smoothness, repair, and cosmetic hair appearance enhancement.
Masks and Treatments
Covers deep conditioning masks, keratin treatments, bond repair systems, and intensive nourishment formulations. Includes salon-exclusive treatments and at-home therapy products designed for damaged, chemically treated, and weakened hair. Evaluates product innovation in protein infusion, hydration repair systems, and periodic intensive care routines across global consumer segments.
Others
Includes dry shampoos, hair sprays, scalp tonics, mousses, styling creams, and specialized hybrid formulations. Covers multifunctional products combining styling and care benefits. Assesses innovations in convenience-driven formats, travel-friendly packaging, and multifunctional hair solutions addressing modern grooming needs across mass-market and premium personal care ecosystems globally.
Segment - Concern
Revenue capture definition
Dry and Damaged Hair
Encompasses solutions targeting hair fiber repair, moisture restoration, split-end reduction, and cuticle reinforcement. Includes shampoos, conditioners, serums, and masks formulated with keratin, proteins, and hydrating agents. Covers both preventive and restorative product usage addressing heat damage, chemical processing effects, and environmental stress exposure across consumer segments.
Dandruff and Flaky Scalp
Covers anti-fungal, anti-bacterial, and exfoliating formulations designed to reduce flaking, itching, and scalp irritation. Includes medicated shampoos, scalp tonics, and specialized treatments with zinc pyrithione, ketoconazole, or natural actives. Evaluates product positioning for chronic and seasonal dandruff management across clinical, OTC, and cosmetic care categories.
Oily and Greasy Scalp
Includes oil-control shampoos, clarifying treatments, and scalp-balancing formulations targeting excess sebum production. Covers deep-cleansing systems, lightweight conditioners, and detoxifying ingredients such as clay, charcoal, and botanical extracts. Assesses usage patterns across humid climates, urban pollution exposure, and frequent wash routines in global haircare consumption.
Sensitive and Irritated Scalp
Encompasses hypoallergenic, fragrance-free, and dermatologically tested formulations designed to soothe irritation, redness, and scalp discomfort. Includes gentle cleansing shampoos, calming scalp serums, and microbiome-friendly products. Covers ingredient safety profiles, minimal-formula trends, and products developed for allergy-prone or medically sensitive consumer groups across personal care markets.
Hair Loss and Thinning
Covers anti-hair fall shampoos, growth serums, follicle-stimulating treatments, and DHT-blocking formulations. Includes both cosmetic and therapeutic-grade solutions targeting hair density improvement and breakage reduction. Assesses product integration with clinical ingredients, nutraceutical influences, and long-term usage regimens addressing progressive hair thinning conditions.
Glossy Hair/Antidullness
Includes shine-enhancing serums, smoothing conditioners, and light-reflecting formulations designed to improve hair luster and visual softness. Covers anti-dullness treatments addressing pollution, dryness, and chemical exposure. Evaluates cosmetic performance products, silicone-based and natural alternatives, and styling-care hybrids used for immediate aesthetic enhancement and finish improvement.
Others (Concerns)
Encompasses niche and emerging hair and scalp concerns not classified under major categories, including hair breakage, split ends, frizz management, color-treated hair maintenance, heat protection needs, and environmental damage (UV, pollution, hard water). Covers multifunctional formulations addressing overlapping concerns through hybrid shampoos, serums, and treatment products across global consumer segments.
Estimation Model
Name
Key Question
Description
Hair & Scalp Concern Layer
Who experiences hair or scalp-related concerns?
Begin with the global population experiencing hair and scalp issues such as hair fall, dandruff, scalp dryness, oily scalp, thinning hair, sensitivity, and damage caused by environmental factors, stress, aging, and lifestyle changes. This identifies the population with a clinical, cosmetic, or preventive need for hair and scalp care solutions.
Awareness & Product Access Layer
Who can access specialized hair and scalp care products?
Apply consumer awareness levels, beauty and personal care spending patterns, retail penetration, e-commerce accessibility, and salon reach to the eligible population. This derives the addressable consumer base exposed to specialized hair and scalp care products through online, offline, and professional channels.
Treatment & Usage Layer
Who actively purchases hair and scalp care products?
Apply category adoption rates across shampoos, conditioners, hair oils, serums, masks, treatments, and scalp-specific products. Account for consumers seeking preventive care, routine maintenance, and targeted treatment solutions, converting the addressable population into active product users.
Monetisation Layer
How much revenue is generated?
Multiply active users by average annual spending across product categories, considering purchase frequency, premiumization trends, multi-product regimens, and professional hair care treatments. Additional value is generated through dermatologist-recommended products, salon-grade formulations, and science-backed scalp care solutions.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-Segmentation Analysis of Product Categories, Hair Concerns & Consumer Profiles
Detailed cross-segmentation analysis across product categories (shampoo, conditioner, hair oils, serums, masks & treatments), mapped against key hair and scalp concerns such as hair loss & thinning, dandruff, oily scalp, scalp sensitivity, and dry & damaged hair. The study further evaluates demand by hair type (straight, wavy, curly, coily), gender, and regional consumption patterns across North America, Europe, Asia Pacific, Latin America, and MEA.
Identifies which product formats are gaining the strongest traction for specific concerns, such as serums and scalp treatments for hair fall, medicated shampoos for dandruff, and masks for damaged hair. Also highlights how concern-led purchasing is increasingly replacing generic haircare routines, enabling companies to optimize innovation and portfolio investments.
Brand Share Analysis & Competitive Benchmarking Across Mass, Premium & Clinical Haircare Segments
Comprehensive benchmarking of multinational beauty companies, dermatologist-backed brands, salon-professional brands, natural/clean beauty players, and emerging D2C brands. The analysis compares brand positioning, ingredient strategy, pricing architecture, distribution reach, innovation pipelines, and scalp-health claims across major global and regional markets.
Helps distinguish volume-driven mass-market brands from premium and treatment-focused players competing on efficacy, ingredient transparency, and clinical validation. Also identifies competitive whitespace in fast-growing categories such as scalp care, anti-hair-fall solutions, microbiome-based formulations, and personalized haircare.
Scalp Health & Treatment-Led Innovation Landscape Assessment
Deep-dive evaluation of emerging scalp-care categories including anti-dandruff solutions, scalp exfoliants, microbiome-balancing products, scalp serums, anti-hair-loss treatments, and clinically tested formulations. The analysis assesses innovation trends, active ingredient adoption, and evolving consumer expectations around scalp wellness.
Provides visibility into the rapidly growing shift from cosmetic haircare toward treatment-oriented scalp health solutions. Helps identify high-growth innovation areas driven by increasing consumer awareness of scalp health, hair thinning, stress-related hair loss, and ingredient efficacy.
Frequently Asked Questions About This Report
The global Hair & Scalp Care market size was valued at USD 88.2 billion in 2025 and is estimated at USD 93.6 billion in 2026.
Key players include L'Oréal S.A., Kenvue, Beiersdorf AG, Procter & Gamble, Unilever PLC, The Estée Lauder Companies Inc., Henkel AG & Co. KGaA, Shiseido Company, Limited, Amway Corp., and Natura & Co..
Key factors include rising consumer awareness of scalp health, increasing prevalence of hair loss and dandruff-related concerns, growing demand for premium and dermatologist-backed formulations, expansion of e-commerce channels, and rising adoption of personalized and ingredient-focused hair care products.
The global Hair & Scalp Care market is expected to grow at a CAGR of 7.0% from 2026 to 2033, reaching approximately USD 150.5 billion by 2033.
In hair & scalp care market by concern, the Oily & Greasy Scalp segment led the market with approximately 29.4% revenue share in 2025
Asia Pacific dominated the market with approximately 35.5% revenue share in 2025, driven by large consumer bases in China, Japan, and India.
Asia Pacific is expected to remain the fastest-growing regional market during the forecast period, supported by rising disposable incomes, premiumization trends, and increasing beauty and personal care spending.
The Women segment held the largest revenue share of approximately 60.6% in 2025, while the Men segment is expected to witness the fastest growth during the forecast period.
Supermarkets & Hypermarkets accounted for the largest share of approximately 39.3% in 2025. However, the Online/E-commerce channel is projected to be the fastest-growing distribution channel, expanding at a CAGR of approximately 9.2% through 2033.
About the Author(s)
Beauty & Personal Care Research Team
Consumer Goods · Beauty & Personal CareThis report was authored by the beauty & personal care research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the beauty & personal care segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


