
- Home
- »
- Pharmaceuticals
- »
-
Head And Neck Cancer Therapeutics Market Report, 2026-2033GVR Report cover

Head And Neck Cancer Therapeutics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Therapy (Chemotherapy, Immunotherapy), By Route Of Administration, By Distribution Channel (Hospital Pharmacies, Online Pharmacies), By Region, And Segment Forecasts
Market Size, 2025
$2.5BMarket Estimate, 2026
$2.8BMarket Forecast, 2033
$6.3BCAGR, 2026–2033
12.0%Head And Neck Cancer Therapeutics Market Summary
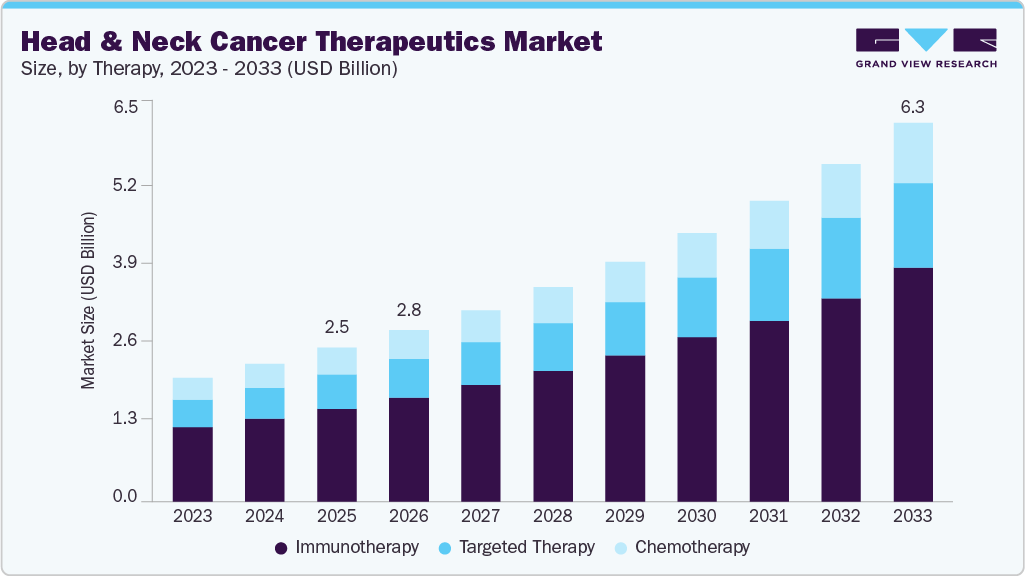
The global head and neck cancer therapeutics market size was valued at USD 2.5 billion in 2025 and is projected to grow from USD 2.8 billion in 2026 to USD 6.3 billion by 2033, at a CAGR of 12.0% from 2026 to 2033. The market in North America dominated with a revenue share of 44.6% in 2025. The market is growing due to the rising incidence of head and neck cancers, increasing demand for targeted and immunotherapy-based treatments, and advancements in diagnostic precision.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By route of administration: Injectable segment held the largest market share of 90.3% in 2025.
- By therapy: Immunotherapy segment held the largest market share of 60.4% in 2025.
- By distribution channel: Retail and specialty pharmacies segment held the largest market share of 57.2% in 2025.
Regional Highlights
- Largest regional market: North America (44.6% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 2.5 Billion
- Estimated market size in 2026: USD 2.8 Billion
- Projected market size by 2033: USD 6.3 Billion
- CAGR (2026-2033): 12.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The incidence of head and neck cancers continues to rise, driving greater demand for targeted therapies and immunotherapy-based treatment approaches. Diagnostic accuracy is improving rapidly, supported by new clinical evidence. For instance, in June 2025, GORTEC’s Phase III REACH trial reported positive outcomes for avelumab combined with radiotherapy in cisplatin-ineligible head and neck cancer patients. The study achieved its primary endpoint of improved progression-free survival and showed a favorable safety profile in more than 500 participants. Increasing awareness among patients and healthcare providers is also strengthening early detection and expanding the use of multi-line treatment strategies. Meanwhile, the growing preference for minimally invasive, lower-toxicity options is boosting the adoption of innovative drug classes. In addition, ongoing clinical trial expansion and accelerated regulatory pathways are improving product accessibility across major global markets.The growing prevalence of human papillomavirus (HPV)-associated oropharyngeal cancers is emerging as a significant driver for market growth. These HPV-related subtypes often respond differently to treatment, prompting a rise in research and tailored drug development. Clinical guidelines increasingly differentiate therapeutic approaches based on HPV status, fueling demand for precision therapies. Pharmaceutical companies are investing in treatment protocols that address viral oncogenesis, expanding the therapeutic landscape. The increasing incidence of HPV-positive cases among younger adults has shifted the disease demographic, creating new market opportunities. Enhanced public awareness and screening for HPV-related malignancies contribute to earlier diagnosis and treatment initiation.
 To learn more about this report, Download Free Sample Report
Adopting combination therapy strategies is gaining momentum in the head and neck cancer therapeutics space, offering improved response rates and survival outcomes. Treatment regimens integrating immunotherapy with chemotherapy or targeted agents are being tested in both first-line and refractory settings. For instance, in June 2025, the FDA’s approval of Keytruda for PD-L1-positive head and neck cancer patients highlights the growing focus on biomarker-based therapies. The announcement also emphasized the unmet need in PD-L1-negative patients. CEL-SCI’s Multikine aims to address this gap by treating patients before standard therapies, regardless of PD-L1 status. Designed to stimulate an early immune response, Multikine represents a novel approach that could broaden treatment access and improve outcomes across diverse patient groups.
Market Concentration & Characteristics
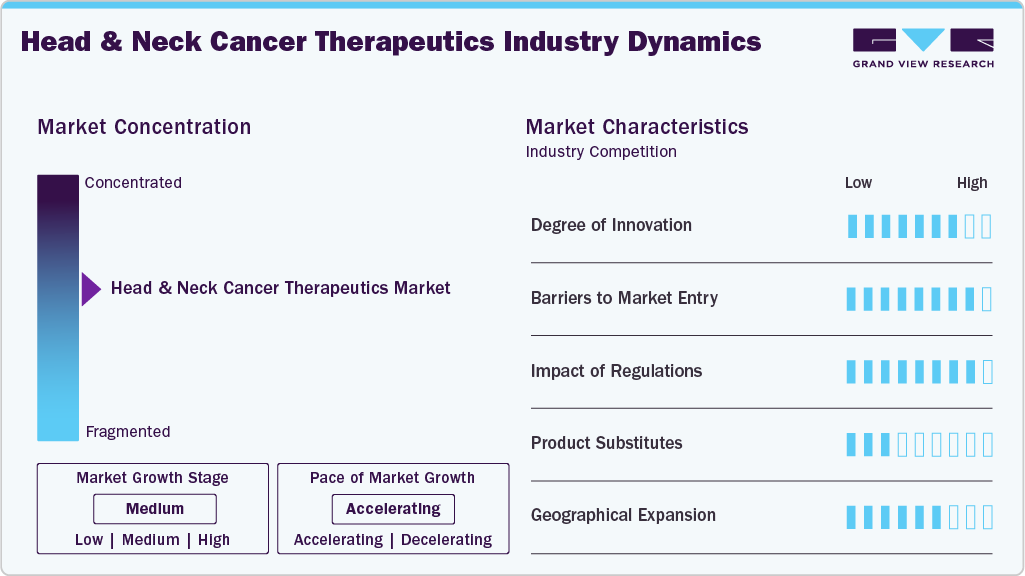
The head and neck cancer therapeutics industry demonstrates a moderate-to-high level of innovation, largely driven by advances in immunotherapy and targeted therapies. While chemotherapy remains a foundation, companies like Bristol-Myers Squibb and Merck have introduced checkpoint inhibitors that offer enhanced survival outcomes. Innovations focus on minimizing toxicities while improving progression-free survival rates. Recent clinical trials emphasize biomarker-driven approaches for therapy selection. This evolving landscape fosters competition among key players to develop next-generation treatments with differentiated profiles.
The market poses significant entry barriers due to the high cost of clinical trials, stringent regulatory demands, and intellectual property protection held by leading firms. Established players such as Eli Lilly and AstraZeneca benefit from extensive R&D capabilities and global commercialization networks, which newcomers often lack. In addition, oncological drug development requires long timelines, specialized trial endpoints, and robust safety data. Market entrants must also navigate hospital formulary approvals and secure access to specialty distribution channels. These obstacles make it difficult for smaller firms to gain a foothold.
 To learn more about this report, Download Free Sample Report
Regulatory oversight shapes market dynamics, especially for injectable and immunotherapeutic treatments. Agencies like the FDA and EMA demand rigorous clinical data on efficacy, safety, and tolerability before approving therapies. Post-approval surveillance requirements, black-box warnings, and REMS programs can impact product uptake. For example, accelerated approvals may be granted for therapies with significant survival benefits, influencing market timelines. Companies must continuously adapt to shifting regulatory frameworks and evolving clinical guidelines in oncology.
Although surgical and radiation interventions are standard in early-stage cases, pharmacological treatments remain irreplaceable in recurrent and metastatic head and neck cancers. Substitutes may exist between immunotherapy, chemotherapy, and targeted agents within drug-based options, depending on patient profiles and tumor markers. However, drugs are not interchangeable without impacting outcomes, especially in biomarker-specific cases. As such, treatment decisions are increasingly driven by clinical algorithms rather than cost alone. Substitution is thus limited, preserving the relevance of differentiated therapeutics.
Geographical expansion remains a core strategy for major players to boost access and market share, especially in underserved regions. Firms such as Roche and Sanofi continue to seek regulatory approvals across Asia, Latin America, and Eastern Europe, where the burden of head and neck cancer is rising. Expansion efforts involve localized clinical trials, regional partnerships, and differentiated pricing strategies. However, varying healthcare infrastructure and reimbursement systems influence the speed and extent of market penetration. Companies that invest in regional supply chains and education initiatives tend to perform better in emerging markets.
Therapy Insights
The immunotherapy segment dominated the market with the largest revenue share of 60.41% in 2025, driven by the ability to deliver durable responses and improved survival outcomes in advanced-stage patients. Agents such as PD-1 inhibitors have demonstrated clinical effectiveness in recurrent or metastatic head and neck squamous cell carcinoma. High adoption among oncologists is supported by favorable safety profiles and reduced toxicity compared to conventional chemotherapy. For instance, in April 2025, Oncology Central reported that the Phase III KEYNOTE-689 trial showed perioperative pembrolizumab significantly improved event-free survival in head and neck cancer patients. Presented at AACR 2025, this Merck-funded study marked the first major therapeutic advancement in over two decades, enhancing outcomes through pre- and post-surgery immunotherapy.
The targeted therapy segment is projected to grow at a CAGR of 11.86% over the forecast period, fueled by its precision in acting on molecular pathways relevant to tumor progression. EGFR inhibitors and VEGF-targeting agents offer specific treatment benefits in biomarker-positive patients. Personalized treatment approaches are increasing demand for targeted agents that limit damage to healthy tissues. For instance, in January 2025, OncLive reported that a targeted therapy trial combining cetuximab and erlotinib with platinum/taxane chemotherapy in recurrent or metastatic HNSCC achieved a 62.5% objective response rate versus 36% in historical controls. Two patients showed durable, complete responses with years-long survival, demonstrating enhanced treatment efficacy.
Route Of Administration Insights
The injectable segment dominated the market with the largest revenue share of 90.27% in 2025 due to its critical role in administering chemotherapy, immunotherapy, and biologics for head and neck cancer. For instance, in February 2025, Cancer Currents reported that the FDA approved Opdivo Q4W SC, a subcutaneous injectable version of nivolumab, for cancers including head and neck squamous cell carcinoma. Administered in 3-5 minutes, this injectable showed comparable efficacy to IV infusion, offering a faster, more convenient treatment option for eligible patients. Most first-line and advanced-stage treatments require intravenous infusion for optimal dosing and rapid systemic action.
The oral segment is projected to grow at a CAGR of 9.64% over the forecast period owing to increasing preference for at-home treatment options that improve patient convenience. Emerging oral targeted therapies offer comparable efficacy with easier administration than intravenous alternatives. Improved patient compliance and reduced burden on healthcare facilities are influencing prescribing patterns. For instance, in May 2023, PubMed reported that a Phase II trial combining apatinib with oral S-1 in recurrent or metastatic HNSCC showed a 72.4% disease control rate, 4.8-month median progression-free survival, and 10.3-month overall survival. The oral regimen was well-tolerated, suggesting potential as an alternative treatment option.
Distribution Channel Insights
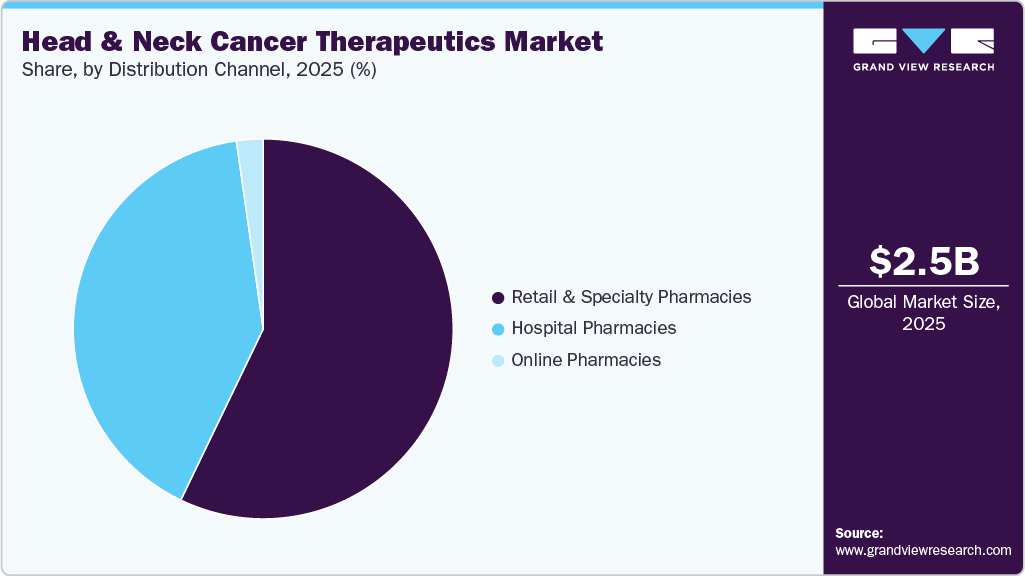
The retail and specialty pharmacies segment dominated the market with the largest revenue share of 57.15% in 2025, due to their broad reach and ability to handle complex oncology prescriptions. These channels offer streamlined access to high-cost therapies, including immunotherapies and targeted agents. Integration with specialty care services ensures timely delivery and dosage management. Patient support programs and pharmacist-led counseling contribute to improved adherence. Pharmaceutical companies increasingly partner with specialty pharmacies to ensure proper handling and cold chain logistics. The growing role of outpatient cancer care further drives reliance on this distribution channel.
 To learn more about this report, Download Free Sample Report
The hospital pharmacies segment is projected to grow at a CAGR of 11.49% over the forecast period due to the central role hospitals play in administering chemotherapy and immunotherapy infusions. On-site availability of advanced therapeutics facilitates immediate treatment in emergency and inpatient settings. Hospital-based pharmacies provide tailored dosing and oversight from multidisciplinary teams. Increasing admissions for advanced head and neck cancer cases enhance the demand for in-hospital dispensing. Integrated electronic medical records systems support safer and more efficient drug management within hospital settings. Continued preference for hospital-based initial therapy drives segment growth across treatment cycles.
Regional Insights
North America Head And Neck Cancer Therapeutics Market Trends
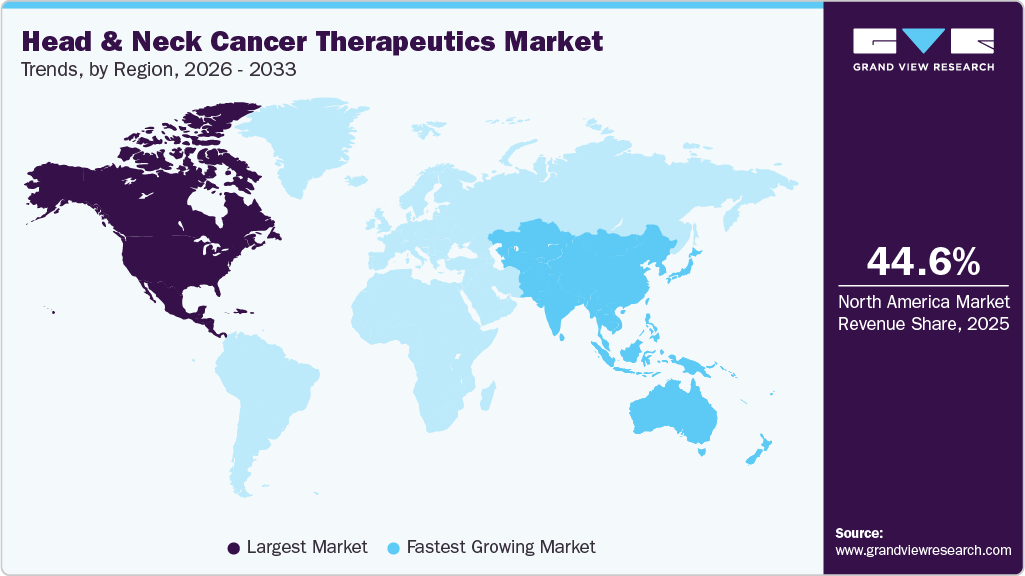
North America head and neck cancer therapeutics industry held the largest share of 44.63% in 2025 due to early adoption of novel treatments and strong clinical infrastructure. High disease burden from tobacco and alcohol use increases demand for effective therapies. The presence of major pharmaceutical companies supports robust drug availability and treatment access. Ongoing clinical trials and quick regulatory processes accelerate market momentum. Specialty cancer centers contribute to widespread administration of immunotherapies and targeted treatments. Advanced healthcare systems ensure patient access to multi-line therapy regimens.
 To learn more about this report, Download Free Sample Report
U.S. Head And Neck Cancer Therapeutics Market Trends
The U.S. head and neck cancer therapeutics industry dominated the North America region due to high healthcare spending and access to next-generation oncology drugs. Key players actively launch and expand therapies tailored to disease progression. Immunotherapies and targeted treatments are widely used in recurrent and advanced-stage cases. National guidelines and swift regulatory reviews support timely treatment updates. Integration of biomarker testing enhances clinical decision-making and therapy selection. Strong distribution networks ensure availability across outpatient and inpatient settings.
Europe Head And Neck Cancer Therapeutics Market Trends
Europe head and neck cancer therapeutics industry shows steady growth driven by rising incidence and integration of advanced therapeutic protocols. The region benefits from robust oncology research and specialized cancer networks. High uptake of precision medicine fosters demand for targeted and immunotherapy drugs. Countries across the region maintain structured treatment guidelines supporting evidence-based care. Pharmaceutical collaborations with clinical institutions help accelerate product access. Focus on treatment tolerability and improved outcomes drives therapy selection.
The UK head and neck cancer therapeutics industry is expanding due to the country’s centralized cancer care and focus on treatment innovation. Immunotherapies are increasingly used following positive clinical outcomes in survival rates. Healthcare systems prioritize therapies with high clinical value and manageable toxicity. Fast-track approval pathways enhance early access to new oncology drugs. Collaboration between healthcare providers and pharmaceutical firms supports treatment optimization. Continuous assessment of patient outcomes influences prescribing practices.
Germany head and neck cancer therapeutics industry maintains a strong position within Europe through its advanced oncology infrastructure. Early diagnosis and comprehensive treatment protocols improve therapeutic outcomes. Immunotherapies and targeted drugs are increasingly used in clinical practice for advanced-stage cases. Hospitals across the country are equipped for administering biologics with close monitoring. Reimbursement mechanisms facilitate access to high-cost treatments. National programs support awareness and screening, promoting early intervention.
France head and neck cancer therapeutics industry is growing as hospitals expand use of personalized and biologic treatments. Treatment protocols are evolving to include multi-line therapy options supported by real-world data. Increased focus on HPV-related cancers is shifting the therapeutic landscape. Advanced diagnostics are widely available, aiding early and accurate treatment planning. Pharmaceutical companies actively collaborate with academic institutions for clinical research. Oncology centers support the delivery of high-value drugs under structured care pathways.
Asia-Pacific Head And Neck Cancer Therapeutics Market Trends
Asia Pacific head and neck cancer therapeutics industry is expected to register the fastest CAGR of 13.54% over the forecast period due to increasing disease burden and expanding treatment infrastructure. Rising urbanization and higher health investments contribute to faster adoption of advanced therapies. The region faces high prevalence due to risk factors such as smoking and oral infections. Local pharmaceutical firms are entering the market with new immuno-oncology products. International companies are also targeting this region for clinical trials and product launches. Access to diagnostics and outpatient care is improving across urban centers.
Japan head and neck cancer therapeutics industry is mature due to its aging population and well-developed cancer care framework. Hospitals are adopting precision treatments based on tumor markers and response history. Domestic companies focus on developing and commercializing immunotherapies and EGFR-targeted drugs. National guidelines ensure uniform treatment standards across facilities. Screening programs support early detection, increasing demand for early-stage therapies. Centralized care supports consistent and efficient drug administration.
China head and neck cancer therapeutics industry is expanding with increased access to modern treatments and rising diagnosis rates. Healthcare modernization is improving delivery of hospital-based therapies across major cities. Domestic and global firms are launching immunotherapies and targeted drugs tailored to local populations. Enhanced cancer awareness drives earlier consultations and improved treatment outcomes. Regional disparities still exist, but major provinces are advancing treatment availability. Growing clinical trial activity supports the introduction of innovative therapies.
Latin America Head And Neck Cancer Therapeutics Market Trends
Latin America head and neck cancer therapeutics industry is growing steadily due to increasing urban cancer care services and awareness campaigns. Oncology hospitals in key countries are integrating newer treatment options. Demand for less invasive, high-precision therapies is rising among younger patient populations. Distribution agreements with multinational drug firms are improving therapy access. Chemotherapy remains widely used, while adoption of targeted therapy is increasing. Reimbursement and availability challenges limit broader market coverage.
Brazil head and neck cancer therapeutics industry dominated the Latin America region in 2025, due to its expanding network of specialized cancer centers. Urban hospitals are equipped to deliver immunotherapy and advanced targeted treatments. Clinical trials and local research support adoption of novel therapies. Oncology professionals are trained in personalized treatment protocols for head and neck cancers. Demand is rising in metropolitan areas with improved diagnostic access. Market expansion is supported by public and private healthcare collaboration.
Middle East & Africa Head And Neck Cancer Therapeutics Market Trends
The MEA head and neck cancer therapeutics industry is emerging with growth opportunities in urban centers across the region. Prevalence of head and neck cancers linked to lifestyle habits is creating unmet treatment needs. Oncology infrastructure is developing, particularly in high-income countries of the region. Multinational drug companies are entering partnerships to facilitate treatment delivery. Clinical education programs are helping to raise awareness among healthcare professionals. Variability in healthcare systems impacts uniform therapy access.
Saudi Arabia head and neck cancer therapeutics industry is growing rapidly due to improvements in healthcare infrastructure and specialized oncology services. Advanced treatment protocols are being introduced at national cancer centers. Hospital pharmacies are integrating immunotherapy and targeted drugs into care pathways. Local partnerships support drug registration and market expansion. Rising cancer incidence linked to lifestyle risk factors is driving demand for early treatment. Medical education programs improve adoption of guideline-recommended therapies.
Key Head And Neck Cancer Therapeutics Company Insights
Eli Lilly and Company and Sanofi continue to expand their oncology portfolios by advancing immunotherapies and chemotherapeutic agents for head and neck cancers. Merck & Co., Inc. and Bristol-Myers Squibb Company focus on PD-1/PD-L1 inhibitors with growing clinical evidence supporting improved survival outcomes in recurrent and metastatic cases. AstraZeneca and Takeda Pharmaceutical Company Limited are investing in multi-line therapy approaches that combine targeted agents with conventional treatments. F. Hoffmann-La Roche Ltd. and Teva Pharmaceutical Industries Ltd. are enhancing their market presence by developing biologics and formulating innovations. Cumberland Pharmaceuticals Inc. is contributing to niche therapeutic segments with oncology-focused drug candidates. The market reflects ongoing competition driven by evolving treatment algorithms, increasing biomarker-based therapy use, and expanding global clinical trial networks.
Key Head And Neck Cancer Therapeutics Companies:
The following are the leading companies in the head and neck cancer therapeutics market. These companies collectively hold the largest market share and dictate industry trends.
- Eli Lilly and Company
- Sanofi
- Merck & Co., Inc.
- Cumberland Pharmaceuticals Inc.
- Bristol-Myers Squibb Company
- AstraZeneca
- Takeda Pharmaceutical Company Limited
- Teva Pharmaceutical Industries Ltd.
- F. Hoffmann-La Roche Ltd.
Recent Developments
-
In March 2025, Aprea Therapeutics signed a Material Transfer Agreement with MD Anderson Cancer Center to evaluate its WEE1 inhibitor, APR-1051, in HPV-positive and HPV-negative head and neck cancers. The collaboration includes preclinical studies on replication stress and combination strategies with immune checkpoint inhibitors.
-
In September 2023, Pierre Fabre S.A. formed a collaboration with Vernalis Research, a subsidiary of HitGen Inc., to advance the development of oncology therapeutics and strengthen efforts in cancer drug discovery.
-
In August 2023, Merck & Co., Inc. reported encouraging outcomes from its LEAP-010 clinical trial, which is evaluating a potential therapy for metastatic and recurrent head and neck cancer. The trial was launched with Eisai to assess the investigational candidate’s safety and effectiveness in this patient population.
Head And Neck Cancer Therapeutics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.5 billion
Estimated market size in 2026
USD 2.8 billion
Projected market size by 2033
USD 6.3 billion
Growth rate
CAGR of 12.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Therapy, route of administration, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key company profiled
Eli Lilly and Company; Sanofi; Merck & Co., Inc.; Cumberland Pharmaceuticals Inc.; Bristol-Myers Squibb Company; AstraZeneca; Takeda Pharmaceutical Company Limited; Teva Pharmaceutical Industries Ltd.; F. Hoffmann-La Roche Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Head And Neck Cancer Therapeutics Market Report Segmentation
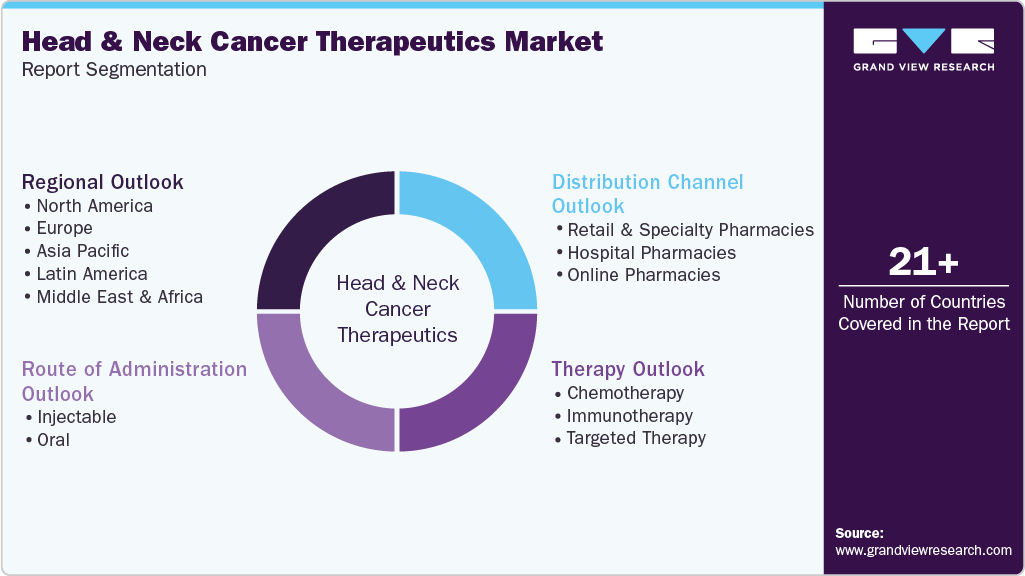
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global head and neck cancer therapeutics market report based on therapy, route of administration, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Therapy Outlook (Revenue, USD Million, 2021 - 2033)
-
Chemotherapy
-
Immunotherapy
-
Targeted Therapy
-
-
Route Of Administration Outlook (Revenue, USD Million, 2021 - 2033)
-
Injectable
-
Oral
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Retail and Specialty Pharmacies
-
Hospital Pharmacies
-
Online Pharmacies
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global head and neck cancer therapeutics market size was valued at USD 2.5 billion in 2025 and is estimated at USD 2.8 billion for 2026.
The global head and neck cancer therapeutics market is expected to grow at a CAGR of 12.0% from 2026 to 2033, reaching USD 6.3 billion by 2033.
The immunotherapy segment dominated the head and neck cancer therapeutics market with a share of 60.4% in 2025. This is attributable to the high sale of branded PD inhibitors such as Keytruda and Opdivo.
Key players include Eli Lilly and Company; Sanofi; Merck & Co., Inc.; Cumberland Pharmaceuticals Inc.; Bristol-Myers Squibb Company; AstraZeneca; Takeda Pharmaceutical Company Limited; Teva Pharmaceutical Industries Ltd.; F. Hoffmann-La Roche Ltd.
Key factors that are driving the market growth include increasing R&D investments for the development of novel therapies, the rising prevalence of head and neck cancer, and rising government initiatives.
North America dominated with a 44.6% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Injectable segment dominated the market and accounted for the largest revenue share of 90.3% in 2025.
The retail and specialty pharmacies segment led with a 57.2% revenue share in 2025.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


