
- Home
- »
- Clinical Diagnostics
- »
-
Hemato Oncology Testing Market Size & Share Report, 2033GVR Report cover

Hemato Oncology Testing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Assay Kits & Reagents, Services), By Cancer (Leukemia, Lymphoma), By Technology, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$4.5BMarket Estimate, 2026
$5.1BMarket Forecast, 2033
$10.9BCAGR, 2026–2033
11.5%Hemato Oncology Testing Market Summary
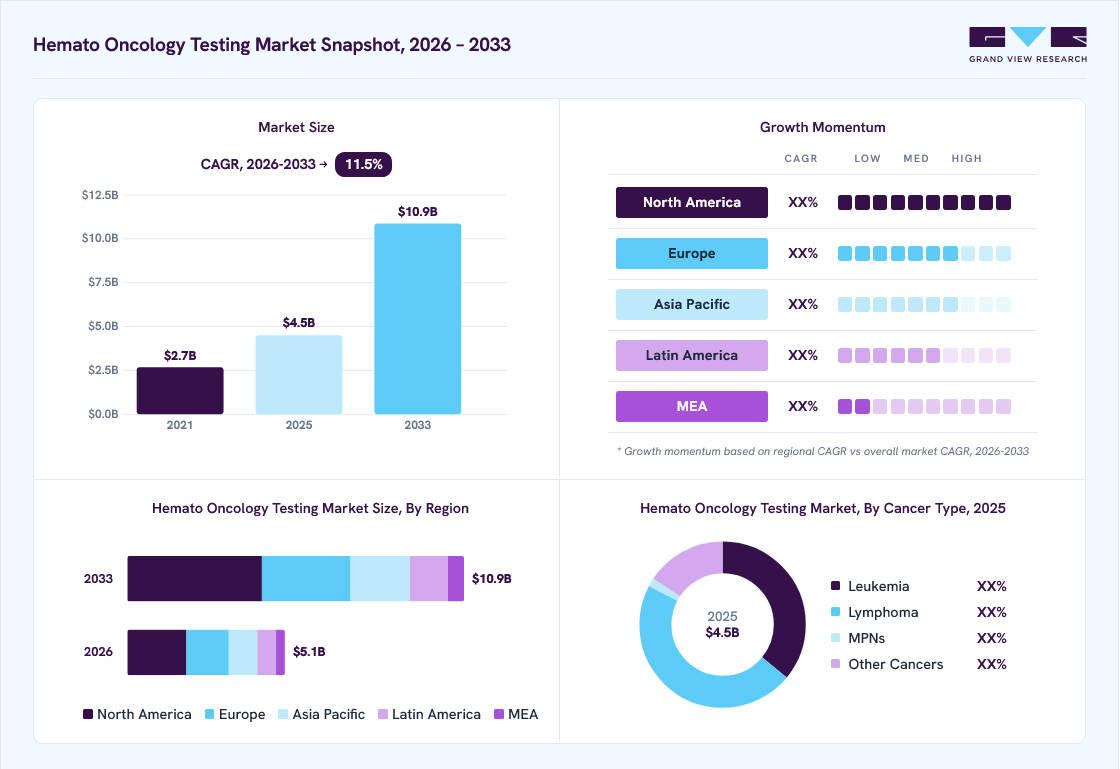
The global hemato oncology testing market size was valued at USD 4.5 billion in 2025 and is projected to grow from USD 5.1 billion in 2026 to USD 10.9 billion by 2033, growing at a CAGR of 11.5% from 2026 to 2033. North America dominated the market, accounting for the largest global share of 38.2% in 2025. Hemato oncology is associated with the diagnosis, treatment, and prevention of blood-related cancers and diseases.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By cancer: The lymphoma segment led the market with the largest revenue share of 46.7% in 2025.
- By product: The services segment led the market with the largest revenue share of 58.2% in 2025.
- By technology: The PCR segment led the market with the largest revenue share of 31.1% in 2025.
- By end use: The hospitals segment led the market with the largest revenue share of 75.0% in 2025.
Regional Highlights
- Largest regional market: North America (38.2% revenue share, 2025)
- By country: The U.S. held the largest share of the North American market in 2025.
Market Size & Forecast
- Market size in 2025: USD 4.5 Billion
- Estimated market size in 2026: USD 5.1 Billion
- Projected market size by 2033: USD 10.9 Billion
- CAGR (2026-2033): 11.5%
Prism AI by Grand View Research Free to tryAsk a question about the hemato oncology testing marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Increasing prevalence of lymphoma & myeloma, growing demand for personalized therapy, availability of advanced molecular techniques for hemato-oncology diagnostics, and increasing drug-diagnostics co-development are some of the major factors anticipated to boost the growth of the market during the forecast period. The rapid evolution of molecular diagnostics has transformed the landscape of hemato-oncology, offering precise and personalized approaches for the detection, diagnosis, prognosis, and treatment of various blood cancers. These cutting-edge techniques have significantly improved the understanding of disease biology and therapeutic response, leading to better patient outcomes and more efficient clinical workflows.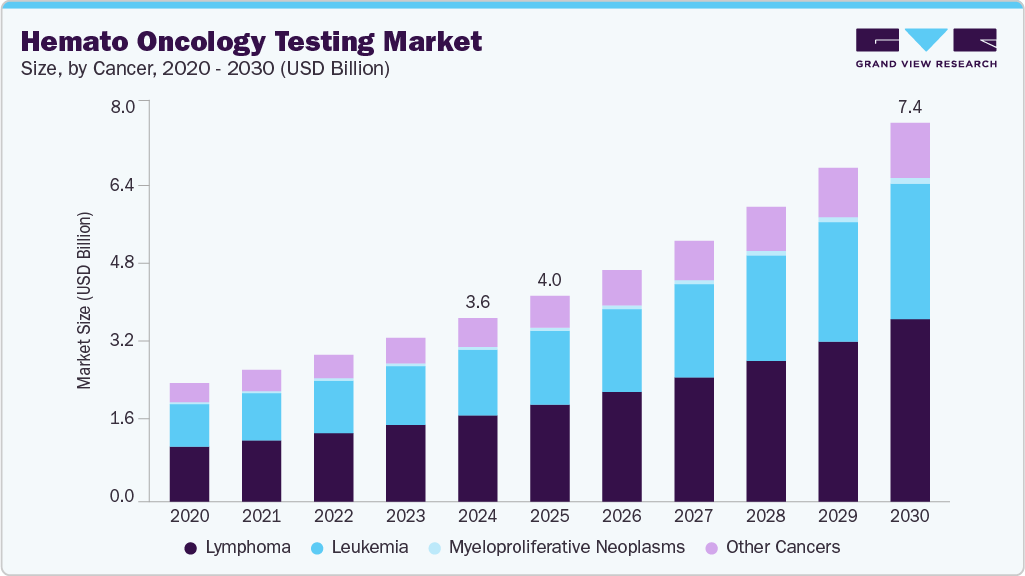 To learn more about this report, Download Free Sample Report
Molecular diagnostics in hematologic malignancies often rely on methods like real-time PCR, fluorescence in situ hybridization (FISH), and next-generation sequencing (NGS) to detect specific genetic alterations. For instance, chronic myeloid leukemia (CML) is routinely diagnosed using PCR-based tests targeting the BCR::ABL1 fusion gene or FISH assays. Standardization of BCR/ABL measurement internationally has facilitated easier and more accurate diagnosis of CML across laboratories. Similarly, acute myeloid leukemia (AML) and acute lymphoblastic leukemia (ALL) benefit from molecular diagnostics, with NGS panels enabling the identification of multiple gene mutations simultaneously, including FLT3-ITD, NPM1, and TP53, which are critical for risk stratification and treatment selection. In lymphomas, techniques like T-cell clonality assays, targeted FISH, and IgVH analysis are widely employed, while the JAK2 V617F mutation serves as a critical marker for diagnosing polycythemia vera in high-risk patients.
Recent advancements have introduced more sophisticated tools such as single-cell sequencing, optical genome mapping (OGM), and long-read sequencing. Single-cell sequencing provides unprecedented resolution at the cellular level, offering insights into clonal diversity and tumor evolution. OGM, as demonstrated in a recent study published in The Journal of Molecular Diagnostics, enables comprehensive cytogenomic profiling of tumors, including multiple myeloma, by efficiently identifying structural variants and copy number changes even in low-yield cell populations. This pan-genomic approach reduces the need for separate, marker-specific tests, streamlining workflows and improving diagnostic accuracy. The study at Lille University Hospital confirmed that OGM can reduce the number of cells required for complete genomic profiling, showing 93% concordance with traditional FISH on five tested markers and identifying over 22 additional genomic variants of interest.
In 2024, Oxford Gene Technology (OGT) introduced the SureSeq Myeloid Fusion Panel, a groundbreaking RNA-based NGS tool designed for the comprehensive identification of fusion genes in AML. This panel, developed in collaboration with leading myeloid cancer experts, covers over 30 key disease-associated fusions, including KMT2A and MECOM, and employs a partner-gene agnostic approach to detect rare and novel fusions in a single assay. The integration of this panel into end-to-end NGS workflows has significantly enhanced the ability to classify samples, reducing the need for extensive bioinformatics resources and improving turnaround times in clinical laboratories.
Moreover, long-read sequencing technologies, such as those developed by Pacific Biosciences and Oxford Nanopore, are revolutionizing the field by providing complete, error-free readouts of complex genomic regions. These platforms are overcoming the limitations of short-read NGS, enabling the detection of structural variants, complex rearrangements, and copy number changes with unparalleled precision.
Collectively, these advanced molecular technologies are reshaping the diagnostic landscape in hemato-oncology, providing clinicians with powerful tools for personalized medicine. The continuous innovation in this space promises to further enhance the accuracy, speed, and cost-effectiveness of cancer diagnostics, ultimately leading to better patient outcomes and more personalized treatment strategies.
In addition, lymphoma and myeloma are among the most common and clinically significant hematologic malignancies in the United States, contributing significantly to the overall cancer burden.
Non-Hodgkin Lymphoma (NHL)
NHL accounts for approximately 4% of all cancers in the U.S., making it one of the most prevalent cancers. According to the American Cancer Society, an estimated 80,350 people (45,140 males and 35,210 females) are projected to be diagnosed with NHL in 2025. This includes both adults and children, reflecting the broad age range affected by this aggressive cancer. In addition, around 19,390 people (11,060 males and 8,330 females) are expected to die from NHL in 2025. The overall lifetime risk for developing NHL is approximately 1 in 44 for men and 1 in 54 for women, though individual risk can vary significantly based on genetic, lifestyle, and environmental factors.
Leukemia, Lymphoma, and Myeloma Incidence
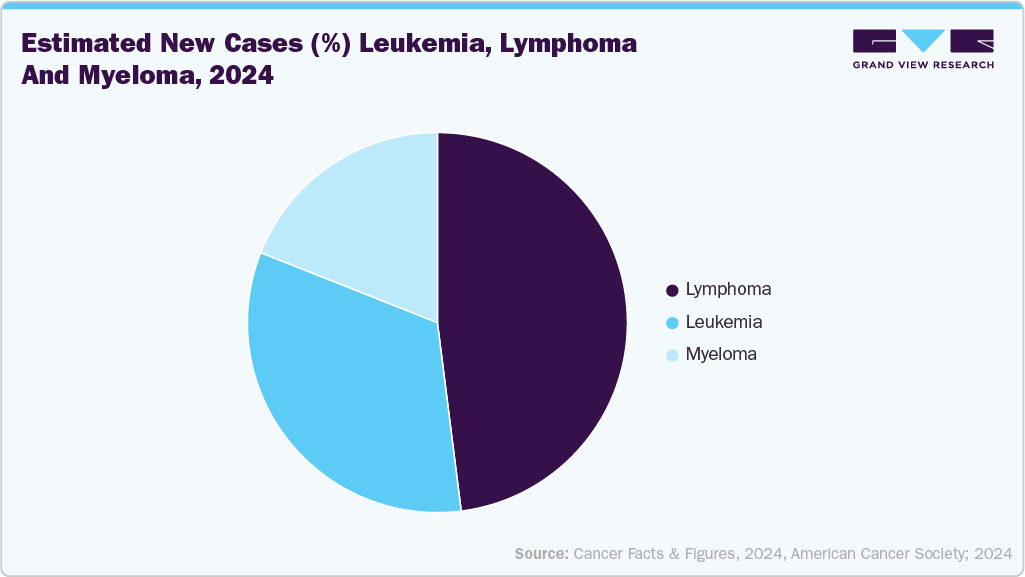
Every 3 minutes, someone in the United States is diagnosed with a blood cancer, including leukemia, lymphoma, or myeloma. In 2024 alone, an estimated 187,740 people in the U.S. will be newly diagnosed with these hematologic cancers, accounting for approximately 9.4% of the 2,001,140 total new cancer cases expected that year.
 To learn more about this report, Download Free Sample Report
Prevalence and Survivorship
As of the latest estimates, approximately 1,698,339 people in the U.S. are living with or in remission from leukemia, lymphoma, myeloma, myelodysplastic syndromes (MDS), or myeloproliferative neoplasms (MPNs). This high prevalence reflects both improved survival rates due to advances in treatment and early diagnosis, as well as the long-term nature of disease management in these patients.
Market Impact and Growth Drivers
The rising prevalence of these hematologic malignancies is expected to drive significant market growth over the coming years. Key factors contributing to this trend include:
-
Early Detection Initiatives: Increasing awareness and early screening programs are leading to earlier diagnosis and better survival outcomes.
-
Innovation in Diagnostic Technologies: Advancements in molecular diagnostics, liquid biopsies, and next-generation sequencing (NGS) are enabling more precise disease characterization and personalized treatment strategies.
-
Supportive Regulatory Environment: Favorable policies and expedited regulatory pathways are accelerating the commercialization of novel diagnostic tests.
-
Patient Advocacy and Awareness: Ongoing efforts by major market players and patient advocacy groups are raising awareness about the importance of early diagnosis and comprehensive disease monitoring.
Overall, the growing incidence of lymphoma, myeloma, and related hematologic cancers underscores the critical need for advanced, cost-effective diagnostic solutions, driving strong demand for innovative testing products and services in the hemato-oncology market.
Market Dynamics
The Hemato Oncology Testing Market is supported by the growing need for accurate diagnosis, disease classification, and continuous monitoring of hematologic malignancies to guide personalized treatment decisions. Advances in molecular diagnostics, flow cytometry, next generation sequencing, and cytogenetic testing are improving diagnostic precision while enabling earlier detection and minimal residual disease assessment. Increasing adoption of standardized testing workflows across hospitals and reference laboratories is further strengthening clinical decision making and supporting improved patient outcomes. For instance, in May 2025, QIAGEN partnered with Foresight Diagnostics to develop a kit-based version of the CLARITY minimal residual disease assay for lymphoma, expanding access to standardized molecular testing beyond centralized laboratories. The collaboration supports broader adoption of highly sensitive diagnostic technologies and strengthens the availability of decentralized testing solutions. Continued investment in advanced diagnostic platforms and precision oncology is expected to support sustained innovation and long-term growth in the hemato oncology testing market.
The growing adoption of precision medicine in hematologic oncology is a key driver of the Hemato Oncology Testing Market, as clinicians increasingly rely on advanced diagnostic technologies to identify disease specific biomarkers and monitor treatment response. Minimal residual disease testing, molecular profiling, and genomic analysis are becoming integral to clinical practice for improving risk stratification and supporting personalized therapeutic decisions. Rising incorporation of these testing approaches into clinical guidelines and routine laboratory workflows is further accelerating market expansion. For instance, in September 2025, Illumina announced multiple pharmaceutical partnerships to expand the use of its TruSight Oncology Comprehensive assay for companion diagnostic development, strengthening access to comprehensive genomic profiling across precision oncology applications. The collaborations support broader adoption of biomarker driven testing and reinforce the growing role of advanced genomic technologies in improving clinical decision making for hematologic malignancies.
The high cost and operational complexity associated with advanced hemato oncology testing remain significant restraints for the Hemato Oncology Testing Market. Technologies such as next generation sequencing, multiplex molecular assays, and comprehensive genomic profiling require specialized laboratory infrastructure, skilled personnel, and rigorous quality assurance processes, increasing the overall cost of testing. Limited reimbursement coverage for certain advanced assays and disparities in access across low- and middle-income regions further restrict their routine clinical adoption. In addition, variability in laboratory standardization and the complexity of interpreting genomic data can delay broader integration into everyday clinical practice. These challenges are particularly evident among smaller healthcare facilities and independent laboratories with constrained financial and technical resources. Addressing cost barriers, expanding reimbursement support, and improving laboratory standardization will be essential to enable wider adoption of advanced hemato oncology testing and support long term market growth.
The increasing adoption of decentralized molecular testing and companion diagnostics is creating significant growth opportunities for the Hemato Oncology Testing Market. Healthcare providers and diagnostic laboratories are expanding the use of advanced molecular platforms to improve access to high sensitivity testing, reduce turnaround times, and support personalized treatment decisions for hematologic malignancies. The growing focus on minimal residual disease testing and biomarker-based patient stratification is also driving investment in innovative diagnostic technologies. For instance, in June 2025, QIAGEN partnered with Tracer Biotechnologies to develop digital PCR based minimal residual disease assays on the QIAcuity platform for precision oncology applications. This collaboration supports the development of standardized molecular testing solutions and strengthens the future adoption of companion diagnostics in hematologic oncology. Continued advances in precision diagnostics and expanding clinical use of molecular testing are expected to create sustained opportunities for market growth.
Market Concentration & Characteristics
The degree of innovation in the hemato oncology testing industry is experiencing rapid growth, driving significant improvements in disease detection, risk stratification, and personalized treatment strategies for hematologic malignancies. Advancements in biomarker discovery, such as NPM1, FLT3-ITD, and IDH1/2 mutations, enable more precise molecular profiling of leukemia and lymphoma. Liquid biopsy techniques using circulating tumor DNA (ctDNA) and cell-free RNA are gaining traction as less invasive tools for monitoring disease progression and detecting minimal residual disease (MRD). In addition, the application of artificial intelligence (AI) to genomic data is refining diagnostic accuracy and supporting more tailored therapeutic decisions. These developments transform clinical workflows and contribute to more effective, patient-specific approaches in hemato oncology.
The level of mergers and acquisitions (M&A) in the market is moderate and gradually increasing as diagnostic companies aim to expand their molecular testing portfolios and access advanced genomic technologies. Firms are engaging in targeted acquisitions to integrate capabilities in next-generation sequencing (NGS), single-cell analysis, and real-time PCR-based assays for blood cancers such as leukemia, lymphoma, and multiple myeloma. Strategic collaborations between molecular diagnostic developers and biopharmaceutical companies are becoming more common, particularly to co-develop companion diagnostics for targeted therapies. While the market has not seen frequent large-scale mergers, selective M&A activity focused on hematologic malignancy diagnostics contribute to competitive consolidation and innovation.
 To learn more about this report, Download Free Sample Report
The impact of regulations on the market is high, as global regulatory bodies impose strict standards for the clinical validation, safety, and effectiveness of molecular diagnostic tests. Agencies such as the FDA (U.S.), EMA (Europe), and PMDA (Japan) require extensive clinical evidence to support the use of diagnostics in hematologic malignancies such as leukemia, lymphoma, and myeloma. The FDA’s oversight of companion diagnostics for targeted therapies-especially for conditions like AML-demands rigorous analytical performance and clinical utility data. In Europe, the IVDR has added complexity to the approval process, requiring detailed technical documentation and third-party conformity assessments. In addition, patient privacy regulations such as HIPAA and GDPR affect how genomic data is collected and managed in research and clinical settings. These frameworks can lengthen product development timelines and significantly shape investment and innovation strategies within the market.
Product expansion in the market is moderate to high, driven by the rising need for precise, multi-parameter diagnostic solutions targeting hematologic malignancies such as leukemia, lymphoma, and myeloma. Developers are increasingly focusing on broadening their assay menus and integrating next-generation sequencing (NGS), digital PCR, and flow cytometry into comprehensive test panels. This trend supports the detection of multiple genetic markers and rare mutations in a single workflow. However, expanding product portfolios requires balancing innovation with technical validation, clinical utility, and compatibility with evolving therapeutic regimens. In addition, collaborations with pharmaceutical companies for companion diagnostics and investments in biomarker discovery contribute to broader testing capabilities, supporting more personalized and targeted treatment approaches across diverse patient populations.
Regional expansion in the market is moderate, supported by gradual improvements in cancer awareness, diagnostic accessibility, and healthcare infrastructure in emerging regions. While North America and parts of Europe maintain a strong presence due to established clinical systems and reimbursement mechanisms, growth in regions such as Asia-Pacific, Latin America, and the Middle East is progressing steadily. Countries in Asia-Pacific are enhancing genomic capabilities through policy support and increased research funding, though access remains uneven across rural and urban areas. Similarly, Latin America and the Middle East are seeing incremental adoption of molecular diagnostics, aided by national cancer programs and infrastructure development. These factors contribute to a measured, region-by-region expansion of hemato oncology testing services.
Analyst Perspective
The Hemato Oncology Testing Market is expected to witness steady growth as precision medicine becomes increasingly integrated into the diagnosis and management of hematologic malignancies. Expanding adoption of molecular diagnostics, next generation sequencing, digital PCR, and minimal residual disease testing is improving diagnostic accuracy and supporting personalized treatment decisions. Growing demand for biomarker driven testing, coupled with increasing clinical utilization of companion diagnostics, is strengthening market expansion. Continued investments by diagnostic companies in assay development, laboratory automation, and strategic collaborations are expected to enhance testing accessibility and workflow efficiency. Advancements in genomic technologies will remain central to the market's long term growth trajectory.
Cancer Insights
Based on cancer, the lymphoma segment led the market with the largest revenue share of 46.7% in 2025 and anticipated to grow at fastest CAGR over the forecast period. The lymphoma segment is dominating the market in 2024 with a share of 47.04% and is expected to showcase the fastest CAGR of over 13.4% over the forecast period. The growing prevalence and improved survival outcomes for lymphoma especially in younger patients-drive ongoing demand for early, accurate, and personalized diagnostics. According to the Leukemia & Lymphoma Society, in 2024, approximately 89,190 new lymphoma cases were found in the U.S., with 8,570 cases of Hodgkin lymphoma (HL) and 80,620 cases of non-Hodgkin lymphoma (NHL). Growing FDA clearance for advanced lymphoma diagnostic technology is also driving segment growth.
 To learn more about this report, Download Free Sample Report
Leukemia is expected to grow significantly over the forecast period. The increasing prevalence of blood cancer is a driving factor of this segment. Multiple genetic and environmental risk factors the a factsheetre identified in the development of leukemia. According to the leukemia and lymphoma society factsheet 2023-2024, around 456,481 individuals in the U.S. are either living with leukemia or in remission. Males are affected more than females, with about 35.5% more men living with leukemia, and higher rates of diagnosis and mortality among them. Leukemia ranks as the tenth most common cancer in the U.S., with its age-adjusted incidence rate rising by 9.4% from 12.71 per 100,000 in 1975 to 13.91 per 100,000 in 2020. Some of the most common tests for diagnosis of leukemia include repeated Complete Blood Count (CBC) tests and bone marrow examinations post diagnosis of symptoms.
Product Insights
Based on product, the services segment led the market with the largest revenue share of 58.2% in 2025, and it is likely to maintain its dominance over the forecast period. Service providers include specialist diagnostic consulting services and patient education services, which offer patients with specific pre- and postdiagnosis care. The majority of these services offer customized plans for individual patients, which are anticipated to grow at a significant rate in the near future. Furthermore, a rise in prevalence of leukemia and myeloma cancers, as well as increased awareness about advanced therapies, such as personalized medicine, have fueled the growth of the services segment.
The assay kits and reagents segment is expected to grow at a notable CAGR over the forecast period. They are designed to detect specific biomarkers, genetic mutations, and other indicators of blood cancer, enabling healthcare professionals to diagnose & treat the disease more effectively. The increasing demand for accurate and rapid diagnostic tests is expected to drive the adoption of assay kits and reagents. In addition, advancements in molecular diagnostics and the development of new technologies, such as Next-Generation Sequencing (NGS), are expected to contribute to market growth.
Technology Insights
Based on technology, the PCR segment led the market with the largest revenue share of 31.1 % in 2025, and it is likely to maintain its dominance over the forecast period. Use of PCR has been key in the diagnosis of blood cancers, as these tests are highly sensitive and detect the presence of various biomarkers in bone marrow & blood cells. PCR is highly efficient in detecting blood cancer cells that are not typically detected by cytogenic techniques, such as FISH. Furthermore, the use of PCR has also been vital in determining a patient’s molecular response to therapies.
The NGS segment is expected to witness the fastest CAGR of 12.7% during the forecast period, due to various advantages this technology offers, such as more sensitivity and specificity. Several cancer researchers have deemed the substantial importance of this technology in hemato-oncology and have put efforts into developing bioinformatics algorithms that could be utilized for cancer screening and test development. For instance, in December 2023, Huntsman Cancer Institute at the University of Utah stated that NGS-based detection has shown a significant potential to predict the risk of relapse of MRD in young adults and children.
End Use Insights
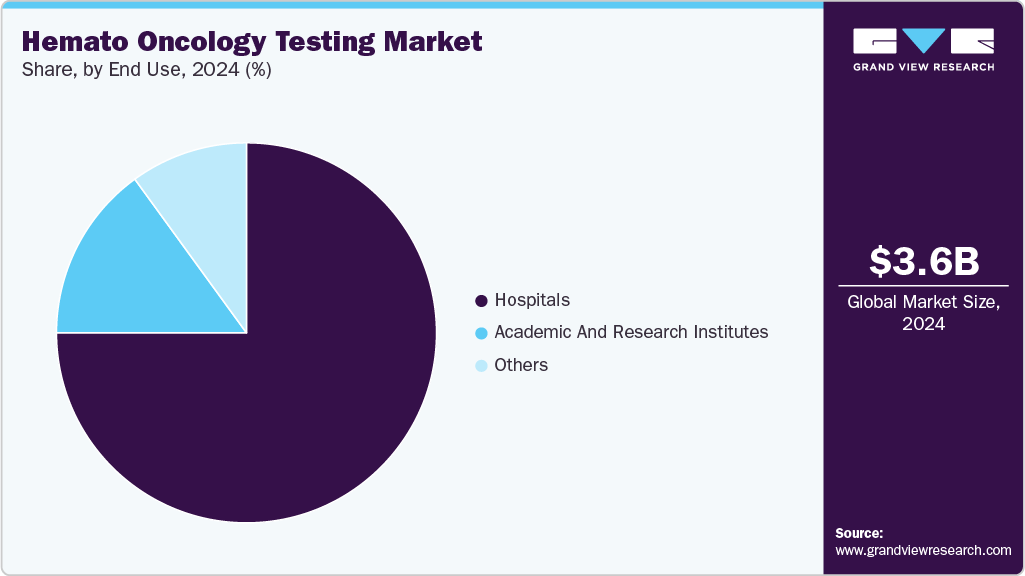
Based on end-use, the hospitals segment led the market with the largest revenue share of 75.0% in 2025. Hospital laboratories are vital components of the healthcare system, serving either within hospitals or as attached facilities. They can be categorized as public or private, catering to specific patient populations. Increase in collaborations between key players and hospitals to introduce novel testing methods for blood cancers is expected to drive market growth. For instance, in March 2025, Mayo Clinic Laboratories and KYAN Technologies entered into partnership to bring KYAN’s Optim.AI, an AI-driven ex-vivo drug sensitivity test to the U.S. market. This innovative platform helps identify optimal cancer therapies using minimal biological material, aiding both treatment decisions and drug development through functional precision medicine.
The academic & research institutes segment is expected to grow significantly over the forecast period. They are likely to remain key drivers of the market growth. These institutions are at the forefront of identifying novel biomarkers, developing innovative diagnostic techniques, and exploring new avenues for early detection, accurate diagnosis, & personalized treatment strategies. As research and study in this sector increase over the forecast period, the market is expected to grow. A growing number of research institutes and laboratories across the globe are likely to increase the demand for advanced and effective diagnostic techniques. The rising demand for standardization in techniques, such as dPCR, is likely to boost the adoption over the coming years. Moreover, increased funding for public and private research organizations is expected to further augment the demand for hemato-oncology products.
Regional Insights
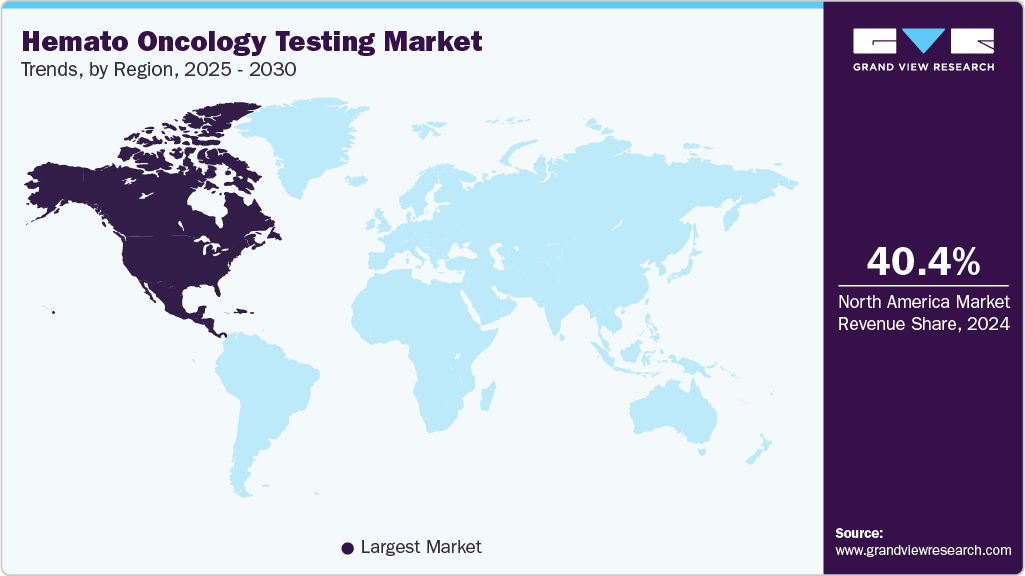
North America dominated the hemato oncology testing market with the largest revenue share of 38.2% in 2025, and it is anticipated to witness the fastest CAGR of 14% over the forecast period. The region’s dominance is driven by several factors, such as increasing prevalence of blood cancer, increasing R&D studies and trials, and technological advancements in diagnostic methods. Various diagnostic tools & techniques are available in the market, including liquid biopsy, Positron Emission Tomography (PET), Next-Generation Sequencing (NGS) testing solutions, and molecular testing.
 To learn more about this report, Download Free Sample Report
U.S. Hemato Oncology Testing Market Trends
The hemato oncology testing market in the U.S. held the largest share in the North America region in 2025, driven by the high prevalence of blood cancer. This can be attributed to several factors, including an aging population, environmental exposures, and genetic predispositions. In addition, advancements in diagnostic techniques have led to early detection and improved reporting of these cancers. Regardless of the underlying causes, the pervasiveness of blood cancer presents a formidable challenge for healthcare providers, researchers, and policymakers, necessitating a concerted effort to develop innovative strategies for prevention, early detection, & personalized treatment approaches.
Moreover, growing strategic initiatives between key players and diagnostic clinics and laboratories is contributing to regional growth. For instance, in January 2025, Mayo Clinic Laboratories and Lucence entered into strategic collaboration to expand global access to Lucence’s LiquidHALLMARK, a highly sensitive liquid biopsy test using next-generation sequencing (NGS) to analyze ctDNA and ctRNA for actionable cancer biomarkers. This partnership aims to enhance personalized cancer care by providing clinicians with deeper genomic insights for treatment planning. The integration of LiquidHALLMARK into Mayo’s offerings may significantly boost adoption of liquid biopsy and NGS-based tests in hematologic cancers by enabling non-invasive, real-time tumor profiling. It strengthens personalized treatment strategies, improves monitoring capabilities, and expands access to precision diagnostics in the U.S. oncology landscape.
Europe Hemato Oncology Testing Market Trends
The Europe hemato oncology testing industry is growing steadily. Blood cancers, including leukemia, lymphoma, and myeloma, are among the most common types of cancer in Europe. According to the European Cancer Information System (ECIS), there were an estimated 467,733 new cases of blood cancers in Europe in the last few years, accounting for approximately 8.5% of all new cancer cases. The European LeukemiaNet (ELN) guidelines for diagnosing & treating AML in adults are widely accepted by physicians and researchers. The rapid progress in genomic testing and the development of new therapies, such as FLT3, IDH1, IDH2, & BCL2 inhibitors, has led to an update of the guidelines. This revised version incorporates a new genetic risk classification system, updated response criteria, and treatment recommendations. Moreover, the market in the country is highly competitive, with multiple players offering a range of tests and technologies. Global companies, such as Bio Rad Laboratories, Asuragen, Alercell, and Abbott, have a presence in the EU hemato oncology testing industry, offering a variety of tests and diagnostic tools. As awareness of blood cancer and the importance of early detection continue to grow, the demand for innovative diagnostic solutions is expected to drive market growth in the coming years.
The hemato oncology testing industry in France is growing with support from national research programs and strong public-private partnerships. In September 2023, Cancer Research UK and the French National Cancer Institute (INCa) signed a new scientific partnership to collaborate on cancer research and improve patient outcomes. The partnership aimed to share knowledge and expertise in cancer research & treatment, develop new treatments & therapies, and enhance international cooperation & collaboration, address common cancer challenges, such as increasing cancer incidence, and improve patient access to innovative treatments. The agreement facilitated the exchange of researchers, scientists, and clinicians between the UK and France, fostering a stronger connection between the two countries' cancer research communities.
The German hemato oncology testing industry is a highly competitive and rapidly evolving landscape, driven by technological advancements, increasing demand for personalized medicine, and government initiatives to improve healthcare outcomes. The market is characterized by a mix of local & international players, including Siemens Healthcare, Roche Diagnostics, Abbott Diagnostics, and Bio-Rad Laboratories. German companies such as bioMérieux, Ortho-Clinical Diagnostics (OCD), and Greiner Bio-One are also major players. Companies form partnerships with research institutions, pharmaceutical companies, and other market players to access new technologies and expertise. Manufacturers further focus on improving the cost-effectiveness of their products and services to remain competitive in a price-sensitive market.
Asia Pacific Hemato Oncology Testing Market Trends
The Asia Pacific hemato oncology testing industry is expected to grow significantly due to the rising demand for treatment options and the increasing incidence of various lymphoma types during the forecast period. Key market players in the region are actively involved in R&D, resulting in a robust pipeline of potential treatments. For instance, Kura Oncology's ongoing clinical trial for tipifarnib, a pipeline candidate being investigated for treating peripheral T-cell lymphoma, demonstrates the company's commitment to advancing innovative therapies for patients.
In addition, there has been a growing interest and investment in developing liquid biopsy tests for blood cancers in Asia. These noninvasive tests can detect and monitor cancer cells or biomarkers in a patient's blood or other bodily fluids, providing an alternative to traditional tissue biopsies. Furthermore, players in the region are focusing on advancements in genomic profiling and precision medicine, leading to the development of targeted diagnostic tests that can identify specific genetic mutations or biomarkers associated with blood cancers. This information can guide personalized treatment decisions.
Japan hemato oncology testing industry is expected to witness rapid expansion, propelled by the government's substantial investments aimed at combating the country's escalating cancer burden. This surge in cancer prevalence is due to Japan's rapidly aging demographics, with one of the highest median ages worldwide at 44 years. Distinguishing itself from neighboring countries, Japan has implemented nationwide cancer screening initiatives, a proactive measure to address its rising cancer prevalence.
For instance, in January 2021, Illumina partnered with Otsuka Pharmaceuticals to develop and commercialize an IVD genomic profiling testing kit for patients in Japan with blood cancers. Such partnerships are anticipated to drive market growth in the region.
Latin America Hemato Oncology Testing Market Trends
Latin America hemato oncology testing industry is growing due to the expansion of healthcare infrastructure and increased investment in the healthcare sector. Many countries in the region are witnessing improvements in their healthcare systems, including the establishment of specialized cancer treatment centers and the modernization of diagnostic laboratories. Government initiatives to enhance healthcare access and affordability are enabling patients to undergo diagnostic testing.
In October 2023, The Pan American Health Organization (PAHO) and the International Agency for Research on Cancer (IARC) launched the Latin America and the Caribbean Code Against Cancer. This new Code, as part of the World Code Against Cancer, aimed to alleviate the cancer burden in the region by offering recommendations grounded in the latest scientific evidence. The development of this Code results from collaborative effort between PAHO and IARC, involving a large group of scientific experts from the region who reviewed the evidence and formulated recommendations for optimal cancer prevention.
The Brazil hemato oncology testing industry is progressing with support from national research institutions, growing awareness, and government initiatives. The government has implemented various initiatives to improve cancer care, including national cancer control programs and funding for cancer research & diagnostics. Policies subsidizing diagnostic tests & treatments make these services more affordable and accessible to the general population. Furthermore, government support for research and innovation in medical diagnostics fosters the development of new & improved diagnostic technologies. These policy measures expand the hemato oncology testing industry by enhancing the availability and quality of diagnostic services.
Middle East & Africa Hemato Oncology Testing Market Trends
The hemato oncology testing industry in the Middle East & Africa (MEA) is growing at a significant pace. The countries in the region are increasingly adopting molecular and genetic testing into their diagnostic protocols. These technologies allow more precise classification of hematologic malignancies, aiding in treatment decision-making and prognostication. The adoption of these advanced techniques, however, varies across the region, influenced by factors such as the availability of infrastructure, skilled healthcare professionals, and financial resources.
Moreover, the increasing number of clinical trials and research initiatives is driving innovation in hemato oncology testing within the MEA region. Academic institutions, research centers, and pharmaceutical companies are conducting clinical trials to evaluate novel diagnostic technologies, biomarkers, and therapeutic interventions for hematologic malignancies. Participation in international collaborative research networks and initiatives such as the Global Initiative for Cancer Registry Development (GICR) & the African Cancer Registry Network (AFCRN) are also expanding research opportunities and advancing knowledge in hemato oncology testing specific to MEA population.
The hemato oncology testing industry in Saudi Arabia is influenced by various factors, including technological advancements, increasing awareness about blood cancer, and the rapidly aging population. The Saudi government has prioritized healthcare as a key sector for development, leading to the establishment of specialized oncology centers equipped with state-of-the-art diagnostic technologies. These centers, particularly in major cities like Riyadh, Jeddah, and Dammam, are equipped with advanced imaging modalities, molecular diagnostic tools, and pathology laboratories capable of conducting comprehensive diagnostic workups for hematologic malignancies. This infrastructure investment is crucial for enhancing diagnostic accuracy, enabling timely treatment decisions, and improving patient outcomes across the Kingdom.
Key Hemato Oncology Testing Company Insights
Major market players engage in various strategies, such as distribution agreements, mergers and acquisitions, and expansions. Most crucially, they exhibit a high degree of innovation in product research and development to improve their market penetration.
Key Hemato Oncology Testing Companies:
The following key companies have been profiled for this study on the hemato oncology testing market.
-
F. Hoffmann-La Roche Ltd
-
Abbott
-
EntroGen, Inc.
-
Qiagen N.V.
-
Cepheid (Danaher Corporation)
-
Thermo Fisher Scientific, Inc.
-
Bio-Rad Laboratories, Inc.
-
Illumina, Inc.
-
Amoy Diagnostics Co., Ltd.
-
ASURAGEN, INC
-
ArcherDX, Inc. (IDT)
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Well Established Players (F. Hoffmann-La Roche Ltd., Abbott, QIAGEN N.V., Thermo Fisher Scientific, Inc., Illumina, Inc., Cepheid (Danaher Corporation))
- Expand hemato oncology testing portfolios through molecular diagnostics, next generation sequencing, polymerase chain reaction assays, companion diagnostics, minimal residual disease testing, and integrated laboratory workflows. Focus on product innovation, regulatory approvals, strategic collaborations, acquisitions, and expansion of precision oncology solutions to strengthen global market presence.
- Broad hemato oncology diagnostic portfolios, established global distribution networks, advanced research and development capabilities, strong regulatory expertise, and extensive installed laboratory instrument base. Ability to deliver integrated testing solutions across hospitals, cancer centers, and reference laboratories through instruments, consumables, software, and technical support.
- Large organizational structures may extend product development and commercialization timelines. Premium pricing, complex regulatory pathways, and dependence on reimbursement policies may limit adoption in cost sensitive healthcare systems and emerging markets.
Emerging Players (EntroGen, Inc., Bio-Rad Laboratories, Inc., Amoy Diagnostics Co., Ltd., ASURAGEN, INC., ArcherDX, Inc. (IDT))
- Focus on expanding specialized molecular diagnostics, targeted mutation analysis, biomarker testing, minimal residual disease assays, and companion diagnostic solutions. Emphasize product innovation, strategic partnerships, technology integration, and expansion into precision hematologic oncology applications to strengthen competitive positioning.
- Specialized expertise in molecular oncology diagnostics, agile product development, faster commercialization, and strong focus on niche biomarker testing applications. Ability to address evolving clinical requirements through targeted genomic assays, customized testing solutions, and advanced molecular technologies for hematologic malignancies.
- Comparatively smaller commercial footprint, narrower product portfolios, and limited manufacturing and distribution capabilities relative to multinational diagnostics companies. Dependence on specialized product segments and strategic collaborations may constrain broader market expansion and global competitiveness.
Recent Developments
-
In April 2025, researchers at the Advanced Centre for Treatment, Research and Education in Cancer (ACTREC), Tata Memorial Centre in Mumbai, developed RAPID-CRISPR. This novel test detects acute promyelocytic leukemia (APL) in less than three hours.
-
In January 2025, Adaptive Biotechnologies and NeoGenomics forged a multi-year partnership to enhance personalized disease monitoring for blood cancer patients. This collaboration integrates Adaptive's FDA-cleared clonoSEQ test for minimal residual disease (MRD) detection with NeoGenomics' COMPASS and CHART assessment services to provide clinicians with comprehensive insights for improved patient care.
-
In July 2024, Thermo Fisher Scientific partnered with the National Cancer Institute (NCI) for the myeloMATCH precision medicine trial. This trial utilizes next-generation sequencing (NGS) technology to rapidly identify genetic biomarkers in patients with acute myeloid leukemia (AML) and myelodysplastic syndrome (MDS).
Hemato Oncology Testing Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 4.5 billion
Market size value in 2026
USD 5.1 billion
Revenue forecast in 2033
USD 10.9 billion
Growth rate
CAGR of 11.5% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Cancer, product, technology, end-use, regional
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
F. Hoffmann-La Roche Ltd., Abbott, EntroGen, Inc., Qiagen N.V., Cepheid (Danaher Corporation), Thermo Fisher Scientific, Inc., Bio-Rad Laboratories, Inc., Illumina, Inc., Amoy Diagnostics Co., Ltd., ASURAGEN, INC., and ArcherDX, Inc. (IDT).
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Hemato Oncology Testing Market Report Segmentation
This report forecasts revenue growth and provides an analysis on the market trends in each of the sub-markets from 2021 to 2033. For this study, Grand View Research has segmented the global hemato oncology testing market report based on cancer, product, technology, end use, and region:
-
Cancer Outlook (Revenue, USD Million, 2021 - 2033)
-
Leukemia
-
Acute Myeloid Leukemia (AML)
-
Acute Lymphocytic Leukemia (ALL)
-
Chronic Lymphocytic Leukemia
-
Chronic Myeloid Leukemia
-
-
Lymphoma
-
Non-Hodgkin Lymphoma
-
Hodgkin Lymphoma
-
-
Myeloproliferative Neoplasms
-
Polycythemia vera (PV)
-
Essential thrombocythemia (ET)
-
Myelofibrosis (MF)
-
-
Other Cancers
-
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Assay Kits and Reagents
-
Services
-
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
PCR
-
Real-time qPCR
-
Digital PCR
-
-
IHC
-
NGS
-
Cytogenetics
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Academic and Research Institutes
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
India
-
China
-
Japan
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Argentina
-
Brazil
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
Kuwait
-
-
Research Methodology
The hemato oncology testing market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each hemato oncology testing segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Cancer
Revenue capture definition
Leukemia
Revenue is primarily captured through diagnostic testing for acute and chronic leukemia, including molecular assays, cytogenetic analysis, flow cytometry, immunophenotyping, fluorescence in situ hybridization, next generation sequencing, and minimal residual disease monitoring.
Lymphoma
Revenue flows from diagnostic and disease characterization tests for Hodgkin and Non Hodgkin lymphoma, including immunohistochemistry, flow cytometry, molecular diagnostics, fluorescence in situ hybridization, genomic profiling, and biomarker based monitoring throughout clinical management.
Myeloproliferative Neoplasms
Market value is derived from molecular and genetic testing for myeloproliferative neoplasms, including mutation analysis, cytogenetic testing, polymerase chain reaction assays, next generation sequencing, and laboratory evaluation supporting disease diagnosis and progression monitoring.
Other Cancers
Revenue is captured from diagnostic testing for additional hematologic malignancies, including multiple myeloma, myelodysplastic syndromes, plasma cell disorders, and rare blood cancers through molecular diagnostics, cytogenetics, immunophenotyping, and genomic testing.
Segment - Product
Revenue capture definition
Assay Kits and Reagents
Revenue is primarily captured through sales of assay kits, reagents, primers, probes, antibodies, controls, calibrators, sample preparation reagents, and other consumables used for molecular, immunological, cytogenetic, and flow cytometry based hemato oncology testing.
Services
Revenue flows from laboratory testing services, contract diagnostic services, biomarker analysis, genomic profiling, minimal residual disease testing, sample processing, result interpretation, and other specialized testing services supporting hematologic cancer diagnosis and monitoring.
Segment - Technology
Revenue capture definition
PCR
Revenue is primarily captured through polymerase chain reaction based testing, including real time qPCR and digital PCR assays, reagents, and workflows used for mutation detection, gene fusion analysis, minimal residual disease monitoring, and disease classification.
IHC
Revenue flows from immunohistochemistry based testing used to detect protein biomarkers, classify hematologic malignancies, differentiate disease subtypes, and support diagnostic evaluation through antibodies, staining reagents, and laboratory testing procedures.
NGS
Market value is derived from next generation sequencing based testing for comprehensive genomic profiling, mutation detection, gene fusion identification, and biomarker analysis supporting diagnosis, prognosis, treatment selection, and disease monitoring in hematologic cancers.
Cytogenetics
Revenue is captured through cytogenetic testing methods, including karyotyping and fluorescence in situ hybridization, used to identify chromosomal abnormalities for diagnosis, risk stratification, prognosis, and therapeutic decision making in hematologic malignancies.
Segment - End Use
Revenue capture definition
Hospitals
Revenue is primarily captured through diagnostic testing performed in hospital laboratories for the diagnosis, disease classification, treatment selection, and monitoring of hematologic malignancies using in house and outsourced testing platforms.
Academic and Research Institutes
Revenue flows from research based diagnostic testing, biomarker discovery, translational research, clinical studies, and validation of novel testing technologies supporting advancements in hematologic oncology diagnostics and precision medicine.
Others
Market value is derived from testing conducted by independent diagnostic laboratories, specialty cancer centers, reference laboratories, and contract research organizations providing specialized hemato oncology diagnostic and monitoring services.
Estimation Model
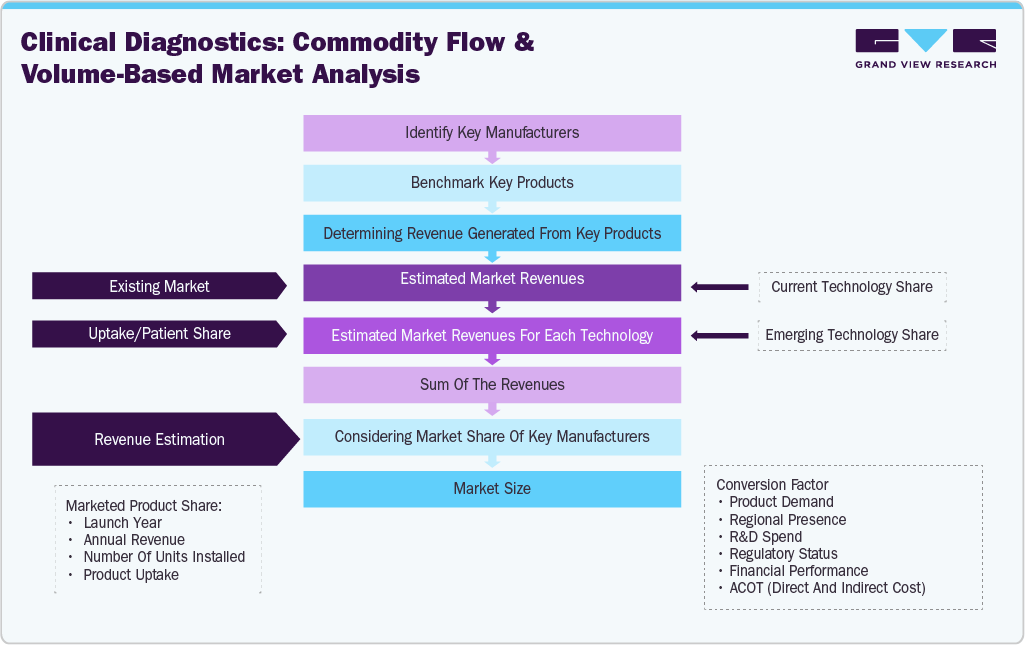
The Hemato Oncology Testing Market size was estimated by identifying key manufacturers, benchmarking their hemato oncology testing portfolios, and analyzing revenue generated from relevant products and diagnostic services. Market revenues were further validated using technology wise patient adoption trends and uptake across hematologic malignancy testing, followed by aggregation of segment revenues and adjustment based on the market share of leading companies to derive the final market size.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Hemato Oncology Testing Competitive Landscape & Technology Assessment
Assessed the global hemato oncology testing market across molecular diagnostics, next generation sequencing, polymerase chain reaction, immunohistochemistry, cytogenetics, and minimal residual disease testing. Evaluated competitive positioning, product portfolios, technology advancements, strategic developments, and adoption trends across hospitals, cancer centers, reference laboratories, and academic research institutes.
Helped the client identify technology adoption opportunities, benchmark competitive capabilities, evaluate product differentiation, prioritize strategic investments, and assess market expansion opportunities across the hemato oncology testing industry.
Hemato Oncology Testing Product & Technology Benchmarking Study
Delivered comprehensive benchmarking of hemato oncology testing platforms across molecular diagnostics, digital PCR, real time PCR, next generation sequencing, immunohistochemistry, cytogenetics, and companion diagnostics. Assessed technology performance, analytical sensitivity, workflow efficiency, laboratory integration, automation capabilities, and product differentiation among leading market participants.
Enabled the client to evaluate technology competitiveness, identify innovation opportunities, benchmark product development strategies, and prioritize investments in precision diagnostics, minimal residual disease testing, biomarker analysis, and genomic profiling technologies.
Hemato Oncology Testing Laboratory Adoption & Commercialization Assessment
Assessed laboratory infrastructure, precision oncology testing trends, biomarker adoption, reimbursement landscape, regulatory environment, procurement practices, and commercialization pathways influencing the adoption of hemato oncology testing solutions across major regional markets.
Supported commercialization planning by identifying market entry opportunities, evaluating customer adoption patterns, assessing operational and investment considerations, mitigating commercialization risks, and strengthening long term growth strategies across hospitals, cancer centers, reference laboratories, and diagnostic service providers.
Frequently Asked Questions About This Report
Some key players operating in the hemato oncology testing market include Cepheid, Amoy Diagnostics Co., Ltd., EntroGen, Inc., Asuragen, Inc., and ArcherDX, Inc.
Key factors that are driving the hemato oncology testing market growth include the rising prevalence of blood cancer, increasing drug diagnostics co-development, and the availability of advanced molecular diagnostics techniques for hemato oncology testing.
The global hemato oncology testing market is expected to grow at a compound annual growth rate of 11.5% from 2026 to 2033 to reach USD 10.9 billion by 2033.
The global hemato oncology testing market size was estimated at USD 4.5 billion in 2025 and is expected to reach USD 5.1 billion in 2026.
The Asia Pacific hemato oncology testing industry is expected to grow significantly due to the rising demand for treatment options and the increasing incidence of various lymphoma types during the forecast period.
Based on product, the services segment held a majority share of 58.2% in 2025, and it is likely to maintain its dominance over the forecast period. Service providers include specialist diagnostic consulting services and patient education services, which offer patients with specific pre- and postdiagnosis care.
Based on technology, the PCR segment led the market with the largest revenue share of 31.1 % in 2025. Use of PCR has been key in the diagnosis of blood cancers, as these tests are highly sensitive and detect the presence of various biomarkers in bone marrow & blood cells.
The increasing adoption of decentralized molecular testing and companion diagnostics is creating significant growth opportunities for the hemato oncology testing market. Healthcare providers and diagnostic laboratories are expanding the use of advanced molecular platforms to improve access to high sensitivity testing, reduce turnaround times, and support personalized treatment decisions for hematologic malignancies.
North America dominated the hemato oncology testing market with a share of 38.2% in 2025. This is attributable to the rising prevalence of lymphoma and myeloma and the growing demand for personalized therapy.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


