
- Home
- »
- Clinical Diagnostics
- »
-
Hematology Diagnostics Market Size Report, 2026-2033GVR Report cover

Hematology Diagnostics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product, By Test (Blood Count, Platelet Function, Hemoglobin, Hematocrit), By End-use (Hospitals, Diagnostic labs), By Region, And Segment Forecasts
Market Size, 2025
$8.5BMarket Estimate, 2026
$9.1BMarket Forecast, 2033
$13.1BCAGR, 2026–2033
5.4%Hematology Diagnostics Market Summary
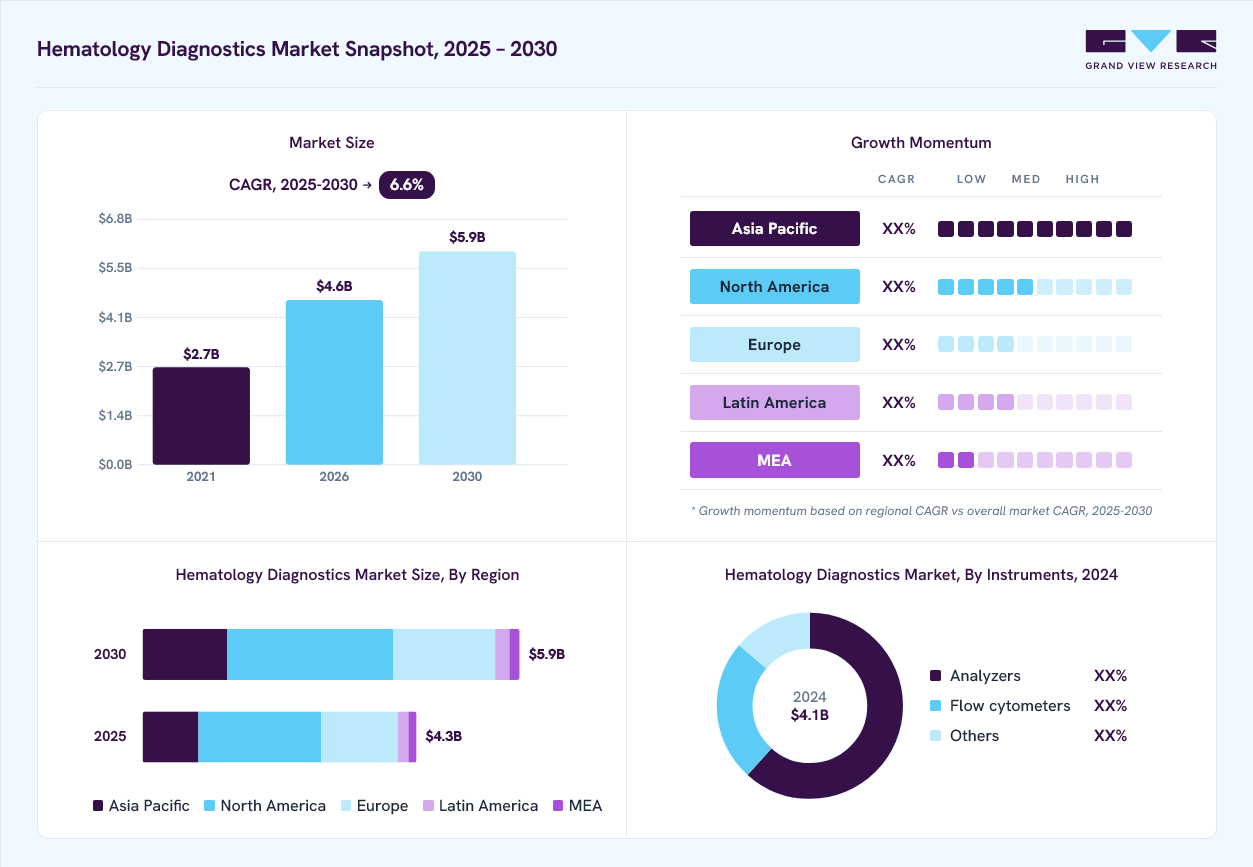
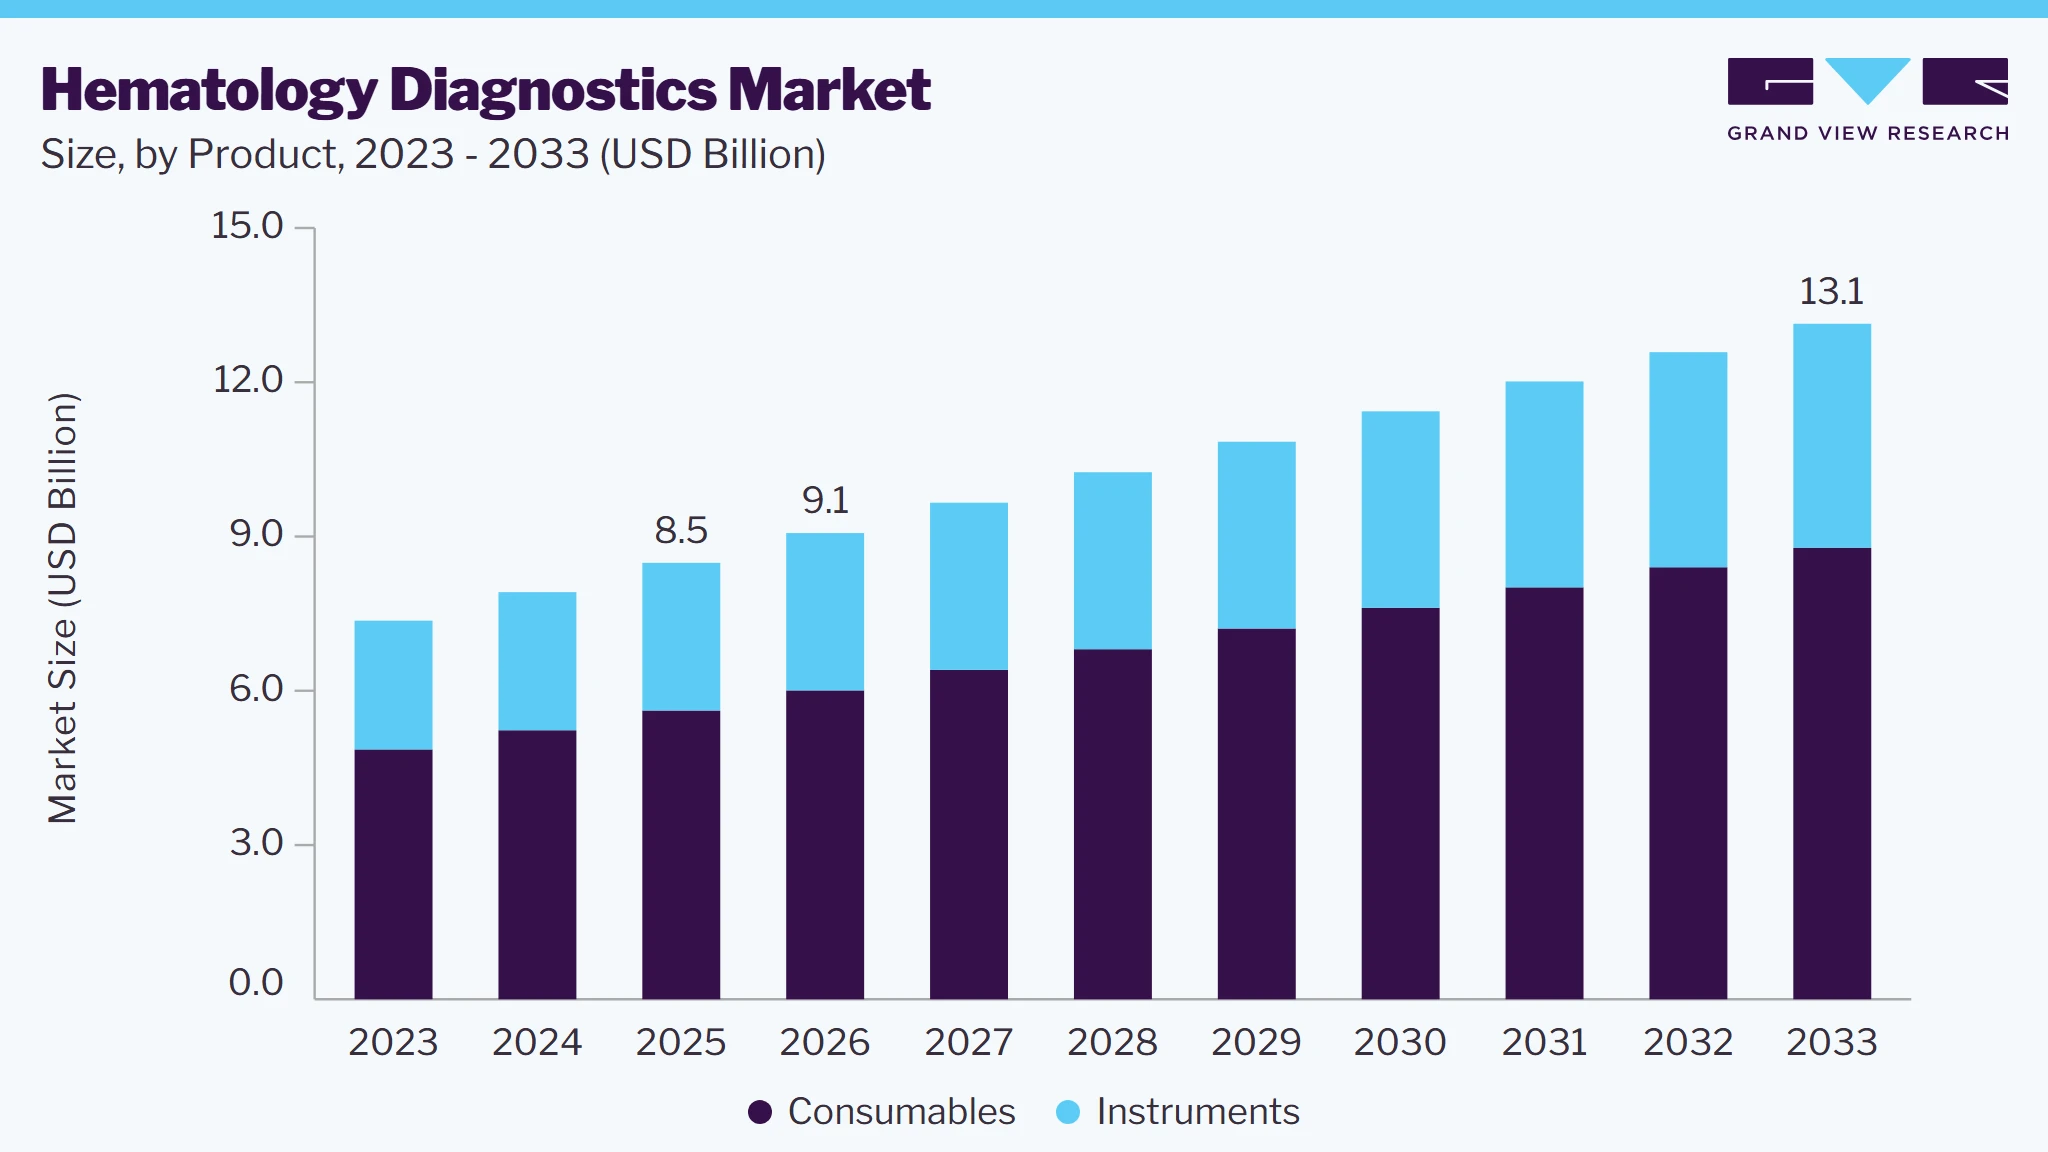
The global hematology diagnostics market size was valued at USD 8.5 billion in 2025 and is projected to grow from USD 9.1 billion in 2026 to USD 13.1 billion by 2033, at a CAGR of 5.4% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 33.4% in 2025. The increasing prevalence of blood cancer is a major factor contributing to the market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Consumables segment led the market with the largest revenue share of 66.2% in 2025.
- By test type: White blood cells (WBC) tests segment led the market with the largest revenue share of 26.7% in 2025.
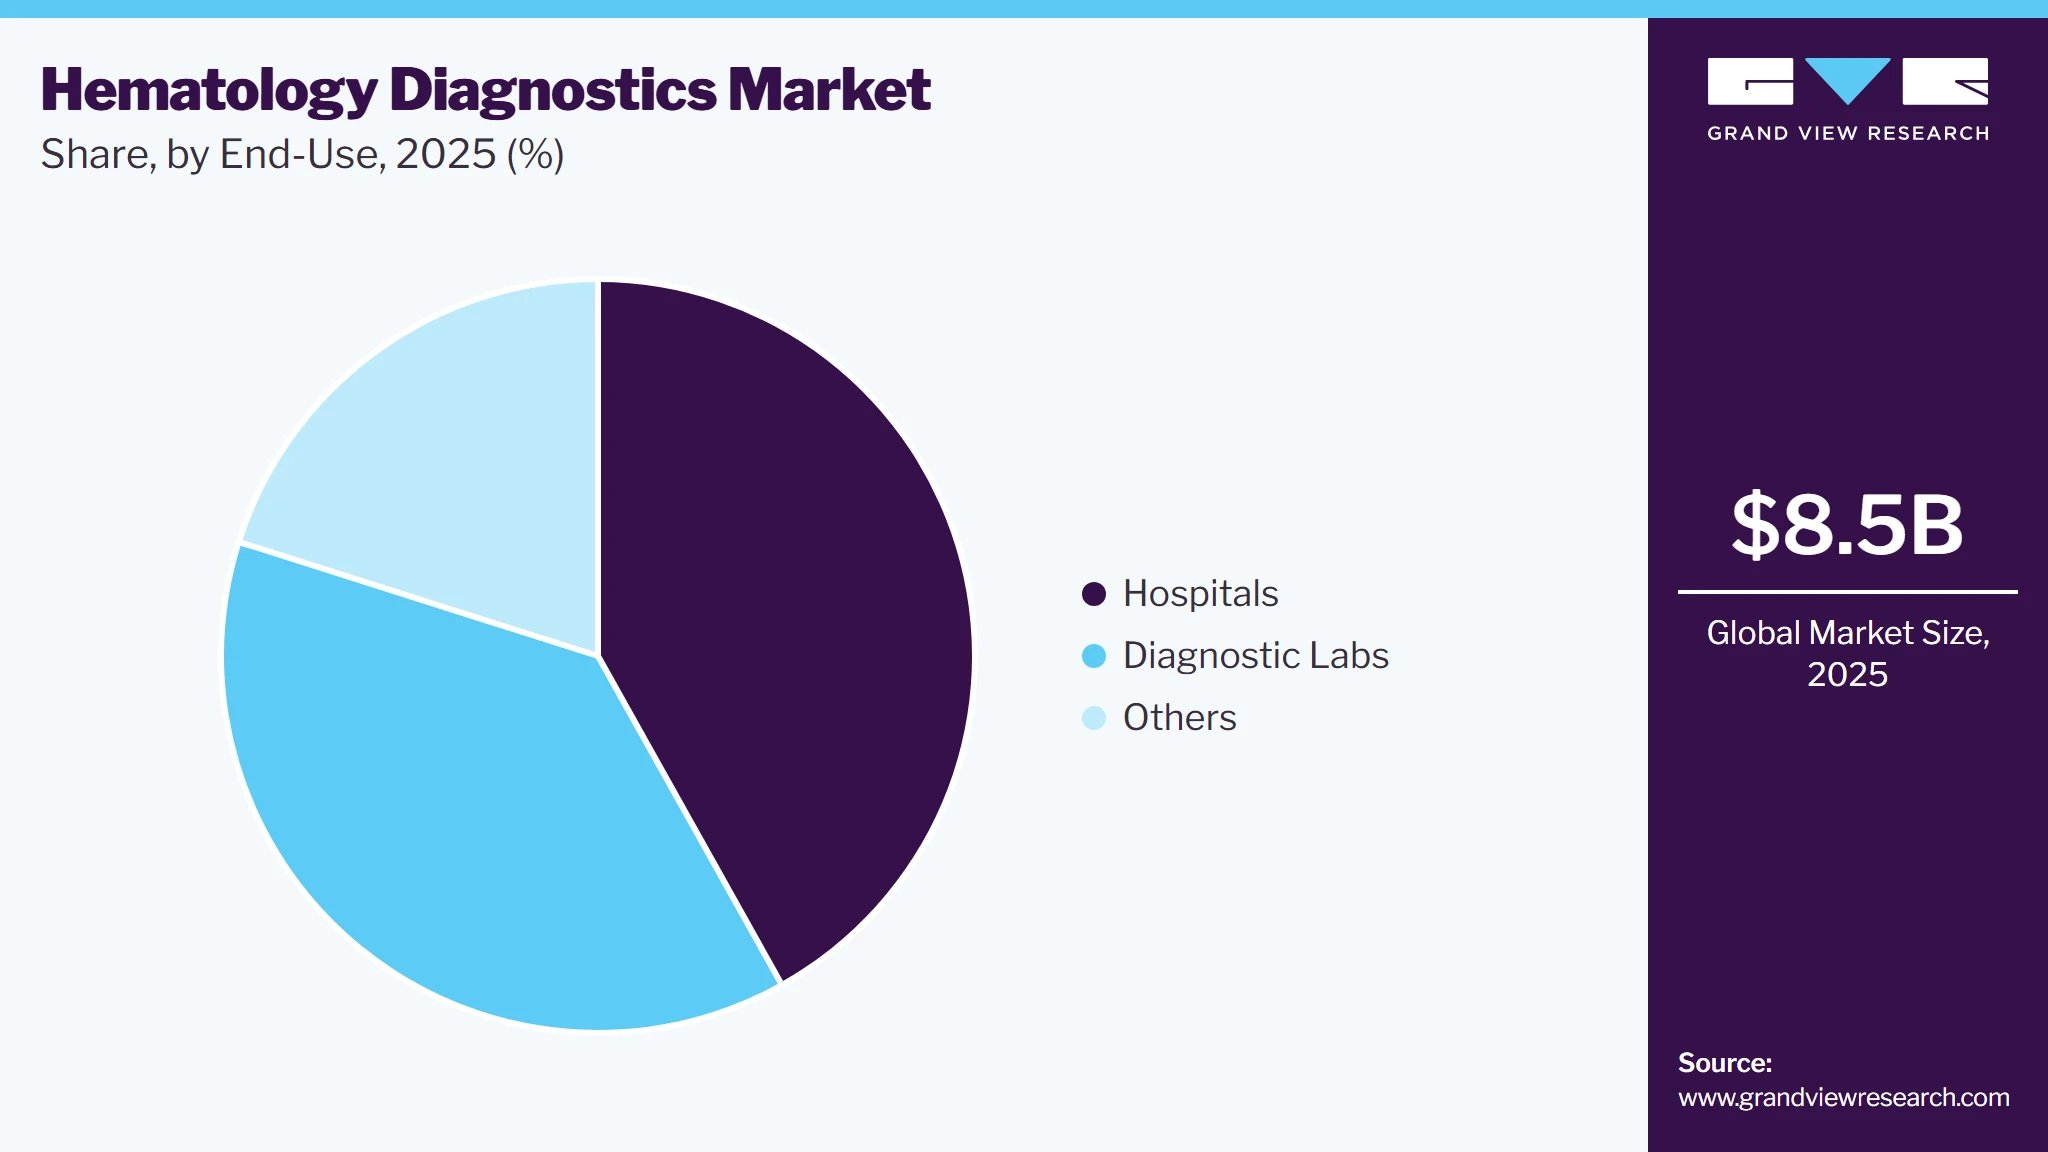
- By end use: Hospitals segment led the market with the largest revenue share of 41.9% in 2025.
Regional Highlights
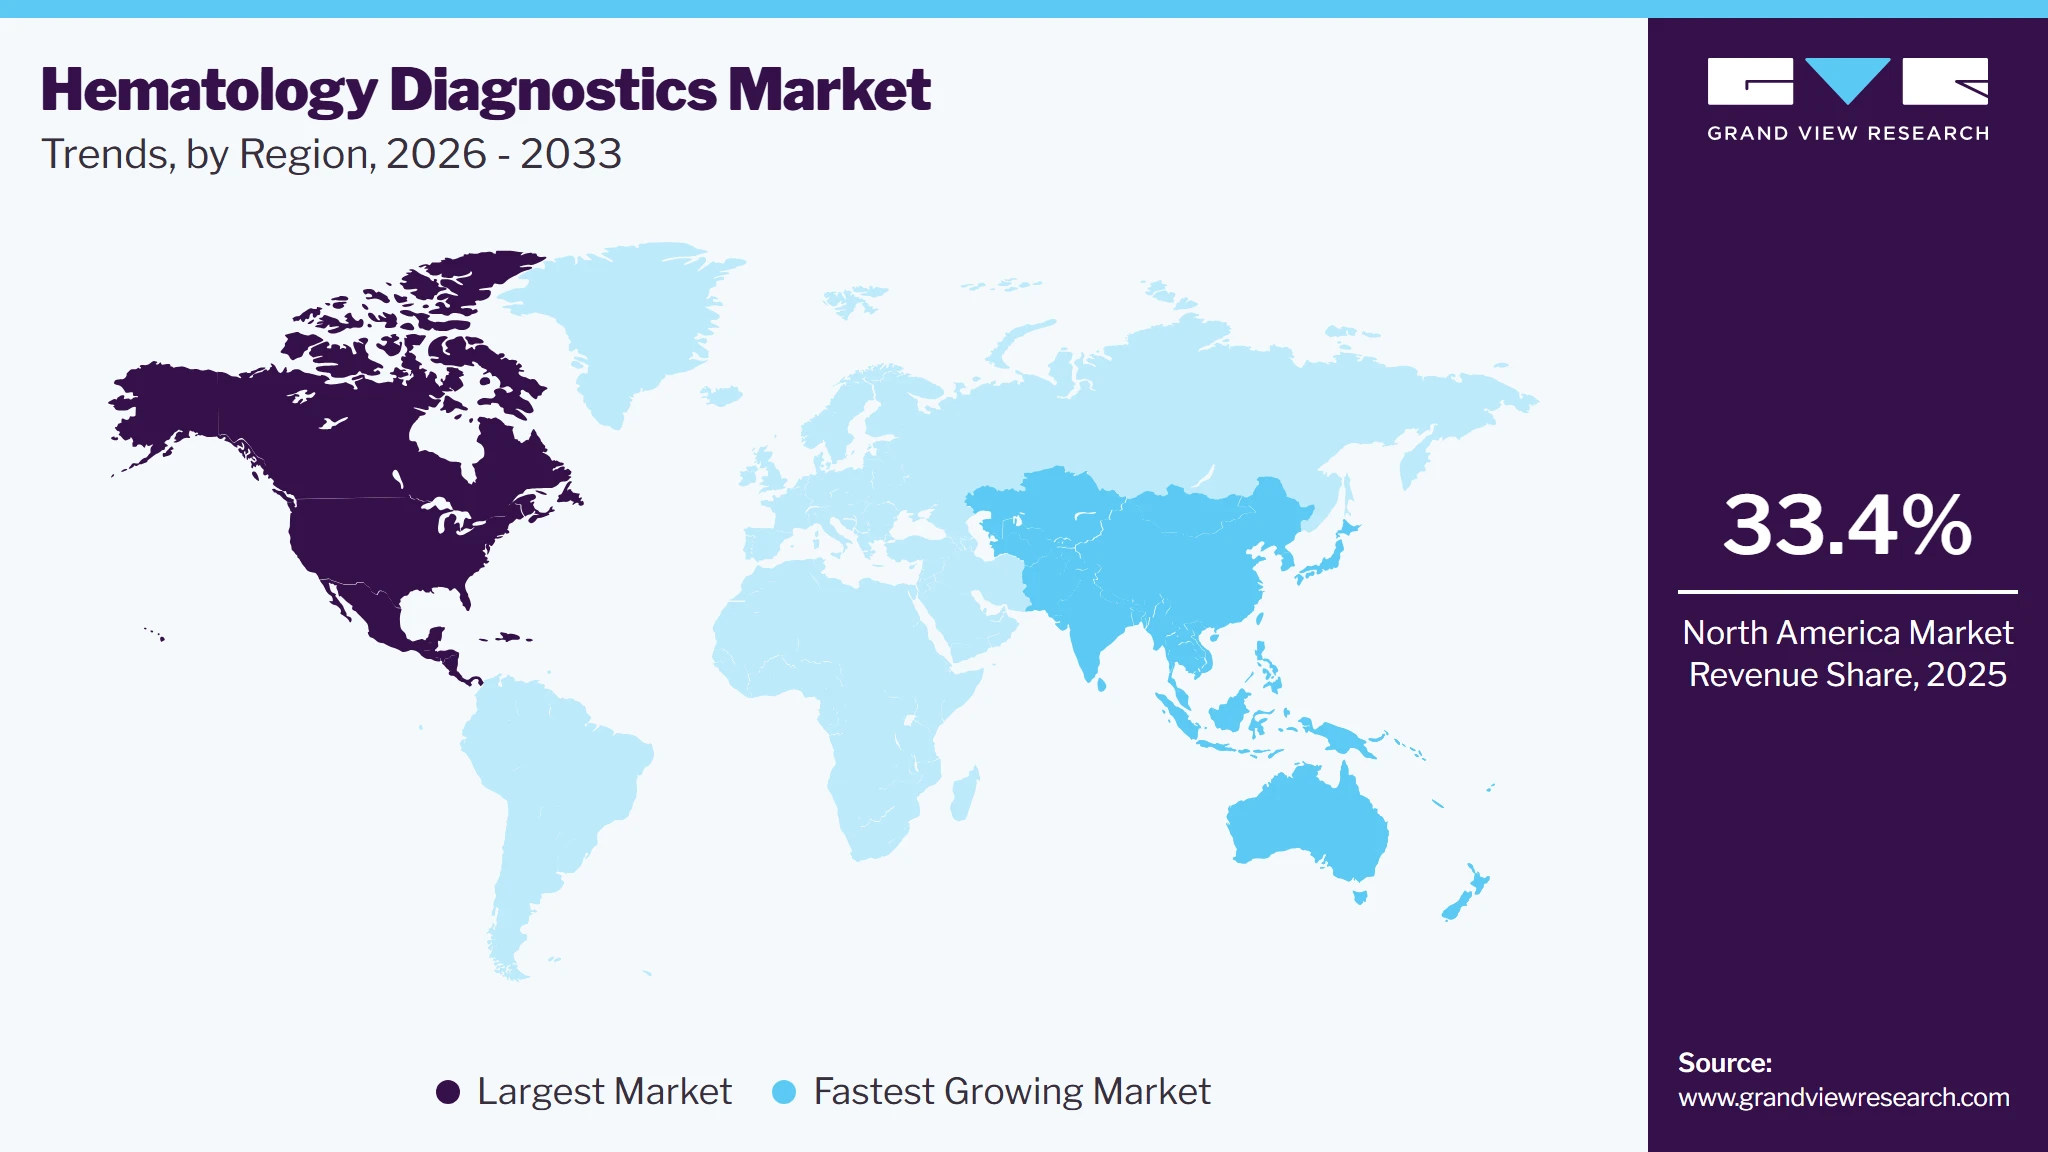
- Largest regional market: North America (33.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 8.5 Billion
- Estimated market size in 2026: USD 9.1 Billion
- Projected market size by 2033: USD 13.1 Billion
- CAGR (2026-2033): 5.4%
Prism AI by Grand View Research Free to tryAsk a question about the hematology diagnostics marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →According to the report published by PhRMA, in 2022, highlights that nearly 89,010 Americans were diagnosed with a form of lymphoma, and the U.S. is expected to see 1,958,310 new cancer cases and 609,820 cancer-related fatalities. Rising awareness about thalassemia and technological advancements in hematology analyzers are factors expected to drive the hematology diagnostic market growth in the forecast period.
 To learn more about this report, Download Free Sample Report
The ongoing technological advancements are aimed at delivering safer diagnoses with the shortest turnaround times and maximum efficiency. For instance, in December 2023, Agappe, an India based diagnostic technology brand has introduced its first of the kind in house manufactured HX series hematology equipment and the Mispa i200 series, an AE-powered Immunology CLIA analyzers, which aims at increasing the speed and accuracy of blood tests. Such advancements are anticipated to drive hematology diagnostics market growth.
The availability of user-friendly point-of-care (POC) hematological tests offers a twofold benefit. Firstly, it reduces the necessity for extensive user training, making it easier for healthcare professionals to operate these diagnostic tools effectively. Secondly, POC tests enable remote testing, allowing medical assessments to be conducted beyond traditional clinical settings. For instance, in January 2023, Seamaty highlighted the success of their SD1 Auto Dry Chemistry Analyzer in the market, this POC instrument excels at providing precise medical diagnoses. Notably, the streamlined tests significantly decrease the turnaround time, enhancing efficiency in patient care. The growing acceptance of such tests, owing to their ability to provide essential insights across various clinical contexts, is attributable to the growing market throughout the forecast period.
Hematology diagnostic equipment are anticipated to experience increased market demand, driven by rising automation and increased spending on diagnostic procedures. Several laboratories are adopting automation for the post-analytical, analytical, and pre-analytical steps to improve efficiency and standardize the process. For instance, in recent years, Tecan and Qiagen collaborated for automating whole blood sampling, reducing the risk of lab staff for coming in direct contact with infectious materials. This is anticipated to contribute to a heightened demand for automation, which would help the market drive market growth.
Market Dynamics
The hematology diagnostics market is driven by the increasing burden of blood disorders, rising incidence of cancer requiring hematological assessment, and growing demand for automated laboratory testing. Healthcare providers are adopting advanced hematology analyzers and integrated diagnostic systems to improve testing accuracy, reduce turnaround times, and enhance laboratory efficiency. The expansion of preventive health screening programs and routine complete blood count testing is also supporting market growth across hospitals and diagnostic laboratories. Continuous innovation in automation, digital workflow management, and high throughput analyzers is further improving diagnostic capabilities and laboratory productivity. For instance, in June 2026, Sysmex America received U.S. FDA clearance for the XR 10 Automated Hematology Analyzer, expanding access to advanced automated hematology testing for clinical laboratories and supporting modernization of diagnostic workflows. Increasing investments in laboratory infrastructure and diagnostic automation are expected to strengthen market expansion and improve access to reliable hematology testing across healthcare settings.
The increasing prevalence of blood disorders and the growing need for rapid and reliable diagnostic results are driving demand for advanced hematology diagnostic solutions. Healthcare providers are investing in integrated analyzers that improve analytical accuracy, increase sample processing capacity, and support timely clinical decision making. The expansion of routine health screening programs and greater emphasis on early disease detection are also contributing to broader adoption of modern hematology technologies. In addition, increasing investments in hospital laboratory modernization and the growing use of digital data management systems are improving diagnostic efficiency and supporting standardized testing practices. For instance, in January 2026, Sysmex America expanded its portfolio with the launch of the CN 9000 Automated Blood Coagulation Analyzer, strengthening its diagnostic offerings with enhanced throughput and operational efficiency for clinical testing. The availability of advanced diagnostic platforms capable of handling higher sample volumes is enabling healthcare facilities to address increasing testing demand while maintaining result quality. These developments are expected to support the continued adoption of comprehensive hematology diagnostic solutions across hospitals, diagnostic laboratories, and specialized healthcare centers.
The hematology diagnostics market faces challenges due to the high cost of advanced analyzers, integrated diagnostic platforms, and automated laboratory infrastructure. Small hospitals and independent diagnostic laboratories often face budget constraints that limit investments in high throughput systems and associated software solutions. In addition to capital expenditure, ongoing costs related to maintenance, quality control, calibration, reagents, and skilled personnel increase the overall cost of ownership. Variability in reimbursement policies across healthcare systems further affects the adoption of advanced hematology technologies, particularly in developing countries. These financial and operational barriers may delay equipment upgrades and reduce access to modern diagnostic solutions, limiting the adoption of advanced hematology diagnostics across resource constrained healthcare facilities. The need for regular software updates, compliance with evolving regulatory requirements, and continuous staff training further increases operational expenses. As a result, many healthcare providers continue to rely on conventional hematology systems, slowing the transition toward fully automated and technologically advanced diagnostic platforms.
The growing adoption of integrated diagnostic platforms and digital laboratory technologies presents a significant opportunity for the hematology diagnostics market. Healthcare systems are increasingly investing in connected diagnostic solutions that improve data management, streamline laboratory operations, and support faster clinical decision making. The integration of hematology analyzers with laboratory information systems and automated sample handling is enhancing operational efficiency while enabling higher testing volumes. Emerging economies are also expanding investments in diagnostic infrastructure, creating new opportunities for advanced hematology solutions. For instance, in June 2025, Sysmex America received U.S. FDA clearance for the XR 20 Automated Hematology Analyzer, expanding its next generation hematology portfolio with advanced analytical capabilities for routine clinical testing. Continued advancements in digital diagnostics and integrated laboratory solutions are expected to create growth opportunities for manufacturers while improving access to high quality hematology testing across diverse healthcare settings.
Market Concentration & Characteristics
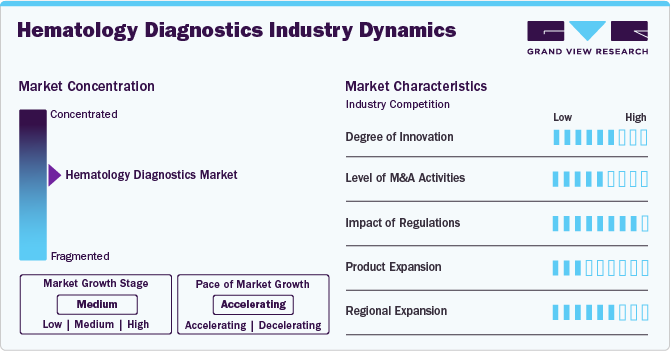
The market is characterized by moderate-to-high levels of innovation, including the frequent development and introduction of novel techniques and diagnostic technologies like laser-based flow cytometry and blood transferrin receptor kits, which define the global hematology diagnostics market. Key players are investing in innovative methods and technologies to meet the global demand of the market.
The market is characterized by the leading players with moderate levels of product launches and merger and acquisition (M&A) activity. Market players like Siemens, Healthineers and Abbott are involved in new product launches and merger and acquisition activities. Such strategic activities as M&A, partnership, and collaboration are only serving to increase company’s competitiveness and expand their geographic reach and help to enter new territories.
 To learn more about this report, Download Free Sample Report
The market is characterized by moderate-to-high levels of innovation, including the frequent development and introduction of novel techniques and diagnostic technologies like laser-based flow cytometry and blood transferrin receptor kits, which define the global hematology diagnostics market. Key players are investing in innovative methods and technologies to meet the global demand of the market.The market is characterized by the leading players with moderate levels of product launches and merger and acquisition (M&A) activity. Market players like Siemens, Healthineers and Abbott are involved in new product launches and merger and acquisition activities. Such strategic activities as M&A, partnership, and collaboration are only serving to increase company’s competitiveness and expand their geographic reach and help to enter new territories.
Regulations have a substantial impact on the hematology diagnostics market. Regulatory frameworks ensure product safety, efficacy, and accuracy, particularly for diagnostic devices and tests. Regulatory factors, including medical device regulations, patient safety standards, documentation requirements, and hygiene standards, have an impact on the hematology diagnostics market. These factors impact the development, manufacturing, and sales of hematology diagnostics equipment. Global regulatory standards are being standardized to accelerate the approval process for hematology diagnostic devices.
Product substitutes pose a moderate threat in the hematology diagnostics market. Hematology diagnostics products have experienced significant product expansion driven by standardization and design advancements. This means developing new and improved things to help doctors and nurses care for patients' better health during medical procedures. They are used for a wider range of treatments, making healthcare even better for everyone.
Several market players are expanding their business by entering new geographical regions to strengthen their market position and expand their product portfolio. Expansion strategies include forming partnerships with local distributors, establishing manufacturing facilities, and launching region-specific products to address local healthcare needs. This approach not only strengthens market position but also diversifies revenue streams.
Analyst Perspective
The hematology diagnostics market is expected to witness steady growth due to the increasing prevalence of blood disorders, expanding demand for routine blood testing, and continued adoption of automated diagnostic technologies. Advances in hematology analyzers, digital laboratory solutions, and integrated workflow systems are improving diagnostic accuracy and operational efficiency across healthcare settings. Growing investments in laboratory modernization and preventive healthcare programs are further supporting market expansion. In addition, product innovation, regulatory approvals, and strategic collaborations among leading manufacturers are strengthening competitive dynamics. The continued shift toward high throughput, standardized, and data driven diagnostic solutions is expected to create sustained opportunities for market participants.
Product Insights
Based on Product, the consumables segment led the market with the largest revenue share of 66.2% in 2025. Consumables further include reagents, stains and controls, and calibrators. The heightened requirement for consumables is driven by the growing need to diagnose blood disorders and other infections. For instance, in December 2023, Sysmex expanded its sales in Europe, which consisted of the reagents used in blood testing for identification of the Amyloid Beta, and Sysmex Corporation developed concentrated reagents for hematology analyzers. Furthermore, the segment's growth is being fueled by an increasing test volume due to rising awareness and early detection efforts.
Instruments are expected to witness the considerable growth with in forecast period. Increasing automation and technological advancements are anticipated to be the primary growth drivers for hematology analyzers. For instance, in July 2022, Horiba medical introduced a new series Yumizen H500 & H550 a benchtop compact analyzer, that provides safe and secure automated quality management and is equipped with Multi analysis modes. Instruments are efficient & reliable instruments, automated racks, and quality tools providing high-quality medical analysis with fast accurate results. Furthermore, another major benefit of utilizing hematology analyzers over traditional cell counting is large-scale capa city designed for all kinds of laboratories and analyses 100+ samples simultaneously in analyzers, which makes it an ideal choice for medical applications. Therefore, such technological advancements are propelling the demand for analyzers.
Test Insights
Based on Test Type, the white blood cells (WBC) tests segment led the market with the largest revenue share of 26.7% in 2025. Organizations such as the American Cancer Society are rising awareness about diseases and chronic conditions such as Neutropenia, which are caused low WBC counts, propelling the population towards having frequent WBCs test. The WBC tests aid in identifying infections, inflammation, and other health conditions that impact WBC count. Hematology diagnostics offer the unique benefit of determining the total WBC count through reliable diagnostic procedures. These tests are valuable for general health assessments during routine check-ups. Similarly, abnormal Complete Blood Count (CBC) test results often indicate underlying infections, creating a consistent demand for diagnosis among patients. This broad scope of application is anticipated to drive growth.
Platelet function segment is projected to grow at the fastest CAGR over the forecast period. Advanced diagnostic tools are in high demand due to the rising prevalence of hematological disorders such as thrombocytopenia and hemophilia. Advances in technology, such as point-of-care testing and wearable monitoring devices, have greatly enhanced the precision and effectiveness of platelet function tests. Increased awareness and extensive screening initiatives have increased the need, as old-age individuals worldwide, who are more prone to blood disorders, also contribute to the requirement for comprehensive diagnostic solutions.
End Use Insights
Based on End Use, the Hospitals segment led the market with the largest revenue share of 41.9% in 2025. This is attributable to growing hematology diagnostics demand in forensic labs and hospital medical labs for disease diagnosis, blood cell counts, detecting illegal drug use, monitoring therapeutic drug levels, protein analysis, blood typing, thyroid function assessment, and detecting the presence of antibodies. According to the British Society for Hematology report, hematology workforce in the UK has increased in hospitals in recent years and about, 6% of clinical hematology staff is due to retire within coming 3-5 years as compared to 11% of nursing staff.
 To learn more about this report, Download Free Sample Report
The diagnostics lab segment is expected to grow at the fastest CAGR of 7.0% over the forecast period. According to the American Clinical Laboratory Association, more than 7 million clinical laboratory tests are conducted annually in the U.S. As a result, the increasing number of diagnostic tests in these facilities and the demand for instruments are expected to drive demand. Additionally, the automation of diagnostic instruments is projected to lower the cost of the tests, consequently driving further demand.
Regional Insights
North America Hematology Diagnostics Market accounted for the largest revenue share of 33.4% in 2025. This high share is attributable to increasing prevalence of cancer; for instance, the global number of cancer sufferers is predicted to rise as lung cancer is the largest cause of cancer death worldwide, with an estimated cancer cases in the U.S. reaching 1.9 million in 2022. The rising incidence of diseases such as anemia, hemophilia, leukemia, sickle-cell anemia, lymphomas, and several infections has contributed to the emerging demand for hematology diagnosis. For instance, a PhRMA report, in 2022, about 184,000 Americans were estimated to be diagnosed with blood cancer. Same reports stated that the prevalence of sickle-cell anemia is about 100,00 individuals and nearly 3.2 million individuals are living with bleeding disorders. Such factors are poised to propel the diagnostics market.
 To learn more about this report, Download Free Sample Report
U.S. Hematology Diagnostics Market Trends
The hematology diagnostics market, U.S. held the largest share in the North America region in 2025. The rise of patient centered test kits and personalized diagnostics, with the emergence of blood related disorders, have boosted the market growth prospects. According to a recent report by Leukemia and Lymphoma Society, in 2023, an estimated 184,720 people in the U.S. are expected to be diagnosed with leukemia, lymphoma, or myeloma. Most cases of leukemia occur in older adults, the median age at diagnosis is 67 years. The growing prevalence of blood illness amongst the population is a rising demand for hematology diagnostic test kits and equipment. For instance, the American Society of Hematology, Sickle cell trait, a blood disorder, affects 1 million to 3 million Americans, and more than 100 million people worldwide carry the sickle cell trait. The presence of several pharmaceutical and medical device companies is also expected to boost the demand for the hematology diagnostics market.
Europe Hematology Diagnostics Market Trends
Hematology diagnostics market in Europe was identified as a lucrative region in this industry. A supportive regulatory framework in the region helps manufacturers to boost productivity and open a wide scope for developments in the region. For instance, in line with the European Commission's Health Technology Assessment (HTA) proposal, the European Hematology Association (EHA) supports a permanent mechanism for joint clinical assessments. This mechanism should concentrate on innovative technologies, such as in-vitro diagnostic devices, that address unmet medical needs or have a significant impact on public health.
The hematology diagnostics market in the UK is anticipated to witness significant growth over the forecast period due to the presence of several small and medium-sized companies that significantly contribute to the economy. The country has a reputation for quality solutions and services including blood test kits and blood diagnosis services via locally based several private blood and urine test services such as Bloods4you and The Blood Clinic. Hence, diagnostics devices are anticipated to witness significant demand in the forecast period
Germany hematology diagnostics market is expected to grow over the forecast period. With the ongoing developments in the regions, such as the German Cancer Research Center (DKFZ) is working on developing new diagnostic methods for leukemia and lymphoma using mass spectrometry. Global players such as Thermo Fischer, Danaher, and Abbott are consistently involved in carrying out strategic mergers and collaborations in the regions, which is anticipated to create lucrative opportunities in Germany.
The hematology diagnostics market in France is anticipated to witness significant growth over the forecast period. The diagnostics industry has been undergoing significant changes, especially in the wake of the COVID-19 pandemic. Recently, few companies have elaborated its interest in increasing their bioproduction capabilities and collaborating with government health sovereignty, for instance, in January 2024, HORIBA Medical introduced a CE-IVDR approved, HELO 2.0 automated hematology platform, offering higher modular solutions with a range of track-based system and quality-controlled parameters.
Asia Pacific Hematology Diagnostics Market Trends
Hematology diagnostics is anticipated to witness significant growth in the hematology diagnostics market. This is attributed to the presence of major market players and local players such as Sysmex Corporation and Agilent Technologies. In addition, this growth owes to the significantly increasing investments in hematology diagnostics technologies across the region, rise in per capita income leading to increased adoption of diagnostic and therapy products coupled with government initiatives to improve healthcare infrastructure are expected to fuel the regional growth. The rising adoption of devices with new advanced features in emerging countries such as China, Japan, and India is anticipated to drive the market growth over the forecast period.
The hematology diagnostics market in China is expected to grow over the forecast period due to the rise in per capita income is leading to increased adoption of diagnostic and therapy products. Government initiatives to improve healthcare infrastructure are expected to fuel the regional market growth. China's rapidly evolving healthcare landscape and patient needs played a significant role in driving the market.
Japan hematology diagnostics market is expected to grow over the forecast period due to the presence of some major companies, such as Sysmex Corporation, Sekisui medical Co., Ltd, Morimoto pharma offering molecular and hematology diagnostics kits. For instance, in Japan, in June 2022, Sysmex launched its XR- series, which is considered as flagship model, having models that includes sample sorting, sample archives, automated quality transportation all in one place, assisting for better and smooth diagnostics procedures. Several government organizations and academic & research institutes have a demand for these devices. Hence, major players in the market are adopting several strategies such as mergers & acquisitions and partnerships & collaborations to stay competitive in the market.
Latin America Hematology Diagnostics Market Trends
The hematology diagnostics market in Latin Americais expected to experience significant growth throughout the forecast period. The market is driven by the increasing prevalence of blood-related disorders such as anemia, leukemia, and hemophilia, coupled with a growing awareness regarding early diagnostic measures. Latin America’s aging population also contributes significantly to market growth, as hematological conditions are more common among the elderly. Advancements in diagnostic technologies, such as automated hematology analyzers and molecular diagnostics, are facilitating faster and more accurate test results, thereby boosting adoption.
The hematology diagnostics market in Brazil is anticipated to grow during the forecast period. The growth is fueled by the country's rising prevalence of hematological disorders, and expanding healthcare infrastructure. Brazil's healthcare sector is undergoing modernization, with an increased emphasis on the adoption of advanced diagnostic tools and technologies. Programs aimed at reducing the burden of non-communicable diseases are indirectly driving demand for diagnostic tests, including hematology diagnostics.
Saudi Arabia Hematology Diagnostics Market Trends
The hematology diagnostics market in Saudi Arabiais anticipated to experience substantial growth during the forecast period. These include a growing prevalence of hematological disorders such as sickle cell anemia and thalassemia, which are particularly common in the region due to genetic predispositions. Saudi Arabia's government initiatives under Vision 2033, which aim to diversify the economy and expand healthcare infrastructure, are expected to significantly benefit the diagnostics sector.
Key Hematology Diagnostics Company Insights
Some of the key players operating in the market include Abbott, Beckman Coulter, Inc., Siemens Healthineers, Mindray Medical International Limited, F. Hoffmann-La Roche Ltd, Sysmex Corporation, Bio-Rad Laboratories, EKF Diagnostics. The market is highly competitive, with a large number of manufacturers accounting for a majority of the share. New product developments, mergers and acquisitions, and collaborations are some of the major strategies adopted by these players to counter the stiff competition.
Key Hematology Diagnostics Companies
The following key companies have been profiled for this study on the hematology diagnostics market.
-
Abbott
-
Beckman Coulter, Inc.
-
Sysmex Corporation
-
Horiba
-
Bio-Rad Laboratories
-
Siemens Healthineers AG
-
F. Hoffmann-La Roche Ltd
-
Shenzhen Mindray Bio-Medical Electronics Co., Ltd.
-
NIHON KOHDEN CORPORATION.
-
EKF Diagnostics
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Well Established Players (Abbott, Beckman Coulter, Inc., Sysmex Corporation, Siemens Healthineers AG, F. Hoffmann-La Roche Ltd., Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Bio-Rad Laboratories)
- Focus on expanding comprehensive hematology diagnostics portfolios through automated hematology analyzers, flow cytometry platforms, coagulation testing systems, and integrated laboratory automation solutions. Emphasize new product launches, regulatory approvals, strategic collaborations, mergers and acquisitions, and investments in digital laboratory technologies, artificial intelligence, and workflow optimization to strengthen global market presence.
- Strong global distribution networks, extensive installed customer bases, broad diagnostic product portfolios, established regulatory expertise, and significant investments in research and development. Integrated laboratory automation platforms, reliable analytical performance, and long standing relationships with hospitals, diagnostic laboratories, and healthcare systems support widespread market adoption.
- High research and development expenditure, stringent regulatory requirements, premium product pricing, and dependence on capital investments by healthcare providers. Large organizations may also experience slower product customization, complex global operations, and longer commercialization timelines across diverse diagnostic portfolios.
Emerging & Regional / Specialized Players (Horiba, NIHON KOHDEN CORPORATION, EKF Diagnostics)
- Focus on developing specialized hematology analyzers, point of care hematology solutions, compact laboratory instruments, and cost effective diagnostic technologies for regional and mid sized healthcare facilities. Expand market presence through distributor partnerships, targeted product launches, clinical collaborations, and geographic expansion while addressing the growing demand for accessible hematology diagnostics.
- Competitive pricing, operational flexibility, specialized expertise in hematology diagnostics, and faster product development cycles enable these companies to address regional healthcare requirements. Focused product portfolios, responsive customer support, and adaptable solutions strengthen adoption across hospitals, diagnostic laboratories, and outpatient care settings.
- Limited global distribution capabilities, smaller manufacturing scale, comparatively lower research and development resources, and lower brand recognition than multinational competitors. These companies may also face challenges in securing global regulatory approvals, expanding international sales networks, and competing with diversified diagnostics companies offering comprehensive laboratory solutions.
Recent Developments
-
In September 2024, Scopio Labs, a medtech startup that creates AI-powered workflow solutions, partnered with Beckman Coulter, a world leader in clinical diagnostics, to hasten the adoption of Scopio's next-generation peripheral blood smear platforms. This partnering with Scopio Labs is majorly to promote hematology digital cell morphology platform adoption.
-
In January 2024, HORIBA Medical introduced a CE-IVDR approved, HELO 2.0 automated hematology platform, offering higher modular solutions with a range of track-based system and quality-controlled parameters.
-
In May 2023, Siemens Healthineers launched next-gen hematology analyzers products. The products include Atellica HEMA 580 and 570 analyzers. The analyzer provides intuitive interfaces & multi-analyzer automation connectivity to remove workflow roadblocks supporting faster results.
-
In July 2023 Sysmex launched its XR- series, which is considered as flagship model, having models that includes sample sorting, sample archives, automated quality transportation all in one place, assisting for better and smooth diagnostics procedures.
Hematology Diagnostics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 8.5 billion
Estimated market size in 2026
USD 9.1 billion
Projected market size by 2033
USD 13.1 billion
Growth rate
CAGR of 5.4% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, test type, end use, region
Regional scope
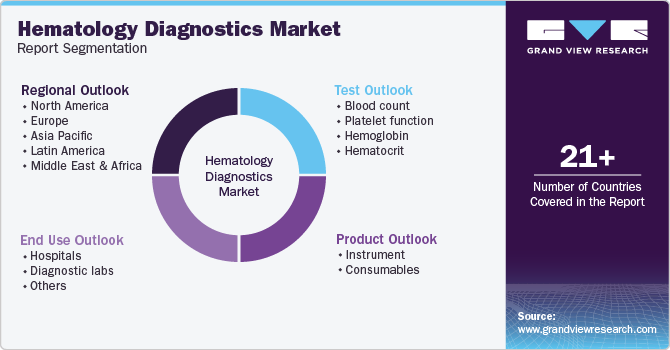
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; and Kuwait
Key companies profiled
Abbott, Beckman Coulter, Inc., Sysmex Corporation, Horiba, Bio-Rad Laboratories, Siemens Healthineers AG, F. Hoffmann-La Roche Ltd., Shenzhen Mindray Bio-Medical Electronics Co., Ltd., NIHON KOHDEN CORPORATION, and EKF Diagnostics.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Hematology Diagnostics Market Report Segmentation
This report forecasts revenue growth at global, regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global hematology diagnostics market report based on product, test, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Outlook (Revenue, USD Million, 2021 - 2033)
-
Instrument
-
Analyzers
-
Flow cytometers
-
Others
-
-
Consumables
-
Reagents
-
Stains
-
Others Accessories
-
-
-
Outlook (Revenue, USD Million, 2021 - 2033)
-
Blood count
-
Platelet function
-
Hemoglobin
-
Hematocrit
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Diagnostic labs
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The hematology diagnostics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each hematology diagnostics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Product
Revenue capture definition
Instrument
Revenue is primarily captured from hematology analyzers, flow cytometers, and related diagnostic instruments used to perform complete blood count analysis, differential cell counting, and specialized hematology testing in clinical laboratories and hospitals.
Consumables
Revenue flows from reagents, stains, controls, calibrators, quality control materials, and other consumables routinely used with hematology instruments for sample processing, cell analysis, quality assurance, and diagnostic testing across healthcare laboratories.
Segment – Test Type
Revenue capture definition
Blood Count
Revenue is primarily captured from complete blood count testing performed using hematology analyzers, associated reagents, controls, and laboratory services for evaluating red blood cells, white blood cells, and platelet parameters.
Platelet Function
Revenue flows from platelet function analyzers, specialized reagents, assay kits, and diagnostic services used to assess platelet activity, bleeding disorders, and response to antiplatelet therapies.
Hemoglobin
Market value is derived from hemoglobin testing instruments, reagents, and laboratory assays used to measure hemoglobin concentration for the diagnosis and monitoring of anemia and other hematological disorders.
Hematocrit
Revenue is obtained through hematocrit measurement performed using automated hematology analyzers, microhematocrit systems, and associated consumables for evaluating red blood cell volume and overall blood health.
Segment – End use
Revenue capture definition
Hospitals
Revenue is primarily captured from hematology diagnostic instruments, consumables, and testing services utilized in hospital laboratories for routine blood analysis, emergency diagnostics, disease monitoring, and inpatient and outpatient care.
Diagnostic Labs
Revenue flows from hematology testing performed by independent and reference laboratories using analyzers, reagents, and related consumables for routine screening, physician referred testing, and specialized hematological investigations.
Others
Market value is derived from hematology diagnostic products and services used by academic research institutes, blood banks, public health laboratories, ambulatory care centers, and other healthcare facilities performing hematological testing.
Estimation Model
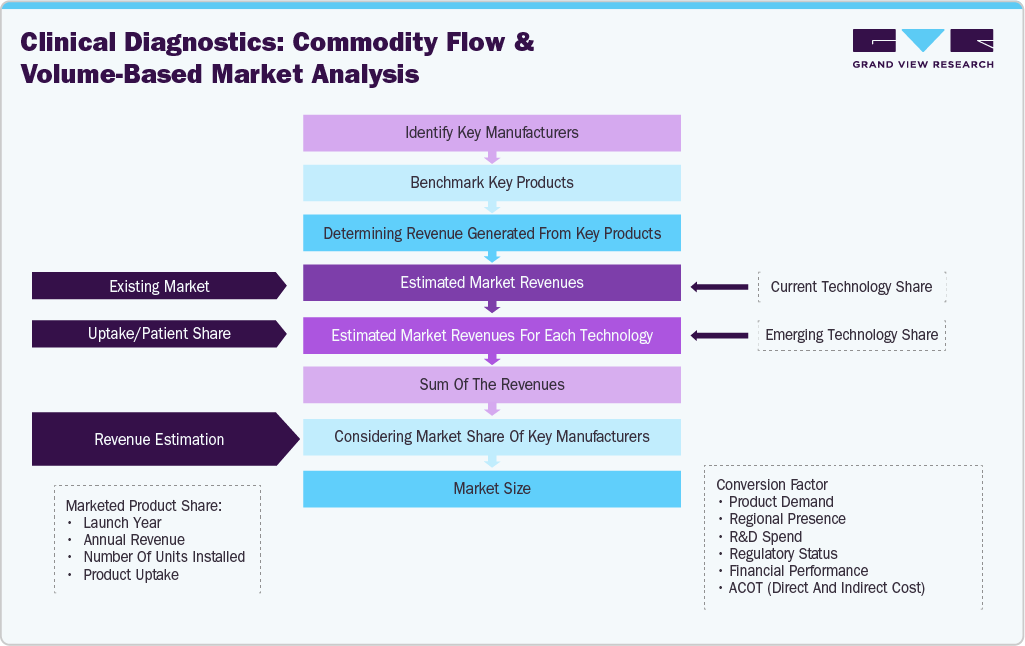
The hematology diagnostics market size was estimated using a bottom up approach by identifying key manufacturers, benchmarking their hematology diagnostic products, and assessing revenues generated from instruments and consumables across major test types and end use settings. Market estimates were validated using disease prevalence, diagnostic testing volumes, technology adoption, and the market share of leading companies to derive the overall market size.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Hematology Diagnostics Competitive Landscape Assessment Across Hematology Analyzers, Flow Cytometry, Coagulation Testing, and Laboratory Automation
Assessed the global hematology diagnostics ecosystem across diagnostic manufacturers, hospitals, diagnostic laboratories, research institutions, and healthcare providers. Evaluated hematology analyzers, flow cytometers, coagulation analyzers, reagents, stains, quality controls, and laboratory automation solutions while analyzing competitive positioning, product portfolios, technology adoption, and regional market presence of leading manufacturers.
Enabled benchmarking of leading companies, identified opportunities for product portfolio expansion, evaluated competitive differentiation across hematology diagnostic technologies, and provided strategic insights into market positioning, laboratory modernization, and technology adoption trends.
Hematology Diagnostics Regulatory, Laboratory Standards, and Commercialization Assessment
Analyzed global regulatory frameworks governing hematology diagnostic instruments and consumables, including FDA clearances, IVDR requirements, quality management standards, laboratory accreditation, and reimbursement policies. Evaluated clinical laboratory guidelines, quality assurance practices, and their influence on product commercialization and adoption across healthcare systems.
Supported regulatory risk assessment, identified compliance and reimbursement challenges, highlighted the impact of laboratory quality standards on technology adoption, and provided strategic guidance for commercialization, market entry, and expansion across key regions.
Hematology Diagnostics Technology Innovation and Laboratory Automation Assessment
Evaluated advancements in automated hematology analyzers, digital laboratory workflows, artificial intelligence enabled data analysis, integrated laboratory information systems, high throughput sample processing, and next generation hematology technologies. Assessed emerging innovations improving analytical accuracy, operational efficiency, and diagnostic performance across hospitals and diagnostic laboratories.
Highlighted innovation opportunities in laboratory automation and digital diagnostics, identified technologies supporting faster and more accurate hematology testing, and provided strategic insights into future market opportunities driven by diagnostic modernization, workflow optimization, and expanding preventive healthcare initiatives.
Frequently Asked Questions About This Report
Some key players operating in the hematology diagnostics market include Abbott, Beckman Coulter, Inc., Sysmex Corporation, Horiba, Bio-Rad Laboratories, Siemens Healthineers AG, F. Hoffmann-La Roche Ltd, Shenzhen Mindray Bio-Medical Electronics Co., Ltd., NIHON KOHDEN CORPORATION, and EKF Diagnostics.
The market is driven by increasing demand for routine blood testing, the rising burden of blood-related disorders, the need for early disease detection, and the growing use of automated hematology analyzers in healthcare facilities and diagnostic laboratories.
North America dominated the hematology diagnostics market in 2025, supported by established healthcare infrastructure and the adoption of advanced diagnostic technologies.
Hospitals accounted for the largest end-use share in 2025, driven by high patient volumes and the need for routine blood analysis and disease diagnosis.
Major applications include white blood cell (WBC) testing, red blood cell (RBC) testing, hemoglobin measurement, hematocrit assessment, and platelet function testing, which support routine blood analysis and the evaluation of various hematological conditions.
Consumables accounted for the largest product segment share in 2025, driven by recurring demand for reagents, stains, controls, and calibrators used in routine hematology testing.
Platelet function segment is projected to grow at the fastest CAGR over the forecast period.
The global hematology diagnostics market was valued at USD 8.5 billion in 2025 and is projected to reach USD 9.1 billion in 2026
The hematology diagnostics market is expected to grow at a compound annual growth rate (CAGR) of 5.4% from 2026 to 2033. reaching USD 13.1 billion by 2033
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


