
- Home
- »
- Medical Devices
- »
-
Holter Monitor Market Size And Share Report, 2023-2030GVR Report cover

Holter Monitor Market (2023 - 2030)
Size, Share & Trends Analysis Report By Component (Wired, Wireless), By End-use (Hospitals & Clinics, Ambulatory Surgical Centers, Others), By Region, And Segment Forecasts
Market Size, 2022
$1.5BMarket Estimate, 2026
$2.2BMarket Forecast, 2030
$3.1BCAGR, 2023–2030
9.7%Holter Monitors Market Summary
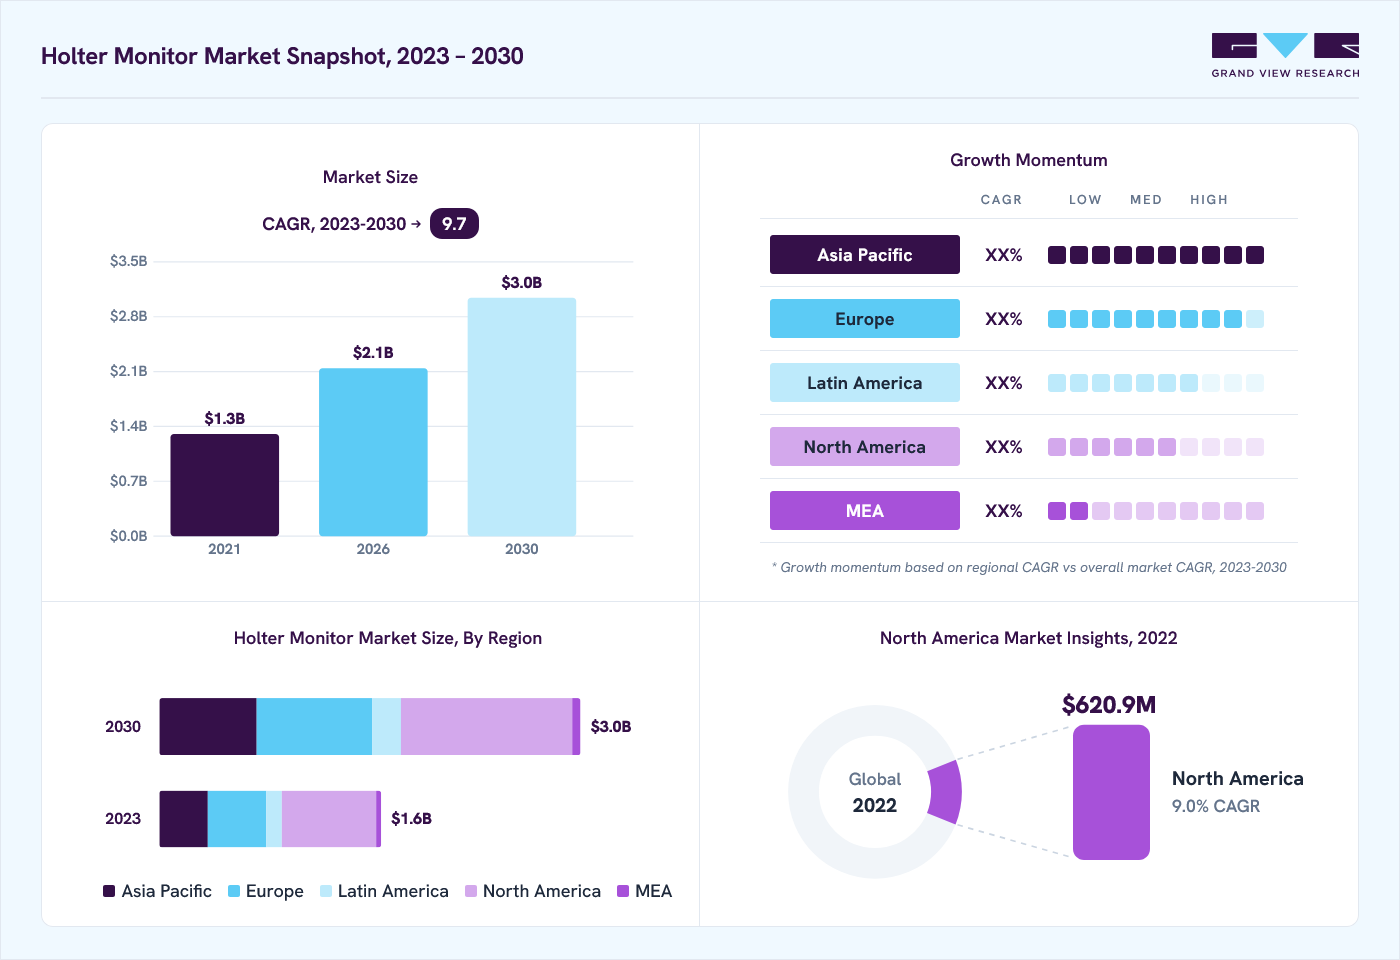
The global holter monitor market size was valued at USD 1.5 billion in 2022 and is projected to grow from USD 2.2 billion in 2026 to USD 3.1 billion by 2030, at a CAGR of 9.7% from 2023 to 2030. North America dominated the market, accounting for a revenue share of 42.8% in 2022. The market growth is attributed to the increasing prevalence of atrial fibrillation (an irregular and often very rapid heart rhythm, known as ‘AFib’), an aging population, and a rising incidence of cardiovascular diseases (CVD).
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- Based on component, the wired segment dominated with a revenue share of 63.54% in 2022.
- Based on end-use, the hospitals & clinics segment dominated the market with a revenue share of 50.42% in 2022.
Market Size & Forecast
- 2022 Market Size: USD 1.5 Billion
- 2030 Projected Market Size: USD 3.1 billion
- CAGR (2023-2030): 9.7%
- North America: Largest market in 2022
- Asia Pacific: Fastest growing market
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2023–2030 annual, 2022 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
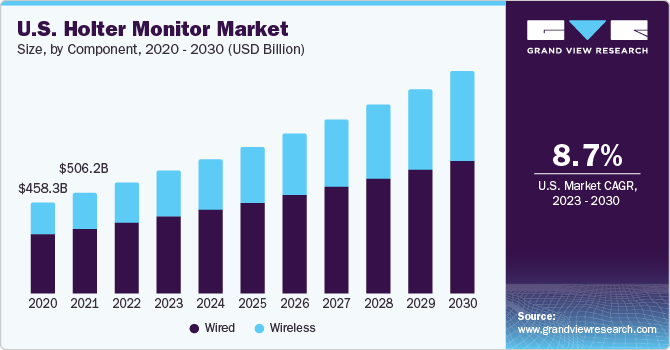
Additionally, the market is being driven by a shift toward ambulatory monitoring devices, continuous technological advancements, greater investments in early arrhythmia detection, developments in telemetry, and favorable regulatory policies.AFib is a common and often undiagnosed heart rhythm disorder that necessitates continuous monitoring for accurate detection and management. According to a study conducted by the European Society of Cardiology (ESC) in April 2023, the recommendation for utilizing 24-48-hour Holter monitoring to identify AFib and non-sustained ventricular tachycardia (NSVT) in patients with hypertrophic cardiomyopathy (HCM) drives the Holter monitor industry. Additionally, past evidence underlines the effectiveness of extended ECG monitoring in improving AFib detection in individuals with cryptogenic stroke or post-pulmonary vein isolation, adding momentum to the market's growth.
 To learn more about this report, Download Free Sample Report
According to the Centers for Disease Control and Prevention (CDC), in 2021, the high prevalence of coronary artery disease (CAD), resulted in 375,476 fatalities. In addition, around 5% of adults aged 20 and above, suffer from CAD. Moreover, in 2021, nearly 20% of CAD-related deaths affected individuals below 65, emphasizing the urgency of monitoring and managing this condition. Hence, the increasing number of CADs is contributing to the growth of the market.
Furthermore, according to the American Heart Association, Inc., in January 2023, 70% of the geriatric population was susceptible to CVD. Hence, the demand for pacemakers and accompanying monitoring solutions like Holter monitors is expected to grow with an aging population and increasing prevalence of heart rhythm disorders. Holter monitors are also crucial in assessing the effectiveness of leadless pacemakers in regulating heart rate and rhythm. As leadless pacemakers are commonly used in patients with heart rhythm disorders, Holter monitors provide extended ECG monitoring, capturing any irregularities or pacing issues during daily activities.
Component Insights
Based on component, the Holter monitors market is categorized into wired and wireless Holter devices. The wired segment dominated with a revenue share of 63.54% in 2022. These monitors are trusted by healthcare professionals for their proven technology and established track record. They offer stability in data transmission, reduced susceptibility to interference, and a cost-effective solution for healthcare providers with budget constraints. Various key players offer wired Holter monitors with advanced features, such as Koninklijke Philips N.V., which offers the Holter system having EASI 12-lead, multiple scanning styles, fast, flexible Zymed smart tools, and many comprehensive tools to support ECG analysis.
The wireless segment is estimated to be the fastest-growing segment during the forecast period. The increasing product approvals are expected to boost market growth as various companies are integrating AI in Holter monitors to increase the precision and efficiency of wireless Holter monitors. For instance, in November 2020, VitalConnect, Inc. announced the launch of VitalPatch RTM. It is designed for patients in need of extended Holter monitoring. The device monitors 21 cardiac arrhythmias using an AI-based ECG analysis solution.
End-use Insights
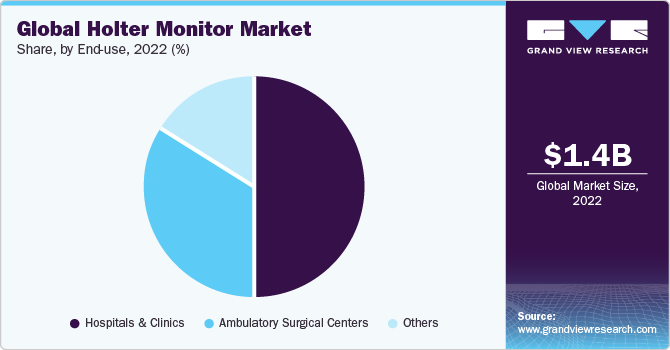
Based on end-use, the market is segmented into hospitals & clinics, ambulatory surgical centers, and others. The hospitals & clinics segment dominated the market with a revenue share of 50.42% in 2022. The ongoing high incidence of CVD strongly boosts hospitals and clinics to engage in the market. In June 2023, the European Environment Agency published an article stating that Europe records more than 6 million new cases of CVD annually, with a substantial 1.7 million individuals losing their lives due to circulatory system disorders. This statistic represents roughly 37% of all documented fatalities in Europe. As a result, there is a pressing demand for efficient cardiac monitoring and care within hospitals and clinics, primarily driven by the prevalence of CVD.
 To learn more about this report, Download Free Sample Report
The ambulatory surgery centers segment is projected to be the fastest-growing segment during the forecast period, which drives the Holter monitor industry also. According to the Ambulatory Surgery Center Association and ASCA Foundation, ASCs annually conduct approximately 22.5 million procedures across more than 5,900 Medicare-certified facilities in all 50 states of the U.S. Furthermore, Medicare's active involvement within the ASC environment leads to substantial yearly cost savings, surpassing USD 4.2 billion, particularly for procedures conducted within these centers. This thriving ASC ecosystem significantly boosts the demand for and utilization of Holter monitors within the healthcare sector.
Regional Insights
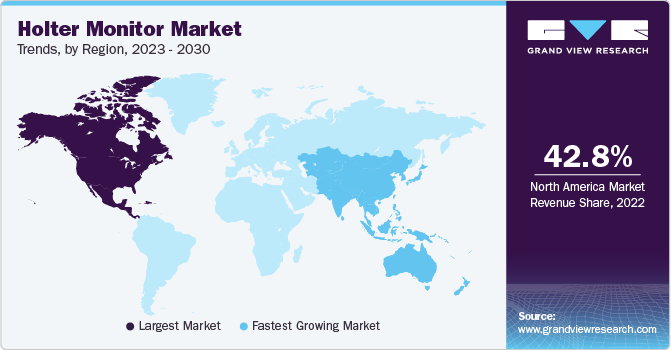
North America dominated the market with the largest share of 42.8% in 2022. The presence of Holter monitor manufacturing companies in the region is a significant driver of the market. It ensures a local supply chain, reducing shipping costs and facilitating customization and adaptation to meet local healthcare needs. Moreover, the prevalence of heart attacks in the U.S., occurring approximately every 40 seconds, is a significant driving force for the Holter monitor sector in the region. According to the CDC, around 805,000 individuals, experience heart attacks annually. It further emphasizes the crucial role of Holter monitors in monitoring and managing cardiac health, hence driving the market in this region.
 To learn more about this report, Download Free Sample Report
Asia Pacific is expected to witness the fastest CAGR over the forecast period. The growth can be attributed to the growing number of patients from nations such as China, India, and Japan for CVD treatment. For instance, in 2022, as per the Indian Council of Medical Research and Registrar General of India, 60% of the total Indian population suffered from heart disease. Such trends are expected to boost the Holter monitor industry during the forecast period.
Key Companies & Market Share Insights
The market players are focusing on various strategic initiatives such as new product launches, expansion, mergers and acquisitions, collaboration, product upgradation, etc. In March 2023, Koninklijke Philips N.V. announced the results of its research at the World Congress of Cardiology. Philips researchers conducted a comparative analysis involving 1, 7, and 14 days of retrospective data collected from the Philips ePatch, an extended-wear Holter monitor. The results showcased that the extension of ePatch monitoring led to a two-times increase in clinically actionable findings after 7 days and a 2.5-times increase after 14 days. These strong initial findings highlighted the market-driving potential of extended monitoring solutions, driving the research team to conduct a more in-depth analysis to gain further insights into the impact on specific diagnoses. Some key players in the global holter monitor market include:
-
Koninklijke Philips N.V.
-
GE HealthCare
-
Hill-Rom Holdings, Inc.
-
Spacelabs Healthcare (OSI Systems, Inc.)
-
SCHILLER AG
-
Bittium
-
Lepu Medical Technology(Beijing)Co.,Ltd.
-
BPL Medical Technologies
-
Biotricity
-
Nitto Denko Corporation
Holter Monitor Market Report Scope
Report Attribute
Details
Market size in 2022
USD 1.5 billion
Estimated market size in 2026
USD 2.2 billion
Projected market size by 2030
USD 3.1 billion
Growth rate
CAGR of 9.7% from 2023 to 2030
Base year for estimation
2022
Historical data
2018 - 2021
Forecast period
2023 - 2030
Quantitative units
Revenue in USD million/billion, and CAGR from 2023 to 2030
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Component, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Germany; U.K.; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; Australia; Thailand; South Korea; Brazil; Mexico; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Koninklijke Philips N.V.; GE HealthCare; Hill-Rom Holdings, Inc.; Spacelabs Healthcare (OSI Systems, Inc.); SCHILLER AG; Bittium; Lepu Medical Technology(Beijing)Co.,Ltd.; BPL Medical Technologies; Biotricity; Nitto Denko Corporation
Customization scope
Free report customization (equivalent up to 8 analyst's working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Holter Monitor Market Report Segmentation
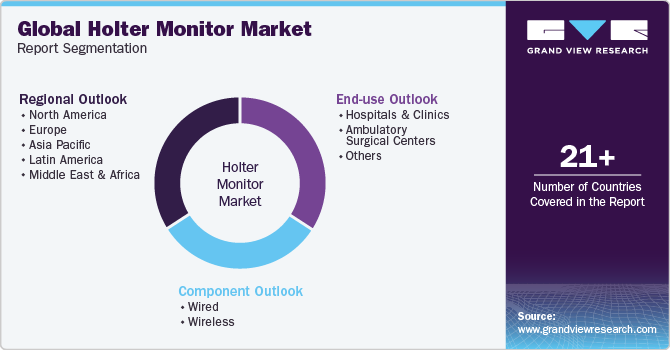
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2018 to 2030. For this study, Grand View Research has segmented the global Holter monitor market report based on component, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Component Outlook (Revenue, USD Billion, 2018 - 2030)
-
Wired
-
Wireless
-
-
End-use Outlook (Revenue, USD Billion, 2018 - 2030)
-
Hospitals & Clinics
-
Ambulatory Surgical Centers
-
Others
-
-
Regional Outlook (Revenue, USD Billion 2018 - 2030)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Sweden
-
Norway
-
Denmark
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
North America dominated with a revenue share of 42.8% in 2022.
The global holter monitor market size was valued at USD 1.5 billion in 2022 and is estimated at USD 2.2 billion for 2026.
The global holter monitor market is expected to grow at a CAGR of 9.7% from 2023 to 2030, reaching USD 3.1 billion by 2030.
Some of the key market players are Koninklijke Philips N.V., GE HealthCare, Hill-Rom Holdings, Inc., Spacelabs Healthcare (OSI Systems, Inc.), SCHILLER AG, Bittium, Lepu Medical Technology(Beijing)Co.,Ltd., BPL Medical Technologies, Biotricity, Nitto Denko Corporation
The market growth is attributed to the increasing geriatric population, increasing prevalence of atrial fibrillation (AFib), and a rising incidence of cardiovascular diseases (CVD).
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


