
- Home
- »
- Advanced Interior Materials
- »
-
Hospital HVAC Systems Market Size & Share Report, 2033GVR Report cover

Hospital HVAC Systems Market (2026 - 2033)
Size, Share & Trends Analysis Report By Equipment (Heating, Ventilation, Cooling), By End Use (Intensive Care Unit, Operating Rooms, Airborne Infection Isolation Rooms), By Region, And Segment Forecasts
Market Size, 2025
$12.9BMarket Estimate, 2026
$13.7BMarket Forecast, 2033
$20.6BCAGR, 2026–2033
6.0%Hospital HVAC Systems Market Summary
The global hospital HVAC systems market size was valued at USD 12.9 billion in 2025 and is projected to grow from USD 13.7 billion in 2026 to USD 20.6 billion by 2033, at a CAGR of 6.0% from 2026 to 2033. Asia Pacific dominated the hospital HVAC systems market with the largest revenue share of 38.6% in 2025. Growth is driven by rising demand for reliable, energy-efficient, and regulation-compliant air handling systems in critical hospital zones such as ICUs, operating rooms, and isolation wards.
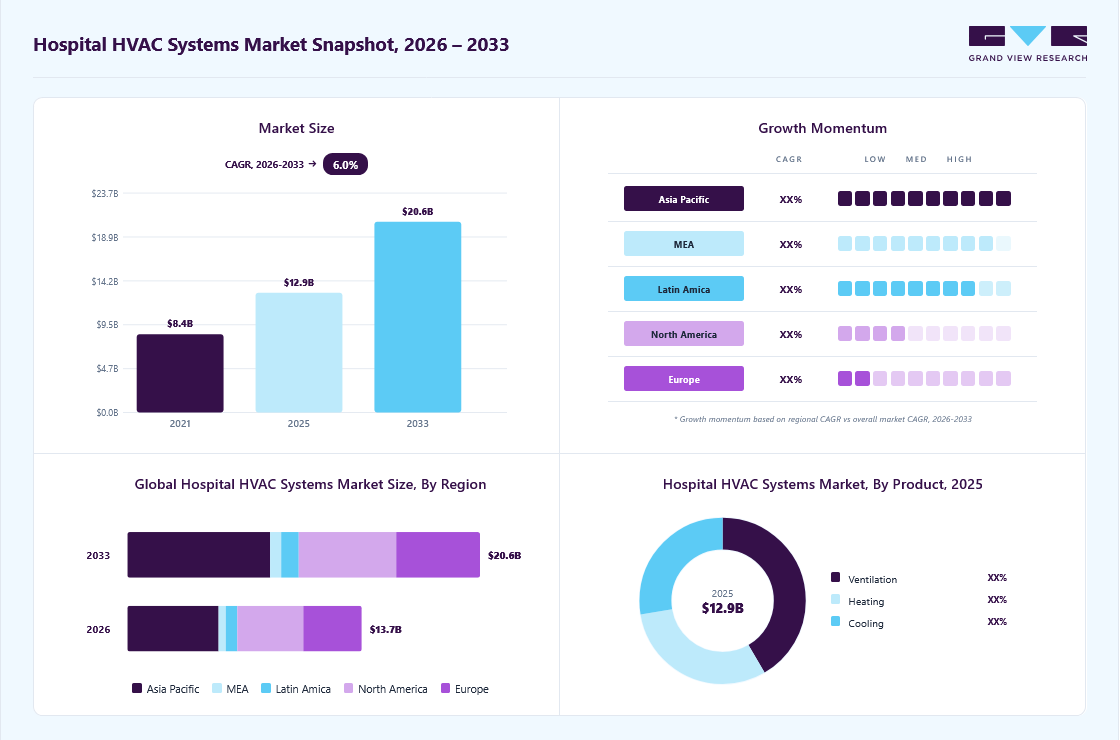 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By equipment: Ventilation segment held the largest market share of 41.5% in 2025.
- By end use: Operating rooms segment held the largest market share of 26.9% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (38.6% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 12.9 Billion
- Estimated market size in 2026: USD 13.7 Billion
- Projected market size by 2033: USD 20.6 Billion
- CAGR (2026-2033): 6.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Government initiatives in regions like North America and Europe, including incentives and rebates for clean heating and cooling technologies, are further supporting market expansion. In addition, the accelerating pace of hospital construction across the globe is playing a significant role in driving demand for hospital HVAC systems. As healthcare infrastructure expands to accommodate rising population needs, urbanization, and growing incidences of chronic illnesses, new hospitals and medical campuses are being developed with greater emphasis on advanced environmental control systems.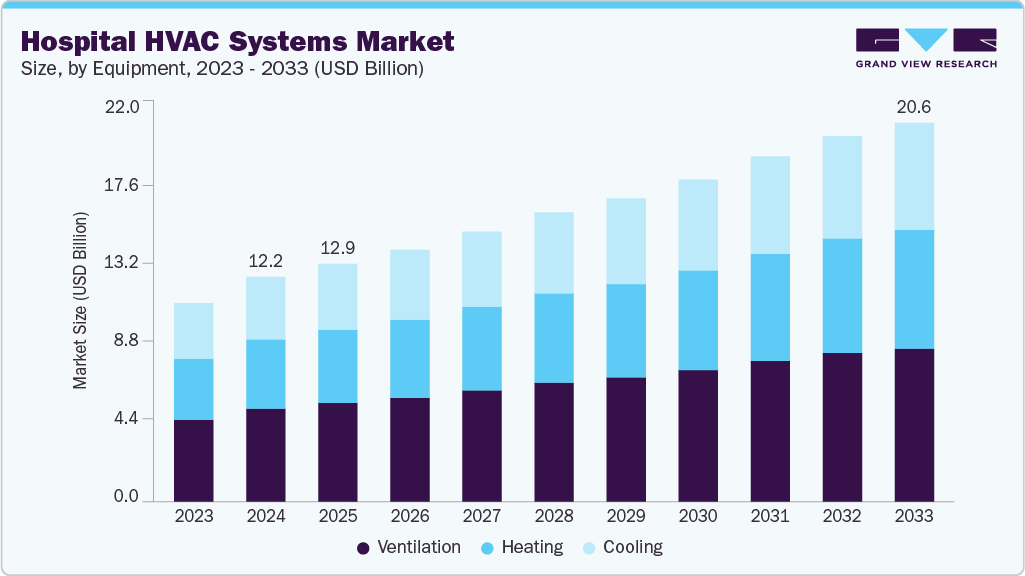 To learn more about this report, Download Free Sample Report
Market Dynamics
The hospital HVAC systems market is driven by increasing investments in healthcare infrastructure, stringent infection prevention requirements, and the growing need to maintain controlled indoor environments across critical care areas. Hospitals are adopting advanced ventilation, filtration, and climate control technologies to improve air quality, regulate temperature and humidity, and comply with evolving healthcare building standards. The market is also benefiting from the modernization of existing healthcare facilities and the construction of new hospitals, particularly in developing economies. However, high installation costs, complex retrofit requirements, and ongoing maintenance expenses remain challenges for market growth. At the same time, the integration of smart building management systems, energy-efficient HVAC technologies, predictive maintenance, and environmentally sustainable refrigerants is creating new opportunities for manufacturers to enhance system performance, reduce operating costs, and support long-term healthcare facility efficiency.
The hospital HVAC systems market is primarily driven by the rising demand for reliable, energy-efficient, and clean indoor air solutions in critical healthcare environments. Hospitals require specialized HVAC technologies to maintain stringent control over temperature, humidity, air quality, and pressure across various sensitive areas such as operating rooms, isolation wards, and compounding pharmacies. The growing number of greenfield hospital developments, alongside ongoing upgrades to existing medical infrastructure, is therefore not only expanding the addressable market for HVAC equipment but also fueling demand for system design services, on-site integration, and lifecycle maintenance. As governments and private healthcare investors continue to prioritize healthcare infrastructure, the hospital HVAC systems market is poised to benefit from both volume growth and increasing technological sophistication.
Limited retrofit feasibility in older hospital buildings acts as a significant restraint for the hospital HVAC systems market, as many existing healthcare facilities were originally designed with outdated infrastructure that cannot easily accommodate modern HVAC requirements. Upgrading these systems often involves extensive structural modifications, including changes to ductwork, ceiling spaces, electrical systems, and airflow zoning, which can be both costly and operationally disruptive. In hospitals, where continuous patient care is critical, renovation activities must be carefully phased to avoid compromising clinical operations, further increasing project complexity and timelines.
The increasing focus on energy efficiency, digital building management, and sustainability is creating significant opportunities for the hospital HVAC systems market. Healthcare facilities are adopting smart HVAC solutions equipped with IoT-enabled sensors, building automation systems, predictive maintenance capabilities, and real-time environmental monitoring to optimize energy consumption while maintaining stringent indoor air quality standards. At the same time, growing emphasis on reducing carbon emissions is encouraging the use of high-efficiency air handling units, variable air volume systems, heat recovery technologies, and low-global-warming-potential refrigerants.
Market Concentration & Characteristics
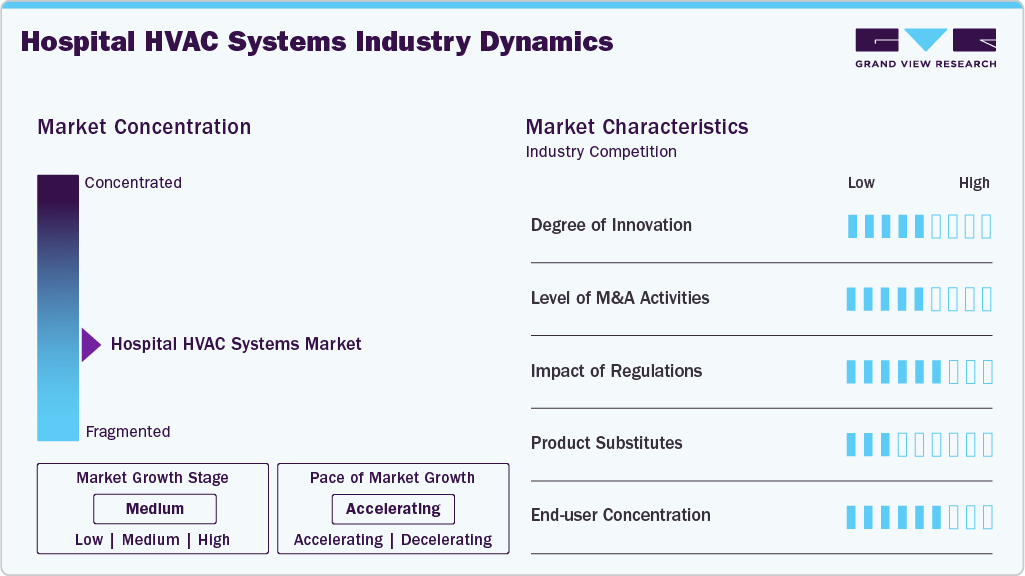
The global hospital HVAC systems industry exhibits a moderately consolidated structure, characterized by the presence of a few dominant multinational HVAC companies alongside several specialized regional players. Leading manufacturers such as Carrier, Daikin, Trane, and Johnson Controls hold significant market share due to their broad product portfolios, technological expertise, and established installation and maintenance networks. These firms often form long-term contracts with healthcare providers, facility managers, and infrastructure developers, securing their foothold in new hospital construction and retrofit projects.
A defining characteristic of the hospital HVAC systems industry is its emphasis on precision, reliability, and regulatory compliance. Unlike standard commercial HVAC systems, hospital HVAC solutions are tailored to critical zones such as isolation wards, surgical suites, intensive care units (ICUs), and pharmaceutical storage areas-each with unique temperature, humidity, filtration, and airflow requirements. As a result, customization and adherence to stringent health and safety codes (such as ASHRAE 170, FGI Guidelines, and CDC standards) are central to product development and deployment strategies.
 To learn more about this report, Download Free Sample Report
Regulatory bodies and healthcare accreditation agencies play a vital role in shaping market dynamics by enforcing standards for air quality, infection control, and energy efficiency. In response, manufacturers are increasingly integrating advanced filtration systems (like HEPA and UVGI), building automation, and smart diagnostics into their HVAC units. Energy efficiency and indoor air quality (IAQ) remain critical concerns for healthcare operators, prompting the adoption of low-energy HVAC solutions and intelligent ventilation systems that reduce operational costs while ensuring patient safety.
While demand for hospital HVAC systems is strong due to ongoing hospital infrastructure upgrades, population aging, and the rise in infectious disease preparedness, the market also faces pressures from capital expenditure constraints and lengthy procurement cycles in public healthcare systems. To maintain competitiveness, key players are investing in modular HVAC units, AI-driven building management systems, and service-based models that offer predictive maintenance and lifecycle cost savings. In this evolving landscape, the ability to balance regulatory compliance, operational efficiency, and indoor environmental control will define long-term success.
Analyst Perspective
The hospital HVAC systems market is growing steadily as healthcare providers invest in advanced environmental control solutions that enhance patient safety, infection prevention, and operational efficiency. Demand is increasing from new hospital construction projects and the modernization of existing healthcare facilities, where precise control of temperature, humidity, air pressure, and indoor air quality is essential for operating rooms, intensive care units, isolation wards, and other critical care environments. Technological advancements such as HEPA filtration, UV-C air disinfection, energy recovery systems, smart building management integration, and IoT-enabled monitoring are improving system performance while reducing energy consumption and maintenance requirements. As healthcare infrastructure continues to expand and regulatory standards for indoor air quality become more stringent, manufacturers offering energy-efficient, high-performance, and application-specific hospital HVAC systems are expected to benefit from sustained long-term market growth.
Equipment Insights
Based on equipment, the ventilation segment led the market with the largest revenue share of 41.5% in 2025. Ventilation plays a vital role in maintaining sterile environments and ensuring infection control in critical areas such as operating rooms, ICUs, isolation wards, and compounding pharmacies. Hospitals increasingly deploy air handling units (AHUs), exhaust systems, energy recovery ventilators, and HEPA filtration units to ensure proper air exchange, filtration, and pressurization.
The growing use of climate-sensitive areas such as ORs, patient isolation rooms, and protective zones is fueling demand for the cooling segment, which comprises chillers, cooling towers, and integrated HVAC systems capable of delivering precise thermal regulation. The increasing use of smart control systems and low-GWP refrigerants in these systems is also contributing to adoption in retrofit and new-build hospital projects.
End Use Insights
Based on end use, the operating rooms segment led the market with the largest revenue share of 26.9% in 2025. This dominance is driven by the critical need for sterile air environments and highly controlled airflow, humidity, and pressurization. Hospitals are increasingly adopting laminar airflow systems, HEPA filtration, and environmental control units in ORs to meet stringent compliance requirements from organizations like ASHRAE, CDC, and WHO.
 To learn more about this report, Download Free Sample Report
HVAC systems used in ICUs demand exceptionally high reliability in maintaining a stable and precise indoor climate, encompassing temperature, humidity, and air pressure. These systems are also required to provide advanced air purification, often incorporating multi-stage HEPA and ULPA filtration, UV-C germicidal lamps, and active bioaerosol management to ensure the removal of airborne contaminants. The presence of vulnerable, immunocompromised patients necessitates uninterrupted system operation, where even minor fluctuations can compromise patient safety. As a result, there is growing emphasis on continuous monitoring, real-time diagnostics, and redundancy-based design, all of which are driving upgrades toward smart, predictive, and failsafe HVAC platforms tailored specifically for high-dependency hospital zones like ICUs.
Regional Insights
The hospital HVAC systems market in North America is witnessing strong growth in hospital HVAC adoption driven by regulatory mandates, aging healthcare infrastructure, and federal funding for system upgrades. There is increasing uptake of smart ventilation systems, heat recovery chillers, and zone-specific pressure control units to support advanced infection control in critical care settings.
U.S. Hospital HVAC Systems Market Trends
The hospital HVAC systems market in the U.S. accounted for the largest market revenue share in North America in 2024. Federal programs such as the Infrastructure Investment and Jobs Act and various clean energy incentives are promoting modernization of HVAC infrastructure in hospitals. Retrofit activity is especially high across older healthcare campuses, with increasing installations of IoT-enabled systems for real-time environmental monitoring and predictive maintenance.
Asia Pacific Hospital HVAC Systems Market Trends
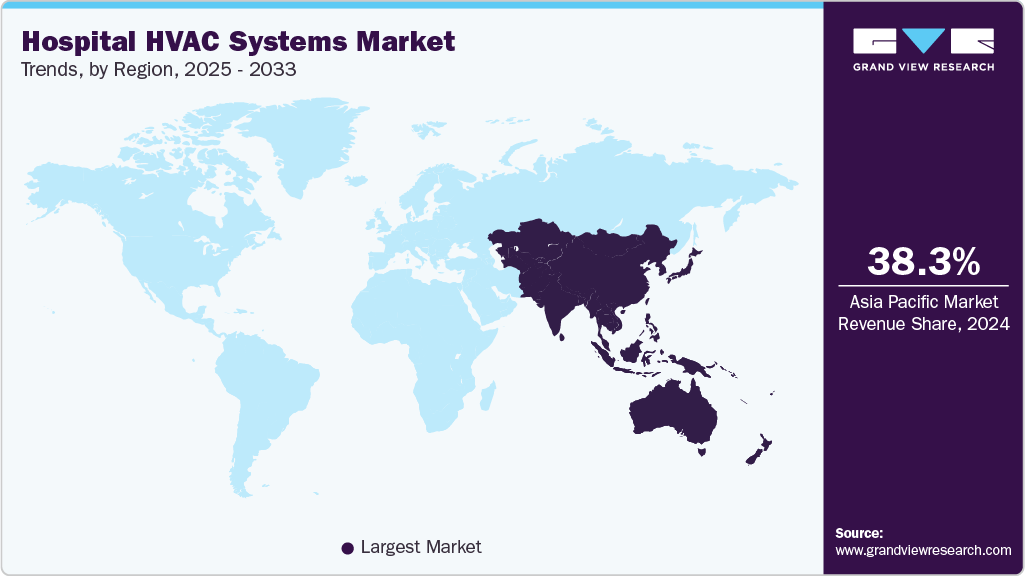
Asia Pacific dominated the hospital HVAC systems market with the largest revenue share of 38.6% in 2025. The region is witnessing rapid growth due to increasing hospital construction, rising adoption of infection control standards, and growing healthcare expenditure. Demand is particularly strong for energy-efficient ventilation and cooling technologies in countries focusing on infrastructure modernization and regulatory compliance.
 To learn more about this report, Download Free Sample Report
The hospital HVAC systems market in Malaysia is projected to grow at the fastest CAGR of 8.9% from 2025 to 2033, fueled by aggressive expansion of public healthcare infrastructure, implementation of cleanroom-grade HVAC systems in ICUs and operating theaters, and government-backed investments in Tier-2 and Tier-3 city hospitals. There is also increasing demand for retrofitting legacy systems with high-efficiency AHUs, UV-C filtration, and low-GWP refrigerants.
The hospital HVAC systems market in China held the largest share in the Asia Pacific region in 2025. fueled by the country’s expanding healthcare infrastructure and rising focus on infection control and indoor air quality. Increasing investments in both public and private hospitals, along with a push for energy-efficient and regulatory-compliant systems, are driving demand for advanced HVAC solutions.
Europe Hospital HVAC Systems Market Trends
The hospital HVAC systems market in Europe is being driven by stringent energy efficiency regulations and aging hospital stock requiring system upgrades. The region’s net-zero building mandates and infection control norms are pushing demand for heat recovery systems, advanced filtration, and HVAC-BMS integration in healthcare environments.
The Italy hospital HVAC systems market is projected to expand at the fastest CAGR of 6.1% over the forecast period. Italy’s market is being propelled by strong domestic engineering expertise, cost-effective manufacturing, and a deep pool of skilled labor, supporting robust deployment and service capabilities. In addition, stringent energy and air quality standards-alongside increasing investment in healthcare infrastructure modernization-are fostering demand for advanced, sustainable HVAC solutions in hospitals
The hospital HVAC systems market in France is projected to grow at a rapid CAGR of 5.8% over the forecast period. Upgrades in HVAC systems across regional hospitals and rising investments in oncology and infectious disease facilities are driving demand. French hospitals are adopting modular HVAC units with integrated filtration and automated compliance monitoring systems to meet Facility Guidelines Institute (FGI) and ASHRAE ventilation requirements.
Latin America Hospital HVAC Systems Market Trends
The hospital HVAC systems market in Latin America is emerging as a fast-growing region driven by new hospital construction, particularly in urban areas, and increased focus on improving air quality in healthcare settings. While the regulatory environment is less stringent compared to developed regions, rising demand for surgical and isolation zones is accelerating system upgrades.
The Brazil hospital HVAC systems market is projected to expand at a significant CAGR of 6.7% during the forecast period, the highest in the region. Growth is driven by large-scale healthcare projects in São Paulo, Rio de Janeiro, and other metros. Increased demand for ORs, ICUs, and HVAC-integrated infection control systems is shaping supplier offerings toward compact, energy-efficient equipment with local support capabilities.
Middle East & Africa Hospital HVAC Systems Market Trends
The hospital HVAC systems market in MEA is experiencing a steady rise in demand for hospital HVAC systems, driven by a combination of climate-related challenges, large-scale public healthcare investments, and growing awareness of airborne infection risks. With average temperatures soaring across much of the region, there is a critical need for high-capacity, energy-efficient cooling systems in hospitals to maintain indoor thermal comfort and equipment performance.
The Saudi Arabia hospital HVAC systems market is anticipated to grow at the fastest CAGR of 7.1% during the forecast period, fueled by Vision 2030 investments in healthcare infrastructure and emphasis on high-acuity care. Large tertiary hospitals and specialty clinics are deploying modular HVAC systems with HEPA and UVGI capabilities, along with centralized monitoring via building automation platforms.
Key Hospital HVAC Systems Company Insights
Some of the key players operating in the market include Carrier Corporation and Daikin Industries, Ltd among others.
-
Carrier Corporation provides heat pumps, air conditioners, boilers, furnaces, air purifiers, humidifiers, dehumidifiers, ventilators, air scrubbers, thermostats, UV lamps, energy services, and building controls to the retail, commercial, transport, and foodservice sectors.It was acquired by United Technologies Corporation in 1979; however, it was separated into a separate business in April 2020.
-
Daikin Industries, Ltd. offers air-conditioning systems, room heating and heat pump hot water supply systems, room air conditioning systems, packaged air-conditioning systems, and air conditioning systems for plants, facilities, and office buildings.
Key Hospital HVAC Systems Companies
The following key companies have been profiled for this study on the hospital HVAC systems market.
-
Carrier Corporation
-
DAIKIN INDUSTRIES Ltd.
-
Haier Group
-
Johnson Controls
-
LG Electronics
-
Lennox International Inc.
-
Mitsubishi Electric Corporation
-
Rheem Manufacturing Company
-
SAMSUNG
-
Havells India Ltd.
-
Honeywell International Inc.
-
Trane
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Daikin Industries Ltd.; Carrier Corporation; Trane)
- Continuous investment in research & development to enhance energy-efficient and infection-control-focused HVAC solutions.
- Strong focus on strategic partnerships, acquisitions, and service network expansion to strengthen hospital project execution capabilities.
- Frequent product launches and upgrades aligned with healthcare compliance standards and sustainability goals.
- Strong global presence with established brand recognition and long-term relationships with hospitals and healthcare infrastructure developers.
- Broad product portfolios covering chillers, air handling units, ventilation systems, filtration, and building automation systems.
- Large organizational structures can reduce operational agility and slow response to niche customer requirements.
- Dependence on large institutional projects exposes revenues to delays in healthcare infrastructure investments.
Emerging & Regional Players (e.g., Haier Group; Havells India Ltd.; Rheem Manufacturing Company)
- Focus on specialized product offerings and regional market penetration with cost-competitive solutions.
- Expansion through strong distributor networks, local partnerships, and selective backward integration for cost control.
- Emphasis on flexible product customization for mid-sized hospitals and retrofit projects.
- Strong local market presence with faster response times and better adaptation to regional hospital infrastructure needs.
- Competitive pricing and simplified operations support higher adoption in budget-sensitive healthcare facilities.
- Intense competition from established global players with stronger brand trust and larger service capabilities.
- Limited financial resources may restrict large-scale expansion, advanced R&D investment, and international market penetration.
Recent Developments
-
In February 2025, Daikin Australia launched the EWYE-CZ air-to-water inverter heat pump, which uses eco-friendly R454C refrigerant and offers quiet operation-making it ideal for sensitive hospital zones. The compact system design allows flexible integration in urban and space-constrained medical campuses.
-
In September 2024, Trane announced it is transitioning its commercial HVAC systems to low-GWP refrigerants to comply with U.S. EPA regulations effective January 1, 2025. The company is also adding factory-installed leak detection systems to models with refrigerant charges exceeding 3.91 pounds, enhancing safety and efficiency. These updates apply to various product lines, including rooftop units and modular chillers, supporting sustainability goals and regulatory compliance.
Hospital HVAC Systems Market Report Scope
Report Attribute
Details
Market size in 2025
USD 12.9 billion
Estimated market size in 2026
USD 13.7 billion
Projected market size by 2033
USD 20.6 billion
Growth rate
CAGR of 6.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Equipment, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Russia; China; India; Japan; South Korea; Australia; Indonesia; Malaysia; Thailand; Brazil; Argentina; South Africa; UAE; Saudi Arabia
Key companies profiled
Carrier Corporation; DAIKIN INDUSTRIES Ltd.; Haier Group; Johnson Controls; LG Electronics; Lennox International Inc.; Mitsubishi Electric Corporation; Rheem Manufacturing Company; SAMSUNG; Havells India Ltd.; Honeywell International Inc.; Trane.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Hospital HVAC Systems Market Report Segmentation
This report forecasts revenue growth at global, regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research, Inc. has segmented the global hospital HVAC systems market report based on the equipment, end use, and region:
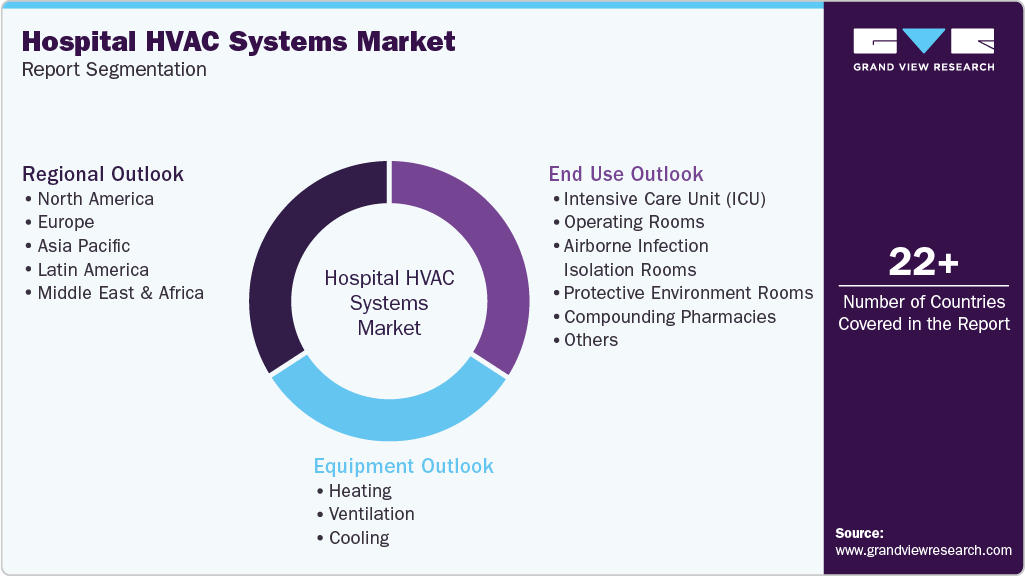 To learn more about this report, Download Free Sample Report
-
Equipment Outlook (Revenue, USD Million, 2021 - 2033)
-
Heating
-
Ventilation
-
Cooling
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Intensive Care Unit (ICU)
-
Operating Rooms
-
Airborne Infection Isolation Rooms
-
Protective Environment Rooms
-
Compounding Pharmacies
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
France
-
Germany
-
Italy
-
Spain
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
Indonesia
-
Malaysia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The hospital HVAC systems market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each hospital HVAC systems segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Equipment
Revenue Capture Definition
Heating
The segment refers to heating equipment used within hospital HVAC systems to maintain controlled indoor temperatures across healthcare facilities. The segment captures revenue generated from the sale of heating systems and related components supplied for hospitals and other healthcare environments.
Ventilation
The segment refers to ventilation equipment designed to regulate airflow, air quality, and pressure within healthcare facilities. The segment captures revenue generated from the sale of ventilation systems and associated components supplied for hospital HVAC applications.
Cooling
The segment refers to cooling equipment used to maintain precise temperature and humidity levels in hospital environments. The segment captures revenue generated from the sale of cooling systems and related components supplied for hospital HVAC installations.
Segment - End Use
Revenue Capture Definition
Intensive Care Unit (ICU)
The segment refers to hospital HVAC systems installed in intensive care units. The segment captures revenue generated from the sale of HVAC systems supplied for ICU applications.
Operating Rooms
The segment refers to hospital HVAC systems installed in operating rooms. The segment captures revenue generated from the sale of HVAC systems supplied for surgical environments.
Airborne Infection Isolation Rooms
The segment refers to hospital HVAC systems installed in airborne infection isolation rooms. The segment captures revenue generated from the sale of HVAC systems supplied for isolation room applications.
Protective Environment Rooms
The segment refers to hospital HVAC systems installed in protective environment rooms. The segment captures revenue generated from the sale of HVAC systems supplied for protective care environments.
Compounding Pharmacies
The segment refers to hospital HVAC systems installed in compounding pharmacies. The segment captures revenue generated from the sale of HVAC systems supplied for hospital pharmacy applications.
Others
The segment refers to hospital HVAC systems installed across all other healthcare spaces. The segment captures revenue generated from the sale of HVAC systems supplied for these applications.
Estimation Model
Layer No.
Layer Name
Key Question
Description
01
Healthcare Infrastructure Demand Layer
Where are hospital HVAC systems required?
Analyze demand across hospitals, ambulatory surgical centers, specialty clinics, diagnostic laboratories, healthcare campuses, and other medical facilities. Assess requirements for operating rooms, intensive care units (ICUs), isolation rooms, cleanrooms, pharmacies, and patient care areas to establish the addressable demand for hospital HVAC systems.
02
Healthcare Construction & Modernization Layer
Where is new equipment demand being created?
Evaluate investments in new hospital construction, healthcare infrastructure expansion, renovation of existing facilities, and modernization of aging HVAC systems. Assess greenfield healthcare projects, capacity expansions, regulatory upgrades, and replacement cycles that drive procurement of new hospital HVAC systems.
03
Product Adoption Layer
Which hospital HVAC technologies are being deployed?
Segment demand by equipment type, system configuration, installation type, application, and end use. Apply adoption rates based on indoor air quality requirements, infection prevention protocols, energy efficiency standards, air exchange rates, pressure control requirements, and building management integration. Assess the increasing adoption of high-efficiency filtration, UV-C air disinfection, smart HVAC controls, and energy recovery technologies to enhance patient safety and operational efficiency.
04
Revenue Generation Layer
How much market revenue is generated?
Estimate annual shipments of hospital HVAC systems by equipment type, application, healthcare facility type, and region. Quantify revenues generated exclusively from the sale of new hospital HVAC systems supplied to hospitals, healthcare facilities, EPC contractors, and HVAC system integrators. The scope excludes installation, maintenance, retrofit services, spare parts, consumables, and aftermarket service revenues.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Benchmarking
The competitive benchmarking customization provides a structured comparison of key market participants based on parameters such as product portfolio strength, technological capabilities, strategic approach, geographic presence, and segment focus. This allows for a side-by-side evaluation of how major players are positioned within the market landscape.
This helps the client understand competitor strengths, identify market gaps, and evaluate their own competitive standing more effectively. It supports strategic planning by enabling informed decisions related to product positioning, partnership opportunities, and differentiation approaches required to strengthen market presence.
Regional Segmentation
The regional segmentation customization provides a detailed breakdown of the market across key geographic regions and countries, highlighting differences in demand patterns, adoption trends, regulatory environments, and end-user preferences. It includes region-wise market sizing, growth potential assessment, and identification of high-growth countries to provide a clearer understanding of localized market dynamics.
This enables the client to identify the most attractive regional markets for expansion, investment, and strategic prioritization. It supports more effective resource allocation and sales strategy development by helping decision-makers focus on regions with the strongest commercial potential and long-term growth opportunities.
Opportunity assessment
The opportunity assessment customization identifies high-potential growth areas within the market by analyzing emerging applications, underserved customer segments, technological advancements, and evolving regional demand trends. It focuses on uncovering revenue-generating opportunities and strategic white spaces that may offer a competitive advantage.
This helps the client prioritize investments toward the most commercially viable opportunities while reducing the risk of misaligned strategic decisions. It supports long-term business planning by providing clarity on where future demand is likely to concentrate, enabling stronger market entry, expansion, and innovation strategies.
Frequently Asked Questions About This Report
The global hospital HVAC systems market size was estimated at USD 12.9 billion in 2025 and is projected to grow from USD 13.7 billion in 2026 .
Some of the key players operating in the hospital HVAC systems market are Carrier Corporation, DAIKIN INDUSTRIES Ltd., Haier Group, Johnson Controls, LG Electronics, Lennox International Inc., Mitsubishi Electric Corporation, Rheem Manufacturing Company, SAMSUNG, Havells India Ltd., Honeywell International Inc., and Trane.
Key factors driving the hospital HVAC systems market include increasing demand for infection control and indoor air quality in healthcare settings, alongside stringent regulatory requirements for ventilation and energy efficiency. Growth in healthcare infrastructure and retrofitting of existing hospitals also contribute significantly.
Based on product, the ventilation segment led the market with the largest revenue share of 41.5% in 2025.
Based on end use, the operating rooms segment led the market with the largest revenue share of 26.9% in 2025
Based on product, the cooling segment led the largest market growth rate of 6.3% from 2026 to 2033.
Based on end-use, the Intensive Care Unit (ICU) segment led the largest market growth rate of 6.6% from 2026 to 2033.
The global hospital HVAC systems market, in terms of revenue, is expected to grow at a compound annual growth rate of 6.0% from 2026 to 2033 to reach USD 20.6 billion by 2033.
The market in Asia Pacific dominated the market in 2025 accounting for 38.6% of the global revenue share driven by rapid urbanization, expanding healthcare infrastructure, and rising investments in medical facility modernization. Government-led initiatives to improve public health systems and compliance with air quality and infection control standards are further accelerating demand.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


