
- Home
- »
- Healthcare IT
- »
-
Identity And Access Management In Healthcare Market Report 2033GVR Report cover

Identity And Access Management In Healthcare Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Software Solutions, Services), By Deployment Mode, By Type (Single Sign On (SSO)), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$1.9BMarket Estimate, 2026
$2.2BMarket Forecast, 2030
$7.1BCAGR, 2026–2030
17.9%Identity And Access Management In Healthcare Market Summary
The global identity and access management in healthcare market size was valued at USD 1.9 billion in 2025 and is projected to grow from USD 2.2 billion in 2026 to USD 7.1 billion by 2033, at a CAGR of 17.9% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 40.7% in 2025. The growing concern regarding data security and compliance with regulations to uphold patient safety and confidentiality is driving the market for identity access management.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: Software solutions segment dominated the market, with a revenue share of 67.0% in 2025.
- By deployment mode: Cloud segment held the largest market share of 67.8% in 2025.
- By type: Provisioning segment held the largest revenue share of 30.5% in 2025.
- By end use: Hospitals and clinics segment accounted for the largest revenue share of 42.6% in 2025.
Regional Highlights
- Largest regional market: North America (40.7% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.9 Billion
- Estimated market size in 2026: USD 2.2 Billion
- Projected market size by 2033: USD 7.1 Billion
- CAGR (2026-2033): 17.9%
Prism AI by Grand View Research Free to tryAsk a question about the identity and access management in healthcare marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Moreover, the increasing adoption of cloud based solutions, rising emphasis on regulatory compliance requirement to ensure patient safety and data security is impelling the market growth. The rapid adoption of cloud-based solutions and advanced healthcare IT infrastructure is further boosting the demand for identity and access management systems. The scalability of cloud-based IAM solutions allows organizations to adapt to changing business needs and effectively accommodate fluctuations in user populations. This scalability is particularly crucial in dynamic environments where rapid growth or sudden changes in demand can occur.IAM solutions are pivotal in safeguarding sensitive patient data by ensuring authorized access and preventing unauthorized breaches. These solutions utilize advanced technologies, such as biometrics, multifactor authentication, and role-based access control, to bolster security against cyber threats & data breaches. To learn more about this report, Download Free Sample Report
Healthcare organizations are increasingly adopting sophisticated IT systems to manage patient data securely, comply with regulations such as the Health Insurance Portability and Accountability Act (HIPAA), and enhance operational efficiency. Integrating IAM solutions with healthcare IT infrastructure streamlines user provisioning, authentication, & authorization processes, improving workflow efficiency and reducing administrative burdens. This integration also enables seamless access to patient data across various healthcare applications and systems, facilitating better patient care coordination & decision-making by healthcare providers.
The progress in healthcare IT infrastructure, incorporating innovations such as IoT, big data, and AI, is a significant factor driving market expansion. Advanced technologies such as intelligent sensors, robotic pills, microcontrollers, digital networking, automotive microcontrollers, radiofrequency, and sensors play a significant role in driving the healthcare IT market. For instance, research reveals that a “robotic pill” can safely dispense an injectable osteoporosis drug orally, providing a viable alternative to its current administration method. This finding, presented at ENDO 2023-the Endocrine Society’s yearly gathering in Chicago, Illinois-demonstrates the feasibility of delivering a well-established and efficient osteoporosis medication through innovative technology.
Furthermore, key players in the market are focusing on the launch of technology advanced products, thereby driving the market. For instance, in November 2023, LexisNexis Risk Solutions has introduced LexisNexis Health Equity and Inclusion Insights, a solution providing detailed and actionable data at the individual level regarding Social Determinants of Health (SDoH). These insights empower healthcare organizations to improve population health, conduct clinical research, and drive initiatives focused on health equity.
Market Dynamics
The increasing frequency of cyberattacks on healthcare organizations, growing adoption of electronic health records (EHRs), expanding use of cloud-based healthcare applications, and stringent data privacy regulations. The rising implementation of multi-factor authentication (MFA), single sign-on (SSO), privileged access management (PAM), and Zero Trust security frameworks is enhancing identity protection, improving user access control, and ensuring regulatory compliance. However, challenges related to integration with legacy healthcare IT systems, high implementation and maintenance costs, interoperability issues, and the shortage of skilled cybersecurity professionals continue to restrain market growth.
The growing adoption of electronic health records (EHRs), telehealth platforms, cloud-based healthcare applications, and connected medical devices is significantly driving demand for identity and access management (IAM) solutions in the healthcare sector. As healthcare organizations continue their digital transformation initiatives, clinicians, administrative staff, patients, and third-party vendors require secure and seamless access to multiple clinical and operational systems. IAM solutions, including multi-factor authentication (MFA), single sign-on (SSO), identity governance, and privileged access management (PAM), help ensure that only authorized users can access sensitive patient information while reducing password fatigue and improving workflow efficiency.
Furthermore, the increasing exchange of healthcare data across hospitals, laboratories, pharmacies, insurers, and remote care platforms has heightened the need for centralized identity management and robust access controls to maintain data security and regulatory compliance. For instance, in February 2026, Imprivata, Inc. launched Imprivata Enterprise Access Management enhancements with expanded passwordless authentication and identity verification capabilities designed for clinical environments. The updates help healthcare organizations simplify secure access to EHR systems, improve clinician productivity, and strengthen protection against credential-based cyber threats.
The implementation of enterprise-grade identity and access management (IAM) solutions requires significant upfront investment in software licenses, cloud subscriptions, infrastructure upgrades, implementation services, and ongoing maintenance. Healthcare organizations must also allocate resources for integrating IAM platforms with electronic health records (EHRs), hospital information systems (HIS), laboratory information systems (LIS), pharmacy management systems, and other legacy clinical applications. These integration projects are often complex and time-consuming due to the diverse IT environments and interoperability requirements across healthcare facilities.
In addition, companies need to invest in employee training, identity governance policies, and continuous system monitoring to ensure effective deployment and regulatory compliance. As a result, the high total cost of ownership and lengthy implementation timelines can discourage adoption, particularly among small and mid-sized hospitals, clinics, and healthcare providers with limited IT budgets.
The rapid migration of healthcare organizations to cloud-based electronic health records (EHRs), telehealth platforms, Software-as-a-Service (SaaS) applications, and hybrid IT environments is creating significant opportunities for market vendors. As healthcare providers enable remote access for clinicians, administrative staff, patients, and third-party partners, traditional perimeter-based security models are becoming less effective. Consequently, organizations are adopting Zero Trust security architectures based on the principle of "never trust, always verify," where every user, device, and application must be continuously authenticated and authorized before accessing sensitive healthcare data. These technologies improve security, simplify identity management across distributed healthcare environments, and help organizations comply with evolving healthcare data privacy regulations. For instance, in May 2026, Ping Identity partnered with OLOID to launch a passwordless Verified Trust solution for the U.S. clinical workforce. The solution enables verified onboarding, passwordless Tap-and-Login, and secure account recovery, helping healthcare organizations strengthen Zero Trust security while improving clinician access to clinical applications and reducing credential-based cyber risks
Market Concentration & Characteristics
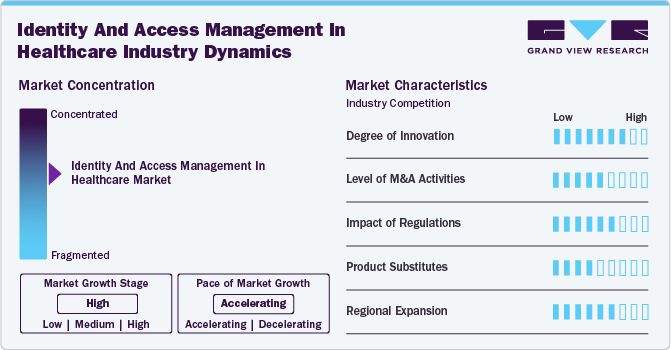
The degree of innovation in the identity and access management in healthcare industry is high. The progress in healthcare IT infrastructure, incorporating innovations such as IoT, big data, and AI, is a significant factor driving market expansion. Advanced technologies such as intelligent sensors, robotic pills, microcontrollers, digital networking, automotive microcontrollers, radiofrequency, and sensors play a significant role in driving the healthcare IT market.
The M&A activities, such as mergers, acquisitions, and partnerships, enable companies to expand geographically, financially, and technologically. It increased the customer base, thereby enhancing the company's position in the industry. In April 2022, Imprivata acquired SecureLink, paving the way for creating a unified platform that manages & secures all enterprise and third-party digital identities offered by a single vendor.
 To learn more about this report, Download Free Sample Report
The industry experiences a moderate level of impact of regulations. The 2016 General Data Protection Regulation (GDPR) is an extensive privacy legislation designed to safeguard the personal data and identity information of EU citizens, affecting any company engaged in business with European customers. Organizations are responsible for maintaining data security throughout the collection and storage processes. A comprehensive IAM solution meeting GDPR data privacy and security compliance standards should encompass the requirements.
Companies in the identity and access management industry undergo geographic expansion strategies to maintain their position in emerging markets and customer base from these regions. The expansion is done by launching products and facilities in new locations or forging partnerships, mergers, and acquisitions with companies from different locations.
Analyst Perspective
The identity and access management (IAM) in healthcare market is undergoing rapid transformation as healthcare organizations accelerate digital transformation initiatives and strengthen cybersecurity frameworks to protect sensitive patient data. AI, ML, passwordless authentication, adaptive multi-factor authentication, identity analytics, and Zero Trust security architectures are emerging as key technologies, enabling continuous risk assessment, intelligent access control, automated identity lifecycle management, and proactive threat detection. As healthcare organizations continue to prioritize regulatory compliance, cyber resilience, and secure interoperability across increasingly connected digital ecosystems, identity and access management is evolving from a traditional IT security function into a strategic capability that enhances operational efficiency, safeguards patient information, and supports the delivery of secure digital healthcare services.
Component Type Insights
Based on component, softwaresolutionsegment held the largest revenue share of 67.0% in 2025. The increasing adoption of electronic health records (EHRs) and other digital healthcare platforms by healthcare organizations is driving the software segment growth. For instance, as per a report by HealthIT.gov, by 2021, approximately 78% of office-based physicians and almost all non-federal acute care hospitals (96%) had implemented certified EHRs, indicating a significant increase from 2011 when only 28% of hospitals and 34% of physicians had implemented EHRs.
Furthermore, the need for software solutions in the identity and access management (IAM) market is being driven by the growing trend of telemedicine and remote healthcare services. The requirement for secure access and identity management in many platforms and devices is growing as more healthcare services are being rendered remotely.
Services segment is anticipated to witness significant growth over a forecast period.The growing complexity of IAM systems and the requirement for specific knowledge to effectively develop, implement, and manage them is driving the demand for services. Moreover, cyberattacks in the healthcare sector are growing, which is endangering patient data. With the escalation in both frequency and sophistication of data breaches, healthcare organizations are increasingly pursuing comprehensive IAM services to protect their systems & data from unauthorized access.
Deployment Insights
Based on deployment mode, the cloud segment held the largest revenue share of 67.8% in 2025. Cloud deployment mode in IAM in the healthcare sector involves utilizing cloud-based services and infrastructure to manage user identities, access controls, and security policies across healthcare organizations. Cloud IAM platforms also provide features such as SSO, MFA, and automated provisioning, enabling healthcare organizations to enhance security while improving user experience and operational efficiency. Moreover, cloud-based IAM solutions offer built-in redundancy and disaster recovery capabilities, ensuring the continuous availability of critical identity management services. Furthermore, the cloud deployment mode in IAM enables healthcare organizations to modernize their identity management infrastructure, adapt to evolving security threats, and efficiently manage access to sensitive patient information in a highly dynamic environment, thereby driving the segment growth.
The on premise segment is expected to witness significant growth over the forecast period. On-premise identity and access management (IAM) refers to the practice of managing user identities and access privileges within an organization's own physical infrastructure.Organizations with IAM on-premise have complete control over the system, including data storage and security. This can be especially important for organizations that handle sensitive data or are subject to strict regulations. Moreover, these systems can be tailored to an organization's specific needs and requirements. This enables organizations to customize the system to their specific business processes and workflows.
Type Insights
Based on type, the provisioning segment held the largest revenue share of 30.5% in 2025. Provisioning is the procedure of providing users with suitable access to resources within a company's network. This encompasses tasks such as establishing, altering, or deleting user accounts and allocating particular permissions & privileges according to their roles & duties.
For example, when a new employee joins a healthcare organization, provisioning entails setting up their user account, granting access to necessary applications such as EHR, and configuring permissions based on their job role. Likewise, when an employee changes roles or leaves the organization, provisioning involves adjusting their access rights to maintain security and compliance. Platforms such as CareRev introduce a versatile workforce framework incorporating elastic provisioning and adaptable workforce technology, reshaping the industry. Employing a flexible workforce strategically enables healthcare establishments to streamline labor expenses, elevate patient care standards, boost workforce morale, and effectively meet quality metric requirements.
The single sign on segment is anticipated to witness the fastest growth rate during forecast period. Single Sign-On (SSO) is a crucial component of IAM in healthcare market, which helps streamline user authentication across multiple systems with a single set of credentials. SSO enhances security and efficiency in healthcare, where access to sensitive patient data is paramount.Moreover, SSO in healthcare can integrate with existing authentication methods like biometrics or smart cards for additional security layers. By centralizing user authentication and access control, healthcare organizations can ensure compliance with regulatory requirements such as HIPAA while providing seamless access to critical patient information for authorized personnel. Thus, SSO significantly improves security, user experience, and operational efficiency within healthcare settings.
End-use Insights
Based on end use, the hospitals and clinics segment held the largest revenue share of 42.6% in 2025. IAM systems are crucial in promoting integration among hospitals, clinics, and other healthcare entities by facilitating secure data exchange while upholding the integrity and confidentiality of data & maintaining compliance with regulatory standards such as HIPAA. Hospitals and clinics have discovered that cloud technology streamlines operations, safeguards data, and cuts costs, all of which are tangible elements in enhancing overall management within healthcare organizations. For example, a patient diagnosed with diabetes generally meets with their doctor or a diabetes nurse educator to examine blood sugar levels over a period. These readings are commonly recorded in a Fast Healthcare Interoperability Resources (FHIR) application.
 To learn more about this report, Download Free Sample Report
Life science companies are anticipated to witness the fastest growth during the forecast period. Life science companies encompass pharmaceutical manufacturers, biotechnology firms, medical device manufacturers, and research organizations. IAM solutions are crucial for life science companies to ensure secure access to sensitive research data, intellectual property, and regulatory compliance information.
As digital technology and cloud usage expand in the life sciences sector, digital data becomes more accessible yet vulnerable to exploitation. IBM's Cost of a Data Breach 2022 report reveals that 83% of surveyed organizations faced multiple breaches, with 60% passing price increases on to clients. Among these breaches, 45% occurred in cloud environments, averaging USD 10.10 million per incident.Life sciences companies, including major pharmaceutical firms like Gilead, Pfizer, Roche, Moderna, & AstraZeneca, and startups like Relay Therapeutics, are enhancing their security using AWS infrastructure, thereby driving the market.
Regional Insights
North America dominated the identity and access management in healthcare market with the largest revenue share of 40.7% in 2025. A major factor propelling its substantial market presence is the need to meet regulatory requirements, particularly the Health Insurance Portability and Accountability Act (HIPAA), which mandates strict privacy and security protocols for patient information. In addition, the rising adoption of cloud-based solutions in North America is anticipated to drive the market. The increasing demand for scalable & flexible solutions and the need for cost-effective IT infrastructure are key factors driving the adoption of cloud-based IAM solutions.
 To learn more about this report, Download Free Sample Report
U.S. Identity And Access Management In Healthcare Market Trends
The identity and access management in healthcare market in the U.S. held the largest share in the North America region in 2025. The identity and access management in healthcare market in the U.S. is experiencing growth, driven by growing concerns regarding data security and the rising adoption of EHRs in office-based physicians & hospitals. Moreover, the presence of well-established healthcare infrastructure & high per capita healthcare expenditure in the U.S. is a major factor accelerating the adoption of Identity & Access Management (IAM) solutions in the U.S. For instance, as per a report by the OECD, in 2022, per capita health spending in the U.S. was USD 12,555, which is higher than in 2021 (USD 12,318). Furthermore, the rising number of cyberattacks in healthcare sector in the U.S. can help boost the adoption of IAM solutions in healthcare. For instance, as reported by The HIPAA Journal, in January 2023, the number of significant security breaches in healthcare reached 725 last year, surpassing the previous record of 720 breaches. These factors are likely to propel the U.S. market over the forecast period.
Europe Identity And Access Management In Healthcare Market Trends
The identity and access management in healthcare market in Europe is driven by various factors. Europe is one of the most developed regions in the world. The presence of a large number of healthcare providers and pharmaceutical & medical device companies enables the adoption of cloud-based solutions. In addition, mandatory implementation of IAM systems by European regulatory authorities is expected to propel the regional market.
Furthermore, the rising cases of cyberthreats, including data breaches and cyberattacks, are likely to drive the adoption of IAM solutions in Europe. For instance, as per data published by the European Union Agency for Cybersecurity (ENISA) in July 2023, a large volume of cyberattacks occurred In Europe over the past 2 years, with healthcare providers representing 53% of the total occurrences.The adoption of cloud computing has significantly transformed healthcare systems in Europe. For instance, continuous digital evolution across European industries has resulted in the uptake of cloud services, mobile apps, and Internet of Things (IoT) devices. IAM systems are pivotal in safeguarding these digital resources and facilitating smooth user access, all while upholding security protocols and compliance standards.
The identity and access management in healthcare market in UK has a substantial market share in 2024. The rising need for secure and efficient access to patient data is a primary driver of this market. With the growing adoption of EHRs and the imperative for healthcare practitioners to remotely access patient data, the implementation of IAM solutions can help safeguard sensitive information from unauthorized access. In addition, the adherence to data protection regulations such as the GDPR serves as a significant catalyst for the IAM market within the healthcare sector.
The identity and access management in healthcare market in Germany is expected to grow significantly over the forecast period. Major U.S. suppliers, such as IBM Security, SailPoint, Ping Identity, and Okta, have subsidiaries in Germany. The growing demand for cloud-based solutions to track inventory by healthcare manufacturers and service providers is expected to drive the market in Germany. Moreover, the rise in cybersecurity threats in Germany is expected to drive the demand for IAM solutions in the country’s market.
Asia Pacific Identity And Access Management In Healthcare Market Trends
The identity and access management in healthcare market in Asia Pacific is expected to witness fastest growth rate during the forecast period mainly due to a rise in regulatory compliance requirements to ensure patient safety and data security, such as the Personal Data Protection Act (PDPA) and the Act on the Protection of Personal Information (APPI), which directly drive the demand for IAM solutions in the region.
The rising incidences of cyberattacks in Asia Pacific are likely to contribute to market growth. Cyberattacks in the healthcare industry can have serious consequences, such as compromised patient data, interruptions to medical care, and financial losses. Solutions for IAM are essential for reducing cyberattack risks. For instance, as per a report by Positive Technologies, in 2022, Asia Pacific experienced the highest frequency of cyberattacks globally, constituting 31% of all attacks. These factors are expected to propel the regional market over the forecast period.
The identity and access management in healthcare market in China has a substantial market share in 2024. The healthcare industry in China is observing notable expansion in demand for IAM solutions, primarily due to rising concerns regarding data security and adherence to regulatory mandates. This sector has intense competition, fueled by prominent entities such as Alibaba Cloud, Tencent Cloud, IBM, Oracle, and Microsoft, which offer extensive IAM solutions tailored for healthcare enterprises. These offerings encompass a spectrum of functionalities, including SSO, multifactor authentication, identity governance, access control, and user authentication.
The identity and access management in healthcare market in India has a substantial market share in 2024. India has readily embraced new technologies in the healthcare sector, including adopting measures to meet rising demand for data security in healthcare. The rising use of EHRs is expected to drive the demand for IAM solutions. Moreover, healthcare establishments are mandated to ensure the security of patient records, prompted by the implementation of legislation such as the GDPR and HIPAA. IAM systems facilitate regulatory adherence among healthcare entities by documenting user interactions and providing authenticated users with secure access privileges. These factors are expected to drive the demand for IAM solutions in India’s healthcare sector.
Key Identity And Access Management In Healthcare Company Insights
Market players are utilizing innovative product development strategies, partnerships, and mergers and acquisitions to expand their presence
Key Identity And Access Management In Healthcare Companies:
The following key companies have been profiled for this study on the identity and access management in healthcare market.
- Veritis Group Inc.
- Fortra, LLC
- LexisNexis Risk Solutions Inc.
- Ping Identity
- Imprivata, Inc.
- IBM
- Okta, Inc.
- CyberArk Software Ltd.
- Delinea
- SailPoint Technologies, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (IBM, Microsoft, Oracle, Okta, Inc.)
Offer comprehensive IAM platforms featuring identity governance, single sign-on (SSO), multi-factor authentication (MFA), privileged access management (PAM), cloud identity, AI-driven security analytics, and Zero Trust architectures.
- Strong global presence, extensive partner ecosystems, broad cybersecurity portfolios, continuous R&D investments, and scalable cloud-based IAM platforms.
- High implementation and licensing costs, complex integration with legacy healthcare IT systems, lengthy deployment cycles, and dependence on skilled IT personnel.
Emerging / Specialized Players (Imprivata, Inc., CyberArk Software Ltd., Ping Identity, SailPoint Technologies, Inc.)
Focus on healthcare-specific identity security, privileged access management, passwordless authentication, identity governance, workforce access management, and Zero Trust solutions for clinical environments.
- Deep IAM expertise, healthcare-focused solutions, rapid innovation, strong compliance capabilities, and flexible cloud deployment options.
- Smaller product portfolios than diversified technology vendors, relatively limited presence outside core IAM segments, and dependence on strategic partnerships for broader healthcare ecosystem integration.
Recent Development
- In March 2024, Fortra and Lookout have established a strategic integration partnership to provide the Digital Guardian Secure Service Edge.
“As businesses migrate data and workloads to the cloud, the threat landscape has become broader and more complex. Threat actors are taking advantage of this complexity, exploiting gaps and relentlessly stepping up the volume of attacks. The Lookout-powered Digital Guardian Secure Service Edge offers a full set of security technologies to protect sensitive data and applications as organizations adopt cloud services and remote work models.”
- In February 2024, Carahsoft and Fortra have unveiled a distribution partnership, bringing cutting-edge cybersecurity solutions to the public sector market.
“Our decision to partner with Carahsoft is based on their established credibility as a trusted partner to Public Sector organizations, offering exceptional market expertise. Leveraging Carahsoft’s extensive reseller network and deep understanding of Government markets, we anticipate continued, rapid growth of Fortra’s Public Sector program. The partnership with Carahsoft will facilitate our Government business expansion while ensuring our joint Public Sector customers’ needs are met.”
- In October 2023, ManageEngine, the enterprise IT management division of Zoho Corporation, launched Identity360, its cloud-native identity management platform that addresses identity and access management (IAM) complexities arising within enterprise workforces.
Identity And Access Management In Healthcare Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.9 billion
Estimated market size in 2026
USD 2.2 billion
Projected market size by 2033
USD 7.1 billion
Growth rate
CAGR of 17.9% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, deployment mode, component, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Norway, Denmark, Sweden, China, Japan, India, South Korea, Australia, Thailand, Brazil, Argentina, Saudi Arabia, South Africa, UAE, Kuwait
Key companies profiled
IBM, Okta, Inc., CyberArk Software Ltd., Ping Identity, SailPoint Technologies, Inc., Imprivata, Inc., Delinea, Fortra, LLC, LexisNexis Risk Solutions Inc., Veritis Group Inc., Microsoft, Oracle.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Identity And Access Management In Healthcare Market Report Segmentation
This report forecasts revenue growth at the regional & country level and provides an analysis of the latest trends and opportunities in each of the sub-segments from 2021 to 2033. For the purpose of this report, Grand View Research has segmented the identity and access management in healthcare market on the basis of component, type, deployment, end-use and region:
-
Component Outlook (Revenue, USD Billion, 2021 - 2033)
-
Software Solutions
-
Services
-
-
Deployment Outlook (Revenue, USD Billion, 2021 - 2033)
-
On-premise
-
Cloud
-
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Single Sign On (SSO)
-
Multifactor Authentication
-
Provisioning
-
Directory Service
-
Audit & Compliance Management
-
-
End-use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Healthcare Payers
-
Hospitals & Clinics
-
Life Science Companies
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Spain
-
Italy
-
Norway
-
Denmark
-
Sweden
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The identity and access management in healthcare market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each identity and access management in healthcare segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment- Component
Revenue Capture Definition
Software Solutions
Revenue generated from software platforms used to manage digital identities, authenticate users, govern access rights, and secure healthcare IT environments. This includes identity governance and administration (IGA), single sign-on (SSO), multi-factor authentication (MFA), privileged access management (PAM), directory services, identity lifecycle management, password management, access management, and related identity security software deployed across healthcare organizations.
Services
Revenue generated from professional and managed services supporting the planning, deployment, integration, customization, consulting, training, maintenance, monitoring, and ongoing management of IAM solutions in healthcare organizations.
Segment-Deployment
Revenue Capture Definition
On-premise
Revenue generated from IAM solutions deployed and managed within a healthcare organization's own data centers and IT infrastructure. This includes perpetual software licenses, implementation services, maintenance, upgrades, and support for locally hosted identity management platforms.
Cloud
Revenue generated from cloud-hosted IAM solutions delivered through Software-as-a-Service (SaaS), Identity-as-a-Service (IDaaS), or hybrid cloud models. This includes subscription-based identity governance, authentication, access management, passwordless authentication, and cloud identity security services.
Segment-Type
Revenue Capture Definition
Single Sign-On (SSO)
Revenue generated from solutions that enable healthcare users to securely access multiple clinical and administrative applications using a single set of login credentials, improving user convenience, workflow efficiency, and security.
Multifactor Authentication (MFA)
Revenue generated from solutions that verify user identities using two or more authentication factors, such as passwords, biometrics, security tokens, smart cards, or mobile authentication applications, to protect access to healthcare systems and patient data.
Provisioning
Revenue generated from identity provisioning and lifecycle management solutions that automate user account creation, modification, role assignment, access provisioning, and de-provisioning across healthcare applications and IT systems.
Directory Service
Revenue generated from centralized directory services that store, organize, and manage user identities, credentials, devices, groups, and authentication information for secure access across healthcare networks and applications.
Audit & Compliance Management
Revenue generated from solutions that monitor user activities, generate audit logs, manage access reviews, enforce identity governance policies, and support compliance with healthcare regulations such as HIPAA, GDPR, and other healthcare data privacy standards.
Segment- End Use
Revenue Capture Definition
Healthcare Payers
Revenue generated from IAM solutions deployed by health insurance companies and payer organizations to secure member information, claims systems, provider portals, employee identities, and digital healthcare services while ensuring regulatory compliance.
Hospitals & Clinics
Revenue generated from IAM solutions used by hospitals, health systems, specialty clinics, ambulatory care centers, and physician practices to manage workforce identities, secure access to electronic health records (EHRs), clinical applications, medical devices, and patient information systems.
Life Science Companies
Revenue generated from IAM solutions adopted by pharmaceutical companies, biotechnology firms, medical device manufacturers, contract research organizations (CROs), and research institutions to protect research data, intellectual property, manufacturing systems, and regulated digital environments.
Others
Revenue generated from IAM solutions used by diagnostic laboratories, blood banks, imaging centers, public health agencies, government healthcare organizations, academic medical centers, long-term care facilities, home healthcare providers, and other healthcare-related organizations.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Landscape Analysis
Analysis of key players based on product portfolio, healthcare focus, identity governance, privileged access management (PAM), multi-factor authentication (MFA), Zero Trust capabilities, cloud deployment, AI-driven identity security, and strategic initiatives.
Helps identify optimal pricing strategy, customer willingness-to-pay, and revenue optimization opportunities.
Company Market Share Analysis
Assessment of market share of leading IAM vendors based on revenue, healthcare customer base, product offerings, geographic presence, partnerships, and strategic developments.
Helps evaluate market concentration, competitive intensity, and benchmark the performance of key market participants.
Regional Cybersecurity & Healthcare Digitalization Analysis
Assessment of regional demand driven by healthcare digital transformation, cloud adoption, cybersecurity investments, regulatory compliance, and increasing adoption of electronic health records (EHRs) and telehealth platforms.
Helps identify high-growth regional markets, investment opportunities, and expansion strategies for IAM solution providers.
Frequently Asked Questions About This Report
Key factors that are driving the market growth includes growing concern regarding data security and compliance with regulations to uphold patient safety and confidentiality, the increasing adoption of cloud based solutions and rising emphasis on regulatory compliance requirement to ensure patient safety and data security is impelling the market growth.
Asia Pacific is the fastest-growing region over the forecast period.
North America dominated the identity and access management in healthcare market with a market share of 40.7% in 2025.
Cloud segment held the largest market share of 67.8% in 2025 while on premise segment is second fastest growing market
Based on type, the provisioning segment held the largest revenue share of 30.5% in 2025. Provisioning is the procedure of providing users with suitable access to resources within a company's network.
Hospitals and clinics segment held the largest revenue share of 42.6% in 2025 while life science companies is expected to be the fastest-growing market.
The global identity and access management in healthcare market size was estimated at USD 1.9 billion in 2025 and is estimated at USD 2.2 billion in 2026.
The global identity and access management in healthcare market is expected to grow at a CAGR of 17.9% from 2026 to 2033, reaching USD 7.1 billion by 2033
Some key players operating in the global identity and access management in healthcare market includes IBM, Okta, Inc., CyberArk Software Ltd., Ping Identity, SailPoint Technologies, Inc., Imprivata, Inc., Delinea, Fortra, LLC, LexisNexis Risk Solutions Inc., Veritis Group Inc., Microsoft, Oracle.
About the Author(s)
Healthcare IT Research Team
Healthcare · Healthcare ITThis report was authored by the healthcare it research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the healthcare it segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


