
- Home
- »
- Medical Devices
- »
-
Implantable Medical Devices Market Size Report, 2026-2033GVR Report cover

Implantable Medical Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Cardiovascular, Orthopedic, Aesthetic, Dental, Ophthalmology, Neurology), By Biomaterial (Ceramic, Metallic, Polymers, Natural), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$102.9BMarket Estimate, 2026
$109.2BMarket Forecast, 2033
$165.3BCAGR, 2026–2033
6.1%Implantable Medical Devices Market Summary
The global implantable medical devices market size was valued at USD 102.9 billion in 2025 and is projected to grow from USD 109.2 billion in 2026 to USD 165.3 billion by 2033, at a CAGR of 6.1% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of approximately 43.0% in 2025. Advancements in surgical techniques, particularly minimally invasive procedures, have expanded the application of implantable medical devices.
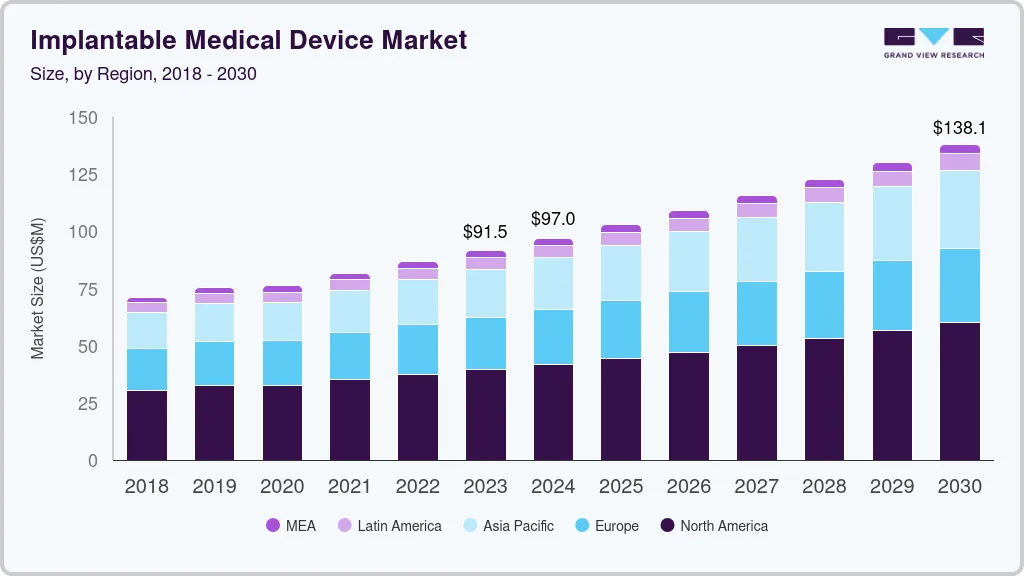 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The cardiovascular implants segment held the largest market share of approximately 30.5% in 2025.
- By biomaterial: The metallic segment held the largest market share of approximately 49.0% in 2025.
- By end-use: The hospitals segment led the market with the largest revenue share of approximately 43.5% in 2025.
Regional Highlights
- Largest regional market: North America (43.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 102.9 Billion
- Estimated market size in 2026: USD 109.2 Billion
- Projected market size by 2033: USD 165.3 Billion
- CAGR (2026-2033): 6.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
For instance, in January 2024, Accelus, a US-based medical technology company, introduced a modular cortical system for spinal implant surgeries. The system allows surgeons to place screw shanks early and customize the construct. The system is available in open and cortical sets, catering to different surgical approaches.
Technological innovation plays a pivotal role in driving the market growth. Advances in materials science, miniaturization, biocompatibility, and sensor technology have revolutionized the design and functionality of implantable devices. For instance, the development of advanced biomaterials such as titanium alloys and bioresorbable polymers has enhanced the durability, biocompatibility, and integration of implants within the body. These materials reduce the risk of rejection, promote tissue regeneration, and improve long-term outcomes for patients.
Moreover, sensor technology and wireless connectivity have enabled implantable devices to collect real-time data on physiological parameters and transmit this information to healthcare providers remotely. This capability supports remote monitoring, early detection of complications, and timely intervention. For example, implantable cardiac monitors can continuously monitor heart rhythms and detect arrhythmias, allowing physicians to intervene promptly and prevent adverse cardiac events.
The rising prevalence of chronic diseases such as cardiovascular diseases, diabetes, and orthopedic conditions drives the demand for implantable medical devices. According to the World Health Organization (WHO), around 422 million people worldwide, primarily in low- and middle-income countries, are affected by diabetes, which causes 1.5 million deaths annually, with the number of cases and prevalence increasing steadily in recent decades.
Implantable medical devices play a critical role in managing chronic conditions, improving patient mobility, and enhancing quality of life. For instance, orthopedic implants such as hip and knee replacements restore joint function and alleviate pain in patients with osteoarthritis, enabling them to maintain an active lifestyle. In addition, implantable devices are increasingly used in the treatment of neurological disorders such as Parkinson's disease and epilepsy. According to Parkinson's Foundation, nearly 90,000 people in the U.S. are diagnosed yearly with Parkinson's condition. Moreover, around 1 million people in the country are living with the condition. Neurostimulation devices deliver electrical impulses to targeted areas of the brain or nerves, reducing symptoms such as tremors or seizures and improving patients' daily functioning and quality of life.
Analyst Perspective
The implantable medical devices industry is expected to witness robust growth, driven by continuous technological advancements and the rising global burden of chronic diseases. Innovations in biomaterials, including titanium alloys and bioresorbable polymers, are significantly improving device biocompatibility, durability, and long-term clinical outcomes, thereby expanding their adoption across multiple therapeutic areas. At the same time, the integration of wireless connectivity and advanced sensor technologies is transforming implantable devices into intelligent monitoring solutions that enable real-time data collection and remote patient management. This shift aligns with the growing significance of value-based healthcare, early disease detection, and personalized treatment.
Furthermore, the increasing prevalence of cardiovascular disorders, diabetes, orthopedic conditions, and neurological diseases is creating sustained demand for implantable therapies that improve patient mobility, reduce disease complications, and enhance quality of life. As healthcare providers increasingly prioritize minimally invasive and connected care solutions, manufacturers are investing in smart, patient-centric implantable devices with enhanced monitoring capabilities. Collectively, these technological innovations and expanding clinical applications are expected to support the market's long-term growth trajectory and create new opportunities for product differentiation and strategic investments.
Product Insights
The cardiovascular implants segment led the market with the largest revenue share of approximately 30.5% in 2025, due to its critical role in managing and treating cardiovascular diseases globally. This segment includes devices such as pacemakers, implantable cardioverter-defibrillators (ICDs), cardiac stents, and cardiac monitors. Cardiovascular diseases, including coronary artery disease, heart failure, and arrhythmias, are leading causes of morbidity and mortality worldwide. According to the various secondary sources & GVR analysis, heart failure affects more than 84 million people globally. The increasing prevalence of these conditions necessitates the use of implantable devices for effective management and treatment. In October 2026, Abbott launched its flagship leadless pacemaker, AVIER DR, in India. The pacemaker is smaller than an AAA battery and precisely synchronizes the heartbeats.
The dental implants segment is expected to grow at the fastest CAGR of approximately 10.0% during the forecast period, owing to the rising global trend towards cosmetic enhancements. The dental implant segment is poised for substantial growth driven by its expanding applications across various therapeutic areas and the increasing demand for prosthetics. Dental implants offer not only functional benefits but also enhance a person's appearance and overall quality of life. Notably, developed countries such as the U.S. have been at the forefront of this growth, with millions of dental implant procedures performed annually, as evidenced by the American Dental Association's data
Biomaterial Insights
The metallic segment led the market with the largest revenue share of approximately 49.0% in 2025. Metals such as titanium alloys, stainless steel, and cobalt-chromium alloys are preferred for their mechanical strength, biocompatibility, and durability, making them ideal for implants that require long-term functionality within the human body. They can be fabricated in complex shapes and sizes, allowing customization to patient-specific anatomical requirements. This versatility supports the development of personalized implants that optimize fit and functionality. These characteristics make metallic implants indispensable in orthopedics, cardiovascular interventions, and other medical specialties, driving innovation and improving patient outcomes globally.
The natural biomaterial segment is expected to grow at the fastest CAGR of over 6.5% during the forecast period. There is a growing patient preference for natural or biocompatible materials in medical implants due to their perceived safety and reduced risk of adverse reactions or complications. Ongoing advancements in biomaterials and manufacturing techniques have enabled the development of more sophisticated natural implants that offer better integration with the body and improved long-term outcomes. Favorable regulatory policies and approvals for natural implants, ensuring their safety and efficacy, encourage healthcare providers and patients to adopt these devices more readily.
End Use Insights
The hospitals segment led the market with the largest revenue share of over 43.5% in 2025. Hospitals serve as primary centers for complex medical procedures, including surgeries requiring implantable medical devices. They offer specialized departments like cardiology, orthopedics, neurology, and oncology, where implantable devices are routinely used. Hospitals provide comprehensive healthcare services, access to advanced technologies, multidisciplinary care teams, inpatient monitoring capabilities, and a foundation for research and innovation, enabling high-quality, specialized care that improves patient outcomes and advances global medical knowledge.
The outpatient facilities segment is expected to grow at the fastest CAGR of approximately 6.5% during the forecast period, owing to the increasing demand for outpatient procedures and patient preference for less invasive treatments. Outpatient facilities align with the growing preference for patient-centric care models, in which convenience and minimal disruption to daily life are prioritized. Patients prefer outpatient procedures because they typically involve shorter wait times, shorter hospital stays, and lower costs than inpatient care. In lieu of these trends, more than 23 million procedures are performed in ambulatory surgery centers (ASCs) within the U.S. annually. In addition, the number of ASCs in the country increased to 6,223 in 2024, up from 6,109 in 2023.
Regional Insights
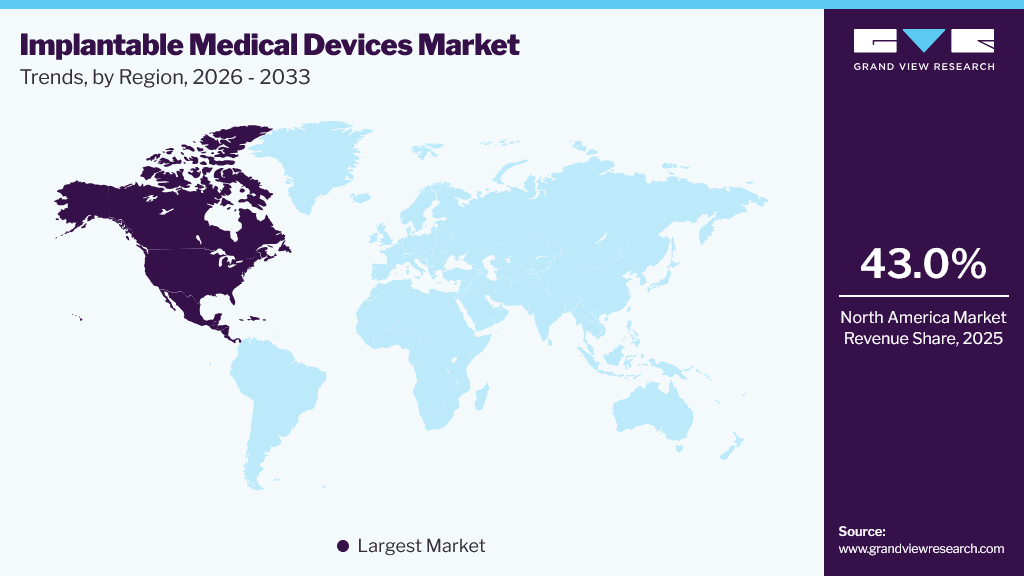
North America dominated the global implantable medical devices market with the largest revenue share of approximately 43.0% in 2025, owing to the advanced healthcare infrastructure, high healthcare expenditure, and a strong focus on technological innovation. The region benefits from a large patient pool and a high prevalence of chronic diseases, driving demand for devices such as cardiac and orthopedic implants and neurostimulators. Moreover, collaborations among healthcare providers, research institutions, and industry players drive continuous advances in biomaterials and surgical techniques. The shift towards outpatient settings for minimally invasive procedures further supports market expansion by offering cost-effective, patient-centric care options.
 To learn more about this report, Download Free Sample Report
U.S. Implantable Medical Devices Market Trends
The implantable medical devices market in the U.S. accounted for the largest market revenue share in 2025, driven robust healthcare infrastructure. Regulatory frameworks like the FDA in the U.S. ensure rigorous standards for safety and efficacy, facilitating market growth. Academic and research institutions collaborate with industry leaders to drive technological advancements and improve patient outcomes, positioning the U.S. as a leader in the global market. For instance, in June 2025, Anika Therapeutics received U.S. FDA 510(k) clearance for its Integrity Implant. The implant is a regenerative tendon-protection device used in orthopedic soft-tissue repair.
Europe Implantable Medical Devices Market Trends
The implantable medical devices market in Europe is characterized by a strong regulatory environment, technological innovation, and increasing healthcare expenditures. The region benefits from universal healthcare systems in many countries, ensuring broad access to advanced medical treatments, including implantable devices. For instance, in February 2024, King's College London inaugurated MAISI, a cutting-edge facility situated at St Thomas' Hospital. This facility marks a significant step forward in the production of active implants and surgical instruments. Its primary objective is to facilitate the seamless transition of healthcare engineering research into clinical applications. MAISI also addresses the critical need for dedicated, compliant manufacturing facilities within healthcare environments. The high prevalence of an aging population and chronic diseases drives demand for various implants.
Asia Pacific Implantable Medical Devices Market Trends
The implantable medical devices market in the Asia Pacific is anticipated to grow at a significant CAGR of over 7.0% during the forecast period. The Asia Pacific market is rapidly expanding due to the development of healthcare infrastructure, rising healthcare expenditure, and the growing prevalence of chronic diseases. Countries like China, Japan, and India are major contributors to market growth, driven by large patient populations and improving access to advanced medical technologies. Aging populations, urbanization, and lifestyle changes contribute to increased demand for cardiac implants and orthopedic implants. For instance, more than 29.1% of the Japan’s population is aged 65 and older.
Key Implantable Medical Devices Company Insights
The competitive landscape of the global market features key players such as Medtronic, Abbott Laboratories, and Boston Scientific Corporation. These industry leaders are actively engaged in strategic initiatives, including mergers and acquisitions, to strengthen their market positions.
Key Implantable Medical Devices Companies
The following key companies have been profiled for this study on the global implantable medical devices market:
-
Medtronic
-
Abbott Laboratories
-
Johnson and Johnson
-
Boston Scientific Corporation
-
Smith & Nephew plc
-
Stryker
-
Cochlear Limited
-
Integra LifeSciences
-
LivaNova PLC
-
Biotronik SE and Co. KG
Recent Developments
-
In February 2026, Motica implants received major FDA approval for their SmoothSilk, Ergonomic, and Round models of breast implants. The silicone gel implants got approval from the FDA after more than a decade since any other breast implant got approval.
-
In 2024, Chinese scientists at Tsinghua University successfully implanted a brain-computer interface called NEO. The interface helped a paralyzed man to control his hand within three weeks.
-
In June 2024, BioHorizons, a dental implant company, launched Tapered Pro Conical, which utilizes a tapered body and thread to provide stability. In addition, this implant can be used for single-tooth and full-arch dental implants.
-
In June 2024, Royal Philips implanted the Duo Venous Stent System, an advanced medical device crafted to address symptomatic venous outflow obstruction in individuals suffering from chronic venous insufficiency. This achievement follows the device's premarket approval by the U.S. Food and Drug Administration, marking a significant advancement in treatment options for affected patients.
Implantable Medical Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 102.9 billion
Estimated market size in 2026
USD 109.2 billion
Projected market size by 2033
USD 165.3 billion
Growth rate
CAGR of 6.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, biomaterial, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; Italy; France; Spain; Denmark; Sweden; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Medtronic; Abbott Laboratories; Johnson and Johnson; Boston Scientific Corporation; Smith & Nephew plc; Stryker; Cochlear Limited; Integra LifeSciences; LivaNova PLC; Biotronik SE and Co. KG
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Implantable Medical Devices Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global implantable medical devices market report based on product, biomaterial, end use, and region:
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Cardiovascular Implants
-
Orthopedic Implants
-
Ophthalmology Implants
-
Dental Implants
-
Aesthetic Implants
-
Neurology Implants
-
-
Biomaterial Outlook (Revenue, USD Billion, 2021 - 2033)
-
Ceramic
-
Metallic
-
Polymers
-
Natural
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospitals
-
Outpatient Facilities
-
Specialty Clinics & Centers
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global implantable medical devices market size was valued at USD 102.9 billion in 2025 and is estimated at USD 109.2 billion for 2026.
North America dominated with a 43.0% revenue share in 2025.
Some of the key players in implantable medical devices market are Medtronic, Abbott Laboratories, Johnson and Johnson, Boston Scientific Corporation, Smith & Nephew plc, Stryker, Cochlear Limited, Integra LifeSciences, LivaNova PLC, Biotronik SE and Co. KG, and others.
The global implantable medical devices market is expected to grow at a CAGR of 6.1% from 2026 to 2033, reaching USD 165.3 billion by 2033.
The cardiovascular implant segment medical devices segment accounted for the largest revenue share of approximately 30.5% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


