
- Home
- »
- Digital Media
- »
-
In-Game Advertising Market Size & Share Report, 2026-2035GVR Report cover

In-Game Advertising Market (2026 - 2035)
Size, Share & Trends Analysis Report By Type (Static Ads, Dynamic Ads, Advergaming), By Device (PC/Laptop, Smartphone/Tablet), By Region (North America, Europe, Asia Pacific), And Segment Forecasts
Market Size, 2025
$142.0BMarket Estimate, 2026
$158.6BMarket Forecast, 2035
$429.4BCAGR, 2026–2035
11.7%In-Game Advertising Market Summary
The global in-game advertising market size was valued at USD 142.0 billion in 2025 and is projected to grow from USD 158.6 billion in 2026 to USD 429.4 billion in 2035, at a CAGR of 11.7% from 2026 to 2035. North America dominated the market, accounting for the largest revenue share in 2025. The in-game advertising industry is gaining momentum as rising gamer engagement and the rapid expansion of mobile gaming encourage brands to leverage immersive placements to reach highly engaged audiences.
Key Market Trends & Insights
- By type: Dynamic ads segment held the largest market share in 2025
- By device: Smartphone/tablet segment held the largest market share in 2025
Regional Highlights
- Largest regional market: North America
- Fastest-growing regional market: Asia Pacific (fastest CAGR, 2026-2035)
Market Size & Forecast
- Market size in 2025: USD 142.0 Billion
- Estimated market size in 2026: USD 158.6 Billion
- Projected market size by 2035: USD 429.4 Billion
- CAGR (2026-2035): 11.7%
Prism AI by Grand View Research Free to tryAsk a question about the In-Game advertising marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The global in-game advertising (IGA) market is experiencing significant growth, driven by advertisers' growing recognition of video games as a highly engaging medium for reaching large, diverse groups of active consumers. The rapid growth of mobile, PC, console, cloud, and e-sports gaming has made video game platforms lucrative avenues for brands to deliver engaging and non-intrusive advertising messages. The growing popularity of freemium video games has further accelerated in-game advertising, enabling game publishers to monetize through rewarded videos, display advertisements, branded content, native ads, and programmatic advertising while maintaining player engagement. Moreover, advancements in AI, real-time analytics, and audience targeting are helping advertisers improve their return on advertising spend (ROAS).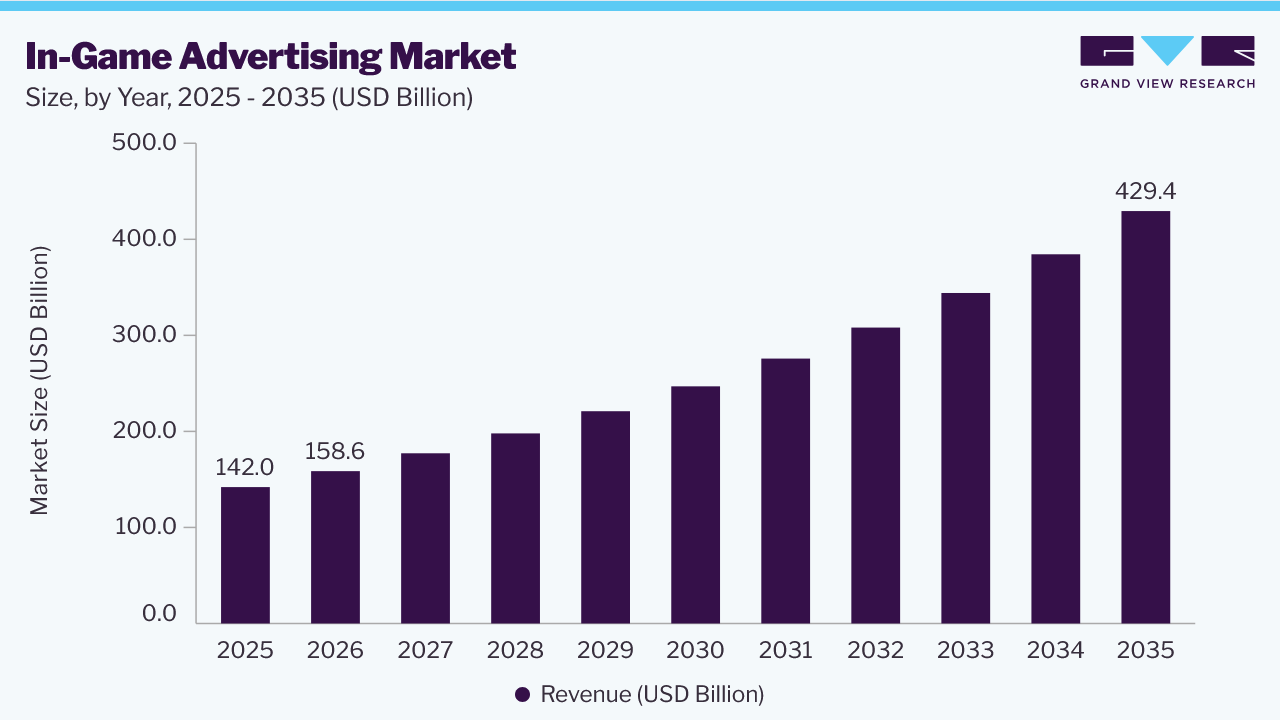 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
As advertising technology becomes more prevalent, new avenues have emerged for advertisers to reach customers across mobile, console, PC, and cloud gaming platforms, enabling them to launch targeted campaigns leveraging first-party data and AI-driven targeting. Furthermore, the growing influence of esports, streaming services, and online gaming communities has encouraged international brands across the automotive, retail, entertainment, consumer goods, and financial sectors to incorporate advertising into games.
Analyst Perspective
The in-game advertising industry is projected to grow steadily as gaming becomes a leading global digital entertainment platform. Rising interest in free-to-play and mobile games, along with advances in AI-driven programmatic advertising, enables companies to create personalized and engaging ads that do not disrupt gameplay. Growth in esports, cloud gaming, and cross-platform networks is expanding advertising opportunities and attracting investment from consumer brands, automotive firms, entertainment companies, and retailers. Enhanced real-time analytics, audience segmentation, and dynamic ad placement are further improving campaign performance. As global interest in gaming increases, in-game advertising is expected to become a core component of digital marketing strategies.
Type Insights
The dynamic ads accounted for the largest revenue share of the global in-game advertising market in 2025. This can be attributed to the rising trend toward programmatic advertising, intelligent audience targeting powered by artificial intelligence, and immediate ad serving across mobile, PC, console, and cloud gaming environments. Unlike static ads, which require changes to the game to adapt ad content based on location, demographics, and seasonality, dynamic ads enable these adjustments without modifying the game itself.
The advergaming segment is anticipated to grow at the fastest CAGR over the forecast period. Growth in this segment is being driven by increasing investments by international companies in gaming solutions designed to enhance customer engagement and brand recall. Businesses are leveraging custom games, branded virtual environments, and interactive gaming experiences to connect with Gen Z and Gen Alpha consumers. Developments in metaverse platforms and creator economies, coupled with the growing availability of AI-driven game development tools, are encouraging brands to integrate advertising into gaming experiences. For instance, in January 2026, Roblox expanded its advertising technology capabilities through more immersive ad formats, strengthened programmatic partnerships, and branded experiences, enabling advertisers to engage with Gen Z audiences through gaming environments. This development highlights the growing adoption of advergaming and branded gaming experiences as effective marketing tools.
Device Insights
The smartphones/tablets segment accounted for the largest revenue share of the in-game advertising industry in 2025, driven by the widespread use of smartphones, increased mobile internet access, and the rise of free-to-play mobile games that rely on advertising revenue. Mobile gaming enables advertisers to reach large, highly engaged audiences through rewarded videos, playable ads, interstitials, and native ads. For instance, in May 2026, Unity partnered with Nexxen to bring Unity’s mobile in-app gaming inventory to Nexxen’s demand-side platform. The integration provides brands and agencies with access to mobile gaming video inventory across iOS and Android, supporting the broader adoption of rewarded video and other in-game advertising formats across mobile games.
The PC/laptop segment is expected to grow at the fastest CAGR during the forecast period. Growth in this category can be attributed to increasing interest in esports, high-quality gaming content, cloud gaming services, and high-end gaming computers, which attract premium advertisers seeking to reach highly engaged audiences. Increased spending on dynamic in-game advertising, branded gaming experiences, and programmatic advertising is enabling advertisers to deliver contextual and targeted ads within PC games.
Regional Insights
The North America dominated the global in-game advertising market, accounting for the largest revenue share in 2025. The region's leading position can be attributed to its large gaming population, the presence of leading game publishers and ad-tech vendors, and the concentration of major technology companies. The high adoption of programmatic advertising, cloud gaming, esports, and AI-based audience targeting has contributed to increased advertising spending across the gaming ecosystem. Rising demand among brands for targeted advertising opportunities within video games is further driving market growth. For instance, in June 2026, Electronic Arts launched EA Advertising, a new platform that enables brands to place advertisements directly within EA gameplay and live experiences across console, PC, and mobile games. The platform supports dynamic in-game placements, branded content, reward-driven objectives, and advertising units across EA SPORTS titles.
Asia Pacific In-game Advertising Market Trends
The Asia Pacific in-game advertising industry is expected to grow at the fastest CAGR over the forecast period, driven by a rapidly growing base of mobile gamers, increased smartphone usage, greater internet availability, and rising investment in esports and digital entertainment. Countries such as China, India, Japan, and South Korea are expected to witness growing demand for in-game advertising as brands increasingly leverage gaming platforms to reach younger audiences. For instance, in May 2025, PepsiCo India partnered with Battlegrounds Mobile India (BGMI) to make Sting Energy the game's official in-game energy drink. The campaign featured Sting as an in-game power-up and introduced a custom BGMI event, connecting the consumer brand directly with India's growing mobile gaming audience.
Key In-game Advertising Company Insights
The in-game advertising market is characterized by global, regional, and niche solution providers competing through technological innovation, strategic partnerships, acquisitions, and expansion of advertising formats and gaming inventory. Leading companies are investing in artificial intelligence (AI), programmatic advertising, cross-platform targeting, interactive ad formats, rewarded video, playables, and data-driven audience targeting to improve campaign performance and player engagement. Providers are expanding their capabilities across mobile, PC, and console gaming while developing native and non-disruptive advertising experiences that integrate with gameplay.
Key In-game Advertising Companies
The following key companies have been profiled for this study on the in-game advertising market:
-
Microsoft
-
Google LLC
-
AppLovin
-
Unity Technologies
-
Anzu Virtual Reality Ltd.
-
AdInMo Ltd.
-
Frameplay
-
Landvault Ltd.
-
Roblox Corporation
Recent Developments
- In May 2026, Microsoft Advertising introduced Rewarded Portals, a new immersive advertising format within Candy Crush Saga that enables brands to deliver opt-in, interactive advertising experiences integrated naturally into gameplay. The solution is designed to improve player engagement while increasing brand awareness and campaign performance across Microsoft's gaming ecosystem.
- In April 2025, Roblox launched Rewarded Video Ads and partnered with Google Ad Manager to enable brands and agencies to purchase the format programmatically. The ads appear as opt-in, full-screen videos within Roblox experiences, with users receiving in-game rewards after viewing the ads.
In-game Advertising Market Report Scope
Report Attribute
Details
Market size in 2025
USD 142.0 billion
Estimated market size in 2026
USD 158.6 billion
Projected market size by 2035
USD 429.4 billion
Growth rate
CAGR of 11.7% from 2026 to 2035
Base year for estimation
2025
Actual data
2021 – 2024
Forecast period
2026 – 2035
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2035
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, device, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; Japan; India; Australia; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
Microsoft; Google LLC; AppLovin; Unity Technologies; Anzu Virtual Reality Ltd.; AdInMo Ltd.; Frameplay ; Landvault Ltd.; Roblox Corporation
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global In-game Advertising Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2035. For this study, Grand View Research has segmented the global in-game advertising market report based on type, device, and region:
-
Type Outlook (Revenue, USD Billion, 2021 - 2035)
-
Static Ads
-
Dynamic Ads
-
Advergaming
-
-
Device Outlook (Revenue, USD Billion, 2021 - 2035)
-
PC/Laptop
-
Smartphone/Tablet
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2035)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Frequently Asked Questions About This Report
The in-game advertising market size was valued at USD 142.0 billion in 2025 and is estimated at USD 158.6 billion for 2026.
The in-game advertising market is expected to grow at a CAGR of 11.7% from 2026 to 2035, reaching USD 429.4 billion in 2035.
The dynamic ads segment accounted for the largest revenue share in 2025.
North America dominated with the largest revenue share in 2025.
Key players in the market include Microsoft, Google LLC, AppLovin, Unity Technologies, Anzu Virtual Reality Ltd., AdInMo Ltd., Frameplay, Landvault Ltd., and Roblox Corporation.
About the Author(s)
Digital Media Research Team
Technology · Digital MediaThis report was authored by the digital media research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the digital media segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


