
- Home
- »
- Medical Devices
- »
-
India Home Healthcare Market Size, Share Report 2026-2033GVR Report cover

India Home Healthcare Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Equipment, Services), By Indication (Cancer, Wound Care, Maternal Disorders, Neurological & Mental Disorders), By Region (Urban, Rural), & Segment Forecasts
Market Size, 2025
$6.4BMarket Estimate, 2026
$7.2BMarket Forecast, 2033
$16.8BCAGR, 2026–2033
12.9%India Home Healthcare Market Summary
The India home healthcare market size was valued at USD 6.4 billion in 2025 and is projected to grow from USD 7.2 billion in 2026 to USD 16.8 billion by 2033, at a CAGR of 12.9% from 2026 to 2033. Market growth is driven by the rising elderly population, increasing prevalence of chronic diseases, and growing preference for receiving healthcare services at home.
Key Market Trends & Insights
- By component: Service segment held the largest revenue share of 84.0% in 2025.
- By indication: Respiratory disease & COPD held the largest market share of 16.6% 2025.
Market Size & Forecast
- Market Size in 2025: USD 6.4 Billion
- Estimated Market Size in 2026: USD 7.2 Billion
- Projected Market Size by 2026: USD 16.8 billion
- CAGR (2026-2033): 12.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
In addition, the expansion of digital health platforms, remote patient monitoring, telehealth, and home-based diagnostic services is improving access to quality care across urban and semi-urban areas. For instance, in May 2025, Even Healthcare expanded its care delivery model by launching its first 70-bed multi-specialty hospital in Bengaluru. The expansion integrates in-person care with the company's existing digital platform, teleconsultation, and continuous patient monitoring services, reflecting the growing adoption of technology-enabled, home-connected healthcare models in India.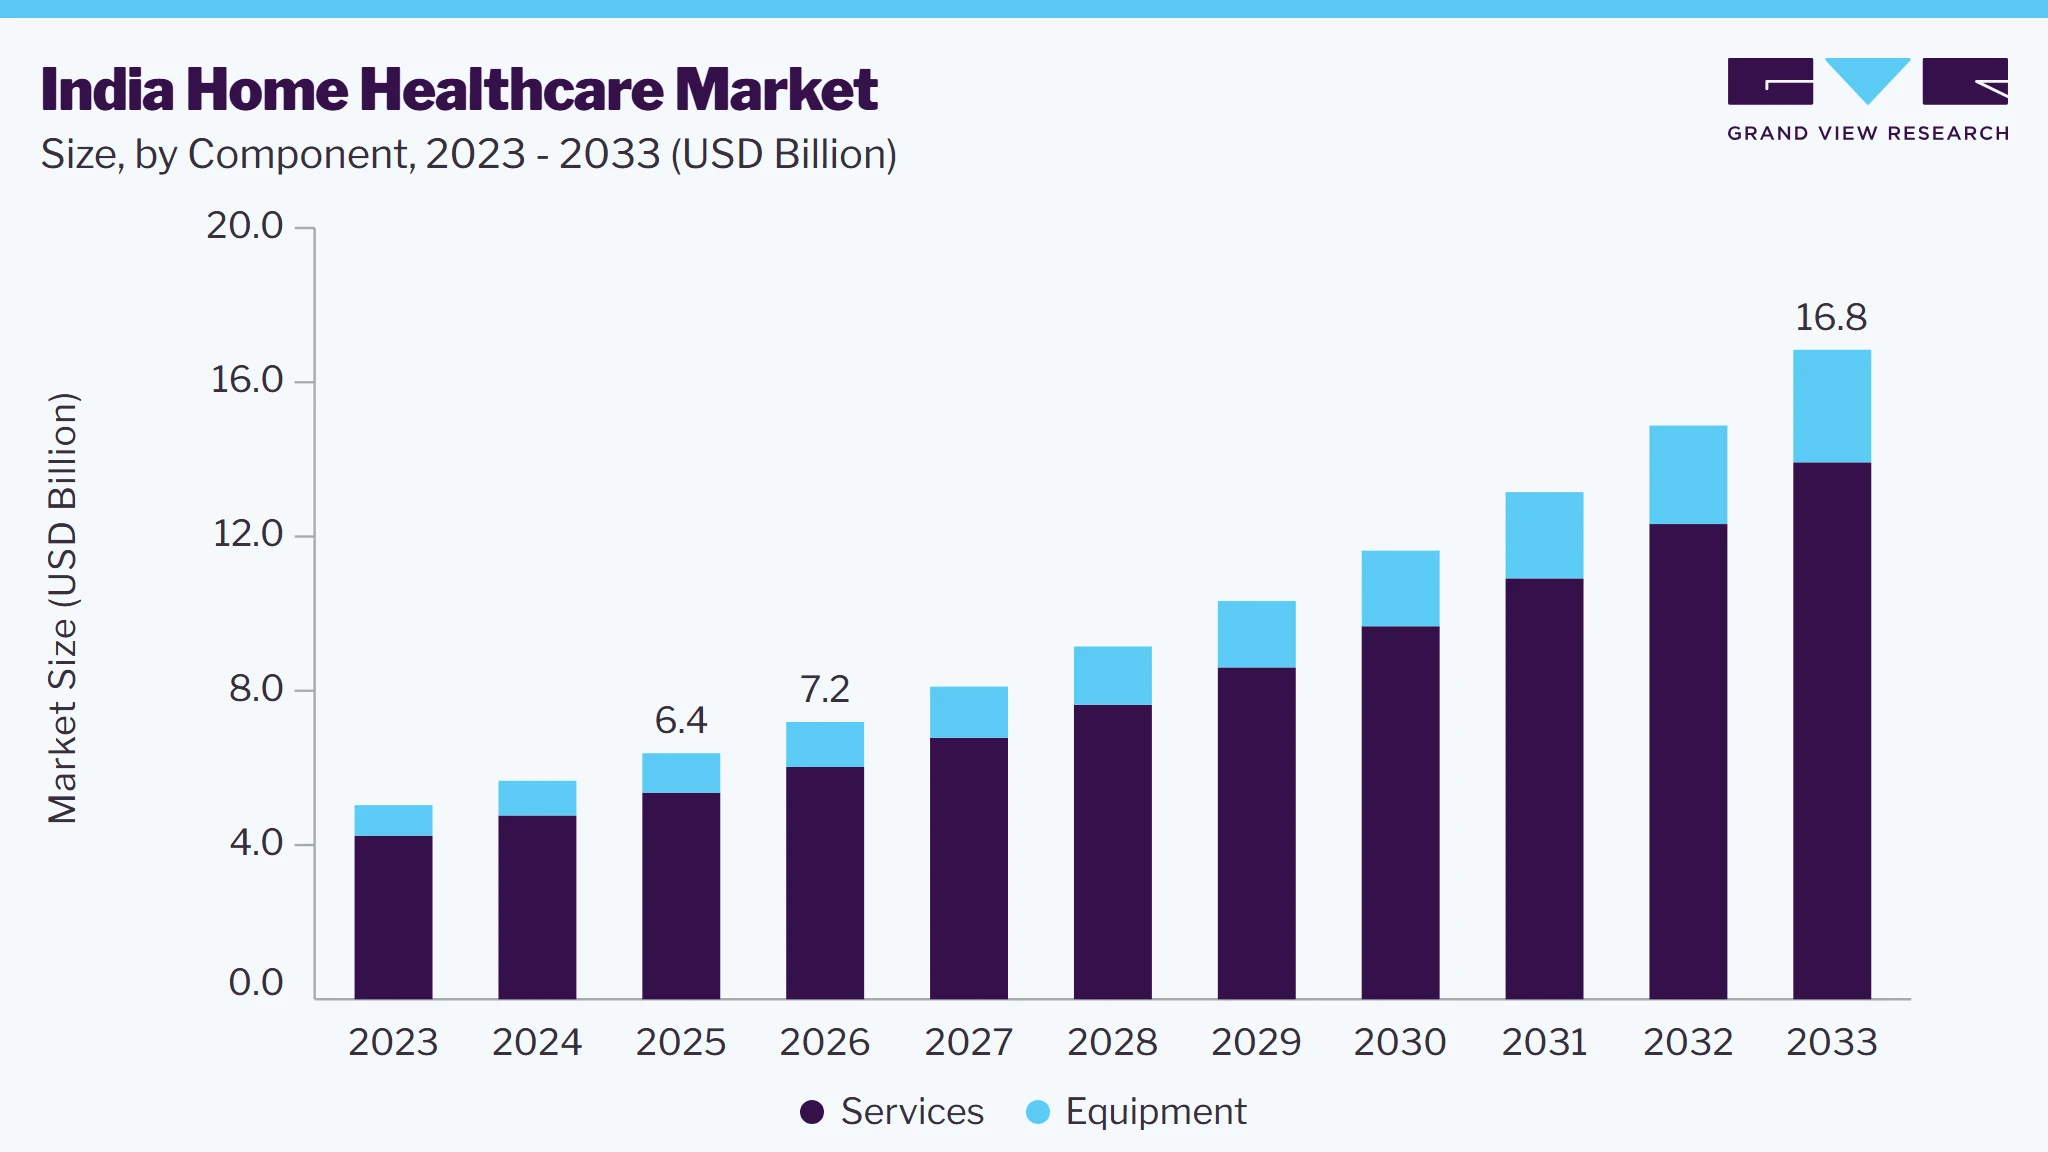 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The section below outlines the key factors driving the growth of the India home healthcare industry, highlighting the rising incidence of road accidents, sports injuries, fractures, and orthopedic trauma cases across the region. It also examines increasing healthcare investments, expanding access to advanced orthopedic care, growing adoption of minimally invasive trauma fixation technologies, and the rising presence of international medical device manufacturers supporting market expansion.
Market Dynamics
The rapid expansion of hospital-at-home programs by India's leading hospital networks is emerging as a major driver of the Indian home healthcare market. Large private healthcare providers are increasingly extending hospital-grade services beyond traditional inpatient settings by offering skilled nursing, ICU-level care, post-operative management, rehabilitation, chronic disease management, infusion therapy, palliative care, and remote patient monitoring at patients' homes. This transition is helping hospitals optimize bed capacity, improve patient convenience, and lower treatment costs while expanding access to quality healthcare outside conventional hospital settings.
For instance, MAX@Home, the home healthcare division of Max Healthcare, significantly expanded its advanced ICU-at-home and step-down critical care services during 2024-2025. According to India Today updates published in June 2025, the company installed more than 1,400 step-down ICUs in patients' homes during 2024, enabling patients requiring oxygen therapy, ventilator support, and continuous clinical monitoring to receive hospital-level care at home. The expansion also included home dialysis, post-hospital rehabilitation, and digital patient monitoring, demonstrating the increasing adoption of advanced home-based clinical services in India.
Similarly, Apollo HomeCare expanded its home healthcare operations in August 2025, reinforcing the growing adoption of hospital-at-home services across the country. According to the Apollo Hospitals Annual Report 2025, the company completed over 508,000 patient care episodes, conducted more than 132,000 home visits, served over 20,000 patients, and delivered nearly 600 home care cases every day. Apollo HomeCare also expanded its palliative care at home program and strengthened remote patient monitoring and digitally enabled clinical care services, reflecting the increasing investment by leading hospital networks in comprehensive home-based healthcare.
The continued expansion of hospital-led home healthcare programs is increasing demand for skilled nursing, rehabilitation services, home medical equipment, remote patient monitoring solutions, and long-term chronic disease management. As more healthcare providers integrate home-based care into their service offerings, the adoption of professional home healthcare services is expected to accelerate, supporting the long-term market growth.
The shortage of skilled and verified healthcare professionals continues to restrain the growth of the India home healthcare market, particularly for advanced clinical services such as ICU-at-home, ventilator management, infusion therapy, post-operative nursing, and chronic disease management. While demand for hospital-level care at home is increasing, the availability of trained nurses, critical care specialists, physiotherapists, and certified caregivers has not kept pace. The home healthcare workforce remains highly fragmented, with many providers relying on outsourced staffing agencies that often differ in clinical training, credential verification, and quality standards. This limits providers' ability to expand services, affects patient confidence, and slows the adoption of high-acuity home healthcare programs across the country.
The challenge is further compounded by intense competition between hospitals and home healthcare providers for skilled healthcare professionals. As hospitals continue expanding hospital-at-home and specialized home care programs, they compete for the same limited pool of experienced nurses and allied healthcare workers. The issue was underscored in August 2025, when Mumbai's VN Desai Hospital uncovered that a contract staffing agency had deployed an individual using forged medical credentials in its ICU, exposing gaps in workforce verification and quality oversight within outsourced healthcare staffing. Such incidents reinforce concerns about the availability of qualified, verified professionals, posing a significant challenge to the safe expansion of advanced home healthcare services across India.
Case Study by India's Ministry of Health and Family Welfare Published in April 2026: Healthcare Workforce Availability and Distribution in India
Background
India has significantly expanded its healthcare workforce over the past decade, with the Ministry of Health and Family Welfare (MoHFW) reporting approximately 5.7 million registered healthcare professionals, including doctors, nurses, midwives, and AYUSH practitioners. While the country has nearly reached the World Health Organization (WHO) benchmark for healthcare workforce density, substantial regional and rural-urban disparities continue to challenge equitable healthcare access and service delivery.
Challenge
Although India has 41 registered healthcare professionals per 10,000 people, close to the WHO-recommended threshold of 44.5 per 10,000 people, the distribution of healthcare workers remains highly uneven. States such as Bihar, Uttar Pradesh, and Jharkhand have fewer than 20 healthcare professionals per 10,000 population, whereas Kerala, Andhra Pradesh, and Arunachal Pradesh report considerably higher workforce availability. Rural regions face the greatest shortage, with only 10 healthcare professionals per 10,000 people, compared with approximately 30 per 10,000 in urban areas, resulting in reduced access to quality healthcare services.
Key Findings
- India has approximately 5.7 million registered healthcare professionals, including doctors, nurses, midwives, and AYUSH practitioners.
- The country has 41 healthcare professionals per 10,000 population, approaching the WHO-recommended threshold of 44.5 professionals per 10,000 population needed to achieve universal health coverage goals.
- Healthcare workforce availability has improved significantly over the past decade, driven largely by the rapid growth in the number of registered nurses and midwives.
- India maintains a ratio of approximately 17 nurses and midwives for every 10 doctors, indicating that nurses and midwives account for more than half of the healthcare workforce.
- Significant regional disparities exist, with states such as Kerala, Andhra Pradesh, and Arunachal Pradesh reporting higher healthcare workforce densities, while Bihar, Uttar Pradesh, and Jharkhand have fewer than 20 healthcare professionals per 10,000 population.
- A substantial rural-urban gap persists in healthcare workforce distribution. Rural areas have only about 10 healthcare professionals per 10,000 residents, compared with approximately 30 per 10,000 in urban areas.
- More than half of India's healthcare professionals are concentrated in urban regions, despite nearly two-thirds of the country's population residing in rural areas.
- Only around 13% of registered allopathic doctors are employed in government hospitals, highlighting the dominance of the private healthcare sector.
- According to the World Health Organization's National Health Workforce Accounts (NHWA) estimates, the active healthcare workforce is closer to 37 doctors, nurses, and midwives per 10,000 population, lower than registration-based estimates.
- Analysis of Periodic Labour Force Survey (PLFS) data suggests that only about 1.9 million physicians, nurses, and midwives are actively practicing, indicating that a significant proportion of registered professionals may be retired, inactive, or working outside the healthcare sector.
- The shortage and uneven distribution of healthcare professionals continue to affect healthcare accessibility, particularly in underserved rural regions, increasing reliance on informal healthcare providers and creating challenges for healthcare delivery.
Market Implications
Despite a growing healthcare workforce, India's healthcare delivery system continues to experience significant staffing constraints due to the uneven distribution of professionals and low active workforce participation. More than half of healthcare professionals are concentrated in Maharashtra, Kerala, Tamil Nadu, Andhra Pradesh, and Karnataka, while many northern and eastern states remain underserved. Additionally, the majority of healthcare professionals are employed in the private sector, leaving public healthcare facilities with persistent staffing shortages. These workforce imbalances increase patient-to-provider ratios, delay access to care, and place considerable pressure on hospitals and primary healthcare centers, particularly in rural regions.
Industry Impact
The shortage and unequal distribution of healthcare professionals are accelerating investments in workforce development, digital health platforms, telemedicine, nurse training programs, and public-sector recruitment initiatives. Healthcare providers are increasingly adopting technology-enabled care models to extend specialist services to underserved populations, while government initiatives continue to focus on strengthening rural healthcare infrastructure and expanding the active healthcare workforce. Addressing these workforce gaps will remain essential for improving healthcare accessibility, achieving universal health coverage, and supporting the long-term growth of India's healthcare sector.
Typical Monthly Service Charges in India's Home Healthcare Market
Service Category
Typical Price Range
General Caregiver Services
USD 156-312 per month
Home Nursing (Basic)
USD 208-468 per month
ICU-at-Home Services
USD 1,560-4,160 per month
Ventilator Support at Home
USD 2,080-5,200 per month
Home Physiotherapy
USD 5-16 per session
Remote Patient Monitoring Packages
USD 21-104 per month
Source: At Home Care, Maa Sewa Healthcare, Healkin, and Wishwaa HomeCare
These workforce shortages increase recruitment costs, delay service deployment, and limit organized providers' ability to expand into Tier II and Tier III cities, ultimately restraining the overall growth potential of India's home healthcare market.
The rapid expansion of at-home diagnostics and preventive healthcare services presents a significant growth opportunity for India's home healthcare market. Rising awareness of preventive health, increasing demand for convenience, and the growing prevalence of chronic diseases are encouraging elderly patients to opt for home-based sample collection, diagnostic testing, ECG monitoring, health screening, and follow-up care. Home healthcare providers are increasingly partnering with diagnostic laboratories, digital health platforms, and hospitals to offer integrated services that combine home nursing, diagnostics, teleconsultation, and chronic disease management. This integrated care model improves patient convenience, reduces the need for hospital visits, and enables disease detection earlier.
The opportunity is to attract significant investments from healthcare and technology companies. In June 2025, Amazon India entered India's at-home diagnostics market through Amazon Diagnostics, enabling customers to book more than 800 laboratory tests with home sample collection across six major cities. The service integrates at-home testing with digital reports and telehealth services, reflecting growing demand for home-based healthcare delivery.
Another major industry development occurred in February 2024, when Thyrocare Technologies acquired Think Health Diagnostics to expand into at-home ECG services. The acquisition strengthened Thyrocare's home diagnostics network across multiple Indian cities and enabled the company to offer comprehensive home-based health check-ups and insurance medical examinations. The company also announced plans to scale these services nationwide, highlighting the increasing commercial potential of home healthcare services beyond traditional nursing care.
As consumers increasingly seek convenient, technology-enabled healthcare services and healthcare providers continue expanding home-based diagnostic capabilities, at-home diagnostics are expected to become one of the fastest-growing segments of India's home healthcare market, creating substantial opportunities for service providers, diagnostic companies, and digital health platforms.
The market continues to face a major structural challenge due to its fragmented provider landscape and the absence of a dedicated national regulatory framework governing home-based healthcare services. While organized companies are expanding hospital-at-home, nursing, rehabilitation, and chronic disease management services, a significant share of the market is still served by small local agencies and informal caregivers with varying levels of training, clinical supervision, and quality assurance. This lack of uniform standards creates inconsistencies in service delivery, makes it difficult for patients to assess provider quality, and limits trust in home-based medical care. It also poses challenges for hospitals, insurers, and investors seeking reliable partners capable of delivering standardized services across multiple states.
Recent developments have highlighted this issue. In January 2025, India Today Insight reported that leading hospital networks are rapidly expanding hospital-at-home services to reduce pressure on hospital beds and emphasized that the broader home healthcare ecosystem remains fragmented, with quality and service standards varying significantly among providers.
Similarly, the Healthcare Services Transformation Platform (HSTP), in its September 2023 report, The Home Healthcare Boom: Opportunities and Obstacles in India’s Changing Healthcare Landscape, identified fragmented service delivery, inconsistent caregiver training, and the lack of a comprehensive regulatory framework as key barriers to the sector’s long-term growth. The report also noted that organized providers are investing in internal training programs, digital monitoring systems, and standardized clinical protocols to overcome these gaps, highlighting the industry’s need for nationally accepted accreditation and quality standards. Until India establishes a uniform regulatory framework for home healthcare providers, fragmentation is expected to remain a significant challenge, constraining patient confidence, payer participation, and the scalable expansion of home-based healthcare services.
Market Concentration & Characteristics
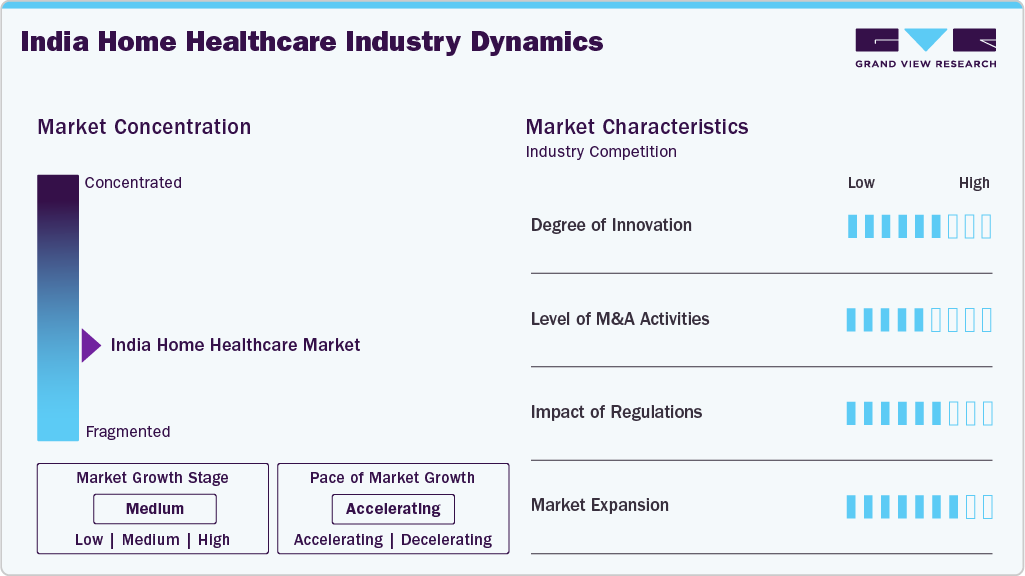
The chart below represents the relationship between industry concentration, industry characteristics, and industry participants. The industry is fragmented, with many products/services in the market. There is a moderate degree of innovation, a moderate level of merger & acquisition activity, a high impact of regulations, and a moderate expansion of the industry.
The India home healthcare market is witnessing a medium-to-high degree of innovation as providers increasingly integrate digital technologies to improve the quality and accessibility of home-based care. Companies are expanding services through remote patient monitoring, teleconsultations, AI-enabled care coordination, digital health records, and hospital-at-home programs to manage chronic diseases and post-acute care more efficiently. For instance, Apollo Home Healthcare has strengthened its hospital-at-home and home ICU services by integrating virtual physician consultations, remote monitoring, and specialized nursing care, enabling patients to receive hospital-grade treatment at home. These innovations are improving patient outcomes while reducing hospital admissions and healthcare costs.
 To learn more about this report, Download Free Sample Report
Mergers and acquisitions in the India home healthcare industry are moderate, reflecting a gradual shift toward industry consolidation. Leading providers are acquiring established regional companies to expand their geographic footprint and broaden their service portfolios. For instance, Healthcare at Home (HCAH) acquired Nightingales Home Health Services in November 2024, strengthening its presence across major Indian cities and expanding its capabilities in home nursing, rehabilitation, elder care, and chronic disease management.
The regulatory environment plays an increasingly important role in influencing the market. Government initiatives such as the Ayushman Bharat Digital Mission (ABDM) are accelerating the adoption of digital health records and improving interoperability across healthcare providers. In addition, the Telemedicine Practice Guidelines issued by the National Medical Commission and the expansion of NABH Accreditation Standards for home healthcare providers are promoting standardized clinical protocols, patient safety, and quality of care. Although India does not yet have a dedicated national regulatory framework for home healthcare, these initiatives are strengthening industry standards and supporting organized Market growth.
Market expansion remains strong as home healthcare providers extend their services beyond metropolitan areas into Tier II and Tier III cities. Growing demand for elderly care, chronic disease management, post-operative rehabilitation, home diagnostics, physiotherapy, and ICU-at-home services is encouraging providers to increase their geographic presence through hospital partnerships and technology-enabled care models. Companies such as Apollo Home Healthcare, Portea Medical, HCAH, India Home Health Care (IHHC), and Suburban Diagnostics continue to expand their service networks to meet the rising demand for affordable, accessible home-based healthcare. This ongoing expansion is expected to support sustained Market growth over the forecast period.
Analyst Perspective
The market is transitioning from fragmented, informal caregiving models to organized, technology-enabled, and clinically integrated home-based care services. Rising healthcare costs, an aging population, increasing prevalence of chronic diseases, growing post-operative care needs, and the expansion of hospital-at-home programs are driving market growth. Patients and families are increasingly seeking convenient, cost-effective, and personalized care outside traditional hospital settings, supporting demand for skilled nursing, elderly care, rehabilitation, palliative care, physiotherapy, remote patient monitoring, and critical care services delivered at home. The competitive landscape is increasingly focused on providers offering integrated care models that combine clinical expertise, trained healthcare professionals, digital health platforms, remote monitoring, and hospital partnerships. Technology-enabled care coordination, AI-supported monitoring, telehealth, and data-driven patient management are emerging as key competitive differentiators. Providers capable of ensuring consistent service quality, expanding into Tier 2 and Tier 3 cities, addressing workforce shortages, and integrating home-based care with hospitals and insurance ecosystems are expected to strengthen their market position as India continues to shift toward more accessible, decentralized, and patient-centric healthcare delivery.
Component Insights
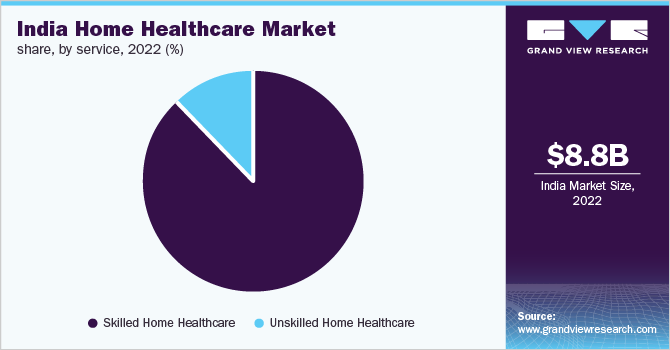
The service segment dominated the India home healthcare market with the largest revenue share of 84.0% in 2025. This segment encompasses a wide range of healthcare services delivered to a patient’s home. This growth is driven by an aging population, as they often require more medical care and assistance with daily activities. Moreover, increased investment in training and certification programs for home health aides ensures a higher standard of care, which enhances patient satisfaction and trust in these services. For instance, the Care Academy provides training for Home Health Aides (HHAs), which is a crucial profession in the healthcare industry. Home Health Aides play a vital role in supporting patients with various medical conditions and disabilities, as well as elderly individuals who require assistance with activities of daily living.
The equipment segment is anticipated to grow at the fastest CAGR over the forecast period. The growing advancements in technology have facilitated the development of portable diagnostic tools and equipment that enable healthcare professionals to conduct tests remotely. This shift enhances patient convenience and reduces the burden on healthcare facilities. For instance, in March 2025, Amazon India launched an at-home diagnostics service under Amazon Medical, offering home sample collection within 60 minutes and lab results in under six hours across six cities. Developed in collaboration with Orange Health Labs, the service is available in Bengaluru, Delhi, Gurgaon, Noida, Mumbai, and Hyderabad. These advancements improve accessibility, promote decentralized healthcare delivery, and position the segment for sustained growth over the forecast period.
Indication Insights
The respiratory disease & COPD segment dominated the India home healthcare industry with the largest revenue share of 16.6% in 2025. India has one of the world's highest COPD burdens due to factors such as tobacco smoking, exposure to household biomass fuel, industrial pollution, poor air quality, and rapid urbanization. In addition, the country's growing elderly population is more susceptible to chronic respiratory conditions that require continuous care rather than repeated hospital admissions. Home healthcare enables COPD patients to receive oxygen therapy, nebulization, pulmonary rehabilitation, sleep apnea management, respiratory physiotherapy, and remote patient monitoring in a familiar environment, improving treatment adherence and quality of life while reducing healthcare costs.
 To learn more about this report, Download Free Sample Report
The cancer segment is expected to grow at the fastest CAGR during the forecast period as more patients require long-term, continuous care beyond hospital settings. Many cancer patients require prolonged chemotherapy, palliative care, pain management, nutritional support, wound care, and post-surgical rehabilitation, making home healthcare a preferred option for ongoing treatment. Home-based oncology services enable patients to receive skilled nursing care, medication administration, infusion therapy, symptom management, physiotherapy, and psychological support in a familiar environment, improving comfort and quality of life while reducing the frequency of hospital visits.
Region Insights
The urban region dominated the India home healthcare market with the largest revenue share in 2025 and is expected to grow at the fastest CAGR during the forecast period. This is due to their higher concentration of healthcare professionals, advanced medical infrastructure, and greater adoption of home-based care services. According to India's Periodic Labour Force Survey (PLFS) updates published in April 2026, urban areas have approximately 30 healthcare professionals per 10,000 population, compared with only 10 professionals per 10,000 in rural areas, providing patients with better access to physicians, nurses, physiotherapists, and allied healthcare professionals who can deliver care at home.
The rural region of the India home healthcare industry is expected to grow at a significant CAGR during the forecast period due to the growing need to improve healthcare access in underserved regions where shortages of healthcare professionals and limited healthcare infrastructure remain significant challenges. As per a PubMed report of April 2026, India has approximately 41 registered healthcare professionals per 10,000 population, close to the WHO-recommended threshold of 44.5 per 10,000, the distribution is highly uneven. Rural areas have only about 10 healthcare professionals per 10,000 residents, compared with about 30 per 10,000 in urban areas, resulting in limited access to physicians, nurses, and specialized care. In addition, only 13% of registered allopathic doctors are employed in government hospitals, further constraining healthcare availability in rural communities.
Key India Home Healthcare Company Insights
The India home healthcare market is highly fragmented, with the presence of both domestic and global players across diagnostic, monitoring, and therapeutic devices. Companies such as Omron Healthcare India, Dr. Morepen, Nureca (Dr Trust), Philips India, Abbott, and Roche Diabetes Care India are among the key market participants, driven by their strong product portfolios and extensive distribution networks. The market is increasingly competitive, with growth supported by rising D2C sales, digital health adoption, and expanding demand for home-based chronic disease management solutions. Market shares are expected to evolve with new product launches, strategic partnerships, and expansion across online and offline channels.
Key India Home Healthcare Companies
The following key companies have been profiled for this study of the India home healthcare market.
-
Apollo Homecare
-
Portea Medical
-
Healthcare atHome (HCAH)
-
HCAH Nightingales Home Health Services (Nightingales acquired by HCAH)
-
Care24 (Acquired by Human Life Management)
-
India Home Health Care (IHHC)
-
Bharat Home Medicare
-
Grand World Elder Care
-
Ezee Medfind LLP
-
Swarg Community Care
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Apollo Homecare; Portea Medical; Healthcare atHome; HCAH Nightingale’s Home Health Services; Care24
- Expand service networks across Tier I & Tier II cities.
- Strengthen telehealth, remote patient monitoring, and home diagnostics.
- Partner with hospitals, insurers, and corporate employers.
- Broaden chronic disease, elderly care, rehabilitation, and post-operative care services.
- Strong brand recognition and clinical credibility.
- Comprehensive service portfolio with trained healthcare professionals.
- Technology-enabled scheduling, digital records, and remote monitoring.
- Established referral network with hospitals and physicians.
- High operating and workforce management costs.
- Limited penetration in rural and semi-urban markets.
- Profitability affected by dependence on skilled healthcare professionals.
- Scaling quality consistently across multiple cities remains challenging.
Emerging Players: India Home Health Care (IHHC); Bharat Home Medicare; Grand World Elder Care; Ezee Medfind LLP; Swarg Community Care
- Focus on regional expansion and personalized home-based care.
- Specialize in elder care, palliative care, physiotherapy, and nursing services.
- Collaborate with local hospitals and healthcare providers.
- Adopt asset-light operational models to reduce costs.
- Strong regional presence and personalized patient engagement.
- Flexible and customized care packages.
- Lower operational costs enable competitive pricing.
- Faster service customization for local healthcare needs.
- Lower brand visibility compared to national players.
- Limited investment in digital health platforms and advanced monitoring technologies.
- Smaller geographic footprint restricts scalability.
- Resource constraints limit expansion and technology adoption.
Recent Developments
-
In May 2026, Apollo HomeCare partnered with Apollo AyurVAID to launch an integrated Transition Care Service aimed at improving post-discharge recovery through clinically supervised step-down care. The service combines physician oversight, skilled nursing, physiotherapy, rehabilitation, nutrition counseling, and Ayurvedic therapies to support patients recovering from surgery, chronic illnesses, and complex medical conditions at home.
"This collaboration bridges the gap between hospital discharge and complete recovery by providing an integrated transition care model that combines modern medicine with evidence-based Ayurveda to improve patient outcomes and continuity of care." - Apollo HomeCare Management
-
In June 2025, Apollo HomeCare launched a 90-minute Doctor-at-Home service in Bengaluru, enabling patients to receive physician consultations, diagnostic assessments, and treatment at home within 90 minutes of booking. The initiative strengthens the company's hospital-at-home model by expanding access to timely medical care for acute and chronic conditions while reducing unnecessary hospital visits.
"The future of healthcare is moving beyond hospitals, with advanced medical services increasingly being delivered in patients' homes through technology-enabled care models." - Apollo HomeCare leadership
-
In June 2025, Amazon India entered the at-home diagnostics Market, expanding its healthcare vertical beyond online pharmacy and teleconsultation. The company introduced home sample collection services through Amazon Medical, strengthening access to home-based diagnostic testing and supporting the growing adoption of digitally enabled healthcare services across India .
India Home Healthcare Market Report Scope
Report Attribute
Details
Market size in 2025
USD 6.4 billion
Estimated market size in 2026
USD 7.2 billion
Projected market size by 2033
USD 16.8 billion
Growth rate
CAGR of 12.9% from 2026 to 2033
Actual data
2021 - 2025
Forecast data
2026 - 2033
Quantitative units
Revenue in USD Million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Country scope
India
Segments covered
Component, indication, region
Key companies profiled
Apollo Homecare; Portea Medical; India Home Health Care (IHHC); Healthcare atHome (HCAH); HCAH Nightingales Home Health Services (Nightingales acquired by HCAH); Care24 (Acquired by Human Life Management); Bharat Home Medicare; Grand World Elder Care; Ezee Medfind LLP (Medfind); Swarg Community Care
Customization scope
Free report customization (equivalent to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
India Home Healthcare Market Report Segmentation
This report forecasts country-level revenue growth and provides an analysis of the latest industry trends across sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the India home healthcare market report based on component, indication, and region:
-
Component Outlook (Revenue, USD Million, 2021 - 2033)
-
Equipment
-
Therapeutic
-
Home respiratory equipment
-
Insulin delivery market
-
Home IV pumps
-
Home dialysis equipment
-
Other therapeutic equipment
-
-
Diagnostic
-
Diabetic care unit
-
BP monitors
-
Multi para diagnostic monitors
-
Home pregnancy and fertility kits
-
Apnea and sleep monitors
-
Holter monitors
-
Heart rate meters
-
Other
-
-
Mobility Assist Equipment
-
Wheelchair
-
Home medical furniture
-
Walking assist devices
-
-
-
Services
-
Skilled Home Care
-
Physician primary care
-
Nursing care
-
Physical/occupational/speech therapy
-
Nutritional support
-
Hospice & palliative
-
Other skilled nursing services
-
-
Unskilled Home Care
-
-
-
Indication Outlook (Revenue, USD Million, 2021 - 2033)
-
Cardiovascular Disorder & Hypertension
-
Diabetes & Kidney Disorders
-
Neurological & Mental Disorders
-
Respiratory Disease & COPD
-
Maternal Disorders
-
Mobility Disorders
-
Cancer
-
Wound Care
-
Others
-
-
Region Outlook (Revenue, USD Million, 2021 - 2033)
-
Urban
-
Rural
-
Research Methodology
The India home healthcare market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing—reconciling supply-side and demand-side estimates—and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each India home healthcare segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment
Definition
By component
Equipment:
Therapeutic Equipment
These are used to deliver therapies or support the management of chronic and acute medical conditions outside hospitals.
Home Respiratory Equipment
Includes oxygen concentrators, ventilators, CPAP, BiPAP, and other devices used to provide respiratory support in residential settings.
Insulin Delivery Equipment
Includes insulin pumps and other devices used for the administration and management of insulin therapy at home.
Home IV Pumps
Includes infusion pumps used for the controlled administration of medications, fluids, nutrients, and other intravenous therapies at home.
Home Dialysis Equipment
Includes dialysis machines and related systems designed to support renal replacement therapy in residential settings.
Other Therapeutic Equipment
Includes therapeutic devices used in home healthcare that are not classified under respiratory, insulin delivery, IV infusion, or dialysis equipment.
Diagnostic Equipment
Covers devices used for screening, testing, measurement, and continuous monitoring of patient health conditions at home.
Diabetic Care Units
Includes blood glucose meters, continuous glucose monitoring devices, and other home-use equipment for diabetes management.
BP Monitors
Includes digital and other blood pressure monitoring devices used for routine home-based cardiovascular monitoring.
Multiparameter Diagnostic Monitors
Includes devices capable of simultaneously tracking multiple physiological parameters, such as blood pressure, pulse, oxygen saturation, and temperature.
Home Pregnancy & Fertility Kits
Includes consumer diagnostic kits used for pregnancy detection, ovulation tracking, and fertility monitoring at home.
Apnea & Sleep Monitors
Includes devices used to assess sleep patterns, breathing interruptions, oxygen levels, and other sleep-related parameters.
Holter Monitors
Includes portable devices used for continuous ambulatory monitoring of cardiac electrical activity over extended periods.
Heart Rate Meters
Includes devices used to measure and track heart rate for routine monitoring, disease management, and physical activity.
Other Diagnostic Equipment
Includes other home-use diagnostic and monitoring devices not covered under the specified categories.
Mobility Assist Equipment
Covers equipment is designed to improve movement, mobility, positioning, and independence among individuals receiving care at home.
Wheelchairs
Includes manual and powered wheelchairs used by individuals with temporary or permanent mobility limitations.
Home Medical Furniture
Includes hospital beds, patient lifts, bedside equipment, and other specialized furniture used to support patient care in residential settings.
Walking Assist Devices
Includes canes, walkers, crutches, and similar devices used to support walking and balance.
Services:
Skilled Home Care
Includes services requiring professional clinical expertise and delivered by physicians, nurses, therapists, dietitians, and other qualified healthcare professionals.
Physician Primary Care
Includes physician consultations, medical assessments, diagnosis, treatment planning, and routine primary care provided at home.
Nursing Care
Includes professional nursing activities such as medication administration, injections, wound management, monitoring, and clinical support.
Physical/Occupational/Speech Therapy
Includes rehabilitation and therapy services focused on mobility, physical function, communication, swallowing, and activities of daily living.
Nutritional Support
Includes diet planning, nutritional assessment, dietary counseling, and nutrition management for home healthcare patients.
Hospice & Palliative Care
Includes home-based services focused on symptom control, pain management, comfort, end-of-life care, and quality-of-life support.
Other Skilled Nursing Services
Includes other professionally delivered clinical care services not included in the specified skilled care categories.
Unskilled Home Care
Includes non-medical assistance with personal hygiene, daily activities, companionship, household support, and routine caregiving.
By Indication
Cardiovascular Disorders & Hypertension
Covers home healthcare services and equipment used for the monitoring and management of cardiovascular diseases and high blood pressure.
Diabetes & Kidney Disorders
Covers home-based care associated with diabetes, chronic kidney disease, dialysis, and related metabolic and renal conditions.
Neurological & Mental Disorders
Covers home healthcare for neurological, cognitive, behavioral, and mental health conditions requiring ongoing care or supervision.
Respiratory Disease & COPD
Covers home-based respiratory treatment, monitoring, oxygen therapy, and related care for chronic and acute respiratory conditions.
Maternal Disorders
Covers home healthcare associated with pregnancy, postpartum care, and pregnancy-related maternal health conditions.
Mobility Disorders
Covers home-based rehabilitation, therapy, nursing care, and mobility support for conditions that impair movement and physical independence.
Cancer
Covers home-based oncology support, nursing, palliative care, symptom management, and other supportive services for cancer patients.
Wound Care
Covers assessment, dressing, treatment, monitoring, and management of chronic, surgical, diabetic, and other wounds in home settings.
Others
Covers home healthcare applications associated with conditions not included in the specified indication categories.
By region
Urban
Covers home healthcare demand in metropolitan cities, urban centers, and other densely populated areas with relatively greater access to organized healthcare providers and medical infrastructure.
Rural
Covers home healthcare demand in villages and rural locations where patients may rely on home-based services because of limited access to hospitals, specialists, and formal healthcare facilities.
Model Details
This research methodology outlines the process for estimating the size of the India home healthcare market from 2021 to 2033. The study covers key service segments, including skilled nursing care, personal care and support services, rehabilitation and therapy, home-based medical services, and other specialized home healthcare services across major Indian regions and urban markets.
The objective is to develop a robust and defensible market estimate through a combination of bottom-up and top-down approaches, supported by primary industry validation.
A triangulated market sizing approach was used, combining:
-
Bottom-Up Analysis from patient volumes, home healthcare visits, number of active providers, service revenues, average service costs, caregiver utilization, and hospital-at-home activity.
-
Top-Down Checks using healthcare expenditure, population aging, chronic disease prevalence, post-operative care demand, hospital admissions, healthcare infrastructure, insurance coverage, and urbanization trends.
- Primary Research with home healthcare providers, hospitals, nursing agencies, doctors, nurses, physiotherapists, caregivers, patients, insurance companies, healthcare administrators, and industry experts.
Step-By-Step Market Estimation Process
Home Healthcare Service Utilization Model
This model estimates the number of patients receiving home healthcare services and the associated annual spending.
Step 1: Country-level data on the elderly population, chronic disease prevalence, hospital admissions, post-operative patients, disability prevalence, home healthcare utilization, and healthcare expenditure for 2021-2025 were collected from government agencies, healthcare organizations, industry associations, hospital reports, and public health sources.
Step 2: Home healthcare utilization rates were applied to estimate the percentage of eligible patients receiving home healthcare services. Utilization rates were derived from healthcare surveys, provider data, hospital records, insurance claims, patient studies, and primary interviews.
tep 3: Average annual spending per home healthcare patient was estimated using consultation charges, nursing fees, caregiver costs, physiotherapy charges, medical equipment rentals, home diagnostics, hospitalization-at-home costs, and provider billing data.
Step 4: Market size was calculated by multiplying:
Number of Home Healthcare Patients × Average Annual Spending per Patient
Step 5: Calculations were performed at the city and state levels, where data were available, and subsequently aggregated to regional and national levels.
Step 6: Historical and forecast growth rates were incorporated based on population aging, increasing chronic disease burden, rising hospital costs, post-operative care requirements, growing demand for elderly care, expansion of hospital-at-home programs, and increasing consumer acceptance of home-based care.
Home Healthcare Provider Revenue Extrapolation Model
This model estimates market size based on revenues generated by organized home healthcare providers and service delivery organizations.
Step 1: The number of active home healthcare providers, hospital-affiliated home care programs, home nursing agencies, rehabilitation providers, elderly care companies, and specialized home healthcare organizations across India was identified through company disclosures, healthcare registries, industry databases, and market intelligence sources.
Step 2: Average annual revenue per home healthcare provider was estimated using company financial disclosures, service volumes, industry benchmarks, provider interviews, pricing data, and proprietary databases.
Step 3: Provider revenues were adjusted for regional differences in service mix, patient volumes, service duration, pricing structures, workforce availability, urbanization, and healthcare spending.
Step 4: Market size was calculated by multiplying:
Number of Active Home Healthcare Providers × Adjusted Average Annual Revenue per Provider
Step 5: Regional and national market values were generated through the aggregation of provider-level and regional estimates.
Step 6: Annual adjustments were applied to account for the expansion of organized home healthcare chains, hospital partnerships, new service launches, technology adoption, remote patient monitoring, expansion into Tier 2 and Tier 3 cities, and investments in home-based care infrastructure.
Patient Volume and Service Cost Model
This model estimates market size based on the volume of home healthcare services delivered and average service costs across major service categories.
Step 1: Service volume data was collected from home healthcare providers, hospitals, nursing agencies, rehabilitation centers, healthcare databases, industry publications, company reports, and primary interviews.
Step 2: Services were categorized into:
- Skilled Nursing Care
- Personal Care and Support Services
- Rehabilitation and Therapy
- Home-Based Medical Services
- Other Home Healthcare Services
Step 3: Average service costs were established using provider pricing data, patient packages, consultation fees, nursing charges, therapy costs, medical equipment rentals, hospitalization-at-home charges, and expert interviews.
Step 4: Revenue generated by each service category was calculated by multiplying:
Number of Home Healthcare Visits / Service Episodes × Average Cost per Visit / Service Episode
Step 5: Category-level revenues were aggregated to determine regional and national market sizes.
Step 6: Forecast assumptions incorporated increasing demand for elderly care, rising chronic disease prevalence, higher post-operative care requirements, growing hospital-at-home adoption, expansion of home-based critical care, increasing demand for rehabilitation, digital health adoption, and the expansion of organized healthcare providers.
Hospital-at-Home and Institutional Partnership Model
This model estimates the contribution of hospital-affiliated home healthcare programs and institutional partnerships to the overall market.
Step 1: Hospital-at-home programs, home ICU services, step-down care programs, post-discharge care initiatives, and hospital-linked home healthcare services were identified across major Indian healthcare networks.
Step 2: Patient capacity, number of home-based beds, service episodes, average length of care, and annual patient volumes were estimated using hospital disclosures, provider information, industry reports, and primary interviews.
Step 3: Average revenue per patient was estimated using service package pricing, nursing requirements, physician visits, medical equipment, diagnostics, medicines, and care duration.
Step 4: Market value was calculated by multiplying:
Number of Hospital-at-Home Patients × Average Revenue per Patient
Step 5: Forecast estimates incorporated the expansion of hospital-at-home programs, hospital capacity constraints, demand for lower-cost care settings, increasing healthcare digitization, remote monitoring adoption, and strategic partnerships between hospitals and home healthcare providers.
Market Validation and Forecasting
The estimates derived from the home healthcare service utilization model, provider revenue extrapolation model, patient volume and service cost model, and hospital-at-home model were cross-validated through data triangulation. Findings were further verified through primary interviews with home healthcare providers, hospitals, physicians, nurses, physiotherapists, caregivers, healthcare administrators, insurers, healthcare consultants, and industry experts.
Final market forecasts were developed by evaluating demographic trends, population aging, chronic disease prevalence, hospital admission patterns, healthcare expenditure, post-operative care demand, healthcare workforce availability, hospital-at-home adoption, insurance coverage, consumer awareness, digital health adoption, and the expansion of organized home healthcare infrastructure, shaping the India home healthcare market.
Customization Table
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Hospital-at-Home & Post-Acute Care Demand Analysis
Delivered a customized evaluation of hospital-at-home adoption across India, assessing demand for post-operative care, skilled nursing, ICU-at-home, physiotherapy, chronic disease management, rehabilitation, and palliative care services. The study also analyzed disease burden, aging population, hospital discharge trends, and patient preference for home-based treatment.
Provides actionable insights into evolving home healthcare demand, enabling service providers to optimize service portfolios, strengthen hospital partnerships, identify high-growth care segments, and develop regional expansion strategies aligned with patient needs.
AI-Based Home Healthcare Demand Mapping & Forecasting
Developed an AI-driven market assessment model analyzing demographic trends, elderly population growth, chronic disease prevalence, healthcare accessibility, digital health adoption, and state-wise home healthcare utilization to forecast future demand across India's major metropolitan and emerging cities.
Enables healthcare providers and investors to identify high-growth markets, prioritize expansion locations, optimize workforce deployment, improve capacity planning, and increase forecasting accuracy for long-term business growth.
Home Healthcare Accessibility & Workforce Assessment
Delivered a customized study evaluating access to skilled nursing, caregiver availability, physiotherapy, diagnostic services, remote patient monitoring, and elderly care across urban and semi-urban regions. The analysis identified service gaps, workforce shortages, affordability challenges, and opportunities for technology-enabled home healthcare delivery.
Supports clients in designing targeted market entry strategies, improving service accessibility, optimizing staffing models, identifying underserved regions, and developing scalable home healthcare solutions through digital health integration and strategic partnerships.
Frequently Asked Questions About This Report
The India home healthcare market size was established at USD 6.4 billion in 2025 and is expected to reach USD 7.2 billion in 2026.
Service segment held the largest revenue share of 84.0% in 2025, while equipment segment is fastest growing component.
Some key players operating in the India home healthcare market include Portea Medical, Apollo Homecare, Nightingales Home Health Services, and India Home Health Care (IHHC), Grand World Elder Care, Healthcare atHOME, Medical, Bharath Home Medicare, Care24, MedFind, Swarg Community Care, and Suburban Diagnostics.
Key factors that are driving the India home healthcare market growth include increasing prevalence of lifestyle diseases, growing disposable income, advancement in technology to offer home care services, and cost-effective alternative to hospital stays.
The respiratory disease & COPD segment dominated with revenue share of 16.6% in 2025, while cancer segment is fastest growing indication.
The India home healthcare market is expected to grow at a compound annual growth rate of 12.9% from 2026 to 2033 to reach USD 316.8 billion by 2033.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


