
- Home
- »
- Advanced Interior Materials
- »
-
Industrial Dust Collector Market Size And Share Report, 2033GVR Report cover

Industrial Dust Collector Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Baghouse Dust Collector, Cartridge Dust Collector), By Mechanism (Dry, Wet), By End-use (Food & Beverage, Pharmaceutical), By Mobility (Portable, Fixed), By Region, And Segment Forecasts
Market Size, 2025
$10.0BMarket Estimate, 2026
$10.5BMarket Forecast, 2033
$15.0BCAGR, 2026–2033
5.3%Industrial Dust Collector Market Summary
The global industrial dust collector market size was valued at USD 10.0 billion in 2025 and is projected to grow from USD 10.5 billion in 2026 to USD 15.0 billion by 2033, at a CAGR of 5.3% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 37.1% in 2025. Increasing focus on reducing industrial emissions and maintaining permissible particulate matter levels is encouraging manufacturers to install and upgrade dust collection equipment. Expansion of manufacturing, construction, mining, and processing industries is further generating demand for dust control systems across production facilities.
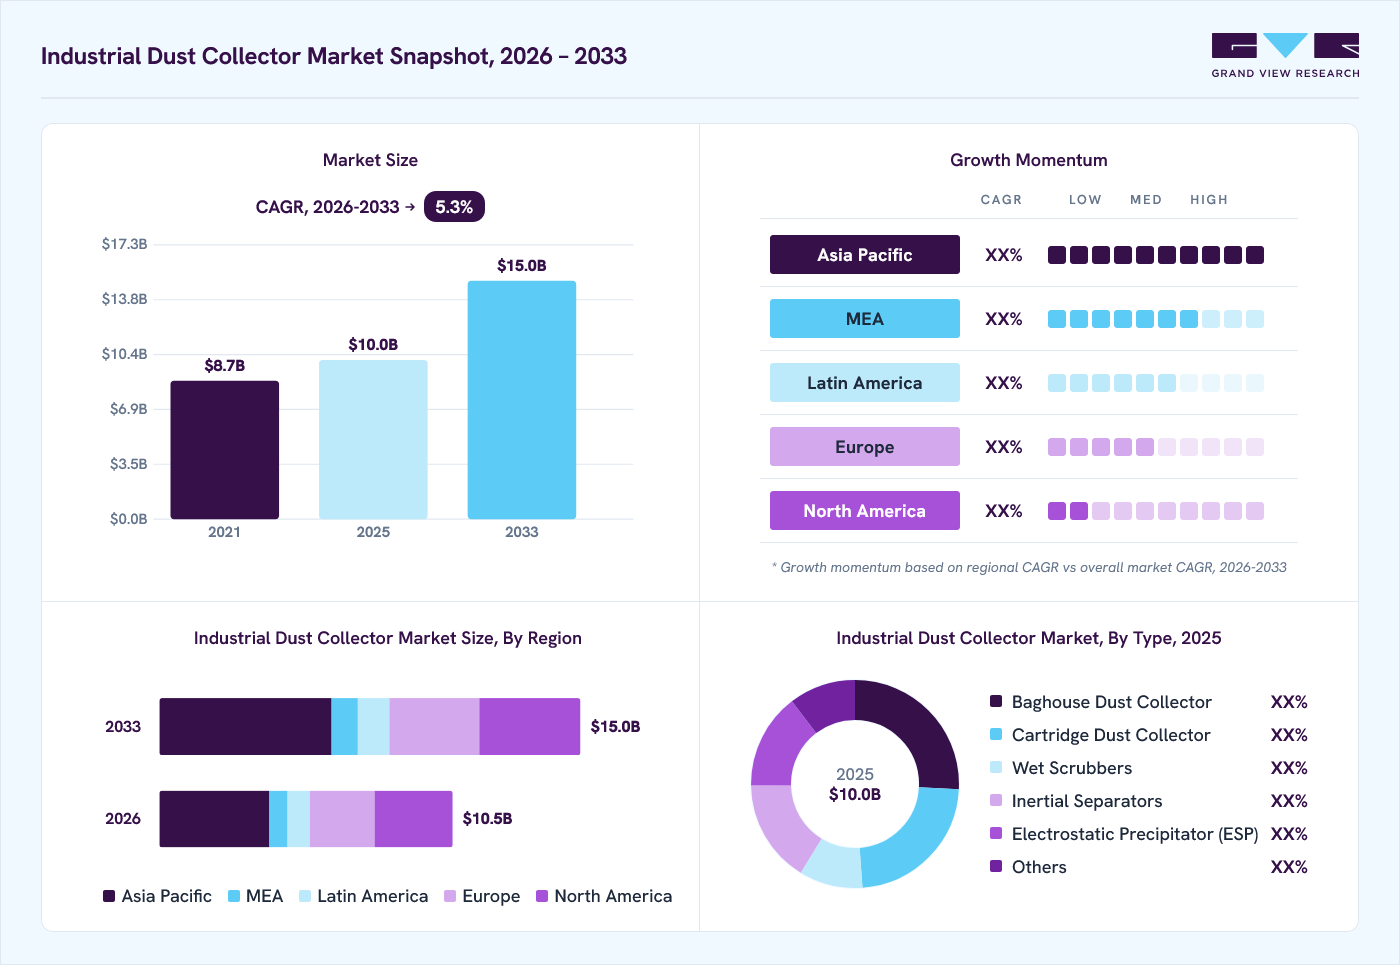 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Cartridge dust collector segment is projected to grow at the fastest CAGR of 7.1% during forecast period.
- Based on mechanism: Wet segment is anticipated to grow at fastest CAGR of 6.1% during forecast period.
- On the basis of mobility: Fixed segment dominated the market in 2025, capturing a 67.1% revenue share.
- By end use: Energy & power segment is expected to grow at the fastest CAGR of 7.1% from 2026 to 2033.
Regional Highlights
- Largest regional market: Asia Pacific (37.1% revenue share, 2025)
- By country: China held the largest share in the Asia Pacific region in 2025.
Market Size & Forecast
- Market Size in 2025: USD 10.0 Billion
- Estimated Market Size in 2026: USD 10.5 Billion
- Projected Market Size by 2033: USD 15.0 Billion
- CAGR (2026-2033): 5.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
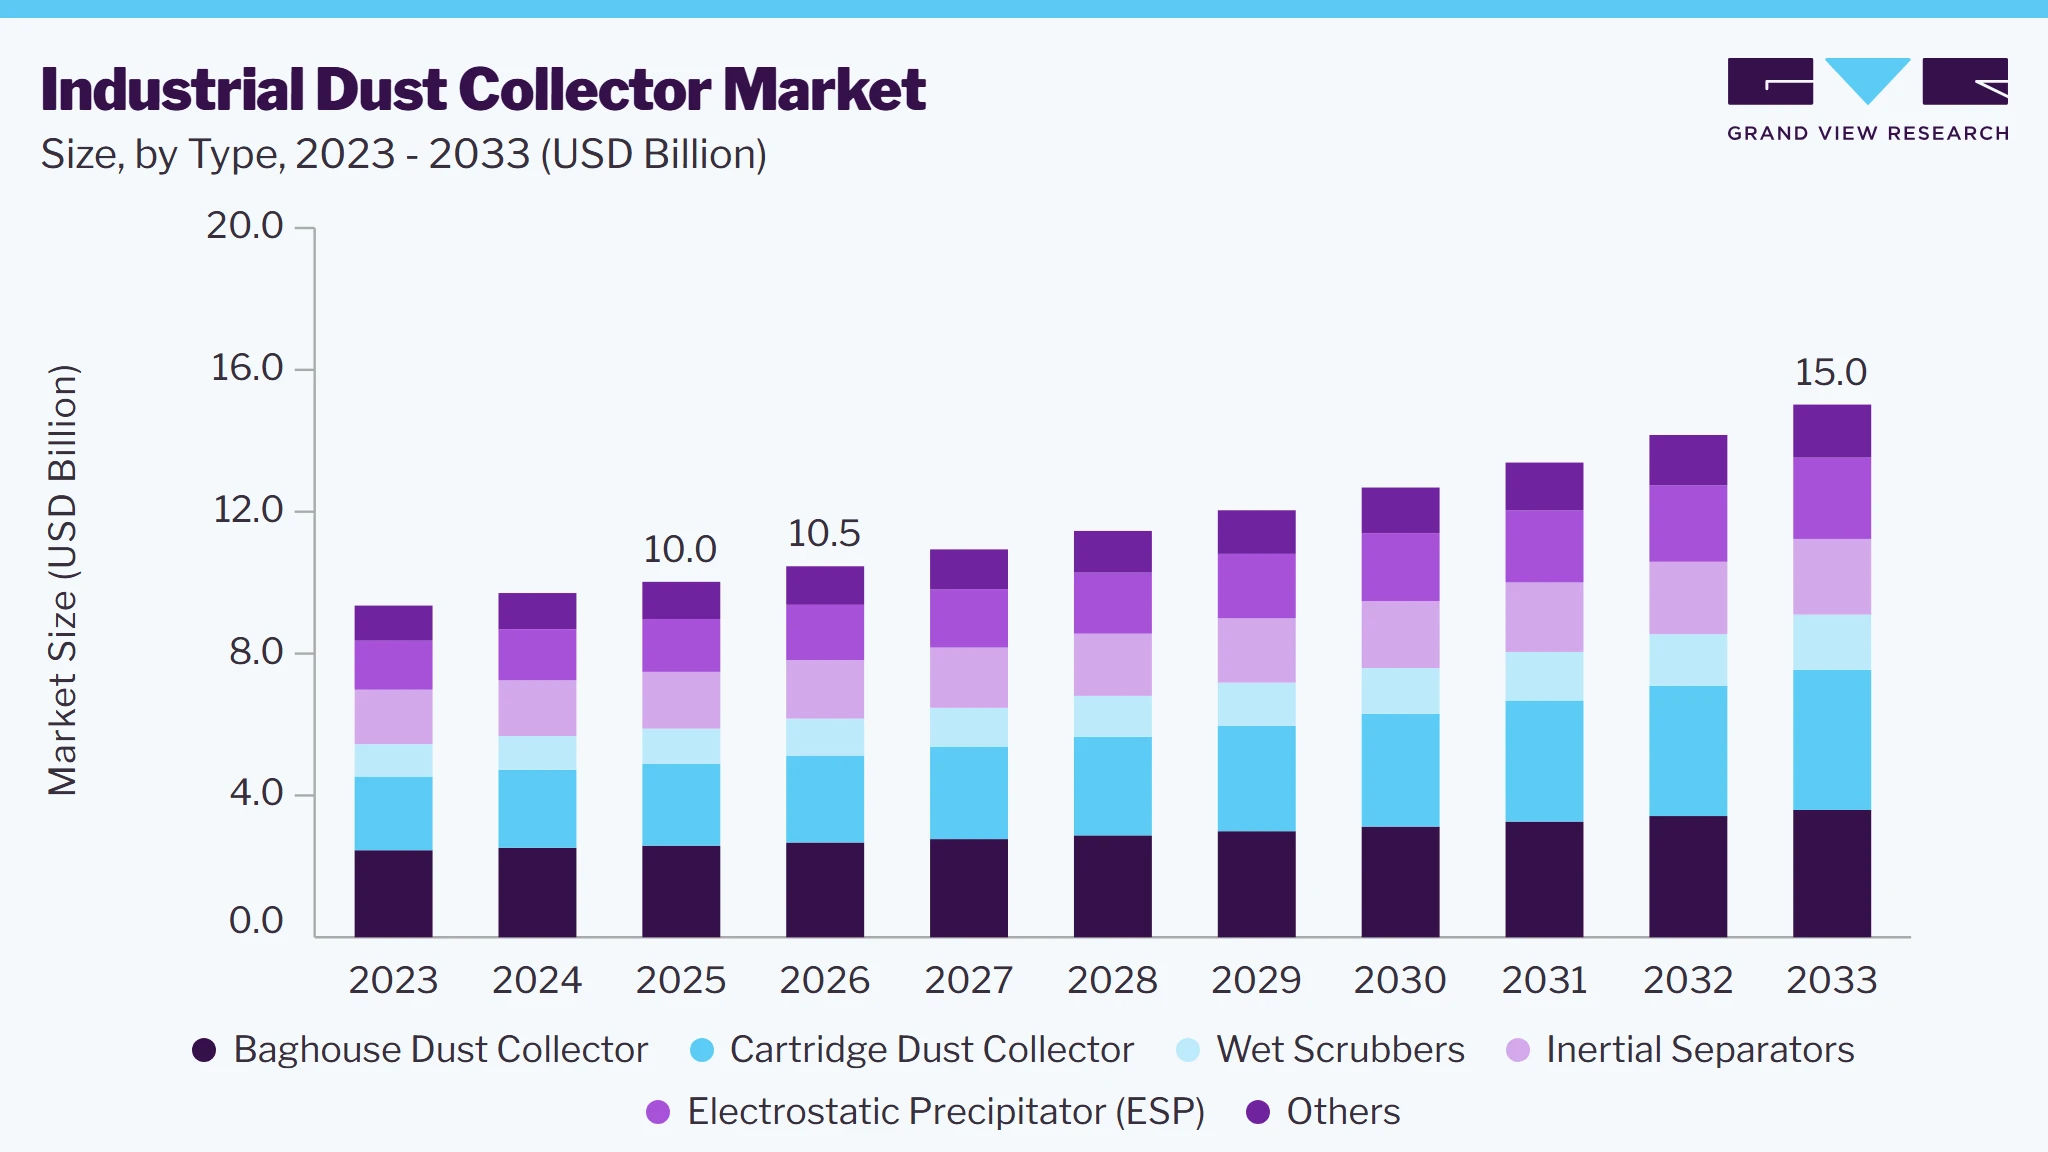 To learn more about this report, Download Free Sample Report
In addition, growing awareness regarding occupational health and worker safety is prompting industries to implement reliable solutions for controlling airborne dust and contaminants. The need to minimize equipment contamination, maintain cleaner production areas, and comply with environmental standards is also supporting market growth. Furthermore, modernization of industrial facilities and replacement of aging dust collection equipment are creating opportunities for advanced and higher-capacity systems.Market Dynamics
The industrial dust collector market is witnessing steady growth due to increasingly stringent environmental regulations, rising industrialization, and growing emphasis on workplace safety across manufacturing sectors. Industries such as cement, steel, and food processing are investing in advanced dust collection systems to reduce particulate emissions, protect employee health, and comply with air quality standards. Technological advancements including high-efficiency filtration media, automated cleaning systems, IoT-enabled monitoring, and energy-efficient dust collection solutions are further supporting market expansion. Additionally, growing awareness regarding sustainability and corporate environmental responsibility is encouraging industries to upgrade legacy air pollution control equipment.
Governments and environmental agencies across major economies are implementing increasingly strict emission standards to control industrial air pollution. Regulatory frameworks governing particulate matter emissions require manufacturing facilities to adopt effective dust collection technologies to minimize environmental impact and maintain compliance. Industries that fail to meet prescribed emission limits face penalties, operational restrictions, and reputational risks, driving continuous investments in advanced dust collection systems.
The substantial capital investment required for purchasing, installing, and integrating industrial dust collection systems remains a key challenge for market growth. Large-scale facilities often require customized filtration equipment, ducting networks, monitoring systems, and ongoing filter replacement, resulting in significant ownership costs. Small and medium-sized enterprises, particularly in developing regions, may delay upgrades or adopt lower-cost alternatives due to budget constraints, limiting broader market penetration.
The growing integration of digital technologies presents a significant opportunity for industrial dust collector manufacturers. Modern systems equipped with sensors, predictive maintenance capabilities, remote monitoring, and real-time performance analytics enable operators to optimize filtration efficiency while reducing energy consumption and maintenance expenses. As industries increasingly pursue automation, sustainability, and operational efficiency objectives, demand for intelligent and energy-efficient dust collection solutions is expected to create substantial growth opportunities for market participants over the forecast period.
Market Concentration & Characteristics
The industrial dust collector market comprises global equipment manufacturers, filtration technology providers, engineering companies, and regional suppliers serving a wide range of industrial applications. The competitive environment varies by product category and application, with companies differentiating their offerings through collection capacity, filtration performance, equipment configuration, and suitability for specific dust characteristics. Established participants generally maintain broader product portfolios, while specialized and regional suppliers focus on application-specific requirements and localized customer needs.
Market demand is closely linked to industrial production activity and the nature of particulate emissions generated during manufacturing processes. Industries such as metalworking, cement, mining, chemicals, pharmaceuticals, food processing, and woodworking require different collection configurations based on particle size, dust concentration, temperature, moisture content, and process conditions. This application diversity contributes to demand for baghouse collectors, cartridge collectors, cyclone systems, wet scrubbers, and other technologies, with equipment selection influenced by process requirements and applicable emission standards.
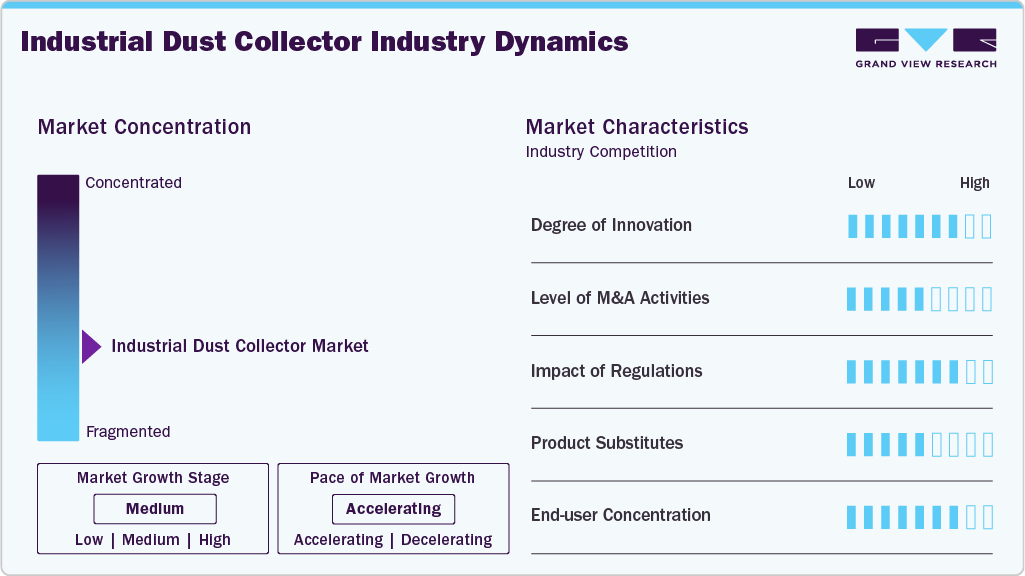 To learn more about this report, Download Free Sample Report
The industry also involves considerable engineering and system-integration requirements, particularly for large-scale installations. Dust collectors may need to be integrated with production lines, ventilation networks, ducting, exhaust systems, and automated monitoring equipment, making technical design and installation capabilities important competitive factors. After-sales services, including filter replacement, inspection, preventive maintenance, troubleshooting, and system upgrades, form an important part of the value chain. Replacement demand from aging equipment and the modernization of existing industrial facilities further contributes to recurring business opportunities.
Analyst Perspective
The industrial dust collector market is positioned for steady long-term growth, supported by increasingly stringent environmental regulations, rising industrial production, and growing emphasis on workplace air quality and employee safety. Demand is expected to remain particularly strong in cement, steel, mining, and power generation industries, where particulate emissions control is critical for regulatory compliance. Technological advancements such as high-efficiency filtration media, energy-efficient systems, and smart monitoring capabilities are reshaping competitive dynamics and encouraging replacement of legacy equipment. Additionally, rapid industrialization in emerging economies and increasing investments in sustainable manufacturing practices are expected to create new growth opportunities for market participants over the forecast period.
Type Insights
By type, the baghouse dust collector segment accounted for the largest revenue share of 25.8% in 2025, reflecting its widespread use across manufacturing, power generation and other dust-intensive industrial operations. The segment’s revenue position is associated with its ability to handle high dust loads and large air volumes while meeting particulate emission control requirements across diverse industrial environments.
The cartridge dust collector segment is projected to register the fastest CAGR during the forecast period, driven by rising demand for compact and efficient filtration systems. Its revenue growth is supported by the suitability of cartridge collectors for facilities with space constraints, along with high filtration efficiency, simplified maintenance, and applicability across various industrial processes.
Mechanism Insights
By mechanism, the dry dust collector segment accounted for the largest revenue share of 66.2% in 2025, reflecting its established use across industries such as metalworking, food and beverage and general manufacturing. Dry systems are suitable for applications where particulate matter can be captured through filter-based or mechanical separation methods, offering a practical solution for continuous dust removal without the use of liquid media.
The wet dust collector segment is projected to register the fastest CAGR during the forecast period, primarily driven by its suitability for processes generating fine, sticky, combustible, or high-temperature particulates. These systems use liquid media to capture dust and can be advantageous in applications where conventional dry filtration faces challenges related to particle characteristics or process conditions.
Mobility Insights
By mobility, the fixed dust collector segment accounted for the largest revenue share in 2025, reflecting its established use in industrial facilities with permanent production setups and defined dust-generation points. Fixed systems are integrated into centralized ventilation and filtration arrangements, enabling continuous collection of particulate matter across processes such as material handling, machining, grinding, and processing. Their suitability for high-volume operations and long-duration industrial use contributes to their broader deployment across manufacturing environments.
The portable dust collector segment is projected to register the fastest CAGR of 6.1% during the forecast period. Increasing demand for localized dust control in workshops, maintenance areas, construction sites, and production zones is creating opportunities for mobile collection systems. Portable units can be repositioned according to operational requirements, making them suitable for facilities where dust-generating activities occur at multiple or changing locations.
End-use Insights
By end use, the steel segment accounted for the largest revenue share of 18.9% in 2025, reflecting the extensive deployment of dust collection systems across steel manufacturing and processing facilities. Dust generation during melting, casting, rolling, cutting, grinding, and material handling creates a sustained requirement for particulate filtration, particularly where facilities need to maintain controlled working environments and comply with emission standards.
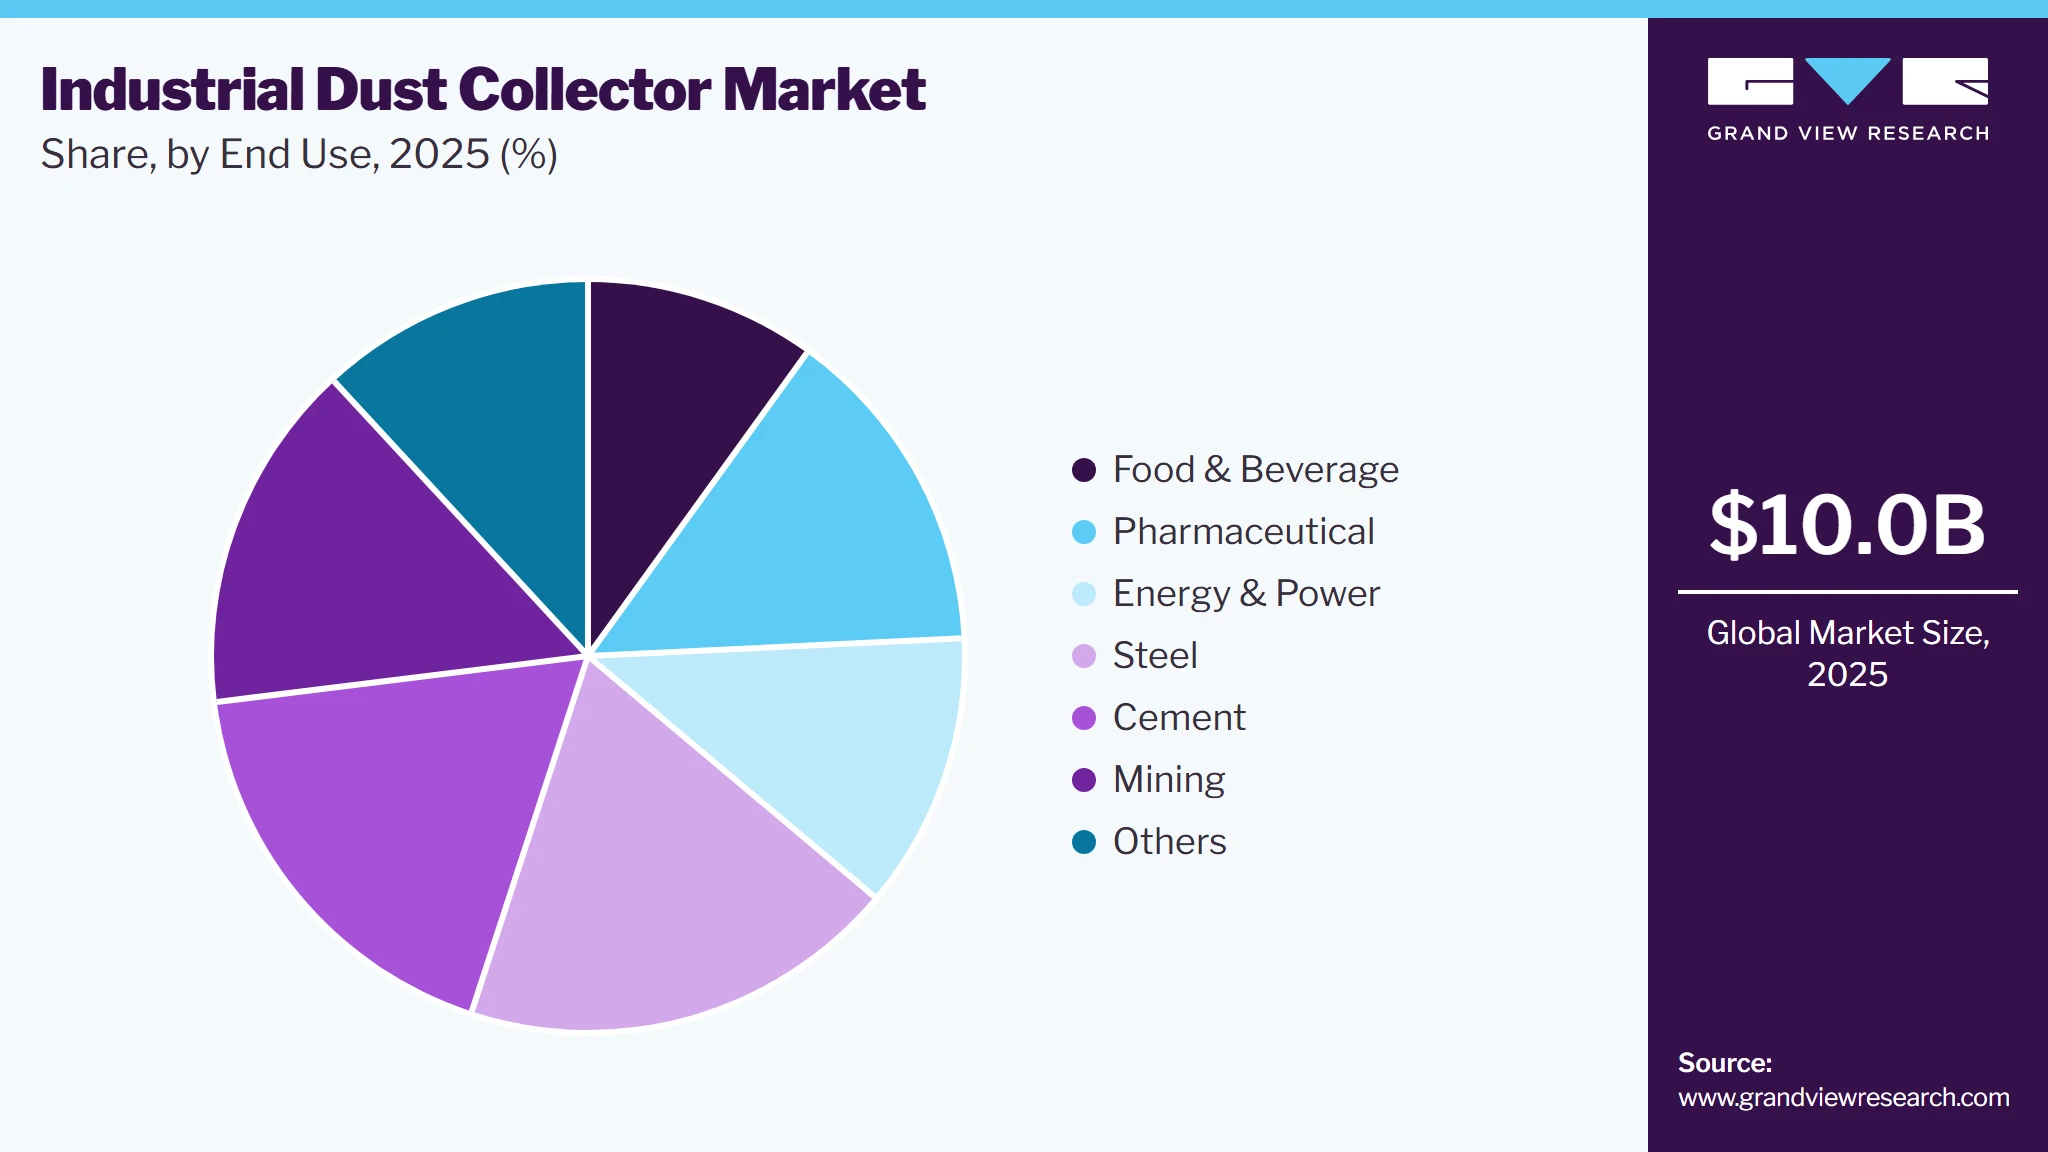 To learn more about this report, Download Free Sample Report
The energy and power segment is projected to register the fastest CAGR during the forecast period, driven by increasing requirements for particulate emission control across power generation operations. Dust collectors are deployed in areas such as fuel handling, combustion, ash processing, and material transfer, creating demand for systems capable of managing high dust loads and maintaining compliance with increasingly stringent environmental regulations.
Regional Insights
The industrial dust collector market in North America held a significant revenue share in 2025, primarily driven by the stringent government regulations regarding emissions control. The implementation of the Clean Air Act and related standards have prompted industries to adopt effective dust collection systems to comply with environmental mandates. Furthermore, increasing investments in infrastructure and manufacturing sectors contribute to heightened demand for dust collectors. Moreover, the focus on improving workplace safety and reducing health risks associated with airborne contaminants further drives the adoption of advanced dust collection technologies in this region.
U.S. Industrial Dust Collector Market Trends
The U.S. industrial dust collector market led the North American market and accounted for the largest revenue share in 2025 due to regulatory requirements and a strong emphasis on workplace safety. In addition, ongoing technological advancements are enhancing the performance of these systems, making them more appealing to manufacturers seeking compliance and operational efficiency. Furthermore, as industries prioritize health and safety, the demand for innovative industrial dust collectors is expected to grow significantly.
The Mexico industrial dust collector market is supported by the expansion of manufacturing and industrial activities, particularly across automotive, metalworking, food processing, and other dust-intensive industries. Increasing emphasis on industrial air quality and compliance with environmental and occupational safety requirements is encouraging manufacturers to adopt effective particulate control systems. In addition, the development of industrial facilities and investments in production infrastructure are creating demand for dust collection equipment capable of managing particulate emissions across various manufacturing processes.
Europe Industrial Dust Collector Market Trends
The industrial dust collector market in Europe is expected to grow substantially over the forecast period, owing to expanding environmental regulations and a strong focus on sustainability. In addition, the European Union has implemented stringent air quality standards that require industries to adopt effective dust management solutions. Furthermore, as countries work towards reducing emissions and improving air quality, there is a growing need for advanced filtration technologies in various sectors, including manufacturing and construction.
The growth of Germany industrial dust collector market is expected to be driven by its advanced manufacturing sector and commitment to environmental sustainability. As one of Europe’s largest economies, Germany emphasizes compliance with stringent air quality regulations that necessitate effective dust collection systems. In addition, the country's focus on innovation and technological advancements further enhances the efficiency of these systems. Furthermore, increasing public awareness regarding air quality issues propels the demand for reliable industrial dust collectors, positioning Germany as a key player in this market segment.
The France industrial dust collector market is supported by the country’s diverse industrial base, including metalworking, automotive, food processing, chemicals, and construction-related activities. Demand for dust collection equipment is influenced by the need to manage particulate emissions generated during manufacturing and material handling processes. In addition, modernization of industrial facilities and the adoption of cleaner production practices are encouraging the replacement of conventional systems with more efficient filtration solutions.
Asia Pacific Industrial Dust Collector Market Trends
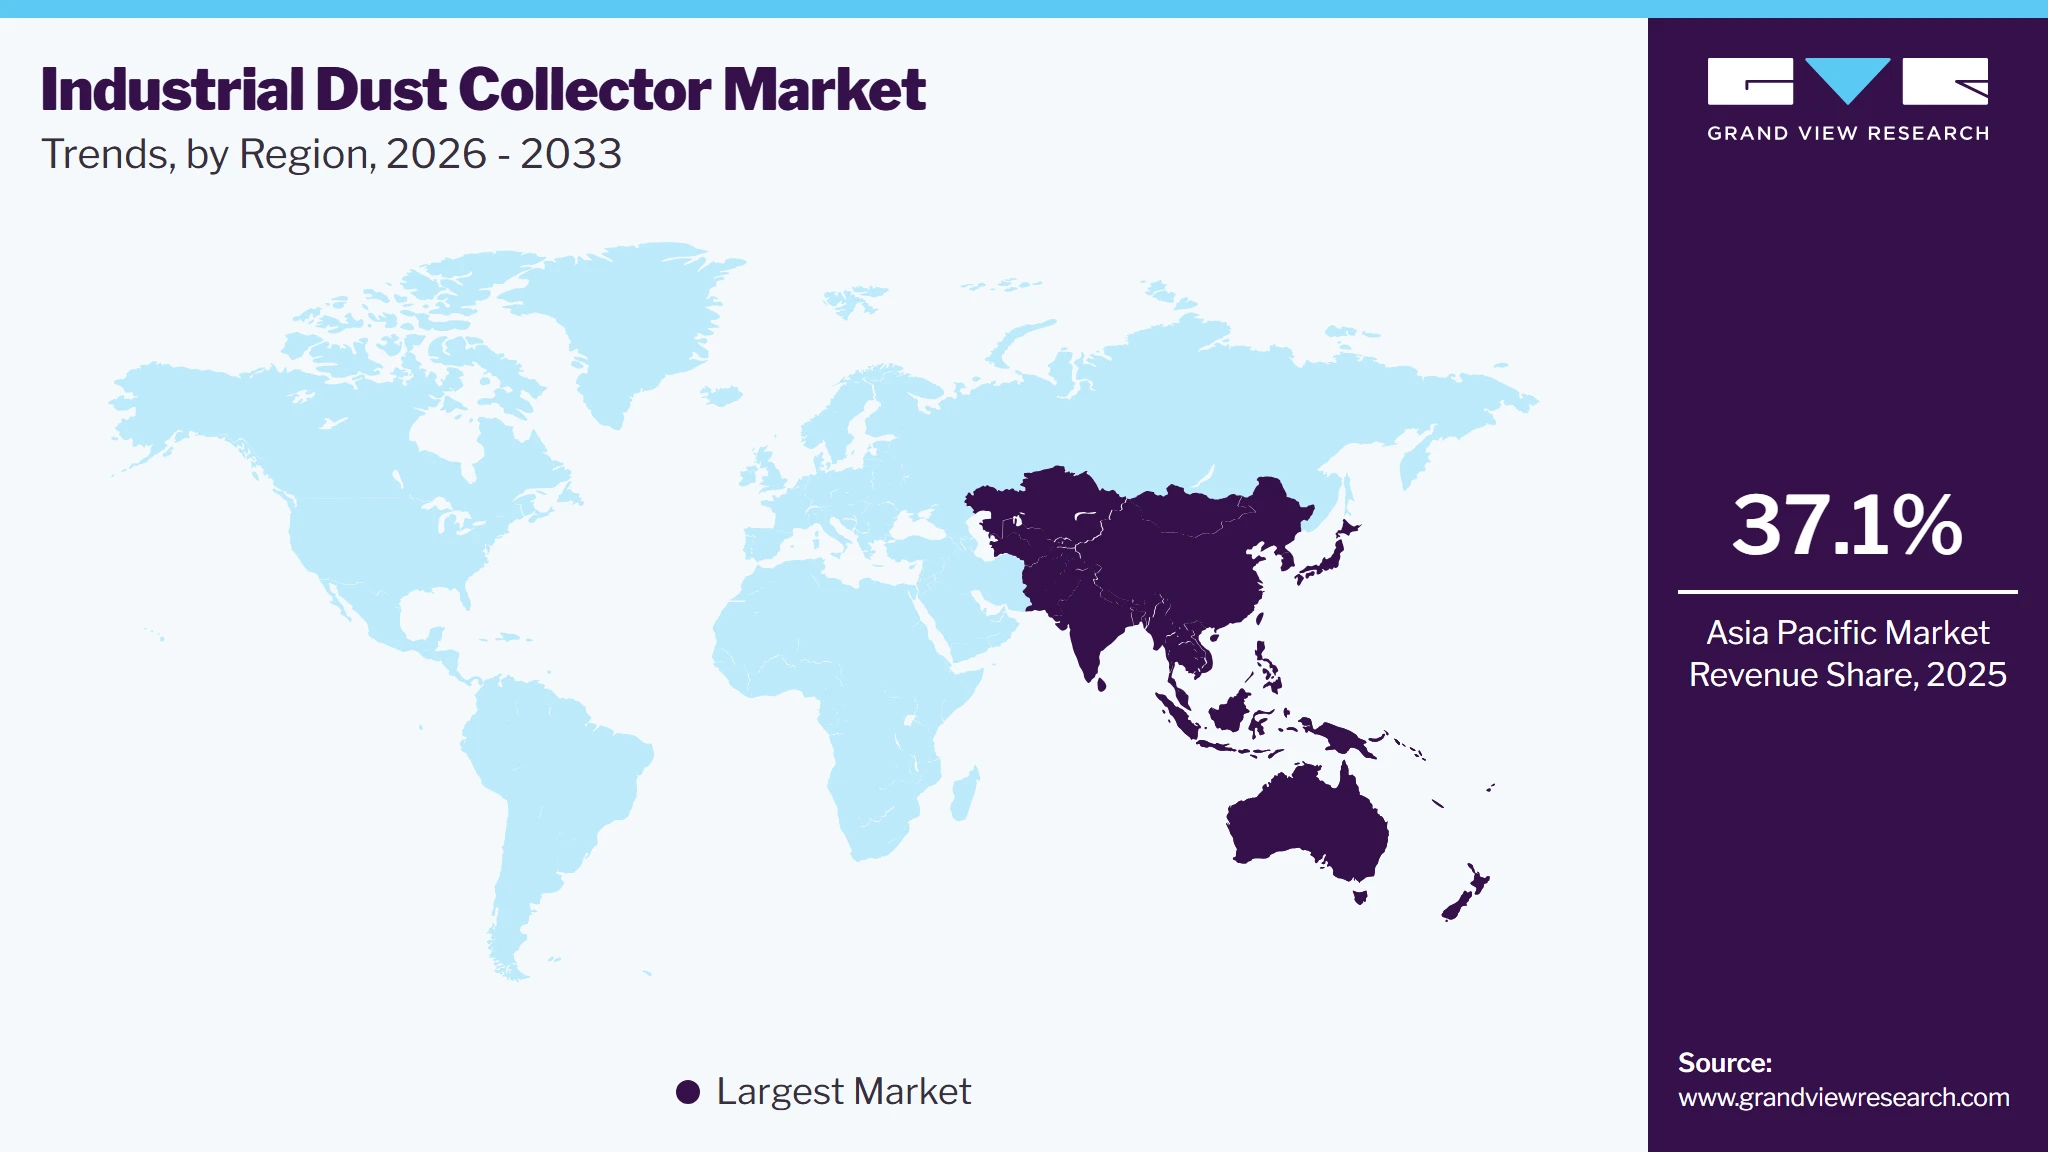
Asia Pacific dominated the industrial dust collector market with the largest revenue share of 37.1% in 2025. This growth can be attributed to the rapid industrialization and urbanization within the region. In addition, as countries such as India and China expand their manufacturing capabilities, the demand for effective dust management solutions increases. Furthermore, heightened public awareness regarding air quality and occupational health is prompting industries to adopt efficient dust collectors, creating lucrative opportunities for market expansion.
 To learn more about this report, Download Free Sample Report
The industrial dust collector market in the China held the largest share in the Asia Pacific region in 2025, driven by its robust manufacturing sector and stringent environmental policies. In addition, the government's commitment to improving air quality has led to increased investments in dust collection technologies, thereby driving the market. Furthermore, initiatives aimed at monitoring and controlling particulate matter in urban areas are driving the adoption of advanced filtration systems, positioning China as a key market for industrial dust collectors.
India industrial dust collector market is influenced by the country’s expanding industrial base and increasing deployment of dust control equipment across high-particulate manufacturing operations. Growth in sectors such as steel, cement, mining, power, and engineering is creating varied application opportunities for industrial filtration systems. In addition, upgrades to existing facilities and the installation of dust control infrastructure in new plants are contributing to market demand.
Middle East & Africa Industrial Dust Collector Market Trends
The Middle East and Africa industrial dust collector market is expected to grow at a CAGR of 5.9% over the forecast period, owing to increasing industrial activities and a focus on environmental sustainability. Rapid urbanization and infrastructure development projects are generating higher levels of airborne particulate matter, necessitating effective dust management solutions. Furthermore, governments in the region are implementing stricter regulations to control emissions, encouraging industries to invest in advanced dust collection systems.
Saudi Arabia industrial dust collector market is influenced by the expansion of oil and gas processing, cement production, mining, and manufacturing activities. Large-scale industrial projects and the development of new production facilities are creating application opportunities for dust collection equipment across material handling, crushing, grinding, and processing operations. The diversification of the industrial base is also broadening the range of applications for particulate filtration systems beyond traditional energy-related industries.
Latin America Industrial Dust Collector Market Trends
The Latin America industrial dust collector market is supported by the expansion of manufacturing, mining, cement, food processing, and metalworking activities across the region. Increasing industrial production and investment in processing facilities are creating demand for equipment that can manage particulate emissions generated during material handling and production operations. In addition, greater attention to environmental compliance and workplace air quality is encouraging industries to strengthen dust management practices.
The Brazil industrial dust collector market is shaped by the country’s extensive mining and mineral processing activities, along with its steel, food processing, and manufacturing industries. Dust collection equipment is required across applications such as mineral handling, crushing, grinding, conveying, and bulk material processing. The development and modernization of industrial facilities, coupled with increasing attention to emission management, is creating opportunities for the installation and replacement of dust collection systems.
Key Industrial Dust Collector Company Insights
Some of the key players operating in the market include Donaldson Company, Inc., Parker Hannifin Corporation, Camfil AB.
-
Parker Hannifin Corporation, headquartered in Cleveland, Ohio, is a manufacturer of motion and control technologies serving diversified industrial and aerospace markets. The company provides industrial air filtration and pollution control solutions, including DustHog and SmogHog systems for dust, fume, and mist collection. Its filtration solutions are used across manufacturing and processing applications requiring particulate control, including machining, grinding, welding, and other dust-generating operations.
-
Camfil AB, headquartered in Stockholm, Sweden, is a manufacturer of air filtration and air pollution control solutions for commercial and industrial applications. The company offers industrial dust and fume collection systems, including dry dust collectors and related filtration technologies for managing particulate emissions across manufacturing processes. Its portfolio serves industries such as metalworking, pharmaceuticals, food processing, mining, and chemicals, addressing different dust characteristics and process requirements.
Key Industrial Dust Collector Companies
The following key companies have been profiled for this study on the industrial dust collector market
-
Donaldson Company, Inc.
-
Parker Hannifin Corporation
-
Camfil AB
-
Nederman Holding AB
-
Imperial Systems, Inc.
-
RoboVent
-
CECO Environmental
-
Sly Environmental
-
Scientific Dust Collectors
-
Micro Air
-
Plymovent
-
Airflow Systems, Inc.
-
United Air Specialists (UAS)
-
Diversitech Inc.
-
Filtermist Systems Limited
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Donaldson Company, Inc., Parker Hannifin Corporation, Camfil AB, Nederman Holding AB, Imperial Systems, Inc., RoboVent, CECO Environmental)
- Expand dust collection portfolios across diverse industrial applications, supported by product development and system integration capabilities.
- Strengthen market reach through established distribution networks, aftermarket services, and geographic expansion.
- Broad product portfolios and established engineering capabilities enable these companies to address diverse particulate-control requirements.
- Strong customer relationships and technical resources support participation in complex industrial installations.
- Higher system costs can restrict adoption among smaller industrial facilities.
- Complex organizational structures may result in longer customization and procurement cycles.
Emerging & Regional Players (e.g., Filtermist Systems Limited, Plymovent, Diversitech Inc., Sly Environmental, Scientific Dust Collectors, Micro Air, Airflow Systems, Inc., United Air Specialists (UAS), regional manufacturers)
- Focus on application-specific systems and configurable dust collection solutions for targeted industrial requirements.
- Expand regional presence through distributors, localized sales, and responsive technical services.
- Flexible configurations and localized support allow these companies to address specific customer requirements.
- Competitive pricing and shorter decision-making processes can appeal to small and mid-sized industrial facilities.
- Limited geographic reach and production capacity compared with multinational suppliers.
- Smaller service networks can constrain participation in large-scale or multinational projects.
Recent Developments
-
In March 2025, Emerson introduced its Dust Collector Monitoring and Control Solution, combining sensors, controllers, and monitoring interfaces to provide real-time equipment monitoring and automated filter cleaning. The solution is designed to enhance dust collector performance, reduce compressed air and maintenance requirements, and help industries manage particulate emissions.
-
In November 2025, Parker Hannifin announced an agreement to acquire Filtration Group Corporation for USD 9.25 billion. The transaction expands Parker’s filtration capabilities through Filtration Group’s engineered technologies and broad industrial applications, including in-plant and industrial filtration. With Filtration Group generating substantial aftermarket sales, the acquisition also strengthens Parker’s recurring filtration business and expands its portfolio of solutions relevant to industrial particulate and air filtration applications.
Global Industrial Dust Collector Market Report Scope
Report Attribute
Details
Market size in 2025
USD 10.0 billion
Estimated market size in 2026
USD 10.5 billion
Projected market size by 2033
USD 15.0 billion
Growth rate
CAGR of 5.3% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, mechanism, end-use, mobility, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; China; Japan; India; Australia; Brazil; Argentina; Colombia; Saudi Arabia; South Africa; UAE
Key companies profiled
Donaldson Company, Inc.; Parker Hannifin Corporation; Camfil AB; Nederman Holding AB; Imperial Systems, Inc.; RoboVent; CECO Environmental; Sly Environmental; Scientific Dust Collectors; Micro Air; Plymovent; Airflow Systems, Inc.; United Air Specialists (UAS); Diversitech Inc.; Filtermist Systems Limited
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Industrial Dust Collector Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global industrial dust collector market report based on type, mechanism, end-use, mobility, and region.
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Baghouse Dust Collector
-
Woven
-
Non-woven
-
-
Cartridge Dust Collector
-
Wet Scrubbers
-
Inertial Separators
-
Electrostatic Precipitator (ESP)
-
Others
-
-
Mechanism Outlook (Revenue, USD Billion, 2021 - 2033)
-
Dry
-
Wet
-
-
End-use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Food & Beverage
-
Pharmaceutical
-
Energy & Power
-
Steel
-
Cement
-
Mining
-
Others
-
-
Mobility Outlook (Revenue, USD Billion, 2021 - 2033)
-
Portable
-
Fixed
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
Italy
-
UK
-
-
Asia Pacific
-
-
China
-
India
-
Japan
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
Colombia
-
-
Middle East and Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The industrial dust collector market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before
publication, with each industrial dust collector segment quantified using the revenue-capture definitions in the table below.Segment Definition
Type
Revenue Capture Definition
Baghouse Dust Collector
Revenue generated from the sale of complete baghouse dust collection systems, including filtration housing, filter bags, cleaning mechanisms, fans, and associated dust handling components.
Cartridge Dust Collector
Revenue generated from the sale of cartridge-based dust collection units incorporating pleated filter cartridges and integrated dust extraction systems.
Wet Scrubbers
Revenue generated from sales of wet dust collection systems that use liquid media to remove particulate matter and contaminants from industrial air streams.
Inertial Separators
Revenue generated from the sale of mechanical dust separation equipment that removes particulate matter using centrifugal force, gravity, or airflow redirection.
Electrostatic Precipitator (ESP)
Revenue generated from sales of electrostatic particulate collection systems that use electrical charges to capture dust and emissions from industrial exhaust gases.
Others
Revenue generated from sales of alternative dust collection technologies, including cyclone collectors, mist collectors, and hybrid filtration systems.
Mechanism
Revenue Capture Definition
Dry
Revenue generated from sales of dust collection systems that capture particulate matter through filtration, electrostatic, or mechanical separation methods without using liquid media.
Wet
Revenue generated from sales of dust collection systems that utilize water or other liquids to capture and remove airborne particulate matter.
Mobility
Revenue Capture Definition
Portable
Revenue generated from sales of mobile or movable dust collection units designed for temporary, flexible, or workstation-specific applications.
Fixed
Revenue generated from sales of permanently installed dust collection systems integrated into industrial facilities for continuous dust control operations.
End Use
Revenue Capture Definition
Food & Beverage
Revenue generated from dust collector systems sold to food processing, beverage manufacturing, grain handling, and ingredient production facilities.
Pharmaceutical
Revenue generated from dust collection equipment supplied to pharmaceutical manufacturing, formulation, packaging, and API production facilities.
Energy & Power
Revenue generated from dust collection and emission control systems installed in power generation plants and energy production facilities.
Steel
Revenue generated from dust collection systems sold for steel manufacturing, metal processing, foundries, and related operations.
Cement
Revenue generated from dust collection equipment deployed across cement production processes, including crushing, grinding, kiln, and material handling operations.
Mining
Revenue generated from dust collection systems supplied to mining, mineral extraction, ore processing, and quarrying operations.
Others
Revenue generated from sales to industries such as chemicals, pulp & paper, woodworking, automotive, and general manufacturing.
Estimation Model
Layer Name
Key Question
Description
Industrial Demand Base
Which industries create demand for dust collection equipment?
Assessment of dust-generating industries such as cement, steel, mining, power generation, food & beverage, pharmaceuticals, and other manufacturing sectors requiring air pollution control solutions.
Technology Penetration
Which dust collection technologies are adopted across industries?
Analysis of market adoption across baghouse dust collectors, cartridge dust collectors, wet scrubbers, inertial separators, electrostatic precipitators (ESP), and other dust control technologies.
Equipment Procurement Demand
How much dust collection equipment is purchased by industrial facilities?
Evaluation of demand based on production capacity additions, facility expansions, environmental compliance requirements, replacement purchases, and technology upgrades across end-use industries.
Revenue
What is the total market revenue generated from industrial dust collector sales?
Revenue generated from the sale of industrial dust collectors, filtration units, electrostatic precipitators, wet scrubbers, and related dust collection equipment across all end-use industries and regions.
Customization Table
Client Request
Customization Delivered Value Adds Regional Segmentation
Delivered a detailed regional assessment of the industrial dust collector market covering North America, Europe, Asia Pacific, Latin America, and Middle East & Africa. The analysis included market size, growth trends, regulatory landscape, industrial activity levels, and demand patterns across key end-use industries such as cement, steel, mining, power generation, pharmaceuticals, and food & beverage.
Enabled identification of high-growth regions, investment hotspots, and region-specific demand drivers. Provided actionable insights into environmental regulations, industrial expansion trends, and future market opportunities across major geographies.
Competitive Benchmarking
Delivered a comprehensive benchmarking analysis of leading market participants based on product portfolio strength, technology offerings, geographic presence, end-use industry focus, strategic initiatives, and competitive positioning. The assessment covered established global manufacturers as well as emerging regional participants active in industrial dust collection and air pollution control technologies.
Assisted in evaluating competitive intensity, market concentration, technology leadership, and strategic differentiation. Supported business development, partnership evaluation, and competitive positioning decisions for stakeholders.
Opportunity Assessment
Delivered an in-depth opportunity assessment identifying high-potential growth areas across dust collection technologies, industrial sectors, and regional markets. The analysis evaluated opportunities arising from tightening emission regulations, industrial automation, smart filtration systems, energy-efficient dust collection technologies, and increasing investments in environmental compliance infrastructure.
Helped prioritize attractive market segments and emerging revenue pockets. Provided strategic guidance for product development, market entry planning, capacity expansion, and long-term growth initiatives within the industrial dust collector industry.
Frequently Asked Questions About This Report
The global industrial dust collector market was valued at USD 10.0 billion in 2025 and is expected to reach USD 10.5 billion in 2026
The global industrial dust collector market is projected to grow at a CAGR of 5.3% from 2026 to 2033, reaching USD 15.0 billion by 2033
Some key players in the industrial dust collector market are Camfil AB; Donaldson Company, Inc.; Parker Hannifin Corp.; Nederman Holding AB; Thermax Limited; Babcock & Wilcox Enterprises, Inc.; Imperial Systems, Inc.; Kelin Environmental Protection Technology Co., Ltd.; KC Cottrell; CECO Environmental; Hamon; Sumitomo Heavy Industries, Ltd.
The industrial dust collector market is driven by increasingly stringent environmental emission regulations, growing industrialization, and rising awareness of workplace air quality and worker safety. Demand is also supported by expanding cement, mining, steel, power generation, and manufacturing activities worldwide.
The cement segment was the leading end-use industry, accounting for 18.9% of the market revenue in 2025.
Asia Pacific dominated the global industrial dust collector market with a 37.1% revenue share in 2025, supported by strong industrial activity and infrastructure development.
The wet dust collector segment is projected to register the fastest CAGR of 6.1% during the forecast period, supported by its suitability for fine, sticky, combustible, and high-temperature particulates
The fixed segment led the market, capturing 67.1% of total revenue in 2025, owing to its extensive use in permanent industrial installations.
The baghouse dust collector segment held the largest market share, accounting for 25.8% of total revenue in 2025, while the cartridge dust collector segment is the fastest-growing type.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


