
- Home
- »
- Energy & Power
- »
-
Liquefied Petroleum Gas Market Size & Share Report, 2033GVR Report cover

Liquefied Petroleum Gas Market (2026 - 2033)
Size, Share & Trends Analysis Report By Source (Non-associated Gas, Associated Gas, Refinery), By Application (Residential, Commercial, Petrochemicals), By Product (Propane, Butane), By Region, And Segment Forecasts
Market Size, 2025
$126.8BMarket Estimate, 2026
$131.0BMarket Forecast, 2033
$169.3BCAGR, 2026–2033
3.7%Liquefied Petroleum Gas Market Summary
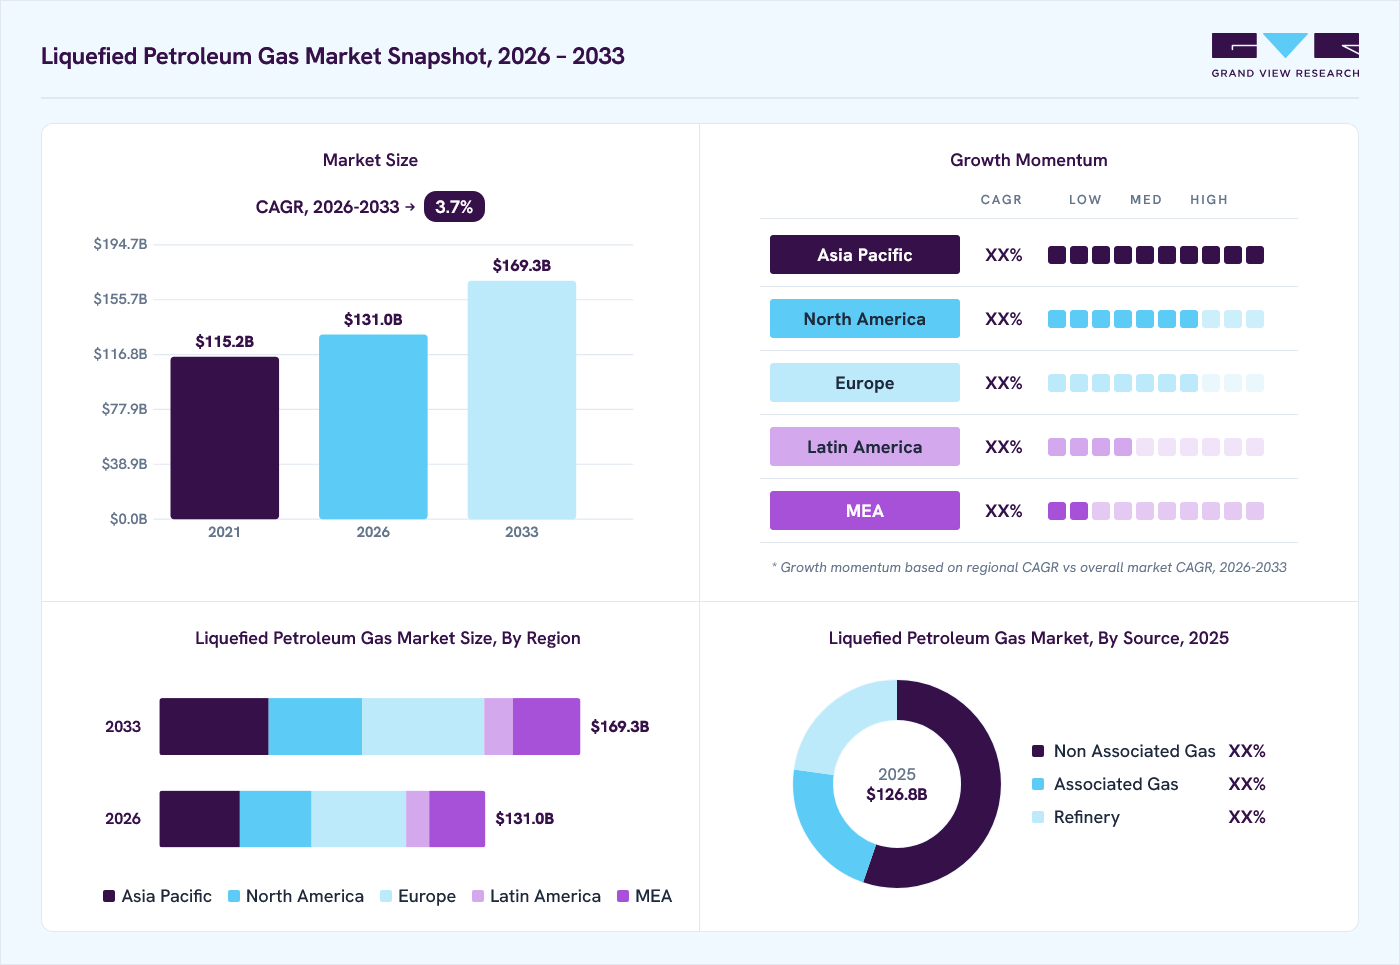
The global liquefied petroleum gas market size was valued at USD 126.8 billion in 2025 and is projected to grow from USD 131.0 billion in 2026 to USD 169.3 billion by 2033, at a CAGR of 3.7% from 2026 to 2033. Europe dominated the market, accounting for a revenue share of 29.0% in 2025. Growth is primarily driven by the increasing use of LPG as a cleaner alternative to traditional fossil fuels across residential, commercial, and industrial sectors. The rising demand for low-emission energy sources to curb urban air pollution and achieve carbon neutrality targets is driving market expansion.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By source: Non-associated gas segment held the largest market share of 55.2% in 2025.
- By application: Petrochemicals segment held the largest revenue share of 17.2% in 2025.
- By product: Propane segment held the largest market share of 47.3% in 2025.
Regional Highlights
- Largest regional market: Europe (29.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 126.8 Billion
- Estimated market size in 2026: USD 131.0 Billion
- Projected market size by 2033: USD 169.3 Billion
- CAGR (2026-2033): 3.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
 To learn more about this report, Download Free Sample Report
Market Dynamics
The liquefied petroleum gas (LPG) market is driven by rising energy demand, increasing adoption of cleaner-burning fuels, and growing usage across residential, commercial, industrial, and transportation sectors. Government initiatives promoting low-emission energy sources and expanding LPG distribution networks in emerging economies are supporting market growth. The market is also influenced by fluctuations in crude oil and natural gas prices, supply chain disruptions, and competition from alternative fuels such as natural gas and electricity. Increasing investments in LPG infrastructure, including storage terminals, transportation facilities, and import capacity, are expected to create new growth opportunities in the coming years.
The growing need for cleaner, cost-effective, and reliable energy solutions is a key driver for the LPG market. LPG produces lower greenhouse gas emissions and fewer pollutants than traditional fuels such as coal, wood, and other biomass-based energy sources, making it an attractive transition fuel for residential cooking, commercial heating, industrial processes, and transportation. Increasing urbanization, rising household energy consumption, and government efforts to improve access to modern cooking fuels, particularly in developing economies, are accelerating LPG adoption. Its ease of storage, portability, and established distribution infrastructure enable LPG to serve as a dependable energy source in regions with limited access to natural gas pipelines.
According to the U.S. Energy Information Administration (EIA), U.S. propane exports reached a record 1.8 million barrels per day in 2025, reflecting strong global demand for cleaner-burning LPG fuels. The growth in propane exports highlights increasing adoption of LPG for residential heating, cooking, industrial applications, and petrochemical uses, supporting expansion of the global LPG market.
A key restraint for the LPG market is the fluctuation in crude oil and natural gas prices, as LPG is primarily produced as a by-product of natural gas processing and crude oil refining. Changes in global energy prices, geopolitical tensions, and supply-demand imbalances can significantly impact LPG production costs, pricing stability, and profit margins across the value chain. Price volatility can also affect consumer affordability, industrial adoption, and long-term investment decisions in LPG infrastructure. Competition from alternative energy sources such as natural gas, electricity, and renewable fuels may limit LPG demand growth in certain applications.
The growing focus on decarbonization and the transition toward low-carbon fuels is creating new business opportunities in the LPG market through the development of renewable LPG, including bio-LPG produced from sustainable feedstock such as vegetable oils, agricultural residues, and waste materials. Renewable LPG offers performance characteristics similar to conventional LPG while reducing lifecycle carbon emissions, enabling energy companies to support sustainability targets without requiring major changes to existing storage, transportation, and distribution infrastructure. In 2025, Neste expanded its renewable LPG initiatives, enabling lower-carbon LPG alternatives and creating new growth opportunities for suppliers to meet rising demand for sustainable energy solutions.
Analyst Perspective
The liquefied petroleum gas (LPG) market is expected to grow steadily due to rising demand for cleaner fuels in residential, commercial, industrial, and transportation sectors. A key trend in the market is the growing focus on renewable and low-carbon LPG solutions as companies aim to reduce emissions while leveraging existing LPG infrastructure. Growing LPG adoption in emerging economies, supported by improved distribution networks and energy access programs, is creating new growth opportunities. However, the market faces challenges from fluctuating crude oil and natural gas prices, as well as competition from alternative energy sources. Increasing investments in LPG storage, transportation infrastructure, and global supply networks are helping companies improve market reach and strengthen supply reliability.
Source Insights
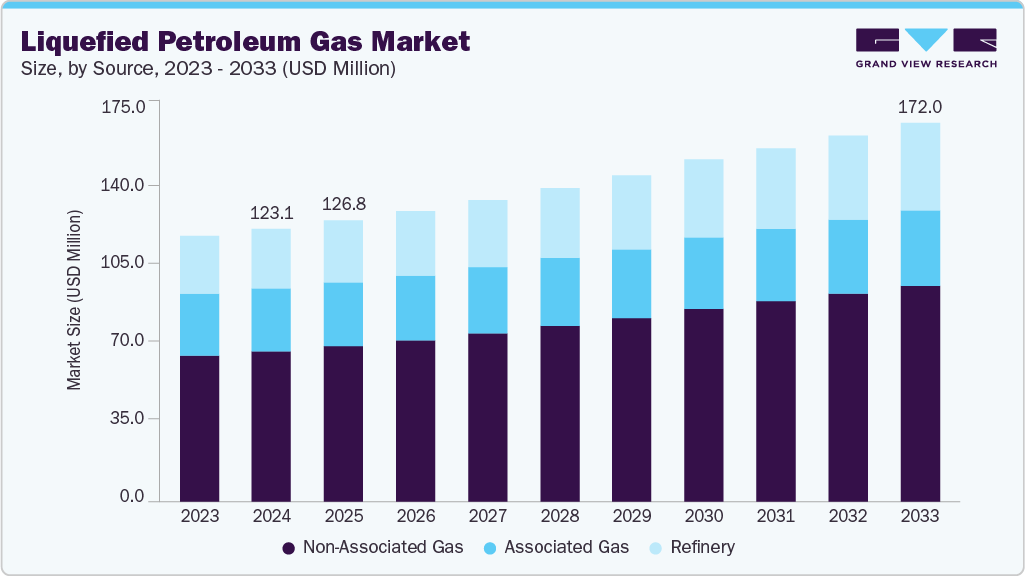
The non-associated gas segment accounted for the largest revenue share, approximately 55.2% in 2025, establishing itself as the leading source category in the global liquefied petroleum gas (LPG) market. This dominance is largely attributed to the increasing international production of natural gas and the rapid expansion of gas processing infrastructure in key producing regions, such as North America, the Middle East, and the Asia-Pacific. Non-associated gas, produced independently of oil extraction, provides a cleaner, more consistent, and reliable feedstock for LPG production. Growing investments in natural gas exploration, coupled with technological advancements in gas separation and liquefaction processes, have significantly improved yield efficiency.
Meanwhile, the associated gas segment is expected to witness the fastest growth, at a CAGR of around 4.5%, from 2026 to 2033, driven by the steady recovery in global crude oil production and increasing efforts to utilize previously flared associated gas. As oil-producing countries such as Saudi Arabia, the United States, Russia, and Nigeria expand upstream activities, the capture and processing of associated gas are becoming integral to sustainability and emission reduction goals. The adoption of gas reinjection, gathering, and liquefaction technologies enables oil producers to convert flared gas into valuable LPG products, thereby enhancing both environmental and economic outcomes.
Application Insights
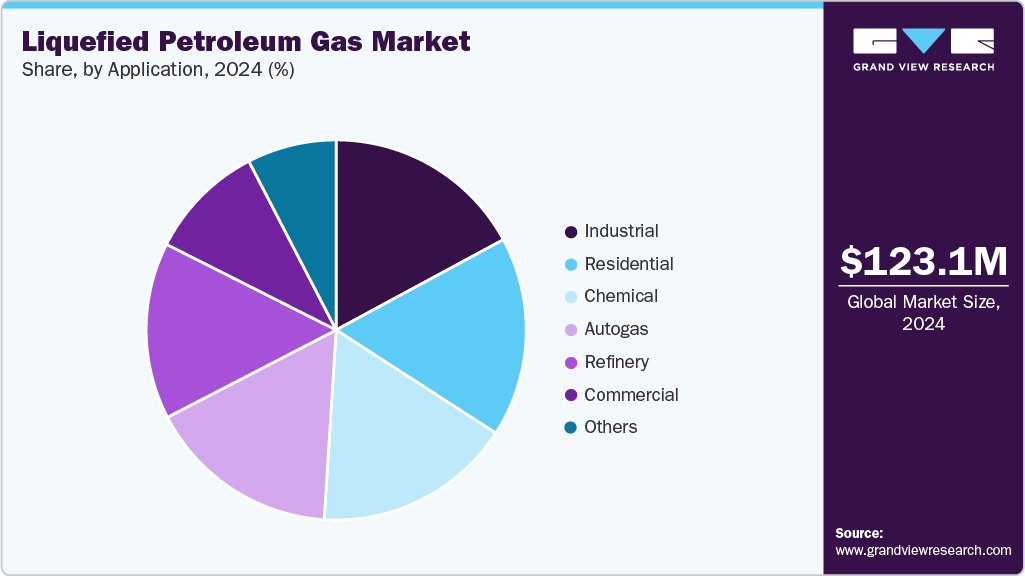
The petrochemicals segment accounted for the largest revenue share of 17.2% in 2025, driven by the extensive use of industrial gases as feedstocks and process gases in the production of chemicals, polymers, fertilizers, and synthetic materials. Growing demand for ethylene, propylene, methanol, and other petrochemical derivatives across the packaging, automotive, construction, and consumer goods industries supported segment growth. Expanding petrochemical production capacities, particularly in the Asia Pacific and the Middle East, along with increasing investments in integrated refining and petrochemical complexes, further strengthened demand for industrial gases in this segment.
 To learn more about this report, Download Free Sample Report
The industrial segment, on the other hand, is projected to grow at the second-fastest CAGR of approximately 4.4% from 2026 to 2033, driven by increasing demand for industrial gases across metal fabrication, machinery manufacturing, automotive, electronics, and general manufacturing industries. Rising industrial automation, expansion of manufacturing facilities in emerging economies, and the growing adoption of oxygen, nitrogen, argon, and hydrogen for welding, cutting, heat treatment, and process optimization are expected to support sustained market growth.
Product Insights
The propane segment dominated the market with a revenue share of 47.3% in 2025, supported by its widespread use as a clean-burning fuel across residential, commercial, industrial, agricultural, and transportation applications. Strong demand for space heating, cooking, water heating, and backup power generation, particularly in off-grid and rural areas, contributed to its leading position. The increasing adoption of propane as a lower-emission alternative to conventional fuels, along with its expanding use in industrial processes and autogas applications, further strengthened segment growth.
The propane-butane mix segment is expected to register the second fastest CAGR of 3.2% during the forecast period, driven by its increasing adoption as an efficient and cost-effective fuel for residential heating, cooking, commercial applications, and autogas. Rising demand for cleaner-burning LPG blends, expanding distribution infrastructure in developing economies, and growing government initiatives to promote low-emission fuels are expected to further support the segment's growth.
Regional Insights
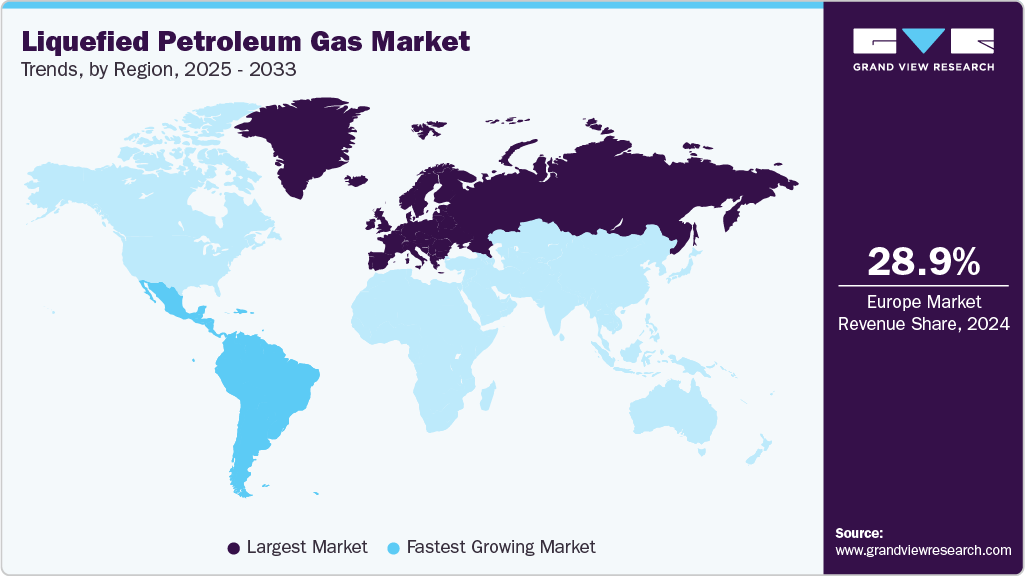
Europe accounted for the largest share of 29.0% of the global liquefied petroleum gas market in 2025, supported by strong energy transition policies, well-established LPG storage and distribution infrastructure, and diversified energy strategies. Market growth is driven by the widespread use of LPG across residential, commercial, industrial, and transportation sectors as a lower-emission alternative to coal, heating oil, and other conventional fuels. Major markets, including Germany, France, Italy, and the United Kingdom, continue to promote LPG to enhance energy security, diversify fuel sources, and achieve emission reduction targets under initiatives such as the European Green Deal and REPowerEU. The growing production and adoption of bio-LPG from renewable feedstocks, including biogas and waste oils, is accelerating the region's transition toward cleaner energy and further reinforcing Europe's leadership in the global LPG market.
 To learn more about this report, Download Free Sample Report
The UK liquefied petroleum gas industry is supported by steady demand from off-grid residential heating, commercial buildings, industrial facilities, and agricultural applications. LPG remains an important alternative fuel for areas without access to the natural gas grid, offering lower emissions than heating oil and coal. The growing adoption of bio-LPG, backed by the UK's net-zero ambitions, is further driving market growth. In addition, investments in cleaner energy solutions and an established LPG distribution network continue to support long-term market expansion.
North America Liquefied Petroleum Gas Market Trends
The liquefied petroleum gas industry in North America represents a major hub in the global LPG landscape, underpinned by abundant shale gas resources, advanced export capabilities, and expanding petrochemical demand. The United States leads regional production and export, benefiting from extensive infrastructure across the Gulf Coast and a steady increase in propane and butane output from shale formations. The region’s LPG exports to Asia and Latin America continue to surge, driven by competitive pricing and production efficiency. In Canada, significant LPG output from the Western Canadian Sedimentary Basin, combined with the expansion of propane export terminals, such as those in British Columbia, further contributes to regional growth.
U.S. Liquefied Petroleum Gas Market Trends
The liquefied petroleum gas industry in the U.S. continues to dominate North American production, driven by its vast shale gas resources, growing midstream infrastructure, and strong export demand. The U.S. accounted for a substantial share of global LPG supply in 2025, supported by major producers such as Texas and Louisiana, which host some of the world’s largest fractionation and export facilities. The increasing use of LPG as a petrochemical feedstock for propylene production, along with its expanding role in residential heating and autogas, is a major contributor to market growth. Federal and state-level incentives promoting clean fuel alternatives, alongside rising investments in liquefaction and terminal expansions, are strengthening the country’s export competitiveness.
Asia-Pacific Liquefied Petroleum Gas Market Trends
The liquefied petroleum gas industry in the Asia Pacific is projected to grow at the fastest CAGR of 4.5% from 2026 to 2033, driven by population growth, rapid urbanization, and the shift toward cleaner energy alternatives. Major consumers, including China, India, Japan, and South Korea, are driving demand through the large-scale adoption of LPG for residential cooking, heating, and industrial purposes. In India, government-led clean cooking initiatives, such as the Pradhan Mantri Ujjwala Yojana (PMUY), have significantly increased LPG consumption in rural areas. Meanwhile, China continues to expand its LPG imports and petrochemical usage, while Japan and South Korea are promoting the use of autogas and industrial applications to reduce greenhouse gas emissions.
Latin America Liquefied Petroleum Gas Market Trends
The liquefied petroleum gas industry in Latin America is supported by expanding residential and commercial consumption, as well as efforts to enhance access to clean fuels. Countries such as Brazil, Mexico, Argentina, and Chile are leading the regional demand, driven by government programs promoting LPG as a safe and affordable alternative to biomass and kerosene. The region’s growing investments in import terminals, storage facilities, and cylinder distribution infrastructure are further enhancing supply reliability. Additionally, increasing industrialization and rising petrochemical activities are creating new opportunities for LPG utilization.
Middle East & Africa Liquefied Petroleum Gas Market Trends
The liquefied petroleum gas industry in the Middle East & Africa is at a strong growth phase, supported by large-scale gas processing capacities, export-oriented infrastructure, and rising domestic demand. The Gulf Cooperation Council (GCC) countries, particularly Saudi Arabia, Qatar, and the UAE, remain key global suppliers, leveraging their natural gas reserves and integrated refinery operations to maintain a leading export position. In Africa, growing urbanization and government initiatives to replace biomass with LPG in household cooking are driving consumption in nations such as Nigeria, Kenya, and South Africa.
Key Liquefied Petroleum Gas Company Insights
Some of the key players operating in the global liquefied petroleum gas market include Saudi Arabian Oil Co. (Saudi Aramco) and Royal Dutch Shell Plc, among others.
-
Saudi Arabian Oil Co. (Saudi Aramco) is one of the world’s leading integrated energy and petrochemical companies, playing a central role in global LPG production and export. Headquartered in Dhahran, Saudi Arabia, Aramco utilizes its vast crude oil and natural gas resources to produce significant volumes of LPG as a byproduct of its refining and gas processing operations. The company exports LPG to major Asian markets, including China, Japan, and South Korea, through long-term supply agreements. Aramco’s ongoing investments in gas processing facilities such as the Fadhili and Hawiyah projects are expanding its LPG output capacity, supporting its strategy to diversify revenue streams and strengthen its presence in the global downstream and chemicals value chain.
-
Royal Dutch Shell Plc is a leading multinational energy company headquartered in London, United Kingdom, with a strong footprint in the global LPG value chain spanning production, storage, distribution, and retail. Shell markets LPG under the brand “Shell Gas,” serving residential, commercial, and industrial consumers across more than 50 countries. The company has been actively enhancing its supply and logistics network through strategic partnerships and acquisitions to ensure efficient and sustainable LPG delivery. Shell is also investing in digital transformation and cleaner fuel initiatives, positioning LPG as a transitional energy source that supports decarbonization in off-grid and rural markets. Its diversified portfolio and commitment to low-carbon solutions continue to strengthen its role as a global leader in the LPG sector.
Key Liquefied Petroleum Gas Companies
The following key companies have been profiled for this study on the liquefied petroleum gas market.
-
Saudi Arabian Oil Co. (Saudi Aramco)
-
Royal Dutch Shell Plc
-
BP Plc
-
Exxon Mobil Corporation
-
TotalEnergies SE
-
China Petroleum & Chemical Corporation (Sinopec)
-
PetroChina Company Limited
-
Qatargas Operating Company Limited
-
Reliance Industries Limited
-
Vitol Group
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Established Players (Saudi Aramco, Shell Plc, BP Plc, Exxon Mobil Corporation, TotalEnergies, Sinopec, PetroChina Company Limited, Reliance Industries Limited)
- Leverage vertically integrated operations spanning upstream oil & gas production, natural gas processing, refining, LPG extraction, storage, and distribution.
- Expand LPG supply through refinery upgrades, gas processing capacity additions, and international trading networks.
- Invest in low-carbon LPG alternatives, including renewable LPG and emissions reduction technologies, to align with energy transition goals.
- Large-scale production capacity and access to abundant hydrocarbon resources.
- Integrated supply chains enable cost efficiency, reliable supply, and global market reach.
- Strong infrastructure base, including storage terminals, LPG carriers, pipelines, and distribution networks.
- High dependence on fossil fuel-based LPG production exposes companies to crude oil and natural gas price volatility.
- Large operational footprints create challenges in adapting quickly to changing market conditions.
- Increasing regulatory pressure on carbon emissions and clean energy transition may impact long-term LPG demand.
Emerging Players (QatarEnergy LNG, Vitol)
- Focus on specialized segments such as LPG trading, logistics, regional distribution, and supply optimization.
- Expand market presence through strategic partnerships, terminal investments, and access to global LPG supply networks.
- Utilize flexible business models to respond quickly to regional demand changes and pricing opportunities.
- Greater operational flexibility and ability to adapt quickly to market changes.
- Strong trading and logistics expertise enables optimization of global LPG flows.
- Ability to enter underserved markets through targeted investments and partnerships.
- Limited control over LPG production compared with integrated producers.
- Greater dependence on third-party suppliers and global price movements.
- Smaller infrastructure footprint can restrict geographic expansion.
Recent Developments
-
In February 2025, Saudi Aramco announced the expansion of its Yanbu Gas Plant in Saudi Arabia to enhance LPG production capacity by an additional 10%, strengthening its position as one of the world’s leading LPG exporters. The project aims to meet rising global demand from Asia-Pacific and European markets and aligns with Aramco’s downstream diversification strategy under Saudi Vision 2030.
Liquefied Petroleum Gas Market Report Scope
Report Attribute
Details
Market Definition
The global liquefied petroleum gas market represents the revenue generated from the sales of LPG products, including propane, butane, and LPG mixtures across residential, commercial, and other applications.
Market size in 2025
USD 126.8 billion
Estimated market size in 2026
USD 131.0 billion
Projected market size by 2033
USD 169.3 billion
Growth rate
CAGR of 3.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative Units
Revenue in USD Billion, Volume in Million Tons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, competitive landscape, growth factors, and trends
Segments covered
Source, application, product, region
Regional scope
North America, Europe, Asia Pacific, Latin America, Middle East & Africa
Country scope
U.S., Canada, Mexico, Germany, UK, France, China, India, Japan, South Korea, Brazil, Saudi Arabia, UAE
Key companies profiled
Saudi Arabian Oil Co. (Saudi Aramco); Royal Dutch Shell Plc; BP Plc; Exxon Mobil Corporation; TotalEnergies SE; China Petroleum & Chemical Corporation (Sinopec); PetroChina Company Limited; Qatargas Operating Company Limited; Reliance Industries Limited; Vitol Group
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Liquefied Petroleum Gas Market Report Segmentation
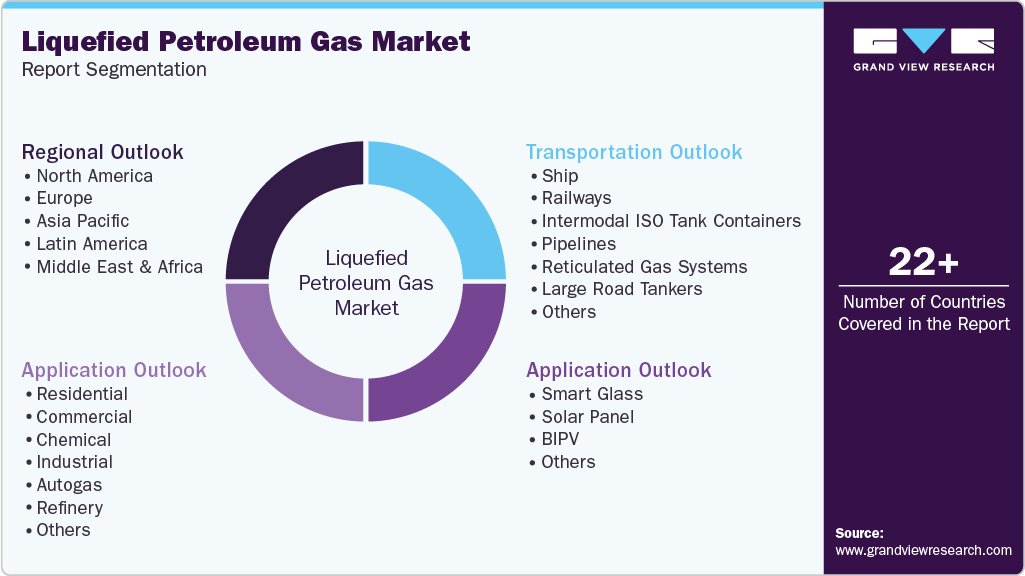
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global liquefied petroleum gas market report on the basis of source, application, product, and region:
 To learn more about this report, Download Free Sample Report
-
Source Outlook (Volume, Million Tons; Revenue, USD Billion, 2021 - 2033)
-
Refinery
-
Associated Gas
-
Non-associated Gas
-
-
Application Outlook (Volume, Million Tons; Revenue, USD Billion, 2021 - 2033)
-
Residential
-
Commercial
-
Petrochemicals
-
Industrial
-
Autogas
-
Others
-
-
Product outlook (Volume, Million Tons; Revenue, USD Billion, 2021 - 2033)
-
Propane
-
Butane
-
Propane-Butane Mix
-
-
Regional Outlook (Volume, Million Tons; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The liquefied petroleum gas market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each liquefied petroleum gas segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Source
Revenue capture definition
Refinery
LPG is produced as a by-product during crude oil refining, where propane and butane are separated from refinery gas streams. The revenue attributed to this segment represents sales of LPG produced by refineries.
Associated Gas
LPG is recovered from associated natural gas produced alongside crude oil during oil production. Revenue for this segment represents the sale of LPG extracted from associated gas.
Non-Associated Gas
LPG is recovered from non-associated natural gas produced from gas fields where natural gas is extracted independently of crude oil. Revenue for this segment represents the sale of LPG extracted from non-associated natural gas.
Segment - Application
Revenue capture definition
Residential
Revenue represents LPG sales for residential applications, including cooking, space heating, and water heating.
Commercial
Captures LPG sales to commercial establishments, including hotels, restaurants, hospitals, offices, and other service-sector facilities, primarily for cooking and heating.
Petrochemicals
Covers LPG supplied as a feedstock for the production of petrochemicals, including ethylene and propylene.
Industrial
Comprises LPG sales to industrial end users, including the metals, glass, ceramics, food processing, textiles, and cement industries, where LPG is used for process heating and manufacturing operations.
Autogas
Accounts for LPG sold as automotive fuel for passenger and commercial vehicles through refueling stations.
Others
Encompasses LPG sales for agriculture, power generation, refineries, and other niche end-use applications.
Segment - Product
Revenue capture definition
Propane
The revenue of this segment represents sales of propane supplied across various applications.
Butane
This segment captures sales of butane supplied across various applications.
Propane-Butane Mix
This segment covers sales of commercial LPG blends containing varying proportions of propane and butane, supplied across various applications.
Estimation Model
Layer Name
Key Question
Description
LPG Supply & Production Layer
What forms the supply base for liquefied petroleum gas?
Identify global LPG production from key sources, including refinery, associated gas, and non-associated gas. Assess production capacity, upstream oil and gas activities, refinery output, natural gas processing infrastructure, and regional supply availability that determine LPG production volumes.
LPG Source & Application Layer
How is LPG supplied and consumed across markets?
Evaluate the contribution of different LPG sources and analyze demand across residential, commercial, industrial, chemical, autogas, refinery, and other applications. Assess consumption patterns, sector-specific demand drivers, and the role of LPG as a fuel, feedstock, and energy source across end-use industries.
LPG Distribution & Transportation Layer
How does LPG reach end users?
Analyze LPG transportation and distribution networks, including ships, railways, intermodal ISO tank containers, pipelines, reticulated gas systems, large road tankers, bobtail tankers, and bike carts. Assess storage infrastructure, logistics capabilities, import/export terminals, and last-mile delivery systems supporting LPG accessibility.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sales of LPG products, including propane, butane, and LPG mixtures, across various end-use applications. The overall market value is determined by LPG production volumes, source contribution, consumption across applications, transportation and distribution channels, and prevailing LPG pricing trends that collectively drive revenue generation within the market.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Landscape Assessment
Benchmarked key LPG market participants based on production capacity, supply chain integration, geographic presence, distribution networks, trading activities, and strategic initiatives. Evaluated competitive positioning of established and emerging players.
Supported competitor benchmarking, identification of market leaders, and assessment of strategic expansion opportunities.
LPG Supply & Source Assessment
Analyzed LPG production sources, including refinery, associated gas, and non-associated gas. Evaluated global supply availability, processing infrastructure, and the contribution of each source to overall LPG supply.
Helped identify key supply drivers, understand source-wise market dynamics, and assess future LPG availability across regions.
LPG Application & Demand Analysis
Assessed LPG demand across residential, commercial, industrial, chemical, autogas, refinery, and other applications. Evaluated sector-specific growth drivers, consumption patterns, and adoption trends across major markets.
Enabled identification of high-growth application areas and supported demand forecasting for different end-use segments.
Frequently Asked Questions About This Report
The global liquefied petroleum gas market size was estimated at USD 126.8 billion in 2025 and is expected to reach USD 131.0 billion in 2026.
Based on source, the non-associated gas segment accounted for largest revenue share of 55.2% in 2025.
The liquefied petroleum gas market is expected to grow at a CAGR of 3.7% from 2026 to 2033 to reach USD 169.3 billion by 2033.
The Europe region dominated the liquefied petroleum gas market with a revenue share of 29.0% in 2025.
Russia dominated the Europe region market with a revenue share of 21.2% in 2025.
Asia Pacific is anticipated to register the fastest CAGR of 4.5% over the forecast period.
Based on application, the petrochemicals segment accounted for largest revenue share of 17.2% in 2025.
The key players operating in the liquefied petroleum gas market are Saudi Aramco, Shell Plc, BP Plc, Exxon Mobil Corporation, TotalEnergies, Sinopec, PetroChina Company Limited, Reliance Industries Limited, QatarEnergy LNG, Vitol, and others.
The liquefied petroleum gas market is primarily driven by rising demand for cleaner and efficient fuels for residential cooking and heating, increasing use of LPG as a petrochemical feedstock, growing autogas adoption, and expanding distribution infrastructure across emerging economies.
About the Author(s)
Energy & Power Research Team
Industry · Energy & PowerThis report was authored by the energy & power research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the energy & power segment of the industry industry. All findings are based on proprietary industry databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


