
- Home
- »
- Pharmaceuticals
- »
-
Liver Metastases Treatment Market Size Report, 2026-2033GVR Report cover

Liver Metastases Treatment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Treatment Type (Chemotherapy, Targeted Therapy, Immunotherapy), By Primary Cancer (Colorectal Cancer, Breast Cancer), By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$1.9BMarket Estimate, 2026
$2.0BMarket Forecast, 2033
$3.9BCAGR, 2026–2033
9.7%Liver Metastases Treatment Market Summary
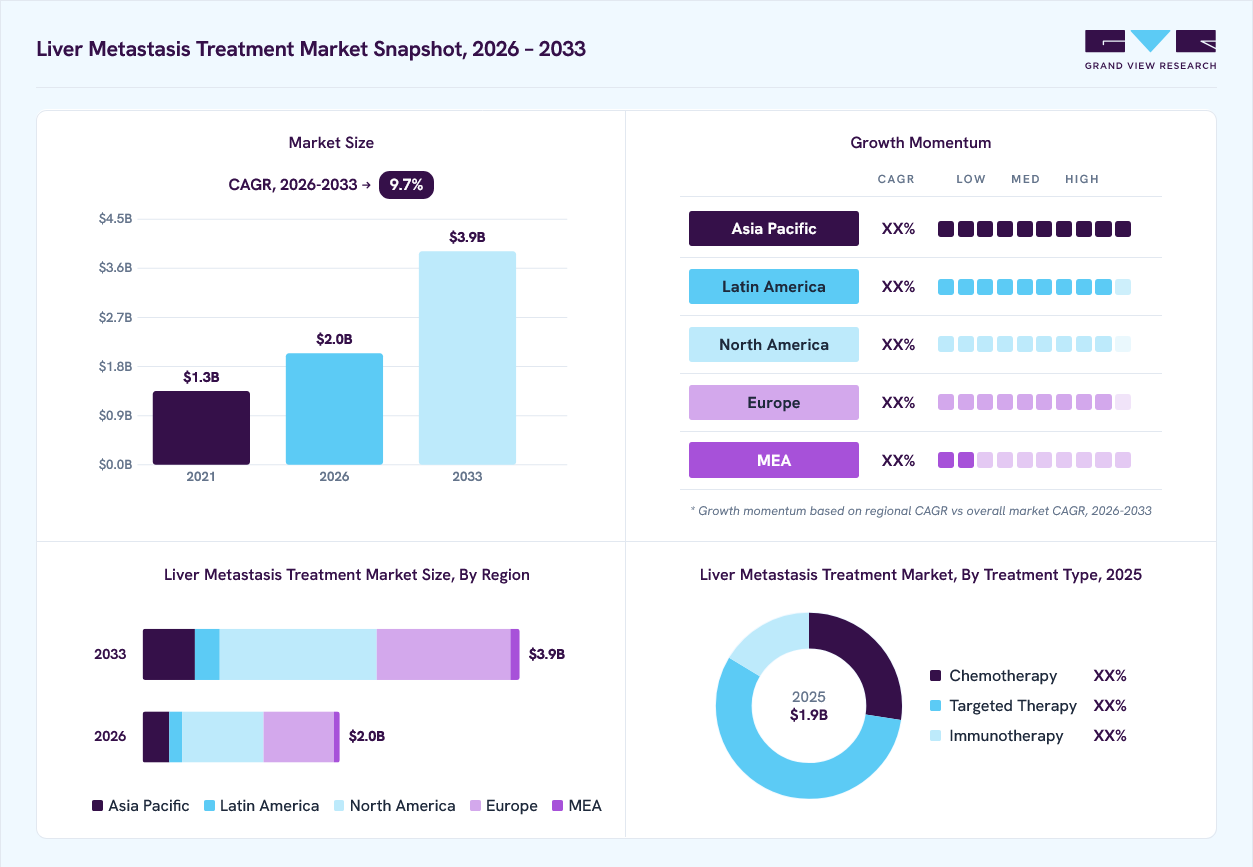
The global liver metastases treatment market size was valued at USD 1.9 billion in 2025 and is projected to grow from USD 2.0 billion in 2026 to USD 3.9 billion by 2033, at a CAGR of 9.7% from 2026 to 2033. The market in North America dominated with a revenue share of 41.2% in 2025. This can be attributed to the rising incidence of the target disease. For instance, the American Cancer Society estimates approximately 1,958,310 new cancer cases and 609,820 deaths in U.S. in 2023.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By treatment type: Targeted therapy segment held the largest market share of 56.1% in 2025.
- By primary cancer: Colorectal cancer segment held the largest market share of 57.4% in 2025.
- By distribution channel: Hospital pharmacies segment held the largest market share of 78.9% in 2025.
Regional Highlights
- Largest regional market: North America (41.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 1.9 Billion
- Estimated market size in 2026: USD 2.0 Billion
- Projected market size by 2033: USD 3.9 Billion
- CAGR (2026-2033): 9.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Liver metastases are especially prevalent in breast and colorectal cancers, impacting both young women and men. The increasing cases indicate a growing burden, which is expected to boost the demand for treatment over the forecast period.Increasing research initiatives show positive results, contributing to market growth. Several government and non-profit organizations are actively involved in research activities. For instance, the National Cancer Institute is running a program P01 focusing on understanding the common mechanism involved in developing liver metastases using a disparate tumor model. Successful completion of study is expected to boost the development of novel diagnostics and medicines for the treatment in the coming years.
 To learn more about this report, Download Free Sample Report
Investments in drug development drive market expansion by contributing to innovation and diversifying treatment options. Ongoing efforts focus on discovering novel therapies, contributing to a broader array of available treatments for various medical conditions. These initiatives promote a competitive landscape, introducing alternatives that cater to diverse patient needs. As research progresses, it opens avenues for partnerships and collaborations, creating a dynamic ecosystem that adapts to emerging healthcare challenges. For instance, in February 2023, the FDA grants Orphan Drug Designation to Genoscience Pharma's ezurpimtrostat for treating HepatoCellular Carcinoma (HCC). The autophagy inhibitor drug undergoes clinical trials, showing promise in combating liver cancer with ongoing research.
Market Dynamics
The liver metastases treatment market is driven by the increasing incidence of metastatic cancers, particularly colorectal cancer and breast cancer, which are among the leading primary cancers associated with liver metastases. Treatment approaches continue to evolve with the growing use of targeted therapies and immunotherapies alongside conventional chemotherapy, supported by advances in biomarker testing and molecular profiling. The adoption of personalized treatment strategies is contributing to changes in clinical practice, particularly in patients with specific genetic and molecular characteristics. Market demand is further supported by improvements in cancer diagnosis, greater awareness of metastatic disease management, and the increasing use of multidisciplinary treatment approaches involving medical oncology, surgical oncology, and interventional radiology. Regulatory authorities continue to review and approve new oncology therapies for metastatic cancers, supporting the availability of additional treatment options. Distribution of liver metastases therapies remains concentrated within hospital-based oncology centers and specialty pharmacy networks due to the complexity of treatment administration and patient monitoring requirements. The competitive landscape is characterized by the presence of established oncology companies focusing on portfolio expansion through targeted therapies, immunotherapies, and combination treatment regimens. Over the forecast period, market growth is expected to be supported by ongoing clinical research, broader adoption of biomarker-guided treatment approaches, and the introduction of additional therapies for metastatic cancer management.
The growing adoption of precision oncology and targeted therapeutics is supporting the development of the liver metastases treatment market as healthcare providers increasingly incorporate biomarker-guided treatment approaches into metastatic cancer management. Advances in genomic profiling, molecular diagnostics, and companion diagnostic technologies have improved the ability to identify tumor-specific characteristics and select therapies based on individual patient profiles. This trend is particularly evident in colorectal cancer, one of the most common primary cancers associated with liver metastases, where targeted therapies directed at biomarkers such as VEGF, HER2, BRAF, and MSI-H have expanded available treatment options. The increasing use of molecular testing is enabling more precise patient stratification and supporting the adoption of personalized treatment strategies across oncology practices. In addition, growing clinical evidence demonstrating the effectiveness of targeted therapies and immunotherapies in specific patient populations is contributing to their broader integration into treatment pathways. For instance, in 2025, Bristol-Myers Squibb received FDA approval for Opdivo (nivolumab) in combination with Yervoy (ipilimumab) for the treatment of patients with unresectable or metastatic MSI-H/dMMR colorectal cancer. The approval expanded the availability of biomarker-based treatment options for advanced disease and reflected the increasing focus on precision-guided oncology care. Such developments highlight the growing importance of molecular characterization in treatment decision-making and are expected to support continued adoption of targeted therapeutic approaches in patients with liver metastases.
The liver metastases treatment market faces challenges associated with tumor heterogeneity and variability in biomarker expression across patients. Liver metastases can originate from different primary cancers, including colorectal cancer and breast cancer, each exhibiting distinct molecular characteristics, disease progression patterns, and treatment responses. While advances in targeted therapies and immunotherapies have expanded available treatment options, many of these therapies are designed for patients with specific genetic mutations, biomarker profiles, or molecular subtypes. Consequently, only a subset of patients may be eligible for certain advanced treatment approaches, limiting the potential patient pool for these therapies. In addition, the molecular characteristics of tumors can evolve over time and may differ between primary tumors and metastatic lesions, creating challenges in treatment selection and clinical management. The requirement for comprehensive biomarker testing and molecular profiling further adds complexity to the treatment pathway, particularly in healthcare settings with limited diagnostic capabilities. Variability in treatment response among patients with similar clinical characteristics also remains a challenge, as not all biomarker-positive patients derive the same level of benefit from targeted interventions. These factors can affect treatment adoption rates, complicate clinical decision-making, and limit the broader utilization of precision oncology approaches. As a result, tumor heterogeneity and biomarker variability continue to represent important constraints on the widespread adoption of advanced therapies in the liver metastases treatment market.
The expansion of biomarker-driven gastrointestinal oncology programs presents a significant opportunity for the liver metastases treatment market, as a substantial proportion of liver metastases originate from colorectal and other gastrointestinal cancers where treatment selection is increasingly influenced by molecular and genetic characteristics. Growing adoption of biomarker testing is improving the identification of patients who may benefit from targeted treatment approaches, supporting the integration of precision medicine into routine oncology practice. Research focused on biomarkers such as HER2, KRAS, BRAF, and MSI-H is contributing to the development of therapies designed for specific patient populations and is expanding the range of available treatment options for advanced metastatic disease. Pharmaceutical companies are actively advancing clinical programs that combine targeted therapies, immunotherapies, and other novel treatment modalities to address unmet needs in gastrointestinal cancers associated with liver metastases. These developments are strengthening the clinical relevance of molecular profiling and enabling more individualized treatment strategies across metastatic disease settings. The growing availability of targeted therapies, coupled with increasing physician adoption of biomarker-guided treatment selection, is improving patient management and supporting broader implementation of precision oncology approaches. As clinical research continues to advance and biomarker testing becomes more widely incorporated into standard cancer care pathways, the availability and utilization of personalized treatment strategies are expected to increase, creating substantial opportunities for innovation and long-term growth within the liver metastases treatment market.
Analyst Perspective
The liver metastases treatment market is shifting toward personalized approaches driven by advances in molecular diagnostics, biomarker testing, and targeted therapies. Precision oncology is increasingly influencing treatment selection, while chemotherapy remains important alongside growing use of targeted therapies and immunotherapies. Challenges such as tumor heterogeneity and variable treatment response persist. Expanding biomarker-driven programs, molecular profiling, and new targeted therapies are expected to drive market evolution and long-term growth.
Treatment Type Insights
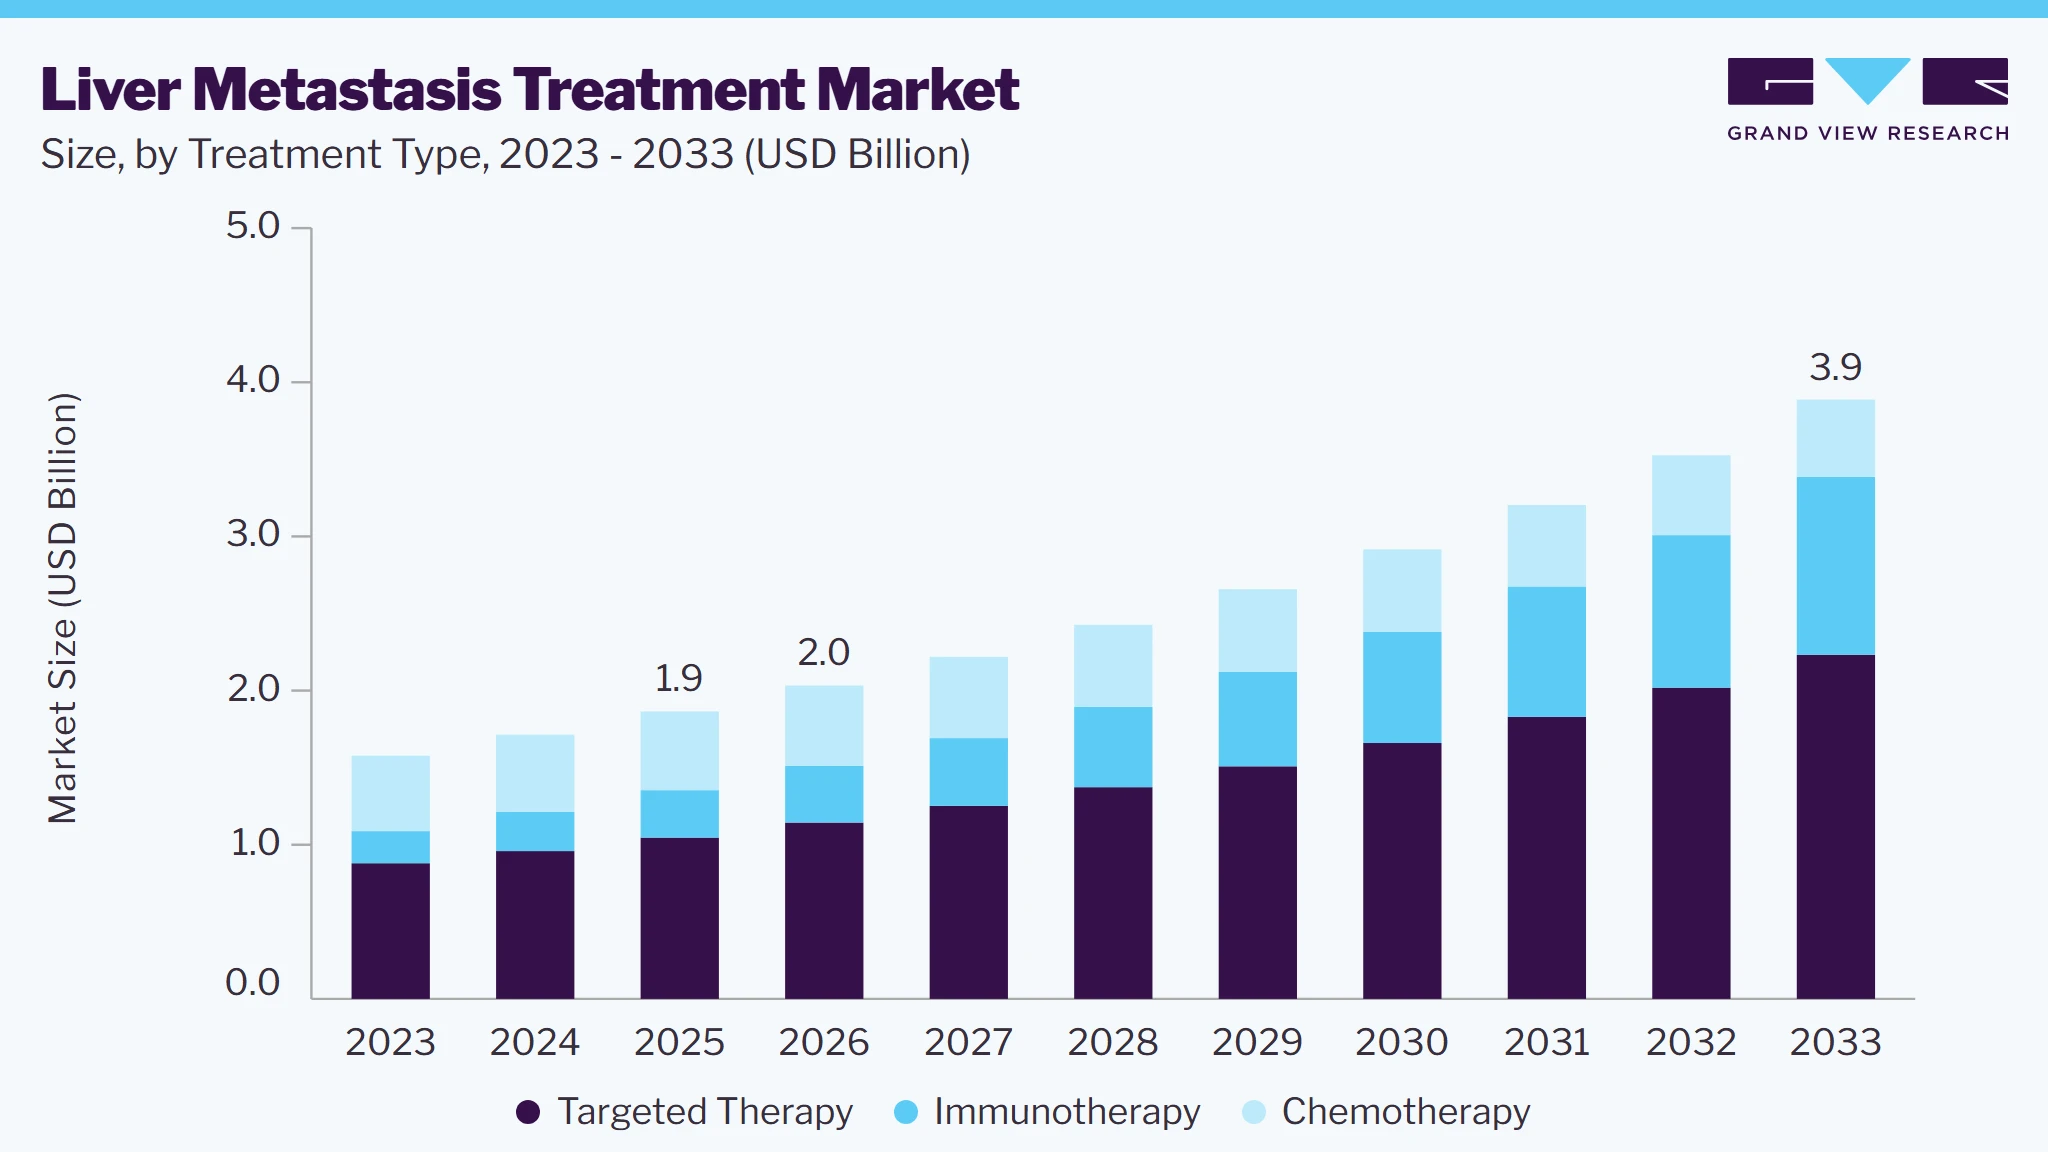
Based on treatment type, the targeted therapy segment led the market with the largest revenue share of 56.1% in 2025. The wide availability of molecular targeted therapy drugs and emergence as an effective alternative medicine over other treatment methodologies. Some of the key molecular targeted therapy drugs used are Cetuximab, Panizumab, and Bevacizumab. Among them, Cetuximab and Panizumab are the most used drugs. Cetuximab is used as first-line drug therapy in patients with colon cancer liver metastases (CCLM). Thus, growing use of targeted therapy medicines to treat patients with the colorectal cancer liver metastases (CRLM) is projected to drive market growth.
The chemotherapy segment is projected to grow at a significant CAGR over the forecast period. This can be attributed to their high usage rate in the past years due to increasing incidence of primary cancers that are responsible for liver metastases in patients. Systemic chemotherapy is mostly used in patients with unresectable hepatocellular carcinoma due to prolonged survival time compared to other treatment methodologies. Several research studies demonstrated that the use of oxaliplatin in combination with fluorouracil and calcium folinate increases rate of survival in CRLM patients.
Primary Cancer Insights
Based on primary cancer, the colorectal cancer segment led the market with the largest revenue share of 57.4% in 2025. This dominance can be attributed to rising incidence of colorectal liver metastases. Liver is main site for distant metastasis in male population with colorectal cancer. For instance, according to American Cancer Society, colorectal cancer, excluding skin cancers, ranks as the third most common cancer in U.S., with an estimated 106,970 new colon and 46,050 rectal cases in 2023. Various research articles and studies suggest that approximately 25-30% of patients with colorectal cancer develop liver metastases, hence, early diagnosis and treatment of colorectal cancer is most important to reduce the burden of liver metastases.
The breast cancer segment is expected to grow at the fastest CAGR over the forecast period, especially due to the risk of liver metastases in women with metastatic breast cancer. According to Breastcancer.org, nearly 50% of individuals diagnosed with breast cancer develop liver metastases with a significant occurrence. Moreover, breast cancer and other prominent cancers contributing to liver metastases encompass bladder, kidney, and lung cancers. This trend is expected to drive the segment at a lucrative CAGR during the forecast period, increasing the significance of addressing liver metastases in various cancer types.
Distribution Channel Insights
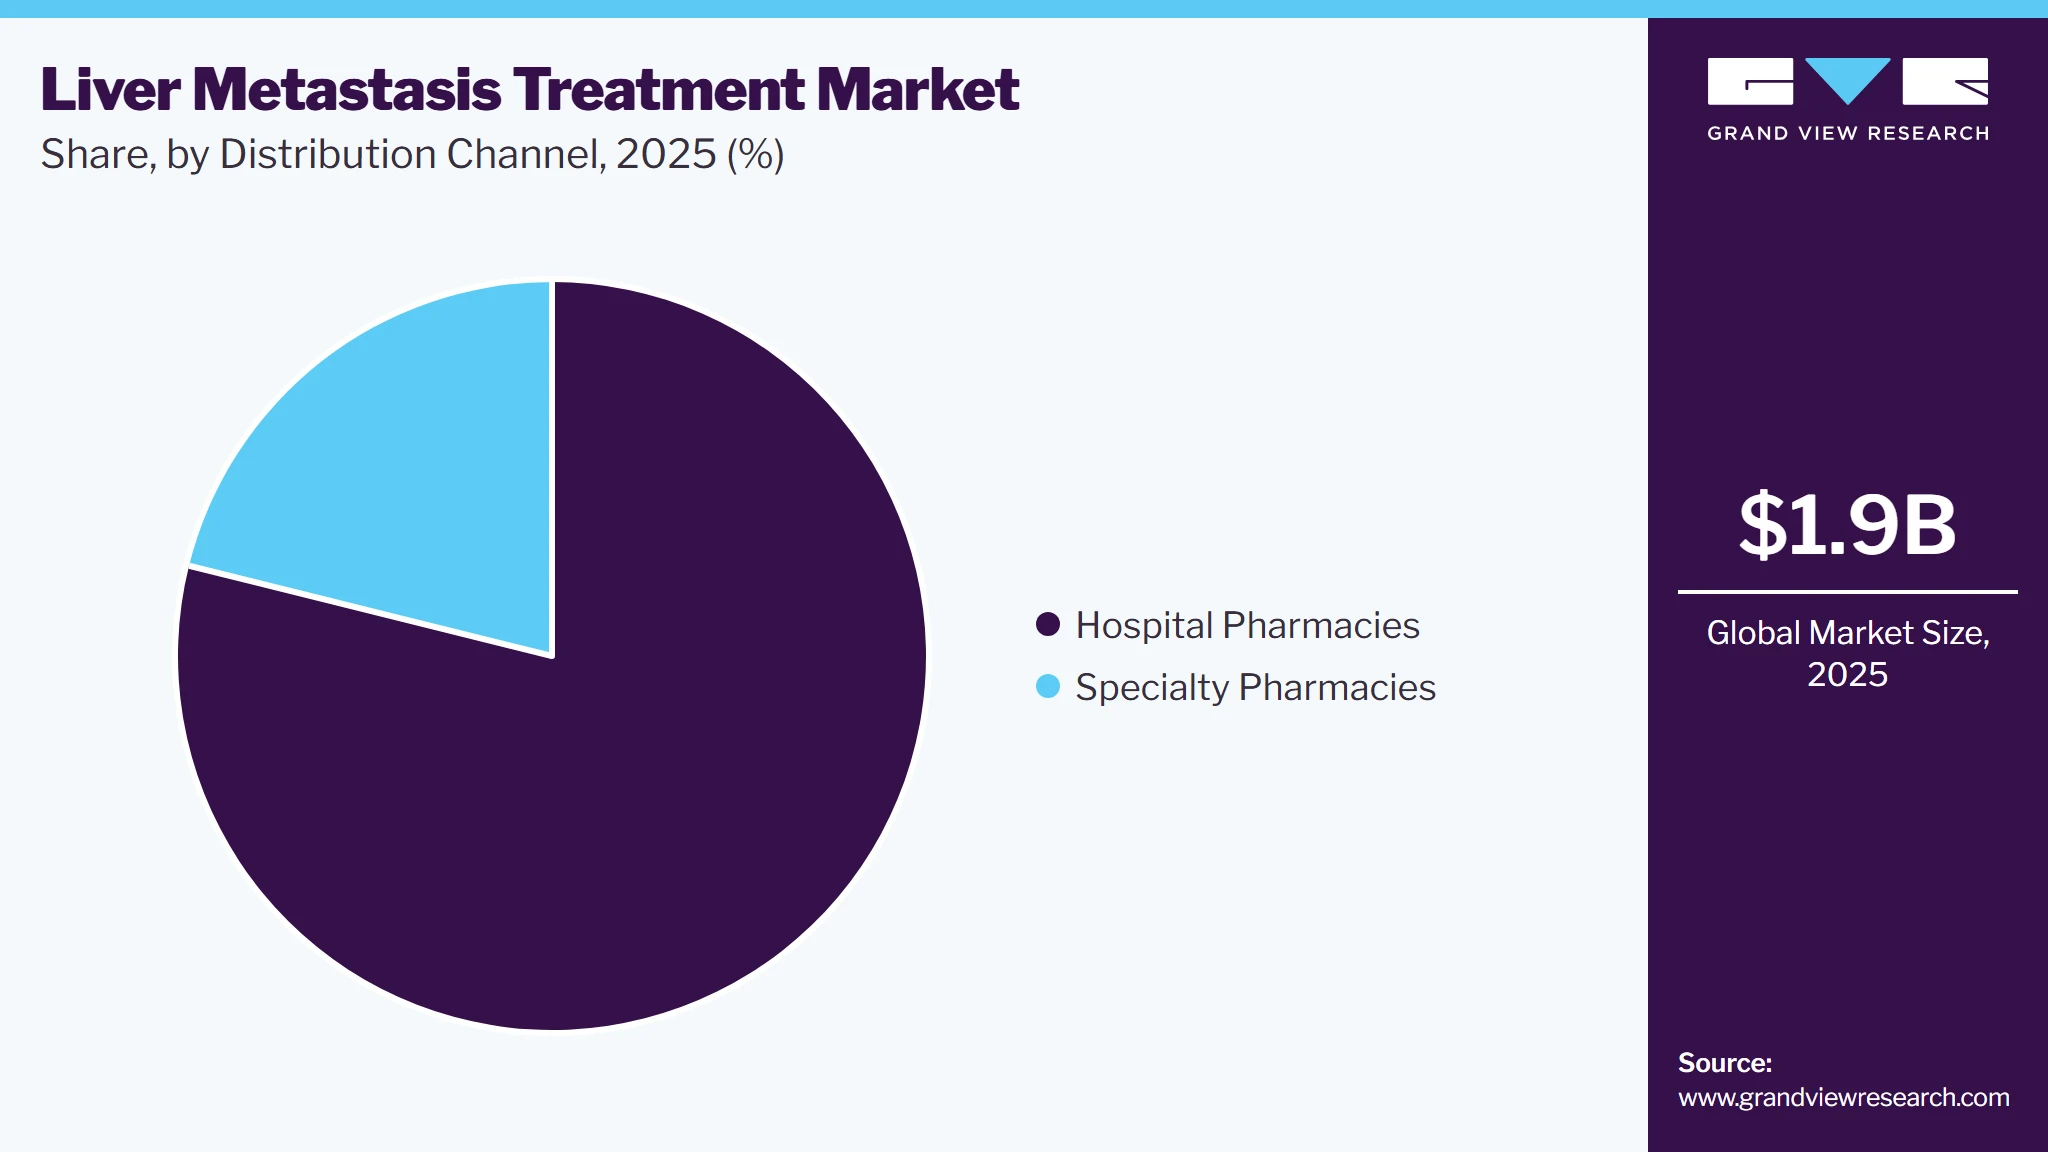
Based on distribution channel, the hospital pharmacies segment led the market with the largest revenue share of 78.9% in 2025. The dominance of this segment can be attributed to high hospitalization rate of patients suffering with liver metastases. In addition, chemotherapy is generally administered in combination with radiation therapy, which is administered in hospitals, which further contributes to the segment’s dominance. Specialty pharmacies are a key component in the distribution of oncology drugs. Specialty pharmacists have experience in dealing with products with special handling requirements and complex dosing schedules; hence are used as a major distribution medium for oncology drugs.
 To learn more about this report, Download Free Sample Report
Specialty pharmacy segment is projected to grow at the fastest CAGR during the forecast period. The segment growth is attributed to the rising prevalence of liver metastases. The increasing demand for specialized medications and services tailored to the unique needs of liver cancer patients, along with advancements in therapeutic options, drives the need for specialized pharmaceutical care. This trend is anticipated to fuel the significant growth of specialty pharmacy services, ensuring targeted and effective treatments for individuals dealing with liver metastases.
Regional Insights
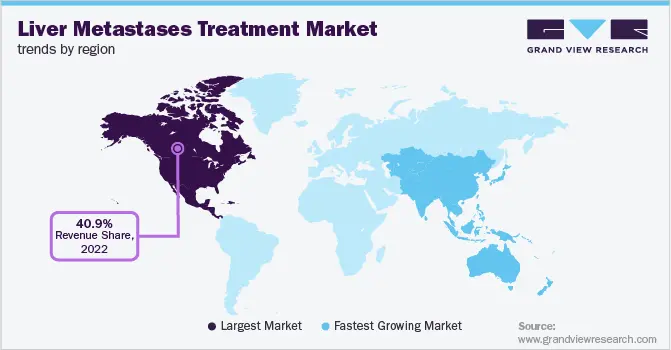
North America dominated the liver metastases treatment market and accounted for the largest revenue share of 41.2% in 2025. The region's leadership is supported by the high prevalence of colorectal, breast, pancreatic, and other cancers that frequently metastasize to the liver, creating sustained demand for advanced treatment options. Widespread adoption of targeted therapies and immunotherapies, supported by routine biomarker testing and molecular profiling, has strengthened the use of precision oncology across clinical practice. The region also benefits from well-established healthcare infrastructure, comprehensive reimbursement frameworks, and the presence of specialized oncology centers capable of delivering complex multidisciplinary care. Continuous investment in oncology research, increasing participation in clinical trials, and frequent regulatory approvals for innovative therapies further support market expansion. In addition, the strong presence of leading pharmaceutical companies and ongoing development of combination treatment strategies continue to reinforce North America's dominant position in the global liver metastases treatment market.
 To learn more about this report, Download Free Sample Report
U.S. Liver Metastases Treatment Market Trends
The U.S. held the largest share of the North American liver metastases treatment market in 2025, supported by its large oncology patient population, advanced healthcare infrastructure, and rapid adoption of innovative cancer therapies. The country continues to witness increasing utilization of targeted therapies and immune checkpoint inhibitors, particularly for patients with biomarker-positive metastatic colorectal and other solid tumors involving liver metastases. Broad access to molecular diagnostic testing, precision medicine programs, and specialized cancer centers enables clinicians to deliver personalized treatment strategies that improve patient management. Strong investments in oncology research, active participation in global clinical trials, and continuous regulatory approvals for new treatment options further strengthen market growth. In addition, favorable reimbursement policies, high healthcare expenditure, and the presence of major pharmaceutical companies contribute to widespread adoption of advanced therapies, reinforcing the U.S. as the leading market for liver metastases treatment in North America.
Asia Pacific Liver Metastases Treatment Market Trends
Asia Pacific is estimated to grow at the fastest CAGR during the forecast period. Asia Pacific is estimated to grow at the fastest CAGR during the forecast period due to the high target disease prevalence. Increasing healthcare expenditure and favorable insurance policies & coverage are further expected to aid market growth. Due to a lack of effective screening practices and access to healthcare in this region, cancers are mostly diagnosed at advanced stages. This represents a key growth opportunity for the market players.
Key Liver Metastases Treatment Market Company Insights
The industry is strategically competitive, and market players are involved in activities such as strategic collaborations, new product launches, acquisitions, technological advancements, and regional expansion.
-
In April 2023, Ablaze Pharmaceuticals announced to initiate clinical trials for a novel peptide drug focused on GPC3 for addressing liver cancer in China. This development stems from the company's licensing agreement for the first-of-its-kind drug candidate, established through a pre-existing collaboration with RayzeBio.
-
In March 2023, Newcastle researchers received £6 million (~USD 7.32 million) from Cancer Research UK for cancer studies. Grants include funds for medulloblastoma, bowel cancer, liver cancer immunotherapy, early melanoma treatment, and cancer screening programs.
-
In March 2023, USC Norris Comprehensive Cancer Center collaborated with Auransa on a phase 1 clinical trial for AU409, a novel drug targeting liver cancer and solid tumors.
Key Liver Metastases Treatment Companies
The following key companies have been profiled for this study on the liver metastases treatment market.
-
F. Hoffmann-La Roche Ltd.
-
AstraZeneca
-
Eli Lilly and Company
-
Bayer AG
-
Ono Pharmaceutical
-
Pfizer, Inc.
-
Bristol-Myers Squibb Company
-
Cadila Pharmaceuticals Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (F. Hoffmann-La Roche Ltd., AstraZeneca, Bayer AG, Eli Lilly and Company, Pfizer, Inc., Bristol-Myers Squibb Company)
- Focus on strengthening their presence in metastatic cancer treatment through the expansion of targeted therapy and immunotherapy portfolios, investment in biomarker-driven drug development, clinical trials for metastatic colorectal and breast cancers, strategic collaborations with diagnostic companies, and geographic expansion across major oncology markets.
- These companies also emphasize lifecycle management and label expansion strategies to increase the utilization of existing oncology products in advanced and metastatic disease settings.
- Strong oncology portfolios, extensive clinical development capabilities, established relationships with healthcare providers and cancer treatment centers, broad global commercialization networks, significant financial resources, and experience navigating complex regulatory pathways.
- Their ability to conduct large-scale clinical trials and support biomarker-driven treatment strategies strengthens their competitive position in metastatic cancer treatment.
- High research and development expenditures, increasing pricing pressure from healthcare systems and payers, exposure to patent expirations, complex global operations, and growing competition from biosimilars, next-generation targeted therapies, and emerging oncology-focused companies.
Emerging Players (Ono Pharmaceutical, Cadila Pharmaceuticals Ltd.)
- Focus on expanding oncology capabilities through selective product development, regional market expansion, licensing agreements, and partnerships aimed at strengthening their presence in cancer therapeutics.
- These companies often target specific therapeutic areas and seek opportunities to enhance market access through cost-effective development and commercialization strategies.
- Greater organizational flexibility, ability to respond quickly to evolving market opportunities, focused therapeutic expertise, competitive pricing strategies in selected markets, and the capacity to address niche opportunities within oncology treatment pathways.
- Limited global commercial infrastructure compared with larger pharmaceutical companies, lower brand recognition in international oncology markets, smaller research and development budgets, narrower product portfolios, and greater dependence on a limited number of therapeutic assets and strategic partnerships for growth.
Liver Metastases Treatment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.9 billion
Estimated market size in 2026
USD 2.0 billion
Projected market size by 2033
USD 3.9 billion
Growth rate
CAGR of 9.7% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Treatment type, primary cancer, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
F. Hoffmann-La Roche Ltd.; AstraZeneca; Bayer AG; Eli Lilly and Company; Ono Pharmaceutical; Pfizer, Inc.; Bristol-Myers Squibb Company; Cadila Pharmaceuticals Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Liver Metastases Treatment Market Report Segmentation
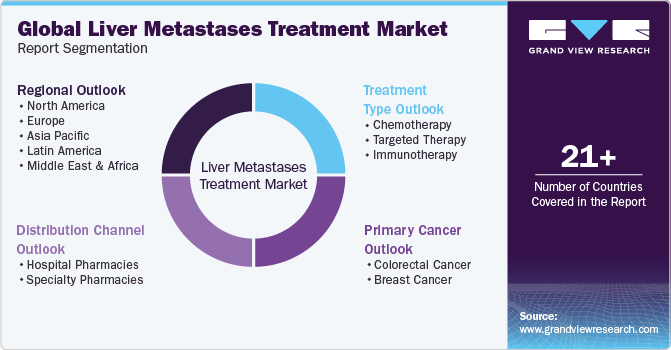
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segment from 2021 to 2033. For this report, Grand View Research has segmented the liver metastases treatment market report based on treatment type, primary cancer, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Treatment Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Chemotherapy
-
Targeted Therapy
-
Immunotherapy
-
-
Primary Cancer Outlook (Revenue, USD Million, 2021 - 2033)
-
Colorectal Cancer
-
Breast Cancer
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital Pharmacies
-
Specialty Pharmacies
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The liver metastases treatment market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each liver metastases treatment segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Treatment Type
Revenue capture definition
Chemotherapy
Revenue generated from chemotherapy drugs used for the treatment of liver metastases arising from primary cancers that have spread to the liver. This segment includes cytotoxic agents administered as monotherapy or combination regimens, including fluoropyrimidines, oxaliplatin-based therapies, irinotecan-based therapies, taxanes, anthracyclines, platinum compounds, and other conventional anticancer drugs. Revenue is attributed to this segment when chemotherapy represents the primary treatment modality prescribed for metastatic liver disease. This segment excludes targeted therapies, immunotherapies, surgical interventions, radiation therapies, and supportive care products.
Targeted Therapy
Revenue generated from targeted therapies used for the treatment of liver metastases. This segment includes monoclonal antibodies, tyrosine kinase inhibitors, anti-angiogenic agents, HER2-targeted therapies, EGFR inhibitors, BRAF inhibitors, and other molecularly targeted treatments designed to inhibit specific cancer-related pathways. Revenue is assigned to this segment when the therapeutic effect is primarily achieved through selective targeting of molecular or genetic abnormalities associated with metastatic tumors. This segment excludes conventional chemotherapy, immunotherapy, surgical procedures, and radiation-based treatments.
Immunotherapy
Revenue generated from immunotherapy products used for the treatment of liver metastases. This segment includes immune checkpoint inhibitors, PD-1 inhibitors, PD-L1 inhibitors, CTLA-4 inhibitors, adoptive cell therapies, cancer vaccines, and other immune-modulating treatments that enhance the body's immune response against metastatic cancer cells. Revenue is attributed to this segment when immunotherapy serves as the primary therapeutic mechanism irrespective of cancer origin or treatment setting. This segment excludes chemotherapy agents, targeted therapies, surgical interventions, and radiation therapies.
Segment - Primary Cancer
Revenue capture definition
Colorectal Cancer
Revenue generated from treatments used for the management of liver metastases originating from colorectal cancer. This segment includes all therapeutic modalities prescribed for patients whose primary malignancy originates in the colon or rectum and subsequently metastasizes to the liver. Revenue is classified exclusively based on colorectal cancer as the primary tumor source regardless of treatment type, biomarker status, disease stage, or line of therapy. This segment excludes liver metastases originating from breast cancer and all other primary malignancies.
Breast Cancer
Revenue generated from treatments used for the management of liver metastases originating from breast cancer. This segment includes all therapeutic modalities prescribed for patients whose primary malignancy originates in breast tissue and subsequently spreads to the liver. Revenue is assigned exclusively based on breast cancer as the primary cancer origin irrespective of treatment approach, receptor status, biomarker profile, or disease stage. This segment excludes liver metastases arising from colorectal cancer and other primary tumor types.
Others
Revenue generated from treatments used for the management of liver metastases originating from all primary cancers not included under Colorectal Cancer or Breast Cancer. This segment includes liver metastases arising from pancreatic cancer, gastric cancer, lung cancer, melanoma, ovarian cancer, neuroendocrine tumors, renal cell carcinoma, prostate cancer, esophageal cancer, and other solid tumors with metastatic spread to the liver. Revenue is allocated to this segment only when the primary tumor origin does not belong to the predefined categories above.
Segment - Distribution Channel
Revenue capture definition
Hospital Pharmacies
Revenue generated from liver metastases treatment products dispensed, administered, and billed through hospital-based pharmacies and hospital-affiliated oncology departments. This segment includes therapies procured by hospitals for inpatient care, outpatient infusion centers, cancer treatment units, oncology wards, and multidisciplinary cancer centers. Revenue is attributed to this segment when treatment products are distributed through hospital pharmacy procurement and dispensing channels. This segment excludes specialty pharmacy distribution and other alternative treatment delivery channels.
Specialty Pharmacies
Revenue generated from liver metastases treatment products distributed through specialty pharmacies that manage high-cost, complex, and specialty oncology therapies. This segment includes products dispensed through specialty pharmacy networks that provide patient support programs, reimbursement assistance, treatment adherence monitoring, therapy management services, and coordinated product delivery. Revenue is assigned to this segment when the treatment product is supplied through a specialty pharmacy distribution model. This segment excludes hospital pharmacy dispensing channels.
Others
Revenue generated from all distribution channels not included under Hospital Pharmacies or Specialty Pharmacies. This segment includes physician office dispensing, independent oncology clinics, ambulatory care centers, academic medical institutions, government procurement programs, cancer specialty centers, and other alternative treatment distribution pathways. Revenue is allocated to this segment only when it is not attributable to the predefined distribution channels above.
Estimation Model
 To learn more about this report, Download Free Sample Report
The study incorporated a combination of primary and secondary research methodologies to evaluate the global liver metastases treatment market. Secondary research involved the review of company annual reports, investor presentations, regulatory filings, clinical trial databases, oncology treatment guidelines, cancer registry data, scientific publications, industry journals, and publicly available information from pharmaceutical manufacturers, healthcare organizations, and government agencies. Primary research included interviews with oncologists, hepatobiliary surgeons, cancer researchers, hospital pharmacists, healthcare providers, pharmaceutical executives, and key opinion leaders to validate treatment patterns, therapy adoption trends, competitive developments, and future growth opportunities. Insights gathered from these sources were used to assess the evolving treatment landscape, market penetration of existing therapies, and the impact of emerging treatment modalities across major geographic regions.
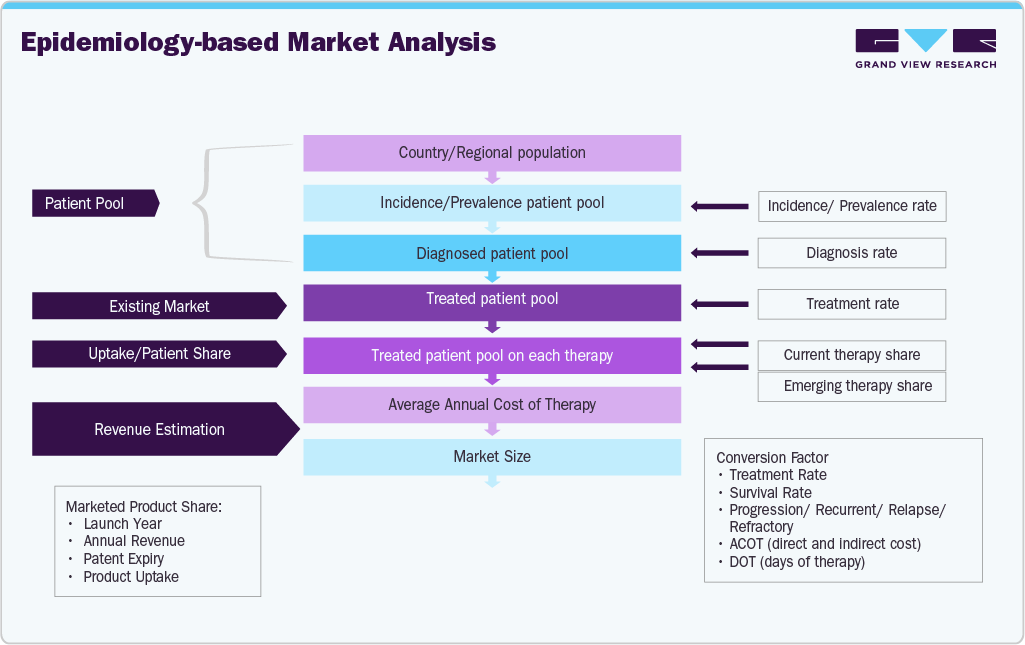
Market estimates were primarily developed using an epidemiology-based market analysis approach. The assessment began with the evaluation of incidence and prevalence rates of primary cancers commonly associated with liver metastases, including colorectal cancer, breast cancer, and other metastatic solid tumors, to establish the addressable patient population. Diagnosis rates, treatment eligibility rates, and treatment adoption rates were applied to determine the treated patient pool. Patients were subsequently segmented by treatment type, including chemotherapy, targeted therapy, and immunotherapy. Revenue estimates were generated by combining therapy-specific patient volumes with average annual treatment costs, treatment duration, dosing patterns, and product utilization rates. The resulting market values were validated through top-down and bottom-up analyses using company revenues, product-level sales data, treatment uptake trends, and competitive benchmarking to ensure accuracy and consistency of market forecasts.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Advanced Therapy Adoption Analysis
Assessment of adoption trends across systemic therapies, including chemotherapy, targeted therapies, immunotherapies, hepatic artery infusion therapies, and emerging precision oncology approaches used in the treatment of liver metastases. Analysis includes prescribing patterns, treatment sequencing, multidisciplinary care models, and utilization trends across major oncology centers and healthcare markets.
Helps identify high growth treatment segments, evolving treatment preferences, and commercialization opportunities across the liver metastases treatment landscape.
Treatment Pathway and Patient Journey Assessment
Analysis of patient progression from primary cancer diagnosis to liver metastases detection, treatment selection, surgical intervention, locoregional therapies, systemic treatment, and follow up management. Includes evaluation of referral patterns, multidisciplinary decision making, treatment eligibility criteria, and factors influencing therapeutic choices.
Supports identification of unmet clinical needs, patient retention opportunities, and market expansion strategies across different stages of liver metastases management.
Diagnostic and Early Detection Landscape Evaluation
Evaluation of diagnostic technologies, imaging modalities, liquid biopsy approaches, biomarker testing, pathology workflows, and surveillance strategies used for early identification and monitoring of liver metastases. Assessment includes factors influencing diagnosis timing, treatment planning, and patient stratification.
Tracks opportunities related to earlier disease detection, improved treatment intervention rates, enhanced patient outcomes, and expansion of the addressable treatment population.
Pipeline and Innovation Landscape Assessment
Assessment of emerging therapies, novel mechanisms of action, clinical development activity, combination treatment strategies, minimally invasive interventions, radiopharmaceuticals, cell therapies, and advancements in precision oncology relevant to liver metastases treatment.
Identifies future growth opportunities, competitive differentiation factors, and innovation driven areas expected to influence market evolution.
Competitive Benchmarking and Portfolio Analysis
Comparative assessment of approved therapies, clinical evidence, treatment outcomes, market positioning, pricing strategies, reimbursement access, pipeline strength, and strategic initiatives of leading market participants involved in liver metastases treatment.
Supports competitive intelligence, partnership evaluation, product positioning, investment planning, and strategic decision making within the liver metastases treatment market.
Frequently Asked Questions About This Report
Some key players in the market include F. Hoffmann-La Roche Ltd.; AstraZeneca; Eli Lilly and Company; Bayer AG; Ono Pharmaceutical; Pfizer, Inc.; Bristol-Myers Squibb Company and Cadila Pharmaceuticals Ltd amongst others.
The hospital pharmacies segment led with a 78.9% revenue share in 2025, while the specialty pharmacies segment is the fastest-growing.
Asia Pacific is the fastest-growing region over the forecast period.
The targeted therapy segment led with a 56.1% revenue share in 2025.
Key factors that are driving the liver metastasis treatment market growth include rising incidence of target disease and increasing number of product approvals.
North America dominated with a 41.2% revenue share in 2025.
The colorectal cancer segment led with a 57.4% revenue share in 2025, while the breast cancer segment is the fastest-growing.
The global liver metastases treatment market size was valued at USD 1.9 billion in 2025 and is estimated at USD 2.0 billion for 2026.
The global liver metastases treatment market is expected to grow at a CAGR of 9.7% from 2026 to 2033, reaching USD 3.9 billion by 2033.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


