
- Home
- »
- Plastics, Polymers & Resins
- »
-
Long Fiber Thermoplastics Market Size & Share Report, 2030GVR Report cover

Long Fiber Thermoplastics Market (2022 - 2030) Size, Share & Trends Analysis Report By Resin Type (Polypropylene, Polyamide, Polyether Ether Ketone), By Fiber, By Manufacturing Process, By End-use, By Region, And Segment Forecasts
Market Size, 2021
$4.1BMarket Estimate, 2026
$4.4BMarket Forecast, 2030
$9.3BCAGR, 2022–2030
9.7%Long Fiber Thermoplastics Market Summary
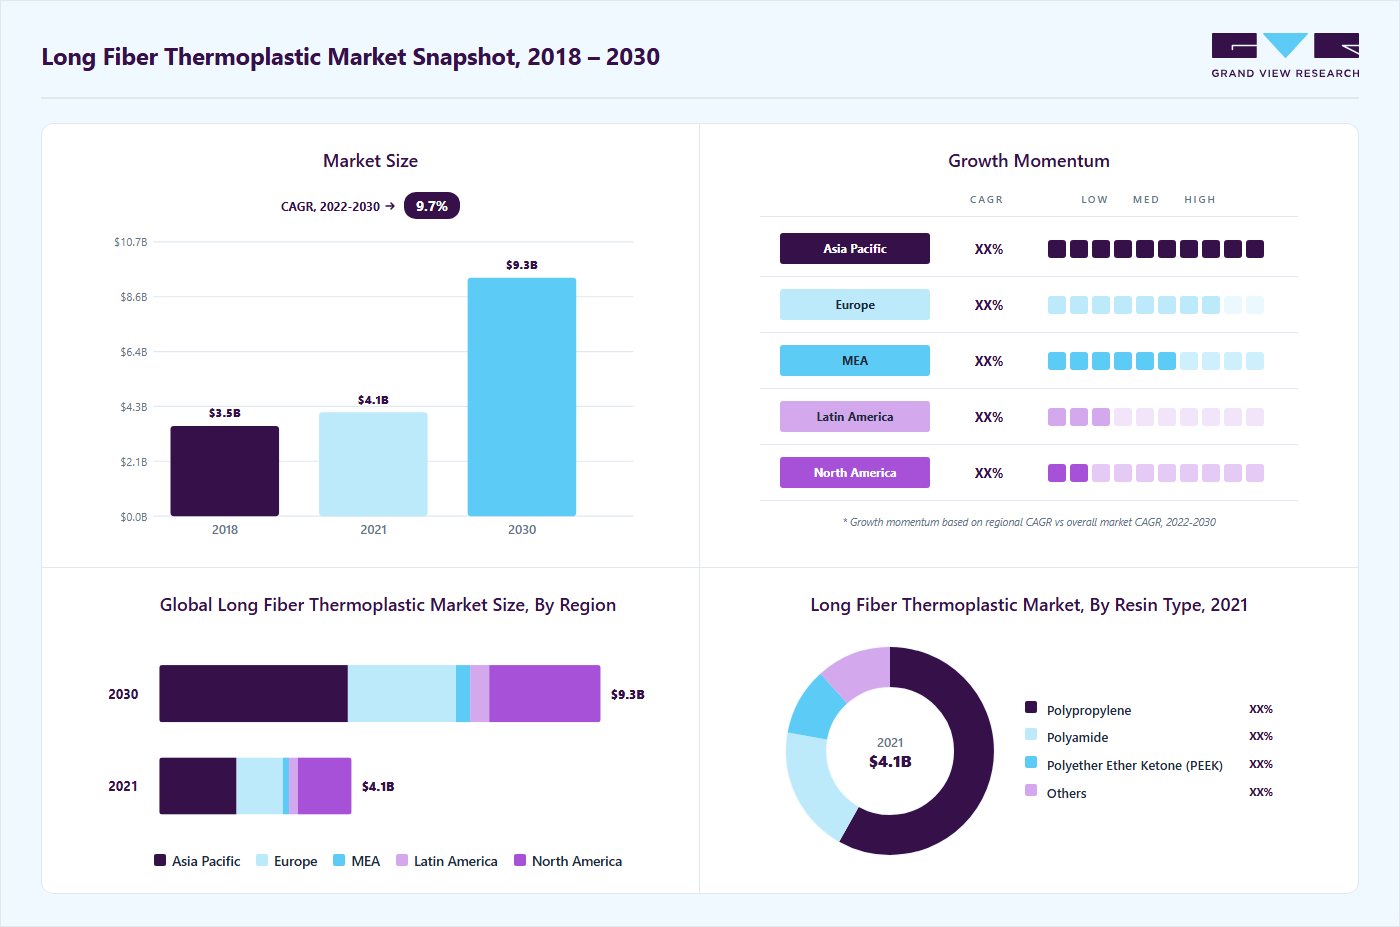
The global long-fiber thermoplastics market size was estimated at USD 4.06 billion in 2021 and is projected to reach USD 9.3 billion by 2030, growing at a CAGR of 9.7% from 2022 to 2030. The market is anticipated to be driven by increasing demand for long-fiber thermoplastics in the automotive industry.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- Asia Pacific accounted for the largest revenue share of 40.2% in 2021.
- North America is expected to account for a CAGR of 8.5% during the forecast period.
- By resin type, the polypropylene segment accounted for the largest revenue share of 58.0% in 2021.
- By fiber, the glass fiber segment accounted for the largest revenue share of 50.3% in 2021.
- By manufacturing process, the injection molding segment accounted for the largest revenue share of 45.0% in 2021.
Market Size & Forecast
- 2021 Market Size: USD 4.06 Billion
- 2030 Projected Market Size: USD 9.3 Billion
- CAGR (2022-2030): 9.7%
- Asia Pacific: Largest market in 2021
Prism AI by Grand View Research Free to tryAsk a question about the long fiber thermoplastics marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
In addition, numerous benefits of long fiber thermoplastics such as high strength, durability, toughness, fatigue endurance, and lightweight are making them better alternatives to metal and conventional thermoplastics in the end-use industries. Growing awareness regarding various characteristics of fiber-reinforced thermoplastics resins like lightweight, durability, flexibility, toughness, and thermal resistance is expected to boost the demand for various types of long fiber thermoplastics in coming years.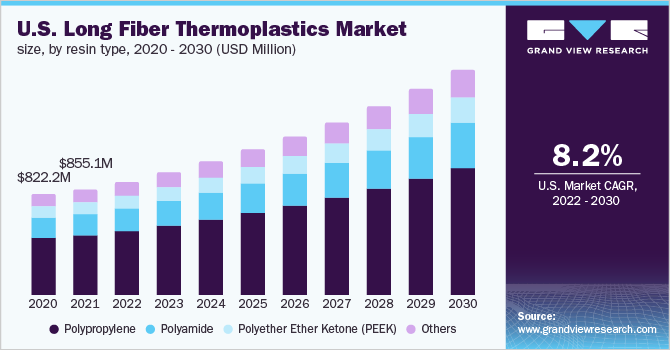 To learn more about this report, Download Free Sample Report
The ongoing R&D, technological developments in the field of long fiber thermoplastics, widespread adoption, and need for thermoplastics composites across various sectors are expected to drive the market's growth in the coming years. In June 2021, Zoltek Companies, Inc. (a carbon fiber manufacturer), expanded carbon fiber production in its Mexico Facility. The new facility can now produce carbon fiber up to 13,000 MT annually.
The government's policies to increase biodegradable plastics & emphasis on a sustainable future have resulted in the widespread use and demand for bio-based long-fiber thermoplastic. In November 2021, Arkema announced the construction of a new bio-based polyamide 11 powders (Rilsan polyamide 11 powders) plant. The COVID-19 pandemic had a negative impact on the long-fiber thermoplastics market. The pandemic led to the sealing of national borders and the temporary shutting down of numerous industries in 2020.
Before the pandemic, numerous countries were dependent on China for raw material supply. In 2020, restrictions imposed by the government on transportation and a lack of raw materials supply from China resulted in less production of long-fiber thermoplastics. In addition, the decrease in the production of automobiles owing to the reduced workforce and lack of demand from consumers resulted in the low demand for long-fiber thermoplastics in 2020.
Market Dynamics
The long fiber thermoplastics market is driven by increasing demand for lightweight engineering materials that deliver superior mechanical strength, impact resistance, and dimensional stability across automotive, aerospace, consumer goods, and industrial applications. Long fiber thermoplastics (LFTs) provide enhanced stiffness and durability compared with conventional short-fiber-reinforced plastics, while offering improved processing efficiency and recyclability relative to thermoset composites. Manufacturers are increasingly adopting LFT materials to support lightweighting initiatives and improve structural performance.
Automotive applications remain the primary growth contributor to the market. LFTs are extensively utilized in front-end modules, instrument panels, seat structures, underbody systems, and battery housings because they reduce vehicle weight while maintaining high structural integrity and impact performance. The transition toward electric vehicles is further accelerating demand for lightweight composite materials that improve energy efficiency and extend driving range. Automotive manufacturers are also prioritizing recyclable, process-efficient materials, supporting the wider adoption of long-fiber thermoplastic technologies.
One of the key restraints affecting the long fiber thermoplastics market is the relatively high cost of reinforced composite materials and specialized processing technologies. The production of LFT compounds requires advanced compounding systems, continuous fiber integration processes, and specialty polymer feedstocks, resulting in higher manufacturing costs than those of conventional thermoplastics. These elevated costs can limit adoption in highly price-sensitive applications and industries.
Resin Type Insights
The polypropylene segment accounted for the largest revenue share of 58.0% in 2021 and is expected to retain its dominance during the forecast period. Polypropylene-based thermoplastics are extensively used in the automotive, textile, packaging, and construction industry. Polypropylene-based long-fiber thermoplastics are very cost-effective compared to polyamide and polyether ether ketone. Thus, their penetration is increasing in the automotive and construction industry.
The polyamide segment is expected to witness a CAGR of 10.1% during the forecast period. Polyamide-based LFTs offer features such as durability, high toughness, and high strength which makes them a good option for automotive manufacturers. Polyamide-based LFTs are inexpensive compared to polyether ether ketone. Numerous players operating in the market such as Evonik Industries AG, LANXESS, and BASF SE are developing and offering a range of polyamide-based composites for the automotive, aerospace, and construction industries. For instance, in September 2019, Evonik Industries AG developed a new polyamide fiber named P84 HT. The new product offers high flexibility and improved mechanical stability at continuously high operating temperatures.
Fiber Insights
The glass fiber segment accounted for the largest revenue share of 50.3% in 2021 and is expected to retain its dominance during the forecast period. Glass fibers are extensively used in the making of long fiber thermoplastics as they are readily available and cost-effective. Long glass fibers improve the mechanical properties of any thermoplastic polymers. Glass fibers are almost ten times less expensive than carbon fibers. According to a 2020 report by the U.S. Commercial Service, glass-reinforced plastics are the most commonly used composite material in Europe.
The carbon fiber segment is expected to witness a CAGR of 10.5% over the forecast period from 2022-2030. Long carbon-reinforced thermoplastics composites are easier to process and more convenient for recycling. Long carbon fiber composites are increasingly being used in the aerospace and sports goods industry. In May 2021, TEIJIN LIMITED launched two carbon fiber intermediate materials brands Tenax BM and Tenax PW for sports applications.
Manufacturing Process Insights
The injection molding segment accounted for the largest revenue share of 45.0% in 2021 and is expected to retain its dominance during the forecast period. The injection molding process has several benefits over other processes, it is very efficient, compatible with a wide range of materials, can be used for large volumes to scale up production, and offers high repeatability and reliability.
The D-LFT segment is expected to account for the fastest CAGR of 10.2% during the forecast period 2022 - 2030. D-LFT is also known as direct roving or single-end roving process, it is very efficient and cost-effective as it avoids the need for semi-finished products manufactured by the material supplier. This process is extensively used to make polypropylene and polyamide-based long-fiber thermoplastics.
End-use Insights
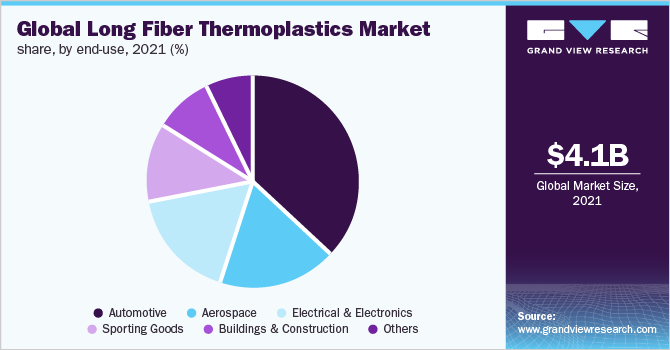
The automotive segment accounted for the largest market share of 37.3% in 2021, in terms of revenue and is expected to retain its position in the market over the forecast period. This can be attributed to the increasing application of fiber-reinforced thermoplastics composites in the automotive industry. Long fiber thermoplastics offer several properties such as stiffness, high strength, lightweight, toughness, and durability. LFTs are used in various parts of automobiles such as bumper moldings, door modules, instrument panel carriers, seat pans, bumper beams, and front-end modules, among others.
 To learn more about this report, Download Free Sample Report
The aerospace segment is expected to account for a CAGR of 10.0% over the forecast period 2022-2030. The demand for long-fiber thermoplastics is increasing in the aerospace industry owing to their lightweight and high strength. Lightweight materials are the primary requirement among aircraft manufacturers as they help in reducing the overall weight of the aircraft and improve fuel efficiency. Carbon fiber thermoplastics are extensively used in the aerospace industry. In May 2022, Solvay, a renowned specialty chemical manufacturer launched a new composite material SolvaLite 714 Prepregs, made of carbon fiber and woven fabric products.
Regional Insights
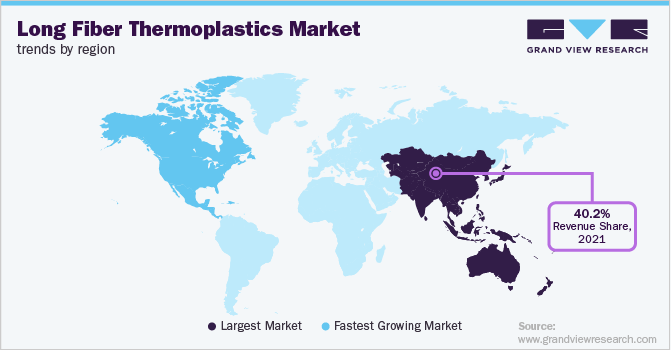
Asia Pacific accounted for the largest revenue share of 40.2% in 2021 and is anticipated to account for the fastest CAGR of 10.4% during the forecast period. The region is expected to dominate owing to the large supply chain and availability of raw materials. In addition, the increasing production of electric vehicles (EVs) in the region is further increasing the demand for long-fiber thermoplastics. China is the largest manufacturer and supplier of Electric Vehicles. According to International Energy Agency (IEA), in 2021 sales of EVs were the highest in China at 3.3 million.
 To learn more about this report, Download Free Sample Report
North America is expected to account for a CAGR of 8.5% during the forecast period. Penetration of long fiber thermoplastics is high in the automotive, aerospace, and electrical & electronics industry. The strong presence of these industries in the region is one of the key factors for the growth of long-fiber thermoplastics.
Key Companies & Market Share Insights
The long fiber thermoplastics market is highly competitive as it features various global and regional market players. The world’s leading companies are undertaking partnerships, collaborations, acquisitions, mergers, and agreements as strategies to withstand the intense competition and increase their market share. Moreover, long-fiber thermoplastics manufacturers are spending extensively on research and development activities to develop advanced products and integrate new technologies and characteristics to lead a sustainable future. For instance, in January 2020, BASF SE acquired the polyamide business of Solvay. This acquisition broadened BASF’s engineering plastics business with innovative products such as Technyl. Some of the prominent players in the global long-fiber thermoplastics market include:
-
SABIC
-
RTP Company
-
JNC Corporation
-
Avient Corporation
-
Celanese Corporation
-
LANXESS
-
Solvay
-
Daicel Corporation
-
Kingfa SCI. & TECH. CO., LTD.
-
SGL Carbon
-
Asahi Kasei Corporation
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weakness
Mature Players: SABIC; Avient Corporation; Celanese Corporation
- Broad portfolios of reinforced thermoplastics and specialty composite materials for automotive, industrial, consumer goods, and electrical applications.
- Significant investment in lightweight composite technologies, recyclable materials, and advanced polymer compounding systems.
- Integrated manufacturing infrastructure and global distribution networks supporting large-scale industrial demand.
- Strong polymer engineering expertise and advanced composite formulation capabilities.
- Established global manufacturing footprint and diversified end-use penetration.
- Large-scale production capabilities improve operational efficiency and supply reliability.
- High exposure to engineering polymer and reinforcement fiber price volatility.
- Significant capital investment requirements for advanced composite processing technologies.
- Dependence on automotive and industrial manufacturing cycles affects demand stability.
Emerging Players: RTP Company; JNC Corporation; Kingfa SCI. & TECH. CO.
- Focus on customized long fiber thermoplastic compounds and application-specific reinforced composite solutions.
- Flexible manufacturing strategies supporting regional automotive, industrial, and specialty engineering applications.
- Expansion into carbon fiber reinforced thermoplastics, specialty industrial components, and advanced lightweight systems.
- Greater flexibility in customized composite material development and specialty engineering applications.
- Strong specialization in reinforced thermoplastic compounding and advanced fiber technologies.
- Faster responsiveness to evolving customer performance requirements and niche market opportunities.
- Smaller global manufacturing scale compared with multinational polymer producers.
- Limited economies of scale in reinforcement fiber procurement and composite processing operations.
- Higher dependence on selected regional markets and specialized industrial sectors.
Long Fiber Thermoplastics Market Report Scope
Report Attribute
Details
Market size value in 2022
USD 4.36 billion
Revenue forecast in 2030
USD 9.3 billion
Growth rate
CAGR of 9.7% from 2022 to 2030
Base year for estimation
2021
Historical data
2018 - 2020
Forecast period
2022 - 2030
Quantitative units
Volume in kilotons, revenue in USD million, and CAGR from 2022 to 2030
Report coverage
Revenue forecast, volume forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Resin type, fiber, manufacturing process, end-use, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; Italy; U.K.; France; China; India; Japan; Australia; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
SABIC; RTP Company; JNC Corporation; Avient Corporation; Celanese Corporation; LANXESS; Solvay; Daicel Corporation; Kingfa SCI. & TECH. CO., LTD.; SGL Carbon; Asahi Kasei Corporation
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional, and segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Long Fiber Thermoplastics Market Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2018 to 2030. For this study, Grand View Research has segmented the global long fiber thermoplastics market report based on resin type, fiber, manufacturing process, end-use, and region:
-
Resin Type Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2030)
-
Polypropylene
-
Polyamide
-
Polyether Ether Ketone (PEEK)
-
Others
-
-
Fiber Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2030)
-
Glass
-
Carbon
-
Others
-
-
Manufacturing Process Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2030)
-
Injection Molding
-
Pultrusion
-
D-LFT
-
Others
-
-
End-use Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2030)
-
Automotive
-
Aerospace
-
Electrical & Electronics
-
Buildings & Construction
-
Sporting Goods
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2018 - 2030)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
U.K.
-
Germany
-
France
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Delivered detailed regional analysis across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa. The assessment evaluated automotive manufacturing activity, industrial automation growth, electric vehicle production trends, aerospace demand, infrastructure development, and regional consumption patterns that influence the adoption of long fiber thermoplastics.
Supported region-specific expansion and investment planning. Identified high-growth manufacturing hubs and emerging composite material demand centers. Improved understanding of regional supply-demand dynamics and lightweight material adoption trends. Enabled optimized production, distribution, and commercialization strategies.
Trade Assessment
Conducted trade assessment covering global export-import flows of reinforced thermoplastics, engineering polymers, glass fiber compounds, carbon fiber materials, and specialty composite systems. The study analyzed regional manufacturing concentration, supply chain dependencies, tariff structures, logistics patterns, reinforcement fiber sourcing networks, and geopolitical influences affecting international market competitiveness.
Supported procurement optimization and supply chain risk management. Identified strategic sourcing regions and major global trade corridors within the composite materials value chain. Improved understanding of import dependence, export competitiveness, and supply risks for reinforcement materials. Enabled proactive planning against trade disruptions, raw material volatility, and logistics-related challenges.
Cross-Segmentation
Delivered cross-segment analysis across reinforcement type, resin system, application, end-use industry, processing technology, and regional demand trends. The study evaluated interactions among automotive lightweighting systems, industrial machinery, aerospace structures, consumer goods, electrical applications, and recyclable composite technologies based on long fiber thermoplastics.
Improved understanding of high-growth application intersections and premium-value composite material opportunities. Supported product portfolio optimization and targeted commercialization planning. Enabled identification of emerging demand combinations and advanced lightweight engineering opportunities across transportation and industrial sectors.
Frequently Asked Questions About This Report
The global long fiber thermoplastics market size was estimated at USD 4.06 billion in 2021 and is expected to reach USD 4,367.9 million in 2022
The global long fiber thermoplastics market, in terms of revenue, is expected to grow at a compound annual growth rate of 9.7% from 2022 to 2030 to reach USD 9.3 billion by 2030
Asia Pacific accounted for the largest share of 40.2% in 2021 owing to the increasing demand for lightweight with high-strength materials in the automotive industry.
Some of the key players operating in the long fiber thermoplastics market include B SABIC, RTP Company, JNC Corporation, Avient Corporation, Celanese Corporation, LANXESS, Solvay, Daicel Corporation, Kingfa SCI. & TECH. CO., LTD., SGL Carbon, Asahi Kasei Corporation.
The key factors driving the long fiber thermoplastics market include increasing demand for long fiber thermoplastics in the automotive industry. In addition, numerous benefits of long fiber thermoplastics such as high strength, durability, toughness, fatigue endurance, and lightweight are making them better alternatives to metal and conventional thermoplastics in the end-use industries.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


