
- Home
- »
- Medical Devices
- »
-
Magnetoencephalography Market Size, Share Report, 2033GVR Report cover

Magnetoencephalography Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (Clinical, Research), By End Use (Hospitals, Imaging Centers), By Region (North America, Europe, Asia Pacific, Latin America, MEA), And Segment Forecasts
Market Size, 2025
$325.5MMarket Estimate, 2026
$345.6MMarket Forecast, 2033
$569.7MCAGR, 2026–2033
7.4%Magnetoencephalography Market Summary
The global magnetoencephalography market size was valued at USD 325.5 million in 2025 and is projected to grow from USD 345.6 million in 2026 to USD 569.7 million by 2033, at a CAGR of 7.4% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 42.1% in 2025. One of the primary reasons likely to drive market expansion during the forecast period is increasing technological improvements in magnetoencephalography (MEG) systems and their growing adoption, as well as the rising prevalence of neurological disorders causing death and disability worldwide.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By application: Clinical segment led the market with the largest revenue share of 58.1% in 2025.
- By end use: Hospitals segment led the market with the largest revenue share of 35.9% in 2025.
Regional Highlights
- Largest regional market: North America (42.1% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 325.5 Million
- Estimated market size in 2026: USD 345.6 Million
- Projected market size by 2033: USD 569.7 Million
- CAGR (2026-2033): 7.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Furthermore, neurodegenerative diseases primarily affect people in their middle to late years of life, and their prevalence is predicted to rise as the population ages. According to the Harvard Neurodiscovery Center, one in every five Americans will be over the age of 65 by 2030. If left untreated, more than 12 million Americans will suffer from neurodegenerative disorders in the next 30 years.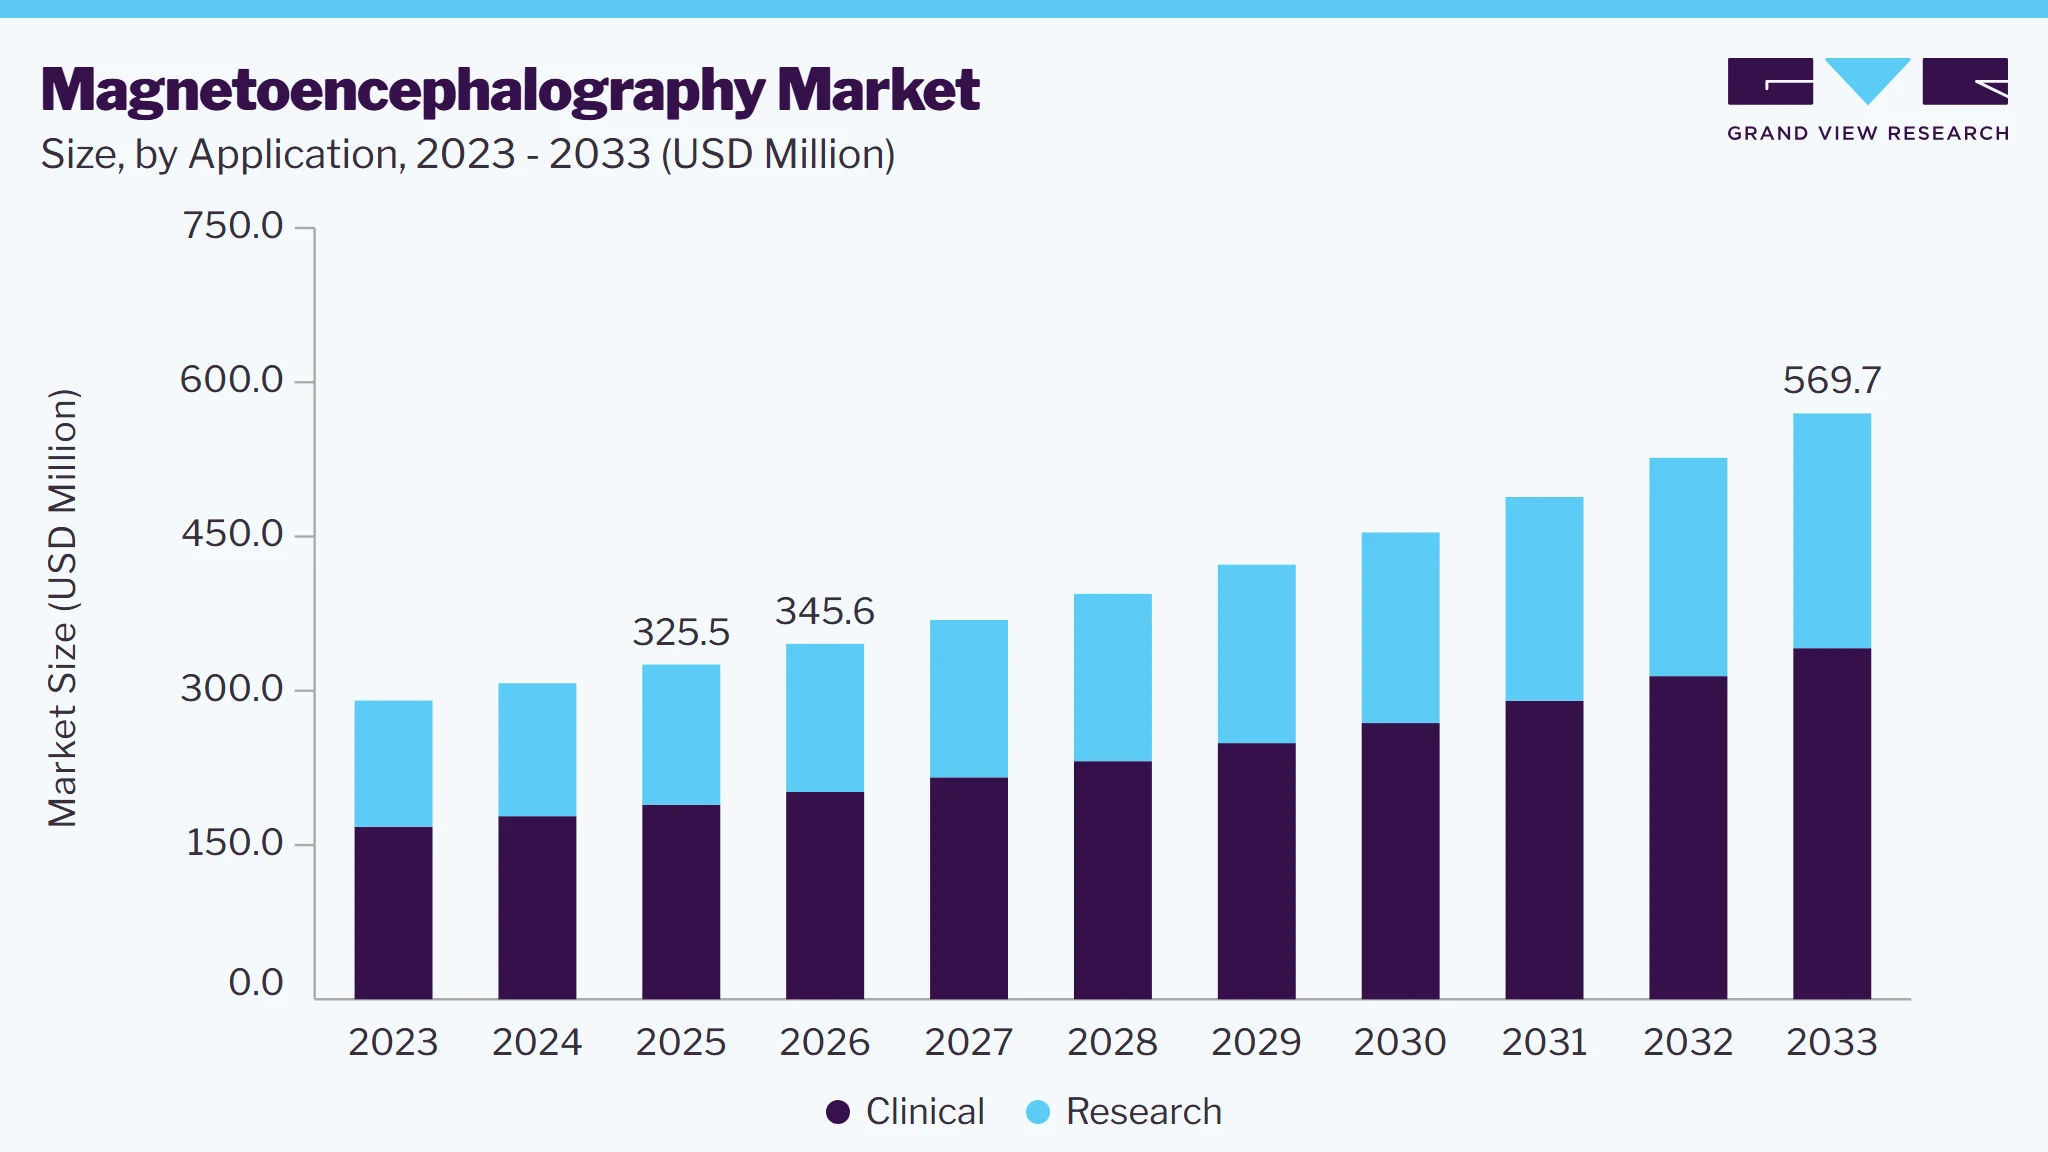 To learn more about this report, Download Free Sample Report
MEG scanners have proved to be one of the most effective devices for investigating epilepsy, brain tumors, emotions, pain perception, and other neurological problems. MEG takes advantage of the fact that neuromagnetic impulses pass through the skull and scalp without being distorted. While technology has been around for decades, recent advances in computer power and hardware have generated growing interest in scanners. There are an estimated 200 MEG scanners in use worldwide, and the number is expanding. For instance, in January 2022, MEGIN announced the sale of its TRIUXTM neo, magnetoencephalography (MEG) system to the Norman Fixel Institute for Neurological Diseases at the University of Florida Health (UF Health).
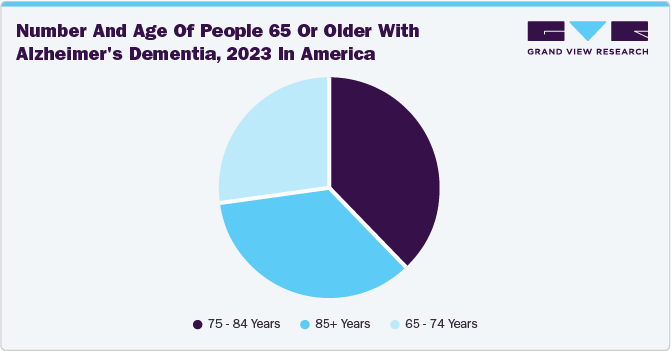
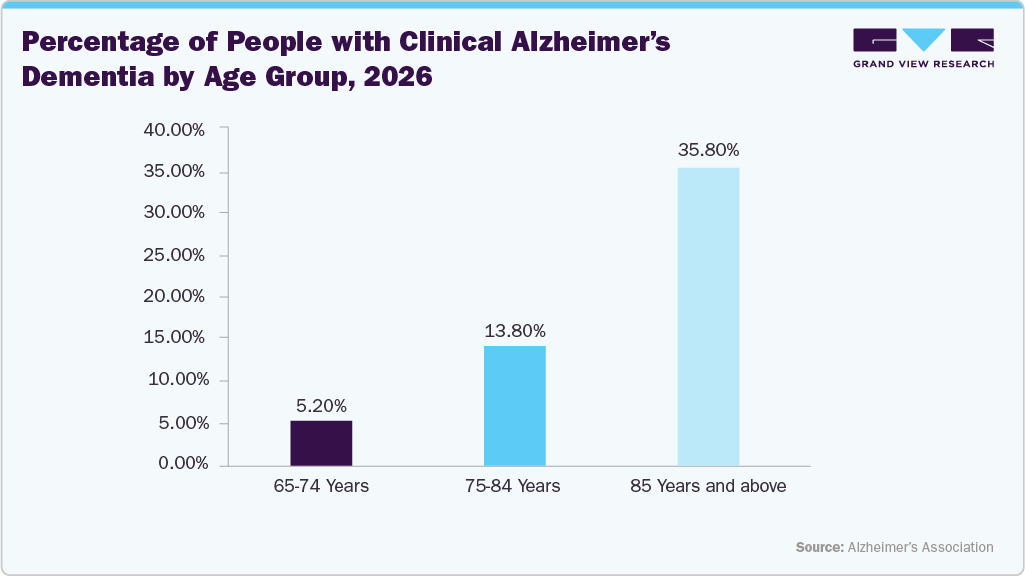
The increasing geriatric population also significantly contributes to market growth. As people age, they become more susceptible to a range of neurological disorders such as Alzheimer's disease, Parkinson's disease, and various forms of dementia. These conditions not only affect the quality of life of the elderly but also pose significant challenges to healthcare systems worldwide. Consequently, there is a rising demand for effective treatments, medications, and therapeutic interventions tailored to manage and alleviate these neurological conditions in older adults. According to the data published by Alzheimer's Association, in 2023, about 6.7 million Americans aged 65 and above are experiencing Alzheimer's dementia.
 To learn more about this report, Download Free Sample Report
Furthermore, one of the major reasons likely to boost the market for magnetoencephalography scanners throughout the forecast period is the growing research and development activities. For instance, the HSE Institute for Cognitive Neuroscience has presented a new method for processing magnetoencephalography (MEG) data that allows for more precise identification of cortical activation zones. The method can be used to diagnose a wide spectrum of neurological disorders and to prepare patients for brain surgery in both basic research and clinical practice.
Government bodies undertaking initiatives to support research activities are also expected to contribute to market growth. For instance, in August 2023, the National Institutes of Health (NIH) has allocated USD 2 million to a research center at UC San Diego within the Qualcomm Institute (QI) to purchase magnetoencephalography (MEG) system. This technology will be used to study the magnetic fields produced by the human brain. The initiative will help to advance the understanding and treatment of various conditions, including autism spectrum disorder, concussions, epilepsy, schizophrenia, post-traumatic stress disorder, brain tumors, and Alzheimer’s disease. The investment will be used to procure MEG device, enabling scientists to observe brain activity by detecting the magnetic signals produced by neuronal electrical currents in real-time. Such capabilities are expected to assist researchers and healthcare professionals in identifying locations of seizures, planning surgeries with precise brain function maps, and developing diagnostic imaging techniques for brain disorders.
“This new state-of-art MEG instrument replaces our old MEG unit installed in 2005, and will have improved signal and faster electronics. We will continue to serve as the UC San Diego core MEG facility for research scientists, and physicians and their patients throughout southern California and the Southwestern U.S.”
-Roland Lee, M.D., director of the MEG Center at QI, and Mingxiong Huang,
Market Dynamics
The magnetoencephalography market is driven by the increasing prevalence of neurological disorders such as epilepsy, Alzheimer's disease, Parkinson's disease, and brain tumors, which require advanced functional brain imaging for accurate diagnosis and treatment planning. Continuous technological advancements, particularly the development of optically pumped magnetometer (OPM)-based wearable MEG systems and AI-enabled data analysis, are improving diagnostic accuracy and expanding clinical applications. However, the market faces challenges including high system acquisition costs, complex installation requirements, and limited availability of specialized expertise. Growing investments in neuroscience research, precision medicine, and expanding adoption of non-invasive neuroimaging technologies are expected to create significant growth opportunities throughout the forecast period.
The rising prevalence of neurological disorders is a key driver of the magnetoencephalography market, as conditions such as epilepsy, Alzheimer's disease, Parkinson's disease, brain tumors, and autism spectrum disorders require highly accurate functional brain mapping for diagnosis and treatment planning. MEG provides exceptional temporal resolution and non-invasive measurement of neuronal activity, making it particularly valuable for localizing epileptic foci and identifying eloquent brain regions before neurosurgery. As the global burden of neurological diseases continues to increase with aging populations and improved disease awareness, healthcare providers and research institutions are expanding the adoption of MEG systems to support earlier diagnosis, personalized treatment strategies, and improved patient outcomes.
 To learn more about this report, Download Free Sample Report
High acquisition and installation costs remain a significant restraint in the magnetoencephalography market. Conventional SQUID-based MEG systems require multimillion-dollar investments, specialized magnetically shielded rooms, cryogenic cooling infrastructure using liquid helium, and ongoing maintenance, substantially increasing the total cost of ownership. These financial and infrastructure requirements limit adoption primarily to large academic medical centers and research institutions, restricting broader penetration across community hospitals and healthcare facilities, particularly in emerging economies.
The expansion of pediatric neurology presents a significant opportunity for the Magnetoencephalography (MEG) market, driven by the growing need for accurate, non-invasive brain imaging in children with epilepsy, autism spectrum disorders, and other neurodevelopmental conditions. Wearable optically pumped magnetometer (OPM)-based MEG systems allow children to move naturally during scans, improving patient comfort and the quality of diagnostic data compared with conventional fixed MEG systems. As awareness of early neurological diagnosis increases and pediatric neuroscience programs expand globally, the adoption of MEG for pre-surgical evaluation, functional brain mapping, and developmental brain research is expected to grow substantially. For instance, in March 2026, the Melbourne Brain Center Imaging Unit (University of Melbourne) launched the Southern Hemisphere's first OPM-MEG facility. The wearable system is specifically designed for studies involving children and allows natural movement during brain imaging, making it ideal for pediatric neurological research.
Furthermore, in March 2026, a ClinicalTrials.gov study (Aston University/Birmingham Children's Hospital) began evaluating OPM-MEG for pre-surgical mapping in children (6–15 years) with drug-resistant epilepsy. The wearable system is designed to fit pediatric patients of all ages and allow movement during scanning.
Market Concentration & Characteristics
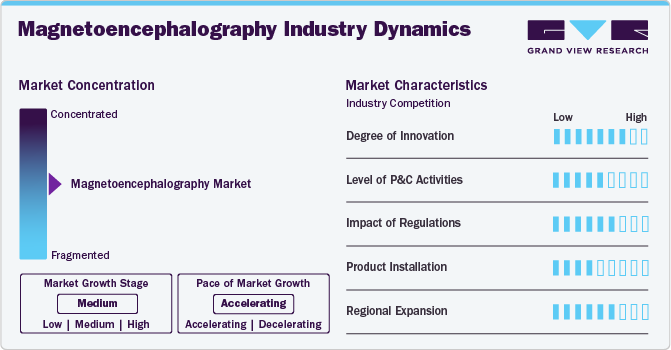
The industry growth stage is moderate. The magnetoencephalography industry is growing majorly due to the growing technological innovations and increase in research and development activities in this industry, owing to the growing number of people suffering from various neurological conditions. For instance, in June 2024, a team of researchers from the School of Physics and Astronomy at the University of Nottingham has employed an innovative MEG scanner to observe electrical activity in the brains of children as young as two years old. According to the university, this device introduces new opportunities for monitoring the achievement of essential developmental milestones.
Technological innovations are improving the accuracy, ease of use, of MEG in both medical and research field. And have resulted in more sensitive and advanced MEG sensors, which enhance the detail and timing of brain activity measurements. This has increased MEG's usefulness in diagnosing and monitoring neurological disorders, such as epilepsy, and in studying brain function in cognitive science. Moreover, improvements in data processing algorithms and software have made the analysis of MEG data more accurate and efficient, making the technology more user-friendly and widely accessible. The combination of MEG with other imaging techniques, like MRI and PET, is also boosting overall diagnostic capabilities.
 To learn more about this report, Download Free Sample Report
MEG devices have undergone significant innovation owing to continuous technological advancements, positioning them at the forefront of medical diagnostics. For example, in June 2024, scientists from Tokyo Tech developed a high-resolution diamond quantum magnetometer for mapping brain activity.
Companies that manufacture magnetoencephalography devices are engaging in partnerships and collaborations. This strategic approach seeks to improve technological capabilities, expand industry reach, and maintain competitiveness. For instance, in December 2023, MEGIN announced a strategic partnership with FIND Neuro, that creates brain network maps to facilitate the treatment of neurological diseases.
Regulatory bodies like the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) play a crucial role in shaping the development of MEG devices.Their stringent guidelines and approval processes ensure that MEG devices meet high standards for safety, efficacy, and quality.
Manufacturers are increasingly focused on the sales and installation of magnetoencephalography (MEG) products. This strategic effort aims to expand the availability and usage of MEG technology in clinical and research settings. For instance, in October 2023, MEGIN announced the sale and installation of its magnetoencephalography (MEG) technology, the TRIUX neo, at Simon Fraser University’s (SFU) core facility, ImageTech Lab.
The geographical reach of magnetoencephalography has been expanding at a moderate to high level. For instance, in January 2022, Compumedics Limited announced a major milestone in the expansion of its global MEG business with the confirmation of its first MEG contract in Asia, secured with the prestigious Tianjin Normal University (TJNU) in Tianjin, China.
Analyst Perspective
The magnetoencephalography market is expected to witness significant growth, driven by increasing demand for high-resolution functional brain imaging in epilepsy diagnosis, pre-surgical planning, and neuroscience research. The commercialization of wearable optically pumped magnetometer (OPM)-based MEG systems is transforming the market by improving portability, patient comfort, and clinical accessibility. While high capital costs and infrastructure requirements remain key challenges, ongoing technological innovation, expanding pediatric applications, and rising investments in brain research are expected to accelerate market adoption over the forecast period.
Application Insights
Based on application, the clinical segment led the market with the largest revenue share of 58.1% in 2025. This is owingto the increasing prevalence of neurodegenerative disorders. According to a study published in the National Center for Biotechnology Information (NCBI), neurological disorders are the primary reason for both physical and cognitive impairments, impacting around 15% of people worldwide. MEG in clinical settings provides precise diagnostic results, with high spatial and temporal resolution, which are frequently superior in clinical settings. Furthermore, it is efficient in pre-surgical mapping of epileptic zones, determining functional areas of the brain, such as those responsible for speech and movement, and diagnosing various neurological conditions.
The research segment is expected to grow at the fastest CAGR over the forecast period. The surge in demand for advanced brain imaging methods to analyze brain activities and diagnose neurological conditions with greater precision is likely to fuel investments in MEG research. Furthermore, as funding and interest in neuroscientific research and development expand, the utilization of MEG in research settings is expected to rise, contributing to the overall market growth of the segment.
End Use Insights
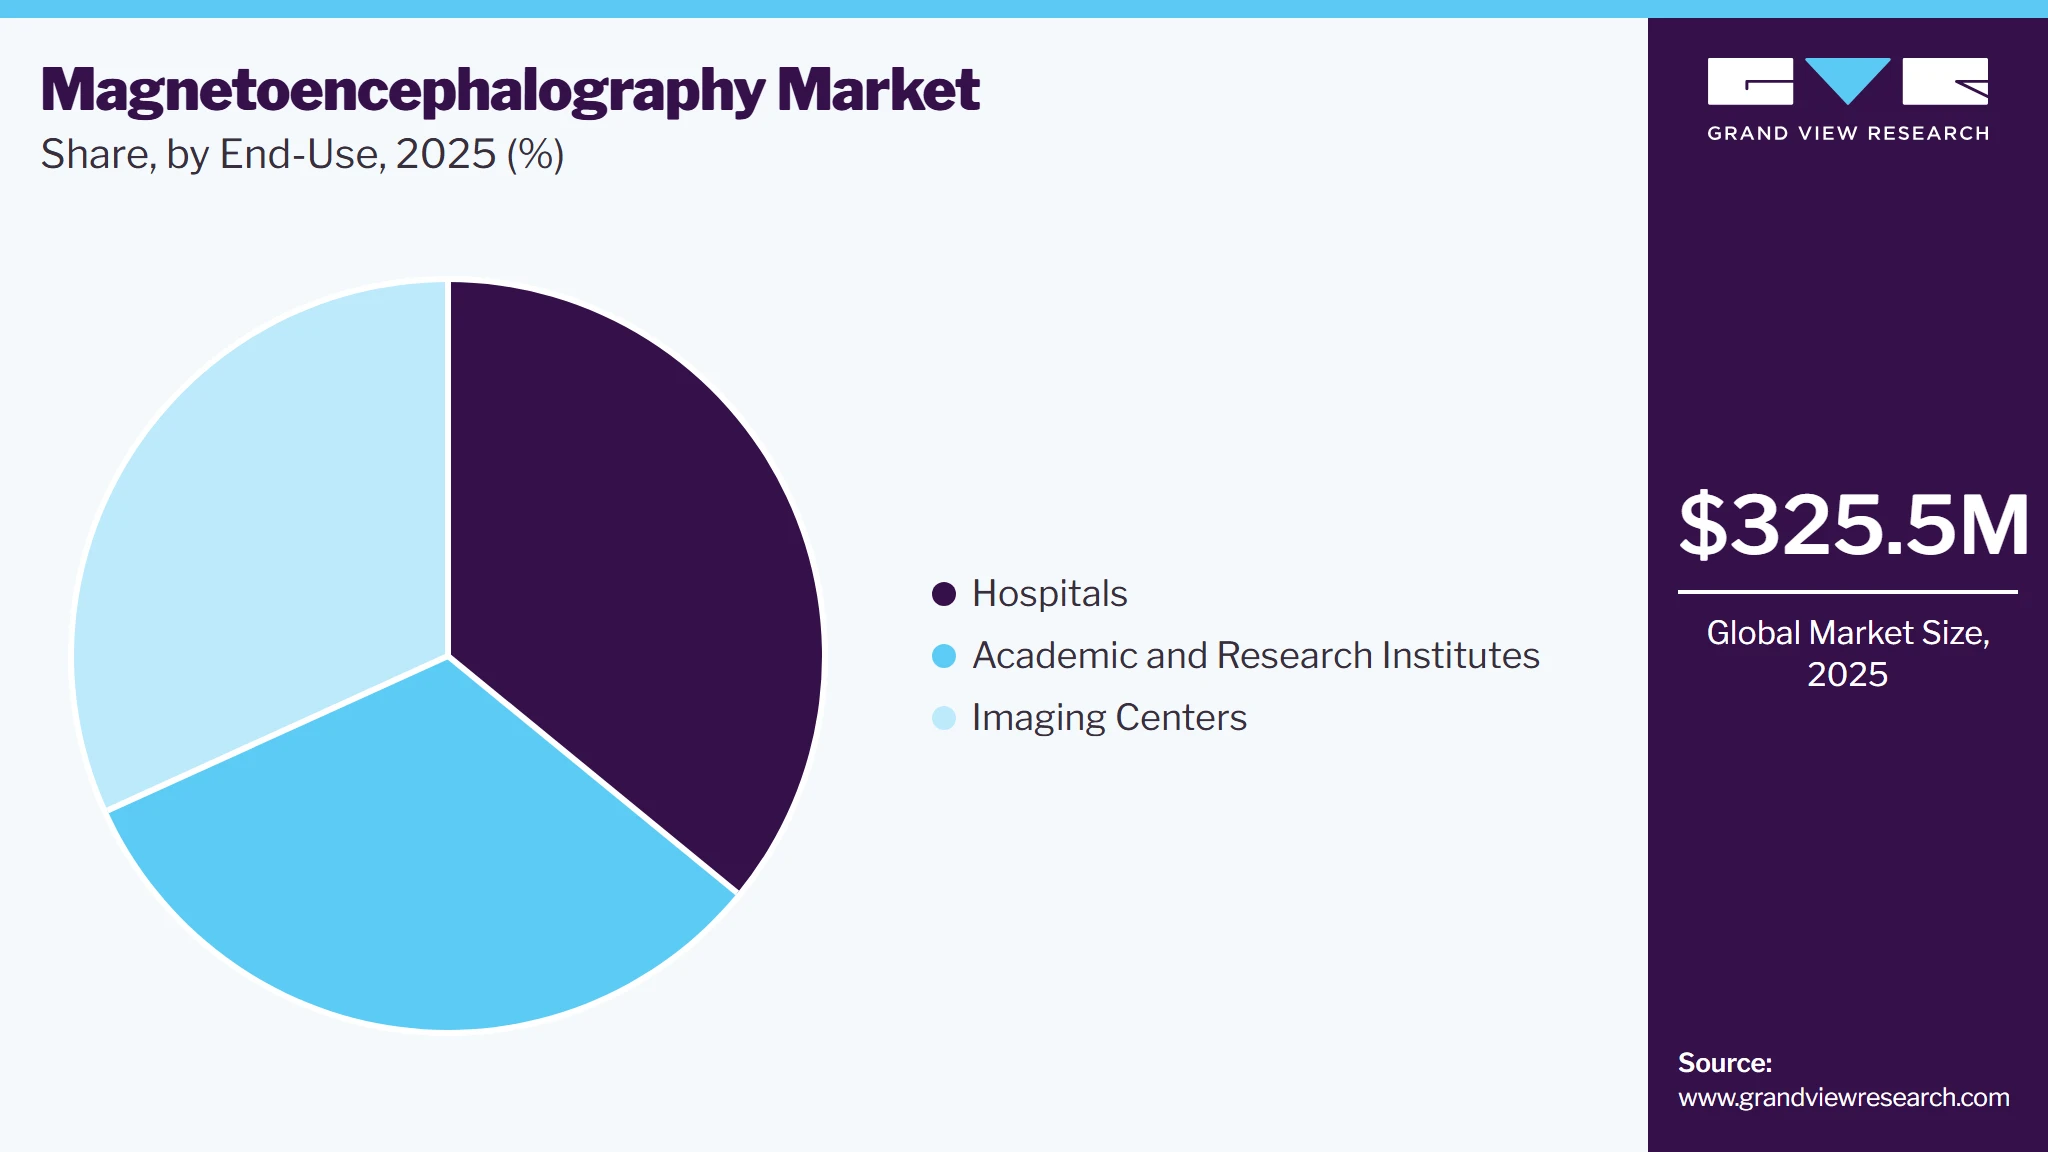
Based on end-use, the hospitals segment led the market with the largest revenue share of 35.9% in 2025. This dominance can be attributed to several factors, including the extensive use of MEG technology in hospitals for various diagnostic purposes, the increase in neurological disorders that require the advanced imaging capabilities of MEG, and the availability of funding and infrastructure in hospitals to support the high costs associated with MEG technology. In addition, hospitals often have the skilled personnel necessary to operate MEG equipment.
 To learn more about this report, Download Free Sample Report
Imaging centers is expected to grow at the fastest CAGR over the forecast period. These centers are increasingly adopting advanced imaging devices, which significantly enhances the quality and efficiency of the imaging services they provide. In addition, the rising number of patient visits is largely because these centers are able to offer shorter waiting times compared to other healthcare facilities. This improvement in both technology adoption and patient turnover rates positions imaging centers as a critical driver for the expansion of market growth.
Regional Insights
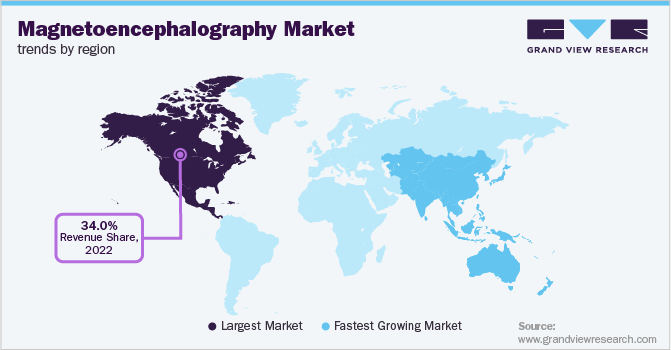
North America dominated the magnetoencephalography market with the largest revenue share of 42.1% in 2025. The presence of key manufacturers in the region, increase in R&D investments, and rise in government funding & initiatives are expected to boost market growth over the forecast period. For instance, the National Parkinson’s Foundation (NPF) provides funds to researchers and scientists for advancements in this field.
 To learn more about this report, Download Free Sample Report
U.S. Magnetoencephalography Market Trends
The magnetoencephalography market in the U.S. held the largest share in the North America region in 2025. This is due to theadvanced healthcare infrastructure, high adoption rates of new technology, substantial research funding, and the presence of major market players in the country, such as Compumedics Limited, Ricoh USA, Inc., FieldLine Inc., and others.
The Canada magnetoencephalography market is expected to grow at the fastest CAGR during the forecast period, owing to the increasing prevalence of neurological disorders, technological advancements, and growing adoption rate. For instance, in July 2021, Cerca Magnetics announced the installation of its first OPM-MEG system at the Hospital for Sick Children (SickKids) based in Toronto for ground-breaking research into autism.
Europe Magnetoencephalography Market Trends
The magnetoencephalography market in Europe held a significant market share in 2024.This is owing to the presence of advanced technologies and infrastructure in the region, resulting in significant healthcare facilities and high-quality patient care. Increasing incidence of neurological disorders, rising adoption of a sedentary lifestyle, and introduction of technologically advanced products in the European market are among the factors contributing to the market growth.
The UK magnetoencephalography market is expected to grow at a significant CAGR during the forecast period, owing to increasing prevalence and awareness about neurological disorders and the presence of several major players in the market. According to Brain Research UK, about 11 million people in the UK are living with a neurological condition. It also stated that neurological problems lead to 800,000 hospital admissions every year.
The magnetoencephalography market in Germany is driven by the country’srobust healthcare system, known for its advanced medical technologies and infrastructure, providing a foundation for the adoption and growth of advanced medical imaging technology. The country's strong emphasis on research and development is further expected to contribute to market growth.
The France magnetoencephalography marketis expected to grow at a significant CAGR during the forecast period, owing to the increasing prevalence of neurological disorders, such as epilepsy and Alzheimer's disease, which increases demand for more accurate and non-invasive diagnostic methods, further boosting the MEG market growth.
Asia Pacific Magnetoencephalography Market Trends
The magnetoencephalography market in Asia Pacific is expected to grow at a lucrative CAGR over the forecasted period. This can be attributed to the increasing incidence of stroke and neurodegenerative disorders, such as Parkinson's and Alzheimer's disease, which heightens the demand for advanced diagnostic tools like MEG. In addition, emerging economies in the region, including China, Japan, South Korea, and India, are experiencing rapid healthcare advancements and substantial economic growth.
The China magnetoencephalography market is expected to grow at a significant CAGR during the forecast period, attributed to the growing geriatric population, along with the increasing incidence of neurodegenerative disorders. The prevalence of age-related neurological conditions such as Alzheimer's disease, Parkinson's disease, and stroke is increasing, thus increasing the demand for MEG to facilitate early detection and effective management of these disorders.
The magnetoencephalography market in Japan is projected to expand at the fastest CAGR during the forecast period, owing to the country's rapidly aging population. This demographic shift results in a higher prevalence of neurological disorders, such as dementia and Alzheimer's disease, where MEG devices play a critical role in early detection and continuous monitoring.
The India magnetoencephalography market is expected to grow at a significant CAGR during the forecast period, owing to the increasing government initiatives aimed at improving healthcare infrastructure and increasing investments in research and development within the neurology field. In addition, rising awareness and increasing diagnoses of neurological disorders in the country, which, in turn, is driving the demand for advanced diagnostic methods like MEG.
Latin America Magnetoencephalography Market Trends
The magnetoencephalography market in Latin America is expected to grow at a substantial CAGR during the forecast period,as significant investments by industry players are driving the development and adoption of advanced MEG technology across the region.Latin America's proximity to North America facilitates the transfer of technology and expertise, further boosting the MEG market. In addition, free-trade agreements with major countries such as the U.S., Canada, Japan, and several European nations are creating favorable economic conditions and reducing barriers to the import and export of medical devices.
MEA Magnetoencephalography Market Trends
The magnetoencephalography market inMEA is expected to grow at a significant CAGR during the forecast period, due to a combination of critical factors. One of the primary drivers is the increased prevalence of neurological disorders, such as epilepsy, Parkinson's disease, and Alzheimer's disease, which necessitate advanced diagnostic and monitoring tools like MEG. As the region's population ages rapidly, the incidence of these neurodegenerative conditions is rising, further boosting the demand for MEG technology.
Key Companies & Market Share Insights
The continuous demand for magnetoencephalography (MEG) by end-users, including hospitals, academic and research institutions, and imaging centers, has generated numerous market opportunities for major players in the industry. This growing demand is driven by the increasing prevalence of neurological disorders, the need for advanced diagnostic tools, and the benefits of non-invasive brain imaging technology. To capitalize on these opportunities, market players are engaging in a variety of strategic initiatives. These include investing in research and development to innovate and improve MEG technology, making it more efficient, accurate, and user-friendly. Companies are also forming partnerships and collaborations with healthcare providers and research institutions to expand their reach and enhance their technological capabilities.
Key Magnetoencephalography Companies:
The following key companies have been profiled for this study on the magnetoencephalography market.
-
Compumedics Limited
-
MEGIN
-
Ricoh
-
CTF MEG NEURO INNOVATIONS, INC.
-
FieldLine Inc.
-
Cerca Magnetics Limited
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Ricoh Company, Ltd., MEGIN, Compumedics Limited)
- Focus on continuous product innovation and software upgrades.
- Strengthen partnerships with hospitals, epilepsy centers, and research institutes.
- Strong global brand recognition and established customer base.
- Comprehensive product portfolios with proven clinical performance.
- High system costs and dependence on magnetically shielded rooms.
- Slower adoption of disruptive technologies due to established product portfolios.
Emerging Players (MAG4Health (Brainbox Ltd., Official Distributor), Cerca Magnetics Limited)
- Commercialize wearable Optically Pumped Magnetometer (OPM)-based MEG systems.
- Collaborate with universities and neuroscience research centers for technology validation.
- Innovative wearable and cryogen-free MEG technologies with improved patient comfort.
- Lower infrastructure requirements and greater portability than conventional SQUID-based systems.
- Limited commercial presence and smaller installed base.
- Restricted manufacturing capacity and global distribution channels.
Recent Developments
-
In November 2024, The University of Alabama at Birmingham and UAB Medicine introduced a new magnetoencephalography (MEG) machine to enhance research and clinical care. MEG measures brain magnetic fields, aiding in diagnosing epilepsy and studying brain functions like speech and vision. UAB Hospital is among fewer than 30 U.S. centers with this technology.
-
In February 2022, MEGIN announced that the University of Nebraska Medical Center (UNMC) had acquired their fourth-generation magnetoencephalography (MEG) technology, the TRIUX neo.
-
In November 2021, Cerca Magnetics, a spinoff from the University of Nottingham, won the best start-up medtech company award at the annual OBN awards. The prize was given to Cerca Magnetics in recognition of their efforts in creating and commercializing the first wearable brain MEG device.
Magnetoencephalography Market Report Scope
Report Attribute
Details
Market size in 2025
USD 325.5 million
Estimated market size in 2026
USD 345.6 million
Projected market size by 2033
USD 569.7 million
Growth rate
CAGR of 7.4% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
MAG4Health (Brainbox Ltd., Official Distributor), Ricoh Company, Ltd., MEGIN, Compumedics Limited, CTF MEG NEURO INNOVATIONS, INC., Cerca Magnetics Limited, FieldLine Inc., Tristan Technologies, Inc. (Conductus)
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Magnetoencephalography Market Report Segmentation
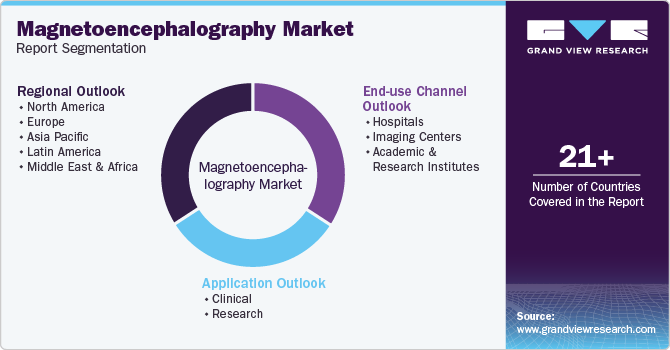
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global magnetoencephalography market report based on application, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Clinical
-
Dementia
-
Autism
-
Schizophrenia
-
Multiple Sclerosis
-
Stroke
-
Epilepsy
-
Others
-
-
Research
-
-
End Use Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Imaging centers
-
Academic and research institutes
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The magnetoencephalography market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each magnetoencephalography segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Application
Revenue capture definition
Clinical
Clinical segment captures revenue generated from the use of Magnetoencephalography (MEG) systems in hospitals, neurology centers, and diagnostic facilities for clinical applications, including epilepsy diagnosis, pre-surgical brain mapping, neurological disorder assessment, and associated software, services, and accessories.
Research
Research segment captures revenue generated from the use of Magnetoencephalography (MEG) systems in academic institutions, neuroscience research centers, and research organizations for brain function studies, cognitive neuroscience, neurodevelopmental research, brain-computer interface research, and related software, services, and accessories.
Estimation Model
Approach
Description
Bottom-Up Installed Base & Procedure Volume Modeling
Models the installed base of MRI systems across hospitals, academic medical centers, neuroscience institutes, and research laboratories by region. Estimates annual MRI procedures (e.g., epilepsy diagnosis, pre-surgical brain mapping, cognitive neuroscience studies), average system utilization, replacement cycles, and average selling prices (ASPs) to derive market revenue.
Top-Down Revenue Triangulation
Aggregates supplier-side revenues from leading manufacturers such as MRI Inc., CernaMagnetics, Computronics Limited, Rech Co., Ltd., and Field Line Inc. Revenue estimates are validated through annual reports, financial disclosures, product portfolios, regional sales distribution, and elimination of double counting to estimate the global market size.
Demand-Side End-User Consumption Modeling
Evaluates procurement and adoption patterns across hospitals, epilepsy centers, academic institutions, and neuroscience research organizations. The model incorporates funding for neuroscience research, healthcare expenditure, reimbursement landscape, installed base expansion, and technology adoption (including wearable UHF-MRI systems) to estimate demand across end-user segments.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Detailed regional assessment of the Magnetoencephalography (MEG) market across North America, Europe, Asia-Pacific, Latin America, and MEA
Country-level market sizing, growth forecasts, regulatory landscape, reimbursement analysis, and competitive benchmarking
Enables region-specific market entry strategies, investment prioritization, and expansion planning.
Competitive intelligence and technology benchmarking
In-depth profiling of key manufacturers, market share analysis, product comparison, pricing assessment, recent developments, and SWOT analysis
Supports strategic positioning, partnership identification, and competitive differentiation.
Pipeline and innovation landscape assessment
Comprehensive analysis of wearable OPM-MEG technologies, AI-enabled MEG software, ongoing clinical research, regulatory approvals, and future product pipeline
Helps identify emerging growth opportunities, evaluate technology trends, and support long-term product development and investment decisions.
Frequently Asked Questions About This Report
The global magnetoencephalography market size was valued at USD 332.5 million in 2025 and is estimated at USD 345.6 million for 2026.
Some key players operating in the magnetoencephalography market include MAG4Health (Brainbox Ltd., Official Distributor), Ricoh Company, Ltd., MEGIN, Compumedics Limited, CTF MEG NEURO INNOVATIONS, INC. , Cerca Magnetics Limited, FieldLine Inc., Tristan Technologies, Inc. (Conductus).
Key factors that are driving the MEG market growth include the increasing prevalence of neurological disorders and the growing advancement in magnetoencephalography scanners.
The global magnetoencephalography market is expected to grow at a CAGR of 7.4% from 2026 to 2033, reaching USD 569.7 million by 2033.
The clinical segment led the market with the largest revenue share of 58.1% in 2025.
The hospitals segment led the market with the largest revenue share of 35.9% in 2025.
North America dominated the MEG market with a share of 42.1% in 2025. This is attributable to the existence of a large number of market competitors in the region, as well as the high frequency of new product releases.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


