
- Home
- »
- Petrochemicals
- »
-
Marine Lubricants Market Size And Share Report, 2026-2033GVR Report cover

Marine Lubricants Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Engine Oil, Hydraulic Oil, Gear Oil, Turbine Oil, Greases), By Region (North America, Europe, Asia Pacific, Latin America, Middle East & Africa), And Segment Forecasts
Market Size, 2025
$8.4BMarket Estimate, 2026
$8.7BMarket Forecast, 2033
$11.9BCAGR, 2026–2033
4.6%Marine Lubricants Market Summary
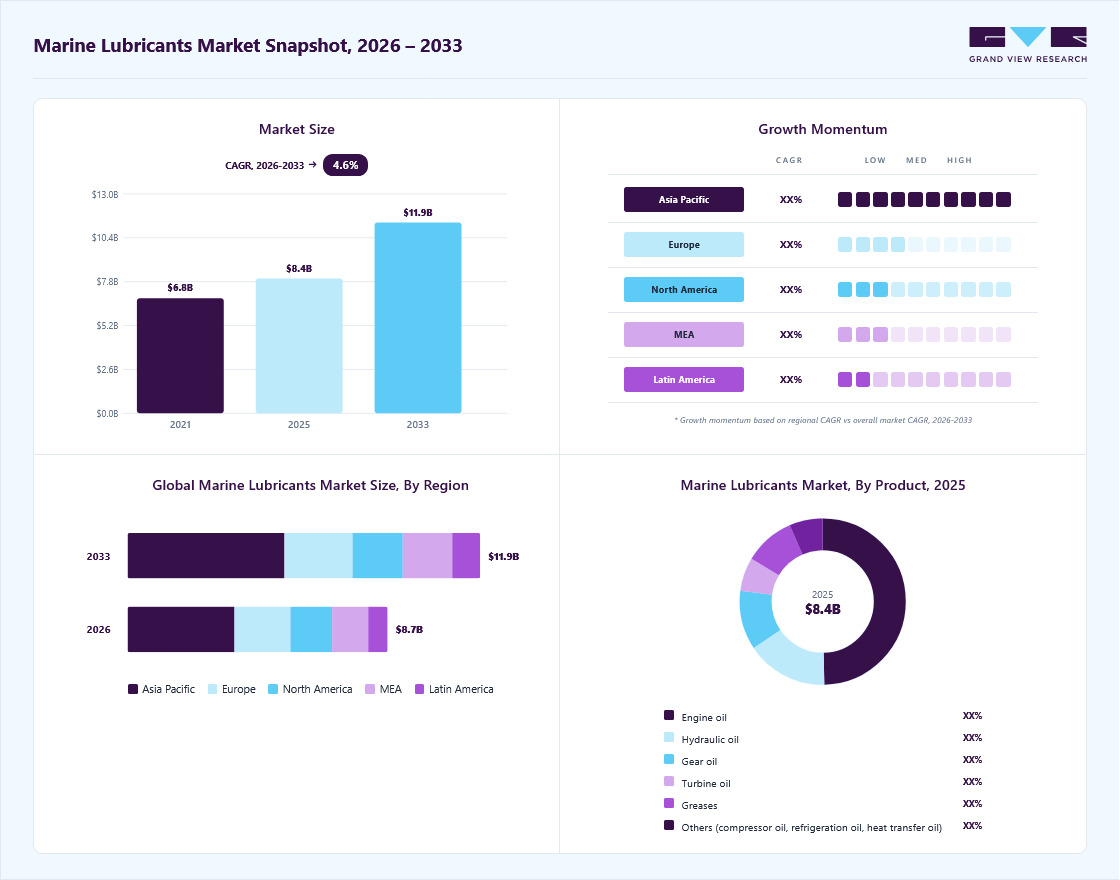
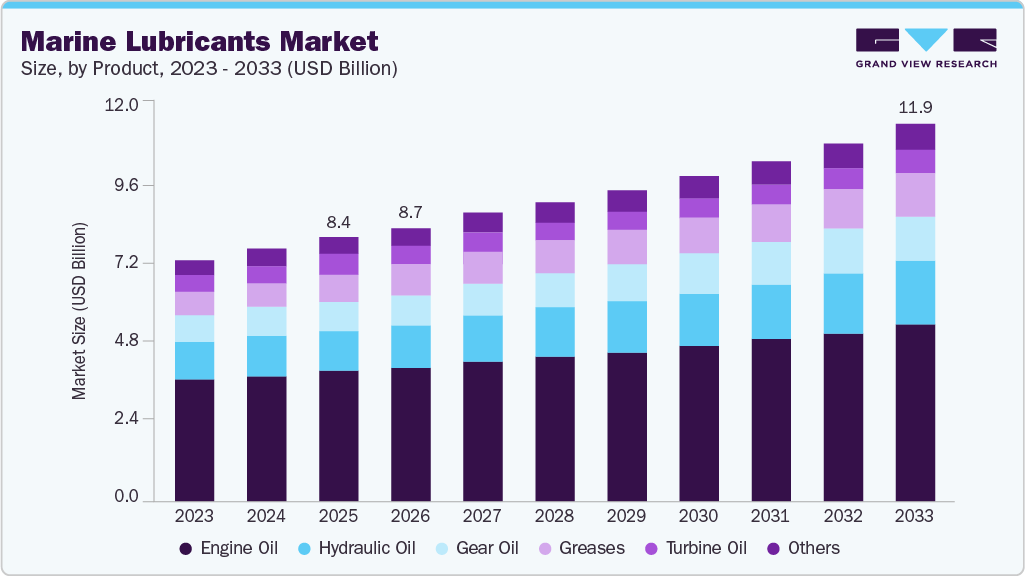
The global marine lubricants market size was valued at USD 8.4 billion in 2025 and is projected to grow from USD 8.7 billion in 2026 to USD 11.9 billion by 2033, at a CAGR of 4.6% from 2026 to 2033. Asia Pacific dominated the global market, accounting for the largest revenue share of 41.1% in 2025, supported by the region’s expanding maritime trade, shipbuilding activities, and growing commercial shipping fleets. Rising global seaborne trade, increasing vessel utilization, and growing demand for high-performance lubricants that enhance engine efficiency, reduce maintenance requirements, and extend equipment life are driving worldwide market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Engine oil segment held the largest market share of 49.6% in 2025.
- Increasing seaborne trade and vessel activity are expected to drive market growth
Regional Highlights
- Largest regional market: Asia Pacific (Approximately 41.1% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 8.4 Billion
- Estimated market size in 2026: USD 8.7 Billion
- Projected market size by 2033: USD 11.9 Billion
- CAGR (2026-2033): 4.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Marine lubricants are widely used across the shipping industry to protect engines and critical equipment while enhancing operational efficiency and reliability. These high-performance lubricants are specially formulated to withstand demanding marine operating conditions and provide benefits such as extended engine life, protection of components at high temperatures, improved machinery performance, reduced mechanical wear, and mitigation of cold corrosion.Evolving requirements across heavy-duty shipping and marine applications are driving extensive research and development activities in the global marine lubricants industry. Manufacturers are increasingly developing advanced lubricant formulations that offer longer oil-drain intervals, reduced maintenance requirements, improved lubricant life, enhanced fuel efficiency, and superior equipment performance. Technological advancements in engine design and increasingly stringent operating requirements are further encouraging the development of high-performance marine lubricants.
 To learn more about this report, Download Free Sample Report
Increasing oil-drain intervals and improvements in lubricant efficiency have reduced oil consumption in inland and coastal shipping applications, creating new competitive and technological pressures across the marine lubricants supply chain. In response, leading industry participants are investing in the development of high-quality lubricants for different types of marine engines and equipment, incorporating advanced additive technologies and formulation improvements to deliver consistent performance under demanding operating conditions.
Environmental sustainability is becoming increasingly important across the maritime industry. The growing volume of global seaborne trade and the expansion of the commercial shipping fleet have intensified concerns regarding emissions, oil discharges, and waste management. The International Maritime Organization (IMO) continues to strengthen and update environmental regulations to reduce marine pollution, control emissions, and limit the environmental impact of shipping operations. These regulatory developments are encouraging ship operators to adopt cleaner technologies and more environmentally compatible lubricants, including products designed to improve engine efficiency and reduce emissions and lubricant-related waste.
Market Dynamics
The marine lubricants market is driven by expanding international seaborne trade, fleet modernization, and rising demand for high-performance lubricants that improve engine efficiency and extend equipment life. However, economic disruptions, fluctuations in crude oil and base oil prices, and changes in global shipping activity may constrain market growth. Meanwhile, stringent environmental regulations, increasing adoption of fuel-efficient vessels, and growing demand for sustainable and biodegradable lubricant formulations are creating new opportunities for market participants.
The continued expansion of international seaborne trade is expected to remain a key driver of the marine lubricants market over the forecast period. The ongoing rebalancing of China’s economy is likely to reshape maritime transportation networks and influence global shipping and trade patterns. Government initiatives aimed at expanding the production of finished goods and strengthening China’s presence in emerging economies are expected to further support international trade flows and vessel activity. The shipping industry experienced a strong growth cycle in recent years, driven by globalization, the increasing division of international labor, and the fragmentation of global production processes. Rising capital investments and rapid industrialization across emerging economies further increased demand for maritime transportation, particularly for the movement of raw materials, intermediate goods, and finished products.
Moreover, China’s resource-intensive growth phase and deeper integration into global manufacturing and supply chains are expected to support demand for marine lubricants. Developing economies that have strengthened their economic and trade ties with China by participating more in regional and global value chains are also contributing to higher seaborne trade volumes. Increased movement of raw materials and manufactured goods across international shipping routes is expected to raise vessel utilization and, consequently, demand for marine lubricants used to maintain engines and critical marine equipment.
Economic cycles and fluctuations in global trade activity directly affect demand for marine lubricants, as shipping volumes, vessel utilization, and fleet operations are closely linked to overall economic conditions. Periods of slower economic growth, geopolitical uncertainty, and trade disruptions can reduce cargo movement and vessel operating rates, thereby limiting lubricant consumption.
In recent years, global economies have experienced considerable structural and cyclical changes, creating uncertainty across the maritime and industrial sectors. Emerging markets, once viewed as major destinations for investment and manufacturing expansion, have faced economic and financial pressures that have undermined business confidence and investment activity. At the same time, developed economies have increasingly adopted protectionist policies, including trade restrictions and measures to strengthen domestic production and demand. Such developments disrupt established global supply chains, reducing international trade volumes and altering shipping routes.
The growing emphasis on environmental sustainability and stringent maritime regulations is creating significant opportunities for marine lubricant manufacturers to develop and commercialize environmentally sustainable products. The International Maritime Organization (IMO) and regional regulatory authorities are implementing measures to reduce vessel emissions, minimize oil discharge, and improve the environmental performance of shipping operations. These regulations are encouraging ship operators to adopt lubricants that deliver high performance while reducing their environmental footprint.
Bio-based and biodegradable marine lubricants, including environmentally acceptable lubricants (EALs), are gaining attention for applications where lubricant leakage or discharge may affect marine ecosystems. In addition, advances in additive technologies and lubricant formulations are enabling longer oil-drain intervals, improved engine efficiency, reduced wear, and lower maintenance requirements. Manufacturers investing in low-toxicity, biodegradable, and high-performance formulations are therefore well positioned to capture emerging demand.
Analyst Perspective
The marine lubricants market is expected to maintain steady growth as expanding seaborne trade, fleet modernization, and rising vessel operating efficiency drive lubricant consumption. Demand is increasingly shifting toward high-performance and environmentally compatible formulations that support longer oil-drain intervals, reduce maintenance costs, and comply with stringent emissions and pollution regulations. Asia Pacific is likely to remain the dominant regional market, supported by strong shipbuilding capacity, growing maritime trade, and industrial expansion across China and Southeast Asia. Meanwhile, technological advancements in marine engines and the increasing adoption of fuel-efficient vessels are creating opportunities for advanced lubricant formulations. However, crude oil price volatility, excess vessel capacity, and fluctuations in shipping activity may moderate market expansion. Overall, innovation, regulatory compliance, and demand for improved vessel efficiency are expected to remain key competitive factors.
Product Insights
The engine oil segment accounted for the largest market share, at 49.6%, in 2025 and is expected to maintain its leading position throughout the forecast period. Engine oils include system, cylinder, and trunk piston engine oils, which are essential for lubricating and protecting marine engines under demanding operating conditions. The growing global population, rising disposable incomes, and increasing consumption of commercial goods are driving seaborne trade and vessel activity, thereby supporting demand for engine oils. Recent product developments by leading manufacturers are further supporting demand for marine engine oils. In May 2025, FUCHS launched its TITAN MARINE range of engine oils for marine applications. The range included TITAN MARINE FC-W SAE 10W-30, a lubricant for water-cooled four-stroke gasoline marine engines with catalytic converters, which received official NMMA FC-W (CAT) approval. The launch expanded FUCHS's marine lubricant portfolio for outboard and other compatible marine engine applications.
The greases segment is expected to be the fastest-growing product category, registering a 6.0% CAGR during the forecast period. Increasing use of greases in deck machinery, bearings, winches, steering systems, and other components exposed to harsh marine environments is driving demand. Their superior load-carrying capacity, water resistance, and corrosion protection make them well-suited for marine applications, where equipment is frequently exposed to high loads, moisture, and saltwater. Growing emphasis on equipment reliability, longer service life, and reduced maintenance frequency is further supporting segment growth.
Regional Insights
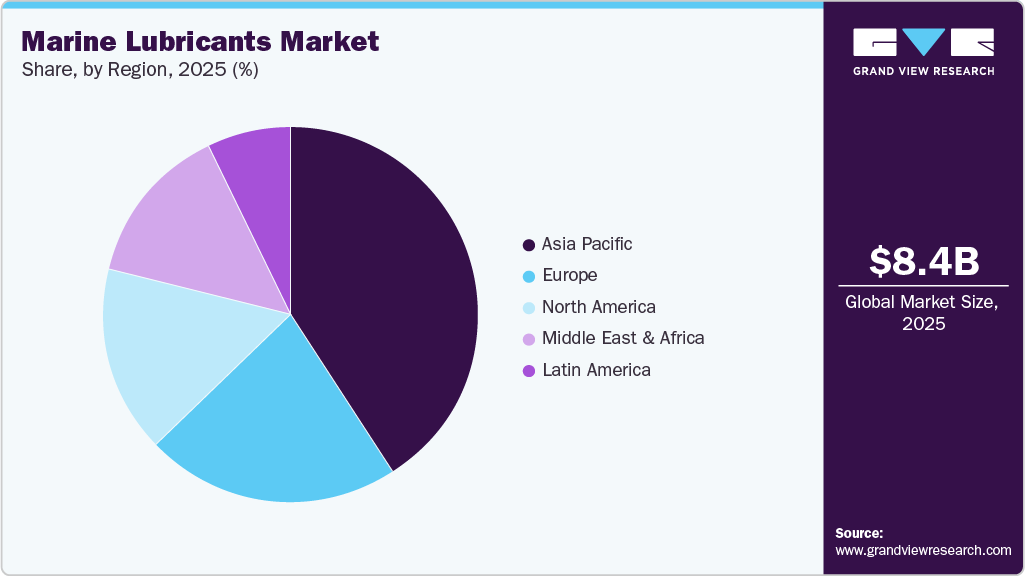
Asia Pacific was the largest regional contributor to the global marine lubricants market, accounting for 41.1% of revenue in 2025. The region’s strong position is supported by its extensive network of major ports, large commercial shipping fleet, robust shipbuilding industry, and expanding international trade with the U.S., Europe, and other developed economies. China, Japan, South Korea, Singapore, and India remain key maritime markets, supported by high vessel traffic and significant shipbuilding and repair activities. Singapore benefits from its strategic location along major international trade routes. The country continues to invest in port modernization and aims to strengthen its position as a leading global maritime and transshipment hub. Continued investments in port infrastructure, manufacturing capacity, and maritime transportation are expected to sustain lubricant demand across commercial shipping and offshore applications.
 To learn more about this report, Download Free Sample Report
China Marine Lubricants Market Trends
China is a major marine lubricants market in the Asia Pacific, accounting for around 40.0% of the regional revenue. The country’s dominance is supported by its extensive shipping fleet, substantial shipbuilding capacity, and high levels of domestic and international maritime trade. The marine industry in China is expected to maintain steady growth throughout the forecast period, supporting the consumption of marine lubricants across commercial vessels, marine equipment, and offshore applications. Furthermore, the expansion of manufacturing activities, supported by relatively competitive labor and raw material costs, is strengthening regional trade flows and increasing demand for maritime transportation and, consequently, marine lubricants.
North America Marine Lubricants Market Trends
North America accounted for approximately 16.0% of the global marine lubricants market in 2025. The region benefits from an established maritime transportation network, extensive inland waterways, offshore activities, and strong demand for marine vessels and equipment. In the U.S., domestic maritime transportation plays an important role in supporting energy infrastructure and the movement of petroleum products, chemicals, and other bulk commodities.
U.S. Marine Lubricants Market Trends
The U.S. marine lubricant market accounted for approximately 80.0% share of North America’s market in 2025. The expansion of U.S. oil and gas production, particularly following the shale oil boom, has increased demand for maritime transportation and offshore support activities. At the same time, investments in shipbuilding and fleet modernization are supporting demand for marine lubricants. Construction and operation of vessels such as roll-on/roll-off ships, offshore supply vessels, tankers, and container ships are expected to provide continued opportunities for lubricant manufacturers.
Europe Marine Lubricants Market Trends
Europe accounted for 21.5% of the global marine lubricants market in 2025. The demand in the region is supported by high shipping density, well-established ports, extensive maritime trade, and offshore activities, particularly in the North Sea. Demand is increasingly influenced by stringent environmental regulations and decarbonization initiatives, encouraging the adoption of low-sulfur-compatible, environmentally acceptable, and high-performance lubricant formulations. Although relatively limited fleet expansion constrains volume growth, demand is sustained by fleet modernization, regulatory compliance, vessel maintenance, and the replacement of aging marine equipment. Increasing adoption of fuel-efficient vessels and cleaner propulsion technologies is also creating opportunities for advanced lubricant solutions.
Latin America Marine Lubricants Market Trends
Latin America is projected to grow at a CAGR of 5.6% during the forecast period. The growth in the Latin America marine lubricants market is supported by expanding seaborne trade, offshore oil and gas exploration and production, port development, and increasing maritime transportation activity. Brazil and Argentina remain important contributors, driven by offshore support vessels, oil and gas transportation, container shipping, and bulk cargo operations. Growing investments in port infrastructure and logistics networks are improving regional maritime connectivity and supporting vessel activity. Although the regional market remains smaller than those of Asia Pacific, Europe, and North America, gradual growth in trade volumes, offshore operations, and maritime infrastructure is expected to sustain demand for marine lubricants during the forecast period.
Middle East & Africa Marine Lubricants Market Trends
The Middle East & Africa accounted for around 14.0% of the global marine lubricants market in 2025. The demand in the region is supported by strategic shipping routes, major bunkering hubs, and strong offshore oil & gas marine activity, particularly in the Gulf region. Increasing port expansions and rising trade flows between Asia, Europe, and Africa are boosting lubricant consumption. In Africa, demand is growing steadily, driven by improving port infrastructure and coastal trade, though adoption levels remain uneven across countries.
Key Marine Lubricants Company Insights
The global marine lubricants market is characterized by the presence of several multinational lubricant manufacturers and specialized regional suppliers offering products across marine engine oils, hydraulic fluids, greases, gear oils, and other specialty applications. Leading companies compete through product innovation, application-specific formulations, OEM approvals, technical services, and expansion of sustainable lubricant portfolios. Fluctuations in crude oil and base oil prices continue to affect production costs and pricing, prompting manufacturers to optimize formulations, improve supply chain efficiency, and diversify revenue streams.
Key Marine Lubricants Companies:
The following key companies have been profiled for this study on the marine lubricants market.
-
JX Nippon Oil & Energy Corp.
-
Quepet Lubricants LLC
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Castrol Limited; Shell (Pennzoil); Phillips 66; Repsol; PetroChina Co. Ltd.; Petrobras; JX Nippon Oil & Energy Corp.; Kluber Lubrication; Gulf Oil International
- These companies are expanding marine lubricant portfolios for two-stroke and four-stroke marine engines, offshore vessels, and marine auxiliary equipment
- Major players are investing in low-sulfur and environmentally compliant lubricant formulations aligned with IMO emission regulations and evolving marine fuel standards
- Companies are strengthening global bunker supply partnerships, port-based distribution networks, and OEM collaborations with leading marine engine manufacturers
- Strong global supply and distribution networks across major shipping routes and ports ensure reliable lubricant availability.
- Broad product portfolios, technical expertise, and established shipping relationships support customer retention.
- Strong financial resources and integrated refining operations enable stable raw material sourcing and production efficiencies.
- Dependence on crude-derived base oils exposes companies to feedstock price volatility.
- Stricter environmental regulations and cleaner propulsion technologies may reduce long-term demand for conventional marine lubricants.
- Large operating structures may limit responsiveness to niche regional requirements and customized formulations
Emerging Players: Bel-Ray Co. Inc.; Quaker Chemical Corp.; Zeller+Gmelin GmbH & Co. KG; Blaser Swisslube AG; PetroFer Chemie; Buhmwoo Chemical Ind. Co. Ltd.; Innospec; UniMarine Inc.; Quepet Lubricants LLC
- Emerging and specialty players focus on high-performance lubricants, specialty additives, and customized solutions for offshore and regional marine applications.
- Companies are investing in biodegradable lubricants, synthetic oils, and application-specific solutions for harsh marine conditions.
- Strategic partnerships with distributors, ship operators, and maintenance providers, strengthening market reach and technical support.
- Greater flexibility and focus on customized requirements support competitiveness in specialized marine applications.
- Expertise in additives, corrosion protection, and performance optimization enables differentiation in premium segments.
- Faster decisions and targeted regional strategies strengthen relationships with local fleet operators and marine customers
- Limited global distribution networks and production capacity may constrain competitiveness against multinationals.
- Lower financial resources and narrower portfolios limit competition with integrated oil companies.
- Reliance on regional trade and third-party base oils may constrain scalability and operational stability
Recent Developments
-
In July 2025, Castrol announced the launch of its new MHP range of lubricants specifically designed for four-stroke medium-speed engines. The range includes Castrol MHP 1-40 and MHP 1-30, which were reformulated with a lower base number and specially selected detergents to provide oxidation resistance and enhanced detergency performance. The development highlights the industry's growing focus on application-specific marine lubricants designed to meet the evolving performance requirements of modern marine engines.
-
In February 2025, Repsol announced that it had developed biodegradable lubricant solutions designed to minimize the environmental impact of lubricant leakage on marine ecosystems. The development aligns with the growing adoption of sustainable marine lubricants as ship operators respond to tightening environmental regulations and rising sustainability requirements.
Marine Lubricant Market Report Scope
Report Attribute
Details
Market size in 2025
USD 8.4 billion
Estimated Market size in 2026
USD 8.7 billion
Projected Market size by 2033
USD 11.9 billion
Growth rate
CAGR of 4.6% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Million, Volume in Kilo Tons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product and region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; Germany; UK; Switzerland; France; Italy; Spain; Netherlands; Russia; China; India; Japan; South Korea; Southeast Asia; Oceania; Kyrgyzstan; Brazil; Argentina; Chile; Colombia; Iran; Oman; UAE; Qatar; Kuwait; Saudi Arabia; South Africa; Angola; Nigeria
Key companies profiled
Bel-Ray Co. Inc.; Quaker Chemical Corp.; Zeller+Gmelin GmbH & Co. KG; Blaser Swisslube AG; Repsol; Kluber Lubrication; Pennzoil (Shell Marine); Phillips 66; PetroChina Co. Ltd.; JX Nippon Oil & Energy Corp.; Petrobras; PetroFer Chemie; Buhmwoo Chemical Ind. Co. Ltd.; Innospec; Gulf Oil International; UniMarine Inc.; Quepet Lubricants LLC; Castrol Limited.
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Marine Lubricants Market Report Segmentation
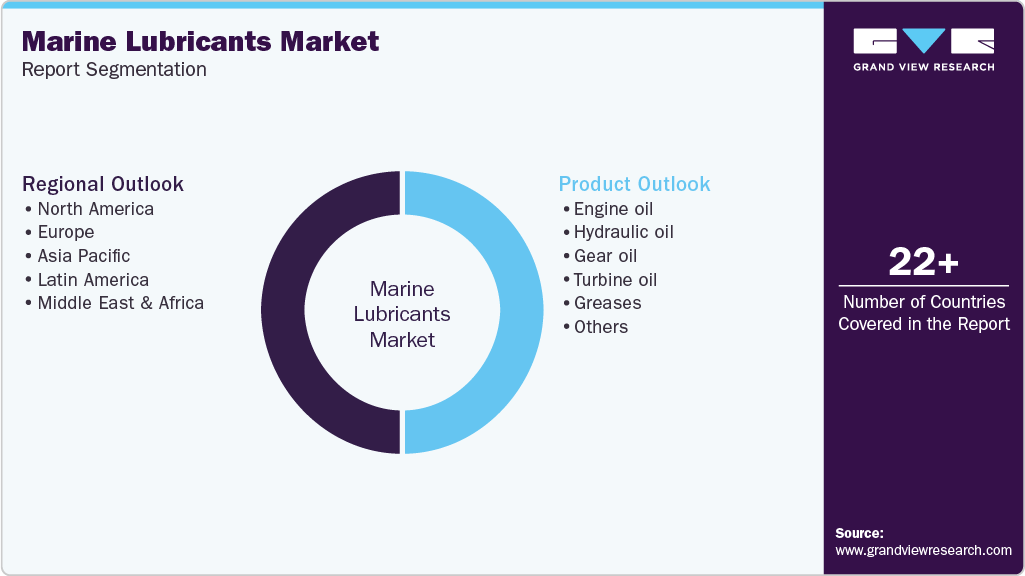
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends across sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global marine lubricants market report based on product and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million; Volume, Kilo tons; 2021 - 2033)
-
Engine Oil
-
Hydraulic Oil
-
Gear Oil
-
Turbine Oil
-
Greases
-
Others (Compressor Oil, Refrigeration Oil, Heat Transfer Oil)
-
-
Regional Outlook (Revenue, USD Million; Volume, Kilo tons; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Switzerland
-
France
-
Italy
-
Spain
-
Netherlands
-
Russia
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Southeast Asia
-
Oceania
-
Kyrgyzstan
-
-
Latin America
-
Brazil
-
Argentina
-
Chile
-
Colombia
-
-
Middle East & Africa
-
Iran
-
Oman
-
UAE
-
Qatar
-
Kuwait
-
Saudi Arabia
-
South Africa
-
Angola
-
Nigeria
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Operating Strategies
Competitive Edge
Weaknesses
Regulatory Compliance Assessment
Detailed assessment of marine lubricant demand shifts resulting from IMO sulfur regulations, emission control areas (ECAs), decarbonization initiatives, and transition toward LNG, methanol, and alternative marine fuels. Includes impact analysis on lubricant formulation requirements and product development trends.
Enable strategic planning around changing marine fuel standards and environmental regulations. Support development of compliant, future-ready lubricant formulations and sustainability positioning.
Pricing Trend Analysis
Analysis of historical and current marine lubricant pricing trends across major bunker hubs and shipping regions. The study includes the impact assessment of crude oil fluctuations, base oil pricing, additive costs, freight rates, refinery dynamics, and supply-demand imbalances on lubricant pricing structures.
Provide visibility into pricing volatility and margin drivers across marine lubricant categories. Support procurement planning, pricing strategy optimization, and long-term contract negotiations with fleet operators and distributors.
Competitive Benchmarking
Comparative assessment of marine lubricant manufacturers based on global port presence, OEM approvals, lubricant portfolio breadth, sustainability initiatives, technical service capabilities, and relationships with shipping companies and marine engine manufacturers.
Support benchmarking against leading marine lubricant suppliers and identify competitive differentiation opportunities. Assist in strengthening market positioning, partnership strategies, and expansion planning across global shipping routes.
Frequently Asked Questions About This Report
Engine oil segment led with a revenue share of 49.6% in 2025, while greases is the fastest-growing segment.
The global marine lubricants market size was estimated at USD 8.4 billion in 2025 and is expected to reach USD 8.7 billion in 2026.
The global marine lubricants market is expected to grow at a compound annual growth rate of 4.6% from 2026 to 2033 to reach USD 11.9 billion by 2033.
Asia Pacific dominated with a 41.1% revenue share in 2025.
Some of the key players in the marine lubricants market include Bel-Ray Co. Inc., Quaker Chemical Corp., Zeller+Gmelin GmbH & Co. KG, Blaser Swisslube AG, Repsol, Kluber Lubrication, Pennzoil (Shell Marine), Phillips 66, PetroChina Co. Ltd., JX Nippon Oil & Energy Corp., Petrobras, PetroFer Chemie, Buhmwoo Chemical Ind. Co. Ltd., Innospec, Gulf Oil International, UniMarine Inc., Quepet Lubricants LLC, and Castrol Limited.
Rising seaborne trade and increasing vessel activity, particularly in emerging economies in the Asia Pacific, are expected to support growth in the marine lubricants market.
About the Author(s)
Petrochemicals Research Team
Bulk Chemicals · PetrochemicalsThis report was authored by the petrochemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the petrochemicals segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


