
- Home
- »
- Communication Services
- »
-
Maritime Surveillance Market Size And Share Report, 2033GVR Report cover

Maritime Surveillance Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Solution, Services), By Application (Surveillance and Tracking, Navigation), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$25.7BMarket Estimate, 2026
$27.2BMarket Forecast, 2030
$45.6BCAGR, 2026–2030
7.7%Maritime Surveillance Market Summary
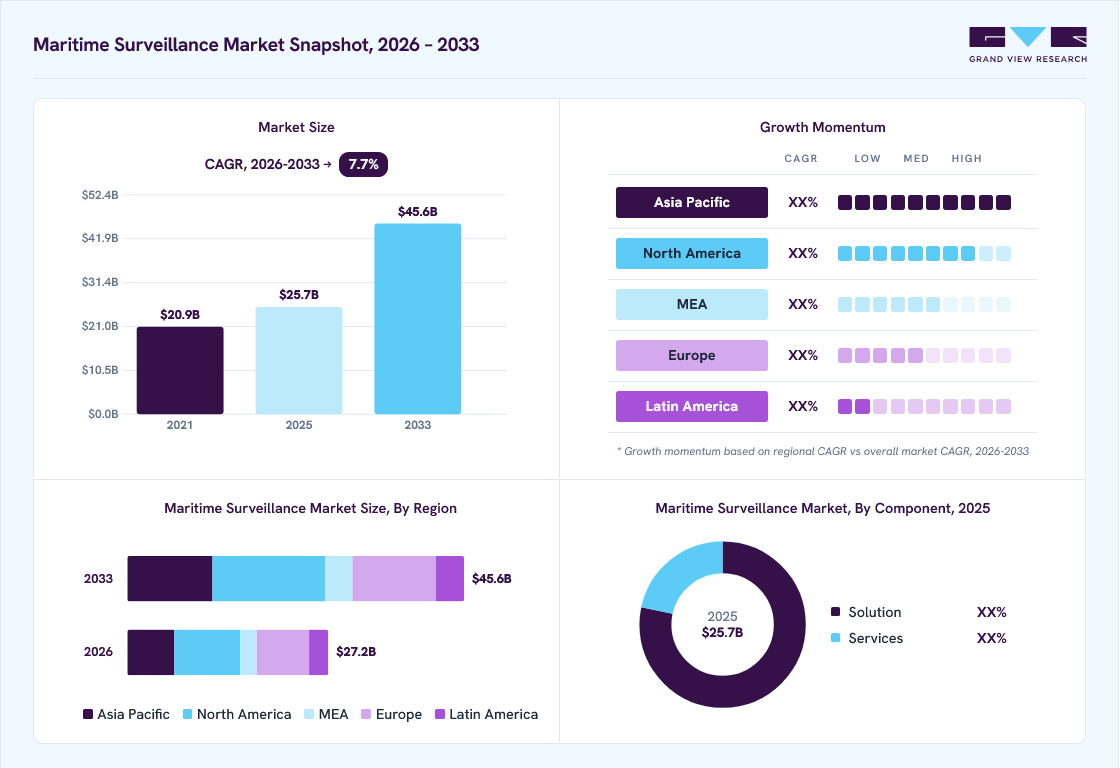
The global maritime surveillance market size was valued at USD 25.7 billion in 2025 and is projected to grow from USD 27.2 billion in 2026 to USD 45.6 billion by 2033, growing at a CAGR of 7.7% from 2026 to 2033. North America dominated the global market with the largest revenue share of 32.7% in 2025. The increasing need for national security and the protection of maritime borders is a significant driving factor of the maritime surveillance market.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: Solution segment dominated the market, with a revenue share of 78.3% in 2025
- By application: Surveillance and tracking segment held the largest market share of 35.3% in 2025
- By end-use: Military segment held the largest market share in 2025
Regional Highlights
- Largest regional market: North America (32.7% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 25.7 Billion
- Estimated market size in 2026: USD 27.2 Billion
- Projected market size by 2033: USD 45.6 Billion
- CAGR (2026-2033): 7.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2030 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Governments worldwide are investing in advanced surveillance systems to monitor and secure their coastlines against illegal activities such as smuggling, piracy, and unauthorized fishing. In addition, the growing adoption of unmanned aerial vehicles (UAVs) and autonomous underwater vehicles (AUVs) for enhanced maritime domain awareness is also contributing to market growth.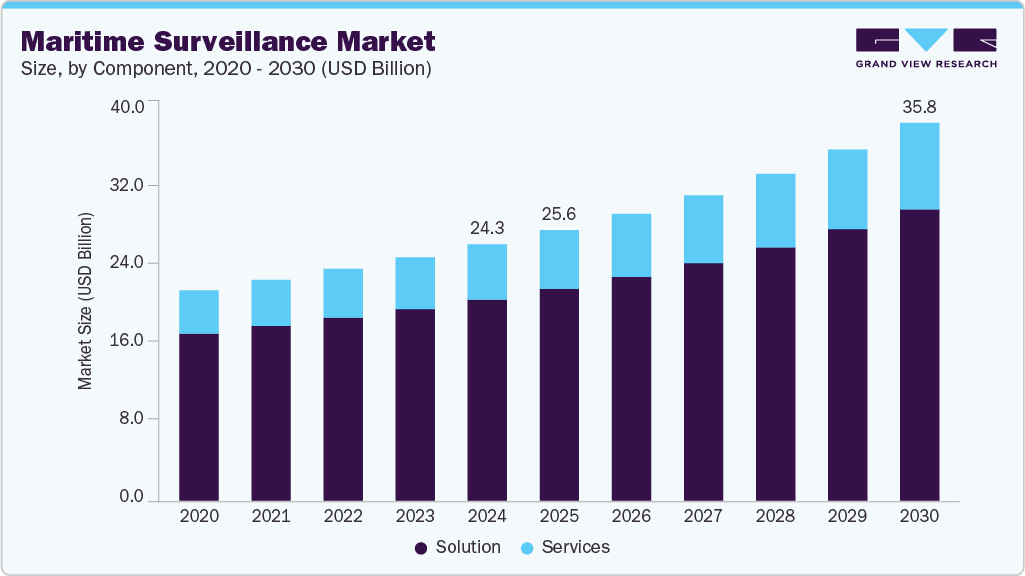 To learn more about this report, Download Free Sample Report
Technological advancements are transforming the maritime surveillance landscape. The integration of artificial intelligence (AI) and machine learning (ML) is enabling the development of intelligent surveillance systems capable of processing large volumes of data and identifying potential threats with high accuracy. AI-driven analytics are enhancing the capabilities of surveillance systems by automating data analysis and providing actionable insights. In addition, the use of blockchain technology is emerging as a trend in maritime surveillance, offering secure and transparent tracking of vessels and cargo.
Another notable technological trend in maritime surveillance is the deployment of integrated surveillance solutions that combine multiple sensors and data sources. These solutions provide a comprehensive view of maritime activities by fusing data from radar, sonar, satellite imagery, and AIS (Automatic Identification System). The use of big data analytics and cloud computing is also becoming prevalent, enabling the storage, processing, and analysis of vast amounts of surveillance data. This helps in identifying patterns, predicting potential threats, and enhancing decision-making processes.
Regulatory trends are playing a significant role in shaping the maritime surveillance market. International maritime organizations and national regulatory bodies are implementing stringent regulations and guidelines to ensure maritime safety and security. The International Maritime Organization (IMO) has introduced regulations such as the International Ship and Port Facility Security (ISPS) Code, which mandates the implementation of security measures for ships and port facilities. In addition, the European Union's Maritime Security Strategy emphasizes the importance of integrated maritime surveillance for safeguarding European waters.
However, high costs associated with the deployment and maintenance of advanced surveillance systems can be a significant barrier, especially for developing countries with limited budgets. The integration of various surveillance technologies and ensuring interoperability among different systems is another challenge that can affect the efficiency of surveillance operations. In addition, the maritime environment poses unique challenges, such as harsh weather conditions and vast areas to be monitored, which can impact the performance of surveillance systems.
Market Dynamics
The maritime surveillance market is experiencing robust growth due to increasing concerns regarding maritime security, illegal fishing, piracy, smuggling, and territorial disputes. Governments and defense agencies are investing heavily in advanced surveillance systems to strengthen coastal monitoring, safeguard critical maritime infrastructure, and ensure maritime domain awareness. The integration of satellite technologies, unmanned systems, radar networks, and artificial intelligence is enhancing surveillance capabilities across global waters. In addition, advancements in autonomous surveillance technologies and the expansion of offshore economic activities expected to drive growth of the market during the forecast period. However, factors such as high deployment costs and operational complexities could hamper the growth of the market.
Growing concerns related to piracy, illegal trafficking, terrorism, unauthorized migration, and territorial disputes are driving demand for maritime surveillance solutions worldwide. Governments are increasingly prioritizing maritime security to protect national interests, commercial shipping routes, and critical coastal infrastructure. Maritime surveillance systems provide real-time monitoring, vessel tracking, and threat detection capabilities that help authorities respond quickly to security incidents. The increasing complexity of maritime threats has encouraged investments in advanced radar systems, satellite surveillance, and integrated command-and-control platforms. Coastal nations are expanding surveillance networks to strengthen border security and improve maritime domain awareness. Defense modernization programs are further supporting the procurement of advanced surveillance technologies. These factors are contributing to the growth of the market.
Maritime trade remains vital to the global economy, making the protection of shipping routes increasingly important. Governments are strengthening monitoring capabilities across strategic waterways and exclusive economic zones (EEZs). Surveillance technologies help improve operational effectiveness and reduce security risks. International cooperation initiatives are also supporting surveillance investments. These factors are expected to contribute to the growth of the market during the forecast period.
The deployment and maintenance of maritime surveillance systems require substantial financial investments, making cost a major restraint for market growth. Advanced radar systems, satellite networks, surveillance aircraft, UAVs, and integrated command centers involve significant procurement and infrastructure expenses. Operational costs related to maintenance, personnel training, and system upgrades further increase total ownership costs. Budget limitations restrict investments, particularly in developing economies and smaller maritime agencies. Long implementation timelines also delay project deployment. These financial challenges limit the adoption of advanced surveillance solutions. Such factors could hinder the growth of the market.
The expansion of offshore oil & gas operations, offshore wind farms, commercial shipping, and marine resource exploration is driving demand for maritime surveillance systems. These activities require continuous monitoring to ensure operational safety, asset protection, and regulatory compliance. Surveillance technologies help detect unauthorized vessel activities, monitor maritime traffic, and protect critical offshore infrastructure. Increasing investments in offshore renewable energy projects are further expanding surveillance requirements. Governments and private operators are deploying advanced monitoring systems to mitigate operational risks and improve asset security. Growing maritime economic activity is creating a greater need for real-time situational awareness, thereby driving the growth of the market.
Analyst Perspective
The maritime surveillance market is experiencing steady growth driven by increasing investments in maritime security, coastal monitoring, and border protection initiatives. Rising concerns related to illegal fishing, piracy, smuggling, and territorial disputes are encouraging governments and defense agencies to deploy advanced surveillance technologies. The integration of radar systems, satellite monitoring, unmanned platforms, and AI-powered analytics is improving maritime domain awareness and operational efficiency. Growing offshore energy activities and expanding maritime trade are expected to further support demand for maritime surveillance solutions over the forecast period.
Component Insights
Based on component, the solution segment led the market with the largest revenue share of 78.3% in 2025. This dominance is primarily due to the increasing demand for integrated systems encompassing radars, sensors, cameras, AIS transponders, and central control rooms. These comprehensive solutions enhance situational awareness and overall maritime security. As maritime activities continue to expand globally, the solution segment's dominance is expected to persist, driven by ongoing technological advancements and the escalating complexity of maritime threats.
The services segment is expected to grow at the fastest CAGR over the forecast period. This growth is driven by the growing need for data analysis, system integration, maintenance, and support services. As maritime surveillance systems become more complex, the demand for skilled professionals to manage and optimize these systems is expected to grow significantly. In addition, the continuous expansion of commercial maritime operations, such as international cargo shipping, offshore energy exploration, and large-scale fisheries management, is boosting the demand for maritime surveillance services.
Application Insights
Based on application, the surveillance and tracking segment led the market with the largest revenue share of 35.3% in 2025. The growth can be attributed to the growing need for continuous monitoring and securing maritime borders and assets. The increasing prevalence of maritime threats such as piracy, smuggling, and illegal fishing has driven the demand for robust surveillance systems. These systems enable real-time monitoring of vessel movements, identification of suspicious activities, and efficient response to incidents.
The search & rescue segment is expected to grow at the fastest CAGR during the forecast period. Search & rescue operations rely on a combination of technologies, including UAVs, satellite communications, and advanced radar systems, to locate and assist vessels or individuals in distress. The growing volume of maritime traffic, along with the rising incidence of natural disasters and maritime accidents, underscores the importance of efficient search & rescue capabilities. Innovations such as automated distress signals, real-time tracking, and AI-driven decision support systems are enhancing the effectiveness and speed of search & rescue missions, thereby fueling segment growth.
End Use Insights
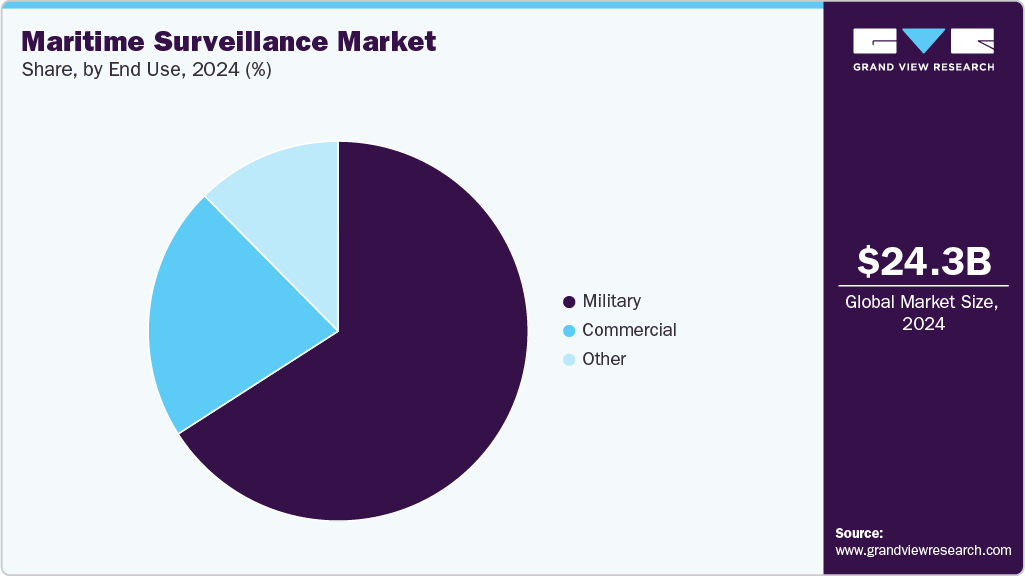
Based on end-use, the military segment led the market with the largest revenue share of 66.6% in 2025. Military organizations rely heavily on advanced surveillance technologies to monitor maritime borders, secure strategic assets, and ensure the sovereignty of territorial waters. This segment leverages a wide array of sophisticated systems, including advanced radar, sonar, satellite imaging, UAVs, and AI-powered analytics, to detect and respond to potential threats swiftly. In addition, significant investments in advanced surveillance technologies, coupled with the critical need for maritime security are expected to fuel the growth of the segment.
 To learn more about this report, Download Free Sample Report
The commercial segment is expected to witness the notable CAGR over the forecast period. Key commercial players, including shipping companies, port authorities, and offshore energy operators, are adopting advanced surveillance technologies to safeguard their assets, streamline operations, and ensure safe navigation. Technologies such as AIS, satellite tracking, and real-time monitoring systems enable commercial entities to enhance situational awareness, prevent accidents, and comply with stringent international maritime regulations. Moreover, increasing maritime trade, offshore energy exploration, and the need for vessel safety have driven the adoption of maritime surveillance solutions by commercial entities.
Regional Insights
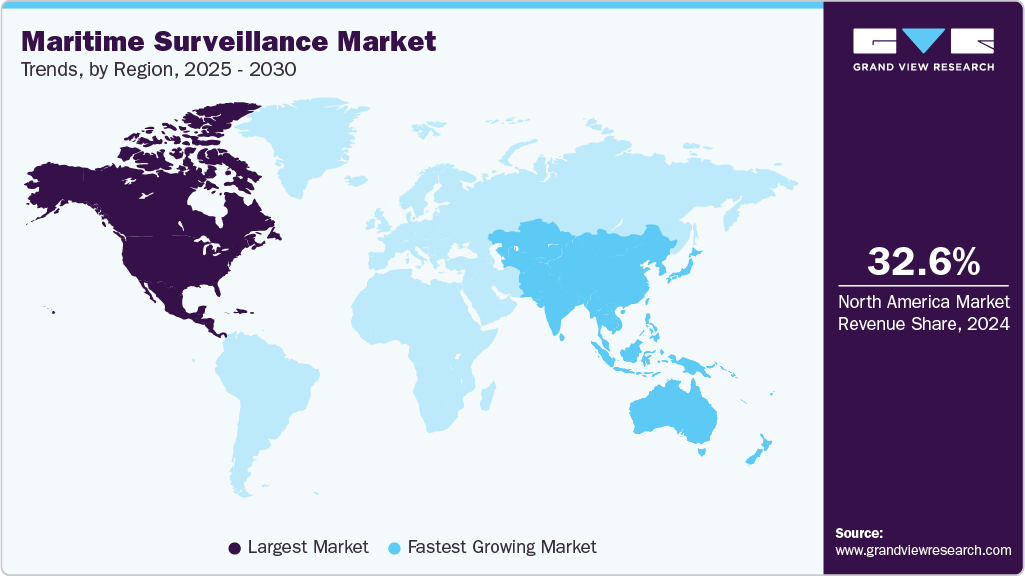
North America dominated the global maritime surveillance market with the largest revenue share of 32.7% in 2025. The U.S. is a significant contributor, investing heavily in advanced surveillance technologies such as unmanned systems, satellite-based monitoring, and AI-driven analytics. The U.S. Coast Guard and Navy continuously upgrade their surveillance capabilities to address threats such as illegal immigration, smuggling, and piracy. In addition, the integration of surveillance systems with homeland security initiatives bolsters the market.
 To learn more about this report, Download Free Sample Report
U.S. Maritime Surveillance Market Trends
The maritime surveillance market in the U.S. held the largest share in the North America region in 2025. The U.S. maritime surveillance market is experiencing robust growth, primarily driven by a comprehensive approach to national security and defense. The country has implemented sophisticated surveillance systems to monitor its extensive coastline, which spans over 12,000 miles. The U.S. Navy and Coast Guard are at the forefront, deploying advanced radar, sonar, and satellite systems to detect and mitigate maritime threats.
Europe Maritime Surveillance Market Trends
Europe maritime surveillance market is expected to register a moderate CAGR from 2025 to 2030. Europe maritime surveillance market is characterized by collaborative efforts among countries to enhance regional security and environmental monitoring. The European Maritime Safety Agency (EMSA) and the European Border and Coast Guard Agency (Frontex) lead initiatives to integrate surveillance systems across member states.
The Germany maritime surveillance market is expected to grow at a significant CAGR from 2025 to 2030. The market growth in the country is driven by increasing government investment in next-generation naval platforms, rising security concerns over maritime borders and offshore assets, and the adoption of advanced surveillance technologies including AI-enabled tracking and satellite monitoring.
The UK maritime surveillance market held a substantial market share in 2024. The UK has continued to prioritize maritime surveillance to strengthen national security, protect critical sea lanes, and support NATO operations. To enhance situational awareness and monitor strategic maritime regions, advanced technologies and multi-platform surveillance systems have been deployed.
Asia Pacific Maritime Surveillance Market Trends
The Asia Pacific Maritime Surveillance market is expected to grow at a fastest CAGR of 8.1% during the forecast period, driven by the region's strategic importance, extensive maritime boundaries, and increasing maritime trade activities. Countries such as China, Japan, India, and Australia are heavily investing in advanced surveillance technologies to secure their waters.
India’s maritime surveillance market is expected to grow at the fastest growth rate during the forecast period driven by a combination of trade-driven infrastructure growth and strategic imperatives such as protecting an extensive EEZ, energy and offshore assets, and ensuring secure sea-lines of communication. Government programs to modernize ports and coastal connectivity increase demand for coastal radars, vessel-tracking systems, airborne maritime patrols and analytics services.
The China maritime surveillance market held a substantial market share in 2024, supported by a dual civil-and-military modernization push, with the People’s Liberation Army, coast guard and port authorities investing heavily in sensors, patrol platforms and networked C4ISR systems to strengthen territorial enforcement, enhance fleet operations and expand maritime domain awareness. This momentum is further supported by a strong domestic shipbuilding and defense-industrial base that enables rapid procurement and large-scale deployment of surveillance assets.
Key Maritime Surveillance Company Insights
Some of the key companies in the Maritime Surveillance industry include Thales Group, Raytheon Technologies, and Saab AB, among others. Strategic partnerships and new product launches have become a key competitive strategy to gain a competitive edge in the market.
-
Thales Group offers defense, aerospace, and security technologies, including comprehensive maritime surveillance solutions. Its offerings span naval radars, maritime communications, and integrated command and control systems. The maritime segment provides solutions for both coastal and offshore monitoring. Notable products include Smart-S Mk2 radar and Thales maritime operations centers that deliver real-time situational data.
-
Raytheon Technologies Corporation delivers defense and aerospace technologies, with capabilities in sensors, radars, and integrated maritime solutions. Its offerings in maritime surveillance include maritime radar systems, sonar solutions, and communication networks for naval operations. The company provides scalable systems for coastal monitoring and offshore security. The advanced maritime communication platforms enhance situational awareness across maritime domains.
Key Maritime Surveillance Companies:
The following key companies have been profiled for this study on the maritime surveillance market.
-
Indra Sistemas, SA
-
Raytheon Technologies Corporation
-
Saab AB
-
Elbit Systems Ltd.
-
Bharat Electronics Limited
-
Thales Group
-
Dassault Aviation SA
-
Kongsberg Gruppen ASA
-
Furuno Electric Co., Ltd.
-
SRT Marine Systems plc
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Raytheon Technologies Corporation, Saab AB, Thales Group, Dassault Aviation SA)
- These companies focus on expanding integrated maritime surveillance portfolios, strengthening defense and coastal security capabilities, and investing in advanced radar, satellite, sensor, and command-and-control technologies. They actively pursue government contracts and long-term defense modernization programs.
- Strong technological expertise, extensive defense industry experience, global customer networks, diversified product portfolios, and established relationships with military and maritime agencies provide significant competitive advantages.
- Long procurement cycles, dependence on government defense budgets, and complex regulatory requirements can affect revenue growth and project execution timelines.
Emerging Players (SRT Marine Systems plc, HENSOLDT)
- These companies focus on specialized maritime surveillance solutions, vessel tracking technologies, coastal monitoring systems, and next-generation sensor capabilities. They emphasize innovation, operational flexibility, and targeted maritime security applications.
- Strong specialization in maritime domain awareness, advanced tracking technologies, and the ability to rapidly develop tailored solutions help these companies compete effectively in niche segments.
- Compared to larger defense contractors, these companies generally have smaller global footprints, lower contract volumes, and fewer resources for large-scale defense programs and international expansion.
Recent Developments
-
In October 2025, Raytheon Technologies Corporation product SPY-6(V)1 radar selected by the German government for installation on eight F127 frigate. The radar features four array faces with 37 modular assemblies each, delivering continuous 360-degree situational awareness, and is part of the U.S. Navy's SPY-6 family used for air and missile defense. The contract includes comprehensive support to integrate the radar with the frigates' design, enhancing the German Navy's multi-mission capabilities and enabling faster, more informed decision-making at sea.
-
In July 2025, Bharat Electronics Limited (BEL) signed a contract with the Indian Navy for the implementation of the National Maritime Domain Awareness (NMDA) project aimed at enhancing maritime and coastal security. The project involves upgrading the existing National Command, Control, Communication and Intelligence (NC3I) Network to the advanced NMDA Network, integrating AI-enabled software for improved data collation, analysis, and information sharing among maritime stakeholders.
Maritime Surveillance Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 25.7 billion
Market size value in 2026
USD 27.2 billion
Revenue forecast in 2033
USD 45.6 billion
Growth rate
CAGR of 7.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share, competitive landscape, growth factors, and trends
Segments covered
Component, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; U.K; Germany; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; and South Africa
Key companies profiled
Raytheon Technologies Corporation, Saab AB, Elbit Systems Ltd., Bharat Electronics Limited, Thales Group, Dassault Aviation SA, Kongsberg Gruppen ASA, Furuno Electric Co., Ltd., SRT Marine Systems plc, HENSOLDT
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Maritime Surveillance Market Report Segmentation
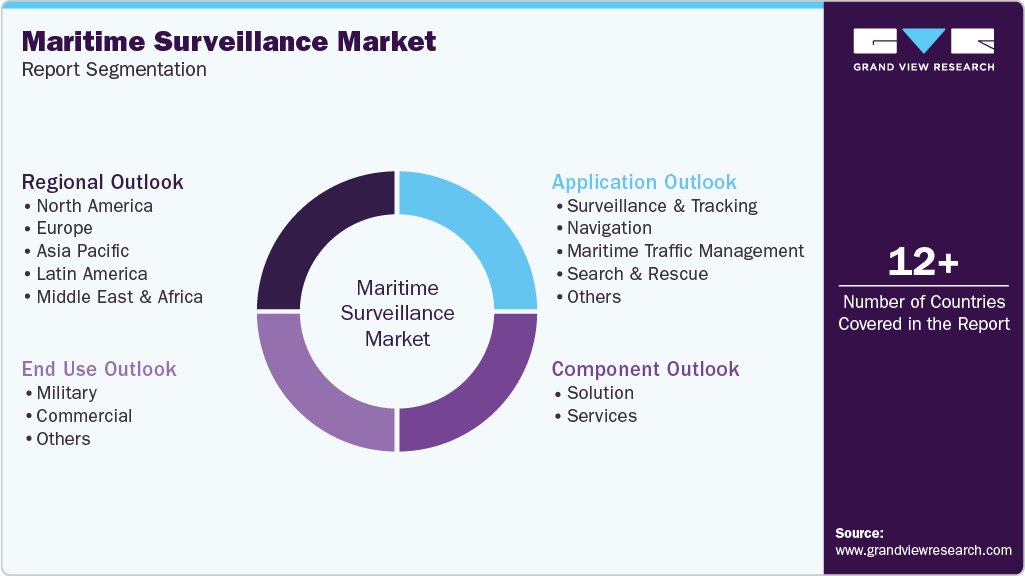
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global maritime surveillance market report based on component, application, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Component Outlook (Revenue, USD Million, 2021 - 2033)
-
Solution
-
Services
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Surveillance and Tracking
-
Navigation
-
Maritime Traffic Management
-
Search & Rescue
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Military
-
Commercial
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
KSA
-
UAE
-
South Africa
-
-
Research Methodology
The maritime surveillance market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each maritime surveillance segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Component
Revenue capture definition
Solution
This segment captures revenue generated from maritime surveillance hardware, software, and integrated systems used for monitoring, tracking, detection, communication, intelligence gathering, and maritime domain awareness.
Service
This segment captures revenue generated from consulting, system integration, installation, maintenance, technical support, training, managed services, and operational support associated with maritime surveillance solutions.
Segment - Application
Revenue capture definition
Surveillance and Tracking
This segment captures revenue generated from maritime surveillance systems used to monitor, identify, detect, and track vessels, maritime assets, and activities across territorial waters, exclusive economic zones (EEZs), ports, and international waterways. T
Navigation
This segment captures revenue generated from surveillance technologies that support safe vessel navigation through real-time monitoring of maritime conditions, vessel positions, coastal infrastructure, navigational hazards, and shipping routes.
Maritime Traffic Management
This segment captures revenue generated from surveillance solutions used to manage vessel movements, optimize port operations, monitor shipping lanes, reduce congestion, and improve maritime traffic flow.
Search & Rescue
This segment captures revenue generated from surveillance systems used to detect, locate, and support rescue operations involving distressed vessels, missing persons, maritime accidents, and emergency situations.
Others
This segment captures revenue generated from additional maritime surveillance applications such as environmental monitoring, fisheries management, offshore asset protection, border security, anti-piracy operations, and maritime intelligence gathering.
Segment - End Use
Revenue capture definition
Military
This segment captures revenue generated from maritime surveillance solutions deployed by naval forces, coast guards, defense organizations, and homeland security agencies.
Commercial
This segment captures revenue generated from maritime surveillance solutions used by commercial shipping companies, port authorities, offshore energy operators, fisheries, logistics providers, and maritime transportation organizations.
Others
This segment captures revenue generated from maritime surveillance solutions utilized by research institutions, environmental agencies, non-governmental organizations, maritime authorities, disaster response agencies, and other entities involved in monitoring and managing maritime activities.
Estimation Model
Layer Name
Key Question
Description
Maritime Operations & Coastal Assets Base Layer
Which maritime regions and assets require monitoring and protection?
Establish the total potential demand base by identifying global maritime activities, including commercial shipping routes, ports, coastal infrastructure, naval operations, offshore energy assets, fisheries, and exclusive economic zones (EEZs). It evaluates factors such as maritime trade volumes, coastline length, vessel traffic, offshore installations, and maritime security requirements.
Addressable Maritime Surveillance Market Layer
Which maritime operations can realistically deploy surveillance solutions?
Refine the total maritime ecosystem into the serviceable maritime surveillance market by considering factors such as defense spending, maritime security regulations, coastal monitoring requirements, border protection initiatives, technological infrastructure, and investments in maritime domain awareness. It determines the share of maritime operations that can potentially adopt surveillance systems.
Maritime Surveillance Adoption Layer
Who is actively deploying maritime surveillance solutions?
Estimate annual demand generation by analyzing adoption among naval forces, coast guards, port authorities, maritime security agencies, offshore energy operators, shipping companies, and fisheries management organizations. It converts the addressable market into measurable deployments of radar systems, satellite monitoring solutions, AIS platforms, surveillance software, and related services.
Revenue Layer
How does surveillance adoption translate into market revenue?
Convert adoption into market revenue through sales of surveillance hardware, software platforms, integration services, maintenance contracts, managed services, training, and technical support. Revenue is generated by applying average system prices, and service fees across different end-use sectors and applications.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Maritime Threat Analysis
Delivered assessment of piracy, illegal fishing, smuggling, maritime terrorism, territorial disputes, and unauthorized vessel activities influencing surveillance demand
Analysis of threat intensity by region and maritime corridor
Supported risk assessment and opportunity identification
Improved understanding of security-driven market demand
Regional & Country Maritime Security Opportunity Analysis
Delivered region-wise and country-wise market sizing, forecasts, and growth analysis across North America, Europe, Asia Pacific, Latin America, Middle East & Africa
Assessment of maritime security investments, naval modernization programs, and border surveillance initiatives
Supported geographic expansion strategies
Enabled identification of high-growth maritime security markets
Competitive Benchmarking & Strategic Landscape Analysis
Delivered benchmarking of major maritime surveillance providers based on surveillance range, technology portfolio, naval contracts, satellite capabilities, geographic presence, innovation initiatives, and strategic partnerships
Analysis of acquisitions, defense contracts, product launches, and expansion activities
Supported competitive intelligence and strategic decision-making
Enabled identification of market gaps and growth opportunities
Frequently Asked Questions About This Report
Asia Pacific is the fastest-growing region over the forecast period.
Based on component, the solution segment led the market with the largest revenue share of 78.3% in 2025, while the services segment is the fastest-growing component.
Based on application, the surveillance and tracking segment led the market with the largest revenue share of 35.3% in 2025, while the search & rescue is the fastest-growing application.
Based on end use, the military segment led the market with the largest revenue share of 66.6% in 2025 and is the fastest-growing end use segment.
Some key players operating in the maritime surveillance market include Raytheon Technologies Corporation, Saab AB, Elbit Systems Ltd., Bharat Electronics Limited, Thales Group, Dassault Aviation SA, Kongsberg Gruppen ASA, Furuno Electric Co., Ltd., SRT Marine Systems plc, HENSOLDT.
The global maritime surveillance market size was valued at USD 25.7 billion in 2025 and is estimated at USD 27.2 billion in 2026.
The global maritime surveillance market is expected to grow at a compound annual growth rate of 7.7% from 2026 to 2033 to reach USD 45.6 billion by 2033.
North America dominated the global market with the largest revenue share of 32.7% in 2025. The U.S. is a significant contributor to the North American market, investing heavily in advanced surveillance technologies such as unmanned systems, satellite-based monitoring, and AI-driven analytics.
Key factors that are driving the market growth include the increasing need for national security and the protection of maritime borders and the rising deployment of integrated surveillance solutions.
About the Author(s)
Communication Services Research Team
Technology · Communication ServicesThis report was authored by the communication services research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the communication services segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


